Small Cap Value Report (Tue 11 Sep 2018) - JD., BRY, LUCE, UPGS, MAI, BLV, SBIZ, PIL, ONEV, MIDW, CYAN

Good morning!
I've had a quick look at the sparkling interim figures from JD Sports Fashion (LON:JD.) - it just shows that, even in tough conditions, the best companies can still deliver good figures. The numbers benefit from an acquisition in the USA. The narrative talks about further international expansion, including in the biggest potential market, the USA - which could be exciting. It looks very impressive, apart from the now loss-making outdoors division - affected by the hot summer (not many people buying outdoor coats for hiking, etc). Worth a closer look, when I have more time. Although I am uneasy about a highly profitable retailer distributing other brands' stock - there's the potential risk of big brands squeezing JD's profits at some point.
Here are some late comments from Monday's announcements. More people will see them if I put them into today's report (I wrote these comments below last night. They're brief, because I'm concentrating my energies more on companies which interest me.
Brady (LON:BRY)
A trading & risk management software company.
Interim results (6m to 30 Jun 2018) look poor (loss-making), but it expects a better H2. With 95% visibility on 2018 revenues, that seems well underpinned.
Balance sheet looks quite weak, but software companies get paid up-front, so can often operate fine with a weak balance sheet.
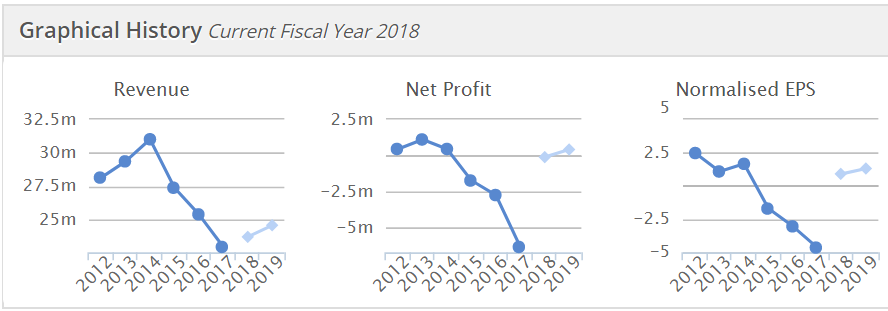
With such a poor track record, it's difficult to understand why this company is valued at anything like the current market cap of £55m (at 66p per share). Maybe the client relationships would be attractive to an acquirer?
The narrative talks about a 3 year turnaround plan. It doesn't interest me. Why pay up-front for a turnaround that hasn't yet delivered profitability?
Luceco (LON:LUCE)
Poor H1 results, but a more positive outlook for H2;
The Group's outlook remains unchanged from the July 2018 Trading Update. The second half of 2018 is anticipated to be a stronger period than the first six months with a return to profitability expected.
Although UK consumer confidence remains fragile the Group has moved into the third quarter with: a 30% increase in the UK Retail order book, lower commodity prices, better selling prices and a more favourable currency position as a result of the hedging actions taken at the beginning of the year and improving currency markets.
Consequently, the Group is well positioned to deliver year-on-year adjusted operating profit growth in the second half of the year.
It's not the sort of company that interests me at all.
UP Global Sourcing Holdings (LON:UPGS)
An in line update. Profit is well down on last year, but as expected.
Not a very good company, in my opinion.
Maintel Holdings (LON:MAI)
Interim results - this telecoms company might be worth a closer look. H1 profit is down slightly against LY, but the outlook comments sound upbeat.
Valuation looks modest, with a low PER and decent dividend yield.
I don't understand this sector, so don't invest in it usually, so it's not for me. Readers might want to have a look into it though, as it looks superficially attractive at first glance.
Belvoir Lettings (LON:BLV)
Share price: 108p (unchanged today, at 08:33)
No. shares: 34.9m
Market cap: £37.7m
Belvoir Lettings PLC (AIM: BLV), the UK's largest property franchise, is pleased to announce interim results for the six months ended 30 June 2018.
This is quite an interesting little company, which mainly operates residential property lettings offices, through a franchise model. There's some ancillary income from property sales & mortgage broking.
Notable features are that it's been growing in recent years, and has a high dividend yield. The shares are quite illiquid, with a wide spread, so it's not one to trade in & out of.
- H1 revenue up 19% to £6.1m
- Adjusted profit also up 19% to £2.43m
- Statutory PBT is up 66% to £2.87m, but this benefits from a one-off £800k boost, from reducing a provision for contingent consideration. Therefore, the adjusted number above is the right one to use when valuing the share
- H1 figures benefit from an acquisition on 13 July 2017 - which didn't contribute at all to H1 last year, but delivered a full 6m trading in H1 this year
- Interim dividend flat at 3.4p
- Good cashflow
- Weak balance sheet, with negative NTAV
- Contingent consideration creditor of £4,155k is in current liabilities - so investors need to confirm how the company is going to pay this? Cash or shares? If cash, where will they get it from? e.g. increased borrowings?
Outlook - trading in line with full year management expectations. Why do they say management expectations, and not market expectations?
H2 has made a promising start.
BLV is expecting c.20% of letting agents to exit the market due to tough conditions & regulations. That seems a good opportunity for it to grow market share. That's an interesting theme more generally at the moment. Sectors which are struggling will have winners & losers. Every participant that goes bust, frees up more market share for stronger competitors.
Stockopedia shows consensus forecast at 11.6p for 2018, giving a PER of 9.3 - that looks about right to me, considering that there's a fair bit of debt on the balance sheet.
My opinion - an interesting small growth company. Over the last 5 years, the share price hasn't really gone anywhere though - although shareholders would have collected in plenty of dividend income over that time.
I'm not comfortable with the high dividend payouts, combined with a weak, indebted balance sheet. That's not a good combination. I'd rather see divis reduced, and the balance sheet strengthen over time. But I'm not a shareholder, so my opinion doesn't matter!
Overall, to me it looks priced about right. Quite an interesting little company, but it's not likely to shoot the lights out in terms of share price - I think there are probably better opportunities elsewhere.
Private property lettings is not an area I want exposure to. Rents are far too high for many low income renters, and this is a political hot potato. The trend seems to be towards Government action to clamp down on lettings, and I imagine that would continue.
Stockopedia's algorithms love BLV - it's ranked as a "Super Stock", together with a cracking StockRank. So maybe there's a bigger opportunity here than I've realised?
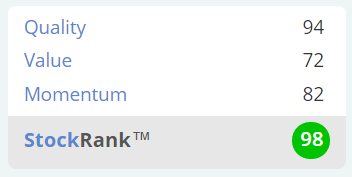
NB. Please remember that StockRanks are not guaranteed to find winners (nothing is). However, the system is now statistically proven, over 5 years, to produce market-beating returns for a basket of stocks. Hence why I take notice of StockRanks as part of my research process on all shares.
Incidentally, nobody at Stockopedia has ever put any pressure on me, or even asked me, to back the StockRank system. Indeed for the first year or so, I held back from saying anything much about it, as I wanted to wait and see what the track record was like. I'm happy to back it now, because it works.
SimplyBiz (LON:SBIZ)
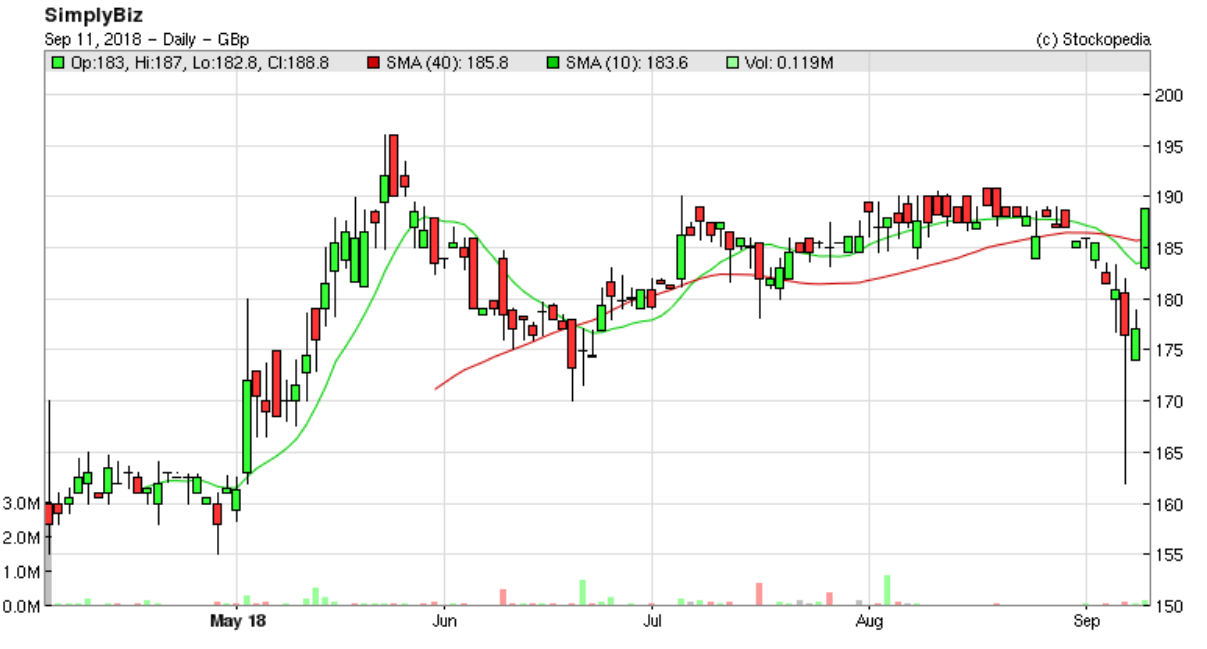
Share price: 185.5p (up 4.8% today, at 10:12)
No. shares: 76.5m
Market cap: 141.9m
SimplyBiz (AIM: SBIZ), the leading independent provider of compliance and business services to financial advisers and financial institutions in the UK, today announces its unaudited results for the six months ended 30 June 2018.
Recap - SimplyBiz floated on AIM in April 2018. It appeared at the Mello Derby investor show shortly afterwards - I recall hearing plenty of favourable comments about SimplyBiz, from successful investor friends at Mello. So it's been vaguely on my radar ever since, as a possible future purchase.
SCVR coverage on the company to date, has been;
16 Mar 2018- Graham briefed us on the company, just before it floated.
17 July 2018 - Graham wrote a section here, commenting on its in line with expectations trading update.
Interim results - announced today look good to me, at first glance.
- Revenue up 13.7% to £24.2m for H1 - the bulk of which (8.6%) came from an acquisition (Landmark Surveyors), the balance is organic growth
- Adjusted profit before tax up 60.8% to £4.5m - a very impressive increase. Also note the very high profit margin of 18.6%
- Adjusted EPS up 61.7% to 4.68p
As an aside, I'm normally happy with adjusted performance figures, providing the adjustments are reasonable. It's fine to adjust out amortisation of acquired intangibles, because those are meaningless book entries when it comes to actually valuing a company.
As Graham has pointed out before, the statutory (i.e. not adjusted) numbers can be useful in assessing whether acquisitions have added value or not, over the long term. Although that's a secondary consideration for me. I don't really care whether a business has grown organically, or through acquisition. It's current performance & outlook that matters to me, and I don't want arbitrary intangibles & their amortisation muddying the valuation waters. So I always strip out acquired intangibles from the balance sheet, and also the related amortisation from the P&L.
Finance costs are unusually high, which is a one-off, as debt was repaid as part of the IPO. The adjusted profit figure removes £1.3m of exceptional finance costs. In future, finance costs should be very low, because debt has now been repaid. The H1 figures include about 3-4 months when the group was still highly geared, pre-IPO, so are not representative of the future.
Dividends - this is reassuring;
Maiden interim dividend of 0.98p per share, in respect of the nine months trading to 31 December, post IPO, as per the stated intention in the admission document
A high margin business like this should have the capacity to pay much bigger dividends in the future.
Outlook - sounds fine, and clearly worded;
Since the end of the period, trading has continued in line with the Board's expectations, and we remain on track to deliver on market expectations for the full year.
Valuation - what are market expectations then? It's helpful when RNSs include a footnote, telling us what market expectations are. The next best thing is a broker update note published on Research Tree, which I'm pleased to report is available in this case, from the house broker.
Incidentally, if you're a serious investor, and do not already have a Research Tree subscription, then you're crazy! Post MiFIF II, I find it a vital source of research information for private investors (I have never had any commercial relationship with RT by the way, for the more suspicious-minded amongst you).
Adjusted ESP forecast for 2018, is 10.5p. So at 185.5p share price, that's a 2018 PER of 17.7 - seem reasonable for a high margin, growing company, in an interesting niche, with recurring revenues.
Forecasts beyond this year are obviously less certain, but rise to 12.9p in 2019, and 15.0p in 2020. That would bring the 2020 PER down to 12.4 if forecasts are achieved.
Balance sheet - looks adequate, rather than strong.
NTAV is sllightly negative, at -£535k. That's not a concern for a business with no capex requirements, and which receives recurring cashflow from customers.
One oddity is that it has cash of £10.7m, simultaneously with having £10.0m in borrowings. Why would this be? Note 11 indicates that the company drew down £10.1m from a new £15.0m Revolving Credit Facility in April 2018.
I think the question needs to be asked, as to why the company doesn't pay off the loan, to save on interest charges, using its cash pile of roughly the same amount? Maybe the cash was at an unusually high spike as at 30 June 2018? I can't think of any other reason why this company would have a loan and cash simultaneously. There doesn't seem to be any issue with large creditors needing to be paid imminently.
It would be useful to have some clarity on this, I've put a call into the company's advisers, and am awaiting a call back. I'll insert here what the explanation is, if/when they get back to me.
** UPDATE - telecon with SimplyBiz CFO, Gareth Hague **
My thanks go to Instinctif Partners for putting me in touch with the Group CFO of SimplyBiz today, who was happy to answer my questions about the cash/debt situation.
The reasons the company has both a £10.7m positive cash balance, and £10m drawn down on its RCF bank facility are as follows;
- Management prudence at time of IPO in April 2018 - i.e. have plenty of cash on hand, so everything goes smoothly
- Adjustments to drawdown of RCF occur quarterly, so the first one was in July, after the interim period end
- Investment opportunities (i.e. smallish potential acquisitions) were simmering away over the summer, so the company wanted flexibility, of having ready access to cash
- If repayments are made on the RCF, then the bank charges non-utilisation fees. So the saving on interest charges from repayment is not that great
- The company may repay some of the RCF using surplus cash at the next review, in Oct 2018, if no acquisitions are imminent
- Debt to EBITDA is low, so the company has plenty of borrowing flexibility
- Very good relationship with Yorkshire Bank
I also asked the Group CFO about the cyclicality of cashflows. He said that revenues are typically smooth - most customers (IFAs) pay on a monthly direct debit, either at the end of each month for that month's services, or pays in the following month.
Outgoings are more cyclical, because staff bonuses are paid in H1. So H2 sees better cash conversion than H1.
There's very little concentration of client risk. Biggest client is about 1% of revenues. Clients typically pay between £250-750 per month, which is about 2% of client revenues. The service relieves them of regulatory worries, so is seen as money well-spent by most clients.
There are competitors offering similar services, but "we work hard for our fees".
I am completely satisfied with the explanations given. My thanks to Gareth Hague for taking the time to telephone me,
** End of Update **
My opinion - SimplyBiz looks good to me. The valuation seems fair, and I very much like the niche which this company serves. Increasingly complex regulation, in many sectors, has opened up opportunities for advisory businesses. It's money well-spent for small companies to pay a subscription, to have expert advice on complex matters, on hand. The alternative, of having to research complex areas yourself, makes me shudder with horror.
Overall then, I'm tempted to open a new position here at some point. Although given macro worries, I'm tending to add interesting companies to my watchlist, with a "buy the dips" mentality, rather than chasing it up in price.
SimplyBiz looks to me like a quality IPO, not something that was buffed up for sale, only to disappoint later - we've had far too many of those this year. So far so good, although it's still early days.
Two companies look as if they'll be leaving AIM shortly, in very different circumstances;
Produce Investments (LON:PIL) - a potato farmer. A recommended cash takeover bid, at 193p has been announced. This is a 35% premium. The price looks fair to me.
The announcement today says that being privately owned will be more suitable for the company. I couldn't agree more - it was always a misfit on the stock market.
Note that the StockRank is 96, and it's ranked a "Super Stock". This share has been cropping up on my value screens for some time now, but I just didn't want to own a potato grower. Just shows, sometimes the most mundane companies can have upside.
Apologies, something went funny with the formatting from this point, I'm trying to sort it out now.
OneView (LON:ONEV)
Down 81% today, on news of the shares de-listing.
I warned SCVR readers off this share twice in the past. So hopefully no readers here got caught out.
We have to be so careful when looking at the tiniest companies on AIM. De-listing is the end game for quite a lot of tiny, loss-making companies. This usually results in c.50% instant losses for shareholders, sometimes more, as in this case. Therefore there's one simple solution;
Don't buy junk like this in the first place!
Toople (LON:TOOP)
This is another micro cap "Sucker Stock", also with a StockRank of 3, which is down 47% today. The reason is a £2.2m placing at just 0.3p per share, a huge discount.
The modus operandi here seems quite cynical - excite the share price with contract win announcements (that's what caused the recent big spikes up in share price), then do a deeply discounted placing as quickly as possible.
Why do I mention this? To warn people that buying into supposedly good news, at a micro cap which doesn't have enough cash in the bank, is asking for trouble. Very often you'll get viciously diluted in a placing that you have no access to.
Again, it's easy to avoid junk like this, just by doing some very basic research. Or, to save time, just avoid shares with a low StockRank.
Unfortunately, the last 3 sections have just disappeared, arrgghh!
This is a very brief summary of what they said;
Midwich (LON:MIDW) - a bit too big for these reports now.
Good results, and outlook, but the valuation now looks very high. It's difficult to see any immediate upside from this valuation.
Cyanconnode Holdings (LON:CYAN) - terrible results, as usual. Admits it needs to raise more cash. Therefore uninvestable.
That's it from me.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
All good points BIACS and hawkipa
my broad hypothesis is this. Capital impact to be circa £200-350m. They have a surplus of £700m so actually could continue without a raise but that would impact upon growth. Seems Fitch appear to have a not dissimilar view. To mitigate they will (1) Insure some of the back book to reduce impact and (2) raise somewhere in the region of £100m in the debt market at circa 5%. Impact of both of those actions circa 1-2p off EPS and reduces over time as back book rolls off.
will certainly be watching the bond market for signals though if YTM rises much higher than 5.5%
Paul - Many thanks for the sterling effort as usual, especially amongst the IT Gremlins
odd price action in JD Sports Fashion (LON:JD.) today as it dipped to 480p on the open and has since rebounded to challenge previous all-time highs. be interesting to see if it does break-out or if this fails
I have been long it for the sheer momentum over the past couple of months...rumours it may be on for FTSE100 entry seems to have boosted it this afternoon
As you mention Paul, it is a bright spot in an otherwise dim and dark sector.
It is conspicuous by its absence in the ranks of short interest, many of the top UK most shorted shares are retailers; the proverbial legion of the damned
Paul, I was interested to see you sold your Cloudcall out of the BMUS portfolio. I know you haven't been keeping this up but still interested in your thoughts with Call. I do own a few and we are expecting some results on 18th Sep.
Hi Camtab,
I still hold Cloudcall (LON:CALL) in real life. The "selling" in BMUS recently was simply to reduce BMUS down to my Top 8 largest holdings only. I don't want the hassle of updating a big public portfolio, and I concentrate my real world portfolio very heavily anyway (my top 8 positions are over 75% of my total portfolio of c.25 stocks, by value).
I like CALL, and think it's oversold right now. It wouldn't take a lot for it to potentially dramatically re-rate, because it has many features which are highly prized at the moment - good growth, very high gross margin, high recurring revenues, low customer churn, SaaS.
The reason it's cheap is because it has repeatedly missed forecasts on growth & cash burn. I'm happy to stick with it, and try to be rational about it, rather than letting emotions creep in (disappointment mainly)
It's a good example of a company that floated on the stock market far too early. Most companies have growing pains, but these need to be endured whilst a private company, then float once the business has matured.
Regards, Paul.
Having said all that I wanted to buy some Redt energy about a month or so ago but was too scared, it was 4p then so would have been more than a double bagger already for me...
I'm taking a lunch break now, then have a long telecon scheduled for 2pm.
If I have enough mental energy left, I'll try to post some brief comments on some more company results/TUs later today, possibly this evening.
Regards, Paul.
JD Sports Fashion (LON:JD.) : " ...there's the potential risk of big brands squeezing JD's profits at some point".
That seems a stretch. Supermarkets squeeze their suppliers and JD now has a market cap. greater than M&S.
Hi Paul - superb analysis from you since you've come back. I continue to be amazed at your ability to type out detailed high quality thought in such a short space of time!
I would like to add some further thoughts to your commentary on Debenhams (LON:DEB) yesterday. The current media speculation is obviously not just relevant to that retailer but companies with concessions. I have held QUIZ (LON:QUIZ) and been quite passionate about its online potential so saw it as a long-term hold, but I have sold my entire holding today because of Debenhams (LON:DEB) concerns. Why? Going back to its last annual results report it has a very high exposure to Debenhams (LON:DEB). At the end of December 2017 its concessions looked like this:
Recall that it recently said problems at House of Fraser would cost it £400k. Using a very crude simple multiplication we could guess that problems at Debenhams (LON:DEB) might therefore cost the company in the region of £4m (11 HoF concessions vs 103 Debenhams' concessions). Or perhaps we could more safely say 'millions'. This is significant when its operating profit in the last financial year was in the region of £8m - not including the long-term loss of revenue.
Own stores (c.70) and concessions (c.150) currently represent around 55% of its profits although this is rapidly declining (for 2017 financial year it was around 67%). I cannot see the company ever having broken down the profitability or revenue split between own stores and concessions so difficult to say exactly what the contribution from Debenhams (LON:DEB) might be.
Stockopedia users are at liberty to challenge me if they think my analysis is alarmist or wrong, or explain to me why the impact might be different. I am an amateur investor and not a retail expert, unlike Paul, and I am unable to properly guess what Debenhams (LON:DEB) might be up to. But while there is uncertainty I think I'd rather sit on the sidelines with QUIZ (LON:QUIZ) and potentially look for another buying opportunity when the share price better reflects risks to its Debenhams concessions.
Are there any other listed brands with strong Debenhams exposure? For example Fulham Shore (LON:FUL) recently said it had plans to open 30 Franco Mancas in Debenhams (LON:DEB) stores: https://www.drapersonline.com/...
Very good analysis, with graphic too. I avoided QUIZ (LON:QUIZ) but was interested in £FULHAMSHORE but I'll pass on then for the moment...thanks.
Looks like you're going to look at SimplyBiz (LON:SBIZ) Paul? Seems off the radar for many perhaps but they seem to have a niche little, growing niche. My thoughts are:
Decent interim results with sales up 14% (some organic, 9% from acquisition of Landmark Surveyors) and EBITDA up 22%. All divisions seem to be performing well and I like how EBITDA margin is up from 20% to 22%. Looks to be in-line with forecasts assuming a bit more growth in H2. By my calculations the P/E for 2018 is 18 and this drops to 14 and then 12 over the next few years which seems good value for 16-22% earnings growth. Main issue is that revenue from the employee benefits software, Zest, fell from £3.3m to £2.5m as customers left legacy platform. Being redesigned though so may bounce back.
The question is how much organic growth they can create and how much growth they'll have to buy in?
Another vote for K3C. Seems to be offering a disruptive financial services model and the results look to support that view.
Hi Paul
As a holder I have taken a bit of a bath in UP Global Sourcing Holdings (LON:UPGS), so tempted to agree with your comment that it is not a very good company. Also your comment has value that Stockopedia is not infallible an indicator of what constitutes a good company.
However. Stockopedia does rank this company at 91, and it has strong metrics on ROC & ROE. Its been through a difficult phase, and seems to be indicating tough conditions ahead, so rightly caution should be exercised.
For those getting in at the right price it is now on a 6x multiple, and showing a dividend yield of 8.6%.
Perhaps all this statistics showing margins of safety will be eroded by current trading conditions, and reduced forecasts, but might be a future punt at this level.
As you can probably sense I am wrestling with the psychological anchor around my neck on this one.
UP Global Sourcing Holdings (LON:UPGS) - I recommend lavinit's article and subsequent comments here: https://www.stockopedia.com/content/oops-upgs-ide-your-head-327743/
He highlights a few red flags you may not have been aware of but is generally bullish.
Whatever Stockopedia says, I don't think anybody would describe UPGS as a high quality company - "ultimately" the net margin isn't high enough and the owned brands are not strong enough. But it is still very easy to construct a scenario for FY2019 forecasts to start improving significantly, the share price to double over the next 6 months and for continued growth from there.
I don't think much will happen before the results, but I'm going to stick my neck out and opine that the share price won't ever return to last Thursday's lows.
This is slightly away from topic but I sense a potentially big contrarian opportunity in Just (LON:JUST) that I would be interested to hear anyones opinion on.
In a nutshell you can buy Tangible embedded value of 230p for 69p : i.e. £1 of assets for 33p.
PE is just over 3* as EPS is now pencilled in at circa 23p with new business storming ahead.
The fall from 150p in last few weeks is all around the PRA consultation on new rules for part of Just (LON:JUST) business, the Lifetime Mortgages division. If the worst outcome is implemented it has a material impact on capital position, but there are a wide range of potential outcomes. Company has sensibly suspended divi until after consultation ends 30th Sep.
BUT......and here's the bit I'm left scratching my head on............
They very usefully in their results show excess capital and sensitivities :
Excess capital is £671m. With rise in interest rates post results say circa £700m now
sensitivities to property values are £204m per -10% so a 35% fall in property, with no subsequent recovery, still leaves them at 100% of capital. The PRA consultation only applies to their back book (not business written recently or going forward) so has a limited time impact as back book gradually rolls off.
They could issue tier 2/3 bonds as a capital buffer presumably. Interest would have an impact on profitability, but really only at the margin. Maybe £10-20m p/a or 1-2p of EPS.
So this feels as though share price is massively impacted by the uncertainty coupled with poor market conditions and could offer a very good entry point.
I totally agree Just (LON:JUST) looks very tempting. However they have let it be known, in a roundabout way, that they themselves have some misgivings over the impact of property values on the equity release portfolio, and that there is very likely to be a rights issue at some time, possibly giving a very large dilution. I formerly held but sold out recently at break even. I feel this is not one for widows or orphans! Lansdowne have recently declared the only a rise in their reportable short interest, at 1.49%. They are the only takers for this action at the moment, so the despondency is not too widespread.
I don't think there will be a rights issue at anywhere near these prices, though it is possible.
They can buy insurance relatively cheaply that offsets such exposure. Effectively a type of Credit default Swap (CDS).
They can issue tier 2 or 3 debt inexpensively, certainly cheaper than an equity raise. Fitch just reaffirmed them as A+ but downgraded from stable to negative until impact known and they also cited that they think management has plenty of capital options open.
I don't think Just (LON:JUST) let it be known they have misgivings on property impact values. They said that they have a good LTV and were priced for a 30% fall with no subsequent growth ever. I'd say that's pretty conservative.
On short interest, I agree that i don't think you'd want to be short. You don't short sell £1 of assets for 35-40p because your risk reward is horrible. Only takes one predator to wait until capital impact is known on 30th Sep, put a 150p takeover bid in the market and your position is completely screwed.
I'm no expert on this, but I seem to recall reading in the Just (LON:JUST) statements that every 0.25% change in the implied deferment rate would affect their 'own funds' position by 80m and every 0.5% change to property volatility assumption would affect this by 30m. The PRA proposal is for an absolute minimum 1% deferment rate and for 13% volatility (these are up from JUST's 0.5% and 12% respectively) so that would wipe out somewhere between 220m - 540m of their 'own funds' (there may be other impacts also within the proposals I expect). So we should perhaps anticipate that JUST could be reduced down to only just about covering the 100% capital requirement and would need to find funds of say around 100m - 300m or so to get back to a decent level of capital cover that would support their business (and to satisfy their banks / financing arrangements). This is fairly serious money for a company with a market cap of less than 700m. If they raised this with debt this is going to be an additional finance cost burden and a drag on profits (plus increased risk through leverage) going forwards. If they raise equity then there's dilution. So looks like there are reasons to be fearful here for holders. If the insurers manage to convince the PRA to do something less drastic (and/or if they agree a long lead in period to the changes over a number of years etc.) then the impact could be a lot less - especially if the discount implies is only adjusted to 1% and not the full 2%. There may well be a big contrarian opportunity here, I don't dispute - but it's always one for the brave when nobody has any idea what the regulator will come up with ... The comments from JUST are (of course!) very bullish and they point out all the nice conservative things they are already doing to manage their risk, but it looks like the PRA has a very different view of the industry and required practice and it's unlikely that JUST will emerge unscathed from the new rules when they are announced - the main question is how bad will it be and has that already been factored in through the 50% share fall over the past months? It may well be, but I don't have enough of a feel for this to be confident I could get it right...
Hi David,
I've never looked at Just (LON:JUST) but I know its name from the bond market as a relatively recent issuer. This chart of its tier 3 debt in yield terms. As the underlying govvie hasn't really done much the spread graph will likely be similar.
To the point about them being able to issue more debt, I think that is possible but it would come at an incredibly expensive price and with a bucket load of covenants. Debt investors in this kind of scenario are open to a deal but far more aggressive than I have ever seen equity investors as it will basically play out, 'what yield do we need to pay you and with what security', so the debt investors will hold the whip hand and you will possibly get distressed guys coming in offering good terms but with equity conversion rights demanded.
To put the yield in context Phoenix tier 3 is trading at 3.54% so a discount of 155bp is substantial. I suspect in this case the debt will be a first mover in this scenario as they will now be crawling all over the company and gaming what might happen using PRA expert consultants who will know the process inside out. They will also have access to management that equity investors likely won't have right now. So it might be worth watching the bond price for signals.
Regards
Paul
Another for K3C please Paul.
Also am I allowed to ask if you have sold a lot of your NEXT shares as I was slightly surprised that they were not in BMUS?
Thanks for all the great commentary as someone who is relatively new to investing I have found it very educational.
Hi jasjones80, if I remember correctly Paul sold out of all Next shares in the summer when I think there was a currency/debt crisis related to Italy? He was closing various positions in a defensive move until the uncertainty had passed.
Hi Wildshot, thanks for that.
Hi jasjones,
Yes, I sold my Next (LON:NXT) shares immediately when the last trading update wasn't as strong as I thought it would be.
I might have made a comment here, and/or on Twitter at the time.
I'll be going back in to Next (LON:NXT) at some point, but only if it drops back further. The share buybacks have stopped now too, which removes a support for the share.
My fundamental view on the company is still very positive, but these are uncertain times, and I don't want to be holding things unless I have 100% conviction on them, and the valuation is attractive.
The nice thing about Next is that it's so liquid I can move in & out instantly.
Regards, Paul.
Thanks Paul that's good to know.
Cheers,
Jason
Encouraging maiden interims from Indy games publisher £TM17.
Hi Paul, A few you might want to glance at.
EU Supply (LON:EUSP) - Microcap that has been a triumph of hope over experience to date. They reported an H1 operating profit but that was only after they started capitalizing development cost. I can see that in their accounts but there is no mention of it in the update. Easy to either have a negative or positive view here. Could be making good profits in 2020! Market value to revenue looks low versus some other more loved SaaS businesses i.e. Cloudcall (LON:CALL)
DP Eurasia NV (LON:DPEU) - Domino's Pizza master franchisee in Turkey and Russia. Things are tough and lots of adjustments in the numbers. Hopefully they should be able to pull through. Fast growing and CEO says that he has gone through two crisis in Turkey before. Third time lucky?
OneView (LON:ONEV) - Sorry story here. Listed in March 2016 and now leaving AIM due to costs etc. Not exactly sure what it does or what has gone wrong.
JD Sports Fashion (LON:JD.) - Maybe one for your eagle retail eye?
Nucleus Financial (LON:NUC) - recently listed IPO. I haven't managed to figure out what it does.
Sanne (LON:SNN) - results but maybe too large for this report at £900m
A huge amount of results worth looking at today.
Another for £K3C please Paul
Luceco (LON:LUCE) - does UK consumer confidence really affect whether people buy light bulbs or not? I'm a bit worried about the economy so I'm going to sit in the dark for a few months.
Luceco (LON:LUCE) - "I'm a bit worried about the economy so I'm going to sit in the dark for a few months."
:), but there is hardly any replacement light bulb market any longer - once you have replaced with LED (and they've made it through the first week or so), they pretty much last forever compared to previous types. Of course there will be a (decreasing) tail of older types in use, but given that (in most cases) it is irrational not to have replaced them early years ago, I suspect the remainder are more likely to be replaced early when people are flush with cash rather than needing to reduce running costs.
Luceco's main lighting market is surely integrated fittings for new build / refurbishment which is very dependent on consumer confidence
"once you have replaced with LED (and they've made it through the first week or so), they pretty much last forever compared to previous types"
Unfortunately that doesn't seem to be the case, certainly for consumer bulbs. I've had a number fail, of several different brands, in time spans ranging from 6 months-ish to a couple of years-ish. It's quite possible that it's the control circuitry that's gone rather than the LEDs themselves, but it makes no difference to me as an end user. I wouldn't be at all surprised if replacing LED bulbs costs me nearly as much as the electricity saved vs. old fashioned filament bulbs.
Having said that, I personally wouldn't touch any company in this space unless they really seemed to have some protectable position, which Luceco (LON:LUCE) doesn't seem to at a cursory glance. Just too much comoditisation too fast to sustain returns in my opinion.
Another request for Alumasc (LON:ALU) and Belvoir Lettings (LON:BLV). Holding both!
£K3C & £TM17 look interesting, as does Alumasc (LON:ALU) thanks Paul & SCVRs...
Paul
I would be interested in your thoughts on Midwich (MIDW), (not sure how to show in blue link form). I hold. It has a great Roce and Roe, net margins a bit thinner. Strong growth and they have advised on target for their revised (upwards) target.
I can see them reaching £30mn Ptb full year from a rough and ready extrapolation of interims with seasonal weighting.
Slight concern is growing debt and poor cash flow being tied up in working capital, higher stocks and debtors, which can sometimes mask an issue. If they can hit 600k sales for full year higher stock will be justified.
Enjoy the analysis from yourself and Graham. Always look at Stockopedia as a filter before investing.
Best wishes
Greyster
Hi Greyster
To show the ticker in blue (that then links to the Stockopedia page) then simply add £ symb9l in front of the ticker so £ MIDW (with no space between the £ and M of MIDW) becomes Midwich (LON:MIDW).
As an aside it doesn’t work where the ticker has a number in it.
Hope that helps.
Michael.
Alumasc (LON:ALU) seems a curate's egg. The rhetoric is extremely bullish, but the figures are less than overwhelming. EPS is down 35%, and revenue down 7%. But the dividend, which seems well covered, is up. The punchline is a possible shift to AIM. Will this trigger institutional selling?
Net debt is £4.8m, and there is still a substantial pension deficit.
Belvoir Lettings (LON:BLV) seems rather more positive, with PBT up 66% off revenues rising 19%. There is no mention of the impending regulatory changes for lettings fees though.
Regional REIT (LON:RGL) seems a decent one for thos seeking dividends. They seem to trade property as much as lease it out. Yield is now c8%.
Does TP (LON:TPG) really have such a massive cash pile?
TP Group. They raised 20m for acquisitions a couple of years ago which remains talked about but almost wholly unused. I sold out today after long hold. Directors seem concentrated on being important rather than profitable - the word 'profit' almost never appears in their releases. But perhaps one day ………?
My morning smallcap tweet: 60% off sale at Telecoms co Toople - to instos only.
Redt Energy (LON:RED), Toople (LON:TOOP), IXICO (LON:IXI), Cyanconnode Holdings (LON:CYAN)
RedT Energy (RED) becomes a preferred supplier of energy storage solutions for UK public sector projects, initially only the NHS.
Toople (TOOP) Uses huge SP rise after its good news 2 weeks ago to make a keep-the-lights-on £2.2m placing at 0.3p, a 60% discount.
IXICO (IXI) wins contract to provide imaging services for a Phase III study in Huntington's disease. Worth £9.1m over a four year term.
CyanConnode (CYAN) H1 rev up 190%. Bizarrely compares H1 op loss with FY loss: "Operating loss of £3,315,931 (H1 2017: £4,785,258), significant improvement on loss of £11,153,094 for 2017 full year." Bullish as always, the 75% SP loss since last H1 RNS not so much.
I'm interested in Redt Energy (LON:RED) now - following the recent announcement of their new generation of storage machines, they announced a pilot with Anglian Water (said there would be a "50% saving in energy by 2040") and today with Essentia.
I think from this, that they are on the cusp of turning from an interesting startup to a mainstream company. If they can pull off the energy saving (and I don't see why not as their kit will allow for arbitrage, peak demand management and renewable inputs) then these will be very attractive to other utilities that draw large amounts of power.
I think its too early to look at their numbers though, but its one to stick an eye on, unless you're feeling speculative (as I am).
This one is highly speculative and the energy storage market is fairly complex. In theory the technical parameters of the RedT Energy flow battery should be very well suited to certain applications but they will be competing against Li-ion batteries which have had billions thrown at their development from big players like SDI Samsung, Panasonic, BYD, Tesla CATL. So the question is will they beat them on price point, at the moment the market is all about li-ion and I struggle to see it being anything but li-ion for at least the next 5 to 10 years.
Also worth noting the Anglian pilot project is tiny, 300kW whereas there have been somewhere around 300MW of li-ion commercially deployed this year in the UK alone. Essentia appears to just be a framework, not sure who else has been appointed but i'd be shocked if it's only redt and no li-ion products.
Energy storage is undoubtedly going to be very big but the different revenues available to the technology are complex and largely under consultation currently. My guess is there will be a small number of very big winners and a big number of small losers but they'll lose big.
I bought Redt Energy (LON:RED) a while back but unfortunately before it collapse to 4p so most of the recent gains have just put me in the black. It's an extraordinarily volatile share at the moment. Today it went up to 9.5p or more and back down to 8.8p which is crackers.
I bought a small position because the technology might be a winner. Might is the operative word. What they sell is Vanadium Flow batteries and they are enormous and heavy. They are unsuitable for cars, phones, etc but they are fine for sitting next to a wind farm and storing electricity when the wind blows and giving it back when the wind has stopped. Currently they are more durable than li-ion, recharge/discharge as much as you like, wont catch fire, and cheaper. Redt now seems to be getting some contract wins but whether it will be the long term winner is impossible to tell. It could be that the winner in the energy storage market isn't a battery at all - it could be using spare electricity to turn water into hydrogen.
Absolutely, its not a mainstream thing at all yet, but the specs for the flow batteries are much more suitable for utility style positions, so I think these tiny pilots are just that - the companies figuring out that they work as expected and advertised.
Li-ion are mostly used because that's all that's been readily available so far. They're a poor solution to this space, and that's why I think these are a bit different. The cost effectiveness of this will be proven in time (and perhaps if li-ion become more in demand with EVs and the like, and a shortage of lithium may push the price up, so these flow batteries should become cheaper options), which is why I highlighted it today. A year should see the results of these pilots proving the tech compared to li-ion.
Another vote for £K3C please. Stunning FY results and current year trading ahead of market expectations. High growth rate and loads of cash. If you are confident on the future prospects of the economy this could be a good one to hold.
Produce Investments Produce Investments (LON:PIL) Please Paul. Lack of discipline on my part I let it go on the drift a month ago!
" The Independent Committee of the Board of Produce Investments and the Board of April 1983 Bidco Limited, a Jersey company ultimately owned and controlled by funds managed by Promethean Investments LLP, are pleased to announce that they have reached agreement on the terms of a recommended cash offer under Chapter 3 of Part 28 of the Companies Act 2006, with an unlisted partial share and loan note alternative to be made by April 1983 Bidco Limited for the entire issued and to be issued share capital of Produce Investments."
Offer 193p Last nights close 142.5
Yes K3C please, figures look excellent, eps up 114%, seem to be well ahead of forecasts.
Hi Paul if you have a chance to look at (LON: K3C) that would be much appreciated.
Many thanks
Take your pick:
Tuesday 11 September
Interims: Cairn Energy, DP Eurasia, EU Supply, Harworth, Hilton Food, JD Sports Fashion, Midwich, Nucleus Financial, Regional Reit, Silence Therapeutics, Simply Biz, STM, Surgical Innovations, Team17, TP, Vectura
Finals: Alumasc, K3 Capital
Trading statement: Ashtead
AGMs: Ashtead, Bailey (CH), Bilby, Cohort, Oxford Instruments, Mulberry, Superdry
Of the above JD Sports Fashion (LON:JD.) (sadly I have never bought), has been the ultimate multibagger - it was 2.25p in Dec. 98 - now
467.4p. Work it out for yourself but I make it 207 times.