Small Cap Value Report (Tue 14 Jan 2020) - FLO, MCB, BOO, GTLY, WJG, D4T4, BOKU, DFS, GAW

Good morning, it's Paul here with Tuesday's SCVR.
Please see the header above, for the list & order, of small cap trading updates/results that I'll be reviewing today. I've also included a couple of mid caps that are particularly noteworthy, and interest me (BOO and GAW).
Estimated time of completion - I'll have the bulk of the report done by 1pm, but as there is so much to report on today, I might need to carry on further into the afternoon, after lunch.
Update at 12:55 - I'm taking a break for lunch now, and will carry on writing this afternoon, as there's loads more I want to cover. the main bit's done, so the 1pm readers have got your money's worth! Look at the extra stuff this afternoon as a bonus. 5pm revised finish time.
Update at 17:24 - today's report is now finished.
Profit warnings
It seems to me that there is a potential opportunity at the moment. The fact is that 2019 was dominated by political uncertainty, and once a general election is called then it is only sensible for businesses to put investment & hiring decisions on ice, and await the result.
Therefore, it could well be the case that some businesses might have had a poor Q4, due to this factor, yet be fundamentally sound businesses which should quickly recover in 2020. There could even be a bounce back effect, with Q1 2020 being better than expected, because;
- The general election result is by far the best outcome for businesses - i.e. a business-friendly Govt with a large majority, also committed to increasing public spending (hence stimulating the economy at least in the short to medium term)
- The Deloitte survey (mentioned in yesterday's SCVR) shows a huge recent rebound in business confidence - suggesting that some investment decisions which were on ice may now be implemented
- Consumer confidence should also rebound strongly, in my opinion, because we have full employment, and good wages growth (above inflation), prolonged low interest rates, etc. Plus minimum wage is going up by c.6% soon, and it has a domino effect upwards as higher paid staff demand that pay differentials are maintained. Therefore, I'm expecting a strong recovery in consumer sentiment & spending in 2020
Put that all together, and I think shares which put out profit warnings now, caused by a soft Q4 2019, could (as always, only very selectively) make good buying opportunities. This is a bit of a one-off factor, which we can take advantage of.
Another factor to consider, is that the stock market tends to react differently to profit warnings, depending on what stage in the economic & stock markets cycles we happen to be in. Broadly speaking profit warnings work like this;
Bear markets - price plunges c.30-50% on the initial warning, and keeps falling, despite short-lived dead cat bounces. This can be because there might be forced sellers, e.g. institutions with redemptions to fund, leveraged punters on spread bets being stopped out, and other investors just capitulating. Hence selling may not be rational, and the company valuation can overshoot on the downside.
The market is gloomy, so assumes that the profit warning is the start of a continuing downward trend in performance. Catching falling knives is very costly in this environment. Shares take a long time (over a year) to recover, if at all. Markets worry about funding - will the bank withdraw support? Fresh equity raises are difficult or impossible to do, or might require a deep discount, wiping out existing shareholders.
Bull markets - price typically drops 20-30% on profit warning, and almost immediately begins recovering, as investors who like the company see the drop in price as a buying opportunity. Problems are seen as fleeting, and investors assume the company will recover quickly and give it the benefit of the doubt. Since other shares are generally expensive, profit warnings are seen as buying opportunities - grab a bargain. Banks remain supportive, and investors are happy to support re-financings on reasonable terms.
Therefore, it makes sense to steer clear of falling knives when the market is bearish, which it was for small caps in most of 2018 & 2019. However, we've seen a stunning recovery in market sentiment since autumn 2019, and especially since the general election result on 13 Dec 2019.
This means that buying carefully selected shares after profit warnings could now be potentially lucrative. But great care is needed, to check out each company properly. Every situation is different, there is no one-size-fits-all way to respond to profit warnings, in my view.
What I'm looking for, in buying opportunities after profit warnings, are shares which pass all these tests;
- Soundly financed, preferably with net cash, so no question of needing additional funding/dilution
- Strong business, with a good track record, that just happens to have had a soft Q4 2019, due to one-off factors
- No deeper, underlying problems
- A business model which I understand, and where I've monitored & researched the company over several years - i.e. companies/sectors that I understand, so I know which companies to avoid
- Strong management with a solid track record of telling it how it is, in trading updates - not companies which consistently over-promise & under-deliver (especially avoiding companies that tend to mislead investors with over-PR'd commentaries which are designed to conceal bad news)
Buying after profit warnings is dangerous, and often produces disastrous results. I've made numerous mistakes in this field over the last 20 years. Therefore, I'm being highly selective about catching any falling knives. I think it also pays to bide one's time. Jumping in immediately after a profit warning can often (usually actually) be a mistake. People anchor to the old price, and hence assume it's a bargain after a 30% drop. But often when you work through the revised forecasts, it's not cheap at all.
So, my mission now is to find shares which warn on profits due to one-off factors, and which may present good recovery plays. I'll be reporting on profit warnings in that context, over the next few weeks.
Today we have 2 profit warnings, from Flowtech Fluidpower (LON:FLO) and McBride (LON:MCB) - so I'll look at these first, and give my opinion on whether they might be buying opportunities or not.
Flowtech Fluidpower (LON:FLO)
Share price: 101.5p (down 20%, at 10:02)
No. shares: 61.2m
Market cap: £62.1m
Trading update (profit warning)
Flowtech Fluidpower plc, the UK's leading specialist supplier of technical fluid power products, provides an update on trading for the financial year to 31 December 2019.
Please bear in mind that FLO's share price is volatile this morning, so it might have changed from the level it is at the time of writing, which is 101.5p.
Graham reported on the company's Q3 2019 update here - which looked satisfactory.
Profit warning today - the announcement presents industry data from the British Fluid Power Association (yes there is such a thing!) showing that revenues dropped about 10% in Oct-Nov 2019. It strikes me that anyone owning this share should possibly monitor the BFPA's press releases, to get early warning of the likely trend in sales at FLO.
Against this backdrop, the Group experienced organic revenue decline of c.10% in Q4; as a result Group revenue is expected to be c.£112.4m which represents overall organic revenue reduction of c.1.5% (H1 growth of c.3% and H2 decline of c.6%) for FY19.
The Board now expects to report underlying profit before tax* of not less than £9.0 million.
That's quite a marked deterioration in performance, from H1 to H2.
Thumbs up to the company for setting out performance clearly. In particular, giving us guidance of not less than £9.0m for 2019 u/l profit, is very helpful. The only improvement I would have liked, is a footnote to inform us of previous market expectations for profit. More and more companies are doing that, which is immensely helpful for investors, to enable us to quickly assess the situation.
Revised forecasts - there are 2 updates today available on Research Tree. I'll just look at the house broker, which cuts EPS FY 12/2019 forecast EPS by 18.2% to 12.3p - PER of 8.3 - whilst that looks cheap, it's quite a big forecast drop coming so late in the year. The risk is that, if Q4's poor performance continues into 2020, then it could feed through to a much lower level of profit for a full year.
Or, performance could bounce back in 2020, as I was talking about in the macro preamble above.
FY 12/2020 forecast is also reduced, to 13.9p (a 16.7% reduction today). It may not necessarily be the case that 2020 improves on 2019, it could get worse, we don't know at this stage.
Outlook - I'm looking for signs of a quick bounceback in performance, but that doesn't appear to be the case here;
Expectations for FY20 have been reviewed by the Board and whilst it is confident that investments made in 2019 will lead to market outperformance, current conditions are such that achieving organic growth may prove difficult, in particular in the first half of FY20.
It is therefore possible that the positive impact of the cost saving initiatives which have now been formulated, and which will shortly be implemented, will be offset, at least in part, by market conditions remaining challenging.
I think this negative-sounding outlook rules out any possibility that I would want to buy any shares today, despite the 20% share price fall. It's probably safer to watch & wait.
Net debt - this is important, because FLO has been acquisitive, involving the use of bank debt;
Net debt** of £16.6m as at 31 December 2019 is in line with market expectations. Q4 has seen debt reduction of £2.5m in a period which paid out a £1.3m interim dividend. A combination of strong operational cash flow, no further payments of deferred consideration in respect of historic acquisition activity and the continued focus on working capital, leads to confidence that FY20 will generate significant positive cash flow.
The double asterisk footnote confirms that net debt stated excludes IFRS 16 lease "debt" - which is absolutely the right way to report it, because IFRS 16 is not bona fide interest-bearing debt, it's just a notional book entry, which shouldn't be there, in my view. Disclose it as a note to the accounts, by all means, but it needs to be removed from the balance sheet & P&L impact too, to get the numbers to make sense to me.
Is net debt a problem? - at £16.6m, it's come down since the interims, when it was reported at £18.8m as at 30 June 2019.
Assuming that trading doesn't fall off a cliff in 2020, then I don't see the debt as a particular problem, because the balance sheet overall looks sensibly structured...
Balance sheet - as at 30 June 2019 looks OK to me.
NTAV is £21.0m - that's fine for the size of the business.
Current ratio (working capital) also looks OK at 1.46
Gross bank debt of £22.6m is funding inventories of £28.1m, plus receivables of £27.0m, therefore is covered more than twice by liquid assets (plus £3.9m of offsetting cash, but that's probably window-dressed for the period end).
I don't know what the bank covenants are - it would be worth checking that out, to plan for a worst case scenario.
Dividends - with a poor end to 2019, and tough conditions expected in H1 2020, combined with the risk inherent in having bank debt, I think the company would be well advised to cut the divis for now, until trading improves.
All too often companies continue paying unaffordable divis, and end up in a (sometimes terminal) mess. It's much better to incur the wrath of investors by cutting the divis, than incurring the wrath of the bank.
My opinion - it's a straightforward situation. If you think performance will improve later in 2020, then it might be worth buying some to tuck away for recovery.
Or, if like me, you're not sure if things are going to get better or worse, then it's probably safest to watch from the sidelines.
It looks a fundamentally good business, making a quite good profit margin.
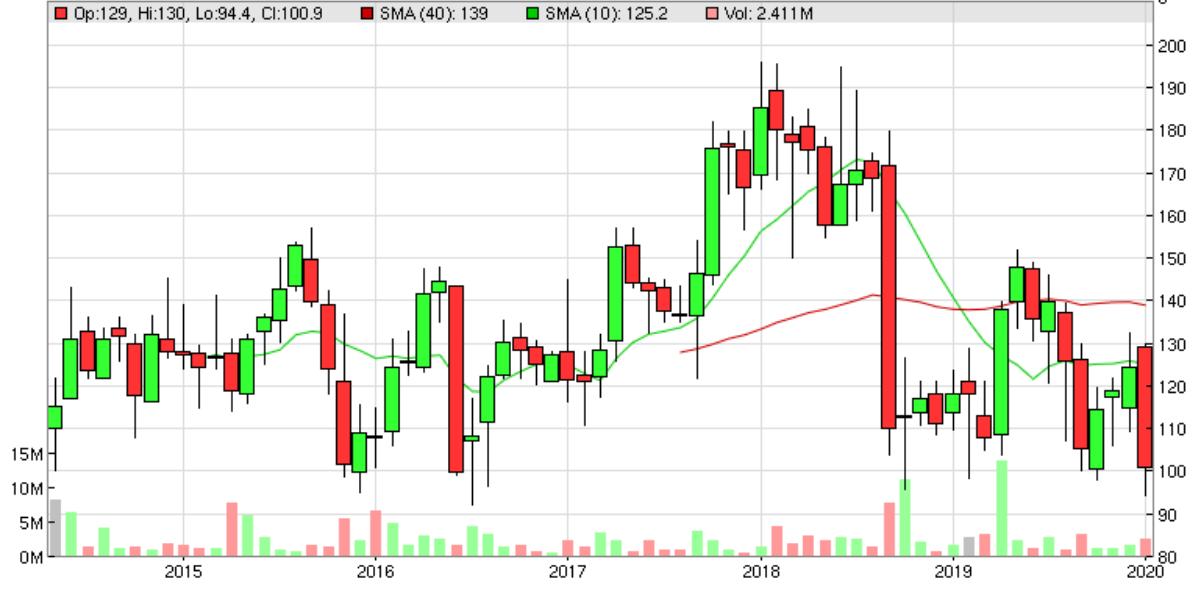
As you can see from the chart below, since it floated, there are rather a lot of large red candlesticks (big drops, for the colour-challenged readers) - meaning that the company is rather prone to warning on profits. This unnerves me. Also note that the share price has just gone sideways overall since it floated (although shareholders have received divis). Not exactly inspiring is it?
McBride (LON:MCB)
Share price: 66.6p (down 16% today, at 11:11)
No. shares: 182.8m
Market cap: £121.7m
Trading update (profit warning)
McBride plc (the "Group"), the leading European manufacturer and supplier of Contract Manufactured and Private Label products for the domestic Household and professional cleaning and hygiene markets, today provides a trading update for the six months ended 31 December 2019.
Note the year end is 30 June 2020.
This company doesn't really interest me, so I'll keep this fairly brief. Graham was uninspired by its last update - here are his comments from 22 Oct 2019. Note that update from the company contained the dreaded H2 weighting for FY 06/2020 profits - which can often be a precursor to another profit warning.
Today it says that H1 revenues are down;
The Group's first half Household revenues at constant currency were 1.4% lower compared to the prior year following a slowdown in the last two months of the period, especially in the UK. H1 UK revenues were 8.0% lower year on year...
This is expected to continue into H2, replacing previous guidance of an H2 recovery;
Reflecting the first half performance, our expectations for the rest of the year are reduced and we now expect full year Household revenues to decline by approximately 2% year on year.
What's the damage? - top marks here for complete clarity. No imprecise wording (e.g. significantly below, materially below, broadly in line with, etc) to interpret, they've just given us the actual figure, hallelujah! Why can't all companies do this?
In the absence of significant raw material cost changes, the Board now expects full year adjusted PBT to be approximately 15% lower than current market expectations(*) reflecting the impact of lower revenues.
(*)Current market expectations refer to a Group compiled consensus for FY20 of adjusted PBT £22.1m.
Even better, McBride has given us a footnote with the previous market expectations.
This is absolute gold standard reporting, and what I've been campaigning for here for years (brokers & PRs do read these reports you know). In fact, I was so thrilled, that I put in a call to McBride's PR at 07:30 today, to thank him & congratulate him on giving us the precise information we need, instead of a load of waffle that many other companies put out!
This approach seems to have worked too. By giving us the expected profit shortfall of 15%, investors have got the information they need, and the share price has gone down 16%. I reckon if a waffley, text-based profit warning had been put out instead, then the uncertainty would probably have led to a steeper fall in share price.
Net debt - looks high, but reassuring re bank covenants;
Net debt closed the period at £113.5m (30 June 2019: £120.9m) excluding the effect of IFRS 16. The Group remains comfortably within all of its banking covenants.
My opinion - this sector doesn't interest me. The customers (retailers) are under intense financial pressure, and have to squeeze their suppliers harder & harder, just to survive.
The new CEO has initiated a strategic & operational review. That sort of thing usually involves exiting low margin activities, but also usually brings exceptional costs.
With so many interesting companies out there, why on earth would anyone choose this to invest in? I suppose the upside could be if the new CEO is able to implement a lasting turnaround. From memory, I think this share has been a turnaround story for several years already.
Gateley Holdings (LON:GTLY)
Share price: 203p (down 3.8% today, at 11:59)
No. shares: 114.7m
Market cap: £232.8m
Gateley (AIM:GTLY), the legal and professional services group, is pleased to announce its unaudited results for the six months ended 31 October 2019 ("the Period"), demonstrating a strong performance with double digit growth in profitability and revenue.
It's an acquisitive group of lawyers. I see the PRs have slipped in a little upbeat comment into the opening description of the company! I can't decide whether I like these or not.
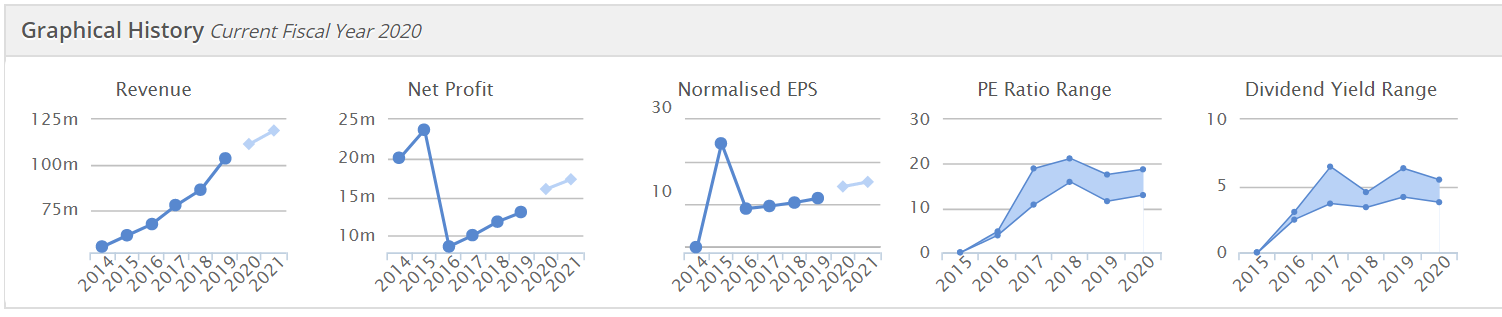
As I'm not familiar with Gateley, the Stockopedia historic graphs & Graham's previous commentary here are a good place to start.
This looks really nice actually - steadily rising earnings, no bad years, reasonable PER if you can buy near the bottom of the range, and good/reliable divis;
Interim results - key points;
- Revenue growth of 11.8% is nearly all organic (10.5%), which is positive
- Good profit margin of 10.6% (PBT of £5.5m divided by £51.8m revenues)
- Net debt down 65% to £2.1m - very good
- Interim divi up 11.5% to 2.9p
- 2 acquisitions in the period
- Outlook says confident they are well positioned to deliver full year market expectations - good
- Balance sheet looks fine to me - receivables are high, but that's par for the course with firms of lawyers - but cash collection could be improved I think
- Cashflow statement is impressive - genuinely cash generative, which it's using mainly to pay big divis
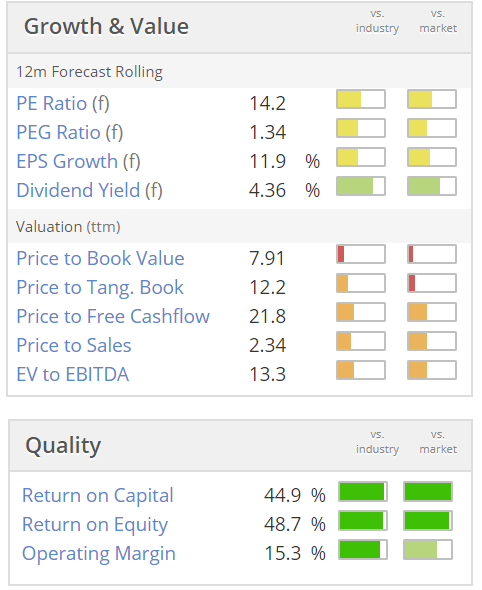
Valuation - looks sensible, I'd say this is about right, because people businesses shouldn't attract high earnings multiples. Lovely quality scores;
My opinion - I don't normally touch people businesses, so it doesn't interest me.
However, the figures look good, I can't see any issues with the numbers at all.
It's established a strong 5-year track record as a listed company, with the strategy & performance seemingly working well, so it might be worth considering.
Stockopedia likes it a lot;
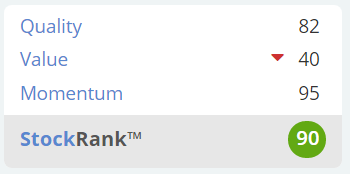
Like so many shares, it's had a big re-rating upwards in the last few months, so personally I wouldn't want to be buying at this point, when others might be wanting to bank their short term profits possibly. Generally at the moment, I'm seeing lots of shares that have had big rallies, running out of steam as profit-taking starts & valuations look stretched. Hence I'm more interested in companies putting out positive updates that have been overlooked in the recent market recovery.
Boohoo (LON:BOO)
Share price: 330p (up 3.7% today, at 12:59)
No. shares: 1,160.2m
Market cap: £3,828.7m
For the 4 months to 31 Dec 2019, and 10 months YTD.
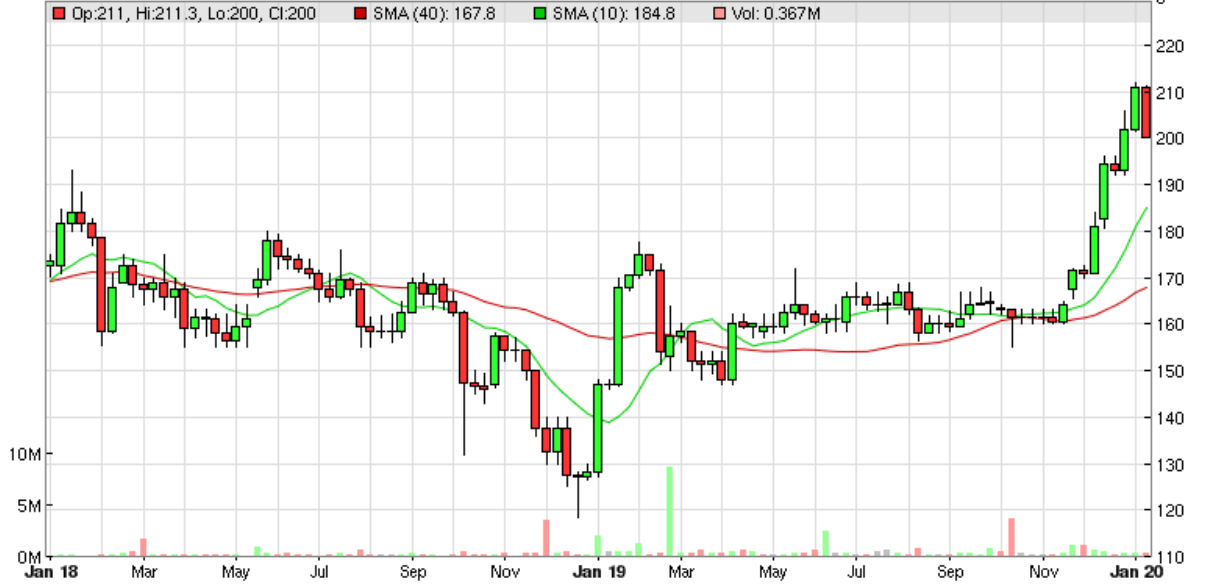
Pretty stunning growth;
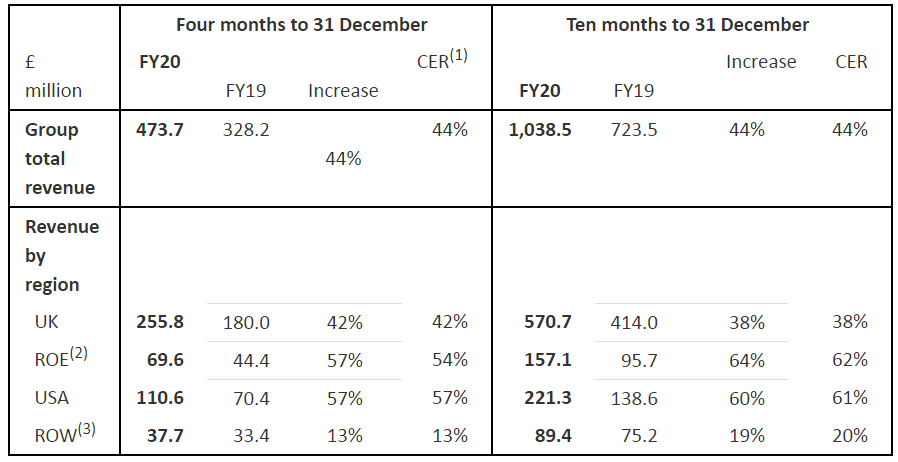
A brief comment to flag that there's yet another sparkling update out today from this online fashion multi-brand empire.
It now has multiple brands, which is a brilliant strategy - each one having the group expertise in design, buying, marketing, IT, logistics, etc, applied to it. So far they've all worked. Brands within the group are now: BooHoo, PrettyLittleThing (part owned by the founder's son), Nasty Gal, MissPap, Karen Millen & Coast. Note that the last 2 are targeting an older demographic from the traditional cheap & cheerful youth market.
Sales are strong internationally too.
With multiple brands (more are likely to be added), and a global market, the sky's the limit for this group, in my view. It guides that growth is expected to slow to c.25% in future, as it gets bigger. Still remarkable.
EPS for FY 02/2020 is nudged up 4% today to 5.43p - giving a PER of 61 times - expensive. Or is it? Given that FY 02/2021 is starting shortly, then we should value it on a multiple of forecast 6.75p EPS, reducing the PER to 49 times. Still expensive? Less so, but also bear in mind that BOO tends to beat forecasts. Factor that in, and the PER might be nearer say 40 in reality. That could easily drop to say 25 or 30 times the following year. Which would make it good value for a company with such strong growth & global markets.
BOO is clearly a big long term winner. I'm sorely tempted to buy back in actually, because if we think forwards say 5-10 years, then how many more failed High Street brands will BOO have hoovered up & transformed online? International sales are only scratching the surface of large markets. This could be a £10-20bn mkt cap company on that type of timescale.
I'll wait for a pullback, and then buy back in at some point in 2020.
If only I'd kept my £4,000/pt spread bet running, when it was 25p per share, that would have paid for a few sundries! Oh well, I can add this one to my list of "if onlys"! Like selling my half a million Asos shares at 9p because the PER looked too high!!
After lunch & a power-nap, let's look at some more shares.
D4T4
Share price: 216.5p (up 5.6% today, at 15:09)
No. shares: 40.2m
Market cap: £87.0m
D4t4 Solutions Plc (AIM: D4T4), the AIM-listed data solutions provider...
I don't normally comment on contract announcements, unless they're material and trigger a change in forecasts. A revised broker note came through on my email this morning, which leaves forecasts unchanged for FY 03/2020.
What's interesting though, is that H1 was very poor, with an extreme H2 bias to profits expected. Normally I'd be very sceptical about that being achieved, but in this company's case it has delivered the big upsurge in H2 required, in a previous year (I forget exactly when).
The gist of Finncap's update note today seems to be saying that forecast earnings of 14.2p this FY 03/2020 are achievable, even though only H1 was only 2.0p, leaving 12.2p to do in H2. Contract renewals, new contract wins, and a healthy pipeline are said to underpin forecasts.
Directorspeak today is effectively a trading update, hence why it's worth mentioning here;
"We are delighted with these contract successes which provide valuable underpinning to both current year and future earnings potential for D4T4, being based on consumption as well as perpetual licence models, and a pleasing endorsement of version 9.0 of the Celebrus product we launched last year. We look forward to providing further updates as the year progresses."
The contract wins today sound impressive, although no figures are given;
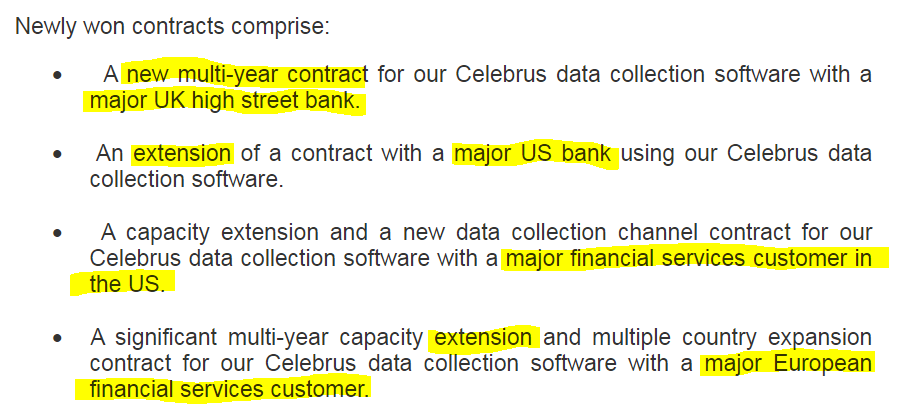
I like the sound of this. Although with forecasts being so H2-weighted, I could understand why investors would want to see the results actually come in on target, before chasing the share price up any higher.
My opinion - looks intriguing.
Boku Inc (LON:BOKU)
Share price: 78p (down 19% today, at 15:52)
No. shares: 255.1m
Market cap: £199.0m
Trading update (profit warning)
This one is a reader request.
Boku Inc (AIM: BOKU), the world's leading independent carrier commerce company, is pleased to provide the following unaudited trading update for the financial year ended 31 December 2019.
I can't make head nor tail of this trading update, nor the company itself. I've just spent a bit of time going through its last interim & full year accounts, and can't get my head around this at all.
Trying a different tack, the share price is down 19% today, so clearly this update has disappointed the market. There's an update note from Edison available, which is probably your best port of call if you're interested in this company.
For FY 12/2019, Stockopedia shows forecast revenues of $51.2m. Today's update says actual is slightly below, at $50.0m to $50.5m, up >42% on 2018. It mentions $3.2m of non-recurring revenue, but it's not clear from the update if forecasts included this or not. It's much better to provide a table of the breakdown of figures, rather than in text, which can be interpreted in different ways.
Ah, I think I've worked out what's going on here. Edison has massively reduced the future growth forecasts. Looking at its report from 11 Sep 2019, the old Edison forecasts are;
FY 12/2020: Revenues $68.1m EBITDA $20.1m
FY 12/2021: Revenues $78.7m EBITDA $27.7m
The latest Edison note today has these revised numbers;
FY 12/2020: Revenues $54.0m EBITDA $10.5m (down 48%)
FY 12/2021: Revenues $62.0m EBITDA $14.3m (down 48%)
As you can see, that's a near halving of forecast EBITDA between Sept 2019 and now. No wonder the share price has been weak.
My opinion - this is too complicated, and it looks as if the company doesn't have very good visibility of revenues, judging from the size of the forecast reductions today.
It seems to be an American tech company, so if it was any good, it would be on NASDAQ, surely?
Given the size of the forecast reductions, I'm surprised the share price isn't down more than 19%. Looking at the trading update, it doesn't seem to spell out that EBITDA forecasts are being slashed. Why not?
The share options charges look very high too.
Overall, I have to file this one in the too difficult tray. Today's big forecast reductions means I'm not interested in delving any deeper.
DFS Furniture (LON:DFS)
Share price: 280p (unchanged today, at market close)
No. shares: 212.3m
Market cap: £594.4m
DFS Furniture plc, the market leading retailer of living room and upholstered furniture in the United Kingdom today announces a trading update for the twenty-six week period to 29 December 2019.
It's a slightly below expectations trading update ("broadly in line")
I'm delighted to see that DFS has joined the growing number of companies which help investors by giving us the market expectations numbers in a footnote - bravo!
Based on low single digit revenue growth assumed in the second half we expect full year profit before tax and brand amortisation will be broadly in line with market expectations*.
*Consensus Profit Before Tax and Brand Amortisation forecast for the 52 weeks to 28 June 2020 of £51.2m on a pre IFRS 16 adjusted basis with a range of £50.0m to £53.6m. This is comparable to the £50.2m underlying pro forma result as reported for the 52 weeks to 30 June 2019.
More positive noises about current trading have probably saved the day;
Order intake momentum has strengthened more recently, and the key Winter Sale trading period has started satisfactorily.
My opinion - the absolutely diabolical balance sheet rules this out for me.
NTAV is hugely negative, at -£287.2m
Watkin Jones (LON:WJG)
Share price: 242p (unchanged today, at 15:04)
No. shares: 255.7m
Market cap: £618.8m
Watkin Jones plc (AIM:WJG), the UK's leading developer and manager of residential for rent, with a focus on the student accommodation and Build to Rent sectors, announces its annual results for the year ended 30 September 2019 ('FY19').
This is such an interesting property developer, with a great niche. It builds student accommodation blocks, and other "build to rent" accommodation (i.e. apartments, studio flats, etc), and its clever niche is that these are pre-sold to institutional investors. Therefore WJG doesn't need to tie up much of its own capital. Providing it project manages each development well (on time, on budget), the it has a low risk model and banks guaranteed profits when ownership transfers to the institutional investor(s) at the pre-agreed price.
I won't go into all the detail, as it's late now, but I recommend subscribers read this announcement, as it's full of interesting industry stats about student accommodation, etc.
Key numbers;
- Adj EPS of 16.7p is up 4.6% on prior year, and looks a beat against forecast of 16.3p - good
- Divis up nearly 10%, giving a yield of about 3.74% - better than cash in the bank!
- Net cash of £76.8m - good
- Build to Rent pipeline is building strongly
- Lucrative contracts to look after day-to-day management of some properties after they are built
Management are really good here, I remember meeting them a few years ago and being impressed. Although note that they have been selling down on a large scale (c. £65m Director sells in last 2 years) - no wonder they were wearing very expensive-looking suits when we met!
How to value it? This is the tricky bit. Normally I like to pay not much over NTAV. In this case though, NTAV is £162m, but the market cap is £618m - a very large premium.
On a PER basis, it's valued at around 14.5 - that sounds OK, but I don't think property developers should necessarily be valued on an earnings multiple, since large projects would dry up in a recession, and you'd be left with nothing potentially, or very little anyway, until the economic cycle improves. So this should probably be seen as an extremely cyclical share - so we should run for the hills if a serious recession loomed.
My opinion - I really like the niche that WJG operates in, and it reeks of good management.
It's difficult to value though. The pipeline looks good, and I could see this share doing well over the next few years, if we avoid a recession.
Games Workshop (LON:GAW) - this extraordinary phenomenon continues, up 9% to 6960p today. Well done to those who took the time to properly understand the business model, and the remarkable opportunity here.
I have to leave it there for today. Thank you very much for all the lovely thumbs ups! I'm a complete baby when it comes to this issue, but there we go, we all have human foibles!
See you tomorrow, where I'm braced for hopefully a positive update from Revolution Bars, one of my Big Four holdings. Fingers crossed!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Great report Paul...thank you and keep em coming.
Could you/ Graham have a look at Kainos a 100% gainer in the short term but concerned to understand whether tis could be a multibagger or an overhype.... any comments welcome
Worry not about the alcohol, some of the best creatives achieved their best when uninhibited!!
Great report today Paul. In particular your thoughts on buying in Bull and Bear markets. Your overview of the markets is extremely useful particularly to a novice like me who believes that the experts in this field know nothing! It would be good if you could give your views on the markets once a month.
Micke
Boku Inc (LON:BOKU) looks way overvalued even after today's sharp drop in share price. This is a business valued on growth, and it isn't growing. At all. Once you strip out the provision release in 2H19, even after adding back the revenue recognised in 1H which otherwise would have been due in 2H19, the 2H19 group revenue is only up 3% relative to 1H19 in both divisions. So Boku is not growing its payments revenue despite the 18% improvement in transaction volumes in 2H. The payments business might have very high gross margins, but I think their customers might also realise this and demand large volume discounts. What's a bit odd is that identity volumes are down to 112m in 2H19 from 141m in 1H19, but revenues are flat between half year periods. I don't understand that piece. But anyway something is telling me that they spent $25m on a shiny fast car (5x revenues) and it has subsequently crashed it into a ditch. The Edison forecasts of $54m for FY20 at +15% yoy look optimistic in the spotlight of 2H19 performance. I have no position on this. I was looking to buy in after today's statement. I won't be now. It won't go bust, so it's not a short either. It'll just painfully trade down in fits and starts, and possibly get injections of optimism from mgmt statements, perhaps even another acquisition. DYOR.
Boohoo (LON:BOO) topline is great but I can't help but think it is at the expense of their bottom line. Margins are quite weak, maybe it is due to their return rate?
The most impressive thing is that they have cracked the US but I do favour £Fevertree at current valuations considering their margins are about 3 times Boohoo and their ability to leverage operations is much easier. I would also prefer Team17 for the same reasons.
But Boohoo (LON:BOO) is still growing around 35% per year, Fevertree Drinks (LON:FEVR) is virtually ex growth if you look at the forecasts. I don't think you can compare soft drink margins to clothing. Fevertree Drinks (LON:FEVR) was a great share in be in a few years but I sold out when growth slowed.
thankyou paul. You have outdone yourself today!
What a mamoth and awesome SCVR. Thank you.
Thank you Paul. Would have liked a little more on Games Workshop as I have shares in that but understand getting a large company. I hope you are enjoying a well deserved large G&T this evening.
Ooh no G+T, it's Dry January!
Actually I did want to make another point about Games Workshop (LON:GAW) - namely that this is a Peter Lynch style share, where the key skill for an investor was not to crunch the numbers, but rather to understand the niche that it operates in, and to know that its Warhammer franchise was developing into a seriously lucrative thing.
People who knew that, could have absolutely cleaned up on the shares, irrespective of whether they were financially literate or not. In fact, being able to crunch the numbers can be a disadvantage, as you worry too much about valuation, and sell too early!
Regards, Paul.
Completely agree. Tesla being a great example.
Awesome report today Paul! I was definitely the first person to give you the thumbs up today as I saw it at shortly after 6am as I was preparing for a day's wage slavery and thought ' **** me!', I mean 'Wow, that's dedication; even Graham doesn't normally post the placeholder that early'.
I salute you also for your Dry January discipline - which sadly I have been unable to emulate and thus will have absolutely no complaints if the early February ones have more of an afternoon bias, timing-wise. Shine on!
Gostevie
Gostevie/Paul
I salute you also for your Dry January discipline - which sadly I have been unable to emulate and thus will have absolutely no complaints if the early February ones have more of an afternoon bias, timing-wise. Shine on
Slightly off-topic this, and I'm not sure whether this is bending the 'rules' of a Dry January, but there are some excellent alcohol-free beers out there these days. The market has moved on somewhat since the days of Barbican Lager, if any of you can remember that.
I enjoy the taste of beer but, particularly as I get older, I don't like some of the side-effects of alcohol. I've pretty much ditched the full-strength stuff permanently now, as have other people I know. Great taste, fewer calories, no social stigma attached to not drinking 'real beer' and no hangover - is this a growth market for brewers?
Sadly, as a holder of Boku Inc (LON:BOKU) today, I've ditched all that low-alcohol nonsense. Pass me another, someone (hic).
As for today's report, if I could give it more than one thumbs up, I would do. Awesome report Paul.
Hi Phoenix,
If you get an opportunity try Adnams "Solestar". Similar to you I like the taste of ale but as I get older can't get on with the various side effects! It is 0.9% and tastes just like the real stuff.
You can meet Watkin Jones (LON:WJG) at Equity Development's next forum if you're interested in ascertaining the quality of management for yourself. https://equitydevelopment.co.uk/2019/11/26/meet-tatton-upgs-and-watkin-jones-investor-forum-february-2020/
Astonishingly detailed report today Paul, well done. Being amazingly thick, I have no idea how to give you a thumbs up (I am 65 after all).
Pity you don’t comment on CLIG, they are amongst the clearest reporters in town, in my opinion.
Another good statement from them today....I have a decent sized holding. One for the boring investors, like me.
I completely agree on City of London Investment (LON:CLIG) Greyinvestor. I was actually thinking of selling, having held for several years, because of the modest growth prospects compared to other opportunities. Today's update reminded me of just what a quality outfit this is. Crystal clear, transparent, honest communications and a sensible strategy - not things to be taken for granted. I changed my mind and will continue to hold.
I hold City Of London Investment (LON:CLIG) too, they have done well for me just by re-investing the dividends over a period of time. I'm not sure if you have seen Maynard Paton's coverage of CLIG through his investment blog- it is extremely good.
Thanks Paul for your comment on £BOO. I am long on it and one of the lucky few that bought in after the profit warning following the IPO. It's my only multi-bagger in the 5-6 years I've been investing - hopefully not the last :-)
Hi Paul,
Its ridiculous that some people give a thumbs down before there is even anything added to the placeholder. Its almost like trolling, but fortunately we have less of them on this site than many. I say Trolls, but we know they are also knobs. You know who you are!!
Keep up the good work. The vast majority of us appreciate the effort.
They may be using a phone where it's hard to click up or down accurately. I'd prefer to assume carelessness rather than malice.
Science in Sport (LON:SIS) 24% up Y-o-Y but inline with expectation. Seems they are moving closer to breakeven and it will be possible next year. What are people's thoughts on them?
Science In Sport (LON:SIS) great gels, useless business. Lots of elite sportspeople use them but I'm not sure how many pay for them. They presented at Mello so there may be a recording
I do like PHD Protein and I even buy it. They took on a supply director from Myprotein which is the big player in the market and added a new CFO and another director. I am seeing a turnaround forming but held off so far.
Maybe if the thumbs up/down were not anonymous, people make think twice before clicking and potentially annoying on purpose unless they have a valid reason at which point the contributor, can engage in a sensible discussion with them.
Come on Ed, make it so.
Then it would turn into a big squabbling match like some of the bulletin boards. I think a no red thumbs option here would be best.
The market has responded positively to the results from Rosslyn Data Technologies (LON:RDT) this morning. It's on my watch list even though it's a "sucker stock". TMV are positive about the order flow and the client base, but the balance sheet is very weak. I'd welcome others' views.
Thanks for highlighting Rosslyn Data Technologies (LON:RDT) It looks to be at the point where it will start to generate cash at the operating level, which could be a catalyst. However, it will need more funding, which will probably keep a lid on the share price.
I noticed the following from them:
"The impact of Brexit, although uncertain, is likely to create a significant jump in demand for the Langdon data services in the coming months and years as companies become required to report to HMRC for imports and exports with the EU. We are excited by its prospects and are implementing plans to benefit from this potential upside."
I think that's the first time I've seen a business get excited about Brexit. At least someone will benefit from the additional admin.
Yes I agree about the 1pm email deadline, being arbitrary. I much prefer a considered approach, so Paul do take your time with the daily update. I would be happy if the finish target was 5pm each day.
Paul ,
You do a fantastic job in providing us with your reports not to mention your general thoughts ... don't let negative people get you down there are many people here who value what you do I am certainly one of them .
I'm wondering if that 1pm email deadline still has any importance - I unsubscribed from it years ago as I just leave a browser tab open on the discussion stream and check that when time allows. For me, the quality of the report is much more important than its timing. Don't be discouraged, Paul - you do an amazing job!
That's an important point. The 1pm deadline has zero importance to me.
What counts here is quality of thinking, not a rushed response to a deadline. I don't care if the report is done in the evening, or doesn't appear at all on some days if there is nothing much to say.
Good to chat about ticks
Anyones thought on the announcement from Tp (LON:TPG) today? Been keeping an eye on them for the last month, not bought shares yet but seriously considering it. Will wait for the share price to settle out after the announcement.
Tp (LON:TPG) yes, I bought the other day at 7.3p - what I like is that the order book is strong and several new contracts announced recently. Sitting on a fwd PE of 11 but given the increases in revenue it wouldn't surprise me to see upgrades this year. Forecasts started the year at 0.2p and ended the year at almost 0.6p so the trajectory is clearly well in the right direction. Trades at a bit of a discount to other defence peers so could easily pop higher I think without any eps upgrades to a PE of 14 or 15. Market cap is £58m but has £9m of cash (and that's after an acquisition). The order book was £79m in Sep so given announcements I expect it to be higher still leading to good visibility of earnings. They reckon they have £700m in opportunities so you're looking at a 12% hit rate to maintain order book. Presume they are better than 1 in 8 win rate on pitches!!
payables are slightly higher than receivables but only by £2m so factoring in the £9m cash there's no problem there.
Only thing I don't like is lack of dividend. That breaks one of my "guidelines" - doesn't kill an investment idea for me but is preferred.
On a technical level it has also just broken out of its range. Has traded 6.5 - 7.5p for a long while so I think this bodes very well for a re-rate.
EDIT - I also just noticed that Robbie Burns (NT) also likes them.
Yes I see Robbie Burns has bought some TP (LON:TPG) but a very small holding for him around £650.
Some interesting comments on Card Factory (LON:CARD) which he is shorting, reckons it will go bust within 2 years.
Just to clarify on TP (LON:TPG) /Mr Burns, the £650 was a top-up - according to his s/s he "bought" £3,250 in September on his original look into.
Hold a few and pondering whether to sell into strength or wait for the full year TU which should be this week and should be good.
Phil
TP (LON:TPG) I see, thanks, I did not go that far back, it did seem a very small buy. It's not a company I know anything about I may do some more research.
Also worth noting with RB that he reports seemingly small trades on his site but actually trades in his own real account in much larger size, so wouldn't read anything into trade sizes unless he says specifically that he is taking a very small position. As an example he recently really liked Kape and on his site bought 5k or so but said in reality told readers he had bought over 50k worth for himself! Just worth noting
Thanks for that information I did not realise that, I did wonder about his Kape Technologies (LON:KAPE) holding which did not seem to tie up with his comments. He made a killing there.
I am a long term holder of Tp (LON:TPG) since before the open offer in 2017 and have accumulated over the last year. IMHO, the Sapienza acquisition is a major step forwards, opening a host of new avenues for them, with good cross-selling opportunities too.
I don't see the lack of dividend as a negative point at the moment, as they have been going through an acquisitive phase at the moment - Tp (LON:TPG) did not exist in its current form only a few years ago.
The 52wk+ ATH is great news and, as you say, a break above this ceiling should be very positive.
Boku Inc (LON:BOKU) if you get chance Paul. Trading update this morning looks OK Rev up, profit up, but shares tanked (down 25%). I must be missing something.
Stop press. Just read other comment, which partially explain. Still seems a big drop for essentially improved performance (but I know missing what you said you would deliver is always recieved badly, but 25% wiped of Value?).
In addition to that comment the next two years have been downgraded in a research note.
thanks for the input. I bought, with a stop just below bottom price. So far so good with the bounce back.
The TechMarketView (TMV) free daily email says the market reacted badly to the revenues in the newly acquired identity division slowing in H2 and the forecast full year loss in this division. However, TMV points out that the rest of Boku Inc (LON:BOKU) represents 87% of the business and that this core business remains strong.
Thanks for the input
Stocko gives forecast op cash flow for Boku Inc (LON:BOKU) as break-even, so net ebitda of $10m looks better than expected, not worse. The identity ebitda loss was still an improvement on the previous year, and they seem to be expensing spend on "building out" the product. Unless there is more to it, a 15% fall in the share price looks a bit mean. On the other hand, EV/EBITDA looks to be about 30, so the shares were probably due a fall whatever the news.
I must admit that I don’t know much about Boku Inc (LON:BOKU) but have just read a research report from Edison (on Research Tree). The numbers this year are only broadly in-line because of a $3.2m positive exceptional (write back of a provision). Also Edison is roughly halving its EPS forecasts for 2020 and 2021 due to an approx 15% cut in its revenue forecasts. Has 108p sum-of-parts valuation,.
Flowtech Fluidpower (LON:FLO) issued a profit warning this morning. The detailed commentary seems to show that the directors are addressing the costs and remain confident.
I would welcome Paul's opinion on whether this apperrs to be a short term or a more serious problem.
Paul has finished his Flowtech Fluidpower (LON:FLO) commentary now. I would share his caution, though I must admit this was on my watch list and has hit my target price. Locally I deal with a business in the same field as Flowtech Fluidpower (LON:FLO) . They have reported none of the headwinds reported here. My guess is $FLO have acquired too much, too quickly and at too higher price. They were perhaps too indiscriminate in their expansion.
I am new to this site I like reading the comments.Is it ok to ask a question here?
I am interested to know why BOKU has released what seems to be an upbeat update yet the shares have crashed nearly a third this morning.What am I missing?
In September, Jon Prideaux, Chief Executive of Boku Inc, commented: "Our overall guidance for the year was for $52 million of revenue, gross margins of 93% in Payments and 40% in Identity leading to adjusted EBITDA growth of between 45% and 50%. Overall revenue at $23.5 million and Adjusted EBITDA of $4.3 million represent 45% and 47% respectively of our full year targets. There's no question that we need a good second half in order to deliver; we anticipate one and thus leave our guidance unchanged."
So this is a miss on the guidance for Boku Inc (LON:BOKU)
Ok thank you.
Good morning Paul
Just a request for you to look at two 'oldies but goldies'
Boohoo (LON:BOO) trading update- another 'shoot the lights out' trading update with upgraded guidance and stunning results
Games Workshop (LON:GAW) H1 Results- and we're on our way to the Warhammer Event Horizon (apologies to Douglas Adams) where all shops become Games Workshop shops. Basic eps up 44%
Serabi Gold (LON:SRB) I took a look at this since it appeared on a number of competition entries. It has a favourable stock rank. For a gold miner it is achieving production guidance and forecasting a rise for 2020 due to efficiency improvements. Subject to approvals over 18 months production could double. This needs financing but the numbers aren't to worrying and shouldn't be difficult given how quickly it will bring increases to production. The production profile provides some gold price protection. Todays trading update is supportive but interested if anyone has any negative feedback out there.
When the report gets 17 thumbs up and 3 down before anything is written, surely the system is pointless?
I would disagree. I think what it shows is the respect and gratitude felt by the majority of this community for the phenomenal levels of work, insight, honesty and humour provided by Paul and Graham across thousands of SCVRs. The early thumbs up are a recognition of what has gone before and encouragement for the slog ahead. I suspect that if doug2500 wrote "Good morning it's doug2500 here with nothing positive to contribute" there would be far fewer thumbs up. By the way, thanks for reminding me to give a thumbs up to Paul this morning.
It's a valid point John, but some people are giving thumbs down before anything is written. What's the point in that? How de-motivating must that be?
FWIW I think the SCVR is excellent and I don't even care when odd days are missed or brief, I'm not going to ever vote down because all the good ones outweigh any blips.
I suspect Paul and Graham get more validation from quality discussion and feedback here than simple thumbs up, and without the negative effects of thumbs down.
Hi Doug. I can only imagine that any thumbs down are from people who don't like to see thumbs up before the report is written. Perhaps they don't share my view that it's a recognition and an encouragement. As to whether Paul appreciates the thumbs up as feedback, he has said so many times on this forum and that's good enough for me. To answer your question "What's the point in that?", I suppose the best answer would be that everybody has an opinion and if the net result is 100+ thumbs up, then that communicates to Paul that the majority of readers appreciate and value his contributions. If the net total was a number of thumbs down then presumably he'd stop doing the report and we'd all be the poorer for it.
Hi doug2500,
It's a valid point John, but some people are giving thumbs down before anything is written. What's the point in that? How de-motivating must that be?
It's incredibly de-motivating, and upsets me immensely when people hit the thumbs down button.
I'm paid to spend 2-3 hours on these reports, and most days I actually spend about 8 hours on them, because I want to do a good job for the subscribers.
I've got to read, understand, think about, and then write about lots of companies. That includes trying to find broker notes, reading up on previous RNSs on each company, that all takes time. If you want quality content, without mistakes in it, then I need some time in the morning to gradually write it up.
I'm busting a gut to make sure the reports are done, or nearly done, by the time the 1pm email goes out, and it's really helpful when subscribers are supportive. The thumbs downers are doing immense damage, because I'm an emotional person and it upsets me immensely to see thumbs downs. I'm looking forward to switching to the new site, where they will be invisible to me.
Regards, Paul.
Hi Paul,
Looking forward to your thoughts on what is an interesting list for me.
Regarding thumbs up/down. I access via a desktop with a nice large screen so no problem for me but I can imagine that it's very easy to hit the wrong thumb if viewing on a 'phone (maybe even whilst travelling on a train?). I did try reading SCVR once on my phone and my finger covered both thumbs so I gave up.
Don't worry about it - you can tell by the number of reads the value placed on your efforts.
Appreciate the great job - certainly if ever I had a question about maintaining my subscription, your reporting would sway me to stay.
I just started having a look at Boku Inc (LON:BOKU) in depth last week (very bullish broker commentary - think Peel Hunt - via III), so interested to hear if the sell-off this morning is an opportunity in your view? I know that Stocko rates it as a sucker stock, but ...
I for one much appreciate your work and insight. It's the man reason I subscribe to Stockopedia.
Reports really appreciated by me. Keep up the great work please.
I respect the work that goes in to these reports and value them highly. But shouldn't the thumbs up be related to the quality of the report. 22 thumbs up for saying good morning! I think the value placed on the reports is shown by the fact that at 0930 already over 1000 people have looked at it to see what it contains. Some might be a little disappointed in fact to see nothing there yet. If todays report turns out to be particularly insightful, and even higher quality than the norm, how do you then acknowledge that, if you have already given it a thumbs up for saying nothing?
Worth noting this morning the gambling commission is banning the use of credit cards with online gamblers. According to their data around maybe less than 5% of transactions use a credit card. Presumably the impact on SCVR favourite Best Of The Best (LON:BOTB) will be very limited.
On a separate note is anyone aware of a planned post Christmas trading update from Sosandar (LON:SOS)? There was one last year on the 10th.
Yes I was wondering about SOS so I rang them. Receptionist didn't understand and said no-one available , so asked to send e-mail, which I did. Still waiting for a reply. Don't think day to day investor relations their strong point, which has me thinking.
Boohoo (LON:BOO)
Not a holder but an interested (and probably a tad jealous) bystander.
I note their upper guidance for FY20 is for +42% Year-on-Year revenue growth.
The upper end of this forecast implies +34% YOY revenue change in the last 2 months of the year, clearly too low.
I recall them under-selling themselves last year at this time, and then shooting past their forecasts at Year End
ie the +42% forecast published today is clearly incorrect, making is almost impossible for them to miss it
Perhaps more realistically the YOY growth for the last 2 periods will remain constant @ c44%, bringing full year YOY to +44%.
In other observations:
a) I note additional revenues starting to come through from MP/KM/Coast (c £9m for the last 4 periods)
b) here is a table of Gross Margins for any interested.
Cheers
A
Hi abtan, some of your figures don't add up....
Example 1
In table 1, using forecast last 2 months of 87M gives FY of 1217M,
but in table 2, using forecast last 2 months of 193M gives FY of 1231M,
The difference between 87 and 193 is 106, so the FY difference should be 106M, but is only 14M!
Example 2
H2 should be (P7-P10) + (P11-P12), but isn't in table 1, but is in table 2
I'm assuming P6-P10 is a typo and should be P7-P10.
Actually, i think if you fix H2 in table 1 that will fix the FY for table 1 and probably correct the percentages....
Regards
Martin
Boohoo (LON:BOO)
Thanks Martin, yes, looked like an error in my table somewhere. Sorry about that.
I've updated the table, though left the commentary the same, as it still shows Boohoo (LON:BOO) playing the same trick as this time last year, when they implied a material YOY slowdown in the last 2 months of the year just to hit the upper end of forecast.
In fact, I've just found my note from last year:
"- Previously guided revenue growth of 19%-32% for P11-P12. Actual was 50%. Why guide so low so close to the end of the year?"
Yes the figures make much more sense now.
Well done for picking up on their "trick"! Basically means they can't miss on their full year figures.
I love that all that is written is "Good morning, it's Paul here with Tuesday's SCVR." Someone has given this an uptick. That has to be a huge vote of confidence Paul, so I have doubled the account in anticipation!
I love that all that is written is "Good morning, it's Paul here with Tuesday's SCVR." Someone has given this an uptick. That has to be a huge vote of confidence Paul, so I have doubled the account in anticipation!
The purpose of the placeholder article, is so that readers can start adding comments from 7am, whilst I'm reading & digesting, then writing up sections for the main report. Maybe the thumbs up are from readers who are pleased that I remembered to put up the placeholder lol!
I see there are 3 thumbs down this morning already, at 09:52 - this pisses me off immensely, and makes me less likely to want to put in the work to produce a decent report. Can the tiny minority of idiots please stop doing this.
“I see there are 3 thumbs down this morning already, at 09:52 - this pisses me off immensely, and makes me less likely....”
Completely agree Paul, thumbs down are pretty much idiotic at any time. Please discuss with Ed the possibility of removing the thumbs up/down system or at least the thumbs down ASAP (though I know how busy you all are).
You cannot “not recommended” a comment in the FT or “dislike” a tweet on Twitter so why on Stockopedia. It is the only bit of Stockopeda I really dislike (sorry no pun intended).
If you disagree with something that you or a commenter writes this should be through a well reasoned comment in the comments section not some anonymous meaningless thumbs down.
In this instance I very much hope my comment gets 100’s of thumbs up so that something is done about it!!
Very interesting writing on profit warnings.
PS We, the subscriber, cannot see that you got 3 thumbs down just the net “score”.
purpleski - should you want to know, you can hovver your cursor over the net "score" and it tells you how many positive votes there have been. Calculate from that how may down thumbs.
But, as I say, quite possible that some or all of those are caused by fat thumb syndrome.
Thx Laughton.
I invariably read on iPhone/iPad so I don’t think I can do that?
Still hope the thumbs down bit is done away with though!!
My morning smallcap tweet: McSlide FY to subside
Telit Communications (LON:TCM) Osirium Technologies (LON:OSI) Flowtech Fluidpower (LON:FLO) Boku Inc (LON:BOKU) McBride (LON:MCB), Parity (LON:PTY), Low & Bonar (LON:LWB), Eden Research (LON:EDEN), Science in Sport (LON:SIS), Gateley Holdings (LON:GTLY), Watkin Jones (LON:WJG), Sigma Capital (LON:SGM)
Telit Communications (TCM) FY rev $391m cf F/C $370m. Rev-cont $381m up 8%. 'Profit in cash' is expected to be in line with the Board's expectations. I'm short.
Osirium Technologies (OSI) guides FY rev at least £1.1m. Bookings at least £1.8m, slightly ahead of market expectations. F/C rev £1.32m so looks like a miss.
Flowtech Fluidpower (FLO) guides FY rev £112.4m with organic rev down 10%. F/C is £115m. Guides U/L pretax at least £9m. Blames tough market. "Expectations for FY20 have been reviewed by the Board and whilst it is confident that investments made in 2019 will lead to market outperformance, current conditions are such that achieving organic growth may prove difficult, in particular in the first half of FY20. It is therefore possible that the positive impact of the cost saving initiatives which have now been formulated, and which will shortly be implemented, will be offset, at least in part, by market conditions remaining challenging."
Boku (BOKU) guides FY rev $50m to $50.5m. F/C is $51.2m. Adj EBITDA $10-$10.5m up 59%. I have no F/C for that. Upbeat language.
McBride (MCB) H1 trading: rev-cont down 4%, Household down 1.4%. Guides FY Household rev down 2%. Guides FY adj pretax 15% lower than current market expectations of £22.1m.
In line: Parity (LON:PTY) Low & Bonar (LON:LWB) Eden Research (LON:EDEN) Science in Sport (LON:SIS) Gateley Holdings (LON:GTLY) Watkin Jones (LON:WJG) Sigma Capital (LON:SGM)