Small Cap Value Report (Tue 15 Jan 2019) - FLYB, FDEV, EHG, GYM, CALL, GAW, BOO, KAPE, DTY

Good morning!
I am back from a fine holiday in Athens - should have gone there a long time ago!
The economy and general state of economic progress did not seem to be doing particularly well on the ground, although that did not detract from a fantastic experience of Greek culture, cuisine, architecture and history. Did I mention the food?
The experience of Greece within the EU has been, let’s be diplomatic, somewhat mixed. And today is apparently going to be the voting day for MPs when it comes to Mrs May’s EU Withdrawal Agreement. It is natural that questions of politics will be on our minds.
This being the SCVR, I will be covering company news first, referring to macro developments only if they have a major impact on the markets.
Best,
Graham
Today we are covering:
- Flybe (LON:FLYB)
- Frontier Developments (LON:FDEV)
- Elegant Hotels (LON:EHG)
- GYM (LON:GYM)
- Cloudcall (LON:CALL) (by Paul Scott)
- Games Workshop (LON:GAW)
- Boohoo (LON:BOO)
- Kape Technologies (LON:KAPE)
- Dignity (LON:DTY)
Flybe (LON:FLYB)
- Share price: 2.6p (-37%)
- No. of shares: 217 million
- Market cap: £6 million
This looks like very bad news for those who were hoping for an improved offer for Flybe.
The consortium, Connect Airways (Virgin Atlantic/Stobart), is lending Flybe's main operating company £20 million, under revised conditions. Flybe wasn't able to satisfy the original conditions.
£10 million of the funds will be released today - implying that it is needed to keep the lights on?
An agreed sale of Flybe's main trading companies to the consortium for £2.8 million will proceed without shareholder approval, since Flybe now has a standard listing on the LSE, rather than a premium listing.
The rationale for switching to the standard listing was presented as follows in Flybe's interim report last year:
This would have the benefit of allowing the Company greater flexibility when considering divestments, particularly to recycle cash, as the current low market capitalisation places restraints and complexity on such disposals for companies with a Premium listing.
A standard listing does offer greater flexibility, but I wonder if the lack of a shareholder vote requirement might have been of greater concern than any issues around recycling cash?
Flybe's recommendation of the offer, published on Jan 11, stated that it was "an attractive option for Flybe's employees, pension scheme members and creditors" - no mention of shareholders.
Today's deals are described as "preserving the interests of [Flybe's] stakeholders, customers, employees, partners and pension members".
If I'm reading it correctly, shareholders will still end up with 1p if the Recommended Offer is accepted by shareholders.
If it's not accepted, then shareholders will have a PLC with c. £2.8 million in cash and nothing else (1.3p/share).
I could be reading it wrong, that's just my interpretation.
It looks like it's over, either way. FLYB shareholders will no longer own an airline.
Frontier Developments (LON:FDEV)
- Share price: 911p (unch.)
- No. of shares: 39 million
- Market cap: £353 million
Notice of results and trading update
Plaudits must go to those who wrote this update. We get transparent expectations:
Frontier expects to report revenue of approximately £64 million for the period compared to £19 million recorded in the interim results last year.
Based on trading performance in the first six months of the financial year, combined with sales over the Christmas holiday period, the Board remain comfortable with the analyst revenue projections of £75 million to £88 million for FY19 (the year ending 31 May 2019) and anticipate that revenue should exceed the mid-point of this range.
Frontier is a video game developer and publisher with three franchises under its belt.
The latest one, Jurassic World Evolution (JWE), is by far its biggest achievement to date, but all three continue to make sales.
Note the heavy revenue weighting to H1: £64 million in H1 sales, versus £75 million to £88 million for the year as a whole. JWE was launched around the beginning of H1.
Frontier's fourth franchise is in the works, release targeted at some point in FY 2020. I suppose it's better to be vague about this in public, rather than committing to a date which can't be met.
I like this company but I don't know how to predict the success of its future releases and therefore feel unable to value it. I'll be more interested in the shares when the company is more diversified across different franchises and when the share price looks less optimistic.
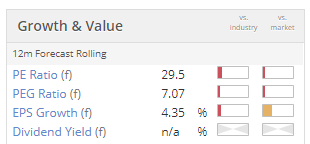
For what it's worth, though, the forecast P/E ratio shown above might be much too high - if the fourth franchise is released over the next 12 months and is a hit, then earnings might turn out much better than this P/E ratio implies.
As a snippet of industry news for GAME Digital (LON:GMD) investors, I would note that "the majority of [JWE] unit sales on all three platforms (PC, PlayStation 4 and Xbox One) are from digital sales", as physical discs now account for the minority of sales.
Elegant Hotels (LON:EHG)
- Share price: 70p (+3%)
- No. of shares: 89 million
- Market cap: £62 million
Elegant Hotels Group plc ("Elegant Hotels" or the "Company" or the "Group"), the owner and operator of seven upscale freehold hotels and a beachfront restaurant on the island of Barbados, today announces its audited results for the year ended 30 September 2018.
Let's sort through the highlights:
- average daily rate up 2%.
- RevPAR down slightly, suggesting that occupancy is down (RevPAR = avg daily rate * occupancy rate).
- Occupancy is indeed down, 62.3% vs. 63.9%. The company says this is due to its acquired hotel missing the peak tourist season. Without that, occupancy was "largely consistent" (down slightly?) vs. the prior year.
Outlook
Trading is in line with market expectations. Caution over macro conditions and UK consumer discretionary spend.
My opinion
The results look reasonable, and the company's adjustments to the numbers aren't too heavy. The only exceptional costs were $0.8 million of pre-opening costs for its new hotel and some restructuring costs.
I'm also very pleased and impressed that the company has taken the following initiative:
From FY 2018 onwards, the Group no longer excludes non-exceptional share-based payment charges from these measures in line with best practice.
Bravo!
Kudos to Elegant (or should I say κῦδος) for recognising that share-based payments are not exceptional, but are instead a matter of routine for many companies.
This should be a lesson for others, who present adjusted profit measures excluding share-based payments - they aren't exceptional, so don't mislead investors by showing us numbers which don't count them.
Anyway, let's drill into the profit figures a little bit:
- adjusted EBITDA $19.7 million. EBITDA margin the same as last year.
- operating profit $14.2 million (slight reduction in operating profit margin to 22.6%).
- PBT $10.6 million, down compared to last year but up 5.5% on an adjusted basis.
Overall, I view this company as offering decent prospects to investors at the current share price.
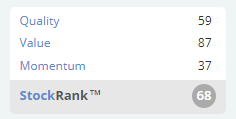
The StockRank agrees:
The company thinks that its net asset value is c. 153p/share, based on GBPUSD at 1.30. This is based on the most recent valuation of the property portfolio by CBRE, and after deducting net debt of $72 million. This property valuation is not reflected on EHG's balance sheet.
I tend not to buy shares in hotel groups, personally, but this one looks more interesting than most. Most of its customers are from the UK - a recovery in GBP will give a big boost to them and therefore to EHG.
GYM (LON:GYM)
- Share price: 211p (-6%)
- No. of shares: 138 million
- Market cap: £291 million
As a prospective investor in GYM (LON:GYM), I'm excited to see that its share price has fallen back - although existing shareholders may have a different emotion!
Let's get up to speed with progress at this gym roll-out that uses the the no-contract, 24/7, low-cost model:
- 158 gyms (up from 128)
- 24.2% market share in the low-cost gym segment (2017: 22.4%)
- revenue misses expectations due to later openings than planned and more weeks of closure due to rebranding of acquired gyms
- 15 to 20 new gyms planned for 2019
It looks to me as if most of GYM's growth in 2018 came from growth in the low-cost segment as a whole, rather than coming from GYM's market share growth within that segement.
Assuming that the company is not planning to reduce its market share, the company's plans for 2019 bring me to the conclusion that the low-cost gym segment is forecast to grow at a slightly slower pace - c. 10% maybe?
Outlook: full year adjusted EBITDA for 2018 to be £37 million. Not entirely helpful, since prior expectations aren't given and adjusted EBITDA is not the only metric that counts. If I have time, I will listen to the conference call later, to see if more useful comments were made.
My opinion
Worthy of further research and at an interesting entry point in my view, given expectations for a significant increase in net income in 2019/2020. If you believe that the low-cost gym segment is set to keep growing at a healthy clip over the medium-term, then it could be very attractive.
This section by Paul Scott.
Cloudcall (LON:CALL)
- Share price: 95p (+4%)
- No. of shares: 24 million
- Market cap: £23 million
(Please note that Paul has a long position in CALL)
Morning all!
I like this morning's update from £CALL (I have an existing long position, held for many years now).
It's been a good example of a jam tomorrow company which has taken far longer, and spent far more money (through repeated placings) to achieve its business plan. That's why the market cap is so bombed out, despite the company operating in a high gross margin, recurring revenue, interesting tech niche.
However, I think the company could now be near that lovely tipping point, where market sentiment suddenly changes from glass half empty, to glass half full.
Growth today is good, and accelerating in both Q3 and Q4, with positive outlook comments too. The company said that sales would accelerate in H2, due to its increase in overheads (primarily developing better product features, and S&M). Sure enough, sales have accelerated in H2 as promised, so mgt credibility should begin to improve.
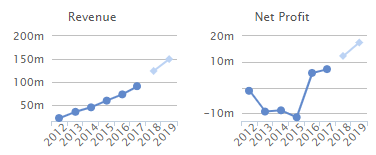
Cenkos forecast from Sep 2018 (on Research Tree) shows losses being greatly reduced in 2019, from £3.7m in 2018, to £0.7m in 2019), which is driven by a strong increase in gross profit - remember there's huge operational gearing here, as organic revenue growth is strong, and it's achieving an 80% gross margin. So when profits do come, they could really soar after a few years. This is what makes this share so interesting, in my view.
Looking at the Cenkos figures, they show no increase in admin costs in 2019 over 2018, which strikes me as unrealistic. Since costs were cranked up during 2018, then I would expect the total in 2019 to be higher - as it's a full year of increased costs, plus wage inflation, etc.
Therefore, my view is that the Cenkos profit forecast is probably a bit optimistic, but I reckon the company is on track to get fairly close. Again, that's on my list of things to ask at the CMD.
What about cash? It's looking tight again - with only £0.9m remaining at end 2018. There is a £1.85m undrawn bank facility, but in the past the company has preferred to do a top-up placing, rather than going overdrawn. I suspect that might happen again this time. Maybe that's the underlying reason for this Thursday's capital markets day? To generate interest & increase the share price, ahead of another placing? I'll be attending the CMD this week, so will ask that question!
It only needs a top-up, so I reckon a placing of £1-2m would push it over the line, to breakeven & then profit. That's not really a big deal, as only 5-10% dilution, and with positive performance reported today, and a stronger outlook than we've had for a while, I think a small placing could be done fairly easily, if needed, and probably at only a modest discount. So for me, the low cash position is not a deal-breaker. Placings are only a problem when they're (a) big, and (b) from a weak position, e.g. after a profit warning. Neither is the case here.
My opinion - it's been a painful journey, but I think things are coming good here.
I'll report back if anything interesting comes from the CMD later this week.
Back to Graham.
Games Workshop (LON:GAW)
- Share price: £31.85p (+1%)
- No. of shares: 32.5 million
- Market cap: £1,035 million
Another very good six months by Games Workshop, the creator of Warhammer miniatures.
The only element I'm questioning is the gross margin, which fell from 72% to 67% (still an extraordinarily high level, it must be said).
The report concedes that the company could have done better on gross margin. Operationally, it is a time of transition:
As we move to complete a series of major investment projects, our gross margin and stock levels are not currently where we'd like them to be. We're looking forward to our new Nottingham factory and ERP projects completing, allowing us to fully optimise our Nottingham site. From there, we'll begin to upgrade our warehousing capacity in both Memphis and Nottingham. These further investments will help us maintain our current volumes, increase efficiencies, and give us good scope for sales growth in the future.
The quarterly dividend is 25p, a reduction from the most recently paid 30p.
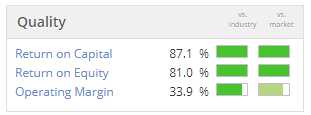
Return on capital employed is tremendous at 96%, down from 119% a year ago.
Cash levels and overall efficiency were affected by a negative working capital movement of £12 million: inventories and receivables built up, while trade payables were reduced. It's perhaps a slight worry, but management have acknowledged it and are keenly aware.
I am a potential purchaser of GAW, though still waiting for that moment when its valuation and my preparation coincide with an opportunity. A unique company with super metrics:
Boohoo (LON:BOO)
- Share price: 177p (-9%)
- No. of shares: 1163 million
- Market cap: £2,058 million
Curious to see the share price fall when the company itself is happy with strong growth over the last four months of 2018.
Group revenue growth expectations for the financial year ending in February have been upgraded to 43%-45%, from the previous range of 38%-43%.
- revenue +43% at constant FX
- gross margin up 170bps to 54.2%
The disparity between bohoo and PrettyLittleThing (PLT) has perhaps left a sour taste in shareholders' mouths, since BOO shareholders only own 66% of PLT:
- boohoo year-to-date revenue +13% at constant FX
- PLT year-to-date revenue +115% at constant FX
Boohoo was founded by Kamani and Kane in 2006, and Kamani then founded PrettyLittleThing in 2012. Amazingly, PLT is now almost the same size as boohoo.
I suppose a concern might be that Kamani can always make a new online brand and, given enough marketing spend, create something that is again around this same size, which BOO shareholders would not own, and would cannibalise the existing brands?
A more obvious concern is that boohoo has reached a natural limit and won't achieve very high growth levels again. If PLT growth were to slow too, as it surpasses boohoo in size, then the growth story would be over.
I'm just thinking out loud here - it's not something I want to get involved with, so I'll leave it up to others to analyse in greater detail. Perhaps I'm being too cautious, and allowing the share price movement to lead my thoughts.
Kape Technologies (LON:KAPE)
- Share price: 106p (-3.6%)
- No. of shares: 142 million
- Market cap: £151 million
I have run out of time but I note that this cyber security company is guiding for adjusted EBITDA "slightly above market consensus" at $10.4 million.
It made an important divestment and has also been active on the acquisition trail. There is too much for me to analyse so I will leave it there. It may be of interest to others.
It has a StockRank of 53, implying average statistical chances - so I wouldn't write it off like I often do for "Sucker Stocks"!
Dignity (LON:DTY)
- Share price: 715p (-0.7%)
- No. of shares: 50 million
- Market cap: £358 million
Many investors have long given up and moved on when it comes to funercalcare provider Dignity.
I note that it is reporting a positive surprise for 2018:
- small growth in market share
- funeral average income higher than anticipated
- overheads lower than expected (marketing spend deferred to 2019)
Underlying operating profits will be approx. £79 million, ahead of current market expectations.
However, there is no change for 2019 expectations - average funeral incomes will be lower, as planned price reductions come into effect.
I would view the small growth in market share as highly encouraging - it says to me that the company's price reductions are working, and that its competitive position has stabilised.
It does have a large debt load to be reckoned with. If you can see it managing its debts, then a P/E ratio of 10x at this bombed out share price might be appealing:
Phew, that was a lot of updates! All done for today.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Flybe (LON:FLYB)
https://news.sky.com/story/top-flybe-shareholder-threatens-legal-challenge-over-2m-bid-11611470
Fascinating to watch...
I think the fears of a new BooPLT are overdone. PLT was built on the Boohoo infrastructure. As presumably Nasty Gal is now being. Not so easy to do it from scratch to this scale, even if you know how to do it.
I saw the other brands as a big future growth area not really discussed. Boohoo becoming a multiple brand white label platform. They have everything in place (maybe not the scale) to set up other non competing brands. They just need to sort out the commercial/financial structure properly and it could be a big upside. It would be very easy for them to set up a Sosandar (LON:SOS) on the platform. Also easy to stop if not a success.
Downside is if it works others could also set up a white label platform and bingo there's no barriers to entry other than stock and marketing. Which could wreck BOO and SOS
Boohoo (LON:BOO)
Re: the concern about Kamani creating an new brand
I’m no expert in legal matters, this post is a question not a statement.
The company I work for has put into my contract that I am not allowed to work for anyone else whilst I am that companies employment and unless I seek prior approval, any business I create will be considered owned by the company I work for.
Surely, there’s an expectation that if any of the senior figures were to do something like this they would have to make a clean break from any and all Boo group activities?
Would appreciate an expert opinion if anyone is prepared to comment or if any can point to examples where directors have set up rival companies to ones they’re directors of so I could have a look at what they did :)
Safestyle UK (LON:SFE) vs SafeGlaze, Lancashire Holdings (LON:LRE) vs Fidelis.
My recollection was that PLT was technically run by Kamani's children and the leaving of 35% with them was to incentivise them, but Paul's comment about Kamani or his children setting up another company is worrying
Hi Graham,
Do you have any thoughts on the DOJ circular re the Wire Act, basically saying that online gaming ban is across the board not just on sports betting (My interpretation - not a lawyer!) given your holding in 888 Holdings (LON:888).
Share prices have reacted negatively across the sector (in what is already a beaten down sector) and 888 Holdings (LON:888) has taken the biggest hit - which I would presume is due to their dragonfish product, which I think is a key driver for why they have some fantastic quality metrics (notwithstanding lack of physical footprint) and that other operators (eg GVC Holdings (LON:GVC) have started in Nevada) whereas 888 is New Jersey based.
Notwithstanding the DOJ, I think dragonfish would have a much bigger market in the US (more entrepreneurial) and therefore I imagine a lot of people will set up their own sites looking for a white label solution.
Would value your tuppence - no position - 888 Holdings (LON:888) at 10x forward with a 6% divi is starting to get very interesting but obviously this price is likely with good reason.
Hi sharmvr, I've downloaded the DOJ circular but won't get a chance to read it until this evening.
I see the whole story in the US as providing upside optionality for 888. If things remain tricky over there, then I guess we have to make do with the European businesses. G
It certainly does not seem to be priced as if it is going into the next phase of international growth in the biggest market around!
I read the first 4 pages - riveting!
Good effort with all the updates today!
Morning all!
I like this morning's update from £CALL (I have an existing long position, held for many years now).
It's been a good example of a jam tomorrow company which has taken far longer, and spent far more money (through repeated placings) to achieve its business plan. That's why the market cap is so bombed out, despite the company operating in a high gross margin, recurring revenue, interesting tech niche.
However, I think the company could now be near that lovely tipping point, where market sentiment suddenly changes from glass half empty, to glass half full.
Growth today is good, and accelerating in both Q3 and Q4, with positive outlook comments too. The company said that sales would accelerate in H2, due to its increase in overheads (primarily developing better product features, and S&M). Sure enough, sales have accelerated in H2 as promised, so mgt credibility should begin to improve.
Cenkos forecast from Sep 2018 (on Research Tree) shows losses being greatly reduced in 2019, from £3.7m in 2018, to £0.7m in 2019), which is driven by a strong increase in gross profit - remember there's huge operational gearing here, as organic revenue growth is strong, and it's achieving an 80% gross margin. So when profits do come, they could really soar after a few years. This is what makes this share so interesting, in my view.
Looking at the Cenkos figures, they show no increase in admin costs in 2019 over 2018, which strikes me as unrealistic. Since costs were cranked up during 2018, then I would expect the total in 2019 to be higher - as it's a full year of increased costs, plus wage inflation, etc.
Therefore, my view is that the Cenkos profit forecast is probably a bit optimistic, but I reckon the company is on track to get fairly close. Again, that's on my list of things to ask at the CMD.
What about cash? It's looking tight again - with only £0.9m remaining at end 2018. There is a £1.85m undrawn bank facility, but in the past the company has preferred to do a top-up placing, rather than going overdrawn. I suspect that might happen again this time. Maybe that's the underlying reason for this Thursday's capital markets day? To generate interest & increase the share price, ahead of another placing? I'll be attending the CMD this week, so will ask that question!
It only needs a top-up, so I reckon a placing of £1-2m would push it over the line, to breakeven & then profit. That's not really a big deal, as only 5-10% dilution, and with positive performance reported today, and a stronger outlook than we've had for a while, I think a small placing could be done fairly easily, if needed, and probably at only a modest discount. So for me, the low cash position is not a deal-breaker. Placings are only a problem when they're (a) big, and (b) from a weak position, e.g. after a profit warning. Neither is the case here.
My opinion - it's been a painful journey, but I think things are coming good here.
I'll report back if anything interesting comes from the CMD later this week.
Welcome back Graham.
It would be good to hear your opinion on the positive trading update from Kape Technologies (I hold) if you have time.
Michael
Hi Graham, I'd also appreciate your thoughts on Cloudcall (LON:CALL)
In the trading update they seem keen to point out that they have enough cash available:
"At 31 December 2018, the Group had available cash reserves of £2.75m, made up of £0.9m of its own cash and an undrawn facility of £1.85m. Cash reserves decreased by approximately £1.5m in H2 2018, compared to £2.5m in H1 2018, and the Company is already well advanced in preparations for its 2018 R&D tax credit claim which is expected to bring in an additional £0.75m in mid-2019."
It looks like they should have enough cash (and ready overdraft facility) to make it through to break even and their broker is predicting that they will reach that point at the end of this year, provided they can maintain steady growth.
Although given Simon Cleaver's track record on over promising makes me sceptical. They started the year with ~ £4.9M in cash and they've burnt through £4M, it could be quite close.
Just in case Paul is lurking, I wonder if he might be persuaded to share his thoughts on today's Update from Boohoo (LON:BOO) ?
Even though he may be feeling a little unloved over the past couple of days, I know that I'm not the only one here who would appreciate his take on one of his speciality companies.
Greece for many years has always had areas of elegance and beauty interspersed by places that are treated as a tip, or an untidy builders yard. This can often be experienced from the journey from the airport to the resort. It doesn't seem to have a particularly good sense of civic pride. In some ways it is a very odd culture to traditional European eyes.
Read Michael Lewis's: Boomerang! for a modest insight into some of the madness of the pre-bust Greece.
Thanks for the suggestions - lots of trading updates today, helps me to sort through them. G
Watkin Jones (LON:WJG) is strictly speaking a midcap these days, but has posted good results today. They forward sell most of their developments, so visibility is good, though they're moving into the rented market. My concern with them has always been, just how much student accommodation is needed???
Elegant Hotels (LON:EHG)
I sold out off Elegant when there was mention that it was very smelly (sewage problems) in some of the locations near their hotels. I don't know if this was a short term issue or was never really an issue, or whether it has now been rectified - but it kinda made the share uninvestable at that time.
Does anyone know if this was/is an issue or not?
I know when i go on holiday and some areas are a bit niffy it would totally put me off going back - when there are so many other alternatives that don't have that issue.
Was over in Barbados last November. Had a look round the Group, did not come across this issue? Anyway. Continue to hold long term.
GYM (LON:GYM)
Acceptable results today albeit they were a miss from expectations i think - openings they had were later in the year than they expected - that is no biggie.
EBITDA (i don't normally use this one but what the heck) is £37 mill - and the market cap is now back down to £310 mill. at 210p with forecast EPS of 12.7 for 2019 thats pe of 16.5 - although i suspect 2019 forecasts may be slightly trimmed.
With the price 30% down from its peak this looks a very good re-entry point for me having mine a while back when the price was more exuberant - i expect the growth will continue and when it slows this business should turn into a cash making machine - the perfect kind of retail rollout - seems a very will run operation.
I am though in no immediate hurry to buy back though in as i want to see how forecasts are revised for 2019 and hopefully 2020 if that info is available soon. I would be kind surprised though if the shareprice went much below the 200p mark - in present times though anything is possible.
rmillaree,
EBITDA is a nonsense measure for a business like GYM (LON:GYM), which is required to invest in a huge inventory of depreciating assets (treadmills, rowing machines, etc.).
The fact that they continually choose to emphasise EBITDA, rather than profits, in their announcements, makes me suspicious, particularly since they also weakened their depreciation policy a year or so ago.
@Effortless Cool (#15)
I've thrown the new numbers into my spreadsheet, and noted the 'Adjusted EBITDA', also includes Exceptional items and Long-term employee incentive costs (these two are an extra £2.4m for 2017).
Anyway, working back from this years £37m Adjusted EBITDA, and roughly doubling H1 costs, I have the following:
Operating Profit: £10.3m (2017: £9.9m)
Margin: 8.3% (2017: 10.9%)
Attrib. Profit: £6.8m (2017: £7.2m)
I think the expansion is going well, as shown by the KPIs, but hope they don't over-stretch. I would also like to see the debt being repaid, so revenue growth drops to the 'real' bottom line.
I sold 25% of my holding in December for 275p, and am contemplating when to re-purchase. Maybe <200p, or wait until March to make sure the results match my workings (or should that be the other way around ! lol)
Thanks for the comment and the pointer - interesting entry point indeed. G
Morning Graham
Good to have you back and glad you enjoyed your holiday to Athens. Greece is a lovely country, hopefully the economic situation will gradually resolve. Any thoughts on Elegant Hotels (LON:EHG). The share is cheap on a number of metrics, but hotels need an awful lot of caoex to remain attractive to prospective clients. Still Elegant Hotels (LON:EHG) does appear to have some competitive advantage as regards its size and positioning and is to my eyes an obvious takeover candidate.
Games Workshop (LON:GAW) is too large for the SCVR, but seeing as you have commented in the past you may have a view?
Games Workshop (LON:GAW) - Considering HY2018 vs FY2018 then today's HY2019 would seem to imply FY2019's forecasts (which have already been trending higher) are likely to be significantly beaten. Or are there some expected one-off factors compared to last year, perhaps a fall off in licencing revenue?
Cloudcall (LON:CALL)
JonBirdy
Today they have reported a 29% growth y-on-y revenue.
Paul noted a £9m 2018 forecast. My sums make it £8.9m. They say today that revenues are in line with market expectations. Am I missing something?
Hello Jon
This just looks like rounding to me.
Stockopedia have 6.87 last year and expected 8.96 which just rounds up to 9 :) - that is close enough to 6.9 to be the same in my eyes
Cloudcall took last years 6.87 and called this 6.9 in the header section - take 6.9 and multiply by 1.29 = 6.901 - even if you use 6.87 last year that gives 8.86 which rounds up to 6.9
amazing how you can make 100k out of nothing :) - lets hope its not superman 3 revisited - hmmm does Simon drive a Ferrari?
Nothing in todays news would make me want to buy back in here - at present 2019 figures stills show loss of £1 over mill (just)- so it looks like 2020 at least before this is a proper money making business.
Boohoo (LON:BOO) - As before, I am concerned about this disparity between PrettyLittleThing (PLT) and boohoo.com performance. Recall that they had an option to buy the whole of PLT at the bargain price of £5m, but chose to only exercise 66% of this, the remainder of PLT staying in direct family hands as a management incentive, to be bought out at market price at the end of February 2022.
https://www.stockopedia.com/share-prices/boohoo-LON:BOO/news/boohoocom-plc-trading-update-and-acquisition-urn:newsml:reuters.com:20161214:nRSN7639Ra/
Ever since PLT's growth has shot ahead of the fully owned boohoo.com and they will now be approximately equal in size at year end. Latterly the margins for PLT have also materially improved relative to boohoo.com. I think the two most likely explanations for the relative performance is that a) aware that boohoo.com and PLT mostly compete in the same market, PLT is being pushed much harder by management in the family's interest. Certainly there appears to be much more display advertising for PLT, or b) there is a natural maximum size (or longevity) for such a business after which it becomes much harder to grow - boohoo.com have hit this limit and PLT are about to. Both would be bad news.
(other possible explanations are the PLT management is simply much better or that they have somehow just got lucky and caught the target market's imagination, perhaps with their choice of influencers).
My other concern is that although they have significantly increased their range for revenue forecasts, market forecasts (from Stockopedia) were already in the top half of the new range. (FY 2018: 579.8, FY 2019E: 836.9, a 44.3% increase).
Along with the big run-up in the share price over the past few weeks, I feel these factors probably justify the weaker share price so far this morning.
(Disclosure: I just sold a trading position)
Indeed this is a worry, I am of the personal opinion that it's not a coincidence that PLT is outperforming Boo and that the family has a bigger stake in PLT than core Boo.
I'm hoping the (relatively) new Chairman, Peter Williams can grab a hold of this issue and start getting all three brands treated with equal weight.
Bit of a bombshell regarding Flybe (LON:FLYB) - appears the directors were not that honest when making the transfer to a standard listing.
Have I read this right, and holders actually end up with nothing, not even the 1p/share? It sounds like the original Flybe will be left as a shell and all the assets depart it.
Re Flybe (LON:FLYB) In response to your query they have had to secure a bridging loan through other means and moving to the Standard Listing on LSE. The 1p/share offer remains valid.
They still promise to pay the 1p in the announcement, the difference with the situation before is that shareholders have no real option to reject the deal now it’s just a cash shell with about 1p per share. The whole thing doesn’t feel quite right even though it may really have been that close to liquidation (in which case 0p would have been the likely outcome).
Bizarrely you can still get 2p on the open market apparently. Can’t figure out why. (I sold my holding yesterday).
Hi Graham
I wonder if you could take a look at Cloudcall (LON:CALL) ?
In July, Paul noted this:
“I like to look at not just year-on-year growth, but also sequential half year growth. This has been;
H1 2017 £3.2m
H2 2017 £3.7m (up 15.6% on previous half year)
H1 2018 £4.1m (up 10.8% on previous half year)
So there's been a slowing there, but still good growth.”
Today they have reported a 29% growth y-on-y revenue. Taking 2017 revenue as £6.9m would suggest 2018 revenue to be in the region of £8.9m, making H2 2018 revenue £4.8m, up 17% on the previous half of H1 2018, so reversing the deceleration of growth seen between H2 2017 and H1 2018.
They predicted strong H2 2018 growth and report today on that happening too.
Paul noted a £9m 2018 forecast. My sums make it £8.9m. They say today that revenues are in line with market expectations. Am I missing something?
Thanks
Jon
My morning smallcap tweet:
TP (LON:TPG), Tax Systems (LON:TAX), MaxCyte Inc (LON:MXCT), Telit Communications (LON:TCM), Elegant Hotels (LON:EHG)
TP Group (TPG) FY trading: delivered revenue and cash ahead of market expectations, adjusted operating profit in line with market expectations.
Tax Systems (TAX) guides FY comfortably in line with management's expectations. Net debt down 32% to £13.9m.
Maxcyte (MXCT) guides FY rev up 19% [F/C up 12%], EBITDA ahead of market expectations.
Telit Communications (TCM) guides FY rev at top end of exp at $427m, adjEBITDA in line with previous guidance at between $30-$35m.
Elegant Hotels Group (EHG) CFO will check out after handover. He is thanked.
Too big for SCVR but a popular/ist “old boy/girl”, Boohoo (LON:BOO) reports with a trading update this morning.
https://www.investegate.co.uk/boohoo-group-plc--boo-/rns/trading-update/201901150700020615N/
Most U.K. retailers would give their eye teeth for figures like this but Boo market reaction can be hard to read as market expectations are so high. Revenues and margins both showing strong growth. Slight niggle that the 4 month picture looks (slightly) less strong than the 10 month so the bears could claim a loss of momentum becoming apparent.
Gus.