Small Cap Value Report (Tue 16 July 2019) - BRBY, FUL, MPAC, BAG, XLM

Hi everyone!
Thanks for all the fantastic feedback yesterday on the subject of tablets. I wandered around a couple of department stores for a few hours, and in the end decided to wait another few months before making a bigger purchase that could also be used as a laptop. There are some amazing new hybrid devices (with both laptop and tablet functionality), and I think I'll choose the Surface Go or Surface Pro from Microsoft.
Burberry (LON:BRBY)
(Please note that I have a long position in BRBY.)
More portfolio news this morning, with a Q1 update from Burberry (LON:BRBY). This was already my second-largest holding, and the shares are up 8% as I type. The company has reported a return to like-for-like store sales growth (around 4%) thanks to a strong response to the company's new product range.
The outlook for FY 2020 is unchanged, including the previously-announced H2 weighting. But I think that investor uncertainty surrounding the new designer is evaporating. Like-for-like store sales growth, the closure of some underperforming stores, and £120 million of cost savings are all reasons for encouragement. I'm happy to continue holding for the foreseeable future.
Note also that this share has a StockRank of 87. I'm not ashamed to buy quality big-caps, sometimes!
Ok, time to check out some small-caps.
- Fulham Shore (LON:FUL) - results
- MPAC (LON:MPAC) - trading update
- A.G.Barr (LON:BAG) - trading update
- XLMedia (LON:XLM) - tender offer
Fulham Shore (LON:FUL)
- Share price: 12.4p (+8%)
- No. of shares: 571 million
- Market cap: £71 million
This restaurant has really grown on me. It started out as a research project, but I found that the sourdough pizzas at Franco Manca were so good and the meals were such good value that I was happy to keep going back.
I also tried out The Real Greek in Covent Garden this year - not such a compelling format, but still a good experience.
These are some decent results:
- Revenue growth is 17%. The total number of restaurants increased by 5%, so the like-for-like numbers must be good.
- "Headline Operating Profit" is £3.5 million (2018: £3.7 million)
- Actual operating profit £1.8 million (2018: £0.1 million)
- Net debt is £9.4 million, a reduction from last year.
The Chairman notes that "much of the capital invested in the UK restaurant sector over the past five years has not been spent wisely" - indeed!
Some of us would argue that there has been a general oversupply of restaurants, but it's probably true that the demise of the restaurant sector also has a lot to do with bad decision-making within it.
Successful restaurant businesses continue to be those that offer consistent, delicious and reasonably priced food made with quality ingredients.
I tend to agree that Franco Manca does this.
He talks about opening restaurants in unusual locations, with the view that customers will find them anyway, if they are good enough - interesting.
Growth plan - now targeting eight to ten new restaurants in the current financial year. The current financial year started with an estate of 60.
Property - Fulham Shore thinks rents must fall further, and is holding out for lower rents on its properties. I agree with that strategy, and share their optimism: we aren't in a normal cycle, but in the middle of a long-term shift where the use of property is changing.
The Chairman comments:
I believe we are due for a longer period of rental decline this time around. Commercial agents, who have historically been aligned with institutional landlords' interests, should realise the boot is now firmly on the other foot. These agents should start to truly represent successful tenants' interests as that is where the power and their interest now lies.
Dividend - no dividend, as the money is needed for the expansion. The Board will "consider a dividend policy over the current financial year".
Outlook - Confident. Franco Manca is coming to Leeds, Edinburgh and Manchester.
Financial Results
The use of Headline EBITDA is a bit problematic for me, since I view depreciation as a real cost of runnng a restaurant business.
If you're happy with the other adjustments, you could take the company's Headline EBITDA and subtract the depreciation and amortisation expense (nearly all of this is depreciation). You then have an underlying EBITA of £3.5 million, which is still a heavily adjusted number.
I'd also want to include the PPE impairments and the share-based payments, since I view them as regular costs of doing business (and you can see that they are in the accounts both this year and last year).
So personally, I would use an underlying EBITA of £3.2 million.
Conclusion
As much as I enjoy dining at Franco Manca, I'm more comfortable being a customer than a shareholder. Even using the pre-tax, pre-interest EBITA number above, you still get a hefty earnings multiple at the current market cap.
This sector terrifies me, so I'd want cheap pricing before I considered getting involved, even for a format which works really well like Franco Manca (or Real Greek).
Remember that bad weather can be disastrous:
Summer of 2018 was much stronger than the previous summer especially with a significant number of days benefiting from warm weather and sunshine.
The sun is shining right now, which bodes well for FY March 2020. And with lots of store openings in the works, the company is set to make hay. Just watch out - summer of 2020 might not be so favourable!
MPAC (LON:MPAC)
- Share price: 184p (+18%)
- No. of shares: 20 million
- Market cap: £37 million
This is what used to be known as "Molins". It's now a high speed packaging business.
Profit for FY 2019 will be significantly above current market expectations.
The current order book, year to date order intake and the volume of quotation activity provides the Board with confidence in the prospects for the remainder of the year.
Pension Predicament
As of December 2018, the company pension fund (according to accounting rules) had assets of nearly £400 million, versus liabilities of nearly £380 million, i.e. a £20 million surplus.
On the stricter actuarial basis, the fund was in deficit of £35 million as of June 2018. That's actually a big improvement compared to where it was three years previously, and the company said:
The actuarial deficit is now expected to be eliminated in July 2024, compared to August 2029 under the previous valuation.
For now, the annual deficit recovery payments to the fund from Mpac are c, £2 million p.a.
My view - there are different ways of looking at this, e.g. you could take the present value of the future deficit recovery payments (about £10 million in total over five years) and add them on to the market cap, to see what the current valuation says the underlying business is worth.
However, it's important to remember that 33% of underlying profit between £5.5 million and £10 million will have to be paid to the pension fund each year until 2024.
So between deficit recovery payments and these bonuses, the pension fund is set to gobble up a lot of cash over the next five years. The more successful that Mpac is, the more cash the pension fund will gobble up.
And even though the pension fund has been managed successfully so far, there is still some risk associated with interest rates and the other ingredients which make up a pension liability, which shouldn't be forgotten.
Equity Development are looking for Mpac to generate adjusted PBT of £5.5 million this year, on the back of a huge revenue increase (including the effect of an acquisition).
That will be a fine result, and the signs are strong that it will be achieved. On the basis of positive trading, we can now say with some confidence that Mpac is likely to outlive its pension fund.
As a result, the debate has moved on to the more bullish question of just how much cash is going to be left over for shareholders between now and 2024. There's probably no good way of analysing this without getting your spreadsheets out and doing the sums.
But away from the financials, we also need to bear in mind that this is a lumpy business. Predicting the demand for Mpac's assembly and packaging machinery is not exactly straightforward. It's too difficult for me.
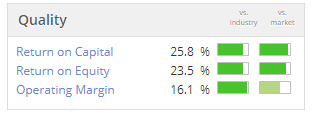
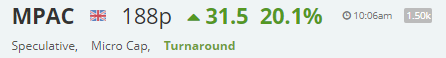
Stocko likes it, calling it a Turnaround stock - how clever! High value and high momentum, but low quality:
A.G.Barr (LON:BAG)
- Share price: 654p (-25%)
- No. of shares: 114 million
- Market cap: £744 million
Again this is not a small-cap, by our definition, but let's say a few words on it.
I entered the soft drinks sector in late 2018, adding Britvic (LON:BVIC) to my portfolio. Barr and Britvic were both interesting to me, but I like Britvic's portfolio and thought that it was priced much more reasonably, even taking its debt into consideration.
But could an attractive buying opportunity at Barr have finally arrived today?
What happened
Barr increased its pricing again, after it had previously cut prices to deal with last year's challenges.
This has not worked out well, and trading has been below expectations.
This has been exacerbated by some specific brand challenges, particularly in Rockstar energy and Rubicon juice drinks, as well as disappointing spring and early summer weather, most notably in Scotland and the north of England, and compounded further as we approach the half year when the prior year comparative weather was at its peak.
So we have another weather-related story. This time, poor weather in Scotland and the North of England (relative to last year) is making it impossible to meet the prior-year comparatives.
On the brand-related issues, the benefits of remedial action will not be felt until later in H2 (the company's financial year ends in January).
Outlook
- H1 revenue down 10% to £123 million
- Not expecting volumes to recover in H2
- Full-year profit expected down by up to 20%
- Exceptional costs will be incurred to regain momentum
My view
Let's figure out the latest PER, first of all.
Adjusted PBT last year was £45.2 million (the adjustments are minor).
Taking this down by 20% gives us £36 million, which is supposed to be the bear case scenario.
Applying tax, we get net income of £29 million.
So by my quick calculations, the current-year P/E is now 25.5x (worst-case scenario) at the current share price.
The portfolio - the staying power of its main brand IRN-BRU is well-understood, and I can also see a lot of value in Snapple.
Other brands, however, don't stand out to me - I'm unfamiliar with many of them. Indeed, today's profit warning has been partially caused by problems with the Rockstar range of energy drinks and with the recipe for Rubicon juice drinks. I'm not familiar with these brands.
So while I'd be willing to pay up for IRN-BRU and Snapple, I have limited interest in many other elements of the portfolio.
For these reasons, I am inclined to stay on the sidelines for now. I'd like to see if Britvic and other peers report sharply declining volumes. I want to know if the pricing strategy has caused any permanent damage to the core brands. And I'd also like to get a sub-20x P/E multiple for an entry point! Perhaps that's too greedy, but it seems fair.
Conclusion - Barr is staying on my watchlist, as I wait for a juicy buying opportunity. Existing, long-term holders might feel inclined to carry on holding, which I would not argue with.
XLMedia (LON:XLM)
- Share price: 78p (+7%)
- No. of shares: 207 million
- Market cap: £161 million
Tender Offer, Notice of GM and Trading Update
Good news. XLMedia proposes to accelerate its buyback efforts with a 20 million-share purchase at 80p. It replaces the existing $10 million buyback programme.
Trading update - business is stable in and in line with expectations. Personal finance publishing is going well in North America, but gambling legislation is hurting revenues in Sweden.
It reiterates that the cash is all real, and continues to flow:
The Company has a positive material cash balance and generates strong cash flows from operations. The Company's current cash balance will support the proposed Tender Offer, ongoing organic investment initiatives and current working capital commitments. XLMedia remains a highly cash generative business and as such will continue to maintain a progressive dividend policy, distributing at least 50 per cent. of retained earnings.
My view - If I was forced to invest in one more Israeli company (in addition to 888), it would be either this or Plus500 (LON:PLUS) (at current levels). There is plenty of evidence that the cash at XLM is real and the new publishing strategy is simple and easy to understand.
I have no idea what it might do over the long run but for now I do think that shareholders could potentially get showered in cash.
Elsewhere:
- the law firm Gateley Holdings (LON:GTLY) has released results and the outlook sounds in line with expectations.
- the premium cinema chain Everyman Media (LON:EMAN) has released a trading update which is in line with expectations, too.
- Cloudcall (LON:CALL) shares are down 10% as it reports a "lag" in revenue from larger customers. There doesn't seem to be any point in commenting on this, as Paul has studied it in a lot of depth.
That will do for today - thanks everyone.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Whilst I agree with the comments about Rocca and David Page - a bit pleased with himself - he may well own the freehold of one of these, I wouldn't be surprised, I do think that Franco Manca has been built to take advantage of the flaws of the other Pizza chains. Small menu, staff paid good wages and keep tips so better loyalty and retention. No need to discount so not raising menu prices and offering 30% off all the time like Pizza Express and Bella Pasta. Also not burdened with a rump of hugely over-rented stores.
It used to be that rent and rates combined should be no more than 20% of net sales to get a decent return. those days are long gone but may be returning. Also relatively low debt 13% of sales v 42% for RTN.for example. 37% for Domino's.
So, A.G.Barr (LON:BAG) and Graham @
"Conclusion - Barr is staying on my watchlist, as I wait for a juicy buying opportunity...."
Prices that reflect a juicy opportunity?
With a forward PE ratio tonight of 25.6 and an industry median of P/E 17.1 then the first thing to expect with such a serious profit warning is that Barr's historic premium rated PER is at least reduced to the industry median for starters, which would suggest the first low to consider is approx 416p - just to be plain average. That would be the first key "juicy opportunity" IMO.
But how far is it from the bounce-off 'golden ratio', the 61.8% Fibbo retracement level? Well taking a reading from the depths of the last crash in 2009 to this year's recent high gives the 61.8% ratio as 429p
So, initially 420's to the 400mid-teens, In other words the lower 400p's?
A quick check of Stocko's valuation metrics give a variety of valuations of circa 340 to 430's for four of them before the horror valuations of zero etc.,
--------------------------------
Just to reduce Barr to the ranks of average, suggests low 400's.
A fondness for last chance saloons with the golden ratio Fibbo 61.8% ratio to bounce off, suggests similar but a little higher in the 420's ......Hmm.
Then there's the Stocko valuations mostly in the mid-300's (bar one, above 400).
--------------------------
So, in summary, commence with small tranches of buys in the low 400's initially? Then see if mid 300's are up for grabs for further tranches?
- But wherever the SP is headed it is a profit-warning hit stock, so whatever price looks appealing eventually, none will be truly "safe" to buy until at least a full 12 months has expired.
Linking to my own post above -
Update:
On Tuesday Graham's carefully considered calculation of the new PE ratio for A.G.Barr (LON:BAG) came out at P/E25.5
My midnight back of a fag packet calc last night came out at P/E25.6
And an update from HL suggesting the new PE as P/E26
I thought we were all, more or less, on the same page but look at tonight's close now that Stocko has fully digested the new landscape.
Tonight it's displaying the new PE ratio as P/E18.9 based on 617p closing SP. That's a considerable difference to all three of us (and the Industry median has increased fractionally to P/E17.2)
So, using Stocko's latest PE ratio the current close of 617p on a premium rating to the average of P/E18.9 would have to fall to circa 561p-ish to be just in line with the industry average (If that's the market's intention).
So the first "juicy buying opportunity" I know amend and offer up as a suggestion of 561p-ish.
-----------------
But if the ultimate retrace is to be (IMO) the best/'final' of the Fibbo retracement levels then quite a further drop to 429p, but it has yet to break past the not-really-a-fibbo-number, the 50% ratio of circa 530p's which coincidentally, is within spitting distance of the Industry median P/E for BARR of 561p.
So all-in-all, for anyone stalking BARR could, ultimately, deide that the middle 500p's might be a strong contender for considering a "juicy buying opportunity"?
Worse case scenario? Longer term, maybe 420p's ?
I thought we were all, more or less, on the same page but look at tonight's close now that Stocko has fully digested the new landscape ... Tonight it's displaying the new PE ratio as P/E18.9 based on 617p closing SP. That's a considerable difference to all three of us (and the Industry median has increased fractionally to P/E17.2)
By the power invested in me via the magic of long division ...
... the 2019 EPS (historical) is 32.2. The trading update indicates a 20% fall giving a 2020 EPS (forecast) of 25.8, giving a PER at the current price of about 24 (615/25.8 = 23.8).
As far as I can see the stock report forecast PER of 18.9 reflects the unadjusted forecasts on the new share price (615/32.4 = 18.9). It usually takes a week or so before new forecast data feeds through into stock reports.
timarr
Re Cloudcall (LON:CALL) (I have a long position) - I've been busy today with family celebrations (birthdays, graduation, etc), hence the late comments here from me.
I quickly looked at the CALL trading update this morning, and thought the RNS read well, and would likely cause the share price to rise. So was a bit perplexed when looking several hours later, and finding it down about 10%.
To save doing all the numbers I too have referred to the update from Cenkos which you can access on Research Tree. They way I see it (and I'm glass half full on this one), is that;
Very good H1 organic revenue growth of +30%, but broker forecast was too high, at +45%. I say too high, because when I recently discussed buying more CALL shares with a sector expert, his view was that the +45% FY 2019 revenue growth target looked too high. So he held back from buying more shares, whilst I forged ahead and increased my position size (at slightly higher than the current price, so not a disaster by any means).
I listened to most of the results webinar, which was useful for more colour on the various points, and some great questions submitted by participants too. Mr Cleaver, as always, very upbeat about the prospects, but apologised for growth being a couple of months slower than expected, due to some CRM integrations & sales leads taking a little longer than expected. I understand why many shareholders will be annoyed by this, as it's pretty much what always happens here, but personally I'm more focused on the strong organic growth, combined with high gross margins & strong recurring revenues. This is a product which is in demand, and (surprisingly) performing better in the USA than the UK. I reckon someone in the US is likely to buy it, potentially at a much higher price than AIM stock market investors give it - there can be a large gulf in valuations, with the USA valuing this type of business much higher than we do.
Cleaver also talked about how CALL is becoming the dominant player in providing unified communication add-ons to recruitment CRM groups. He said that technological change is being driven by the "big 7" global recruitment groups, and that CALL is talking to all of them. If he's right, then it means CALL could own this niche in the not too distant future. I very much like that, and am prepared to be patient.
Cash - the spectre of yet another placing has become more likely after todayy's announcement. Breakeven has been pushed back for the umpteenth time, from late 2019, to mid-to-late 2020. There's no doubt that AIM investors are getting increasingly annoyed with repeated fundraisings, and ever-increasing costs, to drive growth. But what do they want instead? The alternative is to deliberately slow down growth, and defer product development, which would be crazy. The stock market really isn't a good place for small growth companies, in my view. Things always take longer than expected, and cost more than planned, which undermines investor confidence. Perhaps brokers should raise a lot more money when floating companies, including a large contingency reserve?
Personally I don't really care if the company has to do another say £2-3m fundraise, which would dilute by about 10%. I'd much rather they push ahead with growth, and raise money if necessary. The new bank facility is expensive, at c.9% above LIBOR, but on the webinar Cleaver said that the overall cost is roughly the same as the old Barclays facility which had non-utilisation fees. They describe it as venture lending, hence the higher cost than regular lending for profitable companies.
The new broker forecast seems to me, to have overshot too high, to possibly a bit too low. Various things in the pipeline suggest that there could be an H2 weighting, so personally I'm hoping for an acceleration in H2 from 30% to maybe 35-40% in H2. That's for revenue growth.
My Summary;
Bull case
Bear case
My opinion - each investor will form their own views on this. i understand the frustration of bears on this stock. But for me, the potential upside is sufficiently large, that I don't really mind the bumps in the road - it comes with the territory, and doesn't undermine the upside case very much at all, in my view.
Maybe I take a longer term view than others? If growth had stalled, or even gone negative, then I'd unceremoniously ditch this share as a failure. However, the 30%+ organic growth is genuinely exciting. The product works well (I know, as I've tried it), and good momentum is clearly there, with customer growth. It looks cheap to me.
Also use a bluetooth keyboard and mouse. Worth spending money on a good one.
I use a Logitech keyboard which can save 3 different settings, so switching between tablets/phone etc is very easy.
That has always been the thing hasn't it :
Tablets for consuming content, laptops for creating it.
I'm in a similar position to Graham here of considering a new purchase. My trusty Toshiba Laptop does everything I want, but is a little on the bulky side; so I'm leaning towards a decent android tab + bluetooth keyboard and mouse. - Possibly the best of both worlds without having to pay OTT for a "crossover"?
Regarding tablets vs. laptops, IMHO one must reflect on what the primary mode of usage will be (in your case, whilst on holiday).
If creating content, then go for a laptop or top-spec tablet with keyboard and mouse.
If simply consuming content, then any old tablet will do.
All IMHO of course!
Graham, just to add my two-penneth to the tablet discussion - personally I prefer Macs and still use a 5 year old 15” MacBook pro - with the old keyboard (much nicer than the new ones) but mostly use an 11” iPad Pro. It does everything I need it to, and the screen ratio works for me e.g. playing movies on planes etc.
One thing worth considering is that apple have finally seen sense and will be giving the iPad line a slightly different OS to that of the iPhone. This should make it far more friendly for business use, better file management etc, ability to use a mouse and so on. This makes perfect sense as the latest iPad pros are so powerful, have great battery life and fantastic screens, albeit they’re very expensive and hampered by their operating system.
Thanks for flagging that Francis. ( Fulham Shore (LON:FUL) )
I'm obviously having a very fickle day as digging further I have decided to sell out (0.7% gain after costs - I'd settle for being able to achieve that every day).
I hadn't seen your post at the time, which adds just another 'minor' niggle.
I my analysis above I had failed to recognise that the FY19 numbers are for 53 weeks whereas FY18 was 52 - that might seem triviial; but I arrive at the fact that LFLs were probably negative 1%, whereas the management speak directs us towards a view that 17% could in some way be an "underlying" number.
Too much smoke and too many mirrors for me, on reflection (hoho).
Re Fulham Shore (LON:FUL)
I saw David Page present at a Mello City event last year. He was charming and funny but I was troubled by one thing he said that has kept me away from investing, even at the very low levels the SP has been over the past few months.
I asked him about The Real Greek (RG) that opened in Dulwich a year or so ago which is on a site that has seen many casual dining operators come and go over the past couple of decades including Bella Pasta, Caffe Rouge etc. In short, this site struggles and it seemed to me that the RG was never very busy when I passed it. However opposite it, there is a tremendous site with a restaurant called Rocca which is a firm favourite of the Dulwich population and is permanently full.
He made a throw away remark that some of the directors were investors in Rocca and confirmed that the site was very successful. On looking into it, I found that he is one of the directors of Rocca Ltd which in turn is owned by "The Old Boys Club Ltd" a company on who's board he sits with David Sykes.
Now I appreciate he is allowed to run other businesses but for me there is a conflict of interest when it come to identifying good quality sites and in the case of Dulwich, his private interests are arguably disadvantaging Fulham Shore (LON:FUL) shareholders. Rocca has another site in South Ken - was this site considered for Franco Manca?
So not for me
Cheers
Francis
Francis - re Fulham Shore (LON:FUL)
yes, I was also aware of this re Rocca. Oddly when I tried the Real Greek in Dulwich one of the waiters told me the same people owned it. On closer inspection it wasn't Fulham Shore (LON:FUL) but same directors, as you found.
I went to Real Greek again on Friday night in Dulwich and it was pretty empty. Maybe just the start of summer lull but didn't feel particularly profitable. As you say Rocca was certainly full.
What is interesting is that Rocca does wood fired pizzas. Not the same as Franca Manca concept but not different enough to merit a FM in the area, though they do have one in East Dulwich. That itself is now under some threat as 500 degrees has opened 2 doors down and is similar in concept. I do wonder whether this happening in one location can be repeated in others over time and cannibalise even profitable sites?
I don't own Fulham Shore (LON:FUL) and am reluctant to do so for all the comments above as well as some of the others, such as yours.
Sounds like you might be local to me David. Does anyone else reside in the SE24 area (or East Brixton) as I like to think of Dulwich? If there are, perhaps we could organise a get together...Anyone?
cheers
Francis
Francis I don't live in London (not Dulwich) but I am in Dulwich quite regularly for family reasons. I have been also several times to the Real Greek of Fulham Shore (LON:FUL) and the Rocca. The Rocca has been open for several years and therefore I don't think the Rocca site would have been available when RG was looking. The Real Greek is usually pretty empty - although the food/ service is quite good - the Rocca I don't go to anymore after I (and relatives) have been served inedible food there. I have not really understood why the Real Greek site has always been a dud whatever the brand (but it has). The evening sun is on the other side of the street where the Rocca is - but then the Pizza Express on the "dark side" and has been very successful.
HI Wimbledons Printer, more great local knowledge, thank you.
But my question is whether the Rocca site could have been a Franco Manca one (not a Real Greek) and if there was a conflict of interest in that decision?
cheers
Francis
P.s. I have a big holding in B P Marsh. I’m a fan, but it is very dependent on a few very valuable stakes, is it not?
Re BP Marsh, that’s to be expected isn’t it? If you back a number of startups then there is likely to be a few big winners and an overall Pareto distribution.
My own portfolio returns would look less pretty if you took out my three biggest winners. But I do have them.
wrt tablets
I have
2 old iPads
1 Google 7"
1 Samsung 10" Note
1 PC convertible (Toshiba)
1 Surface Book
(+Samsung note phone)
The iPads are best for battery life
The Samsung 10" is the most useful for general light/medium use (was the 7" before that). I find the pen makes a big difference to how I use a tablet.
The Surface Book is very good. But like all Windows PCs, Windows update is an affliction.
Also use Office365 & Dropbox, amongst other services.
Hi Graham, I went through the tablet search and eventually decided to go for a good spec Microsoft Surface Pro. Most importantly, it came with a top spec keyboard too, and a pointer.
I decided that the price was too high new, so I went for a nearly new one on Gumtree, where I could meet and talk to the owner.
Having satisfied myself that all was well, I then bought it. It was a cracking deal. 18 months on, I’ve had zero problems. The Surface had hardly been used.
I still use a four year old iPad, and am doing so now. The Surface is for my financial stuff. So I have both of those plus an Android phone.
A.G.Barr (LON:BAG) might be victim of sugar tax and related recipe changes. Rubicon is popular in the South Asian market which notoriously has a sweet tooth so I think a lot of people were not happy with that. Also the old recipe for Rubicon was branded as 'premium' but also came with a premium price tag.
Thank you for your few on XLMedia (LON:XLM)
"I have no idea what it might do over the long run but for now I do think that shareholders could potentially get showered in cash."
I have held this all the way down to 46p (from 180p) and back to the current price. I should have bought some more at 46p but I was rabbit.
On tablets I still think the best combination is WinPc, iPad and iPhone using Chrome, Office 365 and Dropbox. It covers all bases and works well across all platforms. Yes over a 5 year time frame that probably costs about £20 a month but compared with other costs of running my portfolio that is reasonable.
Best
Michael
I bought some MPAC (LON:MPAC) today, as the pension deficit could be gone as early as 2022 at the next triennial review.
Thanks for today's report Graham. Despite the column's name, nice to see some big cap coverage too, especially when its quality.
Fulcrum Utility Services (LON:FCRM), mentioned above, is a Cayman-registered business. I highlighted this in March on this channel.
This is worth pointing out since Stockopedia list the UK address, not the registered office of the company according to AIM Rule 26. I requested Stockopedia to list the registered office but they decided not to.
I don't know why the listed entity is not a UK-company.
Apologies if you are already aware of this. I don't have any financial interest in this share.
HI Graham, can you please have a look at £xlm’s tender offer?
They say “The Board is of the opinion that the full potential of the Company is not reflected in the current share price and this Tender Offer accelerates our current share buyback programme, further capitalising on our current share price."
That sounds great, although it doesn’t reconcile well with the fact that no members of the board have actually bought shares in the past few months (the CEO being the only exception)...
Albert Technologies (LON:ALB) joins the IPO "D" Listers: placed at 133p in Nov 2015, now at 2.5p as it announces its intent to delist.. another Israeli Tech company gone south.
Adds another reinforcement to the Tel Aviv investing pariah
Cloudbuy (LON:CBUY)
ambrosia
That's the problem here the company knows whats up and the brokers know whats up and the money that matters knows whats up (probably) but we have to work from that gibberish released this morning until we get confirmation of where we are at (updated broker note?) - i am sure Paul will provide some clarity at some stage hopefully :). I do have to believe though its as simple as sales are now £0.7 mill behind expectations and that is thefore bad news (actual v expectations being probably the most important bit of any update) not good news whatever the fancy stats say - although i may be completely wrong in that assumption. I would say on a news day for a small company movement less than 10% isn't always massively indictive of much - the shareprice has been on an excellent run up over the last 4 months so a bit of profit taking may be at play here too from the lucky newer entrants.
I think you mean £call not £cbuy. In the words of Mick Jagger "Hey you, get off of my cloud!"
Cloudcall (LON:CALL) There is a good piece by Cenkos on Research Tree worth a read if you are a holder or follower. I am long.
In essence it looks like the "timing" noted in the announcement does have a read through of something around -8% vs broker revenue expectations for this year. So a minor profit warning.
The missed revenues do however, feed through to next year and so expectations remain broadly the same over 18 months.
Seems like the overall story is intact though and to be fair the US could be a very big market compared to the UK so that is some good news. Also, the user run rate is good exceeding 1000. However, I'd say the company seems to be now looking at enterprise licences of several thousand, which dwarfs existing customer base. What we really need to know is how margins are expected to stack up as this volume comes through as that is going to be the important thing for profitability.
hmm - a mixed bag I'd say and share price has had a run up so not unsurprising to see it down a few %.
The RNS this morning just stated that Cloudcall had obtained an increased £3.0m facility from Shawbrook to replace its existing £1.85m facility at Barclays (maturing 2020). No terms are disclosed. The Cenkos note on Cloudcall (LON:CALL) states that the interest/ facility charges on the new £3.0m Shawbrook facility is Libor +9.0%. This sounds steep and higher than the previous Barclays RCF which was at Base+7.45% on drawn balances and a non-utilisation fee of 2.98%. Cenkos also refers to the new Shawbrook facility as a term loan (not an RCF).
At the CMD in January, CEO Simon Cleaver went to some length to explain why banks are happy to lend to Cloudcall (despite it being negative cash flow), explaining that the banks could cut sales and marketing expense and then run the company for cash, where it should make c£200k per month. Assuming Cenkos is correct about the terms of the Shawbrook loan it shows that banks are demanding a high interest rate to take this risk.
Cenkos has also revised down again its FCF forecasts for Cloudcall (LON:CALL) - it now assumes net cash of £0 at end 2019 and net debt of £1.5m at end 2020 (respectively £1.2m and £1.9m worse than in its note in March). If these forecasts are correct, that does not leave a lot of headroom by end-2020, even with the new £3.0m facility.
It's a great business but how does anyone justify a forward multiple of over 30 for a sub-billion pound company in a competitive and regulated market? Irn-Bru isn't Coca Cola (which is still trading on a lower PE than Barr).
I couldn't agree more. It's market is also highly constrained to the UK and so results susceptible to things like UK weather, which seems to be part of the issue. Why would you hold A.G.Barr (LON:BAG) on a PER of 30 when you can hold Pepsico on a PER of 23? It makes no sense to me.
Another Buffetology stock, of course. Highly moated companies are very rare indeed in the lower echelons of the market, no matter what historical figures suggest.
Also one of the smaller holdings of Nick Train I believe. On another note though, nice numbers from Burberry (LON:BRBY) this morning, which is one of his larger holdings... and mine :)
All the best, Si
Timarr you should start doing your own regular blog, i like the clarity youre able to see in the market, after youve said that it now just seems obvious
what about fevertree, same opinion?
Hi ambrosia
Timarr you should start doing your own regular blog, i like the clarity youre able to see in the market, after youve said that it now just seems obvious
Well, that’s very kind, but with hindsight everything is easy. In any case I have a full-time job that I enjoy very much and I’m very happy to leave the hard work to Paul and Graham.
I think with Fevertree Drinks (LON:FEVR) the jury’s out. Research shows that we love growth stocks – and we’re very good at identifying them. Unfortunately, we habitually pluck defeat from the jaws of victory by overpaying for them. Exhibiting the patience to wait for very good companies to hit a pothole, and then having the skill to identify that it is a pothole and not a sinkhole, is a skill in its own right. After 30 years I’m still not very good at it.
But any company with this type of nose bleed valuation has to have an exceptional offer and a defendable moat – the first to keep growth rates up and the second to ensure competition doesn’t erode margins. The slightest misstep on either and the valuation will dive. Too rich for me, but Fevertree Drinks (LON:FEVR) is one of the few companies out there that might end up justifying its price, because the brand may turn out to be insanely valuable if everyone starts asking for Fevertree instead of tonic.
But A.G.Barr (LON:BAG) on a PER of over 30 – nah, that’s just silly, even in normal times.
timarr
Any chance of a squiz at Fulcrum Graham?
I've noticed loads of companies recently re-stating accounts - and this is one of them!
Cheers,
Jim
Hi Jim!
Thanks for mentioning Fulcrum Utility Services (LON:FCRM) - it's not in my sector coverage, but it's a good example of the complexity for some companies when they change accounting rules.
Fortunately, the rule changes have absolutely no bearing on the fundemental value of businesses - except to the extent that they have to pay accountants and other people to sort out the mess.
The Group has had to undertake significant work to determine the above changes and is now in the final stages of audit.
Fulcrum's reported EBTIDA will reduce, but its reported balance sheet position will strengthen by the same amount. There is no difference to cash, which is the only thing that is not a matter of opinion!
Cheers
Graham
Fulcrum Utility Services (LON:FCRM)
On cash, this from the TU 28/3/19:-
"As at today the Company has drawn £3.0 million of its debt facility of up to £20.0 million supporting its external purchases of utility assets."
I find this a bit of a concern given the disclosed cash position of £10.4m at 30/9/18.
Phil
No position
Good morning Graham,
RE: A.G. Barr Plc
An 'unexpected' warning from A.G.Barr (LON:BAG) this morning. Or was it?! Share price has been taking out new highs in 2019 and got carried away with itself. Revenues down 10% with profits expected to be impacted by 20%. This against tough comparatives from 2018. Seemingly great weather in H12018 but poor weather in H12019. More likely the cause, A.G.Barr (LON:BAG) increased prices which impacted volumes in a competitive market, whereas in 2018 they did the opposite (held prices & focused on volume). This is a quality share, with strong brands, profitable, progressive and reliable dividend, innovative company, building a portfolio of brands to better enable them to meet the challenges posed by shifting consumer tastes/trends and regulation. They have launched new drinks this year, namely: KA Reload, Rubicon Street, St Clements (new range), IRN-BRU Energy and Funkin Nitro Cocktails in a can (all of which came late in H1). In addition, the 20% investment in Stryyk (non-alcoholic spirits) looks interesting too. They've invested in their MK factory, re-formulated, re-launched & re-positioned a large portion of the portfolio in the last 18 months, so a lot has been going on in the background. Funkin Cocktails looks to be growing well - trade & off trade.
I'm a bit disappointed with the news this morning i have to be honest. It will be interesting to learn whether other soft drinks companies have experienced a similar impact on revenues (weather) or if this is just a A.G.Barr (LON:BAG) problem given their relatively focused geography.
All in all, I believe they've invested for the future...I remain positive as a long term holder.
Appreciate your insights if you have any.
Thanks,
Andrew
RE: A.G.Barr (LON:BAG)
It's a great business but how does anyone justify a forward multiple of over 30 for a sub-billion pound company in a competitive and regulated market? Irn-Bru isn't Coca Cola (which is still trading on a lower PE than Barr).
This seems to be a trend - good companies pushed to high ratings justified by historical earnings resilience, which then get hammered when they misstep. In a low interest world a guaranteed growing earnings yield is very valuable, but investors increasingly seem to forget that you have to discount prices to take account of earnings risks.
Another Buffetology stock, of course. Highly moated companies are very rare indeed in the lower echelons of the market, no matter what historical figures suggest.
timarr
Yes agree about A.G.Barr (LON:BAG) - Fizzy drinks are now perceived as unhealthy and even natural fruit juices too high in sugar. The company is now ex growth and I was expecting a -50% drop at the open. Still too way to expensive for my book.
Any suggestions for listed water bottlers, or nil-cal flavoured water companies welcome? Maybe Treatt (LON:TET) will benefit.
Yes, health trends in UK and other developed markets are bad news for fizzy drinks, and that's another reason why you might want to own a much bigger company than BAG with its UK-centricity.
If I could act as devll's advocate for Graham's comment on health trands and fizzy drinks. I think you can argue that the fizzy drinks industry is a good example of an industry which has successfully responded to health concerns. You can check this out by looking at how many reduced sugar or no sugar fizzy drinks are on the supermarket shelves. This has also been done whilst maintaining equally healthy profit margins. I note that the Barr statement does mention a number of problems in relation to its recent performance and the transition to low/no sugar is certainly a challenge, but one that has been met. I think the industries with greater health concerns are the huge confectionary and fast food sectors as here we still have high sugar and, importantly, we also have high fats in many cases. These industries are, for the most part, yet to respond to health concerns.
Looking at the comments section of the BBC article about the A.G.Barr (LON:BAG) profit warning, it would suggest that there are a number of people still deeply unhappy about the recipe change of Irn-Bru. I've no idea of the scale, but people seem to want the old recipe back, even if they have to pay sugar tax on it
I agree.
Whilst the beverage sector is interesting, quite a lot of them seem to be on high valuations which make the investment case much less interesting.
Presumably the positive sentiment is a result of the quality characteristics long since identified in some companies such as Coca Cola and the multi-bagging returns in others, such as Monster Beverage & Fever Tree.
Having seen these examples, it's tempting to scour the beverage sector for other opportunities, so the price gets driven up. I don't see much value.
Whilst these are good businesses, I also cannot consider them as bullet proof. Surely the likes of Irn Bru are at risk from some of their customers figuring out that sugary drinks are very unhealthy ?
Don't think it makes a lot of difference to the average customer, consumer leveraged as they are. How else can one justify £1 a 500ml. bottle of tap water and probably half thrown away.
Yes, something of a shocker from A.G.Barr (LON:BAG) - in fact the hit I think is > 20% on profits - given profits were forecast to increase this year.
I strikes me as wholly unacceptable that they wait until the scheduled trading statement to drop this bombshell, having indicated everything was fine in March and choosing to make no (public) statement whatsoever at the AGM at the end of May.
As this was only their 150th AGM, perhaps they have yet to learn the scope of their responsibilities as a listed company.
I'm out!
Gateley Holdings (LON:GTLY) please Graham, results out are slightly above expectations although op margin is (temporarily?) down due to investment in IT and 'branding'
Cloudcall HY REVENUE UP 30% VERSUS H1 2018 WITH RECURRING REVENUE UP
34%
share price has so far tanked 9%
rmillaree's post was helpful and made things a bit clearer, but I still feel i dont fully understand
Could you take a look at MPAC (LON:MPAC) please as it looks like an interesting turnaround. Valuation is cheap, appears to have net cash, returning to profit this year with FY profit "significantly ahead of market expectations".
They appear to have a large pension deficit, but appear to be making good progress on this.
"The actuarial deficit in the scheme has reduced from £69.9m at 30 June 2015 to £35.2m at 30 June 2018 on a technical provisions basis. The actuarial deficit is now expected to be eliminated in July 2024, compared to August 2029 under the previous valuation. The current annual deficit recovery payments have been maintained but will now cease more than five years earlier than was agreed under the previous valuation."
Cloudcall (LON:CALL)
Another hopeless update from Cloudcall today - this company really takes the biscuit with regard to faffing around and ignoring the most important aspects of a trading update - clearly communicating how company is progressing compared to market expectations for the year - we are over 6 months in and i can't make any sense of what the overall situation with regard to how they are matching up to expectations for the year - a recurring theme with this company.
Ok despite my criticism i will give then kudos for using the user growth table - a decent metric and the numbers look very impressive in this regard - so however bad the rest of the news if i was a shareholder i would be looking at this main core stat as being bang on the money and that will likely make up for weakness elsewhere - caveat at the bottom.
Ok what about the comparison v expectations turnover wise
Stockopedia has £12.4 mill sale this year and the outlook section now says they are on target for only £11.7 mill but no comments as to why this is £0.7 mill lower than what stocky expects.
Ok so the reality is that this looks like a profit warning without them saying that - what a ridiculous situation if this is the case. It was probably to be expected though for those that know this company and particularly as they were trying hard to raise funds earlier in the year one had to expect that everything would be glass chokka full in everything they said when they raised funds - note i have closely monitored this share and i can't ever remember forecasts having been upped for 2019 despite the fact that they raised more cash.
final points
1 going back to the earlier mentioned growth in user stats - this is a decent metric and impressive but obviously the fact they are signing up bigger clients means those clients are paying significantly less per user - somewhat negating the goodness of the stats.
2 this company is still loss making and will probably be more so after todays news? if this is a profit warning. Do i even believe the "us business makes a profit bit" - does it pay its fair share of plc overheads? hmmmmm. This company really could do with someone other than the bod in charge doing the investor communications IMHO. Looks like it may be another 6-12 months added to the breakeven date with the "managing costs" mention again - not another fundraising surely? - i gues updated broker notes need to be looked at fast.
Cloudcall (LON:CALL) Yep serial disappointer does not fail to deliver. Hope someone does not bring out a better mousetrap before it reaches cash positive. Sigh !
Long Cloudcall (LON:CALL)
full year results in line with market forecasts.'
Who?
as for TP (LON:TPG) previous post. apologies for cut off.
TP (LON:TPG) A Positive Trading Update.
No numbers, again.
TP Group plc (formerly Corac Group) designs and develops advanced technologies, engineers complex equipment and systems, and provides support throughout their operational life.
''a significant increase in our sales pipeline''
''The Board remains confident in current trading and expects the Group to deliver ful
Good results from Fulham Shore (LON:FUL), owner's of the excellent Franco manga pizza chain, breaking into profitability. A degustation would be sympatico, grazie mille...
Yes, good results from Fulham Shore (LON:FUL) that have encouraged me to take a small position here (after a long time watching).
One concern though is the management speak - all very self congratulatory (which is fine if justified) but also not very transparent about where the growth is coming from.
The make the point that the net three openings in this year had little impact on the overall growth number.
However, what they fail to make clear is that they increased the size of the estate (number of venues) by 30% in the prior year and therefore a portion of this 17% growth (from the "existing estate") will come from the full year impact of these new venues from last year.
Not a mention of like for likes in the results, so therefore caution about this growth number is needed IMHO.
Just trying to get a bit closer to the "like for likes" with Fulham Shore (LON:FUL) I have come up with the following.
So from this over-simplification, it looks to me as though LFLs might be c. +1%. In fairness, many chains would probably be very happy with that number, but it is a long way short of the +17% that we seem to be steered towards by the management speak.
I'm sure with a bit of spade work, one could identify the precise opening dates (maybe someone here has that detail) which might give a slightly different picture.
I'll keep my small position opened this morning (for now) as I do think those figure are pretty good anyway, but I am somewhat dismayed by the scale of the apparent mis-direction.
re: Fulham Shore (LON:FUL)
Hope you like my degustation. G
My morning smallcap tweet: Albert squares up for delisting. "Leave it, AIM's not worth it."
Albert Technologies (LON:ALB), XLMedia (LON:XLM), Surface Transforms (LON:SCE), £James, Cloudcall (LON:CALL), MPAC (LON:MPAC), Management Resource Solutions (LON:MRS), Lidco (LON:LID)
Albert Technologies (ALB) proposed to delist. "To support further growth, it will be necessary to seek additional funds and the Directors believe that it is in the best interests of the Company to secure a strategic or financial investor with knowledge of the company's core markets...These types of investors are unlikely to be forthcoming whilst the company remains admitted to trading on AIM." Board thonk ALB is undervalued on AIM and "negatively impacts the company's business."
XLMedia (XLM) tender offer at 80p, a 10% premium, for 9.5% max of shares.
Surface Transforms (SCE) wins first order of €2m PA (before tapering off during 2026) from German car mfr (OEM5) for one model. SCE will be the 2nd supplier of carbon ceramic brake discs for this car. Hopes for more models. "Pricing has been agreed across the potential range of platforms providing a link between increasing volumes and reduced product pricing."
Fisher (James) (FSJ) wins orders in the offshore renewable energy sector with a combined value of circa £30m.
Cloudcall Group (CALL) H1 trading. Rev up 30%. New orders received up 44%. Q2 monthly net user growth exceeded the target of 1,000 per month. CALL seems very pleased though FY F/C is for 42% rev hike.
Mpac Group (MPAC) H1 trading: ahead of the Board's and market expectations, Guides FY profit ignificantly above current market expectations.
Management Resource Solutions (MRS) solicitors' report on the takeover of Alerion Consulting mostly exonerates MRS but says board was not sufficiently involved in the process. A separate report on valuation of Alerion will be completed by end of month. Alerion was a newly incorporated company and its principal assets were unregistered intellectual property. Hmm.
LiDCO (LID) get regulatory approval for commercial sale in China for its latest cardiac output monitor with non-invasive technology. "Group has made limited sales to its Chinese distribution partner, and this approval enables us to re-launch with our latest monitor to a very important, rapidly growing market."