Small Cap Value Report (Tue 18 Jul 2017) - SFE, SOM, NTBR, DOTD

Good morning ladies & gentlemen! It's Paul here.
I added a few extra sections to Graham's report last night, in the comments section. So for my comments on Elecosoft (ELCO), Interquest (ITQ), and Conviviality (CVR), please see my comment (no.26) using this link.
I appreciate that me adding extra sections in the comments isn't ideal, but it's a quick & easy way to post stuff on my days off, that otherwise wouldn't be posted at all. Plus I will always add a link to such extra sections, the following day.
Safestyle UK (LON:SFE)
Share price: 230.8p (down 10.2% today)
No. shares: 82.8m
Market cap: £191.1m
Half year trading update - for the 6 months to 30 Jun 2017.
I hadn't realised how much this double glazing company's share price had fallen recently. As you can see from the 2-year chart below, it's now close to the post-Brexit vote low, and autumn 2015 low. So if you like the company, this could be a buying opportunity. Or something might be going badly wrong. That's always the big quandary with buying dips.
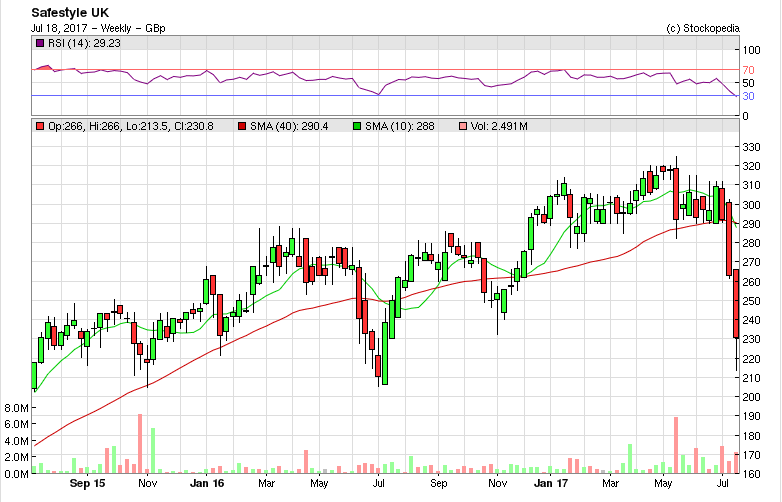
It sounds like market conditions are getting a fair bit tougher - which is consistent with other companies reporting more fragile consumer confidence;
Since our last trading statement at our AGM on 18 May 2017, the Company has continued to trade in line with earlier months, with order intake levels continuing up 2% year on year. Within this overall figure, however, the trend from week to week during Q2 has been more volatile than we have experienced for a long time.
Furthermore, FENSA statistics for the five month period to the end of May 2017 show a market decline in volume terms in excess of 10%. Against this backdrop of patchier consumer demand, it is clear that Safestyle continues to significantly outperform the market and to increase share.
It's good to see that the company is giving fairly specific guidance to investors on how 2017 is likely to pan out;
As outlined in our AGM statement, we expect to report marginal revenue growth in the first half of 2017, with reduced profits. Given the uncertain market conditions and weaker consumer confidence, we consider it prudent to expect only modest revenue growth again in the second half of the year.
This would result in profits for the year being lower than previously anticipated and broadly in line with 2016.
The normalised EPS for 2016 was 18.9p, so if the company does that same in 2017, then at 230.8p current share price, this equates to a PER of 12.2.
Balance sheet - is solid, and the accounts generally look clean to me (I've just had a quick recap on the last full year accounts, which I reported on here. In that brief report, I flagged that, due to its cyclicality, people probably shouldn't pay more than a PER of 8-10 in the buoyant times, for this type of business.
Cashflow - this sounds fine;
Cash flow has continued to be strong and we had net cash of £17.7 million at 30 June 2017 (30 June 2016: £23.6 million), the year on year reduction reflecting the investment in our new production facilities and the payment of a special dividend in July 2016.
Cost-cutting has already been done, to reflect a weaker trading environment;
In anticipation of a continuation of the recent weaker trading environment we have taken firm action to reduce our operating costs in the second half. Having successfully completed the investment in our enhanced production facility on time and on budget, we are well positioned to take advantage of the upturn in demand when it occurs."
My opinion - this announcement is not a disaster by any means. So if you think that consumer confidence, and hence willingness to spend on big ticket items like double glazing is likely to recover, then this might be a buying opportunity.
On reflection, I feel that the share price of this company probably ran well ahead of itself, and the recent fall looks more like an adjustment to bring it down to a more sensible valuation.
As you can see from the usual Stockopedia graphs below, SFE has had an excellent track record, and mentions today that it has been gaining market share, so there is some attraction to this company:
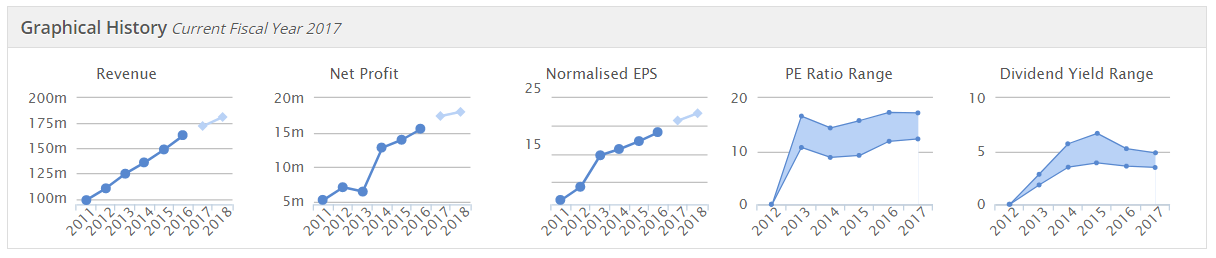
The big question is, where do things go from here? Is this just a temporary softening of demand, or the start of a more serious downturn? Will the company have to discount more, to maintain revenues? That would put its strong profit margin under pressure.
Overall, it doesn't look particularly cheap to me, even after the big recent falls. In a time of wobbly consumer confidence, I'm not sure that I'd want to buy shares in a double-glazing company. Historically they often go bust in recessions, although this one looks too financially solid for that to be likely.
It doesn't appeal to me, although dividend seekers might find it beguiling - if you think those generous divis are likely to be maintained? So a tricky one - quite a nice business, that's still trading OK, which can now be bought at almost a third more cheaply than 3 months ago. I can see why some people might find that quite interesting, but it's not for me.
Somero Enterprises Inc (LON:SOM)
Share price: 287.5p (up 3.2% today)
No. shares: 56.2m
Market cap: £161.6m
(at the time of writing, I hold a long position in this share)
Trading update - for the 6m to 30 Jun 2017.
This sounds encouraging;
Somero is pleased to report that trading in June was stronger than both the previous month and the prior year comparison. This strong performance, together with the continuation of the positive global trading environment, margin improvement and solid operating cash flow generation, has underpinned a positive outlook for H2 2017 and the Group's continued expectation that trading for the full year will be in line with market expectations, as highlighted in the update provided on 5 June 2017.
As usual, the company goes on to give a brief comment on performance in each region, which you can see in the RNS, if you're interested. The main thing for me is that they confirm trading is in line with market expectations.
Directorspeak/outlook comments are upbeat;
"With improved margins and positive cash flow generation, momentum in H1 2017 has continued and we are particularly pleased to see that our customers anticipate a high level of activity going into the second half of the year.
We look to the period ahead with confidence and this is reflected in the Board's decision to pay a special dividend as announced in our previous trading update."
My opinion - this sounds fine to me.
As you can see from the usual Stockopedia graphics below, this is a high quality company, on a modest rating;
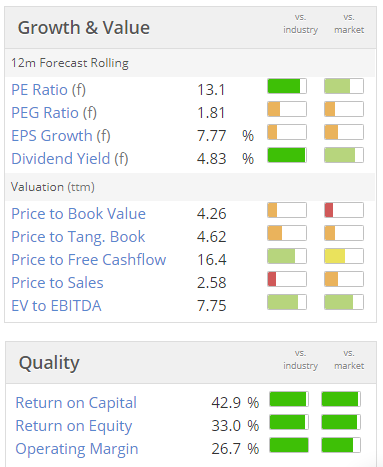
Of course, Somero is a cyclical company. Investors still remember how profits collapsed back in 2008. That said, I think the company's overall markets are now a lot larger. This is because ultra-flat flooring is increasingly important for warehouses, given higher stacking, and automation. Plus, internet businesses mean that many new, high tech warehouses are springing up all over the world. That's a huge market for Somero's customers to address.
So for me, risk:reward still looks good. Therefore I remain a holder in the long-term section of my portfolio. Actually, I forgot I still had them until recently, as they're in an account where I only trade a handful of times per year. So for me, this has literally been a tuck away & forget share!
Hi, it's Graham here with some more updates!
Northern Bear (LON:NTBR)
- Share price: 83p (+8.5%)
- No. of shares: 18 million
- Market cap: £15 million
I mentioned this building services company last month in the SCVR when it released its trading update.
It said results to March 2017 were going to be ahead of expectations and furthermore that it had a particularly strong order book for the time of year, so that there was optimism for the year ending March 2018 too.
Those March 2017 results are announced today, and are excellent:
Turnover from continuing operations of £45.6m (2016: £34.7m)
Profit before tax from continuing operations of £2.4m (2016: £1.8m)
Basic earnings per share from continuing operations of 11.3p (2016: 7.9p)
Cash generated from operations grew to £4.5m (2016: £3.7m)
See how large the cash generated from operations is versus the market cap - a multiple of only 3.3x! But it's probably not worth getting carried away by that, as the company concedes that "favourable payment terms" are responsible for an element of this, and it may reverse.
With the swing from £10 million in net debt in 2009 all the way to net cash today, it is confident now to announce a special dividend of 1.5p. And the final dividend increases to 2.5p from 2p.
Acquisitions: I am pleased to see caution expressed in relation to acquisition policy. Acquisitions will only be executed where, among other things, they "predictably enhance earnings". Good! Adventurous acquisitions have a tendency to go badly wrong.
Indeed, included in today's results are the discontinued operations of an asbestos-related subsidiary which has been disposed of after it continued to drag on the Group's resources.
A willingness to retrench when appropriate is a mark of good management, in my view.
My opinion
As was the case last month, I'm impressed by this company's results and outlook, and I like the valuation.
The StockRanks have also been flagging it up for a good while, so this is a perfect example of when they can work extremely well over a particular timeframe.
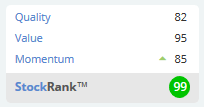
Looking forward, you again probably have to take a view on the outlook for service markets in roofing, solar panels, fire protection, forklift supply, health & safety, etc.
But if you're willing to take on that kind of macro risk, this looks like a great place to do it.
dotDigital (LON:DOTD)
- Share price: 71p (+1.4%)
- No. of shares: 296 million
- Market cap: £210 million
This richly-rated email marketing automation company announces an update for the year ended June 2017.
Growth and EBITDA are in line with market expectations (disclaimer: EBITDA excludes share option scheme expenses).
Overall revenues grew by 19% organically to approximately £32.0m (FY16: £26.9m);
Monthly recurring revenues from dotmailer's SaaS-based usage up approximately 23% to £26.0m (FY16: £21.1m);
Strong cash balances at 30 June 2017 of £20.4m (FY16: £17.2m)
Paul has spoken previously about how this company has been "sweating" its existing clients, even while by implied growth rates the total number of clients appears to be decreasting.
Again, according to these numbers, revenue per client is up by 24%, which outpaces organic revenue growth.
11.9 billion emails have been sent by the dotmailer platform in the period.
It's still a UK business, with some decent prospects abroad too:
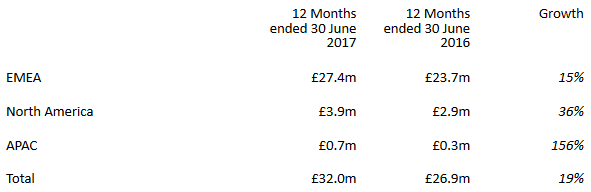
The estimates are for net income of £6.6 million to June 2017, rising to £7.9 million to June 2018.
The dividend yield is only about 1%, but is not relevant since this stock is all about the big growth prospects.
Certainly, it's a strong proposition to marketers at the Dotmailer website (new tab), with one customer describing it as "MailChimp on steroids". I really like MailChimp, personally, so that's a strong statement indeed!
In terms of valuation, the market cap is not quite so expensive when you consider the net cash pile (already at £17 million a year ago).
Fairly impressive stuff overall, then, and I wouldn't be surprised if it had plenty further to go.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
I should start this comment on dotDigital (LON:DOTD) with a disclaimer that I thoroughly detest email marketing so it is entirely possible that I am not being entirely objective.
The obvious point to make is the massive PE, but of course as a high growth share this can be a misleading metric (as the E can rapidly catch up with the P).
But is the growth really that convincing?
19% revenue growth is certainly impressive, and gives lots of scope for operational gearing to kick in in a good way.
And increase ARPU is also generically a very good sign.
But when these factors combine to reveal an implied 5% fall in customer numbers for a company in aggressive growth phase I start to worry.
It may of course be the case that they have previously had a marketing strategy that was too broad, attracting good customers that will stick and grow, together with a large number that will not be retained. If marketing has now become more focused, attracting mostly sticky customers, that would explain the anomaly and maybe make this attractive. But I would want to see some concrete evidence that this was really the case to be able to justify the current valuation.
My personal concern would be that instead this is somewhat more ephemeral and liable to collapse in a puff of smoke.
I will confess that I don't really understand what dotDigital (LON:DOTD) really offer, but I do know that a while back I wrote my own bulk emailer to support a voluntary group I work with, because I couldn't find anything readily available that fit the bill for what I wanted and whilst this is not a wholly slick user friendly offering, it wouldn't take too much effort to make it so and I only employed relatively limited effort (and more limited expertise!) to build. So I have to wonder whether there is really any kind of 'moat' here at all.
As per the start of my comment , I'm probably prejudiced against this business - but I hope I wouldn't let that stand in the way of a decent investment opportunity. So I would really welcome any views to the contrary on this.
Paul, love the idea of you commenting within the comments section and then as you did posting a link in todays report so we can find it. I think I speak for most/all on this site that we would rather hear from you then not! regards
Better though I think to do what Graham did today and add a section to the end of the report as this is then more easily searchable?
Hear,hear! I usually skim the comments, but not always, and rarely when the companies, or the digests, in the main report are of little interest or the comments wander off into ...
So, if there are tid-bits and updates, please keep them in the main body.
Thanks to both of you for the hard work.
Paul,
It would seem that leaky windows are not the only problem at SFE. The share price started to go southwards with determination some ten days ago. I suppose it's too much to hope that insider leaks from PR agencies and NOMADS can always be caught, but this does look bad.
House brokers only get the numbers the night before the release, so clearly there is a corporate issue here.
Hi Paul,
Somero is looking very positive today, so as one off my largest holdings, I am very happy.
But iI see Eagle Eye (LSE;EYE), one of my smaller punts, also gave what looked like a positive trading update, but the response has been a 3% drop in the SP. Is this due to cash situation, as they appear to be getting through the money raised recently quite fast?
Your thoughts would be appreciated.
Nick
Also impressed with Northern Bear (LON:NTBR). results, we have an excellent summer so far this year which should always help towards their roofing business's. As a result from the Glenfell disaster I can also see their survey drone, and Isolar business doing quite well.
Hi Paul and Graham
Any views on Synectics interims?
Peter
Interesting to see how different consumer companies are trading.
I was surprised by Conviviality's strong results yesterday (it seems people are still fine to go out for drinks), but Safestyle is telling us that big-ticket expense is a different thing.
As for Safestyle, windows may not be the hottest thing, but you are getting the lowest cost player in the industry (by virtue of their vertical integration), sitting in cash and with a history of winning market share every year for a very long time. So if you don't mind sitting and waiting, this is the clear industry winning horse. Management also owns a good chunk, which never hurts.
Having said this, I wouldn't go anywhere near worse quality players like Epwin, for example.
Curious as to why you consider Epwin worse quality? Thought their greater product breadth was a plus...
Well, they are not vertically integrated, which is a big negative in my view. Also they have been struggling with the integration of acquistions and have a history of negative LFL growth.
Not saying they cannot turn it around, but when you don't have your house in order the outside headwinds blow much harder.
Did you mean Entu (UK) (LON:ENTU) rather than Epwin (LON:EPWN) ?
No, I don't even consider Entu as "investable". :)
Everyone keeps talking about windows. In fact,possibly the key major step in this business's fortunes is when they relatively recently went into conservatories too. That is an even bigger price item than a few windows. It would be interesting to analyse where they are suffering - windows and / or conservatories?
Please give more details on your negative views of Epwin.
Paul, Im a holder of SOM and asked a few questions last week complaining about the poor investor part of their site(old links), no contacts.. They came back to me and set up a conference call. I had the Finance director and CEO on the call. It was very informative
They are still growing and adding 10% new customers each year and existing customer are buying reports.
One thing I dug into was the CBI backlog of work is the higest its ever been since records began and the biggest backlog of work is in the west. Training is in florida and thats a 9hr (2time change ) to get to the training. I did ask if they were going to build or franchise regionally training but they are not big enough for that yet
I was disapointed we didnt have numbers or percentages this morning. I emailed the investor team to pass the following on
"Do you think in future releases we could get SOM customer numbers based on the regions versus the CBI backlog indicator?
From the best CBI backlog report since records began (see link) you can see a massive backlog increase (up 25%) in the west.These are good numbers.
So for example, wording in a release like
"Construction work backlog in the west is up 25% based on CBI figures, Somero has xxxx % overall customer base here so we look forward to our customers increasing their revenues and then possible purchasing new machines in 2018"
Or
"40% of the new xxxx machines went to the west USA where theres currently a 25% increase CBI backlog indicator of 7months of backlog work. We hope to grow our customer base in the West USA by xxxx% in 2018)
http://www.abc.org/NewsMedia/ConstructionEconomics/ConstructionBacklogIndicator/tabid/272/entryid/8733/abc-s-construction-backlog-indicator-rebounds-in-2017.
I was impressed and they stated that the shareholders are very important and its not the amount you hold as all shareholders are important
Sorry for my typos on SOM
"They are still growing and adding 10% new customers each year and the existing customers are re-investing their money /upgrading and /or buying new machines"
They are not buying "reports" as I stated.. :)
They said A lot of the concrete contractors only travel 100 miles max from their base as the Somero machines are loaded onto lorries and that can take 2-3hrs to get to a job as is quite a slow operation so having staff fly to florida for training is a pain.(Somero do offer training at client sites for a charge) Getting trained in the heat of florida is a lot different to the wet of seattle where most of the backlog of construction work is also, although this is more related to the preparation/finishing than the operation of the report as they stated. They cover this in the training also
I like the idea of franchised training centres where SOM take a cut for outsourcing training (like IBM, microsoft etc) but they are not at that size yet
This share really is a long term hold And forget about it as paul mentioned.
Trumps construction law change has been put on the back burner till 2018 also
I was going to dump it all last week and sell all the shares but learning to be patient isnt one of my virtues
Paul says Somero is one that is in his Tucked Away Drawer.
What other AIM shares are in the drawer. Would he useful for IHT mitigation.
Mrken.
Seems ECEL is also down in sympathy!
North Midland also issued a massive contract win which put them ahead of expectations..
In May I agreed a deal with safestyle for fourteen double windows (ie to replace 28 panes), with difficult scaffolded access to quite a few of them. The ease with which they reduced the price during negotiations, by more than 75%, ending up with a price very similar to a good local company, struck me as indicative of a company which needed turnover. Within a few days of placing the order, there was a request from them to bring the installation drastically forward from the original provisional date, which again struck me as indicative of a company struggling to get enough work. They did a good job, but I felt that the huge relatively new manufacturing facility that several employees of the company described to me, had been built at the wrong time (ie. before the brexit vote), and would be difficult to run at full capacity in current conditions.
At the time I thought about adding the above thoughts to an earlier SCVR, so apologies to anyone who might have found it helpful at that time.
"The ease with which they reduced the price during negotiations, by more than 75%"
I suspect this has more to do with the fact that the first price they quote you is padded and inflated to such an extent that the question is not 'if' but 'how many' times their quote will be halved. I think they've been doing this long before the new factory!
Their timing does not seem great, though.
Yes EV, I was more or less aware of that before discussions began, and I suppose the salesman might have been aware of my awareness, but the speed with which he came down to a price competitive with a good low overhead local company, made me think. The plethora of subsequent contacts by different members of their staff made me think that they would be vulnerable in the event of the slowdown I'm expecting.
Everyone just loves playing the game.
Until the day they get someone that actually accepts the first price they quote!
Dotdigital too please!
Hi jimmy, it's covered!
Graham
Hi Paul, would be interested in your comments on Northern Bear (LON:NTBR) if you get a chance, thanks!
I second that. Northern Bear (LON:NTBR) put out cracking results in my opinion (I'm long)
Well done on getting involved there ricky, I've added a section!
Cheers
Hi Graham
Thanks for covering Northern Bear (LON:NTBR). Perhaps one of the reasons valuation is on the lower side is because the service sector seems out of favour at the moment? I think it's also a bit under the radar being £15M market cap. Looks good for the moment. 1.5p special divi is also a nice unexpected bonus.
Kind regards
Ricky