Small Cap Value Report (Tue 19 July 2022) - BOOM, MADE, PHTM, BEG, LUCE, SOM, HOTC, ITS, EYE

Good morning! I hope you slept better than I did! Paul & Graham here with Tuesday's SCVR.
Agenda -
Paul's Section:
Audioboom (LON:BOOM) - I ran through its interim results last night. Can't say I'm impressed. Low margins, mean little operational gearing. The valuation looks much too high on fundamentals. Although it might be valuable to an acquirer, given that it's a significant player in the US podcast market.
Made.Com (LON:MADE) - online furniture seller puts out another profit warning. Big losses of £80m PBT now expected for FY 12/2022. It's running out of cash too, and hints at a placing being needed. Who would want to fund that, given current conditions? Looks too high risk now, of dilution, or worse.
Photo-Me International (LON:PHTM) - excellent interim results. This is one of my favourite value shares, and today's results, plus a special divi, reinforce that. I think the shares are at least 30% undervalued.
Hotel Chocolat (LON:HOTC) - Roland has done a write-up of today's near-50% crash in share price. But it's so interesting, I've looked at it as well, so we can compare notes later. International expansion has gone wrong, and big write-offs are needed. However, I think the strong balance sheet can absorb this. There remains a decent, growing UK core business. Broker forecast for FY 6/2023 is also clobbered by cost headwinds. Not a bargain yet, but it's getting there.
In Style group (LON:ITS) - poor results, and an increased loss is forecast for the new financial year. I can't see the point in this company being listed, and have given this share a wide berth since it listed. Is it a bargain? In a word. no.
Eagle Eye Solutions (LON:EYE) - 550p (up 4%) (£146m) [No section below] - a very good trading update. Looking at the note from Shore Capital, £6.5m EBITDA only turns into £2.6m adj PBT, and 7.6p EPS. Forecasts for the following year don’t look too challenging, although it says the pipeline might slow in tougher economic conditions.
This looks a very good little growth company, with really impressive clients, globally. But a PER of 72 times looks a bit scary. Maybe the company has strategic value to an acquirer, given that it is integrated into lots of big name retailers? It’s a really interesting company, and I can see why people like it. Valuation is the tricky part though.
Graham's Section:
Begbies Traynor (LON:BEG) (£222m) - Excellent results from Begbies, as expected, and the company guides that FY 2023 should be around the top end of expectations (revenues up to £118m and adjusted PBT up to £19.7m). The dividend increases too, and shareholders will be happy. The momentum behind insolvency work is likely to continue for the foreseeable future, as we enter a point in the cycle that is very favourable to the traditional Begbies business. The company has diversified its services and is well-placed to exploit this economic environment. However, I suspect that the Begbies market cap already prices in a large portion of the forthcoming success.
Luceco (LON:LUCE) (£178m) (-2.3%) [no section below] - trading has been “broadly as expected” at this lighting company, since the Q1 update. “Broadly” is code for “slightly worse”, and the shares are trading slightly lower today. The company’s broker has reduced its revenue forecast for the year from £225m to £216m, and reduced its PBT forecast from £25.2m to £23.6m.
The revenue performance is ahead of the pre-Covid (2019) performance on a like-for-like basis, suggesting possible normalisation soon, after the volatility experienced over the last two years (very high demand followed by destocking). Net debt is estimated at £50m, and this may need to be reduced in order to reassure investors. The company also mentions that inflation is a concern re: consumer demand. This stock is cheap against prospective earnings but the reasons for this may be valid, at least until it improves its balance sheet.
Somero Enterprises (LON:SOM) (£218m) (+5.4%) [no section below] - this manufacturer of equipment for levelling concrete provides an H1 update: H1 2022 has been better than H1 2021, helped by “sizable workloads and project backlogs that extend well into 2023”, in the North American market. Europe saw a lower performance than last year, due to “logistics challenges that delayed machine shipments”, but is anticipated to improve in H2.
The last time I wrote about Somero, in January 2020, I said that their opportunity in China should be viewed as speculative. At the end of 2021, they finally abandoned their Chinese growth plans.
The outlook for 2022 remains in line with expectations: revenues of c. $138.8m, EBITDA of c. $47.7m, and year-end cash of c. $39.9m. I’m not aware of any serious competition facing this company in North America and it appears to be doing well in the European market, too. Encouraged by the QualityRank of 99, the cheap valuation and the net cash position, I have to retain a positive view on this one.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Audioboom (LON:BOOM)
868p (down 2% yesterday)
Market cap £142m
We’ve followed Audioboom for years here at the SCVR. It’s morphed from a basket case, into a much more credible company in the last year or two. It produces podcasts, and sells advertising on them. Nearly all revenues are generated in the USA, obviously a large market, and potentially commanding a higher valuation for the shares. Although US tech has sold off massively in the last year. There was talk of mega cap US tech companies possibly interested in buying BOOM, but that seems to have fizzled out.
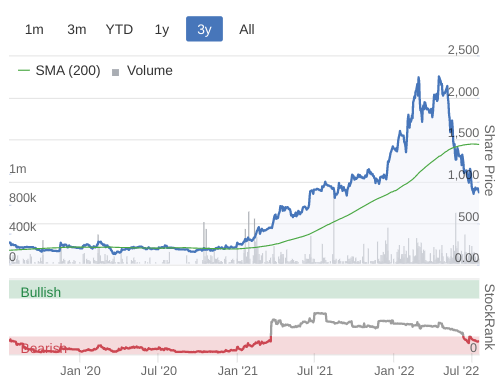
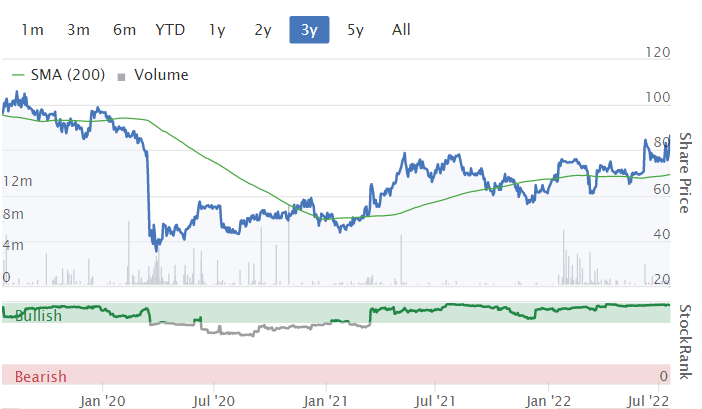
As with so many companies right now, the share price has fallen heavily, so I’m wondering if it’s a bargain now? As you can see from the 3-year chart below, the recent sell-off has been pretty brutal -
.
.
Here are my notes from reading through the interim results - released promptly for the 6 months ended 30 June 2022, reporting in US dollars - so some benefit there when translated into sterling, given dollar strength right now -
H1 revenues $40.9m - up 79% vs H1 LY, but only up slightly sequentially against $38m in H2 LY - not sure if there’s a seasonality bias to H2? That can be difficult to ascertain where turnover is rising fast.
Gross margin is very low, only $8.3m gross profit - hence very little operational gearing with a 20% gross margin. This undermines the investment case for me, because rapid revenue growth here doesn’t make a lot of difference to the bottom line.
Adj operating profit is small, at $2.0m
Share based payments are greater than profits, at $2.3m! So whose benefit is the company actually being run for? This looks inappropriate to me.
Forex gain of $1.0m
Profit before tax of just $566k, so it’s certainly not a value share.
Tax losses are big, so probably shouldn’t need to pay corporation tax for a while (retained losses on balance sheet are $38m)
Outlook - good bookings from advertisers, >£68m for 2022 signed, which I assume is in addition to H1 booked revenues, but they could have been clearer on this point.
Softening of advertiser demand in Q3 - not good.
“Confident of achieving our goals for 2022” - I’m not keen on the loose wording here. Would be better to confirm market expectations, with a footnote to say what they are.
Balance sheet check - not particularly strong, but probably OK. NAV is $17.4m, which is not much relative to the £142m market cap, so there’s very little asset backing here.
No intangibles though, and no development spend is capitalised, which is prudent accounting.
Receivables at $19m is too high relative to H1 revenues of $41m. This is an amber flag. It’s all very well booking revenues, but if half have not been paid by the period end, then it raises questions about how robust the sales & profits are in reality.
Cashflow - unremarkable at $1.5m operating cashflow.
Going concern note - says it won’t need to raise more equity. That looks credible, providing the receivables turn into cash. I’m worried that receivables might not turn into cash, because they’re too high.
Broker update - many thanks to Finncap for updating us. It's forecasting $83.0m revenues, and $3.6m adj PBT for FY 12/2022. That's 20.7c in EPS, or 17.3 pence. Giving a current year PER of 50 times! That looks an ambitious valuation. Although BOOM is on a rapid growth trajectory, so if that continues, the company could grow into the valuation. But a bargain, it is not.
My opinion - the valuation here doesn't stack up at all, on a value basis. It’s barely profitable in H1, and isn’t collecting in the cash very well.
Revenue growth is great, but the gross margin is low, so little operational gearing.
In a booming US tech market, this share soared, but people ask tougher questions about valuation in bear markets.
Therefore I think this share is all about strategic value that an acquirer might place on it. That could work out well, but there’s not a lot of substance, in terms of profit & cashflow, to support the current valuation.
Good luck to holders, but I think the tide might have gone out for the bull case on this share. But if markets rebound strongly, then it could be a nice speculative trade, who knows?
Someone might decide it has value as a platform, hence value-type considerations may not apply to how other people might value this share. So I can see potential here, if you take that approach to investments.
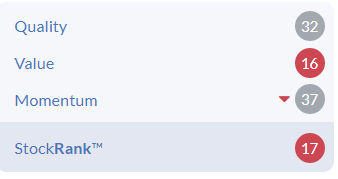
The StockRank system curls its lip at BOOM -
.
Made.Com (LON:MADE)
38.5p (last night’s close)
Market cap £152m
Q2 Trading Update & Revised Guidance (profit warning)
"MADE, the leading digital native lifestyle brand for the home, today announces a trading update and revised guidance"
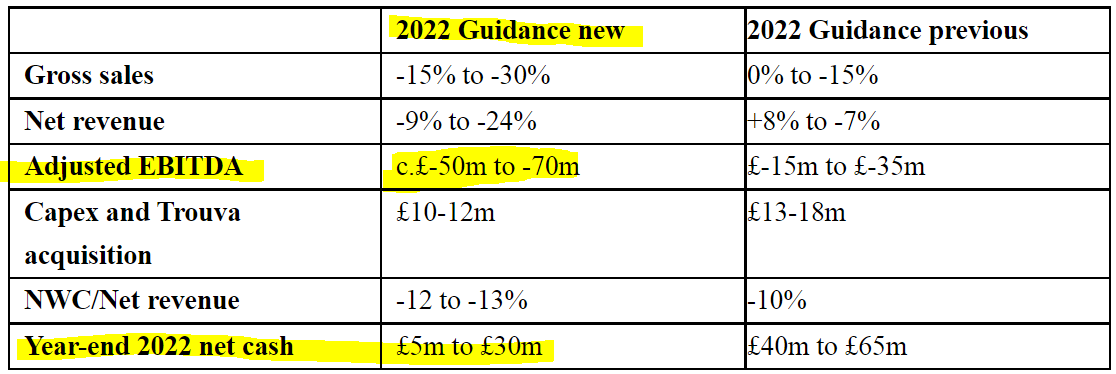
Hats off to this eCommerce furniture retailer for transparency, with a very clear before & after guidance table (below), but it’s very bad news - now predicting a large loss of £50-70m for FY 12/2022, and that’s just at the EBITDA level.
It turns into an £80m loss at the PBT level, based on an update from Liberum this morning (many thanks for that) -
.
.
Actions taken - cost-cutting, but no benefit expected in 2022. £10-15m benefit in 2023.
Placing? - this is making it fairly clear that an equity fundraising is likely - who knows what price the institutions will extract for continued support? It could get ugly for existing holders -
"Alongside these cost actions, Management is considering options to allow the Company to strengthen its balance sheet."
What’s gone wrong? - people are spending less on furniture. DFS also mentioned that demand was softening, in its 9 June update. It’s hardly surprising is it, in the current macro environment, that some people would spend less on bigger ticket, discretionary items.
On specifics, MADE says -
£20m profit hit from additional discounting to clear excess stocks,
Supply chains costs & disruption, but expected to “substantially normalise in the second half”.
Cash - it had £31.5m net cash at end June 2022. But as you can see from the guidance table above, that’s expected to drop to £5-30m by year end, quite a wide range.
Balance sheet - was OK, but remember that heavy trading losses feed through into damage to the balance sheet. NTAV is forecast to drop from £74m at 12/2021, to £28m by 12/2022. Hence it’s probably going to need an equity fundraising to prop that up. Although DFS operates with a massive deficit on NTAV, due to favourable working capital, so maybe MADE could do the same? Although the difference is that DFS is profitable, so can borrow from the bank. I doubt any bank would lend to MADE, given the scale of its current losses.
My opinion - I did have MADE on my watch list as a possible turnaround, but the situation has deteriorated so much, that I would now consider this share uninvestable.
The cash pile is being rapidly depleted, due to very heavy losses, forecast to be c.£80m in 2022.
Maybe being digitally native, thus appealing to younger customers, is an achilles heel right now?
I don’t think MADE has proven its business model works yet, with losses in all previous years. The huge loss in 2022 now forecast, and the likelihood of a placing being needed later this year, means this share has now become high risk, and I think is probably best avoided.
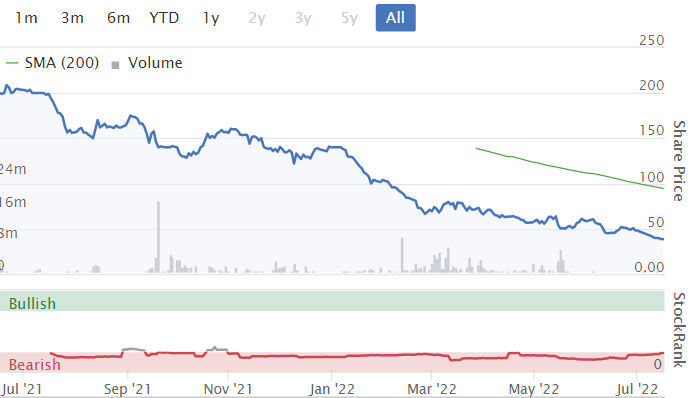
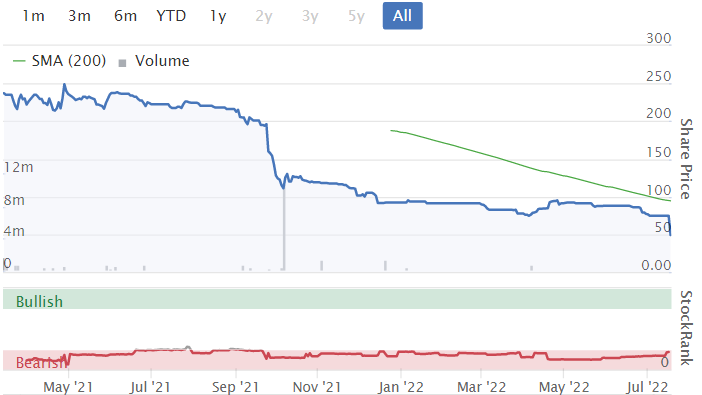
It’s another disastrous float - the shares have only been listed for a year, and this has happened -
.
Photo-Me International (LON:PHTM)
90p (up 12% at 08:21)
Market cap £340m
I remember writing a very bullish section on PHTM here on 7 June, so am re-reading that to refresh my memory. At the time, the company reported strong trading, ahead of expectations, and the shares looked dirt cheap on a low PER, with a decent yield too.
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces its results for the six months ended 30 April 2022 (the "Period").
Today’s H1 numbers look good - key numbers:
H1 revenue £115.3m (up 22%)
Adj PBT £16.0m (up 24%)
Diluted EPS 4.35p
Net cash £43.2m
Dividends - good news here, there’s a 2.6p interim divi, plus a 6.5p special divi - very nice!
Outlook - another company giving very clear guidance -
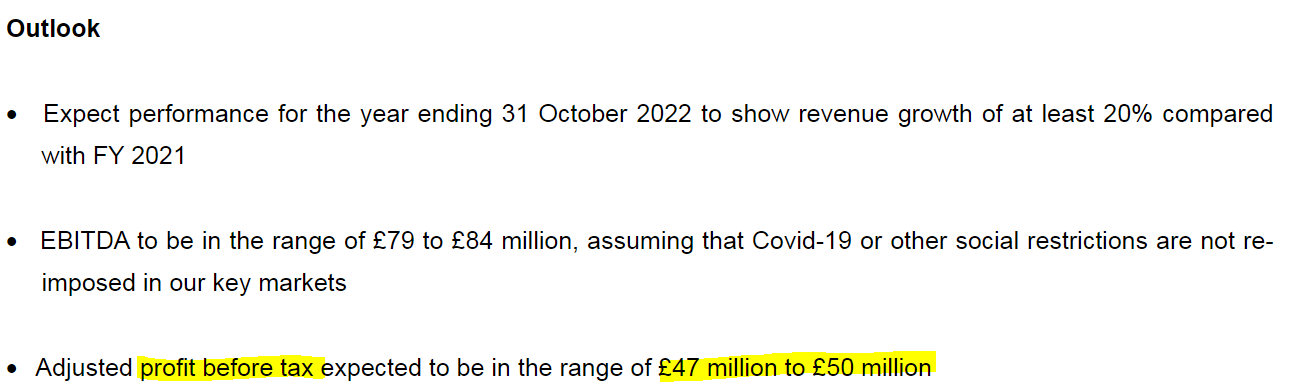
.
Broker forecast - many thanks to Finncap for an update. It has 10.4p EPS pencilled in for this year, double last year.
Hence at 90p per share (although it’s moving around a lot this morning), the PER is only 8.7, which seems too cheap to me, given profits are coming not just from photo booths, but also other activities.
Finncap also highlights that PHTM has raised its prices considerably, so clearly has pricing power, and hence is a good share to hold in a higher inflationary environment. That’s really important right now.
Balance sheet - is strong, no issues here.
Rebranding - from Photo-Me, to ME - makes sense, as this reflects the wider spread of activities.
My opinion - I’ve not gone through all the commentary yet, but skimming it, the company sounds confident.
I remain of the view that this seems an excellent value share. The special divi is icing on the cake.
A more sensible valuation for this share would be 120p+, in my opinion. Plus shareholders get paid well to wait for it to re-rate.
A big thumbs up from me.
.
.
Hotel Chocolat (LON:HOTC)
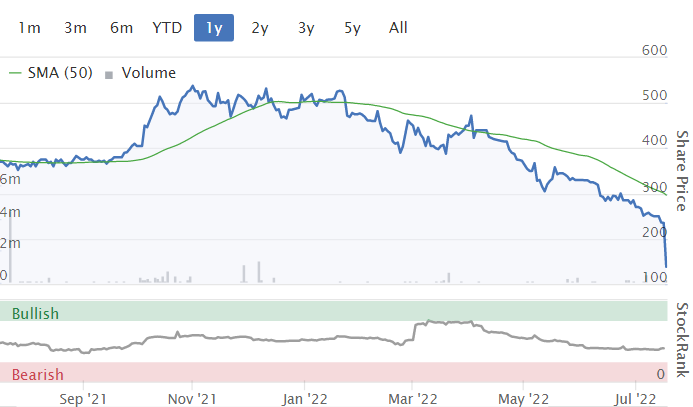
130p (down 45% at 08:30)
Market cap £177m
Good grief, look at this for a 1-year chart, the valuation for HOTC (always on a toppy rating in the past) has been smashed to pieces, like a shattered dropped praline.
.
.
Is this an opportunity for us to get in at an attractive price, I wonder?
Hotel Chocolat Group plc, a premium chocolate brand, today announces a trading update for the 52-week period ended 26 June 2022 ("FY22").
Roland has written a more detailed article about Hotel Chocolat (LON:HOTC) so I’ll just summarise the key points below from my own review of today’s update.
FY 6/2022 underlying PBT in line with expectations at £22m.
Statutory profit will actually be a loss (not stated how much), due to write-downs related to US operations (only 1 store remaining), and Japanese JV. The interim accounts showed a £19.5m loan to the JV within non-current assets. So it sounds as if that’s likely to be written off possibly? It sounds to me as if the Japanese operation is likely to be abandoned (31 stores). Also possibly the US online only operation could be ditched? But these overseas operations were small, so not particularly material to the figures.
Hence it's retrenching back to the UK market, and most profitable product lines, following a strategic review.
Cash of £17m remaining, but it’s squandered a lot of the £40m raised in July 2021 (cash was £54m at Dec 2021). £50m undrawn RCF, so plenty of headroom.
Considerable cost headwinds mentioned, with some mitigating actions - hence a big drop in forecast earnings today.
Big drop in forecast earnings for FY 6/2023 - Liberum has dropped from 14.1p to 5.6p, a 60% drop.
Bounce back expected in FY 6/2024, with Liberum at 12.0p now (was 18.2p)
My opinion - clearly the dream of international roll-outs has gone badly wrong, so the share has de-rated sharply.
So I think we now need to see HOTC as a UK business, with good potential - the commentary today is upbeat about UK expansion plans.
The goal is to get EBITDA to 20% by 2025, which would be c.£40-50m, so if this can be achieved, then the shares would surely be higher than the current £177m market cap?
Is the share price collapse an over-reaction? No, I think the current price of 130p looks about right, given the greatly reduced profit outlook, and what looks like the failure of international expansion. Hence a much lower rating is justified.
If it gets down to a quid a share, I’d be tempted to pick up a few (currently down 47% at 124p).
The balance sheet looks sound, with NAV of £132m at Dec 2021, including £20m freehold property. So writing off the JV receivable of nearly £20m would not put HOTC into an existential crisis. That hit can be absorbed fine, I reckon.
Obviously questions are going to be asked about management competence, and there will be a lot of very unhappy fund managers berating them I imagine. Management have controlling stakes, so probably won’t be going anywhere, and will be more motivated to fix things than anyone else.
HOTC is starting to look interesting. Not quite a value share yet, but not far off.
.
In Style group (LON:ITS)
49p (down 34% at 11:28)
Market cap £26m
Poor results from this eCommerce fashion business. It’s sub-scale I think, and isn’t making any money.
Revenue £57.3m (up 28%)
Loss before tax of £(1.5)m
I ignore EBITDA, because development spend of £1.4m was capitalised onto the balance sheet.
Net cash has halved to £5.8m, but boosted post year end with an invoice discounting facility for wholesale receivables, only costing 2.0% p.a. per note 19, so there must be additional fees I imagine, as 2% doesn’t sound realistic as an all-in cost of the borrowing facility.
Outlook/guidance - admirably clear, but it's not good news - expecting £2.0m EBITDA loss for the year.
My opinion - I don’t think ITS should have floated, but it’s one of many eCommerce businesses that took advantage of the pandemic boost to take money from fund managers with an overpriced float.
This is a crowded space, with lots of me-too operators, with very few actually making any money.
ITS has enough cash to keep going for maybe another couple of years, but it’s difficult to imagine that a consistently profitable business is likely to develop here, given that it’s up against bigger & better competition. Shares are likely to continue in a slow, downward trajectory to zero eventually. Maybe they can pull something out of the hat, you never know, but it doesn't look a viable business to me.
.
Graham’s Section:
Begbies Traynor (LON:BEG)
Share price: 144.7p
Market cap: £222m
We have covered this professional services firm in good detail previously.
Paul covered the year end trading update in May, and I covered an acquisition they announced in June.
Here are today’s results for FY April 2022:
- Revenue £110m (2021: £83.8m)
- Adjusted PBT £17.8m (2021: £11.5m)
- PBT £4.0m (2021: £1.9m)
The adjusted PBT is in line with what was expected, as of last month.
As a reminder, there has been lots of acquisition activity at Begbies. Therefore, while total revenue is up 31%, the organic revenue growth is merely 7%.
I tend to think that organic growth should drive the valuation at most companies, because it’s higher-quality growth.
However, if you trust a company’s ability to deliver successful acquisitions over an extended period of time - and arguably Begbies deserves that trust - then it becomes plausible to give credit for both organic and non-organic growth!
The importance of your view on the acquisition strategy becomes even more clear when we consider the huge discrepancy between adjusted PBT (£17.8m) and actual PBT (£4m).
The difference is explained by “transaction costs” and amortisation of intangibles:
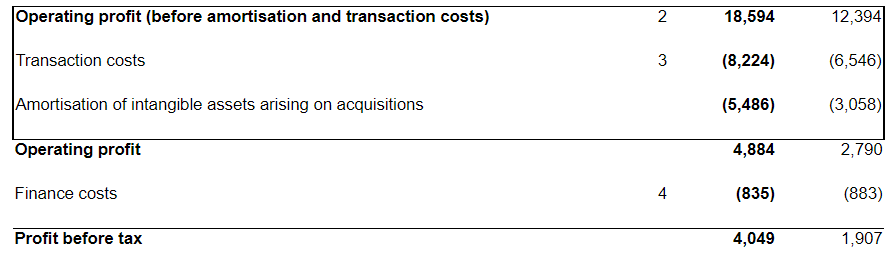
So what are these transaction costs? They do include M&A fees, but actually their main component is something called “deemed remuneration” (please try to stay awake at the back!).
Definition from today’s RNS:
Deemed remuneration, which relates to acquisition consideration, where the vendors have obligations in the sale and purchase agreement to provide post-acquisition services for a fixed period. This consideration is charged to profit over the period of service;
If I try to put this in Simple English: this means that when Begbies buys a company, part of the cost is allocated to payments for the sellers to continue working. This cost is then charged to the Begbies P&L over time, as the work is carried out.
Is it reasonable to adjust this out of PBT? Well, we are now venturing into opinion. Some people will say that it’s fine to adjust it out.
Personally, I would be a little cautious - because I’m not sure that the acquired companies would have generated the same level of revenues, without this work being done. What was the nature of the work being carried out, and what would have happened if it hadn’t been done?
Also, I’m not entirely sure about what will happen in future years, when the sellers inevitably walk away or retire. These are people-based businesses, after all.
It’s the same when we talk about amortisation of intangibles. Some people will say that it’s an accounting fiction, and there is no problem adjusting it out.
And while I agree that the accounting rules are far from perfect, I’m not happy to completely ignore the cost of acquiring intangible assets, such as customer lists.
So for me, the truth is somewhere between the adjusted PBT and the actual PBT. And if I put my sceptical hat on, I get an answer closer to the actual PBT!
Cash flow - when the income statement is very complicated, it’s useful to sense-check the results with a look at the cash flow statement.
At Begbies, the net cash from operating activities for 2022 comes in at £9.8m. This is a useful starting point from which to value the company, in my view, that gets away from the complications on the income statement. It’s an after-tax figure that is effectively “the bottom line” in cash flow terms.
The only proviso I would add is that there were share-based payments of nearly £3m (including payments for deemed remuneration) that serve to inflate the Begbies cash flow. I would therefore be inclined to value Begbies on “real” cash flow of c. £7m. But there is scope for a wide range of views on this, and some people will prefer to stick with adjusted PBT.
Outlook - Begbies has benefited from, and is likely to continue to benefit from, the economic disruption we are experiencing:
Started new financial year in strong position and confident of delivering plans for further growth towards the top end of current market expectations*
Insolvency market (by volume) has returned to pre-pandemic activity levels and is expected to increase further in the current year and beyond
Development of group and our extensive areas of expertise, leaves us well positioned to respond to the challenging economic backdrop
Full marks to Begbies for including in the RNS the FY April 2023 analyst forecasts: revenue of £110.0m-£118.0m and adjusted PBT of £18.5m-£19.7m.
Dividend - the total dividend for the year increases to 3.5p (value £5.4m). The company has an excellent dividend track record and the dividends are covered by free cash flow.
Balance sheet - £85m in net assets, but only £9m after deducting intangibles. The company reports a net cash position of £4.7m.
My view
I’ve always had a positive view on Begbies, and I’ve been impressed by the smooth integrations achieved during its acquisition spree.
My concern now is primarily to do with its valuation. I’ve seen professional services companies go badly wrong before - they are people businesses, usually with limited tangible asset backing, and unpredictable earnings. This needs to be accounted for, in the valuation.
To me, the current valuation at Begbies is pricing in an avalanche of insolvencies. And while I agree that such an avalanche is probably on the way, I prefer to buy cyclical companies when this sort of upside has not already been priced in.
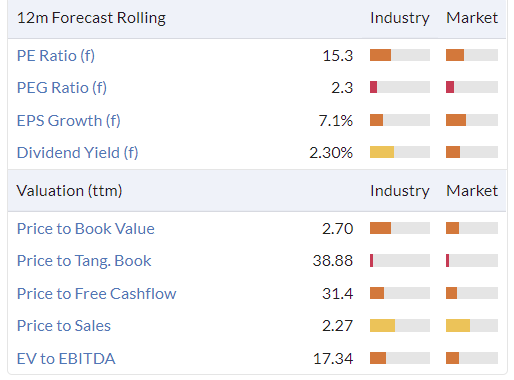
I’m not completely alone in my view, as I also have the Stockopedia computers for company. They struggle to find value here, and award a ValueRank of only 20.
So I give huge congratulations to Begbies investors for the capital gains they’ve earned, but I suspect that the easy money has already been made here, and that the shares are likely to be “up with events” at around their current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
Luceco (LON:LUCE) Electrical compliance legislation was introduced in 2020 affecting 4.5 million UK rentals. There was a lot of electrical work done around that time. No doubt this would have boosted Luceco sales given that they have a significant UK marketshare. Not the only reason for a relatively poor 2022 but surprised the management did not factor this in to their forecasts.
Paul thanks for the Boom analysis - very pleased to hear the other side, useful reality check
Paul's campaign on AIM research is starting to gain traction https://www.standard.co.uk/bus...
Luceco LUCE It is worth mentioning that in March 22 the co completed the purchase for £10mn of the 80% balance of a Surrey (largely) residential EV charger supplier called Sync EV. This will partly explain the rise in debt I suspect but this was also driven by destocking and the resultant build-up of inventory last year. This is apparently reversing now. EV charger supply and installation is a big growth area, but a competitive one which seems to me to be a good fit with Luceco's main business areas, lighting and wiring.
Technically iomart (LON:IOM) has bounced of support and bottom of the channel after a recent sell off.
Technically iomart (LON:IOM) has bounced of support and bottom of the channel after a recent sell off.
........meaning what?
It fell a lot, then went up a bit.
NWOR (I hold) national world now down sub 17p
Stockopedia says market cap now 35 million .
There have been a few director resignations in the past few months that might have further affected sentiment .
With over 20 million in cash and 9 million in operating profit this is currently seemingly totally unloved and under the radar .
Share price always spikes up significantly after results but then drifts back to silly levels .
I wonder if the exiting directors are selling continuously into a very illiquid and weak market just grinding the price lower.
Does feel to me like a bargain and “Mr Market” is throwing up a long term opportunity, unless I’m totally missing something and there’s something going on .
Updated an in-line update at end June when price then spiked to 25p so can’t see much having changed since then .
Hi planetx, quoting somebody from somewhere "a bargain can stay a bargain for a long time." I have been in and out of these several times with not much success. It strikes me that traders love it and play it accordingly. Truth is few want to invest in a declining story but short term news allows traders to in and out on the back of short term filip driven by themselves. Just my interpretation...it could be directors or equally a combination of, still won't have a place in my portfolio again until it can deliver a compelling story that is.
National World (LON:NWOR)
Hi planetx
I actually looked at National World (LON:NWOR) the other day based on your comment a few weeks ago.
I was quite bullish when I started working through the numbers, but by the end I decided that there was actually too much risk involved and things weren't as good as they seemed (to me at least.)
Working through what we know from the last trading update I come to an FY22 operating profit of £6.4m:
But then there is £2m of Capex expenses (I think they said this in the AR) and £1.6m for leases, which brings cash generation down to £2.8m.
Net Cash is currently £21m (I've taken off the final deferred £2.5m payment due March 2023 here) so the current EV = £23m
---
So, we're paying for an FCF multiple of just under 10% and hoping that:
Both seem like big risks in the current climate and I feel that the 10% FCF yield could drop significantly.
---
For clarity I've assumed print costs increase 20% this year and labour costs only increase 2%.
There could of course be value here, but with so many unknowns I decided not to take a position for now.
Cheers
A
Thanks for both comments that’s really good feedback as to other perspectives .
I’m going to maintain it as one of my core six holdings (equals , Crestchic , somero , holders , Sureserve , Vertu) .
The reason is quite local and despite what is perceived to be a declining market I know that the local titles they hold , the Sheffiekd star / telegraph and Yorkshire post are all brands that are very strong and for 100% sure have longevity .
I ask myself on all my core holdings - would I buy the company outright if I had the chance (and budget and energy and skill set )
At current market cap with that cash in the bank for 100% sure I would buy it so that remains my acid test fall back question , when that changes really is the time to sell , but I do love the Yorkshire post on a Saturday .
National World (LON:NWOR)
I agree with you on the long term power of Sheffield Star/Yorkshire Post, etc...it's amazing how many links I'm being sent by friends from local newspaper websites during the current football pre-season.
On a separate note, thank you also for pointing me in the direction of Crestchic (LON:LOAD) a few weeks ago. A fascinating company, which seems to be in a sweet spot right now.
Cheers
A
Crestchic is a great bet , I topped up quite heavily at 192 // 194 last week .
It is towards the top of a trading range right now , it may well punch though into a higher range but if I was you it may come down briefly in the late 180s but doesn’t stay there for long .
I couldn’t believe how tight there previous facility was , must have been a production nightmare and that explains the leadtime / backlogs .
With the new warehouse they should be able to reduce leadtime and vastly improve efficient production , hard to see them not building from here and having a strong next 3 years .
Personally I think they have underestimated their matket and in 3 years the new facility will be at capacity .
But as my old FD used to say “that would be a great problem to have “
National World (LON:NWOR) I was very attracted by the low valuation, 50% of book value, but was put off when I noticed that Harwood sold out in February. But I'm easily put off, I'm amazed I ever buy anything really. https://otp.tools.investis.com...
And Hotel Chocolat (LON:HOTC) I held also at an average just under £2 I sold for a small profit
And Hotel Chocolat (LON:HOTC) I held also at an average just under £2 I sold for a small profit
And....?
If everyone announces their trades here, we'd get tens of thousands of messages, none of which would be of any use, or interest, to anyone!
Used to hold Luceco (LON:LUCE) and Audioboom (LON:BOOM) a few years ago at 33p and 3p. Another 2 companies I missed out on huge profit.
Does anyone understand why the 'unbilled income' figure for Begbies Traynor (LON:BEG) (I hold) is so high? £35m seems pretty high given the turnover.
Not certain, but my bet it is because they will start work on a client without a PO knowing that they, as insolvency practitioners, will have first call on any residual funds. No PO no invoice.
I think it was here that there was some recent speculation that the younger generation would keep spending on the reasonable grounds that they are living at home and don't have to pay the gas bill, but would still be getting a cost of living increase on their wages. So, interesting to see reports of research by Retail Economics and Grant Thornton that said the opposite. According to the Torygraph:
"Younger generations are more likely than Boomers to cut back on groceries, clothing and going out, with the typical household set to slash £887 from their discretionary spending.
Six in 10 Gen Z consumers plan to reduce spending on food and fashion compared to less than four in 10 Boomers. Three-quarters of Gen Z are cutting back to afford a holiday while just a quarter of Boomers are.
The analysis suggests non-essential spending will plunge by £25bn in the 2022-23 financial year..."
p.s. I'm not sure how 60% of Gen Z are cutting back on food and fashion, yet 75% of them are cutting back to afford a holiday, but that might just be the DT hack's interpretation. I think we can still get the idea.
Morning,
Yes I saw that Telegraph article about generational spending. The comments section is particularly horrible - with inter-generational cat fighting in almost every post. What is wrong with these people, why can't they be polite in the reader comments, like we are here (usually!)
Trouble is, it was only a survey. I suspect that people often give the answers they think they ought to give, when asked anything. We saw that with fast fashion - they act horrified, and answer surveys by saying they will boycott supposedly bad companies (virtue signalling basically), but continue spending unchecked.
I'm finding it particularly difficult to work out which sectors are seeing the downturn in spending, as we seem to be getting quite a few contradictory announcements - e.g. J D Wetherspoon (LON:JDW) bad, but Loungers (LON:LGRS) good.
All fascinating, seeing how this unfolds.
Regards, Paul.
On the survey, you might well be right. That might also be the reason why 75% of Gen Z said they would cut back for a holiday, but perhaps only 60% seem able to identify what they would cut back on.
Surveys are not respected by everyone. I recently conducted a similar but slightly less scientific survey, over a pint with some friends and found that 100% of us were planning on cutting back in some way. However, on reporting my results, I was met with a response that went along the lines of: "they're probably all old Scrooges like you are".
My mechanic told me a novel way to cut expenses. One of his customers brought his Merc C Class '16 reg in with a 'f*cked engine' (sorry for the technical jargon) 4 months ago. When the mechanic informed him of the engine status said customer didn't return to collect saving him the price of a new engine.
A bit more detail here:
https://www.retailtimes.co.uk/...
A few selective quotes:
Quite startling, I thought, was the comment:
timarr
About 15% of households are on universal credit - so 36% from a survey sounds bad but may well be roughly true.
That brings home the problems we face.
Interesting re: UC.
With the reported upcoming increases in gas my bill is set to peak somewhere between 300 & 400 a month this winter. My house has a B epc and is well insulated. The government is deducting £400 from energy bills but I think this will still leave many floundering especially when you consider my pre covid gas bill would have been around £500-£600 a year. That will probably buy 6 weeks of heat this winter. Grim.
the best review of my favourite share.
Beg is an excellent company priced for perfect market conditions.
I may trim my holding after Paul’s remarks.
Lucky dip,
It was Graham who reviewed Begbies Traynor (LON:BEG) actually.
I'm more positive on BEG than Graham. Although I wasn't aware of the deemed remuneration line in the adjustments section. That would need looking into, as I don't fully understand it!
Regards, Paul.
Photo-Me International (LON:PHTM) I have been a holder for some years and have high regard for Serge Crasnianski. Always look for any hidden jewels in balance sheets and PHTM has one potentially in its French freehold investment property, in the books at £585K. This has been held many years and in 2011 they sold the following 8 years rental income for a lump sum at the time. Property reverted back to them in 2019 - only valuation I can see in 2018 was 7.7M euros. Rental income seems to have dropped last couple of years ("Other operating income") maybe covid related, but overall gives comfortable feeling.
Paul on Photo-Me International (LON:PHTM) "A big thumbs up from me."
I struggle to see it. The headline from Photo-Me International (LON:PHTM) is:
"Revenue was up 21.9% to £115.3 million (H1 2021: £94.6 million), resulting mostly from the continued easing of Covid-19 related restrictions across the Group's key operating markets and subsequent positive impact of increased demand for passports and other official documentation"
So, with Covid restrictions easing, people wanted to go on holiday and needed a passport. This is obviously a one-off and says nothing about the future. So what will the future hold? Are photo booths the future? Not really. Are laundromats the future? I struggle to see that. Food vending machines anyone?
This seems a well run business and there are some good numbers here, I would agree with that, but when they say "The opportunities for the Group and our consumers are endless" that's the part I struggle to see. It might be my ignorance but I don't see these as real growth markets. Equally, when they say "our strong proposition and market position gives the Group significant pricing power" I would believe that to be true in relation to photo booths, but will that apply to laundry and vending machines? Photo booths make up more than half of revenues, but that seems to me like a market in decline. What then?
I think the market for the washing machines is significant. A few days ago I went for a weekend break to Cheddar. An evening stroll with my daughter found us passing a petrol station with 3 large glitzy stainless steel washing machines right out front. All three being used. They looked good. On closer inspection owned by £PHTM - The area was typical suburban Britain - mix of houses, bungalows, semis, terrace and probably some houses converted to flats. Not super affluent - but equally not run down - just average (probably better than average to be honest). So it seems to me the washing machine business could do quite well. I know it's a sample size of 1 - but I think likely to be typical. I hold.
Those big machines are good for things like duvets that don’t fit in domestic appliances. Also people wash things like horse blankets and other things they don’t want to put through the machine at home.
Where there’s much there’s brass type operation. Always going to be a need for it.
Photo-Me International (LON:PHTM)
We have to understand the difference between the UK large house home owner, and others. Especially so when you look at the Continent which is a big part of the market.
I would agree on the washing machines in the UK. There is one in our local garage, two machines, will start to have a check when I go past but with the dry cleaners closing just before Covid (so 8 mile drive to the next town) there will be a pick up on things like Duvets - remember the joys of babies being sick on them, and also agree with the dog towels (lots of them still around here) and horses etcetera, and no doubt things like the local football teams, where someone used to do several loads to get them through, one at the garage and the Better Half not in a grump has to be a winner.
Must mention to my sister, might be a solution for the youngest concrete covered site gear!
Tommy
A bit more scuttlebutt..
I recently returned from a holiday to the Alps where outside a very large Carrefour was a small building (like a garden summerhouse) containing at least 4 or 5 washing machines that always seemed to be in use.
Next to that was a small telephone box sized machine (for those that remember telephone boxes) which was a pizza vending machine and again it regularly had people using it. It seemed unattractive to me but my kids assured me that the quality is good (from their mates feedback).
It seems to me that there are enough people nearby that the demand for these services will continue and I suppose that the supermarkets are happy if it keeps people in their shops whilst also getting a small income from the space/lease, whilst Photo-Me International (LON:PHTM) will get prime sites and not have extensive lease costs like the old style laundrettes.
Based on the last two TU's/results I took the plunge this morning.
Photo-Me International (LON:PHTM) I hold
An alternative view:
The death of the photo booth has been over stated. Having done a selfie for my last passport I realised it woks have been much better to pay £5 and get it done properly.
The UK is the only country allowing selfies and there is talk that this is less secure than photo booth photos. There are new booths that include biometric data with photos. Making it less likely that other countries will follow the UK and it is possible the UK will reverse the decision to allow selfies.
The laundrette business is now over 30% of turnover and has excellent margins. The growth rate is significant. This is Zulu principal style growth where you get high margin growth at a low cost.
I’m not sure about the food business but it could be additional sales from existing sites and cuts out the high cost of employing someone.
The news flow is all good and the figures look excellent. In the current market environment I can’t find a better story and (not surprisingly) it’s my biggest winner since the market started going backwards last year.
The UK is the only country allowing selfies and there is talk that this is less secure than photo booth photos. There are new booths that include biometric data with photos. Making it less likely that other countries will follow the UK and it is possible the UK will reverse the decision to allow selfies.
There are lots of countries where a digital photo can be submitted for a passport renewal.In the US: https://travel.state.gov/conte...
And New Zealand:https://www.passports.govt.nz/...
And Ireland: https://www.dfa.ie/passports/p...
I'm pretty sure I've seen others too - Singapore, Taiwan, etc.
It would also be interesting to know what the "talk that this is less secure than photo booth photos" is actually claiming.
The original passport application must go through the traditional process - or involve a new one that includes facial biometric capture. When you submit the digital photo for the renewal they do a biometric check to make sure it matches the old one. Exactly the same process is run on a photo booth submitted photo so I don't understand how this is less secure?
timarr
Pre close update out of City of London Investment (LON:CLIG). Weak results; emerging markets are having a rough time so AUM has fallen. I hold but now rate these as a weak Hold. Also an update out of Palace Capital (LON:PCA). Looks very much like a wind down and disposal. Again I hold and rate them as a weak Hold. It's becoming a very tough market, I think, with lots of companies still overvalued due to falling profits. I'm down 13% this year and will probably end up worse. Time for extreme caution; my private equity funds are now on enormous discounts, effectively forecasting a sizeable reduction in asset values. I suspect that these at least are oversold.
I hold City of London Investment (LON:CLIG) in mum's pension (ISA), it has been held for a long while as part of an income strategy, and has paid out nicely so far. ~5% position.
Obviously with my 20:20 rearview mirror, should have sold last Autumn and taken the capital gain and sat with a smug grin...
I had tried selling at one point earlier this to reduce to 1-2% but on a couple of goes one day, I could not get a response (IWeb) so just sat tight. I had sold out of Premier Miton (LON:PMI) and Polar Capital Holdings (LON:POLR) that day to protect capital on the basis of see what happens and can always buy back (typically higher with my lack of skill) - think that they have fallen ~15% since.
I need to re-read as the screen on the phone (iPhone SE 2016) are not coming up right, I think there is a reduce to 2% and see where the year goes. Yes the Dividend looks good, but how much capital is going down to get that?
Nothing much of a surprise, just trying to make the right decisions.
Tommy
What I found encouraging from City of London Investment (LON:CLIG) is they are getting net inflows despite the turbulence - this had been a problem in the recent past and getting new client money now no longer looks like a problem. That for me was previously the main bear case on the share. The FuM performance was inevitable in the current market and actually is offset by the fact that the dollar is strengthening. So I thought this update looked alright especially as the dividend is still fantastic and well supported by the cash position even if EPS falls further temporarily.
i am also intrigued that you see the Palace Capital (LON:PCA) update as negative whereas I read it as a chance to get cash at or above net asset value which it currently trades very far below.
1Spatial (LON:SPA) ( I hold)
A small cap that keeps winning contracts. Today is a European defence company for its 1Telecoms product, this is a first win for this product. Shares have remained stuck, feels like a victory this year:)
I see Hotel Chocolat has been hit very hard. This has had a lot of institutional fans historically but I could never make valuation work. May be more interesting now.
Morning all,
Hotel Chocolat (LON:HOTC) very much down to earth this morning. I'm not a holder as i felt it was overvalued much above 300p but keen to hear Paul, Graham's or other readers thoughts now. Reads to me like it initiated a mumber of growth strategies and some of these have bitten them quite badly, blowing capital in the process. I'm now wondering if this could be in value territory now? I like the brand, the shops and a lot of the product, & have also bought (mainly presents for staff) from the online offering, and have always had a good experience. It's not cheap but I don't completely begrudge the cost, I know I'm a bit of a tightwad!
Morning Mark,
I saw that Hotel Chocolat (LON:HOTC) is down 45% this morning, so am looking at it as we speak! Section should be up by about 10am.
There are loads of interesting companies reporting today, so I'm enjoying myself, and hope to get through as many as possible before I flake out after lunch.
Regards, Paul.
much apreciated Paul.
I love chocolate but found Hotel Chocolat (LON:HOTC) chocolate so revolting that I threw it away. Maybe it’s just my taste buds, but it might be that a lot of others agree including perhaps foreign buyers weaned on very good quality chocolate brands or expensive high quality from small independents.
I seem to remember Paul Scott also disliking the taste of Hotel Chocolat (LON:HOTC) chocolate offering. Not a patch on far far cheaper Moser Roth and Choceur in Aldi and JD Gross in Lidl. And those £1 bars of Aero , e.g Shares with a movie, or Aero dark and mint peppermint or Shareo to make them smile bars, are in a different league too.Try blind tasting any of these against Hot chocolate offering and see if you agree?
So for that reason why alone I’m not tempted to check out Hotel Chocolat (LON:HOTC) as a potential buy just as Deborah Meaden won’t invest in a Dragon’s Den business she doesn’t like. Also I thought Thornton’s chocolate was also way superior, but they also struggled to turn it in to an Investment success.
Tpximpact Holdings (LON:TPX) full-year 2022 results are ahead of expectations. Here's an overview video or podcast.
Management webinar 12 noon today register here.
Sosandar (LON:SOS) full-year 2022 presentation given with results last week is here, video or podcast.
They are on a roll! Granted it's consumer which is covered a lot in the presentation. Their USP is their editorial skills from their magazine background, which drive sales. They feel their demographic is less impacted by the consumer squeeze. Time will tell, but Q1 is super strong and they seem to be proving that so far.
Joules (LON:JOUL) : Needs more debt, losing money and sale growth has fallen dramatically.
It's comforting to see the bank extending borrowing levels by c.5m however it is very short term, only until November.
I think there is a read across here for mid/ market retail or the 'middle income' subset. It seems this group of people is diverting spending from this category of clothes/ garden e.g. to holidays etc and perhaps drawing their purse strings in anticipation of a bleak winter.
These market moves are temporary however and I wouldn't be terribly concerned if I was a long term holder and was content that their long term durable advantage was intact, unfortunately it's not obvious that it is at the moment.
Hi Marmite,
Joules (LON:JOUL) (I hold) is on the list, but there are more important things to look at first.
The short version, is that today's update is a big reassurance, at least for the short term, as you say. I was worried that the bank might be withdrawing support, following the appointment of KPMG.
I don't think there's necessarily read-across to other mid-market fashion companies. It seems to me the problems at JOUL are entirely self-inflicted - the product isn't good enough for the prices they try to charge.
At least the risk of it going bust has just dramatically reduced. Maybe the bank extended the facilities on the understanding that a placing will be done?
Regards, Paul.
At Joules (LON:JOUL), in exchange for providing more cash, I presume Barclays (LON:BARC) will now have first call on the Joules (LON:JOUL) headquarters (in exchange for the additional headroom) as I guess the company has little else of any value. Presumably that is worth more than the extra cash Barclays (LON:BARC) would be advancing.
The way I read this, Barclays (LON:BARC) has zero trust in Joules (LON:JOUL) and is doing all they can to reduce their likely loss here…. …or enable them to trade out of this whilst minimising their exposure.
Hi Paul,
Fair point on the placing that helps makes sense of the very short term extension to credit. I viewed it as comforting for shareholders but now not sure how to take it. Sure it won't go bust in the next 6 months but it's obviously lost at least £5m more than it thought it would a few months ago. This may be even more given the debt position has also increased (unsure of typical cashflow position at this time of the year). It will be interesting to see how this unfolds. Its going to take a good amount of money and real revision of their strategy to turn this around, could this face say a 50% dilution? at 25m market cap? Potentially discounted?
I agree very poor management looking at it from the outside, Next (LON:NXT) faced all of the same headwinds but seems to be on well telegraphed even footed guidance.
RE. Mid market yes I suppose you're right. Perhaps the read across is less fashion facing and more towards staycations, garden furniture, expensive used cars, cafe horse containers etc I associate Joules (LON:JOUL) with countryware ('Barbour lite' - farms, countryside etc) all great benefactors from the lockdowns and the ensuing quest for space. People shifting back to items they've been unable to spend money on over the last couple of years, occasionwear, holiday clothes etc.
H1 update from Alphawave IP (LON:AWE) today, I would appreciate you having a look at this, appears in line, but not easy to understand. There has been heavy recent director buying recently by former founder of Marvell Technology Group, mr Sehat Sutardi. Provided they close the takeover of OpenFive in H2 this looks like a good long term technology investment?
Whenever you look at Alphawave IP (LON:AWE) remember "Bookings" are not revenues, and TSMC's recent comments regarding double booking are interesting....
The key bit of the update is the footnote:
Our bookings comprise in some instances, our estimate of potential future royalties. Our royalties are estimated based on contractually committed royalty prepayments or, in limited instances, on sensitised volume estimates provided by customers.
And that is all before you then consider the matters raised in the FT article of Sept last year which drew attention to contracts with potentially related parties.
Photo-Me International (LON:PHTM) - even after today's rise it is still on a forward p/e of under 10x ! Unbelievable !
Well worth reading the £MINI (Miton UK Microcap Trust) Annual report for anyone interested in UK small and microcap stocks.
Excellent assessment of the market from managers Gervais Williams and Martin Turner.
They currently believe that small company strategies have the potential to deliver premium returns relative to international comparators, although also comment that in the short term there may be continued market turbulence
2022 Annual Report, Final Dividend and AGM Notice - 07:00:07 19 Jul 2022 - MINI News article | London Stock Exchange
Thanks for the link Yellowstone Advisory. Interesting to hear their many opinions although I guess you would expect them to be bullish about the microcap/smallcap sectors in which their funds are invested.
Useful link, thanks. They mention specifically MTI Wireless Edge (LON:MWE), Accrol group (LON:ACRL), Avacta (LON:AVCT), and their list of holdings reads a bit like the SCVR which I suppose is what one would expect. I see they have spent a chunky sum on a PUT option over the FTSE100 at 6200 December 2022.
Interesting update from Palace Capital (LON:PCA) this morning. In the face of a shareholder revolt it has changed its strategy and now intends to sell a large chunk of its property portfolio and return cash to shareholders. This is interesting given it trades significantly below it's NAV per share (c.270p Vs around 380p NAV per share). It's usually been able to sell properties above book value. It feels to me like the company is being wound down with the remaining properties likely being offered for sale later. Any other views? (I hold).
Good update from Somero Enterprises (LON:SOM) this morning. It does make me think about backlog. I work in construction, and the pre-construction process such as planning/design etc did slow down during the pandemic. We all know about the skills shortage, and I also believe there has been been a degree of hesitancy to press the button on some projects, due to inflation busting the budget. I do feel you can see the back log is slowly coming through now. We will see.
We're seeing a bit of this with critical projects coming through but less critical ones facing deferment. Still aim to spend the same amount as before this inflationary period but inflation is eating into project volumes. This works to some extent as the contractors in our segment are also capacity contained.
Also a lot more value engineering or scope stripping e.g from slate roof finish to tiled roof finish. I'm not sure how this translates to warehouses and someros wider market as they are usually just functional boxes from a shell perspective.
A good update yes and the dividend is brilliant, a few years of sustained earnings and an investor could have a significant % of their intial investment back derisking the long term hold.
Yes, very positive update in the context of the present macro economic climate. It would be good to hear young Mr Scott's thoughts?
RE Somero Enterprises (LON:SOM) and to all. I agree with all your comments, though previous history indicates it is cyclical. They have built a lot into their new unit in Wisconsin I think it is, so that should start to pay back in the next year, though that may also be when the backlog has unwound and the cyclicality comes in. A positive meets a negative. Just a thought. Heart tells me to buy more on weakness. Head tells me to hold some cash and wait.
I honestly think that it would be more useful to look at the balance sheet and the cash flow , than the heart and the head dilemma!
Richard Leonard's MADE position (that he was so super bullish on in his PI world video last year) has taken an almighty battering. I wonder what he will be saying about it in his next update....
Not the only one, did he not have Reach (LON:RCH) and National World (LON:NWOR)
Rustbucket - correct.
Don't get me wrong, we all pick losers but he has a very arrogant style of talking. I remember a few times he mentioned re: Novacyt on a PI World interview: "I could make a lot of money on here, a LOT" - then of course NCYT crashed back down to Earth, but naturally he claims to have sold most of his position at the top....
Hopefully this will curb his arrogance.I doubt it though.
Hi Dulpesh,
Oh I like Richard Lennard (never met him), as his style is good fun - eccentric, slightly bonkers, especially when he refers to himself in the third person, which I find highly amusing!
But (like me) he'll probably do best to eat some humble pie, given poor performance & some terrible stock picks.
Regards, Paul.
Personally I'm finding humble pie a bit boring. I need a change of diet.
Reach (LON:RCH) was one of my biggest losers back in the glory days of 2020, finally sold way too late and then watched it all go up again.
It is back on the watch list (as income holding) but waiting for it to start to level out, and also looking at the continually falling earnings as suspect the dividend might not stay secure next year.
Tommy
Reach (LON:RCH) I think great recovery play at some point but seems to be facing so many headwinds and I suspect it could go even lower - higher print costs, potential strikes, lower advertising spend, etc
Reach - Their websites are awful too. They have lots and lots of regional papers, with a huge potential audience online but the stories are almost impossible to read. Completely wasted opportunity, the web development team need to ditch the format and start again from scratch.
I agree with that, I find their websites very cluttered and user unfriendly - tbh I struggle to see how they derive much ad revenue from them as it seems to be lots of irrelevant, pop up ads. That said, revenue growth has been fairly impressive on the digital side so they must be doing something right.
Reach (LON:RCH)
I totally agree. They took over my local paper and ruined the online readability. The old site was a single column of nearly all local stories that could be sorted in order of when written or when last commented on. Now it is a total mish-mash with no order, different sized items splattered around. Less than half the items are local - click on "Child mauled by dog" and you find it is from a Reach local site hundreds of miles away. Then there is a large scatter of gossip - royalty, Gogglebox, Love Island etc. Just awful to try to read, so however good a case may be made on these boards I will not be buying their shares.
I heard that too. Super bullish is possibly an understatement. He was selling it as a sure fire thing, and we all know there is no such thing in investing.
Yes. He was also big on a turnaround at Ted Baker (LON:TED)
I quite enjoyed what I thought was old fashioned Broker style brash confidence, or dare I say, overselling the ideas, but didn't take it too seriously.
It pays to be selective
Thank you Dulpesh. Re Made.Com (LON:MADE) yes I remember that. His justification for a recommendation at around 200p!!!!!was very superficial - his children liked it and they and their friends were buying the products. I remember at the time thinking that this guy really doesn't not impress me. Reminded myself to ignore him in the future.
Final results from Begbies Traynor (LON:BEG) as expected today. Current year trading already at the top end of market consensus so would expect an upgrade at the next update in September.
17% divi increase too. Lots to like imo. The only thing keeping my portfolio above water this year!
Good morning,
Excellent interims from Photo-Me International (LON:PHTM) this morning, specially divi of 6.5p announced too along with 2.5p interim divi.
Will you cover today please Paul?
Regards.
Photo-Me International (LON:PHTM) showing some really strong growth. Paul covered it a few weeks ago and thought it was cheap. I suspect this new update reaffirms that opinion. Special dividend is significant.
Yes I love Photo-Me International (LON:PHTM) it's one of my favourite value shares right now.
Section is now up.
Regards, Paul.
Decent update from £YU this morning, impressed!
Decent update from Somero Enterprises (LON:SOM) today.
I'm not sure why they haven't included more actual tangible figures and % around current performance but the keg statement is:
'The Board is pleased to confirm 2022 results are anticipated to fall in line with market expectations for revenues of approximately US$ 138.8m, EBITDA of approximately US$ 47.7m, and year-end cash of approximately US$ 39.9m.'
Looks like a forecast increase in revenue of c.4% with ebitda roughly in line with last year. This seems well telegraphed to me as last year they did indicate the margin wouldn't be quite as strong due the change in product mix as the industry came out of the various lockdowns. Cash down c2m.
This indicates that earnings have some sustainability at this level and if this persists then it is remarkably cheap.