Small Cap Value Report (Tue 23 Feb 2021) - AIR, TSTL, SOLI, FIF, BEG, TRCS, SPR

Good morning, it’s Paul here with the SCVR for Tuesday.
(Today's report is now finished)
Let’s start with some catch up items from yesterday:
Air Partner (LON:AIR) - (I hold) - trading update & dividend policy
Tristel (LON:TSTL) - interim results. Good, but share looks very expensive, and H2 outlook wobbly.
Solid State (LON:SOLI) - Trading update
Finsbury Food (LON:FIF) - interims look resilient in the circumstances. Shares look cheap, in my view.
.
From today's trading updates & results:
Begbies Traynor (LON:BEG) (I hold) - reassuring Q3 trading update. Looks cheap, based on forecasts for FY 04/2022.
Tracsis (LON:TRCS) - in line update. Looks quite attractively priced, in an expensive market.
Springfield Properties (LON:SPR) - a reader request, interim results from this AIM-listed Scottish housebuilder. Looks quite good.
.
Air Partner (LON:AIR)
(I hold)
65p (down 8% yesterday) - mkt cap £41.3m
Shareholder Update & Dividend Policy
Air Partner, the global aviation services group...
Year end is 31 Jan 2021.
...re-affirms the Board's expectation, as previously stated in the Group's trading update of 20 January 2021, to announce underlying profit before tax of no less than £11.5 million for the year ended 31 January 2021 (FY 2020: £4.2m).
I reviewed it here on 21 Jan 2021, pointing out that the £11.5m annual profit is split:
- £10.5m in H1 (benefits from covid related one-offs), and
- Only £1.0m in H2.
We are reminded that AIR raised £7.5m in a placing, and did some cost-cutting.
Acquisition - CHS Engineering was bought out of administration, and will offer additional services within the AIR group.
Cash - looks fine, with what they call normalised cash of £8.3m. Plus debt facilities of £14.5m, currently undrawn.
Dividends - it paid 0.8p interim divi in Nov 2020, and intends to pay a 1.6p final dividend. The total is therefore 2.4p, yielding a reasonable 3.7%. It’s good to remember that a lot of companies are only tentatively bringing back divis, so there’s scope for yields to rise.
Dividend policy is to aim for 3.0 to 3.5 times dividend cover in future.
Current trading & outlook -
- Profitable start to FY 01/2022 has been made, but below last year’s exceptionally strong H1.
- US business is buoyant.
- Other divisions still impacted by airport lockdowns/quarantine.
- Low visibility.
Guidance -
The Board's current base-case expectation for FY22 is to deliver profits in line with the financial year ended 31 January 2020, despite the continued global restrictions on passenger movements.
FY 01/2020 produced underlying PBT of £4.2m, and underlying EPS of 6.4p Therefore this would put the shares on a current year PER of 10.2, which looks OK to me.
My opinion - I like the specific profit guidance for the current year. AIR should see its airport-related activities improve, once travel resumes - seemingly likely by this summer, judging from the very positive vaccine rollout in the UK.
My main problem with this share, is that it has little visibility, and profitability is quite volatile.
I only hold a very small position personally, but might sit on it for a while, as the company’s performance should improve as aviation comes alive again later in 2021. The dividend yield is useful too, so we’re paid to wait.
Broker consensus forecasts shown on the StockReport don’t seem to be consistent with this update, so I would expect them to fall. That might lower the StockRank in future, possibly?
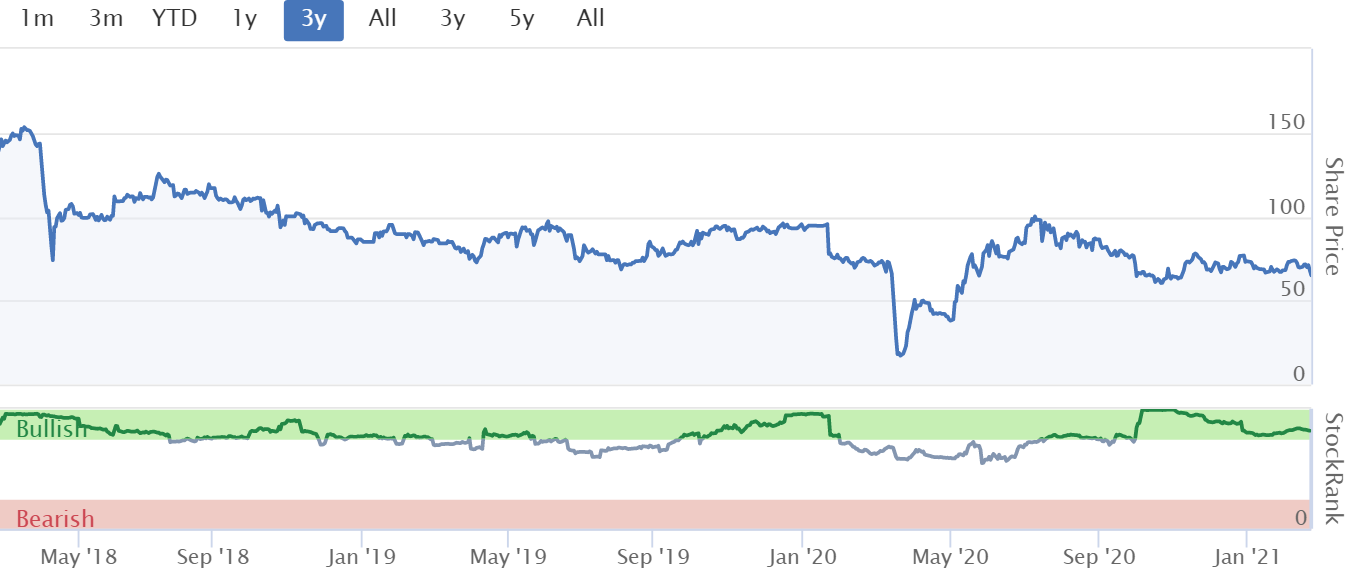
I can’t see myself wanting to hold this share long-term, because it doesn’t seem to be a growth company, and the share price seems stuck in a long-term trading range.
.
.
Tristel (LON:TSTL)
610p (up 2% yesterday) - mkt cap £285m
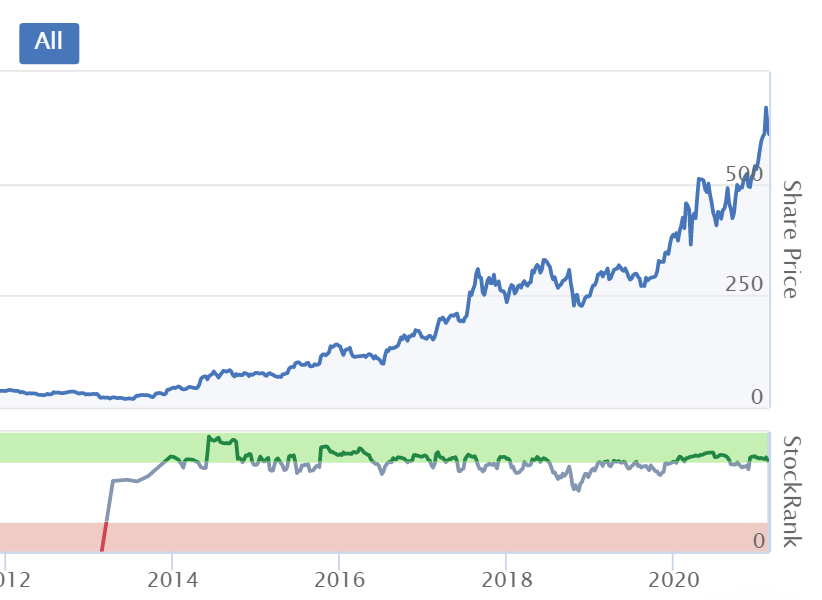
This is an interesting little company, making niche disinfection products. I can remember them doing a presentation at an investor evening years ago, when the share price was below 100p. It’s now 610p. The interesting thing is, that most of the share price appreciation has come from multiple expansion - i.e. it’s now rated on a very high forward PER of 41.6, whereas it used to be priced on more of a value company rating, of about 13. That's a one-off factor, and could even go into reverse, so arguably rather shaky foundations.
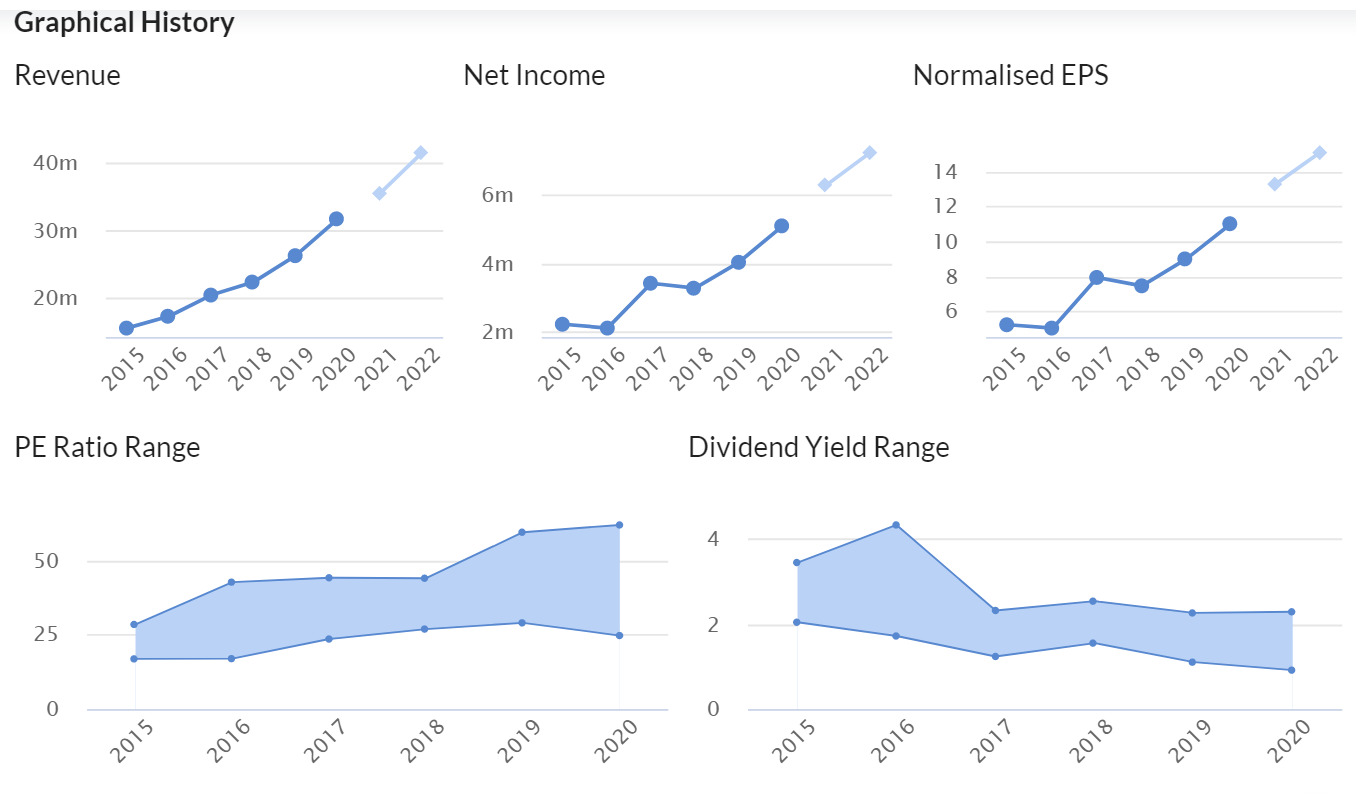
As the graphs below show, normalised EPS roughly doubled from 2015 to 2020, from 5.23p to 10.99p, whilst over the same period, the share price almost 10-bagged. This is also demonstrated in graph 4 below, showing a considerable increase in the PER range. So again, the big gains here have come mainly from multiple expansion, not from profit growth -
.
.
.
Tristel plc (AIM: TSTL), the manufacturer of infection prevention and contamination control products utilising proprietary chlorine dioxide chemistry, announces its interim results for the six months ended 31 December 2020.
The figures look fairly good, but not good enough to justify a PER of 41.6
- H1 Revenue up 15% to £16.8m (at top end of target 10-15% range)
- Strong gross margin of 80%, demonstrating good pricing power & operational gearing
- EPS up 5% to 6.18p (before share-based payments)
Current trading affected by lockdowns still -
Sales of our medical device disinfectants during the first seven weeks of 2021 are lower than budget due to the impact of COVID-19 on patient examinations. We are very confident that by the end of calendar 2021, the ENT, gynaecology, urology, cardiology, and ophthalmology departments where our products are used will have returned to pre-pandemic levels of activity. Whether this will happen in the UK and Europe before our June year-end is unclear at present.
"However, the growth prospects for the Group are as strong as ever and we look to the future with confidence."
H2 sales - difficult to forecast, due to unwinding of NHS stockpiles, and timing of post-covid return to normal for hospitals.
Balance sheet - excellent, no concerns there.
Cashflow statement - fine, it’s a genuinely cash generative business, that is paying divis from surplus cashflow.
My opinion - the cautious H2 outlook comments put me off a bit, as that makes it sound like the company might miss the 12.5p EPS forecast from Finncap for FY 06/2021. At 610p per share, we’re being asked to pay a PER of nearly 49 times this year’s forecast earnings, with a wobbly outlook statement for H2. That seems a very stretched valuation to me.
I think investors are excited about the long-running application for FDA authorisation in the potentially lucrative USA market. Hence upside is being priced in for that. Why would I want to pay up-front for possible future growth? Also, how much business would Tristel pick up in USA? Tristel already operates in lots of countries, only achieving tiny revenues in each. Which suggests to me it’s very niche product. Therefore, how much extra business would come in from USA, and how long (and at what cost?) would it take to gain that new business?
All in all, Tristel is a nice little company, but the share price looks very expensive to me, so not of any interest.
As the long-term chart shows below, patient shareholders here have had an amazing multibagger. However, a profit’s not a profit until you sell. With a PER of almost 50, and a wobbly H2 outlook, I’d suggest that this might be a good time to bank some profits with a top slice. Obviously that’s a decision for each individual investor to make for yourselves.
.
.
.
Solid State (LON:SOLI)
780p (up 1% yesterday) - mkt cap £67m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added supplier of electronic and opto-electronic components, announces a trading update for the year ending 31 March 2021.
- H2 trading robust
- Revenues broadly in line with expectations
- Profits expected to be ahead of consensus forecasts (no explanatory footnote provided), and ahead of LY
- Margins good
- Stronger pound headwind at revenues level, but naturally hedged re profits
- Shortage of semiconductor components could cause delays in FY 03/2022
- FY 03/2022 profit expected to be similar to FY 03/2021
Directorspeak -
"We are very happy with the performance of the business this year. To be upgrading profit expectations ahead of last year, which was itself a record performance, given the challenges all businesses have faced, is testament to the hard work and commitment of the whole team and demonstrates the resilience of the business."
It does indeed look a resilient business, given all the problems with covid.
Broker update - many thanks to WH Ireland for making its research available on Research Tree, which is so helpful.
We’ve got 47.4p EPS for FY 03/2021 (slightly up on LY), then 47.5p for FY 03/2022. At 780p per share, that’s a PER of 16.5 - not particularly good value, considering there doesn’t seem to be any organic growth happening.
My opinion - the business seems to have been resilient throughout covid.
Like most shares, this one has done well in recent months, but looks fully valued to me. I can’t see any appeal to buying now, at this level. Why would a company with little to no profit growth deserve a PER of more than 16? Maybe investors think it might beat forecasts in future?
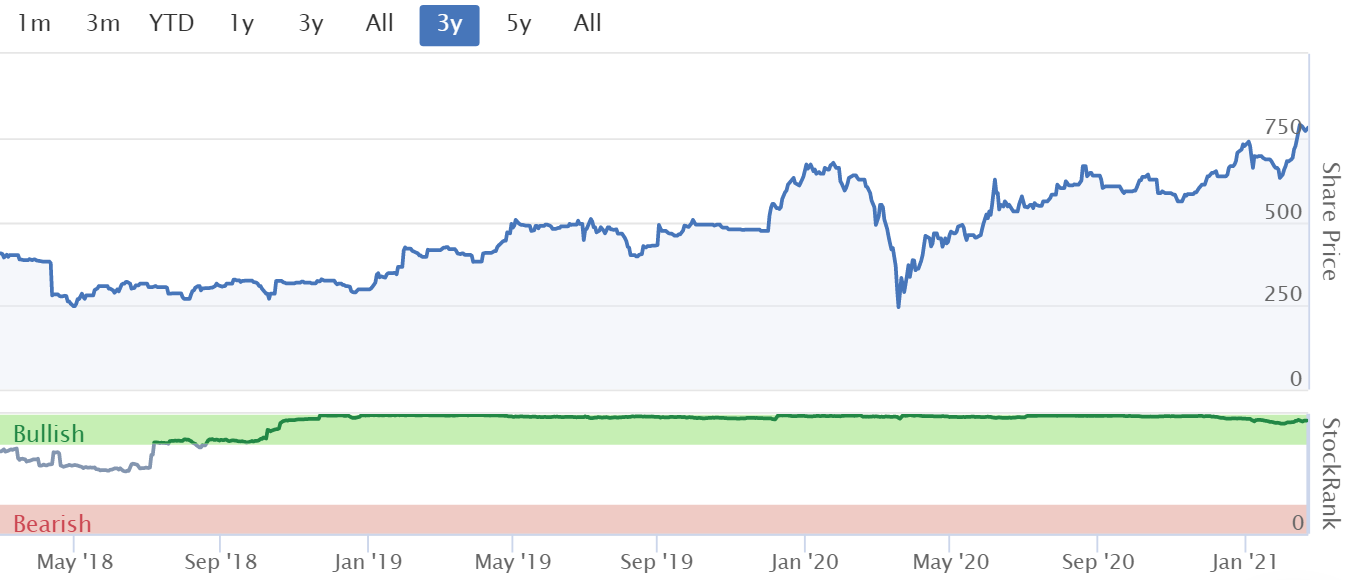
Note the very high StockRank below, so maybe I’m missing something?
.
.
Also, it’s worth noting that semiconductor shortages joins the growing list of macro headwinds being mentioned by lots of companies -
- Semiconductor shortages
- Rising raw materials prices
- Expensive & congested freight from Far East to Europe
- Brexit border problems
- Big rise in sterling vs US dollar in the last year (hurts some businesses, but helps others, e.g. importers)

We should probably be thinking about how these issues might impact companies we invest in. Or, just treat it as normal uncertainty, temporary issues, and ignore it - one of the good things about having long-term investments.
That’s the thing isn’t it? So many people in the markets seem to think they have to be constantly reacting by buying or selling, to every tiny piece of news. Whereas surely it makes more sense to just ride out short term volatility? Depends whether you’re trading or investing, I suppose.
.
.
Finsbury Food (LON:FIF)
71.5p (down 3% yesterday) - mkt cap £93m
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for the retail and foodservice channels, is pleased to announce its unaudited interim results for the six months ended 26 December 2020.
The financial highlights for H1 look fine to me, considering that covid lockdowns & partial lockdowns will have caused many of its customers (e.g. cafes, coffee shops) to have been closed for some of the period.
Although the food retail customers (e.g. supermarkets) have been trading normally.
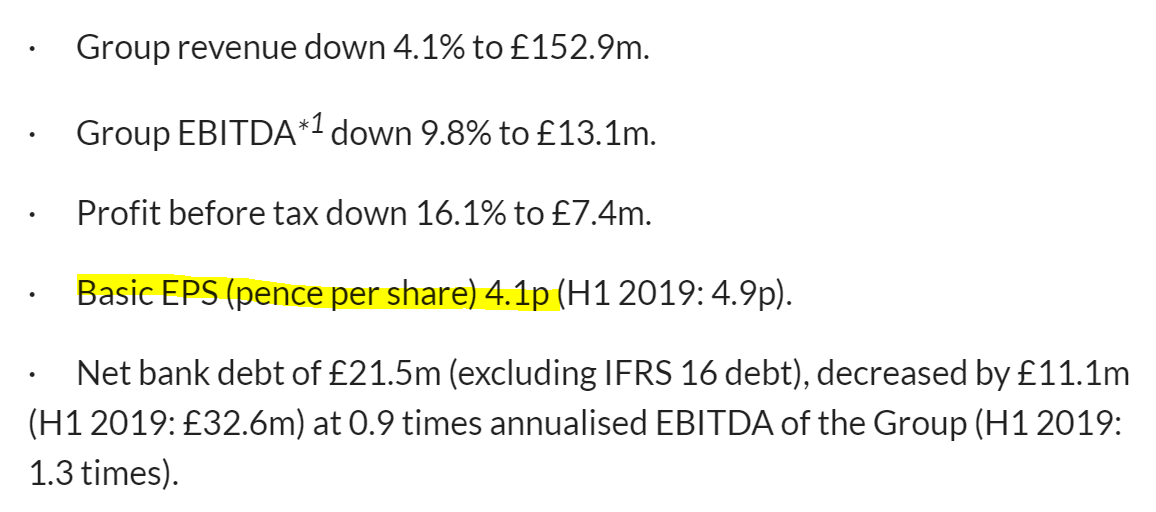
Gross margin increased, now 33.1% - due to operational efficiency improvements.
Brexit - removed a significant risk, but border supply chain issues need to be addressed.
Dividends - suspended, but under review. I imagine these are likely to return to previous levels of 2-3p in due course, implying a future yield of 3-4%
Pension deficit - looks fairly modest, requiring c.£0.7m p.a. cash contributions from the company.
Outlook - sounds cautious, but FIF should benefit from a re-opening of many customers currently closed due to lockdown.
The Board anticipates another resilient performance in the second half
Non-controlling interest is about 10% of profits, which is unusual. There must be a subsidiary which is not 100% owned. Worth checking if you're doing detailed due diligence yourself.
Going concern statement - looks fine, nothing of concern there.
Balance sheet - NAV £104.6m, less intangibles of £87.7m = NTAV £16.9m - adequate, but not strong.
As a presentational issue, I think the company scores an own goal by lumping together bank debt, and IFRS 16 lease liabilities. These are very different things, and in my view should be separately disclosed on the face of the balance sheet, not burying the split in note 6, because a lot of people don’t get as far as reading the notes!
Cashflow statement - impressive, this is a decently cash generative business.
Valuation - consensus broker forecast of 8.12p for FY 06/2021 looks sensible, given that it achieved 4.1p in H1.
Bear in mind that this year has been significantly impacted by lockdown, so next year I would hope it might get closer to say 10p EPS due to normalising of trading as customer re-open. That would value FIF on a PER of about 7 - which seems very good value to me, given that it’s not swimming in debt or pension schemes.
My opinion - although it’s bounced in recent months (what hasn’t?!), FIF still looks good value to me. I see this as an attractively priced value share. IF the lowly PER persists, I wonder if it might attract bidding interest? I could see this possibly being bought by private equity, and with 7 instis owning over 60% of the company, it would probably be an easy deal to do.
.
Begbies Traynor (LON:BEG)
(I hold)
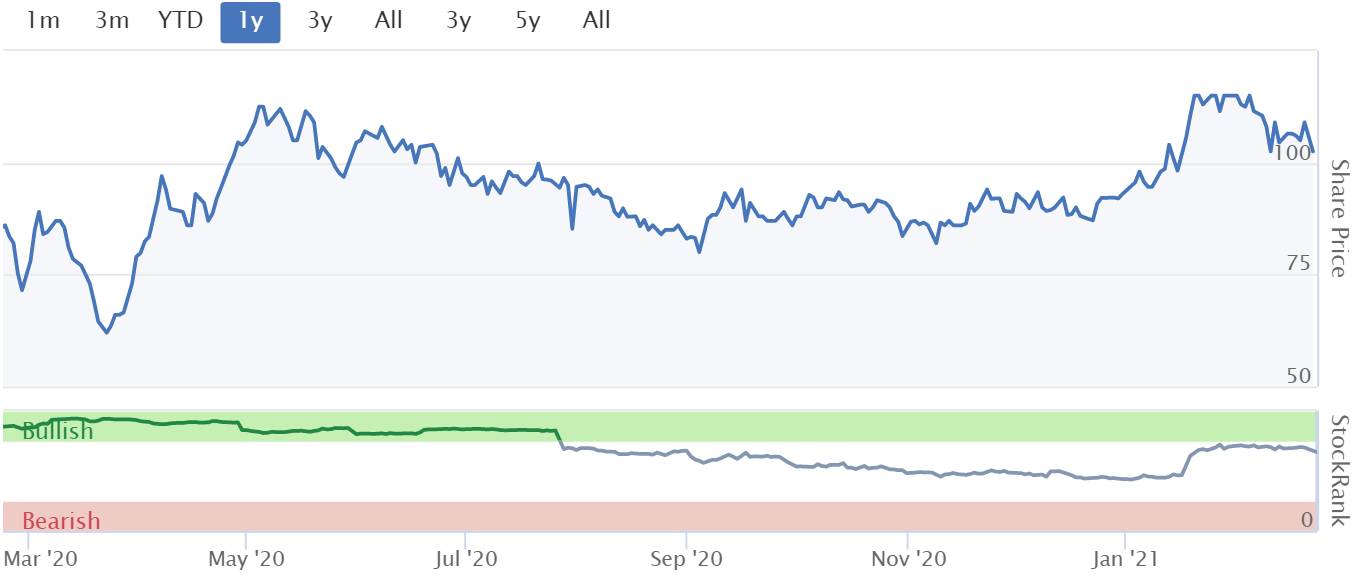
104p (pre market open) - mkt cap £133m
Begbies Traynor Group plc (the "group"), the business recovery, financial advisory and property services consultancy, today issues a trading update for its third quarter ended 31 January 2021.
I’m pleased with this, it sounds reassuring. Key points:
- Strong trading in both divisions
- Confident in full year outcome for FY 04/2021 - at least in line with expectations (footnote: adj PBT £10.2 - 10.7m)
- Liquidity - significant headroom
- Outlook - well positioned to deliver anticipated material earnings growth in FY 04/2022
If we take the upper figure of the company quoted consensus forecast of £10.7m, take off say 20% tax, that gives earnings of £8.6m, divided by 127.9m shares in issue, is 6.7p forecast EPS for FY 04/2021. At 104p per share, I make that a current year PER of 15.5.
More interesting is the growth for next year, partly due to acquisitions, Stockopedia shows 8.66p EPS, which reduces the PER to only 12.0
My opinion - this looks cheap. As we know, large numbers of businesses will need to restructure when furlough ends, which should keep BEG and others busy for a while. Not just with insolvencies, but also with property transactions. I also hold Frp Advisory (LON:FRP) in this sector, which also looks good value and pays divis.
BEG seems to have established a track record of making sensible acquisitions, to broaden its services. That has enabled it to generate good growth, without issuing too many new shares. I wonder if that might trigger a higher PER in due course, perhaps? With a bit of patience, I could see BEG shares maybe get to 125-150p later this year, good upside from 104p today. Not madly exciting, but worth having. Plus divis are paid out in May & November each year.
.
.
Tracsis (LON:TRCS)
655p (down 0.5% at 08:35) - mkt cap £191m
Tracsis, a leading provider of software, hardware, data analytics/GIS and services for the rail, traffic data and wider transport industries, is pleased to provide the following trading update for the six months ended 31 January 2021.
- H1 trading in line with the Board’s expectations
- High activity levels across large parts of the group
- H1 revenue £22m (down 17% on H1 LY)
- Covid impacted H1 revenues by c.£6m
- Events & traffic data businesses should return to normal as lockdown lifted
- EBITDA will be only slightly down on last year H1 £5.6m, because reduced revenues are from lower margin activities, plus cost-cutting done
- Cash £21m, no creditors deferred
- Rail division - doing well, helped by new contract wins, and multi-year recurring revenues
- Guidance - FY 07/2021 expectations remain the same (but we’re not told what they are!)
Investor presentation - isn’t this terrific, bravo to Tracsis, all companies should follow suit (indeed many are) -
The Board is committed to communicating with all investors equally and directly, to ensure that its strategy, business model and performance are clearly understood. Accordingly, as part of the Group's Interim results roadshow, an online investor presentation will be given by management, hosted by piworld, on Tuesday, 13th April, at 1.30pm.
Anyone wishing to participate should register here: http://bit.ly/TRCS_FY21_interim_results_retail
Broker update - many thanks to Finncap for its update note this morning. They’re forecasting 26.1p EPS FY 07/2021, rising to 34.8p next year, when conditions should be more normal.
At 655p current share price, that’s a PER of 25.1 and 18.8 for next year.
I’m inclined to value the share on next year’s earnings, which should be more typical of normal conditions.
My opinion - this looks quite good value. Tracsis is a group of interesting niche businesses, with high margins, cash on the balance sheet, and a track record of successful & disciplined acquisitions. We've also seen that it's been resilient during the pandemic.
To be able to pick that up for a PER under 20, strikes me as quite attractive. Quality at a reasonable price.
.
Springfield Properties (LON:SPR)
151p (up c.1%, at 11:31) - mkt cap £152m
Springfield Properties (AIM: SPR), a leading housebuilder in Scotland delivering private and affordable housing, announces its interim results for the six months ended 30 November 2020.
Significant six-month growth - well placed for the full year
Substantial reduction in net debt through delivery against strong order book
This is a new company to me, I’ve never looked at it before, so please bear that in mind - it’s just an initial review, and I might not understand everything fully.
It listed in Oct 2017, on AIM.
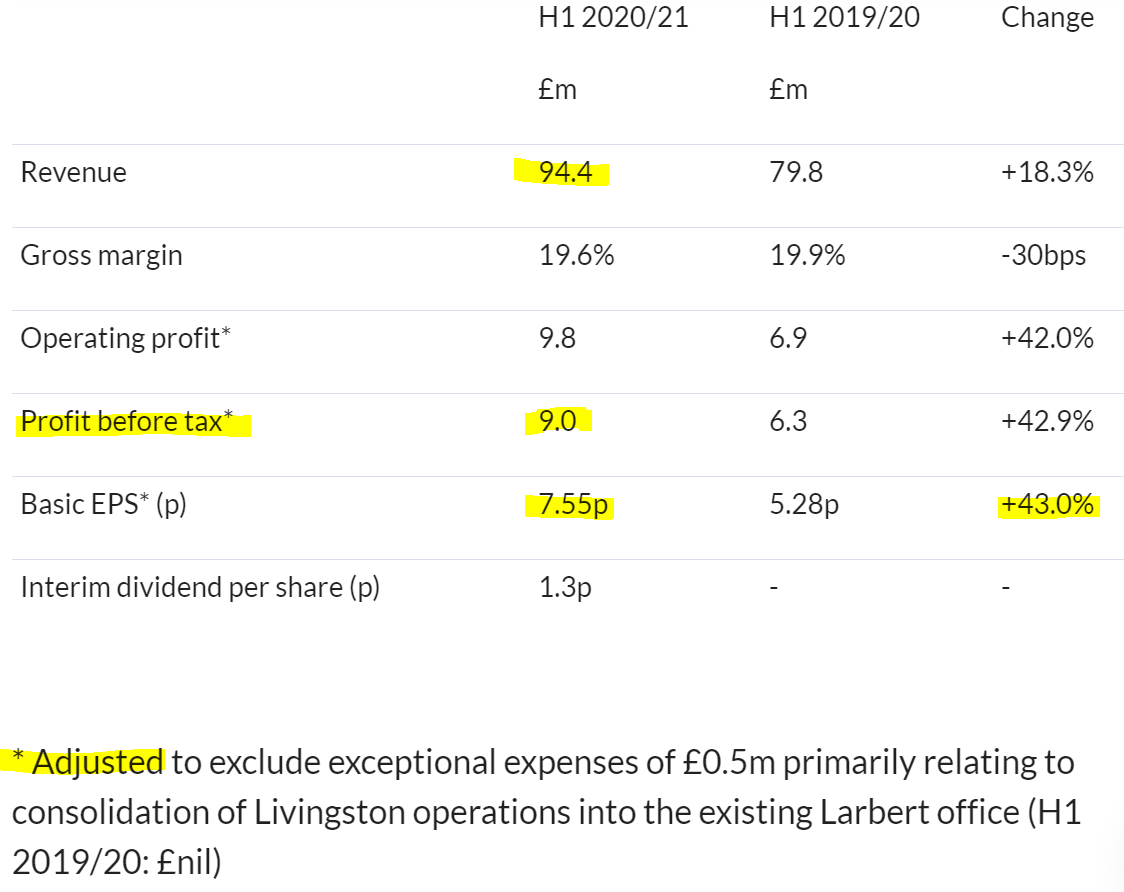
My first impression is that the financial highlights look good, considering there is likely to have been some unhelpful impact of covid -
.
Profit & EPS up 43% on H1 LY, it’s looking good so far.
Land bank -
Total land bank of 15,029 plots (31 May 2020: 15,882) with Gross Development Value ("GDV") of £3.1bn (31 May 2020: £3.3bn)
Outlook -
Robust sales activity strengthened the order book, providing substantial visibility over full year forecasts…
The Group continues to experience excellent demand across the business, which is supported by strong market drivers in private and affordable housing. There remains an undersupply of housing in Scotland and the desirability of the type of housing Springfield offers has increased. With strong demand, good mortgage availability, low interest rates and the First Home Fund for first time buyers, the Group does not expect to be materially affected by the closing of Help to Buy (Scotland). In addition, it does not anticipate any significant impact on its supply chain as a result of the UK leaving the EU, although the Board keeps this under review.
"With substantial visibility over our private and affordable housing revenue for the full year, we look forward to delivering significant growth for 2020/21, and expect to be slightly ahead of current market expectations."
No footnote is provided to tell us what market expectations are.
Dividends - an interim divi of 1.3p is declared, not particularly significant for a 151p share. It paid a 2.0p final divi late last year, so the annual total for divis looks to be about a 2% yield.
Balance sheet - NAV £101.2m. There’s only £1.7m intangible assets, which I always deduct, so NAV looks strong at £99.5m.
As I would expect for a housebuilder, the balance sheet is dominated by inventories at £155.1m, with relatively modest bank borrowings of £18m current, and £16m long-term. That’s fine.
Valuation - looks fairly modest, at 9.7x forecast earnings for next year.
My opinion - on a quick initial review, I can’t see anything wrong with this. It’s got a solid balance sheet, outlook comments sound upbeat, and valuation seems reasonable.
Before buying this, I’d want to run a comparison with other housebuilders. In fact, I’ve just done a comparison with Persimmon (LON:PSN) and Barratt Developments P L C (LON:BDEV) on Stockopedia (it’s under “Tools”, then “Compare with…” on any company’s StockReport). Stockopedia choses PSN as the winner out of those 3 housebuilders. Although I note that SPR ranks highly for the lowest PER and highest earnings growth rate. So it’s well worth considering.
Overall then, my first impression of SPR is positive.
.
That's me done for today. Thanks for dropping by!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
LIFE EVENT for UK_Investor
In early December 2020, I broke through the £1M portfolio for the first time with a low of about £560K end of April 2020.
Today I've recorded my largest ever sales and profits, reducing my portfolio down by about 35%, selling my strongest winners.
I give full credit to Edward Croft and Stockopedia for the StockRank system and metrics that guided myself to this profit.
Today, I sold:-
EVRAZ (LON:EVR) 18 months holding +48%
Central Asia Metals (LON:CAML) 12 months holding +62%
Apax Global Alpha (LON:APAX) 12 months holding +32%
Gross Profit before tax on this lot... £102,124.72 +44%
Reasons:-
1. I am buying a house in 60 days, and today seals the balance of payment due. You can enjoy a country home. You can't enjoy a computer screen with numbers on it.
2. EVRAZ (LON:EVR) has full year results on Thursday 25/02/2021. I think they will be excellent, but if a share is going to wobble either way, FY Results and the Dividend announcement is usually when this will happen. +48% has been a great run and I am literally crystalizing my profits and turning it into a house.
Apax Global Alpha (LON:APAX), again, I've had a great run first getting on @120p a year ago, exiting @200p today. The company has done extraordinarily well, but its SR has now fallen to 89 as the valuation stretches value. There is a Dividend and figures coming up. The results usually always please.
Central Asia Metals (LON:CAML), +62% on a small holding, too small. Its been a great run. Thank you.
3. FEAR. I am feeling techy, having seen an amazing bull run. Now I fear losing my hard won gains, and I have a reason to sell and enjoy this wealth.
4. Paul's commentary and others, and the feeling that the bull run, bubble is due to correct soon, with signs of mania. Today I've pulled the trigger on my strongest positions and winners for a purpose.
I find it incredibly hard to sell a winning share, usually regretting it as it carries on soaring.
5. Its just me here! I don't have anyone to teach or mentor me; making this up as I go and acting far beyond my own incompetence.
What's left:
Well I am now a long way off the £1M club again but I'll be back.
My 4 biggest positions currently:-
International Personal Finance (LON:IPF) (I hold £290K worth presently) +21% @83p - This reports, I think, tomorrow. Its going to be epic either way. If it reaches 95 to 100p, I clean up big. If we ever get the world back to normal, I can foresee 120p. I'm happy to wait another year on this.
IG Group (LON:IGG) (£108K) +37.4% - This is going to be a roller coaster ride. Again, investors can lose or win big. I'm in this for the long term. I'm bullish and feel safe here.
XLMedia (LON:XLM) (£178K) -12% - We are waiting for a major turnaround. Premier Asset Management continues to buy about 1% every month or so, and we looking at a timeframe of this year. 45 to 50p and I make a super-profit.
Plus500 (LON:PLUS) - Only a small foray, ex-div the end of this week -3%. Again, I'm bullish over the medium term.
I am going to enjoy the calmness of my new massive cash position in this uncertain time.
Once my house is bought in 60 days and the dust has settled, and there's some signs of value and stability in share prices, I'll start investing in new cash, based on StockRank QVM principles.
I would NOT encourage my friends to invest right now, unless they have the time and patience to sit out any problems and have reduced personal debt first.
Pretty surprised that £IG , the company itself is only 2.65% down over 5 days. Given they have triggered a mini avalanche in many stocks, many PIs reckon they still have a bright future.
Can someone enlighten me on why closing long spread bets causes price falls? Does the counterparty actually hold physical shares which they sell? Who does take the other side of a spread bet?
If it's a derivative surely it reflects market price not drives it?
I'm a bit naïve on these things.
Generally someone like IG will have brokers who will hold or borrow stock against client positions. Thus why a lot of stocks are unborrowable. So, no it's not just a derivative market though often aggregate client positions won't be hedged perfectly either. More unscrupulous providers may be completely unhedged and are thus just taking the other side of the trade expecting you to lose.
I use IG and I've found this current experience really off putting. it's a dreadful customer service. To sell / buy back is costly and needs managing, also something they won't do for you. Basically they want to take the spread of closing (ie below Bid for longs) and then you have to open in physical shares at the Offer or inside if you can get it.
What they should have done is offer customers the opportunity to B&B, having got their brokers to speak to the MMs in advance. That would have been a small cost but more seamlessly managed. Yes, there would be no leverage available so you'd need to fund the position but better than the current mess they've launched on the market. It is very poor to accept someones positions, then decide half way through you can't be bothered anymore and then hide behind T&Cs and force you to quit them at your own cost. Feels dishonest.
I've used them a lot but now I will consider going elsewhere. I would have complained but guess what - no customer service!! Please wait in a queue for hours before we don't answer anyway......all because of Gamestop......come on you are having a larf!!!!
Tracsis (LON:TRCS) (I hold)
A little bit of a fluffy RNS today. I do understand that they want to signal that business isn't at a dead stop, and its difficult to convey that when you are not in the position of being precise.
However, when it references potential multi year awards, tenders etc, this could relate to business they already have secured as many clients re-tender after a period of time, and quite a lot of the activity means pre-sales activity rather than sales wins.
Most Companies engage in pre-sales activity, and it maybe that Tracsis is in a better position that most because of its strength in its various niches, and its average hit rate.
Hi Trident
I think that one of the key impacts to Tracsis (LON:TRCS) this last year has been all the slow down and shut down on local government spending. So they do lots of exciting cutting edge things like cameras and cables and boxes that count traffic, yes I am a Civil Engineer by training before you ask, so if you ever drive over a single, or pair, of black cables running across the road look at the box on the nearest lamp post to see if it is theirs.
Anyway the railway business has continued as it does lots of things like defects monitoring, so just gets attached to tracks and left there hence the resilience in expenditure throughout lockdown - none of us wants a derailment for any reason. But the roads side has been badly hit. So with life slowly returning to normal the idea being over the next 12 months+ infrastructure spending at the local level resumes, people want new houses, bypasses, junction improvements and all that, hence demand for products and services goes up.
Here is hoping as I hold.
Tommy
Here are my SCVR heat maps for today (prices as at ~1:15pm).
There are a lot of Big Movers today so my apologies to those of you who don't like large heatmaps.
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents:
https://www.stockopedia.com/co...
I have a question - I want to invest in IVOL an ETF traded on NYSE. I have my SIPP with Hargreaves Lansdown. HL tell me they cannot trade it - MIFID 2! I still want to buy it. Does anyone know of a way around this short of finding a broker who can trade it and can look after the admin side of my SIPP. It seems heavy handed to move the whole thing because they cannot trade one left of field ETF????? HL cannot give me any other options I have pursued it as far as I can.
I had a look, not available on HL but is on IG Group (LON:IGG) but: "only trade Volatility Index using a CFD or spread betting account."
So looks like you will need to open a CFD or spread betting account.
Instead of moving your account, which I agree is not worth it for one trade, why not just open a spread bet account?
Don't know if this is on the IG blacklist or not.
So looks like you will need to open a CFD or spread betting account.
Bit of a random OT question here if you dont mind - i had some one tell me they have made 50k profit trading what they think is cfd's? on plusmarkets (pork? to china can't lose kinds trades). It appears that cfd profits are likely chargeable to capital gains tax where spreadbetting is not ?
Question is could this individual likely have done the exact same trades via spreadebts or are they sort of mutually exclusive kind of trades generally speaking. Nice to turn £300 into 50k - even nicer though if you then get to keep that as tax free earnings.
Thanks Herbie47.
Not sure if it has already been reported here or elsewhere but Robbie Burns/ the Naked Trader has just circulated an email to his subscriber list with some horse’s mouth intel on possible fallout from the revision by IG of its mid/small cap margin terms. Bottom line is that IG’s brokers have tightened their terms/increased their costs such that much of the previous business done in that space is no longer viable for IG. Robbie suggests Spreadex as an alternative for top FTSE 350 companies as they are still operating here but have the position under review.
Hopefully the disruption to affected shares is short term as open spread bet positions are unwound. As others have commented could be a possible buying opportunity.
One of the downsides of SPR is the shares are rather illiquid, otherwise I'd probably have bought some today.
Tristel (LON:TSTL)
I sold out a while ago for twice my purchase price as I thought there were better growth opportunities to be had. I believe the USA approval will drag on and on until Tristel's patents run out, they are long in the tooth and the yanks don't like foreign competition. Also cheesed off with never-ending share options.
https://patents.google.com/
Market makers have ‘turned off’ electronic order book for SMT according to ii. It’s in free-fall - down 11% now. Can’t get a quote. Manual orders only. Join a long queue. Big move for a FTSE100 company. Seems overdone really considering the Nasdaq is only falling a few %. 15% of my pf along with UK small caps.
I can buy Scottish Mortgage Investment Trust (LON:SMT) on IG platform @ 1135p.
Tesla one their largest holdings is down around 20% in the last few days, with another large fall today.
yes you can buy! No PI selling though until they’ve got the big boys out :-(
Scottish Mortgage Investment Trust (LON:SMT) I see, well I would watch what happens to Tesla today, at the moment they are down around 6% but were down about 8% earlier. I agree it does look overdone. Good job they sold a load of Tesla off recently.
Share price is going up now.
I exited SMT a couple of weeks ago on concern of Tesla holdings may buy back in.
I've just added to my (substantial) SMT on HL. Discount to NAV would now appear to be c10%. Hope I'm not throwing good money after bad, but they (and other BG trusts/funds have served me very well lately.
Today feels like a great example to why it's impossible to time the market:
- Saga (LON:SAGA) - Included in the IG list, positive govt news regarding holidays - up 11%
- Sylvania Platinum (LON:SLP) - Included in the IG list, windfall dividend, strong rhodium price ($23,800) - down 6%
For me, there's little point making rash decisions as it never really works. I'm happy to watch things fluctuate knowing that process and patience is key.
Quite a day. Some really quality shares moving down a lot presumably off the back of this IG move. However, none of them moving quite as much as all the cryptos. I think BTC's "Gold 2.0" status might have just taken a bit of a knock.
Bit of a shake out going on this morning, probably as much about IGs decision than anything else.
Looks like a wide sell off in small caps now. A lot of my holdings have been dropping 5% a day since yesterday. I think we need to give it a week whilst this IG thing blows over. Per what Paul said on Monday, look for things on sale!
Anyone know why Volex (LON:VLX) has just crashed 10%?
I think it might be a combination of the IG thing and tech sell-off in the US, but seems a bit harsh on Volex (LON:VLX) maybe. At 16x cashflow it's not exactly at a bubble price multiple to my mind. I hold Volex (LON:VLX)
Is Volex a tech stock?! Looks very decent value now!
I also hold...
I agree but I think it has some association with electrification, EV's etc, justified or not. Does appear to be good value. If sell-off continues might be a variety of bargains coming up :)
Hit my stop at 275 now back to 305! Fuming.
I know your pain! Why i am always reluctant to use stops, rightly or wrongly...
I gave up with stop losses for exactly that reason, my last one was XP Power (LON:XPP) which shot up soon after my stop loss was triggered and is now up over 50% in a few months.
MM's at work, Tommy.
Level 2 looking a whole lot better now 0-)
I think it's coz of copper price
In the most recent presentation, according to the notes that I took, they are unprotected in the quarter, if the price of copper moves unexpectedly higher. However, for the next quarter, the price rise will be incorporated into / passed onto the customer contracts. So negative impact will be felt by Volex (LON:VLX) albeit for a few months.
Not sure how material the impact of rising copper prices has on them though....
Job to work out what is going on, is Best Of The Best (LON:BOTB) which was down over 20% in the last 2 days because it's on the IG list or some other reason reason. Yes Volex (LON:VLX) is on the list but then so is Renold (LON:RNO) but that is up 6%.
I see even Sylvania Platinum (LON:SLP) is down over 5% because its on the IG list?
I hold Volex would like to top up but reached limit on size of holding in my portfolio, don't see a reason for the drop in price.
Morning all,
Anyone know why AIM is down so much today?!
Regards.
Some of the largest shares are down considerably, such as ITM Power (LON:ITM), Ceres Power Holdings (LON:CWR), Novacyt SA (LON:NCYT), Proton Motor Power Systems (LON:PPS), Keywords Studios (LON:KWS) and Boohoo (LON:BOO).
Rising bond yields will affect high P/E growth/tech companies as the future value of earnings/cash flow is reduced. Value stocks tend to be less affected, whereas no-earnings 'future bubble' tech will be affected the most.
To my mind, there is an obvious 'future tech bubble', which rising bond yields could rapidly deflate.
US tech seems to be getting torched, might be some contagion/read-across. Scottish Mortgage IT is down 17.5% in the last week, for example.
My guess is IG Index list. Punters have to stump up a lot of extra margin by this Friday or close out. If they want to raise money in time, they need to sell today. Even if the stock is not on the list, people might be selling to support stocks that are on the list. In my view, a lot of small cap stocks are way too expensive and the cause of this is momentum trading based on margin trades and the stack of new clients looking to make money and looking for something to do. That will start to unravel over the next few weeks as punters refuse to put up more and more cash. The "bubble" may well be ending (for a while at least) and novices are finding out that rubbish stocks do not go up every day. It may well get a bit nasty in fact. Opportunities for those with cash at some stage?
I am a relatively new member but listened in to the recent evening presentation which was much enjoyed , I decided to have a bit of a gamble on Renold (LON:RNO) and after early problems I am pleased to report decent profit emerging this morning. You were the presenter Paul and I am happy to help you to blow an early trumpet on your behalf
Hi ken bishop,
You were the presenter Paul and I am happy to help you to blow an early trumpet on your behalf
Thanks, but it's very early days yet. As mentioned in the StockSlam, I think Renold (LON:RNO) is a turnaround with an investing horizon of about 2 years. It could attract a bid sooner than that, who knows?
I'm astonished at how short termist so many people seem to have become. At what point did the stock market turn into a giant casino? I didn't get the memo about that! ;-)
Regards, Paul.
Paul I watched your presentation and was almost complete with me research, I was going to wait for a pull back in the price but opened a starter position today, I remember the Renold Chain factory in Burton on Trent, closed now, never thought I would be a Share Holder.
Boohoo (LON:BOO) presumably the victim of short sellers again and/or people selling to pay IG margin calls. Whatever. It’s a further buying opportunity for me at 332
I will also add. Initially, people may want to visit and buy clothes from physical stores when they open.
I would also add; rising bond yields affect higher PE 'growthy/techy' stocks first. Witness the drops in US tech stocks yesterday. This might be a blip, but also might be the start of a correction. I hold (nervously) and with Boohoo (LON:BOO) seeming abandonment of US expansion in favour of UK-centric 'clothing marketplace' plans and the associated execution risk that brings, probably not for too long if bonds back up.
Also re: Boohoo the possible introduction of an online tax could be weighing on the share price. A few negatives coming together at the same time
The rising bond yields could end up being short-lived given all the supply side stimulus and probably won't change until there are one of the following supply side events: tax rises, fiscal expenditure drops, central banks taper balance sheets or interest rates rise.
The only likely one I see is small tax rises but we might not see any of these until employment is back at full capacity so my own view is a small correction and a continuation of the rally for 6 months until sentiment turns to what supply side measures they will start to use to cool the economy.
I do find it strange that some commentators are already talking about the economy needing to be 'cooled' - not quite sure what economy they are looking at!
These are just my general observations and not Boohoo specific.
Clinigen (LON:CLIN)
ridavies
Thanks for that summary - this is a new company to me - looking at the 2022 forecasts per stocky thats a very reasonable pe of 10 here so that has . here The company has a wad of debt (350mill) but on an glance compared to expected 2022 profits of £100 mill this debt seems reaonable - it sort of looks like they are in the cash generation part of their life cycle now hopefully alebit some comments below ref ongoing investment?
Looking at growth prospects they seem to have reasonable (if no spectacular) expectations.
Future organic net revenues are targeted to grow by at least 5% to 10% on a medium term view with the FY21 now expected to be in the upper half of this range.
Further investments in the platform, particularly in the US and EU infrastructure, digital capabilities, the ERP platform and product development will continue in order to help drive longer-term organic growth. As such, operational leverage is expected to soften in FY21, as previously guided, before improving in FY22 and beyond.
This all looks reasonably interesting/promising - the level of non underlying expenses is very high although this seems to be primarily intangible amortisation - on the basis the company expects future organic growth above inflation levels i am happy to ignore the amotisation as being non relevant adjustments.
So thats a near full set of ticks on an initial glance - the main question that remains here is how much execution risk is there ref hitting near term targets - future profit expectations are much higher than the past - but the numbers today seem reasonably consistent with what they are forecasting so i guess the necessary step change (acquisition led?) in that regard is sufficiently in the past?
I notice the only screen this company qualifies for is the Altman related short selling screen - presumably the debt / lease liAbilities etc sensibly flag this as a company that needs to not be in a position where it needs to go cap in hand to the market at the wrong time.
£clin there top sales person left the company some years back to set up his own drug co which is one of the fastest growing cos In the UK, clinigen seem not to have performed as well since.
Morning Paul, Could you possibly have a look at SPR reporting this morning. I bought last spring, pre CV19,[fitted my growth sieves] and sold when Scottish govt. closed everything. Rebought after ST 's value portfolio inclusion,and checking stoko facts sheet. Covered at weekend by Mail top ten too. This morning's RNS makes for enjoyable reading,and not only being tipped but the financial stats look like a growth co. on it's way. Cheers stay safe Tony
Hi Tony,
Your post triggered me to have a look at Springfield Properties (LON:SPR) so see the section added above about it. Looks quite good to me! Thanks for flagging it. I thought it might make our friends north of the border a bit happier, if I reviewed a Scottish company! ;-)
Regards, Paul.
RNS Reach from Amino Technologies (LON:AMO) this morning announcing "...deployments for GO Malta ("GO"), Malta's leading communications services company and Cablenet, the number one cable operator in Cyprus".
finncap reiterate a 215p target price which would give forward p/e 23 and then 20 at that price, which I consider modest given the software involved and the expanding market.
There was also an announcement on Friday concerning their AGM. While many companies are rubbing their hands with glee that Covid restrictions mean they don't have to put up with shareholders at AGMs, Amino Technologies (LON:AMO) is broadcasting its on IMC with presentation and Q&A immediately following. Good.
(I hold)
Here's a look at the Begbies Traynor (LON:BEG) chart.
Seems to be putting in quite a classic cup and handle formation, which can be seen a bit more clearly on the weekly chart (daily chart shown below).
Typical entry would be a break of the 'pivot point' at the top of the handle, which I have at 117p.
A more aggressive entry would be a break of 109p. Price is on the 50SMA at the moment, a move up past 109p would indicate positive momentum coming in, and allow good stop loss position below the recent low and 50SMA.
Note; Be aware of the spread, about 3% on my platform. Higher than I normally like, but I do think this has potential for upwards momentum.
On Begbies Traynor (LON:BEG) one would expect if this year's eps will be 6.6p or more, than brokers will be updating coming year eps to higher, maybe 7p or 7.5p instead of 6.66p currently.
Also current broker forecast for next year doesn't take into account warnings enhancement from recent acquisitions...
Hi dahokolomoki,
Re: Begbies Traynor (LON:BEG),
Do you mean earnings enhancement rather than "warnings"?
Regarding Solid State (LON:SOLI) - "..many thanks to WH Ireland for making its research available on Research Tree" - yes, it is good that they make it available but you don't need to subscribe to Research Tree you can get it direct as is also the case with joint broker finnCap. In the case of the latter they give target prices. In this case it is 835p suggesting limited upside.
Hi sharw,
True you can get research direct from Finncap & WH Ireland, but personally I prefer it all in one place, hence Research Tree is my preferred source - which also has N+1, Liberum, Cenkos, and others.
It's such a pity that MiFiD stopped my access to the top tier broker research, especially Peel Hunt and Numis, which I really miss.
Regards, Paul.
A fairly predictable surge from £SAGA. Their advertising campaign looks like it could have been perfectly timed. I feel really confident about this. They are so well placed to take advantage of this pent up demand to travel. Their target demographic will be first to be fully vaccinated and have deep pockets. Demand will outstrip supply so I think they can increase margins on cruises. Onwards and upwards.
Clinigen (LON:CLIN) came in with Interims today, with growth slackening. Not a small cap these days by any means, but often what larger companies have to say, especially about the outlook in situations like those right now, can be an indicator for smaller companies in similar markets. Clinigen (LON:CLIN) have suffered relatively because of the focus on Covid 19 and the interruption to more standard NHS work, and therefore usage and orders for the products Clinigen (LON:CLIN) sells. That should change significantly in the next 6-12 months as there is a rush to catch up on the backlog. Cant think of which smaller companies are in this categories, but wiser and more experienced contributors here will be able to fill that gap!
I'm not sure what the changes at Ig Group (LON:IGG) mean for me as an investor?
I have sold all mine. Fed up with their service
My morning smallcap tweet:
Kanabo (LON:KNB) Vela Technologies (LON:VELA) Diurnal (LON:DNL) Non-Standard Finance (LON:NSF) Zotefoams (LON:ZTF) Begbies Traynor (LON:BEG), Tracsis (LON:TRCS)
Kanabo (KNB) has signed its first UK medicinal cannabis distribution framework agreement. "The project aims to create the UK's largest body of evidence for the effectiveness and tolerability of medical cannabis." No £££. [SP=25.4 Cap=91m]
Vela Technologies (VELA) tinpot investing vehicle makes £1.5m placing at 0.09p, a 3% premium. to take advantage of investment opportunities and for working capital. With warrants at 0.125p, only 38% above placing price. [SP=0.09 Cap=11m]
Diurnal (DNL) Chronocort distribution and marketing agreement with Consilient Health for the Nordics, ahead of anticipated European recommendation for approval. Extends relationship with Consilient Health. [SP=62 Cap=86m]
Non-Standard Finance (NSF) FY(Dec) trading: net loan book down 27% after "a solid trading performance" in H2.. Branch-based lending weak in Nov & Dec. Targets substantial equity raise in Q2 to fix material uncertainties regarding going concern. [SP=3.51 Cap=11m]
Zotefoams (ZTF) new Polish factory starts production. [SP=430 Cap=209m]
"Begbies Traynor (BEG) guides FY(Apr) at least in line with pretax expectations of £10.2m-£10.7m. Well positioned to deliver the anticipated material growth in earnings in FY22.
[SP=102.5 Cap=131m]"
In line: Tracsis (LON:TRCS)
Interesting developments re IG's announcement, Trading212 is no longer offering "Penny Stocks" too.
Morning OldManFit,
My broker tells me that a lot of other CFD & Spread Bet companies hedge their positions with IG. Hence if IG have decided to depart the small caps space, then that could trigger other companies following suit.
I got an email from IG yesterday, providing a link to their list of companies no longer being provided. The only one that impacted me was Saga (LON:SAGA) . My mentor always used to tell me, that if you're going to sell something, then sell first! I think he had in mind profit warnings, but also any other situation where you become a seller for any reason.
So I felt I had no option but to ditch most of my IG position in Saga yesterday morning, so it was rather annoying to see that I'd sold into an early spike down, and they recovered to end up slightly on the day.
IG's email told me that they're putting about 900 items (mainly small caps) onto 100% margin this Friday, then they want the positions closed on Monday next week, and implying that they will forcibly close the positions if clients haven't already done so.
Another option they say, is to buy the shares outright, into an IG share dealing account. Which is commercially the same as having them on 100% margin, apart from the tax-free wrapper having disappeared, and not having to pay funding cost any more.
I'm not that bothered about IG, as I do nearly all of my business through Spreadex. I sounded them out yesterday, and got more reassuring noises. So not sure what they're planning on doing re small caps. Although they did ask me to sign away my funds segregation, which apparently makes your account much more attractive to Spreadex, as they can use the cash you hold with them. I'm relaxed about that, as Spreadex has a very strong balance sheet, and seriously wealthy shareholders, and conservative management, and they've never been in any financial trouble.
I remember when I first started doing this full time in 2002, it was almost impossible to get leverage on small caps. Then Hargreave Hale launched a 25% margin CFD service for any size companies. That was what I used to generate a really high return in 2003. It was some time later that other companies launched spread bets in smaller caps, including Spreadex & IG. Would be a great pity if we lose access to them, as I feel the current tiered margin system stops the biggest risk - of blowing up with a huge illiquid position, like I did in 2008.
Regards, Paul.
Paul, given all the insight you have given on Saga I am disappointed you missed out on today’s uplift from Boris’ announcement yesterday.
Hi CamRaid,
I know, IG have cost me a lot of money today, tens of thousands, by botching that announcement which more-or-less forced me to close my SAGA with IG yesterday. Never mind. I've still got loads more SAGA in other accounts, so I'll try to see the glass half full! No point crying over spilt milk, these things happen.
Regards, Paul.
Love your attitude Paul, a lesson for us all.
I am ready p*** of with IG,
Up until yesterday, I was very happy with their services. I have now closed over 40 positions and still going through their list of the share they have stopped trading
I would now be looking to move my account (how many more people will they lose?)
Any suggestions Guys
NOT HAPPY WITH ig !
I find Spreadex excellent for small caps.
My broker told me today that, providing I'm happy to allow them to use the cash on my account (i.e. non-segregated) then Spreadex are very happy to keep my account, and continue offering me small cap positions. So that's very encouraging.
Looks like Spreadex are going to get a lot of business that IG didn't want. The way they've handled things at IG is so high-handed and inept, that I've got serious worries about them, and don't think I really want to do much business with them in future. After all, if they suddenly announce they're stopping doing a load of small caps, then they might follow it up at some random point with a new list of more small to mid caps they're not interested in either.
I can understand if business on some stocks isn't economic for them, in which case why didn't they just put up their fees?!
Maybe IG is now too big to offer decent customer service? It looks that way to me.
Paul.
I was looking into Spreadex and one recent review said that Aim and many small caps were not able to trade. No communication from Spreadex.
IG have had non existent customer services for months, the system keeps crashing and the latest fiasco is the last nail for me, I will move Spreadex in future.
Thanks for the updates Paul.