Small Cap Value Report (Tue 23 Jan 2018) - Quindell, ELCO, LPA, BOKU, EYE, FLO, SSY, VEL, LOOP, LAKE, DOTD

Hi, it's Paul here.
Please feel free to post your comments, and small cap requests in the comments below.
Quindell postscript
This announcement caught my eye. The audit firm which signed off Quindell's dodgy accounts for 2010/11 has been fined £700k + £90k costs by the Financial Reporting Council (FRC). This obscure body supposedly polices published accounts. However it rarely seems to take action, and when it does, is very slow.
The audit partner responsible, has also been reprimanded (big deal!) and fined £56k - which is not a material sum of money to a partner in a decent-sized accountancy firm. Also, look at the timeline - it's now 7 years from those incorrect accounts being created. Hardly a rapid response team!
As longer term readers here will remember, I was consistently very bearish on Quindell, since its accounts were fairly obviously highly suspect. Excessive debtors, excessive capitalisation into intangible assets, and a flurry of acquisitions to muddy the waters, are the usual give-aways of fake profits, so these dodgy companies are really terribly easy to spot. You can spot a highly abnormal balance sheet in just a few seconds, so it really doesn't take any particular forensic accounting skills to uncover dodgy companies with false profits. You just have to have your wits about you.
The same was true with Globo. It was amazing how much venom from deluded fools in the investing community my bearish comments attracted over these 2 dodgy companies. There was even an attempt to get me sacked from this role at Stockopedia, by Quindell/Globo shareholders cancelling their Stockopedia subscriptions! Of course, Ed put editorial integrity before short term revenues, backing me to the hilt. That I was proven correct by subsequent events, was very satisfying.
Anyway, the perpetrators of the Quindell and Globo frauds are still at large, with their ill-gotten gains, having relieved gullible UK investors of hundreds of millions of pounds. As I sadly commented to an investor friend at the weekend, white collar crime in the UK very much does pay. The action taken by the FRC, reported today, is too little, too late, in my view, to properly punish, or deter, the same sort of thing happening again.
Kudos by the way, to Tom Winnifrith, for his tireless, obsessive exposure of multiple wrongdoings at both Quindell and Globo. People may not like his style, but he's done outstanding work exposing many dodgy companies.
Having worked in audit myself, at the start of my career in the early 1990s, I can confirm that it's really very easy to pull the wool over the eyes of auditors. Their checks on the numbers are not very detailed, and a clever FD can cover up all sorts of problems. So the onus is very much on investors to do our own reasonableness-checking on published accounts. If the numbers don't look right, then it's best to steer clear.
A popular misconception is that auditors are highly paid. They're actually not. Audits are often tendered at low prices, in order to get a foot in the door, to enable more lucrative tax, and acquisition-related work to be secured.
American market boom
There seems to be an invisible force pulling the American markets relentlessly higher, with no significant pullback in a long time. This is very worrying. Some are describing it as a "melt up". This is not normal, or healthy market behaviour, in my view. Could we be heading for a crash? I don't know. Markets are meant to "climb a wall of worry", with regular corrections. This seemingly unstoppable move upwards could be the precursor to a violent correction, possibly?
Successful trader Mark Minervini recently tweeted that the only times he can remember the American market being this exuberant, were just before the 1987 crash, and just before the dot.com bubble bursting in 2000.
However, this big rise could be justified? Maybe US shares are re-rating because the big corporate tax cuts in the US will increase earnings considerably? That in turn could trigger an economic boom, of increased investment & a virtuous circle of higher growth, greater consumer spending, etc. Who knows? That's what happened under President Reagan, after all - he initially stimulated the US economy with big tax cuts, which ushered in a period of great economic success.
These things are impossible to predict, and nearly all forecasters get it so wrong that you would have expected them to pack in forecasting as a bad job. Yet strangely, people (especially the media) still treat their forecasts with quite unjustified reverence. Economics is still very much in its infancy, and has barely scratched the surface, in terms of being able to accurately predict what the economy will do in practice.
So I think it's best to accept that we haven't got a clue what the future holds. Despite this, I'm increasingly nervous about this market melt-up, so have opened some short positions on the US markets. That's proving expensive so far, but I don't mind losses on hedges. They're an insurance policy, and insurance costs money.
As regards the UK markets, I'm seeing a lot of nervousness in small to mid caps at the moment. It feels like the days of everything going up, day after day, are now over. We've been spoiled by very buoyant market conditions, for a long time now.
There are many former momentum stars, which have sold off considerably in the last few months (e.g. Boohoo.Com (LON:BOO) (I'm long) and IQE (LON:IQE) . Investors seem to be ignoring many satisfactory, or even good updates, and banking profits instead. There certainly seems a lack of investor appetite to take small caps to new highs at the moment. That's probably quite sensible actually, as lots of small caps are now very pricey, and the UK economy seems to be in a soft patch, so there seem to be lots of profit warnings being issued.
Mind you, bargains can be found in illiquid markets, when some investors start throwing out the baby with the bath water, and/or see their stop losses triggered for no particular underlying reason. I favour such market conditions, as from time to time the market throws a bargain in my direction, as people sometimes act irrationally - scared out of good shares by erratic spikes down in price.
Anyway, let's have a look at some small cap announcements today. By the way, I apologise for any typos today - am using a small laptop, with a screen that I'm struggling to see properly.
Elecosoft (LON:ELCO)
Share price: 45.5p (up 8.3% today)
No. shares: 77.4m
Market cap: £35.2m
(at the time of writing, I hold a long position in this share)
Elecosoft plc (AIM: ELCO), the AIM-listed construction software specialist...
Clever wording makes it sounds better than it is! This is an in line update;
... is pleased to announce that Revenue and Profit before Tax trading for the year ended 31 December 2017 are both expected to be significantly higher compared with Revenue and Profit before Tax for the year ended 31 December 2016 and in line with market expectations.
Cash generation sounds good;
Elecosoft's strong conversion of operating profits into cash in the year enabled the Group to eliminate its net borrowing position at 30 June 2017 and to also improve its net cash position further as at 31 December 2017.
I love it when companies eliminate their debt through cash generation.
Other points;
- High customer renewal rates (a good sign - the product must be good)
- Emphasis on good training & support for customers (again, a good thing)
- Successful acquisition has been integrated.
- Favourable forex movements.
- Outlook - nothing specific, just says "look forward with confidence"
My opinion - I picked up a few of these shares a while back, on a positive update. Generally I'm not keen on software companies, as they're quite prone to profit warnings - often being heavily reliant on lumpy licence sales.
This share looks priced about right, in my view. It's good to have a reassuring update today under its belt.
Stockopedia remains to be convinced, with a "Neutral" style, and a middling StockRank of 51. Let's hope those improve, if financial performance continues to be good.
LPA (LON:LPA)
Share price: 172,5p (up 0.9% today, at 12:51)
No. shares: 12.38m
Market cap: £21.4m
(at the time of writing, I have a long position in this share)
Final results - for the year ended 30 Sep 2017
LPA Group Plc (LPA) is a designer, manufacturer and supplier of light emitting diode (LED)-based lighting and electro-mechanical systems.
It announces today;
...record results for the year ended 30 September 2017 and a strong start to the new financial year.
This company put out a positive-sounding trading update, which I covered here on 1 Nov 2017. As often happens, the surge in share price on the day (responding to a positive update & outlook) continued, with the share price rising about another 12% today.
I won't spend long on this company, as it's too small & illiquid - I was only able to pick up a few shares. It might be of interest to readers with small portfolios, who don't have a problem with illiquid positions.
Key points;
- Revenues up 5% to £22.5m
- Pre-exceptional operating profit up 24% to £1.9m (exceptionals are negligible, so nothing to worry about there)
- Basic EPS up 17.1% to 14.4p - giving a PER of 12.0
- Dividends are modest, but growing - up from 2.5p last year, to 2.7p this year - a yield of 1.6%
- Order intake & closing order book both up nicely, so the outlook & visibility are positive.
- Recent trading - Q1 "significantly ahead" of prior year.
Balance sheet - looks fine to me, with a sound working capital position. There's a little debt, but I don't see that as a problem. Note there is a pension fund, which is in surplus on an accounting level, but may be in deficit on an actuarial basis. It's not significant, as the cashflow statement shows £100k p.a. payments by the company into the fund.
Capex looks high, but the narrative mentions relocating its factory, which is likely to have caused a spike in capex.
My opinion - based on a quick review only, I quite like the figures & outlook here. So for micro cap investors, happy to accept poor market liquidity, this might be worth a closer look. It seems soundly financed, performing well, and has a strong order book. Plus it pays modest divis. I think it would be worthwhile to do some more digging, to understand what products it makes.
The crucial consideration is whether demand is likely to continue, or whether the company is riding on the crest of a wave from one-off orders? Overall though, it's worth a closer look I think.
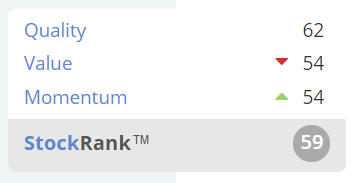
Note that the Stockopedia data (from Thomson Reuters) shows only 9.5p EPS expectation for 2017. So the actual of EPS of 14.4p is a long way ahead of that. Therefore, we can probably anticipate an improving StockRank, once the actual numbers flow through. So I'll wager that this middling StockRank could start to improve soon;
Boku Inc (LON:BOKU)
Share price: 85p (unchanged today)
No. shares: 213.5m
Market cap: £181.5m
Boku (AIM: BOKU), the world's leading independent direct carrier billing company, is pleased to provide the following unaudited trading update for the year ended 31 December 2017. This is the Company's first Trading Update since Admission to AIM in November 2017.
My understanding is that this company's software enables people to buy things on their mobile phones (apps, games, etc) without the need for a credit card. The cost is instead routed to their mobile phone bill, or prepaid account. This is useful in countries where credit cards are not widely used.
2017 revenues exceed $24m - up 40% on 2016 - and an Adjusted EBITDA positive second half
As we know, adjusted EBITDA can hide a multitude of sins - especially at software companies, where large amounts of overheads can be capitalised, thus flattering EBITDA.
This is impressive;
Total Processed Value (TPV)** of $1.7bn for 2017 was more than triple the 2016 amount of $554 million thanks to continued growth across all customer segments - most notably App Stores and Digital Music Subscriptions & Bundling
Although if a tripling of total processed value only results in a 40% rise in revenues, doesn't that suggest individual transactions are being done a lot more cheaply?
Looking on the StockReport, my first port of call for any new company is the historical graphs. These have already scared me off;
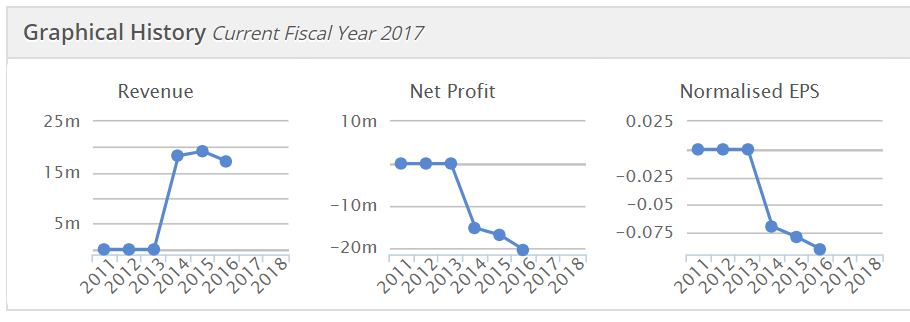
My opinion - it's clearly a jam tomorrow situation. The £181.5m market cap clearly includes some heroic assumptions about future growth. I don't tend to buy into things like that, unless I really understand the sector & the business, which is not the case here. So I think this one is really just for punters, and people who properly understand the business, and think it's likely to deliver the massive growth necessary for the current market cap (let alone a higher one).
This reminds me of Bango (LON:BGO) which looks similar, and is also relying on exponential growth to justify its extremely high (relative to historic losses) valuation.
So these 2 shares could be multibaggers, if the growth gains momentum, or they could crash disastrously, if growth disappoints, and heavy losses continue - requiring further fundraises in future. High risk, potentially high reward. They're not for me - why take the risk?
Eagle Eye Solutions (LON:EYE)
Share price: 224p (down 0.9% today, at 14:19)
No. shares: 25.4m
Market cap: £56.9m
Eagle Eye, the SaaS technology company that allows businesses to create a real-time connection with their customers
Here's our archive of my 3 previous reports on this company. You can find this list of articles on any company, just by putting in the ticker, then clicking on the "Discuss" tab, at the top of the StockReport.
I don't like the company's new description of what it does, as it doesn't actually explain what the company does! Its previous description from a July 2017 announcement was much more clear;
SaaS technology company that validates and redeems digital promotions in real-time for the grocery, retail and hospitality industries
Why change something clear, to something opaque? A very odd thing to do. Clarity, and simplicity are always best.
It reports today on progress for H1 of 2017/18, being the 6 months to 31 Dec 2017. So it has a 30 June 2018 year end.
Here are the highlights, as presented by the company, and yellow highlighting from me;
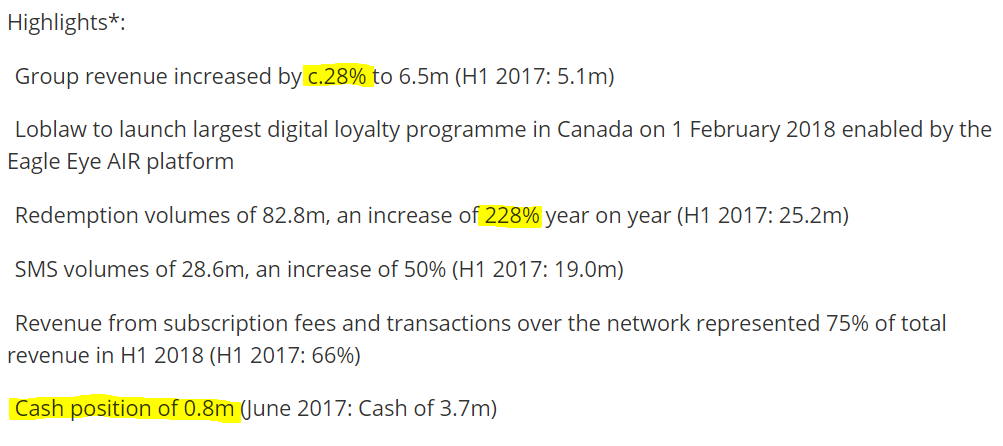
There is strong growth in various KPIs there, but revenue is only up 28% - not madly exciting. I tend to prefer revenue growth of 40%+ at growth companies - because you don't need to grow at that rate compounded, for long before the figures get exciting.
Cash - the other thing that jumps out at me from this list, is that the company seems to have burned through most of its cash. Looking back through previous RNSs, the company raised £6m (before expenses) or £5.8m after expenses, in Jun 2017. So I'm rather surprised it's only got £0.8m left. Maybe there was some debt that was repaid as part of the previous fundraise? Ah yes, I've spotted a £3m facility with Barclays in the last full year accounts, which looks as if it's currently undrawn. I'm not keen on loss-making companies using bank borrowings.
Clearly the company will need to do another placing fairly soon, as it's still cash hungry. A lot of development costs are being capitalised. This is not necessarily a problem, as the company seems well-supported by investors, with a generous market cap for a loss-making company. So raising, say, another £5m would only result in c.10% dilution - unhelpful, but not a disaster.
Outlook - there's lots of commentary in today's update about customer wins, etc.
The conclusion is;
... confidence of delivering its expectations for the financial year ending 30 June 2018.
My opinion - there's definitely something interesting here, in my view. This company clearly has an interesting, innovative product, with big name customers.
However, for me the financial progress has to date been somewhat limited. It's still quite heavily loss-making.
Looking at the broker forecasts, there are big expectations for revenue growth, rising to £22.8m in 06/2019, and £32.8m in 06/2020. Yet these big increases in revenues would only just tip it into normalised profit before tax of just £0.9m in 06/2020. I'm struggling to see how that justifies a £56.9m market cap now.
This share would therefore only interest me, if I could be convinced that the company is set to smash those forecasts, and deliver much higher growth and future profitability. As things stand though, I think it looks an interesting company, with a promising-sounding product, but the financials don't look very good yet, and the price looks a bit toppy. Plus it will need to raise more equity fairly soon, so I'd rather hold fire and re-assess it once it's properly funded. I'd say a placing of £10m+ is really necessary, rather than doing repeat, smaller fundraisings. The danger of that, is that the fundraising window can easily slam shut, in a future bear market, leaving the company potentially high & dry.
The Stockopedia computers only award EYE a low StockRank of 21 - which is understandable, as early stage, loss-making companies nearly always fail to excite either the Stockopedia algorithms, or me!
Anyway, I wish the company well, and look forward to reviewing it again when the next set of numbers come out. As usual, I reserve the right to change my mind at any time, if growth accelerates and makes it a more exciting investment proposition.
Flowtech Fluidpower (LON:FLO)
Share price: 177.25p (down 3.1% today)
No. shares: 52.8m
Market cap: £93.6m
London: Tuesday 23 January 2018: AIM listed specialist technical fluid power products supplierFlowtech Fluidpower plc (LSE: symbol FLO), is pleased to announce the following unaudited update on its performance for the year ended 31 December 2017 and to the period up to this announcement...
The update starts with an in line with expectations comment, and positive noises about further expansion;
"PBT in line with expectations, whilst the Group's heightened profile and enhanced technical skills capabilities created in both the UK and Europe has ensured that opportunities for further significant expansion have continued to be presented"
Revenues up 45% to £77.9m. Scanning through the RNS, the group seems to have made several acquisitions in 2017, which has obviously pushed up revenues. Organic growth is good, at +8%.
Net debt has risen 12% to £14.7m. Note that there has also been some dilution this year, from an equity fundraising.
This is an excellent update, with lots of useful information;
Divisional Gross margins remain broadly in line with the prior year. As a result of a weightier mix towards the generally lower margin PMC operations, a slight reduction in overall margin % is projected, therefore, the Board expects underlying* Profit before tax for the year ended 31 December 2017 will be in the range 8.6m to 8.8m, which is in line with market expectations.
I'm impressed that the group can give a fairly tight range of likely profit, 23 days after the year end. This suggests to me that it has a competent finance department, with good internal controls.
Six acquisitions were made during the year, which strikes me as perhaps being a bit too ambitious. There's a risk that this might have stretched management bandwidth a little thin?
A refurbished/redesigned shared logistics centre has also been completed, with no disruption to customer service. This management team really have been busy! Impressive stuff.
Dividends will rise 5%, giving a yield of 3.2% - not bad.
Valuation - this looks reasonably priced, on the cheap side, even when you adjust for net debt;
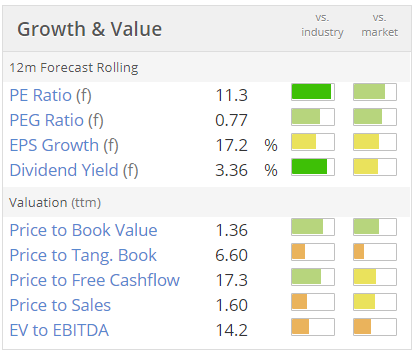
The StockRank is very high, and it is also classified as a "Super Stock";
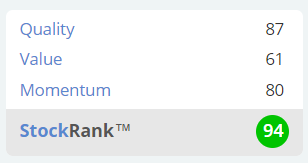
My opinion - I like it. This is a stock we've looked at here before, and felt positive about. It strikes me as a good quality buy & build, which appears to be managed very well.
I like the decent operating profit margin - which comes from holding a wide range of niche spare parts for various machinery, and high levels of customer service, e.g. rapid delivery options, which is vital when the clients' important machines are idle, waiting on a spare part from FLO.
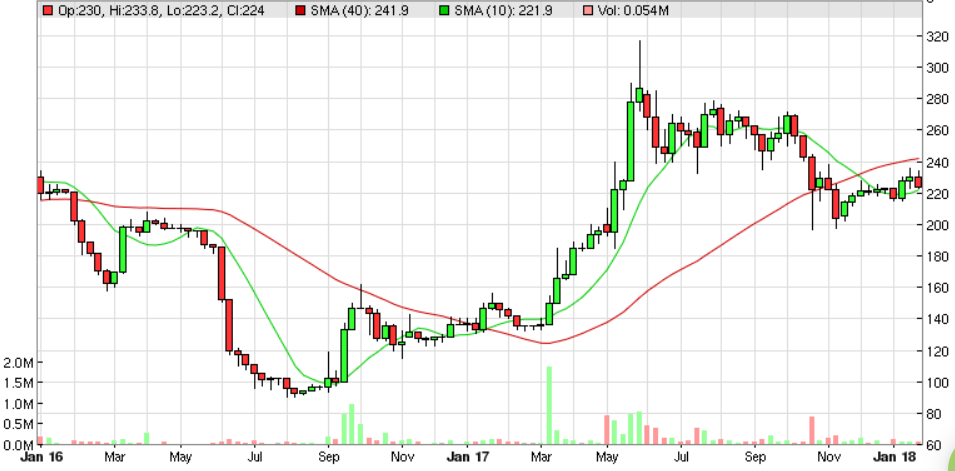
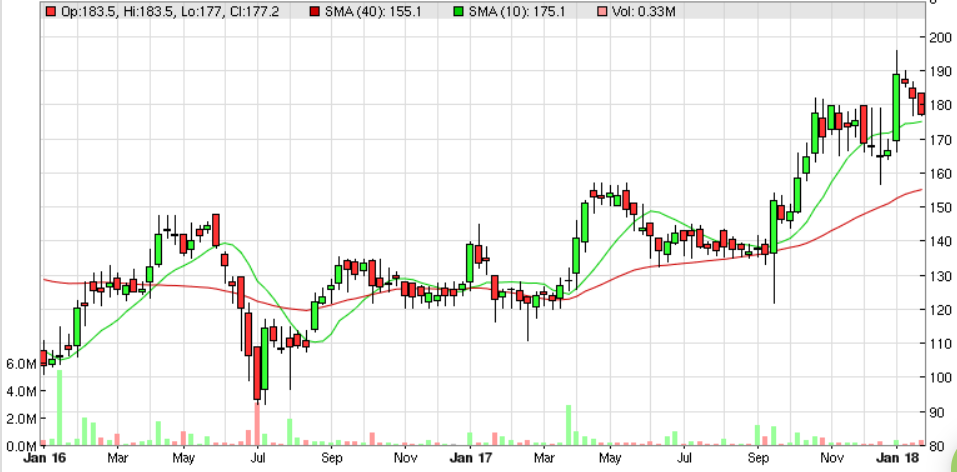
This share looks to me as if it could continue to be a steady riser, as more acquisitions are bolted on. So a thumbs up from me. Here's the FLO chart (geddit?!!!) - if we'd bought that dip in July 2016, we'd be 80% up, plus divis, by now. That's something to think about.
SCISYS (LON:SSY)
Share price: 128.5p (up 3.8% today, at market close)
No. shares: 29.3m
Market cap: £37.7m
SCISYS PLC (AIM: SSY), the supplier of bespoke software systems, IT-based solutions and support services to the Media & Broadcast, Space, Government, Defence and Commercial sectors, is pleased to announce a trading update for the year ended 31 December 2017 prior to entering into its close period.
This sounds good;
The Directors expect the Company's trading results will comfortably meet current market guidance, both in respect of revenues and adjusted operating profit.
That's a strange choice of words. Surely "comfortably meet" would mean beating guidance?
Additional detail also sounds positive;
The Company's overall order book is at record levels and strong across all sectors, bolstered by our 18m contract win with OHB System AG to deliver the ground-station control and communications infrastructure for the German national satellite-communications mission, Heinrich Hertz.
The Directors are pleased to note that the strong organic growth enjoyed at the end of 2017 is continuing into 2018.
The Group's cash flow is particularly healthy, with the net debt position as at 31 December 2017 better than expected, at 5.9m.
Valuation - a broker update today indicates estimated EPS of 10.2p for 2017, and a forecast of 11.2p for 2018. It sounds as if those might be conservative figures, so I'm inclined to value the company on 12p EPS - putting it on a modest PER of 10.7 - whilst that sounds cheap, this company has always been rated on a low PER of 8-10. Maybe it deserves more?
My opinion - I think this share could probably justify a somewhat higher rating, so it looks good value to me. On the downside, I've been frustrated with previous attempts to buy any meaningful amount of shares, because it's so thinly traded.
Eventually I suspect this company might be acquired at a premium, so patience here might pay off. There must be value in its client relationships. So a thumbs up from me, but a thumbs down for the lack of liquidity in the market, which makes it almost impossible to buy in any size, and of course the horrible bid/offer spread also has to be taken into consideration. Maybe management should make some more acquisitions, and considerably increase the size of the group, which would improve market liquidity in its shares too.
Velocity Composites (LON:VEL)
Share price: 103p (down 15.5% today, at market close)
No. shares: 35.8m
Market cap: £36.9m
Velocity Composites plc, the leading supplier of advanced composite material kits, providing engineering value-solutions for the global aerospace industry, is pleased to announce its maiden audited results as a public company for the financial year ended 31 October 2017.
This is a new share to me, which floated on AIM in May 2017. It's interesting to hear the company today state that its AIM listing has increased the company's profile within its industry;
"Our IPO has increased our profile and status significantly within the aerospace community and we have received Request for Quotations ("RFQs") by a range of large, global potential customers ahead of our anticipated timetable.
I've heard similar things from other small companies. Investors can be cynical about small companies floating on AIM, but it can bring significant spin-off benefits for companies, in terms of their credibility vis-a-vis big clients, etc.
I've reviewed the figures, and here are my notes;
- Revenues - H1 £9.3m, H2 £12.1m, full year £21.4m (up 47% on PY - pretty good)
- Underlying operating profit of £0.9m (2016: £0.3m) - a good year on year increase, but a rather slim profit margin on £21.4m revenues. Also, see note 28 - the definition of underlying excludes £446k of expenditure described as relating to future growth. That's a rather aggressive definition of underlying. Including this would reduce profits to only £450k - not much for a £36m market cap company.
- Underlying EPS of 2.39p, giving a PER of 43 - looks pricey, unless future years profits rise considerably.
- Outlook - expecting an H2 weighting for 2018 too, which might have spooked a few people into selling today, perhaps?
- Visibility for 2018 is good, at 85%
- European expansion planned
Balance sheet - is strong, following funds raised in IPO. £5.4m cash (note there is a bit of invoice discount finance within creditors). Receivables seems high - which would need looking into.
Development spend of £0.4m was capitalised - not excessive.
My opinion - these figures are a bit underwhelming. It's a small company, not really making much profits. I'd need to find out more about the company, and its market opportunity. Carbon fibre parts for aircraft sounds an interesting area to be in, but there must be any number of other companies doing similar things, at a guess?
Overall then, it hasn't really piqued my interest as yet.
LoopUp (LON:LOOP)
Share price: 373p (down 3.1% today)
No. shares: 42.07m
Market cap: £156.9m
I've had a quick look at the trading update today, but won't go into detail, as I think the market cap of £160m (at 373p per share) is now far too high, given where the company has got to.
EBITDA grew strongly to £3.5m. If you look back at the H1 results, the company did £1.6m EBITDA, which translated to £510k operating profit. Therefore this implies H2 EBITDA of £1.9m, and c.£0.8m in H2 operating profit. So I make that c.£1.3m operating profit for the full year. Does that justify £160m market cap? It seems to me that the market cap is anticipating several more years of strong growth, which may or may not happen.
It's a good product, I've tried it out. The valuation is too high in my view.
Lakehouse (LON:LAKE) - sorry I didn't get round to this one. The sector is a big avoid for me now. This type of contracting company is just best avoided in my view. Things always seem to end up going wrong - look at Carillion, ROK, Connaught, Silverdell, etc.
dotDigital (LON:DOTD) - in line update for H1 (to end Dec 2017). Spent half its cash on an acquisition. More details of operational developments.
All done, thank you for dropping by!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
LPA (LON:LPA)
I have held LPA for nearly four years. I do not normally trade in micro stocks, but reading the trading statements in the past always made me laugh - not a good reason to invest! Trading statements like sales are "galloping ahead' do not normally feature in other companies trading statements. It appears that their profitability is very much subject to the mix of products being sold. Clearly the move to a new factory has cut the cost of sales, so even without much top line growth, profits are much higher. Probably previous periods were negatively by one off moving costs. Reading their previous narratives they not totally dependent on the domestic market, where one large train order can make a big difference. Its the sort of company the UK has too few of. Will continue to hold
US Market:
The move up does not seem to be euphoric like 1999 (no comment 1987). It is relentless and remarkable of course. Aside from excess positivity, two other rationales stand out as potential drivers IMO:
1) Expectations of meaningful inflation take-off so making real assets very desirable.
2) Looking back in history and a bit laterally, the US is exhibiting behaviours that are like a classic emerging market balance of payments and currency crisis. Throughout history run up in stocks start to happen before the BoP crisis is fully realised and then when crisis hits currency tanks and stocks zoom.
It may just be a grind towards euphoria fuelled by a highly financialised and financially supported economy where margins are very high by historic standards with relative lack of aggregate cyclicality so pushing up the P on the E. We haven't then hit euphoria and the economy globally just kicked into hear which means that euphoria is coming barring geopolitical shocks (its aint coming out of the financial system this time as matron is monitoring and managing closely).
I don't know what's going down. However, I am inclined to give more weight to 2 above than I though...and I have surprised myself in taking that opinion over the last few months. I remain deeply uncomfortable about US valuations, however if it is the BoP crisis route (or the US version of that which will be a little different) then I am inclined to think that US valuations are much less relevant on global basis than is normal and that the all important capital flow pump is not towards the US when panicky moments hit. There is of course market muscle memory and eurodollar market does functionally create a USD short so there will be some panic to USD but my point is that the duration and momentum to it will be weak...and over time we Pavlov dogs will learn to be less concerned about it.
I don't give 1 above a horse in the race as the catalyst...however, if 2 happens then inflation of course comes.
I hate to say it but I think the evidence is that China has won the war in the global economic-financial power fight. China drives the global economic and financial flows. This will become ever clearer over the next decade.
Word out :)
(Of course, all macro is a bit flaky...so I could be wrong)
Well done Paul on battling through your list. Much appreciated.
Jon
re Boku (LSE:BOKU)
I think one thing which may have been missed with Boku is that not only is 40% growth in revenues over the whole year a pretty decent growth rate, but it is accelerating. At the half year revenue was up 21% so by my calculations that means H2 2017 was about 65% higher than H2 2016. I suspect that is significantly higher than they anticipated at the time of the float where I believe they were expecting to break into positive EBITDA on a monthly basis but not for the full half year.
If they are EBITDA positive that should mean they are at least fully funded (wonder what they will do with the $20m cash they raised on floating though...) and they are a lot closer to being profitable than (just to take an example) Cloudcall. Certainly look better value than BGO.
Eagle Eye Solutions (LON:EYE)
Paul, I liked your comparison between the old and new description of what they are.
I'm not totally sure if you were being rhetorical when you asked :
But I'll answer anyway :
"validates and redeems digital promotions in real-time for the grocery, retail and hospitality industries" sounds like a 21st Century Green Shield Stamps [google it kids]
Whereas :
"allows businesses to create a real-time connection with their customers" is quite clearly a paradigm shifting business that you cannot afford to not be invested in.
I'm sorely tempted to give up investing in companies and become a commodities trader instead - I'm short Snake-Oil as there is a clear global oversupply at the moment.
Yes I'm trying (and probably failing as ever) to be witty, but I do seriously wonder whether this trend (which I do think is real) is another indicator of a late stage and over-extended bull market.
I've been 'cautious' for about 18 months or so, but I'm now tending towards 'gloomy'. The global economy is certainly not as parlous as some doomsters would have us believe, but equally I don't think it is as rosy as the indexes would indicate.
"I'm short Snake-Oil as there is a clear global oversupply..."
LOL like it!!
Like saying "I'm long balloon manufacturers as the stock market pundits are supplying more and more hot air" :-)
25,000 shares in Games Workshop (LON:GAW) sold at a price of around 2,467p this morning.
Does anybody have any background to this sale, it appears to have had an adverse effect on the price this afternoon?
I'm long.
Michael.
Nice update from FDM with a resulting 1.9% drop in SP. Any thoughts?
Nick
Paul, as an audit partner in a large firm I think if I may just put you straight on a couple of points. Audits for listed entities are no longer a "way in" and rightly so. Independence now means you can ONLY do the audit and that's it, no fees for anything else. You are correct that the fees are still to low and the regulatory risk of getting it wrong, although not a big fine you may say, is still not great. The £56k for the partner may not be huge but ther career path is now at best a little bumpy. As a fellow partner would you trust a person who just cost you a share of £750k plus reputational damage. Pulling wool over auditors eyes is in my view getting harder to do and will continue to get harder. Direct data analytics and interrogation of systems will make it harder to cover things up, not impossible but harder. Block chain technology will I think help. Now that's not bad, a note about auditing and I nearly got crypto currencies in it!
Paul - Always best to just to rest :)
As you know - Plenty of opportunities and best spotted with a clear head.
Wish you well on a speedy recovery.
@ Paul - as long as Trump is in power the US markets will not tank. The administration will do everything possible to keep the markets running / the tax cuts was another way of prolonging this run for them. Im going to be ready to sell when the next election begins. I'm not convinced that Trump will run again so I will be selling off during the run up to the next election.
Re: Pauls' comments on Boku
Thanks for the comments on Boku Paul. I agree with your conclusion that investing in Boku is indeed a high risk to reward proposition (of the type that you and I would often avoid.) However for me it is worth a small speculative investment as all the numbers are going so strongly in the right direction and this is also happening at Bango which works in a similar area to Boku so I guess the value of this sector is expanding rapidly. For example, transactions processed by Boku more than tripled to $1.7 billion in 2017. I'm not going to suggest that paid for research is accurate, but the fact that today's Edison comment is predicting a profit in FY19 for Boku suggests that there may be light at the end of the tunnel. I would have thought that the merger of Boku and Bango looks like common sense as they are both pioneers working in the same sector for whom profit margins are critical. The merger potential is perhaps one reason why Boku's US investors decided to list the company on AIM where Bango's shares are also traded. I also like the fact that the markets addressed are truly global and I favour Boku over Bango because it seems to have focused more on developing markets where the use of mobile phones to buy things seems to be more widespread. Finally I would note that I was unable to purchase Boku shares through Halifax Sharedealing or Hargreaves Lansdown but found that ii (ex-TD Direct) let me buy the shares. Halifax claimed that you could not keep Boku shares in a their nominee account so that is why they don't allow customers to deal in them which sounds unusual to me. I wonder if the difficulty in dealing is dissuading some potential private investors.
I have also decided to include Boku Inc (LON:BOKU) in my small group of highly speculative sucker stocks (in Stockrank speak). Clearly it is relying on (a lot of) jam tomorrow but I think the growth can continue. The convenience to the buyer of direct carrier billing will I believe grow massively even in those countries where a credit card is common. Can this growth turn into profit? I think that it will and possibly sooner than you expect.
Meanwhile I will try and keep myself grounded by re reading the clear guidelines to avoid risk at this level
2 comments on the Quindell saga immediately caught my eye, and my agreement.
I've backed Tom Winnifrith many times against those who dislike and diss him, he may not get them all right on the upside but his bear and fraud call are nearly all spot on.
I also have been involved in several audits through the years, although never at the helm, I can confirm how easy it is to pull the wool over the auditors eyes and allay any concerns, seen it many times
thank you Paul
one good thing to come out of quincrapp -i came across your posts which i have found to be genuine and helpful not like some who have an agenda
Paul,
Many thanks for covering Boku Inc (LON:BOKU) I think it goes into the too risky box!
Andy
Paul, You state you are long BooHoo, but you also stated you went short on ASOS at around 5800 or so. Are you still short or did you close ?
(Cant see BooHoo as much different to Asos, margins may be slightly better but free cash in both not good)
Of course Quindell was a hogwhimpering disgrace and the professionals involved should be ashamed of themselves. What placed a cherry on top of the crap were two articles: one in Shares Magazine the other in the Investor's Chronicle neither commenting on the sophistry that surrounded the numbers.
Thanks Goodness for the excellent Paul Scott and Tom W who called the company a danger zone and they were right.
Paul.
LPA (LON:LPA)
Stockpedia seems all over the place with Broker Forecasts lately with many of the companies I follow having their forecasts changed dramatically here but nowhere else. Is this a known problem that's being addressed?
With LPA (LON:LPA) I think the change from 13.2p in November to 9.5p is spurious.
I can provide further examples if required to help sort the issue.
Hi Cockerhoop,
If you find what looks like a data error, then just click on the green blob at the bottom RHS of every page, which allows you to send Stockopedia HQ a message.
I do this whenever I find what looks like a data error, and they always fix the numbers very quickly (usually within 24 hours).
Unfortunately, it does seem to be the case that some data errors creep in with small caps from time to time, as Thomson Reuters focus seems to be more on mid to large caps.
I have to say though, the accuracy of the data has improved greatly. I look at hundreds of companies, and only find a data error about once or twice a month. There shouldn't be any of course, but TR seem less than perfect.
Regards, Paul.
Hi Paul,
Thanks for the prompt reply. I've messaged the team citing LPA (LON:LPA) & Ashley House (LON:ASH) as examples. I'd suspected it may have been MIFID2 related so hadn't raised earlier.
Cheers
In relation to Bango (LON:BGO) and Boku Inc (LON:BOKU), I will ask the same question here that I posed on another board.
My concern is there has to be a risk that sales of physical products yield a significantly lower proportion of EUS to Bango than sales of virtual products and that revenue could grow at a much lower rate than EUS. Bangos goal of 2% revenue from EUS is based on sales of virtual products. The company's example (p4 of interim results presentation - http://www.bangoinvestor.com/wp-content/uploads/2017/09/bango-1h2017-interims-website1.pdf) suggests that the vendor gets 70% of EUS with the remaining 30% split between the store operator (13%), mobile operator (15%) and Bango (2%). For physical products, there's unlikely to be 30% of product cost to give away.
Zooplus is a German company that is the largest European seller of animal care products. I think I'm right in saying that all of their sales are online. Their 9 mos numbers contain the following statement: "Total payment transaction expenses in the first nine months of 2017 totaled EUR 8.0 m compared to EUR 6.9 m in the same period of the prior year. As a result, the percentage of sales ratio remained at the prior year’s level of 1.0%." So, Zooplus pays 1%, on average, of EUS. I assume there are debit card, credit card and other types of transactions in there. Assume for a moment that the store operator (Zooplus) gets cut out of the revenue sharing arrangement but that it is otherwise consistent with sales of virtual products. That suggests that the mobile operator gets 88.2% of the revenue share (15%/15%+2%) and Bango gets 11.8% (2%/15%+2%). My question is: how do you get to 2% EUS if there's only, on average, 1% that gets paid away and Bango might only be entitled to a share of that?
Hi gsbmba99: I've had a quick look into Zooplus; i think they have a different business model to Boku Inc (LON:BOKU) & Bango (LON:BGO). They appear to be selling products through their website and taking payment via a credit card. Perhaps similarities with AO World (LON:AO.) can be made, insofar as they are online retailers. However, Boku Inc (LON:BOKU) & Bango (LON:BGO) allow customers to buy products and pay for via their mobile phones - either as additions to the bill, or a deduction from the prepaid balance. Therefore, there is dedicated technology that is being utilised.
Boku Inc (LON:BOKU) had achieved 2.04% return from EUS (prior to today's trading statement) whilst Bango (LON:BGO) achieved 1.79% in 1H2017.
Maybe I wasn't clear in the point that I was making since it was originally a response to a particular comment. I was trying to highlight the discrepancy between transaction processing costs for physical goods and for virtual goods.
Bango's investor presentation details how they get to 2% of end user spend on virtual goods. It is predicated Bango receiving a small share of 30% of the value of a virtual item being shared between the online store, the mobile carrier and Bango. Bango recently signed Amazon in Japan as a Direct Carrier Billing route and there's been much excitement at the prospect of Bango making 2% on Amazon Japan sales.
I was curious to try to work out what kind of margin Bango might be able to achieve if they were processing payments on physical items for Amazon. So I went looking for an online retailer to see how much they spend. I selected Zooplus because they were all online and because they disclosed payment processing costs as a discrete line item. Across all of their transaction types, the total cost they pay away to all payment transaction processing companies averages 1% of sales.
If Bango makes 2% on sales of virtual goods when 30% of the item's value is being paid away, what happens when only 1%, on average, is paid away in the world of physical goods? Can Bango make 2% if only 1% is available and they have to share it with others?
Thanks for your excellent coverage of Quindell, Paul. It saved me from being stung. Another company that appears to have caught some investors napping is Redcentric. Apparently the FCA are/were investigating them but, unless you know otherwise, I suspect any penalties imposed will again be insignificant. I really do think that there need to be far greater deterrents for dishonest behaviour, and that directors who are economical with the truth should be subject to prosecution and liable for the full extent of losses.
Great article today Paul re Quindell and Globo I remember followin developments at Quindell and initially getting sucked in to investing in the company, actually managed to get out with a small profit, but alarm bells for me were when the Chief executive Rob Terry, kept feeding news about everything that the company was doing and supposedly how this was going to add to profits for the year feeding the greed of gambling minded investors. On a few notice boards one person was writing that they knew Rob Terry CEO from the past and he was bad news and so it proved.
Just read an article on Rob Terry in the Telegraph calling investors in Quindell Losers idiots and I am alright because I got out with £35 - 40million and he now has anew investment vehicle called Quob Park Estate and that he no longer likes the AIM market and is looking for investors in North America look out North America Rob the Robber is coming your way if his past is anything to go by.
Flowtech Fluidpower is also of interest to me(LON:FLO Steady share price growth of 30% over the past few months which certainly looks justified by this trading update
Thanks for the reader requests. I've written down the list, and will go through as many of these as I have time for, being;
Boku Inc (LON:BOKU)
Eagle Eye Solutions (LON:EYE)
Flowtech Fluidpower (LON:FLO)
SCISYS (LON:SSY)
Lakehouse (LON:LAKE)
LoopUp (LON:LOOP)
dotDigital (LON:DOTD)
No more requests now please, that's plenty to keep me busy! :-)
On Elecosoft (LON:ELCO) buried in the notes of last year's annual reports is their view on IFRS15 and IFRS16. The first is very important to software companies, on how to recognise revenue.
"The Directors expect that ‘IFRS 15 – Revenue from contracts with customers’ will require a review of the Group’s revenue recognition policies. The timing and amount of revenue recognised may not change for simple contracts that have a single deliverable but certain complex arrangements may have an impact on revenue recognition and related disclosures. The impact of ‘IFRS 16 – Leases’ will require a change in the classification of operating leases to ‘on-balance sheet’ and the related interest expense will be front loaded. It is not practicable to provide a reasonable estimate of the effect of IFRS 15 and IFRS 16 until a detailed review has been completed."
So potential surprise to come, maybe.
Hi dahokolomoki: i did a brief write up last week on IFRS 15. You can find it here: https://www.stockopedia.com/content/small-cap-value-report-thu-18-jan-2018-cpc-pmp-call-cll-cwd-fran-300388/?comment=34#34
I know this might be a bit late but to add to the requests for Eagle Eye Solutions (LON:EYE) and dotDigital (LON:DOTD) can I request a quick look at SCISYS (LON:SSY), up 6% (I hold, but it's spikey!)
I recommend the PI lunches that SCISYS (LON:SSY) holds. The directors are very responsive to questions and you get a really good insight into how they see the future.
Hi FREng,
I agree, the investor lunches that SCISYS (LON:SSY) hold are excellent - they give you a nice, proper meal, with a couple of glasses of wine. Plus you have excellent, close-hand contact with the Directors, who are very open and approachable.
It's a good company, but I've never been able to buy any shares in decent size, due to the lack of market liquidity. Pity actually, as I like the space the company is in, and rate its Directors.
I don't want to get stuck in too many small, illiquid positions, in case there is a general market sell-off and I'm unable to exit. Memories of that happening in 2008 still haunt me. So I try to limit my micro caps to things where I think there is major multibagger potential, which probably isn't the case with SSY.
Regards, Paul.
Paul,
Unfortunately the most recent SCISYS (LON:SSY) lunch was a buffet because they had about 50 people there, so it had to be a theatre style presentation rather than a round table.
The problems of success ...
Perhaps not on the Quindell/Globo scale, but one company I held, and still read the advfn board for education/entertaiment is EVR Holdings (LON:EVRH). This was a pure punt for me when it was originally Armstrong Ventures (RTO into EVRH), and nearly 10-bagged when I sold my last block. The profit from this covered losses on other 'punts' (insert long list here !).
An ex-TMF(?) poster is desperately trying to point out the down-side(s), and the barrage of abuse he receives makes me wonder if it's worth wasting his breath, but he continues. I'm 90% certain he will be proven correct in the end, but wonder if those caught out will learn - I doubt if, based upon their short-sightedness !
Perhaps I should ask Paul or Graham to have a look at this company when their next results are announced - Only, if they're really short on news for that day ! lol
EVR Holdings (LON:EVRH) - I'm short here. As you see with all of these sorts of stocks, people have convinced themselves that this is the next big thing. They've got in early and they are going to be rich. The most obvious recent example I can think of is Cloudtag. The people who bought into that ramp couldn't be told either. They had to learn the hard way. Funnily enough EVR Holdings (LON:EVRH) have made sure they haven't made the mistake that Cloudtag did. You can promise, but it really is better if you don't deliver. Cloudtag unraveled when they actually started producing prototypes of their awful fitness tracker.
It is amazing how the same people continually get away with continually milking private investors. I remember Concha (LON:CHA) when it was 6p. Word clouds were going to be the next big thing for sport focused social media. A business called fansz.com was going to be reversed in and everybody involved was going to be straight down the Ferrari garage to spend a small percentage of their winnings. I shorted that as well, though closed way too early.
>>Maybe US shares are re-rating because the big corporate tax cuts in the US will increase earnings considerably>>
Perhaps not as much as some people think. A cut in the headline rate of corporation tax from 35% to 20% implies a 23% uplift in retained earnings, but one of the investment banks (Morgan Stanley?) calculates a 6%-7% increase. This is because there are thousands of tax exemptions (according to one of John Mauldin's articles) so few companies end up paying 35%.
However …. analysts were already forecasting healthy growth in SP500 earnings in 2018, and the tax cuts will add to that. This is from John Mauldin's latest newsletter:
“Further, Howard Silverblatt at S&P just came out with his forecasted earnings for 2018 (hat tip Ed Easterling for sending this to me). He revised 2017 earnings down by a few dollars to $110 as S&P analysts realized that companies are going to have to take write-downs for their deferred tax losses. But oh my is Howard positive about 2018. Look at this table straight from the S&P site. Focus on the reported earnings highlighted in yellow. Howard is expecting earnings to grow from $110 to $138 in 2018. That $28 jump in earnings represents about 25% earnings growth. If it actually materializes, the S&P 500 is going to be on a royal tear upwards. “
The idea that corporate tax benefits will show up exclusively in earnings is naff. In a competitive market some of it will inevitably flow to lower (than otherwise) prices. The more interesting impact is probably in the "animal spirits" dimension.
Flowtech Fluidpower (LON:FLO) for me as well :-)
Another request from me too for Flowtech Fluidpower (LON:FLO)
Today's trading update was optimistic, but not overly so. Profits for the year ended look in-line with broker forecasts. LFL revenue growth is good, but not amazing. Forward looking statements were optimistic, but not overly so and it looks like current broker forecasts looks to stay.
No immediate acquisitions on the radar but there is a comment about more opportunity.
Absent was any mention of cash flow generation, but it did go into detail why net debt is slightly higher than expected.
I think given the growth profile of the share it should be enjoying a slightly higher forward PE rating than currently. But the decent dividend is good compensation for now, and as Paul said, the markets are jittery and not really in the mood to pay for growth at the moment, so I can't see this re-rating higher in the next few days unless there are broker updates or it gets featured as a tip.
Great to see so many others on Stockopedia have an interest in FLO, and hopefully it will be fruitful investment for all of us!
There's a solid-looking update from dotDigital (LON:DOTD) today. I sold when the directors sold a large slab of shares, when the SP was half what it is today.
Should we too be surprised if over excited share prices look down and get a bout of vertigo? Is that not what shares prices do go up and down?
Regarding previouis corrections, I like many others survived the 2007 down turn with mixed fortunes
Throughout that year brokers with increasing volume reported that the private investor was getting out of the market! there was a warning for those who listened
History does not repeat itself but it does rime
Beware
Bence
another for Flowtech Fluidpower (LON:FLO) please
Paul, Great that you retained your poise during the Quindell saga. I can never understand why private investors are attracted to Quindell/Globo. I think what happens is that they employ good PR people and brokers to hype them up. They then get puffed up bullish newspaper articles in places like the Daily Mail. This attracts a host of "suckers" who but without thinking. The pitch for these kinds of companies is never about the business it is always to do with huge target prices or incredible potential or the amazing leadership. The private investors who have bought in don't like to feel they have been duped and so attack anyone who points out that the emperor is not wearing any clothes. So anyone like yourself who posts something critical gets attacked.
The question then is what companies are like this today? I think Purplebricks is overhyped along with Blue Prism. However, they both seem to have real products.
With regard to how long it takes the regulator to crack down on accounts. Surely things are only obvious a few years down the line when assumptions made in accounts are seen to be phoney. At the time it is just a matter of opinion?
Some good updates from FDM (Holdings) (LON:FDM) and dotDigital (LON:DOTD) today (while XLMedia (LON:XLM) quietly indicates that trading is fine).
However I'd welcome your thoughts on the Computacenter (LON:CCC) tender offer. I've not been involved in one of these before and am wondering how to handle their proposal.
Damian
Paul
Any reflections on the Christmas trading of Revolution Bars (LON:RBG) and Graham's commentary yesterday, which covered quite a bit of ground?
Regards
+1 for Flowtech Fluidpower (LON:FLO)
A footnote on Globo.
Konstantinos Papadimitrakopoulos ('Costis') the fugitive ex-CEO is openly waving his two fingers at UK investors who lost ££££, regulators and law enforcement agencies.
Have a look at his LinkedIn entry. Here is an excerpt. The man's chutzpah knows no bounds.
Chief Innovation Officer
Company Name CP TECHNOLOGY CONSULTANTS
Dates Employed Nov 2015 – Present Employment Duration2 yrs 3 mos
Location Athens, Greece
Passionate about new technologies that affect everyone's lives.
IoT, Automotive, Mobile, Cryptocurrency, Blockchain some of my most favorite areas nowadays.
>
GLOBO - Subsidiaries
CEO
Company Name GLOBO - Subsidiaries
Dates Employed 1997 – Present Employment Duration21 yrs
Location US, UK, IRELAND, GREECE, CYPRUS, UAE
Currently, managing almost all Globo Subsidiaries business and working towards smooth settlement of ongoing issues
It leaves me speechless.
Hi Ram
I’m with you. If you’re left speechless by Costis, I’d advise you to steer well clear of Quob Park, as it may hospitalise you. It’s a sort of “Son of Quindell” with a lot of familiar faces thrown in for good measure. No doubt it will attempt to float in time.
Www.quobpark.com
Paul,
Can you provide an update on the GAME Digital (LON:GMD) news? Major cause for concern, or one to hold? I bought at 38p and regret not taking any profits.
Thanks
Yet another brilliant article, thank you Paul, I might not always agree with your thoughts, but its a fabulous way to start the day, holding your opinions in mind
N Brown (LON:BWNG) please Paul - you have previously been positive on this but today there is a very negative reaction to the trading update. Is it overdone? Also GAME Digital (LON:GMD) price fall to 42p seems overdone - do you agree?
Velocity Composites (LON:VEL) Velocity Composites. Not discussed here before; interesting company. A favourite of Edward Roskill which is a good sign. Good results at first sight but marked down by the market. Perhaps because gross margin is down (and not very well explained or highlighted).
I would say definitely because gross margins (are not just down but) collapsed. Vague explanations in the release sort of make sense but its not clear enough and there is a risk they have taken on less profitable work as they've grown to service the mass aerospace market. IF gross margins recover, this will be a homerun. But there's a bit of info vacuum (and risk) until the company proves itself.
The "invisible" force pulling US markets "up" is (largely) the dollar going down.
Seconding requests for:
* dotDigital (LON:DOTD) - growing nicely. A platform business with good opportunities for long term growth
* Eagle Eye Solutions (LON:EYE) - another platform business. Excellent revenue growth and contract wins but still loss making. Looks as if it might need to raise more funds before it becomes cashflow positive
thanks
Hi Paul would appreciate your thoughts on LoopUp (LON:LOOP), dotDigital (LON:DOTD) and Flowtech Fluidpower (£FLO)
Hi Paul - any chance you can please cover LoopUp (LON:LOOP) as they released a trading update today?
Lakehouse (LON:LAKE) please Paul. Upbeat commentary from management with ok numbers. Is it finally starting to turn.
Lakehouse (LON:LAKE) please Paul. Thank you.
Paul I would be interested in your thoughts on Flowtech Fluidpower Flowtech Fluidpower (LON:FLO) time permitting.
Good morning Paul, it would be interesting to get your view about the GAME Digital (LON:GMD) announcement. Their FD is leaving immediately - red flag? Is more bad news to come or was his time up naturally?
cheers
Francis
Francis,
The GAME Digital (LON:GMD) CFO is not leaving immediately; he is staying to end-March to facilitate handover. The concern here, I think, is less that there are skeletons in the financial closet and more that he did not view the future potential sufficient to convince him to stay in post.
Puzzling though that they should choose to add that ambiguity. "immediate effect" but will stay till the end of March.
Why not just say he will leave at the end of March.
As CFO I would have thought that his formal notice period would be more than 2 months, so my guess would be that has a new job offer and they agreed an amicable compromise.
"he can focus on his other business and personal interests." - Is that a bit like "spending more time with your family"? He doesn't advertise any other current business interests on linkedin.
RE GAME Digital (LON:GMD)
I agree Gromley, for me that wording (immediate effect) created a question mark about him above and beyond the fact he was leaving.
Either management intended to convey this or their communication skills need improving, neither of which will encourage investors. Judging by the sp today (down 13%), others felt this too.
Francis
Hi fwyburd,
I don't want to get drawn into speculating about the departure of the FD at GAME Digital (LON:GMD) (in which I hold a long position). From the tone of the RNS, it sounds perfectly amicable, but you never know with these things. As you suggest, investors generally don't like FDs departing, as it can sometimes be a precursor of bad news. Or it might not, we don't know, hence nothing much I can add really.
As we saw at Revolution Bars (LON:RBG) (in which I also hold a long position) last year, the sudden departure of the FD (or it might have been 2 successive FDs?) was the precursor to news of poor budgeting, and a profit warning. However, the shares soon recovered when a bid was tabled, so in the long run I don't think it actually mattered that much. The new FD at RBG is a pretty solid chap I think, so losing the previous ones may have been a gain in the long run. Also he previously worked for WalkAbout, which was bought by Stonegate, so it's good to have someone in place who knows everyone at Stonegate, as I reckon they might well be back with an improved offer later this year.
Regards, Paul.
Paul, could you please look at £FLO?
Graham liked this company at its last update
Decent organic growth and uplift of dividend..
From my holdings, the CFO resignation at GAME Digital (LON:GMD) doesn't bode well - opened 11% down. Solid-looking results from IG Group (LON:IGG), and in-line updates from dotDigital (LON:DOTD) & Flowtech Fluidpower (LON:FLO). I'm not sure if any of these merit extended coverage here though.
The CCC return of value is extremely confusing!
Morning Paul,
I wonder if you might be able to do a small piece on placing offers? They're something I've not come across before, and the Computacenter (LON:CCC) one I am able to take part in today looks particularly confusing!
Thanks,
IG
Hi IG,
Firstly just to note that the Computacenter (LON:CCC) tender offer is not a placing (where they would be offering to sell shares), quite the opposite in fact.
It is certainly a little complex and my nerdy mind finds it fascinating.
For those interested (and especially I would think those holding shares in a nominee account - there is much more information on the document stored on morning star here)
Here is a précis of my understanding :
Simples ! ;-0
I am not a shareholder, but if I were the way I would personally play this is :
Consider how many (if at all) shares I would like to sell and a what absolute minimum price.
Maybe set tiers - ie I'd sell 10% at 1,200 or above , but 20% if the price was above 1,250.
I don't personally think there is any incentive to bid higher than your minimum acceptable price; you would run the risk of not getting the deal at all if the strike price is lower than your bid, whereas if the strike price is higher than your bid, you'll get the strike price anyway.
To be honest the strike price is likely to effectively be set by any institutions taking part.
It is an interesting exercise in open price discovery, but I suspect they could have achieved the same final result by having a quiet word with the instis as to where to pitch the price. But where would be the fun in that?
Sounds about right Gromley based on my reading of the announcement. It'll be interesting to see what strike price is arrived at via this process but whatever happens the share count will shrink by almost 7% (which is equivalent to the EPS going up by 7.5%). On that basis the P/E will drop from 18.2 to just under 17. This seems like a reasonable rating to me and so I doubt that I'll be tendering my shares (unless the share price drops massively for some reason in the next couple of weeks!).
What I hope will happen is that any weak holders who were thinking of selling will simply tender their holdings now and then the rest of us will be able to stick with a company which seems to be performing well.
Damian
Hi Gromley,
Many thanks for your help on the Computacenter (LON:CCC) tender offer! I've tendered my entire holding at the Strike Price, and we'll see how much I'll be scaled back by. As you say, literally no point trying to bid high, and if over the strike price, you get nothing. As this will be controlled by the very large holders, the best I can hope for is the strike price in any given scenario.
Seems to be a bit of a pointless exercise!
Thaanks,
IG
Paul - your thoughts on Lakehouse (LON:LAKE) please.
Morning Paul - Benchmark Holdings (LON:BMK) final results today. Company has turned around nicely lately
My morning smallcap tweet:
LoopUp (LON:LOOP), Oncimmune Holdings (LON:ONC), Harwood Wealth Management (LON:HW.), Lakehouse (LON:LAKE)
LoopUp Group (LOOP) FY trading - rev(cont) up 36%, ahead of market expectations.
Oncimmune (ONC) update. New distribution agreement for Turkey, min £630k over 3 years. EarlyCDT-Lung test: "an increasing number of distributors requiring Oncimmune to enter individual direct contracts with each institution where blood is taken. These contracts are taking in the region of two to three months to execute. Over time we expect "finger stick" collection to make the test more accessible but currently a significant proportion of the market still relies on blood draw. This requirement for individual contracts has had an impact on the speed with which we are able to build sale"
Harwood Wealth Management (HW.) FY EPS 1.19 (0.24). Group "has performed ahead of expectations". Final div 2.24p (2p).
Lakehouse (LAKE) FY underlying rev (cont) -3%. Underlying EPS 3.7p (5.2p). Final div 0.5p. Frameworks up 22% at £1.9bn, order book up 19% at £631m. Net debt £1.3m (£20.6m), significantly ahead of expectations. "Lakehouse had an excellent year". Hmm. A better year.
Decent updates from small cap tiddlers LPA (LON:LPA) and SCISYS (LON:SSY) this morning if you have time. Pets at Home (LON:PETS) and IG Group (LON:IGG) also reporting positively although beyond the usual £500m market cap threshold.
Gus.
Graham wrote positively about Flowtech Fluidpower at last update. Reasonable update today with good organic growth and divi upgrade. Wouldn’t mind your view please Flowtech Fluidpower (LON:FLO) (FLO.LON)
Thanks
EYE please.
Paul,
Could you include Boku Inc (LON:BOKU) on your list?
Thanks
Paul, Maybe not smallcap but the first IPO of 2017 maybe worth commenting on? I flagged it up late yesterday and Gajri had some interesting thoughts that may be worth looking at:
investegate.co.uk/integrafin-holdings/rns/intention-to-float/201801220700044611C/