Small Cap Value Report (Tue 23 May 2023) - EMR, PMP, AVON, ETP, CLX, WJG

Good morning from Paul, and I'm joined by Roland today, to free up Graham for presentations at Mello Chiswick, which starts today. I'll be wandering over this afternoon, to catch up with everyone!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Lots of news today - we'll do our best with this lot, focusing particularly on the news that's moving prices the most, and less on things that are only in line with expectations and not moving prices -

Summaries of main sections below
Avon Protection (LON:AVON) down 8% to 889p (£267m) - H1 results, downgrade - Roland - AMBER
A revenue warning from this personal protection equipment group, which is still suffering the consequences of a poor acquisition in 2020. I think there could be some medium-term potential here, but the shares still look fully priced to me at current levels.
Eneraqua Technologies (LON:ETP) - down 36% to 168p - FY 1/2023 results , with a disguised profit warning - Paul - RED
Strong results for FY 1/2023, but it turns out that FY 1/2024 are set to plunge. This is almost completely obscured by upbeat-sounding, and I think highly misleading commentary. So a big thumbs down from me, and this now becomes a company I don't trust, so uninvestable.
Calnex Solutions (LON:CLX) up 10% to 109p (£95m) - FY results, in line - Roland - GREEN
Today’s results from this electronics firm show excellent profitability and cash generation, backed by a very strong balance sheet. Forecasts suggest a sharp drop in profits this year, but I think the long-term potential of this business remains very attractive.
Watkin Jones (LON:WJG) (Paul holds) - down 17% to 80p (£204m) - In line H1, but H2 forecast slashed (PW) - Paul - GREEN
I bought this forward-sold contract builder as a medium -term recovery share, half-expecting more bad news in 2023, as mentioned in previous SCVRs. H1 is breakeven (as expected), but contract delays are pushing some big projects into next year, so it's another profit warning. Increasingly solid asset backing from a lovely balance sheet. I see this as a setback, but doesn't change the medium term investment case for me, with my small initial position. You may not agree of course!
Quick Comments
Empresaria (LON:EMR)
61.5p pre-open (£30.5m) - AGM trading update, profit warning - Roland - AMBER
This recruitment group says that the “softening of demand and slowing of hiring decisions” seen late last year have continued into 2023. Net fee income for the four months to 30 April 2023 is 5% below than the same period last year. Half-year profits are expected to be “down significantly”. Current expectations are for a full-year pre-tax profit of c.£7m, versus previous forecasts of £9m. Broker Cenkos has cut full-year earnings forecasts by 28% to 6.4p per share (available on Research Tree).
Roland’s opinion: Empresaria reported a slowdown in healthcare last year and booming demand in offshore services. I wonder if offshore demand may now be easing to more normal growth rates. Unusually in this sector, the group ended last year with a modest net debt position. While I don’t see it as a big concern, the timing seems poor. The shares don’t look expensive, but I think there are safer options elsewhere in this sector right now. I’d stay on the sidelines until we have more clarity on trading.
Portmeirion (LON:PMP) (Paul holds)
Down 8% to 465p [08:07] £65m - AGM Trading Update - Paul - GREEN
H1 is seasonally quiet as usual, expects to match last year’s H1 sales in 2023, which it calls “robust”. “Some increased caution” from US customers in recent weeks. “Well positioned” for seasonally stronger H2, with “strong Christmas order book”, ahead of last year. New products well received. Reiterates strategy to improve margins. Overall, “we remain positive” in both short, and long-term prospects, whilst mindful of challenging consumer headwinds.
Paul’s opinion - tricky this. Is it a profit warning? I’d say no, as it says well positioned for the busy H2, and Xmas orders ahead of last year. That sounds fine to me. But early warning signs from the US could spell trouble ahead maybe? Singers analyst Sahill Shan has not made any forecast changes this morning, sticking with FY 12/2023 forecast of 51.7p EPS (up c.10% on FY 12/2022 actual). So on a PER of only 9.0x, this share remains cheap for medium-term holders like me who don’t care about any short-term softness in demand. For more twitchy types, then today’s update might make them more nervous perhaps?
Paul's Section
Eneraqua Technologies (LON:ETP)
Down 19% to 210p
Market cap £70m
Eneraqua Technologies plc, a provider of specialist energy and water efficiency solutions, is pleased to announce its preliminary results for the year ended 31 January 2023.
ETP floated in late 2021, and looks quite an interesting company. I reviewed it briefly here in June 2022, noting the impressive results for FY 1/2022, and the big order book.
More recently it issued a mild profit warning which we commented on here in March 2023.
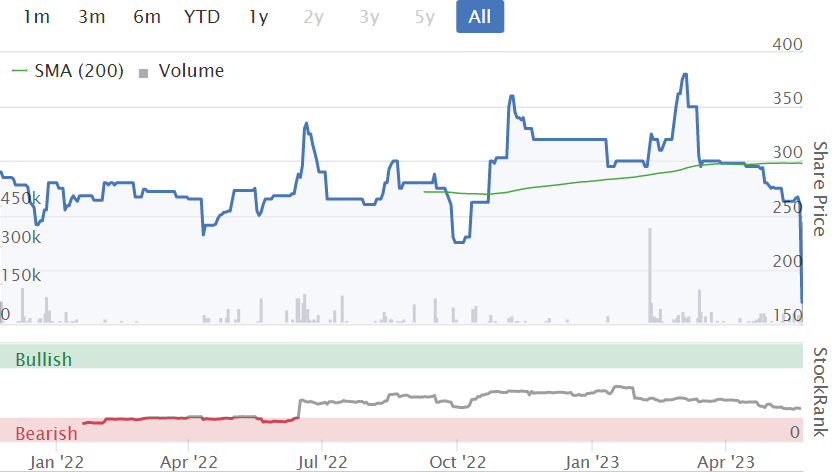
The share price has dropped almost a third since then. Today I was expecting it to rise, as the early snapshot was that trading was ahead of expectations, but it’s currently down 19%, so there must be something wrong, let’s have a look.
Moving on to the FY 1/2023 results, out this morning.
Here’s the financial highlights table
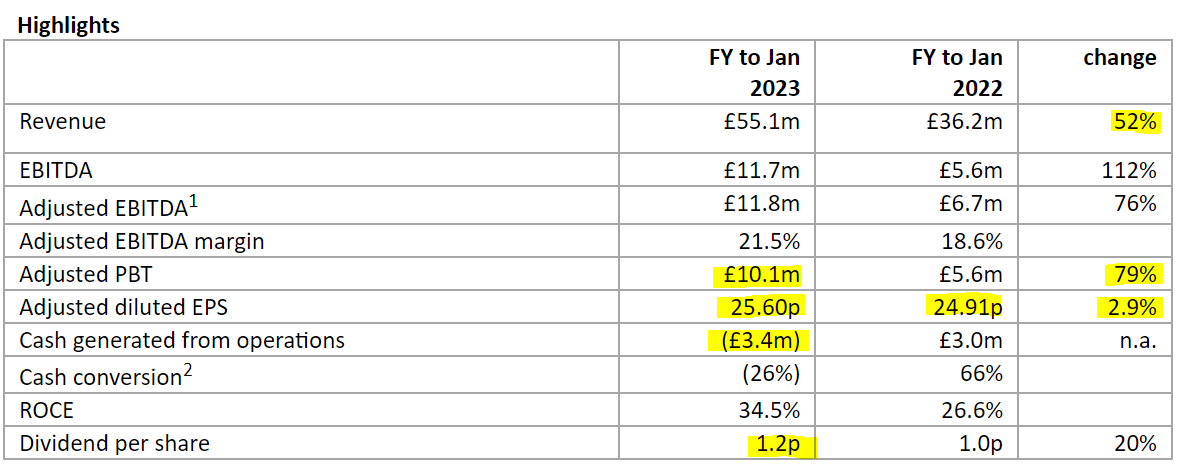
Several things stand out from the table above -
Superb revenue & profit growth.
But hardly any growth in adj EPS - why not?
Negative cashflow - why?
Tiny dividend compared with EPS.
Answers -
Cashflow - it blames having to bulk purchase scarce components in advance, due to supply chain issues. Also a Q4 weighting of sales, meant year end receivables were higher. It says this is now unwinding into cash, post year end. That sounds credible to me.
EPS - why no increase, despite profit being up 79%? There are 2 reasons. Note 5 shows that the weighted average no. shares in issue rose from 22.2m last year, to 33.4m this year. I can’t reconcile this with the AIM Admission Document, which shows 4.3m new shares being issued, resulting in 33.2m in total after listing, in Nov 2021. Since the last year EPS number mainly relates to pre-IPO, I think I’ll just ignore it.
Also there seem to be some adjustments to EPS in the highlights table, because lower down it shows 25.3p dil EPS vs 18.2p dil EPS last year. This is different to the 25.6p vs 24.9p adj EPS figures in the highlight table. Let’s move on, as I’m going down a dead end here, of little use to anyone.
Order book - sounds very strong, in the context of £55m actual revenues for FY 1/2022 -
Record order book3 of £130.4m of which 62% [Paul: £81m] is currently anticipated to be delivered in FY24.
This bit seems to be saying that FY 1/2024 margins will be lower, and is crucial negative information, that you could be forgiven for not having spotted at first -
Unexpected inflation spike in other building works areas during calendar 2022 affected client programmes. This saw some urgent smaller value, higher margin projects move into FY23 with larger, lower margin projects moved to FY24. As a result, we expect to see FY24 revenues significantly ahead of previous management expectations with high-single digit PBT margins, before reverting to a more balanced mix of projects and margins in FY25.
This sounds serious, because the adj PBT margin was 18.3% in FY 1/2023. So high single digit PBT margin for FY 1/2024 seems to be roughly a halving of the PBT margin! That’s a big deal, but not in a good way.
Balance sheet - NAV is £25.0m. Deleting the £8.7m intangible assets, gives NTAV of £16.3m, which looks OK for the size of business.
Noteworthy numbers are that there’s little in inventories. Also a huge receivables figure of £29.2m stands out a mile. This is mainly work they’ve done, but not yet invoiced, and the commentary says it’s mostly turned into cash post year-end, so we have to take their word for that.
Net bank debt is £3.0m, which looks OK to me.
There is risk here. Lots of sales were booked in Q4 of LY, and were not paid for by year end, so we’re having to rely on the auditors having properly checked the receipt of those funds post year-end. Let’s hope they’re doing a particularly careful job on the huge receivables number - remember today’s numbers are unaudited, preliminary figures only.
Forecasts - huge thanks to Singers for crunching the numbers for us. What reads like a cheerful RNS is actually a big profit warning! Singers cuts its aPBT forecast by 42% to £7.0m, which is 15.8p.
My opinion - I’m disgusted with the way this RNS tries to gloss over a big profit warning for FY 1/2024. The commentary sounds upbeat, and that might have misled people into buying shares earlier this morning. The bad news is almost buried, with only the words “with high-single digit PBT margins in FY24” giving any indication that something is wrong, and that profit is set to plunge in this new financial year.
For this reason, I don’t trust the company, and am not interested in buying any shares in it.
It’s probably best to see the FY 1/2023 results as a one-off bumper year, not to be repeated.
What had been a rare, successful 2021 float, has now joined many of its peer group in the discount clearance section. From 277p float, to about 170p no [10:32], down 35% on the day. I opened at 08:00 barely changed, which confirms that the bad news was nastily buried, only dawning on people a little while later. What a poor show.
Watkin Jones (LON:WJG) (Paul holds)
Down 17% to 80p (£205m) - H1 results, FY PW - Paul - GREEN
An interesting property developer, which has a good history of building projects (e.g. student accommodation) to order, pre-sold to institutional clients.
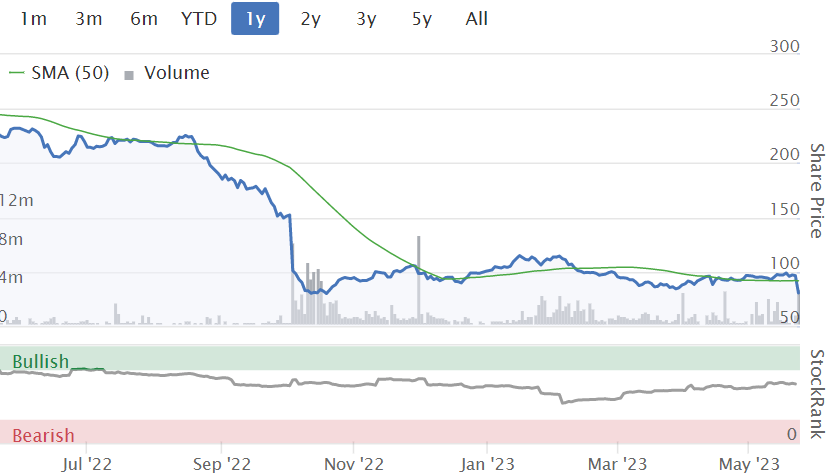
To set the scene, there was a big profit warning in Oct 2022, smashing the price down from c.150p to 80p. I bought a few as a toe-hold for a longer-term recovery, but also (bizarrely maybe!) anticipated another profit warning here on 27 Jan 2023 concluding that 2023 could be a bumpy ride, with another profit warning being a distinct possibility.
On 13 April 2023 I covered its update, when a contractor went bust, disrupting & costing more for a project in Exeter. Again, my conclusion was cautious, that publication of H1 results could trigger another dip in share price.
With hindsight, it would have been better to sit on the sidelines completely, but never mind.
Today’s interims are poor, as previously indicated, they’re actually in line with expectations, around breakeven.
H2 is expected to be materially stronger than H1, which is good.
However, it now looks as if they were previously far too optimistic for H2, and Progressive has roughly halved forecast for FY 9/2023 to £25m aPBT, which is 7.6p EPS.
Historically WJG has tended to produce about 15-16p EPS, so I remain of the view it should eventually recover to that level.
What’s gone wrong this time? It’s just delays to project completions - remember that WJG develops a small number of large building projects, so the numbers can vary a lot if completion of projects slips into the next year, which is now looking likely. It could warn on profits again, if the 5 deals it needs to close don’t happen by year end. So this is not a share for the faint-hearted.
On project pricing, it says this is broadly as expected, but with clients wanting more back-loaded funding, to suit their needs (in a higher interest rate environment I suppose).
WJG sees early signs of a recovery in its market conditions.
Project delays mean £15m profit shifts from FY 9/2023 to FY 9/2024.
Pipeline is down from £2.0bn to £1.7bn.
It calls the land purchasing pipeline “exciting”.
Build cost inflation - early signs of a reduction.
Paul’s opinion - obviously a setback, but one I was half-expecting, as you can see from the 2 SCVRs referenced above. As the shares get cheaper, the balance sheet support gets stronger, NTAV is now £153m, and the market cap down to £205m, so the previously big premium to NAV is now quite small. I don’t see any balance sheet risk, as it doesn’t have a large landbank, as it’s a more build-to-order type of business.
I’m currently about 20% down on a small position size, so it’s no great shakes, and the asset backing is now more solid than before. Hence I’ll wait to see where the share price bottoms out, then probably buy some more. As a medium-term recovery share, it should do well I think, which was my original investing case. This year is going to be worse than originally expected, but there’s no reason to suppose the medium term outlook has changed at all. Hence why I’ll obstinately remain positive in my view of this medium term recovery share.
If you trade in & out of shares on short term movements, then you might see things very differently, which is fine, it’s what makes a market!
There's also the interesting upside from Govt ideas to stimulate infrastructure spending, especially housing, by e.g. pension funds, insurance companies, etc. My thought is this could play right into WJG's strengths, and trigger a nice recovery in this share at some point in the future. So it's not a broken business, and with some patience, I think this could be a good recovery share, but maybe not until 2024 and beyond.
Roland’s Section:
Avon Protection (LON:AVON)
Roland's view: AMBER
Share price: 889p (-8% at 08.40)
Market cap: £267m
Full year Group revenue excluding armour now expected to be c9% lower than the prior year
In January, Paul noted that personal protection equipment group Avon was guiding for an H2 weighting to revenue and noted that the shares looked expensive. This stock has collapsed since the pandemic.
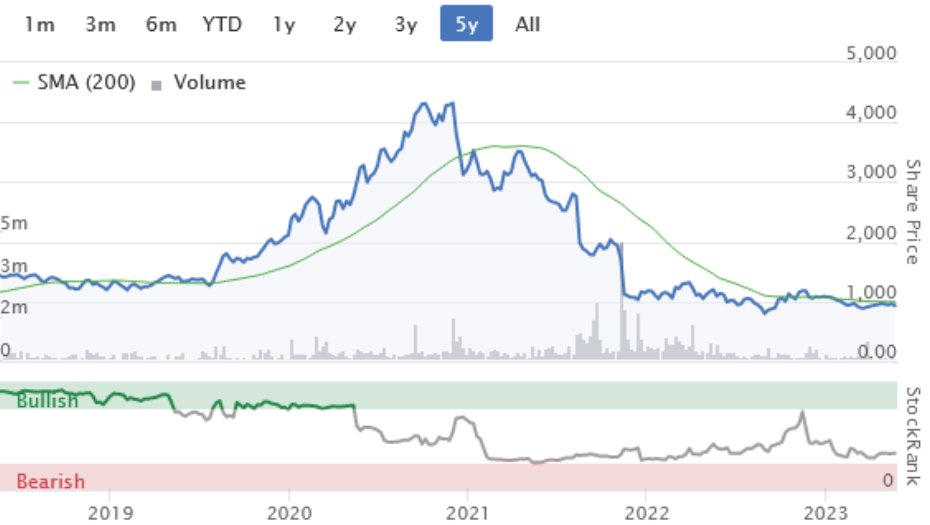
Today’s half-year results – the first under new chief executive Jos Sclater – reveal that full-year revenue is now expected to be 9% lower than the prior year. This compares to previous consensus forecasts for 11% revenue growth in 2023.
Avon says that a helmet programme with the US Department of Defense is going “slower than expected”. The group has also seen a decline in revenue from respiratory equipment following a strong prior year.
Increased revenue from body armour helped to offset this fall in revenue. But the armour business is currently being wound down, so will be excluded from future years’ results. Let’s take a look at some of the numbers.
Financial highlights: these figures cover the six months to 1 April 2023.
Group revenue down by 3.9% to $116.2m
Adjusted pre-tax profit of $0.9m (H1 22: $(2.8m))
Adjusted earnings per share of 2.4 cents (H1 22 (7.2c))
Net financial debt up 26.9% to $71.8m (2.6x EBITDA)
“Record-high” order book up 20.1% to $160.7m
Order intake up 11.9% to $125.6m
Improved order intake seems positive and could point to a stronger performance once the drag from the loss-making armour business is removed:
Armour revenue: $14.6m
Armour operating loss: $(4.7)m
At a statutory level, Avon remained loss-making due to a combination of amortisation charges, restructuring costs and transaction fees. However, these losses were reduced from last year:
Pre-tax loss from continuing operations: $(5.3m) (H122: $(13.6m))
Outlook: the company points to its record order book and says that “good year-on-year revenue growth” in Head Protection sales is expected in FY23 and beyond.
However, sales of respiratory masks are expected to be slower in H2 and lower than previously expected for the full year. There is also some “ongoing risk to shipment timings in H2” – presumably this means that some revenue could slip back into next year.
As a result, full-year revenue excluding armour is now expected to be 9% lower than the prior year. Cost-cutting means that EBITDA margins excluding armour are expected to be “broadly consistent” with the 14.7% reported last year.
I can’t find any broker notes for Avon on Research Tree, so I’ve checked back to last year’s results to calculate comparative figures. I estimate:
Revenue exc. armour of $240m
Adjusted EBITDA exc. armour of $35m
The net debt position is expected to improve during the second half as inventories unwind – I estimate year-end net debt/EBITDA is likely to be c.2x. Still slightly high, but not a pressing concern, in my view.
Roland’s opinion: this business used to be a reliable performer, but the group still seems to be struggling with the consequences of the 2020 acquisition of 3M’s body armour business (and the sale of its milkrite dairy division).
New chief executive Jos Sclater may be keen to get the bad news out up front so that future results will show a stronger comparative performance. Certainly next year’s results should be cleaner and simpler, once the armour business is excluded.
But even so, the underlying profitability of the continuing head protection and respiratory business doesn’t seem that impressive to me, with an segmental operating margin of 8.8%. Perhaps there’s scope for this to improve back to historic levels, over time:
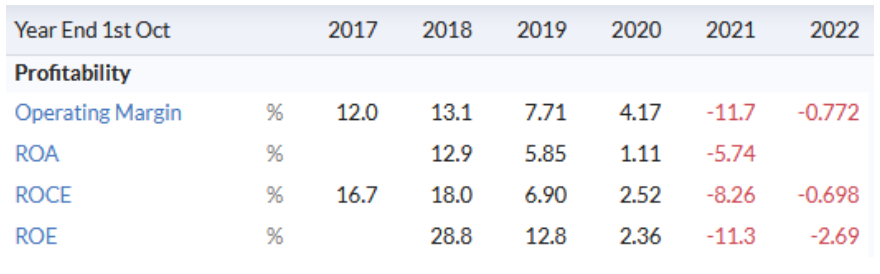
Avon’s debt levels are also worth monitoring, although the company’s explanations and guidance for reduction seem reasonable to me.
I estimate an operating profit of perhaps £17m (GBP) on a continuing, adjusted basis this year. The group’s shares still look expensive to me on that basis, with a market cap of c.£265m.
I think this business could return to growth from next year and may offer some medium-term value. But I’d need to do more detailed research into Avon’s products and markets to take a strong view on this. For now, I think it makes sense to remain cautious.
Calnex Solutions (LON:CLX)
Roland's view: GREEN
Share price: 109p (+10% at 09.40)
Market cap: £95m
Trading in the first few months of FY24 has continued as anticipated, and the Board remains confident in delivering results for the year in line with the revised market expectations.
This owner-managed network testing and measurement specialist floated in late 2020. The stock remains a double bagger, despite having come back to earth recently after the company lowered its FY24 guidance in March.
I’ve always had a positive impression of this AIM-listed business, so I’m interested to see what today’s results hold.
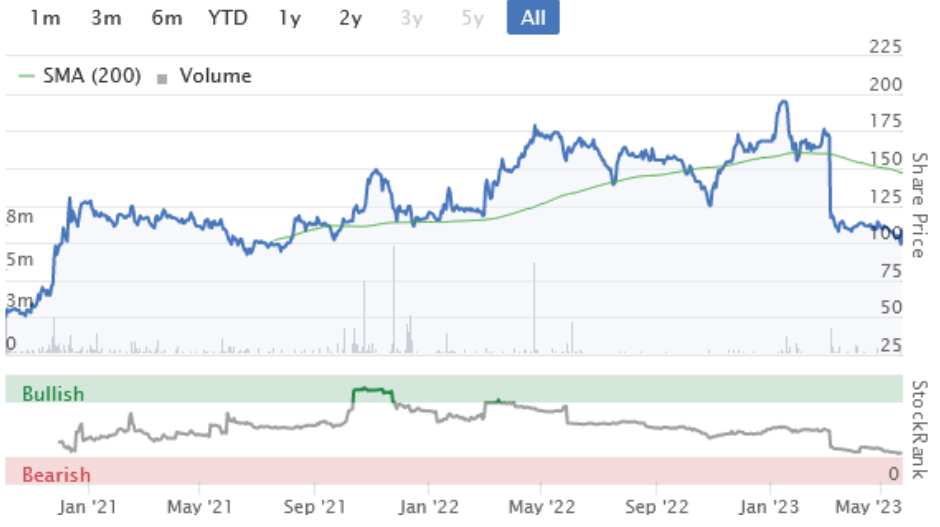
Today’s results cover the year ended 31 March 2023. Growth remained strong, but we need to remember the company’s most recent guidance is that “financial performance in FY24 will be below that achieved in FY23, with the Company's revenues more heavily weighted to H2 of FY24”.
In other words, growth is expected to pause this year, or perhaps even reverse.
Financial highlights: here are the main figures from the year just ended. These are nice clean accounts, so I’m quite comfortable presenting you with the company’s own numbers:
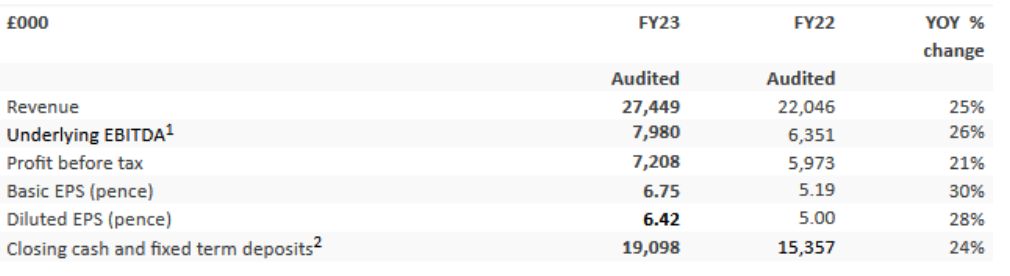
Profitability and cash conversion are very strong at this business. I’ve calculated the following numbers from today’s results:
Operating margin 26.4% (FY22: 27.2%)
Return on Capital Employed: 25.4%
Free cash flow (exc. acquisitions): £6.3m
Free cash flow/net profit conversion: 107%
Free cash flow margin: 23.0%
I don’t see anything to dislike in Calnex’s FY23 accounts. The shares don’t seem expensive to me on these historic numbers, either, trading on 15 times free cash flow (c.7% FCF yield).
The risks – such as they are – must clearly reside elsewhere. Let’s take a look.
Operating highlights: Calnex’s core customer base is the telecoms market. The company sells to both mobile and fixed-line operators. Unsurprisingly, 5G is cited as a major driver of growth.
Telecoms customers accounted for 75% of business last year, down from 77% the previous year.
The remainder of revenue came from data centre and hyperscalers (cloud operators) customers. Calnex sees these as offering good growth potential, given the scale, complexity and geographic dispersion of their networks.
The number of customers who ordered from Calnex last year rose by 72 to 305, but 47% of revenue came from the top 10 customers. So I think there’s still some risk linked to customer concentration.
However, customer relationships appear strong – those top 10 have been buying from Calnex for an average of 10 years.
Outlook: chief executive and 20% shareholder Tommy Cook says that “we have been encouraged to see the early signs of a more stable macro environment”.
The company has left its FY24 guidance unchanged in today’s results.So too has broker Cenkos, which is forecasting a 47% fall in earnings to 3.6p per share this year. That prices Calnex stock on a forecast P/E of 30.
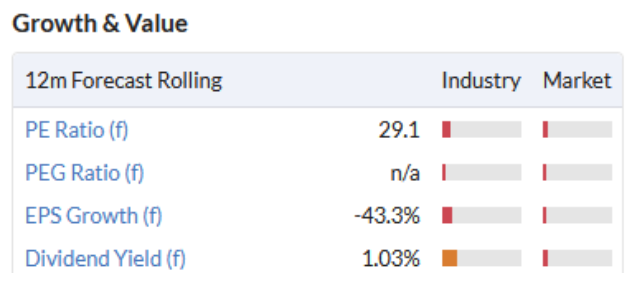
This rating appears to price in a return to more normal ordering patterns over the next 12-18 months. That assumption obviously carries some risk. But given the structural growth characteristics of the telecoms and data centre sectors, I don’t think it’s an unreasonable assumption.
Roland’s opinion: today’s numbers contained few surprises, demonstrating the strong profitability and cash generation that this business has displayed since its IPO.
Founder and CEO Tommy Cook remains the largest shareholder, providing good alignment with shareholders.
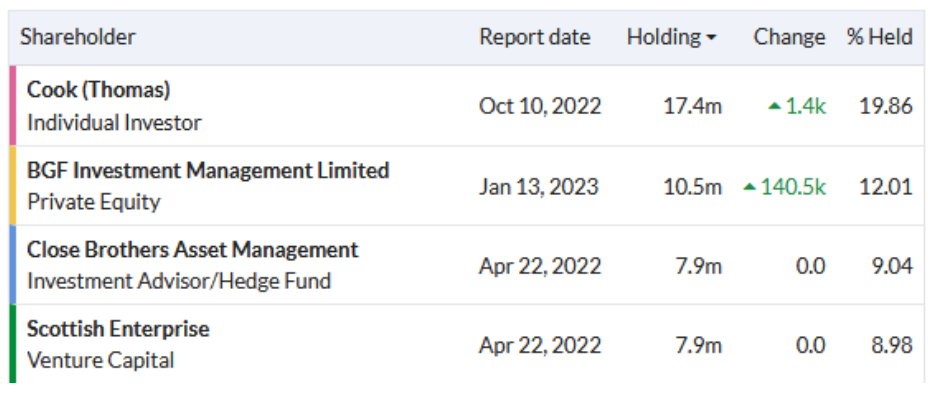
Although the shares look expensive on a short-term view, I think this could be a case where it pays to stay invested.
The balance sheet looks bulletproof to me – net cash of c.£19m accounts for 20% of the current market cap.
While the growth outlook is a concern, I see Calnex as a good quality business with the potential to deliver long-term compound gains.
I’m going to give the stock the green light. Based on today’s results, I would be happy to start buying gradually into a position here, potentially averaging up or down later this year, depending on trading.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
I love companies like Watkin Jones (LON:WJG) . Big fall, but on analysis, strong sales, strong balance sheet, established off-takers like KKR, supportive markets (student accommodation), long track record, stable management, strong cashflow. Bought at 71p after they tanked on deferral of revenue, and again at 64p. Will see if I have misjudged this, or if the market has.
.
Hello All,
Yu (LON:YU.) down a lot today. Is this retail investor panicking because of no TU this week thus far? ( Been one TU at AGM last 2 years ). Or something else amiss? Never good to see a constant trickle down over past few days.
What are your thoughts on XP Factory Paul?
Cheers
My thoughts are how on earth is that down today as well now?!..
This puts a bit more meat on the bones XP Factory (LON:XPF)
DirectorsTalk@DirectorsTalkXP Factory expects a very significant increase in numbers this year (VIDEO) Watch the interview here:
https://t.co/qTEgxX8VHD
Thank you for your comments and analysis on WJG Paul, they were disappointing results but we're in there with you. We will buy a few more today as I think the sell-off might be overdone and their's an excellent business in there imo waiting for better times.
Apropo of nothing in particular, had need to sell a little bit of physical gold today and thought I would look at returns from other assets since October 2019 when I purchased.
Gold +19.68% in 3 years 7 months
BRK.A +60%
S&P +42%
Dow +25%
AIM -13%
BTC +228%
FTSE All share +5%
NASDAQ +80%
This of course is one snapshot in time between two random dates but when one can get 42% and 80% on the S&P and NASDAQ respectively is there any point, apart from the increased “excitement”, of fishing in the micro cap pond?
Hope this isn’t heresy to post this here?
Regards
Michael
When I looked at various fee charging funds the vast majority cannot beat the S&P. Whats the point in them when they cannot even match a tracker ETF.
I guess the joy of small cap investing is hitting on a golden nugget which multibags. I had YU Group and Billington in the last year which gives enough incentive to keep plugging away. At some point therell be a bull market/big profits to be made again in small caps.
It is not one snapshot between two random dates. It is exactly what has been happening for the last 20-25 years and there is no point in investing in the UK micro cap (except from a a few quality companies).
I am now looking forward to read Paul’s bullish (probably) analysis on XP Factory ; another one that will end up close to nothing in the future.
is there any point, apart from the increased “excitement”, of fishing in the micro cap pond?
Hope this isn’t heresy to post this here?
Of course its not heresy.
It's certainly depressing. I imagine that few will be enjoying the 'excitement' right now? The last few years have been a painful time to be invested in UK small and micro-caps. Though a big dose of luck can make all the difference? I did very well until the end of 2019 - and its very seductive to believe that I could have made the decision to sell before it all went wrong. My 20/20 hindight is always perfect.
It was a mistake for me to think that because I'd done well for a few years it would continue. Likewise I don't know if I will continue to do badly because I've done badly for the last few years? Recency bias makes it seem all the more plausible?
I've used the time to focus my somewhat smaller (in size and number) portfolio on UK small caps that where I have a good level of conviction that they will do well in the next few years (just about) whatever is thrown at them. A tailwind will help but I'm not counting on it. For me this cycle is only just starting, the fat lady is not yet singing, indeed she's not on stage yet?
cheers
Mark
That sounds very much like me. Until December 2019 it had all gone rather well (my CARG was 15.6%). But the last 2 1/2 years have been pretty awful.
I started having money to invest around 2012 and got caught up in the “excitement” of micro caps. And I had some good years (6%, 79%, -24%, 16%, 31%, 28%, -10%, 27%, 0%, -15.4 & -19%) and made some good investments but I think it was largely a case of a rising tide lifts all boats. Those figures might look good but the equate to 7.5% CAGR. So on a risk adjusted basis I suspect they are horrible.
In hindsight I should have split the money 30% in each of NASDAQ, S&P and BRK (long term I don’t see the U.K. as a good place to put money to work - it is cheap for a reason as they say) and kept 10% for the “excitement fund” (the stupid thing is I learnt this early on as The Intelligent Investor prescribes this and it was one of the first investing books I read but what does Ben Graham know).
Regards
Michael
If Nasdaq is up 80% doesn't that mean it is now expensive? Just askin...
No , it does not mean that. Just answering.
I'm surprised you only have 19% gain on gold, is that based in $s, because the charts based in £ are showing considerably higher gains.
I tend to agree about the UK markets, my US folio is doing considerably better, although last year was not so good. 80% on the Nasdaq beats most fund managers.
Hi Rusty
That was sterling to sterling but an actual trade of physical gold. Looks like the broker took a good slug, as Sharepad shows 31.9% for G£.
Regards
Michael
These markets are very hard at present. On balance there seems to be more negative news around than positive. The main investor focus is now on debt and how growth will be funded in a higher interest rate environment and with poor appetite for equity issuance.
I had to smile at the Avon Protection (LON:AVON) results..the FD is apparently called Rich Cashin. Incredible how a once safe as houses company has been brought low by poor management. I suspect they are now bitterly regretting the sale of the milk business and the foolish acquisition of the body armour protection. A long haul back to glory I fear.
Eneraqua Technologies (LON:ETP) I was expecting directors to pile in here if 2024/25 recovery is as rosy as they claim. Just listening to the presentation the CEO says he wont be buying.
Certainly seen this current problem coming down the pipe in December last year. Once again another incredibly lucky £1m+ director sale 6 months before a profit warning.
P.S Liberum (made joint broker in March) have a new report out if interested. They see heat pumps taking off in 2025.
They have Gross margins falling to 28% this year > 30% next. Previously ~40%+
Just a brief comment on Eneraqua Technologies , as it is very popular here today.
Just be careful of the massive increase in receivables. Price might bounce back after this massive drop but the future doesn’t look very bright here.
Eneraqua Technologies (LON:ETP)
Just be careful of the massive increase in receivables
Yep 100% agree - just had a quick look and there is a more than doubling here FY23: £29.2m, FY22: 12.4m - note that includes accrued income.
29.2 mill with only 55.1 mill of sales has all the alarm bells ringing for me - they better hope their customers are happy to pay up. In their defence they say 54% of accrued income has been paid over as cash now and they expect 100% cash conversion this year - so they have some sort of "plausible" explanation as to why it is what it is.
Personally exactly the kind of company i feel no need to risk my money with at present.
Does anyone know if there business is reliant on government handouts? i could easily see scenario where these eco handouts if they exist are withdrawn en masse at some stage in the future. Howm many businesses would want to invest without government freebies ?
Does anyone know if there business is reliant on government handouts? i could easily see scenario where these eco handouts if they exist are withdrawn en masse at some stage in the future. Howm many businesses would want to invest without government freebies ?
As far as I’m aware they sell pumps and flow control technology and their customers are local authorities and housing associations. I have no inkling that their income is materially dependent on grants, or indeed comprises any grants at all.
Having a small starter position I don’t owe management any favours here but I think that a company whose directors own 55% of the shares probably has an owner’s eye and will endeavour to right the ship. All this talk of misleading investors and suspicious revenue accruals is a bit moot when the main investors they are “pulling the wool over” sit on the BoD!
Liberum put out a note post-TU at around 9am with a target price between 300p and 400p, which to me is a stretch given the recovery of PBT to FY23 levels will take to the end of FY26 (March)
That said, I put in a sell order early this morning and it failed to execute so it’s not just management I’m pissed off at. Market makers are a rule into themselves.
Thanks, Roland, for the commentary on Calnex Solutions (LON:CLX) .
Just read the results this morning, and clearly a nicely profitable company. I like the clarity in their financial commentary. They come across as a straightforward company which would make a good medium to long term investment. (Currently no position - I sold after the March 2023 profits warning.)
They do capitalise some R&D spend, but to their credit this is made very visible in the results. It is good to see net cash - for once a company with a genuinely strong balance sheet not just claimed.
I can't say I much undertsand what they do, but wonder how they can compete longer term as a relatively small company in a rapidly evolving worldwide industry. Aren't there much larger competitors who could out-compete them purely on R&D investment? So this is a downside along with the somewhat lumpy nature of investment by customers. (Ideally their product would be so essential that customers could not afford to defer purchases.)
Overall I like this company but would personally rate it Amber for now on the basis of their slowing sales and forward PER being a little high. (With risk-free base rates heading for 5%, the worth of growth/high PER companies should be disproportionately reduced.)
Calnex Solutions (LON:CLX)
I took a read-across from industry leader Keysight Technologies (NYQ:KEYS) last week and was confident in Calnex going into earnings. Keysight had fallen badly on a slowdown in the previous quarter, just like Calnex and its competitor/distributor Spirent. Last week however, Keysight shares bounced on a soothing update which suggested that normal purchasing patterns were re-establishing themselves. So, Calnex's reassuring update not only provides a consistent message, but one that is forcefully backed up by the industry giant.
I'm surprised not to see Spirent Communications (LON:SPT) bounce in sympathy. Shares look cheap for a quality operator.
Re Portmeirion (LON:PMP) - I think Paul has pitched this perfectly, medium term good, short term some risk.
However, I think the downside risk is mostly about a temporary miss on revenue. On profits, not mentioned today, I think the tailwinds this year from lower container shipping costs and the cost-savings driven from more factory automation/less quantity of energy used plus the better margins from its growing direct to consumer sales (esp through collectible sets) will cover it. These latter savings/gains should endure which is what will drive the margin gains, esp if sales grow/recover. H1: H2 sales split is roughly 2:3 so the statement about Xmas orders looking better than last year is encouraging (but is very early so not really meaningful!)
Since product NPD and Sales&Marketing development continues to look good and Mgt look sensible, I think Portmeirion (LON:PMP) look a good medium term risk/reward bet going forward. Certainly the business was higher valued in the past when arguably it was less well run, even adjusting for the increase share count .(I hold)
Worth also remember though that US is around 40% of sales so 'some increased caution from US customers during recent weeks in relation to near term ordering' is not great. Also flat sales so far this year not great in the context of an inflationary environment.
I'm confused - Eneraqua Technologies (LON:ETP) say that revenues for 2024 will be "significantly ahead of expectations", then they go on to say that the "order book stands at £130.4m of which we currently anticipate 62% to be delivered in the current year".
But 62% of £130.4 = £80.84m and the forecast revenue for 2024 is £80m so for revenue this looks like an inline trading update for 2024, not "significantly ahead". Anyone any idea ?
I'd imagine with 8 months still to go they'll be significantly ahead on revenue since they're already at 80m
High single digit PBT margins tho.
I'm not buying the whole low margin work has suddenly appeared story. 2025 is forecast at much lower PBT than 2024 was before this mornings results.
where did you get 2025 forecast from ? stocko only shows the forecast until 2024 ! which is showing a rise in earnings but i guess this will be revised down now...
I'm not buying the whole low margin work has suddenly appeared story. 2025 is forecast at much lower PBT than 2024 was before this mornings results.
The company specifically states that it expects to revert "to a more balanced mix of projects and margins in FY25". I would therefore take Singer's estimate of FY25 £9m PBT as a prudent "show me" estimate since it assumes PBT margins stay depressed at around 8.5%. Indeed, Singer acknowledge in their sign off that "management also indicates that the order book is supportive of an improving margin profile."
Profit margins were 12% in FY22 and 18% in FY23. Let's assume a reversion to an unambitious 11% in FY25 and we get a PBT of £11.5m on forecast t/o of £105m. That's 10% ahead of the FY23 number and 50% up on FY24.
Obviously all this is glass-half-full guesswork but the problems are macro-driven, hence prone to unexpected twists and turns, while the drivers of growth are secular and reinforced by regulation. Do you trust management to steer the right course?
No news today with Gulf Marine Services (LON:GMS) but it may be interesting to others that the SP has broken above recent resistance, and just broken above the 200 SMA as well as moving above the 50 EMA last week. I note that a BOD did sell about £20k of shares on 10th May.
yep saw that very good vs net book value, debt coming down.
My issue is day rate for vessels only increasing @ 10% yoy, same as inflation. For this to take off & op leverage to kick in need at least 20-30% increase. Mgt constantly talk about tightening market & increased demand yet not showing in day rates yet & contracts signed months in advance so could be long time yet for rates to meaningfully increase, if ever.
I wonder why Eneraqua Technologies (LON:ETP) has taken such a beating this morning...I though the results were good and the outlook good too ! Looking pretty cheap now.
Seems to be such an illiquid market people take any opportunity to cash out as soon as there is some volume. XP Factory (LON:XPF) had great results imo (Hopefully Paul agrees) and was on a right run until someone sold into it.
@ LON.XPF It's a long statement to read through and it reads well until near the end , after the auditor's report when you discover they made a £1.1million loss
I wonder why Eneraqua Technologies (LON:ETP) has taken such a beating this morning...I though the results were good and the outlook good too ! Looking pretty cheap now.
I think it’s the forecast fall in margins for FY24 from high teens % to high single digit %, which would produce a significant (c40% is my guess) fall in operating profit . There’s also the suggestion that the achievement of FY23 expectations was only reached by some pull forward of high margin business in the final quarter.
Against that, valuation is not demanding for a rapidly growing business.
Eneraqua Technologies (LON:ETP) Broker cut PBT by 42%. EPS down to 15.8p
I had liked the look of this business but personally I wouldn't be touching it now unless it's 160-180p
thanks for that, that explains it - where do you get the broker forecast from ? is this information free or you pay for it ?
Wolf: Eneraqua Technologies (LON:ETP) is falling steadily and looks as though it may be in your buying zone before lunch today.
It is already 169p to buy Eneraqua Technologies (LON:ETP)
Honest to god, I know how to pick them! :( Eneraqua Technologies (LON:ETP)
It could be something to do with the research note from an analyst at Singer with a headline of "Under review from buy ".
"Whilst we upgrade our revenue forecast, the shift in margin mix leads us to decrease our FY24 adj. PBT forecast by 42% to £7.0m. The order book is expected to support a return to more normalised margins in FY25, prompting a recovery in our FY25 earnings forecast. We place our recommendation under review as we take stock of the results, though we continue to see attractions in the medium term investment case."
I am not an analyst but my reading of the results this morning were not remotely as pessimistic and I quote from the prose with the phrase "the group now expects revenues to be significantly ahead of its earlier expectations ,with high single digit PBT margins in FY24 ,before revertibg to a more normal mix of projects and margin in FY25 .
Their order book is still both preserved and pretty big ( many companies would die for it ) and this research note is basically saying that margins will collapse by 42% in 24 - sorry I just don't believe it
"The current year and outlook
The current year has seen work commence on a number of new projects for clients including the London Borough of Lambeth. As outlined above, the very high inflation seen towards the end of calendar 2022 impacted our client budgets and led them to re-prioritise, causing individual projects to move between financial years. As a result of the shift of larger, lower margin projects into the current year, the Group now expects revenues to be significantly ahead of its earlier expectations, with high-single digit PBT margins in FY24, before reverting to a more normal mix of projects and margin in FY25. Importantly, however, no contracts were cancelled or are expected to be cancelled, underscoring the strength of our client relationships and the value of the solutions we provide.
In the current financial year, we expect to extend both our geographical reach and our expansion into new growth sectors, through both organic development and through further acquisitions.
This year we have delivered against the ambitious targets we set ourselves as we laid out our path to growth. Looking ahead, we are confident of continuing to deliver against our clear growth strategy and in being able to grasp successfully the opportunities ahead of us, which in turn will deliver increased value for our customers and shareholders."
A bit of help from Paul would be useful
thanks for this - where did you read the broker note ?
Research Tree
thanks.
Epwin (LON:EPWN)
Solid well commonicated update troday - they dont appear to be having any material issues that seem to be affecting others in building trade ref slowdowns. Use of the workd confident is reasuring albeit still 7/12 of the year to yet
The Group has continued to trade well and in line with the Board's expectations, with revenues to date 3% ahead of a strong 2022 comparative. The Board remains confident of delivering Underlying Operating Profit for the yearin line with its expectations
at p/e of under 7 this company remains unloved - debt under control so solid year of ticking over no bad thing.
MDMGMD Medical Investments (LON:MDMG) have today been delisted from LSE. As a holder I am assuming my investment is now worth £0.
Portmeirion (LON:PMP) Glass half full I would suggest. Christmas order book ahead of previous year. A plus given that is when most profits are made.
Portmeirion (LON:PMP)
its all too waffly for me - why didnt they say on track to meet current expectations (as Epwin (LON:EPWN) did) or admit they are moderating expectations if that is the case - whilst i dont read the summary below as being profit warning i know this company is opaque enough that it could be nudge nudge for brokers to reduce forecasts somewhat. Not sure ahy 10% drop but perhaps market is not impressed with waffle - i most certainly am not impressed with their waffle. Lets se what next broker updates bring. Sometimes i think if you are on track for what you have promised previously you need to somewhat stick your neck out and say that rather than create confusion.
In summary, we remain positive about the short and long-term prospects for our
business although we remain mindful of the challenging consumer headwinds.
EDIT
Cheers for broker update paul somewhat reassuring brokers not changing forecasts - shame company couldnt have told us direct though if that is the boards viewpoint!
Singers analyst Sahill Shan has not made any forecast changes this morning, sticking with FY 12/2023 forecast of 51.7p EPS (up c.10% on FY 12/2022 actual)
Benchmark Holdings (LON:BMK) - just a reminder that we're hosting an investor presentation with management at 12pm today, following publication of Q2 / Interim results earlier this morning - the registration link is here: https://www.equitydevelopment....
Eneraqua Technologies (LON:ETP)
Preliminary results this morning. This company has interesting exposure to environmental and regulatory tailwinds. Results look broadly in line so may not interest the team as much as a profit warning. Perhaps more pertinent, a shift in project timescales means that revenues will be significantly ahead of expectations for FY24, but at the expense of margins, with margins (and possibly revenues - it’s not clear) reverting to mean in FY25 as a normal project mix re-establishes itself.
Hi BnB,
Thanks for flagging this up. Eneraqua Technologies (LON:ETP) looks potentially interesting, I'll try and take a look at this today.
Roland
Thanks for flagging this up. Eneraqua Technologies (LON:ETP) looks potentially interesting, I'll try and take a look at this today.
Thanks Roland
Thanks BnB here's a short overview of the Eneraqua Technologies (LON:ETP) FY23 results by the CEO: video & podcast.
There's a management webinar where you can pose all your questions at 11am this morning. Register here.
My morning smallcap tweet: The front row for all the blows
Come and say hello at the Mello London Show today and tomorrow. I'll be by the Tomb of the AIM Investor.
Home Reit (LON:HOME) First Property (LON:FPO) Empresaria (LON:EMR) Portmeirion (LON:PMP) Harworth (LON:HWG) Pebble (LON:PEBB) Physiomics (LON:PYC) Gresham Technologies (LON:GHT) Codex Acquisitions (LON:CODX) Eneraqua Technologies (LON:ETP), Dowlais (LON:DWL), Epwin (LON:EPWN), Big Technologies (LON:BIG)
◄Home REIT (HOME)► trading and rent collection update. Intends to sell in the near term of a number of properties. Appoints AEW UK Investment Management as Property Adviser. [SP=NA Cap=NA]
◄First Property (FPO)► Loan restructuring by Polish Associate, extends by 7 yrs. [SP=27.05 Cap=30m]
◄Empresaria (EMR)► AGM stmt. Weakness has continued into 2023. Jan-Apr net fee income down 5%; profits are expected to be down significantly. [SP=60 Cap=30m]
◄Portmeirion (PMP)► AGM stmt sounds in line although "some increased caution from US customers during recent weeks". [SP=512.89 Cap=72m]
◄Harworth (HWG)► AGM sttmt sounds in line. [SP=124 Cap=400m]
◄Pebble Group (PEBB)► AGM stmt - guides H1 up. In line? Expects decreasing capital investment from FY24. [SP=100 Cap=167m]
◄Physiomics (PYC)► warns FY-June likely to be more than 10% lower than £750k guidance. Blames "delays in data delivery to Physiomics for contracted projects and the signing of a project with a potential new client". [SP=2.54 Cap=2m]
◄Gresham Technologies (GHT)► AGM stmt - 'confident'. [SP=148.26 Cap=124m]
◄Codex Acquisitions (CODX)► suspended from 24 May due to audit delay. Trading remains in line. [SP=20 Cap=1m]
◄Eneraqua Technologies (ETP)► guides FY24 rev significantly ahead of management expectations with high-single digit pretax margins due to some larger, lower margin projects delayed from FY23. Expects a more balanced mix of projects and margins in FY25. [SP=260 Cap=86m]. I hold.
In line: DWL, EPWN, BIG
B.P. Marsh & Partners (LON:BPM) sold its largest investment today at 50% of its overall market cap. Continues to be a long term value play but surely must trade closer to its NAV given it’s able to prove the accuracy of it through this sale. No comment yet but I expect some sort of special dividend on this
£bpm - would have been nice to get sale at above book value. I always hope valuations are done on reasonably conservative basis so I would hope an acquirer would need to offer a bit more than market value if they want to buy out bpm. Reality is here this is sale on the entire business to third party so bpm possibly had little choice here. Heyho so decent cash to recycle into new ventures and the prior booked returns here do prove the business model works. Don’t think at book value sales will move the shareprice needle much albeit being such a large investment perhaps it might do ?.
They are still trading at a pretty bid discount to NAV so I am hopeful this realization will bring that discount down but I guess we shall see. Expect a bump now on expectations of a special dividend and then a fall when people get bored again.
Good morning Paul. Your comments on Watkin Jones (LON:WJG) results this morning would be very welcome.
Also very interested in this if you have time Paul (I know its Mello and you will be tight on time) - I was a little surprised by the 5-6% drop at the open if I am honest. Admittedly I only skimmed the RNS but (considering this is bombed out already) an in line update with respectable guidance for H2 and beyond I thought would hold the SP.
Yes, I'll be commenting on Watkin Jones (LON:WJG) (I hold) interim results. It's on the to do list above!
@Ben Hazzard, I suspect a 50% divi cut will have something to do with it.
Also, “Currently targeting up to five further forward sales in FY23, with full year earnings performance dependent on concluding these transactions in what remains a volatile environment, as well as finally agreed pricing and phasing terms.” Does sound a bit like warming us up for more bad news down the line.
I hold
Jeremy, both good points, I hadn't noticed the divi cut when I scanned this morning, I wish they would just state these things more explicitly. Looks like it could be a slow climb back up unfortunately (also hold).
"Interim dividend of 1.4p, reflecting building confidence in the H2 performance."
Is a somewhat (being diplomatic) convoluted way of saying, 'we're slashing the divi by 50%.....whilst keeping our nil cost LTIP*.
*The criteria for which include an EPS element which hasn't been finalised by the Remunerations Committee. What odds on the Committee picking a figure right at the bottom of the cycle, resulting in very easy criteria for management to hit/beat? Or am I just being overly cynical?
I think in the world of investing, "overly cynical" just translates to "experienced and wise"