Small Cap Value Report (Tue 24 Sep 2019) - PARK, FA., IDP

Good morning folks,
As far as yesterday is concerned, extra sections were added late in the day by Paul to Monday’s report.
There's quite a lot that I might cover today.
- Park (LON:PARK)
- Fireangel Safety Technology (LON:FA.)
- Innovaderma (LON:IDP)
- Moss Bros (LON:MOSB)
- Ten Entertainment (LON:TEG)
- DP Poland (LON:DPP)
- Versarien (LON:VRS)
Park (LON:PARK)
- Share price: 54p (unch.)
- No. of shares: 186 million
- Market cap: £101 million
(Please note that I have a long position in PARK.)
This is one of those stocks which makes me feel a little unlucky at the moment.
My entry price was 86p in November 2017, for something like 3% of my portfolio. It was just a small position in a company which I admired.
Using Stocko's look-back feature, I am able to go back in time and get a StockReport from that month, showing roughly what the share looked like when I bought it.
This is what I get:
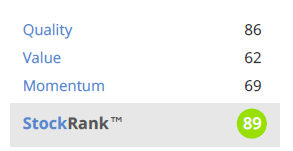
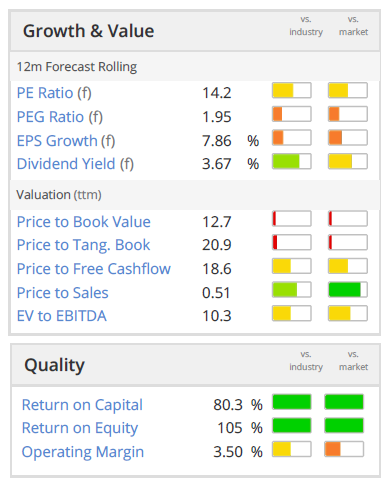
As you can see, it had a fairly average valuation (ValueRank 62) and a super high Quality score (Quality Rank 86).
Now let's fast forward to today.
It's true that Park missed its earnings forecasts over the past two years, with a 2019 miss of over 20% compared to the forecast when I bought into the company.
That miss had a lot to do with the company moving to modern new offices in Liverpool city centre, which created a big (£1.2 million) impairment charge for FY March 2019. The new office, according to the company, will help it to attract staff and have positive benefits for its corporate culture.
In the absence of the impairment charge, Park's FY 2019 result would have been very similar to its FY 2018 result, which was only a tad short of original expectations.
So on the basis that moving offices was a one-off event with positive long-term effects, I don't think that the company has done very badly during the period in which I have held it. But the share price is down by the best part of 40%!
This is where we are at now in terms of valuation:
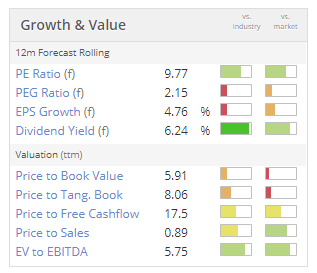
Let's compare some of the main value metrics:
- P/E ratio: 14.2x in 2017, 9.8x today.
- Dividend yield: 3.7% in 2017. 6.2% today (easily covered by earnings).
- EV/EBITDA: 10.3x in 2017, 5.75x today.
In summary, despite Park doing ok (in my opinion), its valuation has been significantly de-rated. I believe that this is a common story across UK small-caps.
So should I increase my position size? If I was interested in dividends, I might do that. But I am already fully invested and already using a little bit of leverage to gain extra exposure to the FTSE index. From a risk control point of view, I prefer being leveraged to the index rather than to individual shares (although exceptional circumstances might change that).
Anyway, let's see what Park is saying today. For those of you who aren't familiar with it, it's mostly in the business of providing gift vouchers and reward schemes, and it runs Christmas saving schemes.
- trading is in line with expectations.
- profitability to be suppressed by "strategic business plan" - new offices, technology and marketing investment. New ERP system, Microsoft Dynamics 365. This spending is not news - investors already knew this was in the works.
- H1 to be unprofitable as always, due to the high seasonality of the business, as it's geared toward Christmas.
- Name change to Appreciate Group plc to be approved at today's AGM.
- Msyterious new product, "targeting currently untapped areas of the gift voucher market", is "well underway". They will hopefully tell us the launch date for this product in H2.
My view - not much news here and I'm unsurprised that the price hasn't moved. But I do think that this is another example of a UK small-cap which has decent quality and is undervalued. But then I would say that, wouldn't I!
The bear case on this share goes something like this: High Street retail is dead, gift vouchers are old hat, and Christmas savings schemes are just a legacy from the 20th century. So if you take a very bearish industry view, you can expect this company to achieve no growth and be a very dull investment that doesn't go anywhere.
From my point of view, it's a unique business that generates a lot of cash and doesn't need to do much to justify its current share price. So I'm sticking around for a while longer yet!
Fireangel Safety Technology (LON:FA.)
- Share price: 20p (-18%)
- No. of shares: 76 million
- Market cap: £15 million
Paul and I have covered this company for some time, and it regularly disappoints. Mentally, I wrote it off as an accident-prone stock some time ago.
It comes back today, remarkably but unsurprisingly, with another profit warning.
What's happened?
What has happened today, in a nutshell, is that the company has admitted that its capitalised development spending isn't worth what it previously assumed it was worth.
Let's get into the weeds just a little bit.
When a company capitalises its development spend, it has an asset on its balance sheet it needs to amortise (write down the value of) over time.
What I always expect is that a company will write down this value on a straight-line basis, e.g. over 5 years.
It turns out that FireAngel didn't do this with its own development spending. It adopted a "units of production" method, which "is only appropriate where demand can be measured reliably".
So it sounds like the company was expecting demand for its new "connected home" products to be of a certain strength, and it planned to write down the value of its development spending as it made these products and sold them. Today, it admits that its assumptions were overly optimistic, "given the difficulty in accurately predicting the take up of its connected home technology".
It's moving to straight-line amortisation over 7 years, which is still a bit too optimistic for me. "Connected home" technology is changing all the time. Prudence would suggest to me that development spending in this area could be obsolete after 5 years, not 7. But there you have it.
There are also exceptional charges relating to battery warranties the company is exposed to for products it sold from a 3rd-party. These are hefty at £1.4 million (10% of the market cap now!).
My view
This company has been planning a turnaround for some time. I am deeply suspicious of its pivot to an "internet of things" type of business model - it could work out, but what are the odds?
You can buy an Alexa-enabled smoke and carbon monoxide detector from Amazon right now. Is this tiny company competing directly with Amazon and other much larger organisations? If so, how on earth is it going to win?
It made an underlying operating loss in H1 and its prospects for long-term success strike me as extremely remote.
Innovaderma (LON:IDP)
- Share price: 89p (+15.6%)
- No. of shares: 14.5 million
- Market cap: £13 million
This is another one that we have covered before.
I wrote a balanced piece on it in February, having been a bit sceptical of its (overly diversified, I thought) brand portfolio. On the bright side, I noted that it could start to look really good value it it hit its earnings forecasts.
Today, it is indeed starting to look value. With a 21% revenue gain, full-year PBT has doubled to £1.4 million.
In February, I noted that the share price increased on a day when brokers actually reduced their forecasts for the company.
The same thing has happened today. The share price is up despite the FY June 2020 net income forecast being reduced from £1.7 million to £1.5 million.
FY June 2021 is pencilled in at £1.8 million, as an initial estimate.
These are after-tax numbers and suggest lots of value available at the current level.
Outlook
- The new financial year has started "very positively" and current trading is "in line with expectations", despite the earnings downgrade.
- Skinny Tan should be in Boots for the full financial year, boosting the result. Superdrug will have a limited edition range for Christmas.
- Roots to get new products and a social media campaign, and the Prolong performance should be more satisfying.
- New disruptive product launch is coming (mysterious for now).
- Like Park, it gets an ERP upgrade.
My view
I've followed this off-and-on for a while, and continue to find it interesting. With the operational and financial success of FY 2018, and with prospects sounding positive, I'm honestly surprised that it remains so cheap.
The positive relationship with Boots and Superdrug, and their support of Skinny Tan, is for me the most interesting and exciting prospect.
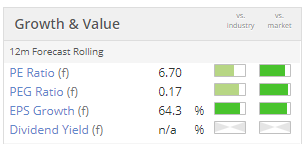
So I do think that this is worth researching in more detail.
Personally, I still don't quite see the logic of having skin, hair and sexual health products under the same roof. I also observe that 59% of Trustpilot reviews say that Skinny Tan is bad, and the product is rated as Poor. So I'm still reluctant to invest in this one for my personal portfolio.
Despite these question marks, it clearly remains possible that IDP could chuck out £2 million+ of PBT every year from now on. If they manage to do that, then surely investors will do well regardless of the logic and the product reviews?
Ran out of steam here, I'm afraid. Too many other things to do today.
I'll be back later in the week, so will try to catch up if things calm down.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Actually it occurs to me that I should caveat that statement; I am assuming that I might get pointers towards information already in the public domain. I doubt I would get any significant undisclosed information and if I did, I would probably be bound not to act on it until it was disclosed.
I thought for a moment there that I had had a "senior moment" but no, it's 2.5 on 6.5m I think?
As mentioned earlier up the thread I did contact their IR about the factual discrepancies. They have outsourced their IR department which worried me slightly, but if the Stock-report is correct they do only have 34 staff so perhaps that is not unreasonable.
I did get a swift acknowledgement but nothing more yet, will chase them up later and also see if I can reach out more directly to the UK based CEO.
I can see a few things beyond the potential factual issues with the accounts that I'd like to get clarity on.
Hello Gromley. Any response from Innovaderma (LON:IDP) ?
Hi mojo - sorry I skipped over your prompt previously whilst tweaking paraic.
Yes, (after prompting) I did get a response from their outsourced IR team.
I had initially only asked three 'technical' questions.
1. The cash "outflow" was indeed mislabelled and this has been corrected in the formal Annual Report that was published a few days ago
2. The outflow "for acquisition of subsidiaries", that I identified as missing in the full year, was consolidated into "Payments to suppliers and employees".
3. Similars for the "transactions costs for shares issues".
To be honest it is a bit difficult to have a proper discussion via an outsourced IR team so I am going to see if I can reach out to their Finance Director directly, to probe some of the more meaningful questions I have (I have a couple of possible avenues to achieve that.). So I will refrain from more meaningful comments until I have achieved that (or not!)
Prima facie I can absolutely understand your original comment, "It feels a bit fraud-y to me." That is certainly a big downside risk, but I think there is an equal chance that this is down to "experience and competence". They may be fantastic at Management Accounting but there is quite a gulf between that and Financial Accounting.
I continue to hold, but I have come to realise that this is MUCH MORE BINARY than I had initially thought.
In the spirit of open disclosure I should tell you that I am likely to either sell all or buy more before my next post on the subject.
Gromley, thanks for getting back to me.
Fraud-y was a heavy description by me! It would be great for you to get direct contact. My experience is that this lack of direct contact with mgt is not always a bad thing. Sometimes its a company keeping their heads down after a stuff up in some way and/or knowing they need to work on their communication and not dig holes. It doesn't quite look like that with Innovaderma (LON:IDP) IMO but what counts is what they do/say from here
I'm sweating here that I might be getting some basic maths wrong! But:
H1 17/18 = 4.2m
FY 17/18 = 10.7m
Therefore H2 17/18 = 6.5m
H1 18/19 = 3.9m
FY 18/19 = 12.9m
Therefore H2 18/19 = 9m
Difference of 3.5m over 6.5m surely?
On your other points:
9m - 6.5m = 2.5m
Oh dear. I'll get my coat.
To be fair, you did say in your earlier post "I'm sweating here that I might be getting some basic maths wrong! "
It happens to us all at some point, so no need to get your coat.(In any case I'm worried you might take mine by mistake!)
Thanks VERY much for those observations mojo - I will have a more careful look tomorrow. I will confess to only have a relatively superficial look in advance of taking my initial position, so those cautions are very welcome so that I can complete a more thorough review. From what you have said i am not really sure I see any major concerns, but I will defo look to examine all of the potential concerns.
I do love the open declaration of concerns one can get amongst the stockopedia community.
No worries Gromley. Like I said, I had a potential interest in Innovaderma (LON:IDP) and feel somewhat disappointed that I don't see an opportunity develop...however, I accept my observations are quick and not based on fulsome appraisal and the negative feel yesterday let a residual emotion about the stock from the past compound in to colour my mood darker
Right, I have had a look through the Innovaderma (LON:IDP) cashflow properly now.
Actually I quite like the way they present their cashflows ; the present the actual cashflows and then you have to consult the notes to see the reconciliation to profit. This compares with the “normal” presentation of cashflow which starts with a profit number of some description and you have to go into the notes to identify what it means. Personally I would rather that accounting standards stipulated that the entirety of the cashflow should be in the cashflow statement, not the notes, but that’s another argument.
Anyway there are a few oddities in the cashflow.
What they call “Net cash used by operating activities” (and “Net cash outflow from operations” in the notes section) is actually cash GENERATED by operating activities. I can only guess that they are using an old spreadsheet left over from before they became cash generative.
Comparing the FY with the H1 there are a couple of question marks.
In H1 they itemised a £73k outflow for acquisition of subsidiaries, in the Full Year I think they have rolled this into the general “Payments for product development/Intangibles”.
Also in H1 they recognised a cash outflow of £50k for transaction costs for shares issued. I cannot work out where this appears in the Full Year, but I think it must be netted off with Repayment of borrowings.
These are potentially quite trivial, but mysteries can hide other things so I have asked the company to clarify.
There are two more material things that come out.
Receivables increased by £1.5m. Bearing in mind that revenues in H2 increased to £9m from £3.8m in H1 I do not find that increase in receivables at all worrisome. In fact they did comment on this “Receivables increasing to £3.3 (FY2018: £1.9m) as a result of strong season opening Boots and Superdrug sales.” I am perfectly satisfied with that explanation.
Intangibles they increased intangibles by £0.9m in the year, more than all of this was for an intangible called “customer lists”. I am uncomfortable with this especially as PBT was £1.4m so on a more conservative measure would have been only £0.5m.
That is not in this case a killer for me, but it is certainly a number I will be keeping a very close eye on.
In the round I still like what I see and have brought my position up to “normal size” this morning, but do agree there are things here to keep a very close eye on.
Edit : I hadn't read the last few posts when writing this, but agree more cause for caution.
Re £IDP I was put right off them when, on 15th February 2018, they said:
"The Company has made considerable progress, both in terms of revenue growth and new product development across multiple categories which it believes will create additional revenue channels and substantial profitability in the second half of this financial year, and therefore the Board remains confident in meeting market expectations for this financial year."
... but then, just 21 days later, on 8th March 2018, they said:
"The Company has made considerable progress and the Board continues to expect the second half year to outperform the first half significantly, however revenue growth for the year will now be less than anticipated at the time of the interim results."
Three weeks between a bullish RNS and a profit warning - either they have very poor visiblity, or were not quite telling things how they were, neither of which are good in my book. The CEO's narrative is always excitable and bullish, both in RNS statements and on the many appearances he makes on the (paid for) Proactive Investors website, and having watched this stock for a while, my personal feel is that he is guilty of repeatedly overpromising and underdelivering. It's no longer one I would consider investing in.
Thanks for that on the management speak Gav it is certainly something that I always take into account.
With that and the concerns about intangibles I am getting a much better feel for why this is so "cheap".
I need to kick a few more tyres on this to get really comfortable, but as it stands I would still stick with the view that the valuation anomaly (as I see it) is just to big, unless it is an outright fraud.
Gav - but you are not really comparing like for like. The entrepreneur became chairman and they brought in an experienced hand as CEO to run the ship. Since then the excitable posts have declined considerably and they have performed in line with the expectations set.
I was put off buying Innovaderma for the reasons stated above but since new management has come in they seem to have managed market expectations much better... albeit we only have about maybe 6 months of evidence of that so far.
I calculated this morning that H2 revenue growth was 54% which is very impressive. Also H1 FY2020 results will presentationally benefit from the fact that H1 FY2019 was quite weak with a fall in revenue so I think the current share price is very attractive. I can't work out why it has fallen back since the start of the week.
Actually I think the Innovaderma (LON:IDP) H2 revenue growth was only 38% (£9.0m vs £6.5m in the previous H2) there is a degree of 'step-change' in that figure too from the roll out of new retail channels, plus improvements in the DTC channels.
Of these channels will improve the H1 numbers, but I really don't know what to expect for H1 as there is a degree of seasonality in skinny tan, but I suspect it is much less than the historic numbers suggest.
The updated revenue forecast for growth of 19% in 2020 (excluding new products which it is prudent to ignore for now) looks a little light to me, so I would be hoping to see upgrades during the year.
I suspect the two things needed to convince the market here are (i) positive cash-flow more closely in line with profits (I see the growth in H2 receivables as being entirely consistent with revenue growth, but others may not view it so generously) and (2) profits that are not so reliant on growing intangibles.
If both of those are delivered (along with the growth) then I would personally hope the share price gains an extra digit.
How did you get to 38%? Isn't it £3.5m difference, over a denominator of £6.5m? Apologies if I am being dumb.
I need to find some time to look more thoroughly at the potential accounting discrepancies you and other commentators have pointed too which look more concerning to me. I wonder if these issues are the reason for the flat price post results?! Interested to hear if the company replies to you.
Innovaderma (LON:IDP) accounts are a bit mucky IMO and they could explain what's going on more clearly
Revenue £12.9 doesn't match receipts from customers £11.5m - obvs this explains why receivables have increased £1.5m (which is most of the £2.1m YoY increase on revenue), but...
I'd like better disclosure on why receivables are up so much and how those receivables are constituted...
Connected to that the cash on balance sheet has hardly budged.
And I find the way it reports its cash-flow odd...deliberately obscuring and/or catching out people that look more lightly? (see cash-flow statement and note 25)...
I don't like that the working capital movements are reported in a note at the very end of the accounts rather than in the cash-flow statement. And those working capital movements are maybe a little dissonant in that they have run down inventory (good) but implicitly are saying that they have a lot of growth to fulfil. I'd expect inventory to be up....and if its down like it is and receivables up so much then I'd expect explanation of why. [I note I am being harsh here and possible to see it a different way...and they do mention something 'seasonal' re Boots and Superdrug but I think its weak-ish]
Altogether, it seems to me that its not quite convincing that it has made the money it claims as a headline
In addition, they are not clear in disclosing how they account for the capitalised development YoY and whether there is any amortisation - see note 12. Implicitly it seems that that wrote off capitalised development at the beginning of last year (£294,715) but the development last year and this year they are carrying forward with no amortisation. Plus on intangibles they have a decent amount tied up in a bunch of products that don't seem to do much.
I'm just putting a negative case partly as I had Innovaderma (LON:IDP) on a remote watchlist whereby I could be interested on market cap less than revenue and profitability showing through....so it sort of in the territory but I feel its not been clear cut on securing its position (in my mind that is!)
The above observations are enough to stop me from looking any closer at Innovaderma right now. If I did I would look to see whether the accounting presentation and practices are consistent year over year or whether they have changed. It feels a bit fraud-y to me. That feeling is partly based on the spin of the old CEO (now chairman and main stockholder at c35%)...I felt he said whatever he could get away with...classic knock down the doors sort of salesman but not the right things for public company CEO.
That's all I've got time for as looking at my own personal basket of horrors reporting at the moment ( Tremor International (LON:TRMR) , AA (LON:AA.) and 1pm (LON:OPM) )...glutton for punishment! Managed to survive Tremor and AA today in price terms although the Tremor ride was wild and number of underwear changes needed. 1pm tomorrow. Praying to make it out of the week....
Oh, and forgot re Innovaderma (LON:IDP) ...
Obvs the capitalised intangibles could go straight into profits (if I interpret what's going on correctly). £325k this year and £250k last year. That's a meaningful lift to profitability each time (and I can't see some counterbalancing amortisation so all to the bottom line).
And making a tangential jump and making messy connection. Staff cost down by decent chunk...£325k coincidentally...but headcount up from 34 to 41. Explained as "reduction in director payments and a move to replace higher salaried cost personnel with better support staff"...a bit fishy again and not quite making sense? Or am I too cynical?
Innovaderma (LON:IDP)
'Capitalised development costs have a finite useful life and are amortised on a systematic basis based on the future economic benefits over the useful life of the project. At this stage, the useful life of the project has not been determined as development is incomplete, hence amortization has not commenced.'
Aggressive i'd suggest.
Innovaderma (LON:IDP)
Note12:
Movement in capitalised development costs:
Table doesn't look correct to me. They appear to have taken last years dev expenditure as a base for this year rather than last years YE balance.
I'd expect £872,328 for YE19 with no amortization.
I agree...which is why I assumed they must have written off the starting CD quoted in FY18...but obvs that should have a note explaining (and I wasn’t motivated to read through definitional notes or old reports). Even if a short case was valid a story company like this could rise a lot from here and get a higher rating first...
Innovaderma (LON:IDP)
Further to my point in post 40 they appear to have carried out the same calculation for FY18 results. It has the effect of only adding capitalised development costs for the last 2 years (ignoring any earlier capitalised development costs - but with no sign of amortization).
Very strange or i'm mistaken. Gromley's point regarding old spreadsheets etc is giving me confidence that perhaps they have miscalculated.
Interesting stuff Gromley and Cockerhoop
I'm interested in how they justify the £0.9m intangibles and in particular customer lists. This seems like it must come from direct sales and not their big retailer relationships? In which case is the prosaic description of what they have done is to ascribe future resell value to customers they have transacted with online?
A positive take on that would be that the intangibles represent recurring revenue. A negative perspective would be that they are double dipping earnings on these new clients.
Obvs my interpretation itself is speculative and I have not read the accounts as closely as either of you, nor have I been in contact with the company.
I had a look at Innovaderma (LON:IDP) after reading Graham's report and others posts here.
One amber flag for me is governance - the Executive Chairman owns 35% of the company. The company is registered in England and Wales but is run from Australia - 4 of the 5 directors and the auditors are Australian. If you wished to speak to a company contact following this morning's announcement you were directed to phone +61 (Australia). All more like an AIM company than main list.
As Graham says, an odd mixture of products, but I give them full marks for getting one onto Tesco shelves:
https://www.tesco.com/groceries/en-GB/products/302228027
As for their Prolong product - if anyone wants to find out about it (not yet available in UK) and are not too prudish you can read here:
https://www.menshealth.com/health/a20134423/premature-ejaculation-treatment-masturbation-device/
Gromley - a report is available at finnCap. They have reduced 2020 eps from 11.5p to 10.3p to reflect higher marketing costs for product launches. (Edit - sorry if duplicated davidjhill's post).
OK results & confident outlook statement from chairman at S&U (LON:SUS) today. Probably more attractive than Park but not all will appreciate the Non prime second hand car loans they do, but they have managed to grow it 20 years on the trot. Plus they have announced a decent looking replacement for the CEO of the motor finance business while the newer Bridging Loan business is into profit now and growing. I've held it for quite some time and happy to continue doing so, but not everyone cup of tea I guess.
Graham, re Innovaderma (LON:IDP) is there any more background on the reduced 2020 expectations? (And who they come from?) They do not seem consistent with the management speak in the public announcement (which of course could be 'spin')
Gromley - re Innovaderma (LON:IDP) house broker has increased revenue expectations by £0.5m but reduced expected ebitda by £0.3m because it reckons the new products will need an enhanced marketing spend of £0.6m initially. Seems to be a small tweak based on the "new disruptive product" alluded to in the results, which appears to have been a surprise.
Thanks David (re Innovaderma (LON:IDP) ) that makes sense and as far as I can see so far they do seem to know how to execute - so I would be happy to consider product launch costs at worst a neutral factor and possibly a plus point.
I took a small starter position today before getting that extra feedback and will certainly be looking further.
I was startled though to compare Graham's write up with the Stocko assessment of "Falling Star". A big driver in the low value score (37) was the PE (based on the 'ttm' numbers) of 79. This was due largely to the 'poor' H1 resulting from Facebook algo. changes (I have seen enough elsewhere to regard this as real rather than an excuse) the FY numbers seem to confirm that they have successfully overcome this.
So once the Stocko computers process these results I expect that Value Rank to improve markedly and it will probably be reclassified as "Contrarian" . Measured momentum will probably remain a drag on the SR, given that I think today's earnings number might show up as a small a miss and the 2020 downgrade will act as a slight drag.
I very much agree with you on not putting too much emphasis (if any on) the TrustPilot numbers. Not specific to TP, but I find on most review sites the 0/1 scores (the lowest dependent on platform) are often dominated by people that did not bother to work out what they were buying; equally the very highest scores I think not just the "fan club" but in some cases [I have no evidence of this here] look like they are seeded by the company in question.
I do though agree that filtering out sensible comments can be useful and given their reliance on DTC, if they do have delivery & service issues on DTC it will be important that the address this swiftly.
Overall though I think these results and the outlook are very promising; so may well be bringing this up to a full sized position after further research.
Graham - re Innovaderma (LON:IDP) I found it odd that the reviews on TrustPilot were bad. I know several women who have bought it, love it and have told their friends about it, so something felt slightly odd.
Looking through a bunch of reviews I noticed some trends and have some observations which may help for context.
1) Skinnytan sells something like 300,000 units per year - there are 116 reviews on TrustPilot. Not very representative ( it's 0.03%!!) . You don't sell 300k units of a product every year if it is genuinely poor.
2) They are predominantly all 1* or 5* reviews. From personal experience of reviewers this means the 1*'s are generally "venters" who haven't got what they wanted and lash out on a review in anger & protest or "disciples" who feel the need to defend at all costs. In either case I generally discount both. I tend to only look at 2-4* reviews as they are usually more objective.
3) Of the bad reviews a lot are related to delivery and customer service on their DTC. Complaints that it takes too long to arrive, often being out of stock and poor customer service. I'd say this is a good half of the poor reviews so logistics and customer care seems to be something they may need to improve upon. Won't affect the retail sales obviously as they are purchased off the shelf.
I agree the shares look good value here and am surprised they don't trade higher. I am long now.
Thanks for another interesting report Graham.
Regarding Fireangel Safety Technology (LON:FA.) I was just thinking if they do "connected" alarms, then when will the many companies who are doing other connected home products see the need to add fire alarms etc. ie More competition. So well done for finding an example.
What I had checked is:
1 Poor customer ratings on Amazon UK. I'm pretty sure people expect alarms to work properly, with zero hassle.
2 Overseas sales are only 26%. On Amazon.de, I see way more competitors than in the UK and these have much higher customer ratings than the Fire Angel product. https://www.amazon.de/s?k=rauchmelder&i=diy&rh=n%3A2077635031&s=review-rank&__mk_de_DE=%C3%85M%C3%85%C5%BD%C3%95%C3%91&qid=1569312441&ref=sr_st_review-rank
I don't own and have no plans to.
I thought I would share my very brief notes on Everyman Media (LON:EMAN) which published interim results today and which I hold.
yet total revenues only up 16%
and ticket revenue only up 9%
Seat prices and Food & Beverage are up, so this implies usage/available seat on average is down or average new venue size is reducing?
Any other thoughts appreciated.
Cheers
A
Following on from Abtan's post, here's the results overview video. CEO, Crispin Lilly talks about H1 19 results, rollout strategy, operational performance & outlook.
https://www.piworld.co.uk/2019/09/24/everyman-media-group-eman-h1-results-september-2019/
Video gives a great overview of the group, and is quite entertaining!
From the announcement, in line with expectations for the year.
· Revenue for the six months up 16% to £28.9m (H1 2018: £24.9m)
· Adjusted EBITDA1 increased 61% to £6.6m (H1 2018: £4.1m)
· Operating profit increased 14% to £1.6 million (H1 2018: £1.4m)
"The appetite for Everyman has never been stronger with our continued roll-out allowing us to deliver exceptional experiences to more audiences across the UK with our increasing footprint. As a result, we have seen progress across both our financial and operational KPIs, with growth in revenue and operating profit driven by increasing admissions and F&B spend. This has resulted in the record market share we are reporting today."
"Our ambitious roll out continues both in the UK and with our first international site, which is due to open in Ireland next year. We are confident that there is significant room for expansion. We look forward to delivering our proven model to additional communities in both countries in the current period and beyond."
Re Everyman Media (LON:EMAN)
I was sufficiently impressed by the presentation and the concept, following some review of basics (I must develop a methodology of investment!) to invest a modest sum.
A bit like a cinema with a bar/eaterie attached. Trendy/Metropolitan style. Could get up your nose if you are not a young wannabe, and sadly, as an old hasbeen I don't qualify.
Could see this being taken out in 2-3 years time by one of the bigger chains if it manages to sustain profitable growth.
So, Tremor International (LON:TRMR) is a gross understatement and should be renamed £RICHTER9
Re PARK (aka soon "Appreciate Group"). After 50 years in the software industry, I have an unshakeable rule to sell any company that announces the introduction of a new ERP system. Fortunately, I don't own any shares in PARK.
Probably of no consequence whatsoever, but I am puzzled by the name change for Park (LON:PARK) , to "Appreciate Group plc"
Are they going to brand themselves this way to their customers? It seems pretty weak to me (plus having the downside that half the population will probably be going is that one p or two?)
If not then what is the point?
I recalled (correctly for once) that Park recently changed their Ticker (November last year) from PKG to PARK, presumably they will change again.
It might not apply here, but I often think these Name/Ticker changes look like attempts by companies to disassociate themselves from their past. (A very pale amber flag if I am having a grumpy day)
I agree with you, but I was amused when "The Scottish American Investment Company" recently changed their ticker from SCAM to SAIN. I guess they got fed up with all the jokes!
And I can't dis-associate OPM from "other people's money".
RNS announcing an understandable change of name:
London: Friday, 22 July 2016: The Company is pleased to announce that following approval from its shareholders on 20 July 2016, IS Solutions Plc has now changed its name to D4t4 Solutions Plc.
Ten Entertainment (LON:TEG)
. Any advice on why Ten Entertainment (LON:TEG) IS UP 7% and Serica Energy (LON:SQZ) is down 7%
I can't speak for Serica but with regard to Ten Entertainment (LON:TEG) everything was reasonably positive despite them only being on track. I was looking for negatives but had to make myself do with the excessive admin fees with regard to the share options.
Note price reaction is often more about the outlook that the numbers delivered - and their anticipation of lfl growth of 4.6% going forward seems a good number if they can hit projections bearing in mind at present main overhead costs are well under control.
Outlook:
The Company anticipates long term average growth in like-for-like of 4-6%
We continue to expand our estate and improve our customer experience through inward investment and product innovation
· Highly cash generative, self-financed growth, strong balance sheet with even better banking terms agreed to grow the business
Second from last there has been recent shareprice weakness possibly due to large holder exiting the company there is a decent logical argument to be made that the shareprice is slowly getting back to former levels now it is apparent there was no logical reason for the spike downward when Woodford was a seller.
Finally Ten Entertainment (LON:TEG) is a reasonably newly listed company having only listed in April 2017. I am somewhat dubious about the motives for companies like this being listed - i think £26 mill went out to previous shareholders at the time of the listing - its pretty obvious they want to maximise their returns and that can leads to business outlook being glass full and a bit more for luck - so if a company can prove into years 3-5 that the business outlook is as per promised that's one less thing to worry about. Its particularly an issue with a company like this where its easy to under invest for the long term and show good short term metrics that then bite back at later date.
Innovaderma (LON:IDP) looks undervalued. Given where they finished the year a 10.3p EPS for the coming year looks more than achievable. I'd say there is some potential for upside surprise on that as the year progresses as it only assumes revenue growth of £2.9m. The Boots rollout for Skinnytan almost trebled the number of stores to over 2000 and this year will see the full impact of that. Cash at £2m with no debt shows no need for additional funding.
Trading on a 12 month forward PE of less than 8* feels overly harsh.
Graham
Would you mind running your eye over the results from Elecosoft (ELCO) today? They must be the only software company that was incorporated 80 years ago and they are generating cash in a difficult market.
Equity Development's note today says: "Consequently, we’ve prudently trimmed our FY19 turnover and adjusted EBIT forecasts to £25.6m (from £26.4m before) and £4.35m
(£4.52m) respectively – alongside nudging down the valuation to 100p/share (vs 115p before), equivalent to c.3x FY20 EV/sales." (At 9.30am they were 74-76p, down 6%)
Graham.
If you can fit it in, I would appreciate your views on the interim results from £ELCO. The headline figures look good and there is an increase in the dividend but the market is not impressed (down 5% right now).
This seems to happen each time the company releases figures.. and then we see a slow clawback.
Thanks,
Richard.
As a novice have two companies today releasing news which to me looks good. Any advice on why Ten Entertainment (LON:TEG) IS UP 7% and Serica Energy (LON:SQZ) is down 7%
Thanks in advance.
Another request for INNOVADERMA please Graham.
They’ve always had products that look to have such strong potential (e.g Hair restore product Roots, Sexual health product Prolong, which could achieve big sales, and Skinny Tan, a popular tanning product) but until today, with little evidence that they were implementing their strategy well.
Do their results today hint things are on the up?
XLMedia (LON:XLM) - for those interested yesterday in discussing XL Media there is a RNS this morning to say that Ory has bought another 324,000 shares at 61.4p. I think we have to assume he is optimistic about the future although I shall wait and see.
Good morning Graham
I would be interested in your thoughts on Flowtech Fluidpower (LON:FLO). Already inexpensive and I suspect may get more so in the short term. I have seen revised broker forecasts of 15p adjusted EPS and closing net debt position of £16.5m versus current net debt of £18.8m, for the full year
Gross margins are impressive for a distributor and I am an admirer of Malcolm Diamond, the non Executive Chairman. A resolution of the current political mess would clearly help Flowtech Fluidpower (LON:FLO) and its peer group. I hold and will likely continue to do so.
Another vote for Flowtech please.
Second vote for your thoughts on Innovaderma (LON:IDP) please Graham. Solid revenue and profit growth yet a very low rating due to past hiccups. My personal belief if that they have turned a corner and the shares will rerate accordingly given enough time.
Hi Ben, I'm studying IDP now. Thanks for the suggestion. G
Hi Graham
Another request to look at interims from Ten Entertainment (LON:TEG). Thanks
Ten Entertainment (LON:TEG)
Decent set of interims out, everything seems to be ticking over fine. It seems like they are just able to increase growth organically , increase sites , increase dividend , continue to invest in current estate without really materially increasing debt - Mina sweet even though that is how it should all work. Caveat debt is up but that’s due to large increase in machine leasing costs which I am guessing is kinda fake debt.
Outlook seems confident - note there are always material exceptional costs so numbers probably not as good as the adjusted numbers would suggest. The only outlier cost wise is the ridiculous 100k 6 monthly cost of administering the executive director share plan - material costs in this regard each year for the last 3 years. Must be easy money coming up with simple formula with complicated legal speak to basically pay out what could be done as an agreed salary bonus at nil external cost 100k down the potty.
Solid results from £TEN today with a predictable early reaction from the market.
However management seem to guiding for reasonable growth on the one hand but being slightly restrained on the other re summer weather related trading and development costs giving lower profit after tax for full year.
Agree with rmillaree about share option schemes
Questions - would like to know more about HMRC issues (min wage?) And why interest should be significantly higher when bank debt is 30% lower.
I hold
Steve
Hi Graham,
Can you review (LON:IDP) full year results out today please. They look to have turned the corner now and established a solid model with plenty of upside possible.
Many Thanks,
R
The +21% revenue is all the more impressive given they had -7.5% revenue in H1 meaning that that H2 must have been stellar (I'm a little short of time today but would calculate this otherwise).
I agree that LON:IDP seems like it has turned a corner and the extra stocking of Skinny Tan is good. The company is still deriving most of its revenues from this one product so might not quite deserve to be on a very high multiple, but it should be higher than the level of now previous financial year p/e of 9-10.
Hi Graham
Can you look at £MMX Minds and Machines please ?
Looks to be swinging into regular and predictable income and profit generation.
Looks like a takeover target as well for bigger companies in the industry looking to consolidate.
Thanks
GH
My morning smallcap tweet: That *bleeping* FireAngel warns again.
Fireangel Safety Technology (LON:FA.), ValiRx (LON:VAL), Allied Minds (LON:ALM), Versarien (LON:VRS), Flowtech Fluidpower (LON:FLO)
FireAngel (FA.) H1 rev up 17%. Cuts FY U/L 'operating result' to -£1-1.5m (before increase in amortisation from more cautious accounting). Blames completion of certain strategically significant trials.
ValiRx (VAL) has now received its £0.43m tax credit. It "continues to carefully manage" its cash.
Allied Minds (ALM) sells HawkEye 360 stake for $65.6m, a 5.6x return. Will return half to shareholders.
Versarien (VRS) AGM stmt is a jack-in-the-box of trials, collaborations, Letters of Intent but no money coming in.
Flowtech Fluidpower (FLO) H1 rev up 6% but expects little or no sales growth in H2. Guides FY pretax £10.8-11.2m due to 'Brexit nervousness'. The Stockopedia F/C is £9.75m, so figs not comparable? Also expects current conditions to persist well into 2020.