Small Cap Value Report (Tue 28 July 2020) - FOXT, GRG, SAA, CARD, IGR

Good morning, it's Paul here with the SCVR for Tuesday. Please feel free to add your comments from the 7am RNS, as I gradually write up the main article throughout the morning. I read all your comments, and am finding them very interesting & courteous of late, which is a pleasure to behold!
Estimated timing - I'm aiming to be finished by the official finish time of 1pm today.
Update at 13:09 - today's report is now finished. Sorry I didn't have time to cover everything.
Quartix Holdings (LON:QTX) - have just emailed me their results presentations, so I'm passing on the links for your interest. I'll write up a section on their figures later today;
Quartix - Interims business presentation video
Quartix - Interim financial presentation video from CFO/COO
.
Interim results - I'm excited to see that the first interim results for 30 June are starting to trickle through - so I'll focus on that first. Trading updates are all very well, but they often tend to cherry-pick key numbers, and omit the full detail (especially if PRs have been let loose on the announcements!). However, nothing can be hidden in interim results. So I'll get cracking on a couple of those first.
.
Foxtons (LON:FOXT)
Share price: 38.5p (up 3% today, at 08:33)
No. shares: 330.1m
Market cap: £127.1m
(I'm long)
Foxtons Group plc, London's leading estate agent, today announces its financial results for the half year ended 30 June 2020.
This half year, as for most companies, is split between a normal Q1, and an abnormal Q2 which was dominated by the unique covid-lockdown. All Foxtons branches were closed between 23 March - 30 May. The company updated the market frequently during the crisis, here is our archive, where I wrote about Foxtons 5 times between April & July, including its 40p fundraising in April, which raised £22m in fresh equity.
Interim results - the commentary is well worth reading for general interest, even if you're not interested in buying Foxtons shares.
Revenues down 22% on last year, at £40.4m
Statutory loss before tax of £(4.3m) - somewhat worse than the loss of £(2.5m) LY H1 - I was pleasantly surprised by this, but remember that it has benefited from the furlough scheme, waiving of business rates, and some grants. Still the Govt schemes have done what they were designed to do - retaining employees, and greatly cushioning trading losses.
Net cash of a very healthy £40.5m - boosted by £4.3m rent deferrals, and £3.5m in deferred VAT. So that's £32.7m of normalised net cash. Top marks to Foxtons for clearly stating these figures in the highlights section. This should set the standard for all companies reporting - they must give prominence to the artificial boost to cash from stretching creditors. Otherwise, they're not being honest, and investors do notice these things.
Acquisitions - strategy is to acquire high quality lettings books. London Stone Properties Ltd was acquired in Feb 2020. I've checked its accounts at Companies House, and it looks a decent business.
Recent trading - the most important bit, to answer the question whether things are returning to normal? The answer seems to be that things are improving gradually, e.g.
Lettings - commissions down 12% in June, down 3% in July - almost back to last year's level
Sales - down 44% in June, down 32% in July, and current pipeline now "broadly in line" with LY - it takes time to rebuild a sales pipeline for an estate agent (viewing to completion typically taking several months), so I think this looks OK.
Outlook - vague - well placed, but cautious. The 6 month Stamp Duty Holiday should be providing a good boost.
Balance Sheet - looks OK to me, although remember the stretched creditors will have to be paid. This begs the question, should cash-rich companies be taking advantage of various schemes to defer payments, and informal arrangements with creditors? In my view there is no point, because they can't earn any interest on cash balances. So why withhold payments? It looks a bit grubby I think, to stretch your creditors when you don't need to. Hence I'd like to see FOXT help the Govt & the taxpayer, by paying up the deferred VAT, which could also be trumpeted as a positive & patriotic thing to do. After all, estate agents can use all the positive PR they can get, for some reason the public seem to hold them in low esteem (I've never quite understood why, as most seem fine to me).
NAV is £131.9m, less intangibles of £112.2m, gives NTAV of £19.7m - quite good, and it includes a decent cash pile of £32.7m normalised net cash, as mentioned above. I'm not sure if that includes client cash (rent deposits, etc), do any readers know? When I rented a flat in Mayfair in the mid noughties, my landlord always complained that Foxtons sat on my cash for several months before paying him. I showed him my bank statements, to prove that I was paying the rent! That was a long time ago though, so hopefully they've improved since then.
Lease liabilities are quite large on FOXT's balance sheet. That could present a problem if more business migrates online, as in surplus costs. There again, you still see plenty of people looking in estate agents windows, and footfall outside zone 1 seems to be growing all the time, from what I can see, subjectively.
I note a new £5m loan has appeared on the balance sheet, which note 9 explains was drawing down of the bank RCF. This was fully repaid on 8 July, and would of course be taken into account in the net cash figures mentioned above, so is not an issue. In fact, that is has been fully repaid, post period end, is reassuring that the cash position is healthy, and no debt is required.
My opinion - I see this as a reassuring update. Foxtons is securely financed, with no interest-bearing debt after repaying the RCF recently. Therefore, I see no insolvency risk here at all.
H2 is likely to be loss-making, I imagine, as the benefit of the furlough scheme winds down, and the sales pipeline is bound to take time to rebuild. Offsetting that, the Stamp Duty Holiday should be a nice boost to accelerate sales transactions. Press reports suggest some people want to leave London and work from home in the countryside. Set against that, there will always be people wanting to come into London as things (slowly) return to something like normal. Other press reports have suggested that the Stamp Duty Holiday has triggered a dramatic rise in enquiries from buy to let investors.
Overall, I'm happy with this update, and it looks to me as if FOXT is now on a recovery path. Its overheads are quite flexible, since I understand staff are partly paid on commission, so reduced sales means reduced staff costs.
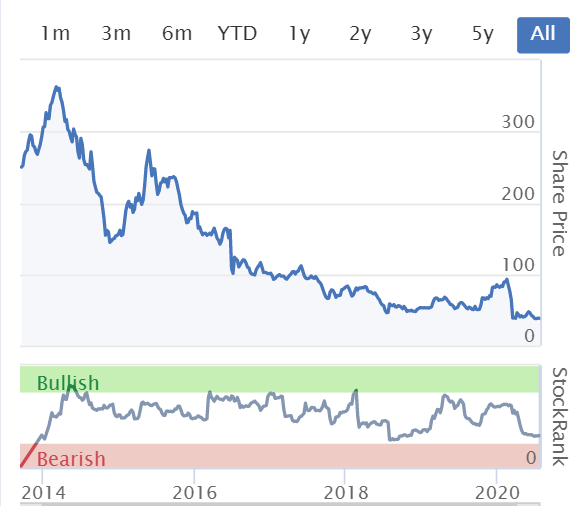
I could see this share being usefully higher, taking a say 2-year view. I've no idea what the share price will do in the shorter term. Buying close to an all-time low, and below the recent placing price, seems quite decent to me.
.
.
Greggs (LON:GRG)
Share price: 1413p (down 3% today, at 10:16)
No. shares: 101.3m
Market cap: £1,431.4m
Please forgive me for stepping outside of the small caps space briefly, but it's interesting & topical. Results from Greggs should have read-across to other companies, and inform us of the wider economic picture with town centres. Here are my notes of the key points only;
Heavy, but not ruinous loss in H1, at £(65.2m)
Since re-opening, most recent week was 72% of 2019 revenues, so LFL of minus 28% - I think that's OK, given that town centre re-openings are still in their early days.
Limited product range - best sellers only - this makes complete sense, as it allows them to operate on leaner staffing levels & reduces central costs.
Click/collect and delivery expected to be rolled (geddit!) out nationally. This is key I think - we're seeing in UK & America, that food businesses which adapt & expand into these areas, are the ones that are surviving. E.g. burrito company Chipotle has seen its shares boom, whilst sadly my favourite UK burrito chain (far better product than Chipotle incidentally), called Chilango, has recently gone into administration. It didn't adapt fast enough, sadly.
This year Greggs is opening 60 new, and closing 50 shops. It should emerge a long-term winner, and over time should be able to reduce its rent costs as leases expire.
Business rates relief for 1 year to March 2021, will save £25m - but of course is then a headwind for FY 12/2021 onwards. Although there might be more relief for smaller shops, and many Greggs are small, so it might fare better than most, at a guess?
Rents - paying monthly in advance, perfectly reasonable in the circumstances. I doubt many landlords would quibble over this.
Inflation - food/packaging/energy expected to cost +4%. On top of large increase in minimum wage this year, that's a nasty headwind.
Furlough - 75% of staff have been recalled, which is good news.
Profit guidance - current trading is cashflow breakeven (i.e. loss-making, once we take into account depreciation of fixed assets, and stretching of creditors). Breakeven profitability is 80% of 2019 revenues - recent trading not far off, although they only give us a single week.
Balance sheet - not great. The update here on 9 April shows that it borrowed £150m under the Govt CCFF scheme. But this was only for 11 months. Today's update has a going concern note which indicates it thinks the CCFF scheme is likely to be extended, but GRG is putting in place alternative arrangements to refinance this debt in March 2021. Given the company's excellent history of profitability & growth, then I imagine it should be OK, but there is an element of risk. If we see a second wave in the autumn, and widespread shutdowns again, then Greggs could be vulnerable. Not out of the woods yet.
My opinion - this is a terrific business, and it should survive, and recover, although there is an element of risk, given its borrowings, if a serious second wave of covid were to force long shutdowns. Although in that scenario, Govt support would likely continue, so it would probably be alright.
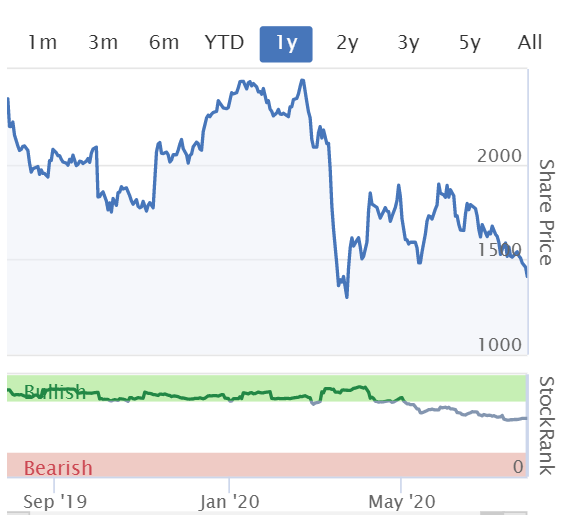
Overall, it looks like recovery to previous levels of profitability might take some time. The share price has scrubbed off the big bounce, and is almost back down to its March lows. Yet it still doesn't look good value to me, on a risk:reward basis. Nobody knows how much (nor how long) town centres are going to recover. Has some footfall been lost forever? We just don't know, hence why pay 22 times forecast 2021 earnings? In my view, it's still too expensive.
.
.
M&c Saatchi (LON:SAA)
Share price: 52.8p (up 14% today, at 11:32)
No. shares: 115.4m
Market cap: £60.9m
Trading, Banking, Strategy Update
Advertising/PR company with a famous name.
I've just re-read the update from 30 June, which was reassuring. Today's update goes further, and says;
Further to the announcement on 30 June 2020, the Company expects to report a small underlying profit before tax (PBT), before exceptional costs, for the 6 months ended 30 June 2020.
That strikes me as a pretty good outcome in the circumstances. During the covid crisis, we've heard from so many companies that they were pulling all non-essential spending, which would presumably include PR. Yet Saatchi seems to have survived intact, helped by cost-cutting.
Surprisingly, Q2 was resilient (but down on last year), better than expected, and client wins are mentioned.
Liquidity - this sounds fine;
The Group's balance sheet remains strong, and has improved further since the announcement on 30 June 2020, with total cash at £59m as of 23 July 2020, compared to £52m as of 23 June 2020. The Group has a committed £36m revolving credit facility (RCF) and a £5m overdraft facility with NatWest. The RCF is fully drawn and the overdraft remains undrawn, leaving net cash of £23m, compared to £16m on 23 June 2020.
There's also a £7m CLBILS facility (undrawn). Given the uncertainty, I don't blame the FD for drawing down a load of cash, just to be on the safe side. But it does look like belt & braces now!
The one glaring omission from this announcement, is disclosure of stretched creditors. As mentioned above, it is misleading to report a buoyant cash position, without disclosing clearly at the same time how much short term gains in the cash position is due to not paying VAT, payroll taxes, or rents on time. Still, it is a PR company, so I would expect them to gloss over potential negatives. That's always a mistake, investors need to be shown the full picture, not selected highlights.
Banking covenants - there are no immediate issues;
We are confident the company can comfortably satisfy its existing covenants for the next quarterly testing period, which falls on 30 September 2020, without needing any alteration....
Dec 2020 & Mar 2021 covenants are relaxed, and a table is given for that, which is helpful. This sounds like sensible contingency planning.
Of more importance is that bank facilities expire on 30 June 2021, so the group will need to renew bank facilities before then.
My opinion - this is clearly a good update, in bad circumstances. Conventional wisdom is that PR/marketing type companies do disastrously badly in economic downturns, but I looked back to 2008, and Saatchi seemed to sail through the problems largely unaffected.
There's a risk that SAA may have to do an equity raise, in order to keep the bank onside for next year's renewal.
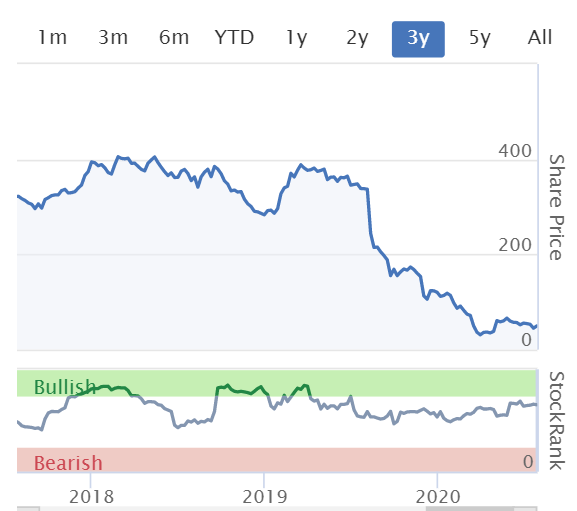
Other than that, I'm impressed with how well the company has done during this major crisis. Overall then, it looks potentially interesting, I'll add to my watchlist. Note from the 3-year chart below, that something was going wrong well before covid hit, so that would need to be investigated properly before buying shares in this. As always, my stuff here is a brief review, not a complete investigation, which readers need to do themselves.
.
.
Card Factory (LON:CARD)
Share price: 44.7p (up 7% today, at 12:15)
No. shares: 341.6m
Market cap: £152.7m
Trading Statement & Capital Markets Day
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, is pleased to update the market on its trading performance and financial position.
Sounds like there's a placing in the pipeline, why else would it be doing a CMD? It certainly needs one. This retailer of cards & gifts went into the crisis with too much debt, and paying overly generous divis. That was tolerable in pre-covid times, but has left it looking precarious in the current climate. Hence why I've changed my view on it - as we have to do when the facts change. Shares are not like supporting a football team through thick & thin. If risk:reward deteriorates badly, then they need to be unceremoniously dumped. Easier said than done though! I ditched mine a while back, and am not interested in buying back in unless/until the debt has been reduced through an equity raise.
On the upside, pre-covid this business was remarkably cash generative, and had the highest operating margin I can remember for a High Street retailer. Hence if footfall recovers close to pre-covid levels, then there's still a very good business here, once the debt is reduced.
Today's update - almost all stores (1,015) now trading again, done on a phased basis in June & July.
Sales - this sounds really good, and is better than Greggs;
Sales realised from our stores have exceeded our initial expectations, with like-for-like sales since reopening down 21.6% (compared to an anticipated 50% reduction in the first month of reopening).
Although the number of in-store transactions has fallen, reflecting footfall levels, the average spend has increased by 24.9%...
How interesting. The obvious questions are;
- What has driven such a large increase in average spend, and
- Is the higher average spend sustainable? If it is, then CARD could do well, even on reduced footfall. So this is highly significant. Or, have customers been catching up with their greetings card requirements, and average spend could then fall back to more normal levels? That would clearly be negative for future LFL sales & make it very difficult to turn a profit
- Was the higher average spend driven by discounting?
Website sales are still up strongly, even after stores re-opened, although slowing to +60.5% growth. I seem to recall that online sales are only a small proportion of the total, and my general impression is that CARD has missed out on a potentially huge opportunity to automate greetings cards. New website launched in early July.
Revenue for H1 is disclosed, but what about profit/(loss)? Nothing said about that, so likely to look grim;
Aggregate revenue for H1 FY21 (i.e. 1 February to 31 July 2020) is expected to be approximately £100m (H1 FY20: £195.6m), with material impact from the 12 week period of store closures.
Cash management - I'll copy this in full, as it's all useful, and (please take note people at Saatchi!) they've disclosed the stretched creditors - why didn't you?!
The Company has continued to manage costs, cash and creditors carefully and expects to remain within its revised banking covenants. Net Debt as at 19 July 2020 was £144.2m, which is below our original forecast, attributable to:
· increased revenues from store and online sales exceeding expectations;
· measures to reduce costs;
· improved terms agreed with suppliers and managing stock intake;
· cost deferrals amounting to c. £24.7m, including rents, VAT and some agreed delayed payments to suppliers. Deferred rents are generally payable over 12 months from September 2020.
To date, the group has received funding of £15.5m under the Coronavirus Job Retention Scheme, which has allowed us to protect roles during recent months. As previously announced, the group is eligible to issue commercial paper under the Covid Corporate Financing Facility, should it be required.
.
Outlook - too early to tell if pent-up demand is boosting sales or not.
Virtual CMD - signup link is here.
My opinion - there's a good business here, but it clearly needs to refinance the debt. To get investors excited enough to put in fresh equity, I think it will need to have a much more convincing online strategy. On my watchlist, but I wouldn't buy until it's refinanced properly.
.
Ig Design (LON:IGR)
Unfortunately, I've run out of time to do a proper write-up about its FY 03/2020 results out today.
So this is just to flag that the Q1 trading update within its report today reads quite well, so it might possibly be worth readers taking a closer look at this company?
The balance sheet is looking a lot better, after some fundraisings & acquisitions.
.
Unfortunately, I've run out of time today, so will have to leave Quartix until another time.
See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Re Quartix Holdings (LON:QTX) dividend - possible 8% pay-out for the year
Subject to satisfactory performance and market conditions, the Board will consider a final dividend for the year with the aggregate of the interim and final dividend set at approximately 50% of cash flow from operating activities, which is calculated after taxation paid but before capital expenditure. The Board will also consider distributing the excess of cash balances over £2m by way of supplementary dividends. The surplus cash would be calculated by taking the year end cash balance and deducting the proposed regular dividend. The policy will be subject to review.
H1 operating cash of £3.7m x 2 x 50% = £3.7m
H1 cash £10.0m + H2 operating cash of £3.7m - H2 dividend of £3.7m - base cash balance of £2.0m = £8m
£3.7m + £8.0m = £11.7m
£11.7m / 48.1m shares = 24.3p
24.3p final + 3.37p interim = 27.7p
27.7p / 348p = 8%
Looks like they are going to try and catch up the final dividend they missed for 2019
Regarding CARD, I think some people (well based on a sample size of one being my wife - not me, too disorganised) may well buy cards in batches. Suspect the sales rebound is substantially temporary as people rebuild their ‘stocks’ - have to think longer term lockdown will have further accelerated the pre-existing trend to digital greetings media
I think this is a business that is going online. Moonpig and Scribbler have very good offerings.
I would concur on the initial sample size of 1 (me), I was very glad when our local Card Factory (LON:CARD) reopened. My partner has to send everyone a card for their birthday, wedding, haircut, it is a Tuesday or whatever so maybe she is single handedly trying to save Royal Mail (LON:RMG) ? Anyway this meant that over two trips to the store we could replenish our greeting card draw (without having to spend £3+ per person) with various things for different ages taking advantage of the 5 for £1 and 10 for £1 offers, acceptable quality and fantastic price, even if you pay full price typically that is £0.29-0.79 so still a big saving over going to Clintons or the Co-op.
The staff were lovely, simple case of "please use the hand sanitizer" on the way in, they concurred it had been reasonably busy since reopening and seemed comfortable overall to be back and working once more and more than helpful when trying to find particular cards.
Though I would state I no longer hold as this was by far my biggest loss last year, I did not head the get out of dodge and kept thinking it would bounce back...
I would happily buy back again but agree with Paul, I want to see stability first in sales and also understand where the debt is going. Note there was also a replacement in the CEO recently too.
Tommy
Card Factory (LON:CARD)
The staff were lovely, simple case of "please use the hand sanitizer"
My recent incident with a staff member in there when i forget to use the sanitiser (didn't realise there was one or i needed to do owt when i walked in and was browsing) was much more traumatic. Lesson learned though it does one good to take ones severe earbashing once in a while when one is in the wrong. My cards were marked so as to speak for next time - so i intend turning up with full monty balaclava (or perhaps a nice chukkie mask) next time to hopefully slide under the radar and not be reminded what a naughty boy i am - my prior trip being pre mandatory mask.
Average increased spend at Card Factory is almost certainly down to pent up demand and people buying more merchandise ahead in case of another lock down. I have non food retail shops and this seems to be the case. Also worth noting that sales in my shops have declined further since face masks became compulsory. Bad news for retail if its across the board
I suspect people being forced to wear masks, on top of social distancing, will largely eliminate the idea of retail as a pleasant leisure activity including impulse purchases at shops one never planned to visit.
More likely IMHO is far fewer better pre-planned shop visits with a list of very specific purchases in mind. That is certainly the case for MrsS and myself who are doing much more prep for shopping trips than was previously the case.
Yes if shopping presents a risk then people logically will seek to minimise it. I added gift wrap and birthday cards to the Ocado order - in normal times I would have gone out to buy them.
Hi Paul. Note 22 of the last annual report says Foxtons does not include client money in its balance sheet (neither the cash, nor related liability). Close to £100m!
Smashing, thanks for answering my query, much appreciated!
Hi Paul,
I don't think you will get time but if you do, could you please have a look at Science (LON:SAG)
They released their half year results to 30 June 2020. The key point is that even during the tough covid19 period these are very impressive results AND ahead of management expectations at half year point. The current PE is ~15:
For those interested in digging into this further, todays interims:
https://investegate.co.uk/scie...
Thanks MGInvestor, that's a good pitch you made for the Science (LON:SAG)
I haven't got time today, unfortunately but you've got me interested, so I've made a note on my pad, and hope to return to it on a quiet news day (maybe Friday?)
Best wishes, Paul.
£GRG. Another great write up Paul and very pleased you broke your small cap rules on Greggs, most helpful. I, like many others I suspect, have a good chunk of my my investment in safe (please don't laugh) larger cap shares including Greggs. Are there any plans for a large/mid cap report eventually? - appreciate it cant be you.
Coming back to Greggs, your comment about the balance sheet "not great" - but its a long way from bad. They have a history of being conservatively run.
I have a large holding in Greggs and have traded batches over the years (mostly sells preCovid when it looked frothy) to the point where I have a negative in-price. I am starting to get tempted again around the £13.50 mark.
I might add, on the positive side, Greggs' competitive positioning is worth considering. Firstly, the UK when it wakes up fully will be poorer and Greggs is positioned firmly in the value market. Secondly its competition, particularly the mid market, is going to be severely dented by current events. Thirdly there will be a lot more people staying at home in the next twelve months and Greggs is likely to be beneficiary. All in all I think there is a recovery upside.
Only have a sample size of two stores, but woudln't people working from home act against Greggs?
The stores I have seen are much quieter now when I have passed. On a usual day they are quite busy, the lunchtime queues go out of the door.
I am sure that anyone working from home now is way more likely to make lunch themselves, rather than go out to a shop and buy it. Also if times got really tough, Greggs itself looks like a bit of an unnecessary expense. There may be people trading down from Pret, but then current customers can trade to making packed lunch.
The share price is interesting though, it's getting towards the lows that we saw at the start of the pandemic, and I am a fan of how they have grown their business. A return to previous profits implies that footfall goes back to normal, like Paul I do wonder if some has been lost forever.
Along with everyone else, I really appreciate Paul's analyses and commentary on our changing lives as well as the extensive range of informed and helpful comments from the community. I was sorry to see the rather disappointing news (and resultant share drop) from Greggs (LON:GRG) as this has been one of my standout shares for the past few years - but maybe it's time for a more modest PE ratio.
Reasonable news from Flowtech Fluidpower (LON:FLO) today I thought. Interesting to see the numbers still furloughed, and those brought back. It would be good to get your views Paul.
Sorry dealtn, there wasn't enough time to cover this one, and I'm lukewarm on it, given the lacklustre track record on share price over the years, so I prioritised more interesting things.
Some redundancies at £FLO were also mentioned in its report and that might not be the end of them.but from the investor angle the survival of the company is what matters most.
Silver
Nothing to really get excited about in today's update from Flowtech Fluidpower (LON:FLO)
Interesting a portion of workers still on furlough.
Cautious tone / outlook. Chimes with what I'm seeing in building industry suppliers I've seen across Europe. New construction is getting back on its feet, but not at levels Pre-COVID. Flowtech should be protected from service and maintenance revenue, to a certain extent.
There's just nothing tremendously exciting and its still trading on a historical PE of 8x adjusted, 12x basic EPS for FY2019.
IMO it needs to be about 20% cheaper, around 60p or less, to be interesting value.
Thank you,
Whitbourne
Kieranj077
jared007
If I’m picking up what you’re putting down, premarket purchasing seems to be more suited to £billion companies to eliminate “wide spreads and unexpected fluctuations” in price. Maybe not the best time to be trying to analyse this in the “COVID” market we are all churning through, but my system has had success in the likes of Powerhouse Energy (LON:PHE) ITM Power (LON:ITM) Best Of The Best (LON:BOTB) CMC Markets (LON:CMCX) Ilika (LON:IKA) , picking them up before the news was officially announced. As someone has told me in private,”many breakouts do give tell-tale signs in advance” which I 100% agree with, and is the reason I trade full time.
But for the ones it’s misses, or I am reluctant to buy Synairgen (LON:SNG) , it would be useful having a firm understanding of the premarket environment. I can either use the knowledge to profit from it, or to be a peace with one's self-knowing that little can be done until the market opens and live quotes can be read.
Thank you once again!
As a definite amateur I tend to stay clear of the market until 8.30 to let things settle down. I don't have level 2 data and I would think that is a minimum requirement to see what's going on.
But being our own bosses we can break our rules which I did with SNG. I had a few shares already so got the RNS in my inbox. I put in a fill or kill order with HL at 07.45 at a limit of 120p which was killed plus a limit buy at the open with ii which was executed at 125p. Very much a punt and ahead so far and no idea what the true value is going to be. Given the Friday close was at 36.5 p I did think I would get some with a 120p limit but not so.
Chasing a price like this isn't my natural game - if there's one thing I hate it's looking at a chart realising I'm the mug who paid the most that share ever traded at!
Greggs (LON:GRG) Spot on analysis of Greggs. Footfall is the key and it isn't coming back anytime soon. Great company but still too expensive.
re Greggs (LON:GRG) - Surely a lot of the footfall reduction must be the still relaitively low commuter numbers. I know that when in a recent role I changed trains onto the London main line you could hardly get by the Coffee & Sausage roll Queue at Greggs
Quote from Greggs when opening at the new London Bridge station
“These openings fit with our wider strategy to expand into more travel locations so we can provide our customers with even more convenient access to our great-tasting food.”
Moneysupermarket released their interim results today, bit of a mixed bag
"While the uncertainty now inherent in some of our
markets makes it difficult to provide financial guidance, we believe we
are likely to face greater earnings pressure in H2 than in H1, given our
good Q1 performance and the phasing of costs through the year.
I was looking to scale out at 353, not sure if I should accelerate that
Good morning Paul, Yourgene Health (LON:YGEN) year-end results today show good progress I think with their growth plans. Any chance of an update to your H1 analysis of last year from a financial perspective.
I had a quick look, and the numbers from Yourgene Health (LON:YGEN) seem to be improving, albeit still loss-making. Cash looks tight. I don't think I could add any value, as it's a specialist sector I'm not familiar with. Sorry about that.
What happened to Graham?
Not complaining, I love Paul’s work, just curious as I haven’t seen him write a report for a while. I hope he is well and will be back soon to help take some of the pressure off Paul who has been doing the work of 10 men just recently!
I believe he is focusing on his own site cube investments.
I think we should all consider a post COVID meet up and buy Paul a beer or two for his continuous efforts during this period. I guess preferably in a £RBG as then there would be two ways to thank Paul
Hope it won't be too far away but fear it just might be
Huge effort from Paul this week and last. He's the main reason I subscribe....
Thanks very much! Nice to know people appreciate my work, although of course I do get paid for it, but it's mainly a labour of love :-)
i second that motion
Graham has gone full time at his web site Cube Investments https://cube.investments/. I am a subscriber
I enjoy Paul’s, Graham’s and Jacks (occasional) SCVR. Though it is Paul’s that brought me here and keeps me reading without fail on a daily basis (along with John Auther’s newsletter).
Thanks Paul.
Micheal, thanks for your help yesterday as well as Laughton and Howard Marx in getting me connected with John Authers newsletter. Although I couldn't access the gold report I was looking for, having entered my e-mail address I find this morning that I have received today's report despite having ignored the Bloomberg suggestion of a paid subscription!
Thank you doublelutz
This should take you to his email on gold without logging in etc:
https://www.bloomberg.com/opin...
Regards
Michael
From Foxtons, as i think a useful read across to many areas, media surveys are generally highly misleading but people buying cars, houses (and until yesterday) holidays tells us a lot more although the incentives may just speed up the buying decisions for those who were to anyway:
Good recovery in lettings applicant numbers, listings and commissions, with lettings commissions over the 4 weeks of June down 12% and over the 4 weeks of July down 3% against the prior year.
· Sales commissions over the 4 weeks of June were down 44% and over the 4 weeks of July were down 32% against the prior year. The sales commission pipeline has strengthened since re-opening and is now broadly in line with last year. Short term future sales activity is further supported by the Government's Stamp Duty relief effective from 8 July 2020.
The sales commission pipeline has strengthened since re-opening and is now broadly in line with last year - if that means after they have worked through the leadtime of commission payments they are back to normal? If so that’s quite surprising .
To me, that seems like waffle. Sales commission pipeline is not guaranteed money, more deals are falling over due to decreased mortgage valuations and general uncertainty. Short-term future sales activity reads to me as if they are conducting more viewings, this doesn't make money although there may be some loose correlation with completed sales.
Lettings commissions should be pretty stable and not have a cliff edge drop, as Foxtons get take a cut of rental income. I would assume that most continued to pay their rent and even if someone didn't they may still recognise it upfront and just increase the provision charge.
It seems to me that sales is the driver behind Foxtons failure. Back in 2014, this division turned over the same amount as lettings, and made more profit. It's more than halved today and now makes a loss. The lettings part has stayed stable but profitability has dropped by almost half, no doubt due to the banning of various fees and general competition.
I just don't see how they will recover to what they used to be. It may be likely that staffing costs could be cheaper with unemployed people hitting the market but it seems like an industry where they have zero pricing power. Raising prices would see people just go elsewhere.
As a landlord and involved with many agents, the feedback on the ground is that business is good with the stamp duty change motivating many. Certainly in the South of England where I am. It is not just the money you save when buying, it is the money the buyer saves when buying your property. That makes negotiation and agreement a lot easier.
Secondly and much to my surprise, all my rents have all been paid in full. A bit late sometimes but that's fine at this difficult time. I have not increased any rents during the pandemic and my expenditure has been lower as tenants have not wanted trades going into their homes. Many of the staff I have got used to dealing with in the agencies appear to have gone and it seems to me that a number of older office managers have called it a day and have been replaced by younger and perhaps more dynamic former assistant managers (and cheaper).
FOXT raised new cash at 40p per share in April. I am building a stake below this price. I also hold the largest estate agent CWD...this has had a strong rally since June on trade rumours of stake building. A lot of business here with many key brands but more debt and much riskier than FOXT I think. A bid or agreed takeover would certainly shake the entire market up.
The downside I think is that the banks do not seem to want to lend any money at the moment. Not just mortgages. I checked my credit card accounts the other day. They always have various offers trying to tempt me to borrow. I don't want to borrow but for the first time ever I get the message "Sorry, there are no offers currently available".
It does not help that the credit agencies seem to be months behind. They blame the banks for not supplying the latest updated information on time. I am sure the banks would point to the huge tasks given to them by Government during the pandemic.
"Due to increased demand dealing with the impact of coronavirus, we’re experiencing delays getting some lender updates. This means it may take a little longer than usual to see any changes to your score or report. Please rest assured we’re working around the clock to do all we can to update your information".
Ig Design (LON:IGR) results today, certainly a CV19 hit, but they remain a quality company and excellent management. LFL revs -27.7%, slightly ahead of revised CV-19 guidance. Strong pipeline, 5.75p final dividend. Optimistic outlook. Here's a short interview with Paul Fineman CEO & Giles Willits, CFO. Video or Podcast.
There is an Ig Design (LON:IGR) FY20 results webinar this Friday 31st July, 12.30 with Paul and Giles, with the opportunity to ask your questions. Register here.
£IMO FY20 results today. Rev:+20%. GProfit: +26%. Cash: £2m. Long term +VE impact as businesses switch to cloud & digital communications. +VE outlook. FY20 results webinar with Q&A 5th August, 10.30am. Register here.Oh, and while I'm mentioning webinars, the next piworld educational webinar is with Richard Leonard, a week Thursday 6th August, 1pm. Investor & Trader: Life in a Family Office. Richard is ex City and now runs a family office. He discusses how he manages money, including what he's learned from his mentors & how it formed his investment philosophy. What he looks for, current markets, what he's buying, red flags, and much more. Register here.
My morning smallcap tweet: Ace trading at CARD
M&C Saatchi (LON:SAA) Open Orphan (LON:ORPH) Flowtech Fluidpower (LON:FLO) Card Factory (LON:CARD) Digitalbox (LON:DBOX) 1Spatial (LON:SPA) Norman Broadbent (LON:NBB) Ricardo (LON:RCDO) ULS Technology (LON:ULS) Wincanton (LON:WIN) Science (LON:SAG) Foxtons (LON:FOXT), Quartix Holdings (LON:QTX), Uniphar (LON:UPR)
M&C Saatchi (SAA) guides H1 small underlying pretax profit, ahead of than mgmt expectations. Covenants OK at next Q. Has relaxed them thereafter, 'mitigating potential risks that could arise even under an extremely severe scenario.'
Open Orphan (ORPH) wins Phase I covid vaccine trial contract from Codagenix.
Flowtech Fluidpower (FLO) guides H1(June) rev down 22%. June down 25% from 41% in Apr. Further cost cutting.
Card Factory (CARD) LFL sales since reopening down 22% cf 50% budgeted. Av spend up 25%. Guides H1(July) rev down 49%. No FY guidance.
Digitalbox (DBOX) guides H1(June) adj pretax ahead of management expectations with rev flat at c £1m.
1Spatial (SPA) AGM stmt. "Customer implementations and projects have largely continued as planned and we have seen a healthy level of new business secured in all geographies, with both new and existing customers, albeit some decision-making remains protracted. The Company's financial position remains robust."
Norman Broadbent (NBB) guides H1(June) down <10% and a small positive EBITDA.
Ricardo (RCDO) guides FY(June) rev down 9%. Order intake down 5%. U/L pretax £15-£16m due to squeezed margins.
ULS Technology (ULS) house mkt rebound has endured to July.
Wincanton (WIN) to build new eCommerce facility in Nuneaton. Loaf contract extended by 5 years.
Science Group (SAG) H1(June) rev up 56%, adj pretax up 50%, ahead of the Board's expectations.
Foxtons Group (FOXT) H1. Recent trading in line.
In line: Quartix Holdings (LON:QTX) Uniphar (LON:UPR)
Hi HollandSmith, are you intending to keep posting these summaries, i hope so, coupled with MR C makes for an excellent early summary before Pauls deep dives.
Hi John,
I've been a full-time trading full time for 5 years now (after quitting my data science role at 25) and in that time I have developed a profitable stock market analytical program. The algorithms continuously scans 4750+ charts to search for real-time mathematical indicators to flag trades are worth executing. I manually trade these for 50 days inside my ISA and so far so good.
But I can’t help feel that I may be missing out on some major moves due to news…
So, I have been waking up early to read the news when it get released to try and work out if there’s any way to profit from it inner-day/week. So far, I haven’t pulled the trigger on any related news events that do not match my algo but getting tempted every day.
At the moment, I feel uncomfortable submitting an order before the market opens as I want to know the exact price I’m buying in for. Is this just me? Or are people comfortable with this? Is it first come first served? Is a submitted order at 7:05 am better than a submitted order at 8:10am?
I am also toying with the idea of scripting a RNS reader that reads/scan everything published at 7 am, summarises it, and then formats it into something which I published. It would be a kinda big job and without any income from it, I’m hesitant going down that rabbit's hole.
Cheers
Dan
Hi HollandSmith, curious to know what software you use for this? Congrats on the move to full time trading btw, I hope to join you one of these days.
It is completely built from the ground up as I couldn’t find anything on the internet which solved my idea I scribbled on the back of a stamp. It uses web scrap for historical stock prices, javascript for algos and displays it in a spreadsheet for functionality. I don’t think it’s impressive to look at, but it delivers the implementation of making a ranked screener that indexes custom oscillators and grading momentum whilst monitoring exhaustion of price.
Everything in my liquid portfolio has been purchased in this way, so it is possible to rank the portfolio, sell the bottom one, and buy the top of the new list.
This sounds impressive and to do this at this age takes courage. Is this purely focused on the UK market as from my limited duration 'playing' with CANSLIM and minervini's VCP i think momentum and volume\ price exhaustion instances are more commonplace across the pond.. i'm looking at something similar using pandas but early days : (
Wow, that's really impressive. Well done. You should release it on a subscription basis like Stocko!!! Think of all that passive income!!
Oh, I would love to! But I'm a nobody! Kinda need to pass the magic 7 digits in an ISA to get some credibility first I reckon.
With your software skills that 7 digits is possible, software was the key to success for this guy:
;t=5sHi Dan,
Personally, I prefer to know the exact price. I've occasionally been caught out with wide spreads and unexpected fluctuations at the open. A limit order is one approach, but then you may still be caught out by unexpected price movements.
Congratulations on your move to full-time trading! And thank you for the morning summaries, much appreciated.
Morning HollandSmith,
Your question about what time to submit an order in the morning is also something I've been wondering . I prefer to know the price but I'm also not sure of the best way to approach market open. Sometimes I feel like I'm missing out if I wait past 8am.
From my observations (not scientific at all), the 8am opening price appears to see an extreme swing up or down (depending on the type of news) but then it goes back towards the opening price after some minutes. Then who knows from there :).
Do others on this forum have similar or different observations? Is anyone aware of any research or data where a buy/sell approach at market open is suggested?
Cheers
Regarding when your order will get filled, I expect it is first come first served for orders at the same execution price. So if you have a resting order submitted at 7:05am, you should get served before the resting order placed at 8:10am. A different price has it's own first come first served line up. There may be nuances to that depending on your broker (they may have premium customers that can jump the queue, or they tie-break on ordered amount etc). You are also competing for the same liquidity in a share with other brokers (HL, ii, fidelity etc are all trying to get your order to the LSE ahead of the others).
One thing to keep in mind is that spreads can be massively wide in the first few minutes, and things can gap randomly and unexpectedly until brokers get a good view of the book (10am-11am). So it can be risky buying first thing in the morning as you can over-pay on the spread.
If you haven't already, I would really recommend getting a realtime level2 data feed to see all this for yourself first hand.
Hope this helps, and good luck with it!
This is seriously impressive and way beyond anything I do or could do. Could you tell me what degree you did? Just some guidance for my 14 year old!
BTW if you haven’t read it yet you might enjoy the book Free Capital (as an aside Paul was short listed for this but did not make the cut, god knows why!) https://www.amazon.co.uk/Free-Capital-private-investors-millions-ebook/dp/B004TLNNL4/ref=tmm_kin_swatch_0?_encoding=UTF8&qid=1595927597&sr=8-1
One of the traders portrayed uses news flow on his Bloomberg terminal to trade and, according the book, is very successful. Writing this makes me want to read it again.
Kind regards
Michael
PS are you on Twitter?
The stars didn’t aline for me after going to Leeds building college for carpentry. Got a simple job and somehow climbed a short ladder to design data products for credit referencing and marketing agencies.
I'll let you know when I set up a new twitter account :)
Nothing wrong with being a Joiner/Carpenter and working you way up, as I well know.
Michael Taylor explains in his free ebooks when you sign up at his website shiftingshares.com , how level 2 works and he also mentions that he buys before market open through Direct Market Access (DMA) at a specific price.
Hi @HollandSmith - as others have commented, a very impressive place to be after just 5 years and I’m sure 7 figures is just around the corner for you! I don’t suppose you have Any links to hand regarding trading through an ISA - that is certainly my next enhancement to this investing lark! Many thanks, Chris
what does your annualized return look like.
You should do a course with Robbie burns nakedtrader.co.uk and read his book too
John 652 well said. 2 great reads before market opens in the morning. Ive been following Mr C for a long time and Hollandsmith has added to the quality. Brilliant .... long may it continue and thanks to them both
Hi, FTSE 100 +0.18% before open
In the year to 30 June 2020, order intake was over £365m, compared to £386m in the prior year.
like-for-like sales since reopening down 21.6%
Pre-tax loss £65.2m (H1 2019: £36.7m profit)
Six months ended 30 June 2020 - £61.9million
conditional agreement to sell its interests in its molasses trading businesses
Online sales grew by 9%
I also really like your updates, same as MrC's early morning snapshots, these help guide me as to which stocks to prioritise for my deeper dives! So keep 'em coming please, if you wish to!
ELM half year results today. Was up nearly 10% yesterday. Should be an interesting open...
Good morning Paul, I'd appreciate your thoughts on M&C Saatchi. Banking covenants relaxed which is good news. Also they report a small profit before 'exceptional costs', which seems to me like not a profit after all.
Hi Paul Could you maybe add something into one of your SCVR's over the next few days / weeks about your portfolio management. It's very interesting picking up snippets of you waiting for funds to add to a position or that you've just sold out and regretted it. What % you leave in cash
I'm pretty hopeless at managing my own portfolio, so not sure there's anything of value I could add! My main interest is doing the analysis, then there's usually enough in my portfolio to make me financially comfortable which is all I want really.