Small Cap Value Report (Tue 29 Oct 2024) - RWS, CCR, YOU

Good morning from Paul & Graham!
All done for today.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
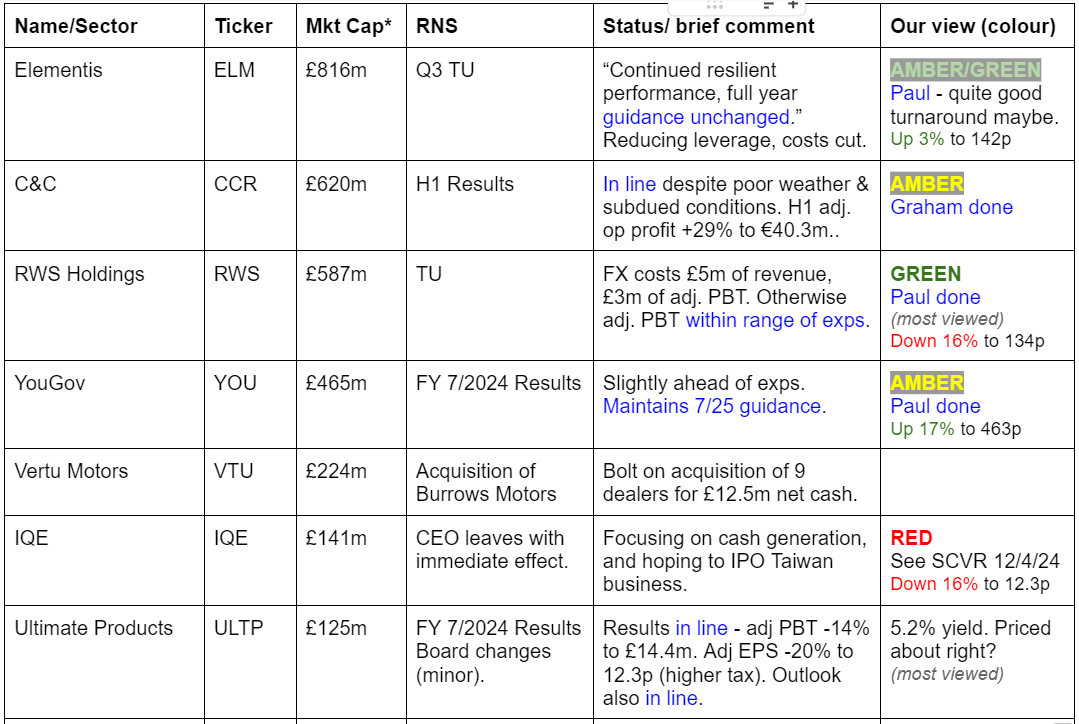
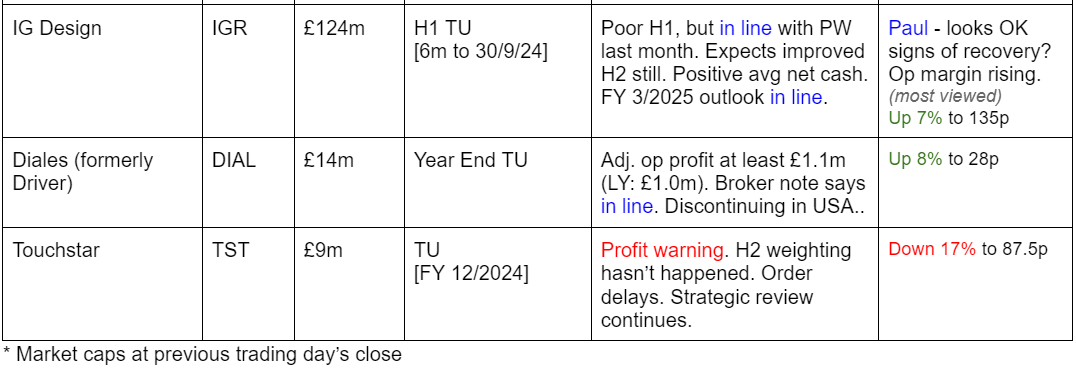
Summaries
RWS Holdings (LON:RWS) - down 16% to 134p (£493m) - Trading Update - Paul - GREEN
More-or-less in line TU for FY 9/2024, if we ignore some forex headwinds. Surprisingly large share price drop today, for what I thought was an OK update. Although broker consensus for FY 92/2025 looks too high relative to the cautious outlook comments. Is this business now structurally challenged by AI possibly (it mentions continuing pricing pressure)? It's difficult to know. OK balance sheet with negligible net debt, and a c.9% dividend yield look very appealing.
C&C (LON:CCR) - down 3.1% to 156.6p (£600m / €721m) - Interim Results - Graham - AMBER
Results are in line with expectations as the company targets €100m of underlying operating profit in FY 2027. If the results were a little cleaner I'd be more interested, but for now I'm neutral.
YouGov (LON:YOU) - Up 13% to 448p (£523m) - FY 7/2024 Results - Paul - AMBER
Weak numbers, as expected, but turnaround actions underway should improve performance in FY 7/2025, and expectations are confirmed. I quite liked it until I looked at the weak balance sheet & poor cashflows, so I do have some reservations. Being AIM, watch out for volatility in the budget tomorrow.
Paul’s Section:
Possible Rebound Watchlist?
Given turmoil in small caps, especially AIM (due to budget worries), I think it’s time for us to all swap some watchlist ideas of potential bargains again. We did this before on market jitters earlier this year, and it threw up some good ideas that did bounce (albeit getting whacked again more recently in many cases).
As mentioned in my weekend podcast, it’s important to keep our nerves in turbulent markets, and if people are panic or tax selling good companies at low prices, their decisions could selectively be providing us with buying opportunities. After all, BLASH (buy low and sell high) is a fairly reliable way to make money in any commercial enterprise, including running a shares portfolio.
It’s been a strange market of late, with obvious and significant disruption from fears about tomorrow’s Budget tax raid. Given that it’s customary for details to be widely leaked to the press (perhaps to test the water, or just because too many people know the details and the press worms the information out of them?!) we seem to have fairly clear details of what’s likely to happen - here are my guesses (based on press coverage mainly) -
Capital Gains Tax - probably going up, but maybe not by a disastrous amount (evidence Starmer’s “wide of the mark” comment)
ISAs - probably some new restrictions, because they were designed for ordinary people to save and build up a tax-free pot, but not for people to become multimillionaires and avoid tax on substantial portfolios - so the argument might go from the Chancellor, I suspect.
Pensions - I imagine tighter restrictions might be introduced on the very generous higher rate tax relief on money going in. Maybe reducing the rate of tax relief, or lowering the annual maximum people can put in? Annoying for high earners, but probably not likely to impact share prices. The abolition of the lifetime limit seems secure, as Reeves has publicly U-turned on her initial reaction to bring it back in. Why should SIPPs be exempt from IHT? That looks an easy target, along with other IHT changes.
EDIT: I forgot to mention speculation over the £250k maximum tax-free lump sum from pensions being reviewed. We've discussed this recently here, in that there's lots of anecdotal evidence that some investors are selling shares (AIM and fully listed) to raise cash to grab their 25% tax-free lump sum ahead of the budget. End of edit.
Employers NICs - seems to be the big one, with a 1-2% increase mooted, and lowering the thresholds - raising up to £20bn. If so, this would be a disaster for the hospitality and retail sectors in particular, combined with another large mooted increase in minimum wage, and potentially losing business rates relief measures. Hence I think these sectors are a complete avoid at the moment - and note that broker forecasts have not been lowered yet for any tax hikes. How will companies react? They’ll have to reduce staff numbers and hours somehow without damaging their customer service too much. They’ll have to raise prices to mitigate the extra costs, if they can. EDIT: it's also likely to mean employers will resist further demands for pay rises from employees. End of edit. Plus some weaker businesses are likely to go bust sadly. I think we’ll see widespread broker forecast reductions (not yet factored in) across almost all sectors due to this possible tax rise.
AIM IHT relief - if this is abolished, then I think we’ll have a period of absolute carnage on AIM. Some companies would be likely to move to the main market, to attract new investors that don’t look at AIM, so those could be OK. Meanwhile IHT portfolio providers would probably see lots of redemptions, spread over quite a while, leading to probable market price dislocation as share prices drop to entice new owners of those redundant shares. If it’s not abolished, then I think we could see a powerful and quick rally, as buyers dive in for the bargains. Hence why I think having a watchlist & some ready cash to deploy now is a really good idea.
My AIM share ideas - as always, these are just some ideas for you to properly research. Last night I just sorted AIM by recent % falls, and manually picked out the companies I think are potentially interesting, based on our SCVR coverage. Here they are - I think a lot of these have seen budget/tax related, fear-driven selling recently, not connected that much (if at all) to company fundamentals. Or things that have disappointed on fundamentals, then overshot on the downside possibly - in no particular order -
Kooth (LON:KOO) - high risk, speculative (I’m not brave enough personally, but it’s tempting!)
Beeks Financial Cloud (LON:BKS) (I hold) - excellent recent newsflow, with several more large contracts said to be close to signing. Also NASDAQ contract set to launch.
Intercede (LON:IGP) (I hold) - likely to beat exps in H2. Good newsflow of contract wins. Doing a small buyback to mop up loose sellers.
Alumasc (LON:ALU) - strong recent update, and modestly priced still. Recent sell-off doesn’t make sense on the fundamentals.
Advanced Medical Solutions (LON:AMS) - no detail, just an interesting company that has fallen recently.
Johnson Service (LON:JSG) - I was surprised how much it has fallen recently.
James Halstead (LON:JHD) - quality company, cyclical recovery likely, price is now reasonable. Widely held by IHT funds.
Warpaint London (LON:W7L) - one of our favourites here, taken a whack recently. Although mgt did sell some of their still large holdings earlier this year.
Tracsis (LON:TRCS) - tends to look expensive usually, but has fallen a lot lately - buying opp possibly? Or is it just coming back down to a more realistic valuation?
Focusrite (LON:TUNE) - has under-performed, but possibly getting near the bottom? Forecast profits have fallen a lot though.
Tribal (LON:TRB) - horrible share, but a bidder was rebuffed at almost double the price it is now.
Gaming Realms (LON:GMR) - I can’t see any reason for its recent sell-off. Although not sure if hikes in gambling duties would impact it or not.
CVS (LON:CVSG) - has all the problems of CMA investigation, but recent share price fall has brought fwd PER down to only 9.5x
YouGov (LON:YOU) - could bounce, maybe profit warning fall overdone, and it’s cost-cutting to drive partial profit recovery. Too much debt though. EDIT: Just spotted that its FY 7/2024 results were issued today, so I'll review those later today (up 14% in early trades)
Gattaca (LON:GATC) (I hold) - only valued at £5m more than its own cash pile, and performing surprisingly well in very tough markets.
SDI (LON:SDI) - down to only 50p. Getting into punting price range maybe?
Tristel (LON:TSTL) - very nice company performing well, but shares are expensive. Recent dip might be an opportunity maybe, who knows?
Somero Enterprises (LON:SOM) - another old favourite, shares very beaten up now, worth a fresh look. Cash machine.
Character (LON:CCT) - recent update seemed OK, but share price battered.
Oxford Metrics (LON:OMG) - disappointed recently, but valuation now looks attractive I think.
Fevertree Drinks (LON:FEVR) - still looks expensive, but shares have dropped a lot, could be worth checking out maybe?
Next 15 (LON:NFG) - another disappointer with a PW, but I wonder if it could bounce?
Let's have your watchlist ideas for AIM possible bargains (if the Chancellor doesn't impose punitive measures of course).
RWS Holdings (LON:RWS)
Down 16% to 134p (£493m) - Trading Update - Paul - GREEN
RWS Holdings plc ("RWS" or "the Group"), a unique world-leading provider of technology-enabled language, content and intellectual property services, today provides an update on trading for the year ended 30 September 2024 ("FY24") ahead of the announcement of its full year results on 12 December 2024.
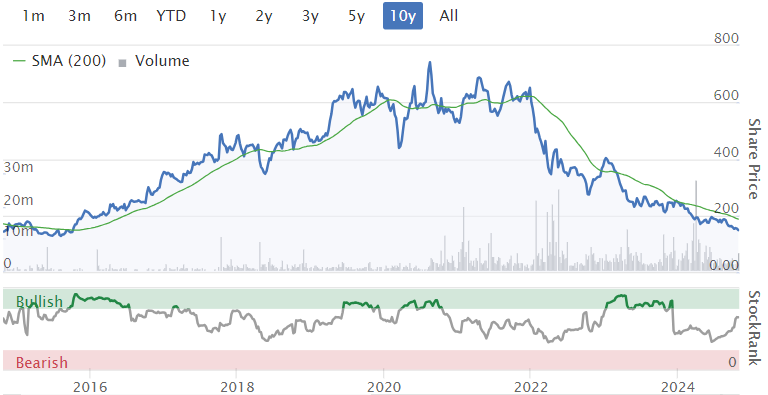
I’ve not looked at RWS since 24/4/2024, at 162p, when I thought the value metrics looked cheap but the vague outlook comments made me wonder if it was limbering up for another profit warning. Also concerns over whether AI is a help or a hindrance? It did bounce about 20% after that, but has more recently fallen down to a new multi-year low - with shares back down to 2015 prices (and there are more in issue, following a fundraise in 2021). Ten year roundtrip for this share -
Today’s update is for FY 9/2024.
“A return to growth in the second half, driven by encouraging performance in AI-led solutions”
H2 constant currency revenue up 2%, vs -2% in H1.
Full year revenues in line with last year. That also seems to be in line with market expectations, checking on the StockReport.
Adverse forex means FY reported revenues will be down 2% vs LY.
Profit guidance -
“The Group expects to deliver adjusted PBT within the range of market expectations² before adjusting for these currency movements.³
³ Reflecting exchange rate movements, primarily during the last two months of FY24, the currency headwind impact on market consensus is estimated to be c.£5m on reported revenue and c.£3m on adjusted PBT.”
Debt isn’t a problem - they exclude leases, which is fine by me -
“The Group had modest net debt⁴ of c.£14m at the end of September 2024 (31 March 2024: £39m net debt), supported by an improvement in receivables since the mid-year.”
Outlook - I don’t like the ongoing pricing pressure comment - so this sounds like no overall profit growth is likely in FY 9/2025 -
“For FY25 we expect to deliver modest organic revenue growth at constant currency, with growth in volumes offsetting ongoing price pressure. We expect foreign exchange to continue to be a headwind to reported revenue and adjusted PBT. “
"Our range of AI-centred solutions are gaining encouraging traction, with TrainAI and Language Weaver in particular seeing strong growth. These solutions, combined with our investment in sales effectiveness and our continued focus on efficiency, enabled by our unique LXD platform, mean we are well placed to emerge from the current market transition in a position of strength."
That’s way too vague for me to understand whether AI is a threat or an opportunity. Some of these language models are now so good, that I can’t help feeling it must mean cheaper, automated competition could be mainly a threat. That’s purely my hunch, not anything near an expert opinion.
Valuation - helpfully, RWS publishes broker consensus on its website, wouldn’t it make life easier if all companies did this?
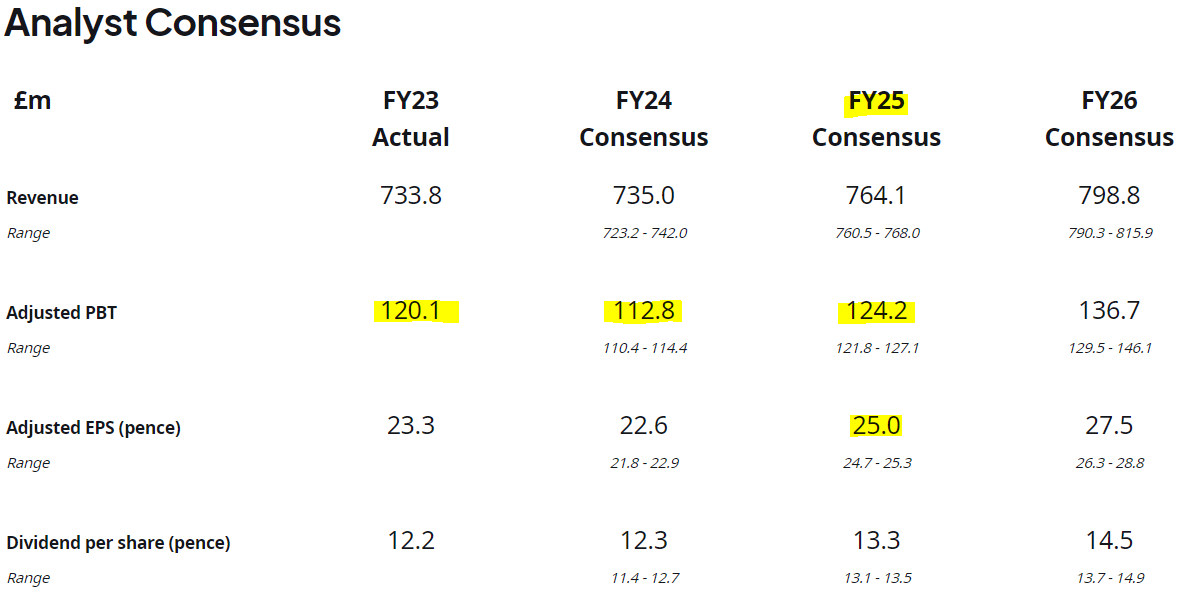
Unfortunately, I can’t tie in the cautious outlook above with the rise in adj PBT forecast. So it looks to me as if broker consensus forecasts for 2025 at least need to come down, c.10% maybe? I think it’s now looking as if RWS has gone ex profit growth. Maybe c.23p adj EPS is the new normal, or may even be in a falling trend to say 20p in FY 9/2025? It’s not looking like a growth company any more, anyway. Hence the PER should be low. It’s already massively de-rated though, as you can see from graph 4 below - also note the divis becoming the main event now! -
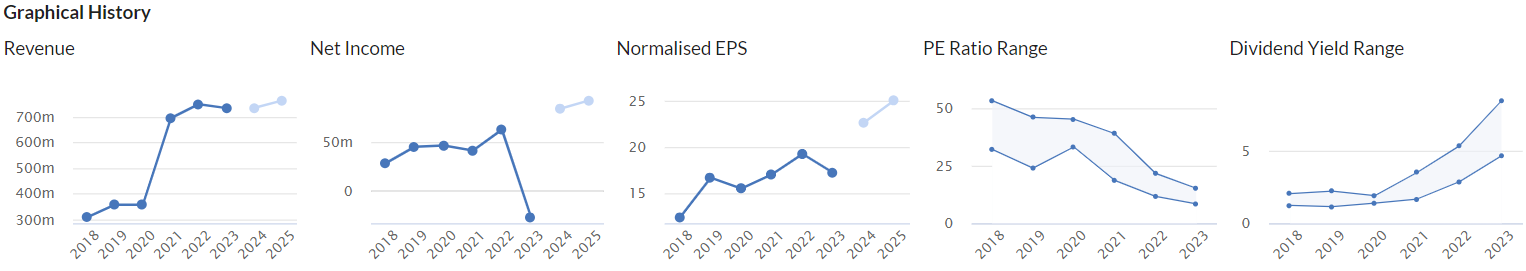
I suspect that graph 3 might deteriorate somewhat as likely broker downgrades feed through, so I’ll treat 20p EPS as my estimate.
Shares are only 134p today, so the PER is only 6.7x even on my cautious 20p estimate. It’s even lower than that on market consensus.
Bear in mind there’s no debt to speak of, and this is a high margin business - very unusual to see a value share price on what seems a quality business.
Note that it has done a lot of acquisitions previously, so there’s a gulf between adjusted and reported profit.
Balance sheet - checking back, the last one at 3/2024 showed huge intangible assets, so taking them off results in £(30)m NTAV. However, I could also deduct deferred tax liabilities, which takes it positive to NTAV of £23m. Bear in mind it has only small tangible fixed assets, and no inventories, and that is more than adequate overall. So it’s a fairly decent balance sheet.
Dividends - I’ve only just noticed Stockopedia has a forecast yield of 8.4%, which will be nearer 9% after today’s share price fall. That’s getting into territory where the market thinks it’s not sustainable. Yet it’s nearly twice covered by forecast earnings, and with a sound balance sheet, who knows that might be a sustainable yield?
Paul’s opinion - I think more broker forecast downgrades are likely, and the hike in employers NICs is likely to be a nasty extra cost. So let’s work on 20p EPS rather than consensus of 25p for FY 9/2025. That gives me a PER of only 6.7x, and a yield of over 9% - with a sound balance sheet, and negligible debt.
This seems to me a very conservative valuation, but I said that last time and it’s carried on going down!
Who knows what the future holds, but based on the facts & figures today, RWS shares look appealing value. So it has to be GREEN, and I’ll accept the risk that another profit warning could leave me with egg on my face! Ideally the company should be quietly urging brokers to soften their 2025 forecasts, since even I can see they’re unlikely to be met. Rather than leaving optimistic forecasts out there, then dropping another profit warning. After all, profit warnings are not necessarily a sign of poor performance, they’re more a failure to give realistic guidance.
To get the PER up from mid single digits, I think RWS management needs to convincingly demonstrate that AI is a benefit, not a threat. If they can’t do this, then a low PER is likely to continue. Mention of ongoing pricing pressure is not good, and suggests to me that there could be a structural problem at RWS from cheaper, AI-driven competition. Do any readers have specific knowledge of this sector?
YouGov (LON:YOU)
Up 13% to 448p (£523m) - FY 7/2024 Results - Paul - AMBER
A turbulent year for this specialist market research & data analytics group -
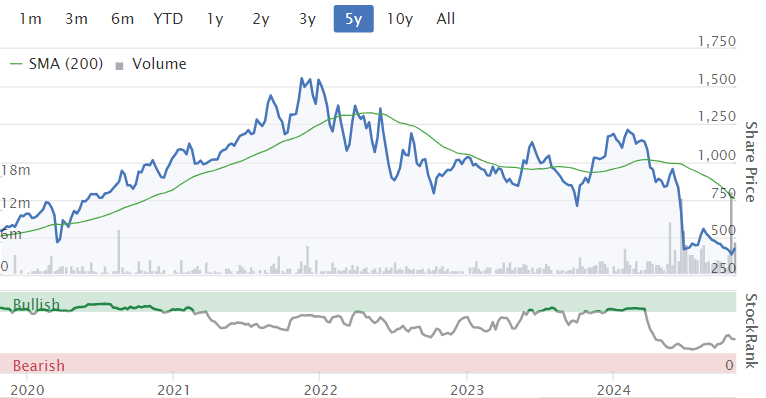
We picked up the story here on 20/6/2024 when YOU shares plunged 39% to 501p on a profit warning. I had to mark it AMBER/RED on the day, since I couldn’t find any revised broker forecasts, and the company’s update was too vague. Plus it had clearly taken on too much debt to fund a large acquisition.
On 6/8/2024 it issued a more reassuring update, indicating cost-cutting had been done, and that trading had slightly improved, and it had headroom on the banking covenants. So my concerns were eased, hence moving up to AMBER at 535p to reflect the improved situation (remember we’re only reporting on the facts/figures/forecasts on one particular day, we’re not trying to predict the future usually).
Today’s full results for FY 7/2024 reassure again with these headlines -
“- Revenue and operating profit slightly ahead of revised guidance
- Execution of cost optimisation plan is on track
- Maintaining FY25 guidance and mid-term ambitions”
Note that YOU shares are AIM listed, so that might help explain the almost constant drift down in Aug-Oct 2024. Coincidentally, I mentioned this share this morning in my list of AIM shares that might be oversold due to budget worries, before I’d realised it had published results today. The StockReport as of last night shows it on a forward PER of 11.0x, on broker forecasts that have stabilised after the lurch down after June’s profit warning. Hence why I thought it was starting to look interesting as a potential recovery trade.
Audit - YOU has gone ahead and published its FY 7/2024, despite the audit not having yet been completed. It says the audit should be completed soon, and don’t expect any material changes.
Highlights table below shows that it’s complicated with a large acquisition blowing the large cash pile and replacing it with substantial net debt, which I really don’t like at all.
Also note that large adjustments create nearly all the adjusted PBT -
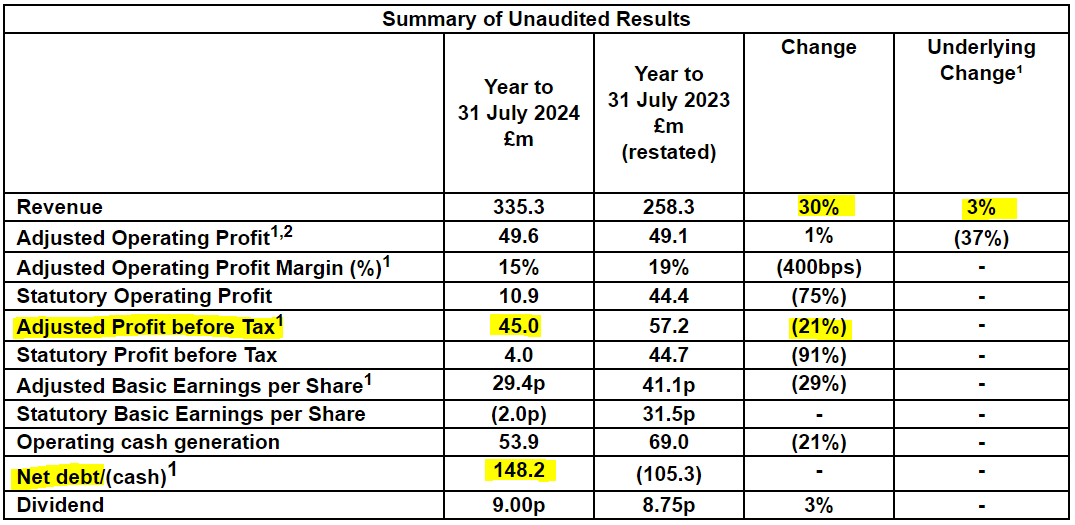
If you accept the adjustments, then despite a 21% drop in adj PBT, it’s still quite a high margin business, not a basket case.
Adjustments are -
“largely due to exceptional costs of £38.7m in relation to the acquisition of CPS, the change in accounting treatment of amortisation costs of acquired customer relationship intangible assets and restructuring charges.”
This table below shows how the poor performance of the two existing divisions dissipated all the profit made by the CPS acquisition.
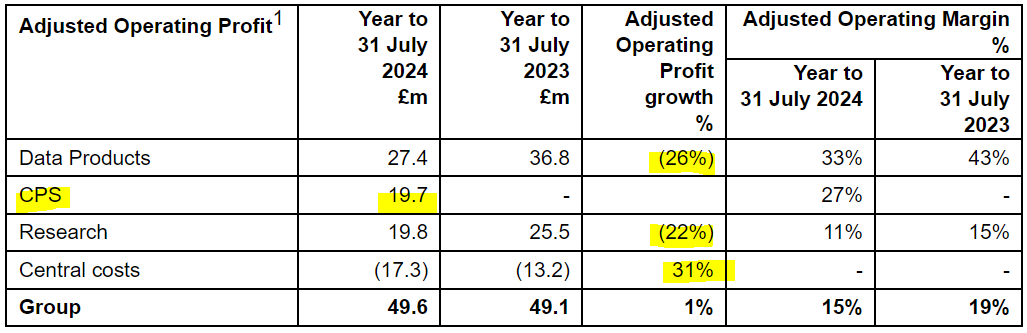
There’s since been hefty cost-cutting, as announced before, since it went into a downturn in customer demand with excessive staffing for a planned increase in demand. There’s a new CEO in charge.
Acquisition - actually it was a huge deal, buying CPS for 315m Euros in Jan 2024. Let’s hope they haven’t screwed up. This bit today reassures -
“The CPS business is continuing to perform well, in line with expectations and the integration is progressing well.”
Another acquisition of Yabble, was done post July year end, but is not material at only £4.5m initial cash consideration.
Cost-cutting of £20m annualised has mostly seen “initial action taken”, with most benefit kicking in H2 of FY 7/2025. £20m is a material number compared with the £45m adj PBT reported above. Assuming no detrimental impact from presumably getting rid of staff mostly, then this suggests a useful increase in profit should be possible in future.
Outlook - key points for FY 7/2025 -
“Our clients continue to value the quality of our products and services, this is reflected by our high renewal rates and strong customer relationships. As we enter FY25, we anticipate that momentum will build throughout the year, weighted towards the second half, as the benefits of our cost optimisation plan and new commercial leadership are realised. We consequently expect YouGov to achieve growth for FY25 in line with current market expectations, and remain confident in the Group's ability to deliver on its long-term ambitions."
I can live with an H2 weighting, as there’s a clear reason for it - as cost-saving measures gradually feed through.
Balance sheet - the usual delusional reporting of this, see my comments below on what the balance sheet is actually like! -
“We maintain a disciplined approach to cash management, and as of 31 July 2024, the Group has a robust balance sheet, with approximately £74 million in cash and cash equivalents and €16 million of the revolving credit facility remains undrawn.”
But at least it seems to have enough liquidity there (assuming bank covenants are met).
Results presentation - there’s a video and slide deck available on its website here - very helpful.
Balance sheet - NAV is £183m, but intangible assets have ballooned in FY 7/2024, with goodwill up from £82m to £244m, and other intangibles up from £36m to £184m. This gives NTAV of negative £(245)m! IF we’re kind and eliminate deferred tax of £(32)m, then this improves a bit to a still-awful £(213)m NTAV. For YOU to claim it has a strong balance sheet is just ridiculous.
However, since it has almost nothing in physical fixed assets, and zero inventories, it’s an asset-light business model, which doesn’t need balance sheet strength. I’ve mentioned this before I think - management should not be telling us their obviously weak balance sheet is strong. Instead they should be saying that their business model is asset-light, hence they can operate fine with a negative balance sheet net tangible asset position.
Something else to bear in mind is that the bank borrowings are mostly a £202m term loan, spread over 4 years (see note 13). That means hefty loan repayments fall due each October. Hence YOU needs to generate a lot of free cashflow to meet these bank loan repayments. So don’t expect generous divis, with the forecast yield only about 2%. Note 14 says that it hedged interest rates on the variable rate borrowings.
Cashflow statement - given the hefty loan repayments due over the next 4 years, cash generation is key.
My interpretation of the FY 7/2024 cashflow statement is that it’s not good. Operating cashflow after tax & interest paid was £37.7m. But it spent nearly half of that (£17.3m) on capitalised “purchase of intangible assets”, which I think is costs related to recruiting for its consumer panels. Take off lease payments of £3.9m, and divis of £10.1m, and treasury shares purchased of £1.9m, and I make that only £4.5m cash generated remaining. That’s nowhere near enough to make the c.£50m pa loan repayments that will now be necessary. In fact it seems obvious to me that the divis will need to be scrapped, because they are unaffordable.
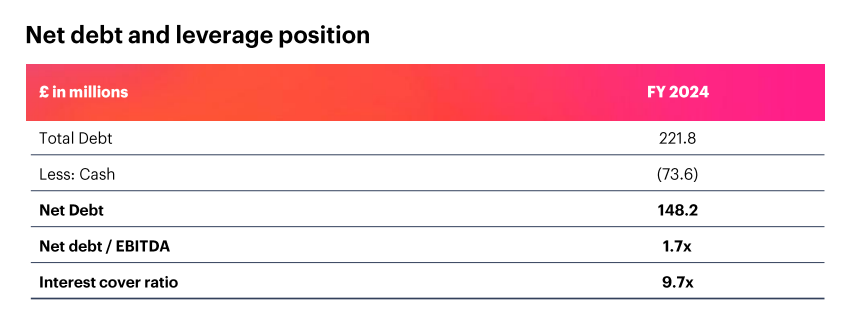
That said the net debt position is not so bad, given that it also has £73.6m in cash - see slide 9 -
Paul’s opinion - the market likes these numbers & commentary, with it up 17% now to 466p at the time of writing (15:24).
However my deeper delve into the numbers has put me off, because YOU actually has a fragile and over-geared balance sheet, and is a poor cash generator.
That said, it had a bad year, and performance should improve in FY 7/2025 due to the cost-cutting.
Plenty of investors don’t even look at the balance sheet or cashflows, so my concerns may not matter to Mr Market, but I’m just flagging the full facts to you. Given that it capitalises a fair bit into intangibles, and now has hefty debt, then the EBITDA numbers are particularly unreliable in my view.
Growth has come from a large acquisition, and is not organic. So should we be valuing this as a growth company? Probably not.
After today’s 17% rise, I wonder if this is the start of a recovery in YOU shares? It could be maybe, as performance seems to be stabilising.
However, my view is that this isn’t as good quality a business as people seem to think it is. A very weak, overly indebted balance sheet, used to fund acquisitions, and poor cashflows, mean it’s not something I would want to own as anything more than a short-term trade.
I can’t get above AMBER.
Graham's Section:
C&C (LON:CCR)
Down 3.1% to 156.6p (£600m / €721m) - Interim Results - Graham - AMBER
This drinks company reports results that are in line with expectations “despite poor summer weather and subdued market conditions”.
Comparisons with H1 last year are complicated by some accounting errors that depressed last year’s H1 profits. Last year’s H1 results needed to be restated (i.e. corrected).
Instead of comparing H1 this year against the corrected numbers for last year, however, CCR leads with the growth rates against the originally published, incorrect figures.
Let’s focus on the correct growth rates:
Net revenue decline 2% at constant currencies
Underlying operating profit +4% at constant currencies to €40.3m
Leverage multiple is 1.1x which is down from 1.5x a year ago. Over the past 12 months, there has been a €26m reduction in net debt (excluding leases) to €81m. This should be a safe level of debt.
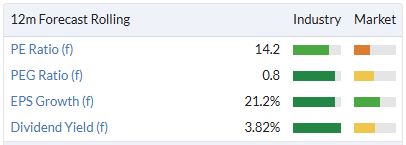
Dividend gets a 6% increase. The forecast yield is 3.8% according to Stockopedia.
Outlook: should make €80m of (underlying) operating profit in FY Feb 2025 and the target is for €100m in FY Feb 2027.
CEO comment:
"I am pleased to report earnings in-line with expectations in HY2025 as we rebuild performance and momentum within the business. Despite unfavourable summer weather, our brands demonstrated inherent appeal and resilience with both Tennent's and Bulmers growing market share and Menabrea and Orchard Pig achieving double digit revenue growth.
Tennent’s increased market share by 5 percentage points in the summer period, despite its volumes declining 7%. In addition to the weather, the company notes that “the 200,000 Scottish fans who travelled to Germany will also have had a temporary impact on the market”.
Magners/Bulmers cider did poorly, again due to the weather. Volumes down around 10%.
Distribution: the distributors Matthew Clark and Bibendum were picked up back when Conviviality plc went into administration in 2018. Management seems very pleased with recent growth in customer numbers but this hasn’t translated into revenue growth yet. This business operates on the tightest of margins and cost efficiencies are expected to boost profits in H2.
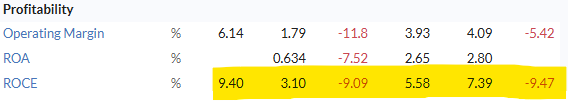
Balance sheet: about €50m in tangible equity, and a huge chunk of PPE (€265m). It has struggled to generate a strong return on all of this capital: see below for the ROCE numbers since 2019. Admittedly there are some Covid years included in this series.
Adjustments: CCR has counted over €12m of costs as exceptional in H1, i.e. they are excluded from the underlying profit of €40m.
€7.6m of “strategic restructuring programmes” following the closure of distribution centres and a depot, and redundancy costs.
€4m for “risk management and control reviews” after the accounting errors.
This may be a little harsh but I wouldn’t be inclined to allow the exclusion of all of these costs. There were €5m of exceptional costs in H1 of the previous financial year. FY 23 saw a €12m exception cost for “onerous apple contracts”. I would be delighted and surprised to see CCR get through a period without suffering any big “exceptionals”.
Graham’s view
I’ve been a fan of this business in the past and went GREEN on it in May 2023 at a share price of 134p.
Paul has been less impressed and was neutral on it in September and in June this year.
Two year chart:
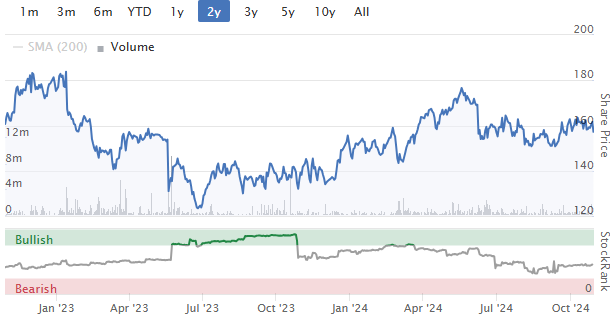
At a PER of 14x, I think I can accept a neutral rating on it, although I’m tempted by AMBER/GREEN.
However, the results have been messy, returns are mediocre, and growth is limited. Maybe things will look different next summer with better weather, but I can accept an AMBER on this for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

138 comments
Ultimate Products (LON:ULTP) - Investor Presentation video recording (FY Results)
Andrew Gossage (CEO) & Chris Dent (CFO) of Ultimate Products plc hosted an Investor Presentation following the release of their results for the financial year to 31st July 2024. They discussed their ambitions for European growth enhanced by their Paris showroom, countered by the the abating challenges of freight costs and UK consumer demand. Management provided a detailed run-though of financial performance figures, and answered a range of questions submitted by viewers.
David Bowie
“And in the death
As the last few corpses lay rotting on the slimy thoroughfare
The shutters lifted an inch in temperance building, high on Poacher's Hill
And red mutant eyes gazed down on Hunger City
No more big wheels
Fleas the size of rats sucked on rats the size of cats
And ten thousand peoploids split into small tribes
Coveting the highest of the sterile skyscrapers
Like packs of dogs assaulting the glass fronts of Love-Me Avenue
Ripping and re-wrapping mink and shiny silver fox, now legwarmers
Family badge of sapphire and cracked emerald
Any day now, the year of the Diamond Dogs
"This ain't rock and roll! This is genocide!" “
Jim Morrison
“This is the end
Beautiful friend
The end”
Just setting the scene for tomorrow.
OK that’s what the media seems to think in the words of David and Jim – lets see what actually happens.
Think most of us will be looking for opportunities.
GLA
Good luck getting through to your brokers. Might me a tad difficult.
I wear rose-tinted specs!
LoL
EricUKInvestor on X, did a Mapping of 27 IHT funds and their holdings. He found that the following companies were highest risk of being impacted: Renew Holdings, Gamma Comms, Jet2, Next15, Johnson Services, Tracsis, Ashtead Tech, Craneware, Judges Sci, Advanced Medical, IG Design, James Halstead, GlobalData, Cohort, CVS, Volex, Cerillion, GB Group and Restore
Thanks EdwardJW,
That's a really good reminder that the IHT funds have generally concentrated in higher quality, and medium to large AIM shares. I think they chased them up to higher valuations during the good years, with fund inflows.
Therefore, if AIM IHT relief is removed or curtailed, it may not have that much lasting effect on other AIM shares, especially some of the more speculative stuff that the IHT portfolio guys wouldn't go near - they're generally very conservative actually. Hence why this idea that the IHT break is crucial for growing companies to raise capital isn't true, in my opinion.
All will be revealed tomorrow! I'll be publishing my immediate review of it in tomorrow's SCVR as soon as the Chancellor has sat down.
Regards, Paul.
Lot of conversation on Retail and Hospitality but I think people have only really considered the headline direct impacts and not the overall financial effect which I suspect will be more diluted than the headlines thrown around.
I took a look at Card Factory (LON:CARD) the other day. Their employee cost base is circa 1/3rd of revenues. 2% ERs NI would give them a £2.8m headwind but remember this is an expense so after corporation tax it’s about £2m against EPS.
A 5% increase in min wage would obviously create an additional £5m.
All very negative but such a headwind can be offset by a 1.5% increase in prices.
So assuming you think retailers have a 2%+ pricing power (and I suspect they do) then they have a lever to significantly offset the impacts.
Companies will pull several levers if those changes come in
1) They will try and reduce FTE hours
2) They will limit pay rises to only employees on national minimum wage reducing the average
3) Increase prices to reflect
So if Card Factory (LON:CARD) add a couple of pence to their cards that should close the profitability bridge. Everyone else will be doing the same so it will likely have little competitive impact. Instead the effect will be felt on jobs in my view.
1. Reducing FTE hours is never easy, doing so will reduce customer service and hamper money going in till. Every time I mystery shop Card Factory the staff are working, not scrolling on phone like so many retailers.
2. Very unlikely, you give the lowest paid employee a pay rise, the next pay grade will say "I want an increase, or I may as well take a reduction in responsibility". I forget which CEO stated it, but one said you increase the minimum wages and you end up giving everybody in the company a rise.
3. If only increasing prices generates higher revenue, then they should constantly do it, sadly demand is not inelastic for greeting cards and gifts. Card Factory has tough competition, while it may be the largest player, it has no pricing power. Watch the last investor relations presentation, they have a pricing department which looks carefully at optimising the price of products.
Yes I’ve watched it Orval - the point is that if everybody is doing it then the demand elasticity equation changes in part because so many people have had a pay rise.
I’m using Card Factory (LON:CARD) as an example but it applies to many others. Increasing wages increases the cost of goods sold - that’s what happens economically, though clearly via a lag effect in most cases.
I disagree on pay - I’ve often increased lowest pay grades and not filtered that up the chain. Clearly you can’t tighten the boundaries too tight but for sure you can do it.
Anyway my point is that the headline impact needs to be considered in conjunction with the levers each individual company has in their locker to pull.
Hi David,
Good points, well made!
I agree that companies hit by the likely tax rises can pull levers, but the turmoil of the 5 years tends to show that it takes time to mitigate any external problems. The negative profit impact is immediate, whereas the mitigating actions taken only tend to lead to a gradual profit recovery, over say 1-2 years. We see this all the time from lots of sectors that have taken several years to recover from covid lockdowns.
The problem I see now, is that current broker forecasts say in hospitality & retail don't seem to have anticipated any of these big tax hikes, and the latest news of a 5% real terms increase in minimum wage (plus the domino effect of higher paid staff demanding the differentials are maintained).
Therefore I suspect we're likely to see a lot of big broker forecast reductions in the coming months, in many sectors. Plus profit warnings where companies haven't guided expectations down. Then maybe some recovery in 2025, but it seems to me the momentum on earnings forecasts is likely to be downwards over the next few months.
On a positive note, listening to the webinar from Gattaca (LON:GATC) (small, lowish quality staffing co - I hold) mgt said things have stabilised and "aren't getting any worse". Their view is that once the budget is out of the way, companies will be able to plan, and are more likely to make hiring decisions again. So I suspect this might be the low point for the staffing sector, hence have dipped my toe in with a tiny opening position in GATC.
Regards, Paul.
Hi Paul,
Yes - I think the key to how badly this impacts is how quickly it gets passed through to consumers. It is almost certainly going to get passed on - the only question is how long it takes. I’d guess those businesses who can do it with a 2% increase will almost immediately increase prices by that amount. It’s inflationary for sure and one of the reasons the 10Y is now over 4.3%.
Handing out large pay rises has never ended well but this Chancellor seems to be oblivious. It’s one helluva gamble. The thing that worries me most is that she doesn’t appear to think she’s taking a gamble……that tells me she has little clue about risk management.
Best
David
My two penny worth:
Warpaint London (LON:W7L)
Volex (LON:VLX)
MS International (LON:MSI)
Synectics (LON:SNX)
Fonix (LON:FNX)
Knights group (LON:KGH)
Not a bargain list.
J D Wetherspoon (LON:JDW)
I shorted in the morning, closed over lunch.
Not for the risk adverse, but if the rumors turn out to be true, would expect falls tomorrow in retail/ pubs/ cleaners that are on aim.
Once the fall is over, I would suggest J D Wetherspoon (LON:JDW) and Card Factory (LON:CARD) as the sort of companies that would benefit from a nice increase in min wage.
Hi Paul. Lots of food for thought in the SCVR today, I just hope that they have deliberately frightened us all, so the reality is perceived as being not quite as bad as expected. Personally I hold a lot of AIM shares and although I can see both the reasons for and against having IHT relief on AIM shares I hope that RR will want to avoid an adverse market reaction and being labelled as Liz Truss 2.0 - let's see. It also will go against all the talk of backing growth and investment into capital markets etc. I am fed up with all the speculation and just want to get through tomorrow unscathed and without a market meltdown. Here is my list of AIM shares I hold or are on the watchlist, which I will look to buy or top up.
Time Finance (LON:TIME)
Cavendish Financial (LON:CAV)
Intercede (LON:IGP)
Beeks Financial Cloud (LON:BKS)
Ashtead Technology Holdings (LON:AT.)
CML Microsystems (LON:CML)
Churchill China (LON:CHH)
Judges Scientific (LON:JDG)
FW Thorpe (LON:TFW)
GB (LON:GBG)
CVS (LON:CVSG)
Sanderson Design (LON:SDG)
Personal group (LON:PGH)
Gooch & Housego (LON:GHH)
Angling Direct (LON:ANG)
Michelmersh Brick Holdings (LON:MBH)
Van Elle Holdings (LON:VANL)
Lords Trading (LON:LORD)
Facilities by ADF (LON:ADF)
Anyone have thoughts on how best to focus on the best ideas or to filter the watchlist to vastly reduce the number of stocks on the watchlist - perhaps focus on high StockRank shares or those with the best value/recovery potential. Good luck tomorrow.
P.S I had a very bizarre dream last night where Paul Scott was giving an investment seminar in a very lush, tropical (dense jungle - looked more like Vietnam) Gozo. The actual investment seminar was in an old wooden cricket pavilion, with an international T20 match going on in the valley below. My phone broke and I realised I only had a one way flight, and therefore would have to relocate to this tropical Gozo.
I didn't even eat any cheese last night.
Not sure what to expect at all tomorrow, suppose nobody is. Is it an old school boxing day sale with genuine bargains of old or is it just a black Friday nonsense that we've all waited months for and in the end it's a damp squib.
I'd be happier with the latter tbh. just get things back on track market wise.
Anyone have thoughts on how best to focus on the best ideas
If you’re investing, rather than trading, pick the highest quality at the biggest discount. Once you are above a certain threshold of price appeal, then quality should guide you more than price. You have some good names on your list, but some I would avoid.
Regarding Paul's ideas list. I really only know Focusrite (LON:TUNE). It has seen a steady decline in share price since the last update in August, which has accelerated in the last week or 2.
For them, I think a lot depends on how their new product releases go, as they themselves indicated with their H2 weighting warning:
Oberheim - A new Synthesiser retailing at £1,499 has been very well received, at a price point of half previous Oberheim products. It's unlikely to cannibalize sales elsewhere in the group (i.e. Sequential). At the UK retailers, the delivered batches have been selling out quite rapidly so far.
ADAM - have launched for the first time a set of headphones designed for mixing (£140). A large number of home producers predominantly mix on headphones rather than monitors, so will be interesting to see how well these sell in a competitive field. Again, these are unlikely to cannibalize existing monitor sales.
Focusrite - Have finally launched the remaining Gen 4 Scarlett interfaces in the range. These are the higher price point products. Most Gen 3 products have finally disappeared from the retailers, apart from the very cheapest in the range. It's fair to say they bodged the rollout of the Gen 4 range from the start.
Novation - 6 new Mk4 keyboard controller products in their Launchkey range.
Not to mention with Black Friday round the corner, I would expect Sonnox to sell a boatload of licences (albeit at deeply discounted prices - music software companies traditionally offer 70-80% discounts for Black Friday).
Obviously it will be a while before there's any indication how well all these are selling...
Hospitality and Retail
Excluding Ramsdens Holdings (LON:RFX) which is in part a retailer I only hold (held) 2 shares in these industries
Card Factory (LON:CARD)
Bonkers cheap, if it can meet expectations which will be a challenge. Also given the number of retail outlets it is likely to be hard hit if as many expect, employers NI and the National Minimum Wage are increased in the budget. A difficult decision but I have sold for a modest loss this morning. Will buy back in if there an overreaction in the share price to tomorrow's announcements.
Young & Co's Brewery (LON:YNGN)
Another AiM share.
These are the non-voting shares and trade at a steep discount to the voting shares, both of which trade at a steeper discount to the NAV which is north of £12. Given announcements from the company's peer group and the AGM statement of 25 July (see extracts below), my view is that the company will report good interims later this month with the City Pub Group acquisition bedding in well and leverage starting to fall.
Youngs is a well a managed company positioned at the premium end of the market with very well maintained pubs, far from the once spit and sawdust boozers. albeit it is also a tad more expensive than many of its contemporaries.
I continue to hold but admit to having a soft spot for traditional British pubs. I also quite like the look of the deleveraging that is happening at Marston's (LON:MARS)
"I am pleased to report that strong trading momentum has continued into our new financial year, with revenue in the five weeks since our year end preliminary announcement, up 33.8% in total and up 10.6% on a like-for-like basis. For the first sixteen weeks of the new financial year revenue was up 26.0% in total and 3.4% on a like-for-like basis.
."We are enjoying a great summer of sport. Customers flocked to our pubs to watch England make us proud, only narrowly missing out at the final of the Euros, and Wimbledon which although wet, saw a number of our pubs breaking records. Our pubs are looking forward to welcoming customers for the Olympics, followed by the autumn Rugby internationals in November. I have no doubt the business will make further progress this year, as it continues to invest in the estate and realise the benefits of the acquisition of City Pub Group, supporting long-term shareholder returns".
Hi Paul,
My list would be -
Animalcare (LON:ANCR)
Beeks Financial Cloud (LON:BKS)
Gamma Communications (LON:GAMA)
Restore (LON:RST)
Team17 (LON:TM17)
Van Elle Holdings (LON:VANL)
Iqe (LON:IQE) . I notice that Mark Cubbit will become the Executive Chairman. Presumably until they appoint a new CEO. Sounds like a brave move.
He is also non-executive chair at Beeks Financial Cloud (LON:BKS) and Concurrent Technologies (LON:CNC) both of which I hold. It will be interesting to see how he juggles these roles whilst taking on an executive role in another plc business which sounds to be in a bit of a mess.
Personally I’m always a little nervous of portfolio non-execs spreading themselves a bit thinly.
B.P. Marsh & Partners (LON:BPM). 2nd RNS today shows further 5% of Pantheon Specialty Ltd bought off Management for £12.5m. A 32% stake was valued at £32.694m in the Half Year results. Does this imply a further upward valuation in the next accounts or am I missing something?
B.P. Marsh & Partners (LON:BPM)
hmmmm good question - note these shares are being converted into preference shares - so i wouldnt necessarily presume that the normal rules would apply that all shares are worth the same. Note as shareholding gets higher you acquire more power - so it might be here there is an element of them paying more so that they can if needs be exert more control over buisness direction. If nothing else as their share increases it might mean they need backing of les of teh founders if the founders have fallen out. Note £250 mil valuation seems a bit of a stretch with £16 mill EBITDA - hey ho perhaps it is that simple and the fact they are paying that suggests things are going so well that the valuation can be justified - we will son enough fin out at next update.
also excellent resuylt cashing out of Lilley Plummer - £4.5 mil uplift in value - that investment has gone from £13.5 mill valutaion January to £21.6 mill sale price - nice quick 60% gain
There was me thinking this company might be struggling to do much more than earn bank interest type returns for the next year or two !!
I have come close to top slicing here a couple of times - thankfully i havent as of yet. Perhaps if the price goes up much more i will ned to get the knife out?
hmmmm surely its back to pedestrian bank interets type returns for the next 12 months ?
I very much see this as dragons den type stuff to people in the know who they fund - some nice quick little risk return for thePantheon bods - another decent advert for anyone else who would perhaps like to partner up with BPM
My contribution re bargain list
The sell-off on AIM shares seems most pronounced in my portfolio but almost everything is down for me over the last 3 months.
Enjoyed your post (and many others here today) Tortoise Investor, and have saved your post as posts quickly get lost.
I agree on Commercial Property which gets regular coverage on the Investment Trust threads here, including Supermarket Income REIT (LON:SUPR) which I hold. Another I hold worth a good look is Schroder European Real Estate Investment Trust (LON:SERE) on a 30% discount.
Agree on Polar Capital Holdings (LON:POLR) too. It’s down to £4.75 from £6 in July, and ditto Cavendish Financial (LON:CAV) where I reduced after their last update but will top up on clearer signs of the plus points you covered.
Construction though is one of the few sectors I never buy, because of the often wafer thin margins so that a big contract going wrong can be disastrous. E.g Carillion.
Others?
I bought De La Rue (LON:DLAR) at 116p after the recent transformational disposal. Paul Scott when analysing it was surprised at the muted share price reaction to “only” 116p. It’s now just 97p and unfathomable fall, unless insiders know that what looks a done deal might not be.
I posted on Ferrexpo (LON:FXPO) in the mid 40s a few weeks ago and ended up buying again at 47p. Key investment case is the awful war ending soon. Share is now pricing that in with a further 10% gain today to 65p. It’s clear that both Russia and Ukraine are having big problems recruiting soldiers now…….and hence the share price gain. A lot more upside IF the war is over soon. Ferrexpo (LON:FXPO) paid 38p in dividends in 2021 ahead of the Russian invasion.
Gulf Keystone Petroleum (LON:GKP) 128p is another I hold with big upside IF IF that pipeline ever opens again. Again the dividends were huge before its closure. Unlike with Ferrexpo (LON:FXPO) where there’s downside risk if investors are wrong about the end of the war, Gulf Keystone Petroleum (LON:GKP) are coping well despite the pipeline closure, and have started to pay dividends again too.
Gulf Keystone Petroleum (LON:GKP) has already paid 2 dividends this year for 12p in total to give 10% yield. In 2022 they paid 80p! Yiannos has also posted the plus case for Gulf Keystone Petroleum (LON:GKP) several times.
So bar surprising bad news the downside looks small.
Finally to the one missed. I used to hold Good Energy (LON:GOOD) and after seeing that it was a “Which” recommended supplier was about to check it out. Too late as the share has rocketed this week on a possible bid.
I'd add Cordel (LON:CRDL) to the list, I followed up on the note written by JonBeddell last Wednesday and was so impressed with what I uncovered.
For anyone looking to do DD, I'd highly recommend reading every RNS dating back to their IPO & then digesting the following two excellent, very detailed broker notes that have been published this year;
https://www.edisongroup.com/re...
https://www.cavendish.com/rese...
Edison is free to read, Cavendish free if you register on their portal.
To me this looks like a rapidly growing SaaS business trading at a £14m market cap which is on the verge of breakeven on 45% turnover growth to £4.4m. Forecasts are for £6.2m this year, so it's trading at under 2x EV/Sales.
What really caught my attention though was the £1m placing at 6.5p on 26th September at a 24% premium to the prevailing share price which saw Rathbones become the largest external shareholder. Rathbones are the largest shareholder in Tracsis (LON:TRCS) so I'd assume they know what they are doing in the rail tech sector... And you don't get a 24% premium unless an II is fairly desperate to get involved!
What else did I like? The fact management have very significant skin in the game & their salaries are extremely reasonable (£90k highest for the CTO, who owns just under 12% of the business). The register appears very tight with the only II's over 3% being Rathbones and Amati (see Paul Hill's interview with Paul Jourdan last year for his positive opinion on them too).
I think it's fairly safe to assume their tech solution is best in class, or at least first in class, given their spate of recent customer wins & blossoming commercial relationships with both Network Rail & Amtrak. They seem intent on adding additional functionality via new modules & the global market is huge.
Certainly one to be watched in my opinion.
YouGov (LON:YOU) just noticed finals are out .... the company put out a 5 year plan from memory this targeted a 20% revenue growth rate...when the guidance incorporated the acquisition this dropped to a still attractive 15%...correct me if these numbers are wrong. Either way current trading is significantly behind plan. I haven't got a broker note but from stocko rev growth is expected to be 15% in 2025. The company guides to inline 2025. I think this is based on achieving the cost saving run rate. 70% of £20m is £14m. Add that to the £49.6m 2024 disclosed Operating profit, you get a 28% pick up to £63.6m.... my best guess is that's earnings between 38 and 40p. This looks to be ahead of current forecast...so there is wiggle room. Optically a cheap stock....to rebuild rating I think revenue growth needs to be between 5 and 10.... and high single digit probably needed for a rebuild to mid teens rating. Today appears to be enough to restore a little confidence but that is all. The question is also what is the sustainable margin.... just using the cost guidance would get a margin of 19% .... but the market is not doing that, currently the increase in operating profit relative to current revenue growth is only 16.3%...... so if £388m is hit, which is up 16% then the company will smash current expectations. The second half weighting is not our friend though, nor current trading. The jury is still out even after today's rise.... previously a very strong stable grower.... I think it all hinges on revenue growth....happy to hear alternate views.
YouGov (LON:YOU)
the company put out a 5 year plan from memory this targeted a 20% revenue growth rate
i think that is the problem with these companies they are great when they are great - but when they are not iots really tricky to sewe whether they will regain lost mojo. Dont know much about the acquisition but i would slightly worry that came around at the level it did as they knew they were struggling - nothing worse than struggling business get £200 mill of debt with acquisition and have new business to bed in that might not be the good value you thought it was.
Surely it would have to be future annual contributions rather than total, otherwise investors, over say 50 , benefit hugely from their lower ( inflation ) contributions from decades ago, which have benefited from compound growth...
As people are using them as an alternative to pensions, then freezing the allowance at £ 20k p.a. would seem logical, as that amount will decrease in real terms over time... plus people have already paid income tax and NI...
Surely the Government should be targeting non-doms and not prudent, working ( or retired ) people who have contributed and saved ?
Hopefully this is the case Cancun and its just idle histeria **- i seem to remebmer Kiers Starmer was asked and said he had no "plans" to look at the 25% tax free lump sum - that might have ben with regard to removing it rather than reducing then maximum amount though.
I think we would all agree(hopefully for first time ever here ?) if someone is at or around retirement age and has 125k available as their tax free 25% element now it would be outright theft if that amount was reduced down so that amount was not now all tax free - surely a line in the sand would need to be drawn so that amount is not affected.
i do remember javingh £30 per week knocked off my projected state pension when the new flat rules came in - we were all told "you wont lose any accrued beenfits". what they didnt say is that most of teh asumed £30 extra per week relied on extra contributions paid betwen then and retirment age. when they did the actual calcs the £30 reduced down to zilch - despite the fcat i was in my 40's. I did feel that not pro ratering limits as approrpiate and handing over % was theft - afetr al i was basing my savings on that extra 30 pw coming in and then it was gone - grrr
Not stock related so excuse this comment, but those of you who, like me, are hard working landlords must have enjoyed a rare week of the media, including Laura Kuenssberg, standing up for us.
Yesterdays's Newsnight opinion was that CGT would only rise to levels similar to that currently paid by landlords as pushing the rate higher has been forecast as counterproductive, ie would not raise extra revenue.
And tbf, she has played a blinder by scaremongering higher rates which has resulted in heavy front loaded sales
I have built a pension from a SIPP and an ISA, currently 500k in each. I have no company pension schemes, I moved a company pension into the SIPP. I'm less than two years from drawing down on it.
If I was to ask a person with a company pension what it was worth, I might get an answer like 35k a year. But I asked what is it worth: 35k times 30 years = 1m. Why should I have to fear for my 1m pension for the next 30 years, when somebody with a company pension of the same value doesn't. We have both worked to build a pot, which is what I thought was the purpose of the tax incentives. 1m provides a moderate pension, or 35K a year is a moderate annual pension amount as per the PLSA.
Maybe thinking I might live till I'm 99 is where I'm going wrong. I don't 500k in an ISA is an excessive amount if you think of it as a pension. Some people may have 1m in an ISA and no SIPP or company pension.
Deleted, I strayed from investment discussion and I don't think added any value here. :) Tim
Many 'working' people make a salary sacrifice into their pensions. This boosts their pension contribution by the amount of the NI not payable on the sacrificed element.
I would imagine we will see threshold limits set on these amounts.
RWS Holdings (LON:RWS) I hold here. They did do an AI technology teach in which is worth checking out
https://www.rws.com/about/inve...
In terms of AI's impact of the business - it's quite complicated. There are parts of the business that will benefit but it will obviously change the dynamics for the many individual translators who use RWS' Trados system for work stream management. On the other hand - they have a business line that helps companies prepare their own data for use in LLMs
It's worth nothing I think that the industry has been wrestling with Machine Translation for a while now - google translate has been around for an age for instance. The excellent Slator Pod is a good resource for insights into the industry. For now, the lingo is about 'human in the loop' - ie first drafts are model driven but there's a paid human translator in the loop which makes sense. For critical use cases in regulated industries etc it is huge career risk to *not* have a human involved.. besides the models aren't there yet.
For what little it's worth, I personally think the AI wave will certainly mean a lot more content is translated but what really matters is will anybody who currently *pays* for translation now, now switch to free online LLMs? I think that's a lot less likely.
Looking forward to the Budget ;- )
I wonder if we can paraphrase the old marketing comment on the Victoria Albert Museum and its Cafe, to say 'A National Health Service-with an economy attached to it.'
In my 30+ years of investing, I've never known the Budget to have ever generated so much prior consternation & concern as tomorrow's announcement.
Just hope our worst fears don't materialise.
'In my 30+ years of investing, I've never known the Budget to have ever generated so much prior consternation & concern as tomorrow's announcement'
I agree with you there, and I can't help feeling that there is a certain amount of unjustified hysteria.
What proportion of the average AIM stock is actually in a vehicle which shelters it from IHT? Impossible to say, but I suspect that it's a very small proportion - nothing like enough to generate the 30% fall that Peel Hunt has talked about.
"a certain amount of unjustified hysteria" re the Budget
We have the most clueless, malevolent Government in living memory, intent on destroying the productive part of the economy and wealth creation in all its forms.
I think everybody targeted for tax increases should be concerned. However, there are clearly some groups likely to suffer life changing loss of wealth due to this budget, for whom a certain level of hysteria is probably well justified.
Of course, most of us would have been financially wiser to leave the UK before the General Election
We have the most clueless, malevolent Government in living memory, intent on destroying the productive part of the economy and wealth creation in all its forms.
Brexit, austerity, more than a decade of internecine squabble and all of it culminating in the most calamitous budget in modern memory and you’re worried about tomorrow’s narrow adjustments to tax and spend???!! The last lot have done far more to harm the UK than this government ever will. I’m ashamed to have once voted for them. That said, this an investment forum, so I suggest you take your party political bias elsewhere. Let’s talk about buying opportunities.
I am concerned about the bending of fiscal rule to be able to borrow an additional £50bn. What impact will that have on interest rates coming down. The now leaked increase in minimum wage is also going to have an impact on sectors like hospitality.
They are being changed not "bent". They are not, and never have been immutable. The Tories changed them 5 times in the last 7 years. Any change that encourages the investment we need for the growth that has been so sadly missing for the past several years is to be welcomed.
Ultimate Products (LON:ULTP) - just a reminder that we are hosting an Investor Presentation with Q&A this Thursday 31st October at 2.30pm following FY results released this morning - the link to register is here: https://www.equitydevelopment....
Ultimate Products (LON:ULTP) - Paul will love the table of broker expectations for the current year and prior year in the results announcement. Why can't every company do this? Brilliant.
*Adjusted measures are before share-based payment expenses and non-recurring items
**Financial summary, including consensus market expectations are set out below
FY23 (Actual)
FY24 (Actual)
FY24 (Consensus)
FY25 (Consensus)
Revenue
£166.3m
£155.5m
£155.5m
£169.3m
Adjusted EBITDA
£20.2m
£18.0m
£18.0m
£20.6m
Adjusted PBT
£16.8m
£14.5m
£14.5m
£17.5m
Adjusted EPS
15.4p
12.3p
12.3p
15.0p
AB Dynamics (ABDP) is another stock getting hammered on AIM. Recent update was ok.
Watch the directors dealings on Ab Dynamics (LON:ABDP), they have been shrewd in the past. Large recent sale by one director. If they start buying, l would follow then.
Some mightily impressive returns from B.P. Marsh & Partners (LON:BPM) ‘s latest disposal just now, turning a stake of £1mm in Lilley Plummer five years ago into over £21mm. Shows how good this management is at this game.
Also at a premium (26%) to it's last valuation in the accounts (per the RNS, I haven't gone back and checked). Very confidence inspiring since their "TNAV" (which they trade at a discount to) is their valuation of their unlisted holdings rather than anything quoted.
(I hold)
True. It also means that cash in hand is about 45% of their market cap.
Synectics (LON:SNX) is an AIM share that has fallen back recently after a very strong rally after recent results. I think it fell about 5% yesterday. Possibly one for the watchlist.
Added Frp Advisory (LON:FRP) to my collection yesterday and may have caught a bounce for a change. Paul reviewed this on fairly recently and called it Green at140p. Sp moved to 154p before succumbing to the malaise of the market. 125p yesterday seemed a decent entry as margins are excellent, pe is reasonable and business is growing organically and through M&A - just announced 4th this calendar year. 4% Divi is well covered and paid quarterly. Still carries the AIM risk so could be worth keeping powder dry till we get past the witching hour.
Then we just have to hope the giant Orange wrecking ball isn't released next week. Can't see that being good for the planet, the Ukraine (and the rest of Europe as a result) or the global economy if tariffs are delivered as suggested. Might have more impact on markets than RR?
Not a popular sector but ITHACA is in my view undervalued, good dividend, 16 year of reserves, recent acq of ENI good fit. sheltered by tax losses. No sensible Oil substitute is sight?
Thanks Paul for your watchlist and to readers who have highlighted others
Hi Paul,
Thanks for your helpful comments today and every day.
I am new to this and keen to understand more about the potential effect of the budget on AIM IHT. Forgive me if I am saying anything stupid. It seems to me that there are four scenarios in the budget regarding this for Rachel Reeves:
One produces the absolute carnage you describe. In scenarios two and three, investors can only crystalise their benefit by dying, a choice they are unlikely to adopt as a financial strategy. They will likely freeze these investments until their natural demise at some point in the future, as these investments will have a locked-in tax benefit over any new investments. How do you think this might affect the market? Four is again as your scenario.
Are these scenarios credible? Is there something I have missed?
Hi Islandhome, What about another scenario where by you have to hold Aim shares for four or five years as opposed to the current two years?
If IHT relief is removed from Aim shares this will have a detrimental affect on London, where it is already struggling with a dearth of new listings, as a place to raise capital particularly for small companies. It is considerably cheaper to be listed on Aim than on the main market so for smaller companies it does not make sense to have a main listing. The removal of IHT relief will be the end of Aim.
Agreed the qualifying period might be extended from its current 2 years to 3, 5 or more years?
Or she may simply put a cap on AIM BPR claims of say £500,000?
Or she may choose to abolish the general BPR eligibility but introduce other tax benefits (such as CGT or IHT exemption) for those say participating in AIM IPOs or placements, only.
I think some of the clever money has sold their AIM shares and then have 3 year in which to reinvest in other BPR qualifying assets, e.g. forestry or EIS/SEIS (unlisted) which offer other tax benefits.
Another scenario for you Islandhome:
A per estate limit of say £50,000 for BPR. Easy to administer (via the IHT 400 form), less likely to cause sudden share price volatility (depending on the limit/cap) and wouldn't lose too many votes (most small shareholders & "working people" with a few shares unaffected). BWDIK!
The history of Business Property Relief as it was first known: -
"It was first introduced by the government to help ensure that when the
owner of a family business passed away, the family would not be forced
to sell the business – or any property owned by the business – to pay any
IHT due."
As usual many tweaks were added over the years to presumably exclude the difficult task of valuing an estate for probate. One exclusion which covers Aim and private companies is "shares not listed on a recognised stock exchange" because of very limited liquidity. Selling a few shares as we know is very different to selling a substantial amount and the only real way of knowing the value is an actual sale, EQLS for example. Passing on this exemption to subsequent holders of more than 2 years standing is where we come in, presumably to create a market in the founders lifetime for selling their shares or for a fund raise.
I really don't expect HMRC to want to have that problem of valuing shares without a main market listing but .gov have form on not taking advice from experts. You could write a book on unintended consequences.
'I really don't expect HMRC to want to have that problem of valuing shares without a main market listing'
HMRC do have a department devoted to valuing assets with no defined monetary value. If they can cope with wine collections and paintings I am sure that they can cope with unlisted shares.
"I am sure that they can cope with unlisted shares." You reckon? They don't have a very good record on dealing with income tax. I think your two examples are much easier than unlisted shares but just my opinion. A rare bottle of vintage wine v several million shares with a market size of 5000.
ISAs .. they were designed for ordinary people to save and build up a tax-free pot,
I am an ordinary person trying to do just that. I have been more successful than some, less successful than others (but then again, that applies to everybody). I have achieved this through guile, luck and prudence. I don't want what I've accumulated to be taken away. To quote Thomas Sowell: "What exactly is your 'fair share' of what 'someone else' has worked for?"
See, this is why I cringe when Lee and others keep talking about "ISA millionaires". Stop drawing attention to it. It only breeds envy and makes the process a target.
But anyhoo, thanks for the AIM share ideas. They are very much appreciated.
Hi Mark, Mabe it's like catch 22. ISA's are not for ordinary people, they are for "working people", but if you have an ISA and can therefore "write a cheque if you get into difficulties" then a working person cannot have an ISA. That's labours logic now.
Hi Mark, thanks for your comments.
I don't think anyone is proposing that ISAs be confiscated in any way. More that above a certain level, any further investment gains would simply become taxable as they would be outside a tax wrapper. Personally I don't see any particular problem with that - you would still benefit from good stockpicking, but would have to pay CGT on gains above a level the Govt chooses. £1m seems reasonable to me, although £0.5m has also been mooted.
Although it's very difficult to see how that would be administered & calculated, it could get very complicated.
There's also the principle of not bringing in retrospective taxation. People who invested money in good faith into a tax-free wrapper could justifiably kick up a stink at the goalposts being moved. Although they're so few in number, that I don't think there would be any sympathy from the wider population!
Thank goodness all this uncertainty & stress is about to be resolved tomorrow.
Regards, Paul.
I think that if the chancellor wishes to limit the tax advantages of ISA's the only practical way to do so is to limit the total value of contributions into the ISA. Anything that is based on the value of an ISA would have to contend with fluctuating values. one day over the limit, the next under. How would that be administered?
It would also penalise those who have chosen to use what they have earned by being a working person to try to build up a financial buffer for use in later life rather than relying on handouts from the state.
I don't think that will work. I have no idea how much I've contributed over the years. I don't think many others do, either.
I believe ISA providers have to maintain records to ensure no-one breaches the annual allowance. HMRC can require this information from them. FWIW I know what I have subscribed as I keep a record. It might take time for some people but I thinks it should be doable.
rwh3ue I can assure you it certainly is Not doable! Some of the money I now have in my ISA will have originally been invested via a PEP in 1986. Cash, funds and equities have been transferred between different providers (some of whom don't exist now) and subsequently different platforms over the last 38 years. The historic records are not available now.
When an ISA transfer is made the new provider is not notified of how much has been invested in previous tax years - only how much of the current year's ISA allowance has been utilised.
Quite right. There is no way I could discover how much I had contributed to my ISA over the years given the administration has been handled by Comdirect, Selftrade, Equinity and Interactive Investor and I may have missed one let alone anyone investing in PEPs.
It's easy to know when the max was subscribed right fron the days of the Tessa. I did this and never regretted it and neither will my heirs. Major was right, it is one way to cascade wealth down the generations, any other way is what only politicians advisors know about.
A similar system worked for pensions for years, with lifetime limits. I can't see why doing the same for ISA contributions would be much more difficult.
"Thank goodness all this uncertainty & stress is about to be resolved tomorrow."
Well, until next October anyway!
Exactly, a big concern for me will be that perhaps the measures announced tomorrow will not be as bad as has been mooted by the likes of the Telegraph, BUT when behavioural change/economic weakness means they do not produce the necessary results, we're all in the same boat again next year.
What's really needed for confidence and good financial planning is a strong statement accompanying any announcements, along the lines of "this is our position and this will not change now for the duration of this term of government", however I imagine Keir & Rachel will have learned their lesson about making such concrete pledges for now!
Paul,
'it could get very complicated'. For the last 60 of my 80 years successive governments have done just that, made financial life ever more complicated. I am just about to give up on it.
Agree with you Paul although note Resolution Foundation, which was pretty close to Labour thinking and whose ex CEO is now a Labour MP, argued for a £100k tax-free ISA limit. Let's see what's said tomorrow.
I agree with other readers that administering any cap, no matter how structured (value of contributions or pots), would be near impossible . . . . . . . .
There is no central record of who contributed what into ISA - when, how much, which provider etc. and trust is placed on investors not to use their allowance more than once. Many investors (even those with large holdings) use a very wide range of providers, so hard to track and I'd also add that many people genuinely lose track of what they have invested or where - whether ISAs or pensions.
There is an argument that ISA disproportionately benefit those with large incomes. While there is some truth in this, it would be more accurate to say they disproportionately benefit those who are both thrifty and are willing to take risk hoping to earn higher returns. Of course, there plenty of honest and thrifty folk are happier to have money deposited, happier with both lower risk and returns - an absolutely valid choice.
I think those characteristics are being overlooked by Labour politicians who don't understand how the human condition actually works and what drives aspiration and thrift. Giving up hard-earned money which has already been taxed in the hope of generating a return and a better tomorrow can only ever be an admirable characteristic . . . . . . . .those who have done so for decades desent being regarded at best as a milch cow and worst undeserving. I have a large 7-figure SIPP which is nothing more than the cumulative value of all the new cars and expensive holidays I chose not to have since I was 25 . . . . . . .and the dominant factor in accumulating it has increasingly become the power of compounding.
Notwithstanding the above, a dominant characteristic of investors is also age, as it's in your 50s that the majority might start generating unspent net income, receive inheritances or a few years later pension lump sums (which they have earnt - these aren't windfalls) and collectively these enable them to invest.
Through the process of compounding there will inevitably be more and more ISA millionaire over time, and eventually a fair few will be worth £10m plus (successful investors can easily double their portfolio every few years so wouldn't actually take that long to go from £1m to £10m).
At some point therefore I suspect there will have to be some sort of crackdown, although hopefully nothing in the coming budget. As others have said, can't see an easy way for this to be administered given fluctuations in portfolio values.
Risk and Reward go togther hand in hand but a Labour government will do away with Reward leaving only Risk for investors. It wants everyone to spend all their money, now. Sorry about the political bit, rant over.
Hi Bouden54
Fairly recently someone did a freedom of information request and established there were already ISA nearly £10m and SIPPs far in excess of it.
I think it was Einstein who declared the power of compounding to be the 8th wonder of the world. Or as my father (an investor since 1965) reflected that his investing experience was that "accumulating £1m take a great deal of effort and discipline, but getting from there to £2m just takes time".
I have a question on tomorrow's budget.
If the AIM Inheritance Tax change is made then will this be something she is likely to say in her speech, or will it be in the budget documents that are released?
I appreciate it that the answer might be that it might be in her speech and it might not be (and only be in the budget documents).
If she does not say it in her speech and it's in the document then does anyone know how we see the document and what search term we should use to find it?
I am seriously thinking that it might bee better to buy the best quality AIM stocks that are at a reduced price today and that even if they go down tomorrow they are likely to come back.
Many apologies for the overlapping replication To The Moon , I was just a tad behind the market as usual :)
Just the ones paying a dividend, perhaps?
Hi, all budget documents are usually uploaded by HMRC and should be available later in the afternoon. For example the 2023 Spring Budget can be found using this link:
Spring Budget 2023 - GOV.UK
Not sure about the search term as it will probably be covered within one of the published docs
Following on from scartridge, it looks like this is might be the place to see the budget as it is delivered. I hope so, rather see it in print personally than listen to her speaking .
Autumn Budget 24
If she's going to do it then she'll announce changes to business asset relief in the speech. If she doesn't say anything and it only turns up in the Budget Red book it will look like she's hidden it and is running scared. That will create two rows (the change itself and the hiding of it) rather than just one.
I’m sorry Paul but with the greatest respect I have to take issue with your comment on ISAs. After all this is a platform / board supposedly dedicated to generating LT investment outperformance. Hence I don’t understand why you / we would accept any third party argument that superior performance (which presumably has taken the form of additional risk and / or contrarian thinking) should somehow be penalised. In a nominally still capitalist economy this is just bizarre to my mind. By all means make the case that people can only put in £X into ISAs tax free ex ante. But to penalise those who have turned that X into 3X or 5X - like a variant of the pension lifetime allowance?? Well, if we go down that road we really deserve our pedestrian economic performance. My understanding is that those who have been squirrelling away the ISA maximum since inception have been able to put away about £300k tax free. Hence those who have turned that into 7 figures or multiple 7 figures are relatively few. They should be an inspiration about what is possible through diligent saving, prudent decision making, yes, and some luck. Instead they are somehow cartoon villains. I was very sad to read Lord Lee following this same line of thinking in a recent article, essentially embarrassed at his success and making the case it should be stopped for those who aspire to come after him. Given we are a day away from the budget and nerves are on edge I hope you / everyone else will forgive this ‘mild’ rant. But sometimes I do despair at the future of this country / continent. There is a reason the US is leaving us in the dust, despite their own political travails. We despise success…
Wasn’t lord lee making the case that above a certain ISA value you can no longer have the tax free allowance to add further? Rather than any kind of cap on total amount? Which is more in line with your point about limiting the amount added, rather than the total like the pension lifetime allowance.
I could be wrong, but that is how I read it.
I have heard Lord Lee say two things. 1. That he personally no longer contributes to his ISA given that the annual allowance relative to the size of his pot means that it’s essentially a rounding error I.e. implying there is an element of self-regulation here. And it makes sense. If you have achieved a larger pot, most probably in later life then it would be odd to take x in dividends or capital drawdown in any given year just to put 20 straight back. 2. The current £20k allowance is “excessive”. I guess the latter comment irked me. If he thinks it’s excessive today why didn’t he say so before in any of the years since it was raised in 2017. As a Lord he had the perfect platform. And what would not be excessive? A lower allowance by implication reduces the opportunity to build a bigger pot. Just strikes me as a case of ‘I’m alright Jack’
Other random thoughts:
- ISA’s are not perpetual trusts. They expire with their owner. Yes, they can be passed on a one off basis to a spouse or civil partner but when they die they are gone. So no chance of them really ever becoming massive pots for most people
- agree with others that creating a retrospective limit would be an admin nightmare and subject to potential legal challenge. Much easier just to limit the quantum from the next tax year. Most ISA pots are only £30k. I can easily see the limit going from 20 to 10. With the message that it’s still very generous and you should consider yourself lucky it wasn’t cut further. Could then be cut further in future budgets to 5 given need for ever rising tax revenues
- ISAs are not an act of altruism on the part of govt. They are designed to give a carrot to people to save so they are not a future burden on the state and most importantly to provide capital for re-investment. We already save too little as a country and consume too much. Too much of the capital we do save goes into non-productive residential real estate. It is a reality that wealthier people have a greater ability / propensity to save. It is a LT good for the country and not just them to push their savings into corporate investment rather than ST consumption or resi
- I wonder if any cap on future contributions would perversely further hurt small cap shares the most. If I can no longer meaningfully top up my ISA am I going to risk what I have in more speculative investments which if they go bust those tax exempt pounds can never be recovered. Better to focus on safer FTSE100 dividend payers
- If changes are to be made I have some sympathy for ring fencing a portion of the pool for British tax registered companies. Say 10 global and 10 UK only. But that’s the one thing which is definitely unlikely to happen
I think if you use the last Labour government figure for the Isa allowance, in real terms it would be £7500.
Wasn't it £ 7 200 ? Which would be approximately £ 11 200 now ?
While I totally agree with what you are saying I don't believe that the government does . It would appear that they are out to punish those that have worked hard, been prudent with their expenditure and saved for a rainy day and their future. We will find out tomorrow if this is the case.
I would add Anpario (LON:ANP) Green on Pauls list, had an adverse reaction to announcement of an acquisition at the end of September and has been going down ever since. (I hold)
MS International (LON:MSI) Had been going up steadily for two years but has suffered a recent sell off to make the PE reasonable again (I hold)
MS International (LON:MSI) has a dominant but elderly family shareholding, they will have to hand it on somehow in due course, and bite the bullet on tax. Cracking little defence business that is underappreciated.
An interesting chart taken from X Michael A Arouet. Tells us what we intuitively know but nonetheless.
Today’s third quarter figures from Pearson (Pearson (LON:PSON) PSON), which calls itself the world’s leading learning company, just highlights the sad significance of the above table. The UK and the rest of Europe just can't match the US when it comes to creating high tech succcess stories.
Pearson, floated on the stock market in 1969, is capitalised at $9.4bn whilst ServiceNow, a Californian software company, with which Pearson has just signed a “meaningful multi-year deal" to help it exploit AI in its workforce skills business, is capitalised at $195bn.
ServiceNow, floated as a $210m IPO in 2012, is now marginally bigger than Pearson in terms of revenues but is valued at roughly 20 times sales, whilst Pearson is valued at 2 times sales.
Pearson’s shares jumped today after news that its underlying sales in the third quarter rose by 5%. By contrast ServiceNow’s third quarter revenues were 23% ahead.
Over the last couple of years Pearson has recruited a new chairman (ex-Google) and a new chief executive (ex-Microsoft). What chances that they can finally turn Pearson into a AI growth stock?
Most of Pearson's business is in the US and came from big acquisitions. So it's effectively a US company that can't keep up with US companies!
Great list thanks Paul - I'm very cautious on Oxford Metrics (LON:OMG) since they're going to have to start competing with things like this for motion capture:
On the subject of an AIM watch list. I would like to add to MS International (LON:MSI) , Journeo (LON:JNEO, Intercede (LON:IGP, Volex (LON:VLX) and Niox (LON:NIOX. I would add to Warpaint London (LON:W7L, but I have a rather large position already. If I did not own such a large position in Warpaint London (LON:W7L, I would be buying.
I agree about Warpaint London (LON:W7L) . Two directors hold 41% of the company between them, so the effect of any selling if BPR is removed will be less than for many other AIM shares.
Paul ,A few more to throw in the ring, please note I hold all.
TIME fallen from 65p to 51p -nothing but upgrades forseen currently. Bought more yesterday
If into gold, as per comment on RFX , SRB -producer on per of 1.9.
AT has fallen from high of over £8 to £5.5 ,recent new acquisition looks profitable to add to a good forward projection ,@ £8+ it looked pricy.
Agree with Paul about GMR and continue to drip buy.
FSG down from £5.2 to £4.50 figs look excellent, and nice divi too.
One of Paul's - SPSY looks a good buy for 2025 too.
Interesting both AT & FSG flit in and out of Slater 'zulu' folder ,lately.
Good luck with your buys Tony
Lets not forget Ashtead Technology Holdings (LON:AT.) in the bargain catogory.
Their recent acquisition Ace Winches resulted in a lower margin because winches are rented out with a team of people, rather than as pure equipment rental. There was poor comms that this would happen and this disappointed the market. On a PE of 12.6 with 21% EPS growth forecast next year.
It has been hard to know what to do about the almost certain rise in employers NI and the less certain removal of IHT relief from qualifying AIM shares.
I have chosen to do nothing.
For example, I own Marks and Spencer (LON:MKS) . They raised staff salaries from £10.20 to £10.90/hour costing an additional £57 million early in the year. The total salary bill for the year end 2024 accounts was £1,738 million excluding social security and pension costs. If the chancellor removed the tax exempt amount for NI and charged an additional 2%, then M&S would pay an additional £34.76 million, or 5.2% of operating profit. The market knows this, yet the shares sale serenely on.
The AIM market has had a more torrid time. 12.7% of my portfolio is in AIM shares, so a 20% fall suggests a 2.54% portfolio hit. I think most of the damage has already been done and the market has assumed the worse.
Hence, I choose to do nothing, but I also hold 20% cash, in case any opportunities present themselves.
Some good watchlist suggestions, Paul. I’ve actually bought a few of those lately, being high quality companies with great operating numbers:
Advanced Medical Solutions (LON:AMS)
Tristel (LON:TSTL)
Tracsis (LON:TRCS)
Warpaint London (LON:W7L)
Additionally, CVS (LON:CVSG) looks interesting, but the overhang isn’t due to clear for at least another 6 months, so wouldn’t be my choice for a potential rebound.
Not on your list, Zotefoams (LON:ZTF) - down a long way and I am finally in, along with other recent purchases FW Thorpe (LON:TFW), Spectris (LON:SXS), GlobalData (LON:DATA) and Bioventix (LON:BVXP)
Also interesting, Volex (LON:VLX) ,Oxford Instruments (LON:OXIG), Keystone Law (LON:KEYS) and Journeo (LON:JNEO)
Thanks BnB! I agree re FW Thorpe (LON:TFW) - usually overpriced in the past, but it's come down to a much more palatable valuation now. c.299p (PER c.14.5x) and has a cash rich balance sheet. High quality scores. Good suggestion, thank you!
Zotefoams (LON:ZTF) - I'm perplexed why this is constantly falling. Nothing to do with AIM, as it's fully listed.
Zotefoams (LON:ZTF)
Zotefoams (LON:ZTF) - I'm perplexed why this is constantly falling. Nothing to do with AIM, as it's fully listed.
zotefoams has always had good times and bad times - must admit i am tempted to buy back in here. i would say the one worry i would have is how much money do they make from nike and what is % chances of nike ending the partnership at some time. These huge mega caps never stand still and its a brilliant advert that the relationshop they have continues but if nike is delivering 30% of profits say that is a risk area as one has to presume at soem stage a company like nikle probably will move on elsewhere- if contracts were ever up for renegotiation the news would obviously leak out and its almost certain the price would be down before the bad news came out if that were ever to happen. I think now though the price does look fairly tempting so i for one might be ready to sepond soem cash here despite my slight nike concerns - there seems enough positives elsewhere in the business that they could hopefully cope withouit nike.
Does anyone have any sort of handle how much of the profits might come from nike ? note with high fixed overhead costs its a double whammy if lare contracts are ever lost as the larger overheads needed to cope with these contracts dont go away quickly - note they mention footwear demand normalising freeing up capacity for other stuff - so perhaps i am over worrying here - perhaps nike have done the necessary job of getting capiacity up are running with good cashflow - i ssupecvt nike drive a fairly hard bargain so perhaps they can make as much selling the same quality to someone who is not nike ! - heck if their stuff is good enough for nike thats a decent advert.
perhaps its just lack of buyers before election generally - if people are cashing in their lump sum pensions as mentioned perhaps its natural that they may be selling their zotefoam shares to get their hands on that cash.
Rmillaree reZotefoams (LON:ZTF) the Nike contract was extended in June last year to the end of 2029. I believe Nike did this to maintain their exclusivity on the specialist materials and development skills that Zotefoam have, within the sports apparel market. Concern and drop in sp may be due to reports of Nike losing share and the sportswear market bing so fashion fickle but not of any likelihood of the contract being terminated early.
I suspect a lot of the drop is profits being redeployed whilst waiting for the ReZorce trial news. Seems to be taking a long time though apparently expected in Q4 now. Quarterly update is due imminently I think so maybe will shed some light. Tempted to top up at these levels.
Zotefoams (LON:ZTF)
the Nike contract was extended in June last year to the end of 2029
thanks for that sevencc - i hadnt realised they have nike in the bag up till 2029 - that being the case my concerns in that regard are probably null and void practicably speaking. It does make the drift somewhat perplexing - hey ho i guess withn the amount of other shares similarly drifting perhaps a p/e of 13 should be looked at as toppy nowadays !
Zotefoams (LON:ZTF) When watching the latest results webinar they reiterated many times that the orders were higher than expected and it was a one off, suggesting they would be lower this time around. However, maintained guidance. That and the more reserved tone and talk of more tests on Rezorce was a big indicator that things would take longer than many punters/traders expected. I'm certainly sitting tight and if it wasn't such a large position I'd be topping up here. Upside far outweighs downside at this level.
Zotefoams (LON:ZTF) results on 31st October I think, I've stayed invested based on my ethos to only trade on news. I'll probably be regretting that!
Many thanks indeed as ever Paul for helping us Newbies :)
1 slight question re tomorrow for anyone whom might know... is there a simultaneous release of a document / transcript ? How quickly will we know the fate of BPR as it relates to Aim ? I believe that the Chancellor normally starts with the Macro situation... ? There isn't time in the speech to mention everything, so could BPR be removed even if she doesn't explicitly talk about it ?
Don't liontrust own a substantial portion of FW Thorpe (LON:TFW) ? It's not a widely traded/held stock. Feels like that will weigh on the shares for a while.
Ultimate Products (LON:ULTP)
I was kinda sitting on the fence with this company - there seems to be a alot to like here and they seem to be doing the best they can (as evidenced as profit per employee - they are obviously pretty lean and mean which is great) and they seem to be doing very will outside the uk which i see as huge positive.
I have been swayed to avoid this one by the following comments.
. First, we expect a home market rebound as the company no longer faces the air fryers comparison issue
I must admit i am struggling to to thgink of any home appliance product that has taken the kicthens by storm as much as air fryers over the last 10 years (anyone who hasnt taken the plunge yet should do).
But having upgraded my air fryer in the last 12 months due to the old one being beaten to death - i dont think i have ever seen as many different brands and options on any product as i did with airfyers. To me the competition here seems insanely tough and with the best will in the world i suspect there will be the main premium brands and then the rest - can they manage competing against the rest i wouldnt say no but i suspect it is a brutal market to compete in. I am probably harshly juedging what is obviously a good company but it the petra brand strong enoughn to stand out in the crowded airfryer market.
Note looking at current broker forecasts the company are currently expectiong return to decent growth for the new year - so i am, kind of swimming against the tide here as normally i like companies that are trending back into better times - i ssupect i am probably missing the point that their custoemrs probably just want a reliable brand name that they can trust not to have mass recall and i do see the need for reliable mid tier brand name suppliers to the main retailers and the like.
At present though i just think the competition will be tough - well done to management here if they deliver the growth in earnings thney forecast. Despite my reservations here i think if they do deliver as expected there could be some decent upside in shareprice here.
I must admit i am struggling to to thgink of any home appliance product that has taken the kicthens by storm as much as air fryers over the last 10 years (anyone who hasnt taken the plunge yet should do).
What’s an air fryer? ;-)
i think you throw chips in the air and they cook
I see Motorpoint (LON:MOTR) as a stock which is trending back to better times - something Paul listed as one of his considerations for stock selection. Small Cap, rather than AIM but down 6.75% today after a steady 100% rise.
Mortgage Advice Bureau (Holdings) (LON:MAB1) have resisted the dip and should make good progress as Zoopla recently reported highest level of properties listed for sale since 2014 and plenty of remortgages now rates may come down slower than forecast due to budget borrowing but 5 year (pandemic) and 2 year (Truss) fixed rate deals end putting borrowers on SVRs. I topped up recently.
For me Intercede is now too expensive but I am old school and buying anything over 20 time earnings is a bridge too far. This puts Beeks out of contention too. So that is 2 of my favourite cos over the last 2 years. The third is Warpaint and honestly if Trump gets in with his tariffs on all things China, the outcome could be difficult. Cosmetics are made in China across the board so relatively W7 could do ok but I don't see it as an exciting proposition and I think the current share price expects some performance from US. So what does look interesting, I like the tin argument and note First Tin raised £8m announcing it after hours last night. I like Uranium stocks but some growth has been factored in. Commodities are entering a new phase for me in a over populated and less Western dominated world. Unfortunately for me I have majored in AIM and this causes difficulties now but on the positive I agree Paul, a good company is a good company and they will find a place. I have long railed at private equity which lacks transparency outside of "I want everything". I hope higher interest rates will put a block on man kinds baser instincts. So currently I am over 50% cash. I may miss upside but I think this time it is different if Trump gets in. A reclusive America changes world capitalism. But you asked for stocks which for me is a useful discipline. Ashtead Tech, Spectra, H&T, Concurrent Tech, Niox (below 20 times) and anything defence I can get at a reasonable price. My boom or bust share (i know but I do like a gamble) Verici DX. But overall I think this is a time not lose capital. Now what happens to Sterling is another thing.....
Trump has actually proposed a 60% tariff on imports from China, a 100% tariff on imports from Mexico and a 20% tariff on imports from anywhere else in the world, including the UK.
Re Warpaint London (LON:W7L) if the US sales are imported via the UK, are they UK products as far as US is concerned?
Yes, a product shipped from the UK to the US would attract the 20% tariff.
AIM shares: Journeo (LON:JNEO) Volex (LON:VLX) Van Elle Holdings (LON:VANL) Brickability (LON:BRCK) Avingtrans (LON:AVG) Restore (LON:RST) Polar Capital Holdings (LON:POLR)
Nearly forgot Ramsdens Holdings (LON:RFX) . Gold price now in excess of £2100/ounce
For starters.
If you had the opportunity to buy any sound small cap share (let's say with a PER under 10; SCVR green or amber/green rating; and Stocko rating over 80 - there are a dozen or so which satisfy these criteria) with a 25% mark-down I can't see how you wouldnt go wrong over 5 years.
Jayman,
I have just had a Stocko price alert triggered for B.P. Marsh & Partners (LON:BPM) (>600p) and have doubled my position. Its share price is bucking the AIM trend by going up, the PE is 10.1, SR 99 and Graham is Green. B.P. Marsh & Partners (LON:BPM) also passes 12 Guru long screens, so all the stars align!
hi jonno
Ramsdens Holdings (LON:RFX) - I hold.
You have posted positively quite often recently regarding Ramsdens and the high gold price but remember that precious metals is only circa 25% of what Ramsdens do. Precious metals offers some protection due to the diversification of the business model but on its own is not so highly influential to overall performance and share price.
Pawnbroking, foreign exchange and jewellery & watches represent the other circa 75% so they all need to be trading well too in order to drive the share price upwards.
More importantly the elephant in the room is the likely increased staff costs to be triggered in tomorrow's Budget e.g. employer NI increase and minimum wage increase. Both will hit Ramsdens hard.
In addition there are several large shareholders who have been reducing their holdings i.e. Close Brothers (10%), Downing (10%) and Otus Capital (5%) which continues to keep the lid on the share price.
Finally, as Paul Scott points out today, retail is probably an area to avoid at the moment.
Plenty of food for thought.
Snazzy
Hi Snazzy
Some fair points. On staffing my impression is that Ramsdens Holdings (LON:RFX) runs a fairly lean ship, although I would need to do a little research to back up this view.
From the Pre-Close Trading update on 10th October
Peter Kenyon, CEO of Ramsdens commented:
"We're pleased with the record profit performance in FY24. All key income streams are growing and we have optimism for further progress in FY25."
"This performance once again demonstrates the strength of our diversified business model which underpins our long-term growth strategy."
This suggests to me that jewellery, pawn broking and FX are at least in-line, if not better. As for precious metals it must be going gang-busters given the gold price.
Despite all he doom and gloom there is much to like. The shares are very cheap, on a 5% plus yield and have cash on the balance sheet. Added to which the CEO, Peter Kenyon owns 3% of the shares.
The shares are AIM listed and selling by Downing and other investment houses is what I believe is keeping a lid on the share price.
Hi Paul,
Thank you for that AIM list. I have been looking at a few myself.
James Cropper (LON:CRPR) issued an in line update on 4/9. It's share price has been languishing recently. Today it has announced the appointment of the ex CEO of Zotefoams (LON:ZTF) as it's new CEO.
Fonix (LON:FNX) - would it's share price have recovered from the Irish gambling regs possible issue if not for the current AIM overhang
James Latham (LON:LTHM) - reasonable in line agm statement towards the end of August, recent fall back in share price
Renold
would be good to have some detail too, as to why you like Renold.
Generous management share options sparked a sell off in Renold (LON:RNO) (I sold too). RSI says Renold (LON:RNO) now oversold. Looks like a correction to me. I’ve bought this dip. It could go further but RSI very low and support at these levels.
YouGov (LON:YOU) in line update today any thoughts here Paul its not on you list
14th on the list
YouGov (LON:YOU)
yep i vote for yougov being covered too please.
I see the shareprice is up 10% today - this share has obviously been in the doldrums - note its gone from being a company with great balance sheet to sizeable debt (albeit with decent amount of cash) after 300 mill euro acquisition.
all that really matters to me is the outlook statement to see if they have turned the corner - copied below.
todays update is a joy of top level clever wording - thats not a criticism they have at least semi nailed their colours to the mast here. I can't work out though is they are quietly confident or they are in the same boat as Nero when he got his fiddle out (that didnt end up well)
So they talk up the prospects here and seem confident but it is the dreared h2 weighting - fair play here in that if they do warn later in the year we we clearly warned of the possbility and the reason is as simple as sales booking not picking up momentum as they hoped "might happen".
No idea which way this will go as to whether things do pick up as expected or remain subdued - but for now at least i am not convinced i want to be buying in here until the pudding is at least in the oven rather than then ingeredients still being in shop and management being in bed despite it being 9.30 and the party starts at 12! (q2 starts in 3 days)
Note one probably simply needs to have faith here if one buys this share - i suspect by the time they confirm that they will meet expectations the share price will already be higher - all i know is that others will have better idea of whether they are hitting current "high" targets or not than me. Not sure how reliable management are at delivering ? their old track record looked great - but i wander if it is a very hard area to forecast in - must admit not sure exactly who their customers are and how much cash they will have to spend (if anyone can advise that would be helpful)
Current trading and outlook
●
Trading for the current financial year is broadly in line with the prior year as expected, reflecting the slower sales bookings in H2 FY24.
●
Continue to see demand for our high-quality Custom Research data, while seeing longer sales cycles for Data Products subscription sales.
●
Sales bookings momentum is expected to pick up in Q2 and Q3 FY25 as we head into renewal season for our Data Products, supported by the launch of new products and features as well as an improvement in market conditions.
Van Elle Holdings (LON:VANL)
Acquisition of Albion Drilling looks a good transaction. Maximum consideration is £3.5m of which £0.5m is cash acquired, so maximum net cost of £3m.
For year end Jan 2024, Albion delivered revenue of £5.5m and PBT 0.8m. Van Elle Holdings (LON:VANL) assessment of the value of the assets acquired exceeds the £3.5m acquisition cost. Acquisition expected to be earnings enhancing in first year with modest cost synergies.
Albion Drilling strengthens Van Elle Holdings (LON:VANL) position in Scotland and in particular in the energy sector.
I hold.
jonno. Van Elle Holdings (LON:VANL) .
Watching the September Springfield Properties (LON:SPR) investor presentation (link below), they gave (between 11m18s to 17m) some colour on the significant investment in Scotland (£37 billion?) around renewables including significantly upgrading the grid, SSE building a couple of hydro schemes to act as batteries, building and civil engineering at Scotland's ports and offshore, new accommodation (predicted 8 to 10k jobs being created), projects already won by Balfour Beaty (who are already clients of Albion) and Bam Nuttal.
Sounds like having an increased presence in Scotland makes a lot of sense for Van Elle
(I hold both)
Which other companies could benefit?
Springfield Properties - Investor Presentation (Full Year results) - September 2024
Character (LON:CCT) share buy-back announced. I don't understand why they are stating that they will pay £2m for authority to purchase a maximum of 2,890,000 shares which equates to 69.2p per share. The price at the moment is 255p. I thought normally there is a floor set.
Character (LON:CCT) The 2,890,000 is the number of shares they were given authority to buy in the AGM. They already bought back over 700k so still allowed to buy back another 2m or so.
Bought back shares will be cancelled.
Diales (LON:DIAL) - "FY trading update shows group on right track" - link to new research note: https://www.equitydevelopment....
Diales has issued an update for the year to September, stating it traded broadly in-line with consensus expectations. This is encouraging, suggesting profitability was largely unchanged in H2 and in turn, higher EBIT margins. The delivery of the hub and spoke model is gathering pace and the group re-branding to Diales completed in July.
Net cash increased to £4.3m (H1 ’24: £3.6m) representing 26% of the NAV and leaves the valuation of the operating business at a significant discount to peers. Staffing related issues in the US have continued, resulting in the decision to close the office and we are encouraged by the Board’s rapid response.
Revenues increased modestly yoy to £43m, suggesting a higher proportion fell during the seasonally weaker H2 (48% vs 43% in H2 ’23), benefitting from a stronger Q3. Underlying EBIT is set to increase yoy to ‘not less than £1.1m’, highlighting a modest improvement in EBIT margins in H2, in part reflecting the cost savings delivered during H1.
Cash levels represent 8p/share and with estimates broadly in-line, we reiterate our fair value/share assumption of 40p.
RWS - stability in the result overall, no growth, but price suggest the market was expecting a lot worse.
ULTP - looks to be on track overall, nothing moves in a straight line. A well run business overall, particularly given it’s in a very competitive sector.
I am assuming both of these will be covered at some point - interested to hear other views.
My morning smallcap tweet: Bolt-on buying bonanza brings bottom-line benefits
Vertu Motors (LON:VTU) Foxtons (LON:FOXT) Van Elle Holdings (LON:VANL) Zentra (LON:ZNT) Diales (LON:DIAL) Iqe (LON:IQE) Proton Motor Power Systems (LON:PPS) Character (LON:CCT) Mycelx Technologies (LON:MYX) Touchstar (LON:TST) Permanent TSB group (LON:PTSB), Ultimate Products (LON:ULTP), Shield Therapeutics (LON:STX), IG Design (LON:IGR)
◄Vertu Motors (VTU)► buys Burrows Motor Company for an EV of £12.5m. Eexpected to be earnings enhancing in its first full year of ownership. [SP=67 Cap=224m]
◄Foxtons (FOXT)► buys Haslams Estate Agents and Imagine Property Group for total of £12.6m, plus £3.4m deferred. Will be earnings enhancing from FY25. [SP=59 Cap=179m]
◄Van Elle Holdings (VANL)► buys Albion Drilling for up to £3.5m, of which £0.5m is net cash acquired. Earnings accretive in first FY of ownership [SP=42 Cap=45m]
◄Zentra (ZNT)► gets £1.6m debt facility secured on property which it's selling. [SP=0 Cap=1m]
◄Diales (DIAL)► guides FY-Sept rev-cont up 1% and U/L op profit -cont of £1.1m+ (£1m). Will exit USA. [SP=25.45 Cap=13m]
◄IQE (IQE)► CEO Americo Lemos scarpers. He is not thanked. [SP=14.6 Cap=141m]
◄Proton Motor Power Systems (PPS)► wins follow-up order from DB Bahnbau for delivery in 2025. No £££. Funding discussions continue to remain relatively early-stage despite talks since Aug. [SP=0.6 Cap=10m]
◄Character (CCT)► £2m max buyback. [SP=255 Cap=48m]
◄MyCelx Technologies (MYX)► wins c.$1.5m REGEN order which helps to underpin 2025 F/C. [SP=38 Cap=22m]
◄Touchstar (TST)► warns FY-Dec rev miss. H2 rev will be broadly similar to H1's. Blames orders taking longer to convert and a significant order delayed to FY25. [SP=110 Cap=9m]
◄Permanent TSB (PTSB)► guides FY-Dec total income broadly flat, NIM c. 220bps, total operating costs are expected to rise by a mid single digit %. "Overall business levels remain encouraging and the bank expects new lending to increase further in the fourth quarter." [SP=1.59 Cap=909m]
In line: ULTP, STX, IGR
Ultimate Products (LON:ULTP) released FY2024 results which confirmed the company’s August trading statement at the sales, EBITDA pre-tax profits and EPS levels.
Detailed figures for sales by geographic region, brand, distribution channel and product category were published. Importantly, European sales advanced by 7%, moving to 34% of group sales from 30% in FY2023 as the company made significant advances with French and German discounters. This offset the negative impact of overstocking in the latter’s supermarket channels.
ULTP’s sales outlook for FY2025 is a return to growth. First, we expect a home market rebound as the company no longer faces the air fryers comparison issue. Second, there are clear signs that the Salter re-brand is working well and there will probably be some early benefits from a similar uplift for Beldray. Third, Europe should see further advances arising from the Paris showroom’s stronger sales into European discounters and more normal German supermarkets trading. However, the pattern of order flows suggests growth will pivot significantly towards the second half of the year.
We highlight UPs superior yield and attractive FY2025 0.8x EV/sales ratio. We continue to highlight potential for a material re-rating of the shares, driven partly by a return to positive sales momentum this year. We retain our 200p/share Fair Value.
Link to new research report: https://www.equitydevelopment....