Small Cap Value Report (Tue 3 Nov 2020) - ACRL, VCP, TCM, UPGS, WHR, OMG

Good morning! It's Paul here with the SCVR for Tuesday. Jack's busy with other stuff, so it'll probably just be me today.
I added more sections to yesterday's SCVR, finishing in the early evening, so here is the link for the full report.
PIWorld interview with Richard Crow ("CockneyRebel"). I've long admired Richard Crow, who's a brilliant investor, and an engaging, down-to-earth chap. His life story is interesting, and this video is chock full of straightforward investment common sense. I enjoyed it very much over the weekend, so I hope you enjoy it too. Highly recommended. I only ever provide links here to the best content that I've particularly enjoyed.
Agenda - this is what has caught my eye this morning -
Accrol Group (LON:ACRL) - significant acquisition, and placing
Victoria (LON:VCP) - 2nd lockdown comments & trading update
Telit Communications (LON:TCM) - 2 possible bidders
Up Global Sourcing Holdings (LON:UPGS) - Full year results
Warehouse Reit (LON:WHR) - Half year results
Oxford Metrics (LON:OMG) - Trading statement
.
Timings - TBC - I've started early, so there should be plenty up by 1pm official finish time. Then a few more hours to finish off everything else later this afternoon.
Update at 12:46 - I'm taking a break for lunch now, and a haircut, as I'm starting to look like a yeti, and with lockdown 2.0 starting on Thursday, this is becoming an emergency! So I'll be back about 2pm to finish off the last 4 sections above. Hence likely overall finish time about 5pm hopefully. I like to dig into the detail properly, which takes time, so thank you for your indulgences.
Update at 17:24 - today's report is now finished.
.
Accrol Group (LON:ACRL)
Share price: 45.0p (up 1% at 08:33)
No. shares: 195.2m + 87.5m placing + ?19.3m option shares? + up to 9.3m open offer = max 311.3m
Market cap: £140.1m (subject to change, depending on outcome of open offer)
I reported in yesterday’s SCVR about this company’s trading update. However, there has been a flurry of subsequent announcements, concerning quite a large (relative to ACRL’s market cap) acquisition, and a placing/open offer to finance it.
Acquisition & launch of ABB (accelerated book build) - when an ABB is announced, it’s nearly always a done deal - i.e. meetings have been going on for a few weeks behind closed doors, hence it’s little more than a formality to announce it. That’s why the books close so quickly after the initial announcement, as it’s buttoned up already.
Confirmation of successful placing - announced at 7am this morning. Key points;
- Quantity - 87.5m new shares to be issued in the primary placing (i.e. this is new money that the company will receive)
- Price - negligible discount, priced at 44p (very impressive, and shows strong demand, so the presentations from management must have been convincing)
- Secondary placing of existing shares (so no new money to the company) of 6.45m shares, from selling shareholders, cashing in some of their chips. This seems to be part of a share options deal whereby management get 19.3m new shares, and are selling 6.45m of them to fund the tax liability. That’s a very generous share options scheme, at almost 10% dilution of the existing shareholders.
- Brokers - this was managed by Zeus & Liberum, who’ve clearly done a good job, a decent sized fundraising, at negligible discount - which protects existing shareholders nicely
- Open offer to existing holders, 1 new share per 21 existing shares. I don’t really see the point of this, as open offers are only really needed where the placing is done at a discount, which this hasn’t been. There probably won’t be a big take up of the open offer, unless the share price rises strongly in the next few days, when it would make sense to take up entitlements for the instant profit.
Acquisition of Leicester Tissue Company - the announcement makes a good case for acquiring this well invested (modern equipment), rapidly growing competitor.
I’m a bit confused though, because the figures filed at Companies House for LTC, make it look as if Accrol might be over-paying for LTC. Consider these figures for FY 09/2019 (its 2020 figures mentioned in the RNS have not yet been filed);
Revenue £19.1m
Gross profit £3.62m (margin of only 19.0%)
Profit before tax £1.22m
Note that LTC's 4 Directors are only paid salaries of £100k in total, therefore to arrive at underlying profits, I would rebase those salaries to a more realistic level, of say £400k in total, which would reduce profits from £1.22m to £0.92m. Although the RNS says the vendors are leaving the business, and signing a non-compete clause. So this could be part of the £1m in projected synergy cost savings.
Net assets on LTC's balance sheet were only 2.43m as at 30 Sept 2019, and total fixed assets only £4.0m. That doesn’t come close to Accrol’s claim that c.£25m has been invested in the business. Unless huge additional investment was made in 2020?
I appreciate that Accrol is quoting 2020 figures, which are not available yet at Companies House, and that it says revenues are growing fast, but even so, the acquisition price looks very high when based on the 2019 numbers. So I question whether this acquisition might be over-priced?
The RNS says;
In the unaudited financial year ended 30 September 2020, the LTC business delivered revenue of £28.0 million, up c.44 per cent. on the previous financial year and adjusted EBITDA* of £4.5 million, up c.181 per cent. LTC's revenue grew at a CAGR of c.70 per cent. between 2017 and 2019.
Fair enough, revenue is up strongly on the 2019 numbers I’ve looked at. Quoting EBITDA isn’t much use, for a capital-intensive company. That said, the depreciation charge in LTC’s books was only £162k in 2019. So where is all this new equipment? It must have been installed in 2020, because there’s no sign of it in the 2019 accounts published by LTC.
How is LTC worth £35.0m plus possible £6.8m deferred consideration (based on earnings targets)? It seems to be based on new contracts, but certainly isn’t supported by the historic, 2019 numbers. My worry would be that recently won contracts might be temporary, and not necessarily turn into sustainably higher earnings. We’ve seen before how the supermarket customers shop around for the best deals, and have no qualms in dropping suppliers to get lower prices elsewhere.
Earnings enhancing? Accrol says;
The Acquisition is expected to be immediately earnings enhancing. Initial Consideration of £35.0 million representing an enterprise value / FY20 adjusted EBITDA* multiple of 7.8x before synergies and 5.5x when combined with the maximum Deferred Consideration (which is subject to new contract incremental EBITDA contributions of £3.1m).
Since the deal is being funded with substantial issue of new shares, then I’d be surprised if it is actually earnings enhancing on a per share basis. Time will tell.
My opinion - I’m a bit sceptical about this deal. The price being paid looks very high, based on historic numbers for LTC. So it appears to be based on new contracts won, or in the pipeline, for LTC. But how sticky are those contracts? Supermarkets aren’t known for their loyalty to suppliers, they ruthlessly drive down cost prices. Hence I wouldn’t place much value on any existing supermarket contract, unless it had binding pricing and long-term duration.
Still, the fact is that this placing was very well supported by institutions, who will have been given more information than is in the RNS. So maybe it is a good deal? Time will tell.
.
Victoria (LON:VCP)
Share price: 425p (down 2.5% at 10:13)
No. shares: 125.4m
Market cap: £533.0m
Comment on the Second UK Lockdown & Recent Trading
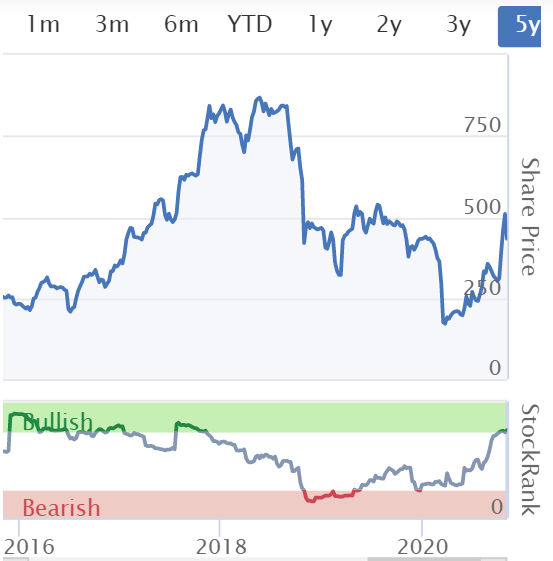
I like to keep an eye on this acquisitive floorcoverings manufacturing business, as it’s an interesting share. As you can see, the share price is volatile, with opportunities for traders to make money either way.
I think it’s good practice for companies to update shareholders on how they see the 2nd lockdown affecting business, and am surprised we’ve seen so few company updates so far.
Before that, I should also mention a partial refinancing type of announcement here on 22 Oct 2020. It has various elements, and is quite complicated. The main element is that an American investor is investing in Victoria (a continuing theme at the moment with UK companies attracting investment from there) Koch Industries (interesting Wikipedia page on it, is here), a large US conglomerate.
Koch’s investment is being structured as an initial £75m investment, and a subsequent possible £100m investment will be made via convertible preferred shares. These are a class of shares that rank ahead of ordinary shares, and receive a more-or-less guaranteed dividend of 9.35%. So conceptually it’s a bit of a hybrid of share & loans. Koch seems to be getting Warrants (to receive newly issued shares, at a price of 350p each) over 12.4m shares, or 9% of Victoria. It’s not clear whether these warrants are additional to any conversion rights over the preferred shares into ordinary shares, or not.
A deal has also been done for Koch & another investor to buy out existing shares held by Invesco, also at 350p per share. Victoria is also buying back 8.44m of its own shares, from Invesco, also at 350p per share.
My view - just on an initial quick review, this looks an interesting deal, raising rather expensive (9.35% annual cost) new funding, to make more acquisitions. It looks like stop-gap funding, which Victoria has the option to repay in future. Therefore I reckon Victoria is trying to get its credit rating improved, by making good acquisitions now, in order to then refinance the preferred shares using cheaper bond funding (which is the main form of existing borrowings, much more secure than bank debt, as it doesn’t have covenants) at some point in the future.
The Board of Victoria PLC (LSE: VCP) the international designers, manufacturers and distributors of innovative flooring, notes the announcement regarding the imminent one-month lockdown in England. Based on the Company's experience of the UK-wide lockdown earlier this year, the Board believes that, in the long run, this second lockdown will make little material difference to Victoria.
Or to put that another way, it is likely to have some short term impact!
All the Group's factories will remain open and continue to accept and deliver orders. Victoria's experienced management team intends to continue production throughout the next month, which is expected to minimise the impact of the lockdown on Victoria's UK business.
The Board believes the Group's liquidity position is strong and we expect to continue to grow at the expense of weaker competitors - particularly those with UK-centric businesses, that do not have Victoria's advantage of generating a very significant majority of earnings and cash from outside the UK.
Therefore, whilst the Group may not be as cash generative had the second lockdown not happened (with net debt therefore reducing slightly less), the Board expects improved profitability as we capitalise on the decline of weaker competitors.
Recent trading has been strong, although some of this must be catching up with pent-up demand from the earlier lockdown;
Trading in recent months exceeded the Board's expectations, with sales for the 3 months to 3 October 2020 recovering above both management's pre-Covid budget (which included the anticipated benefit of productivity investments made over the previous 18 months), and last year's levels. The Board believes this favourable outcome is a result of people spending more time in their homes and working remotely. This trend is encouraging increased investment by consumers in home redecorating, as well as driving new home purchases across all the markets where the Group trades.
Liquidity sounds fine;
Additionally, the Group continues to maintain a strong liquidity position and finished the quarter with cash and undrawn credit lines in excess of £200 million - up from £180 million as at 30 June. Shareholders will also recall that, despite the lockdown in all of Victoria's geographies in the June quarter, negative cash flow was just £7 million for the three months.
Guidance - still withheld;
It remains premature to provide meaningful earnings guidance for FY2021, although the Board looks forward to updating shareholders on 30 November, with the publication of the Interim Results for the six months ending 3 October 2020.
My opinion - this update today sounds reassuring, but it cherry picks the more positive Q2 numbers (July-Sept), but doesn’t give us the YTD numbers (April - Sept), which rather glosses over the lockdown impact. To be fair, it has provided Q1 revenue numbers before, but it’s a pain to have to manually add them up with the Q2 numbers, to get the overall total, that should have been presented in today’s update I feel.
The price in various transactions recently announced, was 350p. That to me sets a valuation benchmark for now. Hence with the open market share price being 425p, I feel that 21% premium is unjustified. I’d probably have a nibble, and add a few to my portfolio if it slips back down to c.350p, but am not interested above that.
There’s not enough earnings visibility at this stage, and it does have a lot of debt.
On the upside, I think the Exec Chairman, Geoff Wilding, has demonstrated a series of apparently successful acquisitions, and his decision to move nearly all the debt onto secure bond financing, just before covid, was a combination of genius, and lucky timing! This makes Victoria a lot more secure than other highly indebted companies, as it's debt cannot be withdrawn, as long as interest payments are made, and is long-term.
Carpets have done well this year, because people are revamping their homes. I forget which company it was, but someone in the sector said the other day that there’s a shortage of skilled carpet fitters at the moment in the UK, because so many people are wanting new carpets.
Overall, I’m often tempted to buy shares in Victoria, but haven’t quite managed to build up enough conviction to press the button.
.
.
Telit Communications (LON:TCM)
Share price: 150.4p (up 8%, at 11:15)
No. shares: 133.0m
Market cap: £200.0m
DBAY Advisors Ltd - Statement re Possible Offer
The company seems to be in play now, with 2 possible takeover approaches;
Telit Communications PLC ("Telit" or the "Company") notes the recent media speculation and confirms that it has received a preliminary approach from DBAY Advisors Limited, ("DBAY") regarding a possible offer for Telit to be made by funds under the management of DBAY.
Telit has also received a preliminary approach from Lantronix Inc, ("Lantronix") regarding a possible offer for the Company (the "Lantronix Proposal"). The Lantronix Proposal was considered by the Board of Telit, together with its financial adviser, Rothschild & Co, and rejected. However, the Company remains in discussions with Lantronix to explore a possible transaction which could be in shareholders' interests. The consideration for any offer, if made, is likely to be Lantronix shares….
For the purposes of Rule 2.5(a) of the Code, this announcement has not been made with the consent of DBAY or Lantronix.
Doing a bit of googling, DBAY is an asset management firm, with a very simple website with little information on it. It says they’re value investors, with the obligatory Warren Buffett & Benjamin Graham quotes on each page - rather unimaginative. I like it when asset management companies give biogs of their team, and case studies on their investments. There’s nothing like that on DBAY’s website.
Lantronix is listed on NASDAQ, but looks very small. There’s a StockReport for it here, showing market cap equivalent to only £92m, so it would be a reverse takeover, if a deal was done with Telit. Maybe this would be a way of Telit getting a NASDAQ listing? Lantronix doesn’t look credible as a proper bidder, so I imagine the DBAY potential bid looks more likely, as a financial buyer.
The above is probably why the share price has only gone up 8% today, as they don’t look particularly exciting bidders able or willing to pay a large premium maybe?
I’m not keen on Telit. I didn’t like the way it presented its accounts, aggressively capitalising costs onto the balance sheet, when I looked at it a few years ago. Things might have improved since then, but for me it I don’t like the accounts, then it just goes in the bin for me as a possible investment.
.
Up Global Sourcing Holdings (LON:UPGS)
Share price: 93.5p (down 8% at 13:59)
No. shares: 82.2m
Market cap: £76.9m
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces its full year results for the year ended 31 July 2020.
The share price has closely tracked broker forecasts this year. In the early stage of the covid pandemic, investors sold off this share because of China supply chain issues. That got resolved quite quickly.
Worries about UK retailers buying less stuff from UPGS also turned out to be wrong, as the company continued selling well, and grew its online presence to help compensate for other lost sales. So it’s been an impressive performance, which we’ve kept abreast with via frequent trading updates. Therefore there should not be any surprises in today’s numbers.
.

..

.
Key points from FY 07/2020 results;
Revenue down 6% to £115.7m - a very creditable performance in my view, given the massive disruption from covid/lockdown
Underlying profit before tax down only 2.7% to £8.2m - again, I’m impressed
Underlying EPS down 2.5% to 7.9p - a PER of 11.8 (93.5p divided by 7.9p) - seems reasonable value to me
Dividends - final divi of 2.795p, giving a total of 3.955p for the year, a healthy yield of 4.2%
Balance sheet - looks fine, with NTAV of £13.3m. I wouldn’t call it strong though, it’s perfectly adequate. Remember that fixed assets are modest, so it doesn’t need a huge balance sheet.
Net debt - drastically reduced to just £3.8m. This has been achieved from positive trading cashflow, and favourable working capital movements (inventories down, but trade creditors up). There might be an element of favourable timing differences there, in that working capital movements can sometimes reverse in the following period.
There’s plenty of headroom £21.3m, on the bank facilities
Repaid furlough monies, and also up-to-date with PAYE and VAT by year end, so there doesn’t seem to be any creditor stretch, good to see
Cashflow statement - all looks fine to me.
Overall - these seem clean numbers, with minimal adjustments, so I can’t see anything untoward in the numbers. The company is financially sound, and I don't see any insolvency risk here at all.
Outlook - sounds fine to me, in the circumstances;
The market conditions for general merchandise remain challenging in the UK and Ultimate Products, like many others, is faced with an uncertain environment for consumers, retailers and suppliers. Despite these challenges, the Group has delivered a good set of results for FY 20 through a relentless focus on our strategy and the talents of our colleagues.
While the conditions in the UK and Europe look set to remain challenging, with further lockdowns now announced, current trading is in line with expectations with the FY 21 order book ahead of this time last year. As such, the Board remains confident about the Group's future prospects.
My opinion - this is a simple business to understand - it imports smallish consumer goods, and sells them to retailers at a modest gross margin of 23%. By having a low cost base, that translates into healthy net profits.
The valuation seems quite cheap, a PER of 11.8, plus you get a healthy dividend yield of 4.2%. Those figures are based on a hugely disrupted H2. Therefore I think it’s reasonable to imagine that future years’ performance could improve.
I think UPGS has demonstrated excellent management of the very difficult situation this year. That gives confidence for the future. Things haven’t always been plain sailing in the past, so I wouldn’t want to chase this share price too high, but where we are now at 93.5p, I think it looks good value.
.
Warehouse Reit (LON:WHR)
Share price: 110p (up 2.3%, at 15:40)
No. shares: 379.3m
Market cap: £417.2m
Warehouse REIT, the AIM-listed specialist warehouse investor, today announces its results for the six months ended 30 September 2020.
Robust financial performance with strong valuation uplift
I’ve mentioned this warehouse property REIT before, as a very interesting niche to invest, both providing a decent flow of dividend income, and relative safety in the current storm.
Earlier this year I looked at retail property REITS, Hammerson (LON:HMSO) and Newriver Reit (LON:NRR), and more through luck than judgement, I managed to catch a big move up in HMSO on a short squeeze, thankfully banking the profits, because HMSO in particular has been a complete disaster since then, as Jack reported here earlier this week.
The reason being of course that conditions for retailers have worsened so much, that CVAs and Administrations on a mass scale now seem inevitable. Hence geared retail property REITs have seen the value of their assets plunge, voids increase, tenants often not being able to pay the rents, etc. It’s just a hideous sector, and things have got a lot worse than I realised they would earlier this year. Asset values look set to continue falling, but the debt doesn’t fall, which squeezes equity down to a point where, as we saw with INTU, in the worst case scenario, the equity ends up worth nothing.
Warehouses are very different though, a few key points;
- As consumer demand shifts online, the demand for warehouses is rising, not falling
- Availability of warehouses is falling
- Rental yields are improving (going down) as investors are cottoning on to this interesting niche, thus driving up capital values for owners like WHR
- Tenants are paying their rents, mostly
- Rents are rising on conventional leases, when 5-yearly rent reviews occur
- WHR is continuing to pay divis, paid quarterly - ideal for income seekers, such as pensions in drawdown
- Properties are actively managed, with development potential being exploited
- REITs are exempt from Corporation Tax, provided they pay out 90%+ of profits as divis - making them good to put into a SIPP
- Share price of 110.5p is below EPRA NAV of 118.4p, which strikes me as decent value
- In a low, zero, or even negative interest rate world, a yield of 6.2p target for this year, divided by share price of 110.5p is 5.6% - good, but remember that there could/should also be a kicker of modestly rising share price in the long term, as asset values appreciate.
- Recession-proof so far, because there’s a structural shift in demand for warehouses, and away from retail space
- Good, solvent tenants - e.g. Amazon is lead tenant, with 11.3% of the rent roll. Wincanton another one.
- Tenants are mostly eCommerce, and logistics businesses
- Raised £153m of fresh equity in the period
- Low gearing - Loan To Value (LTV) was only 20.2% at period end. Target is a maximum of 35% as more assets are acquired. This seems prudent, given that capital values are rising, not falling
- Properties are managed professionally by Tilstone. Management fees don’t strike me as excessive
NAV rose strongly in the 6 months to 30 Sept 2020;
EPRA NTA per share at 30 September 2020 was 118.4 pence, up from 109.5 pence per share at 31 March 2020. The primary driver of the 8.1% increase in the period was the strong valuation uplift, which reflected a like-for-like increase of 6.6%, in part reflecting the like-for-like growth in rents and ERV in addition to yield compression, driven by the strong investor demand for the sector. There was also a smaller benefit from the timing of the payment of the first interim dividend, which was paid shortly after the period end.
My opinion - I really like this share. It’s not one I currently hold, as I’m targeting more rapid capital appreciation, not income. But when I day-dream about how my strategy might change once I hit £10m+ with my personal portfolio (not likely any time soon, I hasten to add!), then this is the type of share that I would switch into, for decent income, and a good kicker from capital appreciation too. What do readers think of it?
.
Oxford Metrics (LON:OMG)
Share price: 75.5p (up 2%, at market close)
No. shares: 125.7m
Market cap: £94.9m
Oxford Metrics plc (LSE: OMG), the international software company servicing government, life sciences, entertainment and engineering markets, provides the following update on trading for the financial year ended 30 September 2020.
Very clear information here;
The Group expects to report revenues of £30.3m and an Adjusted PBT* of £2.5m for the financial year.
The Group finished the year with a strong cash position of £14.9m and no debt.
How does that compare with broker forecasts, and last year’s performance?
It looks a long way short of the forecasts shown by Thomson Reuters, but with only 2 brokers reporting, it could include an out of date number perhaps? So I’m going to ignore that.
Unfortunately, there’s nothing recent available on Research Tree either, so I’m largely in the dark here.
Looking at the split between H1 & H2, it shows a good improvement in profits, in H2;
H1 Revenue £15.3m, Adj PBT £0.3m
H2 Revenue £15.0m, Adj PBT £2.2m
FY Revenue £30.3m, Adj PBT £2.5m
(manually calculated by deducting interim results from FY results)
Outlook -
The Group's fundamentals remain strong, supported by an encouraging pipeline of opportunities across both divisions and a strong balance sheet which together underpin confidence that the Group will continue to successfully navigate current challenges arising from the pandemic.
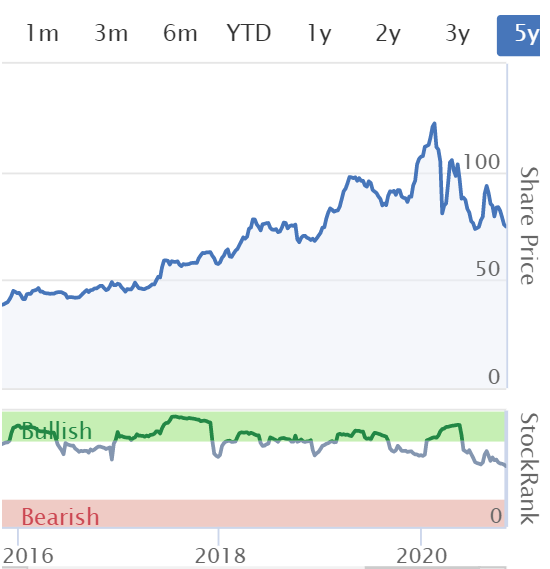
My opinion - based on these numbers, I cannot see how a £94m market cap can be justified. Nowhere near that actually. Therefore, the share is clearly being priced on hopes that profits should recover.
To me, this share price looks vulnerable, if the company cannot demonstrate a significant improvement on the FY 09/2020 numbers reported today.
.
.
That's all I can manage for today, sorry there wasn't time to look at Senior (LON:SNR) - maybe for another day, if people are interested in it.
See you in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
i appreciate you are not keen on Telit and given the history that is not a surprise. How do you square this view with the very high stock ranking ratings Stockopedia gives it ? this would be educational for me in understanding how much weight to give the quality, value, momentum, Stockrank ratings .
Sure, how does £1,000 per day sound for a private research fee?
Well , you work for Stockopedia, i pay a fee. Isn't this the commercial arrangement ?
So how do you square very high Stockopedia ratings with your dislike ? Seems a straightforward question to me as a beginner and a customer (although perhaps not for long at this rate) and didn't warrant a waspy sarcastic reply
Warren Buffett says something like "Praise by name, criticize by category". That's the safe option, but if the evidence is clear, ignoring Mr Buffett's advice & using names seems fair.
On Twitter and other outlets, investors are usually bullish about what they own. To a large extent, this is to be expected, as if someone isn't bullish on a stock, they shouldn't own it.
In other cases, Twitter comments go beyond that.
Then there are a small number of Twitter experts who made all the right trades a few months ago, but only ever post these long after the stock has gone up.
Fortunately, we are all adults and should be capable of filtering what is written. The occasional reminder, as in the post by Andrea also does no harm.
Be great if you can slot in Senior (LON:SNR) at some point @Paul. I have a small holding and am very interested in your expert analysis of them. Trying to decide whether to keep them for the long haul or cut my losses and take the £ into another in my portfolio. I was in around the 69p mark but its been in the 50's for a while now given the pandemic.
The two £TCM bidders are definitely underwhelming (I hold - basically because I think the share is very cheap, if I believe the numbers, which given the history of Telit is a big if). A reverse-takeover by Lantronix would presumably import the Lantronix management into Telit, which would be odd as Telit has totally changed its board and management following the scandals of the past and with Paolo dal Pino now has a CEO with significant experience at large multinationals. Dbay (which in the summer bought a 10% stake), as a financial buyer, would be a price sensitive buyer.
I think if shareholders had been hoping for a bid, they would have hoped either for a bid from the group's largest shareholder the Chinese Run Liang Tai group, whose CEO is on the board, or from one of Telit's competitors, like Sierra Wireless. The reason presumably Telit had to produce this morning's statement was that yesterday a financial site Betaville (I had not heard of it before) said that Dbay and Sierra Wireless were among 3 interested parties "circling" Telit. From this morning's RNS, the Sierra Wireless interest would not appear to be substantiated.
One of the complication's for anyone trying to takeover Telit is the very unusual shareholder list, as it is almost devoid of traditional institutions (apart from Brandes). There are a number of hedge funds - or ex-HF principles, like Davide Serra and scandal-hit former CEO Oozi Cats remains the second largest shareholder.
People listening to the PI World interview with R Crow need to be aware that, whilst as with all PI interviews there is some good & interesting listening material, C Rebel performs a significant amount of ramping of his own stocks on Twitter. This is not only my opinion, I have also had it said to me by investors much more successful than I.
This ramping will take the form of frothy comments, sometimes several times a day, on a positive price movement, the purpose of which seems to be to talk the price up and up. If the price drops then he'll suggest it's an ideal opportunity for bargain hunters to pile in. This will often occur significantly before an RNS is due on trading and/or results, but once such RNSs are out the way then all goes quiet, particularly when the share price falls back sharply afterwards. He will often not make even a single comment on these RNSs, especially when they contain negative news. I have never seen him reveal when he has actually sold anything, but I think it is safe to say that there is an amount of selling going on for good, quick profits. He also has a private chat room with over 250 users, quite a few of which I'm sure also ramp some of these stocks. And rather than respond to ramping accusations, he will simply block those making them from seeing his feed (such as me).
A spectacular ramp I noticed was of Safestyle UK (LON:SFE) coming up to its recent results, with the price talked up from early-30s to over 55p only for the price to dramatically fall once the results were out; it now sits at below 30p. Stocks falling under this ramping regime include Xaar (LON:XAR) , N Brown (LON:BWNG) , Purplebricks (LON:PURP) , Ted Baker (LON:TED) , etc.
From a general point of view, please do your own research on stocks and don't blindly buy those that are talked up by, sometimes, high profile FinTwits. It's a vicious world out there, I'm afraid, you don't know the agenda of those Tweeting, and in particular when they are buying or selling.
Hi Andrea,
I don't know the gentleman - only came across him from the PI world interview, but based on what has happened thus far, I tend to agree with what you have to say at least so far as twitter is concerned.
Interestingly, I did "show the wife the directors" he proposed with him & let's just say she wasn't all that enamoured.
He isn't very quick to respond if you disagree with him, unlike many PIs who I think appreciate an amount of devil's advocate
I think that's very harsh, andrea34. You've obviously fallen out with Richard, as you say. Despite your reservations, I still think it's a fascinating interview.
Over the years, CockneyRebel has mainly invested in mid caps actually, where bulletin board or twitter chat wouldn't have any significant impact either way. I've found he talks a lot of sense.
Anyone who blindly follows anyone into stocks without doing their own research, is a nitwit, surely?!
Paul.
Paul,
It's completely incorrect to say I've "obviously fallen out" with CR. I made a single reply to ONE of his Tweets accusing him of ramping on a day when he had repeatedly Tweeted price movements on a stock and when I pressed him after his suggestion that I unfollow him he blocked me.
Where have I "actually" suggested that he invests in small as apposed to mid cap companies? The ones I have mentioned are simply those that I (and others) have seen him plug in recent months. Additionally, never does he say in any Tweet whether he holds... though I got him to admit (before I was blocked) that I should "assume that anything he Tweets about price movement he holds" - by deduction, if he is repetitively Tweeting on only his own stocks then he's ramping. This is in particular surely true when he has such a big following. As you are no longer on Twitter then you would not see this.
In my post I also said "from a general point of view" people should not follow others but do their own research, so I don't know why you have tried to manipulate my comments as though they are purely directed at R Crow or only high profile investors.
It is extremely important that people know there is such manipulation and dishonesty on social media. As such, I think you should be a bit less aggressively defensive.
My comments in no way detract from the quality of Tamzin's interviewing, which is always very high (as I indicated).
Andrea
Andrea does raise an extremely valid point, not just specifically about one person, but FinTwit in general.
I can't say that I know too much about CR but there is some blatant and very aggressive ramping going on with regard to some specific shares, most notably the Covid stocks. Novacyt SA (LON:NCYT) would be a prominent example, where a certain well-respected PI has been subject to some extremely unpleasant tweets. Any dissenting voices are instantly shot down, I don't think they've ever heard of "confirmation bias".
I used to check Twitter, just to look for any counter-arguments when thinking of buying a share, but I now stick to following a few people I know and trust and am using mute a lot more now I've found it.
On the other hand, the interviews from piworld are a fantastic resource for the private investor and I've appreciated them all.
Personally I'm glad we have professional investors who are willing to shed light either on the stocks they buy/sell or how they think, even if you do consider it 'ramping'.
If it weren't for Paul (repeatedly) providing the bull case on BOO a few years ago, I'd have missed out on a 10-bagger. Similarly I've made a lot of money from other well known investors, including Richard, highlighting stocks I'd have otherwise overlooked.
I've also lost money on highlighted stocks which went south, but I'm the only one in charge of the buy & sell button and the only one responsible for that loss.
People who talk about the stocks they own have no responsibility to provide updates on when they sell, when their opinion might change or anything else. I'm not sure where that sense of entitlement comes from. You're not paying them for advice, are you?
The investing community is a mixed bag. Some day trade, some are LTBH, and some use a mix of styles. It's our own responsibility to read the information provided and understand why we are buying and have our own exit strategy, rather than assume that your own strategy is the same as theirs.
Finally, I suspect people like Paul are paid to talk about stocks in general terms, including ones they own and ones they don't, but that doesn't apply to most investors, who are far more likely to only discuss the ones they hold. I'd find it odd if that were not the case.
Well said Andrea.
I like Tamsin's honest broker style so no criticism there but then am amazed that no one has mentioned Cockney Rebel's inability to recall any investment failures. Mine are etched into my mind!!!
There's just a sheer invincibility about it all; selling their own book - no failures/sells ... For every "Future" being plugged as a success through that "network" there is a potential "Altitude" stock which is conveniently ignored!
Richard Leonard was exactly the same in his interview. He talked quite correctly about never "falling in love with a share" - and then he talked about some of his holds with potential for "google taking them over", "molins talking them over, "GSK taking them over" etc.
DYOR!
Well said! And thanks to Andrea for broaching this topic. I don't do twitter (life's too short) but I do look at advfn for many of my UK holdings (the beauty of that site being there's a separate board(s) for each stock, unlike Stockopedia where it's hard work to sift out comments on multiple historic threads). It's a similar story there. 'Pedestrian' steady/staple stocks (eg the housebuilders) may get one comment every week or two (except at announcement time) while the rampy/spivvy 'hot' stocks are now essentially a waste of space with 200-300 meaningless posts each day. They're actually quick to read because 99% of the posters are filtered - it's just a pity they appear at all! Most of my large losses have been in such stocks. There's a common pattern - a cheerleader spouts on about fantasy numbers and his (invariably a 'he') acolytes join in the ramping ('can't wait for tomorrow's RNS' and similar wishful thinking). Anyone who posts a remotely cautionary view is immediately denounced as a 'shorter' (aka traitor!).
The whole thing is quite laughable but I understand that advfn hasn't the resources to moderate. For large caps it has no effect (amusingly the Boohoo (LON:BOO) thread which our very own Paulipilot originally set up is now the worst example!). But for small caps I suspect there can be enough money involved to influence the share price - used to be called pump and dumpers. That's why I went short-term negative on Novacyt Sa (LON:NCYT) a couple of weeks ago - everyone and their dog was talking about it which meant it was almost guaranteed to fall sharply at some point, as short-term punters were disappointed and stampeded en masse to the next hot covid stock.
I've also seen talk of a ramping/de-ramping 'ring' on advfn where posters act in concert, possibly with multiple id's. JacKnife was one name I was warned about; I've forgotten the others. Sometimes a poster will try to impersonate someone else, using a name just one letter or digit different - childish in the extreme.
As ever, caveat emptor! Don't follow the lead of anyone you don't know personally or have observed over several years.
Anyway, back to RC. I was intrigued by the interview. Largely because I knew his late brother, Bob, in a professional capacity. Bob was on several fronts my favorite client - hugely unconventional, very sharp, marmite-like, intensely focused when it suited him (but at other times had the attention span of a gnat), loyal to his friends and allies, but a contradiction in many respects. He always had a live stockmarket news feed running in his office, which seemed incongruous. We were given to understand that his brother (RC) 'was a stockbroker'. So when I watched the interview, and saw the family and vocal resemblance, the penny suddenly dropped! So RC is indeed a successful PI, who's learned from the school of hard knocks, but is no way a fund manager or 'investment professional' in the sense of having formal training and qualifications or FCA accreditation. (Actually I do think Tasmin should stress this point at the start of her interviews; perhaps she does.) Sorry for this long rambling, but a funny old world, isn't it!
Interesting and fair points.
In fact I used to pretty much ignore ADVFN boards but I actually realised that the filter tool is extremely valuable and now those boards are my primary initial tool to identify opportunities (quiet unloved boards in particular). If I miss out on something, so be it as that is all part of doing it yourself. Additionally I do view twitter but purely to see whether companies are hot or not, especially promoted by the obvious blowhards/sites.
I only wish you had opportunity to filter on this site as there is so much noise (short-termist especially) on here now (covid anybody? and, for me though I recognise that others will disagree -charting/trading mechanisms sometimes promoted with a "product" in mind) complicated by the open nature of each conversation (and maybe this message contributes to that so apologies if so)....
The whole thing is quite laughable but I understand that advfn hasn't the resources to moderate. For large caps it has no effect (amusingly the Boohoo (LON:BOO) thread which our very own Paulipilot originally set up is now the worst example!).
What's ironic about it? I experimented with setting up a thread on advfn years ago, and quickly realised it was a waste of time & energy to police a nest of vipers, so abandoned it.
I'd say watch the PIWorld interview at 18m timeline. I don't know many punters that give a warning like that when they mention shares they like and if that isn't clear enough for you you are hard to please
Andrea
I found the PI world interview with Richard very interesting.
Whilst Richard may suggest stock, I agree with Paul that it would be unwise to follow anyone blindly. Before buying anything, best to do some research of your own.
Personally I have invested in a few things Richard drew attention to - a few I have lost on, but overall excellent returns, most notably via taking a stake in FUTR that has gone from £3.50 to just shy of £20.
Yes, totally agree with you DYOR, and don't trust or blame the bloggers, vlogger, and twitterer's.
BSV
Hi All,
I'm a great fan of the SVCR and find all of the analysis extremely helpful. I also enjoy reading the discussions in the comments too, which also contains lots of great contributions.
I'm a fan of using heat maps to help focus my attention, so I thought I'd contribute a heatmap of what is 'interesting' in the SCVR world today.
The three bonus items at the bottom are the names that Paul has covered today.
Here's a key to explain what's on the heatmaps:
Cheers,
Greensiax
JIM for example say -69% for 1 month price change?
Jarvis Securities (LON:JIM) has recently had a 4-1 share split
Good addition to the SCVR! Wondered if you’d be able to post this up early morning in the comments to compliment the posts from Dan HollandSmith & Mr Contrarian?
Anybody know what is going on with XLMedia (LON:XLM) this week.
This was about 23p last week, surging +21% today to 32p currently. Above average volume.
No RNS on Stocko so far.
For me, I break even @38p, current sell trigger @50p.
It was a buy in ShareWatch at the weekend
Re, XLMedia (LON:XLM)
Interesting. I wonder what it said to get investors so enthusiastic?
Subscribe to find out !
Up Global Sourcing Holdings (LON:UPGS) -> A stock that has been quite well liked but imagine that some are fatigued by it and there are many non-believers viewing it to be a mere import reseller.
Its probable that today's outlook indicates that they are trading quite strongly even if they downplay it. If I parse historic numbers and announcements that they say FY21 is trading ahead of this time time last year. That could be really quite (maybe very) bullish relative to current expectations. A summary of why:
So assuming that FY2019 was steady-state-ish then FY2021 could be tracking as much as c.£5m head on H1 2021 and perhaps momentum into FY2021 results too...so add a a few more £m on FY. The 'surprise' could be considerable.
The language of the outlook is cautious and that is general UPGS style. This seems to provide a lot of room for poor trading.
An other positive factor is that they have traded and recovered well post lock down. This may create positive follow on momentum in that customers see them deliver during tough time. The bug is probably a decent situation for them in that they are budget-quality as a niche....John Lewis stuff at Asda prices.
Online business has also taken a step up during covid and that makes them more robust.
So FY2020 saw two significant hits the the business: 1) big german loss and 2) covid...yet still came close to prior year strong performance (it being a bounce back from FY2018 tough trading....UK general thing). Covid particularly hit discounters in Europe as they were viewed to be non essential retailers
So the hints are of good to very strong momentum. There's always period on period volatility as they do not have forward agreements with retailers...but the good side of that is that they protect their margin much more as they are not co-opted into the retailers margin management.
Strategically, looking through volatility and observing how they have traded it looks like there is significant upside surprise to results which would likely be enhanced by some multiple expansion.
I hold & indeed a lot of what you say above was reflected in the management call. I believe one of the quotes was "if you find our products in John Lewis, we are doing something wrong"
Also, not to be a fuddy duddy socialist (I assure you, I am a free market capitalist, the likes of which would make Steve Baker shudder), but it is a company that I enjoy owning because of how they operate. Living good governance / ESG and making this part of the shareholder proposition (as opposed to some checkbox).
Financially, I think this is one for the patient investor - they have a clear strategy for how to grow. Mgt seem to know what they do and learn from their mistakes.
There are risks with any investment & this is certainly not without those - for me customer concentration is a particular issue as evidenced by the German discounter & the fact that some 30% of sales are with two customers give or take - I like that it is coming down, probably as there is greater sales online now.
The company offers decent (not spectacular growth), is cautious & good management with lots of skin in the game and a well covered dividend. Some income, some growth & positive community impact - what more could one reasonably want from a passive investment.
Vshiv I'm shaded left as our central societal conundrum in democratic West IMO is ensuring majority feel decent about quality of life despite the majority economically being 'failures' (in business and general competitive activities there isn't room for everyone to win) if we wish to maintain a semblance of a society we quite like (free, open, etc). But I'm not socialist as socialism is dead, as it won the political war before last. Its now a romantic notion that some people can't let go of...but on to Up Global Sourcing Holdings (LON:UPGS) rather than politics before I get down vote hammered....
Growth has been more than pedestrian. Over 5 years to FY19 revenue had tripled. Obviously, as shareholders we are interested in time since IPO most and the growth so valuation perspective is skewed by a blowout FY17 followed by a blow-up FY18. To some extent FY18 was a hangover from very successful FY17 particularly with discounters (B&m European Value Retail Sa (LON:BME)). Then there was also a general broad based retail hiccup in FY18 that saw UPGS customers be more cautious on stocking. So if we take a bit from 17 and give to 18 for a bit of smoothing the progress is perhaps a bit more pleasing.
I listened to management call too. Interestingly Simon Showman CEO stated (I need to listen back to be 100% sure) that in next 18 months he believes Europe/Germany will be 50% of revenues! Assuming the rest stay flat he's saying £150m sales run rate in FY22. He also thinks that after Christmas they will need to raise their target for online sales above 20%...so at least £30m from that going forward into FY22...I don't think they expect their other trade to fall away either (particularly the supermarket segment).
Of course Showman is the entrepreneur and inherently optimistic and I don't run with these assumptions. Andrew Gossage MD is much more cautious and will not promote targets like that in meetings. Let's see where they get to but clearly the internal business belief is quite ahead of the market expectations.
Please, call me Vivek.
Wish I could avoid the subject but point I would make is that not all free market capitalists are bad.
When I say a free market capitalist I don't refer to the (direct) primacy of shareholder returns.
I am accutely aware that when a company needs more sales, it asks customers & more productivity, it asks its employees & more roads, it asks its government.
Carnegie starved his staff to maximise profit, built libraries all over the country to create a generation of innovators (among other things, but let's stay positive!).
Apple rented one of those erstwhile public libraries to create a store that is 100% renewable. You can enjoy the renewable power of you are willing to drop a grand on a phone.
Leave for others to judge, neither is right but when looking at extreme outcomes, I think the former is better for society at large.
I speak to bar staff at J D Wetherspoon (LON:JDW) - they like their job, they like being valued, they like the shares & they like that if they work hard and do well - they move up the ranks quickly.
I can't think of anyone at Tesco who speaks that highly, albeit Tesco has an independent and likely more diverse board.
Best,
vivek
Vivek, I don't believe that free market capitalist or people on political right are bad. My observation is that they are often more practical and hands on in their input to society and dare I even say in their effective ' progressivism and liberalism'. I find much about the left to be odious and too much whinging too...obvs the right has its share of negatives too. I think moral divisions between left and right are nonsensical. My issue is one of strategy...I think the right is in a super damaging doom loop whereby it views the national finances like a household budget (insane and highly restrictive and damaging!) and believes that cutting social costs (including low skilled labour costs) powers competitiveness (bonkers!).
I do not believe there is any such things as a 'free market' nor has there ever really been one. The UK created the free market concept in 1800s as we know it as it suited its hegemonic position globally. Countries of means (US, Germany) did a China and undercut where they could...those without means were subjugated by someone. Obvs a super simplification.
J D Wetherspoon (LON:JDW) is great even if the owner can be as mad as an ar*e full of smarties at times ;)
double print! Ignore
I'm a bit late with some results geeking on Up Global Sourcing Holdings (LON:UPGS) but for anyone tuned in here's some additional longer term focused data that supports my post on results day that underlying momentum is strong:
Cumulative revenue growth CAGRs by category (reporting year first broken out in data) + [2020 %age of total revenue]:
Total 14.0% (2014) [100%]
UK 9.2% (2015) [64.0%]
Europe 30.9% (2015) [35.2%]
Germany 99.1% (2016) [9.5%]
Europe ex Germany 15.7% (2016) [25.7%]
Supermarkets 51.7% (2016) [24.3%]
Discount retailers 3.7% (2016) [38.6%]
Online 56.3% (2016) [14.4%] (& note that in H2 2020 was 18.8%, expected c.20% H1 2021)
Premier brands 27.6% (2014) [69.9%]
Other key brands 8.6% (2014) [14.3%]
Other (lesser) brands and own label -4.5% (2014) [15.7% -> from 45.5%]
Its interesting to note that the only categories to report positive absolute YoY growth in every year (so including poor 2018) are Supermarkets, online and Germany. Obviously, there's a base effect in that these three categories came from lower levels.
As UPGS do not have forward sales agreements with customers there can be year to year volatility but the cumulative total sales is good with some very strong underlying areas that have now become significant parts of their business -> ie supermarkets 24.3%, online approx 20% post pandemic and Europe 35.2% (note there is some overlap between supermarkets and Europe).
The reduction is other brands and own label is a representation of the move up in quality by the business. The high percentage of total sales back in 2014 of 45.5% represents a time when UPGS was more vanilla important business and opportunistic acquirer and trader of clearance stock. The reduction in significance of discounters also illustrates the improved quality of business.
I don't think its sensible to extrapolate any of the above numbers and there is always a danger that a category goes bad (eg they have some big discount clients).
UPGS is a super organic growth story. To date the figures support a view that management are really on it. With areas like Europe, Online and Supermarkets now so significant in overall revenue mix its possible that overall growth accelerates a bit from here. If it moves to 20% from 6 year cagr of 14% that would be very impactful.
Paul, Jack, thanks for your mamouth reports yesterday and today. I’m finding them excellent.
Any chance of a comment on Pressure Tech Paul. I have never invested but cannot help but feel it will offer an opportunity at some point hence my interest. They should benefit and their Chair notes they are winning, Hydrogen contracts which is fast growing. BUT meantime they are losing Oil and Gas contracts. Cannot decide and any thoughts most welcome.
Hi Camtab,
I decided not to cover Pressure Technologies (LON:PRES) today, because it's so small now & illiquid, and also operates mainly in a very tough sector, so I thought it better to spend my time today on other more interesting companies.
Sorry about that. If you think it's got amazing recovery potential, then I could be tempted to look at it on Friday, when it's quieter.
Regards, Paul.
Thanks Paul. It would take a better investor than me to make the recovery story for it. However it does feel given the increasing focus on Hydrogen to be in the right sort of place. I expect oil and gas will continue to provide revenue for some years and I think I am right in saying there are only 5 global companies can make cylinders to the spec PT can. Their b/s isn't great but defensible. PE down at 4.5. No Divi. Management? I think it could be interesting. Could be too early. I don't know what it takes to tempt you Paul, if you have time on Friday be great but if not no worries quite possible we can have the same conversation in 6 months time.
This may be unfair based on a whole five minutes of research but Pressure Technologies (LON:PRES) look to me as if they are better engineers than entrepreneurs. They ought to be able to command some sort of premium pricing for their expertise but there's an awful lot of red numbers on their Stockreport.
I agree the hydrogen storage business is the potential that stands out even though it only amounted to £700k of sales in 2019. Must be a possible takeover target for that expertise alone? Meanwhile they say:
"We remain in constructive and supportive dialogue with Lloyds Bank regarding the amendment and extension of the Group's Revolving Credit Facility (RCF)."
Paul
On Accrol Group (LON:ACRL) you say "Still, the fact is that this placing was very well supported by
institutions, who will have been given more information than is in the
RNS. So maybe it is a good deal? Time will tell."
If that happened, why isn't it insider trading?
A very good question there FREng.
Under the Criminal Justice Act 1993, dealing in securities on the basis of information that is not yet publicly known and which would affect the price of the securities if it were made public is a criminal offence in the UK.
Because they are institutional investors, it will be a Vendor Placing which is similar to what we the public can buy but the lead manager/broker would have placed the shares with institutional investors -such as pension funds and HNW beforehand (all parties would be "taken inside"). It is used when the buyer wants to pay for the acquisition by issuing shares in itself but the vendors want to sell for cash.
In these circumstances, to enable the deal to go ahead, the following procedure will take place:
- The buyer will issue shares in itself to the vendor
-The vendors will give up their shares in the company being sold to the buyer.
-The vendors will then sell on the shares given to them by the buyer straight away, in a deal arranged beforehand. They will, therefore, ultimately receive cash in return for giving up their shares.
-Vendor placings cannot normally be at a discount of more than 10% to the mid-market price without the approval of the regulators.
Hope this is useful.
Really useful thanks.
The institution would be aporoached and asked if they are happy to be wall crossed ie be on the other side of the Chinese Wall. If they agree then they WILL be in receipt of inside information but only guilty if they act upon it.
I have not followed the stock but on the basis that its a large placing, the conversations may have been ongoing for some time. The share price has drifted quite considerably so although the discount appears low, it may be a function of discussions starting way higher. As Paul said, an accelerated book build is rarely "accelerated"- its already been covered prior to an announcement.
UP Global Sourcing Holdings (LON:UPGS) total revenue decreased by 6.1% but share price decreased by 14.1% and now to 9.4% at 8:50. I guess the fall today is heighten by my opinion that over October the chart was tightening up from the undecided trying to predict and anticipate todays trading statement. When it disappoints, there can be a rush to sell. I don’t hold and can’t buy today based on this action, but I wouldn’t be a forced seller here and one should take comfort in a nice chart and stock rank. Whenever this chooses to break £1 and turns into support, this trader would be happy to “invest” longterm
Crest Nicholson Holdings (LON:CRST) - I knew my chart score didn’t look right here! - it might be the start of a nice “price staircase”. £1.67 to £2.50 in just over a month. Very nice!
Up Global Sourcing Holdings (LON:UPGS) - If I may ask the trader view. I already hold as a long term investment:
Buying above £1, there are going to be stale bulls all the way up to 140 if not higher - would you trade in and out or ride volatility through this with a stop at £1 or something along those lines.
I dare say £1 is such a challenge, because there are a series of the first dip buyers, who intend to sell if it ever gets back to a quid, not to mention, people who perhaps bought the first break out as a trade and since become long term investors. Sad that this reminds me of myself so much!!
Hi Vivek,
Im looking for when this/if chooses to break £1 and then for this £1 to turn into support to then ride this upwards. I guess I missed some equally import information from this sentence because it all depends on how this happens on the time series.
For example - tomorrow the price might jump to £1.20 and then on Thursday drop to £1.05. I guess there might be eyes on me expecting to press the buy button on Friday if it stayed above £1 but in that hypothetical situation, I wouldn’t because that would be feeding the “stale bulls” you mentioned and the time hasn’t allowed this price to be accepted.
Today was the seesaw day - where today will be marked as a “lower high” instead of a “higher low”. But if it had actually finished higher - could be considered a young and ugly cup and handle and I might have entered. So going forward, price needs to be accepted - which will hopefully happen before 88p so there isn’t a marked “lower low”.
I included the line saying I wouldn’t be a forced seller because of these candles which look the same - and the most recent one is higher than the previous.
And to answer your question, I always ride volatility :)
Thanks
Dan
Trading statement from Strix (LON:KETL) today as part of Capital Markets Day
Strong order book visibility for December now underpins Board's confidence that 2020 profitability for the Group (excluding the impact of the LAICA acquisition) will show modest growth versus prior year
Jack liked this one back in May when 177p - now 230p
https://www.stockopedia.com/co...
Diversified Gas & Oil (LON:DGOC) produced an excellent set of Q3 results last week and management are presenting at a webinar today at 1pm. Following a 14% rise in the quarterly dividend how much more can it rise? Look underneath the bonnet at the company hedging policy and understand how commodity price risk is managed. Hear how the recent partnership with Oaktree Capital will facilitate future acquisition opportunities. Register here
https://us02web.zoom.us/webinar/register/9716034432750/WN_x4OiPSCbRXKoXIamT6sAqg
UP Global Sourcing Holdings (LON:UPGS) Morning all, we're hosting an online presentation today for UPGS at 11am if you'd like to hear from management directly on their full year numbers.. https://zoom.us/webinar/register/7716043902040/WN_DwRWXI2OTZ6vkXXdn8DLYw
And if you want to see our forecasts you can find them here:
https://research.equitydevelopment.co.uk/research/ultimately-theres-brand-value
Morning Paul / Jack would you be able to look at £OMG Oxford Metrics. I hold but sadly the share price is below the March hiatus level. They have no gearing & they are making money which always attracts me to an investment...
Morning ctoman,
Yes OK, I've added Oxford Metrics (LON:OMG) to the list. It's been a long time since I last looked at that one. I used to like it for being profitable, and having a big cash pile. So I'll write up a section on its trading update later today.
Regards, Paul.
Thanks!
re Oxford Metrics (LON:OMG), there seems to be have been a bigger impact on some of their end markets from Covid than has been the case for some other software businesses. Not sure how long lived this will be.
Warehouse Reit (LON:WHR) results today (in which I am long) were boring in a very positive way. Collections of rent are high (above 95%) and the property owned with lockdowns etc are becoming more valuable. This continues to be a tuck away in the bottom drawer for me and it'll bring me 10-15% a year in both dividends and valuation increases.
The biggest risk I see medium to longer term is more property of this type flooding the market. Could someone take some of these shopping mall shells and turn them into additional warehouse space? Potentially but given how much would it would be to convert them and the fact that many are in residential areas or just don't have the same infrastructure then I see it as relatively low risk today.
Would be happy to hear other views
Hi Brooked
Re Warehouse Reit (LON:WHR) I agree. I think this is probably the only sector in real estate that's investable at present. I manage commercial property for a living and well located sheds are always in demand. Only out of town retail parks would convert, but in many locations higher alternative value uses will move in such as trade showrooms / motor trade. Quality office REIT's are tempting with their high yields and massive discount to NAV, such as Regional Reit (LON:RGL), but there's uncertainty about future demand for regional offices, hence risk of voids and lack of growth. I'm currently a growth investor, but when I start looking for income Supermarket Income Reit (LON:SUPR), Warehouse Reit (LON:WHR) and Urban Logistics Reit (LON:SHED) will be top of my list.
my assumption with the office REITs is that at some point they will look at change of use and convert into very profitable flats etc. I've seen an example of just this recently...
Humans have a social need to interact. Its what made us so successful as a society. I remember IBM about 15 years ago sent home thousands of people to full time home office and then realized later that it was leading to people disengaging with the company.
When COVID is eventually neutralized in whatever way I will be hoping to invest in some of the bombed out property companies with offices as my suspicion is that people will go back over time, probably not every day but most of the time.
Re Warehouse Reit (LON:WHR) which I hold the 6.6% like for like increase in property values was good to see. They report a NAV of 118p and are trading at 111p. The big sheds need to be near motorway junctions not in town centres and are in limited supply.
The redundant retail space in out of town locations might be reconfigurable for last mile delivery activity. I think that’s the area Urban Logistics Reit (LON:SHED) are active in, which I don’t hold.
Re Warehouse Reit (LON:WHR)
The redundant retail space in out of town locations might be reconfigurable for last mile delivery activity. I think that’s the area Urban Logistics Reit (LON:SHED) are active in, which I don’t hold.
That's correct, both have recently raised money in oversubscribed offers to expand.
Underlying this, of course, is the rise in online spending. According to the ONS retail spending report (https://www.ons.gov.uk/busines...) online retail was up 53% year on year in September and now accounts for 27.5% of total retail spending compared to 20.1% in February.
I own all of the above plus Tritax Eurobox (LON:BOXE) and Londonmetric Property (LON:LMP) - this looks like a relatively low risk way of playing the pandemic.
timarr
The CEO of Prologis, NYSE:PRD declared on a podcast that they are aiming to buy outskirt shopping malls to convert into fast moving consumer supply chain warehouses. With locations closer to bigger cities it helps reduce the delivery miles whilst encouraging the use of more electric delivery vans.
HS
Curious to know what charting software you use to create the Chart Score graphics?
Hi, both are actually just homemade. Neither are perfect but the score continues to serve me well when the markets are dishing up psychological warfare. Thanks :)
My morning smallcap tweet: Pressure under pressure
Telit Communications (LON:TCM) Amigo Holdings (LON:AMGO) Pressure Technologies (LON:PRES) Omega Diagnostics (LON:ODX) IXICO (LON:IXI) Oxford Metrics (LON:OMG) AFC Energy (LON:AFC) Senior (LON:SNR) John Lewis of Hungerford (LON:JLH), UP Global Sourcing Holdings (LON:UPGS)
Telit Communications (TCM) two bid approaches, one of which rejected. [SP=140 Cap=186m]. I'm short.
Amigo (AMGO) misses target of dealing with all complaint by end Oct. 10% still pending. Complaints remained at a high level for longer than expected. Provision guinance hiked from £116.4m at Q1, to over £150m. Won't start lending until 2021. [SP=12.7 Cap=60m]
Pressure Technologies (PRES) guides FY(Oct) rev only c. £25m (down 12%) and to make an adj operating loss. Blames weak oil and gas markets and slower than expected turnaround of operational performance at PMC division. [SP=65 Cap=12m]
Omega Diagnostics (ODX) Food Detective® test for self-test use approved in China. [SP=91.11 Cap=163m]
IXICO (IXI) wins contracts for Alzheimer's disease clinical trials. No £££. [SP=102.8 Cap=48m]
Oxford Metrics (OMG) guides FY(Sep) rev £30.3m and adj pretax £2.5m. Outllok: "fundamentals remain strong, supported by an encouraging pipeline of opportunities". [SP=91.05 Cap=115m]
AFC Energy (AFC) the serial disappointer makes a long-winded list of all its progress this FY including another successful fundraise natch'. [SP=19.5 Cap=132m]
Senior (SNR) FY outlook 'broadly in line with market expectations' of adj pretax loss £11.2m. WIll remain comfortably within covenants. [SP=60.6 Cap=232m]
John Lewis of Hungerford (JLH) finals delayed. [SP=0.48 Cap=1m]
In line: UP Global Sourcing Holdings (LON:UPGS)
Mr Contrarian. You mentioned being short last time on TCM, when it was 25% lower. Any particular reason?
I've been short since July '19 at 167p.
Aggressive accounting and questions over how much cash it really has.
I closed it today at the open at 150.
Re.£TCM. Thanks MrContarian. Paul or Jack seem to have given it the thumbs down too, not liking either of the potential bidders. Some good detective work between you. Perhaps you should have left it open a bit longer, but maybe too much uncertainty either way. Many thanks
// Annual Results
// Group revenue £13,937m -12% down
// Pre-close statement
// While the profit for the half year will be lower than the comparable prior year period due to Covid, we have seen significant improvement in Q2 compared to Q1
// Q3 Trading Update
// In total, the Group's third quarter orders were 11% lower on an underlying basis (-26% as reported). Underlying OE orders were down 8% (-55% as reported) while AM orders were down 12%. I thought the chart was looking quite strong here, scoring it 83. Will be watching today.
// Third Quarter Trading Statement
// We have experienced good sales activity levels in July, August and September but this is being offset by customer churn and the significant impact the pandemic has on service revenue, which historically accounts for approximately 28% of our revenue. In the three months to 30 September 2020, revenue across our open centres decreased 5.5% at constant currency. Total revenue for the Group (including closed centres) declined to £583.3m compared with £680.3m in the same period last year, a decrease of 10.2% at constant currency.
// Trading Statement
// Group CER sales for the period down 9% year-on-year (H1: down 21%). Group CER sales for the period declined 9% year-on-year, which reflected 15% organic decline and a 6% contribution from the acquisition of Pharr High Performance Yarns (Pharr HP) which was bought in February.
// Trading Update
// The continued focus on the management of working capital, cash generation and the reduction of intra-period net debt volatility has delivered positive results. Net debt at year end is now expected to be approximately £48m which includes £6.5m in respect of the first time adoption of IFRS16 (2019: £75.7m), driven by operating cash conversion of 110% of EBITDA, together with lower finance and tax payments.
If it breaks to the upside, i believe it could slowly float upwards for some time after been held in this positive upwards channel
// Trading Statement
// FY20 Adjusted Profit Before Tax expected to be significantly ahead of consensus of £37.9m and at the upper end of the previously guided range of £35m - £45m. Thinking the score is off here and the orange line correctly predicted the base. We shall we price action over the next month.
// Comment on the Second UK Lockdown & Recent Trading
// Revenues up 28% - Trading in recent months exceeded the Board's expectations and believes the Group's liquidity position is strong. They expect to continue to grow at the expense of weaker competitors - particularly those with UK-centric businesses. Maybe interesting today as it was down -7.4% Yesterday.
// Half Year results
// Total portfolio valued at £563.2 million at 30 September 2020, representing a 6.6% like-for-like increase.
// Genel Energy PLC: Trading and operations update
// "Genel continues to demonstrate its resilience and ability to be move quickly to navigate changing external conditions. Production has remained robust, increasing quarter on quarter, and first oil at Sarta is also now imminent.
// Q3 Trading Update
// In Aerospace, for the Period, sales were 36% lower than for the same period in 2019 on a constant currency basis. On a quarterly basis, Aerospace sales declined 22% in Q1, 40% in Q2 and 45% in Q3, year-on-year. This was as expected, with our 2020 Aerospace revenues significantly reduced as a result of the ongoing impact of COVID-19 and the 737 MAX situation.
// UAE Update: Official launch of the Shari'a project
// announce that it has agreed with one of Europe's largest banking groups ("Shari'a Funding Specialist") to launch, together with iMass Investments ("IMass"), a Shari'a compliant version of its Inventory Monetisation platform.
// Chinese approval for Food Detective® test
// announces that the National Medical Products Administration has approved the Company's Food Detective® test for self-test use in China. Recently sold out here at 95p. I may regret that at the end of the year.
// STV, Reach plc and TSB agree ad-funded partnership
// STV Studios commissioned to produce inaugural Pride of Scotland Awards for STVSTV, Reach Plc and TSB have agreed a deal which sees the broadcaster commission STV Studios to produce the inaugural Daily Record Pride of Scotland Awards, in partnership with TSB. Abit of a non story - for a flat chart.
// Partnership with Take2 Health Limited
// NPC is prevalent in South East Asia and Southern China than other parts of the world, with 35,000 to 40,000 deaths per annum1 and is sometimes referred to as the "Cantonese Cancer". Although rarer than some other cancers, in Taiwan alone there are approximately 1,500 cases per annum, with a roughly 50% mortality rate. Tried to trade this when the score was 100 - but obviously didnt get anyways quickly. No rush to re-enter here.
// Operational Update: Trinidad & Tobago and Suriname
// As a result of the above, as at the end of October 2020, production from existing wells is now consistently averaging around 435 bopd.
// Trading Statement
// The Group expects to report revenues of £30.3m and an Adjusted PBT of £2.5m for the financial year. The Group finished the year with a strong cash position of £14.9m and no debt. Divisionally, Vicon delivered another profitable year and whilst the timing of orders was impacted by COVID-19, as previously reported, it achieved a slightly better performance in the second half than the first half.
OMG Tiffany, like this chart is so like, like, ewww. For the type of compnay this is - its pretty cheap looking - but i believe theres mishaps behind the scenes.
// Final Results
// Total revenue decreased by 6.1% to £115.7 m (FY 19: £123.3 m) - Believe this might have been on a recent piworld interview? Good stock rank. I like the chart. I will be watching!
// Additional Alzheimer's disease contracts
// announces that it has secured new contracts in Alzheimer's disease (AD) clinical trials. The chart is actually looking strong here, but will give it some more time.
// Acquisition of Onshore 3D & 2D Seismic Data Set
// Trinity's onshore licence areas sit within the super-giant greater Forest Reserve Field, located in southwest Trinidad. The Field was discovered in 1914 and has produced over 1.2 billion bbls of oil to date with a recovery factor of between 12.5-18%.
// Settlement Agreement
// On the positive side, SPMP produced and sold its first batches of antimony metal and of gold dore and has been operating individual parts of the plant for short periods at 50% of capacity. This proved that the plant was capable of producing in small quantities but efforts to ramp up production have been hampered in part by the continued lack of funding for SPMP.
// Full Year Trading Update
// Group revenue for the year to approximately £25 million (2019: £28.3 million) Nothing here on the chart.
// Trading Updates regarding Argentina and Chile
// Skip
Grest stuff HollandSmith!
HollandSmith - this breaks out of the width of my mobile. CSS on the chart images maybe? Great stuff though.
Rotate to Landscape i think helps and charts fit perfect.
Hi, I don’t believe the comments support CSS. If they did, my layout would be totally different. Thanks :)
Hi Dan, loving the inclusion of the charts. Thumbs up.
Thank you Mr HollandSmith, what is source for the charts? Nice
OH stop now, you're just showing off !!
Hi HollandandSmith,
Excellent information and always appreciated.
Is possible to provide more information on what the chart score means and what it is composed of?
BSV
Great summary - the charts are a really useful inclusion.
As an aside, 'OMG Tiffany, like this chart is so like, like, ewww' is hands down the best thing I've read today.
Yeah - Morning Dan has a weird sense of humour - he likes to sneak odd lines in for discovery. I’ll let him know you liked it. Cheers Mike!