Small Cap Value Report (Tue 30 March 2021) - LOOP, MPAC, EKF, ANCR, SUS

Good morning, it's Paul & Jack here, with the SCVR for Tuesday.
Timing - today's report is now finished.
Agenda -
Paul's Section:
Loopup (LON:LOOP) (I hold) - results for FY 12/2020 are in line with expectations. A big profit, but it was all generated in H1.
Mpac (LON:MPAC) - FY 12/2020 results. I summarise key points from today's webinar. Nice company, but huge pension scheme worries me.
Jack's Section:
Ekf Diagnostics Holdings (LON:EKF) - new supply contract announcement and upgraded FY21 expectations.
Animalcare (LON:ANCR) - Covid disruption and business restructuring for this veterinary sales and marketing company.
S&u (LON:SUS) - sequential improvement in trading, 4% dividend payment, and brighter outlook for this motor finance and specialist lender.
Paul’s Section
Loopup (LON:LOOP)
(I hold)
83.5p (up 14% at 08:10) - mkt cap £49m
There’s a strongly positive early market reaction to this cloud telephony company’s FY 12/2020 results. On quite high volume too, with 721k shares already having changed hands in the first 10 minutes of trading.
Although this does have to be seen in the context of a big disappointment late last year, when management dropped a bombshell that highly profitable trading in H1 2020 had hit a brick wall in H2. To this day, I still don’t understand what went wrong, they haven’t explained it clearly enough.
As you can see from the long-term share price chart, performance has been erratic, and overall disappointing -
.
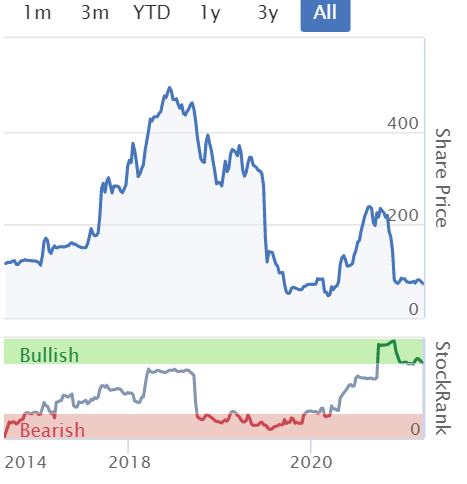
.
I think it’s fair to say they over-paid for a not very good acquisition along the way too, called Meeting Zone. Let's hope management don't do any more acquisitions!
For FY 12/2020.
The headline numbers are in line with the trading update on 8 Feb 2021 -
- Revenues £50.2m (H1: £31.9m, H2: £18.3m)
- Adj operating profit £9.0m (H1: £9.2m, H2: £(0.2)m)
- Net debt £0.7m
Note the huge drop off in performance from a profit bonanza in H1, to just below breakeven in H2. Why? Customers must have switched to a competing product, Microsoft Teams maybe? Or Google Meetings, Zoom, etc? LOOP seems to have retained its “professional services” clients a lot better than more casual users. So perhaps LOOP should be seen as a high-end, niche service, that seems to be used by solicitors, accountants, etc.?
Cloud telephony - this new product was launched in July 2020, and the commentary on it today sounds intriguing. If I’m reading this right, it sounds like a big opportunity. It says the “pipeline of live opportunities” has risen to £106m, assuming an average contract length of 2 years. I wonder how much of this pipeline will actually turn into revenues & profit? Watch this space.
Outlook - 2021 expectations are in line (but they don’t say what market expectations are) -
That said, we are nevertheless confident in our ability to meet market profitability expectations for the year, albeit at a potentially lower level of top line revenue
I can’t find any detailed broker research, but we do have broker consensus figures on Stockopedia for FY 12/2021, £34.2m revenues (a 32% drop in 2020), and a small loss. That sounds consistent with what LOOP says above.
Balance sheet - not great. Writing off the intangible assets (mainly worthless goodwill), arrives at NTAV of £(5.16)m.
Liquidity - it has cash of £12.1m, but borrowings of £12.8m, giving net debt of £0.7m - which looks OK, providing the cash figure isn’t an unusual peak. I’d like to see the average daily net cash/debt figures.
Overall, it looks OK, providing the bank facilities are secure.
My opinion - what to make of this? It’s very difficult to know. The company seems to be trading at a run rate of around breakeven, in H2 2020, and implied by the consensus forecast for 2021. Therefore, I think we should see the big profits for FY 12/2020 overall as a one-off spike in profit from lockdown 1, which has now subsided.
The narrative seems to place a lot more emphasis on new cloud telephony products, with the virtual meetings product almost just a sideline now?
Overall, I have no idea how to value this share! The bull case is that the new cloud telephony stuff takes off strongly - certainly the pipeline numbers seem impressive. The bear case is that the company is a serial disappointer, and the cloud stuff turns out to be hot air. There’s enough upside potential to keep me vaguely interested, so will probably sit tight on my (small) personal shareholding here. I’m not tempted to buy any more though.
.
Mpac (LON:MPAC)
(I hold)
530p (down 3%, at 10:21) - mkt cap £105m
Here are my notes from 7 Jan 2021, when this packaging machinery maker gave an ahead of expectations trading update for FY 12/2020.
Full Year Results for FY 12/2020, published today, didn’t immediately bowl me over -
- Revenues £83.7m (down 5.7% on 2019)
- Underlying profit before tax £6.3m (down 16% on 2019)
- Underlying EPS of 31.4p (down 20.5% on 2019)
However, those numbers need to be seen in the context of a much worse H1 (hit by covid), then a good recovery in H2.
Equity Development has issued a new note today, and I’ve just come off an excellent results webinar they organised too. I jotted down the key points as follows -
CEO used the words “reassuring, resilience, agile”, to describe 2020 performance
ERP software system implemented, “went remarkably smoothly”
Robust order intake of £83.9m
MPAC is focused on healthcare, food & beverage markets - making packaging & processing machinery for them - resilient sectors during 2020 & structural growth markets longer term
Acquisition of Switchback in USA - delighted with performance - order intake since acquisition has been double expectations, good strategic fit, complementary products, synergies working well.
Covid has created opportunities - e.g. customers used to visit to test & sign off new machines. Now it’s all done by video, cheaper & quicker. Can’t see things returning to old ways.
Social media - increased use of this, especially LinkedIn, have good stats relative to a much larger competitor, good engagement with the sector.
Capital-light business model, 22% ROCE
Pension funds (UK one is huge) - £14m accounting surplus. Preparing for June 2021 triennial valuation.De-risking. Hedged against inflation. Partially hedged against bond yields. Well managed, de-risked as much as it can be. Ultimately working towards de-coupling.
Outlook - 2021 so far is trading in line with expectations.
Robust markets, really confident we can deliver.
More acquisitions to supplement organic growth. Have an existing pipeline of relationships which might lead to deals. Also engaged consultants to find other potential targets.
Q re organic vs acquired growth - closing order book of £55m, of which £3m relates to Switchback acquisition. £8m of the total order intake was from Switchback. The rest is organic.
Travel - delighted not to be taking 1-2 long haul flights every month, forgotten what jetlag is like thankfully! Can’t see the long haul flights returning. Need to meet & socialise with clients initially, to establish relationship, but can then maintain the relationship remotely.
Q re tax losses - these boost EPS by c.3-4p, working way through them.
Surplus land in Bucks - anything happening? No, not a priority at the moment, focused on core activities.
Competition - talked about lots of Private Equity activity, one US competitor (Promac?) highly acquisitive, has bought 40 smaller companies! Lots of consolidation.
.
I find watching/listening to a webinar is vastly superior to wading through a long & complicated RNS, and it has the further benefit of being feasible whilst swinging in my hammock and soaking up some rays! Also it gives a flavour for what management are like. MPAC management strike me as open & honest, hands-on entrepreneurs. That’s exactly what I look for in small caps, nothing else matters really. They’re not flashy, quite calm and softly spoken, so my attention did drift slightly at times! Still, it wouldn’t do if we were all the same, as my Gran used to say!
Director shareholdings seem small, unfortunately, and in the past they seem to have been too keen on cashing share options. I thought the whole point of share options, was to enable Directors to build a meaningful shareholding, to align their interests with shareholders, rather than treating them like bonuses? Although to be fair the most recent option sales have been for half, probably just to meet tax liabilities.
Balance sheet - looks OK, not particularly strong, nor weak, the way I see things.
The cash pile of £15.5m looks good, but I recall the CFO said in the webinar that this is flattered by working capital movements that typically unwind partially in Q1. As always, the key numbers we need, but are rarely given, are average daily net cash/debt throughout the year. That's far more meaningful than a snapshot on the year end date alone.
My opinion - I like this company a lot. It operates in interesting, growing markets, and makes a reasonable profit margin. The turnaround has worked, and it got through the covid year in fairly good shape.
For me, the pension schemes are a worry. They’re huge schemes, and that introduces risk, although it has been mitigated as much as possible. The cash payments are currently material, so this is an important issue that can’t just be ignored.
Like practically everything else, MPAC shares have had a great run. Amazingly, the entire small caps index £SMXX is up about 50% in the last 5 months. I do worry that this has perhaps run ahead of itself, and maybe we need to see some consolidation, and retracing, in some shares?
For those reasons, I’m happy to sit on my small, long-term holding in MPAC, but am not tempted to add any more after such a strong run.
Stockopedia loves it!

.
Jack's section
EKF Diagnostics (LON:EKF)
Share price: 77.7p (+10.22%)
Shares in issue: 454,993,227
Market cap: £350.3m
Ekf Diagnostics Holdings (LON:EKF) specialises in the development, production and worldwide distribution of point-of-care analyzers and clinical chemistry reagents for use in hospital and research labs, doctor's offices, blood banks and for in-field anaemia screening programmes.
It’s also a bulk manufacturer of enzymes and has custom manufacturing facilities in the USA for a variety of life science products.
In 2020, the group developed a range of COVID-19 testing products including:
- PrimeStore MTM, an FDA-approved and CE marked sample containment device that allows the safe handling, transportation and analysis of test swabs and samples, and
- COVID-SeroKlir, a leading ELISA-based antibody test from Kantaro Biosciences that provides a precise measurement of COVID-19 IgG antibodies.
So it was one of those Healthcare companies benefitting from Covid trade, but what sets this one apart is that there was already a profitable and growing underlying business long before Covid.
On that point, the major strategy aims of EKF’s core business are:
- to continue to build its installed base of point-of-care analysers which generate an ongoing stream of revenue through the sale of proprietary consumables;
- to supply a range of clinical chemistry reagents for use on its own and third party analysers;
- to grow contract and partnership enzyme manufacturing business; and
- to continue to exploit its Preferred Partnership Agreement ("PPA") with Mount Sinai Innovation Partners ("MSIP"), which allows it ‘advanced access to innovative commercial opportunities arising from certain technologies managed by MSIP.’
It sounds exciting but valuation is a concern, so the company will need to keep growing in order to justify current multiples:

Highlights:
- Revenue +45% to £65.3m,
- Gross profit +58% to £37.4m (so evidence of margin expansion),
- Adjusted EBITDA +113% to £25.5m,
- Profit before tax +180% to £15.4m,
- Basic EPS +202% to 2.45p,
- Cash from operations +171% to £13.8m,
- Net cash +88% to £21.4m,
- Maiden cash dividend of 1p per share.
These are obviously extremely impressive growth rates on the face of it, but they also price EKF at 28.8x FY20 earnings per share with a dividend yield of 1.4%. It’s a high earnings multiple but can be (and does appear to be) justified by current trading and growth prospects.
The 2.45p of basic earnings is lower than analyst consensus of 2.89p, which itself had recently been brought down from 3.6p:

I’ll take that as a sign of brokers struggling to price the temporary Covid opportunity rather than anything to be worried about. A more enduring concern is whether or not EKF can justify a premium valuation once Covid has passed.
There are signs that EKF can generate attractive returns on capital (although this has so far been volatile), so the shares are still worth investigating in my view.
The core business saw revenues fall £6.5m YoY (-14%), but EKF notes signs of a steady recovery. DiaSpect Tm grew sales by £548k (+15%), due to strong performance from OEM partners McKesson and Fresenius Kabi and Quo-Lab was up £210k (+9%) due to improved sales in EMEA and improved shelf-life of reagent cartridges.
Meanwhile, HemoControl and HemoPointH2 sales fell by £2.6m (-36%) as anaemia screening programmes were paused or cancelled and b-HB was down £847k (-9%) due in part to the fulfilment of large orders from Cardinal in Q4 2019.
EKF says that the underlying recovery has continued post period end, with tender wins in Asia and the Middle East, Africa, and the US.
Importantly, EKF has a second trading update out today announcing the signing of ‘a new multi-million dollar global supply contract’ for COVID-19 sample collection kits with its partner from the private sector. Orders will be fulfilled from EKF's production sites in the UK, Germany and the United States.
The global contract is expected to make a considerable contribution throughout the current financial year and the board is confident that trading for the year ending 31 December 2021 will be significantly ahead of already upgraded management expectations.
Conclusion
As an investor looking to earn returns from both earnings growth and multiple expansion, I do wonder if the valuation is too much right now. But then again, EKF looks like a good healthcare company with attractive growth prospects and strong trading momentum. It’s an attractive quality growth stock, assuming the longer term prospects beyond Covid are good. That’s probably the key assumption in determining whether or not today’s share price represents good value.
Quality healthcare stocks can trade at high relative valuations and continue to outperform. Ergomed is a good case in point there. This sector is responsible for more than its fair share of long term compounders.
And EKF has just had by far its most successful year to date, with record turnover and profits. This momentum continues into FY21.
The group enters the new year in an extremely strong position and is making an ongoing contribution to the fight against the COVID-19 pandemic, with strong demand for its sample collection devices driving yet more upgrades.
Meanwhile, trading in its core business is improving, and management indicates that performance for the first quarter of 2021 will be materially ahead of expectations, as will FY21 in general. It’s stellar stuff, and potentially well worth a premium valuation.
Have I missed the boat here? That’s the question I’m asking (and the answer isn’t necessarily ‘yes’). Congratulations to holders so far - I can’t see why you’d sell unless perhaps you’re concerned about post-Covid trading. For now, these are impressive results.
Animalcare (LON:ANCR)
Share price: 238.8p (-0.5%)
Shares in issue: 60,057,161
Market cap: £143.4m
Animalcare (LON:ANCR) is an international veterinary sales and marketing organisation, with operations in seven countries and exports to approximately 40 in Europe and worldwide. It focuses on bringing products to market through its own development pipeline, partnerships and via acquisition.
The group’s share price has been trending upwards in recent weeks but there are mixed signals in terms of valuation - a price to free cash flow multiple of 15.5 is good for its pharmaceutical industry peer group, but the forecast PEG of 5.0 is decidedly less attractive and Animalcare is generating some curiously low returns on capital:

The drop in profitability metrics coincides with a £33.1m acquisition in FY17. So either this was a sub-optimal purchase or today’s low metrics are paving the way for future higher returns.
In FY19, the group’s auditor noted a material uncertainty related to going concern. The FY20 equivalent note states:
The Auditor has reported on the 2019 accounts; their report was (i) unqualified, (ii) included reference to a material uncertainty related to going concern to which the auditor drew attention by way of emphasis without qualifying their report and (iii) did not contain a statement under section 498 (2) or (3) of the Companies Act 2006. The external auditor has reported on the 2020 accounts; the report was (i) unqualified, (ii) did not include references to any matters to which the external auditor drew attention by way of emphasis without qualifying the reports.
This is curious and I’d want to know more about it before investing. I can’t find any more detail at present - it’s possible this was as a result of the developing Covid situation, but I haven’t been able to confirm that. Perhaps somebody in the community knows more. I would not invest before getting to the bottom of it.
Highlights:
- Revenue -0.9% to £70.5m,
- Underlying EBITDA -8% to £12.1m,
- Statutory PBT up from a loss of £1.6m to profit of £0.2m,
- Net debt reduced by £4.2m to £13.6m,
- Proposed final dividend of 2p per share
The group says there has been ‘significant progress in rebalancing, refocusing and defragmenting of product portfolio’. That means the company is looking to improve margins by concentrating sales and marketing resources on a smaller number of bigger brands.
This could be a good move, assuming the core brands are stronger, and could drive an improvement in returns on capital.
Clearly, trading has been disrupted by Covid but it looks like there are some company-specific issues here to be aware of too. It has recently implemented a new organisation structure to deliver more growth.
The fact that the group has been able to use this year to reduce net debt is a positive, and its focus on cash generation and conversion is reassuring. Particularly given the company’s weak balance sheet, which has a negative net asset value. This is a concern.
Animalcare has also progressed its pipeline and its Daxocox product has received ‘positive opinion from Europe’s CVMP’. This is a novel and differentiated COX-2 inhibitor for the treatment of chronic pain in dogs. The group says the anticipated launch in the second half of FY21 will represent a major milestone.
Meanwhile, the September 2020 agreement with Kane Biotech opens up near- and long-term opportunities for biofilm-targeting technologies.
Conclusion
Over the longer term, the attractive fundamentals of the animal health sector makes this worth a closer look, but the balance sheet is not strong and it looks like the company has some restructuring work to do in order to realise higher profits. And the FY19 reference to ‘material uncertainty’ remains a question mark.
Assets are dominated by £50.5m of goodwill and £43m of intangibles - Animalcare has £123m of total assets but just £34.5m of tangible assets, meaning a negative NTAV figure of -£11.9m. Cash generation and conversion are strong though, so this business characteristic helps mitigate that risk.
But Animalcare is not yet generating attractive returns on capital. It could well be that the restructuring and integration work being progressed now is setting the foundation for that down the line.
The group is reducing the number of smaller ‘tail’ or lower value products so that it can concentrate on assets with growth prospects and higher margins. In 2017, the portfolio consisted of around 330 brands which has been reduced to approximately 200 brands.
There could be some easy wins from this work. Management says the increased focus on a smaller number of bigger products has resulted in a 3.2% growth rate for the top 40 brands in 2020. There is also the H2 launch of Daxacox as a nearer term catalyst to look out for. It will be interesting to see how that goes.
Before the 2017 acquisition, Animalcare’s operating margins were around the 20% mark, so there is probably good potential in its markets. Assuming it can get back to those levels of profitability with today’s higher revenue would make for around 16.5p of earnings by my reckoning, which would put shares on just short of 15x earnings. It’s worth noting that TTM free cash flow per share is 15.4p, so that looks like a reasonable benchmark to aim for.
If you can get comfortable with the turnaround, FY19 unqualified audit statement and growth prospects here then this could be worth a closer look but there are a couple of risks being flagged.
I can’t see any director buying activity, that's always something to look for in a stock with a turnaround element to it.
S&U (LON:SUS)
Share price: 2,240p (+0.9%)
Shares in issue: 12,133,760
Market cap: £271.8m
(I hold)
S&u (LON:SUS) is a motor finance and specialist lender with two operating divisions: Advantage Motor Finance (a non-prime motor finance division, and by far the bigger of the two businesses) and Aspen Bridging (a much smaller property loan business).
Advantage lends on a simple HP basis to lower- and middle-income groups who may have restricted access to mainstream products. It remains the core of S&U, although Aspen Bridging was launched in 2017 and the group is ready to increase investment here.
One of the appeals of S&U is its attractive blend of family business / long term shareholder stewardship and its consistently high profitability metrics.

I would argue it’s rare to find this combination on the market, let alone one on a forecast PE ratio of 15x, a forecast yield of 4.43%, and with strong Ranks across the board.
The Coombs family dominates the Major Shareholders list and the minimal dilution over the past ten years suggests that value over time should accrue to shareholders.

Highlights:
- Revenue -7% to £83.8m,
- Amounts receivable from customers -7% to £280.9m,
- Profit before tax -48% to £18.1m (H1 PBT: £6.3m; H2 PBT £11.8m),
- Basic EPS -50% to 120.7p,
- Final dividend -14% to 43p,
- Net borrowings down from £117.8m to £98.8m
Both divisions saw a weaker first half and a material improvement in the second half.
Advantage Motor Finance contributed £17.2m or 95% profit before tax, down from £34m. Up until Covid, Advantage had a track record of 20 years of continuous profits growth. This is a credit to the stewardship of its management and suggests that the results generated over the past year will ultimately turn out to be an unwelcome blip.
Total annual collections stood at £180.5m (2020: £196.5m), with the decrease reflecting smaller book and FCA mandated payment holidays and repossession restrictions (now lifted).
Annual net advances were £102.6m (2020: £149.0m), reflecting lockdowns and tightened Covid related underwriting. Net receivables were £246.8m (2020: £280.8m) and include IFRS forward looking loan loss provisions of £36m for the year (2020: £17m).
Customer numbers were steady at 63,000 (2020: 64,000) and the monthly collection rate against contractual due was nearly 84% (2020: 94%).
These are fairly positive results considering closed car dealerships initially led to an 80% fall in loan transaction numbers and FCA mandated customer repayment ‘holidays’ affected nearly a third of Advantage's customers.
Aspen Bridging contributed £0.8m of PBT, down from £1.2m in FY19, but this performance comes despite a first half during which the property market was effectively frozen. Some pretty dire predictions were made about the UK housing market in early 2020 and so far the outcome has been much more manageable. In fact, the second half was quite strong.
Advances for the year reached £43.5m against £31.3m and progress on product range and broker relationships has resulted in the loan book growing to £34.1m against £21.0m last year.
All this has been achieved whilst tightening checks on borrowers. Loan quality has improved over the past year, with no loans past due and no defaults over the entire book. S&U expects to double investment in this division in the coming year.
Further evidence of long-termism at S&U comes in the form of its dividend track record.

Today the group announces a final dividend of 43p per share (2020: 50p), meaning total dividends of 90p per share (2020: 120p) and a useful yield of 4.03%. I’d expect this to be higher next year.
Chairman Anthony Coombs says:
The current vaccination programme and a more coherent Government policy roadmap for Covid justify greater optimism. Many of the immediate economic consequences have been postponed, and possibly avoided by monetary policy… All this means that S&U's habitual caution should now be seasoned with ambition and optimism for the next two years.
Conclusion
S&U hasn’t come close to meaningful danger over the past year and the outlook is now more optimistic. The suppression of consumer demand and confidence is likely to be temporary and shouldn’t alter the fundamentals underpinning vehicle and property loan demand.
In fact, it could lead to a rebound in the near term and the company is well positioned for this.
Recent government measures such as the extension of the furlough, stamp duty concessions and business support measures should, along with the vaccination roll out, mean management can once again begin mapping out the company’s future growth.
On that note the team says that over the next two years its prospects and strategy will require additional funding. Post year-end S&U has put in place additional longer-term facilities of £50m on terms up to eight years, making for total committed group facilities of £155m.
The attractive mix of quality, income, and earnings growth (barring the past year, of course) make S&U an attractive candidate for a longer term hold in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
Ekf Diagnostics Holdings (LON:EKF) a NED sold about 1 third of his holding (500,000 shares sold) it was reported on Friday.
Animalcare (LON:ANCR) The “Material uncertainty” pointed out by the company’s auditors for the year ending 31st December 2019 was, I believe, made after the year-end. And it was concerning the company possibly having to ask its lenders for a waiver should the COVID pandemic hit its trading position. However, the key EBITDA leverage ratio for 2020 was 1.1 (2019: 1.4). While the bank covenant ratio was 3.5. And, as it pointed out, at the end of 2020, it had available borrowing facilities of some £46.3 million with headroom of £30.3 million (It utilised £16.3 million, “Net of cash balances”). Moreover, it has comfortably exceeded all its bank covenant requirements and has now restored its dividend.
According to its recent announcement, it appears to have reached an agreement with three of its four banks to extend its banking facilities from 31st March 2022 to 31st March 2025 and it expects to conclude negotiations with the fourth bank shortly.
Frankly, I am not concerned with its liquidity or its business model. But for some unknown reason, Animalcare (LON:ANCR) seems unable or unwilling to present itself to investors. The result is that it gets little investor attention and the stock is not as widely traded as, in my view, it should be. I find this even more peculiar given its commercial re-branding exercise.
I have been an investor in several public companies that were bought on, what I regarded as, low valuations. I just hope this is not going to be another. And, yes, I am a shareholder.
Ra International (LON:RAI) (no position)
I continue to be confused by this little company.
On the surface, it seems like a decent business, constantly winning new orders and providing a valuable service.
But little things keep niggling away:
Order Book
For example, the order book is now very large @$187m.
However, it was large at the end of last year too - $148m - and yet it was only able to generate 2020 revenues of $64m.
It would be really useful if the company were to provide order backlog by expected year of delivery in order to manage expectations.
---
CAPEX
$22m of additional land and buildings expenditure in the year ($6m in H1; $16m in H2). That just seems like so much for a company worth £73m.
Another $10m is forecast to be spent on Capex in 2021, which essentially is over and above current underlying cash generated from operations.
This may well be a sound investment in the long run, but it does make me wary that for the last 2 years Capex has been so high without a significant rise in revenues.
LOANS
Another thing that is baffling me.
The company announced a $6m loan in June/July.
From results today it looks like this was increased to $6.5m.
A 7.0%-7.5% interest rate = $455k extra finance costs per year, or $228k finance costs for 6 months, or $38k per month.
But I would still expect an additional interest liability to be somewhere in the accounts, but I can't find it.
Is it bundled into the $6,471k?
Or is it not even in the accounts (which would be worrying.)
---
I stopped researching after the loan interest confusion, but I do wonder if there is hidden value here. It will be interesting to see how that order book develops. As the company states, maybe the material jump will be in 2022.
A
Ra International (LON:RAI) : also the wife and husband team (CEO and FD respectively) own 75% of the shares. They could take the company private at any time and are essentially unaccountable to minority shareholders.
S&u (LON:SUS) (no position)
I thought it worth mentioning a US-based lending company I was researching recently called Upstart, who recently moved into automotive lending.
Here's a c20 minutes introductory video of the company, but you only need to watch the 1st minute to understand why S&u (LON:SUS) 's long term business model might be at risk:
This company's recent growth has been most impressive and if it continues, it's only a matter of time before something similar appears in the UK.
A
https://www.upstart.com/
"Travel - delighted not to be taking 1-2 long haul flights every month, forgotten what jetlag is like thankfully! Can’t see the long haul flights returning. Need to meet & socialise with clients initially, to establish relationship, but can then maintain the relationship remotely".
Agree - if I have to travel then want a GOOD reason other than visit odd places with an expense budget. And not so the company can sell thier new 'mission statement' or update Covid awareness.
Easily done online. Companies saving shed loads and know it. Not great for Premier Inns et al or said hospitality. Anyone seen the housing market booming? Not sure bookcases are moat protected but maybe IKEA will benefit when allowed to open,
I have now watched two Mpac (LON:MPAC) presentations. If I played management buzzword bingo, I would have called "house" today after about 10 minutes, a record for any presentation I have ever watched; I would much prefer plain English.
On neither occasion have I felt the massive optimism of the presentation has been in keeping with the numbers reported. I sold half after the first presentation and sold the rest today, about 10% higher.
If the company delivers as promised, and the pension scheme does not go too badly, the SP is probably cheap, especially after the SP drops of the last two days, but I am just not as confident as I would like to be.
GLAH.
Regarding Loopup (LON:LOOP), I got out a few months ago as one of my 'rules' is to ditch any investment which provides a 25% drop (although I did hold and watch closely through December for a bounce!). The overriding sentiment I read here is no-one seems able to fully understand or explain their financial releases implying management either cannot or more probably don't want to divulge their full business/finance model. Until Loopup (LON:LOOP) are willing to allow investors to 'Do (Y)our Own Research' I'm out...
Until this morning I held £Loop and £Mpac and the difference in their quality of communication made me ditch one and top up the other. No need to guess which way around. With Loopup it has always felt like you are trying to fight your way to an understanding of how they are doing, despite management, and with Mpac, as Paul noted, they appear switched on, committed, and trying to be candid with shareholders. Maybe Mpac shares are a little pricey after a year without that much to show, but they've pulled back the best part of 15 percent from their recent highs, and I know where I'd rather put my money for the longer term.
I sold out of LoopUp (LON:LOOP) months ago, lost faith in the management.
I hold MPAC (LON:MPAC) but sold half this morning, figures were not what I expected, maybe I misunderstood the previous trading update, that's the problem when they just say market expectations, without any figures, but these are well below the ones on Stockopedia. Anyway we will see what happens later this year.
There does seem quite a few pullbacks recently in these sort of shares, so plenty of opportunities I feel.
I'm also out and yet its 15% up today so for me its more of a tradeable cyclical play if you can time it - well done to those in the money still. ;-)))
Loopup (LON:LOOP) - we have a moat a special software that a few legal eagles can use to do confidential discussions on over the internet. Anyone heard of a phone, and sure the WSBetts are not interested in beer anyways. Someone pumped and us newbies will remember.
Chesnara (LON:CSN) I joined the conference call this morning on the FY numbers and it all seems to be panning out as expected. The 3% increase in the final and FY dividend was delivered so an 8% yield that you can believe in with the core business passing up more cash from the divisions than they are paying out to ordinary shareholders. 7.4% gearing only and potential to make acquisitions up to £120m without touching their tier 2 equity requirements. Share buybacks? - they were asked...'never say never' but they made it clear a better use of cash is making selective add on's.
Good solid results from Chesnara (LON:CSN)
I am trying to assess whether this offers better value than Phoenix Group (LON:PHNX) although not easy given they use different metrics. Chesnara has higher yield of 7.8% versus 6.4% for Phoenix, and most importantly Chesnara is well below its economic value per share of £4.24. Phoneix don't provide an economic value figure, but they carry a lot of debt and I believe trading at big premium to their tangible nav per share depending on the way you calculate it. Chesnara also have the advantage of being a lot smaller and nimbler so should be able to pick up cheap portfolios which Phoenix wouldn't bother with now.
Paul, really useful write up on LON:MPAC, thanks
Looks like Spectra Systems (LON:SPSY) wasn't well loved after yesterday's Mello? Dropped quite a bit today!
Spectra Systems (LON:SPSY) ran up on very low volume yesterday and has fallen on even smaller volume today. Not sure you can read anything into it, other than it's thinly traded so relatively small trades can move the price by quite a lot.
Hi Paul, re Loopup (LON:LOOP), the main issue (IMHO) is that UC/social media companies battle to have longer term real 'sticky' business value. Clients, even business ones, will utilise different or multiple platforms and sometimes still jump ship to another. While there might be differentiators such as security, or vertical sector positioning etc. clients will often adjust as their strategy evolves (such as they might want a stronger webinar or podcast facility with decent integrated CRM/Database) and give up maybe a piece of the in-house vendors IP Telephony (such as Enterprise Telephony due to easy overlay SIP telephony from the cloud).
Also, entrepreneurial start-ups might choose to avoid Big Tech lock-in (Cisco, Microsoft), choosing the next level of innovatives (eg Google, Zoom, GoToMeeting) maybe a ''mix 'n match'' best for purpose is chosen (eg use Slack and Skype, un-integrated). The pricing models tell the story. I used Zoho with a startup a year ago - most pricing is on a monthly basis because that's where a large chunk of the broader market is, even Zoom and GoToMeeting (mostly beyond established mid-caps or larger Enterprise) - hope that makes some sense. In my opinion LOOP was a ride for a while during COVID phase 1& 2. IT Services/vendor companies in Comms space make money in good and bad times but I believe one should treat them cyclically.
In summary, the SW & IT Comms space is very much 'horses for courses' ..differentiators don't always last. Zoom shot the lights out because it was a simple established platform (simple pricing, free 45 min conf. calls) that works easily as an overlay to mainstream operating systems, for both layman & Enterprise user. It 'hit the spot' but a broader conversation on who is winning and why, over a longer term, is a bit of a waste of time perhaps. There a ton of vendors in this space. Typically you 'fit in' with the host's technology platform, as most platforms provide UC/Conferencing via your web browser so options of browser/plug-ins/overlay are generally convenient and easy.
To add my tuppeny worth. It's very hard these days to see telephony services of any kind as much more than a commodity. New services become mainstream pretty quickly and it is pretty near impossible for companies to find sources of premium revenue, and if they do it's a bit like being the first hyena to a fresh carcass - they're not going to be left in peace to enjoy their meal for long.
I'm not sure that everyone on here fully appreciates the depth of research that goes into your reports Paul.
Proof, if it was needed:-
"A box of 10 meals arrived at lunchtime yesterday, and I've eaten 9 of them already!"
I am a mere youngster of 57 and hopefully years away from a care home but I really like Parsley Box meals. They are tasty, easy to store and quick to heat up in the microwave.
I didn't take part in the IPO as I was unhappy with the way that Equiniti make investors hold the shares in its own nominee account.
Angle (LON:AGL) I hold
Given the extensive clinical work already completed with the Ovarian Cancer Pelvic Mass Triage assay, it is anticipated that this will be ANGLE's first LDT (Laboratory Developed Tests) to market.
It’s really good news that the Ovarian triage will be the first offering as it should lead to a huge reduction in the number of invasive tissue biopsies performed (with associated risks to patients). It’s also good to hear the company is in advanced discussions with several candidates running cancer trials.
Many thanks Jack for your write up on Ekf Diagnostics Holdings (LON:EKF) (I hold).
“to continue to exploit its Preferred Partnership Agreement ("PPA") with Mount Sinai Innovation Partners ("MSIP"), which allows it ‘advanced access to innovative commercial opportunities arising from certain technologies managed by MSIP.’”
I think that this partnership is not to be under-estimated in looking at Ekf Diagnostics Holdings (LON:EKF) ‘s past (and hopefully future) success. So far this has resulted in spin-outs of Renalytix Ai (LON:RENX) and Verici Dx (LON:VRCI) and also Trellus which is heading for AIM. These spin outs are done by way of distribution of the shares as a dividend in specie, so shareholders share rateably on flotation.
In addition, the company has a record of upgrading and then beating earnings expectations and I reckon it justifies its admittedly high valuation.
Regards,
Ricardo
yes, thanks very much for the quality write-up of Ekf Diagnostics Holdings (LON:EKF) Jack! In addition to the points ricardow highlights above, I think with Ekf Diagnostics Holdings (LON:EKF) there is sometimes the perception that it is just another Covid play. My understanding is that the PrimeStore technology had been developed before the present pandemic and has multiple other usecases:
"PrimeStore MTM (Molecular Transport Medium) is an FDA-cleared sample collection device which deactivates viruses including COVID-19, influenza A, influenza B and mycobacterium tuberculosis allowing safe sample handling and transport, greatly reducing risk of infection to healthworkers, couriers, and lab technicians. "
https://www.ekfdiagnostics.com...
So I think this could have wide ranging applicability especially in e.g. developing countries where there might be more challenges around transport and lab infrastructure etc. Awareness of the product certainly seems to be gaining traction ... e.g. this was recently published in Nature:
"PrimeStore MTM sample processing, in combination with the Ultra assay, has the potential to provide a safe, rapid post-mortem screening test for M. bovis in buffaloes."
https://www.nature.com/article...
So hopefully the last year has raised the profile of the PrimeStore technology generally and there will be lots of future customer demand beyond the narrow Covid testing application.
A reminder that the EKF Diagnostics Holdings (LON:EKF) presentation is at 16 30. To attend ask to register at ekf@walbrookpr.com and they will send you Zoom dial-in details.
The agenda and slides are here: https://www.ekfdiagnostics.com...
So why was the biggest drop (70%) pregnancy testing in South America?
https://www.ekfusa.com/womens_...
I'd encourage any holders to view the Ekf Diagnostics Holdings (LON:EKF) presentation, I attended the call earlier and the commentary was very interesting, especially the Q&A session. As a long term holder, I've seen the stock double and then retreat on the back of a couple of poor acquisitions. That was many years ago, and it's clear now the company is in a very different space.
One concern I had was how dependent future outperformance is on covid testing, it's now clear to me that it's not, and the deal announced this morning (the largest in the company's history) illustrates that. I also asked about the cash pile - it's a continuation of dividends, investing in the business, and possibly an acquisition, probably in the enzyme space (but they don't seem to be in any rush, given the difficultly in finding suitable candidates).
Another concern in the back of my mind was the shareholding of Hardwood Cap / Christopher Mills - just under 30%. In a recent interview he had very positive things to say about EKF (as you would expect!), so possibly holding out for a higher exit multiple:
https://www.voxmarkets.co.uk/...
I agree - EKF Diagnostics Holdings (LON:EKF) was possibly the best presentation I have seen. The directors were down-to-earth tell it as it is people - the exact opposite of shanklin100's experience with MPAC (LON:MPAC)
I'm not sure whether a recording will be made public - the event was not IMC, PI World or similar - it was a standard zoom meeting hosted by the company's financial PR people with all 54 of us listed down one side!
The slides are available - click here
I may write up a few notes tomorrow.
sharw, yes you’re right they were refreshingly open - talked about the good and bad. I’ve met Julian Baines quite a few times over the years, going back to the Stanbio days - again they were very open about the issues at the time. Looking back I remember that they would almost announce deals / sales too early, and then there were issues and the deal or anticipated volume just didn’t materialize.
This helps explain why they are cautious now, under promise and over deliver. So for them to talk about the new supply deal like they did augurs well.
The testing / diagnostic space I feel will be re-examined against the terrible impact of covid - coupled with advances in AI to predict disease (hopefully Renalytix will expand from kidney AI to other areas with Mt Sinai) makes Ekf Diagnostics Holdings (LON:EKF) a core holding for me.
And I do think there is a takeover premium thrown in for free - I could see them being taken over by someone like Charles River Labs in the US.
It does now look as though the major company they are aligned to is Amazon and while there could be concern of their making a bid to take Ekf Diagnostics Holdings (LON:EKF) out at some stage this could prove counter-productive. £AMZN are heavily developing their move into medical care with their own laboratories and direct to consumer medical advice etc, a field Ekf Diagnostics Holdings (LON:EKF) could prove instrumental in assisting through their tie-up with Mount Sinai Health Group. The introduction of Amazon might not be so welcome to them.
£LOOP The opportunity with Microsoft Teams for Direct Routing is probably quite large as the growth in Teams' usage has been huge and MS pricing for this element is very high. It is also a gateway to selling other services to customers. I'm never sure about pipeline value as it depends on who is asking the question and what the purpose is, but probably best to assume the actual figure will be 20% or less, i.e. £10 million for the first year. I was going to dump this but have decided to hold on as we might be seeing an interesting pivot away from the main product which would demonstrate that the management have some qualities. Prior to this the situation looked grim , i wouldn't be surprised if some of the rise is due to shorts closing.
From yesterday's report about Cerillion £CER. The annual results from sept 20 say. ' It is anticipated that the remaining debt outstanding at year-end will be repaid during FY 2021.' This will add 0.6m or about 20% to future years profits so this might support the share price going forward as well as the winning of new contracts which the company only goes after if they feel they can win which saves a lot of expense too
Mpac (LON:MPAC) have a full year results presentation with Q and A at 11am through Equity Development. Sorry can't provide a link but believe it is free for anyone interested, I followed a link from research tree.
I've always liked this company and it seems to be going places but I must admit to being slightly underwhelmed by their results today and sold my holding in them. I feel the share price has got ahead of itself but It could be something I regret though ....
Freely available research note here too.
The broker suggests EPS will be flat in FY21 because higher revenue will be offset by increases in tax (greater profitability unwinds some of their previous tax credits) but then expects EPS to increase to c.39p in FY22.
Re Loopup (LON:LOOP) there is a free (non-house) broker note available here. Interestingly it says a proportion of their customers got a shock from their bills in the first wave of the pandemic and then left Loopup (LON:LOOP) or switched to lower pricing contracts.
I gave up on Loopup (LON:LOOP) a while back and I am very surprised to see the share trading so strongly this morning.
This sentence, with regards to their main Meetings product, leapt out at me:
"Q4 2020 average revenue per day increased by 1% versus pre-pandemic levels in PS, but reduced by 31% reduction in non-PS"
PS = professional services which is their key target market. If they can only grow revenue by 1% in their key target market during a pandemic then that sounds poor to me, albeit I recognise they have shifted their pricing model which will have affected some of the revenue growth.
A lot seems to hinge on their new product offering telephony within Microsoft Teams. Is there not a massive risk that Microsoft just integrates its existing Skype technology into Teams? In addition so many organisations are now using Teams that maybe we will just call a lot of people through the existing platform rather than use some premium add-on technology?
Interested to hear the views of those with more expertise in online telephone technology. In the meantime I am happy to sit this one out.
I'm a lawyer and (albeit anecdotally) have never come across LoopUp in a professional setting. In my experience lawyers generally will use whatever service provider (mainly Zoom/Teams) which is preferred by the relevant client / is easiest to use for the majority of people. Having said that, I am sure there are situations where additional encryption/security is warranted, in which case something like LoopUp may be useful, but not for general run-of-the-mill conference calls & remote meetings which would make up the vast majority of "volume" in terms of service usage.
I've been pondering over my small holding in Loopup (LON:LOOP) over the weekend and decided to wait until the results. I'm puzzled why they are trading up today as I can't see anything particularly promising in the details but have taken the opportunity to sell at 94.5p for an overall profit of 25% which I am happy with. Better to put your money somewhere else if you don't believe in a stock even if the market disagrees (temporarily) I think - but will still watch what happens with interest and good luck to anyone holding....
Loopup (LON:LOOP) is in my "not quite sure" box at the moment. The case they make - that there is a premium market for highly reliable global call routing - is compelling (to me, at least). I work in this part of the industry and agree that a) there is a distinct use case for multinational professional service businesses, and b) it should be possible to create a niche player in this space that can charge a premium.
Is Loopup (LON:LOOP) that player? That's where I'm 50:50 at the moment. £106m pipeline sounds impressive, but do the maths backward and you realise that they would need a direct sales team of at least 50 people to properly service a pipeline of that size. They don't have that many (or anything like it) based on their current headcount. So... either the pipeline isn't real, or they are maxed beyond belief and need to expand their distribution channels dramatically.
The last line of the CFO's statement caught my eye: "the useful economic life of the Customer Relationships asset acquired with MeetingZone may be lower than the 15 years originally estimated for accounting purposes, and as such, the Group proposes to accelerate the acquired amortisation charge for this asset from FY2021"
15 years is heroically optimistic. In telecoms, customer inertia (that's to say, how long you keep a customer even if you aren't providing a market leading service) is between 7-9 years. Adept Technology (LON:ADT), another share I own, typically uses 7 years to assess the lifetime value of customers for acquisition opportunities. Expect that amortisation charge to go up in the next set of results.
Finally, they signal that they need to continue investing in platform development and/or acquisitions. They don't have the firepower to do this so some fundraising is likely to be needed over the course of the next 12 months.
That's all of my bear points out of the way. On the positive side:
- operational gearing on this sort of business is very high
- as an acquisition target, it looks like the sort of business that one of the larger players would find attractive. Its got a valuable asset (the global voice network) and valuable IP and could grow much more rapidly with a better sales and distribution capability
- its very very cheap compared to other players in this market (a value rank of 97, whereas others such as Cloudcall (LON:CALL) and Gamma Communications (LON:GAMA) are in the low 20's).
- its relatively unlikely to go bust.
I’ve looked at the Parsley Box IPO and taken up a small entry position in the Offering via Primary Bid.
Part of the due diligence - and to get a preferential place in the queue in the event of oversubscription - I have also become a customer. While I’m probably not (quite yet) their target demographic (I have my own hair and not all of it is grey), I was impressed by the range of the meals offered, the price of the products, the slickness and ease of use of the website and the efficiency of the logistics behind the order. The meals themselves were fine - good quality comfort food, nicely presented and easy to store and cook. Portions are quite small (again, I’m not the target demographic) but no waste either from excess serving or throwing away ingredients that aren’t used.
I think they have found a gap in the market (combination of convenience and competitive price point wrapped up in an appealing marketing profile) and are now in a land grab to get scale and brand name established before the supermarkets and the likes of Just Eat crowd into their space and eat their lunch. Some of the IPO proceeds will be used to fund this expansion (although bearing in mind the principals are also cashing in a fair chunk of their equity). Relatively low penetration of the target market so far (150,000 customers of 16m “Baby Boomers+”) yet substantial growth in the past 2 years (CAGR reported at 248% albeit from a low base), and c.20,000 mainly very positive (4.5 stars) Trust Pilot reviews suggesting there is some momentum and substance behind the hype.
As ever with an IPO there is significant risk and limited numbers/track record to base an investment case on but ever was it so getting in at the ground level.
Gus.
I know it is only a sample of one but my 86 year old mother-in-law who enjoys her food tried some Parsley Box meals and said they were disgusting! On the other hand an ex-colleague in his 80s considers them quite tasty. As always when assessing a food related product individual preferences will determine how successful the business will be. I won’t be investing as this is getting to be quite a competitive space with relatively limited barriers to entry.
Here are my SCVR heat maps for today (prices as at ~9:00am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Ra International (LON:RAI) results today in line with December's TU. Rev $64.4m (19: $69.1m). EBITDA $14.2m (19: $16.3m). Order book $187m (19: $141m). Cautious short term due to the hostile activity in Mozambique and CV19. Longer term more confident than ever.
Tomorrow 31.3.21, 11.30am, there is an Ra International (LON:RAI) investor webinar. Register here.
And today, following Personal Group (LON:PGH) FY20 results last week, we have a webinar with the CEO & CFO. Register here.
I see someone has referred to Parsley Box, here is a quick overview of this new IPO.
Further, you might also be interested in some of last week's results/analyst presentations from:
Tandem (LON:TND) FY20 results presentation
Judges Scientific (LON:JDG) FY20 analyst presentation
Tribal (LON:TRB) FY20 analyst presentation
Pebble (LON:PEBB) FY20 results presentation
Cvs (LON:CVSG) H1 analyst presentation
and Bonhill (LON:BONH) FY20 results presentation
Hopefully you can join us for the presentations by Personal Group (LON:PGH) and Ra International (LON:RAI) today and tomorrow.
Why is Personal Group (LON:PGH) so unloved :(
RA International (LON:RAI) results out - and there was update yesterday ref the bad news coming out of Mozambique - Ra have taken a hit ref revene timing but the only thing that matters ref that country at present if that hopefully some stability can be restored that can put an edn to the loss of life - i don't really know the full story there so i don;t know if there is any chance that the dleayed contract could end up being terminated.
This is all the the job description of what this company does for a living and they have sufficient cash in the bank so see them through this delay in current/future revenue recognition. They seemed confident anough about future that they have still voted teh dividend.
this is a bit of double whammy as their new brokers were forecasting lower profits this year anyway - note some have said that as new broker they may be starting of with low base level to provide room to upgrade ????
On a positive the orderbook was pretty much at record levels at 31/12/2020 and they have enquieries and potential work coming in all over the place so there is reasons for thinking the potential here is excellent - well the future potential would be good wouldnt it.
Many people, locals and expats have been killed in the recent atrocity in Northern Mozambique. According to UK press reports, RA International’s Mozambique country manager is among the missing. With so many people still unaccounted for, I think it is still time to focus on the human costs.
Michelmersh Brick Holdings (LON:MBH) this morning. Excellent results and outlook with a restored bumper dividend.
StockRank 90 but always overlooked. Little gem.
Hi, Barnesian. Michelmersh Brick (LON:MBH). I fully agree with you. Top class management and one of those companies that, for some reason, seems to fly a little under the radar. Should not be compared directly with other companies in its sector, as it produces specialised bricks, which are in great demand. The company is very cash generative and has made one or two shrewd acquisitions. It has emerged from the covid lockdown in very good shape and has shown its resilience in difficult times.
One of the things to look for is one of the contractors to us has just won this contract, so there is going to be a lot more supply in the market from probably Q4 2022 so worthwhile considering
https://www.business-live.co.u...
Morning Paul, any chance you could cast an eye over the Pensana (LON:PRE) interim results please?
Kevin, I think Paul doesn't handle resources stocks. If it helps, I have been puzzling over Pensana (LON:PRE) for a while, watched the share price shoot up (seems to happen when I don't buy, just watch), and go down this morning. There are just far too many questions, the main one being - where does the money come from for going into production?
thanks for the thoughts Chris - I had a very small (1% of pf) holding of £PRE and have doubled up recently on a dip and again today (although because of transferring in a previously managed pension pot I still only have about 1-2% of pf). I agree there is a funding issue - but even getting ever closer to the planned processing plant in the Humber surely makes them a takeover target or will allow them to raise funds.
.
Good morning Jack and Paul, look forward to seeing your views on Loop and mpac. Just had a look at loop and bagged a few because it's got itself into profit.
Also because Host can mute anyone with a radio on, etc, etc, etc ... etc.
Re mpac, it has paid divis, but you need binoculars to see into the past for the last time they appeared.
But to be fair, it may be spending all its spare cash on more fixed assets like plant and machinery, Hopefully the latter.
8.25am Tuesday.
.
So many results today, these didn't make the 8am cut:
LoopUp (LON:LOOP) FY. Outlook "confident in its ability to meet market profitability expectations for FY2021, albeit at a potentially lower level of top line revenue."
MySale (LON:MYSL) guides FY revenue in line with previous guidance, with Group underlying EBITDA expected to be significantly ahead of market expectations.
Michelmersh Brick Holdings (LON:MBH) outlook "We remain well placed in a market that is both performing well and has positive, longer-term fundamentals. Challenges over imports and reduced UK manufacturing capacity suggest that demand for our products will remain strong and the first quarter of 2021 has been encouraging with a strong order intake and KPIs ahead of expectations despite some poor weather."
Animalcare (LON:ANCR) outlook "We are encouraged by demand levels we are seeing in the first quarter of the year and barring further disruption from COVID-19 we expect revenues to grow over the course of 2021."
So many, Mr. C, that you missed your old friend that you called Direshite ( Dialight (LON:DIA) )
Financial summary - Table was here - Stocko has put at bottom and I have failed to edit it back up here grrr
Key points
· Project revenue significantly reduced but MRO revenue was strong and resulted in market share gains
· Finished goods strategy and essential business status resulted in on-time delivery maintained at 80%, despite supply chain headwinds
· Balance sheet strength improved with inventory unwind of £13.5m and net debt reduced by £5.1m
· Enhanced liquidity from £10.0m of additional bank finance secured with HSBC and UK CLBILS scheme
· Statutory loss of £7.8m reflects lower revenue, includes £6.0m of COVID-19 related costs offset by £5.1m of cost savings
· Increase in quoting activity in 2021; range of profitable outcomes for full year
It looks as if it is heading in the right direction, but this company has had so many false dawns that I am uncertain. Any views?
Morning Paul,
How was your Parsley Box yesterday?
Parsley Box seem like an interesting company but the following description on their website put me off a bit - "No need for a fridge or a freezer! Cupboard stored meals delivered straight to your door and ready to eat within minutes"
Surely the quality can't be great if you can simply store the meals in a cupboard?
Cheers
I was wondering the same thing Kieran. Please tell, Paul!
These so-called ambient ready meals look disgusting to me, even in PB's ads. Whilst demographics are moving in their direction, I would have thought that the old cohort (in which I find myself) will gradually have more sophisticated tastes. Such dishes may have appealed to most 60+ folk in the Fifties , post WW2 rationing, but I am not sure the same applies today. Just look at how the range develpment in e.g. Iceland, has been to more sophisticated, and international dishes.
Not tasted the delights of parsleybox myself but my 92 year old mother now has them all the time and is very happy. Her twin sister had been having them for some time and recommended. It may be more about convenience than taste but my mother likes her food . Their marketing and delivery is very slick and I can see PB getting a decent market share.
Parsley Box looks to me like the last stage before giving up on independent living and moving in to a care home. But that's something an increasing number of people will be keener than ever to avoid after the Covid deaths in care and reading about the number of care home staff who are refusing to be vaccinated.
So it could be a growing niche business and I guess they know how to prepare meals for their target customers.
Hmm - I am learning nowadays to be counterintuitive - if I dont think its a winner - it probably is....
Isn't their a risk that you could be wrong in thinking it's not a winner.
Part of me is tempted to invest in Parsley box based on seeing those in my family use their products, and looking at their offer, their history and their growth prospects. However, I understand that IPOs on average do not provide great returns? Perhaps others can advise on that? I would rather wait and see some real results and good fundamentals.
split your investment
Why not join the Parsley Box presentation and Q&A hosted by Mello this Thursday at noon? It is free for all investors to join and as they are listing later today it means you can get to see them very early on their market debut...
You are invited to a Zoom webinar.
When: Apr 1, 2021 12:00 PM London
Topic: Mello webinar
Register in advance for this webinar:
https://zoom.us/webinar/register/WN_EoZ2cDUWStelt_3RS79opA
After registering, you will receive a confirmation email containing information about joining the webinar.
Hi Kieran,
How was your Parsley Box yesterday?
A box of 10 meals arrived at lunchtime yesterday, and I've eaten 9 of them already! The portion sizes are very small, about half the size of a regular supermarket chilled ready meal.
Taste is generally good. They have a very strong, savoury flavour, and seem more salty than supermarket ready meals. I think they've been formulated for people who remember the war, and rationing.
It's certainly convenient to have a supply of these Parsley Box meals in the cupboard, not having to worry about refrigeration or freezing.
Taste & texture are nowhere near as nice as a regular ready meal from ASDA or any other supermarket. Therefore, I think Parsley Box seems quite a niche product. Maybe the sort of thing you would buy regularly for a forgetful Grandad who was struggling to look after himself?
It seems to me that elderly folk who live independently would just want better quality/tasting food than this, and can order their shopping online, which is what my 83-year old Mum does. She's got a fridge, and a small freezer compartment, and that's fine for her needs. Hence storing ready meals in the cupboard doesn't have any advantage for her, apart from maybe long-life products if she was bed-ridden? (thankfully not)
Overall, I think Parsley Box is too niche, suitable really for people who are maybe close to needing to go into a care home, or are seriously ill.
The key stat I would be interested in, is repeat custom. How many people just order once, then decide supermarket ready meals are much better tasting, double the portion size, and about the same price? It's not for me - the product, or the shares!
Regards, Paul.
"It's certainly convenient to have a supply of these Parsley Box meals in
the cupboard, not having to worry about refrigeration or freezing."
Sounds like plastic food which explains the taste and texture and the salty taste.
re: Parsley Box. All the very elderly that I know rave about https://www.wiltshirefarmfoods.com/
Those are frozen but that doesn't seem to cause a problem. Perhaps we need a comparison taste test!
I just watched their presentation and they say they are targeting baby boomers, basically anyone over 60. I'm in that category but I'd never be one of their customers. Since I stopped work I have all the time in the world to do anything I want. I cook most of my own meals and eat a much greater variety of fresh food than I did five years ago. I get the usual impression of age stereotypying around Parsley Box, the references to baby boomers and grandads like we are just about to fall apart. Maybe I'm not typical but I'll be back in the gym 6 days a week from April 12th, I run, ride a pushbike and a motorbike and still go to gigs and festivals (or hopefully will again soon).
If there are companies out there that want to target people like me they need to think again if their idea of understanding "their demographic" is a greying grandad. I'll still take that as an insult when I'm 90.
I totally agree, I'm over 60 as well, I will never buy this product, I'm quite annoyed by the presentation. I also know many people in their 80s and 90s who would not touch this sort of product but I accept it may appeal to some.
Hello Paul,
Re Parsley Box, I don't understand how these meals with meat, can be stored in a cupboard and not a fridge? Is it because of the high salt content? I did notice on the site that none were low salt meals.
If so I don't think that is a good idea for various reasons. If the storage is the main attraction I don't really see the big deal, most people have a fridge and freezer these days. I cook my own food, it is far cheaper and you can control what goes in it. Most convenience food has far too much salt and sugar for me.
HelloFresh (HFG), a German company, is probably their nearest competition and they seem to be expanding in the UK. They have done well with the lockdowns but I have my concerns when lockdowns finish.
herbie4 - HelloFresh is not a competitor - it does recipe boxes - Parsley Box is pre-prepared and hence can be stored. They are for the very elderly for whom cooking is now difficult. I notice they are also for reduced appetites - 250g meals - standard supermarket ready meals are 400g.
I agree it's a different product but it is still delivering food to your home.
ParsleyBox is targeting the over 60s not just the very old. I question how healthy these products are, for the elderly, as they seem to have high salt content.
Fresh food is better.
Hi sharw
HelloFresh (I hold) have moved into prepared meals.
Check out Factor 75, which they bought last year.
It's only in the USA right now, but I've heard 2021 credit card data is looking good. If true it's only a matter of time before expansion into the UK and their other markets (Germany, Australia, etc....)
Fingers crossed
My elderly neighbour lives off COOK frozen ready meals. COOK has an extensive national network of shops and delivers. My other half rates them too. Not cheap but a cut above the typical supermarket ready meals. I don't see the point of salty non refrigerated ready meals in a country with a reliable electricity grid, maybe Parsley Box knows something I don't about power generation in the UK.
Yes we have a COOK outlet near us, I know someone who uses them and rates them quite highly but she does cook most of their own food.
I must be very fussy because I tried some Cook meals and won’t be a repeat customer. So Parsley Box is well beyond the pale for me.
Can’t match home cooking.
I was tempted by Parsley Box because their growth rate, in just 3 years since formation, is very impressive & eyecatching but their Aim listing document is pretty poor in my opinion. Very light on numbers & forecasts. Loss making with no projections on expected profitability. Products look uninspiring but undoubtedly convenient. I can see people buying a few to keep in cupboard for emergencies but not sure about regular, repeat purchases so is it a long term, sustainable business ? Ready meals are nothing new so if there was a genuine gap in the market for the elderly population then wouldn't one of larger, established food companies have already done it by now ? I think danger is they enjoyed a one off spike from covid and sales will drop once we all return to normal, but to be fair to them they enjoyed similar rapid growth in 2019 as well. They mention in their admission document that 28% of customers reorder within 60 days of initial order. I'm no expert on ready meal food delivery market but that doesn't strike me as high, perhaps just confirms that people order to stock cupboard and then forget about them and get on with enjoying freshly made food most of time. It seems to me that aim of most food delivery companies it to win subscription business so that they have a nice steady flow of repeat business but Parsley Box don't offer this service, perhaps recognising customers don't eat this type of food regularly. That's a pretty big weakness for me as means cost of marketing to acquire new customers will stay high as will constantly be on lookout for new customers to fill gaps of a subscription type model. As Paul says, it's all about repeat business. One to watch but that's about it for now for me.
I am a repeat customer of Paisley Box and have been impressed by the efficiency of the company.The ready made meals are nothing special but it is practical in the era of Covid to have 3 months supply of food in the house and Paisley Box offer some variety to the usual baked beans and canned tuna.Paisley Box have improved their boxes over the last year with clever ideas like 2 free small bottles of wine with the food
This sounds like a worse delivery-in-a-box meal than Gousto or Hellofresh. What's stopping either giant from creating an offering suitable for older generations and replicating Parsley Box?
My morning smallcap tweet: SURE sure got FY20 accounts wrong
Dods (LON:DODS) Lamprell (LON:LAM) EKF Diagnostics Holdings (LON:EKF) Cambridge Cognition Holdings (LON:COG) Velocys (LON:VLS) £B90 Dignity (LON:DTY) Angle (LON:AGL) Rua Life Sciences (LON:RUA) Sure Ventures (LON:SURE) Symphony Environmental Technologies (LON:SYM) Eckoh (LON:ECK) Good Energy (LON:GOOD) Mediazest (LON:MDZ), Pressure Technologies (LON:PRES)
Dods (DODS) guides FY(Mar) adj EBITDA £1.8m (-£0.2m) after stong H2. Proposes to change name to Merit. "The Group intends to continue to integrate the excellent data technology solutions acquired with Merit with the data and content analysis strengths within Dods. The trading recovery in the second half of the financial year just ending provides a strong base for growth." [SP=2.7 Cap=16m]
Lamprell (LAM) JV with Injazat, the UAE's leader in digital transformation, to create and market innovative digital solutions focusing predominantly on the renewables and oil & gas industries. Invests $3.5m each. "The JV will be registered inside the award-winning Abu Dhabi Global Markets financial centre." Award winning! How impressive a start. [SP=58.6 Cap=199m]
EKF Diagnostics (EKF) wins multi-million dollar 2 year global supply contract for sample collection kits from its partner from the private sector which has placed orders worth £6m before. Agreement "expected to facilitate future orders which will contribute materially to 2021 performance and beyond." [SP=70.5 Cap=321m]
Cambridge Cognition (COG) wins £1.3m cognitive assessment contract for a schizophrenia trial. [SP=83.7 Cap=26m]
Velocys (VLS) British Airways extends ownership option for the Altalto project to March 2022. Altalto intends to apply for a grant in Gov't £15m 'Green Fuels, Green Skies' competition. [SP=6 Cap=64m]
B90 (B90) £1.1m placing at 14p, a 2% premium, to help settle the majority of Group's overdue creditors. Co has finalised affiliate agreement with Oddsen (March RNS) to grow the Group's revenues in Norway. [SP=14 Cap=14m]
Dignity (DTY) GM to vote on activist fund Phoenix's proposal to replace exec chmn with its placeman. Co not keen: "Clive Whiley has had a galvanising effect on the business, is well-regarded within the business and is respected in the City as an experienced and effective executive chairman [SP=662 Cap=331m]
Angle (AGL) UK and US clinical laboratories now open and ready to provide CTC analysis services and discussions with pharmaceutical industry customers ongoing. [SP=80.5 Cap=173m]
RUA Life Sciences (RUA) Vascular large bore graft - initial observations indicate animal trial success. Co remains on target to submit US regulatory approval application during Q2 2021 [SP=147.5 Cap=32m]
Sure Ventures (SURE) restates FY20 accounts - £946k of capital distribution was wrongly allocated to revenue. [SP=105 Cap=6m]
Symphony Environmental Technology (SYM) hails conclusion of the 5-year Oxomar study which provides Symphony with further comprehensive and reliable scientific data on the performance of d2w in the oceans. Biodegradation proved beyond doubt and non-toxic to marine creatures. Results also match lab accelerated artificial aging predictions. [SP=14.05 Cap=25m]
Eckoh (ECK) wins $1.35m contract in US Secure Payments, taking total this FY to $11.6m. RNS misleadingly titled "Eckoh wins $11.6m of new contracts". [SP=64 Cap=162m]
Good Energy (GOOD) trading sounds OK but does not say 'in line'. [SP=237 Cap=39m]
MediaZest (MDZ) AGM stmt: co 'continues to win additional new project work at an encouraging rate...expects the majority to be delivered in H2". [SP=0.1 Cap=1m]
In line: Pressure Technologies (LON:PRES)
Cambridge Cognition Holdings (LON:COG) mentioned during Mello last night and delivering further good news this morning:
"Cambridge Cognition wins £1.3 million cognitive assessment contract for a schizophrenia trial
Cambridge Cognition (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce that it has won a £1.3 million contract as the cognitive assessment partner for a schizophrenia trial. Revenue from the contract is expected to be booked over the next three years. This is the fourth schizophrenia trial Cambridge Cognition has secured with this pharmaceutical client in seven months. The first three were announced by the Company on 1 September 2020 in a £2 million contract."
https://www.investegate.co.uk/...
I’m in two minds whether this new Cambridge Cognition Holdings (LON:COG) contract is a good thing or not ...... coat please.
Finals from CV-19 beneficiaries Loopup (LON:LOOP) and Ekf Diagnostics Holdings (LON:EKF) today. Only LoopUp’s results are a bit of a mystery, as ever, with the rider:
Having expanded our strategic scope from a single capability remote meetings business into a broader cloud platform for external and specialist communications, FY2021 is inevitably set to be something of a transitional year for the Group
https://www.londonstockexchang...
I gave up on this after the last set of trading updates. I've decided this is beyond rational analysis.
EKF's results are great on the back of expanded CV-19 testing (PBT up to £15.4m from last year's £5.5m), but as they note:
We believe the Group is in a strong position, however, it is difficult to assess reliably whether there will be any material disruption in the future, and for how long our COVID range will remain relevant. We have modelled a number of scenarios covering reductions in revenue of 10% and 50%, without taking into account the potential benefits of any mitigation strategies such as potential cost savings or insurance claims.
https://www.londonstockexchang...
Which is fair enough. However, they've also released a separate trading update today due to a two year deal with a private sector client:
With subsequent orders under this expanded global contract expected to make a considerable contribution throughout the current financial year and beyond, the Board is confident that trading for the year ending 31 December 2021 will be significantly ahead of already upgraded management expectations.
https://www.londonstockexchang...
So the future may be less rosy, but not yet.
timarr
Good Morning,
Ekf Diagnostics Holdings (LON:EKF) has published results this morning that look pretty strong:
• Revenue up 45% to £65.3m (2019: £44.9m)
• Gross profit up 58% to £37.4m (2019: £23.7m)
• Adjusted EBITDA1 up 113% to £25.5m (2019: £12.0m)
• Profit before tax £15.4m (2019: £5.5m)
• Basic Earnings per share of 2.45p (2019: 0.81p)
• Cash generated from operations of £13.8m (2019: £5.1m)
• Cash at 31 December 2020 of £21.9m (2019: £12.1m), net cash after borrowings of £21.4m (2019: £11.4m)
• Value of investments in marketable securities at year end of £6.5m, after sale of Renalytix shares raised £7.7m (2019: £9.7m)
• Maiden cash dividend of £4.5m paid to shareholders, equivalent to 1p per ordinary share
https://www.investegate.co.uk/...
Whilst it's unlikely to be a small stock Oxford Nanopore has announced today it plans to float on the LSE in the 2nd half of the year. Should be an interesting one for those of us who hold Ip (LON:IPO) who have their 15% valued currently at about £340m
Whilst it's unlikely to be a small stock Oxford Nanopore has announced today it plans to float on the LSE in the 2nd half of the year. Should be an interesting one for those of us who hold Ip (LON:IPO) who have their 15% valued currently at about £340m.
At those figure ON has a fair market valuation of about £2.25 billion.
Estimates of the valuation at launch lie in a very large range - but £5.4 billion is the lowest I've seen, which suggests that the carrying value is understated by a large extent.
Also note that Schroder Uk Public Private Trust (LON:SUPP) hold about 4% of ON - which would be worth £216 million. SUPP's current EV is just over £400 million and their carrying stake of ON is in the portfolio at £68 million, so that's a serious uplift.
The hype around the Oxford Nanopore IPO is quite high. Potential mooted valuations are as high as £22 billion. At that point their value to IPO and SUPP would be twice the companies' market caps.
Wherever the final valuation lies, it looks like being good news for the holders.
timarr
Agree I think it's also excellent its coming on the LSE rather than moving to the US. Just the type of company we need to start shaking up the FTSE100
I’m a bit surprised they are choosing the LSE and apprehensive they may be planning to go for a dual class of shares after the Hill report and encouragement from Mr Sunak.
Could be setting themselves up for a tussle with the old guard like L&G who cling to the old fashioned idea that the shareholders own the company and get to hire and fire management. But that’s pure speculation on my part.
Oxford Nanopore technologies' (ONT) only competitors are illumina (market cap $57B) and pacbio (market cap ($5.9). Both had modest or flat sales growth in 2020 whereas ONT's sales are growing exponentially. In my view ONT offers compelling speed, cost, supply chain and technical advantages over these rivals which is why illumina last year attempted a failed patent suit against the company. If a lost cause like Deliveroo can scrape together £7.5B in the current market ONT has to be worth a generous multiple of that. I think a market cap mid way between pacbio and illumina (£22B) is quite feasible. £22B would be >10x on the carrying value for both Ip (LON:IPO) and £SUPP (I hold both). ONT's unlisted status prevents many funds, ETFs and other strategies from buying, I anticipate huge demand for the shares once listed.
I was happy to be able to double my Ip (LON:IPO) and Schroder Uk Public Private Trust (LON:SUPP) holdings first thing.
Further to Momoko's comments, it is also worth comparing Oxford Nanopore's financial performance with that of Illumina. The most recent annual figures for Oxford Nanopore I could find are to 31.12.19 when revenues (converted to US$) were $72M with loss of $100M. For the same period, Illumina's revenues were $3.5 billion with a profit of $1 billion but it is certainly true that Oxford Nanopore is growing more quickly than Illumina but I think quite a while before they catch up in terms of financial performance.
Agree that the 2019 numbers for ONT are unremarkable, but the company has made astonishing commercial progress in 2020, supercharged by the pandemic they have gained market share and a global research base that may have taken years to build otherwise. Gordon Sanghera the boss articulates the future prospects far better than I : https://nanoporetech.com/ont/a...
Oy, I bought my first ever delivery take away because I wanted to buy shares in Deliveroo! 8:00am first day SELL !
there’s a very bullish update from Ekf Diagnostics Holdings (LON:EKF) today.