Small Cap Value Report (Tue 4 Apr 2017) - FUL, KWS, UTW, NFC, KOOV, ADT, UNG, FLO, TPT, NANO

Good morning! It's Paul here.
I've just about recovered from a fantastic weekend - in particular, participating in the UK Investor Show. I (perhaps foolishly!) agreed to be interviewed by Tom Winnifrith, in a "live bearcast". We didn't get off to a good start, as I had a brainstorm, and turned up at the wrong venue - a North London conference centre. Only to realise, with complete horror, that there was a room full of people, and a very angry Tom Winnifrith, waiting for me at the QE Centre, a couple of miles south of my actual location!
Anyway, I hopped on the tube, and arrived in time to be torn to shreds by Tom. Although I did manage to get some quite good points in, during the brief gaps when Tom paused his monologues to draw breath! Anyway, it was all a bit of fun, and I popped over (well, spent the next 2 hours in) the Westminster Arms, and had all sorts of interesting conversations with various readers of my articles here.
Then it was back over to the QE2 Centre, to do a main stage stint. If you had told me, when I was in the depths of despair, from 2008-2012, that in 2017 I would be on the main stage, interviewing Nigel Wray, I would have laughed at the implausibility of such a suggestion. Yet that's what happened, and the initial stage fright immediately dissipated, and it was a thoroughly enjoyable half hour.
The trick is to prepare really thoroughly in the days beforehand, and practice exactly what you want to say, and how to say it. Also, I telephoned both Nigel Wray & Paul Mumford, and ran through all the questions with them, so had a good idea what they wanted to say.
So I think I've finally cracked how to do public speaking, which for most people (certainly including me) is something which seems very daunting. However, the only way to overcome those worries, is to tackle it head on, by getting up & doing it. That involves accepting that at first, you'll be pretty rubbish at it, but that hopefully each subsequent time is an improvement.
Fulham Shore (LON:FUL)
Share price: 19p
No. shares: 571.4m
Market cap: £108.6m
(at the time of writing, I hold a long position in this share)
Trading update - for the year ended 26 Mar 2017.
This is a restaurant roll out, by experienced management. The main chain is called "Franco Manca", and is a pizza restaurant, with some nice original touches - e.g. blast cooked sourdough pizzas, premium ingredients imported from Italy, "no logo" craft beers at low prices, wine bottles refilled with tap water & mint leaves put on every table when you sit down, etc.
The point being that Franco Manca does actually have some good points of difference, as opposed to being just another "me too" pizza/pasta chain. This is important, as there seems to be over-capacity emerging in the restaurant sector, with so many roll outs occurring. Inevitably that means weaker formats could fall by the wayside.
Fulham Shore also operates its smaller The Real Greek chain, and is experimenting with some interesting new ideas, e.g. street stalls. Both chains make fairly decent operating profit margins at store level, which is absolutely key to determining whether a roll out will work, or not.
As we saw with Tasty (LON:TAST) last week (in which I have a long position), those that make mistakes with poor menus & poor site selection, or just don't offer good enough value for money, can start to go wrong - Tasty warned on profits a few days ago, which I reported on here.
So I was apprehensive about the next update from FUL - is a general slowdown occurring in the restaurant sector, or are Tasty's problems self-inflicted? It seems to be the latter, because FUL has updated positively;
The Board expects that Fulham Shore will report full year results in line with market expectations for the financial year to 26 March 2017.
Other details include;
- The company is to invest £100k in a seasonal branch in Sicily - via a franchisee. I've got mixed feelings about this, but it's not a huge amount of money.
- Rapid & ambitious roll out. 16 new sites opened in FY2017 - going from 29 to 45 sites in one year is a helluva challenge, but the company seems to have pulled it off.
- Pre-opening costs higher than anticipated, due to delays at one site, and 2 additional sites opening earlier, which had been intended for the new financial year. No big deal in my view.
- A further 15 new sites planned for the new financial year (ending 3/2018). Ambitious again, but the company seems to be able to cope with rapid expansion. It does increase risk though.
- Will these formats work outside London? As they are lower priced chains, I reckon they will. The company doesn't indicate any problems with regional site openings to date.
- HSBC borrowing facility expanded from £6.5m to £15.0m, to finance rapid expansion - so this roll out is not entirely self-funding. They're going faster, and increasing borrowings to do so.
Valuation - I'm struggling to get hold of the latest forecasts. It might be helpful if the company commissioned some research, to help investors better assess the prospects of the company. That might also help improve liquidity in this share, which is currently poor.
My opinion - I love good roll outs. The beauty is that bolting on each new site increases cashflow, thus creating a virtuous circle where expansion becomes self-funding. So providing nothing goes wrong, then investors can just sit back & watch the company grow considerably, with little to no further dilution.
When a format works, I also like the roll out to be done fairly aggressively, if management can handle that without making expensive mistakes on site selection. This seems to be one of the issues at Tasty (LON:TAST) for example.
I'm relaxed about FUL borrowing more from the bank, to part-finances rapid expansion, as long as trading remains robust. It would of course increase risk, if trading went badly wrong. Personally I don't see how a chain serving nicely done, large pizzas, from £4.95 each, is likely to suffer in a recession. The opposite could actually happen, as people might trade down from more expensive offerings?
Another key requirement for roll outs is experienced, and capable management. FUL gets a tick in that box.
Overall, FUL has good formats, which work well at individual site level (strong individual site profitability/EBITDA). I've read commentary that EBITDA is nonsense. In this sector, actually EBITDA is critical, and it's the most important measure for assessing performance. The reason being that it's all about cashflow, not profits. I could explain more, but don't have time now. Also it's a pointless discussion. You either understand that roll outs are all about cashflow, or you don't, and miss the point completely.
The ambition here is to get on with it, and build a national chain. That should see profits go through the roof over, say, the next 5 years. That's why I hold this share.
These bank facilites will enable Fulham Shore to gradually accelerate its opening programme and push for a nationwide presence throughout the UK.
Of course, the downside risk is that rapid expansion could lead to mistakes, and things going wrong, as has recently happened at Tasty (LON:TAST) . So roll outs are not without risk. Personally though, my assessment now is that FUL is one of the best roll outs on the UK market, based on currently available facts & figures. Of course, if the facts & figures change, then I reserve the right to change my mind in future. Views on shares should never be fixed. They can & should change when the facts change.
Keywords Studios (LON:KWS)
Share price: 694p (up 1.6% today, at 11:24)
No. shares: 54.4m
Market cap: £377.5m
Final accounts - for the year ended 31 Dec 2016.
Results today look in line with an update given on 8 Feb 2017, which I reported on here. Actually adjusted profit before tax is slightly above, at E14.9m, when E14.8m was indicated earlier. Always nice to put a cherry on top, with a slight beat against a previous update!
This group is highly acquisitive, and describes itself as an - "international technical services provider to the global video games industry"
The pace of acquisitions is the first thing that stands out with this company. It did an astonishing 8 acquisitions in 2016. I cannot understand how management could possibly do so many acquisitions, at the same time as running the business? So that's a bit of a worry. Although the bolt on acquisitions seem fairly small in total, just over E20m, as I noted in my previous report on this company. I wonder why the vendors are selling, if their businesses are doing so well?
Like-for-like ("LFL") revenue growth from existing businesses looks excellent, at +24%.
Cross-selling - someone at the UK Investor Show was briefing me on this company, and reckoned that the acquisitions are good, because it increases cross-selling opportunities. That's confirmed in the narrative today;
25% increase in clients using three or more services from 51 to 64
Current trading - looks fine;
Trading in the first two months of the year has been in line with the Board's expectations
Debt - more debt for more acquisitions. Looks fine, providing profitability remains strong;
Terms agreed for a revolving credit facility of up to €35m with Barclays Bank, which will provide further headroom for selective acquisitions
Diluted EPS - is 10.87 Euro cents. It's about £1 = E1.17 at the moment, so this translates to about 9.3p. Therefore at 694p per share, the PER is slightly under 75. Yikes!
Now of course, the statutory numbers are the most conservative version of profit, so we should also look at the adjusted EPS figures, to remove things like goodwill amortisation (which is fine by me, that's just a rather annoying book entry).
Adjusted basic EPS is much higher, at 20.59 Euro cents, and is up 61%. So clearly the valuation of this company partly hinges on strong growth (although remember that a lot is coming from acquisitions, so that has a one-off benefit). Also it partly hinges on the big difference between statutory & adjusted EPS.
So investors really need to be certain that you're comfortable with the adjustments to EPS, because they're big adjustments.
These adjustments are;
(before share option charges, amortisation of intangible assets, costs of acquisition and integration, and foreign currency movements)
...acquisition and integration expenses of €1.3m (2015: €1.1m), share option charges of €0.7m (2015: €0.4m), amortisation of intangibles of €1.6m (2015: €0.9m), and foreign currency loss of €1.7m (2015: loss of €0.5m).
Balance sheet - Net assets total E100.6m. As you would expect from a highly acquisitive group, this is becoming top heavy, with intangible assets.
Goodwill & other intangible assets total E55.5m, so take that off (to look at the most conservative view of the balance sheet - always worth doing) we get NTAV of E45.1m.
The rest of the balance sheet look fine to me, I can't see any particular funnies in there, or anything out-sized - debtors look about right for the size of business.
Cashflow - this is often more revealing than the P&L statement, and generally I think we should place more emphasis on analysing cashflow.
I don't see anything untoward here either. The net cash provided by operating activities, of E15.0m, is a huge increase on 2015's E3.4m. Although favourable working capital movements in 2016 of E3.2m are the reverse of a E3.2m adverse movement in 2015. So a E6.4m working capital improvement in 2016 vs 2015, reduces the increase in operating cashflow from E11.6m, to E5.2m. Still good, but we mustn't get carried away!
Pleasingly, there's no sign of aggressive accounting treatments that I've seen - e.g. no aggressive capitalisation of costs.
Basically the company has generated a lot of cash, and topped that up with some bank loans, to buy more bolt on subsidiaries.
Dividends - just a token amount really, but that's fine for a group with a growth strategy.
My opinion - I don't really have any opinion on the company's prospects or what the share price might do.
The main thing to point out, is that the stock is pretty expensive now, so the growth has to continue to justify that high rating. If you think that's likely, then everything's fine.
I was asked by a reader to run my slide rule over the accounts, which I've done, and it all looks clean to me - I don't see anything fishy, or suspect in there at all. Personally I would probably reverse out the adjustment of share-based payments, as that's remuneration, but it's not a huge amount. There's also some dilution from deferred consideration (in shares) for acquisitions, but that seems to have been accounted for in the diluted earnings numbers.
Overall - looks interesting, but quite pricey!
Utilitywise (LON:UTW)
Share price: 139p (down 11.6% today, at 16:17)
No. shares: 78.5m
Market cap: £109.1m
Interim results - for the 6 months to 31 Jan 2017.
The market clearly doesn't like today's figures and/or outlook, indeed the share price began falling sharply a few days before results day - funny that - it's almost as if someone knew that bad news was on the way.
This company is the utility cost management consultancy, with controversial accounting policies. I've written about it loads of times before here, please click here for the archive of my reports on it.
The key P&L numbers for the 6 months look like this;
- Revenues up 11% to £46.1m
- Adj profit before tax up 4% to £9.4m
- Adj fully diluted EPS flat at 9.6p
So for a company that talks a lot about growth, it's rather incongruous to see no increase in EPS.
However, overshadowing this, there seem to be 3 problem areas, as follows;
In order to further strengthen the Group's commercial prospects, the Board has taken the strategic decision to discontinue the practice of taking cash advances from suppliers,
as well as increasing the transparency of the balance sheet through a number of prior period restatements
and the non-cash impairment of our investment in t-Mac.
The decision to discontinue cash advances from suppliers and the prior period adjustments will have a one-off impact on net debt but puts the Group in a stronger position to achieve its future growth ambitions.
Cessation of cash advances from suppliers - this looks a big deal, and will result in a really nasty cash outflow in H2 of this year;
These amounts, along with associated VAT, will together lead to a one-off impact upon the Group's cash flow during the second half of FY17 of £16.4m with a resultant increase in the closing net debt of the Group at 31 July 2017 compared to the previously forecast position.
I don't like the look of that one bit. It's a dramatic increase in net debt, in the pipeline.
Prior period restatements - this is explained in note 10 to today's accounts. From what I can make out, there's negligible impact on profit or EPS.
The main issue seems to be that some creditors were included in trade creditors, which should have been included within net debt. Therefore net debt, as restated, is higher than before, with this table showing the restatement;
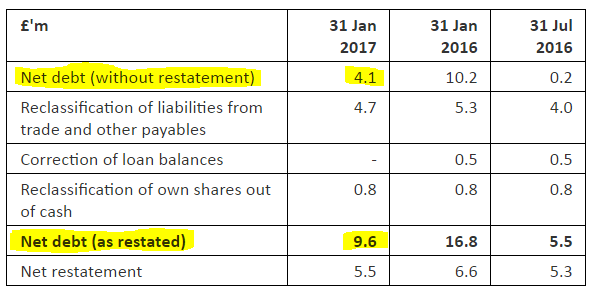
Net debt of £9.6m as at 31 Jan 2017 looks reasonable. However, when you combine this with the £16.4m cash outflow in H2 expected above, then it looks like net debt would be heading for about £26m, less whatever other net cash inflow is generated in H2.
That looks to me as if it's likely to use up most of the available bank facilities - so headroom on the bank facility looks to be dramatically reducing in H2 of FY17 (i.e. now);
The activities of the Group are substantially funded by a £25m revolving credit facility (RCF) with a single lender, Royal Bank of Scotland plc. The RCF facility matures in April 2019. As at 31 January 2017, the undrawn committed facilities of the Group were £20.9m, net of cash and cash equivalents.
I wonder what the bank's view is, of accounting restatements, and the apparent decision to abandon supplier cash advances, and replace that with maxing out the bank facility?
Impairment of t-mac investment - this looks like a goodwill write-off for an acquisition made in 2015, as follows;
The near-term delays in certain revenues has caused the Group to recognise an impairment loss of £13.4m against its investment in t-Mac Technologies, which was acquired in 2015. That non-cash accounting loss has been recognised as an exceptional item within the Group's income statement in the current period
It's described as non-cash, but really that's not true, the way I look at things. If you look back to the announcement of the acquisition of t-mac just 2 years ago, in April 2015, it was paid for using cash borrowed from the bank, and issuing new shares, totalling £10m for the initial consideration.
Since today Utilitywise is writing off £13.4m, then presumably there might have been some additional consideration paid after the original £10m? That was real money, paid out by Utlilitywise, for what it now seems to be saying was a worthless acquisition. Shareholder value destruction, in other words.
Balance sheet - the biggest issue with this company's balance sheet still remains - namely the gigantic amount of revenue & hence profit which has been booked in advance of the cash being received. The other side of the double entry is shown within non-current assets, as a £33.9m asset, called accrued revenue.
This figure should turn into cash over several years, but it's a very aggressive accounting treatment, which I've never liked.
So a huge thumbs down, indeed a loud raspberry from me, for this balance sheet. I don't like it one bit, especially now net debt is set to soar in H2 of this year.
My opinion - what a mess! Multiple accounting issues, and net debt about to soar - it looks horrible to me, I wouldn't go near this share after this announcement.
The dividend yield is looking very attractive, at over 5%, after today's fall.
I see Geoff Thompson is stepping down from Exec Chairman to Non-Exec Chairman, in a separate announcement today. In this statement, he gushes;
...I firmly believe we are still only really scratching the surface in terms of the opportunities available to us
If that's the case, why did he bank squillions in personal share sales in 2012, 2013, and 2014? See the Stockopedia Director transactions page here. Sure there have been some hefty Director buys too, more recently, but these are still dwarfed by the massive sales previously. As the saying goes, follow the money! i.e. watch what Directors do, rather than what they say.
Personally, I like companies with simple business models, and straightforward, transparent accounts. Why get involved in something like this? I think the accounts here are pretty ropey, and I'm not sure management are up to scratch either. With all these latest issues, I can't see any reason to get involved.
Next Fifteen Communications (LON:NFC)
Share price: 385.5p (down 3.6% today)
No. shares: 73.4m
Market cap: £283.0m
Final results - for the year ended 31 Jan 2017.
Checking the archive here, to refresh my memory, I last looked at this marketing group just after the Brexit vote, in late Jun 2016. I flagged up here that it looked set to be a beneficiary of sterling devaluation, and was trading well. The share price is up 65% since then, so am a bit annoyed I didn't buy any at the time. Never mind.
The headline figures given in a table, are adjusted numbers, so it's necessary to review whether the adjustments are reasonable or not. As you can see from the table below, taken from note 2 of today's accounts, the adjustments are huge;
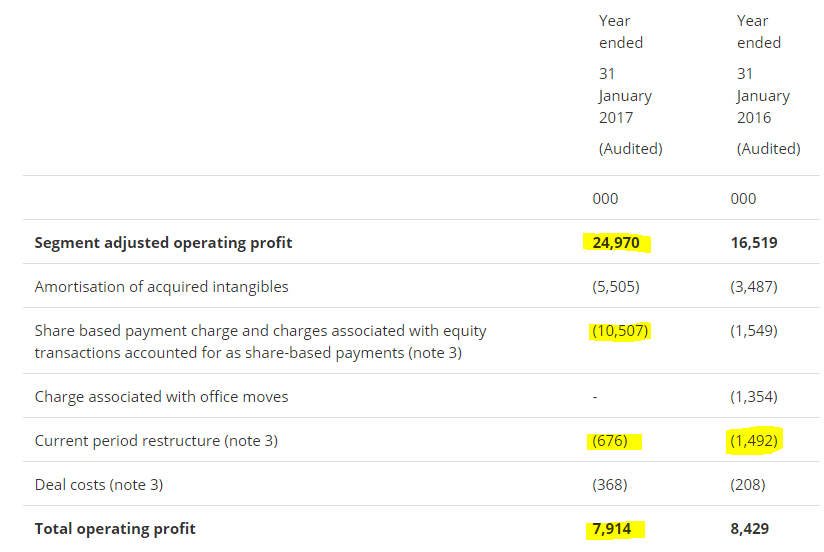
Note 3 shows even bigger adjustments to profit before tax. This makes me uncomfortable, with such big figures involved.
There's a more detailed explanation of the enormous £10.5m share based payment charge, which says;
1 This charge relates to the acquisition of the 20% minority interest in Bourne whereby performance shares were issued as partial consideration, and transactions whereby a restricted grant of Brand equity was given to key management in Agent3 Limited, BYND Limited, MIG Global Limited, The Lexis Agency Limited, Twogether Creative Limited, BYND LLC, Vrge Strategies LLC and M Booth LLC (2016: Bite Communications Limited, Bite Communications LLC and The OutCast Agency LLC) at nil cost which holds value in the form of access to future profit distributions as well as any future sale value under the performance-related mechanism set out in the share sale agreement. This value is recognised as a one-off share-based payment in the income statement. It also includes charges associated with equity transactions accounted for as share based payments.
I haven't got a clue what that all means. Which is a problem, as it's a highly material number.
Also, restructuring costs in both years looks like it's becoming a habit. If so, why is it adjusted out?
Balance sheet - a very top-heavy balance sheet, with ever-growing intangibles. The NTAV is negative, at -£11.5m. There's a fair bit of debt too, especially when you include acquisition-related creditors.
Outlook - this sounds encouraging;
Looking ahead, the Group has made a good start to the new financial year with encouraging signs across our brands.
The Board is recommending the payment of a final dividend for the 12 months to 31 January 2017 of 3.75p per share, which would represent a total dividend of 5.25p for the year to 31 January 2017 which reflects an increase of 25% on the dividend in the prior year.
Although note that the dividend yield is fairly paltry at 1.4% - not surprising, given the weak balance sheet, and heavily adjusted profits.
My opinion - I don't like it. The adjustments to the accounts are massive, and the balance sheet look weak to me.
That said, if you do accept the adjusted figures, then EPS growth to 23.4p (up 38% - helped considerably by favourable forex) looks good. That gives a PER of 16.5, which looks a lot for a company in this sector.
If sterling does start recovering against the dollar, then of course that would be negative.
It seems to me that this share has had a great run, and risk:reward may no longer be quite as favourable as it was a year ago?
A few quick comments now to round off with:
Koovs (LON:KOOV) - let's enter the parallel universe of Indian online fashion. Koovs thinks everything is going great, despite selling clothes for less than it costs to have them made, and losing money hand over fist.
The share price has fallen 8.6% to 50.25p, valuing the company at about £90m - which is astonishing, considering its abject failure to demonstrate it has a viable business model. Remember this thing is burning cash heavily, and will need more, in the not-too-distant future.
In today's trading update, it focuses on top line growth;
Sales* up 87% to £18.6m (1.62Bn INR)
Note the asterisk, which says;
* Gross sales order value placed through the KOOVS.COM website including taxes. This does not represent the revenue of the Group.
Might it not be better to tell shareholders what the group's revenue actually is then? Apparently not.
International expansion - the company is expanding into other markets, in Asia-Pacific & the Middle East, through distribution agreements.
Gross margins - this seems to be saying that the gross margin is still negative, but expected to become positive in the new financial year just started (ending 3/2018):
The company continued to improve its gross margin position by improving intake margin and controlling the level of discounts given, and expects to generate positive gross margins in FY18.
To be clear, a positive gross margin means selling something for more than you paid for it - which is the basic starting point for any business, surely? Not to be doing that already is complete madness.
My opinion - I can't see any mention of the cash position, cash burn, or even profitability. So in what sense is this a trading update? It's not really. It's just a lot of PR.
This remains probably the worst eCommerce share that I've seen. Things could change of course, nothing is set in stone. If investors are prepared to continue funding the losses (which means more dilution for existing holders), then it could perhaps reach a tipping point where a viable business might emerge - if strong growth in sales can be achieved, and if a decently positive gross margin achieved.
There are far too many ifs in the above upside case for my liking. I cannot see the point in taking on so much risk by buying this share. It might eventually succeed, but the business model looks deeply flawed to me, as things stand at the moment.
Adept Telecom (LON:ADT) - the share price is up 12.6% today to 357.5p, so the market clearly likes its trading update today.
This bit sounds good (if you accept EBITDA as a performance measure - something that differs considerably between various sectors, in my view);
The Company is pleased to announce that it anticipates that underlying EBITDA will be around 26% ahead of the previous year (ahead of the market consensus expectation of an 18% rise year-on-year).
Turnover is expected to be approximately 16% ahead of the previous year and above market consensus expectation.
I imagine that's likely to trigger broker forecast increases.
Net debt of £15.8m is a bit (£1.3m) better than forecast.
Divis are up 19% Y-on-Y to 7.75p, but that's only a 2.2% yield, hardly worthy of dusting down the bunting, and getting out the stepladder.
My opinion - I'm not keen on this type of telecoms/IT company. The tech is moving so fast, that you can suddenly see existing business models become defunct, or at least withering away. Hence the valuations are not particularly high, for good reason.
For now Adept seems to be doing well, but how sustainable is that, longer term, I wonder? It's not for me.
Universe (LON:UNG) - results for 2016 are out today, and look OK. Note that the 20% increase in profit before tax is driven by a sharp fall in finance expenses. Operating profit was actually only flat against the prior year, at £2.0m.
The balance sheet looks alright to me. The Chairman sounds upbeat about new products & contract wins, albeit with timing delayed.
I've dabbled in this share before, and found it horribly illiquid, with a very wide spread. So for me that probably rules it out. It looks an OK company though, and it might be worth more research on what prospects are like for new products.
Flowtech Fluidpower (LON:FLO) - this is a good company, providing a wide range of spare parts of hydraulic equipment. It generates decent profit margins, and has been expanding through acquisition.
Unusually, the company has put out 2 separate RNSs, one for its 2016 results, and one for its Q1 trading update.
I don't have time to go through the figures now, but on a brief glance, the business seems to be doing pretty well. That's reflected in a share price up 9.3% today to 140p.
I've looked at this company before, and think it's good, and reasonably priced, so could well be worth a closer inspection.
Topps Tiles (LON:TPT) - the share price has taken a hit today, down 7.7% to 90p, on a rather lacklustre trading update.
H1 LFL sales were down 1.9% in H1, with a worsening trend (Q2 was down 4.1%). Thus some of last year's LFL decent sales growth has been given back.
Although costs seem to have been well controlled, mitigating the impact of weaker sales;
Lower sales growth over the first half will primarily be offset by reduced operating expenditure. Based on an improving trend across the second quarter and a prudent view of the second half, management expectations for full year profits are within the current range of analyst forecasts.
That's quite impressive. I wonder which costs they've been able to reduce, as there's not a lot of scope for retailers, other than cutting staffing levels & bonuses.
Top marks also, for the company helpfully including a note on what market expectations are. This is so useful, I really wish all companies & advisers would make sure this is done as standard practice. To be blunt, it's just laziness and/or arrogance, not to do what Topps, and increasingly lots of other companies are now doing to help provide investors with the information we need;
1 The current range of analyst expectations for underlying profit before tax for the year ended 30 September 2017 is £21.0m to £22.3m, with consensus at £21.8m.
My opinion - I do like this company, but I can't really see any reason to buy any other retailer, when the best quality one of them all, Next (LON:NXT) is so cheap (in which I hold a long position).
And finally, a reader has asked me to look at a blue sky stock reporting today:
Nanoco (LON:NANO) - interim results from this company today look grim. It's a blue sky stock - so a company which is developing some novel product, where everybody gets terribly excited about the potential, and chases the share price up to a high valuation.
The trouble is, practically all blue sky stocks in the UK seem to go wrong - either partially, or very often totally. So punting on shares of this type is an almost guaranteed way to lose money. That's why I don't do it any more. Although there can be big surges of excitement when individual stocks can multi-bag, which is why people like to try their hand at this type of gambling (it's not investing, let's face it).
This company seems to have some credibility - it mentions big name companies which seem to be interested in its product. However;
Although first half results are in line with the Board's expectation, sales have not yet materialised in the second half and we are therefore lowering our full year expectations
To put that into context, sales in H1 (the 6 months to 31 Jan 2017) were only £676k, and the operating loss was £6.4m.
Cash burn is high, and the bank balance is rapidly depleting. There was net cash of £8.3m at 31 Jan 2017, which had fallen from £14.5m just 6 months earlier. Therefore, it looks as if this company is likely to run out of cash before the end of 2017, if sales don't kick in, and/or if costs are not reduced.
This is the nightmare scenario for any blue sky stock - i.e. sales not occurring as hoped, and cash rapidly running out. Investors usually don't want to fund another placing, unless/until there's clear evidence of actual orders in the pipeline.
Often in this type of scenario, companies start issuing lots of bullish-sounding announcements about impending orders, in order to push the share price up, so they can get another placing away.
There's a going concern note with today's figures, which bulls should read carefully.
Outlook comments sound good, but remember that no commercial sales have begun yet;
Progress over the last six months has been transformative for the business. We now have active engagement with nine display OEMs working on 14 different programs and have developed the manufacturing capabilities through our own facilities and those being developed by our partners and supply chain to fulfil the demand. We look forward to our current activities generating our first commercial sales.
My opinion - how can I (or anyone else who is not closely involved with the product development plans) possibly assess whether this company is likely to succeed or not?
It's just a punt, not an investment. I wish the company well, and hope it succeeds, but it's not something I could possibly consider as an investment, as I have no way of knowing what the future holds for this company & its products.
Things always take longer, and cost more than planned. When cash is running out, that means more dilution looks inevitable, and can often be on very poor terms for existing holders.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Hi Paul,
Re Adept Telecom: I think you are being a little harsh on AdEPT, a long term favourite of mine and a very successful investment.
Net debt of £15.8m is a bit (£1.3m) better than forecast.
(Cash flow is very strong which has allowed it to pay down acquisition costs quickly, invest in the business and increase the dividend)
Divis are up 19% Y-on-Y to 7.75p, but that's only a 2.2% yield, hardly worthy of dusting down the bunting, and getting out the stepladder.
(From when it started paying dividends in year ending March 2012 it has been increased by 200% in March 13, 100% in March 14, 58% in March 15, 37% in March 16 and now 19%. Given the prodigious free cash flow I anticipate further strong dividend growth going forward)
My opinion - I'm not keen on this type of telecoms/IT company. The tech is moving so fast, that you can suddenly see existing business models become defunct, or at least withering away. Hence the valuations are not particularly high, for good reason.
(I think your point about technology moving fast is misplaced with AdEPT Telecom. It provides all the communications networks such as high speed broadband, wifi, telephone etc on long term contracts to local authorities and universities though framework agreements. I think it is much more technology agnostic than you think)
For now Adept seems to be doing well, but how sustainable is that, longer term, I wonder? It's not for me.
(I think anyone who has met the management at ShareSoc events in Richmond will know how good the management are. Totally focused on share holder value. After all, founder, Ian Fishwick and family are big holders. Acquisitions have been strategically well thought out, bought at sensible prices and value enhancing. Fishwick is building AdEPT into a valuable company which I think will be an attractive takeover proposition, when management are ready. Anyway, that's the end game that I anticipate.)
In January 2014, when it was 132p, I concluded: "it looks cheap on a prospective PE (according to its broker’s forecast) of 10.9x the year ending 31st March 2014 and a prospective dividend yield of 1.9%." I admit to selling 20% of my holding recently for risk reasons but it is still my second largest position after Fidelity Asian Values IT.
To me it has good (owner, occupier) management, focused on building share holder value, in a sector it knows well. It generates oodles of cash and generates a decent mid-teens return on capital and equity. I don't believe it is at risk of a sudden change in technology. It moves with technological changes. Happy Holder, as they say at JIC!
Comment on the recent results from SPRP would be much appreciated.
Hi brownrigg,
I did 10 companies in one day, that's all I can manage, sorry! ;-)
As regards SPRP - to me, it's too problematic. I know the company well, as I bought some shares in it when they were about 90p and on ISDX. Everything looked great, for several years, it moved to AIM, but more recently the performance has been ridiculously erratic, due to issues about large one-off orders driven by legislation, then odd distribution contracts with suppliers.
I just decided a while back that it's not for me. Too complicated, and opaque.
Looking at the most recent results, briefly, my concerns were confirmed - I don't like companies which can swing so much in profitability. Nobody was saying that the profits would collapse. Everyone was happy when it was 300p per share.
So, a rather peculiar share, I'm uncomfortable about it, so it goes on my list of weird shares that I don't need to bother myself with!
There are simpler, and easier to do shares out there.
Has it really got amazing IP? I don't know, but probably not. The collapse in margins suggests to me that end customers are probably sourcing simple tech from cheaper Chinese companies, after this company made a one-off massive profit from being in the right place & right time.
This thing probably had a good run, but I'm not sure it has any prolonged pricing power. So I'd just sell up & move on. It doesn't pay to FALL IN LOVE with shares which do well for a while. Believe me, I've done that. I made £5m from falling in love with Indigovision, and I lost the lot on the way down. Don't make the same mistake I did!
Regards, Paul.
VMT Paul. It's because the accounts seem so difficult to unravel that I asked your opinion. I'm a long term holder in an ISA from the ISDX days and just get more confused each year. Figures too opaque and too many obfuscations so, as you say, probably time to quit while still ahead. Cheers. Brownrigg
Paul
I wondered if you would help me, I am looking into Nature Group which announced back in Jan this year they have sold their Ports Services business for £4m of which £1m is held in arrears. Not being an accountant I can see we therefore credit the cash element of the B/S. But as I trawl through the accounts I cannot see where the reduction of liabilities will be? Clearly it is the business itself which was losing money. Obviously that means the profit and loss account will benefit so I guess I would have to go back over the periods taking out the effect of the business on the P&L to get the true effect? Sorry if this is a bit basic.
Best
Me again I have just re read your analysis Paul and I think what you are saying is the events created the future debt and so nothing was hidden it was in effect bad business practice where recurrent income and future profits were accrued in advance, and now this practice is stopping, so the Piper must be paid. I recognise this activity as it was prevalent in my business, I didn't participate for obvious reasons In many respects it is a problem in the fund management industry where recurrent income based upon stock market value collapses rapidly in a bear market, both as a result of withdrawals and the reduction in asset value.
Thanks Paul for your analysis of Utilitywise it was a lot to take in when I read the results and my fear was the future and how all the book restatements affected the companies security, what I didn't expect from you and Gus is the debt position and that worries me, I have sold anyway but that is not the point. I am very careful to ensure that net debt is below 40% and no more than 3xnet profits so where did I go wrong if as you say Gus the company has spiralling debt and how did they manage to hide 19million of debt. I have a 13 point fundamental financial check list and it passed with flying colours. My post "A fool and his money" was written a little with tongue in cheek but this situation with hidden debt both from the Stockopedia and Sharepad Screens is worrying and more than a lesson in jumping early. Perhaps, and I know you are busy, you could do a separate piece on such practices and how to spot them.
Regards
Ken.
I am not an accounting expert, but I was interested to look under the bonnet of a publicly quoted company's subsidiaries the other day. It was a way of doing my own total of the consolidated operating profit.
In doing so I came across a subsidiary company they had acquired which itself had a holding company. They had maintained the holding company structure. The trading subsidiary had decent retained earnings, and it had passed a dividend to its holding company in excess of its after operating profits. This dividend was recorded as both revenue and 100% profit in the holding company.
So what gets consolidated, the holding company's profit or the trading company's profit?
In this case the excess wasn't material to the total Group's profit, but could potentially be bit of fillip because most of the other subsids had underperformed comparatively. Struck me as a bit of a potential accounting wheeze which reading the consolidated accounts you may never know.
Styles and Wood (LON:STY) are down 7% today (Wednesday) on a trading statement that seems to be good news despite lower that previous year revenue. Looks like a buying opportunity - what's the bear agrument?
FREng - re. Styles and Wood (LON:STY) I had a look at this stock this morning. My take is
- the 9% drop in rev compared to 2015 becomes approx 15% against broker forecast
- the RNS is careful in saying that management is expecting to meet the Board's expectations, not market expectations
- if you believe that they will meet market expectations for profit and eps despite a 15% fall in revenues, then your faith in this management is a lot stronger than mine
This is a company with lumpy revenues prone to swings as even a change in a single large contract can have a major impact on reported numbers. For this reason I am staying away.
Ram
You said on 31/8/16 that " although too late for this FY, revenue growth from this deal could be around 15% p.a. for 5 years" and that you had bought. I have come to respect your judgement through your postings here, so I would be interested to know when and why you sold again (if you have), given that you didn't expect revenue from the 5 year deal in the 2016 FY.
Cheers, FREng
FReng - Re. Styles and Wood (LON:STY) It's a fair question and I looked up my log of activities to give you a fair reply.
First the background. I am a great fan of Minervini (however not a blind follower) and there are a few hard rules that I just no longer question. My investment horizon is approx 9 mths. So if a stock has the potential to increase by at least 20% in that period (and it passes all other tests) then I buy.
If subsequently the sp falls below 10%, I sell. No ifs, no buts. If the sp rises and continues to rise then I just enjoy the ride and watch it grow.
In the case of STY, I went long in August last per my post at that time. In November, the sp dropped below my 10% red line and I sold.
Looking at the sp chart today, it did recover to above my buy price. In the past, I used to kick and swear at myself but not any more. For every one such stock that looked as if I goofed, there are more which the 10% rule saved me from a major loss.
So my investment framework today is far removed from the long term hold-forever, PE-is-king, GARP model. I do admire people like Lord Lee, but that requires a temperament that I do not possess.
One last comment about today's RNS. When management's credibility comes into question, I used to give them the benefit of the doubt first time round. Not any more. The probability that they disappoint again is a lot higher than thought - based on my experience.
Hope it helps, Ram
Ram,
Thanks for the detailed reply, which I found very helpful. Gradually, I'm becoming more successful as an investor and, in great part, it is from understanding what other investors have found through experience. Thanks very much for sharing yours her so generously.
Regards
Freng
I think my issue with Styles and Wood (LON:STY) is that it shows mgt in a slightly shifty light , i.e. perhaps attempting overly aggressive revenue recognition that came unraveled at year end either pre auditor involvement or worse post their involvement . Given that the business nearly went bust once and the newish CEO is the guy responsible for refocusing and rescuing the business trust is key issue imho . I used to hold but will not revisit until they can discover the art of writing a clear & unambiguous RNS's
Re Utilitywise (LON:UTW), here are some more (mainly bullish) points to consider:
1) The terms of the early payments must not have been attractive to UTW. Hence the change in terms back to the previous arrangement
a. Would not be surprised if Woodford, with his long-term outlook, put pressure on the company to amend the contracts.
b. The company/bank will have modelled the cash flow and headroom, and noted that they had sufficient room available to allow for the H2 cash outflow. Otherwise why would the company make the change?
2) The creditors are due from the big energy providers – minimal credit risk. Although we should normally discount such aggressive accounting, it seems more credible than other scenarios (very reluctant to say ‘this time it’s different’!!)
a. Shareholder list including Woodford and Gervais Williams, amongst other well-respected names must have conducted and been content with their due diligence
3) Stockopedia algorithms’ are impressed. QV rank of 97 (stockrank of 77 held back obviously by momentum)
4) EV:EBITDA multiple of 5.4, PE ratio of 6.6x, yielding 5.4% with impressive quality matrics (given low asset base required) are attractive.
5) The lack of growth of EPS and margin compression is worrying , but:
a. The order book is up 24%
b. Energy consultant headcount up a further 6%
c. Group customers up 17%
d. Introduction of non-domestic water competition should be further opportunity, and;
should see future growth of revenues come through. Can the company maintain its margins though is a more important question – does it actually have a USP?
6) The goodwill write-off of the acquisition is a concern – maybe part of kitchen sinking by the relatively new CEO? Either way, not good. Surely someone should be held accountable for such a poor acquisition?
To summarise, I don’t think it is all doom and gloom, and once you get as comfortable as you can be with the aggressive accounting, you are presented with an attractively valued business, with good quality measures, which should become cash-rich in years to come (once the creditors are settled).
Having held Utilitywise (LON:UTW) in the past, I think the bull case points are well made but the elephant in the room is the spiralling debt and falling share price. I don't see banks being too willing to give the benefit of the doubt indefinitely (even if Mr Woodford is) which suggests there might be a dilutive placement on the horizon if there is a hiccup in the business to shore up the balance sheet. Long term prospects are decent ..... but the journey could be pretty bumpy IMO.
Best,
Gus.
p.s. Epic write up today Paul. I've read shorter books before now and all this quality produced in a matter of a few hours. I do wish you wouldn't sit on the fence with your opinions on the likes of Koovs though
Gus. Re: "I do wish you wouldn't sit on the fence with your opinions on the likes of Koovs though."
I think that Paul was more robust on Twitter, and said that he was now short. That limits what he can say here.
FREng
Hi FREng,
No, I've never shorted Koovs, and am not planning on doing so.
It's too small & valuation too erratic, for me to want to risk shorting it.
Regards, Paul.
Hi, Paul
My apologies. I misremembered the tweet - it was Asos you said you had shorted. It's hard to tell one disaster share from another ....:)
FREng
Hi Paul,
I have read extensively your quality assessments, but there are some anomalies which puzzle me. You have a long investment in Treatt for good reason, as it is fair to say it is a classic Minnervini stock. I would argue that Keywords Studios is another classic Minnervini type stock. Yet you mention that the stock is pretty expensive now, but so is Treatt on the same type of analysis. The point I am making is that it is probably fair to argue that a stock is either cheap or expensive on which strategy you are utilising. I.e. Expensive, on a classic value strategy, but good value for its earnings growth if you are using a Minnervini picking style. You stated:
"As Minervini points out, his historical analysis shows that most multibagger shares are actually on a PER of 30 or more before the big move upwards starts. So if you screen out anything with a high PER, you are excluding the biggest future potential winners from your portfolio - which sounds a pretty dumb thing to do"
So I am quite surprised that you seem luke warm about the stock. It has a healthy quality and momentum stock rank, rising revenue, improving profits, and low net debt. The company has already seen upwards EPS revisions and based on the company outlook could see future earnings upgrades.
Regards,
Roque22x
1 UKInvestor
Hi Paul. I was there for both your sessions & think you did fine, particularly after eventually arriving for the first one. Admittedly you took a bit of a pasting in the first 20 minutes whilst still travelling to the interview.
2 Franca Manca
It must be well over a year ago that I first spotted people queuing outside a pizza shop on Tottenham Court Road. Not checking out the ownership was a failing, since this is one of the few examples of a roll out that is quoted !
Outfits such as Wasabi are privately owned, so no chance to participate there.
3 Tasty
The CEO made a token purchase today, 50,000 shares, which is about a 1.2% increase in his holding.
Fascinating to read the " depths of despair " paragraph.
I went through the same emotions over the same period ,probably for similar reasons. I lost my sad job on the day Merrill Lynch went down.
I pulled out of it when I made myself look at the remnants of my portfolio ...." Aberdeen New Thai"....Ashtead ...Berkeley ......and Staffline....all courtesy of FT .....Persuaded myself I am good and to get back into swimming with the sharks., I now have money to spend on myself.......first time in my life.
I am back surfing down the crest of the wave.......trying to avoid being dumped........great fun.
Hi Paul, your tale of stage fright brought back memories and if I may I'd like to share with readers some training I had back when I worked for an American company. They were very big on develeloping all aspects of one's potential and presentation skills was an area where I was wanting.
As you said, solid prior preparation is essential so you know your stuff but also essential is that you don't dwell on any negative feelings while you prepare. It's so easy to visualise yourself making a mess and forgetting your talk that it becomes self fulfilling, so you have to use the same visualisation process but in a positive way. Imagine the look on the faces of your audience as you lmpress them and imagine the applause as you finish a faultless performance. If you repeat this process, you can convince yourself that you've done whatever makes you nervous many times before. Remember the difference between fear and excitement is what you choose to call it. I used this technique when sailing on a tall-ship and found a fear of heights had gripped me. By convincing myself that I had climbed aloft many times I was able to overcome my fear. Wish I'd done that training when I was young.
A couple of other bull points on Fulham Shore (LON:FUL):
- Its Franco Manca restaurants have small floor space, often using a previously unattractive venue so maybe property costs are lower? In London their branches are often completely full with people queuing down the street to get in (which is usually regarded by punters as a positive sign about the food quality). I suppose this could be a negative in that it might mean individual sites are not as profitable as the sites of chains with larger floor space maybe? But I think part of the problem with Tasty (LON:TAST) is their restaurants that I pass are larger and often have a number of empty tables even during peak times.
- Fulham Shore (LON:FUL) 's restaurants have pared down interiors which means capex must surely be lower than most restaurants I would have thought?
I have bought some Fulham Shore (LON:FUL) today as I am happy they have increased their bank facilities rather than dilute shareholders with another share offering. I have also seen an estimate of 0.9p EPS for y/e 2018 which makes it look reasonable value especially when I personally think it could easily grow into 250-300 restaurants in the UK alone. Its cheap and quick offering and the smaller floor space of its restaurants would work much better in out of city locations than other restaurant roll-outs I think.
In reply to John Eustace, post 23.
"You will have missed TW's blind tasting of tonic waters on the stage at the Investor Show in the morning "
Twelve volunteers from the audience...."
That should ring warning bells for anyone, let alone serious investors. IMO of course.
Hi Paul,
Have you any comment on the end of year results and trading update issued by Flowtech Fluidpower (LON:FLO)
Cheers
Simon
Further to my last post (29), just to clarify that I can see why cashflow is important, but you seem to have used cashflow and ebitda interchangeably in your article. But surely cashflow will allow for capex of both new stores and maintenance capex whereas ebitda will ignore both. To me you have to take account of the capex somewhere. Maintenance capex (or the depreciation arising from it which over the long run on average should presumably be the same) are real ongoing costs and reduce cashflow so surely you can't just look at ebitda, which ignores it. The set-up capex of new stores could arguably be ignored (especially if it just comes out of cashflow from existing stores) and could be thought of as one-off which could be adjusted out, but maintenance capex or its depreciation is by definition ongoing so affects the long term cash generation of the business. Sorry if I am being long-winded, and no doubt confusing or missing something, but would really appreciate a clarification. Thanks.
Hi dgold
I am with you. Firstly when it comes to EBITDA I am always reminded of the Charlie Munger aphorism "I think that, every time you see the word EBITDA, you should substitute the word ‘bullshit’ earnings.” (https://www.forbes.com/sites/brentbeshore/2014/11/13/ebitda-is-bs-earnings/#5d5eca7a6070).
I had a look at Revolution Bars (LON:RBG) last published accounts and could not make out what they were allowing for in net profit and could not figure it out.
For me I am generally interested in what Buffett calls owner earnings so profit + DEPN - less capex. I think it is reasonable if a company is in a roll out faze to add capitalise the opening cost of a shop or bar and then depreciate that over the life of the bar/shop. But in this instance the only profit figure I would be interested in would be the profit less this depreciation of opening costs.
To be honest in my ignorance I don't really know what maintenance capex is but is am not sure that it needs to be distinguished from CAPEX. After 10 years (say) the shop/bar needs to be refurbished and the cost of doing this will covered by the DEPN reserve.
So for me a roll outs try profitability in its early stages (any stage) is after deducting depn of the opening costs.
But maybe I am wrong?
purpleski,
Phil at Sharescope shares your views about Revolution Bars (LON:RBG) in particular:
http://sharescope.us11.list-manage1.com/track/click?u=ecc374bffc2d8dd2c75f5005b&id=d79839407a&e=23419ac258
and EBITDA for restaurants and bars in general:
http://sharescope.us11.list-manage.com/track/click?u=ecc374bffc2d8dd2c75f5005b&id=c05712cbc1&e=23419ac258
Regards,
Seadoc
Purpleski, thanks for commenting. In the Forbes piece that you link to the author explains the difference between maintenance capex and growth capex i.e. growth capex is what you need to pay to expand the business, I think that could be something like the cost of buying a new shop and the major costs of fitting it out for the first time. Maintenance capex is what you need to pay every so often to keep things going. So it could be a partial refurb every few years which you would depreciate over its expected lifetime. I would argue (and I think this is Paul's main point wrt rollouts) that to understand the long term cash generation potential we can ignore the growth capex as it has already been paid (hopefully out of prior cashflow without incurring debt) and the depreciation arising from it can also be ignored. But I would still say that we shouldn't ignore all the small refurbs which will have to be done continually from time to time. So if on average every 5 years the company needs to spend £50k on renewing something or another in a shop we should deduct £10k from the yearly ebitda to get an idea of the real long term cash generation potential (of course there are other problems with ebitda eg why ignore interest costs but let's ignore that for now - I am just talking about the capex side of things). The initial cost of buying the shop as well as any major one-off costs to initially set up the shop in its needed form can be ignored as they are growth capex and have already been spent and should not need to be spent again.
With Revolution Bars (LON:RBG) although it is hard to glean the information from the accounts, Paul referred to the company's presentations, at https://www.revolutionbarsgroup.com/investor-relations/results-centre/ In the one for 2016 (page 8) they break down capex and show free cash flow after deducting just "Maintenance capital expenditure" and list separately the "Development capital expenditure" which is for opening up the new bars (actually they don't buy the properties but they still have a lot of one-off major set-up costs to fit out the bars). The first figure is I think the relevant one, so I actually agree with Paul on this i.e. that Revolution Bars (LON:RBG) has a lot of potential. I am just disputing the equivalence Paul seems to make between ebitda and cash flow, as you certainly have to deduct the maintenance capex even if you don't deduct the growth capex.
Hi dgold
Thanks for the input.
I am still confused :-). I get the difference between maintenance CAPEX and CAPEX (the actual cost of fitting out the bar in the first place). For example tables and chairs will have been purchased initially to open the bar and from time a customer breaks a chair it needs to be replaced
But for me at some point everything in the bar will have to be replaced because it is out of date/tired etc. The original fit out might be good for 20 or 30 years (or even longer) but as some point it will be shut and completely refitted. If I was the owner I would rather that that fit out was carried out from a depreciation reserve and there for me when calculating any cash that the business is throwing off after opening I would always deduct an amount for the eventual refurbishment of the business.
I think that this is quite a good explanation
http://www.valuewalk.com/2016/11/warren-buffett-not-believe-ebitda/
And this as well
http://www.charleswarner.us/articles/WarrenBuffett_EBITDA.doc
Purpleski
In Accounting terms, all expenditure is either expensed immediately else capitalised as a Fixed Asset, & subsequetly depreciated.
For Revolution Bars (LON:RBG), the two principal Fixed Assets are:
So the annual depreciation charge will give an indication as to the likely level of maintenance capex.
https://www.revolutionbarsgroup.com/files/3414/775...
We filmed the Keywords Studios (LON:KWS) analyst presentation this morning, and the full edit will be available tomorrow here on Stockopedia, under Keywords Studios (LON:KWS) "discuss", with a link to the video on PIWorld.co.uk.
It was all very positive.
Tamzin
Hi Paul,
My sincere apologies and I didn't mean to embarrass anyone.... it was as I said.... I've known his name for years but couldn't remember anything about him so simply put it into Google. I have no means of knowing whether this stuff is true or not as with possibly a lot of stuff on the net these days. Maybe it's all fake these days, for all I know.
I do know for a fact though after 23yrs in the game that a lot of share talk has to be taken with a large pinch of salt!! :)
Frank
General question.
Where a Company reports EBITDA up against the prior year, but Net Profit down against the prior year, would we consider the 'potential' position is that the Company has increased adjustments to allow a flattering headline comparison by increasing its adjustments?
I appreciate ideally EBITDA and Net Profit should both be flattering comparatively, but with the trend to reporting EBITDA improvements it is perhaps one of the temptations?
Paul, I know you don't have time today but would you please consider finding the time at some point to explain why EBITDA is more important than profits with rollouts? Certainly, I can't see why you would want to ignore maintenance capex in considering the real profitability of each store. This issue has been sort of discussed in the comments wrt to Revolution Bars (LON:RBG) and it would be really nice if you could enlighten us on exactly how and why you do your sums. Thanks in advance.
Hi dgold,
What retailers & leisure operators do, is look for new sites where they can achieve a rapid payback. So anything that should deliver a 2-3 year payback on the capex, is an excellent additional site.
You really don't have much (if any) maintenance capex in the first 2-3 years, because everything is new. So the new site has paid for itself within 2-3 years, then afterwards it's basically free - all the additional cashflows from that site can then be recycled into funding further new openings. It becomes a virtuous circle.
Maintenance capex is needed on older sites (ones that have been open say over 3 years), but it's not a big deal. Revolution Bars (LON:RBG) for example say it's about 4% of turnover, which is about £5m p.a., so maybe £80k per site? Those are big sites too. So for restaurants, of the like Fulham Shore (LON:FUL) operate, the maintenance capex really wouldn't be much at all - at a guess I'd say probably no more than £20k p.a.
I think if you're looking at a large, and quite old estate, of the kind that say £EI has, then maintenance capex, and a run-down (in part) estate where pubs haven't been revamped for 20 years, in some cases, becomes much more of an issue.
It's not an issue with roll outs like Revolution Bars (LON:RBG) and Fulham Shore (LON:FUL) where the sites are "well invested" - i.e. modern, and in a good condition already.
Regards, Paul.
Paul thanks for the update on Fulham Shore (LON:FUL). It's long been one of my favourite growth shares but I'm biased towards it being Italian myself! Everyone I know seems to prefer Franco Manca to Pizza Express (Tastier dough, cheaper etc)
Were the UK Investor Show segments filmed? I wish I could have been there.
Decent results from Keywords Studios (LON:KWS).
It's interesting that they bill their clients on a time and materials basis only. Given that their credits include some of the blockbuster games titles (think Call of Duty, Grand Theft Auto, Assassins Creed etc.), I would have thought a revenue/profit share arrangement could provide better upside potential.
M&A is clearly core to their strategy so I've been looking at their track record on acquisitions this year and last. Perhaps it's too soon to tell, and focusing on one year's performance may not be a reasonable approach but with that proviso, I'm going to do it anyway.
Overall that doesn't look too bad to me, given that presumably cross-selling opportunities and other strategic benefits won't have had a chance to become fully apparent yet. In some cases I'd say it's even verging on 'looks too good to be true'.
Also worth noting while reading through the acquisition RNSs is that in most cases the founders/sellers are staying on with the company, which is clearly a positive, and as part of the consideration they are given shares with a lock-in period.
It's not all good though; the considerations paid for Mindwalk and Volta Creation look a bit on the high side given the multiples paid for the other companies.
Mindwalk made PBT of $0.8m in 2015 and $0.4m in 2014 (per the acquisition RNS), so to make PBT of only €0.3m in 2016 looks like a big step backwards, particularly when they made the comment at the time of acquisition "Good further growth is expected in 2016".
Volta Creation also seems to have gone backwards since acquisition - PBT of €0.278m in 2016 compares to CAD700k in 2015 (approx. €490k at a rate of 0.7).
I've been a Keywords Studios (LON:KWS) holder for a while now and that's a very helpful summary of their flurry of acquisitions.
Many of the acquisitions are best described as "acquihires" in my view - buying in the expertise and contacts and combining them to build a business that can offer a complete service to the games studios, short of actually coding the games for the time being at least.
For that reason my focus is on the end goal - will they build that coherent business that can take a large chunk of a huge opportunity. So far it seems they may well be able to do that, provided they can keep integrating the parts successfully.
Paul,
You will have missed TW's blind tasting of tonic waters on the stage at the Investor Show in the morning.
Twelve volunteers from the audience were invited on stage without being told the reason. Each was given a glass of tonic water A to drink and then each was given a glass of tonic water B. They were then asked to put their hands up to say if they preferred A or B.
Ten preferred A, one preferred B, and one didn't have a preference.
You can guess where this is going. Tonic water A was Fevertree, and B was Schweppes.
So ten out of twelve investors prefer the taste of £FEVR tonic
Interesting, but of course that doesn't mean 10 out of 12 people are prepared to pay a big price premium for the tonic they preferred.
John
I realise it was just a bit of fun, but really the order of the test needs reversing to check, because we all subconsciously know A is better than B, not to mention the possibility of presentation order bias. So, good for a bit of fun but don't base your investment choices on it.
Hi Paul
Adept Telecom (LON:ADT) ( a long term and quite profitable hold for me) put out a decent trading statement today. Would be interested in your view.
Thanks
Crystal Tipps
I'd also be interested in Topps Tiles (TPT) if you get the time. Thanks
Paul,
Not sure if you will be commenting on the results and Q1 trading update from Flowtech Fluidpower (LON:FLO) today but looked very good to me and worthy of a top up first thing this morning. Is Malcolm Diamond building another Trifast (LON:TRI) ? I guess only time will tell but the omens currently look very good on that front. Looks too cheap to me!
All the best, Si
The end of year report looked good, then the 1st qtr update. Has anyone else got it out so soon? Cracking numbers and have averaged up this afternoon.
Paul
On Keywords (KWS) I'd be especially interested in your views on the believability of its EPS growth given:
* the large number of acquisitions
* the adjustments made to their preferred profit metrics.
Also, on the plus side, statutory EPS is also growing fast and cashflow looks decent (your opinion please). On the negative side there must be an increased risk that some of the acquisitions fail to mesh or that the group becomes unmanageable with acquisitions taking place at such a fast pace.
Thanks as always. Sorry I couldn't get to the show this weekend Would have been good to see you and thank you in person.
paul any chance you can do a remix for us on 'who let the dogs out' woof woof wooof
Went to Franco Manca on Saturday night: olives, 2 pizzas, bottle of ale and glass of wine, all in for £25. Free tap water so no need to squirm when asked by disdainful waiting staff if you want Perrier sparkling or still.. A cheap and cheerful profitable and unique rollout like no other I've been to. A success in the making.
Paul - good to meet you on Saturday. I particularly enjoyed winning a bottle of Distil PLC rum at UK Investor show! :)
I notice TW shares the same interviewing technique as Nigel Farage. He tends to ask the questions that confirm his view of the world. Mind you even Farage, as much as he likes the sound of his own voice, does occasionally allow the other person to speak!
I was half expecting you would arrive at Tom Winnifriths interview just before noon shouting "April Fool!" but it turned out you had fooled yourself!
You managed an impressive recovery in the circumstances even if it was all as scripted as a wrestling match.
I thougt you came over really well as the interviewer on the main stage - another string to your bow if you want to keep that up.
Keywords Studios (LON:KWS) - is a marvellous company. Fantastic growth and more importantly, it appears to have built itself a solid moat and is working in a growing industry. It has good relationships with almost all of the major games developers.
Disclosure - I hold
Hi Paul It hasn't been updated yet and I am sure won't be until they announce the results but Allenbys (the house broker) publishes broker notes for Fulham Shore (LON:FUL) on their website. Keep up the great work. Cheers Greg
I looked for a reminder of Tom Winifrith's history and came across this 'interesting' item
http://financialtrolls.blogspot.co.uk/p/tom-winnifrith.html
Hi Frankyboy.
There's been all sorts of stuff about Tom's history on the internet for years, which he's answered lots of times before. So if people want to rummage around on that subject, they can do that elsewhere.
Can we please keep ad hominem attacks & links to them off Stockopedia, it's just not the sort of thing that Ed & Dave want here.
Thanks,
Paul,
Hi Paul,
I think you came over well in your interview with Tom Winifrith, which I suspect is no mean feat, particularly when the volume on your microphone was much lower than his and so easily allowing him to drown you out. Does he do this on purpose.
Gordon
Hi,
OK - I'll take a look at the figures for Keywords Studios (LON:KWS) and see if I see anything funny. will report back shortly.
Also, yes I'll look at Utilitywise (LON:UTW) and Next Fifteen Communications (LON:NFC)
I've got to take the dogs to the doggie grooming parlour at 12:30, as we're having problems with their hygiene in the house (I won't go into the details), so they need their fur clippered off. Will do a bit more on today's report now, then another chunk probably mid-afternoon, in between dropping off & collecting the dogs.
Oh, the glamorous life of a homeworking writer/investor!!! LOL
Regards, Paul.
Ill be interested to see your thought on Ultilitywise and if they changed the accounting methods with the new FD.
Paul would it be possible to comment on Next Fifteen Communications (LON:NFC) results today? Another one - there have been a few recently -
where good sounding results are nevertheless followed by SP going down instead. Perhaps net debt on this one?
Hi Brackendale - I too am puzzled by the market reaction to Next Fifteen Communications (LON:NFC) . The numbers look OK and seem to beat broker forecasts.
The two negatives which might have a bearing on this could be: 1. the company is going deeper into negative tangible book value territory (lots of acquisitions in the past) , and 2. huge adjustments to the p/l account. For example statutory net profit £1.1m but adjusted np = £18.9m, largely due to share-based payments.
Would you be able to have a look at Nanoco Paul if nothing else it will remind you why you made the right decision to avoid blue sky for the last few years, I think the penny has finally dropped with me after investing in this one.
Cheers Andy
Initially I wasn't too concerned by this either and thought they might be testing the water of a franchise model for future overseas expansion, however I read a report elsewhere that said it was essentially to train pizza chefs before they come to work in the restaurants in the UK. In the face of Brexit and its knock-on effects for EU immigration, that seems a bit of a strange thing to do. However, as you say, it's not a huge investment by the company.
It also came to my attention that the Franco Manca Chorizo pizza is the most popular meal requested on Deliveroo in London. I hold a few as I very much like the concept and it seems like a good roll out with experienced management.
All the best, Si
Hi Paul,
Any chance that you'll cover Keywords Studios (LON:KWS) Final results today? Seem like very good numbers and a lot of PI's hold these. Was concerned about the goodwill growing and the capitalisation of costs - your thoughts?
Thank you!
Hi chillax,
I might mention Keywords Studios (LON:KWS) in passing, but don't feel I can add any value commenting on it, and don't have any particular insights on it, as I don't really understand the sector at all (When has that ever stopped me before, I hear you cry!!! lol)
Regards, Paul.
Hi Paul,
I was more interested in your accounting specialism specialism :-)
Hi Paul You mentioned a while back that the accounts for Utilitywise were suspect and today this appears to be confirmed with a drop in share price and restatement and adjustment to the accounts. Your current view would be appreciated.
Thanks
Ken