Small Cap Value Report (Tue 4 April 2023) - RFX, SAGA, WAND, EPWN, ACSO, VLG, GHH

Good morning from Roland and Graham!
Today's report is now finished (10.20)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's section
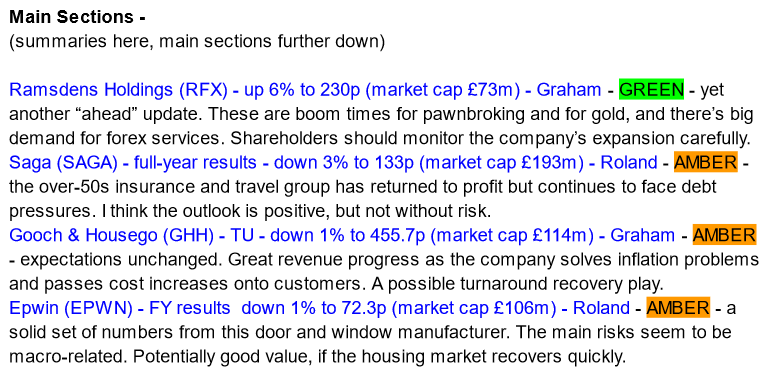
Ramsdens Holdings (LON:RFX)
- Share price: 230p (+6%)
- Market cap: £73m
It’s an “ahead of expectations” update from Ramsdens at the end of H1 (the period ending in March)..
It has turned the production of good news for its shareholders into something of a habit:
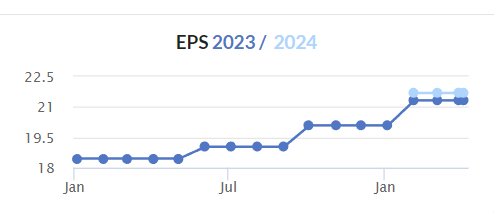
FY September 2023 PBT is now expected to be “not less than £9.5m (FY22: £8.3m)”.
Every Ramsdens service appears to have done well in H1:
Jewellery retail gross profits up 20% year-on-year
Foreign exchange service up 40% year-on-year (though still below pre-Covid levels) as international travel trends continue to improve.
Pawnbroking loan book up 13% in six months to £9.7m, a new record high.
Previous metal volumes purchased up 20%.
It can’t hurt that the price of gold has been very firm, especially since the start of 2023. That’s a tailwind not just for precious metal purchasing but also for the amounts that can safely be loaned through pawnbroking.
Ramsdens is expanding into the South-East and can now be found in places like Basildon and Croydon. I do wonder about the wisdom of expanding into these areas and competing head-on with H & T (LON:HAT) - there are three H&T stores in the middle of Croydon, for example. Will Ramsdens be able to make a living there from foreign exchange alone?
At least the pace of the expansion hasn’t been too aggressive - six new stores opened in H1 - and so hopefully Ramsdens will be able to see if it’s working before they continue..
CEO comment:
We are successfully executing against our long-held strategic priorities. We are focused on driving organic growth by delivering ongoing continuous improvements to our operations, expanding the store estate - for which we have a strong pipeline of potential new stores - and investing in our online offering. In addition, we are continuing to seek and appraise attractive consolidation opportunities in what remains a highly fragmented market."
Estimates - their broker upgrades the FY 2023 adjusted PBT estimate from £8.9m to £9.6m, and their corresponding FY 2024 estimate from £9.3m to £10.1m.
My view
I’m going to give this stock the thumbs up.
It’s obviously not without risk, and previous boom periods have seen successful pawnbrokers overextend themselves and then get into difficulty. So I don’t think this is a “buy-and-forget” type of stock (there aren’t many of these).
Instead, it’s a “buy-and-monitor” type of stock - are their new stores performing well? And if they make an acquisition, that will need to be carefully studied.
But I’m a big fan of their core business and it’s performing wonderfully for now, so I have to take a positive view here.
Gooch & Housego (LON:GHH)
- Share price: 455.7p (-1%)
- Market cap: £114m
This manufacturer of laser components and systems releases an update for H1 (to March 2023). Full-year expectations are unchanged.
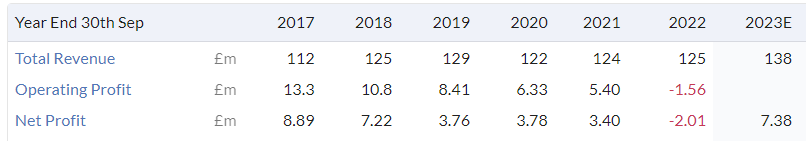
Let’s quickly review some of the key issues facing the company, which fell into unprofitability last year (FY September 2022).
Firstly, the order book became bloated.
Thankfully it appears to be under control now and stands at £124m, providing “good coverage for our expected second half revenues”. Historic orders needed to be fulfilled before the company could pass inflationary cost increases onto customers.
Revenue has grown strongly to £71m (H1 last year: £54m), “supported by favourable exchange rate movements and the effects of price increases to offset cost input inflation”. So the company is solving the inflation problem.
In addition to cost inflation in the supply chain, salaries have had to increase.
Demand sounds robust:
New orders for the Group's products from our semiconductor, data communications and next generation industrial laser markets have continued to be strong… whilst there is evidence that some of the Group's customers in certain industrial and medical laser sub markets are overstocked we expect this position to rectify itself in the second half of the financial year due to underlying end market demand.
Net debt is £19m.
Forecasts - finnCap are forecasting adjusted PBT of £9.3m in the current financial year, rising to £11.8m in FY September 2024. They see only c. £2m of adjustments to these figures in each year.
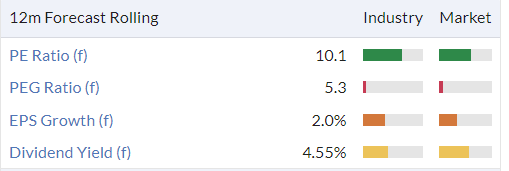
So the P/E multiple is at a reasonable level, even if you want to use unadjusted PBT numbers.
My view - I’ve always found this company interesting, but it has sadly never proven its quality as an investment proposition.
At its current level, it arguably offers some turnaround possibilities. The price to sales ratio is less than 1x and if it hits its targets over the next 18 months then the stock looks attractively priced.
I’ll stay neutral because I just don’t think it has enough quality for me to have the confidence to take a more positive stance. But readers may find more here than I do.
Roland’s Section
Saga (LON:SAGA)
- Share price: 137p (pre-market)
- Market cap: £192m
Preliminary results for the year ended 31 January 2023
Saga aims to become The Superbrand for over-50s and is undergoing a turnaround under the chairmanship of Roger De Haan, a member of the company’s founding family.
Today’s full-year results appear to show a strong recovery in underlying profit, but in fact only one part of the group’s business – insurance broking – actually generated a profit last year.
This situation is set to improve in 2023/24, with the travel and cruise businesses returning to full profitability. However, the accounts suggest that the group’s leverage situation remains potentially challenging, despite improving trading.
Financial summary
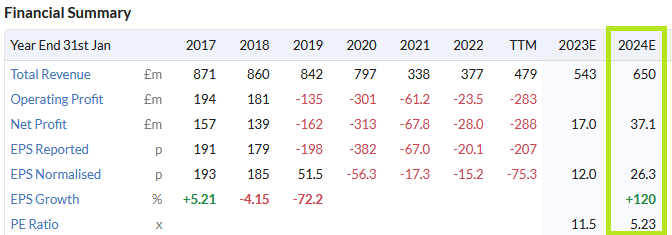
Saga’s headline numbers show a welcome return to profit and a (slight) reduction in net debt. Underlying earnings appear to be in line with Stockopedia’s consensus estimate of 12p per share.
Revenue: +54% to £581.1m
Underlying pre-tax profit/(loss): £21.5m (FY22: (£6.7m))
Statutory pre-tax loss: £254.2m (FY22: (£23.5m))
Underlying earnings per share: 11.9p (FY22: (11.1p))
Available operating cash flow: -28% to £54.9m
Net debt: -2% to £711.7m
Leverage ratio: 7.5x (FY22: 11.7x)
The large statutory pre-tax loss relates to a goodwill impairment charge on the group’s insurance business included in the half-year results. No further impairments have been reported today, so I don’t think we need to worry about this.
Going concern risk? Saga’s leverage still remains extremely high and the company’s going concern notes flag up the ongoing risks.

The group has a £150m bond repayment due in May 2024. The comments in today’s going concern statement suggest to me that funding this redemption could be difficult, if the sale of the insurance underwriting business hasn't been completed by then.
As there’s “no certainty” of an insurance sale, Saga has now agreed a £50m loan facility with chairman Roger De Haan. If needed, this will be used to help fund the bond repayment next year.
On the basis of this new loan facility, the accounts have been prepared on a going concern basis. I think this situation will probably be managed successfully, but I don’t think equity investors should ignore the potential risk of further dilution if trading doesn't improve as hoped.
Operating performance
Cruise: Saga says that its ocean cruise operations generated a pre-tax loss of £0.7m last year, but returned to profitability during the second half, with a profit of £6.2m. A full-year profit is expected for the current year.
Load factor (the percentage of tickets sold) and daily revenue figures are showing a clear trend of recovery:
2021/22: 62% / £299
2022/23: 75% / £318
2023/24 (to date): 72% / £339 - “on track” for target profitability
The company’s river cruise business generated a pre-tax loss of £5.1m last year. However, bookings are said to be 23% ahead of the same point 12 months ago and management expects a return to profitability this year.
Travel: this business generated a loss of £4.1m on revenue of £108m in 2022/23. Bookings at the end of March were 32% ahead of the same point last year, helped by new product offerings such as private jet tours. This business is also expected to return to profitability in 2023/24.
Insurance broking: Saga’s insurance broking business generated a pre-tax profit of £67.7m last year (2021/22: £66.6m).
The total number of in-force policies fell by 3% to 1.7m, despite a recovery in travel insurance sales, which doubled.
Customer retention across home and motor was good, at 83.8%. This seems to suggest that Saga’s brand and/or pricing remain attractive in the over-50s market.
The decline in policy numbers seems to be linked to a decline in new business sales, where 7% fewer policies were sold.
Saga isn’t the only UK insurer to report a slowdown in new business last year - it looks like this may be a consequence of the new regulations requiring insurers to charge new customers the same prices as renewal customers. I guess this will even out over time, perhaps with a lasting reduction in switching and improvement in retention.
Insurance underwriting: last year was tough for UK motor insurers, with escalating claims costs driven by a return to normal driving post-Covid (higher claims frequencies) and a massive increase in repair costs and used vehicle prices.
Saga’s underwriting business reported a pre-tax profit of £19.1m thanks to reserve releases from the previous year of £25.1m. However, these numbers tell us that the group’s underwriting for the year was loss making.
The company says its continuing to “apply material price increases to the motor book”, reflecting continued inflation.
Saga hopes to sell this business to raise cash and repay debt, as I discussed above. Today’s results confirm this process remains ongoing.
My view
Saga’s insurance broking business remains the profit engine of the group. Its brand clearly has some value.
Alongside this, I do think it’s reasonable to expect a significant recovery in profitability from travel and cruise operations this year.
The company’s over-50s customer bases are more affluent than average and much less likely than most other demographics to be affected by cost-of-living pressures, in my view.
I have some concerns about the group’s debt position, but I think that this will probably be resolved without requiring further equity fundraising.
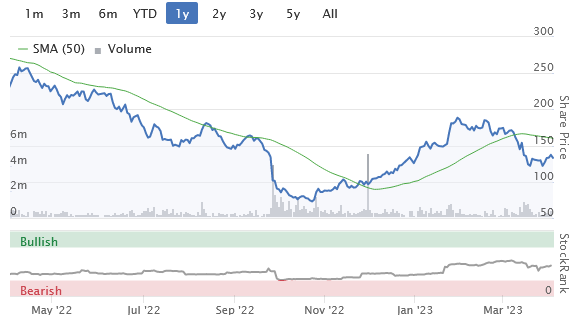
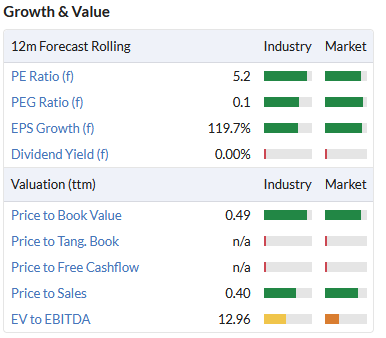
The shares look cheap on a forecast P/E of 5 for the year ahead. But given the financial pressures on the group, I would say the shares are priced about right for now.
Epwin (LON:EPWN)
- Share price: 72p (-1% at 09.00)
- Market cap: £106m
Final results for year ending 31 December 2022
"We have begun the new financial year well. Whilst cognisant of the macroeconomic and market headwinds, the Group remains confident of delivering a further year of strategic and operational progress in 2023, supported by the strength of the medium and long-term drivers of our markets."
Epwin makes doors and windows for residential property, so I think the group’s trading is of interest as a general barometer for the wider economy.
Today’s results cover the last calendar year, so are somewhat backward looking. But the numbers do seem to indicate stable levels of trading, despite some pressure on costs and new-build demand.
Financial summary
Epwin’s headline figures for last year appear to be fairly stable:
Revenue: +8% to 355.8m
Pre-tax profit: -7.8% to £11.9m
Adjusted earnings per share: -2.3% to 8.95p
Dividend: +8.5% to 4.45p
Net debt ex. leases: +90% to £17.9m
Net debt/EBITDA leverage: 0.6x (2021: 0.4x)
Operating margin: 4.8% (2021: 5.4%)
Debt levels look comfortable enough to me - last year’s increase was linked to £17.8m of acquisition payments. Without this, debt would presumably have fallen.
Shareholders get a dividend increase, giving a yield of 6% at current levels. This payout should be covered comfortably by free cash flow, before acquisitions.
Current year trading & outlook: Epwin says that trading so far in 2023 is in line with the Board’s expectations. Revenue so far this year is said to be ahead of the same period last year.
However, the company says that “signs of a slowdown in the housing market” could contribute to a slowdown in both RMI (repair, maintenance and improvement) and new-build markets in 2023.
Epwin says its scale and diverse customer base should provide some resilience against this, but acknowledges the uncertainty.
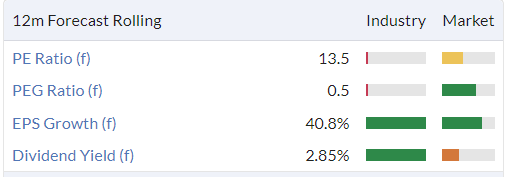
According to Stockopedia, broker forecasts suggest a modest level of earnings growth this year, compared to 2022.
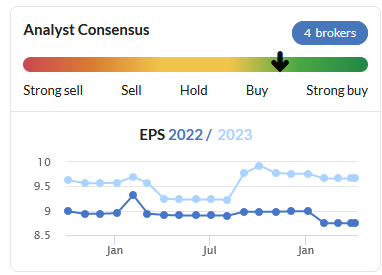
If these estimates are correct and the UK avoids a severe recession, the shares might be attractively valued at this level:

My view
I share Epwin’s view that the medium and long-term demand for the RMI market should remain positive. Epwin reminds us of the “poorly maintained and ageing” state of much of the UK’s housing stock.
I’m attracted to Epwin’s scale and respectable profitability, but I’m also mindful that this is a competitive sector where companies often lack defensive advantages.
On balance, I think the shares are fairly valued and Epwin looks in decent shape. The main downside risks seem to be macro-related. This is an area where investors need to form their own view. On balance, I’m neutral here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Roland - your "Stock in Focus Portfolio" link on the right is broke - it returns 404 not found.
https://www.stockopedia.com/fa...
Wynmstay
Heading for the 400p level by the looks of it.
If it pierces below that barrier and heads further south starting to look very interesting.
Great business Im happy to hold and add .
Hi planetX,
I am with you on Wynnstay (LON:WYN). I have a small holding, bought a little early I am afraid. Current NAV is around 680p if you included the land and property held on the books at cost, which equate to about £10M or 50p per share.
See full year results presentation on PI World on 10 February.
Wynmstay
Heading for the 400p level by the looks of it.
I wasn’t convinced when you were heralding the value just below 600p but I can see the case clearly now. On a fag packet basis, relative to shareholder value, the price is approaching the lows of 2019, which was a low for the last decade. And it’s hitting support at two key technical levels - medium and long term moving averages - so this may be it for the drop. Or, as you suggest, it could go another 10% to breach 400p.
There’s a long term record of shareholder value creation but my business career taught me to shy away from customers who always plead poverty, because “marvellous margins make more money”. And agricultural suppliers are levered to commodity prices which have been tumbling. On the other hand, it’s selling under NTAV and the business is thrown in for free!
The technical support it just found is actually the 50% fib off the last move higher from the pandemic low, which would be considered normal price action imo, the 50% level is often in play for commodities and exposed stocks.
Looking for companies with a proven track record of navigating tough times .
Hard times create strong men, strong men create good times, good times create weak men, and weak men create hard times.
Was discussing with someone yesterday that we are in midst of
- a huge recession and high interest rates and a period of great worry
vesus
- a golden opportunity for anyone with cash, a long term mindset and companies / individuals are in a period of great opportunity to acquire quality businesses laden with debt at distressed prices .
I am myself looking at a US company, 22 million turnover, 4 million stock, great brand in a good sector with huge social media .
Reckon this will be sold for circa 500k, its not for me but I had a look and it is quite literally a bargain.
The last years of zero interest rates, booming markets, and silly frothy valuations has created business owners that are weak, hard times create strong businesses, .
Look for entrepreneurial cash rich businesses that have ability to bolt on distressed acquisitions .
A young Mike Ashley type would be having a fields day both now and in the next 24 months.
I think Portmeirion picked up a brand / company a year ago .
Just rambling here, but worth keeping an eye on any companies mopping up great assets at distressed prices (backed by stock ) and building a long term locker room .
As an example reputedly you could have bought Moore Large bicycle wholesaler few weeks ago for 4 million, that came with 25 million stock at cost and a decent portfolio of brands plus a 40 million a year turnover . Was a perfect acquisition for tandem group .
Re Tandem . Im guessing you meant “would have been “ a perfect acquisition for Tandem “if circumstances had been different”. Suspect Tandem have got their hands full enough on the home front without getting involved in other distractions at this point !
I am sceptical of the management at Venture Life (LON:VLG). Below is a cut and paste of my earlier post in response to Paul Hill's interview with Jerry Randall.
"Not for me Paul. Management well and truly blotted its copy book with the equity raise in November 2020. From memory it raised in excess of £34 million at 90p/share. The CEO and CFO then proceeded to sell 2.75m and 1.8m shares respectively at the same price. I was fortunate to exit at that time for a small profit.
Today's share price 40p! The institutions are welcome. For me, there are far better companies to invest in."
Yes, and that was a few days after floating some 'professors' paper on their toothpaste protects against covid. Suckered me in duh!. Toothpaste ok though just a bit expensive.
Major news from Franchise Brands (LON:FRAN) after the close last night, I hold.
They announced the acquisition of Pirtek, a provider of hydraulic hose services for £212M. This compares to FRANs market cap of £315M on the previous day. The purchace is to be funded by £110 of debt and £110m of new equity, including a £90m placing at 180p.
This makes strategic sense, but is a big deal and greatly cranks up the risk. The shares have dropped from 240p to 185p which is more than I expected, but as the results of the placing are not out yet it's understandable...
Interested to hear others thoughts on this.
Haven't looked at the details of the acquisition by Franchise Brands (LON:FRAN) but it does make you wonder about the value in Flowtech Fluidpower (LON:FLO), which I hold.
Flowtech Fluidpower (LON:FLO) shareholder register is a who's who of the great and the good of UK small cap investors, Harwood, Downing, Odyssean Capital, Gresham House.
Franchise Brands (LON:FRAN) placing got away at 180p and price currently hovering near this level. Deal is hailed as earnings-enhancing and I calculate that the revised EV/EBITDA on the undisturbed share price is around 14.5x (from 16.5x) and around 12x on the new price, very close to that of Domino's Pizza (LON:DOM) coincidentally. Definitely a lot better value though it had risen a little too high in my view. The question is whether the acquisition target generates the cash flows to pay down the debt in under five years, as promised by management today.
Nigel Wray is obviously a canny operator but this is a bold step. And my existing franchise business holding Water Intelligence (LON:WATR), with similar growth forecast, is on only 8.5x EV/EBITDA. Who’s buying either?
Greetings from Gozo (a little dot in the Mediterranean!) - here's a video postcard for you! -
https://youtu.be/SowqBP72BGc
In other news, I've updated my SCVR summary spreadsheet, which I think is a useful, quick way to search (using CTRL+F) the ticker of any company we've written about here, and hover over the cell to have a pop-up window show a brief summary.
Link is here (not for sharing outside Stockopedia please!) -
https://docs.google.com/spread...
I've abandoned updating all the other tabs, as I created a monster here, and it takes a ridiculous amount of time to update. But I've kept the main summary tab going, as I find it very useful myself, and hope you do too.
I'm keeping an eye on the markets, and the RNS, but it's very relaxing not having to actually rush out a report every day! Thanks to Graham & Roland for their excellent work in my absence :-)
I'm hoping to do an investor interview this Friday, with CockneyRebel, who is always full of interesting ideas.
I'm also looking forward to the Easter celebrations here in Gozo, which should be pretty full-on, given how religious they are here!!
Best wishes, Paul.
Have fun Paul. Gozo is lovely, just a shame that the Azure Window fell down just after we were there!
Results from Venture Life (LON:VLG) look good with adjusted eps 4.07p cf consensus 3.43p. Cenkos forecast 6.04p this year for p/e 6.6 at 40p. That gives a PEG of about 0.2 which fits in with Slater being the largest holder.
There is an IMC presentation on Thursday and in the meanwhile:
All those acquisitions plugged into their allegedly superb sales and distribution and Venture Life (LON:VLG) only managed 2% pro forma revenue growth. Slipped in some nonsense in the notes that sales of mouthwash are vulnerable to health of Chinese economy (that'll be a goodwill write down coming?).
In product terms they seem to have gone for the throw a lot of sh1t against the wall and see what sticks approach. Remember this is the management that in late 2020 after claiming massive brand breakthrough (in mouthwashes) with the company moving from contract manufacturing to brand. Looked good and profitable...but that was bs as really they had sold a load of hand sanitiser during covid and called that brand and got a bit of windfall in the process. An honest management would have flagged this as a temporary windfall...but Venture Life presented it as business transformation and new higher level...
...then they raised a lot of money at ramped price, sold their own mgt shares into the placing and then went on to profit warn in 2021.
The usual high profile stock rampers love this stock. Expect them all to exit after they manufacture any pop. Play this game at your own peril. Merit where its dues though...mgt have shown they can spend a lot of money and promote their stock.
TBC the stock may be cheap at current price (assuming adjusted profits real...note 15 to the accounts is critical and not yet published as await full accounts...what is that £3.4m of investment in intangibles...my instinct is to be sceptical...this is a consumer goods manufacturing and distribution biz and costs of production should be straight expensed)...but cheap ain't always enough if there isn't good quality follow through. A few sales and product hiccups and this looks like a very expensive stock with more debt than it can stomach.
In my view, for the market to bottom we need the hugely over indebted balance sheets of many companies to be returned to health via dilutive equity issuance. Saga (LON:SAGA) is a good example of this. The new loan from the founder’s son Mr de Haan (who has been incredibly generous with this new facility in addition to his participation in the equity raise a while back at a significant premium to other investors) is simply more evidence that Saga’s balance sheet will ultimately only be fixed via new equity. Their profitability is wafer thin meaning they cannot internally deleverage and while everyone focuses on the Cruise business the reality is that the insurance business (broking and underwriting) was the mainstay that meant Saga’s debt pile was serviceable. With the insurance biz under pressure from inflation (also see the collapse of Direct Line Insurance (LON:DLG) and Sabre Insurance (LON:SBRE) ) then the insurance mainstay is now no longer there (falling policy count and declining broking income per policy is really painful for Saga (LON:SAGA) ). Thus, management need to bite the bullet and raise new equity. Any investors holding this share need to recognise this reality. And investors holding other overly highly leveraged companies (eg pub companies) need to recognise this reality. It won’t be only Cineworld (LON:CINE) that shows the perils of high debt during this downturn.
Last point, good luck to everyone on here. The fact that this chat room is much quieter than a couple years ago shows we are well on the way to completing the flush out. Better days ahead.
Actually Nebraska - insurance is fundamentally cyclical. You are projecting short term downturns in insurance margins to long term profitability. In reality this is probably around the trough of insurance margin pressure. Same for many other insurers. We have seen this across many cycles - its generally a 5-7 year cycle. The insurance industry is very good at re-pricing, there is usually a lag of 12-18 months.
There is no real need for Saga (LON:SAGA) to raise equity at these levels. They are cash generative and with travel at current levels debt is reducing pretty consistently. The next 2 years will see circa £60m come off the ship debt alone. The LTV against that asset will have come down considerably. Good cruise ships hold value very well.
You can't compare asset backed debt with cineworld either. That's an apples and oranges comparison. Cineworld was a basket case buying goodwill with debt. Saga (LON:SAGA) debt is backed by 2 assets with values well in excess of the debt. In an extreme scenario they could sell the assets to a fleet lessor and lease them back. They clearly think there is more value in holding them as assets.
The bond market tells you it is broadly comfortable with Saga (LON:SAGA) debt too btw. The 2026 bonds offer YTM of around 13%, which given interest rate rises on risk free rates has only really added a couple of percent in risk premium on the bonds.
@davidjhill - my source of data about yields to maturity (YTM) of UK corporate bonds vanished a while back and I've only just started looking for a replacement. My platform is HL and their coverage of bonds is inadequate, also they don't quote YTM. Would you be willing to share your source of data?
my source of data about yields to maturity (YTM) of UK corporate bonds vanished a while back and I've only just started looking for a replacement. My platform is HL and their coverage of bonds is inadequate, also they don't quote YTM. Would you be willing to share your source of data?
Personally, this is so fundamental to the investment case for a bond that I would not rely on third party data. It should be easy enough to calculate YTM in a spreadsheet.
All the best, Si
Well, yes, but the Investors Chronicle used to publish the data and so far as I could see it was accurate. My only bond investment is a bond fund (which as you might expect has been a flop) but l do like to look at what the market thinks of a company's bonds before I buy the shares and I just don't have time to input data into a spreadsheet, I just want a quick way of seeing what the YTM is and I used to have that.
It is a straightforward calculation on excel with minimal data input. Courtesy of Chat GPT (and verified with Excel Help!) the formula is as follows:
The formula to calculate yield to maturity on a corporate bond in Excel is:
=YIELD(settlement, maturity, rate, pr, redemption, frequency, [basis])Where:
settlement: The date the bond was purchased or settled.maturity: The date the bond will mature.rate: The annual coupon rate of the bond.pr: The price of the bond per $100 face value.redemption: The redemption value of the bond per $100 face value.frequency: The number of coupon payments per year.[basis]: (Optional) The day count basis to use for the calculation. If omitted, the default value is 0 (which represents the US (NASD) 30/360 day count basis).For example, if you wanted to calculate the yield to maturity on a corporate bond with a settlement date of January 1, 2022, a maturity date of December 31, 2030, an annual coupon rate of 5%, a price of $105.50, a redemption value of $100, and semi-annual coupon payments, the formula would be:
=YIELD("1/1/2022","12/31/2030",0.05,105.5,100,2)Make sure to format the cell as a percentage to see the yield as a percentage value.
Hope that helps.
Thanks, genuinely, but it's not the same has having a list of all the issues updated daily which I can sort in different ways. Setting up a spreadsheet would not take long. Updating the data would take time I don't have.
I agree, Michael C. While the calculation of YTM is easy in Excel, it is useful to have a list when searching for or comparing bonds that gives the YTM, maturity and rating at least
13% seems very high given the base rate. Bonds are lower risk than shares, shares enjoy growth opportunities bonds don't. Indicates risk is high here.
Nebraska1977, quoting your comment on Saga (LON:SAGA) :
"Their profitability is wafer thin"
"With the insurance biz under pressure from inflation"
"falling policy count and declining broking income per policy"
It depends on whether you view these negatives as transient, or permanent. In the insurance industry in structural decline? And even if it is, do you view Saga as an inferior player in the industry?
Very strong points here - and out of interest, I just looked up the list of major shareholders of both Direct Line Insurance (LON:DLG) and Sabre Insurance (LON:SBRE) - and should not have been surprised to see the list of major institutional holders - who you would hope know better.....that phrase used so much here - DYOR - so important!
Interesting "in-line" update from Solid State (LON:SOLI) - in-line that is, against broker forecasts that had been raised sharply during the year. The question is the extent to which they are riding inventory build by their customers which will have to go into reverse at some point. Next year may see a dip as a result. That said, they seem to have been managing their own supply problems successfully, and look to have improved as a business over the past few years. I will continue to hold.
love Solid State (LON:SOLI) as a business SundayTrader. I don't hold at the moment but did from around £3 to £14 where I felt they were a bit over priced. Business is strong, and management is also strong and conservative imo. They navigated supply chain issues well and have proven astute in their acquisitions. If they dipped much I'd be pleased to buy them back.
Unbound is now a take over target, not that it moved the share price
Rathbones (LON:RAT) as I mentioned it looked interesting I will follow up. Today they announce a merger with Investec wealth - my gut feel is it’s probably a nice fit. A stronger business emerges but it’s not huge immediate upside. The benefit of accretion being offset by potential flow back and so shares small up. This is probably fair - I will read a bit more and comment later. Net net it’s not negative news … but the combination is very dependent on mkt levels.
Rathbones (LON:RAT) Investec (LON:INVP) - A bit of mid-cap news but interesting all the same with an all share merger - roughly 60:40 Rathbones / Investec WIN. Rathbones announces combination with Investec Wealth & Investment UK to create the UK's leading discretionary wealth manager.
My morning smallcap tweet: Pre-open prep
Light Science Technologies Holdings (LON:LST) Anexo (LON:ANX) R&Q Insurance Holdings (LON:RQIH) Digital 9 Infrastructure (LON:DGI9) Smarttech247 (LON:S247) Aukett Swanke (LON:AUK) Libertine Holdings (LON:LIB) WANdisco (LON:WAND) Feedback (LON:FDBK) Argo Blockchain (LON:ARB) Physiomics (LON:PYC) Ramsdens Holdings (LON:RFX) OKYO Pharma (LON:OKYO) Solid State (LON:SOLI), Likewise (LON:LIKE), Gooch & Housego (LON:GHH)
◄Light Science Technologies (LST)► is 'pleased' to announce a £1.5m placing and retail offer at 1p, a humiliating 73% discount, "for product development and intellectual property protection" and of course to keep the lights on. It should be "ashamed to announce". [SP=4 Cap=7m]
◄Anexo (ANX)► guides FY-Dec rev £135-137m, Pretax £24-26m, at the upper end of this range, broadly in line with market expectations. [SP=NA Cap=NA]
◄R&Q Insurance (RQIH)► reviewing strategic alternatives to separate Accredited and Legacy Insurance to set each on a more favourable footing. Guides FY-Dec pretax loss £30-40m. In line? [SP=72.45 Cap=272m]
◄Digital 9 Infrastructure (DGI9)► not aware of any portfolio specific factors that have led to the recent decline in the share price. [SP=61.4 Cap=532m]
◄Smarttech247 (S247)► Principal subsidiary FY-July (really?) rev up 41%, pretax up 18%. H1 2023 trading is ahead of budget. [SP=34.75 Cap=NA]
◄Aukett Swanke (AUK)► sells lossmaking non-core Live Events business for £1. It was acquired as part of the recently completed acquisition of Torpedo Factory. [SP=2.51 Cap=8m]
◄Libertine (LIB)► warns FY-Mar rev £200-400k below the current guidance, dependent on agreement in relation to certain revenues for work completed. Blames development delays. [SP=17 Cap=24m]
◄WANdisco (WAND)► $1.5m contract renewals, 5 yr term. [SP=1310 Cap=884m]
◄Feedback (FDBK)► nine-month, fixed-term contract extension of its contract for the Sussex Health and Care Partnership Integrated Care System. No £££. [SP=153.9 Cap=21m]
◄Argo Blockchain (ARB)► March Bitcoin production down 10% on Feb due to increase in network difficulty. [SP=14 Cap=86m]
◄Physiomics (PYC)► guides FY rev obly c.£750k. Blames squeeze in biotech funding and £200k of projects unexpectedly delayed, Co "pursuing growth through a number of strategic initiatives". [SP=3.57 Cap=3m]
◄Ramsdens (RFX)► guides H1-Mar ahead of mgmt exp with strong trading across all key income streams.. Ups FY pretax guidance to not less than £9.5m (FY22: £8.3m) [SP=215 Cap=68m]. I hold.
◄OKYO Pharma (OKYO)► applies to delist from LSE due to listing costs. Will still trade on Nasdaq. [SP=1.8 Cap=30m]
◄Solid State (SOLI)► guides FY-Mar at least in line with consensus expectations of rev £120.3m, and adjusted pretax £10.45m. [SP=1097.5 Cap=124m]
In line: LIKE, GHH
Good morning Roland and Graham, we have two companies reporting today and at for once we're not facing imminent extinction. Ramsdens pre close Trading Update -- seems to be going well on expansion and trading, and Epwin's finals also looks pretty good too in tough times with a raised dividend. I think you've both covered H&T as your preferred pawnbroker but I'd appreciate any observations on our two holdings if you get time.
Morning JASVFS - you're in luck as both of them are being covered today! G
AT&T (NYQ:TBC) ?
AT&T (NYQ:T) - Q1 results due 26Apr. Any other reason to be interested, nod nod, wink wink. I don't mind a flutter.
err..TBC was the headline of the page. I now realise it meant To Be Confirmed....