Small Cap Value Report (Tue 4 Feb 2020) - ZYT, NMC, XLM, PEG, K3C, ALU, TSLA, ESC

Good morning, it's Paul here with Tuesday's SCVR.
Estimated completion time - 1pm
Update at 13:05 - today's report is now finished.
I've got a few minutes to kill before the 7am RNS starts beeping into life.
I'm delighted to see that we're coming to the end of that part of the year when it's still dark at getting up time. The first glimmer of dawn is appearing to the east.
I woke up with a start, very early this morning, wondering why the listed company D4T4 decided to call itself D4T4. Then it dawned on me - D4T4 looks a bit like the word "DATA" in capital letters, but with the letter A replaced with the number 4. The company's slogan of "All about the data" hadn't previously been obvious enough to enlighten me! Which made me realise that I'd been rather thick.
In fact, I've got form on this. When the Ceefax teletext service was introduced in 1974, I just thought it was a modern-sounding name. It was only when Ceefax was finally discontinued, in 2012, that I realised the name was a pun of "see facts". For 38 years I'd been blissfully unaware of this strikingly obvious fact.
Right here we go, the 7am rush hour in RNS-ville has started!
Initial list
This is what has caught my eye on the first scan of the RNS;
Zytronic (LON:ZYT) - Trading update
NMC Health (LON:NMC) - response to 20% share price fall yesterday
XLMedia (LON:XLM) - business & trading update
Other companies I cover in less detail are: Petards, K3 Capital, Alumasc, and Escape Hunt
Zytronic (LON:ZYT)
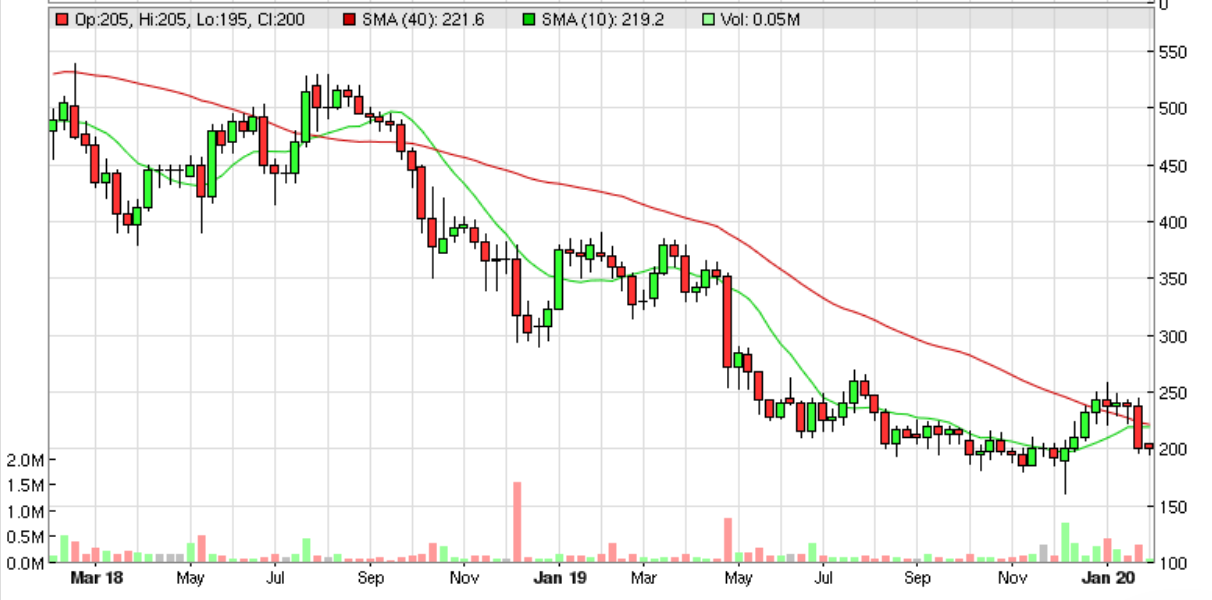
Share price: 192.5p (down c.4% today, at 09:41)
No. shares: 16.0m
Market cap: £30.8m
(I don't currently hold this share)
Zytronic is a world renowned developer and manufacturer of a unique range of internationally award winning optically transparent interactive touch sensor overlay products for use with electronic displays in industrial, self-service and public access equipment.
Background - as you can see from the chart below, the share price here is already bombed out, following lacklustre results, and cautious outlook comments, which I reported about here on 10 Dec 2019.
The problem seems to be lumpy contracts, and a gap created by some big projects reaching their end of life. There's a promising sales pipeline, but converting that into actual sales seems to be an issue. Lots of small caps experience this problem.
Today's update - is a bit of a mixed bag;
We explained at the time of our Preliminary announcement in December, that based on current trading we were cautious about the short term. The position is unchanged as revenues during December and January have continued to be considerably behind last year, however, on a more positive note the order intake during January has shown a significant increase.
These orders are not likely to benefit the first half results but are an encouraging sign of the prospects for an improvement in the second half that we were expecting and is normally the case.
Here at the SCVR we don't like second-half weightings in trading updates, as it often turns out to be a deferred profit warning. However, in this case;
- Management has a great track record of telling it like it is. Hence Zytronic's updates can be relied upon to be truthful, and with a refreshing lack of PR spin
- The H2 weighting is based on a significant increase in orders. Hence is not just wishful thinking.
There's also the matter of Zytronic's very strong balance sheet, full of cash. At the last count, this was 82p per share, so even if the company has a bad patch of trading, it is solidly supported by plenty of cash. Hence the lower the share price goes, the more attractive it becomes as an asset play. At some point Zytronic might even attract an activist investor, with the agenda of bullying management into giving the cash to shareholders - which makes sense as management clearly has no use for the surplus cash, other than as a comfort blanket, earning no return.
My opinion - the cash pile has meant generous divis continued in the past, when it had difficult trading periods, although it has said divi policy is under review (which usually means it's likely to be cut in future). The company needs to distribute the cash to shareholders through a special divi, in my view, then rebase the regular divis at a lower, sustainable level.
I imagine today's update might cause a small downward move in share price. You never can tell though, because poor liquidity leads to small volumes moving the price a lot. I imagine that existing holders are probably likely to sit tight, given the upbeat comments about order intake, and that soft short term trading had previously been announced, so theoretically should not be price sensitive.
It's possible that broker forecasts might be lowered again today, but I've not seen anything yet.
EDIT at 11:17 - an update has come through to my inbox. No change to broker forecast profit/EPS today, which is good news. Note that the divi is forecast to be halved this year to 11.4p, yielding c.6%, so still excellent, but no final decision has been made as yet. End of edit.
NMC Health (LON:NMC)
Share price: 1058p (up 2.2% at 11:21)
No. shares: 208.7m
Market cap: £2,208.0m
Response to share price movement
Too big for a full section here, but this one is topical, so raises my curiosity.
NMC is a group of hospitals in the Middle East, with a full listing in London.
It's been savaged by short sellers, who've managed to smash its market cap down by two thirds - which is a massive impact, reducing it from £6bn, to £2bn market cap.
NMC tries to reassure today with an in line update;
NMC Health PLC ("NMC" or the "Company") notes the decline in the Company's share price yesterday [Paul: it dropped 20%] and confirms that it knows of no specific reason for the fall.
The independent review being undertaken by Freeh Group International Solutions LLC, announced on 17 January 2020, is proceeding.
The Company's operations continue to perform strongly and the Company expects to report full-year 2019 results in-line with management's expectations.
It's tricky in shorting situations. If a target company responds to the short-seller attacks, then it's a case of damned if you do, damned if you don't. Last year, Burford Capital (LON:BUR) was pole-axed by a shorting attack, and its shares haven't recovered as yet - indeed they've drifted back down to the lows. Management perhaps spent too long rebutting allegations against them, and made a big mistake in threatening to sue the short sellers, which I think back-fired.
These shorting attacks do often seem to shatter confidence in the shares of target companies, doing lasting damage. Graham discussed this issue yesterday, making some interesting points.
It all reinforces my aversion to companies which are mainly operating overseas, listing in the UK. There does seem to be a very clear pattern, that an extremely high proportion of overseas companies that list in the UK go disastrously wrong in some way. So why on earth do people keep buying shares in them?
EDIT at 13:43 - this share price is extremely volatile today. In the first hour today, it was up at around 1130p, but has since plunged, being down heavily at 894p at 13:46. End of edit.
Talking of which, let's stay on this theme of disappointing overseas companies listed in the UK...
XLMedia (LON:XLM)
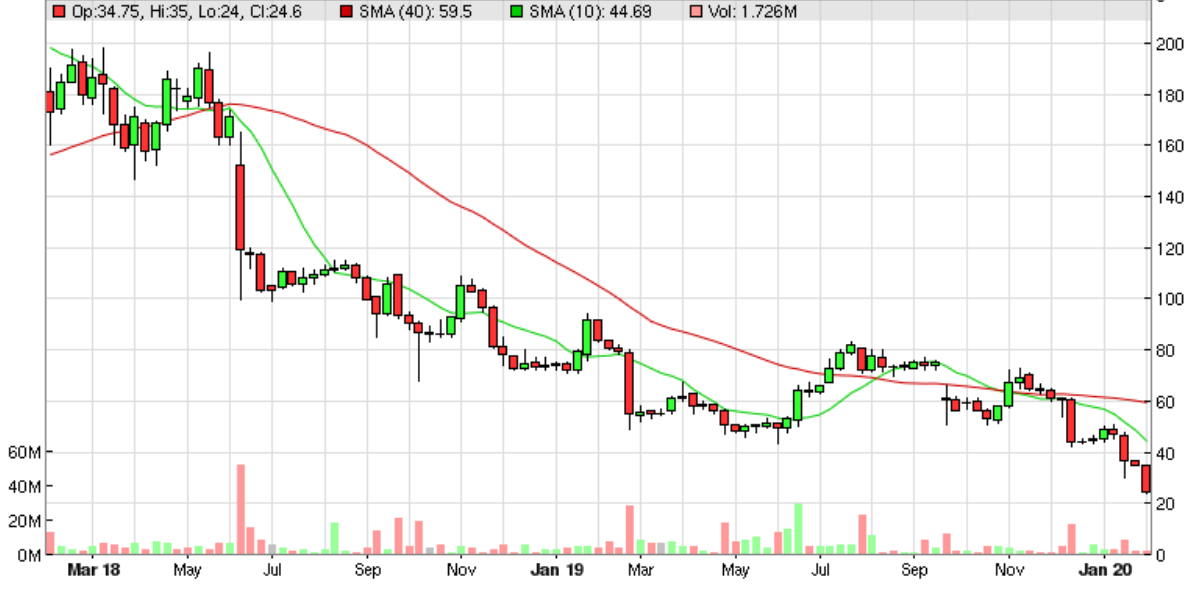
Share price: 24.0p (down 29% today, at 08:35)
No. shares: 206.8m
Market cap: £49.6m
XLMedia (AIM: XLM) provides the following update further to its announcement of 20 January 2020 relating to the reduction in ranking of a number of the Group's websites. The update addresses further developments, immediate actions being taken and the impact on the Group's future strategy.
Graham covered this problem previously, and rightly highlighted how important Google rankings are for online businesses. Any changes can have a major impact on ad revenues, if traffic is diverted away from websites by Google.
I never liked the flurry of ad tech businesses which floated a few years ago. Some of them were remarkably profitable, but it turned out that profits were not sustainable. Hence owners were taking advantage of the stock market, to cash out, and dumping their shares on punters who didn't realise that the profits would not be sustained.
If it's not clear to me how a company makes its profits, and whether that is sustainable, then I steer clear of the shares.
XLM paid out big divis in the past, so there's no doubt its profits were real. The question mark is whether those profits are sustainable?
Today's update - I've tried to understand this by summarising it;
- Trying to resolve the problem with Google
- 23 important websites have been impacted - mainly online casino-related websites
- XLM is getting rid of some of its low quality sites, to hopefully improve Google's perception of its overall business
- Company intends to "allocate significant resources to improving & expanding" its best websites, and creating new websites. (Increased costs & lower profit margin maybe?)
- Unable to determine full financial impact
- Loss of revenue $3-5m p.a. for lower quality sites (presumably won't have much profit impact, as low margin)
- Some additional costs already budgeted for
- Expect impairment charge (goodwill write-offs)
- Dividends scrapped until further notice (this is devastating news for shareholders, as cashflow & divis where what this share was all about)
- Management wants to create a "much stronger and more transparent platform". Hmmm.
Can you make sense of this bit? I'm struggling;
Management expects this to represent a monthly reduction in Group revenues of between c$1 million and c$2 million (assuming only a minor fall in its repeat revenues) [Paul: no idea what this means!].
In addition, management expects that any lengthy period of demotion could impact the rankings once restored and that it may take a period of time to re-establish the former high rankings.
My opinion - I'm no expert on this company or sector, so take my views with a pinch of salt.
Reading between the lines, it strikes me that the party's over - XLM has clearly been making fantastic profits by working the system, the system has realised, and changed the rules.
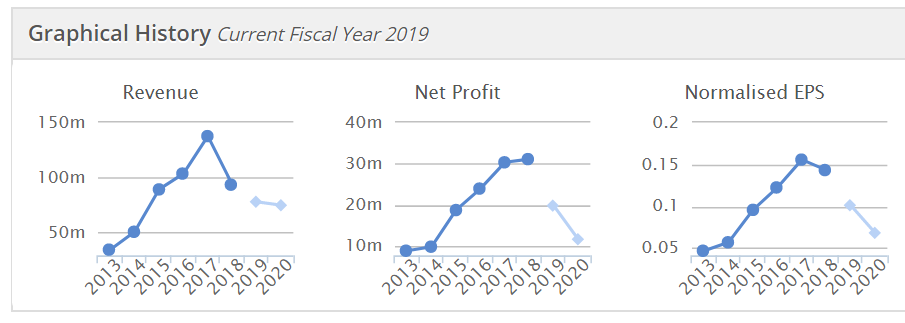
Existing forecasts (prior to today's news) show forecast profit going all the way back down again to 2013-14 levels (see below). What's the chance that forecasts are slashed again? Pretty high I imagine.
Since XLM has suspended divis until further notice, that suggests to me that it might not be generating any meaningful cashflow for the time being. Or it doesn't know, so is playing it safe maybe?
It's another overseas (Israel again) stock where the business model turned out to be flaky. It doesn't interest me at any price, as I cannot work out if there's a sustainable business model here or not.
The last balance sheet showed a decent cash pile, so that should buy the company time to sort out its problems perhaps. Therefore, if you understand the sector & the company, it might be worth spending some time to assess the recovery potential. It doesn't interest me at all though.
The high quality & value scores beguiled the StockRank system I'm afraid. Therefore, I think it's worth applying a manual filter to eliminate overseas small-mid caps, listed in London, from our stock screening, given that so many of them go badly wrong.
I wonder what read-across there might be for other shares? I think it's important to distinguish between online businesses that sell real products & services (less risky), from online businesses that milk the system for ad revenues (more risky).
As always, the most important question for every share, is to ask: Are profits sustainable? Large scale Director selling at IPO, and subsequently, is a very bad sign to look out for. As is an unexpected change in CFO. Put those things together, and there's probably something badly wrong below the surface.
Quick fire sections now, due to time constraints.
Petards (LON:PEG)
Down 22% to 9.75p, so market cap only £5.6m - too small to be bothering with, as the de-listing risk is too high - making risk:reward unattractive. It sells security & surveillance systems.
Two rail projects have gone a bit wrong, and another one is deferred.
Revenues of £15.8m for 2019, below forecast of £17.3m.
Loss-making overall for 2019, but not stated how much.
Outlook comments, and order book of £15m look positive.
Why is a company this small stock market listed? It might help the company win big projects possibly, as being listed is often seen as a prestige thing by customers. Maybe they wouldn't take that view if they knew how much junk there is on AIM!
Petards doesn't pay divis, so owning the shares just looks like dead money.
K3 Capital (LON:K3C)
This one caught my eye as looking potentially interesting due to a positive trading update here on 16 Dec 2019.
It seems to have a disruptive business model earning fees for selling businesses.
Interim results today look good, which is expected, following the strong update announced on 16 Dec 2019.
There's a formatting problem on the balance sheet, as you can see here. I've crossed out the superfluous numbers "05". It's easy enough to work out what the correct numbers for Trade and other receivables are, by deducting the Other assets and Cash figures from the subtotal of Total current assets;
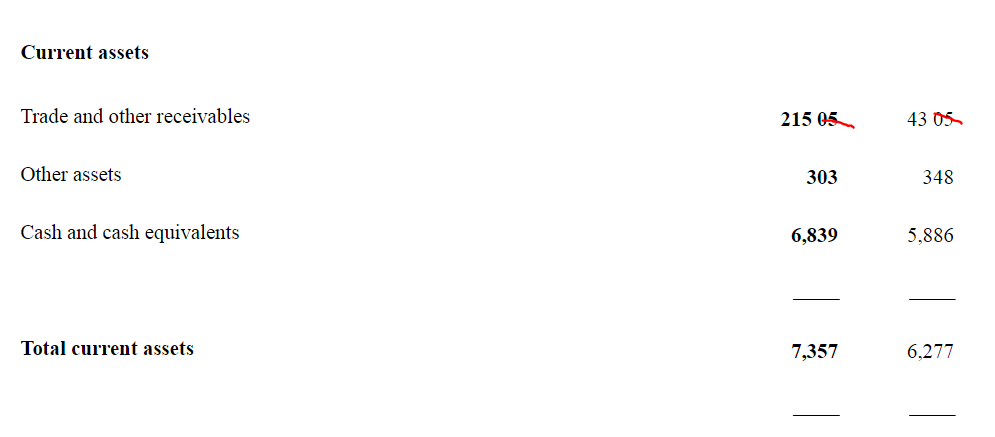
Apart from that, the other numbers look fine to me.
Outlook - positive noises about the improved business environment, highest ever WIP pipeline, and December 2019 trading having been strong.
Management says it is confident of meeting full year market expectations. Possibility of a beat here, I wonder?
My opinion - looks an interesting share, and worthy of a closer look.
Alumasc (LON:ALU)
H1 results (6 months to 31 Dec 2019) are out today.
H1 underlying profit is flat vs H1 LY at £2.3m.
That's been achieved despite revenues being down 7% - due to improved gross margin, and cost control.
This share is cheap because there's a big pension deficit. There is some good news there, because deficit recovery payments have fallen from a massive £3.2m pa to a still large (relative to profits) £2.3m.
Outlook - good order book, and makes other positive noises.
My opinion - potentially interesting, given that it operates in a fashionable area of recyclable/recycled products, for managing water & energy consumption.
Make sure you properly factor in the pension deficit, when valuing this, as the PER is artificially low due to that point.
Tesla (NSQ:TSLA)
The mother of all short squeezes is still underway here. This electric car maker seemed to turn a corner with its latest trading update. The share price rose about 20% yesterday, and pre-opening today is indicated at $852 per share - giving it a market cap of wait for it, $153bn!
To put that into perspective, Tesla is now valued at almost the same as (98% of) the market caps of Ford, General Motors, Fiat Chrysler, and BMW put together! Complete lunacy!
Tesla shares are more a cult than an investment and so far the cult leader, Elon Musk, is winning! It's not going to end well though, is it? Fascinating to watch from the sidelines though.
Escape Hunt (LON:ESC)
I imagine its the shareholders who are likely to be hunting for the escape route. This share has now lost about 90% of its value since floating in 2016.
Today's update sounds upbeat, and flags strong LFL sales in Dec 2019. However, it's light on profitability numbers, which is what I need to value the shares.
The section headed "Full year numbers" doesn't have any numbers in it, presumably the irony was unintentional?
Whilst applications both for R&D credits and a Scottish Enterprise grant have been lodged and are progressing, no income from these potential claims is being accrued in the accounts. Management had originally anticipated recognising a contribution from these sources in 2019.
Taking the absence of such credits into account, Escape Hunt expects that the underlying Group EBITDA for FY19 will be modestly ahead of management's expectations.
We're not told what those expectations are, and I cannot find any broker research.
The words "cash" and "debt" do not appear at all in the announcement.
My opinion - overall, this trading update is completely useless, in not giving me any of the information I need. We'll have to wait until the full year numbers are published. For now, I wouldn't go near it, given that it's a tiny company which is proving coy at providing numbers to the market - which usually means the figures are not good.
DX (Group) (LON:DX.)
Issues an in line update.
I'm delighted to see that there's a footnote giving a link to finncap's research portal, where investors can read today's morning note. This note also covers Alumasc, and K3 Capital, as well as DX.
It's incredibly helpful making house broker research notes available to investors, so hats off to finncap for showing the way forward on this.
I'm not interested in buying shares in a low margin freight business, so this one doesn't interest me.
That's it for today, thanks for reading & commenting.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
The XL Media CEO has brought 879,973 shares for himself @26.45p.
Hi,
Back on the subject of Coronavirus and the comments above, my angle is the quarantining and impact to supply chains etc. China has shut down two cities so far with 18m people there are more reports daily of restrictions on travel etc, so as this escalates, it might be the older and ill who are affected but if the answer is mass quarantine, that's a big risk. An announced vaccine will solve it all however its definitely a watch and see where companies are dependent on china.
One thing to consider about Tesla is that it is not just a car company. It also manufacturers solar panels and battery packs for use in buildings.
I'm not saying the valuation is correct but it shouldn't just be compared against straight car companies.
Re Revolution Bars (LON:RBG) - I don't comment on day-to-day share price movements here. There's no point. Small caps are illiquid, and the prices move on a handful of small trades. Trying to make sense of the price movements is a complete waste of time!
The only prices that matter are;
A - the price I paid
B - the price I sell at
I'm relaxed about the timescales between A and B (normally I would only buy something if prepared to give it 2 years+ to gestate).
Therefore, the prices in between A and B don't really matter.
Regards, Paul.
Hi Paul. Do you have any idea why the Revoulution Bars price has crashed down to round 70p recently. I have not seen any press releases. It looked reasonable value at 90p
I don't think Paul will be worrying too much about this. The share was in a very lengthy trading range and when it broke out moved up quickly as would be expected. Subsequently, you can expect unhappy holders to take the opportunity to sell and it is not unusual for the price to come back towards the top of that range before hopefully moving forward again. However, much more of a fall would tend to indicate that you will have to wait some time for any advance.
I am deeply worried (and embarrassed) about my huge position in XLM @ -45%.
Doublelutz is spot on above.
According to Stockopedia, the Tangible Book Value (liquidation value) is presently 12.93p.
I would infer that the vulchers will come in @ <12p a share, and that would probably see existing shareholders wiped out.
If shareholders are very lucky, they may be able to turn around the company, but this incredibly hard to do, and many obstacles to this.
@ today's close of 24p, its only got half way to go to reach Tangible Book Value.
I'm staying in for now. Can't really countenance the loss.
TBH the turnaround looks hard, if we assume that Google will not budge.
It looks absolutely nailed on that there will be a massive profit warning as the intangible assets will have to be written down, even the ones currently untouched by Google now, because if there is a continued preference for genuine organic content they are going to lose out. Some of their poorer sites could be scrapped altogether.
For example, another of their sites: www.moneyunder30.com - bought for $7m. This seems an incredible price for a site which is just a collection of articles, but no doubt based on multiples of the earning potential at the time.
Writing real articles for syndication and monetisation is a much lower margin business than the spraygun method currently used.
I believe there is a nucleus of good sites here, but who knows at what level it might be?
I feel your pain, I’m currently at a 60% loss with this share. I will put in down as a lesson learnt and move on.
Xlmedia (LON:XLM)
Paul with reference to your comment below:
"Management expects this to represent a monthly reduction in Group revenues of between c$1 million and c$2 million (assuming only a minor fall in its repeat revenues) [Paul: no idea what this means!]".
The demotion of the websites is estimated to cost between $1 and $2 million per month but that assumes that repeat income holds up. When a punter went from the XLM website to open an account with a bookie XLM apparently become entitled to a percentage of the future profits made from that punter. There were some people who thought that meant they would be earning income from that punter for the rest of his life! I don't think they have such loyalty. I suspect they are opening and closing accounts with bookies all the time. Certainly on the few occasions I have a bet it is with a different bookie each time usually to take advantage of a special offer with good odds.
I made very good profits on this one but I use charts to determine when to get out. It has been clear from the high 100's that this was a risky share to hold. At the present price it is a binary bet. Either you will double your money (or more) or lose it all.
Reuters reporting that Foxconn stopped almost all production until at least 10th February
https://www.reuters.com/article/us-china-health-foxconn-exclusive/exclusive-outbreak-to-hit-iphone-output-if-china-extends-foxconn-factory-halt-source-idUSKBN1ZX1ZH
On the other side of the pond, Tesla shares continue their incredible rally. But if a short squeeze, surely there is has to be riches on the other side if one could time it right and afford to ride out further losses. VW shares went up to 1,000 dollars but ultimately fundamentals drag it back down.
Schlumberger are down 25%, can anyone add any information to this? They are a $50bn company so this surely isn't going to be small amounts of trading moving the price. Doesn't seem to have affected BP/Shell.
hi Paul - if you didn't see the interview today on TSLA by Ron Baron (billionaire investor) and Tesla early investor its interesting. He reckons they can be doing $1tn in revenue in a number of years time and is not selling any of his shares, even at these levels !! Wow!!
I'm like you, I can't help thinking this is all bonkers but there are a lot of much wealthier people who consider it cheap.........interesting indeed. I've avoided all temptation to go long or short as my head says to sell and my gut says it is going much much higher........phewee
Today I plot it against bitcoin in 2017 and it actually rises faster. As we speak it is dropping back (probably to earth).
I was bullish Tesla at 180 but it is completely overdone and from what I read, the rally picked up on the back of a huge amount of out of the money call options which caused covering of positions by sellers of the options. Not sure if that is true but it would explain the ridiculous valuation of over $900 per share when it only made 0.56 cents per share in the last quarter - it's best so far.
To put it into comparison, Volkswagen delivers 11 million cars of all types and only generates c. 100 billion in revenue, so there is no way Tesla can generate 1 trillion in revenue, there isn't enough people to buy that many cars, let alone at 50-90k a piece!
Ron Baron is one of those hedge fund guys who no doubt has tonnes of out of the money call options riding on a pump and dump so he would say it is possible.
It would appear that Tesla's soaring share price is being driven by technical considerations (option covering or short closing) rather than fundamental considerations.
An analogous situation occured in the autos sector in 2008 when Porsche announced that via option & swap positions they had acquired 75% of the shares of VW Ordinary shares - short sellers scrambled to close their positions against a tiny free-float & the VW Ordinary price soared.
K3 Capital (LON:K3C) K3 Capital is an interesting one - it will benefit from the large number of baby boomers looking to sell their businesses.
It looks well managed and they have steered themselves through the choppy waters of Brexit.
I think they are one of the type companies who you recently identified as struggling due to Brexit uncertainty (lack of deal flow on people selling their businesses). But now we have political certainty, deal flow should kick off again. Previous support for these was just under 300 and it carries a safe divi too.
I hold.
I note that non executive director Ian Mattioli has bought 40,650 shares at 246p today 5th Feb.
There is confidence in house on this one.
Will you get round to looking at £gan this week. Lots to look at with listing in US coming
XLMedia (LON:XLM)
A quick look at the website https://www.doughroller.net/ mentioned above. Yes, it's a poor quality site mainly loaded with news articles and links to products to earn commission. This is the sort of site Google prefers to rank down as they tend to be just shells with plug-ins loading the news articles automatically from third party news story factories. Bit cheeky really.
NMC Health (LON:NMC)
Quick look, market cap is £2.16b but they have £2.228b in net debt (according to Stocko). On the face of it debt is high. From their last H1 results EBITDA to net debt ratio was 3.4x which is not unduly high, but as a proportion of last year's earnings £248m it's fairly hefty. MW report summary talks about various irregularities on the accounts, asset overvaluation and net understatement. I would pass, as while I appreciate health care is a high capex business, the debt pile is high, MW report aside.
Zytronic (LON:ZYT)
From their annual report the EPS trend has been:
2017 = 29.0
2018 = 22.7
2019 = 16.8
They do have eight patents on their touchscreen technology which is good. But for a small company I wonder how they can compete in the long run against the big display firms in Korea, Japan and China. Also revenue concentration, “At present the Group gets 49% of its revenue from three key customers.” Reads like they are good at what they do, but it’s very niche, so not ringing a growth story here.
on Nmc Health (LON:NMC) whatever the merits/demerits of owning (I have no position yet) you need to watch the headline net debt figure as it is masked by IFRS16, which is obviously not comparable to last year. For something like hospitals I am personally inclined to ignore the IFRS16 impact on net debt. There aren't many loss making private hospitals around the developed world and it strikes me as unlikely to change in the medium term. Therefore showing lease liabilities as net debt strikes me as worthy of a footnote in the accounts but little else. I appreciate others take a different view. The comparable figure is actually a reduction to 2.7* EBITDA and free cashflow should push this further down by y/e. Doesn't feel unreasonably high to me then, though I haven't yet spent a great deal of time on analysis. I am considering a contrarian buy around these levels but need to do more work.
NMC Health (LON:NMC)
After being up 8% in the morning they are now down over 10%
Another tweet from Muddy Waters apparently Edward.
I'm paying little attention to the numbers from China. Too many doubts about their accuracy. I did notice that the first out of China death was a man aged 44.
Hi all,
On the subject of Coronavirus. There was an excellent comment from a reader last week on bias's on information, how we can over-react. The comparison was made with flu & the huge number of deaths per year, compared with Cornavirus.
The markets are , so far, taking this in their stride. For those who want to know more, and having found and read some of the statistics from this excellent website, I'd have a look.
https://www.worldometers.info/coronavirus (you have to cut and paste as Stocko won't let me add the url??)
There no comment from me as to what happens next to this and the affect on markets but this can easily be a nothing , nothing, nothing until it goes binary and then a big impact. Either way its useful information for investors & so I thought I'd share it.
Some of the facts are quite startling, the liner charts on cases & deaths say it all, not least China has quarantined 18m people so far, transmission rates are very high , fatalities are less than SARS but this these comparisons give a good summary:
Comparisons:
...today 20,000 + 18% up on yesterday. - compound that up if you dare!
Great website link on the Coronavirus, John
The site shows that when viewed of a log scale, the rate of change in total cases & deaths is declining:
The incubation period for this novel coronavrius is between 2 & 14 days. So given that the Chinese New Year celebrations took place on the weekend of 24-26 January, by this coming weekend the picture will be clearer as to whether the contagion risks have peaked.
https://www.worldometers.info/coronavirus/
https://gisanddata.maps.arcgis.com/apps/opsdashboard/index.html#/bda7594740fd40299423467b48e9ecf6
This is another good tracker link to Coronavirus cases worldwide.
Death rate looks to be about 2% which, in the grand scheme of things, is not huge (unless you are one of the 2% of course), particularly when compared to SARS (which was about 20% I think.....).
Looks likely a highly virulent disease, but probably one that can be fought off in most cases, perhaps high risk groups (elderly, co-morbidity etc) more likely to succumb.
I think the big risk to markets is the impact on China shutting down....
Cowlid I think you are right, I read last week that almost all of the fatalities are the elderly and those with existing health problems. So whilst obviously no help if you are in that group, it does seem as the majority of the population will likely fight it off, like they would any other seasonal flu outbreak
No optimism from Matt Hancock that the spread of the virus has peaked - statement in the Commons yesterday:
"We will take a belt and braces approach that puts public protection as the absolute top priority for a virus that is increasingly spreading across the world."
The issue for the markets is, initially, to what extent trade will be impacted by government responses to try and curb the spread. If their efforts completely fail to contain the spread, the issue will be to what extent orderly business prevails in the face of hysteria by employees and consumers.
Surprised you are not covering ALU today.
I will again raise the issue of the stockopedia "quality" ranking (raised in relation to Nahl (LON:NAH) yesterday). I see Xlmedia (LON:XLM) having a quality of 93, but the broker forecasts show reduction in EPS of 29% for 2019E and 33% for 2020E. Now clearly, anyone spending 5 minutes on this would draw their own conclusion that this is no longer a quality share, but how does stocko have this ranked so highly (as of close last night).
Surely this should be a flag to management that something wrong - i.e. the amount of highly ranked (per stocko) small caps getting hit with massive sell-offs is surely an issue?
XLMedia (LON:XLM) 's quality score is computed from these components:
According to the explainer here https://help.stockopedia.com/p... the Piotroski F score is "heavily weighted" which suggests that there is not an equal weight to each of the components. Several of the quality components are also based on long term performance which will tend to anchor the quality if there is a short term change in fortune.
Yip, I guess that illustrates the point. How about incorporating some forward looking information i.e. brokers having very weak forecasts indicates drop in quality.
As Paul pointed out, the problem with XLMedia (LON:XLM) was not the quality of the historic earnings - which is what SP and similar systems tries to measure, but their sustainability. That can't sensibly be assessed from the numbers, only from understanding of the business model. I don't see how the figures in the accounts can do that for you.
fwiw, I did make a small purchase XLMedia (LON:XLM) some time ago, being persuaded to it largely by SP's quality score together with the excellent dividends. I sold, also some time ago and at a hefty loss, after looking them up on GlassDoor. Other investors on this forum wiser than I am have repeatedly reminded us that doing research before purchase pays dividends.
But I would find it very helpful if SP let you screen for overseas companies listed in London. At the moment screens typically come back with a lot of companies that I wouldn't dream of investing in, not because they may be bad investments, but because there just isn't enough newsflow about them in this country for a UK based investor.
Regarding ticker names - my favourite is Strix (LON:KETL) - or STRIX, I read a piece somewhere that claimed that companies with a clever " handle" actually performed better. Maybe managers who can be bothered to think up something witty think about everything else they have to do a bit more?
Jim
Snoozebox Holdings (LON:ZZZ) was a good ticker. Didn't help the company or its shareholders unfortunately.
Paul - thanks for the insightful analysis of the latest guff from Xlmedia (LON:XLM) This was a "great idea" purchase by my brokerage (prior to me sacking them last autumn) and now I regret not dumping this at a better price than this morning - a massive loss crystallised and frustratingly inside a family ISA so can't even offset it.
As you point out, simply too much risk in non-UK businesses but UK listed stocks - something I will not fall for now that I have back full portfolio control.
It's days like this that (almost) bring me back to thinking the better thing to do is to annuitise a lump-sum and live off a meagre 4.5%. But then I think where would the fun be in that....
Hi Paul. Will you have a chance to give your views on the preliminary results from RM Education Plc
Morning Paul,
If you get time, wondering if you might take a look at confident but not exuberant HY numbers from Alumasc (LON:ALU) today. They have recently disappointed, and there's still a second half bias, which we all dislike. I've been watching this for w while and am beginning to get interested in a potential recovery here. They managed 10.1p EPS at the FY last year. Market seems to be warming to them, and they kept paying a divi. Another "cheap for a reason contractor", os is there anything vaguely special here?
My morning smallcap tweet: Google drives wooden stake through XLM's heart
XLMedia (LON:XLM) GLI Finance (LON:GLIF) Horizon Discovery (LON:HZD) WANdisco (LON:WAND) Petards (LON:PEG) Escape Hunt (LON:ESC) Zytronic (LON:ZYT) Gore Street Energy Storage Fund (LON:GSF), Uniphar (LON:UPR), SEC Newgate SpA (LON:SECG), DX (Group) (LON:DX.), Numis (LON:NUM)
XLMedia (XLM) huge problems from Google's ranking changes as it demotes 107 of XLM's 'advertorial' sites inc 23 premium sites.Will cut rev by $1-2m pcm on premium sites and $3-5m on others. Trying to persuide Google to restore rankings of premium sites, may sacrifice others to help this. Div suspended. I think Google's action is right - the sites are constracted to grab ranking from 'legit' sites and drive ad clicks on gaming, spreadbetting and investing. XLM had previously boasted of the superiority of its model cf placing Google ads.
GLI Finance (GLIF) warns of FY loss due to slow growth of growth of Sancus UK. But a provision of £1.5m may be reversed if a refinancing of a development loan is successful before the accounts are finalised.
Horizon Discovery Group (HZD) guides FY rev £62.9m about £1m short of F/C. Warns FY20 EBITDA loss despite rev in line due to increased investment.
WANdisco (WAND) guides big FY rev miss as it fails to land a few big contracts in Dec. $16m vs $24m F/C. Guides FY 20 in line.
Petards (PEG) warns of FY loss. Blames a client delaying eyeTrain system deliveries and much lower than forecast profitability on two unrelated rail projects. Sees rev £15.8m cf F/C £17.3m. Expects to be net cash generative in FY20.
Escape Hunt (ESC) stong year end means FY U/L EBITDA modestly ahead of mgmt expectations despite not yet receiving R&D credits and a Scottish Enterprise grant cash as expected.
Zytronic (ZYT) AGM stmt downbeat but sounds in line.
Gore Street Energy Storage Fund (GSF) £1.5m placing at 95.5p, a nil discount, to fund investments.
In line: Uniphar (LON:UPR) SEC Newgate SpA (LON:SECG) DX (Group) (LON:DX.) Numis (LON:NUM)
Could be very bad for XLMedia (LON:XLM). At the worst case, $5m for the tower tiers and $2m/month for the upper tiers equals a yearly hit of $29m.
The fact that they haven't got the larger sites re-instated yet implies that this was not a case of Google making a mistake.
And going forward, who's to say things might not affect their other sites. One of their personal finance sites Doughroller (I assume a tier 1 because of the large acquisition with Webpals), you can visit yourself and the case is quite marginal about whether this is genuinely an informative site or some thin content generated to drive affiliate links.
At least they have cash, and they are right in the strategy needs to change. They need to buy some quality sites, but these might be expensive.
Hi Paul. re: Revolution Bars (LON:RBG) - spotted this article yesterday and couldn’t tell if this was in addition to the lease news we heard in the last trading update, or if it’s what we already know.
https://www.placenorthwest.co....
I drove through Fallowfield one evening last week and saw at least one bar absolutely packed out. It doesn't seem good if they can't make money in this very busy area.
My very rough notes on Rm (LON:RM.) (which I held until a minute ago)
"Not a good update
Revenue growth rubbish and includes 5 months of acquisition.
International growth in H2, excluding the acquisition, is negative.
Cash generation has worsened and net debt up. Also dividend increased which I don't like when debt is also going up.
Most things going in wrong direction and numbers on divisional UK/International splits are not obviously included, highlighting that the company is hiding poor performance.
Sell"
Just sold my RM (LON:RM.) too - I am not impressed.
Peel Hunt just raised their price target to 373p from 330p for RM. Is it a case of jam tomorrow given the 1% rev growth reported? Good if someone can pull some comments from the Peel Hunt notes?
I had the same issue with QINETIQ
Paul please could you include RM. in your list of companies to look at?