Small Cap Value Report (Tue 6 Aug 2024) - RFX, YOU, XPP, ZTF

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
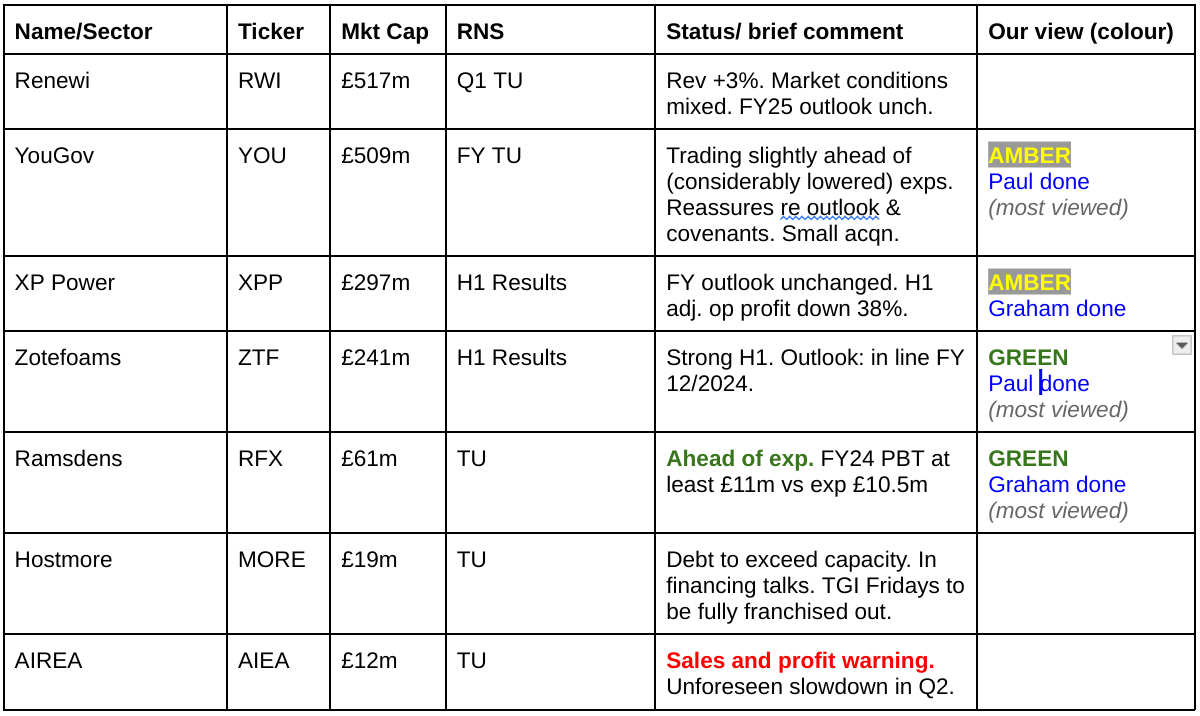
Ramsdens Holdings (LON:RFX) - up 7.5% to 206p (£65m) - Trading Update - Graham - GREEN
Great news from this diversified financial services provider: the sustained high gold price has continued to boost profits from precious metals purchasing. Other divisions are also performing well (although foreign exchange seems to be under a little pressure), and this year’s PBT forecast increases from £10.5m to £11m+. I’ve been a fan of this one for some time and continue to see value here.
YouGov (LON:YOU) - up 22% to 535p (£621m) - Full Year Trading Update - Paul - AMBER
A big rebound in share price today, despite the update only being "slightly ahead" of previously slashed forecasts (after its 20/6/2024 profit warning). Cost-cutting means profit should now rise in the new financial year FY 7/2025, and it confirms trading is in line. Hideous balance sheet, with too much debt - not disclosed today, but we are reassured that it has headroom on bank covenants. I'm less concerned than I was, so move up from amber/red to AMBER as things seem to be stabilising.
XP Power (LON:XPP) - up 1% to 1263p (£306m) - Interim Results - Graham - AMBER
Very poor results have been baked into the forecasts here but H1 profits are slightly ahead of the Board’s expectations and the company is set up well to meet full-year expectations. Management deserve some credit for controlling the damage caused by very poor market conditions. A potentially interesting recovery play.
Zotefoams (LON:ZTF) (Paul holds) - up 4% to 513p (£251m) - Interim Results - Paul - GREEN
Good H1 results, boosted by strong demand for NIKE products in an Olympic year. Outlook is confident, and I suspect it's limbering up to beat FY forecast, despite it saying in line. Debt is up, but still at reasonable levels. The ReZorce development project excites me, and sounds close to commercialisation - that's like a call option on what could be a very important new fully recyclable (mono material) drinks carton.
Paul’s Section:
Zotefoams (LON:ZTF) (Paul holds)
Up 4% to 513p (£251m) - Interim Results - Paul - GREEN
6 August 2024 - Zotefoams plc ("Zotefoams", the "Company" or the "Group"), a world leader in cellular materials technology, is pleased to announce its interim results for the six months ended 30 June 2024.
Strong sales and HPP growth drives record H1 profit
Good results in H1 -
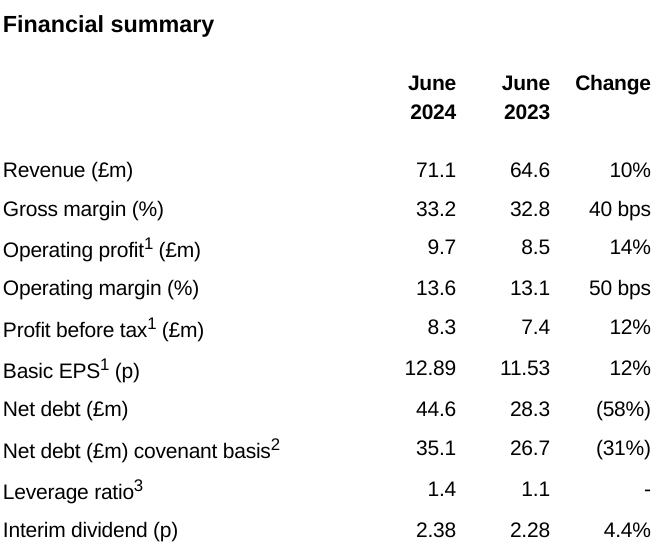
Quite a big jump in net bank debt, up 31% to £35.1m (excl leases), but the leverage ratio looks fine at 1.4x.
Note that the £8.3m PBT figure above is after taking into the losses of £2.2m in H1 at the MuCell extrusion (MEL) division. I think it’s fine to strip out this loss, taking adj PBT to £10.5m, on the basis that MEL is mainly the ReZorce development project. The outcome is binary, so if it for whatever reason doesn’t work commercially, then the losses would stop. If it does work, then we could potentially be quids in, which is an appealing possibility.
As mentioned before here, what I like about ZTF is that the core business is good, and we get the ReZorce project thrown in not quite for free any more, but it was when I put ZTF shares onto my top 20 share ideas list for 2024. So far, so good anyway.
ZTF has been quite resilient in the recent market macro wobbles too, suggesting to me that shareholders are committed to the story, and won’t panic sell on general jitters that are just part of normal markets. I’ve been a bit surprised at the extent of private investor anguish in the last week or so. Markets do this type of thing from time to time, and we have to be resilient, and not get thrown off course by normal market volatility, which can be considerable at times.
It does caution that the growth is largely a one-off benefit from the NIKE relationship this year -
“Group revenue grew by 10% to £71.1m, driven primarily by exceptional demand from Nike, where underlying platform growth was amplified by an Olympic year and inventory build at Tier 1 suppliers.”
Dividends - are modest at c.1.6% yield.
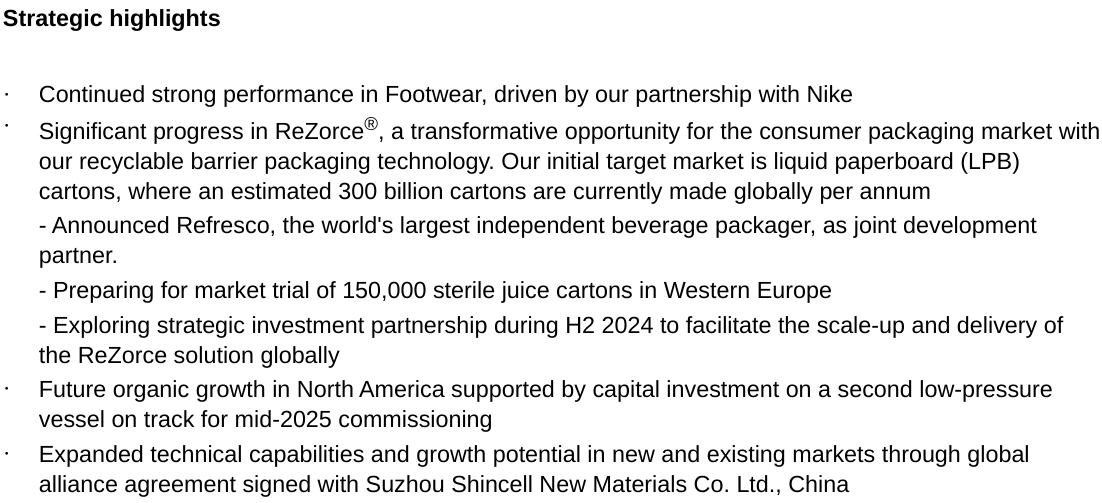
Strategic highlights - I like the prominence being given the the ReZorce (fully recyclable drinks cartons, in development) project, and it seems to now be at an advanced stage. If this takes off, then it could be a catalyst for a serious re-rating here. Or it might not, I don’t know.
Outlook comments sound positive, but my take on this below is that they’re trying to keep us grounded, in terms of not expecting growth to accelerate further in the short-term -
“We enter the second half with positive momentum and with the expectation that market trends seen in H1 will remain largely consistent going into the latter part of the year. Footwear demand is expected to normalise over the coming months, as some of the near-term factors benefiting H1 work through, which will free up capacity to supply markets in both North America and Europe. We will continue to focus on cost efficiency, supported by a stable outlook for energy and polymer input prices.
The Board is delighted with the Group's continued progress, with the benefits of our diverse market profile providing both stability and opportunities to unlock growth in a mixed economic backdrop. We remain confident that the Company will deliver a full year performance in line with market expectations, underpinned by the strong first half performance, and optimistic that we will continue our positive momentum in the medium term."
Any mention of “medium term” tends to be cautionary I think! Which makes me wonder whether the jump in broker consensus from 22p for FY 12/2024 to 29p for FY 12/2025 might be too large? Although looking at Singers (very helpful, thank you!) update note today, it only has £14.7m adj PBT for FY 12/2024, but I’m using the £10.3m H1 adj PBT (stripping out ReZorce losses), so that leaves only £4.4m to achieve in H2. Maybe the Singers note leaves in the ReZorce (MEL) losses? It could be heading for say £18-20m adj PBT, if we strip out MEL losses, so I think there could be good upside on the 2024 forecast. So I imagine instead of 22p, we might be heading for 26-30p EPS for FY 12/2024, if you’re happy to ignore MEL losses. That makes me much more comfortable with the 2025 forecast, so I’m happy overall with this.
As far as I’m aware, there may not be any upside baked into forecasts for ReZorce. So I’m assuming the upside from ReZorce, if it works, would be additional to existing forecasts. Obviously we’re all hoping that it turns out to be a blockbuster product, in which case the sky’s the limit. At times like this, when I can feel a surge of excitement, I remind myself of a renowned fund manager’s words that blue sky projects typically take 7-8 years to reach commercial success. Note that some development costs are capitalised onto the balance sheet.
Costs - some useful detail here, sounds generally OK -
“In the period, the average cost of low-density polyethylene (LDPE), our main raw material, was slightly below the long-run historical average polymer pricing after falling significantly in 2019 and 2020, rising from 2021 and peaking in Q2 2022. Energy prices have stabilised and are similar to the average of the prior year comparative. In the current year, labour costs across all geographies are likely to represent the largest inflationary component within our cost base.”
Balance sheet - looks fine to me. £120m NAV, less £11m intangible assets, gives a very healthy £109m NTAV.
I’m not worried about the net debt of £35m, because the leverage ratio is well within normal range, and ZTF owns the freeholds to most of its factories, providing strong asset backing. A modest pension deficit costs around £850k pa.
Cashflow statement - almost half of profit was absorbed by working capital increases. That’s not a problem, as the cash is only temporarily tied up, it hasn’t vanished as is the case when companies report trading losses.
Capex has increased, and it’s a fair comment that ZTF is a fairly capital intensive business. It makes stuff, so it needs factories full of machines, especially when it’s expanding.
Put it all together, and cash outflows exceeded inflows in H1, hence net debt rising. I don’t see that as a problem - it’s an expanding business, which requires capex in the short term.
Paul’s opinion - I need to wrap this up, and get it published by 13:30, as the InvestorMeetCompany webinar starts then.
I think it’s a mistake to over-analyse the numbers, when the bull case here is so simple - we’re getting a decent business at a fair price. With a call option for ReZorce, which seems to have exciting upside potential.
So I’m very happy to keep holding, it’s a GREEN from me.
YouGov (LON:YOU)
Up 22% to 535p (£621m) - Full Year Trading Update - Paul - AMBER
Small acquisition - of a New Zealand AI company called Yabble, for £4.5m cash + earn out.
The market has lapped up today’s trading update (far more important news than the small acquisition also announced), adding over £100m to YOU’s market cap this morning.
Checking my previous notes -
12/10/2023 - 880p AMBER - Superb FY 7/2023 results. Although I flagged some concerns, including taking on too much debt for an acquisition.
20/6/2024 - 440p - AMBER/RED - Shares almost halved on a profit warning. Making it worse, there was inadequate information, so I decided to avoid this share until more info became available. Also I noted that companies of this size usually recover from profit warnings. This is an interesting conclusion from the data on our spreadsheet kindly created by my friend Phil Hanson. I’ve added a market cap column, and filtered it to just show profit warnings.
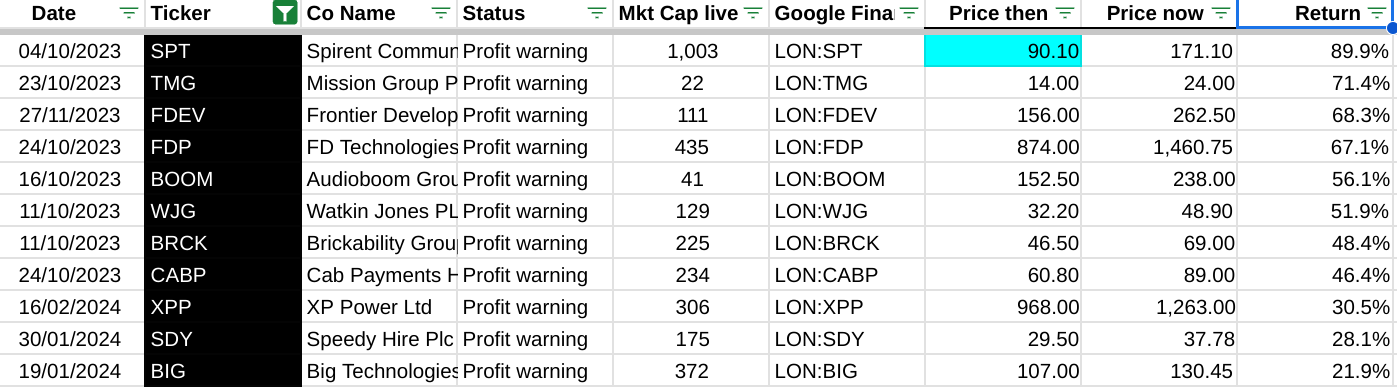
As you can see below, there’s a very strong correlation between recovery of a share after a profit warning, and market cap. Generally the larger market caps recovered, or only suffered a further small fall after a profit warning. Whereas the shares which subsequently went on to continue plunging in price were all sub-£100m market caps. Here’s a screenshot sample of the shares which recovered after a profit warning - so being brave and buying on bad news is sometimes profitable -
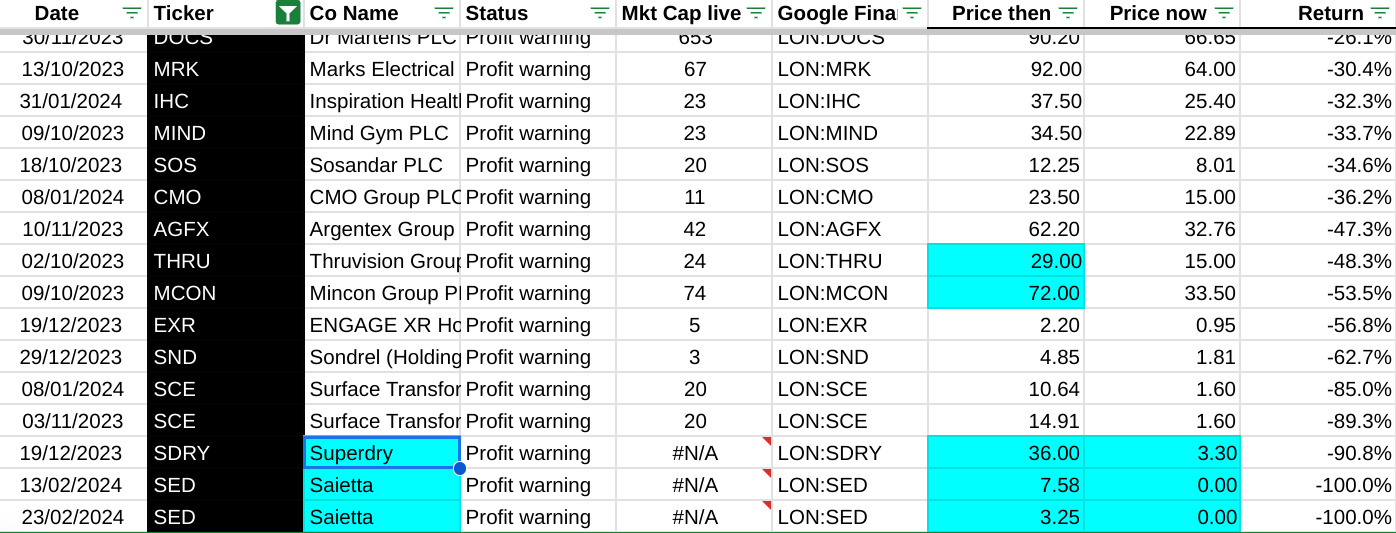
And here’s the opposite end at the bottom - shares which continued falling after profit warnings to now (live prices), are all micro caps sub-£100m market cap. So this seems to clearly be telling us to consider bottom fishing after a profit warning, but not at the smallest companies, where more bad news tends to continue. So a very clear message from this data - don’t give minnows the benefit of the doubt when they disappoint, as they usually continue to disappoint, quite striking results here, hence why I thought it would be useful to share it with you - some horror stories at the bottom, notably Saietta (bust), Superdry (delisted, almost bust), Surface Transforms (enough said!) and the disaster that is Sondrel (also delisting).
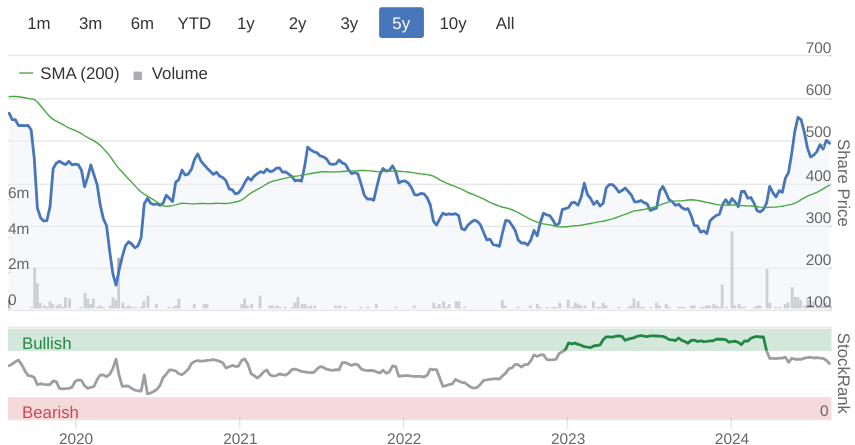
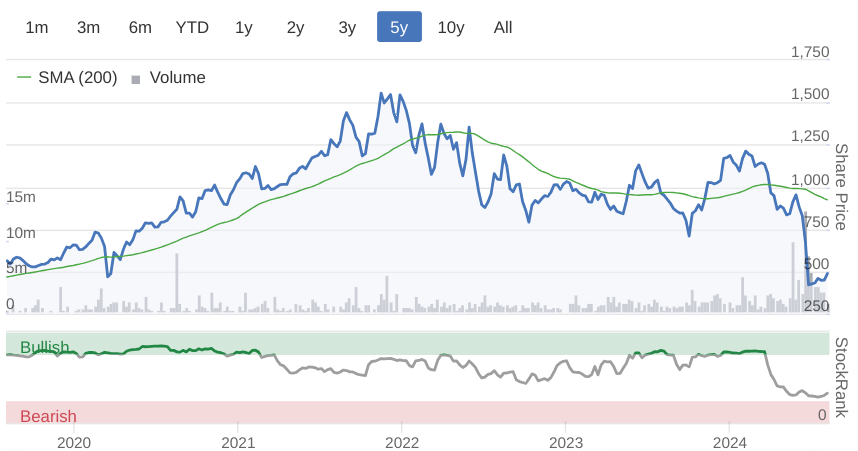
As you can see below on the 5-year chart, the 20 June 2024 profit warning absolutely clobbered YOU shares, a previous high flyer with a good long-term track record -
Confidence seems to be returning today, hence why I’m keen to look at it. Coincidentally I made a list of potential buys after yesterday’s plunge in global markets, and YOU was on my potential buys list.
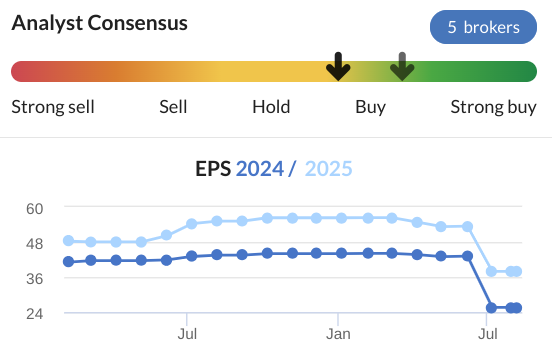
As you can see below, forecast for FY 7/2024 took a tumble in June’s profit warning, from c.43p to 26p - unusual for such a large drop in forecast to happen near the end of a financial year - which very much undermined management credibility I think -
On to today’s update, the headline says -
“FY24 results expected to be slightly ahead of revised guidance”
YouGov now expects Group reported revenues for FY24 to be approximately £327-330 million and Group adjusted operating profit to be £43-46 million, slightly ahead of our revised guidance communicated on 20 June 2024.
I’m quite surprised that has triggered a 22% share price rise.
They’ve done it again, and not stated what the previous guidance was! So annoying. Referring back to the SCVR on 20/6/2024, this is what we said on the profit warning announcement -
“What’s gone wrong? Sales are lower than expected, now guided at £324-327m. It had increased costs in anticipation of higher sales in H2. Revised adj operating profit guidance is now £41-44m. Maddeningly, it doesn’t put this in context by saying what the previous guidance was! How ridiculous is that.” [SCVR 20/6/2024]
Today they’re saying £43-46m, up from £41-44m adj operating profit (not a good measure, since it ignores heavy finance costs).
Debt - it’s shy about disclosing the actual net debt (rather deceptive I feel), which is considerable. Net debt excl leases was £160m at Jan 2024. But it does reassure today on covenants - suggesting that the problem of heavy debt is not a crisis -
“As of 31 July 2024, the Group remains well capitalised, with approximately £70 million in cash and cash equivalents on the balance sheet and €16 million of the revolving credit facility remains undrawn. Excluding the impact of IFRS 16, the Group's leverage ratio2 as of the end of the financial year was approximately 1.8-2.0x and the Company remains well within the loan covenants.”
Cost-cutting - it’s found c.£20m of cost savings, with about 70% expected to be realised in the new year, FY 7/2025.
That’s material to profitability, and would up adj operating profit from c.£45m to c.£65m. Assuming of course that there aren’t any harmful effects from stripping out these costs, which there might be.
Outlook - reassures -
“we expect to meet current market expectations for FY25”
Paul’s opinion - things seem to have stabilised, and thanks to cost-cutting it looks as if the rise to 37.9p adj EPS for FY 7/2025 should be achievable. What rating would be put on this share? Given it has a lot of debt, and a weak balance sheet, I wouldn’t go crazy. Maybe 12-15x? That gets me to a share price of 455p to 569p. The actual share price now is 535p, which is within my range. Hence I think it looks priced about right.
Given that we’re reassured today on profits increasing (mainly due to cost cutting) and that the bank covenants are OK, then I’ve got the extra information that I wanted last time. Hence I’m happy to move up from amber/red to just plain old AMBER.
Looking at the 31/1/2024 balance sheet, it’s actually pretty awful, with negative NTAV of £(227)m. Although you could argue that some of the intangible assets here do actually have some value, it’s not just goodwill.
It could take a while for market confidence to return, and I’d be surprised if YOU shares recover to anywhere near their previous (excessive) valuation, after badly blotting its copybook in June this year. So it doesn’t appeal to me, particularly given the hideous, highly geared balance sheet. That’s why it only pays modest divis.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Up 7.5% to 206p (£65m) - Trading Update - Graham - GREEN
This update is ahead of expectations:
…the Group's good trading momentum has continued into the second half of the financial year to date… the Board now expects FY24 Profit Before Tax to be at least £11m, which is ahead of its previous expectations* (FY23: Profit Before Tax of £10.1m).
The prior expectation was for PBT of £10.5m.
Key points:
The high gold price has increased customer demand for Ramsdens’ gold buying service.
Pawnbroking in line with expectations.
Foreign currency revenues “broadly” in line with expectations.
Jewellery retail “continued to perform well”, helped by a recovery in premium watch sales.
CEO comment:
"Ramsdens' positive trading momentum has continued into the second half of the year, once again reflecting the strengths of our diversified model, trusted brand and the hard work and commitment of our team.
"We continue to benefit from the ongoing investments made in enhancing our multi-channel customer proposition, including our online presence and new Multi-Currency Card, as well as the sustained high gold price, which is encouraging greater awareness and demand for our precious metals buying services."
Graham’s view
This is a stock I’ve been bullish on for some time. I generally tend to like the pawnbroking sector and pawnbroking is one of the four major service categories at Ramsdens alongside foreign exchange, jewellery retail and precious metals purchasing.
At the interim results, the standout performer was that precious metals category with revenues up 35% and gross profit up 25%.
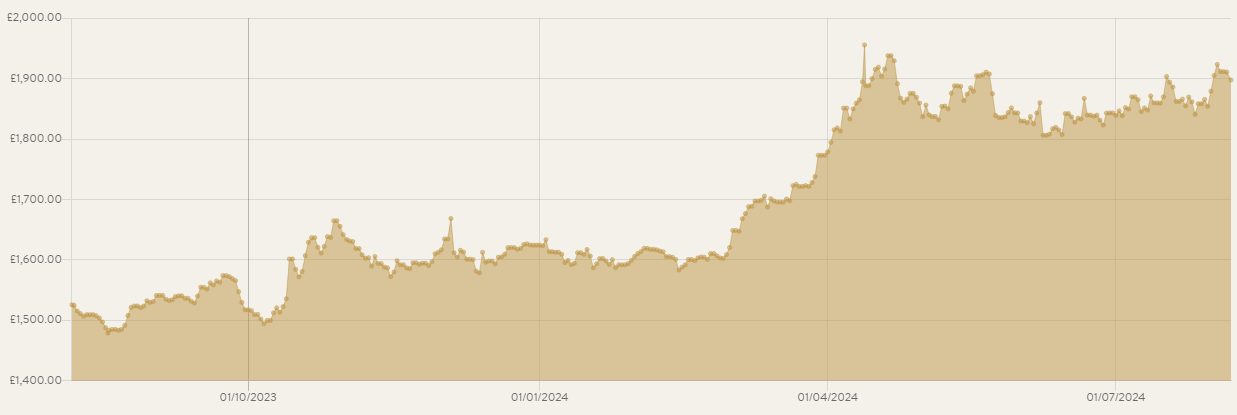
Here’s a 1-year gold price chart from The Royal Mint. After several years of strength, the gold price has surged higher again over the past 12 months:
Latest estimates from Panmure see their 2024 underlying PBT forecast increase from £10.5m to £11.2m.
However, their 2025 forecast is only increased by 3% (from £10.9m to £11.2m), due to expected weakness in FX and upward pressure on the national living wage.
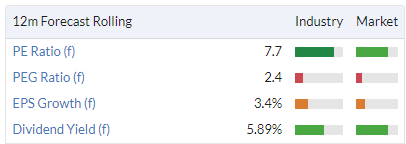
For me, the risks and potential rewards have been priced in at a PER of only about 8x:
I do worry about risks in relation to the company’s expansion plans and its exposure to the gold price, but I’ve had the chance to quiz management on these topics and their answers struck me as sensible and well-reasoned. See the 6th June SCVR for my question on industry competition as the company expands, and the 15th January SCVR for my question on how the company manages gold price risk.
With major risks being well managed (I think!), it should be full steam ahead for Ramsdens and its shareholders.
The company is very proud of the development of its foreign exchange product, especially its multi-currency card, so it is a shame that this market has apparently softened. But with a well-balanced set of income streams, softness in one area can be counterbalanced by strength in another, as is currently happening.
In summary: I’m glad to see the profit upgrades here, and have no reason to change my positive stance.
XP Power (LON:XPP)
Up 1% to 1263p (£306m) - Interim Results - Graham - AMBER
We have interim results from “one of the world's leading developers and manufacturers of critical power control solutions for the Semiconductor Manufacturing Equipment, Healthcare and Industrial Technology sectors”.
The full-year outlook is unchanged as the market was anticipating these very poor numbers.
This stock has been a rollercoaster ride involving financial difficulties, fundraisings, bid interest and profit warnings.
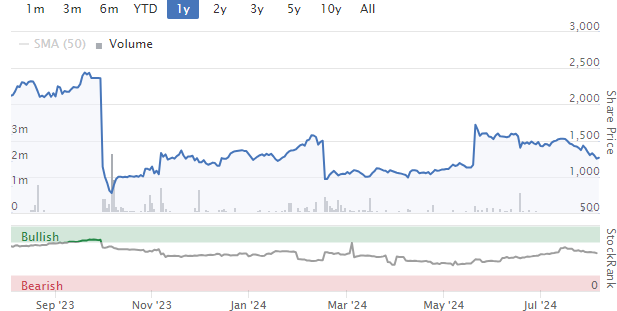
The current state of affairs is that XPP’s NASDAQ-listed suitor walked away (in June) after failing to receive any cooperation from XPP’s Board. The Board are sure that they want to continue as a standalone company, so that is what is happening.
Here are the interim results, using the company’s adjusted figures at constant currencies:
Revenue down 18% to £127m
Book-to-bill at 0.69x, i.e. the order book continues to fall as orders are fulfilled and not replaced.
Order book £149.5m (a year ago: £250m).
Operating profit down 36% to £13.5m.
Net debt fell back to £104m, giving a leverage multiple of 2.2x. This multiple isn’t particularly low but neither is it distressed. The company says that “actions to improve balance sheet resilience are delivering ahead of expectations”.
Outlook:
Confident that our financial performance will improve and reflect underlying operational improvements once channel stock levels reach equilibrium and as demand recovers within the Semiconductor Manufacturing Equipment market
It remains difficult to be precise about the timing of the recovery with channel destocking now expected to continue until the end of the third quarter, longer than previously expected. The profit impact of this is offset by decisive cost actions already taken
Adjusted Operating Profit expectations for 2024 are unchanged, more evenly weighted between each half and generally less sensitive to demand conditions in the second half
Overall this strikes me as a positive outlook statement, in the circumstances. When trading has been so poor, what I’m looking for are signs that trading isn’t getting any worse - and that seems to be the case with the company not relying on a big H2 weighting to meet expectations and with the result “less sensitive to demand conditions”.
CEO comment says “The proactive actions we have taken to reduce cost and working capital have created a solid platform from which to trade profitably and cash generatively whilst we wait for market conditions to recover”.
Graham’s view
It was a bold move to ignore the bid interest in difficult circumstances but management have followed through with a 16% reduction in adj. operating expenses.
Indeed, first half profits were “slightly ahead of the Board’s expectation”, thanks to the extent of the cost cuts.
There has been a broad-based decline in demand from XPP’s sectors: Semiconductor Manufacturing Equipment, Industrial Technology and Healthcare. Unfortunately short-term demand has been much more volatile than anticipated, even if the long-term prospects remain positive.
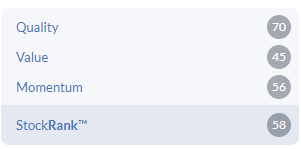
I think I am going to stick with a neutral stance on XPP. I applaud the company’s success in cost reduction and I believe them when they say they are well-positioned for a recovery. But as with other stocks, the timing of recovery is unknown and the market cap here is not at a level that I would consider to be distressed at over £300m (price to sales is about 1x).
I’m in good company as Stockopedia’s computers also see this one as offering quite average prospects from the current level:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Hi Paul - What are your thoughts on the Zotefoams (LON:ZTF) investor meet? I missed it so had to watch the recording so couldn't ask my question around Refresco Nv (AMS:RFRG^D18) and how they benefit from the partnership financially. The collaboration was discussed A LOT and I'd like more information on how it impacts Zotefoams financially so will need to email them. It seems they have delayed the start of market trials by a few months, which makes me think maybe there were a few teething issues identified by Refresco that needed further adaptation. I imagine the delay in monetisation has caused the slight pull back in SP in the afternoon although I am still very confident on the company in the medium term. Maybe it's the change in CEO but the excitement around Rezorce seemed more tempered and the CEO seemed to be managing expectations.
Just adding to Graham's useful comments on XP Power, I note that in the most recent Factsheet from Sanford-Deland Free Spirit Fund, the manager expresses concerns about the way XP Power has treated its shareholders (which used to include this fund) noting that "we deem the company uninvestable". Worth reading for potential new investors.
XP Power (LON:XPP) In summary: XP Power was on our "naughty step" due to a profit warning shortly after expressing confidence in full-year results. The share price was further impacted by debt from acquisitions and a costly US court case loss. We began selling our position.
On May 21, NASDAQ-listed Advanced Energy Industries revealed three cash takeover proposals for XP at significant premiums, made over seven months. Two proposals preceded XP's equity refinancing at a much lower price. While XP mentioned receiving proposals during the fundraise, they didn't disclose the valuations.
The Board proceeded with the fundraise, participating personally, despite knowing of higher-value approaches. We expect the Board to act in all shareholders' interests and expressed this in an unanswered email.
Given XP's recent history, we believe the approach levels should have been public for shareholders to decide. We now consider the company un-investable and exited our position in July.
XP Power (LON:XPP) I trust it’s ok to add some alternative points of view on XPP as I have recently been buying a few shares. My interest was initially piqued by the appointment of Jamie Pike as Chair 18 months ago. He is an experienced Chair who has overseen several company turnarounds, including the successful takeover sale of Cobham to Advent at the end of 2019
XP Power is clearly a business in transition and today’s results show that they’ve not got everything right. Clearly some remain peeved that the bid approaches were not declared to the market and I can understand why- it is a market anomaly which distorts the market; however I believe that their existing larger institutional shareholders are to the main supportive of management and their turnaround plans, otherwise they would have pushed them to announce the bid/ accept it once it became public
As to Sanford DeLand, I subscribe to their newsletters too and am interested to see what they are buying and selling. In fact, it is their clumsy exits which have given decent buying opportunities in the past. The most recent example being PayPoint (LON:PAY) . They said in their July 2023 Newsletter that they had exited their position and while we don’t know their exit price we do know that the price between May & June was 430-467p. It is now 685p excluding dividends. I’m sure they get plenty right but I’ve benefited from buying their sells once they’ve driven the price down . The jury remains out on XPP (& I rarely get my timing right) but I do believe it has potential
The Zotefoams (LON:ZTF) results look good on the face of it (I hold). As a chemist I have had a good look at the chemistry, and it is straight forward and protected by IP. They are a long way down the road to proof of concept, and the ability to use existing packaging lines is a major advantage which will significantly derisk a decision by customers. Twenty years supplying food and drink to the supermarkets across the UK and Europe leave me in no doubt as to the size of the market and potential impact of a truly recyclable drinks carton. Of course this is the excitement for all of us.
However, I am left with several questions arising from their half year results announcement, of a strategic rather than financial nature.
1] Net debt has increased by 41.1% of which half is accounted for under IRFS 16 for assets in China for which Zotefoams has a right of use for 10 years (although paid off over 5 years). This is the result of their global alliance with Suzhou Shincell New Materials Co, Ltd. We are told this alliance secures agreements on technology licensing from Shincell to Zotefoams, development and market co-operation, and regional product distribution agreements, where certain products from Shincell's unique technology will be marketed alongside Zotefoams' existing and future product range. I am currently a little lost as to who gets what, at what price, in which markets and how an IRFS 16 liability has arisen. Somebody brighter than me - Paul - might be able to provide some illumination. In the meantime, I have written to them. It will be interesting to gain a deeper understanding of this relationship ... is it one of equals?
2] Zotefoams (LON:ZTF) is seeking a strategic investor to facilitate the scale-up and delivery of the ReZorce solution globally. They are being advised by Mazzone & Co, who are a US-based specialist in packaging M&A. They are well down the road and imply a strategy is expected during the second half of 2024. Mazzone & Co are a well-known US-based investment banking boutique in the food and drink industry, with specialist knowledge and contacts in the packaging industry.
Transactions — Mazzone & Associates (mazzoneib.com)
The appointment of Mazzone leaves me wondering where the relationship with Refresco fits in. Refresco was announced as the joint development partner for bringing ReZorce to market..... joint development partner, JV investor, or customer? Refresco are the world's largest independent packer of beverages.
Global independent beverage solutions provider | Refresco
The only interesting thing about Zotefoams (LON:ZTF) is ReZorce.
The polyolefin foam business which represents 48% of Group revenue is a commodity business with lots of competitors where gross margins are determined by one's ability to hedge low-density polyethylene feedstock prices.
The High Performance Polymer division, accounting for 51% of sales is very dependent on one global customer.
The future success of Zotefoams (LON:ZTF) will be driven by ReZorce but the strategic execution risk is significant, and I don't yet understand how all these players fit together. My fear is that Zotefoams gives away too much in the dash for market. Just my thoughts and I would be super interested to hear other views.
This is most interesting and valuable, and especially valuable to me because, by my standards, my holding in Zotefoams (LON:ZTF) is large.
I shall be very interested to know if the company bothers to answer, and what you think of their answer. Either way, do please let us know. Their response will be most revealing.
I have also written today to Zotefoams with two less incisive questions. I often write to a company before investing, as i reckon their response - or non response! - can be most revealing of the culture of that company. I once wrote to Volution (LON:FAN) , and I was so impressed by the speed and quality of the response (the CEO even giving his direct number!) that I immediately invested an unjustifiable amount of money. This investment has more than doubled.
On this matter I previously wrote to Zotefoams and was so impressed by the honest and punctual response from the CFO that I increased my holding last year. I hope you receive the same quality of response I did.
My knowledge of Shincell from the previous investor meet was that Shincell was a one off cost to support production and they received none of the IP in the deal.
Fascinated by this. Thanks for letting me know. As yet, I've had no answer, but it is the day after their results, and I must not get too impatient!
Zotefoams (LON:ZTF) you might want to watch today's presentation on the Investor Meet Company platform when the recording comes available.
@SIH - Diabolical results - So why SP holding up?
Looking forward to your comments on @Zotefoams (LON:ZTF). I hold, and am tempted to increase. To my layman's eye it seems a mildly exciting long-term hold. But you are so good at pointing out relevant stuff that i would miss.
btw, everyone else seems to write the name of the company in blue (as a link). Apologies for not doing that. I'm sure i'm being annoyingly ignorant, but perhaps someone can put me right! I have obediently typed in the @ sign.
Type @ and a box pops up for you to put the ticker or name of the company. That’s it.
thanks so much. Beautifully simple. Even though half gaga, I won't forget that!
Zotefoams (LON:ZTF) if you type @ you should get a box appear, just type the ticker ZTF or the name and the stock and several others should appear on a dropdown list, just click on the one you want.
Mark Simpson has written some negative posts on Zotefoams (LON:ZTF), good luck finding them though. I think he was comparing it with Luceco (LON:LUCE).
Many thanks. Goodness this discussion board can be useful, and unlike some others, mostly has a good tone.
Yet more thanks! Without much hope, I just googled "Mark Simpson zotefoams" , and up popped links to two articles, interesting both about zotefoams, and general concepts. The articles, esp if one includes the valuable comments underneath, are quite long (very approx 20 pages each,) so i have printed them out for reading in the bath tonight.
Thanks for this Nettle ... much appreciated.
Domino's Pizza (LON:DOM) price action is wild this morning on their news/update!
it started UP 7% i.e £3 to £3.25 then crashed down double digits after. it is currently -8% from opening from 3.00 to £2.86 a share
extremely erratic price action, mr market in full swing!
"I don't think any are any public listed cos (please correct me) in this area."
Gore Street Energy Storage Fund (LON:GSF)
Lost enough on this
Gresham House Energy Storage Fund (LON:GRID) is another, interest rates and a flood of capacity has clobbered margins in recent times though
Any views on N Brown (LON:BWNG) ? Price has been on a tear since results in June. Big director buys in mid July. Frasers have mopped up 20%. Mkt cap only £109m.
Paul's full review of results here:
https://www.stockopedia.com/co...
For those that follow Card Factory (LON:CARD) they are advertising for a new head of business development on LinkedIn - I wouldn't normally post this but the point is they state in the job description they require international experience (especially in the USA). Anyway just some insight into where they may be going next with their international expansion plans.
Ramsdens Holdings (LON:RFX)
Up 75% to 206p (£65m) - Trading Update - Graham - GREEN
would be nice for shareholders if it ws a75% increase i suspect it should read 7.5%?
75% up on the day. well perhaps best to wait for the pull back.
well spotted! G
UK Construction Output Jumps the Most in Two Years, S&P Says
https://archive.ph/6pbN9
I've been adding Alumasc (LON:ALU) which will surely be a big beneficiary of Labour's push on building homes.
P/e 7.8, yiel 4.99%, MC £78m, 10d/3m volume +134%, StockRank 96.
I agree about Alumasc (LON:ALU) l was looking to top up yesterday or today but the share price did not fall back enough.
Yes Alumasc (LON:ALU) has risen quite a lot so I would also be looking for a better entry point. Luceco (LON:LUCE) might be an alternative way to get some building material exposure? It's actually gone in the opposite direction to ALU having dropped around 25% from its peak, probably partly due to fears over higher container costs, although this should be at least partly offset by lower copper prices (not sure the extent to which they hedge). I currently hold Michelmersh Brick Holdings (LON:MBH) and Eurocell (LON:ECEL) within this area, but looking to add one more.
Reflecting on the pull back... during this moment of relief. I don't think you will find any answers in Macro data nor the post pull back analysis being spewed out over twitter.... the economic data has finally started to deteriorate ....well lets face it, it has for ages but initially it was taken well as CPI fell....and now unemployment data and ISM line up behind it ....suddenly we are in recession fear zone. Honestly no-one knows how sanguine or bad this could turn out....markets don't like recessions though, esp when they are all in. So naturally high profile sellers with big reputations have announced lighter positioning. And you add conflict overseas and riots at home.... suddenly you have a barmy summer. I think I have read somewhere once unemployment data turns down it doesn't pick up without a major policy shift.....
and so there you have it... the market has gone from not yet, ride the bull to crikey, this bull is getting feisty.
But, during these uncomfortable times policy changes are most likely inflationary ( by definition to offset a deflationary bust) and so the real question is just how long it all takes before the mkts get what they want. The speed of the unwind has some positives in this respect as weakness in financial mkts could force the Fed to step in. ie to avoid a deflationary bust. And so ? well reflationary policy will help real assets, which equity is one. Whilst short term bonds will benefit it is unclear whether longer dated bonds will. Bizarrely this could leave monetary policy inert as financial conditions remain constrained. But equities could be ok. The decoupling theory for UK equities MAY still hold but as Paul suggested in his podcast, the Labour government seems to be steering dangerously away from election promises, in the first innings. And the riots don't help. Never the less the starting point is so less hot than the Nasdaq / large cap US equities ... I will be running my book from here. Having said that I don't have many of the hot stocks to think about sadly.
To me, what is clear from this shock is "stuff" is changing. Positioning is likely large and out of kilter .... so Id be quite surprised if this just passes ... and let's face it, a continuation of the current data deterioration will likely result in the same again. So this risk needs a little thought... and therefore cash on sidelines is suddenly a nice thing rather than annoyingly holding back our returns. If you don't love your positions but the mkt does..then it's never a bad time to sell. For now the market has decided the fed is behind the curve... and so bad news is bad news until they catch up IMO. It's always worth reminding yourself how quickly they recovered from the crash of 87 if this is your main fear.
And the point : well you need a portfolio you are happy to ride through tougher markets. Which may just be more volatile rather than negative but as we have now witnessed that can be quite something.
FWIW, apparently only one and a half times (?) in the last half century has Fed tightening been followed by a soft landing. Personally, it was surprising to me that large mortgage increases on both sides of the pond have not had an impact until now. Are Covid savings now exhausted?
Epitychia
Paul Hill showed a chart in his discussion with Paul Scott recently indicating that household savings in the US have come down dramatically post Covid but in the EU these are largely stable and in the UK are even increasing - perhaps this helps explain why the US jobs growth is slowing (but still growing). Reducing interest rates before they hit any possible recession might stave off significant market falls and appear likely through the rest of this year but as we have all learnt to our cost markets overreact on the upside and the downside. Glad I'm not Big in Japan!
USA has a huge lag from mortgage rate changes to impact on consumer finances.
This is because of the 30yr fixed rate standard in the USA.
Will impact volume of new homes sold though. But with net migration (legal and illegal) in recent years at record highs, the underlying demand is increasing still and may mop up the (tepid) new homes capacity coming in the market, keeping house prices high.
@plantex, Any chance you can give an update on how the freight rates are looking? I see that Luceco (LON:LUCE) mentioned the high rates in their last update and price had drifted since. tia
World Container Index - 01 Aug
Drewry’s World Container Index decreased 1% to $5,736 per 40ft container this week
Sorry just back .
Still high.
9000 usd 40 ft from java that i do know
In indonesia exporters getting hammered.
Ill Check again tomorrow but I dont think you have any chance of 5700 per 40 foot as below post from china
The general ipinion was rates staying high
You start with 2 great sentences !
Zotefoams (LON:ZTF) increased demand from olympics. Will this follow through into H2? I see some nice Nike trainers worn by the runners....
Apparently so, the Zotefoams (LON:ZTF) (I hold) review of operations says they expect it to continue into H2 and then moderate thereafter.
The new packaging will be the major catalyst for a sharp price upwards (I hold).
my worry for Zotefoams (LON:ZTF) re Nike is Nike's recent drop in sales etc. I'm no expert at all but if Nike are their exclusive customer for the shoe foam surely this could have a big impact on Zotefoams (LON:ZTF)
My morning smallcap tweet: The Doomtown Rats
Orchard Funding (LON:ORCH) Airea (LON:AIEA) Mincon (LON:MCON) H C Slingsby (LON:SLNG) Hostmore (LON:MORE) Ondine Biomedical (LON:OBI) Ramsdens Holdings (LON:RFX), Epwin (LON:EPWN), SIG (LON:SHI), Zotefoams (LON:ZTF), ENGAGE XR Holdings (LON:EXR), Venture Life (LON:VLG)
◄Orchard Funding (ORCH)► largest customer Nukula has gone into administration affecting £16.7m of lending out of £66.8m. [SP=35 Cap=7m]
◄AIREA (AIEA)► misleading headline "Solid trading in challenging market conditions and positive outlook". In fact warns that it has "moderated its full year sales growth and profit expectations" as Q2 rev down 5.6%. Confident in long-term natch'. [SP=29.8 Cap=12m]
◄Mincon (MCON)► H1-June rev down 16%, op profit €0.2m (€7.8m). Challenging Q1 mkt continued but saw a recovery in order books towards the end of Q2. "Retains its confidence in a return to growth in revenues and margins in H2." [SP=33.5 Cap=74m]
◄Slingsby (SLNG)► H1-June rev down 6%. Blames customers reducing or deferring spending following cost increases and uncertainty caused by the General Election. Passes div. Outlook catious. [SP=349 Cap=3m]
◄Hostmore (MORE)► talks continue on acquisition of TGI Fridays with the aim that the combined business will transition to an "asset light" fully franchised model with no corporate stores. H1 LFL down 10%. Debt in Q3 likely to exceed borrowing capacity, discussions with various parties regarding additional financing. [SP=14.6 Cap=19m]
◄Ondine Biomedical (OBI)► Leeds Teaching Hospitals NHS Trust will begin using Steriwave nasal decolonisation technology this month. [SP=7.75 Cap=22m]
◄Ramsdens (RFX)► guides FY-Sept pretax at least £11m, ahead of expectations of £10.5m. Cites high gold price. FX only broadly in-line though. [SP=193.5 Cap=61m]. I hold.
In line: EPWN, SHI, ZTF, EXR, VLG
Hargreaves services
Chairmans statement finally reveals an independant market appraisal. Valuation of current wind farm assets of 27-29 million which are on the balance sheet at cost of 8 million .
These are very realisable assets in a good sector z
Note these are “current” so that doesnt include the wind farm potential of the other potential projects nor the ones on planning .
The market is ignoring tbis but with them stating they ate going to realise rhese assets its just free cash .
New Gov't committed to committed to doubling onshore wind energy by 2030. https://www.gov.uk/government/...
I wander if this is good news for current on shore wind garm generators or not ? I suspect if block on onshore wind has made current sites more profitable due to less competition what happens if we now move to higher level of excess supply in the wrong place at the wrong time?
I have some forestry in Scotland and have just signed with a. Wind farm developper.
Had 4 companies chasing me all backed by big money PE .
Its all a bit silly and just the latest merry go round for the governement to waste a load of tax payers money with no long term strategy other than headline statements and inittiatives .
The actual issue is not wind farm generation its energy storage .
Seemingky when all our turbines in the uk are spinning we generate enough energy for the UK .
We pay the comoanies for the energy produced .
Then we chuck it down the toilet and dont use it because we cant use it .
So your producing something that you have to buy that you cant store .
Bring back maggie thatcher im sure she leart this at her dads grocers when buyimg milk .
And all these wind farms are effectively getting subsidised by governemt money and then we end up buying electricity we throw away .
Its total madness but its a big political flag to wave and we will pay.
But solve energy storage for wind i think thats the thing givernment should be getting sortted first .
The more you learn and know the more you find smoke and mirrors and the same illuminati types pulling the strings making big money .
And lets not gdt started on carbon credits .
Or dealing with SSE who are putting a huge power line right through scotland .
And dont mention weevils who ate 25% of the trees planted last year .
And the deer who love nipping the budd of saplings
Anyway my dad was wrong
He told me “listen son momey doesnt grow on trees”
Use excess electricity for production of hydrogen maybe.
Gibbs Free Energy says not. By far the most thermodynamically feasible option is to store it in a flow battery, or use the excess energy to pump water back up the mountain for hydro, converting excess electrical energy to potential energy. A mountain loch with a hydro station at the bottom is just a battery.
Or store it - East Anglia has a lot of offshore wind already and more being built. It also has solar farms and now BATTERY storage
Orsted to build a battery system capable of powering 80,000 homes https://orsted.com/en/media/ne...
....or if you're with Octopus like a friend of mine, use it to charge EVs - on one day he tells me he was paying 7.5p per KwH to charge his car at 2pm (not 2 am, as he expected). Why? Because the wind was blowing...
So true. I wish I could give your post two thumbs up. Of course, their get out is to claim that they will export any excess, but funnily enough, all potential neighbouring export markets have their own wind power, and when the wind is blowing in the UK it’s also generally blowing there, so the export price is close to zero. The whole thing is a green washing waste of UK tax payers money. The only reliable, long term solution to our energy needs is nuclear power.
Power storage...
There are a number of organisations working on this. The issue is they are not cheap. But... when there are times that power can have a pretty much 0 value (possibly negative) and other times when the price is high, I have faith in human ingenuity.
I don't think any are any public listed cos (please correct me) in this area. There is Highview enterprises (I hold) that is partly owned by sumitomo heavy industries.
Invinity Energy Systems (LON:IES) makes flow batteries. Unfortunately they don't make much money.
Great post! You talk a lot of sense (unlike all politicians!)
Governments driven by ideology not by science. I have long thought why not fund research to solve the problem first before you spent billions on the taxpayer. The energy storage has not been solved and at the moment sounds really expensive.
science really says CO2 is not the problem, and fossils are still abundant thanks to fracking.
No reason anyone should listen to me, but people might take note of that infamous climate change activist (checks notes) - Margaret Thatcher. Here's her address to the Royal Society in 1988 when the global warming implications of carbon dioxide emissions were becoming apparent. With her background in Chemistry, she did, of course, fully understand the science and that CO2 really is the problem. https://www.margaretthatcher.o...
Amazing isn't it how many of those who have studied and understand science share her views, and how many of those who will fight to the death over their belief that only opinion not facts matter don't have that background!
Molten Salt storage is interesting. One I'm watching for scalable storage eg Sinergy from Siemens AG (ETR:SIE) and lots of others. Early days.
Chris Mills seems quite excited about this one. Notice the stock is in a nice stage 2 uptrend too. The Carbon Border Adjustment Mechanism is still a way off though (Jan 2026). No position at the moment.
Hargreaves Services (LON:HSP) , yes, land assets held at cost has been hidden value.
German operations still impacting results due to Russian pig iron and zinc prices but looks like things are now improving.
Pension deficit now under control, resulting in increased dividend.
Services division should be a beneficiary of promised infrastructure spending, subject to Rachael Reeves' Treasury team.
I hold
£Keller interim results look excellent
"Outstanding first half performance sets new records across the Group as we continued to sustain and build on the material step-up in operational and financial performance delivered in 2023"
Revenue of £1,489.8m, up 5% at constant currency
Underlying operating profit of £113.2m, up 76% at constant currency
Underlying operating profit margin increased by 300bps to 7.6% (H1 2023: 4.6%)
Underlying diluted EPS of 103.3p, up 85%
Underlying ROCE at 28.4% (H1 2023: 16.6%), the highest for 15 years
Net debt of £100.7m, down £46m since December 2023, driven by strong profitability and cash generation, with net debt/EBITDA leverage ratio of 0.3x (H1 2023: 1.2x; FY 2023: 0.6x)
Statutory operating profit up 87% to £105.9m
Statutory diluted EPS of 94.7p, up 110%
Board's expectations for full year 2024 materially increased, underpinned by our record order book of £1.6bn
I’ve owned Keller on and off over the years but have never seen them expand margins quite like this. The margin expansion in the US in particular is exceptional with operating margin now up to 12%. I’d need to try and figure how sustainable they are and why they’re are only managing this now. Phenomenal cash flow to put such a dent in the debt in just 6 months as well.
ZTF Interims looking good - Slight concern over the increased level of debt = Other views?
A combination of an increased inventory for Q3 demand, an increase in the purchase price and investment in fixed assets.
Half the increase in debt is a recognition of liabilities under IFRS 16 resulting from their partnership with Suzhou Shincell New Materials Co. Ltd. The other half? ... see ChrisR below.
Zotefoams (LON:ZTF) interims look reassuring at first reading.