Small Cap Value Report (Tue 6 Dec 2022) - HOTC, VNET, VIC, MERC, HSP, VRS, SOLI, SED

Good morning from Paul & Graham!
Podcast - guilt overcame me last night, so I recorded the weekend podcast here, summarising the previous week's SCVRs, and some macro thoughts. Sorry for it being late.
Hotel Chocolat (LON:HOTC) - as promised, I mystery shopped the Islington branch last week, and was left unimpressed with products, which strike me as ordinary, and over-priced -
Agenda
Paul’s Section:
Vianet (LON:VNET) [quick comment] (£18m) - Interim figures to 30 Sept 2022 look OK, with the hospitality sector returning to normal. Outlook for FY 3/2023 - confident in achieving market expectations. Cash position has worsened. Both inventories & receivables look a little high. Negative cashflow in H1, and note that it’s capitalising c.£2m p.a. into intangible assets (£1m in H1), which puts a question mark over the adjusted profit numbers (which seem to ignore amortisation of capitalised costs). Overall, I don’t think this is worth pursuing. No section below.
Victorian Plumbing (LON:VIC) (£221m) - I review the figures for FY 9/2022. It's beaten considerably reduced forecasts, but only if you're prepared to ignore the excessive share options cost. Great balance sheet, with a big net cash pile, so it's decided to start paying divis. I like the business, but not as much now that shares have risen 80% from recent lows, when we flagged it as a bargain here. So it might make sense to top slice, to lock in some of those profits maybe? It's not such an obvious bargain any more.
Hargreaves Services (LON:HSP) - I review below its in line with expectations update. What an interesting value share this is - super low PER, combined with a big dividend yield, and a strong balance sheet. Lots to like here, for value investors. Harwood Capital owning 28% is a good sign for valuation, but could introduce risk for small shareholders, if they try to whip the upside away, e.g. by pressuring mgt to de-list, or make a lowball offer, both of which Harwood have done before. Overall though, HSP shares look very interesting, and it gets a thumbs up from me.
Versarien (LON:VRS) [quick comment] - top faller of the day, down 34%. It’s got the begging bowl out again, raising only £1.85m at just 10p per share. See what I mean about avoiding any share that needs to raise cash from a position of weakness? It’s not enough either, as more cash is needed, with non-dilutive routes (grants, partnerships) also being explored - good luck with that. VRS has a terrible track record, and management strike me as rampy - lots of exciting announcements, but nothing that ever makes a profit! The tide has gone out for this type of share, so praying for a miracle is the only alternative to dumping the shares and moving on. [no section below]
Graham's Section:
Mercia Asset Management (LON:MERC) (£147m) - this fund manager and investor of its own capital reports good H1 results. The extraordinary gains of H1 last year have not been repeated, however the underlying operating profit measure is up by 6% and the investment portfolio generally appears to be doing well. I continue to find it strange that this stock trades so cheaply considering its fortress-like balance sheet, including a huge cash position, and its good track record. A small acquisition announced today also sounds like good news, bolstering its capabilities.
Solid State (LON:SOLI) (£157m) - a nice earnings upgrade from this manufacturing company. Its acquisition strategy is going well, with the integration underway of a US-based company that it acquired over the summer. Overall, I see more to like here than to dislike: the company has been making efforts to improve its gross margin, and its operating margin is rising. The overall quality of the business appears to be better than average for the manufacturing industry, and this is reflected in a premium valuation for the shares.
Saietta (LON:SED) (£76m) (-3.6%) [no section below] - this 2021 IPO “designs, engineers and manufactures complete light-duty and heavy-duty e-drive systems for electric vehicles”. FY March 2023 revenue forecasts were demolished in November, with the company saying that it was pursuing far larger systems contracts for the following year, instead of near-term revenues. Today’s interim results confirm H1 revenues of less than £1m and an operating loss of £10m. At least it has £22.7m of cash on its balance sheet, thanks to a placing in August, so it has a little bit of runway before it runs out of cash.
It says that it is “on track to ramp up UK-based and India production”, and “remains dedicated to securing several long-term, high volume OEM relationships globally”. A separate RNS today describes a series of agreements with “one of the largest OEM’s operating in the light duty mobility market in India”. £3.2m of revenue is mentioned, which strikes me as a small amount compared to the £32m of revenue baked into expectations for FY 2024. Having already slashed its forecasts for FY 2023, I wouldn’t be surprised to see the FY 2024 forecast getting slashed in due course. Given the very fast rate of cash burn and at a 2024 price/sales multiple in excess of 2x, based on a revenue forecast I don’t trust, these shares look overcooked to me even after they have already fallen by 70% year-to-date. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Victorian Plumbing (LON:VIC)
68p (pre market open)
Market cap £221m
Victorian Plumbing Group plc ('Victorian Plumbing', 'the Group'), the UK's leading online specialist bathroom retailer, announces its full year results for the year ended 30 September 2022 ('2022').
Results ahead of expectations, with H2 revenue growth as the Group demonstrates continued trading momentum and further market share gains, supported by a robust balance sheet
Board proposes maiden ordinary full year dividend of 1.1p and an additional special dividend of 1.7p
I flagged up here on 6 Oct that VIC shares looked cheap at 38p, and with a very healthy balance sheet supporting the downside risk nicely. They’re now up 79% in the last 2 months - not bad going.
Key numbers for FY 9/2022 -
Revenues £269.4m (flat vs LY)
Gross profit margin down, 45% (LY: 49%)
Overheads up 12% to £101.5m
Within that, marketing costs look enormous at £76.2m
Adj EBITDA halved to £19.5m
Statutory PBT shows £11.8m profit (down from £19.7m in the previous year, which had several distortions - boosted by the pandemic, but hurt by £9.4m IPO costs).
Adjusted operating profit strips out the one-offs, so is a good measure of underlying performance, and fell 57% from £37.1m LY, to £16.0m this time.
Balance sheet very healthy, with NTAV of £40.7m, including net cash of £45.5m. It's a capital-light business model, which I like.
Bank facility of £10m RCF is unused, and looks unnecessary.
Cashflow statement - looks very clean, with genuinely good cashflows.
Note 10 shows that £2.2m of internal salaries were capitalised into intangible assets as “computer software”
EPS - this is tricky, as the 3.9p adj EPS seems to ignore the substantial £3.9m cost of share-based payments, as you can see from the workings here -
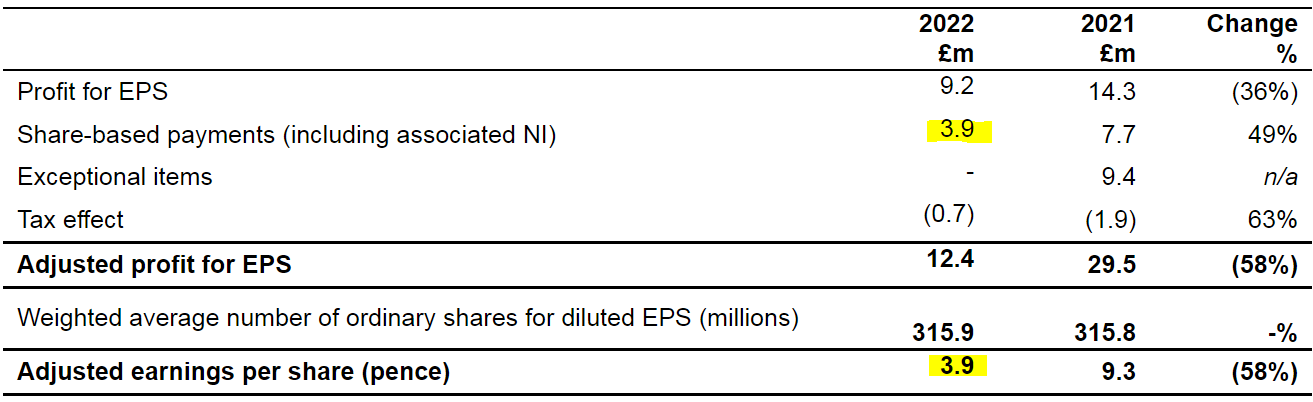
I’d be inclined to work out EPS on the £9.2m unadjusted profit (i.e. including the share-based payments cost), which would re-work EPS to 2.9p, instead of 3.9p. This 2.9p EPS figure ties in with the “diluted earnings per share” figure just underneath the P&L, so this is the figure that I would be inclined to use for valuation purposes, not the higher adjusted number.
Dividends - it’s got surplus cash, so a policy of paying divis with a 3.0x to 3.5x cover is indicated, plus special divis with surplus cash. This results in a 1.1p full year divi, plus a 1.7p special divi. So 2.8p in total, an attractive 4.1% yield. Also, in my view it’s not even breaking into a sweat paying out that amount, so divis could increase without causing any financial strain. Hence I would see this as a potentially high yielding share in future.
Outlook - sounds positive -
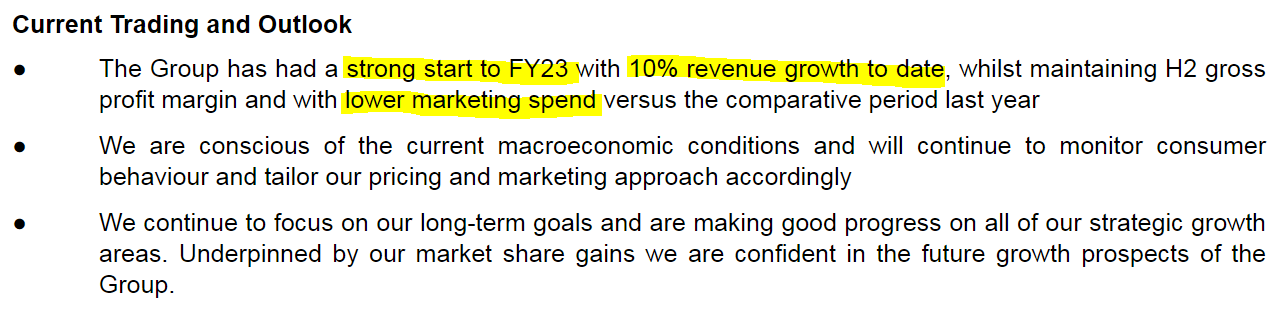
Broker updates - there’s nothing available to me unfortunately. Although the Stockopedia graph shows that forecasts have been considerably lowered (good, as it means less likely to hit a profit warning), and that FY 9/2023 is only expected to be modestly ahead of FY 9/2022, which sounds consistent with the positive outlook comments, suggesting it’s already ahead of the previous year’s numbers in this new financial year. So I think that looks OK.
Valuation - on a PER basis, and using the more conservative 2.9p EPS, at 68p per share currently, I make the PER 23 times - not cheap any more.
Using the company’s adjusted 3.9p EPS figure that comes down to a PER of 17x
If you want to push the boat out a little, then broker consensus for FY 9/2023 is 4.6p, giving a PER of 14.8 - still not particularly cheap. This was on a PER of about 10x last time I looked at it.
The cash pile is now just over 20% of the market cap, so useful asset backing there, and there is an argument for adjusting the PER downwards to strip out surplus cash.
Also there might now be some interest receivable, which on a £45m cash pile, could be quite useful, say £1m+?
My opinion - I think the c.80% rise in share price from the recent low, 2 months ago, is justified, but it now seems to me that the share price is probably up with events, so it might be worth top-slicing some of the profits?
Going forwards, it’s difficult to guess what profits it might generate in future. One angle I like on this share, is that several eCommerce companies have told us recently that online marketing costs are now reducing. Given that VIC spends a colossal amount on marketing, then even a relatively small fall in that cost could drop through nicely to the bottom line.
Overall, given all the uncertainties, if I held this share I’d be tempted to bank some or all of the recent 80% gain, and maybe let a smaller position run.
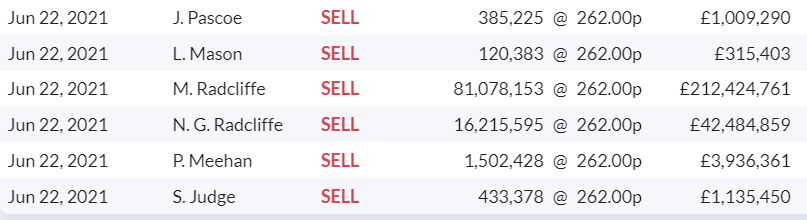
Note the shareholding structure is that it looks controlled by the Radcliffe family (holding c.59% amongst 3 people with that surname). Hence it would be worth checking how committed they are to remaining stock market listed? Note the gigantic, and shrewdly timed Director sells in 2021! There must be some de-listing risk, when they presumably have the cash to buy out minority shareholders, on unknown terms.
.
Hargreaves Services (LON:HSP)
347p (up 1% at 10:02)
Market cap £113m
Hargreaves Services plc (AIM: HSP), a diversified group delivering services to the industrial and property sectors, provides the following update on trading ahead of reporting its interim results for the six months ended 30 November 2022.
This is not the easiest of shares to understand, since it’s a mix of businesses in engineering & property development, which arose as legacy coal distribution activities wound down.
So I think a sum-of-the-parts type analysis & valuation makes sense, which takes too long for us to cover in these reports. However, the valuation metrics look such good value, that I want to flag it to readers as a value share that could be worth you investigating.
Today it says (my summary of main points) -
Strong H1, ahead of LY (both revenue & profit)
All 3 business segments have improved.
Contracts sound well-planned, with cost escalator clauses, or cost plus structures, hence higher costs are being passed on to customers, protecting profits.
German JV has uncertain outlook for H2 (but that's already baked into the forecasts)
Healthy cash position of £18.1m (up £4.3m in last 6m)
Leasing debt has increased £12.2m to £30.6m in last 6m, to service HS2 contract.
Most important point is -
The Board remains confident of delivering full year results in line with market expectations.
Broker update - many thanks to Singers, which provides a brief, but helpful update note today. It’s saying forecasts are prudent, with 71.7p adj EPS for FY 5/2023. That’s a PER of only 4.8 - so you would need to check how sustainable profits are, as such a low PER could be indicating to us that future profits might fall. I see that almost all the profit for FY 5/2022 came from the German JV, which had an exceptional year which may not be repeated.
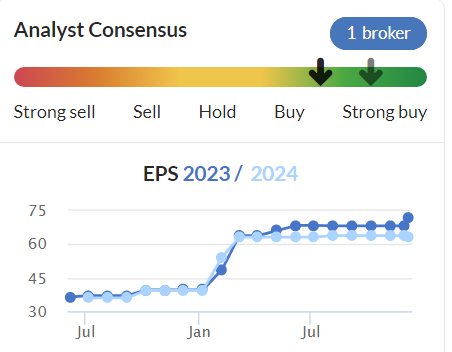
Note that broker forecasts have been rising -
Dividends - HSP has been paying decent divis in the last couple of years, and 21p is expected for this year, giving an attractive yield of 6.1%
CEO results interview - I’ve not seen this before, a video actually embedded within an RNS, which you can click on & play the video as you read the announcement. What a great idea! More companies should do this, I really like a short video that draws out the main points, as it saves loads of time reading all the commentary.
Balance sheet - looks very strong, no concerns here. Note that Stockopedia shows a P/TBV of only 0.63
My opinion - this looks very interesting! I think some readers were discussing it not long ago, and I can see why. We’ve got an exceptionally low PER, a big dividend yield, plus a valuation which is well below tangible book value.
There’s also interesting upside from the Scottish land assets, since people want to either build wind farms, or run cables to wind farms over its land, which could generate decent income for HSP. Plus continuing profits from land disposals.
This has only been a quick review, but it gets a thumbs up from me.
I’ve just seen that Harwood Capital holds 28.2%! Is that good or bad, people ask me. Both! Is my usual answer. It shows there’s value in the share, but it could be that Harwood might try to snatch the upside away from small shareholders. That said, I’ve met HSP's 8% shareholder CEO, and he didn’t strike me as the type who would be pushed around even by a major shareholder. If the right deal came along though, then shareholders could do well from it. Delisting risk is a potential issue though, whenever Harwood have a big position. That said, HSP is financially strong, so there wouldn’t be any risk of dilution, so it’s probably fine. I like this share, it looks good.
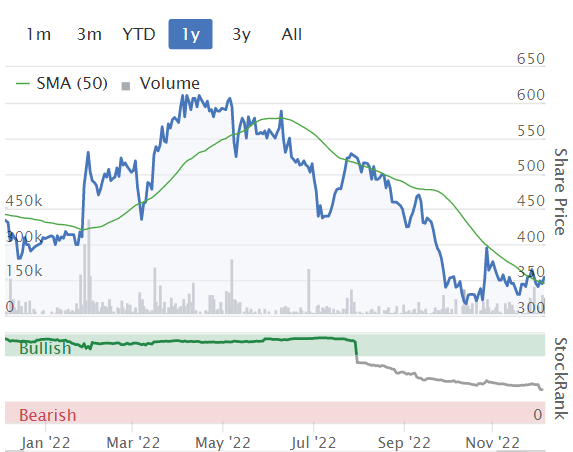
Looks like the chart might be forming a base perhaps? Combined with very cheap fundamentals, I'd say that's attractive.
Although the StockRank system is looking distinctly unimpressed -
.
Graham’s Section:
Mercia Asset Management (LON:MERC)
Share price: 33.5p (+9%)
Market cap: £147m
This is a fund manager and an investor of its own capital in regional businesses (i.e. businesses outside of London and the South East). It argues that “London and the South East has a significant oversupply of capital creating high pre-money valuations.”
I last covered Mercia at the time of its full-year results back in July. At a share price of about 30p, my conclusion was that it looked quite cheap. As of last night’s close, it was still trading around this level.
Let’s get into these interim results for the period to September:
- Adj. operating profit +50% to £3.6m
This adjusted profit measure excludes many items. I think the point of it is to show Mercia’s profits from managing 3rd party funds and receiving interest, while excluding one-off gains such as unusual performance fees and capital gains on its own investments.
- PBT £7.4m (last year: £11m)
This is an unadjusted number straight from the income statement.
Compared to H1 last year, Mercia has incurred higher expenses and has seen a weaker improvement in the fair value of its investments.
- Net assets increase to £206m or 46.8p per share.
If we exclude goodwill and intangibles, net assets are £175m or 39.8p per share.
Total assets under management are up by a few percentage points to £979m. Within this, 3rd-party funds under management increased slightly to £773m.
During a period when most active managers have seen a reduction in AuM, this feels like a big achievement! Mercia enjoyed £54m of inflows, offset by net negative performance and some distributions to investors.
The reason for the lack of outflows is actually to do with the structure of their funds: “all the capital that we manage is in closed-end or evergreen structures, providing a stable source of long-term third-party capital which is not subject to redemptions.”
Cash - one quarter of AuM is in the form of “unrestricted cash available for investment”. So there is lots of flexibility to fund its companies through a recession.
On its own balance sheet, Mercia has £56m of cash and near-cash instruments. I guess this is why it feels confident to raise its interim dividend by 10%.
Direct investment portfolio - the estimated value of Mercia’s own portfolio increased by 10% over the six-month period, to £131.5m.
Acquisition - in a separate RNS, Mercia announces the acquisition of a lender to SMEs with £415m of funds under management. The acquired business makes loans of £2m+; these are bigger than the loans Mercia currently makes. Mercia will pay up to £9.5m for this.
Outlook
With our focus on SMEs within the UK, predominantly businesses in sectors with relatively modest capital needs, we and the funds we manage, are able to continue to support these businesses with additional capital as and when needed during these turbulent times. As almost all businesses in our portfolios are private businesses, our exposure to the public markets is limited. In addition, as a debt-free, cash-rich business, Mercia is well placed to capitalise on both corporate (as evidenced by our recent acquisition) and direct investment opportunities as we invest through the cycle.
My view
I continue to like this one. In plain English, it appears to be good at what it does: making investments in small regional businesses, and seeing a profitable exit. Its own portfolio is doing well, and its 3rd party funds appear to be doing well.
The gains of last year have not been repeated, but it’s in the nature of things that returns won’t be repeated every year.
My main difficulty with Mercia is the complexity involved: there are a number of different layers to the business, and the company’s results statements always feel like a long and difficult read. And then there is the challenge of trying to understand the companies Mercia has invested in, which I have not even begun this morning.
But is it cheap? Oh yes - we’ve got a discount to tangible NAV, for a start. Then if we compare the market cap to funds under management, we find that Mercia is valued at 1.9% of AuM. But that doesn’t give it any credit for its cash pile, which is a significant % of the market cap, or for the fact that the entire company is being valued at less than the value of its balance sheet.
Also, I’ve not made any adjustment for the new acquisition, which has added another £400m in funds under management and looks like it gives Mercia the very useful and complementary new ability to make larger loans.
What have I missed? Or is this stock cheap simply because it’s quite complicated and obscure, and investors are pessimistic about the outlook for SMEs?
Mercia passes the following three bullish screens for Stockopedia:
Solid State (LON:SOLI)
Share price: £13.92 (+6%)
Market cap: £157m
Solid State is “the specialist value added component supplier and design-in manufacturer of computing, power, and communications products”. Here is its website.
In July, it raised £28m to help it to fund an acquisition of a US-based company, Custom Power. This deal has “provided a step change in the internationalisation and technical competencies of our enlarged Power offering”.
Some headlines from today’s interim results, with the outlook now ahead of expectations:
- Revenue +50.8% to £59.4m
- PBT +98% to £4.2m
- Adjusted PBT +60% to £5.2m
The other key number is that the order book has increased to £112.5m (from £85.5m six months previously).
It’s important to always look for organic growth in these circumstances and Solid State confirms that its “like-for-like constant currency organic revenue growth” is actually around 31%: not as high as the headline growth figure, but still very good!
Cash generation has fallen to almost nothing, due to “inventory investment” - a common refrain these days, especially in electronics.
Net debt increases to £16m mostly due to the acquisitions, with a sharp rise in deferred/contingent consideration.
Investor presentation - tomorrow (Wednesday) at 2pm. Here’s the link to register.
Chairman review - calling it “an excellent start to our financial year”, the Chairman confirms that the integration of Custom Power is underway and that more targets in the acquisition pipeline are being studied.
Outlook - the Chairman and the CEO each confirm that expectations for FY March 2023 have now been raised.
The Chairman’s words are worth quoting extensively:
Current order intake continues to be strong and trading since the Period end has been ahead of management expectations. Prospects for the remainder of the financial year are underpinned by the near-term open order book and the resilience and diversity of the Group.
Solid State has gained a competitive advantage from being proactive in managing the impacts of supply chain shortages, which continues to impact current trading. The business will need to be equally proactive in managing inventories and margin pressures against the weakening macro-economic environment in the UK. In the latter part of this financial year end and in to FY23/24 we anticipate seeing some supply chains start to improve. We have benefitted from strong current trading during Q3 23, meaning the Company now expects to be ahead of the current revenue and adjusted PBT consensus expectations for FY23.
My view
I’m not a specialist in this sector, but my impressions coming away from these results are positive:
- The operating profit margin has improved to between 7.5% and 9.3%, depending on how you measure it. Hopefully there is scope for further improvement as the company grows? It looks like it has never achieved a 10% operating margin (manufacturing margins tend to be modest)..
- The company puts great emphasis on its gross margins (around 32%) and has tried to improve them by selling its own brand products and focusing its efforts on higher-margin work. I always like to see own-brand products instead of distribution.
- While shareholders did suffer some dilution this year, the acquisition strategy has fortunately been managed without putting the company into extreme levels of debt.
The current debt load, including deferred and contingent consideration of £14.4m, will require some work to pay off, but an initial look suggests that it should be manageable.
The overall trajectory is positive:
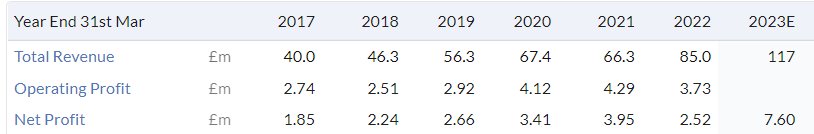
One quibble is that I don’t see any mention of return on capital as a metric. I always like to see this used as a KPI and particularly in capital-intensive industries. Stockopedia calculates SOLI’s return on capital as above-average for the industry:
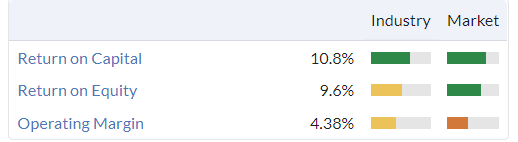
Overall, I see more to like here than to dislike. WIth a PER of 17x, before today’s earnings upgrade, the market agrees.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Hi Paul
Any chance you could look at Inland Homes following the appointment of a new CEO. It looks well undervalued!!
Hotel Chocolat (LON:HOTC) Paul, the video was worth watching for your chocolate nose! I share your dislike - whatever happened to the drive against plastic packaging, which doesn't seem to bother anyone anymore.
Solid State (LON:SOLI) is one of the few bright lights in my portfolio @ 1.5 bag so for this company the PE seems justified. I have had Vianet (LON:VNET) for so long it's getting mouldy, I know I should just dump it, but in this climate where do you stop?
Multibagger prospects are sometimes discussed on this board and one corporate approach which has sometimes generated multibaggers is the serial acquisition strategy (accompanying organic growth of course). This can be a risky strategy if executed too aggressively so I tend to prefer conservatively run serial aquirers. I would suggest that Solid State (reporting today) is one such company. In terms of its corporate style it reminds me a little of Porvair, another conservatively run serial aquirer. Another company reporting today is Oxford Metrics which I have held for many years but I must admit, I never really though of this as a serial aquirer but a passage which caught my eye today was the statement by the compay that it has a:
"M&A pipeline focussed on acquisitions in known markets of
entertainment, Life Sciences, engineering and sports, and on companies which
possess hard-to-replicate, deep Intellectual Property in integrated Smart
Sensing and attractive financial metrics"
So perhaps I had better add that to my list or potential serial aquirers, presumably the funds from the sale of Yotta will be used to buy companies with the characteristics described above.
For me, another attraction of this type of strategy is that depressed share prices of smaller companies may contain a silver lining as they make potential aquisitions cheaper, providing the aquisitions can be made mainly with internally generated cash, although some of the best bargains are of course to be found in private companies, as Judges Scientific would testify.
A lot of profit taking going on today, more so in the small cap space, which is a little disappointing, and seems upside down to me but is presenting buying opportunities.
Small cap shares do appear to be holding up of late above previous lows, but it all seems a little fragile and I continue to keep a decent amount of powder dry.
We could do with some positive momentum drivers, such as
China fully remove Covid restrictions. (Seems close)
A decent reduction in inflation this side of the pond. (remains stubborn)
Some talks between Russia and America re the Ukraine war. (A long way off)
Its hard to call ATM, but with the recession looming I can't yet see the light at the end of the tunnel, with the exception of perhaps a Santa Rally up to Christmas (FTSE 250 and below?), then a tough period dodging profit warnings H1 2023.....maybe then the last of the Bulls will exit the side door...
Slow and Steady wins the race I think, and good luck to you all traversing this minefield!
Why no report on Gooch & Housego - significant AIM quoted company with poor but not very bad results today?
Busy day for me today with Mercia Asset Management (LON:MERC) Croma Security Solutions (LON:CSSG) and Vianet (LON:VNET) hitting the news.
Vianet (LON:VNET) ( I hold) - Thanks for the review Paul. No argument on these figures. In line but not terribly inspiring. Still loss making, cash outflow and net debt rising. At todays 63p it's on 38x adj earnings to Mar23. Very hefty. But plenty of jam tomorrow. A more reasonable 12x adj earnings to Mar24. Growth coming perhaps. But will it continue?
There is a presentation on Investor Meet Company this morning starting soon at 10:30
Word of warning. There may be excessive optimisim. And use of gratuitous jargon. 'Data lakes' may be involved. Wear suitable filters if of a sensitive disposition.
I think the company is at a turning point. The impact of the pandemic and now energy, interest rates and inflaction upon hospitality sites mean it was never going to return straight to pre-pandemic levels. New products have been developed and launched - particularly contactless payment - and growth in high margin sales is obsured by the loss of older business. I give it one more yearto turn the corner or I will admit defeat here, but at the moment it is executing according to plan,
cheers
Mark
Looks like a very positive update from Oxford Metrics (LON:OMG) today, and share up about 10%. No time for more now to justify Paul having a look but the sort of share that might tempt a bidder?
I will be disappointed if there's a bid unless at a very high premium. Put this one in my bottom draw already. Investor Meet Company presentation next week:
*OXFORD METRICS PLC* will be holding a *Preliminary Results* meeting on 12th Dec 2022 at 10:00am GMT.
Oxford Metrics (LON:OMG) is a fantastic opportunity to buy a world-leading niche technology business growing rapidly at a cheap valuation. Roughly £125 million market cap after today's rise , £67 million in net cash, and £5.4 million in net profit in next year's broker forecasts , with comments that the risk to forecasts is to the upside . In the next bull market it would be perfectly reasonable for a business like this with a long runway of organic revenue growth , very high gross margins and operational leverage kicking in to trade at 30x earnings ex cash
Mercia Asset Management (LON:MERC)
£188m hard NAV (30% cash and rest direct investment venture conservatively valued) plus approx £1.25bn high fee sticky assets 3rd party AUM (2/3 venture 1/3 debt) for just £140m market cap.
Direct investment portfolio can be valued (conservatively) at NAV as they don't need to eat their own NAV to pay operating expenses as this covered from operating revenue from 3rd party asset management biz. As they have shown success with their venture investments to date and tend to exit with decent mark up a premium to NAV wouldn't be outrageous either.
Can quibble about valuation to apply to the 3rd party asset management business. If very measily you might say 2% of AUM so extra £25m value or less than 1x revenue. Given this is high margin and sticky fee and AUM are on a growth trajectory in recent years (organic as well as inorganic) adding a few percent more of AUM seems not imprudent.
A business that can be a little hard to comprehend on first take...but lots of value and growth potential if looked at closely with a business model I believe to be a 'fly wheel'
Add in a >3% dividend as a bonus...fully paid for from the operating cash flows of 3rd party asset management (again not diluting NAV of direct investment portfolio)...so if you wanted to look at the 3rd party asset mgt biz in isolation and give it a 2% of AUM valuation at c.£25m that means that biz standalone supports a dividend yield of 18% and growing....(obvs a £25m valuation for that part of Mercia is far far too low!)
Agree but think Georgia Capital (LON:CGEO) is better value.
Pretty much the entire market cap is taken up by its holding in UK listed Bank of Georgia (LON:BGEO) which is doing very well in a strong economy - far better than UK banks. The rest are utility businesses in Georgia like private healthcare, pharmacy, beer ;) etc and all conservatively valued.
Yet you can buy it at 40p in the £ because of "geopolitical risk" vs Mercia Asset Management (LON:MERC) at 80p in the £
Of the two economies I'd rather be in Georgia as much as it pains me to say it.
Still - don't disagree that Mercia Asset Management (LON:MERC) is also a good business and decent value once you get your head around it.
David - that's both a daft and wrong comparison - like Apples to Sausages with some bad arithmetic thrown in - and ridiculous hype re Georgia Capital (LON:CGEO) v Mercia Asset Management (LON:MERC)
What's your view on the economic boom being caused by fleeing russians and their capital (happening all round Russia...to the great displeasure of many locals)? Why not go for even cheaper Ukraine located assets that are listed in UK? After all, if we are willing to equate geopolitical risk to more mundane operational risks in UK then it seems highly unlikely that Ukraine falls to Russia...and we know there will be a lot of (guilty European) funds directed to its rebuild.
Then as a simple matter of valuation arithmetic -> you get 75p per £ hard NAV with Mercia....and then what value the now £1.25bn 3rd party asset manager (on high and sticky fees)? Easily gets us to sub 60p per £.
PS does Georgia pay a dividend? Bit insane to invest in a frontier market (ie more risky than emerging) biz that doesn't pay out a hefty yield.
If you want frontier market risk then I'd suggest you look at Argentina. Banks and finance providers in that country tend to be first class...they have to be to survive the cycles. Super tested and seasoned management. Great yields. And when the good times come (as always happens) they know how to really make money. Now that is a payout for taking risk. High odds that Georgia surprises to the downside and becomes even cheaper...
Just looked at Georgia Capital (LON:CGEO) accounts quickly. A clear negative for is it is that it doesn't have a operating income and relies on dividends (from Bank of Georgia (LON:BGEO) no doubt) and realisations for funding. Therefore, even before considering geopolitical risk etc it should be on a discount to £MERC
So with Mercia at 55p per £ and Georgia 45p per £ ...well I'd say that Georgia looks overvalued relatively and that's before the frontier market factor
Bank of Georgia accounts for 20.9% of Georgia Capital's assets. Its largest investment is a 77% stake in a retail pharmacy business that owns 368 pharmacies as well as a wholesale pharmacy and medical supplies business. While LON:CGEO does not pay a dividend it regularly buys back its own shares at a discount of around 60% to NAV, thereby increasing the NAV of the remaining shares.
Thanks for the info - I don't really know Georgia Capital (LON:CGEO) - however I wouldn't invest other than a drastic discount and after a tough period economically for the country. That's based on quite a bit of experience in emerging and frontier markets directly.
If a discount for what you get is of interest then I'd suggest Petershill Partners (LON:PHLL) with a 50% discount to tangible book -> I've not finished looking in detail but its interesting as have the discount and potentially a growth driver too. However the big ownership by GS is off putting as so dominant
I’m with Georgia capital big time in this debate .
Pretty much all it’s market cap propped up by bank of Georgia holding .
Bank of Georgia is a great share to own in its own right.
Georgian economy has been strong for the past few years and is surging now 20% with influx of Russia .
The discount to NAV is silly because Bank of Georgia is the prime foundation .
Anyway I think it’s a decent strategy to have a percentage of your fund invested into an economy growing at 20% as opposed to UK / USA that are very clearly not !
Also think Georgia is a bit more than a “frontier economy”
Happy to hold, Bank or Georgia I hold too and is my best performing share this year as I bought after it was sold off following Putin invasion .
Agree : Bank of Georgia (LON:BGEO) has compounded at 17% a year for the last 10 years for me and pays a nice 8-9% dividend! It has a strong CET, good cost to income and leverage ratios and is well capitalised and run. Still only trades on a PE of 4 too so I consider there more to come.
Georgia as a country is hardly frontier either and has good GDP growth.
Most of Georgia Capital (LON:CGEO) price is accounted for by its holding in Bank of Georgia (LON:BGEO) (listed) and cash. One thing levelled at it previously was whether it could realise the value of its private assets through a cycle. It demonstrated that via the disposal of its Water utility business for a good premium to book and in cash (USD).
Current NAV is a few pence short of £20 so this now trades around 37p in the £ (so at a 63% discount).
Note sure why Mojo thinks there is a load of hype around it. I've seen very little other than mentioned on here a few times when results are out.
You are hyping Georgia Capital (LON:CGEO) David to use it as a comparison against Mercia Asset Management (LON:MERC) - just a very different risk.
planetx and David - you may not feel Georgia is a frontier market but I assure you it is - with all the variable capital depth and risk appetite that comes with. Companies that would be safe as houses in UK go under in those markets due to surprising events...think the financial crisis of 2008 in western markets and how that felt here (...like out of control armageddon and even good things could go under!)...that's how many crises commonly feel in frontier markets. They can be good investments but one must adopt a different risk-return mindset to developed markets.
What if the bank that underpins value has a negative credit cycle and decides to cut or hold dividends? Georgia Capital will be looking for capital at exactly the wrong time, just when its acutely so across the whole country (you may grumble at dilutive raises on AIM recently...but there is still funding for some risky things and in Georgia sometime in next few years there will be no funding for good things!)...that's procyclical risk magnification...are you sure you've quantified these risks or you just looking at headline numbers and discovering that frontier markets are priced more cheaply? (and note the asset managers with a holding in the company or the bank -> be aware that this is them using a more liquid and easily accessible instrument for their Georgia exposure...and they will be hard sellers of it for liquidity when the inevitable downturn comes) ...
...which gets back round to the silly idea of saying that Georgia Capital is better than Mercia as its on lower price to NAV -> one you got Mercia discount wrong and the successful profit making operating company must be consider as part of any value calc and I'd suggest bring Mercia to a price to 'fair value' that is less than 60p in £ when translated into NAV speak. And two, the argument above!
I could accept an argument growth is better for Georgia Capital and its cheap for that growth etc....but if you are saying that its 40p in £ (looked 45p to me on quick look) then that's a bad value trade off against Mercia at (IMO) 55p (you can quibble and say 60p) in £ on crude equivalent (and Mercia probably has decent growth operationally and in NAV terms).
So I think you guys really don't understand the risk you are taking. I say this having invested directly in emerging and frontier markets spending significant time in them.
Whatever...I like Mercia...I might be wrong. You can find big discounts elsewhere. I like the ones at Petershill Partners (LON:PHLL) and, sideways but related to this discussion, Secure Trust Bank (LON:STB) for example and think they are severely discounted good assets....I don't like the one at Molten Ventures (LON:GROW) as I see NAV and funding stress.
Georgia Capital may continue to do very well. I'm no expert on Georgia. But your arguments hint to me you don't really comprehend the risks you are taking.
PPS if you want to find a frontier market that seems like it isn't then I have you Argentina to sell. I love it as a place and got some truly great cos (as they have to be to survive the cycles). BUT it is very definitely a frontier market...and when people locally and internationally lose confidence in it its messy.
Its truly reckless to compare frontier risks to developed markets!
PS high GDP growth economies tend to provide poor equity returns compared to more moderate growth econs. There is no pro-risk argument there. The reason is that the downside tends to be brutal and reveal a lot of bad risks were taken plus foreign capital flows out fast compounding it.
On the theme of mystery shopping, I wonder how many holders of Georgia Capital (LON:CGEO) or Bank of Georgia (LON:BGEO) have visited the country. I have. While it is a beautiful country full of wild, wonderful places and friendly, hospitable people, it is also riddled with corruption despite huge efforts to tackle it. They sacked all policemen over the age of 30 at one point to tackle this.
I do hold Georgia Capital (LON:CGEO) on the basis of its recent price performance against Bank of Georgia (LON:BGEO) but I hold in pretty small size for the reason that, having visited the place, it would not surprise me one morning to wake up and find that Bank of Georgia (LON:BGEO) had discovered significant accounting irregularities.
I agree mammyoko
Georgia Capital (LON:CGEO) and Bank of Georgia (LON:BGEO) may be great cos and stocks - I don't know and haven't done work. My naturally contrary mentality makes me wary of 'frontier market' stocks in country experiencing a boom with positive capital account flows (probably more speculative than structural...usually the way unless there are explicit capital controls) that neighbours such a big, dysfunctional and (to them) economically important country. My inclination (based on past sore slammed in door greedy fingers) is to be thinking about the exit rather than the entry. Frontier markets should be bought at bottoms when no-one likes them. That said, a growth period can prove elongated and powerful...maybe this is Georgia's time to shine...but its important to know that about Georgia to believe in the value of two discussed stocks.
My bemusement and annoyance is around the idea of making a discount to NAV/book value comparison between a frontier market stock and developed market ones. That basis of comparison would very rarely have one out of frontier markets...
...it makes no sense as a comparison.
As an example I exited NAK Kazatomprom AO (LON:KAP) earlier this year as internal Kazakh things got hot and we had Ukraine rumblings. Great assets and super cheap...but other circumstances looked dicey. I'm a uranium market structural bull and believe Kazatomprom is the best asset globally by a mile. If it were Canadian or Australian I'd have bags full of it. But had to let it go...knowing it could triple in value if things okay and uranium bull market actually gets going
Croma Security
Good story developing for patient shareholders and strategy announced today looks spot on.
Divest itself for cash of low margin security part of business and focus on the high margin side . Pretty standard stuff but we’ll done for getting on with it.
Looks like MBO all lined up so let’s hope they go through a full process to get a correct price.
There’s a good story developing here, executive pay is a touch high but this is a solid company albeit a micro cap in a bit of a sweet spot with decent technology in their hands .
Was getting very cheap if you can stomach illiquidity and microcaps this looks a company that is finding its niche .
Still trying to work out how I feel about the Croma Security Solutions (LON:CSSG) news today.
Positives - With shareholder approval required and the largest shareholding being with the remaining management, we should hopefully extract a decent price for Vigilant that should clearly demonstrate the massive undervaluation of the remaining business, which will be roughly in for nothing after adjusting for surplus cash.
Negatives - It's a tiny business already and divesting Vigilant will make it much smaller still. Delisting risk will be higher. Also, I'm not clear on the leadership strength if Morley leaves.
Hi Paul, just wanted to say thanks for flagging the adjustments point for Equals (LON:EQLS) yesterday. I took a look last night and wasn't comfortable with the adjustments so sold out
Equals
For me it’s a strong hold , the direction is clearly upwards and it is profitable and growing .
Sector is good .
More importantly it works well, I signed up my business to check if it was actually commercially useful and have to say it is a step above moneycorp, argentex, banks etc .
Suggest it is worth shareholders and potential shareholders to sign up and use the product . That’s the best acid test .
Try it before you buy it . (New shareholders)
Try it before you sell it (Existing shareholders)
Maybe a few other readers with international payments requirements can sign up and feedback but I’ve been doing international payments 30 years and it is good .
Thanks planetx,
I agree - there's nothing like mystery shopping a company's products for yourself, to see if they are any good.
I remember Ed did that with Globo (a fraud from a few years ago, that I wrote 29 negative articles about here!), he downloaded some app they were trumpeting as brilliant, and found it completely unworkable. Shareholders in Globo tried to get me sacked from Stockopedia, threatening to cancel their subscriptions unless I stopped writing negative stuff about it. I ignored them, and was proven correct. Only 1 shareholder ever apologised to me.
I did something similar with Altitude (LON:ALT) quite a few years ago now, so it might have improved, but its supposedly 3D product viewing software was nothing of the sort, and very clunky to use.
So often the claims made by companies don't stand up to scrutiny, and we have to try to find independent sources which can vouch for products or services.
If a product/service really is class-leading, then to me that would probably trump any concerns over adjustments in the accounts.
Regards, Paul.
Paul
Thanks , the accounting stuff TBH is above my pay grade .
So I have to fall back on old school pudding eating .
Be good if other readers with international payments needs signed up too .
Might be worth you looking at Chroma security if they divest of security division as outlined today it leaves them a real nice business , and with hundreds of “mom and pop” competitors looking for a simple exit they will acquire good businesses very cheaply .
They do seem to have found a bit of a sweet spot and now looking very good
Although the amortisation of staff costs for software development initially appears significant for Equals (LON:EQLS) (I hold) the categorisation is into intangibles and the annual charge for amortising this category is running above the level at which the costs are being added. I therefore see this as responsible accounting and certainly not a red flag.
I would be interested in a contrary view if I have misunderstood this
I think for me the valuation became an issue. Assuming 6m profit the rating is x30. A bit too heady for me. Also with the growth drive, profit may suffer for a few years.
Are there any funds that invest in major oil companies? Looking to get exposure to oil as it'll likely creep upwards in the next few months now that EU and others have set a cap on Russian exports. tia
£SPOG is a good choice if you'd like to buy an ETF
I would just buy BP and Shell and save on the fund fees! Alternatively, ishares do a range of energy based ETFs. If you prefer a fund then Guinness Global Energy is pretty good.
Ashtead Technology Holdings (LON:AT.)
Further progress for Ashtead Technology with the addition of Hiretech.
I'm Bullish about the future of this company tapping into the expanding offshore renewables, and declining decommissioning / life extending for the oil and gas industry. Seem in a sweet spot, and worth a look at the companies website. A pull back below 300p would be a great buy in IMHO.
Ashtead Technology (AIM: AT.), the international subsea equipment rental and
solutions specialist, is delighted to announce it has further expanded its
mechanical solutions service offering with the acquisition of the entire share
capital of Hiretech Limited ("Hiretech") for a total consideration of £20m on
a cash and debt free basis.
Hiretech generated revenues of £6.5m, EBITDA of £4.1m and EBITA of £3.4m
for the twelve-month period to October 2022. The Group expects the transaction
to result in double-digit earnings accretion in FY2023 and generate returns
significantly in excess of the Group's cost of capital in the first full year
of ownership.
I hold this one
Telecom Plus (LON:TEP) Not a small cap but chairman just sold nearly half his holding, 3.5m, 4.4% of total share count for 2400p, £84m. My worry is the recent rise in users is due to TEP being the only company being suggested by comparison sites for switching suppliers. So they may switch away once energy prices drop.
Victorian Plumbing (LON:VIC) Results ahead of expectations, with H2 revenue growth as the Group demonstrates continued trading momentum and further market share gains, supported by a robust balance sheet
Board proposes maiden ordinary full year dividend of 1.1p and an additional special dividend of 1.7p
Key performance indicators
22
21
Total orders(7)
'000
880
906
(3%)
Active customers(12)
'000
608
638
(5%)
Average order value(8)
£
306
297
3%
Average Trustpilot rating(9)
Score / 5
4.5
4.3
5%
Marketing spend as a % of revenue
%
28%
26%
(2ppts)
Trade revenue as a % of total
%
20%
16%
4ppts
Current Trading and Outlook
●
The Group has had a strong start to FY23 with 10% revenue growth to date, whilst maintaining H2 gross profit margin and with lower marketing spend versus the comparative period last year
●
We are conscious of the current macroeconomic conditions and will continue to monitor consumer behaviour and tailor our pricing and marketing approach accordingly
●
We continue to focus on our long-term goals and are making good progress on all of our strategic growth areas. Underpinned by our market share gains we are confident in the future growth prospects of the Group.
Meaningful Director buy, at RBG Holdings (LON:RBGP) from the under-pressure CEO:
RBG Holdings plc (AIM: RBGP), the professional services group, announces that on 5 December 2022, Nicola Foulston, Chief Executive Officer, purchased a total of 250,000 ordinary shares of 0.2 pence each ("Ordinary Shares") in the Company at an average price of 64.65 pence per Ordinary Share for her SIPP.
Following this purchase, Mrs Foulston is beneficially interested in 11,765,264 Ordinary Shares, representing 12.34 per cent. of the issued share capital of the Company including 355,264 Ordinary Shares held in her SIPP and 11,410,000 Ordinary Shares held by Cascades Limited.
Ummmmm I looked at her purchase this morning and thought it was just about meaningful considering how wealthy she is.
Enjoyed the podcast on the drive in this morning, so many thanks.
I consider these to be a "Brucie Bonus" so never feel guilty for having the odd week off.
Thanks Bob, much appreciated! I was pleased to get close to my 30-minute target time as well. That will also make it quicker to type up the written version later today.
Best wishes, Paul.
Why do you type these up out of interest when folk can listen? It’s a lot of extra work.
The typed up version is much appreciated
Why do you type these up out of interest when folk can listen? It’s a lot of extra work.
Because some of us really appreciate the written digest?
Why do you type these up out of interest when folk can listen? It’s a lot of extra work.
I think over time people will see the value in the transcripts, because you can search for companies, and quickly review a lot of content. Imagine having to listen to hours of audio, to try to find something previously of interest!
It's ultimately driven by demand/feedback. The transcripts get 60-80 thumbs ups here, which tells me that enough people find them useful for me to put in the work typing them up. Also, it's a nice additional service for Stockopedia subscribers I think, as opposed to free podcast listeners.
EDIT: plus of course, our hard of hearing subscribers appreciate transcripts very much.
thanks for the light comedy of your nose in the hot chocolate
Hi Paul
Have you thought about using:
Either an automated (AI) translation service $10/hour such as Sonix https://sonix.ai. Never used but just Googled.
Or an online transcription service of a real person who do them pretty cheaply. My 16 year old was going to offer the service for very little (to you or me but meaningful to him) but I think his A-level studies got in the way.)
Regards
Michael