Small Cap Value Report (Tue 8 Jan 2019) - JOUL, FOOT, ACRL, STAF, Missguided

Good morning, it's Paul here.
Please see the header above for the stocks I intend covering today.
There's a nice recovery underway in decent quality retailer shares at the moment. The emerging trend seems to be that the better retailers (e.g. Next (LON:NXT) ) recouped the sales dip in Nov 2018, in Dec 2018. Although it's once again eCommerce sales which proved key - growth online offsetting the drop in physical store sales, for Next.
Even shares in poor quality retailers seem to be seeing some buying interest, given that share prices have already factored in Armageddon. So anything not too bad, could be seen as positive. Maybe. Who knows, sentiment can turn on a dime at the moment. These are certainly difficult, but rather exciting markets.
To summarise my current thinking, the only retail shares that interest me, should ideally have some combination of the following characteristics;
- Niche or differentiated & desirable products (not re-selling generic, or third party products)
- High proportion (over 30%, preferably 50%+) of sales online
- Sound finances
- Short leases on physical stores
- Low valuation
A lot of smaller, weaker, retailers are likely to go bust in 2019. Therefore there will be more market share available for the survivors. Plus rents are likely to continue falling considerably, on lease renewals. Hence why this sector, whilst a minefield, is very interesting to me. I focus on this sector because I understand it far better than any other sector, and it usually pays to stick to what you know - as the chance of success is greater.
I seem to have writer's block this morning, but will see if I can get into my stride now.
Joules (LON:JOUL)
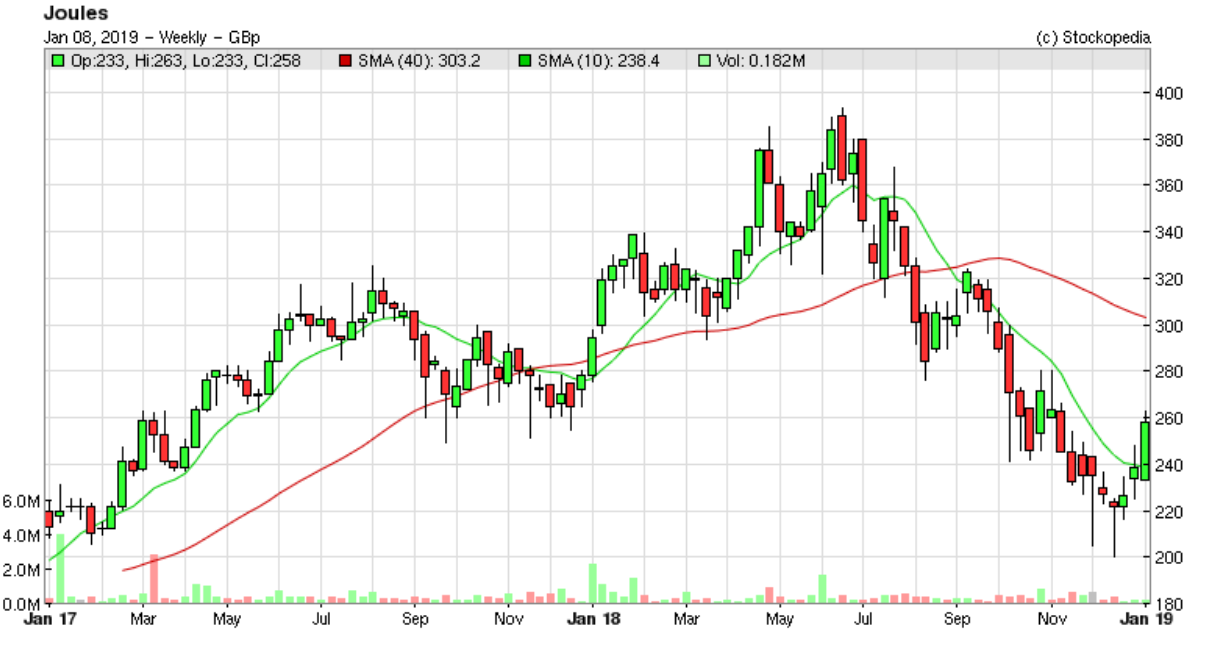
Share price: 255p (up 4.3% today, at 11:18)
No. shares: 87.8m
Market cap: £223.9m
Joules, the premium British lifestyle brand, today updates on the Christmas trading performance of its retail business for the seven-week period to 6 January 2019 (the "Period").
Checking back, I wrote positively about JOUL here on 5 Dec 2018, thinking it looked good value at 207p. It's up 23% in the month since then - pity I didn't back my judgement with a purchase, but such is life.
Whoever writes the trading updates for Joules should probably be reassigned to other duties, as they almost always strike me as ambiguous & unclear, and sometimes contradictory.
eCommerce is a stand-out positive aspect of this share - it's almost half of Joules' total retail sales. That ties in nicely with my bullet points in the introduction to this article. So a positive tick in that box.
Retail sales - the company lumps together its store sales, and eCommerce sales into one total, not giving us the split between the two. This is unsatisfactory, because we really need to know how the physical stores are performing, since they have large fixed overheads.
Best practice is to clearly state store sales (LF) and eCommerce separately, then also show the combined total. Joules has not done that today.
Anyway, the total is up 11.7% against last year, "on a comparable basis". Is that a LFL figure, or does it include new store openings? Comparable basis suggests it might be LFL, but I'm not sure.
To confuse matters even more, there has been a change in treatment of concessions revenues, from wholesale, to retail. This reporting is absolute rubbish. They should just include a simple table, giving the relevant breakdown of the figures.
Outlook - this at least is clearer;
Retail performance during the Period supports the Board's previously stated confidence in the Group achieving full year 2019 PBT in line with its expectations.
That's impressive, given tough market conditions.
Valuation - the forward PER has moved up from 14.1 a month ago, to 16.3 today. So it's not quite the bargain it was in Dec 2018.
In difficult market conditions, I wouldn't want to be paying more than a PER of low to middle teens, even for a fashion retailer that is performing well online. A higher multiple could be justified if it was online only, and growing faster.
For now, I'd say it's probably priced about right.
My opinion - a good company, which is performing well, in tough market conditions.
Note that the StockRank system recognises the high quality of the business, but is unimpressed with value and momentum;
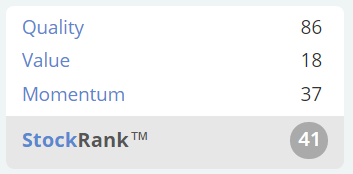
Note that the StockRank has edged up from a lowly 37 a month ago, to a still rather mean 41 today. Perhaps that might continue rising, as time goes on? It's interesting to follow how the StockRanks move about, in response to data changing over time. You can monitor this, by clicking on the grey "Print" button on each StockReport. A drop-down menu appears, allowing you to see StockReports going backwards, at monthly intervals. A handy feature.
Footasylum (LON:FOOT)
Share price: 27p (down 17% today, at 12:06)
No. shares: 104.5m
Market cap: £28.2m
Footasylum, a UK-based fashion retailer focusing on the branded footwear and apparel markets, announces an update on trading performance for the 18 weeks ended 29 December 2018 (the "period")...
Online - is now 33% of total sales (up from 30% a year earlier), which is starting to look interesting.
Revenue growth of 14%, which is meaningless, since new stores have been opened, it includes online growth, so they've obscured what the LFL sales performance from their shops is. That's because it's almost certainly negative.
Store sales are up 5%, but again that's not a LFL figure.
Margin pressure - competitive pressures have required discounting to clear stock. Not good.
Therefore, while Footasylum continues to expect to report FY19 revenue in line with consensus expectations, FY19 gross margin is now expected to be lower than current consensus expectations.
Bank covenants - a company that's barely profitable should not have any bank debt in my view. This is a considerable risk for this company, but today it says;
Footasylum remains (and expects to remain) in compliance with the covenants of its £30 million multi-currency revolving credit facility.
Cost reduction plan is being implemented, which will result in exceptional costs.
Profit warning - this doesn't sound too bad, in the circumstances. I was expecting worse;
Footasylum now expects to report an adjusted EBITDA for FY19 towards the lower end of the current range of analyst forecasts.
It's a pity there isn't an asterisk, stating what these forecasts are.
Outlook - challenging.
My opinion - this update is not as bad as I expected. The share price is so bombed out, that the outcome looks pretty much binary - either it's going bust, or there could be a decent bounce at some point. One for (brave or foolish?!) traders perhaps?
I like that 33% of sales are online. The key missing information, is what leases the company is committed to? How onerous are they? How long are the lease expiries? If it can manage down its retail estate, and migrate more online, with just a handful of flagship stores, then there might ne something here. Very high risk though, so DYOR is more vital than ever.
Accrol Group (LON:ACRL)
Share price: 12.25p (down 42% today, at 12:25)
No. shares: 195.2m
Market cap: £23.9m
This is a tissue processing company.
It's another profit warning;
... the continued weakening of Sterling against USD since September 2018 and increasing tissue prices have impacted profitability considerably
The figures look pretty grim;
... the Board now expects that Adjusted EBITDA in FY19 will be c.£1m*. In terms of the overall turnaround plan itself, this is expected to result in up to £8.0m of exceptional costs in the business during FY19.
Revenue is rising, expected to be up c.8% to £126m in FY19.
Net debt - this is the deal-breaker;
Net debt as at 31 October 2018 was reduced to £22.6m and management expect FY19 year-end net debt to be no more than £30.0m (FY18: £33.8m), which is a result of improved working capital management.
My opinion - performance of this company has been diabolical since it listed. Is it a viable business at all? With a ton of debt, it's difficult at the moment to see how the equity has any value. Maybe performance might improve in the future, who knows? Do I want to punt on that happening? No.
Staffline (LON:STAF)
Share price: 1120p (down 10.4% today, at market close)
No. shares: 27.9m
Market cap: £312.5m
Staffline, the Recruitment and Training group is pleased to report that trading for the financial year ended 31 December 2018...
Trading has been in line;
... is expected to be in line with market expectations.
Why is the share price down 10% today then?
- Significant costs incurred in winding down the Government's Work Programme - resulting in £20m of exceptional costs
- Net debt increased to £63m - as a result of these exceptional costs, plus payments related to acquisitions in H2
Results for 2018 will be published on 30 Jan 2019 - a pleasingly tight reporting schedule, which suggests to me that the finance dept at Staffline must be on top of their game. Rapid reporting nearly always means good financial controls are in place, together with a capable finance team.
My opinion - this is a long-standing favourite of mine - I remember flagging it as a good share when it was under 300p, after meeting management, years ago. Despite today's setback, there is a generally positive tone to today's update, with more detail given which I've skipped over here.
The valuation looks about right to me at the moment.

MissGuided
(private company)
The Guardian apparently reported that this fast fashion eCommerce company (similar to Boohoo (LON:BOO) ) has just released terrible figures. Given that it's a private company, I figured that the journalist must have had an email alert from the Companies House website (a very useful feature). Therefore I've had a look at its figures at Companies House (which is now free, it used to cost £2), and the numbers & narrative are both very interesting.
Missguided website is here - warning, a fast-moving graphic on the home page might trigger an epileptic fit.
As a key competitor to BooHoo, I had previously assumed that Missguided must also be rapidly growing & highly profitable. Actually yes, it has grown rapidly, but profit has only ever been small, and in decline since 2015.
Results for the 53 weeks to 1 April 2018 are dire. Here's a snapshot;
- Revenue up 5% to £216m
- Pre-exceptional EBITDA down from +£3.7m to -£26.5m
- Loss before tax (after exceptionals) of -£46m
- Gross profit margin crashed from 51.9% to 43.7%
- Balance sheet NAV dropped from +£4.9m a year ago, to -£41.6m
- A new shareholder loan of £27.9m has propped up the company - without this, I think it would have gone bust by now
What's gone wrong? The narrative points to 2 main problems;
- A large increase in overheads, including bringing in a new layer of management (who have obviously screwed things up spectacularly) - this resulted in a 60% increase in central support costs, which is crazy
- "Poorly selected product" - requiring deep discounting to clear it
- Physical stores opened, which are "too large", and loss-making. Required a £5m onerous lease provision, and write-off of £4.5m of previous capex
The comment below, from the narrative, is particularly important;
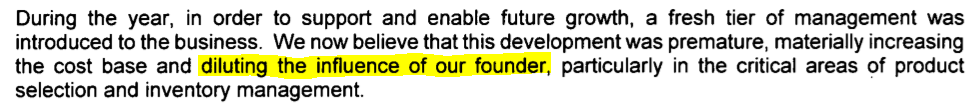
This has read-across to Superdry (LON:SDRY) which has also lost its way recently, after a dominant founder retired. It seems to me that fashion businesses in particular, are often highly dependent on a key individual or maybe a couple of key people. The founders are the driving force of any business, so there's a lot of risk when they decide to move on.
Once entrepreneurial businesses grow too much, and become too corporate, then the life blood of the company can quickly ebb away. Missguided seems to be a dramatic example of that. Clearly incompetent new management has almost wrecked the business. Luckily the shareholder(s) have deep pockets, and have been able to rescue the business with that £28m loan. How much more funding they have available, I do not know.
This situation also reinforces just what an iron grip the Boohoo (LON:BOO) group has on the young, fast fashion space. Its 3 brands dominate this area, and seem to be killing the competition. Missguided needs to get its act together fast, or could face insolvency - which would be a big boost for BooHoo of course.
One of the great skills of BooHoo's founders, is that they built a great team of talented people around them. I noticed this positive culture when I visited BOO's HQ a couple of years ago. The founder showed me round, and he acknowledged every member of staff. The body language from his staff was positive - they obviously respected him a lot, and were not fearful.
Missguided has clearly failed, spectacularly, to make the transition from owner-managed, to a larger, more corporate arrangement. This is something worth pondering, and looking out for at other growth companies. As we've seen here, the consequences for out-growing the ability of management to manage, can be disastrous.
OK, all done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Really interested to read your commments on Missguided. My 20 year old student daughter cited Boohoo, Nasty Gal and PLT (she was shocked and impressed they were all the same company) as well as Missguided as the go to brands for young women. So I was quite surprised to hear Missguided doing so badly. I’ve said here before I would sell up if Boohoo (LON:BOO) founders stepped down. That blend of creativity, a deep understanding of your market and business savvy seems especially important in fashion. Angela Aherne was another great example at £BRBY
Paul,
I note you have MissGuided in your header, and I'm sure we readers can near-guess what your opinion/analysis will be along the lines of ! lol ... Perhaps they should have read the SCVR to see that B&M retailing is (generally) on the decline !
On a similar vein, I've just read:
US retail giant Sears seeks liquidation
https://www.bbc.co.uk/news/business-46797097
One comment made was :
"Its recent journey to this point has been characterised by incredibly poor strategic decisions, chronic underinvestment and continuous financial machinations designed to keep the company afloat.
All of this impacted trading, which has remained dire, making Sears more like a patient in a coma than a fully functioning retailer."
"Maybe performance might improve in the future, who knows? Do I want to punt on that happening? No."
Perfectly put - this and similar comments in the past from Paul have been extremely educational and the best advice possible, saving me from many such value traps, thanks very much, and keep going!
Foot....bought more today. Basket case stock down 90 per cent in a year but this seems to me a fair entry price for newer holders like me. I thought like PS that the statement could be really dire; but there are some highlights such as
"Online continues to perform strongly, up 28% to £36.0m".
So after a heavy fall I think all the gloom could be firmly in the price.
Staffline (LON:STAF)
rmillaree,
I agree that was a £20m bombshell from Staffline. Hopefully, that is kitchen-sinking but I don't believe we have been given enough information to judge the company's performance. There is no profit guidance and since we were never told the cost of last year's acquisitions (except for Learndirect which was a nominal sum) we can't even judge the cash generation.
'Excluding amortisation charges on intangible assets arising on business combinations and non-cash charges for share-based payment costs, total exceptional costs will be GBP20 million in 2018, principally due to the aforementioned PeoplePlus transformation'
I think this actually means total exceptional costs (including amortisation, share-payments etc) will be more than £20m.
So, on the one hand, the 'underlying' business is performing well but, on the other hand, there was very little profit to be had in 2018!
Something for the bears and the bulls, but just as well the market seems quite perky today.
jombaston
Staffline (LON:STAF)
Yes - i think you are right that the very unexceptional exceptionals will likely be more than 20 mill
There is no profit guidance
I think they confirmed that profits ignoring the "elephant that is the exceptionals" are in line as they quoted the following.
Per todays update
Staffline,is pleased to report that trading for the financial year ended 31 December 2018 is expected to be in line with market expectations.
I guess its pretty to easy to hit targets when so much can end up in exceptionals though - lets hope when they do 200p eps that is not pre 150p exceptionals.
Hi
Sopheon (LON:SPE) adding to its partnering links. Excerpt from RNS today (I hold a small holding).
Sopheon, the international provider of software, expertise, and best practices for enterprise innovation management solutions, announces that it is partnering with global confectioner The Hershey Company (NYSE:HSY) to support digital transformation of Hershey's product innovation portfolios.
Regards
Howard
Staffline (LON:STAF)
A bit of a bombshell trading update from Staffline this morning, trading inline with expectations however exceptional costs for the year will be £20 mill and debt up to £63 mill - so shareprice down nearly 10% (albeit clawing back). On a more positive note they expect no exceptionals 2019.
Is this a bombshell news or not ? i don't really know - they had 4.5 mill exceptionals H1 and it was well flagged up there were issues with the Work program - perhaps there is an element of Kitchen sinking here that will help the 2019 expectations being met on a clean basis - but i have to view it as at least £10 mill down the swanny with £10 mill extra debt to match - a fairly decent chunk of this years profits.
Debt was 37 mill at 30/6/18 and 32 mill at 31/12/17 - thats a big jump but there was acquisitions in H2 and it could be that the Work program cashflow positive next year who knows - they haven't specifically mentioned that debt will drop down quickly in the new year so they obviously have work to do in this regard. They are expecting 32 mill net profit this year(2019) so debt is very manageable but one of the attractions of this share was the reasonably modest debt level - i guess they will say profit has gone from 18 mill in 2017 to expected 32 mill in 2019 - so that has to be funded somehow.
My main hope if that the expectations for 2019 remain reasonably intact as without the future earnings growth this share would be much less attractive - its all to easy to look at nice rosy forecasts at the start of the year and think the company is going great guns.
Within the welfare to work sector Staffline (LON:STAF) has a reputation as a spreadsheet driven organisation. It is an industry which wants to do good and they are losing good staff as a result.
Richard Goodwin
ref Staffline (LON:STAF)
Do you know anything about the new prison work - is this likely to be less risky than the welfare to work?
I can't imagine anything worse than welfare for work where a high % of individuals probably have no interest in doing their bit and presumably they were paid on results which was always going to be a challenging situation.
i am hoping with the prison work its more of a go in do your mechanical teaching bit and get paid on a simple basis for this basic service provided - they should at least have a captive audience :) here.
It seems to me this work should be simpler but i am just making this assumption without any facts to back it up.
The Staffline (LON:STAF) website says that 91% of its teaching staff were 'graded 'Good' or better'. 'Good' is the lowest ranking that does not necessitate remedial action. The situation in my local gaol is that the educational provision was provided by the local Tech, but was then put out to tender. An agency got the contract and offered to re-employ the old staff, but under reduced conditions. They left and were replaced by a never-ending stream of under qualified and desperate individuals. The place is a mess; but the agency is still picking up its cheques and will continue to do so. Make of that what you will. Prisons are managed to a budget, and targets regarding re-offending etc are managed to fit the budget.
As a holder of Wandisco (WAND) I am excited by today's announcement of Product launch with IBM. Their relationship with IBM seems to be strengthening. Will IBM take them over? I have doubled my holding first thing this morning. As always this is not advice DYOR
Hi Paul
Re Joules, you have commented in the past about their clothing range being nothing special, and a bit pricey. Having bought many of their clothes, for me and partner, I can vouch for the quality of their goods. Regular customers of Joules, will buy, because their clothes will still be wearable in years to come. When you have family members who hate shopping, and only ever wear the same shirts, Joules is a god send.
I hate buying clothes that end up in the bin after a few wears. It stopped me buying in M&S when their quality declined. The Joules menswear that I have seen is more robust.
I would require the rag trade to put on the label the number of washes that their clothes will last for so we can calculate a cost per wear. It might help resist the environmental impact of disposable fashion.
I have seen corporate clothing, uniforms and so on, specified that way so it's perfectly possible to do.
Re: "to put on the label the number of washes that their clothes will last" - Love it!
Brilliantly simple idea that instantly shifts the discussion from price (BooHoo) towards quality and value for money. Should be a part of the quality players marketing communication material at least.
Would no doubt be resisted as impossible to measure and/or open to gaming by cheats and would no doubt lead to some strange effects (polester vs cotton anyone?) - but this is the sort of thing that govt or well designed regulatory schemes can help with in the way. Fridges are now required to give energy ratings.
The environmental benefits would be enormous plus there would likely be positive balance of payment/substitution effects for the UK.
I agree John, its also worthy of note about Joules. I have a relative who has a farm on the Falkland Is, and buys his clothes from their shop in Leics. He says they stand up well in their long hard winters. Its what alerted me to them, then I searched, found out they were listed, and bingo
I cottoned onto Joules (pardon the pun )from my wife (who knows nothing and cares even less about investing). She said the clothes, while expensive, were very good quality. Seemed interesting as a smaller cap (majority of my stocks) so I bought. Just goes to show that some of your best tips are likely to come from people and things you know about. You just have to listen :-)
The opposite is true as well -
"You know it's time to get out of the market when the shoe shine boy gives you tips"
Joe Kennedy, Winter 1928
My morning smallcap tweet: Accrol bogs down.
Accrol Group (LON:ACRL), Sigma Capital (LON:SGM), Footasylum (LON:FOOT)
Accrol Group (ACRL) guides FY adj EBITDA only £1m if weak £ and high tissue prices continue. Guides FY rev up 8% to £126m, broadly in line with market forecasts - I have £128.6m. "FY20 results will include the full annualised benefit of the structural cost savings achieved in FY19."
Sigma Capital Group (SGM) guides FY pre-tax profit up 205%, slightly ahead of market forecasts.
Footasylum (FOOT) guides FY adj EBITDA towards the lower end of analyst forecasts due to 'higher than expected levels of promotional and clearance activity'. Plans to cuts costs.
Hi
A couple of product/dservice developments which might interest some.
Codemasters Group (LON:CDM) portion from RSN.
Codemasters (AIM: CDM), the award winning British video game developer and publisher specialising in high quality racing games, today announces that it has entered into a joint development agreement (the "Agreement") with NetEase, Inc. (NASDAQ: NTES) ("NetEase"), one of China's leading internet and online game services providers, to develop a new mobile game (the "Game") for the global market.
WANdisco (LON:WAND) portion from RSN.
WANdisco (LSE: WAND), the LiveData company, has launched a new joint engineered solution with IBM to support relational database technology for the first time, significantly expanding the Group's addressable market.
With reference to gaming sector. I note Frontier Developments (LON:FDEV) up today and yesterday.
Also US NVIDIA chip maker going into gaming chips.
https://www.thestreet.com/investing/nvidia-unveils-new-products-targeting-notebook-buyers-and-cost-sensitive-gamers-14825415
(I hold v.small amounts Codemasters Group (LON:CDM), WANdisco (LON:WAND), £FDEV)
Regards
Howard
Gateley Holdings (LON:GTLY)
A strong set of interim results today. Attractive PER and yield due to recent SP fall.
Initiation note from finnCap on Research tree makes positive reading
Phil