Small Cap Value Report (Tue 8 Nov 2022) - AGFX, PSN, ARB, MRK, HFG, ZOO, WHR

Good morning! It's Paul & Graham here with you today.
Agenda
Paul's Section:
Housebuilders - I want to know what's going on in the housing market, so have strayed out of small cap territory, to look at a trading update from Persimmon (LON:PSN) today. It's guiding down expectations for 2023, which shouldn't be a surprise to anyone who watches the TV news. There's a large increase in its cladding provision, which is unsettling, so that's an important issue not to overlook. The whole sector looks dirt cheap to me, with many well below their own NTAV. Again, fairly obviously, a cooling property market is bound to have read-across for other consumer sectors - e.g. furniture, estate agents, DIY maybe?
Marks Electrical (LON:MRK) - interim figures are as expected, and the outlook comments seem encouraging. Balance sheet looks fine. Cashflow has almost all come from increasing creditors, so that might reverse in future perhaps? It seems a good, well managed company, but in a horrible low margin sector. It's difficult to see much immediate upside on the share price, after a recent 25% bounce.
Hilton Food (LON:HFG) - it's another profit warning. I can't see any appeal to this share, now that earnings have stopped rising. That's caused the shares to de-rate this year from a PER in the twenties, to now about 12. Why was it ever valued so highly in the first place? It seems to me that the valuation has reset to something more sensible. There's a fair bit of debt on the balance sheet too. It's not for me.
Warehouse Reit (LON:WHR) - I refresh my memory on this property REIT which specialises in owning & renting out warehouses. Asset values have fallen, although the shares trade at a 20% discount to net asset value. The dividend yield of 5.2% isn't exciting, in a higher interest rate environment, so it doesn't float my boat unfortunately, despite the recent plunge in share price.
Graham's Section:
Argentex (LON:AGFX) (£136m) - excellent H1 results from this FX broker, as expected after a terrific trading update in October. Cash conversion has cooled down but in exchange for this the company is enjoying the excellent margins that are achievable when dealing in forwards and options contracts. Looking ahead, I expect that forex conditions will normalise and perhaps result in calmer market demand for brokerage services (think of all the dramatic headlines around the pound in recent months). Despite that prospect, I think there is good underlying momentum at this business which should continue even in normal circumstances. A dividend will be declared with the next set of results, for the period ending December 2022. Plenty of reasons for continued optimism here.
Argo Blockchain (LON:ARB) (£34m) (-6%) [no section below] - we reported recently that Argo was in danger of an equity wipeout, due to its overly aggressive growth strategy. It is currently suffering from a) bitcoins that are increasingly difficult to mine - this is a design feature of the bitcoin system, b) higher electricity prices and other input cost inflation, c) the bitcoin price being stuck around where it was in late 2020 (Argo seems to have assumed that that Bitcoin price would rise forever), d) over £100m of borrowings. Today the company reports that it has finished selling the mining computers that it recently bought, and that its mining capacity is unchanged at a “hash rate” of 2.5 (it previously planned to reach 5.5 by the end of 2022). It also reports an improved “mining margin” of 32%, but this leaves out the depreciation of mining equipment, i.e. one of its biggest costs. Mining profit minus depreciation remains firmly negative. These shares are a punt on the bitcoin price rising and on electricity prices falling, and on financing discussions having a favourable outcome for shareholders. I don’t have confidence in any of these things happening.
Zoo Digital (LON:ZOO) (£152m) - this company has turned the corner and produced a maiden H1 profit, along with great cash flow generation. For years, I worried about ZOO’s valuation but it finally makes sense: they appear to have reached a scale where they can at last generate real profits and cash for shareholders. Long may it continue! The current trend for Netflix to produce non-English language content is a great tailwind but I don’t think it’s a flash in the pan. After Squid Game, there appears to be a real appetite from viewers for content that is produced locally in languages other than English and is properly subtitled or dubbed. So I’m not going to complain about Zoo’s above-average PE ratio: it is an expensive stock but I suspect that it deserves its premium rating.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Housebuilders
I was thinking about dipping my toe into this sector, which now looks amazingly cheap. Unlike previous recessions, this time housebuilders are well funded, with strong balance sheets, so there are not any solvency issues. Persimmon updates us today.
Persimmon (LON:PSN)
1226p (down 7% at 09:20)
Market cap £3.9bn (not a small cap)
For FY 12/2022 so far. Key points -
Recent deterioration in market conditions.
Selling prices down 2% recently.
Increased cancellations rates (risen from 21% to 28%).
Forward sales (for 2023) has dropped to £0.77bn (last year: £1.15bn)
On target for 2022 sales (14.5-15.0k houses)
Inflationary pressures of 8-10% “being managed well”, so margins still industry-leading.
Forecast cash of £700m at year end.
£750m capital returned to shareholders this year.
Help to Buy scheme has ended, was used for 20% of transactions.
Has plenty of land, expecting to buy less in 2023.
Cladding remediation provision is being increased to £350m. This seems a very large increase. Looking at interim results to 6/2022, the provision (note 9) was £69.3m, so a whopping £281m increase, if I've got those numbers right.
Capital allocation - is being revised, sounds like they’ll probably be paying out less generous divis.
Guidance for 2023 - too early to judge, but expecting fewer completions, and lower prices - impacting margins.
My opinion - this is not a share I follow closely, however, I want to see what’s happening in the property market, for wider read-across. Sorry if that triggers some readers, who are unnerved finding a mid-cap in a small-cap report!
The large increase in cladding provision is worrying. I’m not sure how it could jump from £75m originally, to £350m now? What’s the betting it increases further? High, I would have thought. So this issue needs careful scrutiny for other builders.
Given all the news recently, it surely shouldn’t be a surprise to anyone that the housing market is cooling. That’s already been anticipated by plunging share prices across the sector. Taylor Wimpey (LON:TW.) Is only down 2.5% in sympathy today, versus Persimmon’s fall of about 7.0% at the time of writing.
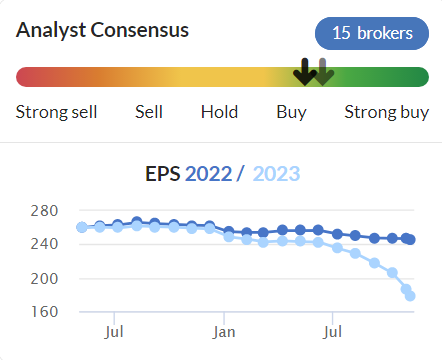
As I’ve mentioned before, brokers have been slashing 2023 earnings forecasts from July this year. Current estimates are that Persimmon’s earnings of c.246p this year (FY 12/2022) are set to fall 28% to 178p in 2023. At 1237p/share, that’s a 2023 PER of only 6.9 times. Hence arguably the share price looks cheap, as it already prices in a nasty downturn in earnings. The risk is obviously that a housing downturn could be worse, and longer, than currently imagined. So who knows?
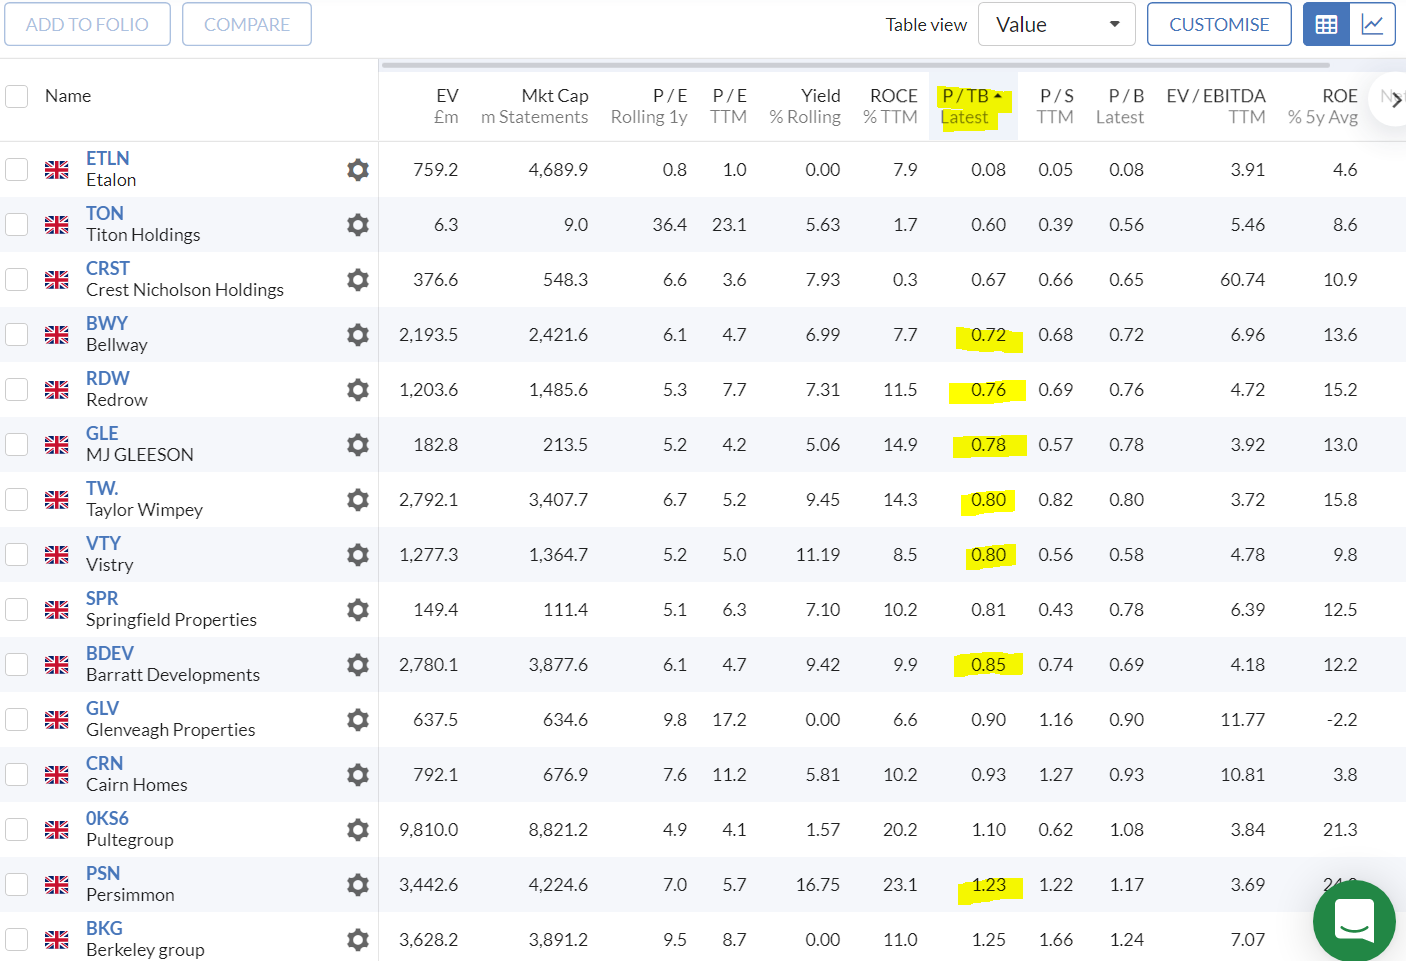
I prefer to look at Price to Tang.Book, rather than earnings, in times of a housing market downturn. Stockopedia’s sector tables (below) are really handy for this - see below - we’re spoiled for choice in terms of housebuilders trading at below their net tangible assets, and with safe, cash-rich balance sheets too. That’s very attractive, in my view. They could get cheaper still of course, but I think this sector could provide rich pickings for value investors prepared to hold long-term (clickable link on table below) -
.
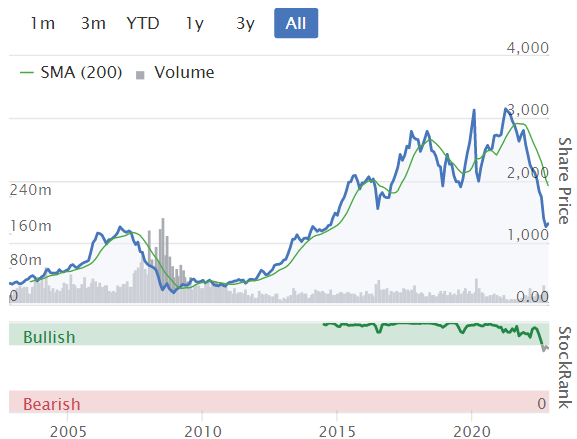
Note from the long-term chart that recovery from the 2008 crash was very slow for housebuilders, but then really took off, providing a fabulous return for patient investors, two thirds of which has gone up in smoke in the last year (there have been big divis from PSN too).
.
Marks Electrical (LON:MRK)
72.5p (up 2% at 10:45)
Market cap £76m
Marks Electrical Group plc ("Marks Electrical" or "The Group"), a fast growing online electrical retailer, today announces its unaudited results for the six months ended 30 September 2022 ("the Period" or "H1-23" or "first half").
The story here is that MRK is small, but gaining market share quickly, through having a simple & efficient operating model, selling electrical items online.
I recently reviewed its H1 trading update, coming away with a positive impression of the business, but cautious on valuation. Also, forecast earnings of 4.3p this year FY 3/2023, is lower than the 5.0p achieved in the previous 2 years. I suppose we have to be realistic about the macro picture, and inflation, so a dip in earnings this year isn’t a calamity, it’s to be expected really. I think investors need to focus more on the longer term, which should be good for MRK in my opinion.
H1 numbers look like this -
H1 revenue £43.1m (as expected), up 15% vs H1 LY
Profit before tax of £2.1m, slightly up on H1 LY
Adj EPS of 1.66p. That leaves 2.6p to do in H2.
Outlook - sounds perky, despite macro conditions - and the same terminology as used in the last update -
The resilient performance delivered in the first half provides us with solid foundations to deliver our strategic objectives in H2-23.
The business has continued to prosper during the start of the second half, with an acceleration in sales momentum in October and a strong continuation into November. As we benefit from improved gross margin and operating leverage during the peak trading period, we expect to improve our Adjusted EBITDA margin in H2-22 and remain on track to achieve our full year targets.
Balance sheet - is clean, and simple (e.g. it has none of the stuff relating to warranties, that complicates the balance sheet of larger competitor AO World (LON:AO.) )
Working capital looks healthy, and includes a £7.7m cash pile. Although note that the increase in cash has mainly come from increasing trade creditors. This is shown more starkly on the cashflow statement.
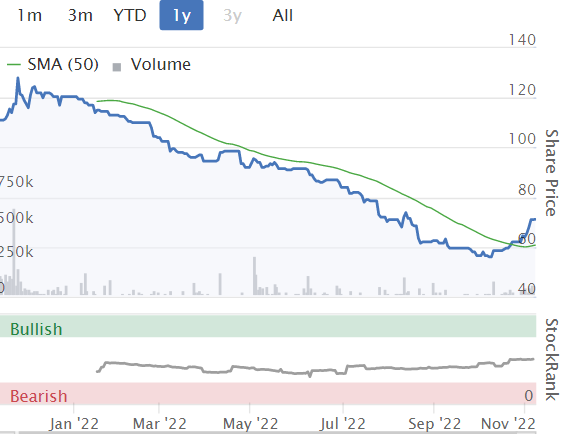
My opinion - I think this is a good business. The share price has risen about 25% from recent lows, and doesn’t strike me as a bargain. So it’s difficult to see much upside in the short term. Longer term, I imagine that the business could grow, although electricals retailing is one of the last sectors I would want to invest in, due to the low margins, and plentiful competition.
.
Hilton Food (LON:HFG)
546p (down 14% at 10:56)
Market cap £488m
I last reviewed this company here on 15 Sept 2022, when it fell sharply on a profit warning.
It’s fallen another 22% in price since then, so is it entering value territory? I wasn’t impressed last time.
Hilton Food Group plc ("Hilton Foods" or the "Group"), the leading international multi-protein food business, today announces its Autumn trading update.
This year is FY 12/2022.
Revenue (and volumes) in line with expectations.
“Challenges” in UK seafood division.
Oh dear, it’s another profit warning -
…the Board anticipates that operating profit will now be below its expectations for the full year.
Outlook - “well placed for 2023”
... financial position continuing to be strong, with leverage remaining at comfortable levels.
I’ve just been reviewing previous RNSs, and wondered why Hilton Foods had bought a tyre business? But then realised I’d accidentally put in the wrong ticker, for Halfords. Looking at the correct interim results, Management may be comfortable with the debt, but personally I’m not - net bank debt of £221m looks too high, going into a recession, for a business that only ekes out a tiny profit margin (£2,039m revenues in H1, and only £34m adj PBT, that’s only 1.7% profit).
My opinion - I can’t see anything of interest here. It would need a strategy to meaningfully increase profit margins, to interest me.
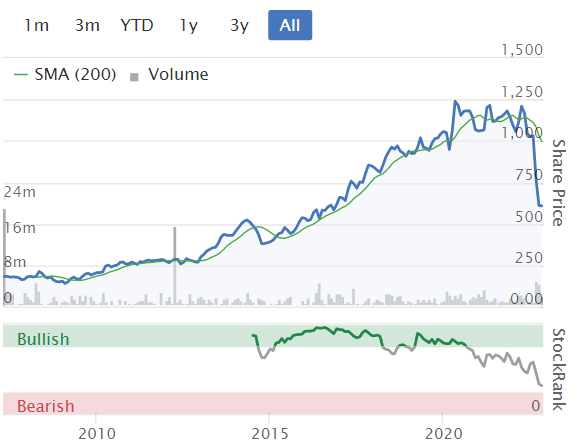
Shareholders have had a rude awakening in the last year, after years of decent progress -
.
Warehouse Reit (LON:WHR)
122p (down 1% at 11:15)
Market cap £519m
I rarely look at property REITs, but a friend introduced me to this share a few years ago, with a very simple investment theme - that warehouses were undervalued (selling at below replacement cost at the time), there aren’t enough of them (in demand due to the growth in online shopping), and WHR shares provided a nice low risk way of getting a decent income (of about 5-6%). The investment case was also that the tenants would generally be stable, and not likely to go bust (unlike retail lettings businesses).
That was then, when interest rates & inflation were low. In a higher interest rate world, going into recession, do these shares still make sense?
Like many property shares, there was a recent plunge in share prices - some have blamed this on the LDI pension debacle, where pension schemes facing big margin calls dumped anything they could, to raise liquidity.
Could there now be a buying opportunity, especially if you believe (as I do) that interest rates could be coming down again if, as seems likely, we go into a recession in 2023, and inflation falls?
Interim Results (to 30 Sept 2022)
Some figures for H1 -
Gross property income £24.1m (up 3%)
Operating profit £17.0m (up 1.8%)
Adj EPS 2.8p (down 10%)
Dividends per share 3.2p (up 3%)
Total divis for the year are expected to be 6.4p, yielding 5.2% - not madly exciting these days, better yields are available elsewhere.
EPRA NTAV per share 153.3p (down 12%)
The drop in NTAV has been caused by a fall in property valuations. Could values fall further?
Hence the share price of 122p is at a 20% discount to NTAV.
Balance sheet - NAV is £679m, or 160p per share. I don’t know what the EPRA adjustments are, to reduce that to 153.3p. Investment properties are £1,020m, and interest-bearing debt is only £334m, so a nice comfortable LTV (loan to value) of about 33%.
The property companies which got into serious trouble, and even went bust (eg INTU in 2020) saw calamitous drops in asset values, e.g. for shopping centres. It strikes me as very unlikely that WHR would see such a collapse in its property values, given that they’re not directly dependent on shopping footfall.
Debt - the other key thing to consider for all property investments, is the term, and terms of the bank borrowings. Note 15 explains that a consortium of 4 banks have extended facilities of £345m, which expire in Jan 2025 - just over 2 years time, but can be extended by a further 2 years.
Covenants are interest cover, and market value.
Interest rate risk looks well covered, with 75% of borrowings capped.
My opinion - the 5.2% dividend yield isn’t enough to get me excited.
With the benefit of hindsight, zero interest rates for a long time, led to many assets becoming over-valued, including property.
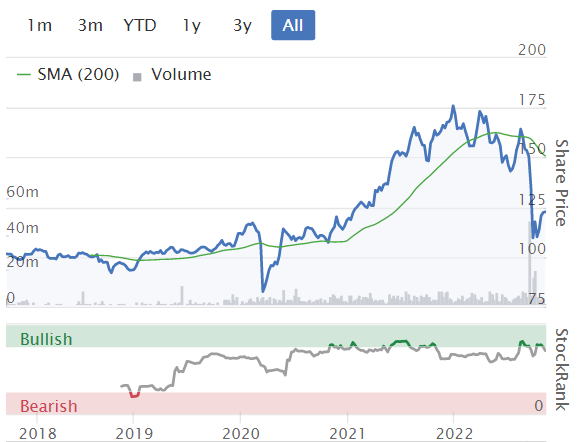
Another thing to worry about, is that there have been reports of some property investment companies suspending redemptions, to stop forced selling of assets. Although as we've seen in previous property market downturns, valuations tend to decline, due to sellers wanting to sell things in order to reduce gearing. Simply supply & demand then means prices go down. So maybe it's better to watch from the sidelines for now?
.
Graham’s Section:
Argentex (LON:AGFX)
Share price: 120p (pre-open)
Market cap: £136m
This share came to my attention over the summer as offering high growth at a cheap valuation.
In October, it issued an H1 trading update that was ahead of expectations. The valuation still looked very modest at the time.
I’m not the only one who noticed: the share price has had a nice bounce and is up over 50% from its summer lows.
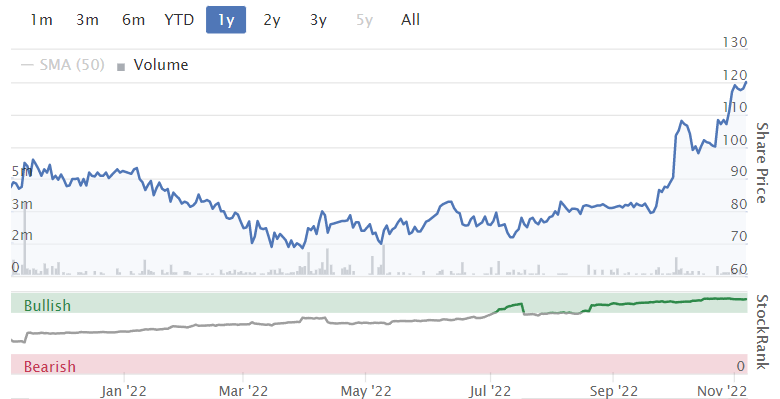
Not that it’s too relevant at this stage, but the IPO price for these shares was 106p, back in 2019.
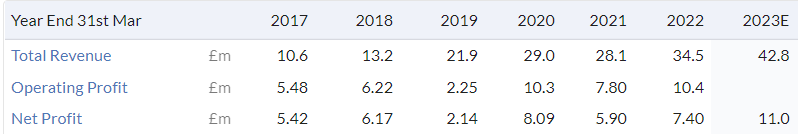
The company was much smaller back then:
Let’s dig into today’s interim results:
- Revenue +75% to £27.4m
- Adjusted operating profit +55% to £7.3m
- Actual operating profit +45% to £6.4m
Operationally, the number of corporate clients is only up by 12%. So clearly that is not the growth driver, but rather there are other factors involved in driving growth (e.g. increased share of wallet as clients abandon banks in favour of specialist brokers, and increased overall trading activity compared to other years).
On that latter point: with all the headlines around Sterling and the political changes that have occurred over the past few months, this was an unusual year for forex, with widespread concerns around rapidly changing exchange rates. So I think we need to understand the reported 75% revenue growth at Argentex in that context.
Other operational news:
Structured solutions grew from 1.9% of revenues last year to 9.5% of revenues this year. It’s reasonable to assume that the margins here are much fatter than the margins in spot and forward transactions.
There are some interesting comments on cash conversion: the revenue mix has resulted in lower cash conversion, because of a lower percentage contribution from spot trades (where the trade happens instantly and revenue is therefore generated straight away). But it’s almost certainly worth sacrificing some cash conversion in exchange for the higher margins from the other trade types
More clients are trading on the Argentex online platform. This is good news for shareholders because it reduces the overall labour intensity of the business. But online platform revenues were still less than £1m during the six-month period, so still a low percentage of overall revenues.
The new Netherlands business has “exceeded expectations and is generating meaningful revenue” after getting an e-money licence.
Headcount has crossed over the 100 mark to reach 107.
Outlook
Momentum has continued across all facets of the strategy into the last quarter of our new reporting period. Although market dynamics continue to be supportive, we maintain a balanced approach to risk, particularly in light of the uncertainty through this period of high inflation.
I don’t see anything to cause concern here.
They also say “as highlighted in the 3 October trading update, the Board expects that the financial performance for the full year will exceed current market expectations”.
I would not interpret this as a fresh upgrade, because of the phrase “as highlighted in the 3 October trading update”.
Updated consensus forecasts are difficult to source, but Paul Hill (equity analyst for Vox Markets) reckons that revenue will come in this year at £47 million, versus prior forecasts of only £42.8m.
Note that with the company’s financial year-end changing from March to December, the next financial statements we get will be audited statements for the 9 months ending December 2022.
Net cash rises to £25.8m and a final dividend is expected at the end of the financial year.
My view
The market seems to have caught up with the upgraded expectations, as there is no further share price increase this morning.
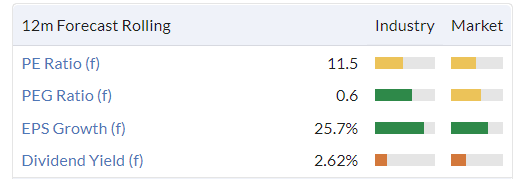
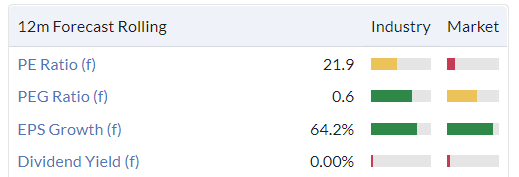
With a c. 50% increase in the share price versus where it was priced during the summer, I also think it’s fair to say that the easiest gains have been made here. But note that the valuation is still not at particularly demanding levels, using Stockopedia estimates (and bear in mind that the estimates have been moving quickly):
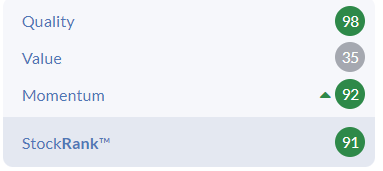
StockRanks don’t see too much value, but do see plenty of quality and momentum, calling it a High Flyer:
I will maintain my view that this is my favourite listed FX broker, and has a valuation that still gives it room to provide new shareholders with a decent return.
Zoo Digital (LON:ZOO)
Share price: 171p (+1.5%)
Market cap: £152m (about $175m)
This is another share that provided a nice buying opportunity in mid-summer, and is now up by around 60% since then.
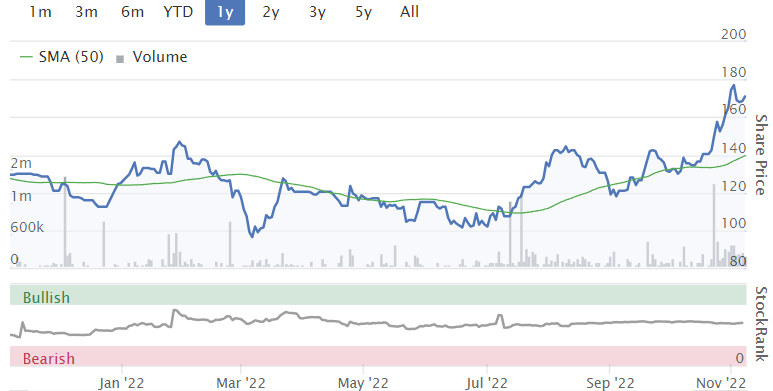
My views on ZOO have evolved over time: I thought it was overvalued for many years, but more recently I thought it had grown and developed to a point where shareholders could be more optimistic (e.g. see here for my thoughts in July).
Note that the current share price is not much higher than the levels it reached way back in 2018, when it was much, much smaller:
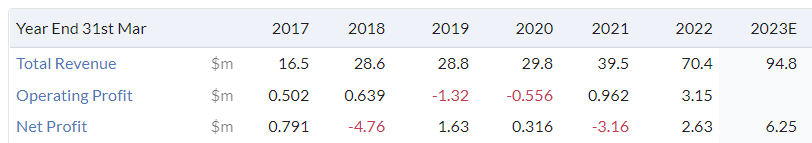
Here are today’s interim results:
- Revenues +91% to $51.4m
- Adjusted EBITDA more than doubles to $7.3m (important: adj. EBITDA has not historically translated into profits and cash)
- Maiden H1 PBT of $3.5m
- Cash inflow from operations $7.6m, cash outflow from investments $2.0m
At last! We get some real profits and cash flow here finally (I’ve taken the cash numbers directly from the cash flow statement, instead of using the company’s numbers).
Operational highlights:
Localisation revenues up 150% to $32.3 million. This includes subtitling and dubbing.
Zoo’s fortunes are closely tied to Netflix, and is a key beneficiary of Netflix’s drive to fund high-quality foreign (non-US, non-English language) productions that can be enjoyed by a global audience. I think it’s fair to say that the revenue opportunity from translating these productions into English and other languages is bigger than the revenue opportunity that ZOO would normally have translating productions from English into other languages.
For example, I recently watched the gruesome All Quiet on the Western Front on Netflix. This is a new German-language World War 1 epic, and I watched it with English subtitles.
Media services revenue up 39% to $18.2 million.
Zoo’s freelancer network increased 27% to 12,343.
And now for the outlook. The full-year is expected to be in line with expectations:
Strong order book across all service lines with good visibility for H2 and a pipeline of work from established, satisfied customers
Further expansion of international operations to deliver revenue growth and improved visibility across multiple service lines
Clear opportunity as streaming service providers continue to focus on content as a key differentiator, with increased sourcing from international markets
Industry notes
Some comments from management are worth repeating. They note that “production of film and TV content has exceeded pre-pandemic levels”, referencing both the United States and UK spending.
Within the industry, the highest growth is seen from “Over-the-Top” (OTT) providers, i.e. from services you can access on the internet without a dedicated media subscription. Netflix is considered an OTT provider since you can access it from any internet-linked device, including a smart television.
ZOO says that it has a 4% market share of its current addressable market. Could the industry ever be sewn up by players such as ZOO taking a huge market share? I’m not sure. But the trends are positive. This paragraph seems worth emphasising:
…OTT streaming companies are ZOO's primary commercial focus, and all indications suggest a shift in their purchasing strategies towards engaging with a smaller number of more capable vendors of media and localisation services. In this regard, ZOO is well positioned within the market as a one-stop shop, providing all services needed to prepare entertainment media for distribution on streaming platforms across all required languages.
The Group is one of perhaps five organisations in the industry with this capability, in ZOO's case differentiated by its proprietary cloud software platforms that enable high efficiency and scalability in its operations, leading to the high rates of organic growth that have been delivered in its recent reporting periods.
My view
I still maintain that it’s the streaming companies - the likes of Netflix, Disney+, and so on - who have most of the negotiating power when it comes to getting their content translated. They have the intellectual property and they own the relationship with their vast audiences.
But I have come round to the idea that Zoo has built a reliable and comprehensive set of services that is not easy to replicate and can therefore command a decent level of profitability. They seem to have finally turned the corner and become a company that doesn’t need to hide behind “adjusted EBITDA” to demonstrate profitability. In addition, it’s hard to deny that they have exposure to an excellent growth trend (the globalisation of media) that looks set to continue for years to come.
Therefore, I’m no longer going to grumble about ZOO being overvalued. It’s expensive again, yes, but for good reasons:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Marks Electrical (LON:MRK) - we hosted an investor presentation from Marks Electrical Group plc, the fast-growing online electrical retailer, following publication of their Interim Results: https://www.equitydevelopment....
Mark Smithson (founder & Chief Executive Officer), and Josh Egan (Chief Financial Officer) ran investors through their strong top-line performance, ongoing market share gains, a detailed overview of financials and a strategic update including the growing installation offering. The team also discussed the outlook and answered investor questions.
The full video has been divided into chapters (see below):
0:00:16 Key highlights
0:03:48 Financial overview
0:10:00 Strategic update: customer proposition
0:24:48 Strategic update: brand awareness
0:29:52 Strategic update: operational capacity
0:36:57 Strategic update: financial performance
0:38:24 Summary & Outlook
0:41:24 Questions & Answers
Paul - I do hope BUMP has not hurt you too much today if you still hold some - ATB
Hi matylda,
Given the incredibly low market cap (too small for the SCVRs now), I thought the trading update from Seraphine (LON:BUMP) was actually quite reasonable, I was fearing worse.
There was a distressed seller, suppressing the share price, but Christopher Mills took it out at 10p recently. There could be other institutions selling, this is a worry with recent IPOs, as they tend to have inadequate liquidity, because the IPOs were done by placing big lumps of shares with institutions. And now those institutions could need cash, to meet redemptions.
Anyway, I think it's crazily undervalued now, so doubled my position size this morning. As always, time will tell if this was a good, or bad move.
Regards, Paul.
Fair comments - I didn't notice the Harwood investment, that's usually a decent medium term indicator - Good Luck with it Paul
I have a general question not connected to UK small caps. Does anyone know of any managed (basket) currency funds? This could be active or passive but should concentrate on non GBP currency investments, possibly through short-dated bonds.
Don't want to recommend anything in particular, bere will be loads of OEICS that invest in global bonds - try those in the Global Bond sector. They often come in currency hedged and unhedged versions - obviously check you get an unhedged version if you want non GBP exposure. Also worth checking the duration of the fund - if you want something fairly steady, more like cash then probably no more than 3-4 years duration. Longer duration funds tend to be very volatile. This information can usually be found on fund factsheets - I would check out a few and go with one that you like the look of, with a decent track record and experienced fund manager.
Thanks for the comment valueman. In the 2022 annual report from Zoo, they strongly emphasise the investment by Netflix in international content. Netflix is mentioned 14 times in the report, and they analyse many different aspects of Netflix's reach and its spending patterns.
Paul,
Following your comments on Persimmon, a very large company, it would be most interesting to read your comments on M.J. Gleeson ( I hold) , which is a much smaller company, and, perhaps more important, has a particular niche in the market - building very cheap houses. I think i'm right in saying that, so far, it has been cheaper to have a mortgage on a Gleeson house, than to pay rent.
I know nothing about the housing market, but one friend in the trade tells me that Gleeson is an ethical company. Which is quite refreshing, if accurate!
Following your comments on Persimmon, a very large company, it would be most interesting to read your comments on M.J. Gleeson ( I hold)
Paul is a most helpful and responsive fellow but please don’t waste his valuable time asking for information that you could simply look up yourself by searching for his analysis of Gleason on Stocko. It’s easy enough to do.
Thanks for your comment nettle. Yes it would be interesting if Paul wants to make any comment on Gleeson as the company is distinctive because of the niche you mention and I believe it also has a relatively low exposure to the cladding related liabilities which Paul highlights in his article.
Hi Nettle. Paul in fact briefly covered M.J.Glesson on his webimar with Paul Hill of Vox Markets a week ago. Try this link. https://videos.voxmarkets.co.u...
I think you’re factually incorrect here . ‘“Zoo’s fortunes are closely tied to Netflix, and is a key beneficiary of Netflix’s drive to fund high-quality foreign (non-US, non-English language) productions that can be enjoyed by a global audience.”
Zoo’s main customer is Disney and the other major studios .Netflix is a tiny customer who mainly operate through Zoo India . They do their own localisation . They used to be a big customer years ago but since set up their own . Zoo’s future is tied to Disney ,Paramount, Peacock ,HBO .
Ashtead Technology Holdings (LON:AT.) looks to be rerating today, and would normally look at selling into the rise...however...
I am really bullish about this company and the areas it operates in, which is subsea inspection, maintenance, and repair. So we are talking decommissioning of oil and gas but also maintenance of existing fleet and importantly equipment for off shore wind farm and clean sea based solutions.
Decent broker upgrades, trading ahead of expectations, yes some debt (3xprofit), but backed up with assets. The growth figures if achieved look game changing. Divi's a bit crap, but am after share price growth with this one.
I just feel its in a sweet spot ATM, trading between a shrinking oil and gas sector, trying to wring every penny out of its assets, and a growing off shore green energy revolution. It isn't cheap, but is operating in a proper niche IMHO.
Thought I would flag it and welcome any comments, Paul, Graham what do you think of this one?
Paul
(I Hold)
Ashtead Technology Holdings (LON:AT.) popped up on my risers and fallers and I'm scratching my head trying to work out why I've never looked at it before today. Great trading update dated 10 October. Revenue and profits growing, debt reducing, and they are positioned in both the hydrocarbon and wind sectors - hard to see a decline in demand for subsea tech.
£AT
I think AT got a favourable mention in Judith MacKenzie's slot on last night's Mello. Sorry but I don't have any detail until I watch the recording.
We have thousands of illegal immigrants who came to the UK for housing first, jobs second and families at home to be brought in thirdly and this is why I hold Barratt Developments (LON:BDEV) Persimmon (LON:PSN) Redrow (LON:RDW) and Vistry (LON:VTY) in the Large Caps. What could possibly go wrong?
The land market being overheated due to delays on planning applications, inflation on material and banks nervous about lending due to uncertainty over job security. Apart from that....
On a more positive note...I have plumped for Soc of Lloyds 4.75% Oct 2024...and Western Power (National grid) 3.625% Nov 2023. I want to be relatively short dated and not have too much accrued interest in the price. If you have half a years interest accrued you just swap income for a loss which I don't like doing. By being short dated I know I get my money back. In my pension Ive gone for the Gen Accident prefs which yield 7%... the lower 7.875% is closer to par than the 8.875% ....but it doesn't really matter as they are unlikely to be redeemed IMO.
I had been running a long in £TECS which is 3x short tech ETF....through the poor inflation print and all the negative tech numbers. Despite all this news seemingly going the right way ....the stuff rallied anyway .... and I gave up a week or so ago. My general observation is volatility is falling....so investors are dumping all their hedges at the moment....and part of this may contribute to Dollar selling...in a way I don't really understand. However its clear for now Dollar weakness and market strength go hand in hand. China relaxing zero covid may mean further relaxing of hedges ( not all inv hedges...supply chain protection and credit default too) which means more Dollar weakness.
Ive been buying commodity exposure...like Rio Tinto (LON:RIO), Fresnillo (LON:FRES) and some financial like £BARC .... my most likely purchases lower down the mkt cap will be industrial which all seem to be reporting well. The other vehicle I used in my pension for commodities exposure was Amati Strategic Metals which has a decent Lithium weighting amongst others.
All comments welcome.... good luck out there
Hi
Which dealer are you using to pick up your bonds?
I am with IWeb which has worked for a while, cheap and does what I needed, but obviously when looking wider not the right solution, so hence the question on whether to move some or all to a different place.
Thank you
Tommy
This account is with Saxo... pretty good - I was trying to buy a different bond and getting nowhere. I bought the Gen Accident prefs through AJ Bell and all seemed to work fine .
As a general rule Saxo works well when their algo trades and for small caps harder to trade I like Swissquote as they let you see the order book. I haven't tried them for bonds. Obviously the prefs get a stamp hit.
Thank you
You can still buy the Aviva / GA prefs with iWeb, though corporate bonds are a different matter.
Hi,
I have a fair amount of commodity exposure in my PF with Sylvania Platinum (LON:SLP) Jubilee Metals (LON:JLP) a copper ETF and Ecora Resources (LON:ECOR)
I recently added to the Sylvania Platinum (LON:SLP) on some of the down days, but in the end decided I didn't want to become too overexposed in any single stock so also bought into Blackrock World Mining Trust (LON:BRWM) with the view that I'd let them do some of the work, to work out which resources to get into at what time - it also provides a near 5% dividend as well and is a great allrounder.
My one regret is having got back into some gold stocks again about 6 months ago - I keep falling into the trap of listening to people saying "everyone should have some gold in their PF as an inflation hedge" - I normally ignore it, but decided this time it might have some weight. It's not looking good currently, but I suspect we are starting to see a turn in the gold stocks - you just need to be careful to know what to get into; miners, prospectors or a sector fund.
Paul Please can you explain why, for housebuilders, you prefer to look at Price to Tang. Book, rather than earnings, in times of a housing market downturn?
House builders is an interesting topic imo. With regards to your question to Paul, I believe price to Tang, book value is better as a house builder will fare better in a down turn in the housing market. Builders are very cyclical. While they have fallen a lot in the last few years and the PE is very low as well as their NTAV, future esp have not really been set for these companies yet. Builders have little say in the selling price, as it is set by area and demand. Demand will likely fall with rising interest rates, as well as cost of living and this in turn will likely bring the house prices down and then affect the profit of builders. With profits set to fall, the PE will rise and then make house builders look not so cheap. So for those builders that do have cash they will be able to buy additional land cheaper as it falls in price. As i mentioned, builders are a very cyclical sector and while they have fallen a great deal so far, I believe they still have further to drop when the actual profits are shown to drop. That, imo, will be the time to buy into that sector.
The increase in cladding provisions for Persimmon (LON:PSN) is explained by the pressure put on them by Michael Gove in April Persimmon signs up to Gove cladding deal | News | Housing Today .
A list of developers who have signed up is available here List of developers who have signed building safety repairs pledge - GOV.UK (www.gov.uk) . Not all builders have signed up.
Hi Paul
Really enjoyed your weekly podcast and you often refer to shares that now have a good valuation.
Could you please do a "Special Feature" where you discuss your top 5/10 small caps that you think are now good value for the inevitable(hopefully) return of the bull market?
Thanks
Good idea but perhaps a larger sample of shares being closely followed by you (PS) with background colour/commentary designed to encourage debate among subscribers on their respective bull and bear points?
Crestchic
As I predicted few days ago would briefly drop into the 240s .
What I didn’t expect was the huge trades, looks like a major player sold down a big chunk which briefly put the downward pressure and these were snapped up yesterday and day before , I’m thinking by harwood .
Looks like circa 10% of the company changed hands .
Now market has nothing to sell and needs to buy so will be heading back north .
Anyway some exceptional trading levels for a small cap
Hi planetx, lest you think you are talking to yourself, I was also following these moves quite closely and managed a decent top up first thing yesterday. I was waiting to make sure it wasn’t directors selling but as you say, it looks like a large seller being mopped up swiftly, possibly by Harwood.
Re - Crestchic (LOAD)
Me too Re' Crestchic (LOAD)
Well done you if you caught the 245p level I didn’t quite catch that as I was buying around the late 248s
These are very long term holds so not worried about totally catching the dip .
I’m trying to arrange a quick walk round their new facility I want to see if it is now fully operational .
246p - sometimes it pays to average down and sometimes it backfires but the fall was anomalous to the general market last week, as you were highlighting.
Hi Planetx and Brilliant Leader
Added at 251.75 on Friday and 245.5 yesterday.
I have a lot of confidence in LOAD. which has been strengthened by my communications with Peter Harris, both at the factory visit and in subsequent emails. This makes adding on pullbacks a simple decision. Peter owns a lot of shares and is building a company for the long term.
Planetx - I would be pleased to join for a walk-around. Maybe it helps if a group of us is interested?
Michael
Michael
I’ll let you know when I have some news
Didn't get in anywhere near the lows but thank you, anyway, planetx for drawing my attention to Crestchic (LON:LOAD) . Your conviction inspired me to take a close look and I made it my first conviction trade of the year so very happy with the outcome so far
Seraphine (LON:BUMP) really down with a BUMP! Very little to shout about with this tiddler. Consumer spend really will take a hit as the Seraphine (LON:BUMP) type consumers look for the many other ways of meeting their needs, particularly hand me downs and second hand /nearly new markets. Its a tough world.
Hi Paul Scott - I wasn't sure if you were intending to cover ABF today? I know they are a little larger, but I know you're a Primark fan so thought this might be on your list? Many thanks!
We hold drkelly1975 and I enjoyed reading the statements today, if only all results were presented as clearly. My timing was wrong with ABF but we have averaged down and we're happy to hold.
I liked the result and the ethos. Great diversification as well. To me - good opportunity for US expansion as well. That also brings in more dollars, but will take a bit of time to ramp up to something really meaningful. Great to see the share buyback of approximately 5% as well. So margin on Primark reduced for 2023 - great opportunity to increase market share.
Persimmon (LON:PSN) have lengthy statement out, with little good news im afraid.
The balance sheet is (strong) with £700m net cash. My quick check against land creditors ....you have £190m non current, £217m current... they have added £590m of which £175m has been paid and £115m will be before the year end. This potentially leaves the land creditor looking a little high at £707m.
Sounds like the dividend will be cut substantially and 2023 is a right off now. Its notoriously difficult to generate cash in a downturn... which is why they will be buying no more land.
In terms of the outlook there is a ray of sunshine in that despite hawkish rhetoric from the Fed it feels as though rates are peaking. Bond markets haven't moved much at all and the UK market has improved significantly since 30 September. 10 year yields have fallen from 4.8% to 3.6%. Although it is very expensive to fix at 5%+... relatively attractive 2 year discounts are available c3%.... which limits the current affordability hit ...and therefore maybe supports price a little.
Its hard to say what the dividend will be... half?...possibly passed in 23 and the whole thing takes shape from 2024 onwards. For the others the fag pack calculation above re land creditor reveals if you need to be really worried or not. You need enough cash and no debt (with balance sheet covenants) to cover land commitments.
Im not too sure about the provision to sort cladding issue - it was announced a few weeks back so maybe the £350m is not new. Quite an increase from £70m.
Overall it looks like a year of difficulties ahead as the pain of rate rises works its way through the system.
What are the community views on builders? They haven't crashed as I would have expected. Even now, off their lows when we know they probably won't generate enough cash to pay those divis in 2023. There was an interesting article on stocko saying builders are not a good long term hold and that PEs need to be high before you should be investing. Still doesn't look like we are there , or have forecasts just not adjusted?
Difficult times for all housebuilders. The main issue is lack of mortgage availability. I see a solution coming! it is called a lifetime mortgages which means the length of mortgage is going to be 50-75 years. Essentially people will be renter but they do not know it and do not feel like renting.
The love of owning your place in this country and around the world is immense and they cut everywhere else to get their own castle!
In my mind the housebuilders are good values at this levels if you look beyond the next year or two. they do not go bankrupt but may not pay dividend either. instead they can buy land for the next cycle.
thanks for this. My only comment, if I understand what you said correctly, is where you said it is notoriously difficult to generate cash in a downturn. That may be true of Persimmon specifically (I don't know it in detail) given its commitments, but is not true in general of housebuilders if they slow/suspend projects and land purchases. It can actually be a time when net cash increases. A good builder managing the cycle well can then (credit lines depending) fill the land hopper at better prices.
If they build less than they sell then yes its possible.
The devil is in the detail of course on land. A builder can in theory generate cash quite easily but to balance this against the P&L is more difficult. The normal way round this issue is to take balance sheet write down of inventory and land ...which then allows them to clear stock profitably and move fwd.
This is actually a pretty gloomy outlook that im not sure I agree with. I think for the volume guys .... volumes will obviously be lower next year...and pricing might hold up for them ok ...betweeen 0-10%... this would be a hit to eps. BUT if Stocko is right 178 is already forecast ....which is down 27%... maybe this slips a little more.
Depending on many factors which I have no idea of my guess on the divi would be between half and none. Half would not be the worst outcome and still leave the stock yielding close to 10%. The one snag if we muddle through is that rates won't fall that much either. So the outlook for house prices wont be particularly positive or negative. In the late 90s these stocks all traded on 4.5x since everyone thought housing was about to turn down again.
I hold a range of the house builders. I f you are thinking of buying at these levels you are buying the value of the balance sheet rather tan the future earnings.
Bellway (LON:BWY) land value ps seems to be lower than the share price. IC said recently that it is too late to sell but too soon to buy. As a holder I am stuck for now but I feel sure at some point there will be corporate activity that will move share values. Various corporate raiders must surely be looking at the land held in balance sheets not to mention the cash. One bid would move the whole sector.
Argentex (LON:AGFX) interims look good, even if they are benefiting a lot from current market conditions.
I'd be keen to know what any updated 'market expectations' are now because a previous Singer note in July had massively downgraded full year profit expectations which led me to sell (and which btw doesn't seem to be reflected in the Stockopedia numbers). This is partly reflected today in the lower margin but I am wondering whether the margin got worse as the period went on and whether H2 is therefore going to be softer than H1. I also note they still talk about a strong growth on their current investment in technologies having a benefit in the 'medium term' which suggests there might be softer margins for a couple of years perhaps?
Here you go guys - brief commentary here
https://www.linkedin.com/posts...
Are your FY numbers for a 9 month period?
Given they made 5.1p adjusted EPS for H1 (albeit based on old financial year I think?), your FY22 predictions suggest a pretty bad H2 - how come?
It's only a 9 month "year" - (they've changed their year end), - maybe that's it. Bit confusing when everything is referenced in FYs and half years.
Not sure because Singers this morning have FY22 6.5p adj eps, FY23 7.2p adj eps - so don't think the low EPS number is just because it's for 9 months not 12. This will hopefully come up in the investor meet presentation later.
Paul you say you're basing your target evaluation on a 15x EBITDA. Isn't that rather rich for a relative small player? It only needs a couple of larger clients to run into problems on adverse FX movements and things could look quite different. Alpha FX, which is in fact 5x the size, had exactly such a problem, and that was with just only one client which misjudged things at the beginning of the pandemic. Luckily for Alpha, it could raise money in the markets and bail out its client's position and let it unwind over time, and Alpha made money on it overall. But truth be told, there is good reason why size comes at a premium in this sector.
LON:AGFX have always had a problem with customer churn. I assume that is because their bespoke service is more expensive than competitors and so the move to more online trading. Year 22 quoted as 1624 active clients with 528 new ones. Year 21 they has 1385 so 289 clients did not stick around.
They seem to have given the issue a lot of thought and the solution is not to quote the number of new clients in their reporting. 152 more clients trading this 6 months than in the same period last year but when they have a new Dutch office and a large sales team it I would seem like the problem persists.
If they can find a way of keeping clients then the business may have real traction but until then I would always be nervous in advance of any update.
Marks Electrical (LON:MRK) - investor presentation this Thursday (10th Nov) at 12.30pm with the CEO and CFO of Marks Electrical Group plc - interested parties can sign up here for the live event with Q&A: https://www.equitydevelopment....
Today's CEO & CFO interview here together with some analyst commentary too
https://www.linkedin.com/posts...
https://www.linkedin.com/posts...
Marks Electrical (LON:MRK) - "Connecting the growth drivers" (new research piece out here: https://www.equitydevelopment....)
Marks Electrical’s 15.1% first half sales growth was announced in last month's trading update, driven by market share gains. Today’s interim results release evaluates those share gains in more detail, as well as including three important indicators of ongoing and sustainable progress within the business – margin resilience, a strong return profile and the company’s net cash position. The company is well placed to make further share gains in H2. Despite a competitive market, the company continued to invest in its brand and customer service levels. Moreover, MRK expects to meet current market expectations of profit growth for the full year. The company’s intrinsic value incorporates its industry-leading 4.8 Trustpilot score and significant headroom in terms of both market share and brand awareness levels. A positive cash position was reflected in the announcement of a 0.30p interim dividend. We maintain our fair value of 150p per share.
Marks Electrical (LON:MRK)
Great set of results I thought, really ground out from clearly tough market conditions. They appear to be taking market share, but the marketing costs are of course increasing.
I know this Leicester company from years ago and they have always been hard working, and I see that continuing...down to earth owner who knows his business (Its in the name).
Am I buying in today? Well no because as John Snow said winters coming, and this recession could be a long one. Do I want to hold a share with this head wind?...I think not, well not at the current SP.
All that said any shoots of recovery and if the P/E is still reasonable then the grinding out of results in this climate I wont forget, and makes me confident about Mark and his company.
Today's CEO & CFO interview here together with some analyst commentary too
https://www.linkedin.com/posts...
https://www.linkedin.com/posts...