Small Cap Value Report (Tue 9 July 2024) - PULS, AGFX, BEG, VTY, CPI, HTG, Movers: INDV, PAGE. Brief: LGRS, WINE

Good morning from Paul & Graham!
All done for today, see you tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
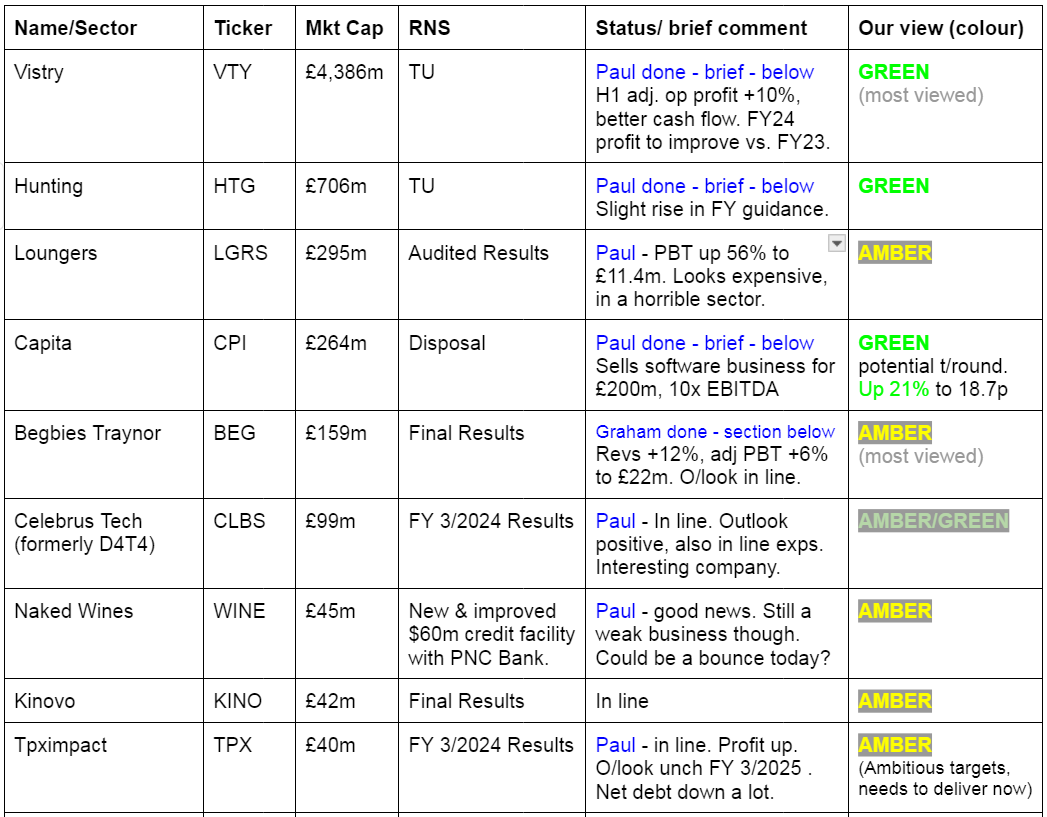
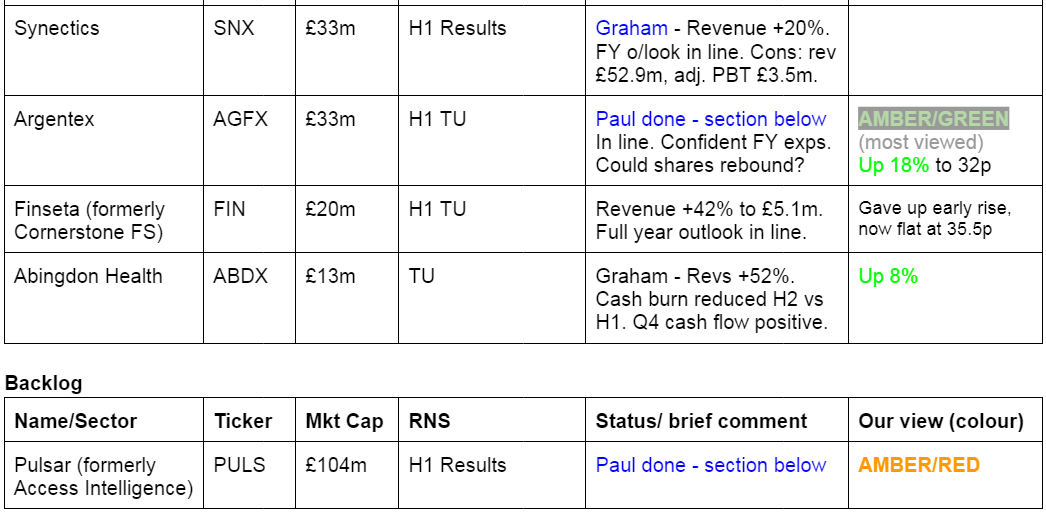
Other mid-morning movers (with news)
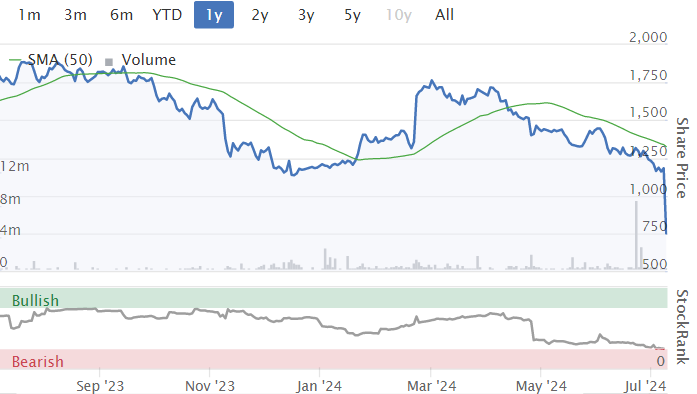
Indivior (LON:INDV) - down 32% to 780p (£1.04bn) - Profit warning - Paul - BLACK (no view on fundamentals)
This pharma more than 10-bagged from 2020 to early 2023 peak c.1975p. It’s since given up 60% of the peak price.
I won’t go into the detail here, but a profit warning today says it reduces profit guidance, due to various problems. Cutting costs. Reduces operating profit guidance to $285-320m range, previously $330-380m. Discontinuing sale of schizophrenia drug Perseris, as no longer financially viable. IMDV moved its primary listing to USA last month, since c.50% of its shareholders are American. Today’s 34% fall is much larger than brokers originally expecting 10% fall. One for bargain hunters to investigate maybe? No view from me, as I haven’t researched it, am just flagging up the large % fall today.
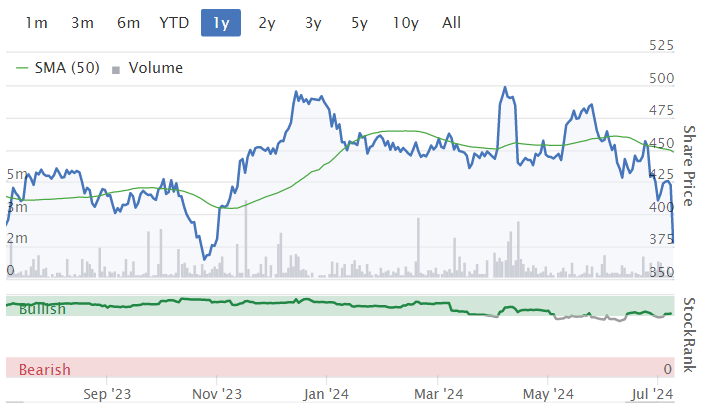
Pagegroup (LON:PAGE) - down 10% to 382p (£1.26bn) - Profit Warning - Paul - BLACK (AMBER on fundamentals)
International recruitment group, says Q2 trading soft in almost all regions. Candidate & client confidence low. More cautious FY 12/2024 guidance now operating profit c.£60m. Operating profit was £119m in FY 12/2023, and £196m in FY 12/2022.
Paul - I’m surprised that the soft recruitment markets are getting even softer. I would have expected signs of a recovery beginning, but that’s not the case. Even after today’s fall, PAGE shares don’t look obviously cheap, arguably they already factor in a strong recovery that hasn’t even started. Balance sheet is fine, so no solvency/dilution issues. Generous divis might have to be trimmed a bit? It should recover in due course though, but why would I want to pay up-front for a recovery? Read-across to smaller recruiters today, eg STEM down 4% - vulnerable to a PW also l I wonder? Tough sector still. Are there any more structural sector problems I wonder, eg disruption from online competition? Let me know if you’re a sector expert!
Summaries
Pulsar (LON:PULS) - down 5% to 81.5p y’day (£104m) - H1 Results - Paul - AMBER/RED
This used to be called Access Intelligence, and we've not reviewed it for 18 months, so I wanted to get the archive up-to-date. Continued losses, poor cashflow, and a weak balance sheet put me off. But it promises better performance in H2.
Argentex (LON:AGFX) - up 7% to 29p (£35m) - H1 Trading Update - Paul - AMBER/GREEN
A catalogue of problems over the last year have crushed this payments/forex company's share price and profits. Could we be seeing the early signs of it stabilising today under new management? It looks that way to me, so I've pushed the boat out with a move up to a (speculative) amber/green.
Begbies Traynor (LON:BEG) - down 2% to 97p (£155m) - Final Results - Graham - AMBER
Solid results from Begbies with decent organic growth (6%) boosted as usual by some acquisitions. Insolvency work is plentiful but M&A/advisory remains slow, with a recovery anticipated later in the year. I remain neutral on this as the current market cap seems fair to me, given the sector in which this operates.
Vistry (LON:VTY) - unch. 1288p (£4.35bn) - H1 Trading Update - Paul - GREEN
[Brief section, no more detail below] - we’ve flagged before the good, differentiated (through partnerships eg with Local Authorities, Housing Associations, etc) and superior business model of this housebuilder, and have previously been amber/green on it. Today it says -
“The Group has delivered a strong performance in the first half which underpins the Board's confidence in its expectations for the full year. “
Broker consensus is for c.90p EPS, so that’s a PER of 14.3x, falling to 12.2x if next year’s 106p forecast is achieved.
Like all listed housebuilders, it’s nicely asset backed, although P/TBV is relatively high at 2.1x. It had net debt of £323m at 6/2024 - modest considering the asset backing & earnings. Excellent disclosure of average month end net debt, higher at £490m. Reckons it will be net cash by Dec 2024 year end. Dividend yield is a pleasant 4.6%, almost twice covered, plus share buybacks underway. It says that building materials have fallen in price this year vs last, that’s interesting - maybe not so good for the building supplies sector. Cost savings expected to continue in H2.
Paul’s opinion - I think Vistry has the best business model of the UK listed housebuilders, which is reflected in a higher valuation relative to NTAV. It also looks in pole position to benefit the most from the new Govt’s focus on increased affordable housebuilding. Although as with everything, we await firm details. Overall, even though this share has done well, I suspect it could have further upside over the medium term. Hence I think we should be GREEN. It might be a nice one to buy the dips?
My only worry is that a tax-hungry new Govt might well also be eyeing the massive profits the big housebuilders generate, and might find a way to grab a bigger slice for themselves? I think housebuilders already pay a 4% surcharge on their profits (RPDT), so what’s to stop the new Govt hiking that further?
Capita (LON:CPI) - up 20% to 18.5p (£315m) - Disposal - Paul - GREEN
This was another potential turnaround that Richard Staveley also mentioned in his recent interview with Paul Hill, with all sorts of insightful comments on Capita and others. Hence I had just put CPI on my list of share ideas to revisit, so today’s news is timely. I’ve liked the turnaround potential here in the past, but shares never seemed to reflect the significant progress that’s already been made in repairing its previously over-geared balance sheet. I flagged it as amber/green here on 14/12/2023 as a potential recovery share.
Today’s disposal is Capital One, a standalone software business, that has been sold for £200m, a 10x EBITDA multiple. This will hit short-term profits (as £19m pa PBT drops out of the group numbers in future), but
“Capita is maintaining its medium-term guidance for the continuing Group based on the benefits of the cost saving and technology initiatives previously outlined.”
Requires shareholder, and Govt approval.
Paul’s view - note that Capita only had £182m net financial debt (excl. leases) at Dec 2023. So assuming no big changes, this disposal wipes out all that net debt. Although its balance sheet overall is still weak, it does benefit from getting substantial up-front cash from customers - so a favourable working capital cycle means balance sheet weakness doesn't matter that much. It only becomes a big problem if Govt decides to become a slow payer.
I would argue that since the disposal is at a valuation multiple considerably greater than CPI’s own PER of 4.5x, then that would seem to make sense, and improve the overall position for CPI.
As Richard Staveley points out, if Capita achieves its target operating margin in future, similar to what it achieved in the past before everything seemed to go wrong, then the share price could end up substantially higher than it is now. That is a big “if” though! It wouldn’t surprise me if this share doubles from here, which would only take the PER up to about 8-9x. If it then out-performs against what seems modest forecasts, then maybe more upside? Overall I see positive risk:reward here, and there will be likely loads of investors who won’t even look at Capita shares, just assuming it’s still a basket-case. Hence an opportunity maybe? Time will tell, we can’t predict the future.
Hunting (LON:HTG) - unch 428p (£708m) - H1 Trading Update [ahead exps] - Paul - GREEN
“Hunting PLC (LSE:HTG), the global precision engineering group, today issues a trading update, ahead of its Half Year Results to be released on Thursday 29 August 2024.”
H1 trading is ahead of management expectations.
Order book is up, at $700m ($565m previously at 31/12/2023)
H1 EBITDA guided at $59-61m, ahead exps, and 22% up on H1 LY.
H1 EBITDA margin is 12%, with 12-13% guided for FY 12/2024.
(was 11% in 2023, and 7% in 2022)
Improved performance in H2 expected, due to cost-cutting.
Net debt negligible at June 2024 ($9-11m)
Outlook is positive for both FY 12/2024 and 12/2025, helped by (previously announced) big Kuwaiti orders.
Guidance -
FY 12/2024 EBITDA guidance raised to $134-138m (it said on 15/5/2024 that expecting towards top end of $125-135m range. So this update today is hardly any different)
Note that EBITDA was $103m in 2023, and $52m in 2022, so there’s been a very strong profit recovery here.
FY 12/2025 EBITDA guidance $160-175m (changed or unchanged???)
I wish companies would explicitly state the before, and after guidance, when they update the market.
Net cash of $30-40m expected at 31/12/2024.
Broker update - many thanks to Canaccord for sharing their work with us, available on Research Tree. They forecast US$0.42 adj & dil EPS for FY 12/2024, rising nicely to US$0.61 for FY 12/2025 - both figures very slightly edged up today.
Convert into sterling, gives 32.8p and 47.7p, so at 428p/share the PERs are 13.0x and 9.0x - that seems attractive value, especially considering HTG has a superb balance sheet, with a P/TBV of only 1.19x. So you’re getting surplus capital in for free.
Paul’s opinion - we’ve been flagging HTG as a good value share for a while, and my recap of the numbers today confirms that remains the case, despite the shares having risen considerably already this year.
It all depends whether the boom in profits will continue or not. Obviously I have no idea about that, you have to assess that sort of thing, which is the next stage of research after our quick reviews here. Order lumpiness could be an issue if the large Kuwait orders turn out to be one-offs.
Based on the information as of today, it’s got to be GREEN.
Pulsar (LON:PULS)
Down 5% to 81.5p y’day (£104m) - H1 Results - Paul - AMBER/RED
Pulsar Group Plc (AIM: PULS), the technology innovator delivering Software-as-a-Service ("SaaS") solutions for the global marketing and communications industries, is pleased to announce its unaudited half year results for the six months ended 31 May 2024.
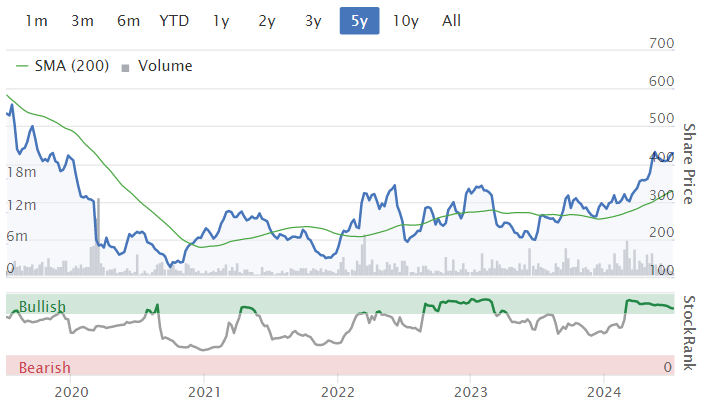
This is the new name for Access Intelligence. I last looked at it in Jan and Dec 2022, and wasn’t impressed - noting its continuing losses, weakish balance sheet, and wobbly outlook. I’ll take a look today with fresh eyes, let’s see if things have improved, as the share price has had a strong recent run up.
Nearly all (96%) of revenues are recurring.
H1 revenue £30.8m (up 1.3%)
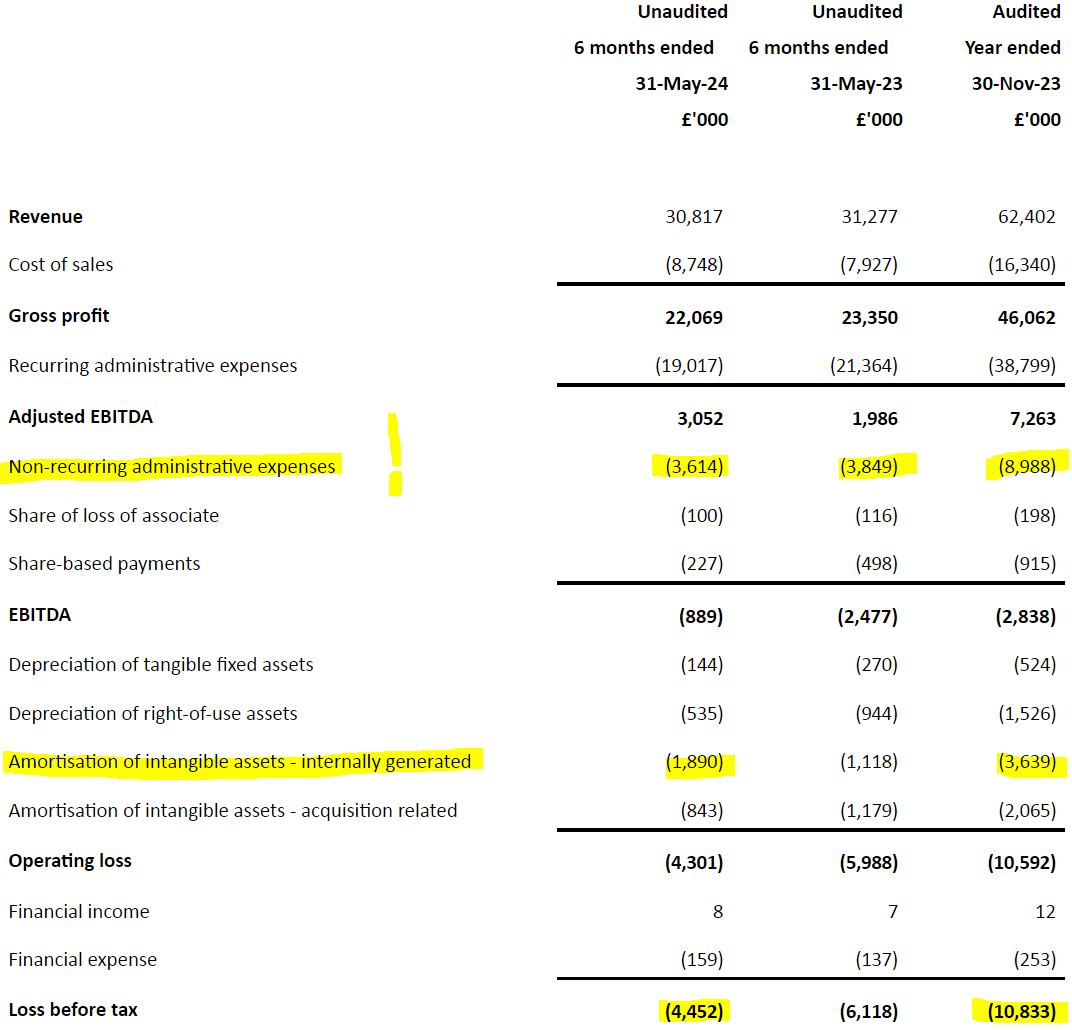
Adj EBITDA £3.1m (up 55%) - but my previous notes point out that positive EBITDA turns into PBT losses, so it's a meaningless measure.
Outlook - trading in line, so we should be able to rely on this year’s forecast -
“the Group continues to trade in line with the Board's full year expectations.”...
“Overall, the Board remains confident in Pulsar Group's outlook for the second half of the year and beyond…"
“The ARR growth delivered by the Group during the first half is expected to contribute to higher revenue in the second half, whilst the Group's pipeline also continues to grow with a number of strategic opportunities expected to close during the second half.”
“the majority of expected non-recurring costs have been incurred in the first six months of the financial year are all expected to contribute to improved free cash flow conversion into the second half of the financial year. The Group's third quarter is usually a strong period for customer invoicing and we therefore expect to see the net debt position reduce over the coming months.”
You can see from this table below, there’s a gulf between adj EBITDA and PBT again, huge. However, if the heavy non-recurring costs really do not recur, then that would take the company quite close to breakeven in future, so more research is needed on the nature of these “non-recurring” costs -
I can tolerate short term losses, if the balance sheet is strong, so this is key.
Balance sheet - looks very weak to me. This company clearly needs an equity raise to strengthen its balance sheet.
Some numbers - NAV is £46.2m, less intangible assets of £69.3m, gives NTAV of £(23.1)m.
Working capital looks tight, with only £1.25m cash, but a current ratio of a very poor 0.32.
Note that new loan liabilities have appeared in H1, of £2.9m (current) and £1.5m (non-current), which were not on last year's balance sheet. So it’s moved from net cash of £2.7m May 2023, to net debt of £3.2m at May 2024 - a worrying deterioration. So the bank facilities are now crucial - it arranged a £3m loan, plus a £3m overdraft in H1, but reckons improved cashflow in H2 should address this.
Cashflow statement - looks poor to me. Positive cashflow last year was only generated thanks to favourable working capital movements (extending creditors). That’s slightly reversed in H1 this year, meaning there’s nothing in cash generation. Plus it then capitalises a lot of its payroll in development spending, at £3.4m in H1 (FY 5/2023: £8.6m).
Paul’s opinion - I’ve seen enough to make me want to give this share a wide berth.
It’s not yet demonstrated an ability to make proper profits. Growth is pedestrian. It’s cash hungry, and has a weak balance sheet, so an equity placing looks inevitable here - indeed they should do one, since the £104m market cap gives plenty of scope to repair the balance sheet with only (say) 10% dilution.
Upbeat outlook says H2 will be better - it needs to be!
Why pay £104m for something so lacklustre, and which has been around for many years too, delivering no dividends, and often giving back share price bull runs? The share count has tripled in the last 6 years, so it looks like they’ve bought in growth through acquisitions.
I’m happy to turn positive if it delivers some decent numbers, but it hasn’t done. Therefore I have to be cautious given the weak cashflow & balance sheet, it’s AMBER/RED.
As always, we don’t know what the future holds, so if it does deliver a stronger H2, then shares could go up. Also bear in mind that software companies are often highly attractive to bidders, who value them differently to our approach here of value/GARP. So it might appeal to a different type of investor who is prepared to value it on adj EBITDA and recurring revenues.
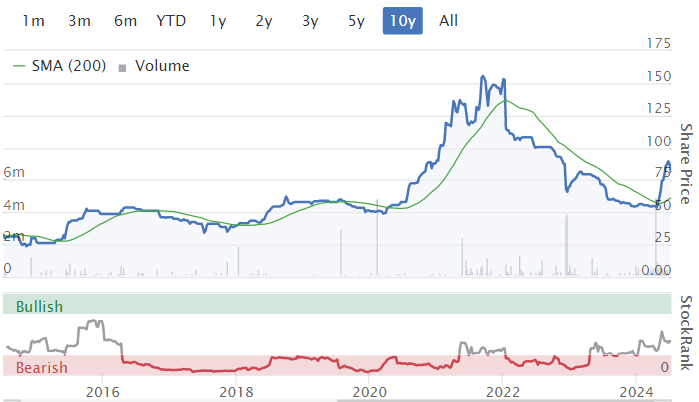
Ten-year chart is uninspiring - and quite low StockRank for most of this period too -
Argentex (LON:AGFX)
Up 7% to 29p (£35m) - H1 Trading Update - Paul - AMBER/GREEN
Argentex Group PLC (AIM: AGFX), the global specialist in currency risk management and alternative banking, today announces a trading update for the six months ended 30 June 2024.
I’ve just been looking through my previous notes, and had forgotten what a can of worms this share has been in the last year.
Very briefly, the CEO abruptly exited in Oct 2023, followed by the CFO a fortnight later. Then came several profit warnings. On 2/5/2024 it announced a £3.25m (before fees) fundraise at 45p, increasing the share count from 113m to now 120.4m. The original announcement had stated it hoped to issue 11.3m new shares (actual was 7.2m issued). It was a surprise to me that it needed a fundraise at all, given the cash already on its balance sheet.
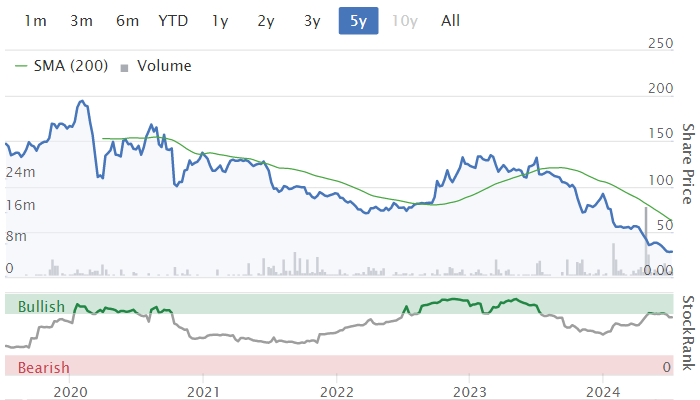
The share price has been awful for investors in the last 5 years -
Previously it was profitable, but as you can see from the graphs below, EPS has just collapsed, down into losses now for 2024 & 2025. I still don’t understand what specifically went wrong at AGFX to cause this profits collapse? -
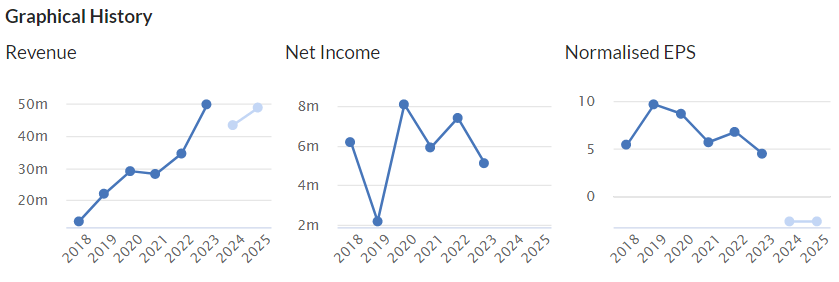
Today’s H1 update makes it sound as if things are stabilising, and not getting any worse, hence why I speculated in my pre-market open comment above that we might see a bounce today.
Here are the company’s headlines today -
Trading in line with expectations
Positive momentum against strategic objectives with key hires to accelerate move into Alternative Banking
Interim CFO has accepted a permanent role
(I like this, as it suggests that he’s not found a can of worms and hence is happy to stay put. So this reassures somewhat that the problems are probably not terminal)
Guidance - H1 revenues c.£23.9m (down 4.4% on H1 LY)
Signs of improvement? - yes, but vague and no figures -
“Although adverse market conditions experienced during 2023 in the core FX business continued into the first quarter of 2024, trading momentum in the second quarter has been encouraging. The Group continues to make good progress across the areas of strategic focus, particularly in regards to the acceleration in Alternative Banking and the geographic expansion overseas.”
Outlook - for FY 12/2024 -
“the Board remains confident in its full year expectations.”
Although a reminder that “in line” is not good, when broker forecast (thanks to Singers) is a PBT loss of £(4.9)m in FY 12/2024, and a £(4.0)m loss in FY 12/2025. So a very low bar, which we need to see AGFX thrashing in future, with ahead of exps updates, for it to regain market credibility I think. Hence this is very much a not getting any worse update, rather than a positive update.
Losses damage balance sheets remember, so it might need another small placing perhaps?
Overseas expansion - granted an Australian licence, ahead of schedule in application for a Dubai licence. I like the sound of this, as it possibly indicates a company on the front foot, not a declining business in firefighting mode.
Balance sheet - was last reported at 31/12/2023. It showed £38.3m NTAV, slightly above the present market cap of £35m. It had a clean going concern statement too at Dec 2023. I’m not at all expert in analysing financial services companies, but to me this balance sheet does not look stretched. Maybe the small fundraise earlier this year was to pre-empt any balance sheet erosion from expected trading losses in 2024 & 2025?
Paul’s opinion - the excellent Richard Staveley of Rockwood Strategic mentioned AGFX in his recent interview with Paul Hill, which I highly recommend, it’s full of fascinating stock specific insights from start to finish. I won’t put words into his mouth, oh well maybe just a little, he was saying AGFX could be a good turnaround. Although I would temper that by noting that Harwood reduced its stake in AGFX in April! So it can’t be their no.1 pick, and they might be stale bulls wanting to exit, who knows?
I think there might be tentative signs here of a turnaround beginning to take shape perhaps? Together with a decent enough balance sheet, and a bombed out share price, I’m minded to push the boat out a bit, with AMBER/GREEN. OK that’s not supported by any profits or divis, so it won’t appeal to value investors. We can’t just sit on the fence with everything though. So please bear in mind that this is a more speculative thing than our usual amber/greens.
Generally I’m not keen on the business models of these alternative payments/forex type companies. As we saw with the recent update from Equals (LON:EQLS) , a lot of the growth recently has come from higher interest rates meaning it picks up the interest receivable, running into millions. That’s fine, but it’s exaggerated profit growth in the last 1-2 years in my view.
Graham’s Section:
Begbies Traynor (LON:BEG)
Down 2% to 97p (£155m) - Final Results - Graham - AMBER
This is an old favourite at the SCVR: Begbies Traynor, a professional services consultancy that is traditionally known as an insolvency practitioner.
“Business recovery” remains its largest service line, accounting for 60% of revenues.
Today we have full year results for FY April 2024: there is progress against the prior year by most measures, but not by PBT and EPS.
EPS is affected by the higher corporate tax rate:
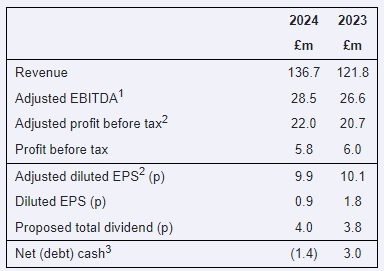
Organic growth is 6%, total growth 12%. Four acquisitions contributed £5m to revenue.
Comment by Ric Traynor:
I am pleased to report on another successful year of strong financial performance, which now represents a decade of profitable growth… We have delivered value to shareholders across the cycle having tripled the size of the business with a six-fold increase in profit since 2014.
We have started the new year confident of a further year of growth, in line with market expectations…
Outlook - “encouraging activity levels in all service lines with positive momentum”. Organic growth is anticipated to remain at similar levels for the new year.
Insolvency: activity remains at elevated levels, due to higher interest rates. There were 25,400 insolvencies during the year (previous year: 22,600). Begbies is ranked #1 nationally for insolvencies, and within this is ranked #2 for administrations. Sectors under particular pressure now are construction, real estate, financial services and support services.
Advisory and corporate finance: should improve as M&A is anticipated to recover later in the year.
Property advisory: “well-placed to build on its recent strong track record”.
Financials
The non-underlying items at Begbies tend to be a hot topic here, as they are so large:
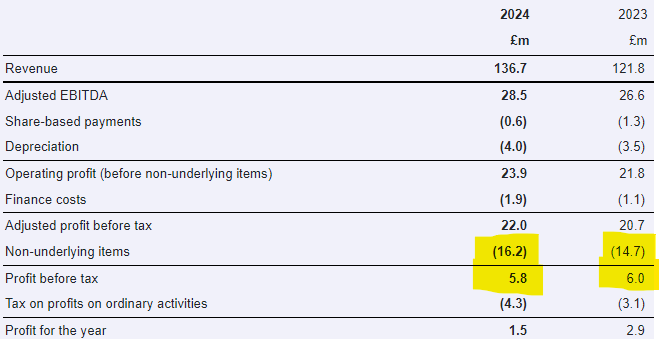
As the table above shows, even before the impact of the higher corporate tax rate, Begbies was already posting a slightly lower pre-tax profit in 2024 vs. 2023. This is due to the impact of higher non-underlying items.
All non-underlying items relate to how the company must account for its acquisitions.
Therefore, if you’re happy to write off all acquisition-related costs, you can use adj. PBT figure and not concern yourself with the statutory number.
This is how the non-underlying items break down for FY 2024:
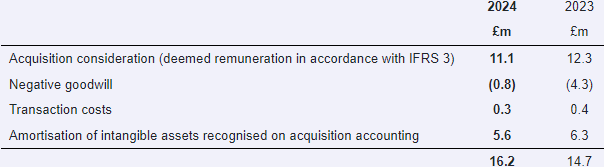
The major difference is that Begbies didn’t benefit so much from negative goodwill (this is what happens when you buy a company for less than the fair value of its assets).
There is £11m of acquisition consideration that is tied up with the continuing participation of key employees (the sellers of the companies bought by Begbies).
There is also £5.6m of amortisation of intangible assets: these assets primarily consist of customer relationships, brands and order books.
Balance sheet: net assets are £78m but these are nearly all intangible assets. The balance sheet includes £45m of “unbilled income” within receivables, up from £37m last year.
Graham’s view
We last discussed Begbies in February, when I took a neutral stance. I do generally have a positive impression of the business and I admire the stewardship of Ric Traynor who remains the largest shareholder (17%).
When it comes to valuation, I try to take a middle ground between allowing some of the non-underlying items, while at the same time accepting the logic behind the accounting rules. There is a £16m gulf between adj. PBT and statutory PBT, and I think the truth lies somewhere in the middle.
It’s interesting that despite the continued high levels of insolvency activity, the BEG share price has been so soft:
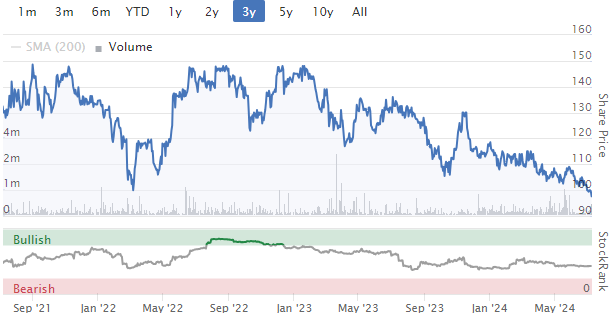
At a market cap of £155m, lower than it was the last time I analysed this share, I’m inclined to again think that this could be worth studying for value. However, given the sector (professional services/accountancy) and the highly adjusted accounts, I can’t bring myself to upgrade my stance from neutral.
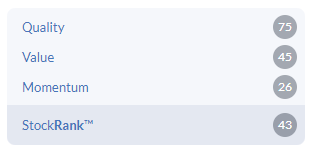
It seems that the StockRanks agree with my human assessment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
What do people think is happening with Hunting (LON:HTG) ? Paul is super positive on it, green today, no red flags he's seen in the release - but it's down 16.73% right now
This is the SCVR from July, latest RNS is a profit warning. Hunting (LON:HTG)
Oops, sorry!
Loungers (LON:LGRS) As a shareholder with shares held in a Nominee account can anyone tell me if and how I can claim the shareholder benefits? TIA
Loungers (LON:LGRS) - Investor Presentation (FY Results) video recording - July 2024
Nick Collins, CEO, and Stephen Marshall, CFO of Loungers plc hosted an Investor Presentation covering its Full Year results for the period ended 21st April 2024. Management discussed highlights, including a record year for sales, profits and site openings. They provided a detailed Financial Review and a thorough look at Strategy and Operations, including relevant Case Studies. Loungers highlighted the strong pipeline of new sites as well as strong trading performance over the first 11 weeks of the current financial year. Finally, the team answered a range of questions submitted by viewers.
Video recording now available - Begbies Traynor (LON:BEG) Investor Presentation (FY Results) - July 2024
Ric Traynor, Executive Chairman, and Nick Taylor, Group Finance Director of Begbies Traynor Group plc hosted an Investor Presentation covering their Full Year results for the period to 30th April 2024. Management discussed highlights of another year of strong financial performance, including overall revenue growth of 12%, a record year for Property advisory, four value accretive acquisitions and another year of dividend growth. The team provided a detailed Financial and Divisional review, and commented on their strategy for growth and the outlook. There was also a wide-ranging Question & Answer session at the end of the presentation.
Begbies Traynor (LON:BEG) - "Good results and strong momentum into FY25" - research report here: https://www.equitydevelopment....
Reliable results are a BEG characteristic. FY24 included 12% revenue growth (6% organic), just ahead of our forecasts which puts it well on track to achieve its £200m medium term revenue target; we project that by FY27. The outlook is also confident and our FY25e forecast only includes organic growth and full contributions from recent acquisitions.
As a result of cash generation in the period year-end net debt was £1.4m (FY23: £3m net cash): that is certainly impressive post £11.1m of acquisition payments and EBT share purchases. Encouragingly, all operations performed as expected.
Revenues from business recovery and advisory were up 7% y‑o‑y, business recovery 13% ahead and insolvency was particularly active. Property advisory had a particularly strong 12 months. It reported 26% revenue growth to £40m, a record year for the division, and higher margins on the back of organic growth and contributions from acquisitions.
The growth outlook from this higher base is on track to hit an ambitious medium-term target. Our retained 175p / share fair value/share assessment dates from mid-2022 with revenues and adjusted operating profit having since increased by 24% and 29%, respectively.
Begbies Traynor (LON:BEG) FY24 results presentation to analysts. (Following on from Graham's coverage above) Video & podcast.
FY25 in line with expectations Rev £142.1-146.3m; PBTa £23.1m-24.3m
Insolvency levels are elevated & anticipated to continue into 2025.
M&A instructions pipeline encouraging with recovery anticipated later in the year.
Positive activity in debt advisory and funding
Property advisory: good prospects for acquisitive and organic growth
Cash generation and renewed and enlarged debt facility give flexibility to execute growth strategy.
The ambition of medium-term revenue target of £200m
Next update September 2024 AGM.
Goodwin (LON:GDWN) joined the FTSE 250 Index, promoted from the FTSE SmallCap Index. The SP fell 9% !! (I hold, and will pick up a few more)
I was browsing the Vistry (LON:VTY) website after reading Paul's summary on their results. It would appear they are closely aligned with the new Govt's priorities on social housing and the benefits to us all of taxpayer investment therein. I've attached a link to an article written by Greg Fitzgerald, Chair/CEO, effectively offering support to the new Government's proposed social housing programme.
https://www.vistrygroup.co.uk/...
Let's hope the quality of their developments improve. I live on one. The build quality is appalling as is the customer service. They lie when selling. Many owners here have had to move out into temporary accommodation whilst their houses were repaired (new roofs, sloping floors, collapsing gardens you name it). The development was started 8 years ago. we moved in 5 years ago and were promised it would all be finished in 18 months. Last house was built 3 years ago but development still far from finished. Unpaved roads and paths and generally looks a total mess still. Maybe Greg Fitzgerald and the new housing minister would like to visit to see for themselves.
Chinese exporters raise fears of Christmas freight crisis
Red Sea attacks push up costs and put pressure on profits during critical season for trade
https://archive.ph/FrnLG
Surprised the likes of Luceco (LON:LUCE) and IG Design (LON:IGR) have made no comments on the sharp rise of freight.
Tandem (LON:TND) James Latham (LON:LTHM) Shoe Zone (LON:SHOE) have warned recently.
Does anyone have any idea of why Eurocell (LON:ECEL) has suddenly jumped 7% today? Nothing on RNS that I can see.....
Eurocell (LON:ECEL)
Epwin (LON:EPWN) is up 4.7% today too so perhaps something sector related? Perhaps we are going to have something akin to a Santa rally with regard to stocks that may perhaps be viewed as benefiting most Labours policy changes. Labour certainly seem to have a bee in their bonnet about getting new houses built - in that regard i applaud them 100% and lots of new houses being built should benefit eurocell and epwin i would presume?
Eurocell (LON:ECEL) Michael Taylor (@shiftingshares on X) posted the below at around 2pm.
Am guessing that, and the sector moves, is what is behind it. Let's hope it keeps momentum.
Just a quick thank you to Paul & Graham . I am in awe of your (early bird) work ethic and analysis. Also a fan of your insight and humour. In the immortal words of Fun Boy Three 'It aint what you do it's the way that you do it'. Keep it up.
ps I've only been with Stockopedia since Feb 24 and am pleased to report on a portfolio of 13 diversified QM stocks I am up 28%. Of course I may just be a lucky monkey dart thrower writing the occasional shakespeare but at least now I know what I'm aiming for! Thank you for the enjoyable journey.
I like your style Fire Juggler, I'll have to play that song now! :-D
(and a belated welcome to Stockopedia, and thanks for the lovely feedback!)
Fun Boy Three ????? Try the original by Ella F https://www.youtube.com/watch?...
Y'know, nostalgia ain't what it used to be 8-(
Paul - I’m surprised that the soft recruitment markets are getting even softer. I would have expected signs of a recovery beginning, but that’s not the case. Even after today’s fall, PAGE shares don’t look obviously cheap, arguably they already factor in a strong recovery that hasn’t even started. Balance sheet is fine, so no solvency/dilution issues. Generous divis might have to be trimmed a bit? It should recover in due course though, but why would I want to pay up-front for a recovery? Read-across to smaller recruiters today, eg STEM down 4% - vulnerable to a PW also l I wonder? Tough sector still. Are there any more structural sector problems I wonder, eg disruption from online competition? Let me know if you’re a sector expert!
No, there are no structural problems. Online plays a big role in hiring nowadays but it is a tool successfully exploited by recruiters rather than a competitive force. What’s freezing the market is a lack of confidence on the part of both clients and candidates, coupled with a hoarding of talent by companies who fear being unable to replace key skills in any upturn - behaviour that leaves fewer funds available for new hires. This tends to become a vicious circle - a lack of openings deters job-seekers, a lack of candidates argues for hoarding employees!
This has actually been the longest hiatus I’ve witnessed. And my experience covers the recession of the early 90s and the GFC - both of which were MUCH worse in terms of economic consequences than the post-pandemic period of adjustments to labour markets.
My take is that companies are waiting for “the most anticipated recession” to finally arrive or for interest rates to start falling in time to avert the recessionary risk. Once they have some clarity, we’ll enter a new hiring cycle and recruiters will prosper again.
Do I see value? Not in relation to current earnings. But the important lesson with cyclicals is that they look expensive when cheap and vice versa. So I do see a good entry into a structurally growing sector. But I like SThree (LON:STEM) as a long-term hold, and Hays (LON:HAS) and Robert Walters (LON:RWA) for the recovery potential. My hunch is they start to rise with the first rate cut - unless it is one forced by economic stress!
BnB do you have any thoughts on how the new labour rules we can expect may affect recruitment companies - will that perhaps exacerbate things if Labour are moving away from firing and rehiring. do you think companies will be more likely to stick with what they have fully on books ? if thats the case could there be shrinkimng of the marketplace as companies do les hiring and firing ?
BnB do you have any thoughts on how the new labour rules we can expect may affect recruitment companies - will that perhaps exacerbate things if Labour are moving away from firing and rehiring
Only mildly and only at the very bottom end of the market - think Staffline (LON:STAF). Most of the listed recruiters work in well-defined, stable verticals, like book-keeping and clerical, IT and professional, where zero-hours contracts tend not to proliferate. Indeed, the temp model offered by the likes of Hays (LON:HAS) gives companies all the flexibility they want. The IR35 legislation brought in by the Tories to collect very little extra tax was far more disruptive than anything Labour is planning. So much for a bonfire of red tape!
Listening yesterday to a debate between two economists, one on the left and one on the right of politics. It was a discussion of growth relative to taxation levels to fund State spending.
The one on the Right suggested that further tax impositions would stall growth. The chap on the Left said it was difficult, and suggested that perhaps a Windfall Tax on Banks would raise Billions as they had profited from the inflationary environment and their arrangements with the Bank of England.
It was interesting because I hadn't heard this particular route for additional Revenues mentioned before. But I don't know how this sits with the previous Govts disposal of its shares in NatWest (I hold) as it is bound to damage its share price if it happened. Would that stop them though? Probably not is my guess.
Windfall tax on banks was mentioned, a few years ago, when interest rates went up. I would not be surprised if Labour did it and also on various other companies that make a good profit. But what happens when they get into trouble because they won't have the reserves to fall back on? Same for oil companies. If the oil price falls then there won't be any windfall tax. If it falls below $40, they may be asking for help.
I think ther is probably some logic for windfall tax on the banks if they have made easy money from benefiting from overnight rates or lending too or from the government as has been suggested. its all pretty ridiculous though that the taxpayers should not have been letting the banks make all this easy money in the first place - then gov treasury should make sure that wherever posible taxpayers benefit not a semi or fully private banks who are luck enough to be "part of the club". ditto for teh energy companies by securing fixed rates at obviously top whack prices some time ago. In summary hopefully its simply tougher fairer negotiotionals rather than simply robbing an easy target bank - i certainly wouldnt rule anything out in that regard.
Does anyone have access to Cannacord's BUY rating and SP target of £1.85 for Card Factory (LON:CARD) ? Saw on ADVFN a post that says "Its preferred mid-cap pick is Card Factory, rated ‘buy’ with a 185p price target, which it said offers a multi-channel growth opportunity in the UK and internationally as the business focuses on the large non-card, gifting and celebration market."
Thanks to beachbum on Advfn!
Card Factory (LON:CARD) no position. Anecdotal observation.
Was in a busy mall north of Bristol yesterday afternoon sitting opposite the Card Factory shop for 15 minutes. In that time, saw few people entering the shop and most of those that did were walking out with balloons. I assume there's a good margin on balloons but not much other merchandise shifted while I watched.
Celebrus Technologies (LON:CLBS) Final Results to end March24 – from this £100m Mcap data anaytics, management and fraud detection business. The company is in transition from seller of services and box reseller of hardware/software to provider of its Celebrus platform software on a SaaS basis with multiyear blue-chip contracts billed annually
Good set of results, ‘comfortably ahead’ of revised expectations on March TU for revenue up 52% at £32.6m and profitability adj eps up 40% at 11p according to this mornings note from Cavendish available free on research tree.
The big jump in revenue and profitability is distorted by a large contract including low margin hardware that slipped from FY23 into H1 FY24. Management prefers to use software sales as a more consistent indicator of the companies continued transformation and growth:
Annual Recurring Revenue: £20.2m up 20.9%
Software revenue: £22m up 14.7%
Software gross margin: 72% (68.8%)
and net cash of £30.7m at year end – which is ‘unusually high’ and due to combination of working capital movements with a ‘normalised’ cash balance of around £25m.
FY25 forecast is for 9% increase in revenue to £34.2m and 17.5% increase in adjusted eps to 12.4p as declining hardware sales are replaced by more predictable and consistent ARR and software sales around or above 20% yoy.
Accounting for the 25% in net cash the SP is on around 15x current year adj eps – looking quite cheap for a company growing ARR at 20% yoy with 70% gross margins?
Having been unenthusiastic about acquisitions while the Celebrus platform product has been fully developed – in these results management is now clearly guiding towards a possible acquisition of ‘IP’ which will add technologies and valuable solutions to the Celebrus platform. Looks like there may be a use for the excess cash being generated by the business – before long.
I see Celebrus Technologies (LON:CLBS) as a long term software growth opportunity – but it’s not easy for investors to judge what the software does for its customers and the
growth in ARR and software sales has been obscurred by the declining low margin hardware sales. It’s one of the those ‘hidden in plain sight’ opportunities that can easily be overlooked. Not thatsuccess is guaranteed! But the new product development is well funded by the declining business which also helps to limit the downside risk.
I’m pleased by these results and looking forward to see how the next couple of years unfold, which if it continues at the same rate of progress will result in a considerable increase in shareholder value,
cheers
Mark
Celebrus Technologies (LON:CLBS)
IMC presentation today at 14:00 by CEO Bill Bruno and CFO Ash Mehta
https://www.investormeetcompan...
In today's results the CEO refers to the current year FY25 as a pivotal year - I look forward to hearing a more of what this means.
Ash Mehta appears to be an excellent and experienced CFO - his financial review is the first part of the report that I read.
The combination of both seems to be an excellent team - more than the sum of the parts, so worth a view if you have any interest in the company I think?
cheers
Mark
The Indivior (LON:INDV) warning today brings me back to the contentious subject of share buybacks. Whilst I understand the mechanics of buybacks and the positive impact they can have on eps, I retain the belief that dividends are a better form of shareholder return. They are a tangible and immediate benefit to shareholders that can be deployed in whatever way suits the individual (e.g. by buying more shares in the company or investing elsewhere). The buyback on the other hand is intangible and theoretical and only benefits shareholders if the company share price is genuinely cheap and likely to rise (and are management the right people to make an unbiased assessment of that?!).
When I compare two of my holdings, the afore-mentioned Indivior and Legal & General I think to myself that whatever their share price performances from here I have had many sizeable dividends from L&G that would cushion any capital loss from a future setback. With Indivior I have no such cushion and a share price that has now slumped and proved that the company was wasting shareholder cash with 'expensive' buybacks. I am not trying to compare these companies as investments of course, but it does make you think about the true value of buybacks?
I don’t understand the logic of choosing a company on the day of a profit warning to come up with an opinion whether buybacks work or not. Whether Indivior (LON:INDV) opted for a dividend rather than a buyback the result would have been exactly the same today for the shareholders.
All the best
well said yiannos1 - share buybacks work well if the company will perform well in the future and work bably if then company goes into retreat. If the share price is "cheap" you either have faith in future prospects or not if you dont probably best to sellup and move on. Its pretty obviuous though that if company comes out with profit warning affer large buyback that will with hindsight benfit look bad - thats says more about the company investment case than the buyback proces imho.
I think you are missing my point, yiannos. Company management will always favour a share buyback because their natural bias will see the shares as 'undervalued '. That could be because they genuinely believe it to be true or because they are trying to convince others. Either way, they are not in a position to make an unbiased decision. Not to mention that many are rewarded on share price performance and eps targets, both of which get a short-term boost from such financial engineering.
If surplus cash is really being generated then pay it back to shareholders or invest it in the business itself.
You have missed completely the point of your original post drifting to something totally different.
Just for your information global dividends have always been more than global buybacks and only recently because of Apple (NSQ:AAPL) have been getting closer to dividends (for your thesis on company’s management bias on management!).
All the best
I would like to think that when any company starts a share buyback it is because they are bullish on their future prospects. If they were not, they would simply hold off and start the buyback after a poor trading update. Of course they don't always get it right as has happened with Indivior (LON:INDV) today. You only have to look at Future (LON:FUTR) to see the positive impact of their share buyback in recent months for an example of what it looks like when it goes well.
I would like to think that when any company starts a share buyback it is because they are bullish on their future prospects.
Us as private investors would like to think so - the reality is if we take companiew like Aviva and they sold off underperforming bits of their business - they might not really have a clear vision ref the future and they simply have excessive funds they are unsure what to do with - i suspect many simply use buybacks as its perhaps as safe and efficientoptions as dividends - slightly less risky than doing somethging else.
The whole point about buying any share is being confident about prospects of teh company - in that regard having buybacks present IMHO never turns a ruderless company into a good company. If you pick the wrong company thats due to buisness fundamnetals and nothing to do with whether buybacks exist or not - imho.
Heck what do i know i sold out of Aviva when they started doing their buybacks and teh shareprice has held up and they are payinga decent divi - to be fair to Aviva management seem to be doing the simple stuff right.
I agree sparkler. A key reason why I’ve held Legal & General (LON:LGEN) for many years (except for a temporary sell in the covid crash) is because until very recently they’ve eschewed buybacks and opted for increasing the annual dividend. At my 155p buy price later in 2020 Legal & General (LON:LGEN) is now paying me 15% a year in dividends, and they are still promising annual increases too. That’s a good and growing return even without the current 50% capital gain.
That’s the thing with dividends. We get real money and are free to do what we like with it. With buybacks we don’t get real money, and if that Company buying back issues a profits warning or the share price falls anyway below the buyback prices, then there’s NO income at all and a capital loss. Big deal.
There are SO many examples like Indivior (LON:INDV) where buybacks have either been followed by a profits warning and big share price fall below all the buyback prices, or have fallen just because of subsequent poor updates. e.g I sold Abrdn (LON:ABDN) over 5 years ago as the share price fell away from £5 as they started what has turned out to be a multi year and multi £million buyback programme. The share is now down to just 160p or so…the price I bought back at a year or ago for the now 10% dividend thanks to that big share price fall. And at this price Abrdn (LON:ABDN) might attract a bidder or two. I’m getting 10% a year income from ABDN while waiting and hoping and have missed out of most of the 70% share price fall after their buybacks.
Buybacks do increase eps but reward sellers who have Abrdn (LON:ABDN) or Indivior (LON:INDV) or whoever as a willing buyer of their shares. But the intention is to reward those staying and not those wanting out! And eps can fall anyway (e.g after a profits warning) as can the PE ratio if the share or sector loses favour.
It’s easy to show where buybacks failed. It’s impossible to claim as BenHazz has today that the buybacks definitely worked as we can never know how what the share price would have been now without the buybacks. I hold Future (LON:FUTR) and bought near the bottom because it looked ludicrously oversold, so the big bounce could well have happened anyway especially as updates since the lows have reassures…..so far. But if there’s a surprise big profits warning then the share price could get hammered , buybacks or no buybacks.
I agree that it is "impossible to claim the buybacks have definitely worked", of course it is. However, mathematically, the additional shares bought will almost certainly will have supported the progress and positive momentum of the SP. The fact we are unable to attribute a specific value to how much support they have provided, unlike with dividends, is likely one of the reasons a lot of people do not value them.
We are constantly warned about small “story” stocks and indeed most of these ugly ducklings turn out to be ugly ducks. But occasionally a swan arises and today’s inline confirmation from Velocity Composites (LON:VEL) (I hold) may just be one of these. They have been in the verge of making a breakthrough to profit for a long time, as presentations at Mello confirmed, but now it really appears possible, although you do not have to be much of a cynic to decide to wait until you actually have a profit to look at. Their business in designing and making kits of prep reg carbon fibre to build complex lightweight shapes for aircraft is a very considerable moat and many years of business can follow. House broker, Dowgate, available through Research Tree, is marking a target price over 60% above current levels.
Capita (LON:CPI) share price is up 21% today after the disposal news.
I bought after this Sunday Times article in May:
https://www.thetimes.com/busin...
Here’s a section from it including Private Eye like Mr Contrarian here calling Capita (LON:CPI) Crapita! Is that now changing? Promising recovery share? Hope Paul has time to follow up his “Potential interesting turnaround,” comment, but there are SO many other updates again today, and there’s a limit to what he and Graham can analyse.
After 30 years living in London, Hernandez’s English, for all the jargon, is word perfect, but still carries a hard-to-place European accent that betrays a childhood of moving around the Continent, following his Spanish-German diplomat father. When we meet, on a sweltering summer day, he is sporting a grey checked blazer, white shirt and black chinos that match his gelled hair.
Up his sleeve is a plan to find £160 million worth of savings, partly from job cuts, in addition to 900 announced in November. It will also try to move some of its roles to lower-cost centres such as India and South Africa. “We spend £2.6 billion to make £2.6 billion,” Hernandez says.
He also hopes to streamline the business by “doubling down” on “four to five” areas where the company sees growth, while withdrawing from less-profitable work. “I think it’s very important that we start by getting smaller and fitter so that we can then get better and bigger — and it has to be in that order,” he says. Hernandez gives no hints on where Capita will concentrate its efforts, but the company is expected to focus on government outsourcing, providing customer services for business, pensions services and its work on defence, which includes training Navy recruits.”
Yes I think Capita (LON:CPI) is an interesting turnaround possibility, because although it developed a poor reputation in the media earlier this century, it must be doing something right as it still has a turnover of £2.6bn. If the new CE can at last get the company to operate profitably, then even a small margin can turn into sizeable profits.
I actually bought some Capita (LON:CPI) yesterday as a long term recovery play after la bit of weekend research, didn't expect+20% in a day, happy days.
Glad I listened to Paul's podcast on vox with Richard Staveley!He can be as API as he likes, but if my contact with entities that have their origins in Capita (LON:CPI) is representative (and it may not be), he is going to discover a large number of poorly constructed spreadsheets that have been maintained by 76 different people over the past decade, and any initiative to improve or automate matters falls foul of the IT security dept who believe they run the business.
A clear winner of the General Election.
From what I read and hear, Investing landscape appears to have changed with the new government. UK is now an investable country for domestic and international investors. For those who like the idea of investing in UK but not sure which company I have a suggestion, LLOYDS appears to be a front runner. A pure play on UK economy , good divi and a good looking chart.
Isn't it a little early to be declaring that the new govt will be positive for the share markets as a whole, and much more capital will flow into UK companies?
Hardly any concrete plans announced yet!
On the subject of Indivior (LON:INDV) , there are multiple reasons why the shares have been savaged; 1. The new litigation settlement suggests that this risk is not resolved. 2. The abandonment of Perseris and stalling of Opvee blow a hole in the diversification strategy and 3. The growth prospects for Sublocade are questioned. Worst of all, management reconfirmed guidance as recently as 23rd May as the move to a primary US listing was taking place and this update seriously undermines either their credibility or integrity or both. That is why I think a 30-40% fall looks about right, Paul.
Bloomsbury Publishing (LON:BMY) - Nice recommendation in the Times today extolling the virtues of Bloomsbury - which a bit odd as these articles normally follow the day or two after results published.
Hopefully this link to the Tempus Bloomsbury Publishing (LON:BMY) article will work https://www.thetimes.com/busin...
Somewhat surprisingly the article does not mention the recently announced HBO Harry Potter TV series which should certainly do Bloomsbury no harm whatsoever.
Begbies Traynor (LON:BEG): Insolvency is lower margin. As the economy improves as interest rates fall then the higher margin property, advisory and M&A businesses should push the ave margin back up and compensate for the falling insolvency business. Much better balanced portfolio and definitely under appreciated.
I’m amazed at the muted reaction to Naked Wines (LON:WINE) news this morning…
Gone from having a major covenant issue to realistically not even testing it, with ample added liquidity and independent validation of the inventory… I’d have thought it would be up 20%+
Hi RupertEvans12,
Yes I was also expecting a bigger relief rally in Naked Wines (LON:WINE) after today's good news on its new & improved banking facilities. Although I recall that it had previously announced that it was close to signing a new banking arrangement.
Another issue is that it says today the audit is delayed, as it was last year. I imagine that's probably due to wanting to get a clean going concern statement, which should be possible now the new facilities are in place.
Problems remain though - its giant wine lake needs to be seriously drained, and of course the business is now in decline, as it doesn't seem able to spend enough on marketing to replace the customer churn. As customers leave, they take their cash balances with them, so negative growth is cashflow negative.
It's one thing from averting potential insolvency (achieved today I reckon), to actually turning it into a viable business - which is looking distinctly doubtful in my view. WINE had that brief burst of profitability during the pandemic, which fizzled out. It's been spectacularly badly run in my opinion too, over-buying vast amounts of wine. Who knows what condition all that wine is in? You can't find out without checking the original batches & tasting them. It wouldn't surprise me at all if they need to do more (maybe large) write-downs of inventories. Half of it could be vinegar, for all we know! Quite a fun job for the auditors though, doing the annual stock checks!
Mind you, the market cap is only £45m, and with secure bank facilities now available, there might be a speculative trade here, who knows!? It's little more than guesswork, so more a gamble than a logical investment, in my view. The brand is quite well known too, so maybe an acquirer might see some value in this?
It will be fascinating to see how WINE pans out!
Smaller Virgin Wines UK (LON:VINO) seems much better managed, and has a decent balance sheet. But that seems stuck at about £60m revenues, and modest profitability, so little point in it being stock market listed now. Gresham House own 42% of VINO, so might want an exit, possibility of a sale to private equity? Or (much worse) just a de-listing.
Regards, Paul.
Thanks for the response, Paul!
Tend to agree with you that there's plenty of work to do getting it back to growth. But I think the lender will have had to do some diligence on the wine lake as part of their underwriting process - so we can be more confident than before at least that it's not half vinegar!
Would be keen to see either Paul or Graham's take on Begbies Traynor (LON:BEG) .
Whether you rate the company or not, it is an interesting share to look at from a financial accounting perspective.
There are HUGE adjustments (adj EPS is 9.9p vs 0.9p statutory). Due to the way they do acquisitions. Out of +12pp growth, +6pp last year was inorganic growth, and more so in past years.
Does one take on face value the adjusted numbers? Does one use other metrics, like operating cashflow? Maybe some more fancy maths on the contingent paid and payable to come?
If you take the rosy numbers; £22m adjusted PBT, £12.4m free cash flow then the market cap of £160m looks sensible given the market leading position (of the insolvency practice) and acquisition growth flywheel they have proven, as well as the security blanket (as a contrarian share to economic health).
I've been invested here for a few years now and its something I grapple with every time I look at the results; I'd appreciate Paul & Graham's (or anyone else's!) take on how they approach looking at Begbies.
(I hold in the Boon Fund)
Begbies Traynor (LON:BEG) results today (I hold). Feeling a bit underwhelmed as thought business recovery/insolvency activity might pick up by now (bad for business owners of course) although the outlook statement does sound quite bullish: 'Activity levels across our service lines are encouraging with positive momentum across the group' without often cited commentary about uncertainty in the economy etc that you usually see in outlook statements from most companies. Before the last year the company also, rightly or wrongly, traded on a relatively strong p/e multiple - 15 wasn't unusual.
There is always a huge gap between statutory and underlying earnings. A large part of this is labelled 'acqusition consideration'. For newcomers to Begbies Traynor (LON:BEG) they said in a presentation previously (see Q1 of the Q&A tab) this is what is outlined in a sale and purchase agreement. They said it is treated as a P&L item rather than a capital item because they require the vendors to stay with the business for a set time (usually 5 years). They pay those individuals a salary but this is charged ‘above the line’ - it is only the consideration element that is excluded for buying those businesses.
As a non-accountant I still don't fully understand that explanation but sharing it for others' info. You'd hope they know what they're doing on that!
Edit - should have mentioned that the company says the main reason post-tax profit and EPS is down slightly on last year is corporation tax plus they had slightly tighter operating margins.
On the PE multiple... both brokers notes (Cannacord and Shore) this morning picked up that the PE is much lower than historic, and also against peer set. Cannacord says should be back to the 15x level, given the point in the cycle (with insolvencies due to grow strongly).
On acquisitions... Begbies takes a more unique approach.
Usually, an acquisition will have a big fixed price, so this gets booked immediately into a capex like treatment on the P&L, with a big amount of acquisition intangibles in fixed assets, that amortises into the P&L accounts over years. This also gets adjusted out of annual accounts, by many companies.
In Begbies case, the fixed price component of their acquisitions are usually small. However, they have big earn-out clauses based on financial performance. As well as senior management lock-in (high) salaries for the first few years, for continuity and knowledge/relationship transfer. These are the big adjustments that are flowing through the P&L at the moment, due to the huge number of acquisitions done in the last few years.
On tax... they have a valid point, with tax rates going up from 21% effective to 26% for them. But so does every other UK company... funny how one can adjust out many things in accounts to show a more "true" (ha!) LfL comparison over two years, but can't do it for tax.
(I hold in the Boon Fund)
Finseta (LON:FIN) good update today showing they are maintaining momentum (in line). Was concerned after the recent pullback (like a few small caps) whether the story had changed. Hopefully will carry on the upward trajectory. (I hold)
Hi Scotty,
I'd be a little wary on Finseta (LON:FIN) At first glance these figures look great when compared against H1 23, but if you compare then with the previous 6 months then not nearly as positive.
Forecasts are for profit to halve in FY24 from FY23
At FY23 results in May mgmt said not expecting sequential growth at previous level from H223 to H124 given the seasonality of HNW transactions (stronger in H2) and also final off-boarding of white label customers by end FY23 (see / hear IMC Q 5. In FY23 results pres.). Not clear whether they were expecting an actual fall, but given v positive sounding outlook stmt and 54% yoy growth excluding white labels I think is worth looking at.
I’m not sure where your forecasts for “profit to halve” come from? Current forecasts seem to have PBT falling from £1.3m to £1.1m, and Adj. EBITDA rising from £1.7m to £1.9m. I suspect conservatively set given the number of upgrades last year.
Marstons.
Did I miss this one, or did it just disappeared yesterday?
Not on back log, so yep, another dissappear-ee
Sorry chri55. Paul has been quite restrained in his response.
This is simply rude and unnecessary. Please stop acting like a child
Unnecessary and unfair.
For CHRI55 sake what is your problem? I rarely comment but read the SCVR every day and you consistently seem to have a downer and spit your dummy out on a regular basis. Why do you stay.... In my opinion Paul et al get through a massive amount of work everyday and I for one am very grateful for their comments and assessments.
It's on my manual list, to try to look at Marston's (LON:MARS) at some point. I tend not to add it to the list unless I'm sure I can do it. But we've had an avalanche of new news today.
By commenting on it the way you habitually do, you actually make it a lot less likely that I'll want to cover it! Maybe have a think about that.
And again, please read the explanatory notes. WE. DO. NOT. COVER. EVERYTHING.
Not a small cap, Smurfit Kappa, but nice to see it return today as Smurfit Kappa (LON:SWR. I hold, been long for years.
Hi I'd appreciate a look at Kinovo (LON:KINO) , with the legacy issues at DCB finally settled and the main business of green energy installations doing well it looks a bright future (I hold)
Hi threeputt,
I just had a quick look at Kinovo (LON:KINO) but am too tired to do a proper write-up.
As you say, the main business seems to be doing well. Results are in line with a previous TU, so nothing price moving in today's announcement.
I'm still a bit worried about the legacy issues, despite them regularly reassuring us with progress updates saying things are gradually getting resolved. There are still some cash outflows to come, and the balance sheet is already stretched - negative NTAV c.£(5)m. Also note that receivables and trade creditors seem a bit odd to me. Note 23 shows quite big creditor of £3.5m owed to HMRC, which I suspect might have some arrears in it possibly? Also note it says 90-day payment terms to creditors. Plus £4.1m is included in trade payables which is actually an HSBC payment card balance - which I would say should be included in net debt. It claims these payment cards are used for admin convenience, but I don't believe them! The 90-day credit is more likely the reason for use, and £4.1m is a huge number to run up on a company credit card! Average trade credit has gone up from 66 days to 85 days. So there's hidden debt here, and I think it needs a £5-10m placing to sort out this balance sheet properly. In the meantime, KINO is being pretty creative in stretching their suppliers & other creditors.
I would factor that into your valuation, so it might not be as cheap as we might otherwise think.
As regards the core business, I just can't get excited about it. There are so many competitors offering the same services, regulatory compliance for housing. I can't see how it has any pricing power, so probably little to no scope to raise margins.
Probably priced about right overall? Plus with the risk that something unpleasant could yet resurface from the legacy issues. And no divis likely due to the weak balance sheet & remaining cash outflows.
It's difficult to see much attraction here.
Good luck with it though, it's now in an up-trend, and broker forecasts have been creeping up.
Regards, Paul.
Thanks Paul, appreciate the input and very valid points
Loungers (LON:LGRS) - "All-day strategy success, with more to come" - link to new research report: https://www.equitydevelopment....
Loungers’ FY24 results illustrate the strength of its all-day café-bar model with record FY24 revenues increasing 25% to £353m and Adj. EBITDA (pre-opening costs) rising 26% to £59.6m, 1% ahead of our, and consensus, estimates. The group’s growth strategy is on track with continued food innovation, 36 new sites (and some record-breaking sales) and an expanded regional management structure. Meanwhile, whilst we make no significant changes to our recently upgraded forecasts, current trading of 5% LFL sales growth in the last 11 weeks and seven new Lounge openings, is very encouraging.
We initiated on Loungers earlier this year, detailing why its profitable model and self-funded growth was undervalued (see “Loungers: Delivering self-funded growth “all day” long”). The 257-site group still has huge scope to grow towards its ambition of over 650 sites, driving 14% CAGR in Revenues, 15% CAGR in Adj. EBITDA and 21% CAGR in Adj. EPS FY24-FY27E. Whilst Loungers’ share price has rallied 35% since March, we believe this high growth is not reflected in the group’s valuation.
We reiterate our Fair Value of 370p (8.0x our calendar 2025 EV/Adj. EBITDA).
I hold LGRS. Was in Bristol last week and went to North street- site of one of the early Lounges. They have expanded next door- so now have 3 interconnected buildings. since I last went there. Seemed busy although we were lunching just down the road.
My morning smallcap tweet: I Could Have DCF'ed All Night
Sivota (LON:SIV) Haydale Graphene Industries (LON:HAYD) World Chess (LON:CHSS) Naked Wines (LON:WINE) Abingdon Health (LON:ABDX) Capita (LON:CPI) Water Intelligence (LON:WATR) Tpximpact Holdings (LON:TPX) Synectics (LON:SNX), Finseta (LON:FIN), Vistry (LON:VTY), Argentex (LON:AGFX), Begbies Traynor (LON:BEG), Celebrus Technologies (LON:CLBS), Kinovo (LON:KINO), Velocity Composites (LON:VEL)
◄Sivota (SIV)► Apester, its majority owned subsidiary in Israel, goes bust. The recovery value is not expected to be material. [SP=30 Cap=3m]
◄Haydale Graphene Industries (HAYD)► wins China distribution deal worth $4m min over 5 years. Also provides Haydale with exclusive access to their new partner's range of proprietary Carbide and Cermet products for the US and UK markets. [SP=0.3 Cap=5m]
◄World Chess (CHSS)► to host some chess game. [SP=4 Cap=28m]
◄Naked Wines (WINE)► new $60m secured credit line. Gives $25-30m increase in unconstrained liquidity based on current inventory levels. [SP=61.33 Cap=45m]
◄Abingdon Health (ABDX)► guides FY-June rev up 52%. Cash balance of £1.3m. Q4 C/F positive. Expects strong revenue growth in FY25. [SP=10.3 Cap=13m]
◄Crapita (CPI)► sells standalone software business (Capita One) for £200m on a cash-free, debt-free basis.That's 10x EBITDA. [SP=15.48 Cap=263m]
◄Water Intelligence (WATR)► buys Feakle Gas and Plumbing in Ireland for €2.32m structured as a four-year earnout. [SP=423.34 Cap=73m]
◄TPXimpact Holdings (TPX)► FY-Mar. Guides FY25 in line, H2 weighted due to election timing. [SP=41.21 Cap=38m]
◄Synectics (SNX)► H1-Mar. Guides FY more evenly weighted than in prior years and comfortably in line with market expectations of £52.9m rev and £3.5m adj pretax. [SP=185 Cap=33m]
In line: FIN, VTY, AGFX, BEG, CLBS, KINO, VEL
Synectics (LON:SNX) interim results out re-iterating the recent update. Looks positive with no negative comments. The interim dividend being re-instated should prove to be a positive for the share price today. The share price is not far off the recent highs so hopefully it may break above and create a new high. For me this company has turned into a longer term hold with revenues likely to continue to steadily rise over the next few years with growth looking positive coming from its many different division. All in all it looks good though it’s not likely to light up the sky, it looks to be a good steady burner GARP share. The interim dividend return should be a positive factor.
I hold Synectics (LON:SNX) too. No bank debt and sector tailwinds (security) bode well. Cracking chart, hoping we see a break of the ascending triangle shortly.
Synectics (LON:SNX) I hold too. When a company has a weaker H1 it leaves people with a higher risk of a profit warning later in the year. So in this case, I’d like to think with the strong H1 that there is an increased chance of upgrades in the months ahead. Here’s hoping !
I agree Synectics (LON:SNX) is looking good to hold. I would not be surprised at all for further upgrades this year from new contract wins. Nothing new in the broker notes which are very positive. Good cash position.
Would I buy at the current share price? - No, but that is purely because it is not the strategy I use and I find it difficult, psychology wise, to buy a share near the top. But this has been mention on stockopedia several times by Ed, Paul and Graham regarding other stocks where buying a stock on a high that is on a growth is often a very good strategy. Games Workshop (LON:GAW) comes to mind here and I see Synectics (LON:SNX) in the same category.
It is clear further growth is possible here, and from a number of different areas within the company.
The positives I see are the cash position, low PE and PEG and despite continual higher costs worldwide the company has done well lowering their expenses and keeping a good control on their finanaces.
The negatives I see would be if new contracts do not emerge and growth then does not continue. But as I have said, new contracts could come from several different areas and I do see this happening. The other negative is the low share count of just 17m shares. This has stayed the same for quite a few years now which is good as it show the company does not dilute the shares and it's cash position gives no indication that a dilution is likely to even happen. The low share count though would lead to higher volatility, both ways, and could make it difficult to sell and at a wider spread, which would make it a share you would not want to hold too large a holding in.
So while I would not buy personally at this price, I am more than happy to run this stock until the day I see a negative report out. And having a low average share price, any small percentage increase from here on is actually almost double that for me on my original investment.
Hi GMT
Synectics (LON:SNX) update looks in line with their last TU as you say. Interested in your comment that you wouldn't buy now. What do you think it's worth now and at year end?
My take for what it's worth and probably over optimistic would be 15x this year's EPS, or 10x next, so £2.40. As we get to their Nov year end I'd suggest worth 12x next year's EPS so £2.90-£3.
Increasing revs, pbt and eps with forward PEG less than 0.5 and growing net cash pre-IFRS 16. Order book continues to edge up with hints that some channels have been constrained by budgetary issues suggests to me that there is underlying, pent up demand. Bodes well?
I only bought in recently and agree the spread isn't very friendly.
£2.40 is inline with the broker who have a target of £2.30-£2.80.
Going with the thesis of running your winners I see no reason to sell until I do see a reason. If it did do a spike up to previous high of £2.52 then I would certainly re-evaluate the share and consider selling, with a possible buying back at a lower price.