Small Cap Value Report (Wed 11 Apr 2018) - GMD, AIR, BLV, NXR, SRT

Good morning, it's Paul here!
I'm up early today, to finish off the unfinished sections from yesterday. There seems to be so much going on at the moment, which sometimes distracts me from the task in hand here.
Here are a couple of interesting situations which I've been immersed in recently, GAME Digital (LON:GMD) , and Air Partner (LON:AIR);
GAME Digital (LON:GMD)
Share price: 38.7p (up 7.6% yesterday, at market close)
No. shares: 172.9m
Market cap: £66.9m
(at the time of writing, I hold a long position in this share)
Takeover bid speculation
NB. This is speculation on my part, but the reported trades yesterday do seem to suggest something might be going on.
I monitor all positions in my portfolio pretty much in real time, and when there's unusually large volume traded, I sit up and take notice. This can occasionally be a precursor to a takeover bid, if a potential acquirer is buying stock in the market. The trouble is, we don't know who is buying or selling, until the "holding in company" RNS(s) come out, day(s) later.
Sometimes though, very large volume goes through, and you can work out who is selling (but not necessarily who is buying).
In this case, with Game Digital, I noticed traded volume of over 60m shares early yesterday afternoon. Bear in mind that a more typical daily volume for this share is under 1m shares, so something unusual seems to be happening.
I got my broker to email me over the list of >3% shareholders, from his Bloomberg terminal, as I couldn't readily find that information on GMD's own website. Next, I looked at the reported trades for GMD yesterday (courtesy of MoneyAM), and noticed this block of very large trades;
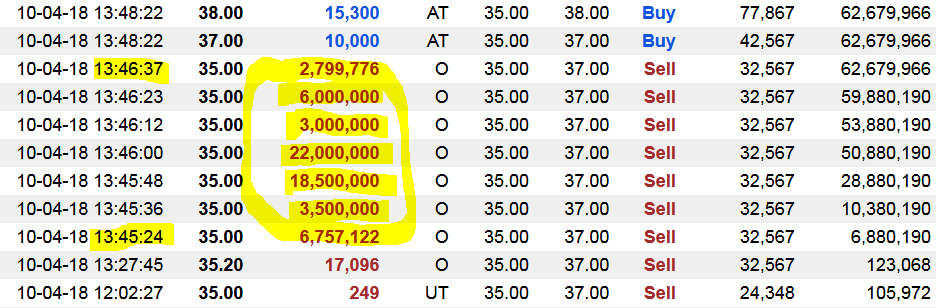
The "buy" or "sell" indicator is meaningless, as by definition every trade in the market has to have both a buyer & a seller, otherwise the shares wouldn't change hands at all.
The trades I have highlighted above stand out like a sore thumb, because they are;
- very large
- at the same price of 35p
- bunched together, happening a few seconds apart, so are very likely to be the same seller (not necessarily the same buyer though)
Adding together the highlighted items, comes to 62,556,898 shares. So who is the seller?
There are 2 really big shareholders in GMD, namely;
- Duodi Investments SARL: 63,179,898 shares (36.5% of the company), and
- Sports Direct International: 44,000,000 shares (25.44% of the company)
So logically, the seller can only be Duodi Investments. We already knew (from reduced holding RNSs) that Duodi was selling, and that I think was probably the main reason that the share price had been very weak in Jan-Mar 2018.
Interestingly, if you deduct the 62,556,898 large trades from Duodi's holding of 63,179,898 shares, then the difference is a round number - 623,000. That suggests to me that the transactions are almost certainly linked to Duodi. There's no other shareholder with enough shares to have sold 62.557m shares, so it has to be Duodi.
Some quick googling shows that Duodi held the shares for Elliott Advisors, a hedge fund which originally owned GMD and floated it in 2014. It has been suggested in the press that Elliott is raising cash to fund its imminent acquisition of Waterstones, which is expected to complete later this month.
Now the interesting part. Who is the buyer of Duodi's stake? My money is guessing that it could be Sports Direct. There is an increasingly close relationship between GMD and Sports Direct. Not only does SD already own 25.44% of GMD, but it recently announced a joint venture to open new "Belong" format gaming shops within SD stores. This is such a close relationship now, that the logical next step would be for SD to buy out GMD completely. It also makes commercial sense, as the cost could be financed from GMD's own cash pile. Mike Ashley of SD has a long history of deals like this, so again the history fits my theory very well.
Therefore, putting 2 and 2 together, and hopefully arriving at 4, I think a takeover bid for GMD could be imminent. With the possible buyer being Sports Direct. It all seems to fit together, although I should emphasise that this is guesswork on my part - I do not have any inside information. If I did, I would keep schtum, because that's supposed to be the whole point of inside information - you don't disclose it to anyone.
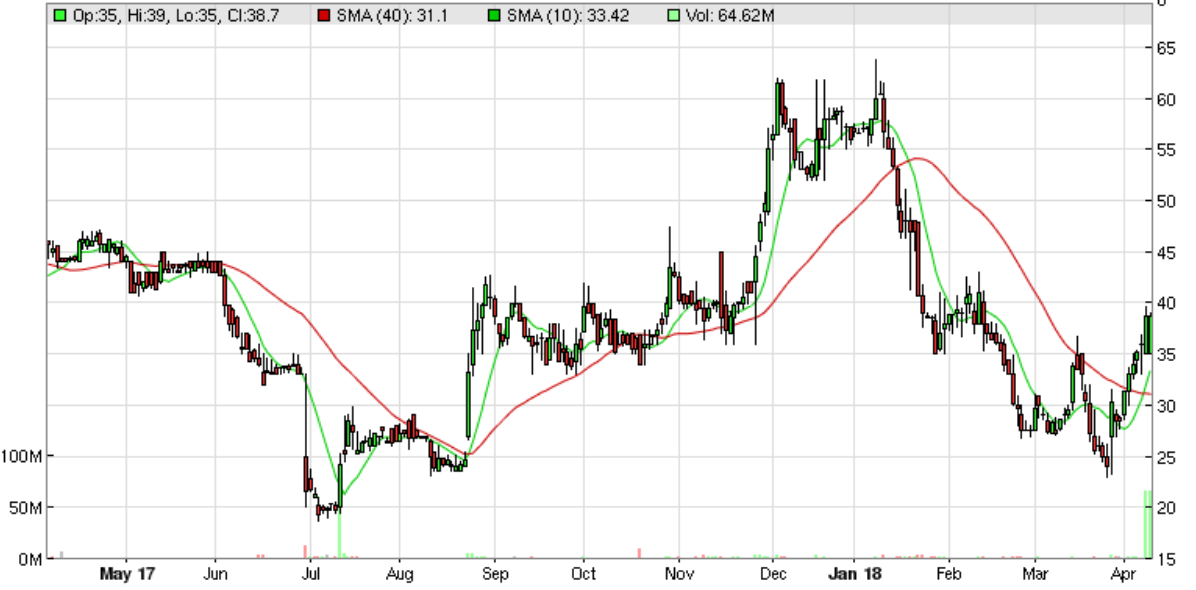
The burning question is, if I'm right that GMD is now likely to be bought by SD, what price are they likely to pay? It's got to be 35p minimum, as a bid can't be below the market price paid for shares. The share price rose strongly yesterday, and bulletin board activity shows that plenty of other people have spotted the large trades, and joined up the dots that it must be Duodi selling.
I take the view that, at 39p, the downside scenario would be a bid at 35p, so I'm only risking 4p by buying/holding at the current price. My feeling (and again this is guesswork) is that a takeover bid between 50-80p is most likely. It depends what level the Board at GMD can negotiate with what is probably now its controlling shareholder i.e. Sports Direct.
It will be very interesting to see how this situation pans out. There's obvious value in GMD, because c.80% of its shop leases expire or can be broken this year. Therefore it has a unique opportunity to radically change its store portfolio, and reduce costs. The new Belong format has shown in trials that it has an excellent 16-month payback period on average, so should make a good roll-out. Plus GMD has a fantastic balance sheet, stuffed with cash. The period end cash balances are probably seasonal peaks, but even so, it has a strong net working capital position.
Let's hope GMD shareholders are in for a bumper payday soon. My portfolio could certainly do with a boost, as Q1 this year has been shockingly bad (although it's really only giving back some over-sized profits from last year, so isn't a cause for alarm in my view).
EDIT: Gromley puts forward (comment no.3 below, in the comments section) an alternative (and credible-sounding) theory. He reckons that the Duodi holding at GMD might have been broken up & placed with various as yet unknown institutions. That's a persuasive argument, as the holding was broken up into several trades, which might have been finding homes with various buyers. No doubt we'll find out soon whether my takeover theory, or Gromley's placing theory is correct. What we can agree on is that the seller has been cleared, one way or another.
End of edit
There are some very interesting special situations in retailing right now. The carnage in the sector generally has thrown up some interesting bargains, but also plenty of value traps to avoid - e.g. Mothercare (LON:MTC) , Debenhams (LON:DEB) , Carpetright (LON:CPR) , and plenty of others.
Amazingly, looking at my own portfolio, 9 out of 10 of my largest personal holdings are retail/hospitality special situations, namely (in size order);
£RBG (203p cash bid from Stonegate in Jul 2017, rejected as too low by RBG shareholders. We can now buy in the market at 145p - doesn't make sense! A self-funding roll-out, with good pipeline of low rented new sites. Virtually no debt, and paying a decent divi)
£NXT (forward PER of 11 for the best fashion retail business in the UK. Online now generates more profit than stores. Strong cash generation. Outlook improving)
£FCCN (excellent recent disposal of Toast boosts cash to about half mkt cap. Moving into profit this year, as loss-making sites close. Wholesale & licensing doing well & valuable. Company now "in play" as founder likely to sell in foreseeable future
£GMD (as above
£BWNG (dirt-cheap internet retailer. Excellent divi yield)
Sosandar (LON:SOS) (highly speculative, early stage)
Gear4Music - excellent international growth. Not cheap, but is rapidly becoming a significant player in its niche. Great entrepreneurial management, with big stake.
Airea (LON:AIEA) - company also in play. Pension fund is big, but now fully funded. Closure of heavily loss-making carpet division will leave a highly profitable commercial flooring business. J Halstead is considering a bid. Big special divi imminent.
Superdry (LON:SDRY) - a quality international fashion growth business. Looks cheap after recent sell-off, but I won't be surprised if it announces soft current trading.
Portmeirion (LON:PMP) - good quality pottery business. Trading well. Nice balance sheet. Good value.
So my portfolio has a huge concentration on consumer-related special situations, I didn't realise it was quite this concentrated. A little further down my portfolio list, I also hold;
Best Of The Best (LON:BOTB) - recent sell-off seems overdone, and Directors have been hoovering up recent sells. Good long term potential, but growth not as aggressive as it could be.
Headlam (LON:HEAD) - good quality carpet distributor, with lovely balance sheet, and looks very good value. Nice divis.
Boohoo.Com (LON:BOO) - I bought back in recently, but am worried that growth might disappoint, so only a smallish position right now.
Angling Direct (LON:ANG) - looks a good niche growth business. Buying small competitors cheaply, as well as online growth.
That's probably enough share ideas to be going on with. As always, I'm only giving an opinion on those shares, not recommending them. It's none of my business what shares you put in your own portfolios, that's entirely up to you. Doing your own research is what it's all about.
I do wonder if my concentration on consumer-related special situations is far too much? I'll give that some more thought. However, my reading of things is that the outlook for the consumer is beginning to improve, so that seems the logical place to look for bargains, given how bombed-out the sector is. It's also fairly easy to spot & avoid the banana skins (famous last words!)
Belvoir Lettings (LON:BLV)
Share price: 102.5p (unchanged yesterday)
No. shares: 34.9m
Market cap: 35.8m
(at the time of writing, I hold a long position in this share)
Preliminary results - for the year ended 31 Dec 2017.
... the UK's largest property franchise group
These results look pretty good to me.
Adjusted EPS of 11.3p (versus Stockopedia forecast of 10.5p) - looks like an earnings beat.
PER of 9.1, based on that 11.3p adj EPS
Total divis in line with forecast, up slightly at 6.9p (vs. 6.8p last year) - a great yield of 6.7%
Revenues up, but costs down, drove a big increase in profitability.
Weak balance sheet - NTAV is negative, at -£7.0m
My opinion - I like the profit growth, and the excellent yield. However, for me the weak balance sheet deters me from buying any more shares in this. I try to always either avoid companies with weak balance sheets, or only take small positions in them (as in this case).
Another issue is that the Government action to abolish lettings fees could harm future profits. I didn't find sufficient reassurance in the narrative to find comfort on this problem.
On balance then, I've decided to retain a modest position, for the divis, but decline to buy more shares for now.
Air Partner (LON:AIR)
Share price: 87.1p (up 17.7% today, at 09:16)
No. shares: 52.2m
Market cap: 45.5m
(at the time of writing, I hold a long position in this share)
Further update on accounting review
What an interesting situation this has been so far. After the recent Conviviality collapse, I think investors are (rightly) taking an extremely dim view of any share where the bean counters can't actually count. The initial announcement can be the thin end of the wedge, as I discovered to my cost with Conviviality. So catching the falling knife can be a big mistake, if undisclosed additional problems then begin to emerge.
I'm just re-reading my notes from 3 Apr 2018, when the accounting problems were first disclosed to the market. The situation looked very concerning, but not life threatening. For that reason, I picked up a little long position in the company yesterday, with incomplete information, as a bit of a punt. That was a stroke of luck, as today's update is generally reassuring, triggering an 18% rebound in the share price so far today. Key points;
- PWC & Rosenblatt solicitors have been providing independent support to the company's review - no doubt at a 6-figure cost, I imagine.
- Review is making "good progress", and is ongoing.
- Total cumulative impact (of presumably over-stated profits) is believed to be under £4m - not much more than the previously mentioned estimate of £3.3m.
- Results for y/e 31 Jan 2018 will be pushed back to 31 May 2018, just over a month late.
- Distributable reserves are sufficient to continue paying dividends.
- Intention to declare a 3.8p final dividend - this is a strong message of confidence, in my view. Although it's still subject to completion of the audit.
- Policy on dividend cover of 1.5 to 2.0 times underlying EPS is reaffirmed.
- Underlying PBT of £6.4m for y/e 31 Jan 2018 is also reaffirmed (excluding the costs of this review). Accounting corrections will go through as prior year adjustments.
- No customers, operators, or suppliers have been adversely affected.
- The company won't comment on rumours or speculation, but will update the market via RNS. Good - that's the right thing to do.
My opinion - I'm reassured by this update. We're still not in the clear, but I'd say that the risk of a meltdown has probably receded now, enough to probably make the shares investable again, for more risk tolerant people like myself.
For me, the crucial thing is that the balance sheet here is pretty solid. Yes, a lot of the cash pile is client money, but there's no reason to suspect clients would want to withdraw that money - as AIR's overall solvency looks fine.
Personally I only tend to make punts like this fairly small, so that if it does all go disastrously wrong, then the losses aren't too bad. The update today sounds reassuring to me, so I've topped up with a few more - but still only a smallish overall position.
I think the company should fire its FD. There's just no excuse for leaving large balance sheet accounts unreconciled for over 4 years. That's just plain sloppy. In my days as an FD for a larger company/group, I had every significant balance sheet account reconciled to the penny, at every month's management accounts. You have to do that, to maintain proper control, and to ensure there are no nasty surprises. All the debtor & creditor accounts should be controlled via spreadsheets, detailing precisely what is in there, and each one checked carefully every month. My mind simply boggles at the idea that AIR's FD just didn't know what was in the largest balance sheet account, deferred income.
Norcros (LON:NXR)
Share price: 182.5p (down 1.75% today, at 12:16)
No. shares: 80.14m
Market cap: £146.3m
Norcros calls itself the market leading supplier of innovative branded showers, shower enclosures and trays, taps, bathroom accessories, tiles and adhesives...
Today's update is for the year ended 31 Mar 2018.
Group underlying operating profit1 for the year is expected to be in line with the Board's expectations.
- There's more detail given, which I won't regurgitate here. Just a few key points;
- More restructuring needed at Johnson Tiles - exceptional cost of £2.1m, to deliver annualised savings of £2m p.a.
- Net debt of £48m is up sharply from prior year's £23.2m, due to acquisitions. This seems to be getting a bit high to me, but the company says it's only 1.3x EBITDA, which sounds reasonable.
- Merlyn (largest & most recent acquisition) is performing strongly.
- Challenging market conditions, but "well placed to make further progress".
My opinion - it's dirt cheap on a forward PER basis, of only 5.9.
Nothing is said today about the huge pension fund. If the pension deficit reduces, then that could trigger a re-rating, perhaps?
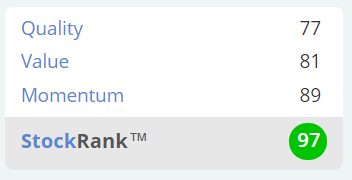
Management seem to be doing a good job of balancing growth by acquisitions, pension deficit funding, and paying divis (the yield is about 4.5% currently). StockRank is 97.
I like the company, and thought management seemed on the ball when I met them last year. What's going to trigger a re-rating though? That's the ongoing problem with this share - I think there are probably lots of stale bulls, who would like to sell, but can't due to lack of liquidity. So, a bit like Mission Marketing (LON:TMMG) yesterday, it just seems one of those shares that is always cheap, and trades sideways. Maybe that could change one day, I don't know.
Stockopedia really likes it - "Super Stock" style, and very high StockRank. Maybe this share might suit very patient investors, who might eventually be rewarded with a re-rating;
SRT Marine Systems (LON:SRT)
Share price: 24.5p (up 15.3% today, at 12:47)
No. shares: 127.7m
Market cap: £31.3m
Year end trading update - for the y/e 31 Mar 2018.
SRT, the global provider of maritime tracking, monitoring and management systems...
Subject to audit, for the year ended 31 March 2018 the company expects to report a 22% year on year increase in revenues to £13.5 million, and profit before tax and exceptional items of £1.3 million which is broadly in line with market expectations.
Stockopedia shows £15.0m forecast revenues. So I'm not quite sure how a £13.5m result can produce profits broadly in line. Maybe there are some adjusting factors? I'll have to look at the full figures when they come out.
At least the company is profitable though, and has delivered a reasonable increase on last year's revenues, although profit looks to be similar to last year.
My opinion - I've mostly lost interest in this company, because it's been promising a huge pipeline of work, and bulging order books for years now. Yet the breakthrough profits still haven't happened.
I hope to add sections on Universe (LON:UNG) (potential hit from Conviviality) and Epwin (LON:EPWN) later, but am having a rest first. So more sections may, or may not happen.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Series of RNS just out confirming Duodi have completely exited from GAME Digital (LON:GMD) and shares have been picked up by IIs in batches. Milton have taken the largest 13% chunk.
https://www.investegate.co.uk/game-digital-plc--gmd-/rns/holding-s--in-company/201804121622397798K/
Gus.
(Edit: Oops - sorry just read Willhampson post on another thread with same update).
Enjoyed reading this report with regards to GAME Digital (LON:GMD) really useful insight with interpreting the volume of trades. I personally think there is a lot to be said about volume, but you don't hear about it very much.
its good for short term entries and exits anyway.
if any one can recommend and good books on the subject, that would be very much appreciated.
Great write up today Paul, thanks - I was particularly taken by that last paragraph on balance sheet recs, I too have seen both sides as a FC when I was working, one was managed perfectly as you say on a spreadsheet recc'ing each balance sheet, a very good company, the other the intention was there but it just took one unknowledgeable person to just chuck unknown items into sundry debtors/creditors, suspense etc without narrative and leave it to the next person to sort out to wreck a companies accounts, I know which one I preferred.....
Some very interesting write ups, none of which I hold but garner an interest lol, I look forward with interest to your write ups on Epwin (LON:EPWN) and Universe (LON:UNG) as they are both shares I am watching keenly for an entry
Superb coverage of events. Thanks . Makes my task of trying to manage my portfolio so much easier and yes more enjoyable.
BB
Paul,
Just wanted to say thanks for the excellent coverage and insights provided in yesterdays and todays updates - Fantastic stuff that I know takes a huge amount of time.
The first drink's on me at Mello!
I know it’s rather blue sky, but back on October 9 Graham commented on CPX, a small developer of super capacitors (no, I don’t either). Anyway just flagging up interesting rns today in which new prismatic mini capacitor is announced...
“The Company will develop its 3V technology first in thin prismatic form to meet demand for small, inexpensive, energy-efficient power solutions for thin wearables, key FOBs and other IoT devices. CAP-XX plans to then integrate the 3V technology into its larger prismatic supercapacitors, automotive modules and other products for high-energy, high-power applications.
The new 3V supercapacitors will eliminate the cost and inefficiencies of the low-dropout (LDO) voltage regulator or buck converter often required to step the voltage down to work with the industry's existing 2.7V-rated thin, prismatic super capacitors”.
Looks interesting.
A snippet of news to give the (possible) downside to online retailers (albeit one in private ownership):
http://www.bbc.co.uk/news/business-43727118
Headline is just that, and only there to attention-grab.
"Littlewoods owner Shop Direct puts 2,000 jobs at risk"
Paul,
Have you decided not to comment on Card Factory?
Card Factory (LON:CARD). Reasonably encouraging commentary in the The Times today, when I was expecting the same old dirge, about greeting cards being analogue in a digital world.
Seems young people like cards in the UK as well, according to their interpretation of Card's analysis.
Don't think Paul is going to being commenting on it, is my take.
The Special dividend is down from 15p, but still in the 5-10p range, if everything remains as is or better, giving a healthy yield. Counters to overhead increases are potential, because of easing of dollar headwinds, and also through an efficiency cost review, though not expecting profit growth in ye '19, I think. Sales were up, however, which shows the model is still generally working.
Steady as she goes, for the time being. Market seems to like the outlook so far. As mentioned by earlier commentators debt is up, but would imagine its ratio to EBITDA is still within range, and it would have been easy to not pay any special if they were worried. So it seems trim and review is the way forward, which seems fairly sensible.
Thanks very much Trident, for your excellent post.
Regards,
Clive
on EPWIN pretty good performance given input cost inflation due to FX and major issues with 2 biggest customers. if no other headaches FY18 will see divi 8% 2 x covered by EPS and cash. net debt down to 0.5x. I think management doing a good job in a tough market.
A couple of thoughts on Superdry (£SPDY). I have recently started selling down a position in Joules (£JOUL) which has similar characteristics - strong growth driven by growing online, wholesale and international growth. Joules trades on a 24x PE vs 14x for Superdry. Clearly a big valuation gap for businesses with a similar profile.
I have two concern with Superdry.
1) High levels of stock - at HY they were carrying £200m of stock on forward sales of £850m = 85 stock days. That seems high to me for a clothes retailer and I wonder if they are building up stock they will have to write down. Last year write downs were minimal. Does anyone have an idea what is normal in the industry?
2) Capex is high - £56m last year on EBIT of £87m and the dividend was funded from cash reserves. Capex was running at a similar rate at H1 this year and cash continues to fall.
Any views on these concerns much appreciated as am considering opening a position.
Tristan
I currently hold Superdry (LON:SDRY), bought in on the last price fall, although they've fallen a further 12% since I bought them! Timing's clearly not my strong point.
A quick read of the last accounts give an overview of Capex and working capital.
The number of stores, both owner and franchised / licensed have increased by 17.7%.
Capex spending on the Store portfolio, £21.1m, infrastructure £8.1m, plus cash outflow (capital additions and intangibles) of £26.8m. Total Capex of £56m. The reasoning is as follows:
............capital contributions to support franchise growth globally and store refurbishment investment to introduce the brand's Next Generation store concept. Infrastructure investment to enhance our Ecommerce customer experience and strengthen our central capability and facilitate our future planned growth also continued. The most significant investments within this related to ongoing introduction of multi-channel capability to our distribution centres located in Europe and North America and the implementation of a new OMS within Ecommerce.
Full year guidance for capital expenditure remains at between £60m and £70m.
Capex this year is not too dissimilar to last year and has been increasing over the last few years due to the business expanding. The clear knock on effect is lower FCF per share in the short term, but hopefully increased ROCE (currently around 21%) thereafter.
*
Total retail sales Q1 17 - Q1 18 are YOY up 15.6% (although LFL down) with average floor space increasing 16%.
Inventories have thus increased from £160.5m to £200m or 24.6%, with total working capital increasing by 33.5%.
Again, the reasoning is -
The increase of 33.5% partly reflects the impact of currency and planned acceleration of seasonal inventories to ensure high levels of product availability in the key trading period. The remaining inventory growth is broadly in line with the revenue growth of the Group.
.........Trade and similar receivables remained well managed with a reduction in debtor days since the previous year.Trade and similar payables increased by 22.0% to £151.5m (1H17: £124.2m). This growth, which is marginally lower than the corresponding growth in inventory, reflects the timing of seasonal deliveries, outlined above, and the progressive movement of suppliers to standard trading terms.
I'm more than happy to hold this stock (unless something fundamentally changes to the detriment of the business) as my time frame is medium term at least.
I remember when Anthony Bolton sold his stake in ITV to Sky and everyone got excited thinking a bid was in the offing. He sold it on the proviso of no bid happening otherwise he wouldn't have sold at the price he did. I would be baffled if a sophisticated investor sold such a controlling stake for nil premium if a takeover was around the corner, they would have been kingmaker in any deal. It'll be placed with various institutions. Ashley hardly ever, ever buys businesses at premiums. He prefers to pick them up out of admin. But fingers crossed something happens to for all GMD holders.
On the other hand the remaining GAME Digital (LON:GMD) shares were arguably loose change to Elliott, given that they sold the other 60+% of the company at £2.00 & £2.60 per share some time ago.
Next (LON:NXT) vs ASOS (LON:ASC) - I also prefer Next (LON:NXT) but it is concentrated on UK vs ASOS (LON:ASC). IF the UK were to go into deep recession then it would be vulnerable (to topline sales and margin reduction, not solvency). ASOS (LON:ASC) has established a bigger proportion of international sales and has laid a groundwork for expansion - although I personally see its 'fashion' sense as more likely to fade than than the more boring, slightly older Next (LON:NXT) typical item. Next is safe middle class, middle age fashion, steadily going online......which is actually the heart of the market in the UK at least. Big shakeout in UK clothes retailer likely in next 2 years and Next (LON:NXT) will be standing tall. ASOS (LON:ASC) is something everywhere but nowhere irreplaceable.
On Next (LON:NXT) vs N Brown (LON:BWNG) - personally, I like Next (LON:NXT) best but I think the market has been over harsh on N Brown (LON:BWNG) although it got lucky at the interims when the excellent progress on the credit book bailed out the balance business (gross margins margins dropped). The fact it makes so much on the credit side is a strength so long as it keeps its customers happy and buying product.
N Brown (LON:BWNG) is now v. cheap for an 80% internet business with several well established brands that has recently completed a transformation to be fully digital and a major simplification of brands. Critical is whether
i) JD Williams relaunch as a Lifestore kicks on (I worry as they just replaced the Agency who had launched the idea after only 1 year)
ii) if Simply Be can fight off all the new entrants and increased focus on clothes for 'curvy' women.
iii) that they keep up customer service scores. This is my big worry as recent Feefo/Trustpilot ratings have been lamentable. I hope this is short term cock up/transition not a consequence of the all new digital systems!
With the US finally starting to motor and the UK business much more focused, it should really start to motor in next couple of years.
Disclosure I own Next (LON:NXT) (biggest holding) and also hold £BWNG
Probably too late for today, but I would suggest that Ergomed (ERGO) is moving towards Paul & Graham's universes as it announced today that its own biotech and pharmaceutical drug development activities are going to be given less emphasis in the future as it concentrates on its rapidly growing business providing services to drug developers (which of course is a much more predictable type of business). I think some may have overlooked this company in the past as it was an unusual mixture of speculative drug development projects and outsourcing services for clinical development. My opinion is that the current rating is mostly supported by the core clinical development services and there is little value assigned to the drug development projects and I would be interested to hear any comments from a financial perspective from Paul or Graham.
The volume for Game Digital was way above the average volume traded for the stock - so forgive me if this is a stupid question but why didn't that volume of trades precipitate a larger price change?
They weren't sold on the open market, they were placed at a price agreed between the various parties. Therefore the trades had no impact on the price at all.
indeed, off-exchange transactions though I thought MiFID II was going to put the kibosh on those ... there are volume rules I think which trigger an auction
Re Boohoo.Com (LON:BOO), Next (LON:NXT) and ASOS (LON:ASC), there is also QUIZ (LON:QUIZ) reporting tomorrow. They are doing shed loads of marketing (in London at least) so I am interested in this as a potential GARP share given its current internet revenue is low so there is a lot of room for growth. Have written more here: https://www.stockopedia.com/content/quiz-clothing-340023/ (I hold a small amount which may increase or decrease tomorrow!)
if GAME Digital (LON:GMD) finishes up around these levels it will at least have to comment on the movements/speculation
Hi Paul.
Regarding £LON:AIR.
The auditors should be in the firing line, as well as the FD. If deferred income is a large balance sheet account, they should be on like a shot, to understand that any mechanisms underpinning are sound, as there are obvious revenue recognition potholes surrounding it.
Regarding £LON:AIR. I see the Auditors are Deloittes. I wonder what the Debtors section of their audit programme looks like or whether it exists at all. This is basic stuff to anybody who was trained in auditing back in the day. And this isn't just one year.
Re: £LON:AIR.
Today there is a lot of sample testing for audit purposes, and depending on the sample size, it is possible to see that could become quite a complacent process, if the allocation of deferred income to incorrect periods as a core principle was going adrift.
Re: £LON:AIR.
Quite but then that just dilutes the value of an audit. Having same SSA for past 4 years may be significant. People are too interested in systems, risks and polices at the expense of a hard examination of the composition of the balance items. Shareholders in general deserve far more than they are getting. Never mind that in this case no creditors, debtors or employees were adversely affected, allegedly, the poor shareholders were!
GAME Digital (LON:GMD)
@ Paul., I pay for ShareScope Pro which is super for trading: this has SharePad free access added as a bolt-on which is a nice graphical compliment to the more technical ShareScope : the DD coverage in SharePad is very useful and tracks changes in major DDs and city holdings. I tend to use these changes to indicate major trends in ownership . I also set volume change alerts in ShareScope which can track major intraday changes in target names using their datamining functionality
I'm sure you are aware of it , but worth flagging as part of the arsenal: it is technical to learn but invaluable once mastered (that's only took me about 8 years mind)
I would add Bonmarche Holdings (LON:BON) and UP Global Sourcing Holdings (LON:UPGS) to Paul's list of downbeaten retail / consumer shares.
Bonmarche Holdings (LON:BON) - Has cash with a EV PE of below 4x. Would benefit from higher interest rates due to cash and age of customers. Stores well invested. "the flexibility of leases means...we are in a position to alter the profile of our store estate relatively quickly".
UP Global Sourcing Holdings (LON:UPGS) - Drop in profits is quite likely to be temporary due to destocking (etc), but still a forward PE of 6.25. Large director buys. Some debt but appears manageable, falling and with positive TNAV. (H1 Results due 30/4).
(After the Conviviality (LON:CVR) experience I sold out of Connect (LON:CNCT), but they may also be due a bounce)
You could add:
Topps Tiles (LON:TPT), Moss Bros (LON:MOSB), Shoe Zone (LON:SHOE), Footasylum (LON:FOOT), Dunelm (LON:DNLM). Even JD Sports Fashion (LON:JD.) is down about 22%.
Hi leoleo,
I would add Bonmarche Holdings (LON:BON) and UP Global Sourcing Holdings (LON:UPGS) to Paul's list of downbeaten retail / consumer shares.
And I'll take them straight back off again!! ;-)
I can't see any reason to hold either, as fairly low quality businesses. Why buy junk, when you can buy the best company in the sector, Next (LON:NXT) , for a fwd PER of 11?
Regards, Paul.
Paul,
I tend to agree with you here - which is why I'm puzzled by your N Brown (LON:BWNG) position. IIRC they make nearly all of their money from the financing arm, i.e. interest from customers who have bought on credit, rather from the actual clothes themselves. Surely Next (LON:NXT) the better bet here also - higher margins, better business, clear strategy and faultless shareholder communication?
How about adding SCS (LON:SCS) ? :)
Not particularly liked as we all know it sells down market sofas and it had 2008 financial accident but keeps on performing and producing huge amounts of cash. Focused strategy and experienced management. https://www.stockopedia.com/co... & https://www.stockopedia.com/co...
I bought UP Global Sourcing Holdings (LON:UPGS) on the fall. The mgt make me a bit nervous. In particular I think the FD is underpowered relative to CEO and may lack the ability to stand up to him. They've certainly made a mess of communication and returns since IPO. However, my hunch based on analysis (https://www.stockopedia.com/content/oops-upgs-ide-your-head-327743/) is that the return potential of business is high and the quality of their business model is quite decent. Earnings will be volatile as they do not tie up with their retailers but that gives them greater margin over time and more flexibility.
My hunch is that they got caught out badly with some "channel stuffing" with rapid store growth from their retailer customers as well as a consumer downturn effect so their earnings are in a severe down...but the bounce back could be truly spectacular. Of course, their business model is not well understood so they will get further hammered for earnings disappointments and will need to do some hard persuading to the positive side.
I have tried to speak to the company directly and they were awful about contact. Immaturity? Hubris? Weak FD? Dodgy? Its a worry...but my (sorry to use word again) hunch is they are just a bit stupid and not moved to a public market mentality...plus a CEO who built it, views it as his baby and doesn't have a good view of market punters (or advisors)
I'm uncomfortable, down near 10% from purchase and understand I'm a bit in the dark and need my hunches proved out. I'd like mgt to do a better job communicating where they are at and how their model works....but I do think I have a real option here that could be many multiples (inc big future divis) what I paid for it.
At your own risk. My more experienced UK stock picker mate (a pro, not usually micro cap though) thinks its a bit of a dodgy company based on his quick read (self dealing).
lavinit,
Yes, both SCS (LON:SCS) and Bonmarche Holdings (LON:BON) have considerable surplus of current assets over liabilities in the form of cash. However according to their 2017 annual reports, the vast majority of SCS's operating leases are 5 years plus (a total liability far exceeding their market cap), whereas Bonmarche has a fair few within one year and the vast majority less than 5 years (total liability somewhat less than market cap). Plus Bonmarche Holdings (LON:BON) is much cheaper on a P/E basis and (as a homeowner) I prefer to avoid too much housing market exposure.
Of course, I read your article before buying UP Global Sourcing Holdings (LON:UPGS) , and very helpful it was too - thank you! The callable borrowings was the thing that really concerned me, but it appears to be being paid off (even with the excessive dividend) and I was reassured by the current ratio and positive NTAV.
Hi Leo
I see the attraction in Bonmarche Holdings (LON:BON) and thought about it. It’s probably better value than SCS (LON:SCS) but my bias is that SCS has the clearer growth path and higher quality earnings. It can double earning thro it’s cash and then has organic capacity over a few years to open 30 new stores in targeted areas...so that’s 200% earnings growth without LFL top line. I think SCS is on a clear-ish path to this absent retail Armageddon. I also think SCS has a securer niche and for whatever reason others aren’t trying to take them on in the bargain basement and are aiming mid market and up. I too was concerned on leases. I beleive they overreached in their mega store opening circa 2005-2007 and did it with long leases. So being worked thro and I think manageable plus it’s part of why cash earning will keep outperforming accounting earnings driving value.
Bonmarche is a growth business :) ...oldies are still going to shop on high street. Plus I like that they have so many shops in less flash places. Cheap and sounds like cash flow to me if they have their product right. Of course they do have some competition, more so than SCS IMO.
I’ve spoken to CFO at SCS with detailed list of questions and feel really satisfied that they run business well. I’m not as on the case with Bonmarche partly as Sun Capital IPO’d both and still hold big stake in both that they want to exit soon. I don’t see a prob and think these were well executed IPOs but 1 of the 2 is enough for me. It may be you have the winning horse and I’ve not done my work!
I agree with your point on UP Global Sourcing Holdings (LON:UPGS)
Interesting market response from both Boohoo.Com (LON:BOO) and ASOS (LON:ASC) to the latter's inline interim results. BOO is currently down approx 5% reversing yesterday's gains and ASOS is down approx 8% with heavy volatility compounding recent falls.
ASOS emphasised today that they are in an investment phase and this seems likely to have spooked the market, but the same applies to BOO and neither have ever paid a dividend.
BOO continues to look much better value with a forward PE of approx 40 and recent 100% revenue growth vs ASOS with a PE of approx 60 and recent 25% revenue growth. Boohoo.Com (LON:BOO) 's margins are also intrinsically higher, although their recent price "investment" (i.e. cuts) make it difficult to see by how much.
ASOS also has more to lose in terms of rating and momentum and I remain bullish BOO (medium term) and bearish ASOS (short term).
(edited as tilda symbol meaning approximately had been replaced with what looked like a minus sign).
Hi leoleo,
I looked at the ASOS (LON:ASC) figures this morning, and thought they're deeply unimpressive, as usual. This business makes little profit, and recycles that into massive capex. Hence why the balance sheet has little NTAV, despite never having paid a dividend. Cashflow looks terrible, with most of its cash pile having been spent on capex & adverse working capital movements.
It is an H2-weighted business though, and a 4% EBIT margin for the full year guidance is reaffirmed - which is a poor margin for a business of that size.
The only surprise to me is that Asos shares are recovering after this morning's 11% sell-off.
On any rational basis, even being generous, I can't get to a valuation of more than £30-40 per share. Nowhere near the current £67 per share.
I've been waiting for years for the price of Asos to crash, but to no avail! I remain short - it's just not a very good business. Compare the massive free cashflow that Next generates, with basically close to zero that Asos has generated in its entire existence. Bonkers! Also note that Next (in which I have a long position) is transitioning well to online sales, where it now makes more profit than from its retail stores. PER of 11 for Next, or PER of 63 for Asos, when arguably Next has a better online business than Asos (much more profitable anyway), plus the stores thrown in for free.
Regards, Paul.
Boohoo.Com (LON:BOO) are only down 1% now according to my broker. When are Boohoo.Com (LON:BOO) next results due out?
Both Boohoo.Com (LON:BOO) and ASOS (LON:ASC) have recovered much of their losses. According to January's trading update:
"boohoo.com expects to report its results for the 12 months to 28 February 2018 on 25 April 2018."
Oops re £SPD!
Ignore
Re GAME Digital (LON:GMD) - reasonable to assume that this holding was, at some point during the placing process, offered to £SPD? If Secured Property Developments (OFEX:SPD) not the buyer then also reasonable to assume that Ashley doesn't want to bid for £GMD? Otherwise, he would have taken it.
I don't know if this has been posted already, but for anyone interested I see you can now vote in the Mello2018 Investor Awards for one's favourite online share blogger here.
You may recognise a couple of familiar names in the shortlist.
r.e. Belvoir Lettings (LON:BLV)
Total divis flat at 6.9p - great yield of 6.7%
a minor correction, Paul. The dividend was actually increased slightly, to 6.9p from 6.8p.
Another issue is that the Government action to abolish lettings fees could harm future profits. I didn't find sufficient reassurance in the narrative to find comfort on this problem
Agreed.
Asagi (long BLV)
Hi Asagi,
r.e. Belvoir Lettings (LON:BLV)
a minor correction, Paul. The dividend was actually increased slightly, to 6.9p from 6.8p.
Sorry, you're absolutely correct - thanks for pointing out - I shall correct the main article now.
I had jotted down on my notepad yesterday that the 6.9p divi was as forecast, but this morning when typing up the article I misread my own handwriting, thinking it said that the divi was flat against last year. Doh!
Apologies.
Regards, Paul.
Hi Paul,
The UK takeover rules state the following:
"When a person or group acquires interests in shares carrying 30% or more of the voting rights of a company, they must make a cash offer to all other shareholders at the highest price paid in the 12 months before the offer was announced (30% of the voting rights of a company is treated by the Code as the level at which effective control is obtained)."
hxxp://www.thetakeoverpanel.org.uk/th...
Therefore wouldn't any takeover bid for GMD have to be for at least 61.5p?
This is unless Sports Direct setup a SPV to acquire shares or some other proxy acquirer - and the purchase of controlling rights could be split up.
Then they would likely meet the part of the code that stipulates the acquirer should offer at a minimum at the same level as the highest price Sports Direct paid in the last 12 months.
Sports Direct acquired their stake on 12 July 2017 at around 24p (to my knowledge they have not bought or sold shares since)
GAME Digital (LON:GMD) Sports Direct would have to announce a mandatory offer 'if' they were the name that acquired the 36% of the shares. They have 28 days to do so following the purchase of the shares.
It it is not Sports Direct, but another name who acquired all the shares, same would apply for any purchase >30%.
GAME Digital (LON:GMD) would also have to issue a response to any takeover rumours.
Handy guide: https://www.slaughterandmay.com/media/39320/a-guide-to-takeovers-in-the-united-kingdom.pdf
Re GAME Digital (LON:GMD) Paul, as per your excellent analysis concluding the massive stake sale by Duodi, we can see all the sale trades going through... but there are no corresponding buy trades...? Why can't we see those?
Every trade has a buyer and a seller. Yes, sometimes these can be a sale to a "market maker" from a shareholder or the reverse.
But there is no way the "market makers" would take on over one third of the shares of a company (AIUI they usually try to have a broadly neutral book).
These were trades by one institution (Elliot) to other institutions (tbc), the fact that the price was at the bottom of the spread suggests that it was the seller who instigated the trade, although to be honest to be able to offload this volume of shares without going below the spread strikes me a being a very good deal by the seller. I would say these transactions were discussed and planned over many days and possibly Elliott convinced the buyers that the fact they were known sellers was depressing the market price.
Thanks Paul, you must be correct that the seller of GAME Digital (LON:GMD) can only be Elliot. Elliot has a reputation as one of the smartest of hedge funds, therefore they are unlikely to have been duped over on this trade - obviously they have been a seller for some time after gaining control of Game - presumably through buying the debt ahead of the previous restructuring.
I am sceptical that Sports Direct could have gone over 30%, without having had to announce it already. Going over 30% would trigger a mandatory bid and therefore the creation of a false market (if not confirmed), which the Takeover Panel is always keen to avoid. While Mrobiston (post 10) is correct that they have 28 days to launch a bid - this is to launch the bid - not to announce the crossing of the threshold.
GAME Digital (LON:GMD) Presumably it cannot be Sports Direct or a related party otherwise they would have to make a mandatory offer given the percentage of shares they would now hold (?)
My morning smallcap tweet:
Air Partner (LON:AIR), SRT Marine Systems (LON:SRT)
Air Partner (AIR) shenanigans update: total restatement will be <£4m. "The Board believes that no shareholder should be further disadvantaged by the impact of this matter... intends to recommend that the final dividend payable for the year will be 3.8p." Reiterates underlying pre-tax guidance of not less than £6.4m. Review ongoing.
SRT Marine Systems (SRT) guides FY rev up 22%, pre exceptional pretax £1.3m, broadly in line with market expectations. "These results reflect the excellent progress we have made across all our business operating segments." Well, as a holder, I ain't dancing yet.
Other news that may be of interest this morning is a trading update from Norcros (LON:NXR) , I sold out a few months ago (I think the price is up slightly since then) but I think you still hold?
Overall they report in line, but (perhaps because I still have my gloomy head on with regards UK retail) I note the passage on Johnson Tiles
I'm not sure off the top of my head how big Johnson is (other than being I think c. £50m of revenue), but the previous restructuring had roughly the same cost (£2.3m) and involved the loss of 90 jobs, so overall this looks quite chunky.Interested in any thoughts here.
Norcros (LON:NXR) trading update to day
Group underlying operating profit(1) for the year is expected to be in line
with the Board's expectations.
Group revenue for the year is expected to be in the region of £300m (2017:
£271.2m), 10.7% higher than the prior year on a reported basis, 8.7% higher
on a constant currency basis, and 4.4% higher on a constant currency like for
like basis.
The big news that could impact Norcross (LON:NXR) is the situation with the pension deficit which will only come out when the full results are disclosed. If the gap as closed and by a meaningful amount we could see a revaluation. I will hold until then
Hi Paul,
On the subject of GAME Digital (LON:GMD) I absolutely agree with you that it looks like Elliott / Duodi selling out their stake (not only could they use the cash for their Waterstones bid, I also understand they are rumoured to be involved in a potential rescue for Claire's).
It seems premature to me though to presume that to presume that Sports Direct might be the buyers.
The highlighted 7 transactions are lots ranging in size from 2% to 12% of the total shares in issue, to me that looks more like a "placing" across several institutions.
Obviously that's all speculation until we see the Holdings Notices come in (the Sports Direct IR team have alreadt been on RNS this morning to post a transaction in own shares notice pertaining to yesterday - I'm not sure if I'm stretching too far for conclusions if I wonder if they would have posted any other holding notices at the same time?).
Personally, I'm not sure I see the logic of SPD increasing stake and forcing a bid, but we will see.
Hi Gromley,
On GAME Digital (LON:GMD) you commented (no.3 above)
The highlighted 7 transactions are lots ranging in size from 2% to 12% of the total shares in issue, to me that looks more like a "placing" across several institutions.
That's a persuasive argument, you could well be right.
I've added a comment in the main article, referencing your alternative hypothesis! Maybe it's wishful thinking on my part that Sports Direct might bid for the whole company.
Thanks for your input!
Regards, Paul.
I think you have read the situation correctly, also the price at which the transaction is done is normally a good indicator of who initiated the deal, a discount to prevailing market price would imply the seller, and a premium would imply the buyer. That’s not to say that the clearing of an overhang, even at a discount can be positive for the share price. It’s also unlikely that anyone but a very naive shareholder will sell their stake to a potential bidder at a price significantly lower than a bid for the whole company shortly afterwards without conditions attached.
Hi Paul: That's some great analysis of GAME Digital (LON:GMD) and I wanted to express my thanks on the insights and also your commentary on the special situations. Plenty going on to keep us busy.
Thank you Paul for sharing. I really learn a great deal from your comments and others on this board. All the best.