Small Cap Value Report (Wed 11 July 2018) - BRBY, SWL, ORCH, SFE, BLTG, SOS

Good morning!
Football is the major story today. There's also quite a lot of stock market news:
- Swallowfield (LON:SWL) - trading update
- Orchard Funding (LON:ORCH) - application for bank licence
- Safestyle UK (LON:SFE) - trading update
- Blancco Technology (LON:BLTG) - trading update
- Sosandar (LON:SOS) - final results (this section written by Paul Scott)
10:30 AM: I have taken Alpha FX (LON:AFX) off the list, because it's an "in line with expectations" update. I've also taken Fishing Republic (LON:FISH) off the list, because its market cap is so small. Paul will be in touch soon with his thoughts on Sosandar (LON:SOS).
12:45 PM: Ditched a few more.
It's too big for this report, however one of my top holdings Burberry (LON:BRBY) released a Q1 trading statement that was in line with expectations.
Retail revenue was flat due to currency headwinds, or +3% at constant FX. "Comparable sales", which includes online sales and is measured at constant FX, was also +3%. There was no change to guidance, except that current exchange rates are more favourable. It remains on track for £100 million of cost savings.
The share price is down 4.5% as I type. Investors were evidently pricing in a little extra. There is also continued uncertainty to be faced as the company beds in a new Chief Creative Officer and responds to weak trading in the UK, Europe and the Middle East.
Personally, I continue to hold. These shares have been in my portfolio since January 2016, and I would like to keep them for the foreseeable future.
Swallowfield (LON:SWL)
- Share price: 275p (-13%)
- No. of shares: 17 million
- Market cap: £47 million
This is of particular interest to me, as I own shares in the similar company Creightons (LON:CRL). Both are engaged in the manufacture of personal care products, and manage their own brands.
Today's full-year update is broadly in line, i.e. a slight miss.
Swallowfield's two divisions, Brands and Contract Manufacturing, performed very differently this year.
Profitability in Brands is significantly ahead of expectations, reporting strong momentum, rising margins and the successful integration of a men's hair styling brand.
Revenue and operating margins in Contract Manufacturing, on the other hand, are both down compared to the previous year. Cost inflation and contract delays are to blame.
I'm inclined to think that this is not a serious profit warning. The problems in Manufacturing sound temporary to me:
Actions are underway to mitigate the material cost increases and the new contracts are now in full production and expected to contribute positively to future growth.
The occasional contract delay is to be expected in this kind of business. It's par for the course. For three major contracts to all be delayed is especially unlucky, but at the end of the day it's probably still just a case of bad luck. And anyway, most of Swallowfield's value is in its Brands division.
Investors may also be a bit concerned about the spike in net debt to £11 million. This is up from £3.6 million a year ago. Again, the company says that this is a temporary spike due to timing issues.
My view
I would like to buy this stock, at the right price. It's a type of company I like to own, particularly the Brands side of the business.
Swallowfield's enterprise value is £58 million at the latest share price, though with incoming cash receipts this will hopefully reduce by a few millions.
Brokers are guiding for £5.8 million in adjusted PBT for the current financial year.
That suggests an earnings multiple versus Swallowfield's enterprise value of 10x at the current share price, before we take the company's financial adjustments and corporate taxes into consideration.
It's a close call but I think I still have a preference for Creightons at current share prices. Swallowfield does slightly better if you run a Stocko comparison.
If Swallowfield's new CEO can go ahead and prove that the increased debt levels and the contract delays are indeed temporary issues, I do suspect that the Swallowfield share price will recover.
Orchard Funding (LON:ORCH)
- Share price: 99p (unch.)
- No. of shares: 21 million
- Market cap: £21 million
Application for Bank Licence & New Appointments
I last covered this specialist lender in a March SCVR.
Today we get confirmation that it has submitted an application for a bank licence to the PRA and FCA.
If successful, that would significantly reduce the company's cost of funds, reduce its reliance on other banks, and enable it to scale up. It anticipates receiving the licence by the end of the year.
Coinciding with this news, Orchard announces the appointment of some new Directors.
I previously wrote that I thought these shares would react positively to strong evidence that a bank licence would be granted.
It's great to have a clear timeline now for when the company thinks this could be achieved.
I wonder if it will need to raise equity, and how much, to seal the deal?
Another holding of mine, PCF (LON:PCF), had net assets of c. £25 million when it was granted a banking licence. It then raised a further £10.5 million, "to maintain the regulatory level of capital and liquidity that the Group is required to hold as agreed with the PRA and FCA".
Orchard's net assets were last reported at £13.5 million, so only about half of the level that PCF had when it got a licence. Its regulatory requirements won't be exactly the same as PCF's, naturally. But I would still be braced for an equity raise, if the application is successful.
If there is a future fundraising to provide enough capital to support a bank structure, that could be the ideal entry point. I maintain a watching brief.
Safestyle UK (LON:SFE)
- Share price:40.8p (-18%)
- No. of shares: 83 million
- Market cap: £34 million
Safestyle UK plc, the leading retailer and manufacturer of PVCu replacement windows and doors to the UK homeowner market, today issues an update on trading.
We have been watching the situation go from bad to worse with this company. See the trend in EPS guidance below. This is why momentum trading works:
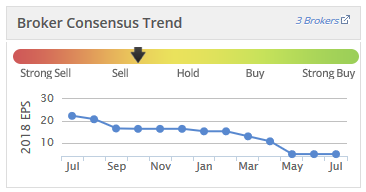
Thankfully, it had a strong balance sheet before this mess erupted. Otherwise, it could easily have gone bust already.
The cash balance is forecast to be break-even at year end, with borrowing facilities in place should they be needed.
Safestyle has struggled with a weaker consumer environment and an aggressive competitor who has apparently been undercutting it and stealing its staff. It is pursuing legal action against Safeglaze, which is also based in Bradford.
My view
It sounds to me as though staff are going to do well in these circumstances, at the expense of shareholders. Sales commissions and recruitment costs are up.
The Board expects margin improvement in the medium and longer term. It's not something I'm eager to bet on right now, personally. This is a cyclical and I think a commoditised industry, and I have no idea to what extent Safestyle's profitability might recover.
Blancco Technology (LON:BLTG)
- Share price: 76p (+3%)
- No. of shares: 64 million
- Market cap: £49 million
Trading Update and Notice of Results
A reasonable update from this data erasure specialist. Its performance has been troubled and its share price has collapsed over the past 18 months.
It has a new CEO and also announces a new CFO who will join later in July.
Revenues for FY 2018 (ending June) are lower than expected, while profit margins are better than expected.
Cash flow was positive in H2, reducing net debt to £2.8 million.
My view
I've just had a quick look at the interim balance sheet. Equity was £49 million, exceeded by £65.6 million of intangibles.
Meanwhile, £9 million of gross bank borrowings were drawn from a £12.4 million facility - not much headroom. So it's good that the net debt position has improved since then.
I'm not tempted to buy shares in it at this stage, due to the balance sheet and track record. But let's try to keep an open mind and wish good luck to the new brooms.
(This section is written by Paul Scott, who owns shares in Sosandar at the time of publication.)
Sosandar (LON:SOS)
- Share price: 23.2p (+9%)
- No. of shares: 107 million
- Market cap: £25 million
As promised, here is my take on the results today from Sosandar, an early-stages ladieswear eCommerce company, based in Wilmslow.
The historic figures are of little interest, because this share is all about growth. But for completeness, revenues for y/e 30 Mar 2018 were £1.35m, and the adjusted EBITDA loss was £3.1m. In this case, EBITDA is a perfectly reasonable performance measure, because the depreciation/amortisation charges are negligible (as it has hardly anything in fixed assets, as production/distribution/IT are all outsourced). There is no capitalisation of IT spend either. So EBITDA is clean.
LFL revenues are up 268% for the 6m to 03/2018. That's a strong percentage, but it's coming from a very low base. Nevertheless, to be credible, an early stage growth company should be delivering triple digit growth rates, and it is.
Forecast sales - what matters most, is how revenues can be expected to grow. Happily, I was able to work out sales & growth for Q1 of the new financial year (ending 03/2019). This is possible because the narrative today tells us that Q/e 06/2018 was up 73% sequentially on Q/e 03/2018. That's a very impressive quarterly growth rate.
We can work out that Q/e 03/2018 revenues were £492k. I've calculated this by taking full year revenue of £1,353k, and decucting the 9 month interims revenue of £861k.
If we then apply 73% sequential growth, then this arrives at my forecast of £851k revenues in Q/e 06/2018. If you multiply that by 4 to annualise it, we arrive at £3.4m revenues. However, that assumes that no sequential growth occurs, which is ridiculously pessimistic. In reality, I think this demonstrates that Sosandar is heading for perhaps £4-5m revenues this year ending 03/2019, maybe more? That's way ahead of the original plan, in the Turner Pope note from when the company floated, which forecast £3.3m revenues this year. So in a nutshell, it looks to me as if Sosandar is trading well ahead of plan, in terms of revenues.
Gross margin has improved strongly too, to 49%. That's seriously good, for such a small fashion business. It's being achieved by strong sell-through at full price, and good stock control. Or put another way, its product is in demand, and they are not having to discount much to shift it. All very encouraging.
The narrative today is dripping with positives about the outlook for the business, so I am greatly encouraged. It seems to me that we have confirmation today that this business model is going to be a success. Whereas yesterday, it was still highly speculative & uncertain.
Cash - there is £4.6m cash pile. Losses & cash burn should reduce this year, because turnover & gross profit should be rising considerably. If we take a mid point of £4.5m revenues, at 50% margin, then that's £2.25m gross profit for this year. That's up from £0.66m gross profit last year, an increase of £1.6m in gross profit - which would roughly halve the adjusted EBITDA loss this year, to about £1.6m.
In reality, I doubt that will happen, because the company will want to spend more on building its team, and other growth-related expenditure. But there's little doubt that the company has plenty of cash headroom for now. It might decide to do a top-up fundraising in 2019 or 2020, but that's of no concern to me whatsover, because it would be raising cash at a much higher share price than now - from a position of strength, since investors would probably be queuing up to put money into such a fast growth eCommerce business.
So anyone wittering on about cashflow and placings, is just scaremongering. The cash position is fine, and won't be a problem unless growth stalls. The opposite is happening, sales growth is accelerating.
Overall then, as you've probably gathered, I'm greatly encouraged by today's news. I don't know how to value this share, as it's all about future growth. In a bear market it might only be valued at £10m. In a bull market I could see it being valued at £100m+, once investors twig that the business model is working. Who knows?
I'm in this one for the long-term, so the short term price doesn't really matter. It's all about backing management, and as I've said before with Sosandar, the management team is the real deal. They're experienced, and are delivering exactly what they set out to do. I recommend reading today's narrative with the figures in full, as there are lots of very encouraging things in it.
Obviously, as a loss-making growth company, this won't appeal to value investors!
Graham here again. I think we are all done - thanks for dropping by and good luck to England tonight!
Cheers
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Must admit I'm finding it hard to interpret the Swallowfield (LON:SWL) trading update - I hold.
What I'm juggling:
On the plus
- PBT significantly ahead
- Brands business significantly ahead, and expected to grow (this one one of my original drivers for investment). Revenues up 16% and (one assumes) already high margins now higher
- Contracts delayed, but now in full production and will contribute to next financial year
- Fish embedded well
On the minus
- increasing costs (in line with industry)
- net debt at £11m - but to significantly reduce. It doesn't give any indication to what
- operating margins significantly down
Forward PE now below 10, brands expected to continue to grow, contract business to improve profitability with new contracts underway, and debt to come down.
One nagging brexit doubt is that EU countries account for £23m of the £74m revenues - but was this already baked into share price weakness.
Anyone else in same boat / any thoughts on this one?
Cheers
Just an observation which demonstrates maybe the time it takes for new management to understand how their particular "train set" works, but three of today's announcements are from companies which have recently had new CEO's and in each case have wiped around 20% off their value. They are Frenkel Topping (LON:FEN) Safestyle UK (LON:SFE) and Swallowfield (LON:SWL)
I think the last couple of paragraphs of the Burford Capital (LON:BUR) release are interesting following some earlier discussion on previous threads about their “earnings surprise” potential.
https://www.investegate.co.uk/burford-capital--bur-/rns/update-re-successful-petersen-appeal-court-result/201807110700042340U/
Basically, they say that while they appreciate the coverage they get from investment analysts their earnings forecasts are less guided by the company than might be the case for say a typical manufacturing company. Given the nature of their service, they see the embedded value of their ongoing cases as being commercially sensitive and neither lead the analysts nor comment on the accuracy or otherwise of their forecasts. The only reliable interim mark we get is when they come to sell a piece of an ongoing case and even this is often opaque in terms of disclosing exactly is being sold and on what terms. In the past Burford Capital (LON:BUR) results have tended to blow away analyst forecasts on the upside - this commentary maybe helps to explain why.
Gus.
Hi Gus
I do hold Burford Capital (LON:BUR) and always thought the lack of updates on specific cases was a legal/sensitive matter.
However, I am signed up to receive alerts from IMF Bentham (same sector, listed, but based in Australia) and I am always getting updates on cases, often with numbers included.
I wonder why they seem so much open than Burford Capital (LON:BUR) ?
Cheers
A
Gus.
It is an important point that you flag and maybe why Stockranks have historically tended not to score Burford Capital (LON:BUR) as highly as they might if Broker guidance was forthcoming...
Full text here:
Trading Prospective investors and other market participants should not treat, and Burford does not intend to treat, the financial projections produced by research analysts as indicative of the market's expectations of Burford's future financial performance. We specifically eschew any obligation to correct estimates made by financial analysts or to inform the market should we come to believe that our actual performance will diverge from those estimates. This is, of course, different to the approach taken by most operating companies, in respect of which research analysts can produce relatively reliable estimates and the relevant company will advise the market if it expects to see performance materially different from the consensus of analyst forecasts. It is important that investors understand that Burford takes a different approach as a result of the different nature of its business.
What a great company! Ian
Paul re Sosander,
I am a holder since the UK Investor Show so I am doing nicely.
If the market opportunity is as good as they say, what do you think would happen if someone like ASOS went after the same market? Do SOS have any form of USP that enable them to withstand that sort of competition?
Hi richjp,
If the market opportunity is as good as they say, what do you think would happen if someone like ASOS went after the same market? Do SOS have any form of USP that enable them to withstand that sort of competition?
I don't think any fashion business really has much of a USP. It's all about consistently offering customers products that they want, at the right price, and of decent quality. Then happy customers return, word spreads, thus building the business.
The good thing about Sosandar (LON:SOS) is that it's tackling an under-served part of a large market, and seems tuned in to what its customers want. An interesting snippet from my telecon with management today, was that the demographics of Sosandar's customers are turning out to be far broader than they anticipated. So it's not just 35-55 women who are buying their products, that is only 51% of their customer base.
Perhaps surprisingly, 55-64 year olds are 23% of their customers, and 9% are over 65.
At the other end, 18-34 year olds make up 17% of their customers.
I like that, because it means that the lifetime value of a Sosandar customer should be large - e.g. a customer who discovers Sosandar aged 40, could conceivably have a lifetime value of 25-30 years. Contrast that with the young fashion chains like BooHoo, which is constantly having to recruit new teenage customers, to replace the ones who drop out when they get to (say) their mid-20s.
In other words, the marketing spend that SOS makes now, should generate a long stream of future earnings from each customer. Although the cost is up-front, and the benefit is gradual. The report today showed what seemed to me to be pretty good figures on repeat customers - that's a key metric I think.
All rather encouraging. There's a lot of future potential here, in my opinion. They seem to be getting all the core stuff right. The sales growth & eventual profitability should then flow through in due course, providing nothing serious goes wrong.
Regards, Paul.
Does anyone know if the proposed US tariffs affect British products made in, or shipped from, China? Could be messy for some companies if they are affected and are major exporters. I see they apply to a host of consumer and agricultural products.
Hi Paraic,
I'm not sure I understand the question. If it's made in China, how is it a British product?
If it's made in China by a Chinese company that has a British parent company and shipped to the US, then yes I would expect the Trump tarriffs to apply. Similarly if it's made in China for the British company by a contract manufacturer.
If it's made in China and imported direct to the UK then the existing EU tarrifs would apply, not US.
Thanks merlotman. Re: Burberry (LON:BRBY) and Next (LON:NXT), they are very different holdings, for the reasons you outline. I much prefer Burberry (LON:BRBY) to be honest, but saw value in Next (LON:NXT) when I purchased it, and continue to hold. The correlation doesn't seem too scary, as they serve such different markets. All the best. G
Graham thanks for your coverage of Burberry (LON:BRBY). I don't hold but did a comparable analysis with Next (LON:NXT) and decided on the latter due mainly to value. Interested to see you hold both - presumably you are comfortable with two significant holdings in same sector as as Burberry (LON:BRBY) is an international brand focused on a store based luxury retail offering whereas Next (LON:NXT) is more of a strong UK general brand moving online. I still can't help that there would be some correlation in SP were UK consumer spending to take a dive. As an aside I don't tend to invest in small caps but do appreciate your and Pauls commentary on larger cap stocks and macro issues. Keep up the good work!
Hipgnosis Songs Fund (LON:SONG) launched today - it was mentioned in a prior SCVR. Looks like a positive lisitng. They also announced the acquisition of 75% of a music catalogue from Terius Nash containing well known hits such as Umbrella by Rihanna, Single Ladies by Beyonce and Baby by Justin Bieber. Also hits by Jay-Z and Kayne West are included. I feel this is quite a good quality acquisition.
Thanks for another great report Graham :) I appreciate all your efforts on a daily basis, and big thanks to Paul for taking time in his absence to give us his view of Sosandar. I hope you're getting plenty of rest and recharging the batteries ready to provide regular commentary again.
I'm highly encouraged by the Sosandar (LON:SOS) update. I track their Facebook performance and take the time to read the comments and reviews. They're generally great and FB likes are up ~50% from 31st Dec. The customers regularly comment that they buy a lot of different items from Sos, or get the same item in different colours. It's pleasing to see the high margin products, like the leather skirts and jackets getting good reviews.
One thing that concerns me is, if they get a bad review, they get several at once. It seems to me (speculation) that they have a critical member of staff they can't do without, when they have some time of the wheels start to fall off - Paul if you could ask them about this that would be great (I don't expect any kind of response to this ask :)).
Very encouraging, I see this buying me my long dreamed of Porsche 768 in a few years :)
Any chance you could touch upon AFX please? Revenue growth by 50% with Profit for year expected in line but mainly because of the spend this year to hire resources. That sounds positive to me if they continue to grow at that level whilst maintaining profit margins, especially for next year and so on.. Thoughts anyone?
Hi Pratt, re: Alpha FX (LON:AFX) it sounds positive to me too, and it will be interesting to see how it plays out. I will keep an eye out for more detailed announcements from the company in future. Cheers. G
I notice you have included Burford Capital (LON:BUR) on your list and having taken a quick look at the RNS it looks positive to me, but not exactly a game changer. Petersen will be held in the US, but I think most were expecting that. It does at least reduce the risk of Argentina managing to get the case back to a non-objective court in BA.
The more interesting part is that on the secondary market Burford's holding is now valued at $800m (based on selling just 3% and they may not get that if they tried to sell the lot). It could be argued they may be stuck in for the long haul on this unless they keep selling tranches off as who has a spare $800m to buy it? I took a quick look at the 2017 annual report that stated Petersen on secondary market was $660m at that point so it is significant uplift on that individual case.
I suspect if you already liked Burford Capital (LON:BUR) this just made it even better due to the uplift in secondary valuation, and if you are not such a fan I doubt this will have changed your mind as if you value it on a NAV basis it will not have moved the needle too much.
Hi pgs, thanks for the summary on Burford Capital (LON:BUR). I took it off the list based on the view that today's news was probably expected by the majority of shareholders (the share price is almost unchanged), and I don't have any particular legal expertise or information to share in relation to the Peterson case. Appreciate your comment. G
Hi Graham,
Thanks for the updates again today.
Re Burford Capital (LON:BUR), Repsol accepted $5billion for their 51% share in YPF. The Petersen share was 25%, thus indicating a value of ~$2.5 billion (plus interest since) for Burford's petersen asset.
Burford is entitled to 70% of the recovery in the Petersen matter (from which Burford will need to pay meaningful expenses which would be expected to reduce Burford’s recovery to something below 60%)
So this equates to $1.5 billion (plus interest).
But the RNS today stated a carrying value of only $800million - "implying a valuation of $800 million for our original total Petersen entitlement".
Seems like a very conservative valuation
I agree re Burford Capital (LON:BUR). I was going to suggest you not bother to cover it earlier on but kept quiet in case you had a different take on things.
I think Burford will just be pleased that the Petersen case can start to move forward again towards a resolution, but I expect the Argentine government will still try to delay every step of the way. Kicking the can down the road seems to be the key political skill of our times.
Sosandar (LON:SOS) (I hold a long position in this share)
As promised, here is my take on the results today from Sosandar, an early-stages ladieswear eCommerce company, based in Wilmslow.
The historic figures are of little interest, because this share is all about growth. But for completeness, revenues for y/e 30 Mar 2018 were £1.35m, and the adjusted EBITDA loss was £3.1m. In this case, EBITDA is a perfectly reasonable performance measure, because the depreciation/amortisation charges are negligible (as it has hardly anything in fixed assets, as production/distribution/IT are all outsourced). There is no capitalisation of IT spend either. So EBITDA is clean.
LFL revenues are up 268% for the 6m to 03/2018. That's a strong percentage, but it's coming from a very low base. Nevertheless, to be credible, an early stage growth company should be delivering triple digit growth rates, and it is.
Forecast sales - what matters most, is how revenues can be expected to grow. Happily, I was able to work out sales & growth for Q1 of the new financial year (ending 03/2019). This is possible because the narrative today tells us that Q/e 06/2018 was up 73% sequentially on Q/e 03/2018. That's a very impressive quarterly growth rate.
We can work out that Q/e 03/2018 revenues were £492k. I've calculated this by taking full year revenue of £1,353k, and decucting the 9 month interims revenue of £861k.
If we then apply 73% sequential growth, then this arrives at my forecast of £851k revenues in Q/e 06/2018. If you multiply that by 4 to annualise it, we arrive at £3.4m revenues. However, that assumes that no sequential growth occurs, which is ridiculously pessimistic. In reality, I think this demonstrates that Sosandar is heading for perhaps £4-5m revenues this year ending 03/2019, maybe more? That's way ahead of the original plan, in the Turner Pope note from when the company floated, which forecast £3.3m revenues this year. So in a nutshell, it looks to me as if Sosandar is trading well ahead of plan, in terms of revenues.
Gross margin has improved strongly too, to 49%. That's seriously good, for such a small fashion business. It's being achieved by strong sell-through at full price, and good stock control. Or put another way, its product is in demand, and they are not having to discount much to shift it. All very encouraging.
The narrative today is dripping with positives about the outlook for the business, so I am greatly encouraged. It seems to me that we have confirmation today that this business model is going to be a success. Whereas yesterday, it was still highly speculative & uncertain.
Cash - there is £4.6m cash pile. Losses & cash burn should reduce this year, because turnover & gross profit should be rising considerably. If we take a mid point of £4.5m revenues, at 50% margin, then that's £2.25m gross profit for this year. That's up from £0.66m gross profit last year, an increase of £1.6m in gross profit - which would roughly halve the adjusted EBITDA loss this year, to about £1.6m.
In reality, I doubt that will happen, because the company will want to spend more on building its team, and other growth-related expenditure. But there's little doubt that the company has plenty of cash headroom for now. It might decide to do a top-up fundraising in 2019 or 2020, but that's of no concern to me whatsover, because it would be raising cash at a much higher share price than now - from a position of strength, since investors would probably be queuing up to put money into such a fast growth eCommerce business.
So anyone wittering on about cashflow and placings, is just scaremongering. The cash position is fine, and won't be a problem unless growth stalls. The opposite is happening, sales growth is accelerating.
Overall then, as you've probably gathered, I'm greatly encouraged by today's news. I don't know how to value this share, as it's all about future growth. In a bear market it might only be valued at £10m. In a bull market I could see it being valued at £100m+, once investors twig that the business model is working. Who knows?
I'm in this one for the long-term, so the short term price doesn't really matter. It's all about backing management, and as I've said before with Sosandar, the management team is the real deal. They're experienced, and are delivering exactly what they set out to do. I recommend reading today's narrative with the figures in full, as there are lots of very encouraging things in it.
Obviously, as a loss-making growth company, this won't appeal to value investors!
Regards, Paul.
EDIT - there should be an initiation note out from Shore Capital shortly, who are the new broker (announced today). So I'll keep an eye out for that (if I can get hold of it - they're not on Research Tree unfortunately), and it will be interesting to see if their number crunching ties in with my optimistic view (based on bumper sales in Q/e 06/2018).
I spoke to Sosandar management & their advisers briefly this morning, in a telecon. I emphasised the point that PIs can't get hold of broker notes now, post MiFID II, unless brokers put them on Research Tree. They took my point on board. I do everything I can to encourage companies & advisers to get better information out to private investors, at every opportunity.
a higher profile broker is a positive move for Sosander. They seem to be well advised financially. Initiation note from Shore is obviously going to be positive otherwise they wouldn't have got the mandate. this could be 5x in a years time with current revenue trajectory.
Thanks Paul...this is the type of investment that I really hate but your analysis was fantastic in explaining the investment proposition in a way that made sense of the valuation
Re Sosandar
Hi Paul, thanks for your notes on Sosandar which I hold. I don’t have much experience of investing in clothes retailers and wanted to ask you a couple of questions. Do you think the first quarter revenues for the new financial year could have been strongly positively impacted by such hot weather and do you know if clothes purchases are significantly cyclical or fairly evenly spread across the year? I’m just trying to take a read from the indicated first quarter revenues about what that can tell us for expected full year sales to end March 2019.
Well done on the early purchase. Trading (in my view) is looking very encouraging.
Regards
Andrew
Andrew asked;
Do you think the first quarter revenues for the new financial year could have been strongly positively impacted by such hot weather and do you know if clothes purchases are significantly cyclical or fairly evenly spread across the year?
That's a good point actually. The quarter ending 31 March is the quietest quarter of the year for fashion retail. So there would be a seasonal step-up in sales from calendar Q1 to calendar Q2. That seasonal increase this year would have been enhanced by bad weather in Q1, and good weather in Q2.
Off the top of my head, thinking back to my days working in the sector, the seasonal uplift would be roughly 20% I think. But that was for a business which had very young customers. Sosandar's seasonal uplift might be different, as it has an affluent & middle-aged customer base, which presumably doesn't need to economise on discretionary spending after Christmas, like younger people do.
So the short answer is that yes there would have been some seasonality benefit in Sosandar's Q1 to Q2 sales uplift, but nowhere near the 73% they reported, in my view.
Regards, Paul.
Re Sosandar: thanks Paul, that’s really helpful.
Regards
Andrew
Good write up Paul
Sosandar (LON:SOS) is one of the most exciting ground floor stories I've seen in a while and the triple digit annualised growth certainly demonstrates what you'd hope to see given the low starting revenue base.
I agree that valuation is indeed tricky but I'd put this akin to an early stage tech company (I know there are differences, but valuation metrics are similar). Rule of thumb is 8-10* revenue so £28m - £50m or 33p-60p feels like an appropriate range to me.
That said, like yourself, I am in for the longer term provided revenues continue to grow at an appropriate pace as I believe in the management.
Griffin Mining (LON:GFM) is a cash cow, I topped up after todays news as I think its still undervalued.
Griffin Mining (LON:GFM) announced a couple of minutes ago that they have signed the contract for the zone II Caijiaying Zinc-Gold mine. Up 4.2% at time of writing.
Hi Is2g08
I'm not sure Graham covers mining stocks here. I too hold Griffin Mining (LON:GFM) - was surprised that the impact on SP was so modest, given how far back it's fallen from it's recent highs. Happy to continue holding though...
ppdrs
I thought he may due to it's inclusion in the NAPS. I guess we can have a discussion here though!
Up 8% now - I could see it regaining recent heights and plowing on further.
I also bought a few Griffin Mining (LON:GFM) this morning as it looks like game changing news. Seems to me this is mainly a bet on the Chinese economy. If the Chinese choose to weaken the Renminbi to counter US tariffs it won't help the SP, nor if Chinese resource consumption reduces. As ever roll the dice and hope for the best!
The NAPS is a fantastic project but I can't cover every sector, so will be remaining silent on £GFM! Good luck with it anyway. G
Sosander....holding from when they used to be a gold stock and added earlier this year. Target of 100 pence to sell any. May take two years. Celebrity section on their website shows all the Loose Women from the daytime tv show wearing sosander fashion. I wonder if they have a deal with the show or producer?
Morning all!
Sosandar (LON:SOS) (in which I hold a long position) is one of my favourite shares, so I've agreed with Graham that I'll submit a section on that for today's report. I've just come off the phone with management, so will collect my thoughts & have something posted here before lunch today.
Best wishes, Paul.
Sosandar (LON:SOS) thirded. Wish I'd bought more at 11p!
Also wondering if anyone had any thoughts on Frontier IP (LON:FIPP) (no position), could it be the thinking investor's Tern (LON:TERN) ? '...specialises in commercialising university intellectual property, today announces portfolio company Pulsiv Solar has won a UK government grant to reach an important milestone in the development of its patented, energy-efficient solar power technology... University of Plymouth spin-out Pulsiv Solar £129,929 towards a £288,732 project... will complete the technological development of its solar micro-inverter by April next year. Frontier IP holds an 18.9 per cent stake in the Company... In laboratory conditions, Pulsiv has demonstrated its technology is significantly more energy efficient than existing micro-inverters...The aim.. efficiency improvements of at least 5 per cent over current market leaders. The micro-inverters can be used either as new or retrofitted to existing solar panels.' May investegate further.
My morning smallcap tweet:
Ilika (LON:IKA), Fishing Republic (LON:FISH), PCI- PAL (LON:PCIP), Swallowfield (LON:SWL), Safestyle UK (LON:SFE), Frenkel Topping (LON:FEN)
Ilika (IKA) £4m placing and £1m open offer at 20p, a 13% discount. Needed for larger battery development but mainly for keeping the lights on (£3m). "Ilika has now extended its commercialisation roadmap to include large format Stereax cells for automotive power and now intends to build a new pre-pilot production line." I don't see how the orders of magnitude increase in capacity will be achieved. The Stereax M250 cell (albeit very small) has 10,000 less capacity than a typical Li-on cell.
Fishing Republic (FISH) guides H1 rev £3.4m (£4.1m). Store LFL -22%. Q1 margins below the Company's expectations mainly as a result of clearing old product lines. They knew they were doing that, right? Q2 margins improved, close to 2017. Absurdly slow reporting of dismal Q1.
PCI PAL (PCIP) guides FY broadly in line with expectations. "Our stated strategy is to focus on the channel sales route to market, evolving away from our previous mainly direct sale route. I am pleased at how quickly this evolution is happening albeit that we are still learning the timelines of the contracting, testing and go-live process."
Swallowfield (SWL) guides FY broadly in line with expectations. Rev flat but pre-tax significantly up despite underlying operating profit marginally behind last year. F/V is for rev up 1%,
Safestyle UK (SFE) warns FY rev below market expectations and small U/L pretax loss. Blames weaker consumer spending, loss of significant numbers of canvass, sales and installation staff to the new competitor.
Frenkel Topping (FEN) warns H1 operating profit halved YoY and FY profit below market expectations.
Orchard Funding (LON:ORCH) please. You have covered before and today we have news that the planned banking licence application has been submitted and they hope/expect it to be granted by the end of the year. An opportunity to broaden funding base, reduce cost and scale up, but they sound like they will take it slowly, which is fair enough. A real chance of growth in the medium term I would hope.
Hiya, Orchard Funding (LON:ORCH) is in the list, thanks for the rec. G
Only a brief look at the Sosandar (LON:SOS) results, but the comparatives look to be 7 months vs 12 months?
Shame this wasn't explicitly stated + it makes it difficult analyse + exaggerates the growth figures
Not a holder
Ilika (LON:IKA) Proposed placing to raise not less than £4m and an open offer to raise up to £1m. Graeme Purdy, CEO, outlines the detail:
http://www.piworld.co.uk/2018/07/11/ilika-ika-fund-raise-presentation-july-2018/
Ilika are are all about solid state batteries. The fund raise will be used with grants to commercialise the IP developed so far, to take forward into licensing agreements.
Sosandar (LON:SOS) Full Year Results: Record revenues and growth across KPIs
Sosandar PLC (AIM: SOS), the online women's fashion brand is pleased to announce its results for the year ended 31 March 2018. Showing great Financial and operational highlights. Interesting price movements in last few days. StockRank increasing to 29. I hold.
Morning Graham, Sosandar (LON:SOS) have released their results for Y/E 31/3/18 and these show some explosive revenue growth of 387% to £1.35m albeit from a low base. Also they have improved gross margins and increased customer database numbers through heavy marketing.
I would welcome your views on this interesting company.