Small Cap Value Report (Wed 13 June 2018) - MUL, NTBR, CNCT, CAY

Morning!
On the menu today we have:
- Mulberry (LON:MUL) - preliminary results
- Northern Bear (LON:NTBR) - trading update
- Connect (LON:CNCT) - trading update
- Charles Stanley (LON:CAY) - final results
5.30pm Edit: had to cut this short here, due to time constraints.
Last call for Mello South: I've been informed that the last 30 tickets for tomorrow's conference are being offered at £30.60, i.e. at a 66% discount to the full price.
Besides the speakers I've already mentioned who will be there, the event will have Leon Boros and David Stredder on a panel with two fund managers, each discussing the secrets of their own stock-picking success.
There will also be a Dragons Den event which will herald "the rebirth of Hofmeister Beer - follow the bear" (I am too young to appreciate what this is referring to).
The complete schedule can be viewed at this link. Ticket-holders will be able to view all the sessions that are filmed at their leisure afterwards and the tickets can be picked up, with the 66% discount, at this link.
CEO Interview - I'm about to do an interview with the CEO of PCF (LON:PCF) (in which I have a long position), so if you have any questions you'd like me to ask, there is some time to post them in the comments below.
11:30am: I've finished the interview with Scott Maybury at PCF. Very interesting and helpful - I should be able to publish a report on this in the next few days.
Mulberry (LON:MUL)
- Share price: 745p (-4%)
- No. of shares: 60 million
- Market cap: £447 million
I've been writing very positively in the last few days about the luxury brands Burberry (LON:BRBY) (which I hold) and Ted Baker (LON:TED) (which is on my watchlist).
Despite my belief in luxury goods as an investment space, I am still very sensitive to the valuation multiples attached to these shares. And I've failed to understand the valuation attached to luxury handbag designer Mulberry (LON:MUL) in recent years.
However, it might be starting to look at bit more attractive now. The shares have de-rated from the 1000p-1150p range for 2017 and hit a low at 600p earlier this year, before recovering to the current level.
Today's results show a sharp increase in PBT, if you exclude expenses associated with expansion in Asia:
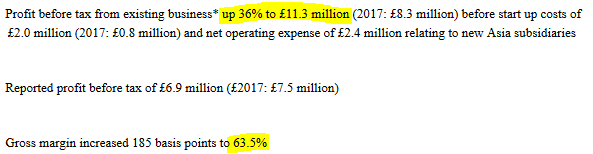
If you trust that the adjustments are reasonable, we have a historic PBT to earnings multiple of about 40x.
That's still a very rich valuation, and beyond what I'd be willing to pay, but at least the valuation is moving towards reasonable territory.
The adjusted costs are associated with opening new Mulberry entities in Mainland China, Hong Kong, Taiwan and Japan - these could have very significant growth potential.
Unfortunately, the outlook is very weak in the short-term, due to poor performance in the UK:
Retail like-for-like sales down 7% for the 10 weeks to 2 June reflecting International up 1% and UK down 9%, due to lower footfall and fewer tourists, as more widely reported
If I was to put my bullish hat on, I would point out that long-term, the UK may account for only a small percentage of Mulberry's sales. So if the UK has lower footfall and fewer tourists than expected, it's not such a huge issue in relation to the long-term value of this stock.
As the international footprint grows (and total international retail sales increased by 20% in these results), the vulnerability to UK consumer spending patterns lessens.
A 9% fall in LfL sales over the recent 10-week period is still a bit worse than might have been expected, and doesn't reflect terribly well on the brand, so on that basis I guess we could justify today's share price reaction.
Balance sheet sounds good: £25 million in cash, no debt.
Operating Margin is poor: 4% using the official numbers, or 6.5% if we add back the Asian expenses.
Operating expenses look too large: 60% of sales, or 57% if we add back the Asian expenses.
By contrast, operating expenses are 52% of sales at Burberry and 53% of sales at Ted Baker. So I'd like to know why Mulberry is suffering a 5% hit to its operating margin in expenses, compared to other high-end brands.
Anyway, this stock is out of my valuation range for now. Let's continue to monitor developments.
Northern Bear (LON:NTBR)
- Share price: 82.5p (+18%)
- No. of shares: 18.5 million
- Market cap: £15 million
There is a great comment by Luthrin (who owns NTBR shares) in the thread below (comment #22), which I would highly recommend reading.
Luthrin also made a noteworthy comment the last time I covered this stock, in February. February's trading update notified us that performance was ahead of management expectations, as does today's.
It's completely impossible for any one individual to be an expert on large numbers of shares in varying industries, which is one of the things that makes writing this report so challenging. But reader contributions make it a far more valuable project. So do check out Luthrin's comments.
Let's take a look at today's full-year update from this building services group in Northern England:
The Group's continuing operations have continued to trade strongly and ahead of management expectations over the second half of the financial year, despite the severe winter weather, particularly during the first three months of 2018.
Revenue and operating profit from continuing operations for FY 2018 will be ahead of the prior year, even after "transaction costs and amortisation of acquired intangibles associated with the H Peel acquisition".
H Peel, acquired on July 2017, will have made a contribution to operating profit. I would also be curious to see how the results would look on a like-for-like basis, excluding the contribution from H Peel.
No equity raise is foreseen, and yet shareholders can look forward to both an increased dividend and the potential for more deal activity. I agree with the company using its balance sheet in the most efficient way possible, but shareholders will need to satisfy themselves with the increased risk this entails:
Our revolving and overdraft bank facilities provide us with the resource to continue with our progressive dividend policy whilst having the financial wherewithal to look at similar acquisitions without the need to raise new equity.
Northern Bear reported PBT from continuing operations of £2.4 million in FY 2017, and £1.3 million H1 2018, including only a short period of H Peel Ownership.
Given the series of "ahead of expectations" updates, I wonder what level of PBT might be reported for the full-year. I can't see any broker forecasts (unsurprising for a company of this size), but could £3 million be possible, I wonder? I don't have any solid basis for that number, I'm simply guessing.
Stockopedia thinks that the forecast P/E ratio is 5.8x, and awards the stock a sparkling StockRank of 89.
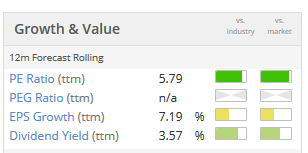
So it's another micro-cap value opportunity for those willing to invest in tiddlers. It won't turn out to be the next Google or Facebook, but it is cheap. Good potential for both earnings to increase and for the valuation multiple to increase over the next two years.
Connect (LON:CNCT)
- Share price: 29.15p (-44%)
- No. of shares: 248 million
- Market cap: £72 million
A share price fall of this magnitude is often a nasty shock so commiserations to anyone holding this.
Connect is a specialist distributor, with specialties in early distribution (newspapers and magazines) and mixed freight, especially items of irregular dimensions or weight (IDW).
The wording of this update would lead you to believe that the wheels are coming off:
- "extremely disappointing" performance since May 1.
- "materially reduced" PBT forecast.
- Pass My Parcel being shut down (check out its poor reviews on trustpilot).
- CFO leaves with immediate effect (he had already resigned), CEO also set to go when a replacement is found.
Looking at Connect's various activities:
- Tuffnells (serving the irregular dimensions or weight market) full year performance to be "no better than the first half". In H1, it suffered an adjusted operating loss of £0.2 million.
I need to query some of the commentary on this. In H1, Connect said in relation to Tuffnells that:
...the underlying Irregular Dimension & Weight (IDW) market is strong and its characteristics are a good fit to the Group's capabilities.
Today, it offers the following explanation for poor performance at Tuffnells:
As reported in May 2018, the IDW market is currently volatile.
What have I missed?!
- Early distribution activities: performing worse than expected. Weaker than anticipated benefit from World Cup product. Revenue decrease of 2.9%.
Can we conclude from the above that revenues would be materially worse than 2.9% down if there had been no benefit at all from the World Cup?
My view
This is now in territory where brave (or foolhardy) value investors will be piling in.
Net income had been forecast at c. £34 million prior to today's announcement.
But the announcement doesn't quantify the new profit expectations, and I haven't done the leg work to find out what they are.
So if you are in the same position as me, you are in the dark as to official profit guidance.
I expect that the company is still profitable. We just have to hope that the wheels aren't falling off to such an extent that management lose control of the situation.
Net debt was £84 million at February 2018, with a net debt/EBITDA covenant of 1.47x.
One of the debt covenants requires this multiple to stay below 2.75x, i.e. the company would be in breach if EBITDA halved without any reduction in net debt.
It looks to me as if the shares are now pricing in an equity raise.
I am not tempted to go bottom-fishing in this situation, as it happens too often that multiple things go wrong all at the same time in a situation such as this (trading momentum stuck in a downward trend, CEO/CFO being replaced, assets being sold off and business units being wound up).
If you can take the view that trading has a good chance to stabilise and covenants are unlikely to be breached, then the risk:reward might be ok. I'll pass on this one for now.
Charles Stanley (LON:CAY)
- Share price: 345p (unch.)
- No. of shares: 50.7 million
- Market cap: £175 million
Excellent results from this investment manager.
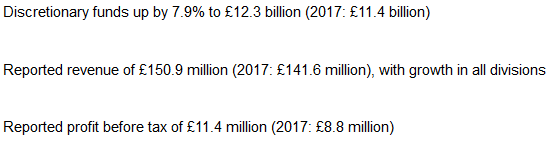
The cash position improves to £66 million and the dividend for the year increases 33%. There's not much for a shareholder to dislike.
The video published at piworld earlier is very helpful in understanding how the CEO/CFO interpret the result. Their main financial objective (and currently their main source of frustration) is to improve the operating margin to 15%:
The focus for the 2019 financial year will be on driving top line revenue growth whilst improving operational efficiency and in turn harnessing operational gearing.
An example of where operational gearing will be important is Charles Stanley Direct. This is still loss-making on a trailing 12-month basis, but it was profitable in H2 thanks to growth in Assets under Administration.
For the overall group, what they call the "Core Business Operating Margin" improved by 160bps to 8.8%. But if you include the cost of share awards to the investment management team, the profit margin achieved was merely 7.2%.
The company is cautiously optimistic about the future:
Combined, the global and UK outlooks provide a reasonably favourable backdrop for our transformation programme and should bring growth in revenues, profits and margins if well executed, which in turn will support our progressive dividend policy and thus generate long-term shareholder value.
My view: looks good value. Management will have to go ahead now and prove they are capable of improving that profit margin. If they could do that, the shares would be really good value. I suppose I'd prefer to wait to see firmer evidence of that.
However, this is not a category of financial stock which I am interested to invest in. I prefer buying shares in fund management companies, as opposed to wealth managers.
Fund management is a much less labour-intensive activity than financial planning or discretionary stockbroking, and I think this results in better returns for investors.
Empirically, we can compare the 9% return on capital at Charles Stanley (LON:CAY) versus 22.5% at Ashmore (LON:ASHM) and 30% at Jupiter Fund Management (LON:JUP) (using Stocko data). Of course it's no coincidence that the fund managers have vastly higher operating margins, too. So I prefer to fish in the pond of fund management companies.
I was heavily distracted today, preparing for Mello and with a few other things going on. So I didn't cover as much as I wanted to, or in a very timely manner - apologies.
Tomorrow's report will be written over the course of two hours, when I arrive at Mello. Let's see how it goes!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Marketing for Mello South still on the Sharesoc website today: https://www.sharesoc.org/events/
Meet The Fund Managers 14 June: Expect to see...some well-known fund managers such as Mark Slater, Andy Brough...
If that isn't using high profile fund managers to attract attendees then what is it? The reality is that both fund managers used to promote the event are not attending. These were the two managers that the marketing literature highlighted the most. They were the first ones mentioned. I personally booked as I wanted to see Mark and Andy. If I had of known they weren't attending I wouldn't of booked. Tickets are not refundable under any circumstances.
It seems to me strange that we criticise companies that over promise and under deliver. But in this context I am being churlish and a whiner according to some posters here. I only wanted to make one specific point which I think was fair to make. David is a good event organizer and Mello Derby was very good.
But the simple point is that under consumer protection laws you can't promote something on one basis when the reality is different. This is not a case of opinion or me being a whiner it is just the law. So technically people who bought tickets on the basis of seeing these fund managers could ask for reimbursement. Obviously this is a very strict way of dealing with things but I am just explaining UK law in this area as opposed to us debating things for ages.
If you feel the law is unfair you can always right to the advertising standards authority and the various consumer protection groups. You would have to be making the case that a product can be marketed on one basis while the actual product is different. Good luck with that!
Or Beeks Financial Cloud (LON:BKS) ?
Regarding Connect (LON:CNCT). My corner shop - despite multiple requests - has had no deliveries of World Cup stickers for my kids’ sticker book for two weeks now! The demise of Connect (LON:CNCT) has nothing to do with the market, it’s pure management incompetency. The recovery story is highly dependent on Monday’s incoming CEO. Does anyone know of him?
I am very much looking forward to seeing how that works Graham - is panto style audience participation allowed or frowned upon?
Dewhurst (LON:DWHT): operating profit for the half year down from £3.1m to £2.5m. However, last week the company announced that it would be acquiring A&A Electrical Distributors for £10.5m cash plus 25% of A&A's profits for the next two years. A&A made £3.3m profit before tax in the year to 2016, on a turnover of £11.4m. Sounds like Dewhurst got a bargain there. And don't forget that with Dewhurst there are the expensive DWHT voting shares (875p) and the cheaper DWHA non-voting shares (565p). I hold DWHA.
Hardide (HDD) presentation just posted, from the Progressive Equity Research - piworld event held on Monday (11.6.18).
High margin. Patent protected IP. Dependent on oil and gas, so benefiting from oil price. Slowly diversifying into other sectors.
Here's Phil Kirkman CEO and Peter Davenport – CFO
http://www.piworld.co.uk/2018/06/13/hardide-plc-hdd-investor-presentation-june-2018/
With an introduction by Gareth Evans, MD Progressive Equity Research
Phil Kirkman, CEO
What is Hardide? - 01:55
The business model - 04:20
Aim listing & placing – 05:35
The group facilities – 06:00
Key facts - 6:43
Patented coating technology - 09:10
Intellectual property - 13:10
Key markets – 14:30
Accreditations - 17:38
H1 18 overview - 18:19
Peter Davenport, CFO
Financial trends – 20:45
Financial overview H1 18 v H1 17 - 22:40
Income Statement 23: 32
Balance sheet – 23: 40
Q&A - 25:30
RE: Mello South
I note that Mark Slater has a 3.25% in XLMedia (LON:XLM): he has had a few screamers in the past year or two Lakehouse (LON:LAKE) amongst others springs to mind. Maybe worth a discussion with him on how he views these as clearly his capital seems to be more "patient!" than others. Many on here have become much more Minervini-like in handling losses.
There's a useful discussion around investor versus trader in there somewhere and the spectrum of behaviours that vary across the fundamental to technical spectrum of styles and resulting timings (and tolerances)
Working in the travel industry, I am very familiar with the late discount model. There is a fundamental difference between a full-price early purchase and a late discount. The early buyer has a definite place. Anyone who waits for a discount runs the risk that the event is sold out, and they don't get to go. The two purchases are not the same thing, even though they supply the same thing.
The trouble is that people will change their behaviour if they know the longer they wait, the bigger the discount. Hopefully timarr will be along soon to tell us why! And this is not really the behaviour David wants if he is planning an event with a lot of fixed costs. With all due respect to Mello, I would suggest that going to a one-day investing event does not have the same importance as planning your annual holiday for most people.
Pricing tickets for events like this is very difficult, and I feel sorry for David as I have been in a similar situation in the past organising smaller scale events for a not-for-profit society.
All the best, Si
"The trouble is that people will change their behaviour if they know the longer they wait, the bigger the discount."
*Some* people may well. Personally I would book now for the next Derby event without knowing the price or line-up. I am price inelastic. I have no problem with selling off tickets cheap late in the day if (crucially) there are any left, to people who are price-elastic.
Jon
*Some* people may well. Personally I would book now for the next Derby event without knowing the price or line-up. I am price inelastic. I have no problem with selling off tickets cheap late in the day if (crucially) there are any left, to people who are price-elastic.
In fact most people will, as observed by behavioural economists (Kahneman, Thaler, Ariely etc.) human beings are predictably irrational especially as consumers when it comes to pricing. Even when you identify a share you want to buy, who amongst us never waits for a pull-back to buy it slightly cheaper? Perhaps it's only me...
When you're organising an event you need an idea of demand as early as possible, particularly whilst you still have some flexibility in your own fixed costs in running the event. The low-cost airlines increase prices as the flight departure gets nearer because it engenders the behaviour they want from their customers. To do the opposite will only likely engender the wrong kind of behaviour and if the lower pricing is very visible it's likely to create some resentment from your best customers and change their behaviour when buying tickets in future.
It's not an easy problem to solve, and behavioural pricing is a whole subject in itself, but it helps a lot if you have a good idea of demand early on and get the initial pricing right, which is easier said than done.
All the best, Si
Hi Si
I actually work for a rare holiday company that doesn't do late discounting. They offer a small discount for early booking, which helps them to assess demand, and potentially consolidate dates that aren't selling well. But behavioural pricing is definitely a big deal in travel because fixed costs are high and marginal costs low.
But we have probably spent long enough on this topic. Perhaps I am unusual in thinking Mello events do have attractive initial pricing. Attractive to me, in any event :)
Maybe see you at a future one?
Jon
I’d just say it seems a little like churlishness to criticise David & the Mello team for the fact that some high profile & very busy speakers have dropped out ...they’re not employees of Mello or indeed paid to attend so it’s unsurprising that diary conflicts will have an impact as the event looms. The Derby event was outstanding..if Mello South comes close (& I’m sure it will) then those paying £90 ....or £30 ...will have had exceptional value for money. As to location i’d prefer it to take place in my village...but understand totally that it won’t unlesss I personally organise the whole thing myself.
Churlish looks like the word that fits.
Working in the travel industry, I am very familiar with the late discount model. There is a fundamental difference between a full-price early purchase and a late discount. The early buyer has a definite place. Anyone who waits for a discount runs the risk that the event is sold out, and they don't get to go. The two purchases are not the same thing, even though they supply the same thing.
If David has to attach caveats to every mention of Mello events that line-ups are subject to change, etc etc it will be a sad day. If we are investors surely we are all grown-ups with some appreciation of risk and reward?
My 2p.
Jon
Thanks Rhomboid and you are spot on. There are lots of variables to consider when running these events and costs can go through the roof very quickly especially if running an event in London or very close to it....the venues in London that are feasible for doing exactly what we did in Derby cost 5x the amount I have in my budget and it would then be prohibitive on ticket costs.
Mello covers the cost by charging good companies about a quarter of the price that the low grade companies pay to be at London events. I want to attract good companies and encourage investment into good management teams who are happy to engage. If I fail to attract good companies at the right price then my events are simply not viable. I naturally have a harder sell getting them to distant locations but I do try to be fair to everyone by moving it around the country.
You are right Rhomboid1. There is no way that David or the Mello team can force people to keep their appointments. And as for the cost of the tickets..... I attended both days at the Mello Derby event, listened to and spoke to maybe 10 or 15 companies and bought shares in one. Talking to the founder and CEO of this company gave me the confidence to invest. These have gone up 24% so far, a very good return on the ticket, travel and hotel costs. The only reason that I won’t be at Mello South is that I am out of the country this week.
I bet that was Alliance Pharma
Good guess but no cigar TheArb. crazycoops got it right. It was Beeks Financial Cloud (LON:BKS) . It'll be interesting too see how it does over the next few years. Will it be a confirmation that meeting management face to face improves our ability to select good stocks? Or does face to face makes it easier for management to pull the wool over our eyes?
Sorry you are just plan wrong. This is a ridiculous straw man's argument. Let me be clear. I think David is a very good event organizer and Mello Derby was very good. I am making a specific point about how Mello South was marketed and what the reality is. I think people have to be very clear about how they market things otherwise it is viewed as misleading consumers. This is what the law says so it is not me being "churlish" or a "whiner." If you think it is a good idea to market x but sell y then I would be happy to sell you lots of things. You just won't get what you ordered. I don't see how setting up a straw man argument when I am putting forward a specific point is helpful.
On your points:
1) If you are to market an event with high profile speakers - Slater, Brough - you can contractually ensure they will come. That makes sense if you are marketing the event. I personally paid a fair whack as both people were stated to be coming. They were the headline "stars" that I booked tickets for.
2) No refunds - Mello has a no refund under any circumstances policy. This seems odd and unfair given that the event is marketed in a certain way and the reality is sometimes different. The full list of the schedule only comes out a day or so beforehand. So you are buying a ticket in the dark.
I note that David has commented here. I don't think the argument that "if you think you can organize a conference better then do so" is very constructive. How can the two high profile speakers that were "booked" suddenly not be turning up i.e. Slater, Brough. These were the "headline" speakers.
But I think I will leave this here. Other people on this thread appear to think it is ok to advertise something as X and to deliver Y with a no refund policy. Fair enough and good for you!
Dear ratioinvestor
Firstly many apologies for anything that I said that hurt your feelings. One of the things that I like about this site is that we usually find polite and supportive ways to agree or disagree with each other. And on re-reading this thread I find that I agree with some of the things you have said and some of the things rhomboid1 said. I am also not sure whether you were meaning to reply to my post or to rhomboid1 or whoever else joined in. I can understand the strength of your disappointment that the speakers who were advertised when you bought your tickets will not be speaking.
Probably most importantly, I did not call you either churlish or a whiner. Nor did I think of you in those terms. But maybe my wording was not clear enough. My objective was only to highlight the excellent value for money that these Mello events offer. As I said, I have done very well out of my one purchase of shares in a company I met at Mello Derby. And I had a similar experience at my first Mello event (in 2015, I think). At that event I was introduced to the qualities of Bioventix. I bought a day after the event. I have bought more since but the original purchase is now +260%. These two successful trades and all the things I have learned have made me more than friendlyly inclined to David and Mello events.
See you again another time on the SCVR
With all good wishes
Ok thanks. I think we all know and agree here that David organizes good events and is a great host. But if an outsider booked and saw the advertising for the two famous fund managers and then saw they weren't attending after they had paid they would think it is strange. I don't see why that is such an unreasonable or controversial point? I accept that David is a very nice person, a great organizer and Mello Derby was great. I am not arguing to the contrary as some appear to suggest. One of the headline advertised speakers dropping out I could understand. But both just seems odd.
However, if we extend the logic of the argument some have used here you could say this. I could organize an event next year highlighting Warren Buffett and Charlie Munger. Sell no refund tickets and then produce a lineup without both individuals attending. Does anyone seriously think that is something that would be appropriate? I am obviously stretching the point by using the world's most famous investors but the overall issue remains the same. If you do think that would be fine then please send me a message as I am organizing an event "definitely" with Buffett and Munger next week for £500. The actual lineup will have them both dropping out but I will only tell you later after you have bought your non-refundable ticket. If you think that is fine then fair enough I guess!
Hi,
The profit warning today from Connect (LON:CNCT) seems pretty awful to me.
Thankfully I'd got cold feet some time ago, as mentioned here on 1 May 2018 SCVR - pointing out the weak balance sheet, and lacklustre performance (which has clearly now worsened).
For me, it's over - I've today sold the last little scrap that remained in my portfolio. I can't see any reason to hold this share, now that there must be doubts over its solvency - it has too much debt, and we now know it is trading badly. The only upside I can see, is that profits should improve once PassMyParcel has been shut down.
The main reason for holding this share was for the high dividend yield. Although it's another reminder that very high divi yields are a red flag - in recent years the market seems to have been very smart at predicting which companies are likely to cut their divis.
I hope other readers here have not been too badly burned on this one.
Regards, Paul.
1 Anyone is free to organise their own events. I'm not planning to organise any, so would not dream of criticizing anyone else for minor pricing issues.
2 There is a choice between going to Mello & not. We can evaluate the programme & the pricing.
3 The organiser is entitled to try & make a profit & vary prices to do so (or to breakeven). Investors are entitled to take into account this when deciding when to buy tickets for future events.
4 The Derby event was worth every penny & very well done.
Incidentally, I cannot currently make a booking on the Mello website, as it goes to the payment page & freezes up.
jonesj I can get to the mello ticket area in this link https://mellosouth.ticketswitch.com/book/JVNN-mello-south/#perf=none&date=2018-06-14
I had a bit of 'gulp' moment this morning on reading the Connect (LON:CNCT) statement - I couldn't momentarily remember where I had set my safety net stop position.
I was forgetting that it was 55p and had been triggered a little while. I was going to say that was a stroke of good fortune, but of course that is not true to set these stops to cope with circumstances precisely like this (and the fact that it was a guaranteed stop means it would have still got me out at 55p even if it had survived to this morning).
None of this though takes away from the fact that I should not have had this small position anyway, I think I said in previous discussions that this position didn't fit with my current strategy - so why didn't I see - poor self-discipline. Betting (before the event) on issues such as those at Connect (LON:CNCT) being fixed might work in the percentages (after all the 25% I lost compares with a likely gain in excess of 100% had things gone differently) but it's just not what I do any more. I actually one other similarish position, but significantly larger - I need to have a long hard talk to myself!
Anyway on to today's announcement - it was truly horrible, but I'm not sure it was -45% (-67% at one point) horrible especially on an already beaten up share price - it even had one piece of goodish news in it.
This business lost £6.3m last year and the play was that they either bring it to breakeven or close it; lifting group profits by nearly 20%. I am actually surprised they are closing it as it seemed to me they simply mispriced it based on failing to understand the ration between shipments and returns - it is a service that retailers want so presumably someone will be able to meet then need and make money? Anyway, promptly closing it is superior to incurring years of losses failing to turn it around.
We of course, do not know what the exit costs are at this stage.
Moving on
Below expectations clearly, but not disastrous imho given that we already know news distribution is in secular decline.
The worst bit though is in Tufnells
Tufnells H1 revenue was £87.3m and if this is down in the region of 10% and falling directly to the bottom line that looks like a c. £9m hit on this years profits (excluding any impairments).Against this backdrop I don't really understand the comment
Surely that implies a significant uplift in Q4? I delivered that would reduce the £9m I mention above.
Anyway it is not clear why Tufnells' revenues are down, so we don't know whether they might get worse. A "volatile" market is really no description at all. (As an aside I would just say that I think most investors read "volatile" as being fluctuating as a trained Chemist I read prone to evaporation!)
There is a Tufnells' employee who posts from time to time on the ADVFN board and he has been warning for some time that Tufnells is a mess (although it is not uncommon for employees in a business under transition to think that), I don't think though that even he picked up quite how bad things were.
At the end of May annoucing the sharesave option price of 43.6p (20% discount at the time) he said
"I'll take a no-lose punt at that. I've ended up cancelling all the Sharesaves I've been in so far. Surely it can't go much lower!" Hmm.
In summary though :
The CEO and CFO are both going, the latter immediately and interestingly they already have his replacement lined up to start on Monday.
Overall though whilst today's fall "feels" overdone, I don't think there is enough meat on the bone to take a proper judgement and there is still clearly a mess to sort out.
Net debt at £84m(end H1, H2 normally lower) shouldn't be a deal breaker although cash closure costs for PMP and further restructuring in Tufnells could put this number under further pressure,
Not at all tempted to take a position currently until we have more clarity, but the FY results in November should make a fascinating read.
I asked the Tufnells driver who made a delivery to my neighbour this morning what he thought of Connect's results. Perhaps not surprisingly he didn't know about them and didn't seem to care. I was surprised though when I suggested to him that he googled them when he got home in case his job was at risk when he said 'I don't give a stuff mate, I'm self employed, it's all part of the scam'. Not quite sure what to make of that.
I note that fuel costs are also on the rise.
Love it - straight from the Peter Lynch philosophy of investing, even if it was accidental
Afternoon all,
Is it too late for a shout out for commentary on Eckoh (LON:ECK)
ATB,
Mark
Eckoh (LON:ECK)
Not at all - I will find a spot for it on the list. G
i know you didnt have time on ECK, but if chance tom,, surorised so many selling, with postive results in usa, strong pipeline, and good growth expected,,am i missing something
re: Eckoh (LON:ECK). I've run out of time, after failing to cover as many stocks as I intended to. Too many distractions today. Maybe I will get to it on Friday. Sorry about that.
Graham
The Tern (LON:TERN) chart is starting to look like Bitcoin. Can it just be momentum investors? I'm long (and happy).
Mulberry (LON:MUL)
Interested to see your comments on this one.
On a brief look it looks hopelessly overvalued - PER of @70 and low growth - guessing there must be something else in there.
Phil
"Last call for Mello South: I've been informed that the last 30 tickets for tomorrow's conference are being offered at £30.60, i.e. at a 66% discount to the full price."
Never understood the Mello pricing and subsequent discounts. If the tickets were offered at a reasonable price in the first place, there would be no need for late-comer discounts, ShareSoc discounts, BOGOF offers, Twitter giveaways etc.
I had thought some well-known fund managers were presenting:
http://melloevents.com/latest-...
"The theme is Meet the Fund Managers and Andy Brough, Mark Slater, Ralph Baber and others who will be sharing their thoughts with you in the idyllic Kent countryside."
But Andy, Mark and Ralph are not mentioned on the latest schedule.
Yes that makes a lot of sense. It just seems to create bad will. If you paid full price for a ticket. Around £90 and can now see the last few are available at £30 then what would you think? Also I agree that speakers and companies were talked up a lot but as you say many of the fund managers initially talked about aren't going. I paid much more than £30. Why not just have a standard headline price to start with of say £45.
Also you have to book a ticket with no refund before knowing the schedule i.e. who is speaking etc. So it is a bit of a gamble and you have to take based on what is promised in advance. As you state a lot of the fund managers discussed in reality aren't attending. I think it is unfair to promise lots of speakers. They can't make it now but there is a no refund policy. I don't see how you can talk about XYX fund managers attending, sell tickets partly on that premise and then those people aren't in the lineup.
We are lucky to have someone organizing these events. However, I do feel they could be in London as it generally means much less travelling. I also think there should be a video option for people to pay just to see the presentations online afterwards. The cost of Mello South with travel etc can be over £100 for the day which is a far amount IMO.
Just to reiterate we are lucky to have someone organizing these events but I would prefer a London location. Perhaps a conference place in a relaxed area such as Hampstead. I think that would more easily attract fund managers. Or perhaps the small venue in Islington's business design centre.
I also think that as the price goes up these events become much more exclusive and hard for people to access. What about early stage investors, students etc who want to attend but have limited means. I am thinking about not attending now to be honest. Due to the last minute discounted tickets and secondly the lineup being different to what was talked about. If you are going to offer massive ticket discounts you should offer them to everyone. Feels like you are mug if you bought a ticket early on:
http://melloevents.com/wp-cont...
Mello - no event like this can undertake to refund people if a few presenters drop out. Anyway, I would draw an analogy with Glastobury Festival (where tickets are generally told out before the first act is announced) - the sum is greater than the whole and it isn't about the individual presenters.
As far as location is concerned, yes I'm inclined to agree that being South-East of London benefits a very small proportion of attendees compared to those it disadvantages. Derby in contrast was at least closer to the centre of the country than London, and had cheap accommodation. For what it's worth, I'm in the Midlands but central London would have been equally convenient as Derby.
Special offers actually make it more inclusive. Hopefully for most of the people who paid £90 the amount was irrelevant whereas for some people a £30 offer allowed (or persuaded) them to come when they wouldn't have otherwise done so. Yes, in an ideal world it would have been the early birds that got the discount, but leaving empty spaces is in nobody's interests.
leoleo73 - This is not a few presenters dropping out. This is pitching it as a fund manager event but the three fund managers highlighted aren't attending. In reality no fund managers appear to be talking. My point was that you can't market it on one premise and the reality being very different. If these presenters weren't certain it shouldn't of been marketed using them. People book for the main headline acts - Slater, Brough - but these guys aren't attending it seems. It is like advertising Glastonbury with high profile headline acts that aren't now attending. That just comes across as false advertising to me. If speakers aren't confirmed don't use them to advertise the event.
South-East London - It just seems too far away for me. It takes the same amount of time to get to Derby by train!
Special offers - To me it comes across as trying to get the most out of attendees. I.e. those that can pay more we will sell high priced tickets to. Then we will try and get price sensitive people on other tickets. You can't do very high priced tickets to people that book early. Then do discounted tickets at the end. The people who bought the high priced tickets did so on the premise that this was the price you had to pay and that it might sell out. When Apple discounted its initial iPhone it offered receipts to early buyers too so they didn't feel annoyed.
I think Derby was about £80 for two days or something. This event is £90 for one day at the headline price and the headline people who they said were going to attend aren't going to attend. To me that doesn't seem fair but that is just my view. If you had booked Mello South for £90 and on the premise that it was the advertised "fund manager event" and now no fund managers are attending and tickets are £30 I personally think you would have every right to feel annoyed.
Obviously here I come across as a whiner. I don't really see it like that. I just think that events should deliver what they promise. Secondly they shouldn't offer special deals as this just makes it seem unfair. Instead of all these special deals why not just have one fair price. If the £90 price is too high and you can't sell the tickets then the price should be lower. It is like Lidl/Aldi versus other supermarkets. We hate all the gimmicks of the supermarkets but like Lidl/Aldi's standard price without gimmicks. It just seems fair.
If someone was coming from the North to see say Mark Slater, Andy Brough and had paid £90 I think they might be somewhat frustrated. That is Just my view. Event was marketed like this on 9 June (a few days ago). Highlight is mine:
25 good quality companies, great speakers/fund managers & really interesting panel sessions & interviews lined up
My main point is that you can't use high profile fund managers to market an event and then mysteriously they aren't appearing. How can that be fair? I could market an event based on Robbie Williams headlining and then produce a schedule two days before without him on the roster. Not least given that Mello is quite expensive. For Sharesoc you can go to events for free after you have paid the annual membership of about £50. You see fund managers and companies at their events. UK Investor, Master Investor and Shares event are also free effectively (if you get tickets in advance).
Looking at the companies at the event and Eserveglobal is rated as a sucker stock here. Ten Lifestyle has a stock rank of 15, Corero stock rank 24, Non-Standard Finance stock rank 14, Redstone Connect ROCE of 6.5%. So the general quality is quite mixed although there are some quality companies at the event.
Mello pricing of tickets is based on those who are based in the City but choose not to be members of ShareSoc pay full price.....Stockopedia & ShareScope subscribers receive a discount and ShareSoc full members get the best discount and reduced membership as I personally want to encourage investors to join ShareSoc.....the rest is down to the very last minute offers if tickets are still available and we still had 30 this morning. I think that is fair and reasonable.
Speakers can change but we do have a great line up and although Andy Brough had to pull out last week we still have Ralph Baber ( Slaters) and John Warren (partner to Paul Marriage) who are both top fund managers and Guy Thomas is coming who could not be headlined months ago so clearly speakers can change....that is what you have to cope with running these quality events. I do not want a free show with poor quality companies on display.
Those who attended Mello2018 were delighted to have been a part of it. This event is a trial one day show....I may get it only part way to what we want to achieve and may get parts wrong....a learning curve but what we have is really worth having compared to seeing companies that most who read these reports would never want to invest in !
I do my best and if any of you want to try to run an event rather than being just an investor then please give it a go.....I will happily relax and attend. David
Trakm8 Holdings (LON:TRAK) - TRAKM8
Up 10% on no news?
Re Northern Bear (LON:NTBR)
My previous comment on Northern Bear, which I made after February's trading update, is here.
Northern Bear exhibits much the same characteristics as Triad (LON:TRD) , both in terms of valuation and share price action (my comment on Triad in Monday's SCVR is here). Yesterday both stocks were classified by Stockopedia as speculative contrarian micro-caps, but Triad's full year numbers have today been incorporated into its StockReport and it's been reclassified as a 'super stock'.
February's trading update allayed fears that Northern Bear had been caught up in the Carillion collapse and the share price jumped as a consequence, but in March it slumped again, most likely on fears that operations had been affected by the 'Beast from the East'. Bad winter weather will always be a concern with this company (it's the reason it doesn't pay an interim dividend), but it's worth bearing in mind that it's high winds that are the primary issue due to the curtailment of roofing work. Also, this is a double-edged sword - wind storms disrupt operations but at the same time they can cause a lot of roof damage which is good for future business.
Even though I didn't think the hit to trading from March's weather would be as bad as 2015/16 when there were periods of persistent high winds, it was nevertheless a surprise this morning to read such a positive statement from the company. The Feb trading update said that adjusted profit before tax (i.e. not including transaction costs and amortisation of acquired intangibles associated with the H Peel acquisition) was running ahead of last year, but now they're saying that PBT will be ahead even with these exceptional costs included.
It's clear that the dividend will be raised, but I don't think they should up it by much. Northern Bear's balance sheet isn't great, and I'd prefer the company to strengthen it by building up a working capital buffer. This is something that has become more important in the aftermath of Carillion, with public bodies in particular now scrutinising the financial strength of contractors a lot more closely (one of the reasons why Morgan Sindall (LON:MGNS) is looking so strong).
As for news flow, there's never been much out there for Northern Bear, but I note that at the end of March the company released a statement (not as an RNS though) saying that CEO Graham Jennings was stepping down as MD of subsidiary Jennings Roofing so that he could concentrate on his primary role "due to the expansion and further development of Northern Bear". Also, a few days ago there was this news piece which shows the almost-complete High Point View building which has replaced the derelict High Point Hotel on Whitley Bay's promenade. NTBR's subsidiary Northern Bear Building Services handled this contract.
I continue to hold.
Thank you for your valuable contributions on Northern Bear (LON:NTBR). I have referred to them in the report. G
Thank you for the acknowledgement, Graham.
For some reason I keep thing Dewhurst $DWHT is a Butchers.
Must be having a senior moment.
I always mentally add in an extra word or two to meaningless company names so I can remember what they actually do. Company names used to be like that. So today we have "Mulberry Handbags", "Northern Bear Building Services", "Connect Parcels", "Charles Stanley Stockbrokers", "Biffa Waste", "Dewhurst Lift Controls", and "Norcross Bathrooms". Also, companies should be banned from calling themselves anything containing the word "solutions" unless they are actually in the business of selling solutes dissolved in solvents!
I think we already know that Graham (also Paul) is not a fan of low margin building contractors so unlikely to be very positive on NTBR.....But I like (and hold) it......very undervalued IMHO!!
I hold Ebiquity (LON:EBQ) as one of my two "punts" for 2018 but today's RNS does not look good. Despite an optimistic twist from Ebiquity's RNS, the stark fact is that the Competition authority (CMA) has given Ebiquity and Nielsen until just June 20th to show how a monopoly is not created in the sale of EBQ's media division.
This sale is key to EBQ's development and cash position and a failure to sell would seem to be unpleasant. The share price has spotted this
Northern Bear (LON:NTBR) please
Norcros (LON:NXR) FY Results to 31st March 2018. This is one of my largest holdings. Here are my thoughts - I would very much welcome the opinions of Graham and other contributors.
Results generally look good for a stock with a forward PE of 6.5, with underlying diluted EPS up 6.1% (the adjustments being reasonable). The dividend has been raised by 8.3% which suggests confidence although the yield is not high probably due to the weak balance sheet.
In November they bought Merlyn, a shower tray / enclosure supplier funded by a mixture of new equity and cash. This has provided a significant boost to reported turnover, profit and EPS figures. We can look forward to a continued benefit in 2019 with a full year's contribution and in particular the next interims which will go from a zero to a full contribution. The current P/E is 199.5/29.5 = 6.8 vs forecast of 6.5 which suggests this may not be fully reflected in forecasts. Note that debt shown on the stock report hasn't been updated yet for the new borrowings.
Approximately 1/3 of their business is in South Africa and this continues to grow faster than the UK business. As it becomes a larger this has the potential to make an increasing contribution to overall growth. There are risks, but I see this exposure as a positive thing.
This is a company with a large pension scheme who's deficit that has been reducing in recent years. This has continued, however not to the extent that I think payments can be reduced yet. I think there is some realistic hope this may happen in 3 years time and announced in the HY 2023 results. This could realistically add 10-15% to EPS. The reducing deficit also provides a significant boost to their weak balance sheet. Conversely any worsening of the pension deficit is a significant risk to both the balance sheet and profitability.
Having apparently missed their strategic objective to grow revenue to £420m by 2018 (it is reported at £300m), they now plan to increase it to £600m by 2023. Regardless of whether the succeed, any serious attempt will require acquisitions and, given their existing debt, dilution. Perhaps their previous failure to meet their growth target suggests they are carteful to wait for the right opportunities, but personally I would prefer they paid off their existing debt and then bought back shares or raised their dividend.
Overall I am happy to hold, although as a large position I may trim exposure if the price rises significantly.
Leoleo73 Norcros (LON:NXR) is now my 2nd largest holding and like you I am happy to hold as I hope & expect the share price to continue to drift up further whilst paying decent +/- 4% dividends on this delightfully boring stock. I like the continued focus on innovation and exports and they do seem to be pulling out group synergies. Plus all the acquisitions are all working - there seem to be reasons to trust the mgt. Triton seems to be finally improving and even the weak spot (Johnston Tiles UK) must have a decent chance of recovery after its latest round of restructuring to cut costs and decision to focus on a niche market of small tile formats. I also worried Merlyn might cause indigestion but no sign so far.
Big picture this share was held back by i) its pension deficit - now decreasing in both absolute terms and relative to group with (surely!) mid term help from interest rises ii) its focus on South Africa - where a new president promises better governance and growth and a chance for the whole Southern Africa region (Mugabe also gone, commodities on the up). There is still a risk of a UK housing or consumer recession but the group is larger and much more diversified now, with debt still under control at 1.2 EBITDA.
Share price as I write (212p) is the highest its been since it crashed in 2007 recession. A PER of 8 would equate to +/- 250p. Nothing is certain in life but risk/reward looks good for continued modest gains IMHO.
Charles Stanley (CAY) FY results 2018 out today, here's a video with the CEO & CFO. Good embellishment to the results RNS today. Also good insight to the sector.
http://www.piworld.co.uk/2018/06/13/charles-stanley-cay-full-year-results-2018/
Paul Abberley, CEO
Year achievements - 00:14
Ben Money-Coutts, CFO
Financial highlights – 01:16
Paul Abberley, CEO
On-going strategy – 04:32
Market outlook – 05:12
Investor outlook – 06:20
Also important for anyone who uses Charles Stanley (LON:CAY) as a broker. The recent revelation (c.f. Beaufort Securities) that administrators can dip into ‘ring fenced’ investment accounts (climbing the fence to scrump the apples from the apple trees) makes it even more important to monitor the financial health of our brokers. And I wonder whether brokerage clients will start to move their accounts to larger (and therefore considered safer) brokers.
I will watch with interest. I don’t hold CAY but I do have a brokerage account with them.
My morning smallcap tweet: Bear bullish. Connect's Cashmore cashiered.
Norcros (LON:NXR), Haydale Graphene Industries (LON:HAYD), Crystal Amber Fund (LON:CRS), Connect (LON:CNCT), Northern Bear (LON:NTBR)
Norcros (NXR) Even makers of bog-standard stuff like showers, taps and tiles are promising to "leverage Group synergy opportunities." FY looks OK, bullish words but no current trading nos. I hold.
Haydale Graphene (HAYD) warns on FY, guides rev up 15 to 20%, pretax loss 'below expectations'. Or worse than expectations if you don't want to be ambiguous. "We remain confident, however, that this is primarily a timing issue and that many of these expected forecast sales should now be recognised in FY-2019." CEO steps down to a sales role or "business development in the UK and abroad" to spin it nicely.
Crystal Amber (CRS) will increase the performance fee paid to Crystal Amber Asset Management (Guernsey) Limited, a related party. Divs will now be included in total return. Why did the sharp chaps at Crystal Amber Asset Management not spot that in the contract in the first place? Or do they just fancy a pay rise?
Connect Group (CNCT) FY materially reduced profit expectation due to 'extremely disappointing' trading. They are able to use such a phrase because the CEO & CFO are sacked. Div will be slashed or passed. CEO was Mark Cashmore.
Northern Bear (NTBR) trading - continuing operations have continued to trade strongly and ahead of management expectations in H2 despite the severe winter weather. I hold.
Morning all,
Nice trading update from Northern Bear (LON:NTBR) this morning. I think there were a lot of concerns on the impact of the weather this winter on the building services group - however trading still strong and ahead of management expectations despite this. Hopefully that eases these now and the sp will start to head in the right direction. Paul and Graham have both covered positively in the past year.
Any other holders/thoughts? I am long, having taken a small position this year.
Cheers
I suspect the north east based Northern Bear (LON:NTBR) slips under the radar of many southern based investors, and hence does not get the rating it deserves. Its track record is excellent and deserves a higher rating.
I hold,but would be interested in Graham's views.
Richard
Northern Bear (LON:NTBR) tends to release pretty good results have a great price gain on the day and then drift down over the next 3-6 months. It is still 9% below the opening price last time it released an RNS despite issuing nothing but good news.
Hi, I'd be interested in your thoughts on Eckoh (LON:ECK), on the face of it a fairly good lull year trading update I thought, US growth strong but some issues in the UK that are being corrected. Whether its enough to carry a fairly high PER I'm not sure, guess we're about to find out :)
I agree with Reacher that the Connect (LON:CNCT) update is one of the ugliest I’ve seen in recent times. Tin hats for holders this morning.
At the other end of the spectrum, small cap tiddler Northern Bear (LON:NTBR) has come out with a pretty effusive “ahead of expectations” trading update where the board are “pleased” and “delighted” in equal measure about several things.
https://www.investegate.co.uk/northern-bear-plc--ntbr-/rns/trading-update/201806130700051812R/
Also an honourable mention for Norcros (LON:NXR) which reports full year results steadily ahead across most key headline metrics.
https://www.investegate.co.uk/norcros-plc--nxr-/rns/results-for-the-year-ended-31-march-2018/201806130700051829R/
Gus.
Morning all - a nasty trading update from Connect (LON:CNCT) with expectations being materially reduced. Pass My Parcel division will be closed. CEO will be stepping down and CFO steps down with immediate effect. The dividend will be reduced.
https://www.investegate.co.uk/connect-group-plc--cnct-/rns/trading-update/201806130700081916R/
It's one of the most brutal RNS I ever remember reading, I wonder how the market will react. Objectively it seems pretty positive to me, declining businesses using the legacy cash flow for mistaken transformation projects is a classic error, and they seem to be on the ball here. Couldn't help put a limit order (at 14p) in case of opening chaos.
Dixons Carphone (LON:DC.) is reporting a data breach, so it may be worth putting in a low limit buy there too!
Connect (LON:CNCT) . I have the team from Conviviality (LON:CVR) to thank for avoiding that one - following the fiasco there I looked through my portfolio for similar shares and sold CNCT at 60p. Although I made a loss I'm going to chalk it up as a "win".
Graham, I think you mean Weds 13th June in the heading!
Looking forward to your comments.
Thanks Chris