Small Cap Value Report (Wed 16 Jan 2019) - SOM, NXR, OPM, HEAD, CLIG

Morning all,
A busy round of updates. This list is provisional:
- Somero Enterprises Inc (LON:SOM) - trading update
- Norcros (LON:NXR) - proposed acquisition and trading update
- 1pm (LON:OPM) - interim results
- Headlam (LON:HEAD) - trading update
- City of London Investment (LON:CLIG) - trading update
Somero Enterprises Inc (LON:SOM)
- Share price: 337.5p (+15%)
- No. of shares: 56 million
- Market cap: £190 million ($244 million)
Well done to holders, as Somero delivers that pleasant phrase: "ahead of expectations".
Key points:
- 2018 revenues and EBITDA "moderately ahead of market expectations". (EBITDA was expected to be $29 million)
- net cash "more significantly ahead of expectations" (it was expected to be $25 million)
- no change to dividend policy
The company is excited about its new product, the SkyScreed 25, which you can watch in operation at this link. It will be officially launched later this month.
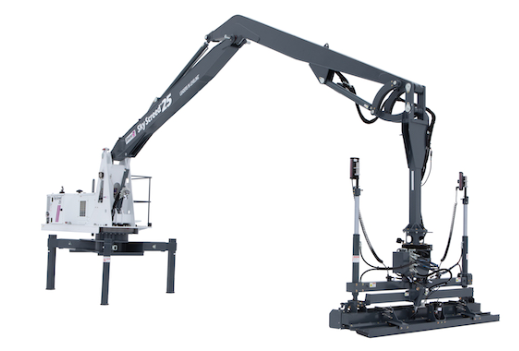
A booming US construction industry is responsible for Somero's outperformance, as Europe, China and Latin America were all down by varying amounts.
My hunch that it will be impossible to penetrate China is unchanged after the company says its efforts there "have yet to gain full traction".
Outlook
Confident of more profitable growth in 2019.
My view
Stocko shows a forecast for net income of $21.4 million for 2018, rising to $22.7 million in 2019.
"Moderately ahead" - is that a 3%-5% beat? Perhaps 2018 net income was $22 - $22.5 million? And 2019 income could be $23 - $24 million?
Let's assume that the enterprise value is in the region of $210 million, after deducting an estimate for Somero's big cash pile.
So I would put the cash-adjusted P/E ratio for 2019 at c. 9x. Stockopedia's 9.4x estimate for the rolling P/E ratio is possibly too high:
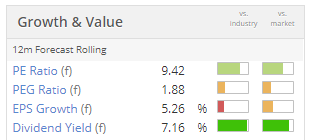
Whichever way you look at it, the company is cheap on conventional metrics and is a top performer when it comes to return on capital, operating margins, etc.
So it's difficult for me to argue against the view that the shares are still undervalued, and perhaps structurally undervalued due to their listing on AIM.
When I studied this company in some detail, I came to the view that it faced very little competition, at least in North America/Europe, and I believe that this is still the case. It offers the best machines and one of the very few options when it comes to achieving flat concrete floors. This explains its surprisingly high returns.
Congratulations to holders. I can't quite convince myself to buy shares in a small American company, so I will leave it to others to enjoy the ride.
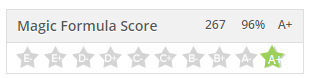
Worth noting that the StockRank is an excellent 88, and it has an A+ from the Magic Formula Score, i.e. high returns and low valuation.
Norcros (LON:NXR)
- Share price: 195.7p (+0.4%)
- No. of shares: 80 million
- Market cap: £157 million
Proposed Acquisition and Trading Update
Let's cover the first thing last: trading is in line with expectations. The bathroom/kitchen products group is experiencing a "challenging" environment, but expects to outperform its markets and deliver results in line with expectations.
Nothing wrong with that at all.
Separately, it is buying a South African plumbing materials company for up to £12 million. It made pre-tax profit of £1.9 million in FY 2018.
Acquisition Rationale: expand the bathroom portfolio with complementary products, reinforce the Group's overall position, and strengthen the subsidiary with Norcros' distribution channels, etc.
My view: Rather like Somero, I can see some strong arguments for investing in this company. It is cheap on a P/E basis (6x), is being managed well, and is executing its plans. It has some recognisable brands, e.g. Triton electric showers, and has an excellent track record of profitability (nearly always profitable).
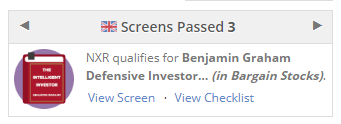
It also has a very strong StockRank of 86, and passes three of the Screens (in Bargain Stocks, Income Investing and Growth Investing).
Against that, you have to bear in mind the debt load (£53.5 million at September 2018), the pension liability (£29 million), the lack of organic growth, and the exposure to South Africa (one-third of revenues).
In conclusion, I'm inclined to think that these shares are priced about rght. For example, trailing EV/EBITDA is 6.5x according to Stocko. Its latest acquisition, excluding the earn-out, is at a trailing P/EBITDA rating of 5.2x. Norcros certainly deserves a higher rating than an undiversified subsidiary, but I would be surprised if it deserved a rating that was 50% - 100% higher.
1pm (LON:OPM)
- Share price: 46p (unch.)
- No. of shares: 87.6 million
- Market cap: £40 million
This SME lender is doing fine - all the financial metrics making positive progress. Revenue up 15%, EPS up 12%.
The only slight negative is that the bad debt provision has nudged up to 2% of the portfolio (1.8% a year ago).
60% of loans it originates are forwarded on to other lenders, with the rest being funded on its own balance sheet.
Organic growth has been the focus over the past six months. Acquisitions are a possibility in the next phase of growth.
Outlook is optimistic.
My view
There is no reference to return on equity (ROE) in today's results - it would be helpful to get a comment on how the company sees this metric evolving for them.
At its final results for FY 2018, it reported return on capital of 13.3%, up from 11.5%.
A note published by Hardman says that ROE was 13% in FY 2018, and forecasts the same again in FY 2019 and FY 2020.
That's quite a reasonable level for an SME lender, in my view. Being paid research, I presume these forecasts match with what the company itself expects to achieve.
The company's history of acquisitions muddies the calculation, however - goodwill is £28 million, i.e. more than half of balance sheet equity. Tangible equity is just £23 million.
My portfolio holding, PCF (LON:PCF), currently trades at nearly 2x tangible equity. 1pm (LON:OPM) is at a similar multiple at the current share price.
I'd rather take a conservative view and value it based on tangible equity - from that perspective, 1pm looks fairly priced. While its P/E multiple is undoubtedly very cheap at just 6x, that looks to me like a fair reflection of the balance sheet position.
By the way, I note rumours that Atom Bank is about to be snapped up by BBVA. I wonder if this could become a trend - challenger banks getting bought out by the big names.
Headlam (LON:HEAD)
- Share price: 394p (-1.5%)
- No. of shares: 84.6 million
- Market cap: £333 million
Let's take a quick look at the update from this floorcoverings distributor.
2018 is in line, after much concern that it would be a miss.
2019, on the other hand, is pointing lower. Reasons given:
- a changing revenue mix leading to lower margins
- higher distribution costs, administrative expenses
- efficiency initiatives being at an early stage
This seems like one of the better companies associated with floorcoverings. The description of the business on its own website is very clear. It provides a massive logistics operations, enabling suppliers and retailers to focus on their own core strengths.
It is preparing for Brexit by stocking up on additional inventory - sensible.
Headlam has net cash, good returns, and isn't spending too much on acquisitions. It's keeping things simple - I like simple!
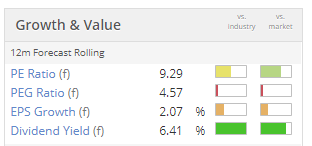
I'm leaning towards the view that this one is underpriced. Hopefully it can start to grow profits again by FY 2020:
City of London Investment (LON:CLIG)
- Share price: 361.65p (-4%)
- No. of shares: 26.7 million
- Market cap: £99 million
FUNDS UNDER MANAGEMENT - Trading Update
This investor in closed-end funds has seen a net outflow of $42 million over six months, and negative performance has contributed to a total reduction in funds under management (FuM) of some $480 million.
Key points:
- FuM is $4.6 billion at Dec 2018, versus $5.1 billion at June 2018.
- The primary strategy, Emerging Markets, outperformed, but the newer strategies all underperformed.
- On a positive note, CLIG has received notification of inflows worth $125 million to be funded over the next quarter
The update includes a link to the following picture, showing that the current dividend (plotted with squares) is worth almost as much as the company's entire net income:
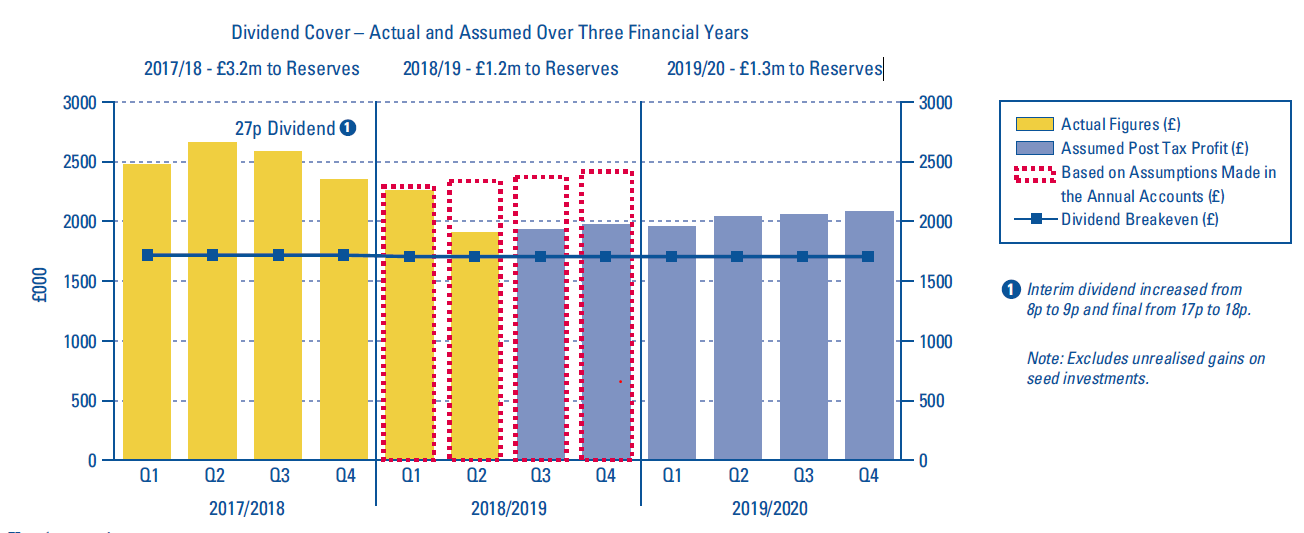
The dividend yield is a stonking 8%.
I would think that prospects for long-term growth are probably still good - emerging market asset managers enjoy some nice tailwinds. Short-term developments have been a bit disappointing, and the share price reaction has left the stock with a ValueRank of 98. The Stocko system ranks this as a Super Stock.
So this is another fund management company that I am keenly interested in. I also think that Ashmore (LON:ASHM), Jupiter Fund Management (LON:JUP) and Schroders (LON:SDR) are worth a look.
Other stories in passing:
- City Pub (LON:CPC) - trading in line, acquisition.
- Works co uk (LON:WRKS) - gifts & stationary retailer trading in line, loss-making but plans to grow
- Van Elle Holdings (LON:VANL) - weaker margins in one divison and a revenue miss at another means full year performance significantly below expectations, shares down 25%. High StockRank, could be worth investigang.
- EKF Diagnostics Holdings (LON:EKF) - adjusted EBITDA ahead of expectations
- Actual Experience (LON:ACT) - early stage company, loss-making but confident. Sucker Stock.
That's it for today. It's hard to cover things in a lot of detail when there are so many updates - hope I provided a few ideas for you at least!
All the best
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Hello wavewarrior
Somero Enterprises Inc (LON:SOM)
but no comment on the High Risk Earnings Manipulation according to Stockopedia
Your wish is my command albeit i sometimes comment plenty of gibberish and this is the first time i have dug into this useful stat.
Ok
First up i am kind of guessing the fact we have passed the year end but the final accounts aren't submitted means we should expect the current figures to be out of date pretty soon once "last" years finals are released and processed.
Ok stocky is fantastic all green and red boxes - that makes it simple.
Margin/asset quality/sales growth excessive/depn stable/sales expenses out of control (like that one kinda auto "don't invest" flag that one) /financing stable / accruals nice and low (all dodgy accounts come with high accruals did you know)
ok stocky has green safe mark for all of these tests - thats looking good.
Ok the big red fail is on "are receivables increasing in proportion to sales" - presumably this is an auto fail in a similar manner to my comments on accruals.
Ok we have a bonus in that stocky gives the overall package a number with some nice comments that are whoosh over my head.
The exact Beneish threshold varies depending on the relative error costs of missing out potential manipulators versus mis-classifying a non-manipulator (Type 1 vs. Type II). A -1.78 threshold implies a 13.8% chance of mis-classifying a non-manipulator, which Beneish suggests is a reasonable compromise level.
Ok the number for somero is -1.75 - oooooh thats so close a miss as not really a miss.
However it is a miss so i would say there is a 13.765432% chance that something could be dodgy - pick a number between 1 and 8 and hope that aint the number at the bottom of this page.
ok lets drill down to the dodgy numbers
2016 receivables 6.3 - 2016 turnover 79.4
2017 receivables 11.00 - 2017 turnover 85.6
WTH (eck) thats a 74% increase in receivables and an 8% increase in turnover - that sounds incredibly dodgy on a comparison of the numbers - so one can see why there is a red flag.
Time for a sanity check and back to real life what about the debtor days
thats about 42 days for 2017 and 26 days for 2016 - in the real world 26 days for debtors is eceptional and 42 days is probably fair to middling.
ok lets look for comment from the company
even with the year-end increase to accounts receivable driven by particularly strong sales in December 2017,
Ok thats a perfectly simple explanation that rubbishes my calculations of debtor days - fair play to the company for explaining it so simply.
Lets chuck in the provisions for good measure - ok less bad debt in 2017 but one would expect this to be fact based number so nowt to worry about.
As of December 31, 2017 and 2016, the allowance for doubtful accounts was approximately US$ 859,000 and US$ 743,000, respectively. Bad debt expense was US$ 141,000 and US$ 400,000 in 2017 and 2016, respectively.
in summary i have zero concerns and the red flag is on just a red flag and a pretty dubious one at that - that's what mechanical filters do though - its not like they could ever program a computer to beat the best Go player on the planet (the look on the poor Lee's face when he realised the computer had outsmarted him and the game was lost was classic)
4
Interesting (if I might say a little quirky?) run through of the Somero Enterprises Inc (LON:SOM) earnings manipulation risk score rmillaree, thanks for that.
As you point out the only sub metric on which Somero Enterprises Inc (LON:SOM) fails is the "Are receivables increasing in proportion to sales?" and then only marginally.
This can be a useful indicator as it can show that a business (in order to make it's numbers look better) is recognising revenues that it may not actually be entitled to, perhaps because the particular contract milestones that would make the revenue contractually due have not been completed (and perhaps if things don't go to plan may never do so), or worse perhaps because there is an active deception going on in order that someone can meet their targets.
I have some indirect experience of the latter having happened.
Of course the answer can sometimes be much more benign and simply reflect, as is the case here, that it you make a lot of sales late in the year where the payment terms mean the cash will come in next year then this ratio will look elevated.
This isn't the first time I have seen "false flags" from the earnings manipulation risk score.
Fairly recently I was looking at a company that failed three of the eight tests of the M-score.
So to my mind the Beneish M-score (earnings manipulation) causes one to ask some useful questions, but if those can be answered satisfactorily I am personally totally comfortable.
On the other hand the stocko description of the measure says
Some while ago I had a dig into some of this research (until my eyeballs started to bleed - why are statisticians incapable of using clear language?)
Anyway I think (happy to be corrected) that the was that
And not that
86% of companies that are flagged by the Beneish test are manipulating their earnings.
An important difference and like rmillaree, I cannot see a real concern in this case.
A lot of favourable reaction to Somero (SOM) but no comment on the High Risk Earnings Manipulation according to Stockopedia
Patisserie Holdings (LON:CAKE)
The only useful information that they should be able to give us is what is happening about trading from the day after the bad bod was chucked out. Presumably the first thing they would put in place is a simple system to log stuff in a reasonably accurate manner from that point on the bad egg has gone.
all they say is the following
It will take some time before a reliable trading outlook can be completed
What a joke that the management / directors backed by their forensic specialists and big buck accountants cant have set something up so they could add up the figures for the period 11/10/2018-10/1/2019 - 3 months new clean slate stuff and release within 7 days. The lack of anything useful other than ii's worse than we feared makes me think this may be a terminal situation in the near future or a situation where only the very best outlets are pre packed and shipped out to someone in the know for a fiver or 5 veggie sausage rolls picked up from Greggs. Hopefully its not that bad as there is loads of jobs on the line here for the actual staff in the stores who do the real work serving customers every day and sorting out deliveries behind the scenes etc.
Patisserie Holdings Patisserie Holdings (LON:CAKE) update states that the extent of the fraud was even more extensive than previously thought....thousands of false entries in the ledgers!
https://www.investegate.co.uk/patisserie-hldgs-plc/cake/company-update/201901161553543018N/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=Patisserie%20Hldgs%20PLC%20Alert
It sounds as if they haven't uncovered half of what was going on: "among other manipulations, this involved thousands of false entries in the Company's ledgers." This seems to have impacted the assessment of current trading which Patisserie Holdings (LON:CAKE) gave back in October 2018.
Are the systems so corrupted that an assessment of trading from 1 October cannot be made? Are there any consequences for those complicit in the fraud? Also, what value did Grant Thornton's audit provide insofar as they were unable to detect this material misstatement, and the significantly deficient internal controls?
Further thoughts re Patisserie Holdings (LON:CAKE). If there are thousands of false entries in the ledgers I would guess these must be false cash sales postings as surely no other items of income or expenditure would run to thousands, hence revenue and cash balances would have been overstated. Which begs the question why would someone falsely inflate the takings? And yes standard accounts preparation and audit procedures ought to pick this up through bank reconciliations.
I can think there might be several reasons why this would be done - for instance employees might be assessed on this metric and it might be tied to bonuses.
Understood ...but thousands. That must imply the same thing happening across many branches
ref - posting of thousands of thousands of false transactions I am presuming it would be pretty simple for one individual with master admin rights to post that volume of transactions without any difficulty - it’s probably as simple as keeping the garden neat and tidy during summer for a fit retired individual who has 8-10 hours per day spare with not much else to do. Posting 25 transactions a day to keep any nasties out of sight and keep the fake summary numbers ticking over would probably take at most 10% of their daily effort that’s 5k a year - probably their easiest task of their day if no one is really closely checking what they are doing. Ideally one would like to think that this could never happen but so many business owners hand the keys to the safe to their trusted staff that - all they may then want to here at the end of the month is what they want to be told - ie yes boss you made a shedload of dosh - I am guessing this case could potentially be as simple as that despite this being 400 million pound business at that time. Motives of one random individual could be anything and may have started out as simply not wanting to disappoint a somewhat stubborn boss who may not want to hear bad news or be overly unaccepting of the person presenting bad news that is not their fault, it could be someone with a desperate need for cash short term or any of the other psychological traits that would lead them down that route.
stockopedia's financial warning signs should be followed by some simple analysis to see if there is really a reason to have concerns. As Millaree,s analysis shows there should be nothing of concern wrt an easily explicable increase in receivables from one year to the next. A simple price increase at year end can bring forward sales and result in an increase in receivables.
Nice to have you back Graham, a very comprehensive update, as usual
The government announced yesterday that the (no) fees to tenants bill will become law on 1 June 2019. From that date there will be all sorts of restrictions on what can be charged to tenants, deposit levels and so on. Very good news for tenants, less so for landlords and very bad for letting / estate agents. Income from letting is more important to most agents that sales income. Stocks like Countrywide and perhaps Purp and others will need to invent themselves. With the bookmaker gaming machine limit due soon, which I support, this change and the constant closing of larger stores by M and S amongst others I cannot think what the High Street will look like next year. Far fewer bookmakers and estate agents won’t be a loss I guess. Planning changes will allow change of use of shops to residential. All this has to have a big impact on other companies apart from retail. Landlord insurance is a definite growth area for instance. Small and medium sized building firms are so busy at the moment. Lots of others will do well I am sure
Good to see some independent copy on SOM. I have been in and out of this (at the top) and been watching its steady decline. Now have gone back in. The introduction of the new Skyscreener is a no brainer excuse for getting back in. As far as I am aware there isn't a similar piece of kit out there. Labour cost savings will have a big impact on building costs and I can see this being a world class beater and the price has just broken out of its 4mth down trend so to my way of thinking it is providing another chance to make a few bucks!
Paul I am watching SOS but not as excited as I am about SOM!
Another SuckerStock GetBusy (LON:GETB) updates
" Following on from the Group's strong trading in the first half of 2018, trading in the second half has continued at a similar pace. The Group expects to report that total revenue increased approximately 20% to £10.9m, on a constant currency basis. Adjusted EBITDA is expected to be in-line with expectations while cash as at 31 December 2018 was substantially better than expected at £2.5m, compared to £2.4m at 30 June 2018.
Growth in the Group's high quality recurring subscription revenue, at constant currency for the full year, was 22% with the growth rate in the UK accelerating to 17% following strong order intake and the transition to a pure subscription model. Annualised Monthly Recurring Revenue at 31 December 2018 was £10.3m, an increase of 19% at constant currency."
The broker forecasts a breakthrough into profit when 2018 figures are released on 5 March, but that normalised EPS will show a loss that year and the following year.
GetBusy (LON:GETB) passes the R&D Breakthroughs screen.
[no position]
Sucker Stock Seeing Machines (LON:SEE) issues an update: "The Group is expecting to report revenue for H1 2019 of A$13.5m (H1 2018: A$14.6m), which is in line with the Board's revised projections following the review of the Fleet business completed in September 2018.
The Board's expectation for FY2019 revenue to be approximately in line with FY2018 remains unchanged."
Realism dawns: "
the introduction of fully driverless vehicles at Level 4 and Level 5 is now anticipated to be much further away than the industry had predicted…”
Good morning Graham
Further to your 18 Sept report on City of London Investment Group (CLIG).
Would you please review todays funds under management trading update.
Thanks
Pablo
Hi Pablo, yes, I'm working my way towards CLIG. Cheers. G
Another busy day of announcements. More votes from me for coverage of Headlam (LON:HEAD) and 1pm (LON:OPM) . I'm also interested in Somero Enterprises Inc (LON:SOM) and Norcros (LON:NXR) but they have I think been covered very well in previous reports. Both of those acquisitions look like positive news.
Another request for Somero (LON:SOM) please.
Dividend policy maintained and with net cash up next supplemental dividend should be higher.
New products “meaningful contributors” to strong performance. And launch of SkyScreed25 imminent.
US strong but they haven’t cracked China yet.
Seems a lot to like; the more so since share, even after 15% bounce so far today to 337p, is still well down from September’s 422p 2018 high.
Van Elle Holdings (LON:VANL)
i have never looked at this one - on an initial inspection it seems to be a bit of a mini ongoing car crash at present.
It looks like the new bod in charge is laying out some clear simple steps that look good on paper - but the actual business performance is going backwards - they updated on 10th December only a month ago - but are now blaming what looks like some of the same reasons for delays - for a worsening since 10/12/2018 - all while confirming trading was in line H1. Strewth perhaps the new bod has been dropped in at the deep end but i would have expected them to kitchen sink and move on by now ?
presuming this is a services type business they can be fickle and decent margin contracts can be hard to come by.
There is really nothing here that gives me any confidence that they will achieve anything like the decent numbers that stockopedia projects into the future - way to much uncertainty here for me despite this being a "super stock" for now (will that last past broker updates). Perhaps one to come back in 6 to 12 months to see if they are back on more solid footing trust wise - give us a target then hit it please.
Re Norcros (LON:NXR) - Buy and build strategy is the declared Norcros strategy. So given this, buying House of Plumbing in South Africa for x6 earnings looks a good buy and fit (as have their other purchases in last 5 years). Very focused bolt on but does get them outside of tiles and opens up more opportunities for cross selling the other UK centric brands.
Given debt is raised locally, it also frees them short term from the need to repatriate capital across 2 variable exchange rates - sterling and SA rand. Of course, it also further dilutes the pension scheme.
Given trading is otherwise in line I am happy to keep on holding, recognising the price reflects several risks (SA politics & X rate, cyclical housing, pension, sterling).
.
Somero Enterprises Inc (LON:SOM) - As well as being ahead of forecasts for FY2018, I thought the outlook was particularly forthright for such a US-focused business:
It is my understanding that while they would be aware of any downturn almost immediately (as per Paul's recent interview with them), their earnings would not be affected for a while due to the "strong pipeline of construction projects" (as they put it today). This is a valuable attribute.
I continue to question why it makes sense for them to be quoted in the UK on AIM, but for as long as they don't need to issue more equity, the significant valuation discount this causes can be seen as an advantage to investors.
Edit: Share price movement and broker upgrades are likely to have a significant impact on the Stockopedia momentum score over the next few days, probably restoring them to Superstock, or at least High Flyer.
Another vote of 1pm (LON:OPM) please Graham. Positive interims and as with many UK small caps, the performance and investment metrics are in my view under appreciated. I hold.
I also think that Headlam (LON:HEAD) are making a good fist of a challenging market. The company has provided fairly specific guidance as to expectations for the forthcoming prelims and outcome for next year. I don't hold but if it drifts much lower will be tempted as when the political/economic fog clears the current management initiatives should provide a much improved performance. Until then the company has net cash and in my view is well managed. There is also a generous divided that is not far off being twice covered and £35m plus in the bank
I shall endeavour to concentrate on individual stocks and shut out the din caused by the current political chaos.
All the best
Hi jonno, 1pm is in there now. Cheers. G
Graham, there is a Cenkos note on £1PM today (on Researchtree). This also compares the balance sheet of £1PM to PCF (LON:PCF), but states that price/book for £1PM is 0.73 versus 1.6 for PCF (LON:PCF).
Different calculation? Any thoughts?
(holder of both companies)
Presumably it's the inclusion of intangibles at 1pm (LON:OPM) responsible for that difference. G
Just over a month after Van Elle issued a trading update that expected ' to deliver full year performance similar to that of last year' the group is now talking of profits 'significantly below its previous expectations'. There is a new ceo in place but this company has been a major disappointment since its 100p a share IPO in October 2016.
Van Elle Holdings (LON:VANL) (SuperStock) Interims: down 30% today on a profit warning despite "in line with revised expectations" results and the CEO writing: "These challenges have been frustrating, but it is pleasing to see outlook for the final quarter remaining robust and with a strong pipeline of target projects providing good forward visibility."
The Interims provide the detailed numbers. Maybe this is a good entry point for longer-term investors.
[no position]
Hi Graham,
Second any chance of Headlam (LON:HEAD) seems ex growth but balance sheet is strong and some consolidation taking place in the sector don't know if you would see any plus's from a value investors point of view rather than growth ?
Thanks
TUs today from Manx Telecom (LON:MANX) (in line) and from M Winkworth (LON:WINK) who say:
Total revenues rose on 2017 and are expected to be within 5% of market expectations while, subject to audit, profits before tax are expected to be higher than in 2017 and slightly ahead of expectations of GBP1.4m. The Company expects to announce its final results for the year ended 31 December 2018 on or around 3 April 2019.
Over the course of the year the Company opened six new offices, merged four with others in neighbouring vicinities and closed one, raising the total number of franchised outlets at year end to 100 (versus 99 in 2017). The number of new franchise applicants rose by almost 80% in 2018 and this year we expect to see further opportunities to grow new franchises.
After returning 9p per share of surplus funds to shareholders in July, Winkworth ended the year with a strong net cash position and the directors are pleased to announce that the Company will pay an increased dividend of 1.9p (2017: 1.85p) per share for the fourth quarter of 2018, bringing total dividend payments declared for the year to 7.45p (2017: 7.25p).
Van Elle Holdings (LON:VANL), SR 93 / "super stock (Interims today, SP down to 55p at 9pm) please!
Also, for those interested, Headlam (LON:HEAD) - "marginally ahead / in line" but v cautious outlook. Divi up. "Strong balance sheet" claim made - so this alone warrants a proper check!
Thought I was in for a bad day but thankfully I also hold £SOM!
Also - second for 1pm (LON:OPM) please.
City of London Investment Group (CLIG)
Trading update today
Norcros (LON:NXR)
Trading in line which is excellent news. The current forecasts for profits for 2019 (25 mill net profit) and 2020 (27 mill net profit) and a sea change compared to the 10 mill they delivered in 2018 and previously.
Any acquisition lead path to growth and chuck in the SA unit and one can understand why the market doesn't particularly like this share - debt is up now and there is also the pension deficit.
The good news is that the company only really needs to deliver on expectations for a couple of years and the cash should start to flow through from the higher profits
I was kind of hoping they may take stock and consolidate but there is the new acquisition with £10 mill paid upfront - looks like this is just added to the debt pile. Debt was £53.5 mill at 30/9/18 - and in some respects we should really potentially factor in nearly £50 mill of future pension commitments if the deficit reverts back to higher levels - at least the pension fund issued is decreasing. On the whole i am happy with the acquisition, its just small enough that in can probably be covered from in 6-9 months profits although i was expect the debt to be increased again come 31/3/2020 - based on 27 mill net profits its only a couple of times profits - but one has to presume that at some stage the purple trading patch they have had may run out of steam.
Lets just hope they keep ticking over , keep additional acquisitions sensible and hopefully start to make a debt on the debt / pension deficit over the next 18 months. I kinda guess the market will only really wake up to this one when they see the company can start to pay back the debt at decent lick and i think that will still take some time.
rmillaree,
Norcros (LON:NXR) - I have similar thoughts to yours. The best thing that can be said about the acquisition is that it is small and I would prefer they reduced debt. As a consumer-exposed cyclical it seems imprudent to be going into a likely world-wide recession (albeit exact timing, depth and length unknown) with so much debt.
The fact is however is that they have set themselves a £600m revenue target for 2023 (see their 2018 Annual Report) and this will almost certainly require significant further acquisitions.
Rm and Leo
Re Norcros (LON:NXR) it may also be a factor in their calculation that they have some unrepatriated funds in RSA and the FX risk may be more or less equivalent to buying this small operation. EDIT sorry did not see Zip man's post
Just a thought
Disclosure - I hold
Steve
Somero Enterprises Inc (LON:SOM) please
#SOM please
Somero Enterprises Inc (LON:SOM)
Great TU today.
New High-Rise product sounds interesting. Cash "significantly ahead" bodes well for the special dividend.
Phil
My morning smallcap tweet:
Somero Enterprises Inc (LON:SOM), Norcros (LON:NXR), M Winkworth (LON:WINK), EKF Diagnostics Holdings (LON:EKF)
Somero Enterprises (SOM) guides FY rev moderately ahead of market expectations, EBIDTA also. Net cash 'more significantly ahead' of market expectations of $25m. Also makes small acqusition. I hold.
Norcros (NXR) acquires South African based RAP Plumbing Supplies for £9.7m plus £2.4m earn out. Earnings enhancing immediately. Trading is in line. I hold.
M Winkworth (WINK) guides FY rev within 5% of market expectations (I assume below!) but pretax slightly ahead of expectations of £1.4m.
EKF Diagnostics (EKF) guides FY adj EBITDA comfortably ahead of market expectations. H2 cash generation very strong with net cash at the end of the year of £9.4m.
1pm (LON:OPM) H1 results out today.
They continue to consistently perform. Here, good clear comms by CEO, Ian Smith and CFO, James Roberts, a quick round up of the results, and how they see things:
https://www.piworld.co.uk/2019/01/16/1pm-opm-fy19-interim-results-january-2019/
Somero Enterprises Inc (LON:SOM) starts off 2019 with an acquisition
https://www.marketwatch.com/press-release/somero-supports-growth-strategy-with-acquisition-to-start-off-2019-2019-01-15
Some analysis of the brexit palava on uk stocks would be great