Small Cap Value Report (Wed 17 Jan 2018) - BEG, GATC, NAH, UTW, CPC, TST, MYX

Good morning, it's Paul here!
Please see the header above for the companies I shall be writing about today.
Carillion & trade credit insurance
The demise of Carillion on Monday this week is clearly still a very big issue at the moment. Watching the TV news last night, I hadn't realised just how extensive the company's reach is - managing so many areas of public services, e.g. prisons, school meals, etc. I found the TV news reporting alarmist, irresponsibly so. Employees should have been reassured by the media that most jobs would almost certainly continue, under new contracts. Instead, tens of thousands of people are now (probably unnecessarily) fearing for their livelihoods.
Quite a mess. The knock-on effect for suppliers who are now facing bad debts, is likely to be serious too. Indeed it could push some smaller, and/or financially weak suppliers, and subcontractors, into insolvency too.
A keyword search produces this list of listed companies which have issued RNSs concerning their exposure to Carillion. There will be more to come, no doubt. The longer it takes a company to comment, then I'd assume the bigger the potential problem.
This is a timely reminder that sales on credit are a gift, until the cash has been paid by the customer. Hence why it's so important for investors to check (as best we can) the quality of the receivables (also known as debtors) on the balance sheet, within the current assets section.
- Are those debtors actually collectable in full?
- Is a company overly dependent on one or two big customers?
- How solvent are its biggest companies?
- Does the company insure its trade receivables? (they should do, where there is any doubt over customer solvency).
- Is debtor days reasonable (anything over 60 days is an amber flag to me, over 90 days is a red flag). For UK companies, remember to adjust for VAT - i.e. revenues excludes VAT, whereas debtors includes VAT. So I would first divide debtors by 1.2 to take it from gross to net of VAT, and then calculate debtor days (there's a link above showing how to calculate debtor days).
- Has trade credit insurance ever been withdrawn & caused disruption?
These are good questions to ask companies when we meet management. This can be an area of considerable risk, which many investors overlook. I like to hear an FD answering confidently, and in detail, when asked these sorts of questions. I want to get the feeling that the FD is really on top of the risks, and manages those risks tightly. It takes a very strong FD to stop the warehouse shipping goods because he can't get insurance cover on the customer. So I worry less about whether the FD is affable, and more about whether s(he) is strong enough to stand up to the CEO, and other people in the business. Hence why the dynamic between the CEO & FD is always interesting to observe at company meetings. A weak/submissive FD, and overly dominant CEO probably means that there could be inadequately enforced financial controls. As an aside, it was interesting to note that Globo used a highly paid, but unqualified FD. That's a red flag because such a person would be highly malleable - since the career risk of not complying with the CEOs demands would mean a large drop in salary at alternative employment.
The Carillion situation is also a reminder that, in some ways the trade credit insurance companies are just as, or sometimes even more important, than a company's bank. Very often the trade credit insurer is facing a bigger financial risk than a company's own bank. If trade credit insurance is withdrawn for a particular company, then that can often tip it over into insolvency. That was exactly what killed off the original Game Group, in March 2012. (the new incarnation, GAME Digital (LON:GMD) (in which I have a long position) is much more solidly financed, so does not face the same risk now.
This brings me nicely on to:
Begbies Traynor (LON:BEG)
Share price: 70.5p (down 0.4% today)
No. shares: 107.6m
Market cap: £75.9m
(at the time of writing, I hold a long position in this share)
Begbies is the UK's only listed insolvency practitioner. This quarterly report is always worth a read, for independent facts & figures on the health of UK companies.
It's a gloomy assessment;
493,296 businesses were experiencing 'Significant' financial distress at the end of the 2017, up 36% compared to the same period last year (Q4 2016: 361,856) and 10% higher than the previous quarter (Q3 2017: 448,011).
Reasons given are;
- Rising inflation,
- stagnant real wage growth,
- weak Pound,
- political uncertainty,
- November's rise in interest rates, and
- the ever-tightening credit environment
I would add to that list my own points: increasing online competition, wage costs rising from Living Wage & other costs (apprenticeship levy & pensions), rising business rates in some areas, increasing regulatory costs/hassle in some sectors. So there's no doubt that life is really tough at the moment for a lot of (especially smaller, private) companies.
As a result, 258,349 UK businesses ended the year in a position of negative net worth1, while a further 154,251 demonstrated a worrying increase in their working capital deficit.
Although note that financial distress is quite concentrated in 3 particular sectors;
The data shows that 'Significant' distress rose across every sector and region of the UK over the past 12 months. Support Services was the worst performing sector by volume, with 121,095 businesses showing signs of financial difficulty at the end of 2017, up 43% on last year.
Over the same period, financial distress in the UK Construction industry grew 31% impacting 62,294 firms, while 'Significant' financial distress in the Real Estate sector increased by 46%, hitting 40,508 companies.
These three sectors alone made up 45% of all UK businesses in 'Significant' financial distress.
That's giving us a very clear steer on which sectors to treat with caution. Note also that this data was prepared pre-Carillion, so support services and construction sectors are likely to get worse in 2018.
Exporters are doing well - again something we already knew, but worth noting, so we focus our energies on stockpicking companies which have this helpful tailwind in their sales (geddit?!!);
However, there was more positive news for businesses with a strong export book who benefitted from the devaluation of the Pound, particularly within the manufacturing and engineering sector.
Very interesting stuff. As stock-pickers, I think we do need to carefully consider the macro-economic situation. It's not good enough to just pick apparently cheap stocks, whilst ignoring the industry & economic outlook. Cheap shares are usually cheap for a reason. I'm very wary of some sectors at the moment. Although there are always stars, even when the going is tough - actually that's often when star companies do best, hoovering up market share from weak & failing competitors.
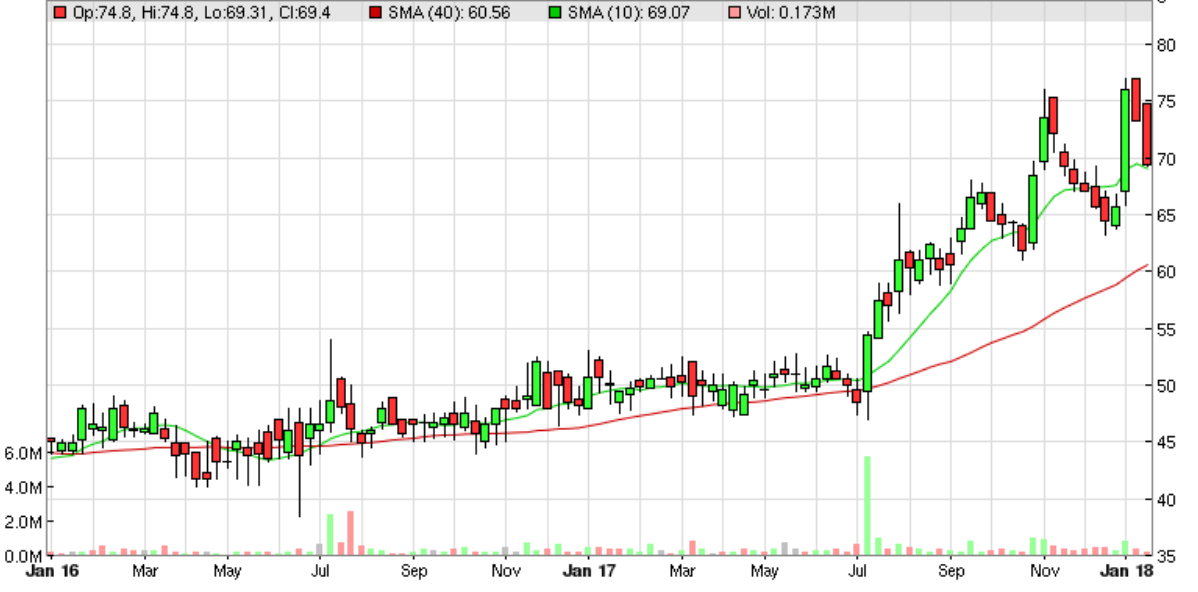
Begbies shares have done well lately. Even though the forward PER has risen to 17.9, which is looking a bit toppy, I suspect that there are likely to be earnings upgrades here in future. Hence why personally, I'm not in any rush to sell my BEG shares. There's a 3.5% dividend yield. Divis have started to rise too, after being static for a long time. That's indicative of an improving outlook for earnings.
The recent spike up was caused by a newspaper tip. The trend still seems firmly upwards, which is another reason to make me want to continue holding.
Gattaca (LON:GATC)
Share price: 260p (up 6.1% today, at 10:35)
No. shares: 31.8m
Market cap: £52.7m
(at the time of writing, I hold a long position in this share)
Statement re share price movement (re Carillion)
Gattaca plc ("Gattaca" or the "Group"), the specialist Engineering and Technology (IT & Telecoms) recruitment solutions business, notes the recent share price fall.
It sounds as if the financial impact is negligible;
Whilst Gattaca has outstanding debts from the Carillion group, the vast majority of these are insured by a leading credit insurer and, at this time, we estimate our uninsured balance sheet exposure to be less than 100,000.
The impact of Carillion's liquidation on our balance sheet will therefore be minimal. Our annual Net Fee Income from the Carillion group of companies is in the order of 0.5m.
The company has not taken this opportunity to reassure on overall trading, which concerns me a little. Although it confirms that a trading update will be issued on 8 Feb 2018, for the 6 months ending 31 Jan 2018.
My opinion - I've been getting increasingly bored with holding this share, as it seems to be allergic to rising in price. Although occasionally a large dividend is received, which temporarily alleviates my negative mood.
Unfortunately, I contributed towards yesterday's sharp drop in share price. I noticed that a Director had sold some shares, and combined with worries over its possible Carillion exposure, I decided to sell some of my shares. My broker only managed to dispose of a few thousand shares, whereupon the share price began to plummet. It went into auction (triggered by a 10% fall in price apparently), and by this time it was looking like I'd have to take near to 230p to exit in any size.
At that level I decided to pull my sell order, because it suddenly dawned on me that the Carillion exposure couldn't have been bad, otherwise a Director wouldn't have risked selling, and being accused of insider dealing (i.e. selling in advance of material bad news). Admittedly, such insider dealing is fairly commonplace on AIM (e.g. Telit Communications (LON:TCM) - where I remain short), so a Director selling is not a guarantee that there won't be imminent bad news. However, my feeling is that the Directors at GATC seem reasonably straight, so I wouldn't put them down as the type that would break the rules.
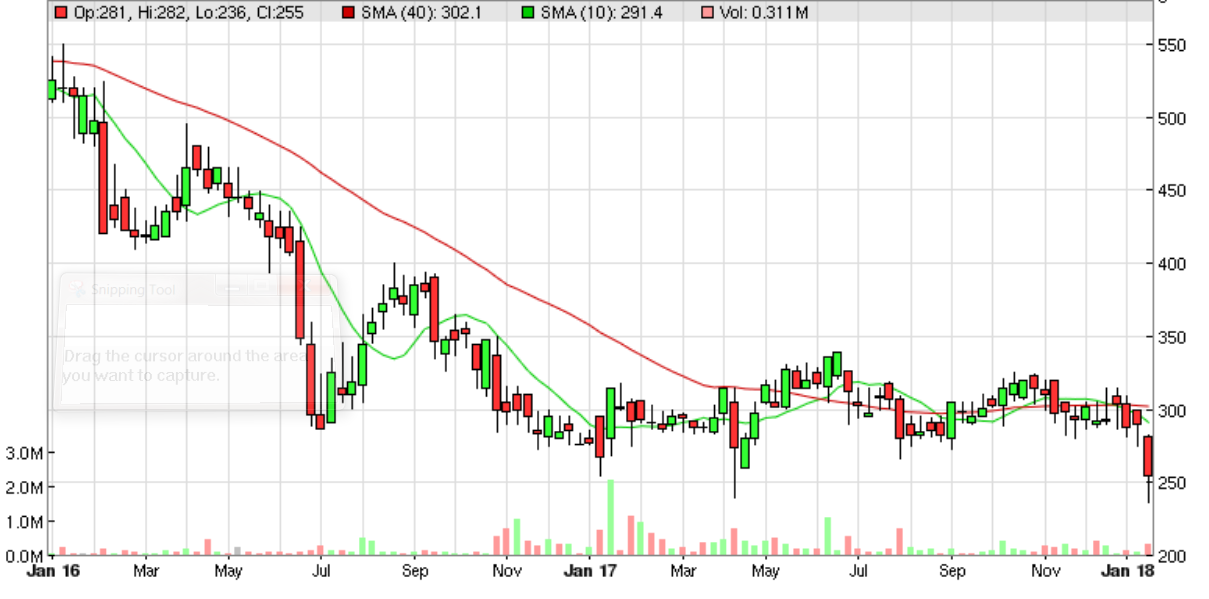
That's worked out fine, as the shares have bounced a bit today. I'm concerned that the company might yet warn on profits though. Are the divis sustainable? The yield of about 9% suggests that divis might need to be cut in future. I'm on the fence about this company. Will probably hold my remaining shares, but not with any great conviction, as I suspect a profit warning could be on the cards in due course.
The problem with so many small caps is that there's so little liquidity in the market. This can cause violent share price movements. That's both a nuisance, but can also provide opportunities to make money, if you're stock-picking is good, and you're not freaked out by sudden moves down. Selectively, panic sellers can sometimes hand us bargains on a plate. I'm not sure that's necessarily the case with this share though. Performance has been lacklustre of late.
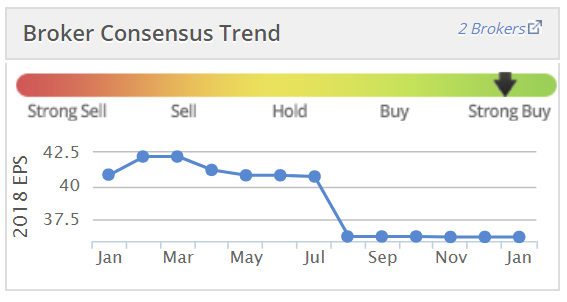
Note that earnings forecasts have already been reduced. A further reduction would not surprise me in the least. Although there are some big infrastructure projects in the pipeline, which the company has previously mentioned as giving it confidence in future earnings.
NAHL (LON:NAH)
Share price: 179p (down 2.2% today, at 12:00)
No. shares: 46.1m
Market cap: £82.5m
NAHL, the leading UK consumer marketing business focused on the UK legal services market, today provides a trading update for the year ended 31 December 2017.
I absolutely loathe this sector, due to previous awful experiences with ambulance-chasing type companies, involved in compensation, or legal stuff. Accident Exchange and Fairpoint were both disasters. However, readers have asked me to look at this, so I will. Also, some friends whose judgement I respect, have told me that this company is OK.
2017 trading - is in line at the underlying trading level;
The Group has continued to trade well and is expected to deliver underlying operating profit in line with the Board's expectations. Our finance charge has come in at a lower level due to prudent capital allocation and our balance sheet remains strong. Consequently, underlying earnings per share for FY17 are expected to be ahead of Board expectations.
First warning sign - claiming to have a strong balance sheet is to me an amber flag. Often I find that the opposite is true. Let's have a look. The top RHS section of the StockReport throws up some interesting initial pointers, which I have ringed in a wobbly red pen;
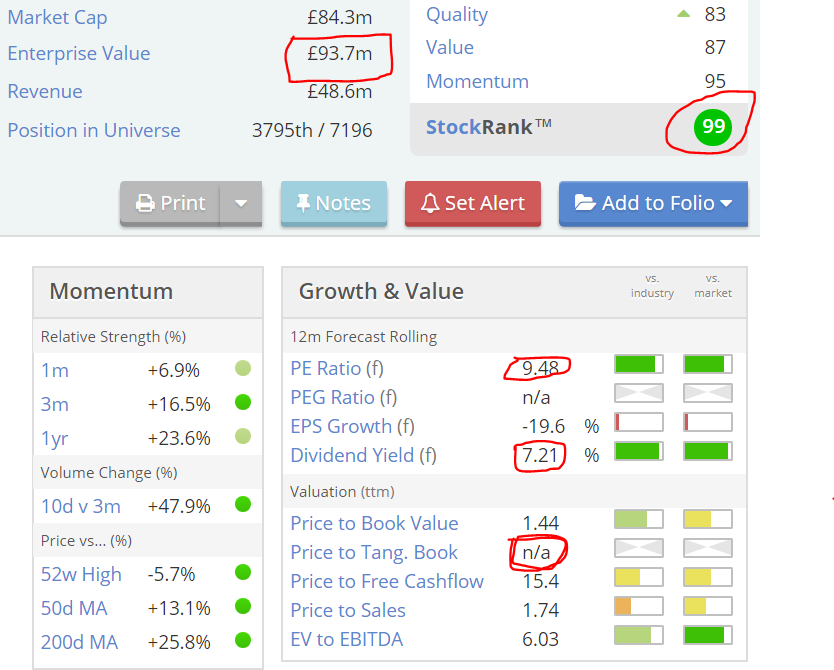
- Enterprise Value at £93.7m is higher than Market Cap of £84.3m. Deducting one from the other, this tells me that the company had £9.4m of net debt in the last accounts.
- StockRank of 99 suggests that the Stockopedia computers really like this share. So that makes me sit up and take notice, then form my own view (which usually coincides with the StockRanks). Also note (not shown in the picture above) that the Stockopedia styles shows it in green, categorised as a "Super Stock". Again, that's a clear positive.
- The PER of 9.48 and divi yield of 7.21% are attractive, hence shown in green.
- Price to Tang(ible) Book (Value) is shown as n/a. This is a warning sign, because that means P/TBV is negative - reinforcing my suspicion that this company may well have a weak balance sheet.
Balance sheet - with the above initial review process, I've already homed in on the balance sheet as being my main area of focus. It's easy to post big profits in this sector, but they can often be bogus. The tell-tale signs are on the balance sheet, with inflated debtors usually.
Here is a quick review of the most recent balance sheet (interims, as at 30 June 2017);
NAV is £58.4m, but this includes £60.4m goodwill and £7.8m "intangibles". Looking at note 8, the bulk of this is £6.6m described only as "contract related". A footnote says that these intangibles are related to 4 acquisitions, so I'll therefore treat this the same as goodwill, and write it off.
NTAV drops out negative, at -£9.7m. That's not good - I don't normally like to invest in companies with negative NTAV. However, if a company is highly & sustainably cash generative, and doesn't need any significant fixed assets, then I am prepared to make exceptions.
Interest-bearing debt - it has £3.7m in current liabilities, and £6.6m in creditors over 1 year, so that's £10.3m in total, less £0.8m in cash, so net debt of £9.5m. That looks a modest level of gearing, given that the company made £18.0m in underlying operating profit last year.
Debtors - this is where I'm expecting a huge, bloated, long-term & difficult-to-collect receivables book. Much to my surprised, receivables is actually fine - at £14.1m (as at 30 June 2017). For a business that's doing about £50m p.a. revenues, a £14.1m debtor book looks perfectly reasonable (especially as this sector usually has very extended debtor books).
Work-in-progress - surely there's a ton of costs held in limbo on the balance sheet as WiP? No, there's absolutely nothing! Zilch.
I hate to say it, but this balance sheet looks clean to me - if there are any bodies buried here, I can't see them!
Cashflow statement - this also looks clean to me.
Working capital movements did blunt the operating cashflow somewhat, but it still generates enough cash to pay its tax, and the generous divis were just about covered by cashflow last year: net cash from (post-tax) operating activities was £9.26m, and divis paid was £ 8.54m.
Outlook - I'm not entirely sure what this means, but this could explain why forecasts seem to be for lower profits in 2018 & 2019? Would this also absorb working capital, I wonder? Perhaps any readers who are more familiar with the company could fill in the gaps for me.
As previously guided, the opportunity to drive future growth means that the investment required to fund cases as part of the ABS' is expected to increase in 2018.
Alongside the successful relaunch of the NAH brand, these initiatives have enabled the Group to continue delivering a high quality service to its Panel Law Firm partners and the number of enquiries generated has grown 8.4% per cent year on year.
I wonder why they had to relaunch the NAH brand? That suggests something might have gone wrong previously, or some kind of regulatory changes possibly?
Ah, I've just spotted this bit - there does seem to be regulatory change underway;
Whilst there have been no specific developments regarding the previously announced regulatory changes by the Ministry of Justice, the Board expects the changes to come into effect no earlier than April 2019. The Group continues to evolve its business model to optimise the opportunity presented by the changes.
Clearly then a proper understanding of the legal & regulatory framework, and likely future developments, is going to be key in ascertaining whether this share is a good one, or not.
Other points;
Bush, the Group's Critical Care division, experienced slightly softer trading in the fourth quarter against expectations...
Fitzalan, the Group's Residential Property division, delivered a creditable performance although trading conditions remain challenging...
The Group also made a 0.8m release from the legacy pre-LASPO ATE provision which will increase reported earnings per share.
My opinion - these figures look really good, although I note that the company seems to have flat revenues & profits. So is it cheap because it's ex-growth, I wonder? I note that the graphs below seem to show consensus profit forecasts falling, which I need to verify;
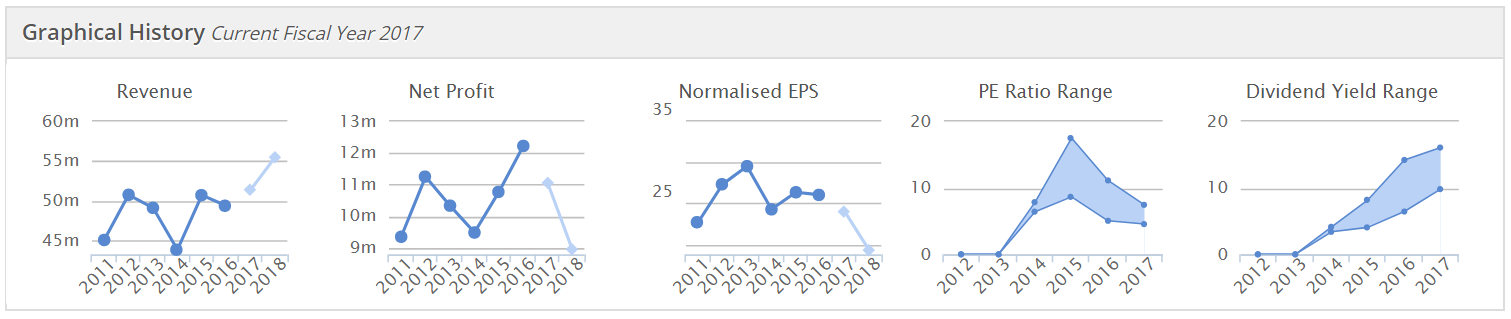
I haven't as yet seen any updated broker research today, but will edit this article if anything surfaces.
On my review of the figures, I have to say this share looks potentially interesting.
However, this just isn't a sector that I'm prepared to get involved with again. A highly profitable company like this could be vulnerable to regulatory change. We've seen this happen several times over the last 15 years or so. In some cases, companies' business models were blown to smithereens overnight by regulatory changes.
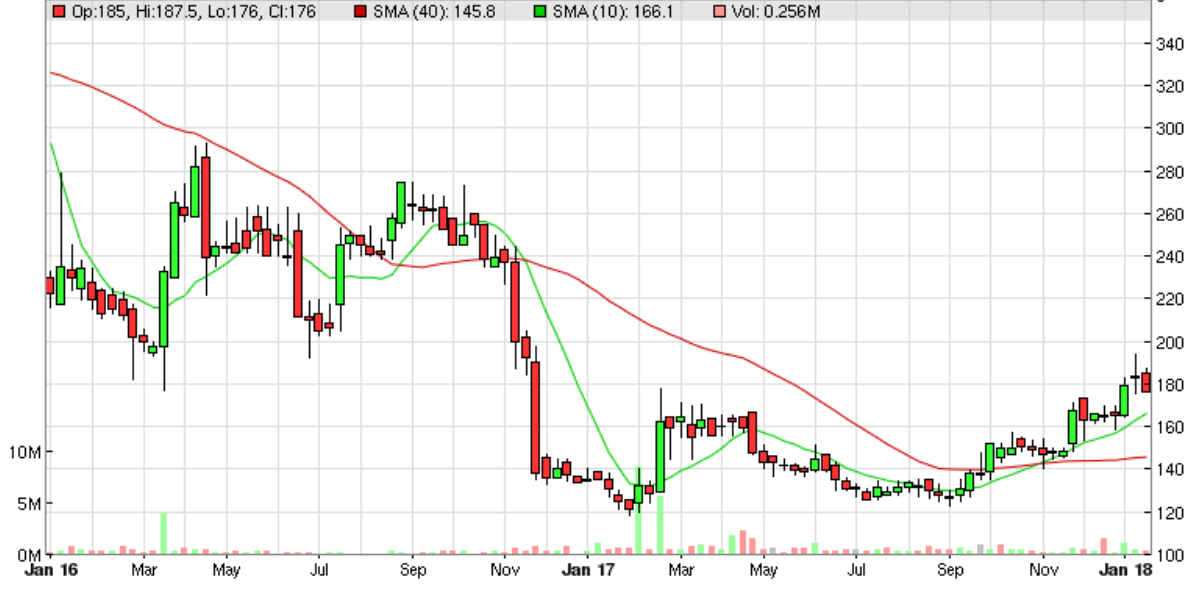
So there has to be a question mark over whether this company's bumper profits & cashflows have long-term sustainability? It's not for me, although I can see why people would find the numbers attractive. The chart also looks attractive - this looks a classic Mark Minervini stage 2 bullish phase - a long base having been formed (stage 1), followed by a rise above the moving averages. You see! Those chartists did eventually get to me!!! ;-)
Utilitywise (LON:UTW)
Share price: 39p (down 15.3% today, at 14:05)
No. shares: 78.5m
Market cap: £30.6m
Utilitywise, the leading independent utility cost management consultancy, announces a further update in respect of its full year results for the year ended 31 July 2017 ("FY17").
As a reader suggests in the comments below, it really isn't worth wasting much time on this appalling company and its dodgy accounts. We have an archive here groaning with material detailing all the ins & outs of the repeated accounting problems.
I've just been looking back at my previous articles, including 6 sceptical articles in 2013. My 2014 articles on Utilitywise are interesting, is that it seemed to be gradually dawning on me that the accounts were not right. Here in Oct 2014 I broke cover & explained why I thought the revenue recognition policy was suspect, and concluded;
Conclusion - I don't like it. There are too many red flags, the accounts look odd to me, and I'm not at all convinced that profits will be sustainable in the long run. Combined with a high valuation, that makes these shares uninvestable in my opinion. It's just an opinion, and I fully expect to get shot down in flames by existing shareholders in the company!
The share price then was 289p, so by spotting the dodgy accounts very early, as potentially nasty loss was avoided. If a humble blogger can spot dodgy accounts, why can't fund managers, is a valid question to ask?
Accounting policies - are being changed again, at the insistance of the auditors (well done them!), following the engagement of another firm of accountants, to give a second opinion;
The review, which was undertaken by a major accountancy firm, is now complete and, as a result, Group results will now reflect a change to the accounting policy of the Group regarding the estimation and recognition of revenue on contracts.
This proposed change will have no impact on the cash flows or underlying economic performance of the Group.
Whilst the bit I've highlighted is true on cashflow, it does mean that previously reported profits were over-stated.
It sounds as if there's plenty of work still needed, in order to finalise the 31 July 2017 accounts. Does this mean that there's a risk of the shares being suspended if accounts not filed by 31 Jan 2018? Quite possibly. The clock's ticking, with only a fortnight left to publish its figures.
The Group currently expects to complete its year-end audit process in respect of FY17 and announce its final results by 31 January 2018. However, due to the volume of work required there is a risk that the audit will not be complete by this date.
Impact on 2017 profits is not yet known.
Impact on 2018 profits is significant;
There is also likely to be a material impact upon the Group's reported revenue and accounting profit in the year ending 31 July 2018, with the absolute impact becoming estimable once the revised accounting policy is finalised.
The bank is being kept informed, but I wonder how much patience they have remaining? It must be tempting to just shut the business down, and collect in the run-off cash on existing contracts, from energy companies, over a number of years. Details are given about bank covenants, which might need waivers.
My opinion - it's just so messy, and with so much uncertainty, I find it impossible to value this company. We don't really know whether it's profitable at all. On the other hand, the debtors should turn into cash, over a number of years. So there could possibly be some value in the company. It has to go in the "too difficult" tray, I'm afraid. I certainly wouldn't want to be holding any share which is only 14 days away from suspension, and embroiled in a complex accounting mess. The institutions are high & dry. They can't exit, even if they want to. Whereas private investors with modest holdings can just hit the sell button any time. That gives us a big advantage.
(work-in-progress)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
As a holder of Gattaca (LON:GATC) I note another drop in price today with no evident news but alongside continuing rumbling about Carillion (LON:CLLN) on the Radio 4. I assume the two are linked, despite the rapid response from Gattaca (LON:GATC) 's CEO in an attempt to unhitch the two companies. Interesting to see the sharper fall on fear of a link than the grudging recovery that the almost rebuttal produced. I suspect I may have to bite this bullet before long.
My use of the £ sign has been as required but, unless something magical happens as soon as I click on "submit", I fear they will stay as £.
Hi Paul,
As I understand it, NAHL are issuing more shares. Interested to hear your thoughts on that. The stock certainly looks good on the StockReport. However, I've made a decent profit on this holding and with the company still being under investigation and now raising more money via shares I've cashed in and taken profit on this holding.
Morning Graham/Paul, since there is no placeholder can I place a request of announcements today for consideration for your report. I'm interested in the updates from Air Partner (LON:AIR), Headlam (LON:HEAD) and Newriver Reit (LON:NRR). Of particular interest in Newriver Reit (LON:NRR) due to it's association with the high street. Today was most interesting with particular reference to the lower rent per square foot compared to last year however the increase in footfall. Also what appears to be their strategic decision to not be involved with department stores.
That’s a brilliant report Paul, thanks for all the hard work. Regards, Andrew
The text on red flags relating to debtors is better value than paying for a two-day debt collection course. It is insightful of Paul to highlight the significance of having an unqualified FD. I'm sure the note is not autobiographical.
I have personal experience of this. I took over as FC from an unqualified guy many years ago. The company had recently been acquired by a PLC and there had been an earnout target in place for the year of acquisition. The selling owner was still CEO of the company and he pulled every scam available (none legit) to maximise the profit for that year. His unfortunate unqual guy did all that was asked of him (no instructions on paper). However, some of the methods used were crude and easily identified during the audit. Some were not - how do you spot that raw materials supplied to the company were paid for by another party? Or that sales invoices paid by a customer during the did not involve the supply of the goods stated? Mr CEO paid for both items personally. Cost £1X, benefit £8X, gain £7X - and X was big. No-one was ever investigated criminally - indeed Mr CEO became a member of the PLC board as a result of the shares issued to him on acquisition!
Good story. I remember when our privately held co. was selling to a huge corporation our FD brought a gnome into his office. When I asked why he said it symbolises the seven dwarves, to remind us directors that this year, everything costs seven times the price we pay. It was a very effective reminder to be abstemious, although we didn't bend the rules, much.
Jon
NAHL: Paul's report says
"these figures look really good, although I note that the company seems to have flat revenues & profits. So is it cheap because it's ex-growth, I wonder?
THere is a specific reason why the 2018 Forecast Sales and Profit is lower than 2017, before resuming growth in 2019. In simple terms, NAH have changed a part of their model to something called an "ABS Structure", in response to the Regulatory Changes first flagged by the Ministry of Justice in 2015.
Before 2017, the NAH Model was to earn a small % Fee for passing on an enquiry into their Helpline onto a firm of Solicitors to deal with. The new ABS structure was put into place during 2017 with two Large Legal Groups, and is effectively a "joint venture" where NAHL will earn a larger % of the total Fee earned. Some enquiries will be passed through the new ABS structure, and some through the traditional route. Given that an average case takes 18 months between inception and final settlement, the revenue which passes through the ABS Structure for NAHL will be recognised later than before, albeit a (hopefully) bigger amount. 2018 is effectively a "hiatus", and monies recieved through the 2 ABS structures will not start to accrue until the second half of 2018. The Arden Forecast for 2019 shows the position starting to normalilse, with a PBT increase of over 20% compared to 2018. I would presume the numbers will not be fully normalised until 2020...given that the second ABS only started towards the end of the 2017 year.
anyone got any idea why Telit is up so much today?
In relation to Paul's comments on Utilitywise (LON:UTW) and its accounting issues it is worth mentioning the accounting standard IFRS 15 "Revenue Recognition" came into force on 1 Jan 2018. It is more prescriptive and requires detailed analysis of contracts. This is likely to impact Utilitywise (LON:UTW) and perhaps cause issues in its 2018 reporting. I'm sure it will impact construction and service companies that have long term contracts also.
Paul - If Gattaca (LON:GATC) were going to warn on profits then they have an obligation to do so immediately, not wait for a trading statement. If, as you point out, you are comfortable the Directors play a very straight bat then I would expect an in-line statement and no more/less. That was my view and as a consequence took advantage of the spike down yesterday but sold this morning when they retraced back to 265p. If the trading statement did warn on profits outside of any disclosed Carillon impact it would be a big red flag for me, particularly as this RNS was designed to provide investors with comfort, so I would view it as duplicitous.
A director selling 4% of his overall holding doesn't concern me in the slightest. £35k worth of sales is irrelevant and could be for many reasons (a tax bill for example given time of year). If this was a higher % or a regular occurrence I would probably be more concerned.
All of that said if you believe the macro environment makes for a poor read across to this type of recruitment firm and that profits will be under pressure, as opposed to the Directors slightly more bullish assessment of future growth, then I agree with the other chap who said you probably shouldn't be holding.
Disclosure : I am also long a core holding. Like you I like the dividend but view it as broadly maintainable. I don't expect them to set the world on fire growth wise but don't view them as expensive either. I can see a total long term return in excess of 10%+ which is acceptable. Hopefully, I'm not too far wrong :)
Paul - what a brilliant report and dissection of finances on LSE:NAH. That one piece of work today is worth the Stockopedia subscription !
Hi martin576,
Wow, thanks!!! Your comment made my day :-)
With NAHL (LON:NAH) , I thought it would be useful to walk readers through my process of analysing a company that's new to me. So it's good to hear that you found it useful.
Regards, Paul.
Hi Paul and re NAH;
As you may recall I run a company that provides funding to law firms to run their cases and as such I was interested in your thoughts on NAH. Your summary seems fair and re your question about not knowing the reason as to why their investment in cases will go up, I have an opinion.
I believe this probably centres around that current CMC (Claims management Companies), such as NAH generally 'pile high' new leads and sell the lead to the law firm (along with profits from associated introductions such as insurance etc).
The case then has to be validated by the law firm to see if it is viable and there is a claim. This has historically been carried out by the law firm but it takes time, money and, of course, the are acquiring a large number of cases which they pay for which are then reduced as cases are abandoned although the CMC has already been paid! Whilst 'bad' cases are sometimes replaced by the CMC, this just extends the timescales for the law firm and doubles their work load in vetting the new cases before they can start being a lawyer.
However, the market is changing and the sectors are widening and instead of just supplying a name of a lead to the law firm they, the law firms are now tending to now look for pre vetting and verification of the claim before they acquire the case.
This will mean it takes longer from NAH getting a lead, then through the verification process which is likely to lead to a number of deals falling by the wayside. Only then, when all the info is gathered and it is likely the case is realistic, will the law firm buy the case. This of course takes time and money and would suggest this is what was meant by the comment you highlighted.
This will lead to a greater level of funding being required by the CMC (investment in cases and back room analysis) to get through the process and it may be that the number of cases could reduce due to the vetting process and being thrown out but they will be able to charge more for this added service.
Please note this will not be across all the cases they source/sell but certain sectors that do require verification of the claim such as holiday sickness, housing, financial mis selling.
Please note this is my personal opinion and I cannot be absolutely sure this is their particular business case adopted by NAH, I am just forming an answer to your query based on an understanding of the market and the way it seems to be changing across the different sectors.
I hope this makes sense Paul and happy to chat through if you want to give me a call.
Regards
Norman
Hi Paul
I found your £NAHL walk-through invaluable too. Really interesting. Thanks very much.
I recall other subsribers suggesting a Stockopedia balance sheets pdf guide. If ever there were the resources to produce one, that would be great. (I might then become aware of my many unknown unknowns ;)
Regards, Jon
Paul on the subject of lack of liquidity and EMS that market makers will deal in at the bid being older and wiser these days post Indigo and gearing what is the max percentage of your portfolio you would put into any one share even high conviction stuff ?
Thanks
Paul (re. Carillion), thanks for the comments regarding checking the accounts of companies. These, for me, are of invaluable help in the research process. M
"You see! Those chartists did eventually get to me!!! ;-)" Trying to predict share price movements from a chart doesn't hold a candle to more in-depth analysis..
Payment terms, I like the Belgian system of enforced 30 day terms for all deals.
I've had to negotiate 120 day terms and it is a nightmare, but I've also offered customer a 1/2% discount if my clerk never had to phone them in a year. Such a waste of time and efficiency, move to the Belgian system
Re: Debtors.
Agreed, about the importance of this. No point (long-term) increasing turnover if you're not going to be paid :o)
It seems Carillion stretched their payment terms sometime last year to 120 days, which should have sounded warning-bells.
A company I knew, many years ago, sent statements at month end, and gave a discount (5%?) if paid before the 15th of the following month. This 5% was factored into the profit margin already. (Clever buyers ordered on 1st of the month, thereby getting 6 weeks credit and a discount.)
Any company that hadn't paid by 15th, were initially phoned to enquire as to why, which more often received a "Doh!, we've missed out on our 5% discount, but will make payment now.". If no payment a week later, the salesperson was sent in to 'evaluate the situation' (high-street shops). If they felt uneasy they'd remove the company's stock or arrange for it to be collected.
No stock would go out if a buyer's debt was still outstanding the following statement-date, and the FD was a no-BS person, dealing with any enquiries from these personally.
Bad debts were extremely rare, and the debtor-days target of 45 was usually close, and never exceeded the 60 you mentioned.
speaking of charts Paul, NAHL (LON:NAH) has showed a classic cup and handle shape chart, which indicates momentum rising. I hold after opening a small position few weeks ago, buying after the handle had formed.
I geddit Paul! On which note I will take the opportunity to thank both yourself and Graham for these invaluable daily small company updates.
Thanks Paul for the response.
Regards
Trident
In terms of Gattaca (LON:GATC), Equity Development a note this am: https://www.equitydevelopment.co.uk/edreader/?d=%3D%3DQO3MjM
They've not made any change to their 2018 numbers or beyond. I assume this is paid for research, but we won't have long to find out how they've performed.
General question
Do companies just announce trading updates?? Do they sometimes give notice of a forthcoming trading update announcement??
Thankyou.
Mr Ken.
Sometimes notice is given and you'll see an announcement under the company's ticker symbol and sometimes it isn't. The Alliance News Web feed on the LSE website (http://www.londonstockexchange.com/exchange/news/alliance-news/archive.html?&page=5) normally contains a heading "UK Earnings, Trading Statements Calendar - Next 7 Days". If you click on that (http://www.londonstockexchange.com/exchange/news/alliance-news/detail/1516118956340618900.html), you get a listing. You can also use this feed to check "UK Shareholder Meetings Calendar - Next 7 Days" and "UK Dividends Calendar - Next 7 Days". I think they are updated daily.
Remarkably muted reaction from the market to the trading update from Henry Boot (LON:BOOT) even though earnings are forecast to be comfortably above their already revised expectations. Maybe their statement about the draft valuation coming in below expectations has put some people off? Still I've decided to top-up to a full holding as I like the progress that they're making and tone of their announcement. Given that they're slightly upgrading the 2018 forecast already gives me a sense that trading is strong and that the broker forecast for a slight profit fall needs to be amended.
Henry Boot (LON:BOOT) are up about 4% today, not a bad rise - perhaps the following statement 'muted' things a little...
Finally, the Group has now received the draft 2017 year end valuations of the Group's property portfolio which, despite gains on industrial properties, was below our expectations following a reduction in the values of mixed-use secondary retail properties within the portfolio.
Yes my heart sank when I read that statement! But then I read on further and realised that profits are actually going to be above expectations.
So I don't quite know what to make of this revaluation. It sounds bad but without any numbers it's impossible to know what sort of miss we're talking about. Also if, for example, they'd been expecting £75m to grow to £100m but it only got valued at £90m then that's still not bad. However if, instead, it got valued at £70m then that would be terrible.
Not a great statement then in giving us guidance but maybe all will become clear with the results.
Regarding Begbies Traynor (LON:BEG) , they are looking a little expensive on a forward P/E basis to me, even without adjusting for debt.
I've held these for a long time so can't be certain, but I'm pretty sure they used to be much cheaper and certainly the yield was well above 5% for a long time. I realise this mostly reflected the poor future prospects for insolvency work due to ultra-low interest rates, but in my mind it also reflected my understanding they were reliant on specially qualified staff.
Now that insolvency trend seems to be firmly on the rise (and with "good" short-term prospects amongst small construction firms), my question is: Have they really retained the capacity to take on a lot of new work? Have they really had staff sitting around idle all this time? Won't it be really difficult / expensive to recruit and retain now? I think these are questions that Paul may be particularly well qualified to answer.
Furthermore, the diversification into conveyancing smelt a bit like capitulation to me, and the timing is now looking poor. It looks like a great strategic move though as the two activities should do well at different points in the cycle, but with one part of their business presumably now static/declining is the current P/E really justified?
The share price spike earlier this month appeared to be due to a new year's tip: http://www.telegraph.co.uk/business/2017/12/30/stock-tips-shares-will-bring-cheer-2018/
I sold a small amount into this spike, but I am currently holding the rest.
[edit: This message was written before seeing Paul's write-up and isn't supposed to be a comment on it. As I am at work it often takes me a long time to complete messages]
It's not a small cap but Diploma (LON:DPLM) issued an in line update today.
What's interesting is that they mention a currency headwind, and I think that's the second time recently I've heard that. Amazing how quickly things turn around.
NAHL PLEASE
HI Paul
Are you surprised not hear anything so far from Sosandar (LON:SOS) about Christmas trading?
Obviously they are a small outfit, and the returns side of things I suppose side of things could stall releasing info?
Regards
Hi Trident,
"Are you surprised not hear anything so far from Sosandar (LON:SOS) about Christmas trading?
Obviously they are a small outfit, and the returns side of things I suppose side of things could stall releasing info?"
Actually, I wasn't expecting SOS to issue a Christmas update. They're so small (basically a start-up) that I don't think seasonality would have much meaning yet.
The company put out an update on 11 Dec 2017, saying that trading to end Nov 2017 had "exceeded management expectations". It also said that increased marketing spend has "yielded strong results".
So it seems clear to me that the next update is likely to be good. Although I think expectations need to be kept grounded, as it's a very early stage business. I'd rather see the share price tread water between announcements, and only rise once the company has established a good track record. It's not helpful to see speculative frenzies develop in early stage companies, in my view.
So let's see what happens in due course! People get too impatient in bull markets. This kind of stock will take years to develop into a decent-sized business (and may not succeed of course). That said, my eye is on the long-term prize. If this works, then it could be a 10-bagger or more, with patience, in my view. Downside risk is that if it's clearly not working, then the share price would wither away, and I might end up selling for a 50-75% loss. It has enough cash for the next 3 years though, so shouldn't need to raise any more.
Regards, Paul.
Good morning!
Thanks for the reader requests, and please try to remember to always put the company name or ticker in every comment. Even if it seems obvious that you're replying to a particular post, it may not subsequently be obvious from the comments list which company you're talking about. Sorry to keep nagging on this.
I will take a look at NAHL (LON:NAH) and City Pub (LON:CPC) (reader requests).
Also I'm going to mention today: Gattaca (LON:GATC) (I'm long) , Begbies Traynor (LON:BEG) (I'm long) (Q4 red flag report), Touchstar (LON:TST) placing (I'm long), Utilitywise (LON:UTW) yet another accounting mess, Mycelx Technologies (LON:MYX) and anything else there's time for.
Regards, Paul.
Hi Paul,
When I read your Gattaca (LON:GATC) write up (which is well thought out as always) it occurred to me that your conviction seems so low that really you should be out and watching from the sidelines.
If I held Gattaca (LON:GATC) then I would have sold based on your article and thanked you for saving me an inevitable further loss in the future.
I worry that in 6 months there will be a follow up article that says “i’ve Looked back at my old reports on Gattaca and I don’t know why I kept hold of even the smaller holding, I could see there was a profit warning coming, why didn’t I take action back then”.
It’s quite often that grit my teeth and sell a share that i’ve been unnecessarily in love with because your articles give me insight into something that I had missed. Trying to control my behavioural biases in 2018 and your input helps.
I hope you won’t think me rude if I suggest that if you sold it you would feel better!
Cheers
Carey
Hi Carey,
Interesting, thanks.
If Gattaca (LON:GATC) was more liquid, I would sell it now. Trouble is, it was such a struggle to sell any yesterday, that it put me off.
Maybe I'll revisit this. Thanks for the prompt.
Regards, Paul.
Nice to see growth in non-EM mandates at City of London Investment (LON:CLIG)
NAHL (LON:NAH) please, seems to be a recovery in progress.
City of London Investment (LON:CLIG) (I hold) announces solid H1 and a increase in the interim dividend (div yield already over 6% - but well-covered by profits and cash flow). Margins have drifted down by a couple of bps. Given performance by this focused asset manager is very dependent on the direction of emerging markets, outlook is as always uncertain but for those who like a company to give clear guidance - CLIG sets out what revenues and costs will be over each of the next six quarters, given certain assumptions.
Re Utilitywise (LON:UTW)
I don't expect you to comment on the latest update about their accounting shenanigans, it's not worth the effort.
But it makes me laugh every time I read an RNS that shows how poor a job management are doing but then finishes with standard boiler plate blurb like: "Utilitywise is a leading independent utility cost management consultancy..."
If UTW considers itself to be "leading", god help us all. Get a grip and show some humility
Francis
Yes Francis, Utilitywise (LON:UTW) is indeed "... a leading independent utility cost management consultancy...". It just can't manage revenue!
I have mentioned it in the past but Inspired Energy (LON:INSE) is not a Utilitywise, only recognising revenue when the customer actually uses the energy.
I have topped up on Inspired Energy (LON:INSE) this morning and you may not be surprised to know I don't hold Utilitywise (LON:UTW)
Dave
XL Media has been mentioned here a few times. This morning they have confirmed a successful placing with institutions raising £31.7M at 198p which is only marginally below current price. It is to be used for acquisitions they have in mind. Over the past couple of years this share has more than doubled.
Yes I noticed that. My initial thoughts we're that it was a rather sizable dilution but upon reflection I'd like to think it's a pretty good sign that they could raise so much money so easily at almost no discount to the average price of the last couple of months, especially after the run it has had over the past year. There must be a lot of institutional demand, even at today's elevated share price.
Note: Currently my 2nd largest holding.
My morning smallcap tweet:
Earthport (LON:EPO), Gattaca (LON:GATC), Mycelx Technologies (LON:MYX), Deltex Medical (LON:DEMG), M Winkworth (LON:WINK), NAHL (LON:NAH)
Earthport (EPO) CFO resigns, leaves end Jan. Sounds amicable. I'm short.
Gattaca (GATC) comments on 15% price fall. Uninsured balance sheet exposure to Carillion less than £100k. "Net Fee Income from the Carillion group of companies is in the order of £0.5m. Gattaca continues to support the delivery of important public services and management is actively engaging with the relevant Carillion counterparties to ascertain how we can continue to support the related underlying projects which would also maintain this income, whilst ensuring that we will be paid for such services."
MyCelx (MYX) FY trading - 2 orders in Q4 - rev will exceed market estimates by 20%-30%, net loss down within a similar range. Expects to be EBITDA and cash flow positive. Guides 2018 rev at least as high as 2017.
Deltex Medical Group (DEMG) wins 'strategically important account' from US teaching hospital.
M Winkworth (WINK) guides FY rev broadly in-line with market expectations, down <5%, despite opening seven new offices. Will pay tot div 7.25p, up a token 0.05p.
NAHL Group (NAH) guides FY rev in line, adj EPS beat due to lower finance costs. No numbers, probably a small beat. I hold.
Thanks TC,
Deltex Medical (LON:DEMG) That account may well be the salvation of the company. It could draw the attention of one of the US medical equipment behemoths Not least the manufacturer of the alternative fluid monitoring equipment the use of which actually increased the length of hospital stay after surgery. Deltex Medical (LON:DEMG) is a tiny company, well 150% bigger this morning, and I see that about 10% of shares in the company have been traded by 10.00. It could be a bumpy day.
Regards, Seadoc
Edit: I should add that I hold.
Hi Seadoc, I agree with you on Deltex and continue to hold. Here’s hoping.
Regards
Andrew
Would welcome thoughts on City Pub (LON:CPC) which I don't think has been covered here before. Very strong trading update released today, along with indication that it will double the size of its estate over the next 3 to 4 years.
Second for NAHL please!
NAHL (LON:NAH) reports 2017 EPS to be ahead of expectations. A potential recovery play or too much regulatory risk ?
Will be interesting to see how Veltyco (LON:VLTY) opens today with the phrases 'crypto' and 'blockchain' in the RNS. Have they missed the boat given the recent falls in crypto currencies or will there be a big jump in price?
Gattaca (LON:GATC) have made an announcement re Carillion: https://investegate.co.uk/gatt...
Uninsured bad debt estimated at £100k. Net fee income involving Carillion: £500k/pa (0.7% of total for FY2017) but hope much of these will continue. No mention of knock-on effects in the industry.
[added:]
To address simoan's points: I get the impression from this agency, others I have invested in, and ones I have used in the past that it is very difficult to grow organically or even hold on to business beyond a certain size. It is a people business and there is a pattern of individual recruiters leaving to form their own companies or joining their ex-colleagues smaller companies. To grow or even stand still it is necessary to then buy these companies from time to time, despite the knowledge that some of the recruiters working there will quickly leave. So IMHO recruiters will always look like bad businesses with bad management. It is just a matter of price.
Reviewing their FY2017 figures again: They have considerable intangible assets, flattering the price / book but weighing down profits. Cashflow looks much better, easily covering dividends despite (hopefully one-off) working capital movements. Normalised cashflow yield looks to be well over 20%, potentially significantly higher next time if one-off factors reverse. However, as described above, this might be one case where amortisingintangibles gives a better view of profitability than not doing so.
To address simoan's points: I get the impression from this agency, others I have invested in, and ones I have used in the past that it is very difficult to grow organically or even hold on to business beyond a certain size. It is a people business and there is a pattern of individual recruiters leaving to form their own companies or joining their ex-colleagues smaller companies. To grow or even stand still it is necessary to then buy these companies from time to time, despite the knowledge that some of the recruiters working there will quickly leave. So IMHO recruiters will always look like bad businesses with bad management. It is just a matter of price.
leo,
So you are saying these type of people businesses make bad investments as Graham wrote recently, and I agreed with him. If you need to buy companies and run up debt to stand still, that sounds like a pretty lousy business to invest in!! Of course, none of this is an excuse for the way the management of Gattaca (LON:GATC) have run the company in the past 5 years. I speak as someone who can remember when it was called Matchtech (the change of name is a red flag in itself) and the share price was 500-600p. Of course, it is now half that.
You only need to spend 5 minutes looking at the Stock Report to see that despite several acquisitions, including the large one of Networkers International, whilst revenue has increased as you would hope and expect, profit has not, EPS has not, ROCE has plummeted, a low operating margin has decreased even further, and the only thing that has increased (quadrupled in fact) is net debt. And they are not even managing to reduce the debt effectively whilst maintaining a huge dividend.
To me this just smacks of poor management that has done nothing to add shareholder value through a time when employment has been buoyant at best and benign at worst and recruiters should be doing well. If you compare the share price over the last few years with other smaller recruiters (e.g. Harvey Nash, Robert Walters) it tells you everything you need to know.
All the best, Si
I could not agree more with Si (well said) I remember Matchtec as well I had GATC shares sold last year (at a 10% loss) name changes in general do make me uncomfortable however what bright spark came of with name Gattaca !! I should have just fled then.
All the best Tony
SI,
Re: Gattaca (LON:GATC). Yes I am agreeing that people businesses are bad businesses, but where they are consistently profitable (Begbies Traynor (LON:BEG) being another example), they can make good investments at the right price. Borrowing to cover debtors, especially when they are insured, and especially when the debt is very cheap seems perfectly reasonable to me. This working capital would be freed up in a downturn.
I did look at Harvey Nash (LON:HVN) 's performance over a 5 year period and it seemed to be just as bad, and perhaps worse taking into account dividends. I didn't look at Robert Walters (LON:RWA) before now. Yes, the share price has nearly doubled in 5 years, but dividends have been only around 1% pa so that will be partly down to higher internal investment and may be due to P/E expansion over the period - certainly the P/E is now very high for a recruiter, though the EV/E slightly less so.
I did look at Harvey Nash (LON:HVN) 's performance over a 5 year period and it seemed to be just as bad, and perhaps worse taking into account dividends. I didn't look at Robert Walters (LON:RWA) before now. Yes, the share price has nearly doubled in 5 years, but dividends have been only around 1% pa so that will be partly down to higher internal investment and may be due to P/E expansion over the period - certainly the P/E is now very high for a recruiter, though the EV/E slightly less so.
Hi leo,
I don't want to belabour the point I'm making but I don't know why you chose 5 years? I said "a few years" as that takes in the period post the large acquisition of Networkers which completed in April 2015 and that added £30m in debt to a fairly debt-free balance sheet. Try a three year chart and see what you think. Add in any other recruitment company you can think of and you will see Gattaca (LON:GATC) has underperformed pretty much all of them quite badly in share price terms.
If you can explain how the Networkers acquisition has added any shareholder value whatsoever, I'm all ears. Of course, the cheeky buggers even awarded themselves loads of shares in a "Value Creation Plan" a few months post completion in recognition of their superb performance. For the avoidance of doubt, I used to hold Gattaca (LON:GATC) so I have followed it quite closely over the last 5 years but I have no axe to grind other than the poor management. I wish you well with your investment in Gattaca (LON:GATC).
All the best, Si
Veltyco (LON:VLTY) release RNS with the headline "Acquisition of Crypto Wallet service provider". It is acquiring a 51% stake in "Varkasso Limited ("Varkasso"), a company that has the exclusive rights to use 8Crypt, a software platform providing crypto wallet solutions based on blockchain technology" and will pay for it partially via a share placing. No details about the financial performance of Varkasso provided.
The slightly cynical part of me thinks £ VLTY are jumping on the bandwagon. Will be interesting to see how share price reacts.