Small Cap Value Report (Wed 17 May 2017) - CAKE, FOXT, ALT, ZTF, IDEA

Good morning, it's Paul here.
I updated yesterday's report with a few more sections later in the day. To see the full report, please click here. It includes my comments on;
K3 Business Technology (LON:KBT) - profit warning (looks nasty)
Accrol Group (LON:ACRL) - in line trading update
Zytronic (LON:ZYT) - decent interim results & outlook
Interquest (LON:ITQ) - lowball bid from management - company now in play
Koovs (LON:KOOV) - RNS saying no reason why share price is falling (other than that the company needs to raise more funding)
On to today, I've included in the header the companies which I intend reporting on.
Patisserie Holdings (LON:CAKE)
Share price: 333p (up 4.1% today)
No. shares: 100.0m
Market cap: £333.0m
(at the time of writing, I hold a long position in this share)
Interim results - for the 6 months ended 31 Mar 2017.
This group's main operations are the chain of "Patisserie Valerie" cake & tea/coffee shops. It's a roll out share - i.e. the company is expanding (opening around 20 new sites each year) funded from its own cashflow.
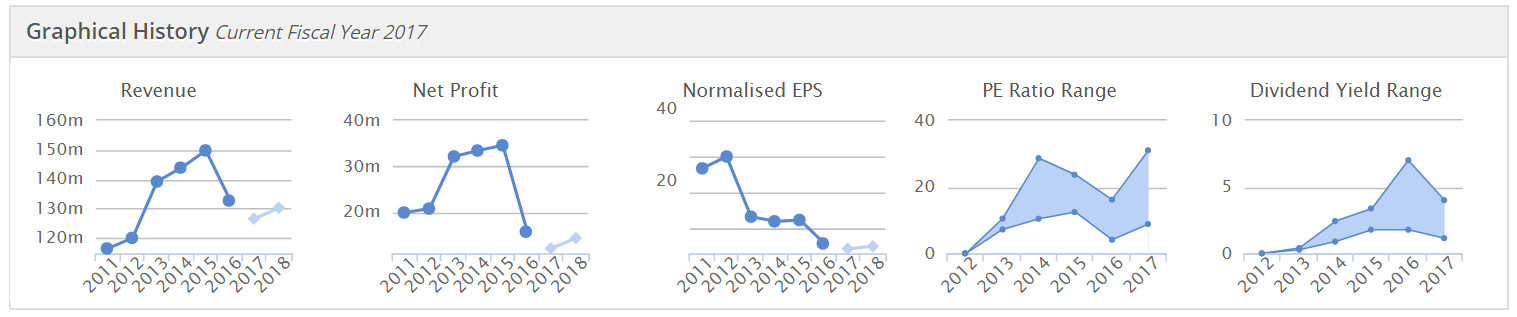
If you look at the Stockopedia historical graphs, you can see why this is one of my favourite shares - with revenue & profits growing in diagonal lines - steady, predictable growth. With no debt.
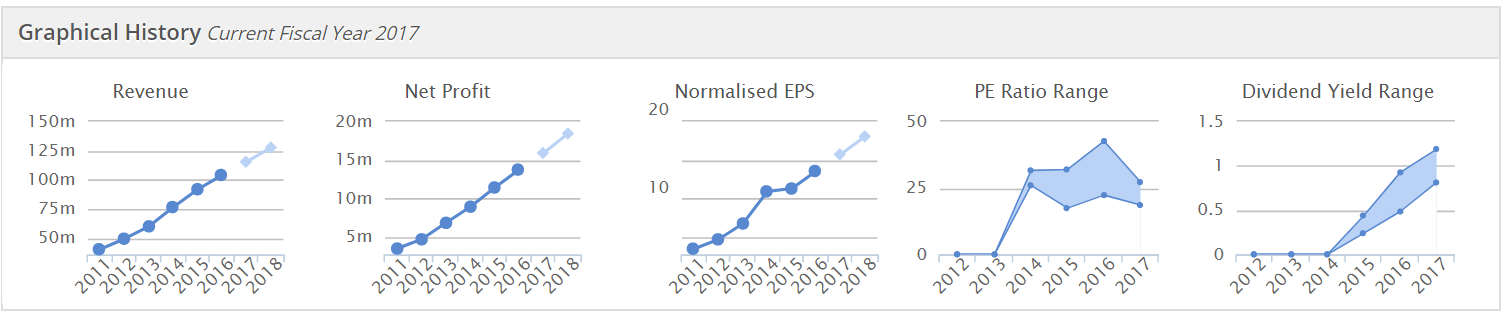
Remember that the net profit figures shown on Stockopedia are post-tax. So you can ascertain by comparing graph 2 (net profit) with graph 1 (revenues) just how strong (and consistently good) the net profit margin is at this company.
Profit growth is all well and good, but if the company is constantly issuing new shares to finance growth, then the benefit to EPS can be small. Not so in this case - as you can see from graph 3, with terrific EPS growth over the last 6 years.
Graph 4 shows us that the stock has never really been cheap - hardly surprising, given how well it's performing. So I would tend to see a PER of about 20 as being (in historic terms) about as cheap as we're likely to be able to buy the shares.
Finally graph 5 shows the emergence of divis. Clearly the yield is still very low, but the trend is upwards. Remember also that the company is using much of its cashflow to finance expansion - opening 20 new stores each year, at a reasonable cost of about £400k per site. Therefore, once the company reaches maturity, and stops expanding, it will have scope to pay out very much larger future divis.
It's amazing how much information can be quickly gleaned from these 5 little graphs.
Anyway, back to the interim figures, which look good to me. A few numbers;
Revenues up 11.0% to £55.5m
Pre-tax profit up 15.7% to £9.7m - note the exceptionally high profit margin of 17.5% - this is key to a successful roll-out, as it should mean that new stores are highly profitable, hence giving a very good return on capex.
Diluted EPS up 19.2% to 7.88p. It's always worth checking the tax charge, if the % change in EPS is different from the % change in profit before tax (and also worth checking if new shares have been issued). In this case, the P&L tax charge seems to have dropped from 20.3% in H1 last year, to 18.1% in H1 this year. So that flatters EPS somewhat.
Outlook - sounds fine to me;
Performance in the six weeks after the period end has been good with a strong Easter period. We are on track with our roll-out programme and have some exciting new locations for the remainder of the year. We continue to react positively to changes in the market place and I am confident we are well positioned to deliver another period of good growth in the second half of the year.
I would have preferred a specific confirmation of trading in line with market expectations. However, having seen several broker notes this morning, there doesn't seem to be a problem. The brokers confirmed that trading is in line, and that forecasts might even be raised later this year.
Balance sheet - this is superb, with no debt, and cash of £16.2m, up from £8.9m a year ago, despite having opened about 20 new sites in the last year.
The beauty of such a strong balance sheet, is not only that the company could sail through any economic downturn unperturbed. It's also that there is scope to make acquisitions. This is hinted at in the narrative, and mentioned by brokers.
So in effect, there is additional earnings to be added on, at no dilution to shareholders in future. That should be factored into the valuation, in my view.
Cashflow - a really clean cashflow statement, showing just what a quality business this is. It's too big for me to reproduce here, but it's well worth looking at the cashflow statement. That shows a business generating pots of cash, which is then used to finance its expansion capex, pay divis, and there's money left over to add to the cash pile. Really terrific.
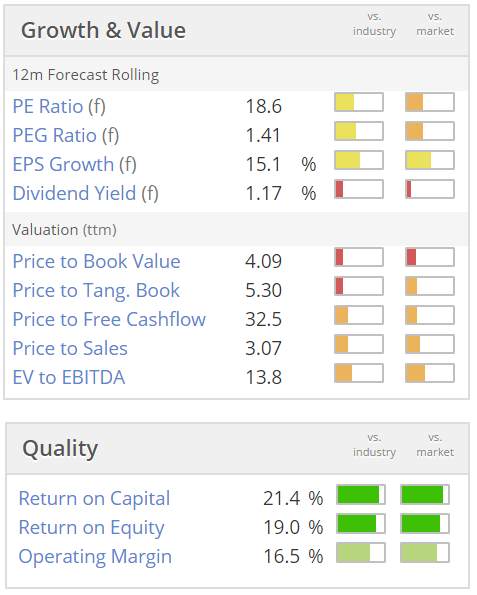
Valuation - I don't think this valuation looks stretched at all, for such a credible growth company. A high quality, self-funding roll-out, with net cash, on a PER under 20 actually looks rather attractive to me;
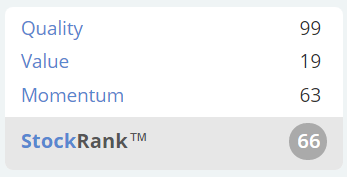
Stock Rank - I'm surprised the StockRank is not higher. 66 implies it's a good, but not great company (I disagree on that point!). Note that the value score is very low, but there's an ultra high quality score.
In terms of the intriguing new StockRank Styles classifications, CAKE is reported as;
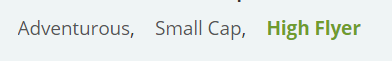
Note that the green colouring on "High Flyer" indicates that this is one of the successful investing styles. More info on the StockRank Styles is here. Remember these are computer generated, and back-tested, but not infallible.
My opinion - you may have guessed by now that I like these figures! This company really is a class act. Luke Johnson owns 38.6% of the company, so I'm very happy to be riding on the coat tails of this very experienced & highly regarded entrepreneur.
Hospitality is cooling as a sector at the moment. This is due to problems with rising costs, and over-capacity. Several companies in the sector have reported a decline in profits, and slowing or halting expansion plans.
As always, the best companies sail through troubled waters, taking the problems in their stride. That's exactly what's happening here. Cost pressures have been mitigated, it's just a really well-run business, with an excellent format.
I like the comments about expansion overseas now being considered.
Eventually, I reckon this company is likely to be sold, for a decent premium. This is alluded to by several brokers today.
EDIT: Many thanks to one of our star members, Bestace, who has flagged up a results presentation on CAKE's website. Well worth a read - it's here.
Slide 7 is particularly interesting, as Bestace points out below. It's an EBITDA bridge, showing the factors which moved EBITDA from last year's figure, to this year's. Here it is:
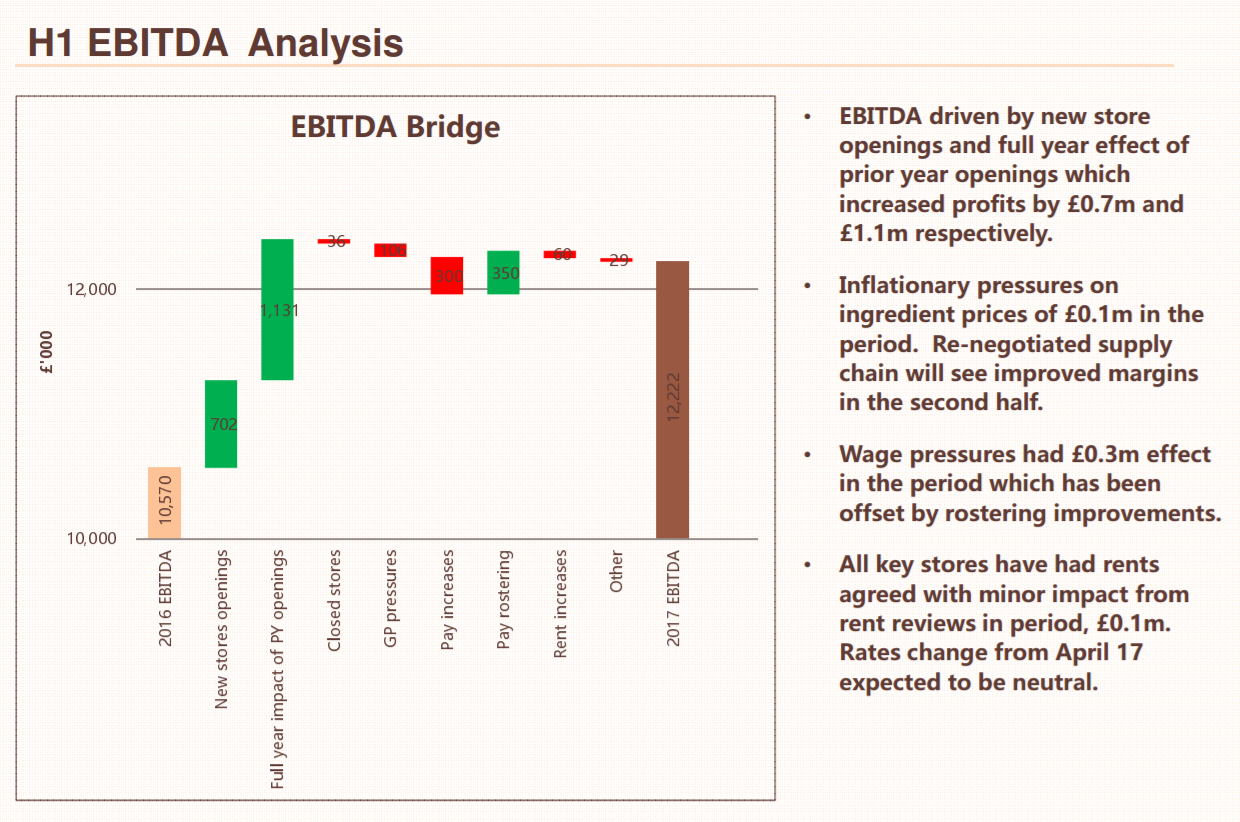
EDIT 2: I forgot to mention, another nugget of gold in the CAKE results presentation - the payback period on new sites is just 23 months! That is astonishing. Payback period is a key measure which helps you determine whether a roll-out is any good. Anything under 3 years is excellent. Under 2 years is awesome.
Foxtons (LON:FOXT)
Share price: 103.25p (down 2.6% today)
No. shares: 275.1m
Market cap: £284.0m
(at the time of writing, I have a small short position on this share)
Q1 trading update - this is the premium-priced estate agent, focused on London & some surrounding areas.
It says Q1 was in line with expectations, but note the sharp declines in sales commissions;
During the first quarter Foxtons performance has been in line with the Board's expectations.
Group revenue was £28.7m compared to £38.4m in the first quarter last year and £26.4m in the fourth quarter of 2016. This quarterly performance is set against the record sales volumes in the first quarter last year when a number of transactions were brought forward ahead of the stamp duty surcharge on buy-to-let investments and second homes.
Our first quarter revenues comprised property sales commissions of £11.1m (2016: £20.0m), lettings revenues of £15.5m (2016: £15.8m), and mortgage broking fees of £2.1m (2016: £2.6m).
The London property market has slowed considerably, especially at the top end, where punitive Stamp Duty changes are probably more of an issue than Brexit. Another issue might be unrealistic pricing. The Evening Standard this week had an article on a property in a desirable area, where the asking price had been reduced from £40m to £30m. It was a fairly large property, but was semi-detached!! Who in their right mind would pay £30m for a semi?! Ridiculous.
The other problem with top end London property, is that some vulgar neighbour could make your life hell by the latest craze of excavating gigantic basements - causing noise & massive disruption to everyone around them. Who would want that, after just buying your £30m semi?!
Back to Foxtons. It confirms today that it has no debt;
Foxtons holds a net cash position with no debt.
Look how profitability has collapsed from the boom years of 2013-2015;
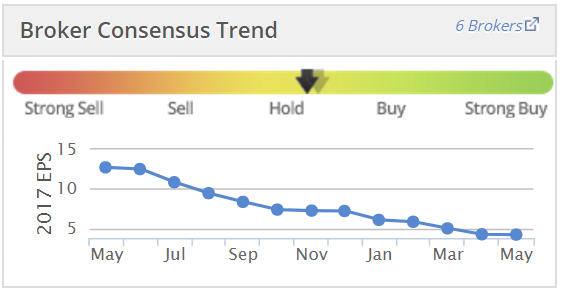
The markdowns in broker forecasts over the last 12 months have been striking;
Valuation - on current figures, the forecast PER for 2017 is about 25 times. Clearly that looks expensive, but this is a particularly bad year - and companies often look expensive on a PER basis, in a year where earnings are poor.
So the question really is, are earnings going to improve? It's difficult to see any catalyst at the moment for that to happen.
My opinion - I wonder what impact the online estate agents (market leader Purplebricks (LON:PURP) - in which I hold a long position) might have?
Foxtons charges eye-wateringly high fees in London, that look commercially unsustainable to me. Hence one of the reasons I put a small short on this share. Reputationally, Foxtons are not highly regarded either - in fact Londoners I've spoken to seem to constantly complain about them.
Altitude (LON:ALT)
Share price: 65.5p (down 2.2% today)
No. shares: 46.4m
Market cap: £30.4m
(at the time of writing, I have a long position in this share)
Preliminary results - for the year ended 31 Dec 2016. So very late figures, which readers will know is something that particularly rattles my cage.
This company has a tiny exhibitions & publishing business, which is barely worth mentioning. Although it does generate a modest profit. The exciting bit is a new venture, which is being pursued in the USA, called Channl. This is a software portal, which connects distributors of promotional goods (e.g. branded pens, mugs, rucksacks, etc) with the end customer and the factory.
The interesting thing is that Channl enables distributors to create many thousands of individual websites for each potential customer, with 3D viewing products mocked up with the client's logo. So it replaces, and is better than, catalogues. The customer can order online, if they like the products. The idea is that Altitude sits in the middle, and takes a cut of the revenues.
Management has been making big claims for this product. If these claims turn into reality, then the upside potential here looks remarkable. The only problem is that there's not any hard information on actual results so far.
The trouble with today's announcements, is that it's more jam tomorrow, and no firm evidence that this project is going to be a commercial success. So I'm a bit of a nervous shareholder. I've got no idea if it's going to work or not, this one is a bit of a punt.
There's not really any point in dwelling on the 2016 numbers, but for the sake of completeness, the key figures are;
Revenues £4.3m (down 4.7%)
Operating profit before amortisation charges & a few other small bits & bobs of £565k (up 94% on prior year). So at least it's not massively loss-making, as this type of jam tomorrow share usually is.
Balance sheet - is weak. Trade payables look stretched, at £1.75m, although there was £741k in net cash at 31 Dec 2016.
Placing - also announced today, this has fixed the cash position. FinnCap has raised £2.5m in fresh cash at 60p. Also, they placed 2.025m existing shares, held by a major shareholder, Keith Willis. So the cash position & balance sheet should look OK after this placing, which is not highly dilutive, so it's fine.
My opinion - I wouldn't normally go near anything like this. However, a friend with a good track record on small caps, has spent a long time researching it, and he reckons it's the real deal. So almost as good as being told by a bloke down the pub, I hear you scoff!
Time will tell whether this was an inspired stock pick, or a complete dud. I've only put in an amount I can afford to lose, which is usually wise with jam tomorrow shares. If there is any game-changing news, then I'll report back to you. For the moment though, this can only be considered a complete punt.
I think the pressure is now on management to deliver, rather than talking up the potential.
Zotefoams (LON:ZTF)
Share price: 311.5p (up 7.4% today)
No. shares: 44.4m
Market cap: £138.3m
Trading update - covering Q1, ended 31 Mar 2017.
The company calls itself a world leader in cellular materials technology. In language I understand, I'd say they mainly make foam for things like car seats.
A few key points from today's update;
- Revenues up 28% in Q1 vs Q1 last year - in line with management expectations.
- Some forex gains, so at constant currency growth was 16%
- Additional production capacity of c.20% is expected to come online around end of Q3.
Outlook - why can't they say that profits are in line with expectations or not? Instead we get this waffle;
While it is still early in the year, and we are mindful of the less stable political and macroeconomic environment, we continue to expect 2017 to be another year of progress and remain confident about the long-term prospects of the business."
To me, that sounds a little hesitant. However, the market has lapped it up, with the shares up 7.4% today. Also, since they said earlier in the RNS that revenues were in line, I suppose we can probably assume that profit was in line too. It's a lot easier when things are spelled out more clearly.
Valuation - brokers are forecasting 15.3p EPS for 2017 (PER of 20.4), and 17.9p for 2018 (PER of 17.4), so the shares look priced about right to me.
Shareholders get a dividend yield of about 2%
My opinion - it looks fairly good. Probably the main downside for me, is that it's so capital intensive, with lots of fixed assets needed to manufacture its products.
I seem to recall there was talk of some blockbuster new product a couple of years ago, so that might be worth having a dig around for. Overall, I'd say this company might be worth doing a bit more work on - growth has been good in recent years, with more in the pipeline. The valuation seems fairly sensible, providing nothing goes wrong.
Ideagen (LON:IDEA)
Share price: 95p (up 1.1% today)
No. shares: 198.1m
Market cap: £188.2m
Trading update - for the year ended 30 Apr 2017.
This is an acquisitive software group, specialising in supplying software to highly regulated industries (e.g. healthcare, financials, etc).
Here are the main points summarised;
- Results should be in line with market expectations.
- Trading robust across all key verticals.
- Organic revenues growth was 10%
- Four acquisitions made in the year.
- Revenues £27.1m, adjusted EBITDA of £7.8m expected, both up 24% on prior year.
- Transition to SaaS is going well.
- Cash generation "extremely strong".
- Net cash at 30 Apr 2017 of £4.2m (significantly ahead of market forecasts)
- Positive outlook comments, confident about current year & beyond.
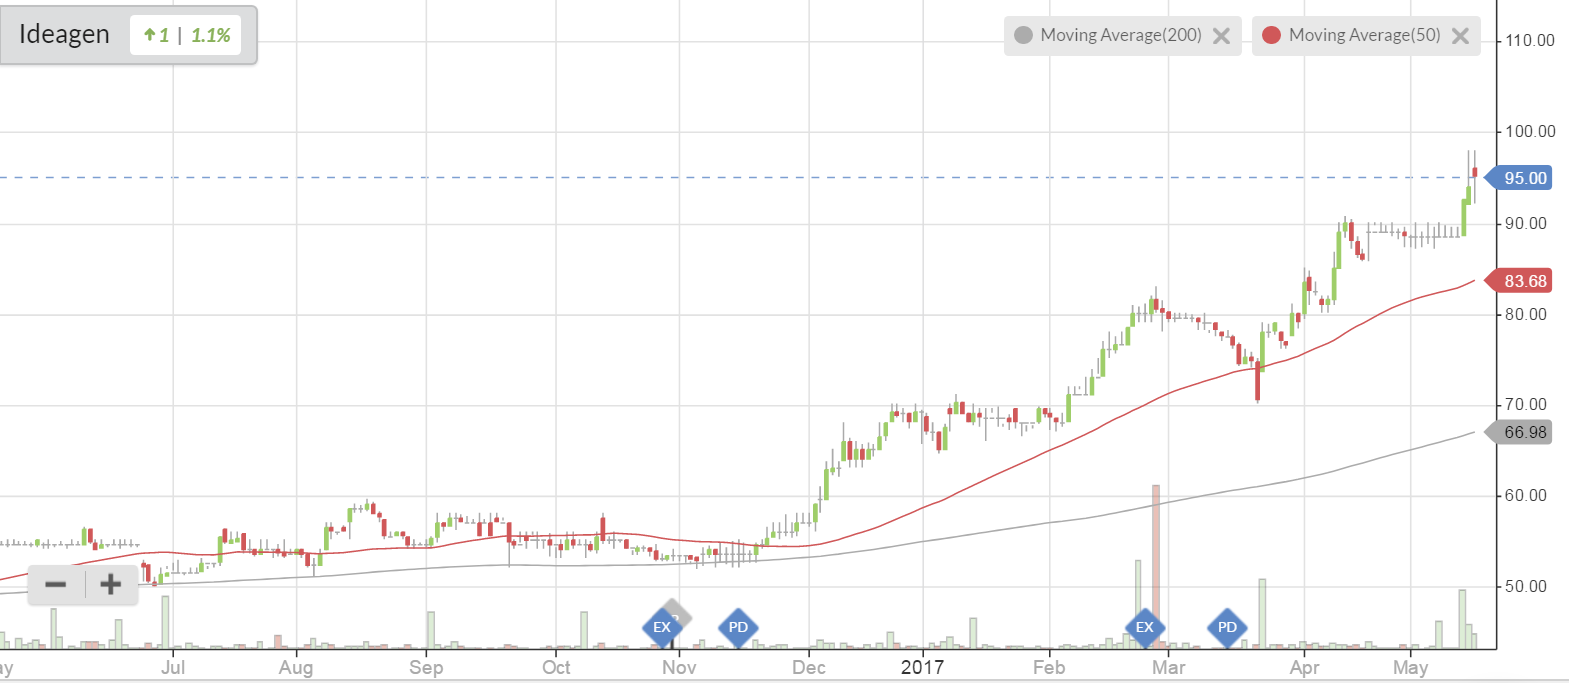
That all sound very encouraging. I suppose the question is, how much has been anticipated by the big rise in share price of late?
The forward PER is 22.4, which looks a fairly full price to me. There again, performance seems to justify the share price almost doubling in recent months. Well done to holders!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Slightly dated (a couple of months old) but interesting article from Phil Oakley on how he assesses roll out valuations. Comments extensively on Patisserie Holdings (LON:CAKE) as well as a couple of other stocks with topical relevance to Revolution Bars (LON:RBG) and others.
https://www.sharescope.co.uk/philoakley_article141_f.jsp
My principal takeaway from this is that timing the exit to an investment is key on the basis that as and when momentum starts to fall away there is the compounding double whammy of lower earnings and a lower market p/e rating giving a sharp decrease in share price. Sods' Law, this is often the point at which many private investors decide to climb aboard.
Gus.
Whoops...The above relates to Post # 29.
Zotefoams (LON:ZTF) I'm pretty sure the 20% increase in capacity is an increase in global capacity not the companies capacity. This would put it in a commanding position. That's my understanding anyway.
In April, the company entered into a 12-week agreement with Sainsbury's to supply 12 nationwide stores with its product, which is being sold in-store from Patisserie Valerie branded counters at Patisserie Valerie price points.
Foxton is an estate agent I found arrogant and rude. I would never approach them again.
Lennart
Londoner
I live and work in Central London and concur with Paul's thoughts about Foxtons (LON:FOXT)
I have never heard a good word said about then.
In recent months our Young Engineers Network (essentially a drinking club but also used to welcome new graduates to our employer and London) have actively been steering people away from them for lettings.
I have no personal experience of them but this doesn't sound good.
I like your long Purplebricks (LON:PURP), Short Foxtons (LON:FOXT) .. a new form of option structure: the Scott Collar
NCC (LON:NCC) catching a bid today up almost 10% possibly on the back of the boost in Sophos (LON:SOPH) which is up on good earnings and the whole Cry me a River (of money) ransomware
As far as Foxtons (LON:FOXT) and other estate agents are concerned, if the next Government bring about a ban on charging tenant fees, other than a deposit and rent, then that will really hurt their lettings income.
I'm certain that these charges have absolutely no relation to how much it costs to carry out tasks. So I'd expect the costs to be drastically reduced as the costs are passed to the Landlords, who can shop around, and away from tenants, who have far fewer options. Not only that, it would remove a significant cost of moving. What is the point of spending several hundred pounds in fees to save say £25 or £50 a month in rent? I'd expect rents to fall in that situation and put further pressure on their fee income.
I have no current position in Foxtons (LON:FOXT) , but I'm keeping it on the watchlist as a potential short. It really depends on what the next Government does to tenant fees.
Regarding the government threat to limit charges on tenants, I think it was Belvoir Lettings (LON:BLV) that put out a statement that similar legislation in Scotland some years back had no real impact on agents' profits, and perhaps M Winkworth (LON:WINK) that suggested that they might take a 9% hit. I think Property Franchise (LON:TPFG) also had a largely dismissive response. Of more relevance to Foxtons (LON:FOXT) is a possible cooling in the London market. I live in the grim north so have little to say on the latter. For those looking for yield, estate agents seem to me to be a reasonable repository for their money at the moment, but future growth prospects seem limited.
All, I share Paul's enthusiasm for the graphical history mini graphs but a caveat regarding EPS is worth sharing.
If the net profit is negative and the number of shares is increasing it will make the EPS appear to be improving more than it is when in fact the loss is being diluted across a greater number of shares.
Paul's thoughts on CYAN would indeed be most welcome! Still waiting for the turnaround...
Hi runthejoules,
Please don't take offence to what I'm about to write but Cyanconnode Holdings (LON:CYAN) is the exact type of share every investor should be placing firmly on their barge pole list.
a) It's a highly speculative, micro-cap penny stock.
b) It has a Stockrank of 1.
c) It's impossible to value.
d) It hasn't made a single penny in net profit for over 10 years.
e) It qualifies for 3 short selling screens.
f) The company burns through cash and needs to raise money from investors, diluting existing share holders.
and finally, the stock is classified as a Sucker Stock! I can't see any appeal in owning this share and waiting for a turnaround could be a disastrous strategy. I don't normally give investment advice, but I would strongly rethink your decision to hold out for a turnaround.
Kind Regards.
Hi BH1991,
You are right to sound the bargepole warning on Cyan. However, I once held a stock that I bought at floation (back then it was on the old OFEX market). For years it was a one product-serial-not quite there-kind of stock. Until one day, it wasn't. And it's ahare price went from the mid teens right up to about £3.50. It's now around the £2 mark. It's been my only serious 20-bagger where I was thankfully in there in volume. It's name - Sprue Aegis plc. And it yields for me a dividend (at my 20p average entry price) of 40%!.
Not bad if you can find them?
I agree you have to have a strict bargepole policy and this could well be one of them. I for one am NOT convinced by Cyan at the moment, but it is firmly on my watchlist for sustainable green shoots, and even then, I would only dabble. Trouble is, you can then miss the biggest part of any re-rating.
I feel the same way about Redstoneconnect BTW, but I have only picked up a tiny opening position.
Regards
Thanks both. No offence taken at all. I think next time they release an RNS for another deal, if the SP goes up (as it often does, for about five minutes), I will come straight out of it. But not just on your opinions but my own! Going to try to follow bargepole criteria like yours and Paul's more in future - more discipline, less optimism. Cheers!
With jam tomorrow stocks, it's true that occasionally people hit the jackpot (especially in a bull market). However, in my experience, punting on things like CYAN is just gambling really. Unless you know the sector inside out, and are certain that you're onto a winner.
Also the jam tomorrow stocks that do zoom upwards in bull markets, often end up being worthless a few years later, once the BS unravels. I'd like to do a study of jam tomorrow stocks, and systematically plough through everything small cap & speculative that floated in the last 20 years, and see what the end result was. I bet it would be absolutely dire.
Still, that doesn't stop the spivvy rampers that try to (effectively) steal our money, from pumping crap. All they need to do, is create a nice spike, then they sell. I despise people like that, and have come across plenty in my time. They pick stocks that you can't value - so things that don't have earnings or divis. That's why it's best to avoid junk like that - a key message of this site, both the geniuses with their algorithms at Stockopedia HQ, and in my small way, with my "nose" and experience of spotting wrong 'uns like Globo, Quindell, and plenty more. Put the 2 together, and it should cover most bases at avoiding dangerous stocks. and of course the crucial DYOR bit.
Regards, Paul.
Hi,
I'm not going to have time to do a write-up on Cyanconnode Holdings (LON:CYAN) . However, on a quick glances, the figures look terrible. A huge loss on, very low turnover. Very much heavy cash burning, jam tomorrow sort of thing. Not for me.
Regards, Paul.
It's amazing how much information can be quickly gleaned from these 5 little graphs.
Paul,
Yes, I agree. I realise it's probably just me but I'm not sure what the PER and Yield range charts are based on; I read through the Stocko Help page on them and I'm none the wiser.
Say for PER, what P and E is the range based on? Is the E the FY earnings result or (estimate for current year) and the range varies with P for each year? And if so, what E is it - Basic or Diluted? Same applies to the Yield range chart. It would be nice to know exactly what is being shown so that I can make better use of them!
All the best, Si
Paul
Do you have a view on Wincanton. Today's prelims look resilient, with several new contract wins and increase in the dividend. Debt is coming down and the outlook positive. Given the continuing rise of internet shopping logistics is increasingly important, although construction also appears a promising sector for Wincanton. However there remains the substantial pension deficit to contend with, hopefully this will eventually be eroded by a rise in yields, at some point?
Regards
Jonno
Good afternoon Paul (and all),
I wondered if you had seen and had any thoughts on CyanConnode Holdings plc, whose results came out yesterday. I think you were long last year, and you had a small spat with Mr Winnifrith? Superficially the (very late) results and recent contract wins look good but my God, what a serial disappointer this has been. Could it be on the cusp?
Revolution Bars: I have been lookimg for a decent entry point and the recent falls tempt me a lot. However it feels to me like consumers are in serious belt tightening mode right now. I'm in the bar/clubs trade myself: 2016 was fantastic but 2017, whilst benign, is nowhere near as good. If amything I'm sensing an impending shakeout, particularly led by restaurants (and others in over rented leases or where the recent rates revaluation may bite badly). Should this transpire, this may be good news for the strong and conservatively run, and I would include RBG in that category, but sentiment may drag this stock down a bit further for now. If anything, Revolution Bars may be able to accelerate the roll out a bit as rents can be squeezed even more. I am very much on the lookout to expand myself!
Just my opinion!
wrt £CAKE a finnCap note today they stated:
Management hasreaffirmed its 20 new stores target for FY17, although this mayprove conservative given the imminent on-boarding of a four-site package fromMaison Blanc. International expansion has moved up the agenda...
Nice. Very nice.
Patisserie Holdings (LON:CAKE) no mention of increase in turnover of existing units . unless I missed it.
I agree that interim results for CAKE are very good. However I couldn't see any LFL figures which are normally reported in these type of retail roll outs. Does this mean that all the growth is coming from new outlets, and if so, does that matter? Without LFL growth and bearing in mind cost increases, profitability on existing units could start to reduce.
Patisserie Holdings (LON:CAKE) have never reported on LFLs so I think it would be wrong to infer that growth is only coming from new outlets. All we know is that the 11% growth in revenue has outstripped the 8.5% increase in the number of stores compared to this time last year.
The presentation they have posted online to accompany the H1 results is worth a read, in particular the EBITDA bridge chart on slide 7.
Hi Bestace,
Brilliant, thanks for flagging up the results presentation on CAKE's website.
I'll copy the EBITDA bridge into the main report.
You're a star, thanks! :-)
Regards, Paul.
Hi Bestace
Thanks for flagging that presentation and to Paul for posting here.
My take on the EBITDA bridge is that sites that were fully operational throughout FY2016 make up all the figures from "Closed Stores" to "Other". This implies that current stores actually had a negative impact on EBITDA. Happy to be corrected if I'm misreading the chart.
I have no opinion on how this will impact Patisserie Holdings (LON:CAKE) in the long term; it was merely an observation.
I am not a holder.
Abtan
Yes, LFL growth matters a lot ! If the core sites are underperforming or show any meaningful decline than you have to question if the underlying business model is working? (see Tasty / Crawshaw). Either the business is not operating efficiently or consumer tastes / habits may have changed.
A sensible management team would then put the roll-out on hold whilst the core business returns to growth. You don't make decent ROCI's with a cookie cutter model of rolling out more underperforming sites!
Do they usually report LFL's of mature sites ? If they are conspicuous by their absence I'd be a little concerned.
Generally on the sector, I know a lot of the private operators well and there are some strong headwinds in this space (rates, rent, wage inflation, oversupply, deliveroo etc) which are impacting LFL sales and restaurant EBITDA / contribution margin. Sector data is not overly positive.
My advice would be to invest only in those businesses considered the best operators in this sector. There will be winners and losers in this space and due to the high operational leverage, the impact on any fall in LFL sales will be amplified on the bottom line.
ps. I'm suspicious of the budget gym sector for the same reason. A well know listed group does not talk about LFL growth in their prospectus - it's all about fast growth from rollout.
c.30-40% of new members are not regular gym goers (i.e. subscribing because it is cheap).
The gyms are very lean operating models with a high level of fixed overheads. A lot of their expansion came when sites were acquired at very attractive rental multiples during the last down-turn.
Ultimately increasing rents, rates, wages will mean costs will go up and once gyms operate at optimal capacity, the only lever you can pull to maintain margin is fees. If fees need to increase faster than wage growth, what happens to your membership numbers?
They still have some runway to go but I question long-term sustainability of margins in the sector.
Your comments on the importance of LFLs represent the consensus view and up to a point I think that view has some merit, but there is a counterview:
Most people here will be familiar with the old refrain about revenue being vanity, profits being sanity and cash flow being reality. In other words what matters most to investors is not so much top line growth or LFLs, but overall profitability (i.e. the bottom line) and cash flow.
Focusing on top line growth and LFLs can lead to perverse actions such as discounting to boost sales at the expense of gross margin and overall profitability. Furthermore weak LFLs may be a symptom of a broken business model, but it does not necessarily follow that just because LFLs are weak, the business model is broken or that existing stores are underperforming.
For example if weak LFLs are due to increased competition and if you're one of the stronger players in the marketplace, you might want to increase the pace of the rollout to put pressure on your competitors. Pausing and waiting for the trading environment to improve, or trying to fix something which isn't actually broken might be missing an opportunity.
In the case of Patisserie Holdings (LON:CAKE), clearly the business model is not broken and I think focusing on this comment in the Patisserie Holdings (LON:CAKE) presentation is more important than speculating on whether their LFLs are weak:
The 'now' in that comment might imply it hasn't always been the case that all stores have been profitable, but they have included the exact same statement in every 6-monthly update since they listed. The time to start asking questions about possible under-performance will be if they ever remove this statement from their updates.
On low cost gyms, I don't think you are drawing a comparison between that sector and Patisserie Holdings (LON:CAKE), but it's worth remembering that CAKE requires little capital to expand, their stores are profitable from day 1 and their payback period for each store is very low. None of those features apply to low cost gyms, so in the case of CAKE I'd suggest pushing ahead with the rollout is the right strategy even if LFLs are weak (not that I accept that they actually are weak).
The gyms analogy is one to mull over. As you say, a well known listed gym company does not talk about LFL sales. As I pointed out in January, one of them didn't have significant LFL sales growth based on sales v number of sites (Revenue: +22.6%, members + 19% & number of gyms +20%). There are also several competitors rolling out gyms & when I look through the windows, lots of empty running machines.
Moving back onto Patisserie Valerie, well Paul's pitch has my interest. It's about time I actually visited the local branch, so I can understand how it is differentiated from Costa, Starbucks, Nero, Pret a Manger etc.
At one end of the market we see Greggs has moved from a bread shop to fast food & serving in shop coffee, although quite a low end offering. Service is also sadly lacking.
Then I notice Costa & Starbucks are broadening their food offering, so I suppose it is necessary to work out what differentiates CAKE & whether that difference will remain in place.
No it doesn't really matter but it is rare not to report it .one has to assume that as it isn't reported the figures are static or negative. Surprised Paul did not comment on it
.I think the company is well run and worth investing in. Going into supermarkets is a good idea as relatively low cost and increases exposure to a sector of the population that might not go to their outlets.
Paul, if you get and are able to share any feedback from Blue Prism (LON:PRSM) Capital Markets Day today, it would be much appreciated.
Thanks,
Jane.
As I said on another thread, they are possibly down due to MAB's results today "challenging market backdrop" etc etc...
Correlates. Interesting to note that MAB are chasing a more premium experience for their customers in order to mitigate growing costs. This bodes well for RBG as they are the definition of premium experience.
http://www.bucksfreepress.co.uk/news/13367429.Man_arrested_and_another_injured_as_bar_fight_spills_onto_street/
http://www.getreading.co.uk/news/reading-berkshire-news/man-coma-after-reading-brawl-12182671
http://www.liverpoolecho.co.uk/news/liverpool-news/liverpool-boxing-legend-shea-neary-3374101
Premium experience??????????? ; )
My idea of premium experience is cira one headbut a night
Also saw one of these in Debenhams Oxford str last week ; was early morning so too early to judge the trade.
Might be an idea to get the van backed up for some more RBG. Can't see any reason for the fall.