Small Cap Value Report (Wed 18 July 2018) - MPAC, CALL, HEAD, RDL

Good morning!
Today we have in line with expectations updates from Hotel Chocolat (LON:HOTC), Premier Foods (LON:PFD), DX (Group) (LON:DX.), Strix (LON:KETL), Bloomsbury Publishing (LON:BMY) and Team17 (LON:TM17).
So I intend to focus on MPAC (LON:MPAC), which issued a profit warning, and on Headlam (LON:HEAD). Paul has also written a section on Cloudcall (LON:CALL).
MPAC (LON:MPAC)
- Share price: 145p (-34%)
- No. of shares: 20 million
- Market cap: £29 million
I have previously described this as "a pension fund with a small operating business attached".
It traded under the name "Molins" and was traditionally associated with the tobacco industry, but sold its tobacco division in August last year.
What is left is a packaging machinery business focused on the pharma, healthcare and food & beverage markets.
Today's news
"...the business climate has softened considerably as the year progressed, attributable in part to general economic as well as Brexit related uncertainty, leading to customers deferring machinery investment decisions. The Board believes these contracts will be delivered in future financial years."
Many small-cap investors will be familiar with this type of profit warning. Decisions on contracts get delayed sometimes, it goes with the territory.
It's still a disappointment of course. A longer sales cycle ultimately means lower earnings for MPAC and makes it a less valuable company.
Blaming economic and Brexit-related uncertainty is a bit harder to stomach. Given how many companies have reported that H1 was in line with expectations, it suggests that most companies are not finding conditions as difficult as MPAC is.
The UK manufacturing PMI has been softer than it was last year, but it remains north of 50. This means that most manufacturing companies are continuing to report an improvement in conditions.
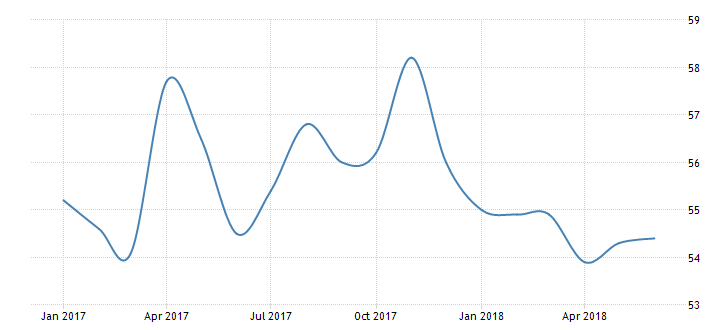
Source: TradingEconomics.com
The final point I would make is that only 14% of MPAC's sales are to UK-based customers (according to the 2017 annual report), while 24% are to Europe (excluding the UK). Most of the company's sales are to either the Americas or to Asia Pacific. The US economy is extremely strong right now.
So while I accept that capex spending is cyclical, I think we need to take the idea of "economic uncertainty" being to blame for this profit warning with a large grain of salt.
Alternative explanations might be that the packaging niche in which MPAC operates is struggling, or that specific problems at MPAC are causing it to struggle.
The next named problem in today's announcement is much more tangible. Two legacy projects are running late and their cost overruns are eating into MPAC's profits for the current year.
Again, this is standard fare: contracts which don't work out as planned. This is why contract-driven businesses need to be on modest valuations. We need to allow for the occasional mishap!
Updated numbers
Revenue will be in line with expectations, but "the closing order book will be lower as a result of market softening and profits are currently expected to be around £1.2m below current market expectations."
Equity Development have cut their 2018 EBIT forecast for MPAC by £1.3 million to £1.5 million. Their note is available online.
My view
There are two elephants in the room with MPAC.
The first is the cash pile. This is forecast to end 2018 at £24 million.
Normally, if I saw a profitable company with £24 million of cash and a £29 million market cap, I would want to buy the stock.
But the other elephant in the room is much larger. It's a £400 million UK pension scheme.
The accountants valued this scheme at December 2017 as follows:
- Assets £415 million
- Liabilities £397 million
- Net surplus £18 million
The actuaries valued the scheme at June 2015 as follows:
- Deficit of £70 million (funding level of 83%)
An updated actuarial view on this would be helpful. The June 2018 valuation will be completed in H2 2019.
I was tempted to buy MPAC shares when I saw the announcement first thing this morning, but I had to remind myself that it's largely a bet on the performance of the pension fund. Marginal variations in the long-term value of its assets or liabilities will have a bigger effect on shareholders than marginal variations in the performance of its packaging business.
In general, pension funds benefit from higher interest rates (it means that future liabilities are worth less today, and that the future return on pension fund assets will be higher).
UK rates have not improved since June 2015. So that is one reason for caution in relation to the next actuarial valuation.
If I expected that UK rates would have a substantial increase, or had some other reason to expect the actuarial deficit to go away, then I would be a lot more interested in these shares.
Example calculation: If you add the together MPAC's latest market cap, the £70 million UK pension deficit from 2015, and subtract the £24 million of forecast year-end cash pile, you get an enterprise value of £75 million.
Based on payments made into the UK pension fund since 2015, we might reduce our estimate of MPAC's enterprise value to £65 million. That's the implied market estimate (using 2015 pension assumptions) for the value of the operating business.
If MPAC achieves its EBIT forecast of c. £3 million next year, that's not terrible value. But it's not a screaming buy either. And we are also punting on the pension fund.
The next section is written by Paul Scott, who owns CALL shares.
Cloudcall (LON:CALL)
- Share price: 134.5p (+2%)
- No. of shares: 24 million
- Market cap: £32 million
Somewhat belatedly, here are my comments, in response to reader requests above, on the Cloudcall (LON:CALL) trading update yesterday. I hold a long position in CALL shares.
Firstly, it was clearly a profit warning, but a fairly mild one. The 2 brokers which report on CALL (both make their research available to subscribers of Research Tree) both put out updates, reducing 2018 revenue forecasts from c.£9.5m to c.£9.0m.
One broker reduces its 2018 EBITDA loss from £2.4m to £3.1m, and the other reduces from a £1.9m EBITDA loss, to a £2.9m loss, so quite a significant drop in forecasts at the EBITDA level.
What's gone wrong? The company says it's all down to timing of recruiting & training new sales people, which has taken longer than expected. It says there's not a problem with customer demand, they just didn't have the internal resource to bolt on new customers at the pace required.
The brokers clearly believe that explanation, as they have not reduced revenues forecasts for 2019. The company also talks about expecting a strong H2 in 2018, as the new recruits kick in.
If it all pans out as the company suggests, then the current share price weakness should prove temporary. The trouble is that the company has proven somewhat accident-prone in the past (repeatedly missing targets, especially on cash burn), so investors are wise to take the company's outlook comments with a degree of scepticism. That doesn't make it a bad company, but I'm just pointing out that it tends to be overly optimistic, and then disappoints a bit. But that's within an overall picture of strongly growing revenues (which have risen organically from £3.3m just 3 years ago, to forecast c.£9m this year - that's very impressive growth).
Organic growth - is still very impressive, as noted above. The market tends to put a significant premium on the price of any company delivering over, say 20% organic growth at the top line. CALL is still well above that, at +31% Y-on-Y revenues growth in H1 of 2018. That's still a very impressive growth rate, albeit below the previous forecast of c.39%. I don't think the company should be punished too hard for this.
I like to look at not just year-on-year growth, but also sequential half year growth. This has been;
H1 2017 £3.2m
H2 2017 £3.7m (up 15.6% on previous half year)
H1 2018 £4.1m (up 10.8% on previous half year)
So there's been a slowing there, but still good growth.
Note also that the company has sticky, recurring revenues - because its product is excellent (I use it myself). Cashflow is hence highly predictable, with customer receipts coming in regular as clockwork each month. Customer retention levels are high, because people find the product so useful. That's key for building a SaaS business. Gross margins are also very high - again a key point.
Will it need more cash? Almost certainly, yes in my view. Does that matter? Not at all, in my view. There is no reason for shareholders to worry about another fundraising, because the company is well beyond the blue sky stage, when fundraisings are uncertain & can be done at deep discounts if investors are nervous. CloudCall's business model is now proven, and if it needs say another £3m to push it over the line into profitability, then that would only be about 10% dilution, and I reckon Instis would be queuing up to participate.
Evidence for this is that the last placing raised £5.7m in late 2017, and was priced at 143.5p, only a 5.3% discount to the then share price of 151.5p.
The only circumstances in which CALL would struggle to raise more equity, would be if the whole market turns bearish, and/or if CALL's revenue growth grinds to a halt. If that happens, then we'd be looking at a much lower share price, for sure. But that hasn't happened, hence why I think worries about another placing are wide of the mark. It's not a worry to me at all, for the reasons given.
Note that the company has a track record of repeatedly stating that it will not need to raise more cash, and then going on to raise more cash! So the reassurances given in the latest update that it has adequate cash resources, and worthless in my view, given the history. But it doesn't actually matter either way.
Is this a buying opportunity? That's obviously up to each individual to decide for themselves. I see this as a "good" profit warning - i.e. temporary, fixable problems, with the business model & growth story intact, just slightly blunted in H1.
The share price recently peaked at 193p. So being able to buy at 135p today, seems an attractive proposition to me. I can understand emotions kicking in, and some investors' patience wearing thin, but taking a longer term view, this share could be worth substantially more, once you factor in a few more years' strong growth, and the eventual move into profit.
Tech shares like this are not really valued on profits at the moment. The market is instead placing more emphasis on growth, with strong organic growth (combined with lots of operational gearing here, from high gross margin) should attract a premium rating.
There are plenty of private equity buyers around, willing to pay eye-watering valuations for growth tech companies. I would welcome a takeover bid for CloudCall, providing the premium is sufficiently large. It doesn't sit well in the stock market, where people are too focused on short term performance. Whereas, the better option for a growth company is to set aside short term profitability, and instead "go for it" in terms of growth, which might mean incurring heavy losses in the short term.
For stock market investors, CloudCall has been frustrating, in that the runway to profitability seems to be extended each year, by a year! The company is increasing its costs to take advantage of growth potential (and extending the features of its product), but with the time-lag inherent with that type of spending, it results in administrative costs relentlessly increasing, and absorbing the benefits of increased sales/gross margin. Hence why I don't think CALL should be listed on the stock market - it would be better off as a private company, and able to press on with faster, but more cash-consuming growth in the short term.
Overall, I think that for investors who are prepared to be patient, then we should do well out of this one in the long-term. The current market cap is extremely low for a SaaS business that's not far off profitability. Just look at the valuation of LoopUp (LON:LOOP) to see what can be achieved in this sector.
Regards, Paul.
Next section written by Graham.
Headlam (LON:HEAD)
- Share price: 456.25p (-1%)
- No. of shares: 84.3 million
- Market cap: £385 million
This is an H1 update for "Europe's largest distributor of floorcoverings".
Paul last covered it in May (link), when the company issued what he described as a "mild profit warning".
This also feels like a mild warning. Note the phrasing used:
Subject to no further downturn in market conditions and the Company experiencing the usual weighting of trading to the traditionally stronger second half of the year, the Board is currently confident of delivering expectations for 2018.
It's similar phrasing compared to what the company said in May.
Like-for-like (LfL) UK revenue is down 5.5% in H1. This is a small improvement compared to the 6.3% reduction reported for the first four months of the year.
It's crucial to focus on LFLs, as Headlam has made three acquisitions so far in 2018. These are described as "infill acquisitions", i.e. not too big.
My view
This is another cheap stock in the household goods / retail sector. There are quite a few of these knocking about at the minute.
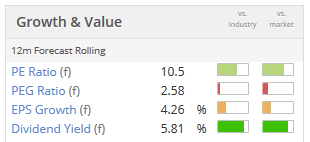
Checking the archives, I see that I wrote positively about it last August, with the share price at 575p.
I gave it points then for the clarity of its presentations, its long-running dividend track record, and its lack of acquisition activity.
However, since then, it has been surprisingly active in acquisitions. In December 2017, it purchased a Dutch company for up to £35 million, to diversify into ceramics and broaden its capabilities in other types of hard surface.
This reduces my interest in the stock, as I like to keep things simple by looking for companies with organic growth, whenever possible. Or if there is no organic growth, then I want a cheap valuation. I don't want growth by acquisition instead.
Other aspects of the stock remain attractive. It qualifies for the Stocko screens "Best Dividends" and "Dividend Achievers". Cash generation has typically been excellent.
This has been a rare example of a distribution company that has succeeded, for reasons Paul may have figured out back in March (in a nutshell, that independent retailers don't have the space to store all of the floorcoverings needed for customer orders).
So I retain a positive overall view of Headlam.
I wonder if it's really wise to go hunting for acquisitions, though, when business is tough? I know from my own career experience that acquisitions are incredibly distracting, and take up a great deal of management time. I'd worry that management may have too much on their plate, dealing with a tough environment and also trying to bed in a bunch of subsidiaries.
Ranger Direct Lending Fund (LON:RDL)
Please note that I currently own RDL shares.
Holding(s) in Company - this is a stock I classify within the "fixed income" part of my portfolio, as it is mostly invested in loan assets and is not using much leverage.
It's a special situation as the fund is headed for wind-down after a shareholder activist battle won by Oaktree (the firm created by Howard Marks) and LIM Advisors.
There was a little bit of news yesterday I thought I would mention: LIM has increased its stake from 10% to 12%.
LIM now has Board representation, and I take it as a positive sign that it is increasing its stake. I reckon that LIM is probably more knowledgeable when it comes to RDL than whoever is selling. We shall see!
I think the NAV is at least 871p at latest exchange rates, using end of April data. I am looking for this discount to close, for the bulk of fund assets to generate a reasonable return until they mature, and for wind-down expenses to be low.
Calling it a day there. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
I disagree that this is the wrong time for Headlam (LON:HEAD) to be looking for acquisitions. Now that the whole industry is struggling, it is the smaller ones that do the worst, and so Headlam (LON:HEAD) should be able to pick up lots of small acquisitions at really good prices, and then also realise a lot of synergies.
Granted, this will stretch their balance sheet and also management attention, but if they get it right they could end up really building a business that throws off lots of value in the next few years.
BIt of a late comment - re Ranger Direct Lending Fund (LON:RDL) which Graham has previously elaborated on further by pointing out the high dividends previously paid plus the discount to NAV. I believe the discount to NAV of about 9% is probably not sufficient reason to buy the assets, given that it will take a few years to realise the loans. But Graham's point is that there also large dividends of 90-100p per year on the way, which is what helps to make it into a good deal.
I just wanted to question this assessment. Could it be that the NAV already takes it into account the high expected income due to be converted into dividend payments, and that therefore as the income is received and paid out the NAV will therefore decrease to offset this? If this is true then the case for buying is much weaker. Would be happy to hear Graham's opinion (or anyone else's).
Ranger Direct Lending Fund (LON:RDL)
Dgold
Could it be that the NAV already takes it into account the high expected income due to be converted into dividend payments, and that therefore as the income is received and paid out the NAV will therefore decrease to offset this?
That's a pretty decent question that did pique my interest, as i like a decent value play.
Graham did say the following in the 11th June article which suggests the company does indeed earn some sort of crust while waiting for its chips to be cashed in. probably a bit akin to the boring bit when its down to the last 2 at the WSOP of poker, and they keep playing for another 11 hours when everyone has gone just because the refreshments are on the house.
Per Graham
So I do think I will get a nice interest yield on the existing debt portfolio and then get a capital return as the portfolio is liquidated.
Ok does this tally with the 2017 annual accounts ? lets have a look
http://www.rangerdirectlending...
Aside (Ooooh top marks for sensible directors fees)
ok (all dollars)
Investment income 26 mill - 8 mill other income - fees (hmm is that where directors have their snouts?) + expenses 14 mill
profit 20 mill (Dollars)
now swap to GBP???*^*???
Market cap 125 mill (StockyP hope its the right page this time)
that looks like some kind of decent yield with similar profit previous year (18 mill) to the previous year.
So without knowing didly squat (are the yielding assets going, going , gone?) it looks like there is some sort of income that will presumably reduce as stuff is liquidated. However at that time one would probably expect some sort of payout or similar so the excess cash ain't just sat there doing nowt.
I agree, because of the volatility of these deficits (or surpluses) it is difficult to know how to treat them.
But, if you don't take it into account the EV then aren't in practise taking it off the balance sheet? (As used to be the case). And if you do that, then pension deficit payments cease to become "internal transfers" but becomes a real cost.
The £1,8m pa they are paying deficit payments amounts to 5.7p per share which wipes out the earnings you are predicting.
Which suggests the company is only making sufficient profits to service its pensioners with nothing left to add value for the shareholders.
That's an overly harsh description perhaps, but unless you make the assumption that the IAS19 figure is correct and there is no "real" deficit (which actually I don't consider a too unreasonable assumption) or you need to account for it either by looking at EV or by expensing the top ups through the P&L imho.
I think people are missing the point really on MPAC (LON:MPAC)
The profits warning relates to 2 legacy (non repeated) contracts that will impact profitability by £1m but the business is still profitable and should be around 5p EPS for this year and 10-12p next.
Although order book has shrunk next year revenues are well covered and its markets are growing at 5% p/a, not shrinking. That does admittedly raise questions as to why the order book shrunk at all which, is the core negative for me.
Cash is 165p and if you only value the business at 8* this years reduced forecasts you still get something worth 205p.
I also don't think you can treat pension schemes effectively as debt and just add to EV. It's too volatile, depending on many actuarial calculations, performance and long term interest rates. Rather, in my view attention should be paid to (1) agreed contributions / relationship with trustee (2) affordability of those contributions even in a tough market and (3) actual likely deficit/surplus rather than an out of date triennial review. On all these accounts I think MPAC (LON:MPAC) are appropriately placed.
Structurally the market they are in is also positive - so whilst I have downgraded my personal target from 275p to 225p to reflect the short term order book I was very happy to add at 122p this morning.
Further to Gromley's comment, I would also point out that cash is not 165p per share as you state, Equity Development helpfully show this figure for past years and expected figures for future years. For end 2017 it was 146p, for 2018 they expect 118p and 105p for 2019. Part of the reason for the reducing cash is the pension fund payments - I haven't delved into it deeply enough to work out the reason for the rest.
K3 Business Technology (LON:KBT) just posted the presentation from ShareSoc July 18, last week, following their H1 results.
https://www.piworld.co.uk/2018/07/18/k3-business-technology-kbt-presentation-at-sharesoc-july-2018/
The new management who joined in October 16 are making their presence felt, with margins up and opex down. Could be interesting if they can maintain the momentum.
MPAC: I think the two recent departures of very senior people was significant and could have been mentioned. Simon in IC recommended the share the previous day and still believes it is a good buy at today's reduced price.
Not for me: falling knife?
Interesting comments on the MPAC (LON:MPAC) pension scheme Graham.
There is an interesting compare and contrast with yesterday's announcement from 600 (LON:SIXH)
At the last report (November 17) their comparable pension figures were
Accounts.
Assets : £232.4m
Liabilities : £188.7m
Surplus : £44.7m
Actuarial view - Surplus £12.2m
Yesterdays announcement was that they have agreed (as have the trustees) to sell the pension schemes to Pension Insurance Corporation Plc and expect to get a net £3-4m (I presume this to be the figure net of 35% tax).
Personally I'm not so sure that is such a great deal, but 600 (LON:SIXH) look to be very short on cash and were certainly burning it in the previous financial year, I also think the company on a stand-alone basis looks too highly valued.
This does though demonstrate what can be done.
I would expect the actuarial valuation of the MPAC (LON:MPAC) fund to have improved since the 2015 number, but not I would expect by nearly enough to bring it in to surplus.
The next actuarial valuation will be as at June-2018, but as it took them two years to complete the last one, we may not see this until 2020.
So no cause whatsoever for immediate excitement, but it is worth remembering that separating the company from the pension scheme could happen at a later date if and as the overall health of the scheme improves.
If you have time, I think Carr's (LON:CARR) is a company that is worth covering. Nice business with a long track record.
Good morning!
I posted my thoughts on Cloudcall (LON:CALL) (in which I hold a long position) on yesterday's report's comments section. However, as most people probably wouldn't notice it there, here is a copy;
Hi,
Somewhat belatedly, here are my comments, in response to reader requests above, on the Cloudcall(LON:CALL) trading update yesterday. I hold a long position in CALL shares.
Firstly, it was clearly a profit warning, but a fairly mild one. The 2 brokers which report on CALL (both make their research available to subscribers of Research Tree) both put out updates, reducing 2018 revenue forecasts from c.£9.5m to c.£9.0m.
One broker reduces its 2018 EBITDA loss from £2.4m to £3.1m, and the other reduces from a £1.9m EBITDA loss, to a £2.9m loss, so quite a significant drop in forecasts at the EBITDA level.
What's gone wrong? The company says it's all down to timing of recruiting & training new sales people, which has taken longer than expected. It says there's not a problem with customer demand, they just didn't have the internal resource to bolt on new customers at the pace required.
The brokers clearly believe that explanation, as they have not reduced revenues forecasts for 2019. The company also talks about expecting a strong H2 in 2018, as the new recruits kick in.
If it all pans out as the company suggests, then the current share price weakness should prove negative. The trouble is that the company has proven somewhat accident-prone in the past (repeatedly missing targets, especially on cash burn), so investors are wise to take the company's outlook comments with a degree of scepticism. That doesn't make it a bad company, but I'm just pointing out that it tends to be overly optimistic, and then disappoints a bit. But that's within an overall picture of strongly growing revenues (which have risen organically from £3.3m just 3 years ago, to forecast c.£9m this year - that's very impressive growth).
Organic growth - is still very impressive, as noted above. The market tends to put a significant premium on the price of any company delivering over, say 20% organic growth at the top line. CALL is still well above that, at +31% Y-on-Y revenues growth in H1 of 2018. That's still a very impressive growth rate, albeit below the previous forecast of c.39%. I don't think the company should be punished too hard for this.
I like to look at not just year-on-year growth, but also sequential half year growth. This has been;
H1 2017 £3.2m
H2 2017 £3.7m (up 15.6% on previous half year)
H1 2018 £4.1m (up 10.8% on previous half year)
So there's been a slowing there, but still good growth.
Note also that the company has sticky, recurring revenues - because its product is excellent (I use it myself). Cashflow is hence highly predictable, with customer receipts coming in regular as clockwork each month. Customer retention levels are high, because people find the product so useful. That's key for building a SaaS business. Gross margins are also very high - again a key point.
Will it need more cash? Almost certainly, yes in my view. Does that matter? Not at all, in my view. There is no reason for shareholders to worry about another fundraising, because the company is well beyond the blue sky stage, when fundraisings are uncertain & can be done at deep discounts if investors are nervous. CloudCall's business model is now proven, and if it needs say another £3m to push it over the line into profitability, then that would only be about 10% dilution, and I reckon Instis would be queuing up to participate.
Evidence for this is that the last placing raised £5.7m in late 2017, and was priced at 143.5p, only a 5.3% discount to the then share price of 151.5p.
The only circumstances in which CALL would struggle to raise more equity, would be if the whole market turns bearish, and/or if CALL's revenue growth grinds to a halt. If that happens, then we'd be looking at a much lower share price, for sure. But that hasn't happened, hence why I think worries about another placing are wide of the mark. It's not a worry to me at all, for the reasons given.
Note that the company has a track record of repeatedly stating that it will not need to raise more cash, and then going on to raise more cash! So the reassurances given in the latest update that it has adequate cash resources, and worthless in my view, given the history. But it doesn't actually matter either way.
Is this a buying opportunity? That's obviously up to each individual to decide for themselves. I see this as a "good" profit warning - i.e. temporary, fixable problems, with the business model & growth story intact, just slightly blunted in H1.
The share price recently peaked at 193p. So being able to buy at 135p today, seems an attractive proposition to me. I can understand emotions kicking in, and some investors' patience wearing thin, but taking a longer term view, this share could be worth substantially more, once you factor in a few more years' strong growth, and the eventual move into profit.
Tech shares like this are not really valued on profits at the moment. The market is instead placing more emphasis on growth, with strong organic growth (combined with lots of operational gearing here, from high gross margin) should attract a premium rating.
There are plenty of private equity buyers around, willing to pay eye-watering valuations for growth tech companies. I would welcome a takeover bid for CloudCall, providing the premium is sufficiently large. It doesn't sit well in the stock market, where people are too focused on short term performance. Whereas, the better option for a growth company is to set aside short term profitability, and instead "go for it" in terms of growth, which might mean incurring heavy losses in the short term.
For stock market investors, CloudCall has been frustrating, in that the runway to profitability seems to be extended each year, by a year! The company is increasing its costs to take advantage of growth potential (and extending the features of its product), but with the time-lag inherent with that type of spending, it results in administrative costs relentlessly increasing, and absorbing the benefits of increased sales/gross margin. Hence why I don't think CALL should be listed on the stock market - it would be better off as a private company, and able to press on with faster, but more cash-consuming growth in the short term.
Overall, I think that for investors who are prepared to be patient, then we should do well out of this one in the long-term. The current market cap is extremely low for a SaaS business that's not far off profitability. Just look at the valuation of LoopUp (LON:LOOP) to see what can be achieved in this sector.
Regards, Paul.
That's pretty much spot on Paul, ice write up. Mirrors my view as well.
Paul, Thanks for that. I met Cloudcall (LON:CALL) at the Shares investor show in January. CEO seemed very good and confident. I remember questioning about the competitive position and it was all about focusing on the recruitment sector. The edge was recording calls within their platform to allow easy play back. I couldn't get too excited due to the Market cap to sales valuation. Secondly, the difficulty in understanding the competitive environment and thirdly the unclear timeline to profitability. Fourthly, the lack of clarity over what kind of margins this company will have when it is profitable. I didn't do any follow-up research to assess these points.
A few follow-up points if you have time. Thanks,
1) As you use the product it would be great to have some feedback on why it is better than the competition and how it can sustain its edge. Surprised that you are using it as I thought it was only for small companies?
2) The valuation argument you put forward is all relative. We could argue that LoopUp (LON:LOOP) is overvalued. But a difficult comparison as LoopUp (LON:LOOP) is profitable. In other words, if we are comparing Cloudcall (LON:CALL) to an overvalued sector and a stock that is overvalued then it will seem cheap (not sure if either is the case). So I guess I would ask looking just at Cloudcall (LON:CALL) what do you think about its valuation relative to its potential and the risks? This is I guess what matters most for a growth company. What is its current valuation relative to its potential.
Hi Graham
I know you focus on actual news not price movements but given you own it I wondered if you had any thoughts on H&T recent price weakness
I have assumed that was the usual function of the weakness of the gold price but would also like to know if Graham thinks there could be other issues. https://www.gold.co.uk/gold-price/
Hi guys, I'm not aware of any other reason. G
SRT Marine Systems (LON:SRT) - call me cynical and probably ignorant, but I read their announcement as follows:
The customer didn't meet the financial or governance requirements for an EU development loan. They don't have they money to pay themselves, but hopefully the UK government's export guarantee programme will be more relaxed.
We recognise revenue upon the signing of contracts that amount to little more than letters of intent, rather than when payment is guaranteed or as services are delivered. Our forecast results are therefore subject to large adjustments at any time, including many months after the period close. While this is one of the reasons we are slow at producing our accounts, prior year adjustments cannot be ruled out.
We were relying on this single contract for most of our revenue and to make a profit last year, and if it doesn't come through this year then we can't really say whether we'll make money this year. We are a very small company with very big customers and therefore easily bullied on contract terms.
This is not a share I follow, but I can't understand why such a business would have been valued at 16x forward earnings before this news or why it has fallen by only 15% today. Very happy to be corrected as always.
Re SRT Marine Systems (LON:SRT), harsh, but not unreasonably so. It is not unheard of for small software companies whose business is with a few large customers, such as governments, to start work on projects on "little more than letters of intent". Usually it works out OK in the end. But how on earth is the outside investor in a plc to make any assessment of whether or not the directors' judgement is sensible? They can't. The market cap here is little more than a blind punt on the quality of the software offering.
I think this will probably come good in time. But in the meantime the equity investors are completely at risk. (I have held earlier, but sold out about a year ago, partly because of a feeling that contracts like this tend to end up being spread out over more years than originally intended.)
Hi everyone - MPAC (LON:MPAC) and Headlam (LON:HEAD) are the most requested and I agree they are the most interesting ones today. So I'll be writing about them first, and then seeing what I have time for after that. Thanks. G
Hi anybody out there know anything about Russian stocks, in particular ETALON, appeared recently in the Stockpedia screen of screens, with what looks like a good PE PEG ROCE, rating 88. Passed 3 screens. A good 1qtr update yesterday to my untrained eye. Graham any chance a quick look. A brill world cup and tourism maybe on the rise. Trump Putin who knows.
Looking for any issues some may have perceived in the past, RUSSIA, CURRENCY ETC. No chat anywhere on the subject. A long way from a high, no idea if tilting at windmills or as good as it reads. Any thoughts, Whichever all the best
Hi Graham
Another request for Headlam (LON:HEAD) and Bloomsbury Publishing (LON:BMY)
Thanks
Hi Graham
I believe Paul may hold both Headlam (LON:HEAD) and MPAC (LON:MPAC) , so is it worth getting him to comment here. (The old adage says profit warnings come in threes, so there may still be one to come in Headlam (LON:HEAD).
Hi Graham
Apologies for hogging your time of late, but several companies in my portfolio have released RNS updates recently, so please feel free to concentrate on requests from other members if you feel they will be of greater interest to the Stockopedia community.
I hold Headlam (LON:HEAD) which released a trading update this morning. Whilst trading continues to be challenging, it appears that there has been an improvement since the AGM statement on 24 May which reported a total revenue decline of 5.4% (UK -6.3% and Europe +0.2%) versus 4.5% now (UK -5,5% and Europe +1.8). Subject to no further deterioration in trading Headlam (LON:HEAD) is confident of meeting expectations for the year.
I also hold Bloomsbury Publishing (LON:BMY) and Strix (LON:KETL) both of which issued trading updates this morning but would be more than happy if you are able to cover Headlam (LON:HEAD).
Have a great day.
Jonno
Morning Graham
Following on from the first comment, I would also like to hear your views on Headlam (LON:HEAD) if you have time. I hold.
Jon
Another request for MPAC (LON:MPAC) Down 40% at time of writing which is less than net cash, I think.
Positive spin from a note issued here
Normally I would adhere to the policy of selling when a profit warning is issued as per Stockopedia research on the subject. But when trading at an albeit reduced profit, with a new strategy and below net cash the share price reduction seems a tad overdone IMO
Xeros Technology (LON:XSG) - maker of low-water washing machine systems - up 20% on Chinese manufacturer licensing news. Used to hold, like the tech, shoulda woulda coulda bought back in first thing as it's now up 20%. Still loss-making though. WOuld be interested to hear Graham's conservative views on the company!
SRT... continues to be the ultimate test of patience for optimistic investors. Every time I think news of a blockbuster contract win must be due, yet another setback occurs, if only a temporary one. Why oh why do I keep holding on in expectation that anything will ever change here? (Perhaps not a rhetorical question, that)
Yours, exasperated once again
B2V
My morning smallcap tweet: SRT shocking revenue twist.
SRT Marine Systems (LON:SRT), Real Good Food (LON:RGD), Bagir (LON:BAGR), Omega Diagnostics (LON:ODX), Carr's (LON:CARR), MPAC (LON:MPAC)
SRT Marine Systems (SRT) stiffed by another Gov't. A SE Asian government customer cancels €28.5m fisheries monitoring project announced in March 2018. It has decided not to use an overseas development assistance loan from a European government funding, but its own. Rev for FY18 (ended March!) reduced by £8.2m to £5.3m resulting in a loss before tax and exceptional items for the year of £4.3m. C/F not affected. Customer says it will place new contract. I hold.
Real Good Food (RGD) £1m open offer at 5p (a 55% discount!) to keep the lights on.
Bagir Group (BAGR) 'Strategic Partnership' going ahead. Shandong Ruyi will pay $16.5m for 54% of the Company's enlarged share capital.
Omega Diagnostics (ODX) appoints distributors in Ghana, Zambia and Zimbabwe for its CD4 HIV test. Approvals needed.
Carr's Group (CARR) FY trading slightly ahead of the Board's previous expectations (detailed in the Group's interims).
Mpac Group (MPAC) warns FY profits expected to be around £1.2m below current market expectations. Blames soft market (Brexit natch') and delays in 2 legacy projects.
Good Morning Graham!
I wonder if you could cover the MPAC (LON:MPAC) profit warning today, please? I don't hold, but I've followed them, and would be really interested in your take.
Thanks,
IG
Hi IG - sure! MPAC (LON:MPAC) news is fairly interesting. G
Morning All,
TA from Headlam (LON:HEAD) this morning (I hold). Total Revs up 0.6%, LfL's down 4.5%.
States: "Subject to no further downturn in market conditions and the Company experiencing the usual weighting of trading to the traditionally stronger second half of the year, the Board is currently confident of delivering expectations for 2018".
Seems reasonable value, with good quality metrics although slightly low op margin. I think I'm going to stick with it as the divi is good and covered (1.64).