Small Cap Value Report (Wed 19 Apr 2017) - Election/forex, LRM, ALT

Good morning!
As we all know, political events can have a big influence on markets. So it was interesting to watch what happened yesterday, after Mrs May announced that she's holding a snap general election on 8 June.
This triggered a big move upwards in sterling, which currently stands at just over $1.28. I'm flagging this point because a surprisingly large number of shares have been boosted by weak sterling. Dollar earnings make up the bulk of the FTSE 100, for example - hence its plunge yesterday. However, plenty of smaller caps also have seen their sterling earnings boosted considerably by forex.
Therefore, I am currently reviewing my portfolio, and considering whether to bank profits on shares which have received a large boost from forex in the last year.
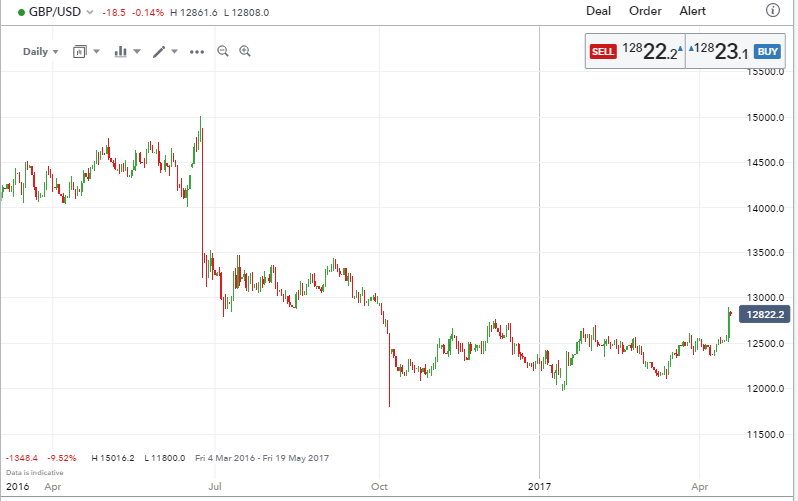
Looking at the sterling:dollar chart below (courtesy of IG), you can note the big moves as follows:
June 2016 - a sudden devaluation of sterling from the Brexit vote
Oct 2016 - another sharp plunge in sterling, although I can't remember any specific reason for that at the time
Oct 2016 - Apr 2017 - sideways range, around £1 = $1.25
Now - who knows, but sterling is looking stronger, in the short term anyway
Importers have been struggling with weak sterling, as it's increased the cost of imported goods. Hedging arrangements only defer the pain. So weak sterling has been one of the woes hurting shares in UK retailers.
IF that pressure is now alleviating, then this could perhaps be a good time to reconsider whether it's time to snap up some bargains in the retailing sector? As mentioned previously, the only conventional retailer that interests me at the moment is Next (LON:NXT) - whose shares seem bizarrely cheap to me at around £42.
I think there could be a better outlook for Next than its extremely gloomy outlook of a few weeks ago suggested.
Going back to the election, markets seem to be anticipating Mrs May winning a bigger majority than her current, wafer thin majority of 17 (per the TV news last night). A bigger majority should make Brexit negotiations (and implementation) easier, so I think the market is probably right to cheer this move.
Anyway, it's a good time to monitor sterling, and to consider how your shares may be affected. Looking at the chart above, by Oct 2017, the year-on-year movements in sterling could actually start to be a headwind for many of the companies which have enjoyed a big tailwind in recent times.
The danger is that some investors may have got carried away with forex-related earnings growth, and over-priced shares with very strong earnings growth. We could therefore see some share price corrections later this year, when people realise that the forex gains were a one-off, and could now even begin reversing.
Lombard Risk Management (LON:LRM)
Share price: 11.7p (up 9.7% today)
No. shares: 400.6m
Market cap: £46.9m
Trading update - for the year ended 31 Mar 2017.
I last reported on this banking software company here in Oct 2016, noting that things seemed to be improving.
The information today is presented as if it's positive, but I'm not so sure.
The Company is pleased to announce that it expects to report revenues for the year, ahead of current market forecasts, in the region of £34.0m to £34.4m, primarily driven by strong revenue growth in the Company's Risk Management and Trading Software division.
Stockopedia shows market consensus as revenues of £31.9m, so this looks a reasonable beat at the top line level.
The Company expects to report a year-end net cash balance of £7.0m and
adjusted EBITDA in the region of £2.4m to £2.8m, significantly better than market expectations.
The net cash figure looks OK, and dispels any short term worries about needing another fundraising.
However, EBITDA is completely meaningless at this company, because it is so aggressive in capitalising development spending. EBITDA can be a useful measure in some sectors, where it can be a proxy for cashflow, but that is certainly not the case here.
The year-end cash balance was higher than expected due to a strong focus on debt collection and improved working capital management.
Capitalised Research and Development is expected to be in the region of £7.5m.
As you can see there's a mammoth amount of development spend capitalised, of £7.5m, so the underlying cashflow is clearly still very negative. It looks like the cash figure may have been flattered by short term movements. So I'm getting worried about whether that £7.0m cash figure can actually be relied upon?
The company did say at the interims that H2 would be a period of heavy investment in new product development.
My opinion - I did have a dabble in this share around 8p. However, a Simon Thompson article triggered a sudden spike up to 12p in mid March, so I was very happy to bank a lucky 50% gain. Why look a gift horse in the mouth?
I remain fairly sceptical about this company. Whilst there are some signs of improvement, in terms of revenues, and contract wins, it's still a long way from being a viable business in terms of profitability.
Indeed, on a recent video, the CEO made a comment which seemed to suggest he also had some doubts over whether there was a viable business here. That was one of the reaosns I was happy to sell up.
Overall, there are some promising signs, but this company still has a lot to prove. It's track record has been very poor, and it's been hungry for cash in the past, with numerous fundraisings. That said, there does seem to be a good market opportunity, with its software apparently in demand, due to regulatory pressures.
A lot of its customer contracts are surprisingly small - that was another key point which came out of the CEO interview. I think the jury is still out, on whether this will become a viable business or not. That's not good enough, to tempt me back in.
Altitude (LON:ALT)
Share price: 76p (up 27% today)
No. shares: 46.4m
Market cap: £35.3m
(at the time of writing, I hold a long position in this share)
New supply agreements - this share is a bit too speculative for me, but a friend persuaded me to buy some recently. Graham wrote a section on it here on 14 Feb 2017.
The company has a small existing business, but the excitement (and valuation) mainly rests on hopes for its new activities in America. The story is that the boss at Altitude has experience in the promotional goods sector, having been in a senior role previously at 4imprint (LON:FOUR) .
Altitude's big idea is that it provides a software platform for a large number of promotional goods suppliers. This enables them to make personalised websites for their customers, instead of printed booklets. So customers can see products, with their own branding already applied, via 3D visualisation software online. They then place orders, and Altitude receives a cut of the gross profit from the manufacturer.
It seems too early to be sure whether this is going to work or not. So in that sense, this share still looks jam tomorrow to me. Hence why I'm only a nervous holder at the moment, until some tangible proof emerges that the business model is actually working.
This bit, in today's announcement sounds good;
The first of the new agreements is with Market Brands LLC ("Market Brands"), based in Buffalo, New York State, USA. Under the agreement, Market Brands has undertaken to recruit 100 new sales staff who will target the creation of tens of thousands of branded web stores for small businesses throughout the USA. The stores will be powered by Altitude technology and fulfilled through Aprinta. Altitude will be remunerated through a percentage of the sales value of every order in line with the Group strategy.
My opinion - it's very unusual for me to even consider jam tomorrow shares, as they nearly always go wrong. So I've no idea whether this one will be any different, or not. My friend reckons he's checked it out thoroughly, and he's got a good track record, so I'm hoping for the best, whilst expecting the worst.
If I do get sucked into a jam tomorrow share, I always try to size the position so that a disastrous outcome isn't too financially damaging. The other key thing is to unceremoniously dump the shares once it becomes clear that things are not working out as planned. The really big losses are incurred by people who fall in love with a story stock, and cling on to the bitter end.
Mind you, occasionally a jam tomorrow share does actually work, although I'm struggling to think of any examples.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Paul have you ever had a look at £SMS? Reported at the end of lats month and seem to have lots of potentila as well as good performance currently. Accept they are not highly rated on Stockopediaprinciples, especially on Value. Just a thought when things are relatively quiet. Would welcome your thoughts, or anyone else on here. Thanks
If you click on discuss it will show the posts, nothing since 2011. My first glance, debt is soaring but profits are not and yes VR is only 9. EPS forecasts not high and latest EPS is down. So not one for me at this time. Also must be vulnerable to changes in Govt. policy. I have a smart metre but it's waste of time because I changed supplier so it no longer works as a smart metre, that reminds me I have to do some metre readings.
Going back to the currency issue that I mentioned in today's report - it sounds like some readers have got the wrong end of the stick.
My point is that it makes sense to calculate how much of the earnings increases in our portfolio holdings have been driven by forex gains (often not terribly clear from company results), and then strip out that factor (which can be huge).
You might find that there's not very much underlying earnings increase at all, once one-off forex movements are eliminated.
Ignore this issue at your own risk! It's worth checking - which was the intended message in today's report, even if not everyone got the message.
P.
Hi,
Yuk - I am NOT liking the silly political comments today. We don't want that kind of nonsense cluttering up the comments section here please. Keep the politics for Twitter rants, like I do! ;-)
I had hoped to comment on more companies today, but unfortunately there were some technical glitches this morning. Also, I only had a couple of hours available to write, because this afternoon I was being a NED for one of the small businesses I assist - setting up a new accounting system on Xero.
I do find it's useful to sometimes just switch off from the markets, and do something more practical & hands-on.
We've decided to apply to go on Dragon's Den - so watch this space, I shall keep you posted!!!
Regards, Paul.
If there is a change in trend in currency this could prove an interesting situation for some stocks out there.
For example take Alumasc (LON:ALU). Not the cheapest out there . With previous report shows decent all round trading with some areas showing record revenue, their margins suffered a bit with the fall in Sterling , but have have already acted upon this by increasing prices.
Their H2 results should show their margins coming back in line again. If Sterling were to strengthen again this could improve earnings nicely.
Sean.
To drag us back on topic, RTC (LON:RTC) put out a positive sounding trading update with the AGM statement today, and the share price is up somewhat.
(Small long position)
Paul's point refers to changes in trend of GBP and not individual movements: some very significant movements can be a signal for trend change. Those are the ones to pay attention to and watch for evidence that either supports or refutes the hypothesis. The market is a discounting engine and some of the moves yesterday in correlated stocks support the currency trend- change hypothesis. Buying on that weakness is just another value trap if earnings are re-rated by appreciation of the repatriated currency
To my mind, when you are buying anything heavily denominated by a currency, it is madness not to pay attention to the likely trajectory of that currency unless you are good at hedging (and therefore not ignoring currency by definition)
Re Sterling, I can't in reality see it gaining any real momentum over the next few weeks, a snap election from my perspective changes nothing in respect to Brexit, the decision is already in play and I very much doubt a change in either party or approach. Any stocks that have had a blip because of this are either buying or shorting opportunities in my opinion depending upon whether they are exposed by, or supported by, a weak pound.
Personally I saw yesterday as a bit of a buying spree for some stocks that I felt were overly punished, and today I'm up on most of them and I hope to be up on them all over the next few weeks. We'll see what happens, obviously I could be completely wrong, who knows, my stops are guaranteed and tight just in case ;-)
The counter view on the GE is that the structural problems in the economy are still there - a high fiscal deficit and balance of payments deficit; anaemic growth despite rock-bottom interest rates. The call for the early election could be seen as designed to avoid an election once the actual implications of Brexit become known - these might well disillusion a lot of people, making a 2020 election more risky. So: an election called now for party political reasons to exploit a fragmented opposition. A renewed mandate with a larger majority? Most probably. But a stronger economy and a stronger pound? I see the current recovery of the pound as temporary, rather than structural - and am watching with interest those forex earners. Buying opportunities beckon.
I think the election announcement and accompanying strength in sterling is a good example of why you should ignore movements in currencies when investing in shares. It's good to be aware of what is happening in the currency markets but I'm afraid I lack the ability to predict events such the election announcement, so I can't predict currency movements in the future which is why I don't attach much importance to them when making buy or sell decisions.
Peterthegreat agree entirely.
Tax Systems results were out today ,were you not going to comment on them from memory.
I thought you had said you would wait until results and then comment but I may be mistaken ?
Seems to have a lot of debt and has turnover not decreased ?
Be interested in your thoughts I find these things hard to fathom.
Shouldnt there be clearer rules for reporting results, alomng this line,
We made this
We lost this
It cost us this to make what we did.
Next year we expect to make this.
easyJet (LON:EZJ) is a good play on stronger currency. The underlying business is performing well: it is increasing capacity and still has high load factor (how many seats are taken). This was 92% in Feb compared to 90.4% a year ago despite over 8% higher total capacity. However, the share price has fallen 25% over the last year primarily due to higher fuel costs (which are in dollars) as a result of weakening currency. It's up 4.5% today. I obviously hold.
Hi. Did exactly what you did with Lombard Risk for the same reasons. Always find the timing of sells much trickier than buys! Pondered using a stop loss, but encouraged by your decision and logic. Hope we have not left too much for the next man / woman !
Hi Paul, any thoughts on LON.BON have been watching for a while as its dirt cheap. But guess that's due to poor sales growth and a fashion brand that's out of fashion... Be good to hear your thoughts. Cheers Mark
Another political ‘certainty’ to build our portfolios around. I have reshaped mine accordingly but have paced my breath in anticipation of another public vote hopefully my heart follows suit.
I'd have to check but did someone put through a daft trade overnight on the GBP currency back in October 2016? I recall something like that happening in recent history but I don't know if that's the explanation for that massive drop around that time.
I sold Somero Enterprises Inc (LON:SOM) and Avation (LON:AVAP) yesterday purely on the currency movements and bought some Next (LON:NXT) despite my previous misgivings.
It's a time to bend with the wind.
It was quite handy to have some dollar earners priced in pounds where the currency impact was not immediate. My direct holdings in US shares obviously don't have that cushion.
I sold Somero Enterprises Inc (LON:SOM) and Avation (LON:AVAP) yesterday purely on the currency movements and bought some Next (LON:NXT) despite my previous misgivings.
It's a time to bend with the wind.
IMHO This is a big call. I know I am not clever enough to know what will happen with exchange rates for the rest of this week, let alone the rest of the year so there is no way I am going to sell fundamentally sound companies. I take my hat off to those that can do this on a regular basis but it seems like a zero sum game to me.
We still have Brexit negotiations ahead and I can see a two-fingered salute to the Tories on it's way in the election. I'm no LIb Dem supporter and never vote in General Elections but I will be voting for them as a protest to scumbags like Michael Gove who had the bare-faced cheek when interviewed on TV last night to state that the Lib Dems would say anything to win votes. It's just like the Referendum never happened Michael, isn't it? If only everyone's memory was as short as yours!
All the best, Si
If you think the Tory's won't win a landslide, you are either delusional or don't understand sentiment, polling & FPTP. We are already seeing polls swinging to back Brexit, and it certainly appears to me the hardline stance of some remainers is softening towards acceptance, excitement in some cases!
But it's her own colleagues that she's really standing against. She wants to get enough moderate Tories in with a large enough majority to be able to do a deal without being held captive by her Eurosceptic wing. So she will be free to "betray" them.
Yes, I'd go along with some of that. I'm not entirely sure she is 'betraying', although it is pretty opaque tbh. She believes a new, clear and well defined mandate will give the EU what for in negotiations. She doesn't want anyone (Lords, Pro-EU MPs Tory or otherwise) frustrating the process and stalling negotiations.
I think she is doing the right thing both in terms of 'Brexit' and for her party. Whether this will leak into other areas of Government is up for debate. I saw a potential Royal Commission on the NHS mentioned this morning, and we all know she is a fan of Grammar Schools.
If you think the Tory's won't win a landslide, you are either delusional or don't understand sentiment, polling & FPTP. We are already seeing polls swinging to back Brexit, and it certainly appears to me the hardline stance of some remainers is softening towards acceptance, excitement in some cases!
For the avoidance of doubt, I expect the Tories to win and get the majority they are looking for. My stance has nothing to do with how I voted in the referendum, but is all to do with who lied the most and the loudest during the Referendum campaign and Tories on both sides of the debate did so like troopers. And then our local Tory MP who represents a constituency that voted Remain decided to vote for Brexit in passing it through the commons. She can go swing as far as I'm concerned, more interested in her career than representing what her constituents voted for. My one hope is that Gove & Co. lose their seats and that Boris isn't even an MP come 9th June, let alone Foreign Secretary.
All the best, Si
" My stance has nothing to do with how I voted in the referendum, but is all to do with who lied the most and the loudest during the Referendum campaign "
Guess you forget Clegg's "There is no EU Army,no plans for an EU Army,nor will there ever be!"
Plenty more lies Remain side than Leave I recall - much of which came from likes of Clegg, Farron,and the dimwits on Labour's front bench...
Funny that.
A vote for libdems is a wasted vote - you'd be better off voting Labour. At least that would count.
"And then our local Tory MP who represents a constituency that voted Remain decided to vote for Brexit in passing it through the commons. She can go swing as far as I'm concerned, more interested in her career than representing what her constituents voted for"
Equally vocal with regard to ALL those MPs voting "Remain" despite their constituencies voting Leave? No thought not.
"My one hope is that Gove & Co. lose their seats and that Boris isn't even an MP come 9th June, let alone Foreign Secretary"
Gove was superb.Don't see what your beef is with him. Boris, well, a decent Mayor of London, humourous, does put his foot in it but so what.Incredibly smart & charismatic - beats pants off most in HoP.
Hi Simoan,
You may be taking your hat off, but I might have to eat mine.
However, my thoughts are that the drop in the pound in October was the market pricing in a hard Brexit so if we are now going to be a little less pig-headed the pound could recover to around the pre - October level. I think that would still leave us below purchase price parity.
I'm certainly not sure enough of this to start trading the currency, but I am going to review my US holdings and start to take some profits.
I voted you up for the Gove comments!
What an excellent post simoan. I could not agree more. Avation (LON:AVAP) is an undervalued company and Somero Enterprises Inc (LON:SOM) is a quality company. Somero Enterprises Inc (LON:SOM) is based in the states and reports in $ and does not then convert them in to pounds and Avation (LON:AVAP) is based in Singapore (as is XP Power (LON:XPP) another core holding my initial purchase was Feb 2012 and is up 130%) and reports in $ also.
Avation (LON:AVAP) I can imagine selling at some point but Somero Enterprises Inc (LON:SOM), unless management really screw up I can imagine still being in my portfolio in 10 years time. I first bought January 2016 and five times since. Initial purchase is up from 136p to 310p. It is now my 5th biggest holding.
I may well use any continued weakness to top up but that's a market.
As for the GE I will hold my tongue. I don't want to come between InvestedGeordie and Simoan!:-) All I hope is that the SCVR comments do not get like it did pre and post referendum in the run up to the GE.
As for the GE I will hold my tongue. I don't want to come between InvestedGeordie and Simoan!:-) All I hope is that the SCVR comments do not get like it did pre and post referendum in the run up to the GE.
Yes, I'm sorry for commenting on the General Election. I normally only comment on topics Paul mentions in his reports so felt it was OK today but agree it would be very tedious if it was debated every day between now and June. I will desist in future.
Apologies to all, Si
Agreed, I will pack this in, as counterproductive in truth.
Michael Gove and his friend Boris, made a number of outrageous promises in the referendum campaign that the must have known could never be honoured. Unfortunately this deception carried the day. Many of the older people who voted out won't have to be worried about the longer term impact but it the younger generations who will be permanently poorer.
I reckon the shift in GBP is a significant trend change so your thoughts on headwinds to the correlated equities should bear out. conversely, as well as general retail, airlines and travel/leisure should catch a bid (check easyJet (LON:EZJ) and International Consolidated Airlines SA (LON:IAG) today as well as Thomas Cook (LON:TCG) ). Pharma and O&G NMX sectors have lost their 200MAs and Miners are looking ropy: some short term trading shorts
Perversely, the bigger majority for May will potentially mean a softer BREXIT given she is from the moderate side: more Tories = decreased loony right wing backbencher influence = more moderate BREXIT = better negotiation and outcome on economy therefore higher GBP...at least that's the narrative I like atm
Good trading weather ahead
Hi Paul
I noticed that you sold out of Somero from your fantasy portfolio after the election announcement yesterday. Was that due to your thoughts on currency earnings or was something else behind your decision? I know that you've only been selling to buy in better ideas recently, so was interested in your rationale.
Thanks
Jonathan
Hi kidznet,
You asked;
I noticed that you sold out of Somero from your fantasy portfolio after the election announcement yesterday. Was that due to your thoughts on currency earnings or was something else behind your decision? I know that you've only been selling to buy in better ideas recently, so was interested in your rationale.
As always, it's complicated! I've banked some profits on my personal & family portfolios with Somero Enterprises Inc (LON:SOM) as it's had a great run. A lovely business, but it tends to be valued on a fwd PER of 10-12, and has now reached about 15. Perhaps that's high enough for now, I don't know? Also perhaps the main benefit from the strong dollar has now been had?
Although, on the other hand, I haven't sold any SOM in my SIPP, which tends to be a handful of long term holdings. So I'll probably continue to hold there.
BMUS tends to be a bit of a hybrid, between my mid and longer term ideas. There's not really any particular structure, or set of rules behind it.
Bottom line is this - my selling decisions are very often absolutely terrible!
A good example - I sold BOO way, way too early.
So you'd have to be a complete idiot to follow my selling decisions, as they're usually bloody awful! I'm a lot better on buying decisions, but even then, plenty are wrong. Most are right, or rightish though. My selling decisions are hopeless though, so please ignore them!
Everyone has to make their own buy/sell decisions anyway. I'm not a guru, and don't want to be anyway. It's just a view, at a snapshot in time here. People can often then take my best ideas, and do much better with them than I do, which is great.
Regards, Paul.
As always, it's complicated! I've banked some profits on my personal & family portfolios with Somero Enterprises Inc (LON:SOM) as it's had a great run. A lovely business, but it tends to be valued on a fwd PER of 10-12, and has now reached about 15. Perhaps that's high enough for now, I don't know? Also perhaps the main benefit from the strong dollar has now been had?
Paul,
I have had similar thoughts myself but they quickly subsided! Somero Enterprises Inc (LON:SOM) is my largest holding mainly because I've just let it go without top-slicing. I don't believe a PER of 10-12 is correct for this company. Yes, I realise it's in a cyclical industry but then again most cyclical companies do not enjoy anything like the kind of margins that Somero Enterprises Inc (LON:SOM) is able to sustain. It is to all intents and purposes a US company, only the share price is in GBP. If it were listed in the US rather than the UK it would be on a PER of 20, no problem.
With regard to currency movements I have no idea what will happen and I am happy to admit that. As a private investor, I find there is a great power in acknowledging my "known unknowns" and not wasting time on them. Once you acknowledge this you can spend your time on more important things, like more time researching to find the "unknown knowns".
BTW I don't feel it's right that you should be made to feel accountable for what you buy and sell and wish people would stop asking as it clearly places pressure on you which I personally do not find acceptable.
All the best, Si