Small Cap Value Report (Wed 2 May 2018) - PDG, AXS, EMR, PLA, OTMP, AIEA

Good morning, it's Paul here.
Firstly, my apologies for yesterday's (lack of) report. I've set aside all day today, with no meetings, to cover both yesterday & today's RNSs of interest. I'll do today's report first, then circle back to yesterday's report this afternoon.
The header shows the 5 company announcements that I'll be tackling first today.
Empresaria (LON:EMR)
Share price: 82p (unchanged, before market open)
No. shares: 49.0m
Market cap: £40.2m
Empresaria, the international specialist staffing group, will hold its Annual General Meeting today at 1.00pm ...
The most important bit is a brief trading update;
"The Group remains on course to meet market expectations for the full year. A trading update will be published on 25 July 2018 and interim results for the six months ending 30 June 2018 will be published on 22 August 2018."
The first thing I check is the graph on each company's StockReport, which shows the movements in consensus broker forecast EPS. In this case, as you can see below, broker expectations for earnings have fallen a fair bit recently;
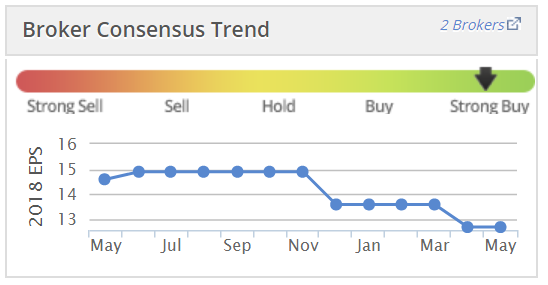
This might possibly be related to forex movements. Empresaria has considerable overseas earnings. The relative strength of sterling against the dollar in the last year, means that the forex translation of some overseas earnings into sterling is now adverse on a year-on-year comparison. Whereas earnings at this group had previously benefited from weak sterling in 2016, and the first half of 2017.
Having said that, checking the figures, sterling has been relatively flat against the Euro in the last year. So currency movements are more an issue for sterling-dollar.
Change of CEO - Joost Kreulen is standing down as CEO today (not seeking re-election at the AGM), but will continue as a part-time consultant. This suggests no animosity, which is reassuring for investors (if it's true).
Spencer Wreford (currently COO, and formerly CFO) is taking over as CEO.
My opinion - I met these two Directors a year or two ago, and it struck me then that Wreford seemed to be a CEO-in-waiting. Kreulen didn't look in the best of health, so having a reduced role in the business, with less travel seems a sensible move.
As you can see from the StockReport section below, Empresaria looks good value on a PER basis;
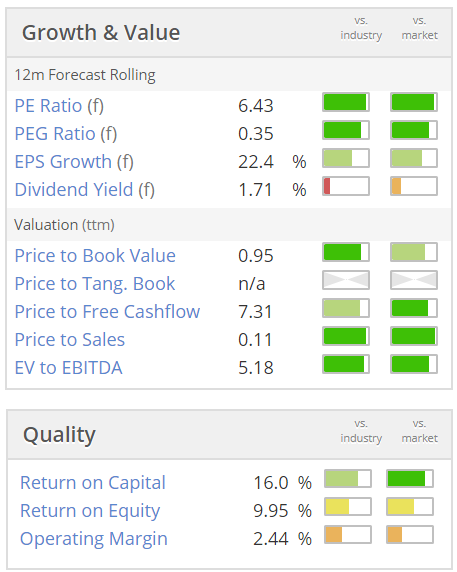
The issue for me, is the balance sheet, and debt position. It's very difficult to decide how to treat invoice discount financing. You could argue that it doesn't matter, as it's related to receivables. The interest cost is absorbed within earnings, so maybe we can just ignore it?
The problem with that approach, is that you would make no distinction in valuation between companies with lots of invoice discounting debt, and those with none. Clearly that doesn't make sense.
Mr Wreford did email me quite recently, asking if I wanted to discuss how the debt is accounted for, but (as usual) I was overwhelmed with work, and didn't get round to responding. At some point though, I would like to get my head around the balance sheet of this company a bit better.
Balance sheet - overall this fails my basic tests.
NTAV is negative, at -£5.2m - whilst not disastrous by any means, I do like to see positive NTAV before investing in anything.
Current ratio - not great, at 0.97, which is below my usual cut-off of 1.3. Although it should be noted that nearly all the bank borrowings are shown within current liabilities (as opposed to being in long-term liabilities), so that suppresses the current ratio.
Conclusion - this is a tricky one. This seems a well-managed group, which has performed well in recent years. However, it has a balance sheet which is a little too weak for comfort, in my view. This means that the apparently low PER is not really such good value, once you adjust the figures for fixing the balance sheet with a hypothetical equity raise.
The alternative, is something like Gattaca (LON:GATC) which is now on a similar market cap to Empresaria (LON:EMR) . Gattaca has a much better balance sheet (on the two measures above), but seems to be a serial disappointer, and badly run.
The question then is, do I want a fairly decent business with a rather weak balance sheet (EMR), or a poor business with a stronger balance sheet (GATC)? I'm not really feeling that either is particularly compelling right now.
Pendragon (LON:PDG)
Share price: 28.9p (down 3% today, at 08:52)
No. shares: 1,417.5m
Market cap: £409.7m
(at the time of writing, I hold a long position in this share)
This Interim Management Statement for Pendragon PLC, the leading online automotive retailer in the UK, covers the period from 1 January 2018 to 1 May 2018. Unless otherwise stated, figures quoted in this statement are for the three months ended 31 March 2018.
I'm struggling to understand some of this announcement, with some oddly worded sections, e.g.;
During the month of March, where we were unable to retain sufficient used stock to meet demand and sales suffered as a result. We are increasing used inventory levels in quarter two with a view to capturing an increased volume of activity at an improved margin, as this stock will increase our proportion of newly acquired used stock.
When I can't understand or struggle to interpret specific details, I tend to look for the overall conclusions. In this case, it sounds like the business is performing in line with expectations;
"Our profitability in the first quarter of the year is in line with our expectations against a backdrop of an exceptionally strong comparative in the prior year...
The strong performance last year was caused by changes in vehicle tax;
In the first quarter of 2017, the industry experienced the effect of the vehicle licence tax changes which brought forward vehicle revenue into quarter one of 2017.
The financial difference in Q1 2018 versus Q1 2017 is quite marked;
Underlying profit before tax fell to £15.0m from £32.4m in the prior year.
Clearly the group has a lot of catching up to do for the rest of 2018. Although Q2 2018 should see the benefit of the prior year vehicle tax changes reversing.
Outlook - this is quite interesting, and has read-across for other car dealers;
The Group has a clear focus and direction to transform the business and double used vehicle revenue by 2021, enabled by our market leading software and investment in used car and aftersales stores in the UK.
The expected market conditions in quarter one impacted profitability. We anticipate our performance in 2018 to be in line with expectations given our assessment of a stronger second half versus a weak 2017 comparative.
I don't normally like H2-weighted trading updates. However, in this sector demand is relatively easy to predict. It's not as if they are dependent on a couple of big contract wins (as is often the case with software companies, or project-based businesses). This is a retail operation - of cars, and of course the lucrative after-sales work too.
Therefore, I think we can probably rely to some extent on the more optimistic H2 outlook. This also ties in with my macro view, of rising real incomes (wage rises recently crossed over, to overtake the inflation rate - which is now falling). Hence I've been positioning myself into good quality consumer-facing stocks this year, anticipating something of a recovery in consumer spending later this year.
Overall then, I think this might be a good time to reassess car dealer shares, with possibly some recovery potential later this year. Share prices seem to be recovering a bit at Pendragon (LON:PDG) and Vertu Motors (LON:VTU) . I like Vertu (but don't currently hold any) due to its very good asset backing. Cambria Automobiles (LON:CAMB) also has a decently strong balance sheet, full of freehold property, as with Vertu. So these shares in particular are really a hybrid of a car dealer, and a property company.
Another interesting angle, is that the Government has caused considerable confusion over the status of diesel cars. So some of the recent softness in demand for diesel cars might well be buyers deferring purchases until there is more clarity. That has the potential to trigger a bounce-back in demand at some point.
Overall then, quite an interesting sector, offering good value, and tangible asset backing in many cases. I only have a smallish long position in Pendragon, and have no plans to buy any more for the time being. I like its 5% dividend yield. Also, it has an interesting & decently profitable software business, which might at some point be spun off on a higher rating than the rest of the business - so potential upside there.
The downside with this sector is that it could just be dead money - with shares oscillating in a sideways direction, which has an opportunity cost. Investor sentiment seems firmly negative on the sector generally, hence low PERs, despite asset backing.
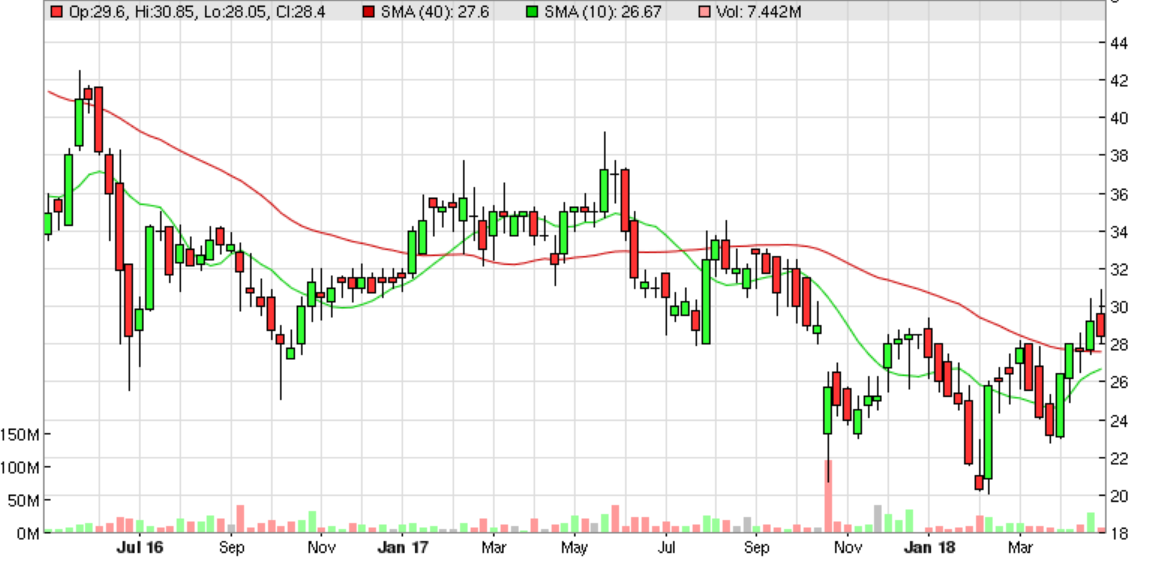
As you can see, PDG has not been a good investment over the last 2 years. In the roaring bull market of 2016-17, much better gains were available on more growth-orientated companies;
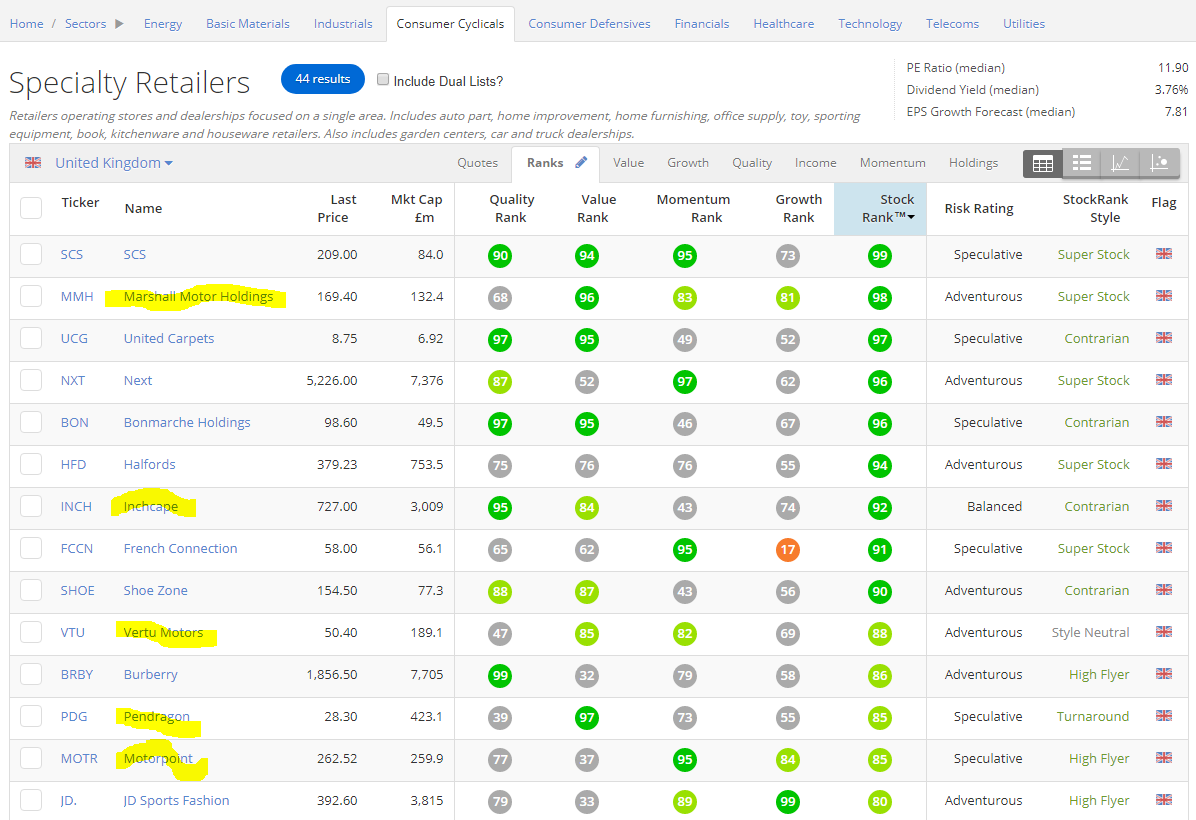
Note that you can click through from any company's StockReport to its sector. I sometimes do this, and then sort the sector by StockRank. This can be a very quick way of finding potentially interesting companies to research, in a sector, which you might otherwise miss.
Here is the speciality retailers sector, sorted in descending order of StockRank. I have used the wonky highlighter to show the car dealerships in the list;
EDIT: Note that the AGM voting didn't go smoothly;
17.12% voted against Directors Remuneration
25.94% voted against re-election of Chris Chambers (Non-Exec Chairman)
Whilst the motions were carried, companies should recognise that, given the difficulty of voting at AGMs (many private shareholders are excluded, due to the awful nominee arrangements), that a significant vote against any motion is a serious matter. It shows that shareholders (probably institutions) are sufficiently unhappy to take the trouble to vote against.
So clearly, Pendragon needs to re-assess its Directors remunerations, as some shareholders are not happy. Also, the new Chairman seems to be unpopular, so should maybe consider resigning?
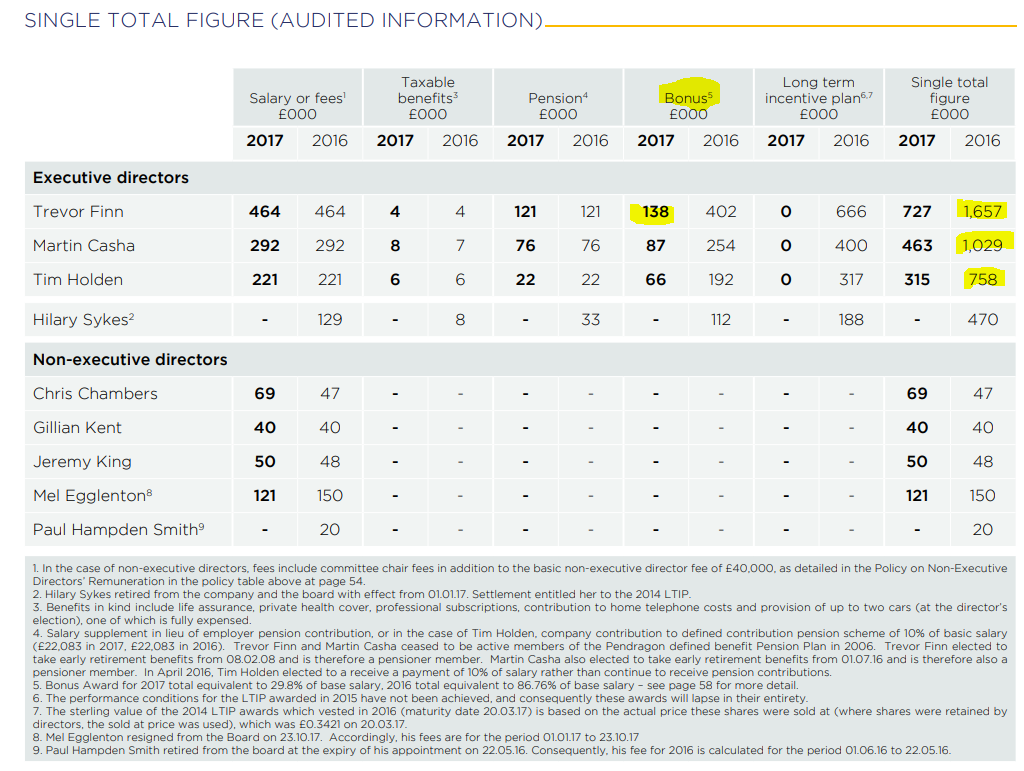
I've had a look at the 2017 Annual Report. Below is the table of Directors remuneration. The 2017 figures are not a huge concern (although why were any bonuses at all paid, given that profit fell?). However, look at the 2016 figures, which are just ridiculous.
This group seems to have bonus arrangements, an LTIP, and a so-called Value Creation Plan (which is legalised theft as far as I'm concerned). How many incentive schemes do they need? I'm not surprised that some shareholders are unhappy. Executive greed really does need to be tackled. If companies don't sort this out themselves, then a future probably Government will do.
My view on various incentive schemes, is that they tend to pay out when the macro picture happens to be favourable. Directors may have had little overall input into a big rise in profits. They just happen to be in the job when the economy is booming & profits soar across the sector.
Accsys Technologies (LON:AXS)
Share price: 80p (up 3% today, at 10:55)
No. shares: 111.5m
Market cap: £89.2m
Purchase of Arnhem land & buildings
The opportunity has come up for this maker of specialised processed wood to buy the freehold of its site in Arnhem.
It seems to have exercised a right of first refusal, from the landlord wishing to sell.
It doesn't look a done deal yet though, as the E23m+VAT cost has yet to be financed. Discussions with a bank are underway.
I very much prefer it when companies own their freeholds. It gives certainty, and also long-term valuation upside.
Trading update - for the year ended 31 Mar 2018.
This sounds quite interesting. Key points;
- Accoya sales volumes up 15% in H2 (improvement from H1, as FY is +7%)
- Total revenues up 8% to E61m. This rather pedestrian growth is due to well-known production capacity constraints.
- Gross margin improved, due to price rises.
- Capacity expansion of 50%+ soon to come on line. This is the interesting bit, as if increased production is lapped up by customers, then it could lead to a step change in profitability (which has been non-existent in the past).
- Strong pent-up demand - a very good sign, indicating that some or all of the new capacity will find willing buyers.
- Tricoya plant in Hull - construction should be completed in mid-2019.
My opinion - this is a share I held in the past, but it was taking too long to develop. So I sold, and have kept a watching brief.
It's tempting to buy back in, with production soon to make a step-change upwards.
How do we value it, though? I can't find any broker research, so it's difficult to know where to start. Generally I'm not keen on capital-intensive businesses like this, which have to build factories, and then expand them to increase production. Although, it sounds as if there might be licensing opportunities too.
It's tempting, although this company has been promising jam tomorrow for a long time. Maybe we're on the cusp of better things, with production rising 50%+ shortly?
I think on balance, I'll pass on it, given that I don't know how to value it. Although for punters, who are prepared to take on more speculative positions, this one looks to be at quite an interesting stage.
Plastics Capital (LON:PLA)
Share price: 118.5p (up 1.3% today, at market close)
No. shares: 39.0m
Market cap: £46.2m
Plastics Capital (AIM: PLA), the niche plastics products group, is pleased to announce that it expects trading for the financial year ended 31 March 2018 to be broadly in line with market expectations.
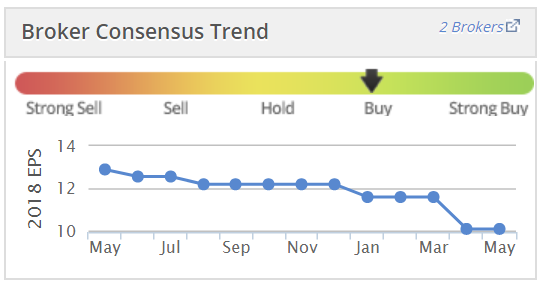
Slightly below, then. Stockopedia is showing 10.1p forecast EPS, so that's a PER of 11.7.
I do wish companies would always include a footnote, explaining what market expectations are (in their opinion), as there can be differences.
Note that broker expectations have fallen a lot in the last year. Therefore being slightly below considerably reduced forecasts really isn't particularly impressive;
Net debt - finished the year at £14.7m - a considerable amount, at nearly 32% of the market cap.
The business seems to be capex-hungry too, and doesn't seem to generate much free cashflow.
Directorspeak - this positive tone (below) doesn't seem consistent with results being slightly below the considerably reduced forecasts, or maybe I'm missing something?
"We are pleased to report exceptionally strong organic growth. Generating sustainable organic growth has been a challenge in recent prior years but after two consecutive years of strong growth we can see that the investments that we continue to make in people, business development, product development and new capacity are making a sustainable difference. We can see this continuing as we move into the current financial year."
My opinion - I see this as (at least partly) a lifestyle business for the Directors.
Returns for shareholders are scant, with the divis being slashed last year. Hence the yield is now only about 1.8%. I'm not keen on indebted companies paying dividends anyway.
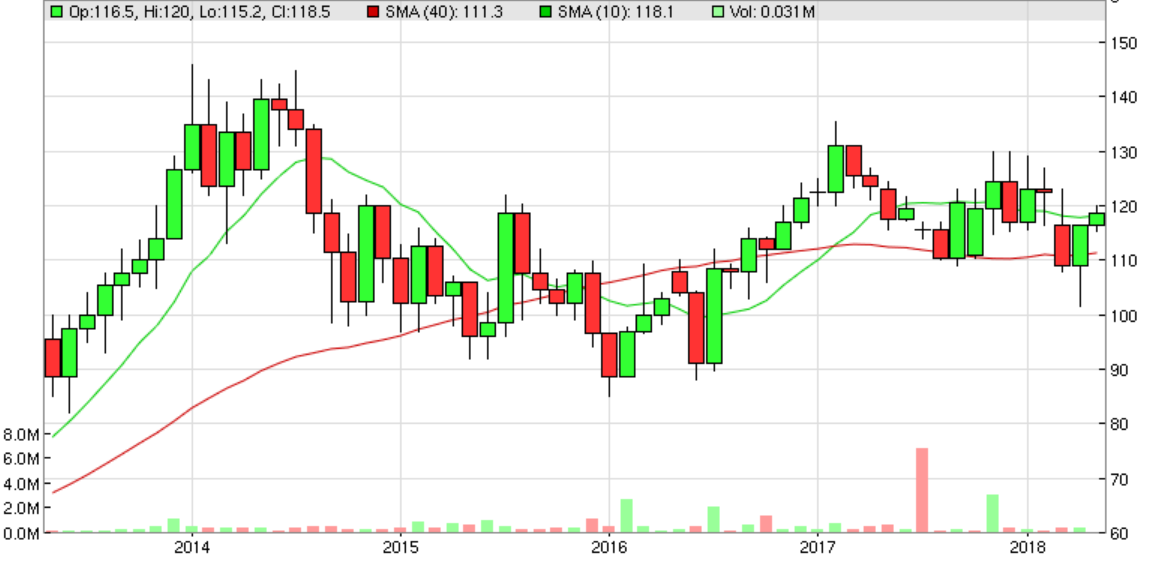
The other problem is the opportunity cost of holding this share. Look at the 5-year chart below - it's not really going anywhere, is it? What's likely to change, to drive the valuation higher?
The other problem is that the group already has more debt than I would like. So to make further acquisitions, it would need to either further over-gear the balance sheet (risking disaster in the next recession), or dilute shareholders with more equity raises.
Given that PLA shares are on a fairly low rating, then it makes no sense to issue new shares for acquisitions, unless exceptionally cheap acquisitions can be found. So overall, the group is in a bit of a catch-22 situation.
I really can't see any attraction to this share, unless it is able to meaningfully lift future profits above the current level. It's on a low PER for a good reason - because it's a collection of not particularly good businesses.
STOP PRESS! This announcement came out this afternoon, shortly before the Takeover Panel deadline:
Airea (LON:AIEA)
Share price: 58.5p (up 3.5% today, at market close)
No. shares: 41.4m
Market cap: £24.2m
What's PUSU, I thought? It must be Put Up or Shut Up. I thought that was a slang term, but it seems to be a real term used in takeover situations, which are governed by the Takeover Panel.
5pm today was the original deadline for James Halstead to either withdraw its possible takeover interest, or announce a firm intention to bid.
At 3:20pm this afternoon, Airea issued a statement saying that it had requested, and been granted, an extension of this deadline by 21 days.
What's interesting about this, is that Airea is clearly taking seriously the approach from James Halstead. Otherwise it would have terminated discussions, which it hasn't. Therefore due diligence is clearly underway.
... Discussions between both parties commenced following the 5 April 2018 announcement, and are ongoing. The purpose of this extension is to provide the directors of both Airea and James Halstead with the opportunity to continue their discussions, including the provision of certain key information to assist James Halstead in assessing the value of the Company...
My opinion - I'm relaxed about whatever happens here. James Halstead can have it, if they pay up a decent price (in my view the company could be worth up to 100p per share).
On the other hand, if bid talks fail, then there would obviously be a hit to the share price in the short term, but there could be a bigger result for Airea shareholders in the longer term. I explained in detail in this 18 Mar 2018 article what the opportunity is for Airea shareholders.
The abbreviated version is that the highly profitable core commercial floor-coverings business ("Burmatex") is doing very well, and expanding with new products & new geographies. The heavily loss-making carpets division ("Ryalux") is being closed down, after several years attempting in vain to turn it around.
Hence overall group profitability should soar from historic levels, once those Ryalux losses have gone, in future. That's what is driving the current re-rating, and I think it could have further to go, potentially.
The downside issue is a large pension fund, which although supposedly fully funded now, is still sucking cash out of the main business, to de-risk it. This could prove an impediment to a takeover approach, as agreement of the trustees would be needed, I think?
I'm keeping some powder dry, to buy more Airea shares, in case the bid approach falls through. This share is very illiquid, and buying can be tricky. I dread to think what it would be like trying to sell, if bad news comes along in future.
Some people might be just in this share for the bid approach. So I'll be happy to take their shares off their hands, at a lower price, if the bid approach falls through! Overall, I think this is a very interesting special situation.
Note also that Airea appears within one of the best-performing Stockopedia screens, called Tiny Titans, which is modelled on the work of James O'Shaughnessy. I tend to look at stocks in this screen about once a quarter, and have picked up some nicely profitable stock ideas from this, in the past few years. It's a good place to look for overlooked small companies.
OnTheMarket.com
Share price: 147p (up 6.5% today, at market close)
No. shares: 60.5m
Market cap: £88.9m
This is the property portal site, challenging the duopoly of Rightmove & Zoopla.
It announces today that it has increased to 7,500 the number of estate agents signed up to its portal. This is up 2,000 since the shares listed in Feb 2018.
Amazingly good progress, until you realise that they're on special offers, predominantly free of charge!
The offering of predominantly free or discounted introductory rates is a key element of the Company's growth strategy, which aims to increase the core agent customer base, the number of their property listings on the portal and the traffic the portal attracts.
This is not as daft as it seems. After all, how else could they hope to dislodge Rightmove (in which I have a short position), unless they offer an alternative service free of charge? The reason I'm short of Rightmove, is because it makes excessive profits, and this is bound to annoy its customers. If someone else comes along offering a free service (initially), then why not give it a go?
Website visits are rising, but that's because OTMP now has a refreshed advertising budget, after the recent fundraise.
My opinion - I think the chances of OTMP succeeding commercially are very small indeed, since Rightmove has such an entrenched position. However, the prize for this lucrative market, is very big. Therefore, if OTMP makes decent progress, it could rise considerably.
I'm keeping a watching brief for the moment. I'd like to see what OTMP's cash burn is like too. It's all very well driving traffic to a website with TV adverts, but you can burn through plenty of cash very quickly that way. Then when the adverts stop, web traffic goes back down again.
I don't see anything different about OTMP's portal. So why would customers stop looking at Rightmove, where most properties are to be found, to use a different portal with far fewer properties on offer?
For this reason, OTMP's business model really doesn't seem to have any killer blow potential. But you never know! If it does work, then the shares would be a major multibagger. So I suspect some people may have bought the shares on the basis of it being a call option on success, that would probably end up worthless, but has an outside chance of major success.
All done for today!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
James Halstead (LON:JHD) has decided not to bid for Airea (LON:AIEA), for now anyway. It will be interesting to see where the price settles at the open tomorrow. It was around 43p prior to the announcement of a possible offer, so presumably this or thereabouts is where it will drop to?
A fascinating report as ever - I'm flagging a couple of these for more research. You seem to have lost the header for the Onthemarket (LON:OTMP) section, though.
Hi grb,
Thanks, I've fixed that now.
OTMP seems to be one of the few tickers that upsets the user interface.
P.
Horizon Discovery (LON:HZD) has jumped 30% on an RNS re a possible offer by Abcam (LON:ABC) at 181p per share. Abcam's proposal has been rejected by Horizon's board.
I took an initial small position in Horizon in February despite its 'sucker stock' rating (everyone's allowed one in their portfolio, right?). The rationale for this was Horizon's lowly market cap compared to those of gene editing companies in the US, where current valuations are reminiscent of the dotcom era. It seemed plausible that Horizon could either become a bid target or undergo a rerating based on this valuation mismatch. I was also encouraged by a number of substantial director purchases in early Feb.
I bought more shares in April when the price went below 140p and there were more director purchases, most notably from non-exec Dr Jonathan Milner, who is a significant shareholder in Abcam and also its Deputy Chairman.
Personally, I'll be disappointed if Horizon is taken over. It's in a very high growth market, and after years of losses seems about to become profitable. With a relatively fixed cost base, those profits could be expected to rise very strongly if revenue projections pan out. However I'm not in the least surprised that Abcam has it in its sights - it would be a very good fit in my view.
Not sure of the best place for this as it is a left-field observation on one of tomorrow's small cap RNSes.
Worry not, this is not insider information in fact it is very much outsider information.
Tomorrow is the AGM for Trinity Mirror (LON:TNI) (to be renamed "Reach" thereafter) and they will make a trading statement.
Over the last three years or so trading statements have been exceptionally predictable; market conditions are always 'challenging' or 'volatile' (or sometimes both), but performance has always been 'in line' with expectations (or in the case of Q4 updates slightly ahead).
However, I strongly suspect we may see a subtle shift in tone.
On the 17th April Johnston Press (LON:JPR), included the following in their announcement :
Tracking in line with prior year is a sharp contrast to the significant declines that both Johnston Press (LON:JPR) and Trinity Mirror (LON:TNI) have seen in print advertising over the recent past.
The Johnston Press (LON:JPR) share price was unmoved by this announcement, mainly I think because the bigger question for Johnston Press (LON:JPR) shareholders is whether they will actually have any significant share in the equity once the bonds become due for renewal.
As a result I suspect that the "read across" to Trinity Mirror (LON:TNI) has been largely overlooked, the price is up slightly over the last couple of weeks, but nothing beyond the faint uptrend that has been in place all year.
The reasons cited by Johnston Press (LON:JPR) are very much industry factors rather than company specific, so I very much expect Trinity Mirror (LON:TNI) to report something similar.
So aside from already having a holding in Trinity Mirror (LON:TNI) on value grounds , I decided to take an additional small "coin-toss" position on tomorrow's announcement. I feel that the coin is weighted in my favour and I'm getting better that evens odds.
This could be a bit of false memory syndrome, but I can think of a small number of occasions in the past where I have felt that a company statement could be reasonably be predicted based on other recent information, but where the price has not moved, each of these produced good returns on the day.
This is not a scientific study by any means so I could be forgetting occasions where the statement did not come out as expected or where the price did not move as expected, so I'm just floating this as an idea for now, but it is something I will be looking to track going forwards for companies in my universe.
I wonder if others can think of instances like this that have either gone in the right or wrong direction?
Trinity Mirror (LON:TNI) Johnston Press (LON:JPR)
Noticed this myself (infact I think someone posted it here on one of the threads) but didnt have the courage in my convictions to add to my holdings in Trinity Mirror (LON:TNI) . Hope you are right and wish you well.
If nothing else it might detract from discussions over gov't getting involved in the merger - does anyone really care about plurality in newspapers apart from politicians? The newsprint arena must surely now be an insignificant part of general media news. The name Facebook springs to mind for some reason.
Anyway good luck!
Phil
Paul - with regard to your comments about the AGM at Pendragon (LON:PDG) I looked at an old RNS and see that the now chair was chair of the remuneration committee at the time of last year's AGM and put forward a controversial "Value Creation Plan" which had a 47.45% vote against with the remuneration report having 44.66% against.
"We note that shareholders approved our new remuneration policy and value creation plan. The board believes that this new policy, and the VCP is fundamental in supporting the delivery of our strategy, rewarding both the executives and senior management group driving its successful delivery, on its maturity in four years' time," Chairman of the Remuneration Committee Chris Chambers said in a statement.
Paul, it is interesting that all of the car dealers are reporting growth in used car sales and a strategic shift towards that part of the business. Makes sense when the new market is soft. BCA and Motorpoint seem to be doing ok so market consolidating, which again not surprising I suppose given impact of ability to look for cars online.
Everyone is getting excited about Innovaderma (LON:IDP) but don't forget that this isn't a prescription medical drug or medical device. I think it is likely to be an over the counter product and potentially not covered by medical insurance, so less margin as customers have to pay themselves.
Details are sparse but it might be an easy to copy product without IP?
A heads up for Avon Rubber (LON:AVON) which I have held for 15 yrs with an annualised return of 22%. They sold the tyre business long before I got involved and then the bendy bits for cars and washing machines. Now 1/3 high end milking bits and (a bit over) 2/3 defence having the orders for many (inc USA) bio-protection masks inc aircrew. I see that after 5 yrs there is an increasing order for replacement filters. EPS up 30%, Divd up 30%. I am not asking Paul to review (probably still digesting his Lordly scone).
I bought originally when (?) Sarin was released in Japan but I think all productive capacity now goes to military round the world. One in my bottom drawer and now not cheap but the half year report comes across as very positive. Might be of interest to anyone looking for a 250 company earning mostly $ rather than £.
Regards,
Seadoc
I've held Avon Rubber (LON:AVON) for quite a while too and always mean to sell but never get round to it. They seem to produce and hoard a LOT of cash - now up to £40 million with no stated plans as to what to do with it other than a vague "This strong cash position provides funding to support our organic growth strategy and value enhancing acquisitions.". At least they put the divi up 30% but it's still mean.
RE Pendragon (LON:PDG) and Consumer Confidence
data on consumer confidence doesn't look great of late : the latest in April was -9 on an expected -7 while the overall trend is also downward from recent peak of around 8 in 2015 ..mind you the 2008 trough was -40 so I suppose it is all relative. Changing a car is often a hugely discretionary decision, unless there is a radical change in sentiment I'd suggest the data predicts otherwise . Car sales in March this year were off 13% from last year's peak (tho that was 10 year high). If interest rates are destined to rise then surely there is a headwind on credit and affordability since most car sales now are in effect cheaply financed leases?
Not sure I agree with the thesis that we have reached "peak car" but that may also be a consideration.
Finally, owing 2 diesel burning 4x4s, I can see that part of the markets is pretty knackered now: I am just going to suck up the (govt enforced) depreciation and not change for a good while
Just a few points for debate, Pendragon (LON:PDG) share price does mirror the below drop in consumer confidence but that may well be just co-incidence or apophenia on my part
Link to consumer date here
Hi dscollard,
I too looked at the recent consumer confidence data, and discovered something very interesting.
As you can see in the table below, people seem fairly comfortable with their personal situation, but there is a massive negative score on their view of the general economic outlook. I suspect this might be heavily influenced by unrelentingly negative news coverage of politics & economics. How else would people form such a view, given that few people are economic experts? (and such experts are useless at predicting anything!)
Therefore, looking at things in a contrarian way, I see scope for improvement in consumer confidence. I'd be a lot more worried if people were negative about their own personal circumstances, but they're not.
(I highlighted the wrong year below, it's the first column (April 2018) that I should have highlighted)
So an overall score of -9 actually masks a positive "Personal Financial Situation" of +4
As regards new car sales, the whole market has changed. People are getting used to leasing new cars, often for very low costs, relative to their earnings. E.g. an average person takes home about £1.5 - £2k per month. Yet they can lease a smallish new car, say a Corsa, for about £150 per month. There would be little to no maintenance or repair costs, so it's a no-brainer, compared with buying some unreliable, thirsty, clapped-out heap secondhand.
This suggests to me a change in the market dynamics, and a sustainable level of higher new car sales. Once the Govt pulls its finger out on diesels (good/bad?), then there could even be pent-up demand to be unleashed for new cars?
Plus, note that car manufacturers are steering people towards the multimedia attractions of the car being a big extension of your mobile phone. This is interesting to me, as in our increasingly congested & slow roads, perhaps more people just want a pleasant personal space, and ability to use their phone/music/apps, in a voice-activated way, as being more important than fast 0-60 times, top speed, etc?
I don't buy top-end cars any more, as they're pointless. You can't use 300+ bhp anyway, so why have it? It's just a temptation, and would probably end up in either a driving ban, and/or a horrific accident. Maybe that's just me getting older?!!! ;-)
Best wishes, Paul.
"It is a peculiar empirical phenomenon that while people tend to be optimistic about their own future, they can at the same time be deeply pessimistic about the future of their nation or the world. Tali Sharot, associate professor of psychology at UCL, has popularised the idea of an innate optimism bias built into the human brain. That is, we tend to be optimistic rather than realistic when considering our individual future. If you were to ask newlywed couples to estimate the probability they will divorce in the future, they would likely reject the possibility outright. Yet today roughly 40% of marriages in the UK end in divorce. Another example is asking smokers to estimate their chances of getting cancer and again, most would underestimate their risk. This optimism persists even when people are presented with the relevant statistics."
https://ourworldindata.org/optimism-pessimism
@Paul, more granularity in those data you have: what is the source?
Sound interpretation , the consolidation in grocery could also be net positive to disposable income .
I live in the country these days: single lane roads play havoc with paint jobs so I am much more pragmatic these days too
@Paul, more granularity in those data you have: what is the source?
I just downloaded the data from the usual GFK source of consumer confidence stuff, here;
http://www.gfk.com/en-gb/insights/press-release/uk-consumer-confidence-drops-two-points-to-9-in-april/
Then I think if you click on "download press release", you can get a bit more detailed info.
Yes, retracing my steps, here it is;
http://www.gfk.com/fileadmin/user_upload/dyna_content/GB/documents/Press_Releases/2018/CCB/GfK_Consumer_Confidence_April_2018.pdf
I must stress that I have no expertise whatsoever in interpreting this data. Just think it's interesting, so good to drill into & think about.
I don't agree at all that people are over-confident about their own personal financial outlook. Quite the opposite actually. People tend to have a very good idea about their own personal outlook, and a very bad idea of the general economy.
Regards, Paul.
P.S. I have a diary note to review this kind of monthly data. The reason being that it is often misinterpreted by the press - who for example mix up retail sales volumes, prices, and overall value. Journalists often get basic stuff wrong, because they're young, inexperienced, and have little to no real world business experience. Hence why it's dawned on me, that I can get good insights from checking the data myself.
great thanks, much appreciated. I tend to agree that people are more prone to catastrophizing, especially now we have so many social media channels to enable and share it
Hi Paul,
I'd really appreciate it if you could find time to look at the debt situation for Empresaria Empresaria (LON:EMR)
I hold and they have fallen 50% since last April, they appear to have a highly motivated team through equity (they go into this in reports) and from the website:
* Management equity philosophy is a unique proposition for entrepreneurial managers to have a share ownership in the companies they run, along with access to a Group network to support them and provide access to finance and staffing expertise.
They appear quick to address issues in the business, which given how many they acquire is important (from jan rsn):
* The Group has worked to minimize the impact of changes to temporary worker legislation in Germany and the business in the Middle East has been resized resulting in an improved performance.
So if they debt is sensible and explained they appear well positioned in a tight labour market, and cheap.
thanks
John
Hi john652,
The debt position at Empresaria (LON:EMR) is all explained quite clearly in their last results statement.
It's more a question of how we assess & interpret the overall financial position, and then how we value the shares. I admit to finding that bit difficult with Empresaria. When I have such doubts, then I usually steer clear, just to be on the safe side.
Regards, Paul.
Hi Paul,
Yes, agree, and Mello principle of any doubt is move on I guess. I've held for quite a few years so I think I'll wait until the trading statement and see what happens.
Pastysupper. They released the RNS late afternoon yesterday. I really dislike Companies doing that as it’s not a level playing field. Couldn’t they have waited until 7am today? It was luck and unfair that I happened to be monitoring share prices just after they announced their supposedly wonder FDA approved premature ejacultion solution product. So I bought a few at 135p and the share price has shot up to nearly £2....for now.
I’ve held IDP before after it was tipped in Small Company Sharewatch and took profits as seemed overhyped. IDP have so far been better at producing exciting sounding RNS news than proper information on sales and profits for their various products. They sell a supposedly popular skin tanning product and also something that is supposed to be very good at restoring hair. IDP fails my ADVFN rule.......small companies there getting hundreds of rubbish posts a day generally end up doing badly. otoh there’s just a chance that the hype and claims for their products are justified, and also it’s not too late for SCSW to cover it in their May edition. But it’s a fun punt and not worth risking much imo.
Anybody here have an opinion on the Innovaderma (LON:IDP) RNS yesterday and the subsequent spike in its share price? They've released a new product in the US which there seems to be a lot of excitement around. I'm torn on this as it seems like A decent risk/reward balance, given the (still) current lowly rating and potential for a significant upside. On the other hand it smells a bit like one of those overhyped pump and dumps.
Same suspicion here Patsy re a pump, I also suspect they will need more cash soon to launch this product simultaneously in the US/Aus, plus potentially EU. The product does sound interesting and potentially lucrative but I just have no idea how it will feed through to the bottom line of Innovaderma (LON:IDP), which makes it a no for me currently. Happy for holders though as it has been a rocky ride of late for the SP.
Another Mello Derby company presentation, (three more to follow in due course).
N4 Pharma (N4P) presentation at Mello Derby 2018
Nigel Theobald, CEO
http://www.piworld.co.uk/2018/05/02/n4-pharma-n4p-presentation-at-mello-derby-2018/
Introduction – 00:36
Business model – 00:40
One year on – 02:16
Sildenafil MR - 03:22
Nuvec – 07:38
Summary – 15:38
Q&A – 16:10
Coverage of RNSs is all very nice Paul but I'm sure what many want to know about is the quality of the cakes and sandwiches at The House Of Lords :-)
Hi Laughton,
Coverage of RNSs is all very nice Paul but I'm sure what many want to know about is the quality of the cakes and sandwiches at The House Of Lords :-)
LOL! I had a fantastic time at the House of Lords yesterday afternoon. What a privilege to be given a guided tour. I knew that the Houses of Parliament are big, but once inside I was staggered at the full extent of the place - it's gigantic! No wonder that new MPs often say that they struggle to find their way about inside.
At home, I drink my tea from a massive Sports Direct mug. So the rather dainty tea cups in Parliament's tea rooms struggled to satisfy me. So I got through about 8 cups of tea, and a very good scone with jam & cream. The only negative was the thin paper napkin. And a server who intermittently made a helluva racket with crashing baskets of crockery, etc, just behind the counter.
It's was very strange to see a few faces walk past, which I recognised from Question Time, including Priti Patel.
Afterwards, I was allowed into the actual debating chamber of the House of Lords. There are a few seats for visitors on the side. It was fascinating to hear them debating. It struck me that, because Lords are appointed, rather than elected, they don't have to worry about playing up to the cameras, or scoring petty points against each other. Instead there was a polite, and co-operative atmosphere, with Lords giving proper replies to the questions raised by the other side, and being very courteous to each other. I like that.
The topics under discussion whilst I was there, included transport problems in Cambridge, and increasing protection for whistleblowers in the NHS. One Lady suggested that Cambridge could build its own underground railway system. A Lord gently pointed out that tunneling costs at least £250m per kilometre, so it probably wouldn't be economic, and could also incite riots in Peterborough, where people are already unhappy about Cambridge getting more funding than them!
I'll certainly take more of an interest in the Lords, in future. We only ever seem to hear negative things about it. However, my impression was of a decent group of people, with a lot of experience, trying to improve the detail of legislation, for not much money (£300 per day attendance allowance has to cover travel & hotel costs, for example).
Whilst them being appointed is clearly not democratic, it does have some benefits - in that debate is higher quality, and less partisan, precisely because they don't have to seek re-election. So there wasn't any petty point-scoring that I witnessed. The Commons has primacy of course, as the Lords can only delay legislation that they don't agree with.
Overall, a fascinating day. Although I am sorry that it disrupted the service here.
Regards, Paul.
Having spent nigh on 17 years in London the only tourist event I have done (other than London eye, paid for by employers) is the houses of parliament tour. Not quite as glamorous as yours Paul, but was fantastic experience.
Especially when the guides tell you about some of the idiosyncrasies of past ministers. Would strongly recommend it to anyone who has a spare few hours in London.
Full disclosure: I have no holding in the Houses of Parliament :)
My morning smallcap tweet:
Scholium (LON:SCHO), Third Point Offshore Investors GBP (LON:TPOG), Empresaria (LON:EMR), Plastics Capital (LON:PLA), Accsys Technologies (LON:AXS)
Scholium Group (SCHO) FY trading: guides small profit (-£224k). Nothing about expectations. No published F/C .
Third Point Offshore (TPOG) plans move from standard to premium listing. Will repurchase shares instead of paying a div.
Empresaria Group (EMR) CEO resigns, replaced by COO. Nice words.
Plastics Capital (PLA) guides FY broadly in line with market expectations. "As highlighted in the announcement on 1 March 2018, the financial year finished with both sales and profits a little weaker than expected. For the year overall though we experienced a year of exceptionally strong, primarily organic, sales growth...As previously explained to shareholders, we have continued to invest heavily to add capacity and capabilities to support double digit revenue growth, and, whilst this is being achieved, this re-investment will continue to impact on depreciation, interest costs and cash flow." On 1 March guided FY marginally below current market expectations due to bearings div.
Accsys Technologies (AXS) FY trading. Rev up 8%. F/C is for 1.4%. H2 rev up 15%. ""It has been a strong finish to the year, although we have been capacity constrained with all our customers on allocation. Our revenues, sales volumes and margins were all up in the second half." Looks like a beat but don't say so.