Small Cap Value Report (Wed 20 June 2018) - BOTB, HSS, FOOT, RDL, SFR, THAL

Good morning!
Today, we have a couple of very welcome guest comments from Paul.
It looks surprisingly quiet on the RNS front, in relation to stocks in my universe.
Stories on the radar so far include:
- Best Of The Best (LON:BOTB) - final results
- HSS Hire (LON:HSS) - refinancing
- Footasylum (LON:FOOT) - comment on yesterday's dire announcement
- Ranger Direct Lending Fund (LON:RDL) - AGM yesterday
- Severfield (LON:SFR) - results for FY18.
- Thalassa Holdings (LON:THAL) - share buy-backs/earnings preview
Mello meeting: a quick plug for the next Mello meeting in Beckenham. It's on Monday (25th June) and will feature Sosandar (LON:SOS). All you have to pay for is your own drinks and dinner, and e-mail David in advance to say that you're going. Here's the link!
Best Of The Best (LON:BOTB)
- Share price: 295p (+7%)
- No. of shares: 10.1 million
- Market cap: £30 million
(This section is written by Paul, who owns shares in BOTB.)
Results look as expected. What's interesting is that the company (which runs a weekly competition to win supercars & other prizes) is to exit all its remaining airport sites, and become an online-only business. I think this might trigger a re-rating of the shares at some point. The decline in the airport locations (which have become too expensive to operate) has masked good online growth. Today it reports 23% underlying online growth, which is now 84% of total revenues, and set to become 100% of revenues when the 3 remaining sites are closed.R
I think the company is gradually learning which marketing expenditure works best, and this comment (below) today gives me hope that growth might accelerate. Given that each additional sale is virtually pure profit, then this process of increased growth from increased marketing could become a virtuous circle. That's what makes the shares so interesting, in my view;
All our online marketing investment is carefully tracked and constantly fine-tuned to ensure we are optimising the returns. As confidence in the returns on investment improves, we anticipate increasing our marketing budget by approximately 40% in the next financial year, across the full range of previously tested channels.
Remember that sales are international, not just UK. So the potential market size is the entire world!
Note that today's outlook statement is positive;
BOTB has delivered increased revenues and profits slightly ahead of management's expectations and remains strongly cash generative. We believe the business is well positioned for the new financial year, which has started encouragingly, and I look forward to updating shareholders on further progress in due course.
There's another special divi announced today, of 4.5p, on top of the regular 1.5p divi. There have been lots of special divis paid in recent years, and I expect more of the same.
Paul's opinion - I'm a long-term holder here. I think valuing the company on a PER basis is missing the point. The point is all about the future potential, if growth were to really accelerate. Also, the eventual outcome is likely to be a trade sale. Imagine the upside to a large betting group, if they were to buy BOTB and then ram their own customer base through their own marketing channels. With each extra sale almost pure profit, that could make the company worth multiples of the current price. You might say, couldn't a big betting group just replicate what BOTB has done instead? Yes they could, but BOTB has spent almost 20 years building up a reputation & customers. So why incur all the start-up losses from a new operation, when a big betting group could just buy BOTB and have a ready-made additional business, with good potential upside?
This share is horribly illiquid, so tricky to buy. Note that the company takes out sellers, by buying in the market. So selling would not necessarily be a problem.
HSS Hire (LON:HSS)
- Share price: 32.05p (-2%)
- No. of shares: 170.2 million
- Market cap: £55 million
HSS successfully secures refinancing
(This section is written by Paul, who does not own shares in HSS!)
HSS Hire (LON:HSS) has refinanced its debt, in what looks a terrible deal. They're paying between 700 & 800 bps over LIBOR on a new £220m facility. Plus they're having to give away 8.5m warrants too. This just shows the foolishness of running a hire company on hideously expensive debt. The whole point of operating in this sector is to finance the hire fleet on the cheapest credit available - which can only be obtained if a company also has decent equity on its balance sheet. Another example of why balance sheet strength is very important! I reckon the equity here is probably worthless. This extortionately expensive debt deal confirms that.
Footasylum (LON:FOOT)
- Share price: 72.5p (-9%)
- No. of shares: 104.5 million
- Market cap: £76 million
(This section written by Paul.)
When I saw that the share was down c.50% yesterday, I quickly read the announcement, and almost bought some. However, this urge to buy immediately after profit warnings has cost me dearly in the past, as it's usually a mistake. The trouble is, I tend to "anchor" to the old share price, and hence jump to the conclusion that the share must be cheap at a 50% lower price. This is usually a mistake.
Thankfully, I managed to curb my urge to buy, and instead did some research on the revised forecasts. Or rather, I just read a broker note from N+1 Singer, which is available on Research Tree. They have reduced forecasts considerably, and are now only forecasting 4.8p EPS for the current financial year. So at 80p last night, the share is not cheap, based on the revised forecasts.
Worse still, as Graham mentioned in yesterday's report, FOOT was sold to the market on the basis of very strong organic growth in both sales and profit. That story has now almost completely collapsed. It now seems that the company is struggling to generate profit growth, despite opening loads of new shops. This really calls into question its whole business model. I've never been particularly keen on retailers which sell other peoples' products. They can be squeezed on margins too easily, and undermined by the brands selling their own products through their own websites. Why use an intermediary retailer when you really don't need to?
Overall then, I've probably got too many concerns about FOOT's business model to want to risk buying the shares, even at the new, rebased down valuation.
On the upside, it does have a decent balance sheet, so there are no solvency issues, even if trading deteriorates further. Plus, this is actaully a great time to be opening new shops on the High Street - as landlords are increasingly desperate to fill empty units, so reduced rents and generous inducements (e.g. reverse premiums to fund the fit-out, and long rent-free deals) are becoming increasingly prevalent. It might actually pay companies like FOOT to put a hold on new shop openings, and wait for even better landlord deals in the future?
I think Graham's estimate (in yesterday's SCVR) of a 60p share price, as a good potential entry point, looks about right. Who knows, the share price might even undershoot that? At 50p I would probably be a buyer.
This one joins the long list of stock market floats which were over-priced, and opportunistically timed. This reinforces my own aversion to investing in new issues. It seems safer to wait at least a year, or even 2, before considering buying into new issues.
We have a great advantage over institutions. New issues are some of the limited number of situations where instis can buy in decent size, so they naturally tend to be drawn to them. Whereas you and I can bide our time, and buy in any time we like. Furthermore, Instis are high & dry, if something goes wrong, in that it's so difficult for them to dispose of a large stake. Whereas you & I can press a button and exit instantly, if our stakes are smallish, any time we like.
The above is why I've never invested in any small cap funds. Their liquidity problems are so restrictive, that they lose a lot of the benefits of small cap investing. They have to be outstandingly good stock pickers to succeed, because they can't move in & out of small caps when they want to.
Ranger Direct Lending Fund (LON:RDL)
- Share price: 813p (unch.)
- No. of shares: 16.1 million
- Market cap: £131 million
(This section is written by Graham, who owns shares in RDL.)
A string of AGM-related notices have been released by Ranger this week. The AGM was yesterday.
To recap, this is the debt vehicle that became the target of a shareholder activist campaign by the value equity portfolio manager at Oaktree.
Oaktree is Howard Marks' firm. Marks is considered by many (including me!) to be one of the world's top value investors.
So that's what initially got me interested in the story. I checked the numbers and realised the stock was trading at a modest discount to NAV, even assuming that its large failed investment (in a lending platform called "Princeton") turned out to be worthless.
Ranger hasn't performed particularly well since inception, and so Oaktree and another institutional shareholder were both calling for it to be liquidated.
Excluding Princeton, I thought the rest of the portfolio was ok. Buying into it at a discount, with the potential for it to generate a good return and then to receive a return of capital, is the plan.
I don't include this within the "equity" portion of my personal portfolio, although I acknowledge that strictly speaking, that is what it is. For my own purposes, since the underlying assets are primarily debt obligations, I categorise this as a fixed income investment.
Anyway, what happened at the AGM?
The Ranger board at first resisted the activist campaign, but most of them (3 of 4) eventually said they intended to resign prior to the meeting.
The AGM took place yesterday, with the result that:
- one of the four existing Board members was re-elected.
- two Oaktree nominees were elected.
- one of the nominees from LIM (the other activist shareholder) was elected.
Comment by the Oaktree portfolio manager:
Oaktree is confident that the refreshed Board will have the requisite experience to oversee RDLF and ensure a smooth and successful wind-down of the Company for the benefit of stakeholders,” said Patrick M. McCaney, Managing Director and Portfolio Manager of Oaktree’s Value Equities strategy.
Sounds good.
The strategy which sounds best to me and has been proposed by LIM is to allow as much as possible for the existing portfolio to mature as normal.
The average maturity on its debt portfolio is just two years. So two years from now, half of the loans will have naturally liquidated themselves, with no unusual transaction fees. That is ideal.
Longer-term debts should be sold only if this can be done at a fair price: there is no need for a fire-sale.
I'm very confident that the new Board is well-qualified to oversee this process and maximise value for shareholders.
NAV was last reported at $183 million, for April 2018 (assuming Princeton is worthless).
Divide by the latest $1.32 exchange rate and 16.1 million shares, and I get an NAV per share estimate of 861p.
The GBPUSD exchange rate is an important risk factor.
Personally, I've been buying a lot of USD-denominated debt over the last few days. I need to think carefully about how much of this, if any, I want to hedge back to GBP or EUR.
Ranger's discount to NAV (excluding Princeton) at the latest offer price is about 4%. Unfortunately, the bid-ask spread is quite wide.
Severfield (LON:SFR)
- Share price: 85p (+4%)
- No. of shares: 302 million
- Market cap: £257 million
Results for the Year ended 31 March 2018
(This section is written by Graham.)
Quite a few reader requests for this, "the largest structural steel specialist in the UK".
Severfield is the UK's market leader in the design, fabrication and construction of structural steel, with a total capacity of c.150,000 tonnes of steel per annum, which represents c.17 per cent of UK structural steel production.
Today's results are encouraging:
- Revenue up 5% to £274.2m
- Underlying* profit before tax up 19% to £23.5m
- Special dividend of 1.7p per share
- Return on capital employed ('ROCE') of 16.5%
- "Over 100 projects undertaken during the year in key market sectors including the new stadium for Tottenham Hotspur FC, the retractable roof for Wimbledon No.1 Court and a new commercial tower at 22 Bishopsgate"
The UK order book has reduced slightly. That's the only small negative feature in today's results. As we've discovered, the relationship between the size of an order book and future revenues is not as clear-cut as we might have presumed!
It's good to see that the adjustments made to "underlying" PBT are modest. There is the amortisation of some acquired intangibles, plus movements on some currency hedging contracts.
2018 is left-hand-side, 2017 is right-hand-side:
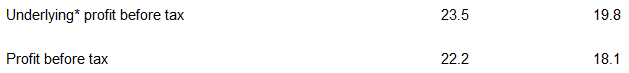
Why do I care so much about this issue? The reason is that shareholders are nearly always paying for these adjustments. Acquired intangible assets had to be paid for with shareholder cash. They still had a cost, even if we call it "amortisation" and recognise it gradually over a period of time, instead of putting it all through the P&L on day one.
Thankfully, the accounts are Severfield are pretty clean in this regard.
Also comforting to read that the company has a ROCE target of 10% through the economic cycle.
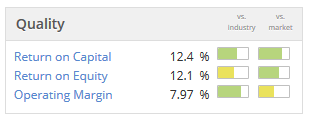
That's not a very high target but it's comforting that the company puts so much emphasis on it. It has also been comfortably beating this target in recent years (I guess it's supposed to do that during the bullish parts of the cycle).
Stocko algorithms believe that the company is high Quality, estimating quality metrics as follows:
The CEO also issues a very positive outlook statement. Note the reference to the "stable" order book:
The strong performance of the Group has continued into 2018, with good revenue and profit growth supported by strong cash generation. The strategic and operational progress that we have made over recent years gives us confidence that the Group is well placed to deliver sustainable future profitable growth. With a high quality and stable order book of £237m and a strong UK pipeline of opportunities, we expect 2019 to be another year of progress in the UK.
My view
The company is doing really well, and has a fine reputation among blue-chip clients. The £50 million Google project at Kings Cross is particularly impressive.
It won't be going on my watchlist, because it doesn't tick enough of the boxes in terms of the checklist I am using these days.
- It is B2B and contract driven (note how large the Google project is relative to the order book as a whole). Four recent London projects have revenues of £20 million each. This is lumpy business.
- Like any construction business, it is cyclical. If you add up the company's net income from 2010 - 2017 (inclusive), you get a negative number. Perhaps there are particular reasons why performance was so bad during the previous cycle, which won't happen next time?
I could be missing out, but I don't believe that I can predict contract wins or time the economy, so I'd rather not play.
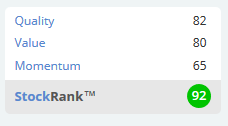
If things do stay rosy for a few more years, then the shares could easily turn out to have been cheap at the current level. Trailing diluted EPS is 5.97, for a fully diluted P/E ratio of 14x.
The valuation multiple is not expensive, management sounds competent, it has good market share, and the order book is stable. So there are still plenty of positives for existing shareholders.
IAS 15: A quick note for accounting nerds. Severfield reckons that the new accounting standard on revenue recognition won't affect its results in a material way.
The conclusion of this assessment is that the directors are satisfied that no material adjustments will be required on the initial application of the new standard.
Personally, I think that the new standard is very logical. It requires business contracts to be broken down into separate "performance obligations", and to recognise revenue as these performance obligations are satisfied. It makes good sense and it's reassuring that most companies have said it won't change their results very much.
Thalassa Holdings (LON:THAL)
- Share price: 84.5p (unch.)
- No. of shares: 19.1 million
- Market cap: £16 million
No real news from this one today, except for a small share buy-back.
I'm flagging it because results are due very soon - this week - for the year ended 31 December 2017.
Every value investing bone in my body is telling me to buy it, but I've resisted the temptation (so far!)
As described in my previous report on it, the company had $20.3 million cash (£15 million) as of December 2017, plus a 25% ownership stake in Local Shopping Reit (LON:LSR). That's worth about £7 million at today's share price.
So by my maths the shares are priced at a discount of almost 30% to cash plus LSR, which is a very conservative estimate of NAV.
My difficulty is that I don't know what the future investment strategy is going to look like. Thalassa has invested in everything from mining to commercial property to underwater robotics.
The Chairman is manually closing the NAV discount with these share buy-backs, so I do think that the outlook for the share price is positive, at least in the short-term. Long-term, however, I have no idea about what Thalassa might invest in. Without clarity on its strategy, it's not something I can put my own funds in.
As it says on its website:
The Company was established as a holding company with various interests across a number of industries.
If it had a clearly defined plan that was sensible, I think it would and should trade around NAV (or at least at the value of cash and property).
As I said at Mello, with balance sheet-focused value investing, you need some kind of a catalyst to unlock value. Without that catalyst, your money can get locked up fruitlessly for years.
I experienced this myself with Northamber (LON:NAR) and several others. If you are waiting three or four years for a catalyst then you could easily be destroying value, after taking the time value of money into account.
With Thalassa, that catalyst could be a focused investment strategy, more buy-backs, or a special dividend (I would favour the first two options). It would also be much better if results could be issued faster than six months after year-end. Let's see what happens - I'm still on the sidelines.
That's all for today - cheers.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Hi peterg,
I agree, BOTB model does not seem very honest if one winner and that’s it. I think I will email them for some ckarity here. I have posted your response below as Stocko seems to be hiding replies and not putting them in the main thread:
Reply to rambutan2:
Fine, but if they want to stay in business they need to be seen to be relating the winnings to the income. If they expand online they can't just keep the payout on the same basis and pocket the difference. They might get away with it for a while, but the market would catch on in the end and they would end up with a reputation of being rip off merchants, or regulated. So if they significantly increase revenue from online punters they have to increase their outgoings too.
Peter
Aston Martin DB7 - I out-ran the rozzers! V12 6 iitre - say no more!
Hi Paul,
Peter G (post 27) makes an interesting point, do you know how Best Of The Best (LON:BOTB) game play algorithms work? On the website you can chose from 180 cars with a weekly winner. if 999 people choose a Ferrari and 1 chooses a Ford Focus and the Focus person wins, do they pocket the difference, and of course vise-versa and therefore potentially take a loss. Do they scale increase the winners based on the number of sales or in this just one winner regardless of ticket sales, hence pure profit after a certain level? thanks John
BOTB website
Entrants can choose from the 180+ cars in the Dream Car competition line-up. At the end of each Dream Car competition, one car is won. This is determined by matching the winning coordinates from the Spot the Ball game (as chosen by our panel of expert judges) to all the entries.
john652,
Each week there is just one car won, regardless of ticket sales. Some weeks it is a more expensive vehicle, some weeks a hot hatch. Truly random.
Fine, but if they want to stay in business they need to be seen to be relating the winnings to the income. If they expand online they can't just keep the payout on the same basis and pocket the difference. They might get away with it for a while, but the market would catch on in the end and they would end up with a reputation of being rip off merchants, or regulated. So if they significantly increase revenue from online punters they have to increase their outgoings too.
Peter
Re Inspired Energy (LON:INSE) I bought it and held for a small profit of about 12% over 3 months while Yu (LON:YU.) doubled. Ballocks to that.
Thanks Dave, that is very clear. I have studied Yu (LON:YU.) which is in the same space (it’s a supplier, not an advisor). Might be worth keeping an eye on both of them. Cheers - G
Best Of The Best (LON:BOTB) is a stock I would potentially be interested in, but echoing Paul's point about liquidity I simply couldn't bring myself to buy something with a £30m market cap and 15% free float. And buying back shares apparently!
I think they need to open it up more if they're serious about the listing.
Hi Chris,
Best Of The Best (LON:BOTB) is a stock I would potentially be interested in, but echoing Paul's point about liquidity I simply couldn't bring myself to buy something with a £30m market cap and 15% free float. And buying back shares apparently!
I think they need to open it up more if they're serious about the listing.
I love the dividends from BOTB!
Every time I get a massive cash divi, I email Will & thank him for it. Basic good manners :-)
It's just good manners!
Management do actually appreciate that kind of email.
Cheers, Paul.
The special divis on Best Of The Best (LON:BOTB) are fab :-D
Graham,
I repled to your post 34 and it indicates that there is a reply at the bottom thereof but it has not appeared here so I reprint below-
Hi Graham,
Well they don't have a monopoly or a moat so I do not see them as a very long term investment over many years. However they have 85% client retention, organic growth via selling additional services to clients and acquire related small companies at prices which tend to be immediately accretive partly from cash flow and share issuance but they have also taken on more debt. Net debt of around £15M does not look unreasonable bearing in mind the rapid growth.
They placed £9M with institutions in 2017 to fund some of the acquisitions and current holders include Miton 15.4%, Living Bridge 11.7%, Cannacord 8.6% and Slater 5.5%.
Not surprisingly with 9 acquisitions since listing on AIM all that goodwill has created a negative NTAV and as mentioned I don't see a long term hold here. The confidence I have for the current year is based on the order book which at £39M is 37% up on 2017. I expect this to be reflected in the profits for H1 and FY18.
I see the share price has moved up 5.4% during the day.
Dave
EU Supply (LON:EUSP) just posted the investor presentation given last week by CEO. Quite interesting, I think. Although a real microcap c.£10m MC.
http://www.piworld.co.uk/2018/06/20/eu-supply-eusp-investor-presentation-june-2018/
Hi Graham
Apologies for flogging this particular horse (I requested it last week) but if you were minded to look at Duke Royalty (LON:DUKE) on this quiet day, I'd value your expert opinion.
cheers
Francis
Hi Graham
I've had a look at Duke Royalty (LON:DUKE) recent presentation. http://www.dukeroyalty.com/~/media/Files/D/Duke/documents/investor-presentation-may-2018.pdf?pdfdata=1
It seems to be interesting. On my initial quite quick look it has some echoes of an early stage of Burford Capital (LON:BUR).
But, I could not quite grasp what their business model offers differently to other sources of business finance. In short, I could not distill from the presentation what their USP is.
If you have a moment, I would interested to hear from you what you are spotting in them that attracts you?
Regards
Howard
Hi Francis, I do appreciate you flagging up Duke Royalty (LON:DUKE). Unfortunately I haven't got enough hours available to study it today. I'll bear in mind that you've requested it for future reference. Thanks! - G
Francis,
Thanks for flagging (or flogging) Duke Royalty (LON:DUKE) again. I'm intrigued and I'll open a starter position in it I think.
I assumed from the name that they would be into resources, but in fact that's a sector they avoid entirely.
Bringing a new business model to the UK could well be rewarding. It strikes me as a potential reliable earner that should be less cyclical - a tuck away in the SIPP type of investment.
Good comments on FOOT...thank you. Went short on this yesterday as it seems dire to me. Down another 8 per cent today despite plenty of small trades. What if the eps is just 3p or so next year? Talk about a late bull market mugging......
Very true..I wonder if it will trigger my stop, then start to go back up to add insult ...:-).
I'm now going to eat my lunch of humble pie, and see what is happens this afternoon.
But, as I said in my other thread, I feel for the investors who were long on this before the announcement.
Graham,
As it is a quiet day perhaps you could look at Inspired Energy (LON:INSE) who issued an in line but very positve TU today in advance of the AGM.
As I have said many times before they are not a Utilitywise but appear to get tarred with the same brush being on a forward pe of 11.4 for the current year despite having excellent CAGR growth rates by most metrics.
They do have a large 5 year LTIP but the shares have all been issued to the EBT and going forward are included in the current share count calculations.
Dave
Hi Dave, I've not studied Inspired Energy before so not sure I have anything sensible to add on that one. Seems like its in a growing space (energy consultancy). Would you be able to summarise the investment thesis at all? I am particularly interested to know if they have a competitive advantage that is sustainable, or is it more that they are riding the wave in energy consulting at the moment?
Hi Graham,
Well they don't have a monopoly or a moat so I do not see them as a very long term investment over many years. However they have 85% client retention, organic growth via selling additional services to clients and acquire related small companies at prices which tend to be immediately accretive partly from cash flow and share issuance but they have also taken on more debt. Net debt of around £15M does not look unreasonable bearing in mind the rapid growth.
They placed £9M with institutions in 2017 to fund some of the acquisitions and current holders include Miton 15.4%, Living Bridge 11.7%, Cannacord 8.6% and Slater 5.5%.
Not surprisingly with 9 acquisitions since listing on AIM all that goodwill has created a negative NTAV and as mentioned I don't see a long term hold here. The confidence I have for the current year is based on the order book which at £39M is 37% up on 2017. I expect this to be reflected in the profits for H1 and FY18.
I see the share price has moved up 5.4% during the day.
Dave
Graham, See reply at post 37, Dave
Possibly an old question, but grateful for any thoughts. Where you invest in dividend reinvestment plan (DRIP) which is not in a tax wrapper, such as an ISA, what is the tax status of the reinvested dividend?
My assumption is that the dividend should be declared for income tax purposes, and that tax will be due notwithstanding that the funds have been reinvested.
That's my understanding, but remember there is still a £2,000 dividend allowance to use up before tax is due.
https://www.gov.uk/tax-on-dividends
Thanks for the response. Yes, I recall there is a dividend allowance, albeit lowered recently.
Regard
Paul said:
The same though was echoed by Guy Thomas at last week's Mello when he said that it was very difficult to invest more than 8 digits (10M) in small caps due to liquidity constraints.
Wise comments
A question on AIM shares/IHT/BPR which has had comment before.
Anyone got a view on the eligibility of Telford Homes, Watkin Jones and Inland Homes. I ask because there seems some doubt about the eligibility of property type AIM shares. Thankyou. Mr Ken.
The Investors Champion AIMearch tool here https://aimsearch.investorschampion.com/ can provide an answer for a small fee. You need to distinguish between property builders and property investors. There is also the matter of joint ventures and passive investments on balance sheets which could bring 'excepted assets' into the equation...and other factors as well.
The Investor's Champion AIMsearch tool helps identify the IHT qualifying statuis of all AIM companies
Specifically on Telford Homes (LON:TEF) it may comfort you to learn that when a shareholder at last year’s AGM raised the question of moving to the main market from AIM, qualifying for IGT relief was a key reason given by the company for remaining on AIM. I would espect the others you mention to qualify as well, but I have not specifically checked.
Many thanks for that Andrew.
Mrken
I too would appreciate your thoughts on Severfield (LON:SFR) . I hold right now and would appreciate your thoughts on where you think this one could go as they head towards their 2020 target.
Hi Graham
Another vote for Severfield (LON:SFR), if you have time. I hold and may add.
All the best
Jonno
Hi Graham - Any chance you could comment on yesterdays update from ACCSYS please. Seems a good company but figs difficult to comprehend!
Thanks
Second request on ?AXS, though I am not sure that analysis of the historic accounts helps much. Difficulty I have is figuring out the impact on profit of the current capacity increases. But any company that can sell more than it is making has to be interesting. I hold.
Footasylum (LON:FOOT) - when I saw that the share was down c.50% yesterday, I quickly read the announcement, and almost bought some. However, this urge to buy immediately after profit warnings has cost me dearly in the past, as it's usually a mistake. The trouble is, I tend to "anchor" to the old share price, and hence jump to the conclusion that the share must be cheap at a 50% lower price. This is usually a mistake.
Thankfully, I managed to curb my urge to buy, and instead did some research on the revised forecasts. Or rather, I just read a broker note from N+1 Singer, which is available on Research Tree. They have reduced forecasts considerably, and are now only forecasting 4.8p EPS for the current financial year. So at 80p last night, the share is not cheap, based on the revised forecasts.
Worse still, as Graham mentioned in yesterday's report, FOOT was sold to the market on the basis of very strong organic growth in both sales and profit. That story has now almost completely collapsed. It now seems that the company is struggling to generate profit growth, despite opening loads of new shops. This really calls into question its whole business model. I've never been particularly keen on retailers which sell other peoples' products. They can be squeezed on margins too easily, and undermined by the brands selling their own products through their own websites. Why use an intermediary retailer when you really don't need to?
Overall then, I've probably got too many concerns about FOOT's business model to want to risk buying the shares, even at the new, rebased down valuation.
On the upside, it does have a decent balance sheet, so there are no solvency issues, even if trading deteriorates further. Plus, this is actaully a great time to be opening new shops on the High Street - as landlords are increasingly desperate to fill empty units, so reduced rents and generous inducements (e.g. reverse premiums to fund the fit-out, and long rent-free deals) are becoming increasingly prevalent. It might actually pay companies like FOOT to put a hold on new shop openings, and wait for even better landlord deals in the future?
I think Graham's estimate (in yesterday's SCVR) of a 60p share price, as a good potential entry point, looks about right. Who knows, the share price might even undershoot that? At 50p I would probably be a buyer.
This one joins the long list of stock market floats which were over-priced, and opportunistically timed. This reinforces my own aversion to investing in new issues. It seems safer to wait at least a year, or even 2, before considering buying into new issues.
We have a great advantage over institutions. New issues are some of the limited number of situations where instis can buy in decent size, so they naturally tend to be drawn to them. Whereas you and I can bide our time, and buy in any time we like. Furthermore, Instis are high & dry, if something goes wrong, in that it's so difficult for them to dispose of a large stake. Whereas you & I can press a button and exit instantly, if our stakes are smallish, any time we like.
The above is why I've never invested in any small cap funds. Their liquidity problems are so restrictive, that they lose a lot of the benefits of small cap investing. They have to be outstandingly good stock pickers to succeed, because they can't move in & out of small caps when they want to.
Regards, Paul.
Hi Paul,
A good review of the Footasylum (LON:FOOT) situation. I bought this morning and the shares are just hovering at my stop-loss level (and I'm not going to move it down).
Retail seems to be very sensitive at the moment, especially anything with a street outlet content.
Not really my field, but that lack of confidence is like an anchor.
Maybe I should just buy Amazon as a buy and hold and forget the sector.
Severfield (LON:SFR) again Graham if doable thanks
Graham. Could you comment on yesterdays Full Results from Flybe?
Hi tony, sorry about that. G
Another vote for Severfield (LON:SFR) please. Looks like more good steady progress here, but with the big added bonus being a nice fast-paced uptick in performance of the Indian JV. This could potentially be a driver for a small re-rating here - they say that things have improved so much that they are going to struggle to service the India market demand from their current infrastructure and are looking at ways of investing to increase their capacity. The current India business' order book is already up 35% on last year even before such investments (having improved its profit last year to 0.5m from 0.2m) so it's easy to see this part of the business potentially generating a couple of million of profit in the next couple of years which equates to 10% of global profit suddenly (from next to nothing last year) and could be a nice kicker to the steady UK growth performance. Special div. is nice and makes sense given the cash hoard and strong balance sheet. A lot to like. I am a happy holder.
biacs thanks for this summary - will take a look
If Immunodiagnostic Systems Holdings (LON:IDH) were capable of delivering on its promise, it could be a really interesting share. Royalty stream losses from Vit D switching to large diagnostic machines nearly complete, Vit D assay lfl losses flattening out, recent deals to bring 100 new tests to a machine that can only do 22 in Europe, 10 in the US and 6 in China. Unfortunately, they've not been able to clear a single test through the US FDA in more than 2 years so how do they cope with 100 new ones? It looks like things probably not going to get a lot worse. But will they get any better?
Severfield (SFR)
Good set of results this morning. They have a target of 26m PBT by 2020 - might well get there early.
Started to pay special dividends - current increases yield to 5% - scope for further given their 33m in cash.
Phil
(Apologies - pound sign has gone AWOL again on my computer.)
Hi Phil, I've included Severfield (LON:SFR) in the report. It's not for me but hopefully I've given it a fair look! Thanks as always for the request. G
Graham
Severfield (LON:SFR) (I've got my £ back!!!!)
Many thanks for your analysis - its contrary to my veiws as I suspect you suspect - but it's good to hear contrary opinions - it makes you reanalyse your own conviction which can only be good. We have the same information, our opinions differ basically on emphasis. I think a growing company with a 5% yield (assuming further specials) is rare, especially in contracting with a 8% operating margin and a management with emphasis on ROCE . I take your argument about the cyclical nature but think there are some positives here - for example we will be building a lot of warehouses (on-line) and high-rises (housing shortage) in the coming years which will require steel frames. So, at least at the moment, I have high conviction here.
Time will tell and each to his own.
Thanks again.
Phil
Hi Graham
Severfield (LON:SFR)
Thanks for your comments - I don't wholly agree, but its good to have a contrary opinion to reassess your own conviction.
I think Severfield (LON:SFR) is in a good place - its the UK leader in its field. Whilst I accept your argument about the cyclical nature of construction I would suggest we need more warehouses, high-rises .... etc which mitigates this.
I accept your comment about adding the net income for the last 10 years but you can't make that argument for the last three which is when the current management was put in place. I realise this is a classic "its different this time" argument, but with a management concentrating on a ROCE target and an operating margin of 8%+ I think they have earned the benefit of the doubt. But time will tell.
We have the same information but come to different conclusions based on emphasis. I see a stable, growing company offering a 5% yield which seems attractive compared with a lot of others.
Thanks again
Phil
Deleted. Paul reviewed ;-)
Good morning!
A few quick views from me, from things that caught my eye on today's initial review of the RNS;
Best Of The Best (LON:BOTB) (in which I hold a long position) - results look as expected. What's interesting is that the company (which runs a weekly competition to win supercars & other prizes) is to exit all its remaining airport sites, and become an online-only business. I think this might trigger a re-rating of the shares at some point. The decline in the airport locations (which have become too expensive to operate) has masked good online growth. Today it reports 23% underlying online growth, which is now 84% of total revenues, and set to become 100% of revenues when the 3 remaining sites are closed.
I think the company is gradually learning which marketing expenditure works best, and this comment (below) today gives me hope that growth might accelerate. Given that each additional sale is virtually pure profit, then this process of increased growth from increased marketing could become a virtuous circle. That's what makes the shares so interesting, in my view;
Remember that sales are international, not just UK. So the potential market size is the entire world!
Note that today's outlook statement is positive;
There's another special divi announced today, of 4.5p, on top of the regular 1.5p divi. There have been lots of special divis paid in recent years, and I expect more of the same.
My opinion - I'm a long-term holder here. I think valuing the company on a PER basis is missing the point. The point is all about the future potential, if growth were to really accelerate. Also, the eventual outcome is likely to be a trade sale. Imagine the upside to a large betting group, if they were to buy BOTB and then ram their own customer base through their own marketing channels. With each extra sale almost pure profit, that could make the company worth multiples of the current price. You might say, couldn't a big betting group just replicate what BOTB has done instead? Yes they could, but BOTB has spent almost 20 years building up a reputation & customers. So why incur all the start-up losses from a new operation, when a big betting group could just buy BOTB and have a ready-made additional business, with good potential upside?
This share is horribly illiquid, so tricky to buy. Note that the company takes out sellers, by buying in the market. So selling would not necessarily be a problem.
HSS Hire (LON:HSS) - has refinanced its debt, in what looks a terrible deal. They're paying between 700 & 800 bps over LIBOR on a new £220m facility. Plus they're having to give away 8.5m warrants too. This just shows the foolishness of running a hire company on hideously expensive debt. The whole point of operating in this sector is to finance the hire fleet on the cheapest credit available - which can only be obtained if a company also has decent equity on its balance sheet. Another example of why balance sheet strength is very important! I reckon the equity here is probably worthless. This extortionately expensive debt deal confirms that.
Over to Graham for the rest of today's news!
Regards, Paul.
I suspect the apparent easy trackability of online ads might be an illusion and they may lose something not keeping a few loss-making sites in major airports for marketing purposes... In the fight between Google/FB and random small businesses, I wouldn't bet on the latter winning...
Re Best Of The Best (LON:BOTB), I was previously put off this company by it's website that was very old fashioned and very tacky, and just rubbish. However, they have a new one, which is none of the above. The airport sales guys always seem to have walked off the set of the comedy 'phone shop' and that put me off too.
However I think the market is there to be expanded, as you say Paul, a big gaming company or ideas such syndicate purchasing like all the groups who buy lottery tickets. They have the model and lots of data and that can always be leveraged. Definatey worth another look.
I thought the airport sites were the best marketing for Best Of The Best (LON:BOTB). It was the only reason I ever knew of them before reading about them here.
But I'm not one to gamble on that type of thing so perhaps the people who will are to be found online.
Tend to agree. Being in airports was incredible good marketing and by moving out they are loosing their USP (some online sales may even have arisen from punters within the airport itself) Its now not going to take much for a competitor to move into their space, as there are no barriers to entry other than a good marketing strategy.
Given that each additional sale is virtually pure profit, then this process of increased growth from increased marketing could become a virtuous circle.
I would have thought that the prizes - expensive cars - were a large part of their costs. If they keep increasing sales without matching the prizes I would have thought that would have a negative impact on perceptions and would be a dangerous path to take. So I'm not sure I agree with that statement.
Peter
My morning smallcap tweet: Deltex new CEO leverages MBA dictionary.
Mysquare (LON:MYSQ), Northbridge Industrial Services (LON:NBI), Best Of The Best (LON:BOTB), Elektron Technology (LON:EKT), HSS Hire (LON:HSS), Deltex Medical (LON:DEMG), CAP XX (LON:CPX)
MySQUAR (MYSQ) The loss making co acquires loss making MyPay Myanmar for £1m cash and £1m paper. Issues £2.2222m convertibles. Bargepole.
Northbridge Industrial Services (NBI) £2.5m placing at 125p (3.5% disc) to pay an outstanding deferred consideration of £1m and for working capital.
Best Of The Best (BOTB) FY pretax up 6% to £1.6m, slightly ahead of management's expectations. Final div 1.5p + special div 4.5p. Current year started encouragingly,
Elektron Technology (EKT) AGM stmt. Guides FY rev up YoY. F/C is flat.
HSS Hire Group (HSS) £220m loan at 7 to 8% over LIBOR and a revolving credit facility of £25m at 2.5 to 3% over LIBOR to refinance its debt. Issues 8.5m warrants at 1p as sweetener worth £2.7m at current SP.
Deltex Medical Group (DEMG) AGM stmt. New CEO will do everything better. What can we say to holders? Oh, I know: "optimising the Group's sales and marketing activities in order to maximise the Group's revenues and addressable markets" and "husbanding cash resources". Need a bit more. "Facilitate sales into a broader number of clinical areas around the world to increase the size of the Group's addressable market".
Cap XX (CPX) Guides FY rev at least A$4.9m. F/C is A$5m. Guides EBITDA loss A$1.6m. There is a 'sharp increase' in enquiry levels which if all converted to orders, would be US$20m per annum, including over US$2m existing design wins (=sales?). That's rose tinted max.