Small Cap Value Report (Wed 23 June 2021) - BOOM, G4M, JOUL, VTU, MRL, MANO

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Could I ask that subscribers please don't copy any content from here onto any other websites. It's subscription content that people are paying for here, so it shouldn't be plastered all over the internet for non-subscribers. Thanks.
StockSlam - is tonight! A fun, free, social event online. 10 pitches of 3 minutes each, from private investors, talking about shares they like. Details here.
Timing - today's report is now finished.
Agenda -
Paul's Section:
Audioboom (LON:BOOM) - trading update from yesterday. Impressive revenue growth here, but no profits yet. Looks interesting, but how do we value it?
Gear4music Holdings (LON:G4M) - I had a short phone call with management, here's what I asked them.
Joules (LON:JOUL) (I hold) - trading update for FY 05/2021. Slightly ahead of market expectations. I plough through the detail. This is one of my favourite long-term holdings. Priced probably about right for now, but big increases in earnings are forecast. Strong growth from Friends of Joules ecommerce marketplace. Stores now re-opened and trading ahead of 2019.
Vertu Motors (LON:VTU) (I hold) - more profit upgrades. This looks astonishingly cheap, on a PER of c.8, and fully asset backed with freehold property. It's also up-to-date with eCommerce, and has twice as many cars for sale online as competitor Cazoo, which is currently valued on the NYSE at $7bn!
Jack's Section:
Marlowe (LON:MRL) - strong adjusted results and runrate revenue already comfortably ahead of FY21. Management is executing at pace but there's a lot to keep on top of at this buy and build operator.
Manolete Partners (LON:MANO) - good growth in case numbers and potential for more insolvencies as government support relaxes, but liquidity is an issue and there is a degree of subjectivity required in the accounts.
Audioboom (LON:BOOM)
900p (up 2% at 15:18) - mkt cap £141m
Audioboom (AIM: BOOM), the leading global podcast company…
Revenue expected to be significantly ahead of current market expectations … and an increased adjusted EBITDA
Revenues, not profits note.
Key points -
High demand for ads has allowed a 22% rise in average ad unit pricing - sounds encouraging
Greater than 97% fill rate on the top 15 shows
Allenby has published an updated note today for FY 12/2021-
- Revenue $46.1m (up an impressive 72% on LY)
- Adj profit before tax £224k
- Net cash £1.57m
So really, it's trading just slightly above breakeven. Would I really want to value that at £141m market cap? Maybe, if that kind of revenue growth is likely to continue, and would result in operationally geared explosive upside to profits.
My opinion - it’s been hopeless in the past, but the current strategy does seem to be delivering very strong revenue growth. It remains to be seen if that can translate into meaningful profits.
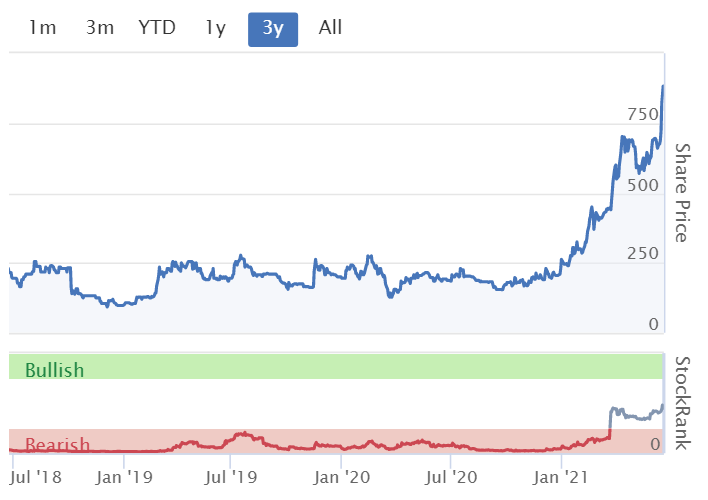
A spectacular chart too. Will the big rise stick though, or is it a speculative bubble? Who knows!
.
.
Gear4music Holdings (LON:G4M) - (I hold)
Chat with management
I was kindly offered a brief slot in the schedule yesterday, here’s what I asked (abbreviated) -
Q1. G4M develops its own, bespoke eCommerce software. Isn’t this costly, and unnecessary, with ready-made cloud software available (e.g. Shopify)?
A1. Definitely not. Bespoke software is key to our success - very flexible & we can design in whatever special features we want. Not particularly costly.
Q2. Recently acquired brands bought - how is this managed?
A2. Each situation is different. G4M can breathe new life into dormant or semi-dormant, or neglected brands, often with a long history, at modest cost. Won’t take on anything that the team can’t handle.
Q3. How accurately can you track the effectiveness of your marketing spending?
A3. Very accurately. It’s a sophisticated & specialised area.
Q4. Would you buy other online retailers, and be a consolidator?
A4. We’d look at specialised situations, which add something new to the group, but not interested in buying struggling competitors, as we can pick up their business gradually anyway, without having to buy them.
Q5. Repeat customers seem low.
A5. We do see a lot of large, one-off purchases, that’s the nature of the business. Customers are profitable from the first order. Cost of acquisition is only £9 per customer. Gross profit is c.£32 from first order. So it’s a good business model that works, even if people only buy once from us. Last year saw a lot of one-off customers, due to pandemic lockdowns.
Q6. You got a boost from lockdowns last year, but it must have hurt some product categories too, as musicians stopped live gigs & playing together in bands, etc. Is there upside this year from some product categories?
A6. Absolutely right. We’re seeing categories related to playing outdoors (e.g. large amplifiers), and bands playing together rising now.
Q7. I’ve heard that UK musicians have reported difficulties with deliveries from European competitors, such as market leader Thomann. Is this benefiting G4M?
A7. Thomann were already losing market share in the UK to G4M. Cross-border transactions are difficult, hence why we try to do as little as possible. Existing European hubs (Sweden & Germany) were set up for other reasons, but have worked very well since Brexit. We try to do as little cross-border transactions as possible. Product goes from Far East straight into European hubs, so no Brexit issues. New hubs in Spain & Ireland are quite cheap to set up, and will be important at improving service in those markets. Hoping to be operational in H2 this year.
Q8. What about further expansion internationally? USA market must be an eventual target?
A8. There’s so much more potential in Europe, so we’re going for that first. USA would involve a lot of investment, something for the future.
Q9. Southern & Eastern Europe look like an obvious gap on your map (in presentation slides) for fast delivery coverage.
A9. Yes, well spotted! We’ll get Spain & Ireland set up this year, then another European hub is likely in future.
NB. this is from memory, I didn’t take notes, so it might not be 100% accurate, but I think it accurately records the gist of what was said, if not the exact words.
.
.
Joules (LON:JOUL)
(I hold)
285p (Tuesday’s close) - market cap £318m
We’ve enjoyed a spectacular rally since the vaccines were introduced in November last year. My feeling is that this strong rally became a bit frenzied, and looked indiscriminate. Lots of fundamentally quite challenged businesses with poor balance sheets, and existing problems (pre-pandemic) suddenly multi-bagged. Often the biggest % risers seemed to be the riskiest shares. A “dash for trash” as it’s been called - maybe that’s over-stating it a bit.
Where I think we are now, is that some big share price rises are sticking, if companies produce excellent trading updates. Whereas others are slipping back down again, especially the more speculative stuff, when it becomes clear that trading performance does not justify the large rise in share price since last autumn.
That’s a very healthy process, but it does mean that it makes sense to bank profits where we just got lucky, rather than picked good companies. I can see a lot of that going on at the moment, and reader comments reflect it, e.g. “Why has xyz plc, or the X sector, gone down 10% this week?” Probably because the prices got ahead of themselves, and people are banking the profits! Also this is a traditionally sluggish time of year, when a lot of traders switch off their computers and do other things.
With retailers, key things I’m looking for are -
- eCommerce growing strongly, and a major (ideally c.50%) proportion of sales
- Modest (or no) overhang of problem property leases (ideally solved with a CVA/pre-pack)
- Marketplace websites - i.e. earning commissions selling other brands too
- Decent balance sheet, with no need for equity fundraising dilution
- Distinctive brand(s) with pricing power
- Good at everything - "retail is detail"
My preferred list of retailers is therefore the online-only giants, Asos (LON:ASC) (I hold), Boohoo (LON:BOO) (I hold), and successful mixed physical/online companies Next (LON:NXT) , Joules (LON:JOUL) (I hold) - much smaller. At the more speculative micro cap end, Quiz (LON:QUIZ) (I hold) - which got rid of all its problem leases last year, and has an established online operation.
Marks And Spencer (LON:MKS) strikes me as an interesting one to keep an eye on. It’s also going down (late) the marketplace route, and has come under fire along with John Lewis recently (see Sunday Times last weekend) for excessive fees of c.38% charged to third party brands.
What’s the betting BOO under-cut this when they properly re-launch Debenhams online marketplace in the autumn? (it’s soft launched already, but with limited stock & not many outside brands yet). I think the city has not yet realised the potential of Debenhams as an online only operation. It was already a top10 eCommerce fashion site before it went bust, doing c.£300m sales online. With BOO breathing new life into it, I reckon this could be £500m+ incremental revenue (and 10% standard BOO group EBITDA margin). Bolt that onto the BOO forecasts, and you can see what the potential for big upgrades to next year’s numbers might be.
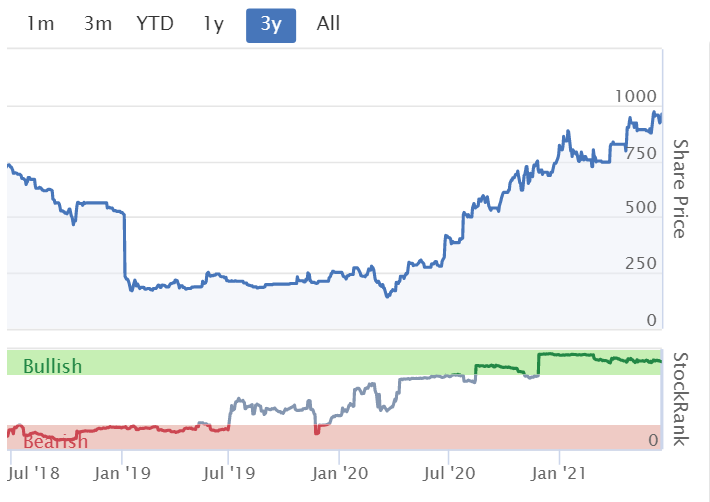
Back to JOUL. Note from the chart that the big recent rise has stuck (so far anyway, it’s been whippy this morning), because newsflow has been strong, and broker forecasts have seen very large increases. That’s often the case at the moment - shares which appear expensive on high forward PERs, sometimes turn out to be performing way ahead of forecasts - hence the valuation turns out to be not as toppy as it looked. Analysts are always way too cautious coming out of a recession, which provides us with opportunities to find companies which are likely to thrash overly cautious forecasts.
.

.
This is what JOUL says today-
Joules, the British lifestyle group, provides an update on trading for the financial year ended 30 May 2021 (the 'Period').
PR headline -
Continued strong digital momentum combined with store sales ahead of expectations since re-opening
Key points -
Revenue up 4% to £199m in FY 05/2021 (despite store closures during the pandemic - eCommerce more than recouped the shortfall)
Positive contribution from acquisition of Garden Trading Company (from Feb 2021) - this is important, because through its marketplace (“Friends of Joules”), JOUL has the opportunity to monitor & offer to acquire the most successful third party brands.
Guidance - pre-exceptional profit before tax is slightly ahead of market expectations (1)
- FY21 analyst expectations: £5.2 - £5.3m
Thank you for the footnote!
Excellent growth of +48% in Friends of Joules marketplace revenues (no figure given)
Stores re-opening (8 weeks ago) - better than expected, sales ahead of pre-pandemic comparatives 2 years ago - that’s excellent, many other High Street operators are still struggling to return to pre-pandemic sales levels.
Stores were closed for almost half FY 05/2021, with sales down 41% - making the overall group result of positive revenue growth all the more remarkable, although we already knew this, as it’s been previously announced.
Acquisition of Garden Trading - going well, sales growth of +78% vs LY - this looks to have been a very good acquisition, at an attractive price.
Wholesaling - impacted by customer store closures, so sales down -17% - I’m surprised it wasn’t worse than this, probably helped by demand from eCommerce wholesale customers.
Net cash of £4.7m, with £39m headroom on bank facilities - looks fine to me. Unusual ESG-linked bank facility, as previously discussed here.
New CFO, Caroline York, joining on 26 July.
Online - is now a remarkable 77% of retail sales. That could drop in future though, as shops hopefully trade without further interruption. Maybe we should be valuing JOUL as an online, growth business, not a retailer?
Outlook - upbeat, but no specifics -
As a result of the strength of the Joules brand and the increasing diversification of the Group's digital-led business model, we believe that the Group is very well positioned to continue to deliver its ambitious growth plans."
Broker update - many thanks to Liberum for publishing its notes on Research Tree, which is so helpful, as follows;
FY 05/2021 - 5.0p EPS (PER of 56, based on share price of 280p)
FY 05/2022 - 12.5p (PER 22.4)
FY 05/2023 - 18.0p (PER 15.6)
As you can see, the valuation looks reasonable on forecast earnings for this current year, and cheap on next year’s forecast. That’s assuming forecasts are met, of course.
My opinion - this is one of my favourite stocks, as a long-term, hold forever investment. Therefore I’m not too fussed about the short term valuation.
FY 05/2021 was heavily disrupted by the pandemic, but it’s good to see the company remained profitable thanks to shifting much of its sales online.
JOUL has all the characteristics I look for, so it remains a long-term hold for me. Maybe priced about right for now? I’m looking to increase my position size by +50% on any weakness.
.
Vertu Motors (LON:VTU)
(I hold)
46.3p (up 1% at 10:23) - mkt cap £168m
Vertu Motors is the fifth largest automotive retailer in the UK with a network of 149 sales outlets across the UK. Its dealerships operate predominantly under the Bristol Street Motors, Vertu, Farnell and Macklin Motors brand names.
Vertu Motors was established in November 2006 with the strategy to consolidate the UK motor retail sector. It is intended that the Group will continue to acquire motor retail operations to grow a scaled dealership group...
[from “Notes to Editors” in today’s announcement]
The current financial year is FY 02/2022.
Here are my notes from 12 May 2021, which I’ve just re-read to refresh my memory. I concluded that VTU looked extremely cheap, on a PER of only 7.9. The price has barely budged since then, so VTU seems to be fighting a headwind, despite putting out strong trading updates, and broker forecasts being raised substantially of late.
Today’s update is only about another 6-7 weeks since the last one.
Key points today -
- Strong trading has continued - driven mainly by used cars
- Strong H1 performance is anticipated (if current trends continue)
- Risks remain - covid, and vehicle supply constraints
- New vehicle supply problems (due to component shortages) “increasingly apparent”
- Elongated timescales from customer order, to delivery, for some brands
- Demand for used cars “remains very robust”
- Reduced supply of used cars causing “exceptional wholesale pricing environment”
Profit guidance -
In light of the strong trading performance to date, driven largely by the exceptional used car market environment, the Board now anticipates that the Group's full year adjusted profit before tax will be above current expectations and in the range of £28m - £32m.
Outlook - more strategic than specific -
The Board remains confident in the prospects for the Group. With its strong asset base, scale, Manufacturer relationships, well invested systems including the Click2Drive sales technology platform and experienced leadership team, the Board believes that the Group is strategically very well placed to capitalise on the changes and opportunities in the UK motor retail sector.
Broker updates - many thanks to Zeus and Liberum, both have issued updates today. Taking the average, we have latest forecast EPS of:
This year FY 02/2022 - 6.45p (PER of 7.3 [at 47p per share])
Next year FY 02/2023 - 5.75p (PER of 8.2)
Both brokers are assuming that this year’s bumper figures might soften next year. The share is still dirt cheap, even on that conservative forecasting basis.
My opinion - given the very low PER, and the freehold property backing, this share just looks the wrong price to me - far too cheap. Maybe I’ve missed something?
I’ve no idea what the catalyst would be to trigger a re-rating, and don’t really care. If it’s asset backed, and incredibly cheap, I want to own it, and the valuation should sort itself out one way or another at some point in the future.
I particularly like that VTU is hot on technology too, so it’s not some dinosaur business, but seems forward-looking. Check out its website, which offers similar online purchase capability (with delivery & 14-day money back guarantee) as Cazoo and Motorpoint (LON:MOTR) (I hold). Yet MOTR is valued far higher, and Cazoo is in the stratosphere with a $7bn valuation via a NYSE SPAC! Yet Vertu’s website currently has twice as many secondhand cars for sale, as either of those online competitors! This is an incredible valuation discrepancy, in my view. And an opportunity for Vertu to pivot towards faster online growth, and see a potentially large re-rating of this share. Lots to like in other words.
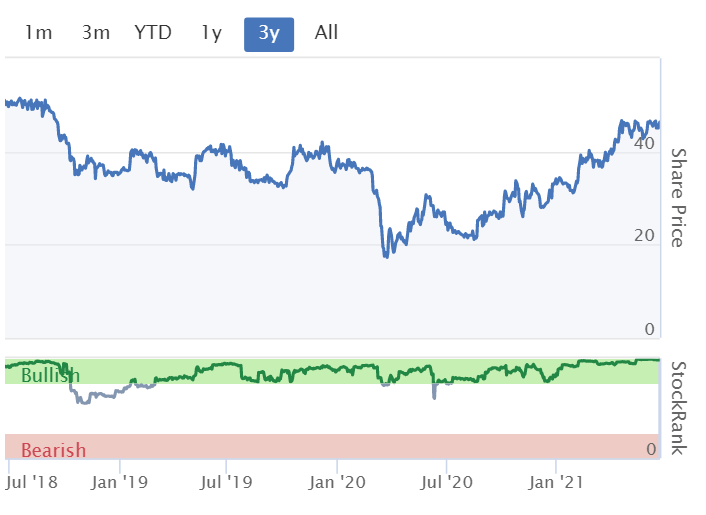
Stockopedia's StockRank system loves it too! StockRank is 98
.
.
.
Jack’s section
Marlowe (LON:MRL)
Share price: 855p (+0.94%)
Shares in issue: 77,123,772
Market cap: £659.4m
Marlowe (LON:MRL) is a buy and build operator that owns a growing portfolio of businesses that provide clients with safety, risk management, regulatory compliance, and systems maintenance services. It hopes to become the UK’s trusted name in the provision of regulated safety and compliance services through a mix of organic and acquisitive growth.
The activity here in terms of acquisitions is breathtaking. It’s either highly impressive or quite risky, and whether that’s the former or the latter depends on the quality of the management team, ability to integrate businesses, and their M&A nous.
So far, this strategy has entailed fairly consistent equity dilution. A recent placing means shares in issue are now at 77m.

While this dilution is worth monitoring, so far total earnings per share has increased at a CAGR of 21.6%, so it looks like management has been buying profitably on a per share basis.
The share price has been strong recently, and now the group is valued at 28.6x forecast rolling earnings. The market is assuming ongoing growth.

Marlowe has a revenue target of c.£500m and adjusted EBITDA of c.£100m over the next three years. That’s against today’s FY21 revenue figure of £192m and adjusted EBITDA of £28.7m, so it’s quite ambitious.
And the recent placing to raise c.£100m before expenses means Marlowe can continue to grow in keeping with its established model.
Highlights:
- Revenue +15% to £192m,
- Adjusted EBITDA +30% to £28.7m,
- Adjusted operating profit +33% to £19.7m,
- Statutory operating profit -52% to £1m,
- Adjusted PBT +31% to £17.1m,
- Statutory loss before tax of £1.6m (FY20 PBT: £0.5m),
- Adjusted basic EPS +6% to 25p,
- Statutory EPS down from -0.8p to -3.1p
The difference between the statutory loss before tax and the adjusted profit before tax includes £2.2m of acquisition costs, £5.6m of restructuring costs, £6.5m of amortisation of acquisition intangibles, and £4.2m in legacy long term incentives.

Assuming the latter is executive remuneration, I’d add this cost back in. It’s real, and it’s material, and it’s not a one-off.
Marlowe introduced a new Executive Incentive Plan (EIP) recently that could lead to further dilution - 10% over 10 years above £6.90 per share assuming 10% annualised growth in the share price from the start of the Performance Period on 1 April 2021 based on an opening share price of £6.90 per share.
This is capped at a maximum aggregate award of 4,902,295 new ordinary shares but it seems like a big payout with a very achievable target given that the share price is already 23% ahead of this threshold price in a matter of months.
It makes me slightly more cautious on this company than I have been in the past. With all the (necessary) estimation in the accounts, why not tie ultimate management compensation to a more concrete and fundamental measure of value, such as operating profit growth? That would put me more at ease.
Marlowe continues to grow though, there’s no doubt about that. A flurry of recent acquisitions mean the current 12-month run rate revenue is now up to some £280m, with c83% recurring. Some 46% ahead of the FY21 figure.
Margins are also expanding, with divisional adjusted EBITDA margin up from 13.1% to 16.2%. This could be an important dynamic moving forward as Marlowe scales up.
Net cash generated from operating activities, before acquisition and restructuring costs, has grown from £11.2m to £28.3m. After acquisitions & restructuring, net CFO is up from £3.4m to £20.4m. So actual cash flows have also grown considerably.
This is dwarfed by a total of £71.9m spent on investing activities (£68m on acquisitions and a net £3.9m on capex). Of the £170m raised in share issues and £80m in new bank loans, £149.1m has been spent on repaying debt.
Fifteen acquisitions were completed during the year.
In terms of the current trading and outlook, the group says organic growth is in line with its medium term targets.
Eight acquisitions have been completed so far during the new financial year, with a ‘strong pipeline of earnings enhancing acquisitions’
Conclusion
This is perhaps the most active buy and build operator I’ve come across. Fifteen acquisitions in FY21 and eight already in FY22 is some going. There is execution risk here, and it leads to quite complicated accounts full of subjective adjustments, but that’s just the nature of the beast at present. This business model has done very well for Sdi (LON:SDI) and Judges Scientific (LON:JDG) in unrelated industries.
The notable gap between adjusted and statutory results could be more clearly and prominently explained in the results, however.
That’s not to say there’s anything untoward here, but when there are such large and frequent adjustments coupled with multiple acquisitions in any one year, that creates a great deal of subjectivity and human input across a variety of key accounting figures.
Buy and builds do often require trust on the part of the shareholder that management is providing an accurate representation of the underlying progress of what is a rapidly evolving enterprise. While Marlowe is busily acquiring now, I suppose the aim is that one day it will be in its final form, in which case restructuring costs and all the rest of it really will disappear.
That end state could be a highly profitable company that occupies a dominant position in defensive markets with attractive recurring revenue characteristics. The total addressable market is estimated to be worth nearly £7bn (growing at c3-4% per annum) and is highly fragmented.
So it’s all to play for and management appears to be executing well.
I think either you spend a long time going through Marlowe’s history, its acquisitions, and its accounting adjustments - or you trust in the management team, you are reassured by the institutions on board (who most likely have far greater access to management than PIs will ever get) and hold shares in what could be a far larger company in five years’ time.
The third option, of course, is to focus on other opportunities.
For now the wide gap between adjusted and statutory results makes me cautious, and the valuation at present seems full, although I accept that Marlowe has ambition, is growing revenue with scope for margin expansion, and could quite possibly grow into and beyond today’s share price.
Manolete Partners (LON:MANO)
Share price: 241.90 (+0.79%)
Shares in issue: 43,571,425
Market cap: £105.4m
It’s rarely boring in the world of litigation financiers. Manolete Partners (LON:MANO) releases this trading update on the same day Litigation Capital Management (LON:LIT) announces its participation in the Comet Group liquidation claim. Then of course, prior to this, we have the Burford Capital (LON:BUR) - Muddy Waters short selling saga.
Very small free float here at 25% of shares in issue; the spread is 417bps and it looks like you can reliably buy or sell around £5k at market prices so liquidity is a consideration.
Manolete has a ‘grand old duke of york’ share price chart, marching up and then down the hill. That could mean the shares are due a rerating at some point, or it could also show that there are some holders waiting for signs of life so that they can sell down some of their stakes.

Highlights:
- Total revenues +49% to £27.8m,
- Realised revenues +214% to £24.4m,
- EBIT -25% to £7.4m ‘reflecting lower level of unrealised profits due to exceptional Government measures, a more conservative assessment of the value of our in-process cases against the background of the pandemic and the full year effect of our expanded staff network’
- Profit before tax -26% to £7.0m,
- Diluted earnings per share -24% to 13p,
- Proposed final dividend of 1p; total dividend of 2.17p (FY20: 4.17p)
- Gross cash receipts from completed cases +61% to £12.2m
The group notes £2.8m of net cash from operations, but if you account for £5.9m of investment in cases, this falls to a cash outflow of -£5m. In fairness, this reflects good growth in case numbers.
Looking at the balance sheet, the group has £1.1m of cash and around £8m of debt. Of the £57.4m in total assets, £37.5m is made up of investments. The group defines these as ‘the costs incurred in bringing funded and purchased cases to the position that they have reached at the balance sheet date’.
A 214% increase in realised revenues to a record level of £24.4m sounds impressive, and a record 198 new case investments were made in FY21, with 135 cases completed. So the group sounds busy. Manolete adds that its investments yield an average Money Multiple of 2.7x and ROI of 168% on 388 completed cases since inception.
The group now has a new RCF with HSBC for £25m over an initial three-year period to 1 July 2024, with an option to extend by a further year and an additional £10m accordion if required.
Manolete comments:
The insolvency process will play a critical role in allocating capital and resources to truly sustainable businesses in the post-pandemic UK economy. With the widely reported large backlog of insolvency cases, we expect new case enquiries to increase over the foreseeable future and we will continue working hard to deliver outstanding returns to both the creditors of insolvent estates and our investors.
Conclusion
The results value Manolete at 18.6x FY21 EPS, with a yield of 0.9%. Earnings per share looks better than the broker consensus forecast, but is some way below FY20 normalised EPS of 17.2p.
If it can get back to that level, the PER would be 14.1x, and the company was growing strongly prior to Covid. So there’s an argument to be made here that the shares are undervalued.
But I struggle to reconcile the cash-hungry business model with the double digit returns on capital and returns on equity. Accounting standards in general seem ill-equipped to handle this business model. These litigation financiers require a different method of valuation.
And there is a good deal of subjectivity in its case valuations. Furthermore, the group talks about ‘cash latency in the Company's financial results’, with the large majority of the cash benefit of FY21's record realised revenues yet to be reflected in cash reserves. Is that not just an unfavourable cash conversion cycle by another name?
These companies require specialised knowledge - which I’ll happily admit that I don’t have - and there is a good deal of uncertainty and subjectivity in the accounts. It’s clear that the market shares this sentiment. The analyst forecast on the StockReport has a price target of 520p - more than double these levels. So some degree of uncertainty is priced in.
This is not necessarily the company’s fault - but the end result regardless is that there’s too much risk and uncertainty here for me as I struggle to value the company and its prospects. The lack of liquidity is an additional consideration, but it does also mean that if Manolete does well, the share price could rerate aggressively.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Boohoo (LON:BOO)
bit ot but it is after the witching hour of 4.30pm. Boohoo are almost back at my target buy some price of 310p.
I am a complete numpty when it comes to charts but but i prefer a good looking chart to a bad un given a choice.
Does anyone who can read the tea leaves (charts) have an opinion on the boohoo chart - it looks distincly wonky at present - it looked like it has always been on an uptrend from a basic midpoint straight line average since early 2019 which has always given me comfort - however if a put some of the fancy parallel lines in that chartists use it looks like its outside of the that upwqard trending zone now and it looks like the current midpoint line i would draw from the start of 2021 is in a downward trajectory albeit reaosnably gentle. I would say each time the price has got to the low 300's level it has bounced stongly so it may be that there is resistance at around the 300-310p level.
rmillaree with respect you are probably better off asking that question on the Boohoo (LON:BOO) thread that Paul set up:
https://www.stockopedia.com/content/boohoo-boo-trading-update-q1-3-months-to-31-may-2021-discussion-823109/
Boohoo (LON:BOO) is in a channel an undecided zone. Until Mr Institution can decide its good for the ESG portfolio then Boohoo will sit in the doldrums.
378p a good alert (can set it in stocko so dont need to watch) and then 400p go unfurls the sails, but watch out for the white whale.
With regards to Vertu Motors (LON:VTU) it's interesting to see how many used cars they actually offer. Bristol Street and Macklin both offer 7836 used cars so presumably it's the same stock on both. Vertu motors have 2398 used cars. I believe this stock is included in the Bristol Street number.
Having a separate website which looks to all intent and purposes as a pure online player like click2drive should be simple to achieve and might be easier to market.
VTU is a share i have looked at a few times recently without using the buy button. The tiny margin and nebt debt i find quite concerning? Appreciate anyones thoughts
Hi MrBeak,
tiny margin - this is a red herring I think. Car dealers, most of the revenue is just pass-through. It's the margin made on each car that matters, gross profit. So, a bit like staffing companies, I would focus on gross profit, not revenue.
nebt debt i find quite concerning? - debt is to fund the inventories. Offset the two, as both could be quickly eliminated if needed. That's why lenders like lending against cars. Then you're left with a great pile of freehold property, in the case of VTU, which is why it's so attractive to value investors.
Hope that helps.
Regards, Paul.
Thanks Paul, great advice
We don't do advice!!!! Thanks for reminding me re the disclaimer.
Paul , another great find I hope. Your comments certainly have made me want to do some more research. Many thanks.
What’s more concerning to me is the tiny top line growth over many years, compounded with profit drops pre-covid.
Probably a good buy out target due to its low valuation but for me it would be too much of an opportunity cost against faster growing industries.
I sold my MANO in 2019 but I had a very quick look at the figures which reminded me how difficult it is to piece together the business from the figures. But we might mention that the government 'pandemic' intervention in terms of business support has helped thousands of businesses survive and that these measures are being curtailed and (I believe) expected to be permnently removed by September. This might provoke a rash of insolvencies. As a reminder that all is not well in businesstravel majors were understandably bleating for more support on this morning's news. I also wonder how difficult it is to actually get paid by people who have owned insovent businesses at the moment. There was a very noticeable large rise in trade receivables (over £10mn) over the year to March 2021 and a concurrent sharp drop in cash at hand. I would like to know why this happened though I didn't read all the text accompanying the results.
However, I will say that one of the factors in the price decline has simply been that the share went up too much after listing. I also understand Mr Winnfrith has been conducting an 'anti-MANO' campaign and directors' sales haven't helped so there is a slight poor odour around the company, as there is with most of the litigation firms. They attract short sellers. But finally I also note that MANO continues to do company presentations - which initially attracted me to the company - which is I suppose a good sign.
Manolete Partners (LON:MANO) (no position)
"There was a very noticeable large rise in trade receivables (over £10mn) over the year to March 2021"
Wasn't this related to the £9.3m case they won back in November 2020, from which:
A
With all the discussion lately on ridiculous changes in company names ( £AMO springs to mind), Vertu Motors (LON:VTU) is one that might actually benefit from it. The PLC name’s a bit stale- even “Click2Drive” could highlight the online offering. Otherwise, I can see the price sitting on a PE of 7/8 for eternity!
Yeah I must admit I agree with this bryans1311 - have been thinking the same lately when comparing them to Cazoo and Motorpoint. If there's an eventual go to place on the internet to buy cars, then I feel their brand names / domains work much better than Vertu Motors or Bristol Street Motors. I hold.
Otherwise, I can see the price sitting on a PE of 7/8 for eternity!
I remember saying that about Dart Group, when it was about 100p per share! It 20 or 30 bagged after that, I think. It's all about patience.
P.
"Could I ask that subscribers please don't copy any content from here onto any other websites. It's subscription content that people are paying for here, so it shouldn't be plastered all over the internet for non-subscribers. Thanks. "
Is it ok to copy it in the notes sections on stocks in my stocko folder? I notice they don't stay there which means it's a lots harder to quickly check points you have made and I want to reference in the future? They are staying in Stockopedia.
Is it ok to copy it in the notes sections on stocks in my stocko folder? I notice they don't stay there which means it's a lots harder to quickly check points you have made and I want to reference in the future? They are staying in Stockopedia.
Of course! Please feel free to copy anything for your personal use, or even to send to a friend, etc. I'm just saying please don't copy Stockopedia content onto free bulletin boards, that's all. :-)
Best wishes, Paul.
Thanks for reporting on the call with Gear4music Holdings (LON:G4M) . Reassured by the comment that they’re not yet looking to have a go at cracking the US market, preferring to focus on growing/adding European satellite hubs. North America has been the graveyard of too many wannabe Napoleons looking to expand too far too soon. When companies set out plans to take on the US I’m always reminded of this Far Side cartoon. ( Boohoo (LON:BOO) exempted, naturally!)
Gus.
Apologies if someone has remarked on this already but Renold (LON:RNO) - a favourite here - seems to have fallen a bit in recent days on delayed results which has potentially spooked the market that the auditors may have spotted something. To me it sounds like maybe a pandemic backlog issue but does anyone else have any reflections? I don't hold - am slightly less enthusiastic about the turnaround compared to others on here as the CEO has been there since 2013 so there should be more signs of the the turnaround working by now in my opinion but everything has a price and I am hovering over the buy button...
It a reasonable size holding for me. Deloitte and the FCA warned of this problem at the start of the pandemic FCA asks companies to delay publishing preliminary announcements | Deloitte UK, however until the formal announcement from Renold (LON:RNO), doubts will remain. I haven't seen many examples of other companies being affected though. A 30% fall from peak suggests the market has reacted, but the longer it goes on, the weaker sentiment will likely be.
Renold (LON:RNO)
To me it sounds like maybe a pandemic backlog issue but does anyone else have any reflections?
Based on the wording they used the announcement seemed reasonably innocent , however you can't beat a bit of probing questioning here if the company and see what the response is as sometimes statements are very carefully worded to be silent on something we would loved to have known.
eg do you have any projected timescales and can you confirm that the delay is specifically purely related to issues with auditors being unable to carry out their workload rather than specific accounting issues or extra workload that should have been expected by the board would require extra time to audit - make em squirm if you are asking the question.
For clarity here is statement and it does not give me anything that i would specifically worry about.
Further to the announcement of 28 May 2021, the Group's auditors, Deloitte LLP, have requested additional time to complete their audit processes. As a consequence, the Company will not publish its results for the year ended 31 March 2021, on 17 June 2021, as previously advised, and will issue further guidance as to the new announcement date in due course
The Board confirms that trading for the year ended 31 March 2021 was in line with its previous expectations and that expectations for the current year are unchanged.
One item i would point out is the more red flags there are the more i would worry - to my cost i still hold PCF (LON:PCF) which had too many minor issues that i ignored - unfortunately the company (reynold) does have history here back in 2019 with accoutning issues - hopefully the cfo from then has gone and you would hope that they have upped their game in the meantime.
As you say the shareprice does seem to be heading more into value territory by the day - just another example (or huge coincidence) of the golden rule that the market really does hate any uncertainty. I would probably rather wait to see how this mop flops before adding i must admit - sometimes though being over cautious (Card Factory (LON:CARD)/Saga (LON:SAGA) spring to mind) can mean one misses out on good gains - particualrly if the next update includes good news ref current trading - its highly likely the results will contain an outlook update so if things are back to normal that boat may have sold by the time the op flops.
Hi PatrickL,
Yes indeed, Renold (LON:RNO) has delayed its accounts twice now, blaming delays to the audit. But both times it has said the figures are in line with expectations.
Personally I don't think there's any point in speculating over this. If it unnerves you, then you have the option to sell some or all (which clearly some people have done). If you're relaxed about it, or prepared to take the risk anyway, then sit tight (which is what I'm doing).
For me, the main risk is if the bank is wobbly on continuing to provide facilities. So I checked the net debt position, and it's come down a lot, and relatively modest, so doesn't look to be any issue with solvency.
I think it's always good, with all positions, to think about the worst case scenario, and how much it would cost if the company went bust. Although you can usually see those situations coming, and get out before the proverbial hits the fan. Also, I usually calculate the cost of a profit warning c.30% drop in share price - would that be tolerable? If the position size is too large, which I'm often guilty of, running a concentrated portfolio, then even a 30% drop looks quite scary!
Assuming there's nothing awful going on, then Renold should be a good stock for economic recovery.
We'll just have to wait and see.
Regards, Paul.
Renold (LON:RNO) is not the only one to have a/cs delayed. Redcentric (LON:RCN) said the same thing last week and, given a major accounts scandal a couple of years ago (PwC were fined £6.5m), this calming piece appeared:
"Peter Brotherton, 53, Redcentric’s chief executive, said that there was nothing untoward and that auditors were simply taking a little longer to complete audits through having to work remotely. He told The Times: “I’m conscious of the fact that with our colourful history you could be thinking, ‘Crikey, what’s happened now?’ But there’s nothing wrong at all, the business is in great shape and the results will be very good.”
I had a look at this yesterday as there was a downward spike in the SP (which quickly recovered). Both RNS state that the request for extra time to publish accounts came from Deloitte (in the first instance specifically naming COVID, the second RNS states "further to" so I read the same reasoning). - Both statements reiterate that trading is in line.
It seemed they were ready to roll with the presentation following results on the 17th until they pulled the plug the day before. They didn't issue another date which suggests to me they don't want to further damage confidence in the market until they are certain they can publish.
Reasons for caution: There were accounting issues in 2019 (pertaining to the years 2017, 2018 & 2019) which are likely weighing on market sentiment to the news.
https://www.investorschronicle.co.uk/tips-ideas/2019/07/10/renold-discloses-accounting-error/ [may need to copy and paste this link]
Reasons for calm: Deloitte have postponed results at other companies
https://news.bloombergtax.com/...
On balance I’ve decided to take the RNS at face value (noting that their statements don’t preclude problems yet to be revealed) and continue to hold.
I bought Renold (LON:RNO) recently, just before the downturn, so I'm hoping that the RNS just now saying that 'Ocorian Limited as trustee for the Renold plc Employee Benefit Trust' going to 3.38% voting rights from 'not applicable' is good news.
Re G4M
Many thanks for the notes Paul. I found the comments from them about which territories are targeted for expansion interesting. If their key expertise is particularly in the adaptation of their website to the needs of different European needs then this makes a lot of sense to me. USA could be a market that is harder to crack.
(I hold)
Morning Paul / everyone,
Thanks for the notes regarding Gear4music Holdings (LON:G4M), confirms to me it's a Coffee Can stock, with a huge runway for growth ahead!
Regards
My morning smallcap tweet: Joules energised
Joules (LON:JOUL) Mercantile Ports & Logistics (LON:MPL) Anexo (LON:ANX) Vertu Motors (LON:VTU) Touchstar (LON:TST) Maestrano (LON:MNO) AFC Energy (LON:AFC) Allied Minds (LON:ALM) BigDish (LON:DISH), Directa Plus (LON:DCTA), 1Spatial (LON:SPA), LSL Property Services (LON:LSL)
Joules (JOUL) guides FY(May) U/L pretax £5.5-6.5m, ahead of forecasts of £5.2-5.3m. Rev up 4% Stores have performed ahead of mgmt expectation since re-opening. Garden Trading has traded ahead of mgmt expectation since acquisition in Feb.
Mercantile Ports & Logistics (MPL) wins 10y port contract. Worth c. £7m in first 3 years. [SP=0.56 Cap=11m]
Anexo (ANX) possible offer of 150p, a 9% premium. DD proceeding. [SP=136.25 Cap=158m]
Vertu Motors (VTU) guides FY adj pretax £28-32m, above current expectations. due to shortage of new cars driving an exceptional wholesale pricing environment for used cars. [SP=45.9 Cap=169m]. I hold.
Touchstar (TST) YTD performance exceeded mgmt exp. "We expect a strong first half performance to, at a minimum, underpin the full year results." Will update guidance in interims in Sept. [SP=78.5 Cap=6m]
Maestrano (MNO) first USA contract, with Union Pacific Railroad. It's "the first of several "Pilot" projects, engineered to demonstrate both the efficient data capture process and rapid Artificial Intelligence analysis of the resulting digital "point clouds"." [SP=12.77 Cap=22m]
AFC Energy (AFC) H1. Expects multiple new system orders in H2. After covid delay, a fuel cell system now on track for dispatch to ACCIONA in Q4 2021. [SP=59 Cap=432m]
Allied Minds (ALM) share buyback up to $3m. [SP=20.4 Cap=49m]
Amala Foods (DISH) £540k loan facility extended to to Q1 2022. "This will enable to the Company to achieve initial commercial traction." They hope. Has used £200k so far. [SP=1.11 Cap=4m]
In line: Directa Plus (LON:DCTA) 1Spatial (LON:SPA) LSL Property Services (LON:LSL)
Good morning Jack and Paul, it'd be great if Jack could have a look at Marlowe (LON:MRL) final results today. Lots of moving parts complicated by many acquisitions but key metrics like margins showing very positive growth especially in their Governance Risk and Compliance segment (up to 32.7% from 27.2%). Run rate healthy with 83% recurring revenues.
Cheers
Francis
Morning Francis,
Jack is looking at Marlowe (LON:MRL) as we speak!
I'm looking at Joules (LON:JOUL) (I hold) and then Vertu Motors (LON:VTU) (I hold).
Regards, Paul.
£vtu trading statement adjusted profit forecast between £28-32 million.
£:ANX, Statement of possible offer by DBAY who from memory already own 25%. Any thoughts Paul and Jack?
Looks like a very cheap opportunistic bid, taking advantage of the fact that the share price has not yet recovered from the effects of the lockdown. Key factors seemingly not yet in the share price include:
1. competitors have gone out of business as a result of the lockdown, given Anexo (LON:ANX) more room for growth
2. very sound finances
3. the VW 'dieselgate' litigation which should give Anexo (LON:ANX) a large one off windfall. This is not (as I understand) in broker's forecasts
If you haven't seen it already, the Yellowstone Advisory hosted investor presentation by management provides a good overview of the business and the bull case for the shares (there is a link in a recent Anexo (LON:ANX) RNS). I have held for a long time and would have expected the share price to double as lockdown eases and the VW case progresses
And sadly, in cases like this with large founder director holdings, low bids like this one can be waved through if the directors see the bid as to their advantage. I am hoping, but not overly confident, that the current major holders hold out for a much higher price or, even better, refuse the bid and reap the rewards of growing the business. DBAY already own 29% and three directors own 67% between them so this bid will succeed if the directors want it. More than likely, the bid would not have been made without prior discussions with the director shareholders which would make this a 'done deal'.
Hi JulianH.
Agree with what you say about Anexo (LON:ANX) , i.e. opportunistic and low ball. Reading the release the comment “While the structure of the possible offer is not yet confirmed, the status of Alan Sellers, Executive Chairman, and Samantha Moss, Managing Director, Bond Turner, as joint offerors to DBAY's possible offer is under consideration.” suggests that although keeping their cards close to their chests, the top two are probably in a concert party with DBAY. With the Chairman and MD compromised it’s hard to see who can reasonably stick up for getting best value for the minority shareholders.
Gus.
Hi FuzzyHaha,
I've had a quick look, and the striking feature is the low premium mooted in this possible bid from DBay for Anexo (LON:ANX) - only about 9%, a long way short of the customary 30%+ for takeover bids.
I see DBay already owns 29%, and the 2 Directors mentioned who might become joint offerors, totals 35%. That's 64% in total, so they can do whatever they want with the company.
So it looks like small shareholders could be about to get your upside removed, for a paltry bid premium. Very unsatisfactory I would say. Not many people hold a share for a maximum upside of 9%.
That said, looking at the StockReport, Anexo looks pretty awful - big profits & low PER, but little cashflow, and only tiny divis. Whereas Redde Northgate (LON:REDD) (I hold) is an absolute cash machine, paying out lovely big divis, year after year. So it beats me why anyone would want to hold Anexo in preference to Redde. Maybe a takeover bid would provide a nice clean exit, for a share that has failed to inspire investors since it floated in 2018.
Regards, Paul.
Thanks Paul,
with hindsight £:REDD would have been a better investment. It was the Dieselgate windfall and ironically the DBAY involvement that helped the investment decision back in February