Small Cap Value Report (Wed 27 Nov 2019) - SOS, SCS, ABDP, OTB, WATR

Good morning, it's Paul here.
Early on, I'll be focusing on the interim results from Sosandar (LON:SOS) (in which I hold a long position). I've got a telecon booked in with mgt early on. I'm expecting to see a big increase in marketing spend, fuelled by the recent £7m placing, and an acceleration in sales growth (after a slowish Spring/Summer season). Seeing as these are already known factors, then the key thing will be the current trading statement. If Autumn/Winter sales are going well, then the recent share price recovery could continue.
Estimated timings - as always, it depends on what newsflow there is. My intention is to start early, and be finished by 3pm. Update at 15:34 - apologies, I nodded off after lunch (trainee pensioner LOL!). Am back at work now, so I'll be finished here by 5pm. Update at 17:00 - today's report is now finished.
On my agenda today;
Sosandar (LON:SOS) - interim results & a quick call with management
SCS (LON:SCS) - AGM trading update
Ab Dynamics (LON:ABDP) - results headline figures look fantastic, so I'll report on this, even though it's moved above my usual upper mkt cap limit
OnTheBeach (OTB) - preliminary results FY 09/2019
Water Intelligence (LON:WATR) - upbeat-sounding trading update
Rejects
Filtronic (LON:FTC) - in line. Not very interesting, so I won't report on this one.
Grafenia (LON:GRA) - only £8m market cap, and headline figures look weak - I'm not convinced this company has a viable business model. Therefore not of interest.
Appreciate (LON:APP) - interim results out today are not very important, as it has a strong H2 trading bias. Trading outlook unchanged, so nothing for me to report on.
Sosandar (LON:SOS)
Share price: 25.75p (up 3% today, at 08:09)
No. shares: 162.9m
Market cap: £41.9m
(at the time of writing, I hold a long position in this share)
Sosandar PLC (AIM: SOS), the online women's fashion brand, is pleased to announce its unaudited results for the six months ended 30 September 2019.
Short results presentation video is here
Preamble - Revised strategy - the business plan at Sosandar changed somewhat earlier this year. Therefore over the summer £7m was raised in a placing at 15p (same as the IPO price, less the 0.1p broker fees). They decided to accelerate growth with a big expansion of product range for Autumn/Winter (roughly doubling of number of styles). This required an increase in headcount (new designers/buyers), plus raised a cash requirement for increased inventories, from new factories.
Given the state of the whole sector (even major UK retailers struggling & at risk of going under), factories are less inclined to offer credit to UK retailers. This point is mentioned again in today's interim results commentary. Over time though, as confidence builds, then factories do extend credit. So it's a bit of a one-off hit to cashflow in this period. Not a problem as there's plenty of cash available.
This is reflected in working capital - e.g. inventories are up from £735k a year ago to £1,920k (essential for producing increased sales in the peak season). Whereas trade creditors have only gone up from £1.0m to £1.2m.
Plus it became apparent that SOS needed to spend a lot more on marketing, to achieve the necessary growth in sales. Put these various issues together, and it was clear that SOS needed a lot more cash than originally planned. This was all explained very well by management, in a series of meetings over the summer, one of which I attended.
Looking at the interim results today, management has done what they told us they would do - bolstering confidence. In particular, the expanded product range has indeed delivered the very challenging growth planned (c.100% Y-on-Y uplilft targeted, which looked very ambitious) for Autumn/Winter.
Sales growth - there was a soft patch in Q1 (Apr-Jun 2019) which caused a big (overdone) sell-off in the shares when it was announced that growth was only 23% on prior year.
The trend of sales growth vs last year since has been excellent;
Q1 (Apr-Jun 2019): +23%
Q2 (Jul-Sep 2019): +84%
Q3 (Oct-Dec 2019):
October - "sales growth well over 100%", over £1m sales (net of returns)
November - "on course to exceed" October.
Incidentally, I recalled that Oct 2018 was the peak sales month last year. Whereas this year, a very strong Oct is set to be exceeded by Nov sales. That's very good news, buried in the detail. I queried this point with management this morning, and James Bowling, CFO, confirmed that my recollection is correct.
Management were confident that they could achieve +100% sales growth in the seasonal peak season of Autumn/Winter, and (so far) they are delivering on this challenging target. With the caveat that it's being achieved by spending considerably more on marketing than originally planned.
Increased costs - We knew that costs would rise considerably (that's why they raised the £7m, to spend it on growing the business). Unfortunately, the nature of the business is that money has to be spent up-front on developing a range of products (it's all bespoke remember, nothing is off the shelf), and attracting new customers through marketing spend. Then the benefit flows through in future.
Administrative expenses have therefore risen from the previous run-rate of about £3m per half year, to £4.3m in H1 of FY 03/2020. This is as expected.
The latest broker note has administrative expenses of £9.2m pencilled in for the full year, so that allows for a further increase to £4.9m in H2. The previous forecast was for £7.7m in administrative expenses this year. Therefore people who comment that the company is only hitting its sales targets by spending a lot more on marketing, are correct.
However, as an investor, what would I prefer? That the company limps along with slower growth, because management are too scared to spend big on marketing? No way. I want to see the business grow as fast as it can, providing the marketing spend is delivering decent results (which it is).
A key point in understanding the business model at Sosandar, and why its strategy makes sense, is that once a customer has been acquired, they tend to be loyal, and return. Therefore the lifetime value of customers is estimated to be very high (there's not enough data yet to put a figure on that).
Broker forecast - the latest forecast (from Oct 2019) shows an operating loss of £3.8m for FY 03/2020. The H1 loss is £2.8m. Management today confirms that they're trading in line with full year expectations, therefore we should see a sharply reduced loss of c.£1.0m in H2, which is seasonally stronger than H1.
Therefore anyone taking the H1 loss, and doubling it for the full year, is not paying attention!
The nice thing about online businesses, is that the main spend is on marketing, and this can be dialled up or down at will. The lead times are only about 1 month. This is a huge advantage over bricks & mortar retailers, whose costs are mainly fixed.
Clearly though, whilst the business remains loss-making, it's a speculative share, and not for widows or orphans.
Valuation - sometimes people say that the market cap of £42m is bonkers for a loss-making company. If you took that approach, you'd have missed many major multi-baggers. Many successful companies are loss-making in their early, start-up stages.
In particular, I think there have only been three pure-play online fashion businesses ever listed on the UK market. 2 out of the 3 (Asos & BooHoo) have been major multi-baggers. They have demonstrated how rapid early stage growth then snowballs. Both looked very expensive all the way up. Indeed, I explained why BOO was not expensive (as many people thought it was) when it was 34p, here in 2015. The same arguments could apply to how we value Sosandar today. Once SOS breaks into profitability, the sky's the limit in terms of valuation, as we saw with both Asos & BOO. That's why people are prepared to pay a premium now, because it looks like the business plan is going to work.
For completeness, the third UK-listed online fashion share, which has been a disaster from day one, is Koovs (LON:KOOV) but that operates in the much more difficult Indian market. There's 5-years worth of negative articles about KOOV from Graham and I, here. It was blindingly obvious that Koovs wasn't making any progress, and it looks close to going bust - although you never know, people have repeatedly bailed it out in the past.
Balance sheet - bolstered by the £7m placing, and a previous £3m top up placing, cash is fine for now. There's £6.9m in net cash, which is plenty for the next couple of years. Management made the right decision to raise more money in one lump, rather than leaving investors permanently fretting about future fundraises.
The house broker forecasts £4.7m cash remaining at 03/2020. That looks a bit too conservative to me, as H2 cash burn is not likely to be £2.2m, which is implied by that figure.
Q&A with management
There's nothing much else of interest in the Sosandar results today, so let's move on to my rather rushed Q&A early this morning with management.
Q1. Celebrity endorsements seem to have dried up compared with last year?
A1. No! (Julie then reeled off a list of celebrities spotted wearing Sosandar) - that's just this week alone - in 2 days! Various publications pick up on celebs wearing Sosandar, and link to Sosandar's website (in return for a small affiliate fee arrangement), which drives sales of those items.
Q2. I've noticed your website has a lot of old lines still on it.
A2. These are end of line, fragmented ranges, which are put on our "Outlet" page, at a discount. They sell quietly in the background, until everything is gone. It may look like a lot of styles, but the actual number of garments is small.
Q3. You mention taking on a lot of new suppliers. How do you manage product quality control with new factories?
A3. Suppliers (factories) are competing for our business, so they make sure the quality is right. Product quality is paramount for us. We approve pre-production & production samples. Plus our buyers visit the factories a lot, to build relationships & inspect goods personally.
Q4. There was previously talk of you selling via third party websites. Any progress on this?
A4. We're getting lots of approaches from websites wanting to sell Sosandar. Talks ongoing.
Q5. What's the payback on marketing spend?
A5. Just over a year. Once a customer has placed their first order, it becomes much easier/cheaper, as we can contact them again via email & product brochures. Expanding the product range improves repeat purchases, as there's more likely to be something of interest. All marketing channels are performing well, and we target the money where we're getting the best return. Lots of sign-ups from TV ads, we send them a brochure immediately. They're hot leads, which convert well into sales.
Q6. How are new product categories performing?
A6. Really well. Denim dresses have been a success, and we're launching our own jeans range in the spring. Hope to have signature designs, which customers buy repeatedly over & over again. Returns rate is lower on denim & accessories. Accessories are being trialled at the moment.
My opinion - I spotted from day 1 that this management team have what it takes to make a success of this. So far, so good. Although it's a fair criticism that the original business plan greatly under-estimated the amount necessary for marketing. Show me a start-up that doesn't greatly under-estimate the costs of scaling up!
How to value it at this stage? That's very difficult. Personally, I'm comfortable with the current price, and am happy to wait for the company to grow into the valuation. Although history with Asos & BooHoo shows us, that once these things really start to motor, in terms of revenue growth & profitability (mind you, Asos has never really made anything much in free cashflow, despite being valued in the £billions), then the valuation is likely to look very expensive. PER is not the right way to value fast-growing, high gross margin businesses.
So if things go well, then we could look back in a few years, and kick ourselves for not seeing the potential in Sosandar at sub-£40m mkt cap.
If things go badly, then the downside case would be that the business needs to keep raising more money, and sales growth slows. There's no sign of that now though, rather the opposite - sales growth is accelerating strongly, and there's plenty of cash.
As I say, not for widows or orphans, but a very interesting little company, with superb management, in my view.
I should add that Stockopedia's algorithms hate this type of loss-making, speculative share. So as expected, they throw a cold bucket of water over SOS bulls (a useful sense check!), as follows;
"Sucker Stock" classification - ouch!
Very low StockRank;
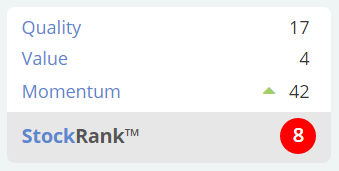
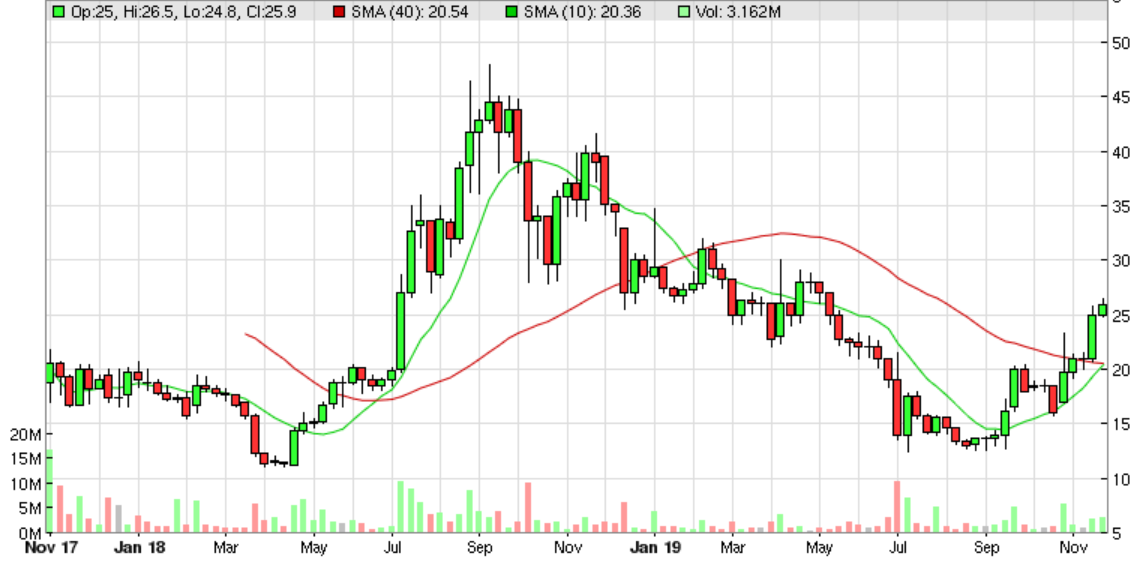
The 2-year chart below is a reminder that this type of difficult-to-value, speculative share, can often be a stomach-churning ride of euphoria on good news, and stomach-churning losses if the newsflow disappoints. So definitely not for the faint-hearted;
SCS (LON:SCS)
Share price: 217p (down c.2% today, at 10:28)
No. shares: 38.0m
Market cap: £82.5m
AGM Statement (trading update)
ScS, one of the UK's largest retailers of upholstered furniture and floorings...
It's not very good, but is in line with expectations;
"It is clear that the ongoing economic and political uncertainties are continuing to impact consumer confidence and spending. However, the Board is pleased to report that the business is trading in line with our expectations.
In the 17 weeks ended 23 November 2019, the like-for-like order intake decreased 7.1% and the two year like-for-like order intake decreased 4.0%.
This is an improvement on the like-for-like trading for the first nine weeks of the year which we reported with our full year results.
Checking back to my notes here on 4 Oct 2019, the last reported order intake was a decrease of 7.6%. Therefore today's updated figure of -7.1% is only marginally better. Same ballpark really. So sales remain resolutely downwards, and a drop of 7% is a significant level, which would have quite a geared effect on the bottom line. Although it's no doubt already factored into the current forecasts, hence why management says it's trading in line with expectations.
Economic outlook- as the bad news is already factored in, then that could result in future good news being good for the share price, perhaps? With full employment, and wages rising well ahead of inflation, I can't help thinking that the outlook for 2020 might be better than many people currently think. Consumer confidence figures have been showing for a while now, that people are reasonably upbeat about their own circumstances, but extremely negative about the general economic outlook.
Everyone talks about Brexit uncertainty - but how much uncertainty really is there? Very little I would say. If you take the time to read the (short) Political Declaration which the UK & EU have agreed, both sides basically want to keep everything pretty much the same as it is now. Many peoples' views on Brexit seem to come from scare stories that they want to believe, rather than from any rational thought, or factual research. It often pays to remember that most human decision-making is emotional. Once I figured that out, life became a lot less perplexing! This is why economic models & predictions never work, because people don't behave rationally much of the time.
Back to ScS.
Valuation - because broker earnings forecasts have been cut, this has pushed the PER up from 7.3 when I last looked at it, to 9.6 today, despite the share price being slightly lower;
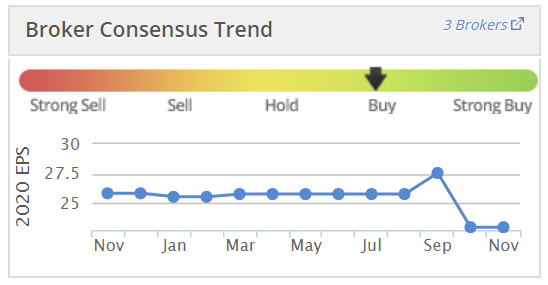
I'm struggling to see why I would want to buy it on a PER of 9.6, when LFL sales are running 7% below last year. The only reason to buy would be if I expected a strong recovery in sales next year.
Dividends - are very generous, but not terribly well covered, at 1.37 times. Another downgrade to profits could raise the spectre of a dividend cut perhaps?
Balance sheet - absolutely excellent, no solvency issues here.
My opinion - probably have to be neutral on this one. If consumers spend more next year, then this share could do well. On the other hand, do I want to bet on that happening? Not especially.
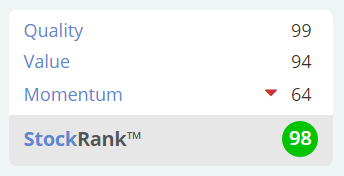
Stockopedia loves it;
Ab Dynamics (LON:ABDP)
Share price: 2615p (down 8% today, at 11:51)
No. shares: 22.4m
Market cap: £585.8m
AB Dynamics plc ("AB Dynamics", the "Company" or the "Group"), the designer, manufacturer and supplier of advanced testing systems and measurement products to the global automotive market, is pleased to announce its final results for the year ended 31 August 2019.
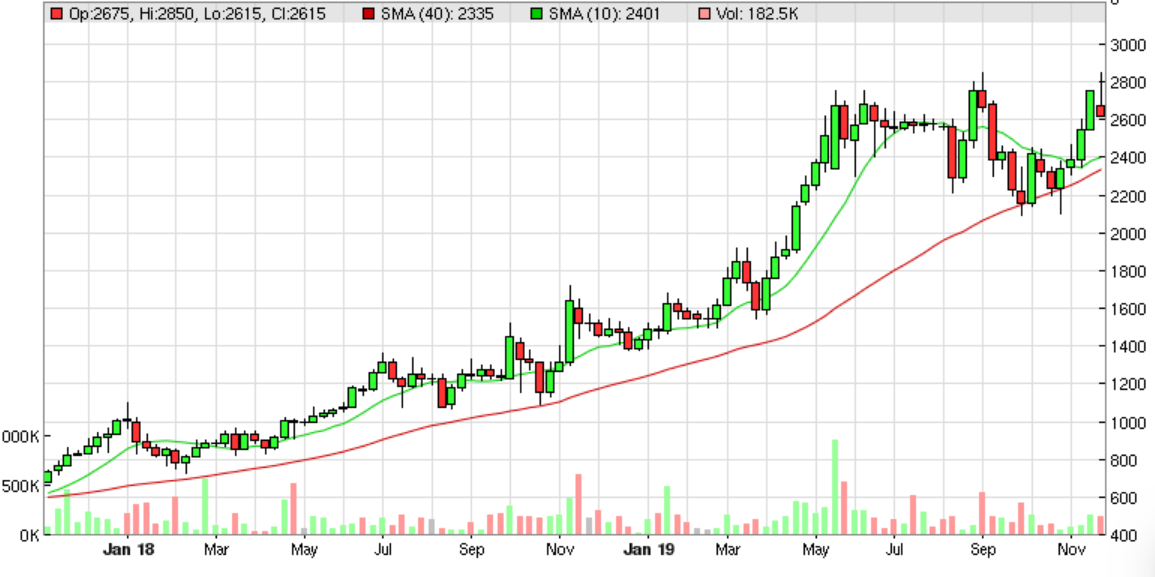
The headline figures caught my eye this morning, as they look outstandingly good. So I was a bit surprised to see the share price down 8% today. Although looking at the chart, it's only giving back some recent gains, and the share price has been trending sideways for the last 6 months, after a terrific run in recent years;
As the highlights show, ABDP has performed very strongly in FY 08/2019;
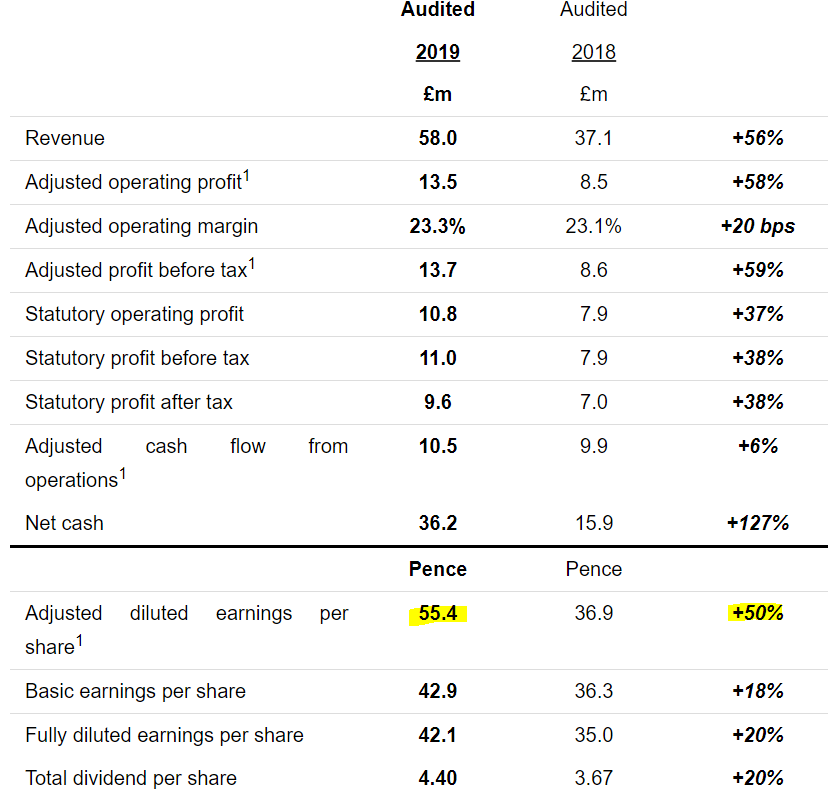
Mind you, a market cap of nearly £600m is incredibly high, for a company that's only delivered adj operating profit of £13.5m on £58m sales - still quite a small business, albeit one with strong growth, and high margins.
If for any reason this level of profitability proved to be unsustainable in future, then this share would see a very dramatic fall. That's the general problem with shares - it's all very well valuing things on a multiple of profits, but how do we know whether profits are going to be sustainable or not? In reality, a lot of it is really just educated guesswork.
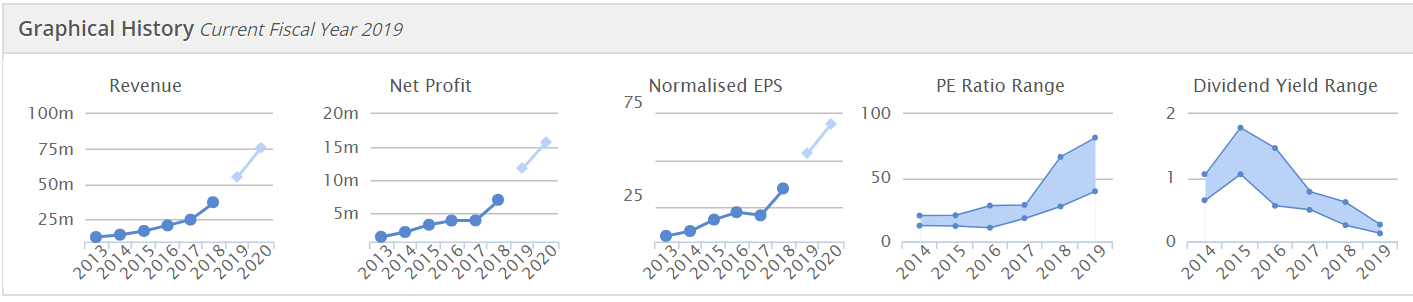
As usual the Stockopedia graphs provide a great summary - namely, a superb track record of revenue & profit growth, but combined with a rapidly increasing rating & reducing divi yield - so the key question here is, are ABDP shares now perhaps over-valued?
Earnings - the 55.4p adj EPS seems to be ahead of broker consensus of 53.9. The PER is 47.2
Forecast for FY 08/2020 is 69.7p EPS, for a PER of 37.5
Acquisitions - when you have very highly rated paper, then issuing more of it, to make acquisitions is an excellent idea;
Following a successful share placing in May 2019, raising net proceeds of £48.2m, acquisition expenditure totalled £35.4m with £18.1m on rFpro and £17.3m on Dynamic Research Inc.
Balance sheet - bulletproof. Although intangibles have shot up from nil, to £41m in the year, this was more than all funded with fresh equity. That has fully preserved the balance sheet strength.
Outlook - sounds positive overall, apart from the last section, which reminds us that the automotive sector is having a tough time at the moment. The comment about constraining margins doesn't help, either;
AB Dynamics operates in long-term growth markets and has established a unique position as a leading designer, manufacturer and supplier of advanced testing and simulation solutions to the automotive industry globally. We continue to invest heavily into new product development that is critical to our future success and it is particularly pleasing therefore to report that we have now received a third order for our advanced Vehicle Driving Simulator ('aVDS'). We expect simulation to play an increasingly important and critical part in the development of semi and fully autonomous vehicles in the future as manufacturers will need to evaluate their vehicles extensively under large numbers of complex scenarios to provide a safe environment for all road users.
As in previous years, we have a healthy order book that provides good forward visibility and will continue to invest in our capabilities and infrastructure which will tend to constrain our margins.
Whilst we remain optimistic about our prospects and the Group's future, we do remain alert to the continued difficulties faced by many of our customers selling into the global automotive market.
My opinion - that's probably as far as I can take this. The company has a superb track record, which is reflected in a high valuation.
What investors need to focus on, is what the outlook is like, and whether earnings growth is likely to continue - because the high valuation of this share very much rests on that being the case.
To pay this sort of lofty valuation, I think investors would need to properly understand the competitive landscape too. Who else is selling this kind of equipment? Are competitors developing similar products which might erode ABDP's margins possibly? Or does ABDP have an unassailable lead that will only get stronger? Without knowing that sort of stuff, I wouldn't want to pay such a high rating. It might be justified, I don't know. Hence overall, due to having limited knowledge, I can only be neutral on this share at the current level.
OnTheBeach (LON:OTB)
Share price: 439p (up c.1% today, at 15:36)
No. shares: 131.2m
Market cap: £576.0m
With over 20% share of online sales in the short haul beach holiday market, we are one of the UK's largest online beach holiday retailers...
The way the headline figures are presented initially confused me, as it looked like a big beat against last year. Then I realised that one column is adjusted numbers, and the other statutory ("GAAP" = generally accepted accounting principles).
There's a £7.7m hit to profit from the recent insolvency of Thomas Cook. The other adjustments are OK, being primarily the reversal of the amortisation charge relating to acquisitions (i.e. what used to be called goodwill amortisation). Practically all analysts & most investors are happy to value companies on adjusted figures, as am I - although it always pays to check the adjustments, just in case something daft has been slipped through as an adjustment. The principle is to value companies on a multiple of earnings that exclude one-offs costs or gains. That makes sense to me.
Adjusted EPS is only up 1% on last year, at 21.4p, for a PER of 20.5 - that seems a tad warm, given that there's not any profit growth to speak of.
Dividends - held at 3.3p per share, yielding only 0.75% - so there's not much earnings growth, and a lousy dividend. So far, not so good.
Outlook comments are interesting, so here's the bulk of that section;
The first quarter of our financial year (calendar Q4) has historically been the quietest trading period for the Group. The failure of TCG has led to a material shift in market dynamics as it had a 20% share of beach holiday passengers and approximately 20% of the seat capacity to beach holiday destinations. This has created a significant short-term lack of seat capacity as well as an unprecedented opportunity in the medium term to gain share.
Search demand has therefore been strong throughout the period following the failure albeit the loss of seat capacity has led to a supply / demand imbalance with a significant increase in flight pricing, particularly for winter 19/20 departures and for travel to Eastern Mediterranean destinations.
The Board strongly believes the correct course of action to ensure that On the Beach is best-positioned to capture market share, is to focus on price competitiveness and to increase the visibility of all of the Group's brands, with the expectation that seat supply will normalise during FY20. Whilst the consumer environment will continue to be challenging, we remain confident in the ability of our resilient and flexible business model to significantly increase our market share in the medium term.
That makes this share a lot more interesting. It's clearly got a really good opportunity to greatly increase market share. Hence why the PER of just over 20 is now starting to make sense. The market is clearly pricing-in increased profit in future years.
Forecast EPS for FY 09/2020 is a big increase in EPS to 26.2p, which would lower the PER to 16.8 - much more palatable. I'm warming to this share as I work through the numbers!
Balance sheet - given that Thomas Cook went bust, it would be wise to check how financially secure all other travel shares are. This one's fine, OTB has a sound balance sheet.
It should be noted that Thomas Cook had a bizarrely over-geared, train wreck of a balance sheet, years before it went bust. The seeds of its demise were sown years in advance, through bad, and ultimately disastrous financial engineering - piling massive debt onto its balance sheet. Internet competition only finished it off, but it was fatally wounded years earlier.
OTB is securely financed, so there are no such problems here.
My opinion - it seems that selling holidays online is very lucrative. I do wonder if the profit margins might come under pressure in the long term?
Overall, I reckon OTB looks quite good. Although if I had to pick one share from this sector, it would be Dart (LON:DTG) - which looks better value than OTB, despite having doubled in price in recent months.
Stockopedia agrees, giving OTB a StockRank of 59, but DTG an almost perfect 97.
Water Intelligence (LON:WATR)
Share price: 275p (up c.2% today, at market close)
No. shares: 16.9m
Market cap: £46.5m
Water Intelligence plc (AIM: WATR.L), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide a trading update through the end of October with respect to a year-to-date sales growth milestone.
Is it just me, or does this update sound a little rampy? Sometimes less is more, and I don't think the company should have issued this update. It's only added 2% to the share price too, so it looks like the law of diminishing returns has kicked in.
The company put out a more detailed Q3 update, saying it was comfortably in line, just a month ago. So why say the same thing again today?
We report that once again we have surpassed the prior full-year revenue result earlier than expected. Through the end of October, we achieved $27.5 million in revenue which stands significantly ahead of the full year 2018 result of $25.5 million. Profit before tax (statutory and adjusted) remains comfortably in-line with expectations for full year 2019.
Outlook comments sound excitable, but tantalise us with the prospect of another possible increase in forecasts?
... While surpassing the sales milestone is important, we seek to finish the year strongly and to set even higher near-term targets than expected...
My opinion - it looks quite a good company, but is very small, mainly based overseas (USA), and doesn't pay divis. I like the profit growth, and strong trading updates, but feel the share price currently looks about right. Therefore I'm neutral.
All done for today, see you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Comparing DTG and OTB is like comparing chalk and cheese. One is a supplier, the other a distributor. One benefits from the demise of a major competitor, the other suffers from a reduction in supply. (a possible benefit to OTB evaporated when Hays Travel bought the TCG shops)
If I was DTG now, I would be playing hard ball on the commission levels I pay OTB - after all OTB are short of flights / holidays available to them having placed a lot of business through TCG - hence the comment about search volumes increasing (which just increases OTB overheads)
Disc: I am long DTG and was short OTB but closed out - think the market gets the benefit to DTG but not sure it sees the full implications for OTB.
Paul, I’ve read the bios of the management team at Sosandar and they look pretty good but can you set out in more detail why you are so impressed? At this stage, a huge part of investing in this share is a bet on the mgmt team so a bit more colour would be appreciated. Thanks.
Paul, I’ve read the bios of the management team at Sosandar and they look pretty good but can you set out in more detail why you are so impressed? At this stage, a huge part of investing in this share is a bet on the mgmt team so a bit more colour would be appreciated. Thanks.
I suppose it hinges on me being a CFO in the fashion retail sector between 1993-2002. You pick up a lot of knowledge when you control the finances of a business, as in any sector, and you just learn what type of people are bullshi#@ers, and which ones know what they're talking about.
Hence I can spot people who know what they're doing in my sector (BOO, NXT, SOS), and avoid clueless idiots (KOOV)
Regards, Paul.
Dear Paul
I am unpressed with the magnanimity of your boss as you seem to be ‘biting the hand that feeds you’ as you have today pointed out a particularly egregious example of the shortcomings in the StockRank score. Sosandar (LON:SOS) receives a low score and is considered investable, whereas Scs (LON:SCS) receives a high score but you effectively consider it to be too risky.
As are rather anxious and newish investor, whilst I understand your reasoning: I am not requesting blind obedience to the Stockopedia Gods, however perhaps an official ‘Stockopedia’ view could also be put forward. This would allow another viewpoint to help understand the share universe in which Stockopedia works and when it does not. Alternatively this criticism of the StockRank system could be used by the developers to place, say, a ‘confidence’ factor in the StockReport.
This is not a plea to change your reporting style - I very much enjoy reading your reports – without your personal view theses would be dull indeed.
Alternatively this criticism of the StockRank system could be used by the developers to place, say, a ‘confidence’ factor in the StockReport.
I think this is a misunderstanding of Stockranks. They're statistical and high ranks will result in some outperformance across a portfolio - but they say nothing about individual stocks, although it's often interesting to analyse why a stock has a particular rank. There is, therefore, no inconsistency at all in Paul taking one view of a stock and the ranks taking another.
So, for example, stocks that have similar attributes to Sosandar (LON:SOS) will on average tend to do badly. Similarly stocks with attributes like those of Scs (LON:SCS) will on average tend to do well. But a specific ranking says nothing about how Scs (LON:SCS) or Sosandar (LON:SOS) will perform in future.
timarr
Hi MrFlabby,
I am unpressed with the magnanimity of your boss as you seem to be ‘biting the hand that feeds you’ as you have today pointed out a particularly egregious example of the shortcomings in the StockRank score...
Sorry, but you've got completely the wrong end of the stick there.
Maybe read up a bit on the StockRank system, to get a better understanding of it?
https://help.stockopedia.com/product-guide/stockranks/the-stockranks
It's a terrific system, which has delivered excellent multi-year results. Quite how you came to your conclusions, is a complete mystery!
Paul.
Re: Victoria (LON:VCP)
They released interim results yesterday. Frankly trying to make sense of its reported P&L gave me a headache, so had a look a look at its cashflow. Its says cashflow has improved, although I note in its cashflow it is adjusting upwards for amortisation of IT software for the period, which would improve comparatives. I always thought amortisation was a non-cash item, so no doubt in my ignorance I have discounted this, and doubt that real cashflow has improved.
I guess it makes sense to put its financing on a longer term footing by way of bond financing, albeit these have been done on worse interest terms than previous Bank debt.
Am I wrong to worry who is holding those bonds? There was no disclosure of this, but I guess it will appear in the notes of the full years accounts in due course.
Hi Trident,
Yes I agree - I started looking at results from Victoria (LON:VCP) yesterday, and rather quickly developed a mild headache, so decided to abandon my analysis.
Does it matter who is holding the bonds? They don't have covenants, so it was a clean issue, not a distressed situation.
I much prefer more secure bond funding, to bank debt. Although even allowing for that, the balance sheet looks stretched to me, with too much debt. I've discussed that with the company, who disagree with me, they think the level of debt is fine, because of the cash generative nature of their businesses.
Regards, Paul.
Prepahps worth mentioning that mid-cap Softcat (LON:SCT) issued a +ve Q1 Trading update today....
"We've performed well during Q1 of our new financial year. Customer numbers and gross profit per customer were both up on the prior period, and we again saw growth across all areas of technology and customer segments. We also successfully opened our new office in Birmingham in September and are excited about the contribution it can make over the long term. While it is still early in our new financial year, I'm confident we will achieve the goals we have set ourselves for 2020."
Under SCS: " If you take the time to read the (short) Political Declaration which the UK & EU have agreed, both sides basically want to keep everything pretty much the same as it is now."
No they don't! Easily shown to be something that's going to be entirely different in practice. Not the place for a Brexit discussion so I will stop here.
Please do however keep the SCV reports coming. All the best.
SCS (LON:SCS)
I completely agree with your analysis Paul.
I was a rather strong holder until recently, when I realised how much a 7% drop in revenue will have on operating profit; by my estimates a decrease from £14m to £7m.
Operating cash flow, less working capital, less CAPEX = £15m in 2018-19
Assuming the 7% drop in revenue continues, this figure could quite rapidly drop to £8m
This would barely cover the dividend payment of c £7m, which therefore looks at risk of being cut.
I remain on the sidelines for now.
Cheers
A
Sosandar (LON:SOS)
I continue to be perplexed by Sosandar (LON:SOS) .
On the one hand there is no denying the stellar growth and margins being achieved. Those alone make a compelling argument to jump in now.
However, there are a few things I continue to struggle with:
There are some big names pointing to the sosandar domain, mainly the tabloids, however, the number 1 website by Page Score (ie the most powerful URL) is clipperlogistics, and the first blog that appears does not seem to be a big name (annelibush.com) and relates to a post from 2017.
I realise that sosandar is relatively small, but I'm struggling to understand where they are getting their online referral traffic from.
Today was the first time that this metric has not been published. I'm always suspicious when figures are omitted; it makes me think that the company are hiding something.
Watching on the sidelines for now.
Cheers
A
Re Appreciate (LON:APP) - I think worth commenting that whilst the trading outlook is unchanged, the RISK around the second half looks reduced. This is valuable to me for a business trying to deliver a significant transformation and modernisation plan.
I see Appreciate (LON:APP) as having delivered on several rather dull executional and strategic milestones this H1 (eg move to new office, revamping & separating Christmas Saving product, getting more, relevant brands signed up for the giftcard business. Also, long flagged new product "Gifti" is getting a soft launch pre-Xmas. Actually, I like this as new concepts often need some refining post launch; better to learn cheap and iterate. Will be ready to push by Q1.
Overall, as Graham has said does not need much to go right to suddenly look a lot better business - with >6% divis whilst we wait.
Not quite sure if Giftli will be a hit product.
It looks like the launch and marketing isn't being handled very well. No domain name registered yet, multiple other products/websites named the same. The sneak peak video on YouTube looks a bit amateurish (overloading emojis into the video is meant to appeal to millenials??).
Despite that, I do like the progress in the main business that Appreciate (LON:APP) has achieved in H1. So hope Giftli doesn't sidetrack too much management attention and resources.
RE Sosandar (LON:SOS) - IMHO Key points are :
Put together, this suggests growing to > £20-30Mn pa should be achievable within a couple of years at which point this will become a very good investment.
We should not need or expect Sosandar to become anything like as big as BooHoo or ASOS to be made very happy because we are taking a lot of risk but getting in the ground floor. I hold but expect to have to hold for another 3 years yet.
Today's profit warning from Stm (LON:STM) (which I hold) has taken 25-30% off the price so far - it's usually fairly illiquid which won't have helped. I'm thinking that this might prove a good entry point, and will think about adding some. Net cash is now a very significant proportion of the market cap. Scores highly on value and badly on momentum. Good quality scores make it a classic contrarian stock.
Purely for the record Simon Thompson of the IC has put this down as a sell today having backed it to date. Crudely new business has been slower than expected and Finncap (you can get their stuff if you register) have modified forward estimates fairly dramatically. You may be aware of this but my view is that in general ST is excellent despite some catty comments.
Some encouraging signs from OnTheBeach (OTB) today after a difficult spell?
Demise of Thomas Cook was a short term negative but they say provides a longer term opportunity with reduced capacity and pricing pressures easing.
And “Failure of TCG provides unprecedented opportunity in medium term to gain market share.”
And already search demand stronger since TCG failure, and also “significant increase in flight pricing.”
The strong finish to 2019 perhaps bodes well, as does renewed appetite for East Med and Turkey, and strengthening early sales for 2020.
.Another plus is the £ strengthening....for now. Not hedging £ proved a mistake . Will they in future?
iirc Boo came to market 10x the cap of SOS and was already profitable - not really realistic to compare the two companies at this stage imo.
Also looking forward to Paul’s update on Sosander’s results. Hope it helps confirm that they are very encouraging.
Recent performance suggests pace is accelerating, with £1 million revenues (POST returns) in October and November set to exceed that.
Also like the bit at the start of the Outlook statement....”extremely confident about future prospects.”.
A slight beef is that they are “on track to meeting Management expectations for the year.,” but so far are tending not to exceed Management expectations as BOO did time and again after that early profits warning. BOO has continued to do that ever since. Perhaps when SOS first do that will be when the share price really accelerates too.
It looks as though it will be a slower journey than it was for BOO, but based on progress so far could be equally rewarding for investors prepared to be patient.
So many these days want instant success and with little interest in seeing an ambitious small Company, with it seems very shrewd Management, progress to becoming a potentially very big and successful online retailer.
I’ve held SOS for a good while and very hopeful it could be as rewarding as BOO in time. Meanwhile as long as newsflow is OK SOS looks a great medium term lockaway and perhaps as big a winner as BOO.
(Thanks for your outstanding updates here on BOO Paul, from when they issued that early profits warning, when I bought and it 8 bagged. AND it proved a mistake selling as fast growth and share price continues).
Morning all,
Looking forward to Paul's comments on Scs (LON:SCS) (glad to hold, I think!). Another of mine, Appreciate (LON:APP) - I think I'm glad to have recently purchased but agree these results are not the key ones and it's a potential recovery situation and a weak hold here!
The other one in my p/f was Pressure Technologies (LON:PRES) where there was a guilty verdict from a jury pursuant to Section 2 of the Health and Safety at Work Act, following a prosecution and trial brought by the HSE following a fatal accident at its subsidiary Chesterfield Special Cylinders June 2015. Financial penalties, according to the company earlier, are "not possible to determine with any certainty". They now seem certain to be levied (there is no mention of any appeal). This is another turnaround situation. SP hit at time of writing is down 13p (13%) to 90p. Hopefully the company has seriously learnt from this tragedy and can then move on.
Luckily for me the Stm (LON:STM) bullit was dodged - price alert triggered this morning - was watching and considering. Am wondering if there's value in this now but Mr Contrarian is right to be sceptical of a long list of excuses!
Have a good day!
Are Versarien becoming investible?
Two results overview videos from piworld today.
1. Sosandar (LON:SOS) H1 results overview to 30th September 2019, by Jt CEO & Founder Julie Lavington and Head of Finance, James Bowling.
Record revenues. 54% margin. Increasing product range with investment in product & marketing.
2. Appreciate (LON:APP) (formerly Park Group, PARK). H1results overview to 30th September 2019.
Ian O’Doherty, CEO outlines what’s been achieved in the period, not least the new name, their move to new offices, the pending launch of a new product, Giftli and more. This illustrates the execution of strategy, and a confidence in the full year.
Appreciate (LON:APP) formerly Park Group (PKG) might be worth a look with their Half Year report out today. This is one Graham has written about in the past and their turnaround strategy may be in the early stages of gaining traction. Revenue increased by 21.3% to £33.2m (H1 2018: £27.4m) and management sound bullish. Their new millennials targeted Giftli product "..the only gift card product with the ability to create a personal story to share with the recipient, reimagining gifting for the digital audience" (no, me neither!) might become a cherry on the pedestrian cake in due course.
My morning smallcap tweet: Nasty pricks puncture STM
STM (LON:STM) Grafenia (LON:GRA) Versarien (LON:VRS), SCS (LON:SCS), Filtronic (LON:FTC), Sosandar (LON:SOS)
STM Group (STM) guides FY rev only £23m, U/L pretax £2.5m. Blames lots of factors: rebranding tte Carey acquisition has taken longer than expected, successful application of the Carey Master Trust to the Regulator took longer than anticipated, weak Pensions new business.... 2020 also hit by slower new product revenue and additional ongoing costs. Never like to see blaming this that and the other.
Grafenia (GRA) a bit of lightness in the PR BS "We're not rushing to do deals, so we can say we've done a deal. No deal is… well, you've heard that before."
Versarien (VRS) yet another Partnership Agreement, to use graphene ink in clothing.
In line: SCS (LON:SCS) Filtronic (LON:FTC) Sosandar (LON:SOS)