Small Cap Value Report (Wed 29 Jan 2020) - GATC, QXT, EMR, PDG, RNWH, SCS

Good morning, it's Paul here with Wednesday's SCVR.
Timings - I should have this finished or nearly finished by 1pm.
EDIT at 12:29 - I've covered most of the more important things for today. I'm taking a lunch break now, will finish off this article by 3pm.
EDIT at 15:46 - today's report is now finished.
More thoughts on China
If you're not interested, just skip this section.
Overnight, the US markets seemed to shrug off worries about the coronavirus. From what I can make out, the attitude seems to be that this crisis will get sorted out, like all previous crises, and it shouldn't affect America. I'm not sure that's sensible. As we're seeing on our TV news, some large Chinese cities are like ghost towns, as people prefer to stay indoors to minimise the risk of becoming infected with a potentially fatal illness - who can blame them?
As I see it, there are two problems for markets. One is potential panic - SARS apparently hit markets by something like 6% to 13%. Although it's difficult to isolate that from other bearish factors going on at the same time - as one reader pointed out, that was the same time as the second Gulf War was building up, which kicked off in Mar 2003. Casting my mind back, I think the build up to the Iraq War was more of a worry for investors than SARS. Also, SARS didn't spread like this new virus is doing now.
Restrictions on travel (especially aviation) in & out of China is bound to affect shares in airlines, cruise ships, etc. Also I note that $SBUX warned last night of an earnings hit from having to temporarily close over half its 4,292 Chinese stores. As the world's second-largest economy, events in China have more impact on the West than when it was a subsistence agricultural economy in the past.
What about supply chains being disrupted? Numerous companies in the UK and USA import parts and finished goods from China. How will production and transportation of those be impacted? How long for? Plus of course, the UK luxury goods are popular in China, so sales of those might fall.
Will markets look through this crisis, and see profit warnings connected with China as being a temporary blip? I'm not sure. In the UK, the market tends to mark down shares quite sharply, even if a profit warning is due to temporary factors. Although as we saw with Joules (LON:JOUL) profit warning recently, a temporary negative (over apparently a one-off internal blunder re managing its inventories) triggered a 30% plunge in price initially, about half of which was recovered quite quickly in subsequent days.
All in all, I'm cautious, and have decided not to open any new small cap positions until we have more clarity. Also, I've shorted the Hong Kong & US indices, as a general hedge. They don't particularly correlate to UK small caps, but the US does set the general direction of markets.
Are US markets expensive?
I've shorted the US market purely as a hedge against possible escalation of the problems globally, and because I think the US is in any case probably overdue a correction (everything feels too bullish).
My shorts on indices hardly ever work, so this comes with a giant, neon-flashing warning sign! As always, I'm just reporting on my opinions, not giving advice.
The problem with a geared small caps portfolio such as mine (or part of my portfolio anyway), is that you can't really move in & out of things. It's too expensive (bid-offer spread), and there's not usually enough liquidity to be able to buy & sell in reasonable size. Hence why, when I get nervous about macro stuff, then shorting an index gives me some comfort. That combined with gradually reducing some position sizes and gearing.
Anyway, I decided to do more digging on the US market overall recently. I'm lucky enough to have access to Stockopedia's international coverage, so find it easy to research US stocks because all the info I need is presented in a familiar format.
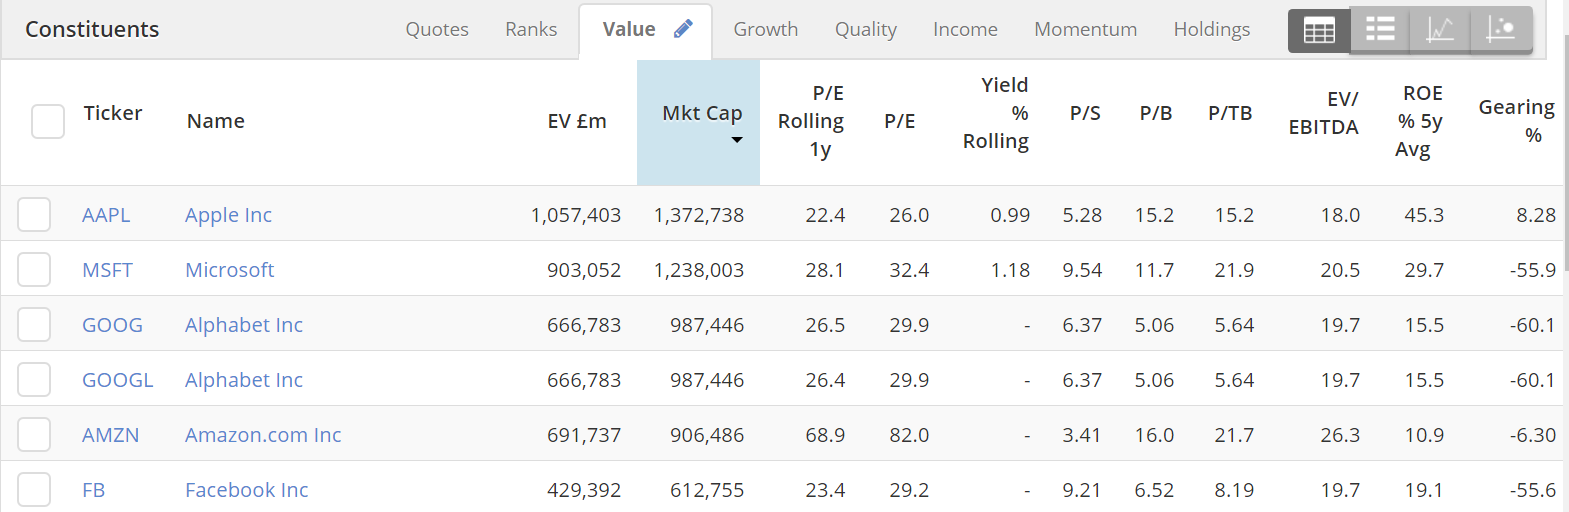
Sorting the S&P 500 in descending order of market cap (biggest first) reveals that the top 5 (ignoring Google being double-counted) most valuable shares are the tech behemoths (see below). Given their dominance, do the forward PERs in the 20s (apart from Amazon, at 68.9) really seem excessive? I don't think so. These outstanding companies with large moats justify high valuations, especially in such a low interest rate environment.
A PER of 25 is an earnings yield of 4.0% - much better than cash in the bank, or treasuries. When that 4% return is being mostly retained within the business, and re-invested on a ROCE of between 11.4% to 27.5% for these 5 companies, then that produces a great long-term return (assuming these companies are not undermined by competitors). Therefore a PER of 25 is not necessarily expensive at all, for a high quality business.
Lots of US stocks buy back their shares too. We've seen in the UK how transformative that can be over the long term, e.g. Next (LON:NXT) enhances its EPS every year with buybacks, and that has had a remarkable long-term benefit for shareholders.
Going back to Starbucks, the StockReport shows avg no shares falling from 1,526m in 2014, to 1,181m now, a drop of nearly 23%. Look at how this has helped the EPS progression;
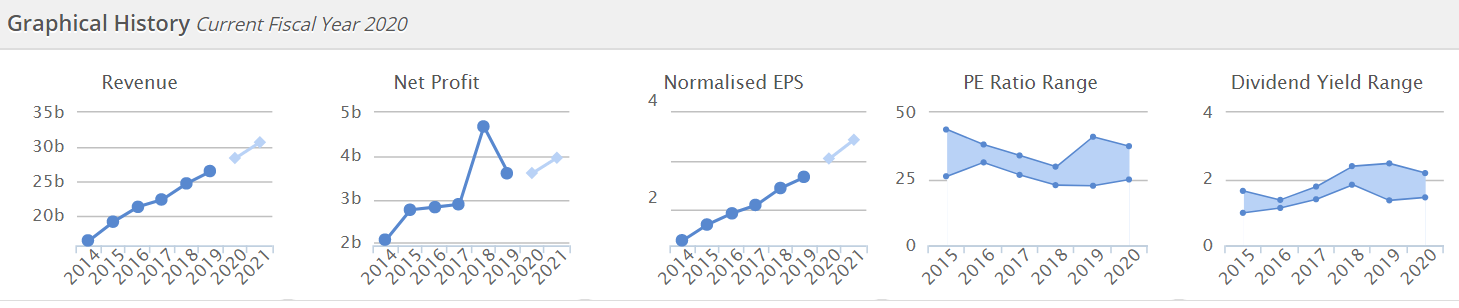
As you can see from graph no.4 above, the PER is always expensive, but justifiably so, as Starbucks is such a remarkable business & brand.
Long-term investors have cleaned up. Whoever said that elephants don't gallop was clearly wrong! They do in the USA. All of this does sometimes make me wonder if I'm wasting my time on UK small caps, and should instead focus on up & coming US stocks? That said, we only need to uncover the occasional nugget of gold in the UK market, to achieve very good overall results.
Maybe a concentrated UK small caps portfolio, combined with some US stocks might work well? Having better liquidity, and a much larger pool of high quality companies, does make the US market seem more attractive. I've dabbled in it before, but never seriously.
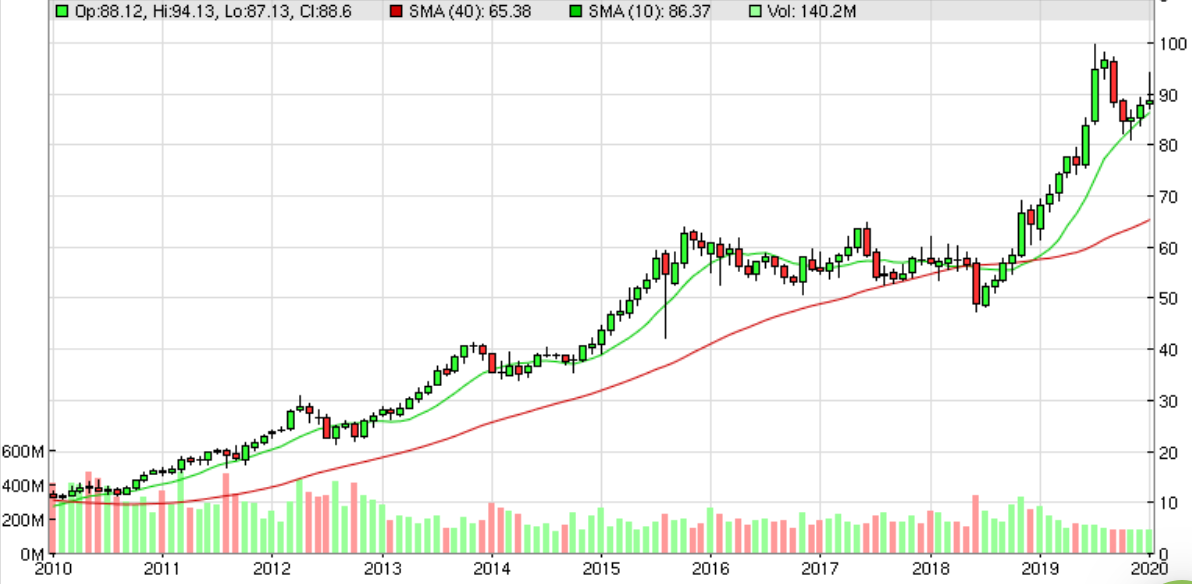
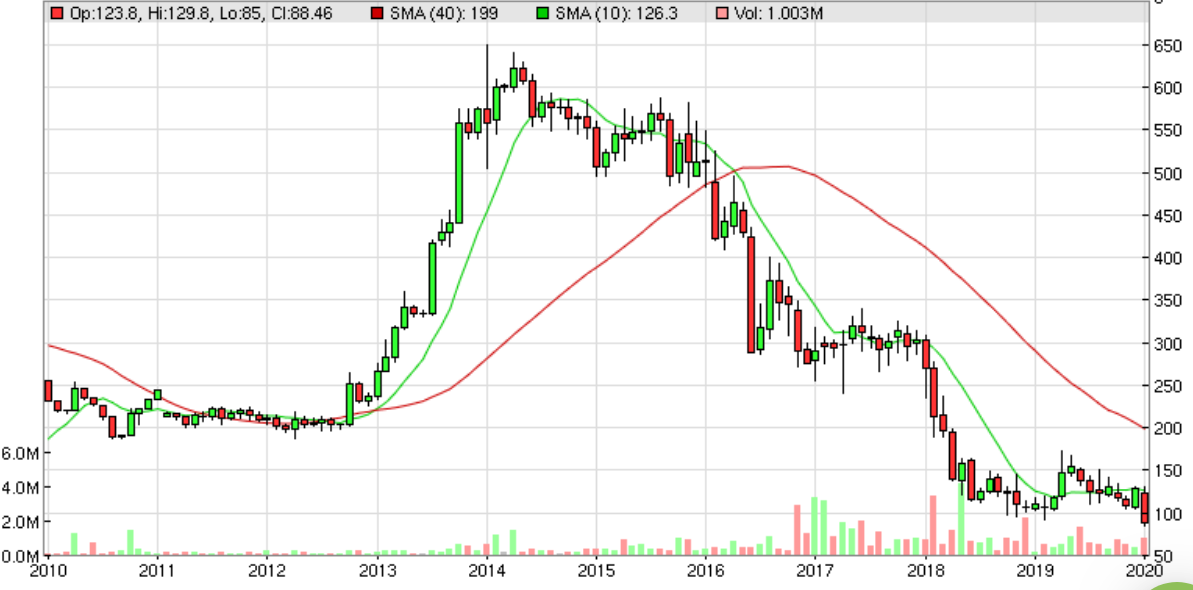
Here's the 10 year chart for Starbucks:
Overall then, whilst I feel we could see a correction in US markets, and they seem far too complacent about coronavirus, I certainly wouldn't bet against the US market for the long-term.
Recession risk is the big risk. We're overdue a recession, and maybe China could be the trigger? Who knows, it's all guesswork really.
The nightmare scenario for me, is that UK small caps drift down on nervousness about China, whilst US large caps storm upwards.
EDIT: I should add that, for long-term, ungeared investors, then none of this really matters. Indeed, falls in share prices for small caps provides a buying opportunity, both in terms of price, and availability of stock for things that can be nigh-on impossible to buy in any size in more normal market conditions.
My SIPP is such a long-term portfolio, and I'm not doing anything with the positions there - they're buy & hold (as reflected in BMUS).
End of Edit.
(sorry for all the typos in the first draft, think I've eliminated them now on an edit)
On to today's news. My initial list of things to look at is;
Gattaca (LON:GATC) - profit warning
Quixant (LON:QXT) - looks like a profit warning
Empresaria (LON:EMR) - same sector, trading update
plus trading updates from;
Pendragon (LON:PDG)
Renew Holdings (LON:RNWH)
SCS (LON:SCS)
Reporting on 5 companies is usually about right, in terms of time & energy.
Gattaca (LON:GATC)
Share price: 90p (down 14% today, at 08:56)
No. shares: 32.3m
Market cap: £29.1m
Trading update (profit warning)
This staffing/recruitment agency often comes up on value screens, but the reason it looks cheap is because it so often disappoints on earnings, turning out not to be cheap after all - that's the general danger with low PER shares. They're usually cheap for a reason. Moreover, turnaround talk from companies is also cheap, but usually doesn't work!
Whilst it is disappointing news, a profit warning, this announcement is perfect in how it is presented. Please would all the brokers & PRs who read these reports, take note - this is how all profit warnings should be presented, it's a model of clarity;
Following a review by the Board of the outlook for the business for its financial year ending 31 July 2020 ("FY20"), it now expects the Company's continuing underlying profit before tax to be approximately £6.0 million, which is below current market expectations*.
* Consensus expectations for underlying PBT are £10.0m.
That's it! Perfect. It tells us everything we need to know. None of this nonsense of having to interpret "broadly", "significantly", "materially", or "substantially", etc etc ad nauseam. Whilst at the same time feeding the house broker the actual figures, and then restricting access to the broker notes, to give an unfair advantage to some investors. That's the bad way to do things. Gattaca is showing the way to do things well.
A hat tip to Gattaca's advisers - Liberum, and Citigate Dewe Rogerson, who no doubt will have helped craft this excellent, model of clarity announcement.
Even though profit expectations have fallen 40% today, the share price is only down 16% at the time of writing (admittedly on low volume). That seems to show that, if the full facts are given, and quantified, then investors don't panic sell. Plus to a certain extent, the bad news was already in the price.
There's a lesson in that for all other companies & advisers who are still putting out opaque, overly complicated trading updates that all too often seem crafted to deceive, rather than inform. I would seriously urge companies to sack your PR advisers, if they are encouraging you to obscure bad news, in cleverly worded announcements. It doesn't work! Investors see through it, and punish the share price even more. Plus, all too often, such ill-advised PR nonsense actually repels investors, because they see the company as being dishonest and don't want to own the shares in future.
It's so refreshing from my point of view, having to plough through and unpick the real meaning of trading updates every weekday, for years now, to find one which is so simple, and so clear. Hence why I'm making such a big deal about this. All advisers need to print off Gattaca's announcement, and pin it to the wall, as a model for how to present trading updates to the market.
What's gone wrong? - a short & clear explanation is given, so a thumbs up here as well from me;
Gattaca experienced a challenging environment across the staffing market, driven by the economic and political climate in the UK for the first five months of FY20 (August to December 2019) which has resulted in net fee income 11% lower than the same period last year.
The market has not recovered as quickly as expected and short-term growth remains uncertain, despite the decisive result in December's General Election.
The timing of UK investment in major infrastructure projects is still not clear and certain manufacturing, automotive and rail sectors continue to be impacted by a lack of confidence. In addition, there is continued uncertainty surrounding IR35.
At least the company is still profitable. The lowered profit forecast of £6m (down from £10m) is still not bad for a company valued at only £29m market cap.
IR35 - I goggled this to see what it's about, and it rings a bell from reports on the TV news. This is what google says;
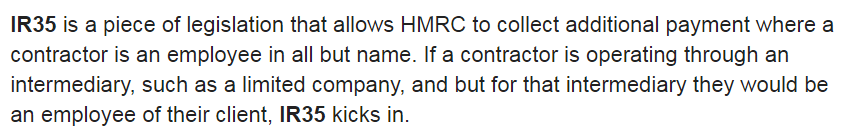
That sounds potentially bad for staffing agencies. I'm no expert on tax matters any more, because it's all become so complicated, and there have been so many changes since my CFO days in the 1990s. That was before the internet, where instead I had to rummage in my paper copy of Tolleys to find answers to tax issues. Does anyone else remember those loose leaf tax guides, where a bundle of update pages arrived by post each month, and had to be manually inserted into a special over-sized lever arch folder! If you mis-filed anything, it was lost forever, hence why I always did the filing myself, instead of delegating it!
I think the tax advantage of classifying someone as a contractor instead of an employee is that the employer avoids employers NICs of 13.8% - a substantial saving. Plus it makes hiring/firing simple, with no tribunal costs, etc. From the contractors point of view, the saving is on employees NICs, which can be avoided by setting the salary from their personal services company a whisker above the lower limit, then paying themselves mainly through dividends (which don't incur NIC). Put that together, and HMRC is losing a ton of money through NIC avoidance. It's amazing they haven't clamped down on it more vigorously before.
Tight labour market - we've also had something of a jobs miracle in the UK in recent years, with very high levels of employment, creating labour shortages in some sectors. This has made some companies more keen to employ directly, in order to retain good people, rather than use temporary staff through an agency. Staffline (LON:STAF) mentioned this point in one of their profit warnings.
My opinion - the sector headwinds look horrible, hence I'm feeling that it's probably best to steer clear altogether.
The forward PER last night, before the profit warning, was only 4.27 - this is usually not value, it's a warning sign that the market has correctly identified that the forecasts are too high, and the company is performing badly.
Note that Gattaca stopped paying dividends in 2018, after years of paying arguably over-generous divis.
Profitability here is dropping like a stone, which makes me wonder if historic levels of profit are ever likely to be recouped? Given the headwinds mentioned above, I suspect probably not.
Recruiters do have the advantage of being able to cut costs, e.g. reducing staff, and paying staff on variable commission linked to fees earned from clients, making it flexible.
Overall, I don't see any appeal to this share. It probably shouldn't be stock market listed, what's the point of a listing now that its heyday is gone, and possibly unlikely to return?
Quixant (LON:QXT)
Share price: 162p (down 21% at 10:36)
No. shares: 66.4m
Market cap: £107.6m
Trading update (profit warning)
Quixant (AIM: QXT), a leading provider of innovative, highly engineered technology products principally for the global gaming and broadcast industries, today provides an update on trading for the year ended 31 December 2019.
Profit warning - well done to the company & its advisers (Alma PR & finncap) for giving us specific revenue & (more importantly) profit figures;
The Board expects to report revenue for the year of $92.3m and adjusted profit before tax of $10.7m.
The majority of the shortfall against expected revenue has been experienced in the Gaming Division which has had a consequential impact on profit.
Unfortunately, they did not include a footnote in the RNS to give us the now defunct market expectations. I'm surprised at this, as another finncap client which reported yesterday, Sopheon (LON:SPE) , included a link to the finncap update note. The good news is that finncap has its own research portal, or everything is in one place on Research Tree, both of which I find incredibly helpful.
Revised figures - finncap reduces profit & EPS for 2019 by 11% - not a disaster, but coming at the end of the year, not great either. It's a 5% revenue miss, hence with operational gearing, the impact is greater on profit. EPS of 13.9p is a PER of 11.7
Rather more concerning, is that the 2020 forecast has come down a lot, by 32% to 15.4p (12/2020 forecast PER of 10.5). That looks cheap, but will the revised numbers be achieved in 2020?
Outlook comments are a mixed bag, but I like the comment about growth in 2021 at the end;
"The previously announced softness in demand from several of our gaming customers has continued for a longer period and been slightly more pronounced than previously anticipated.
This has impacted our financial performance in the Gaming Division over the second half of the year.
We are confident in delivering healthy growth in 2020, however, the recent softness has led to having a more conservative view on the level of growth and we are reviewing costs in line with this lower revenue expectation.
We have initial orders for significant new business which we believe will contribute to sustained growth into 2021.
There is also talk of lower margin products going end-of-life at Densitron, a previously independent listed company which Quixant acquired.
Balance sheet - it claims to have a strong balance sheet, so of course I had to check, as so often such claims are false. In this case I'm happy to confirm that the company is being truthful - it does have a good strong balance sheet,
Net cash is reported today as being $16.2m at 31 Dec 2019, up from $12.4m 6 months earlier. Note that it reports in US dollars.
My opinion - this share looks good value. However, given that it's struggling to maintain profitability, and lowering expectations for the second time in 6 months, then there's a question mark over performance.
Before buying this share, I'd want to understand in detail what makes it tick. It reminds me a bit of Zytronic (LON:ZYT) - which makes good margins on niche products. However, performance is dependent on long-running contracts, and hence customer orders can be lumpy. End of life products are also an issue for ZYT.
Overall, I think it might be worth a closer look, as the valuation is now looking attractive. So this is more of interest to value investors, than growth investors, I would say.
Empresaria (LON:EMR)
Share price: 54p (down 4%, at 11:56)
No. shares: 49.0m
Market cap: £26.5m
Empresaria (AIM: EMR), the global specialist staffing group, today provides a trading update for the financial year ended 31 December 2019 ahead of announcing its full year results on Wednesday 18 March 2020.
Another staffing group, with the distinction from Gattaca above, that Empresaria has a spread of international businesses - very odd for such a tiny market cap company. They seem to operate largely independently. This portfolio approach of operating businesses does however give some protection against regulatory or operational problems in any one country impacting the group too much. It also gives flexibility, Empresaria could potentially sell subsidiaries, if it needed to raise cash, to say reduce gearing in an economic downturn.
Today's update is in line;
The Board confirms that it expects the Group to deliver results in line with current market expectations for the financial year ended 31 December 2019...
Adjusted profit before tax is anticipated to be in line with market expectations at £9.3m (2018: £11.4m)...
Great, well done to Alma PR & Arden, for including the figure of what market expectations are. That saves time, and adds clarity, for people reading the RNS - many thanks!
The adjusted profit figure of £9.3m looks great considering the market cap is only £26.5m, but does exclude (unquantified) restructuring costs.
Given the sector headwinds mentioned before, and some interesting reader comments below, it's difficult to avoid the conclusion that profits here might continue falling.
My opinion - I don't want any exposure to this sector, so even though the share price looks amazingly cheap, I'll give it a miss for now.
Of the 2 recruiters mentioned today, Empresaria would be my preference, if forced to buy one of the two, due to its higher profits, lower earnings multiple, and geographic spread. Although I've never been particularly happy with EMR's balance sheet & debt position. Let's move on.
Shorter sections now, as I've covered the more interesting smaller companies reporting today. For the avoidance of doubt, I try to focus my time on profit warnings, and out-performance announcements. So the biggest price movers, usually. Then whatever is left can have shorter sections, due to time constraints.
Pendragon (LON:PDG)
Share price: 11.3p (down 2% today, at 14:41)
No. shares: 1,396.9m
Market cap: £157.8m
This is for the year ended 31 Dec 2019.
There's something wrong with this car dealers, but I can't remember what it is? Do any readers remember what it might be? Possibly a mis-selling, or some other investigation? Google to the rescue, yes it seems that there is an FCA investigation into Pendragon, and Lookers, about car finance selling. I try not to invest in anything where there is anything like that going on, as it creates unquantifiable risk.
Going through the announcement, I don't really have anything much to add from MrC's snapshot first thing, in the comments section (thanks again for these MrC, they're brilliant!).
Accordingly, the Group's underlying profit before tax for FY19 is expected to be around the bottom end of current expectations. However, the Board remains confident that the improvement in performance during the second-half puts the business on a much stronger footing as we enter 2020.
There's no footnote as to what market expectations are in the RNS. Checking on Stockopedia, it's forecast to be loss-making (post-tax) at -£10.0m for 2019. So a lousy performance, despite the chirpy narrative today about H2 having improved.
Pendragon seems to be taking self-help measures, such as closing 22 under-performing branches, cost control, and better managing inventories.
My opinion - there is a possible case for looking at car dealers as a contrarian value investment. They've been up against some unusual negative factors - e.g. confused Govt policy on diesel that resulted in a sharp fall in sales - buyers might hold off until policy is resolved. There's also electric cars to think about - in terms of pent-up demand, with lots of new models starting to hit the market.
Final point, is that I see consumer confidence being likely to improve strongly in 2020, due to the end of political chaos, and the 6.2% increase to minimum wage coming in April, which is likely to have a domino effect as higher paid employees seek to maintain differentials over low paid colleagues.
If Pendragon can return to previous levels of profits, then the shares now would look extremely cheap. I don't know how likely that is, and the FCA thing worries me, so I'll give it a wide berth for now.
I wonder about sector consolidation presenting opportunities maybe? I've been wondering about that for a while, and nothing has happened yet.
Renew Holdings (LON:RNWH)
Engineering services group - Q1 (Oct-Dec 2019) trading update is in line with expectations. Also;
- Order book up 14% year-on-year, at £651m
- Net debt & cash generation in line with Board's expectations
My view - I was impressed with the P&L performance when reviewing the last full year results here. That article also explained why I don't like the risk here, because it has a worryingly thin balance sheet. That may not matter when it's trading well, but means there's no financial cushion if anything were to go wrong - which it often does in this sector.
So far so good though, management seems to have done a great job in navigating through these risks.
SCS (LON:SCS)
Trading update - 26 weeks to 25 Jan 2020.
In line with expectations. Pleasing to see that LFL sales have returned to growth in the last 9 weeks (peak trading period), at +1.2%. That's tons better than -7.1% decline in LFL sales in first 17 weeks. Which makes me wonder why performance is only in line, and not above expectations? Maybe they had to drop prices (and hence profit margin) to drive sales?
Long-serving CEO has handed in his notice. Sounds amicable, so no particular worry there.
My view - I like this share, and it's on my possible purchases list. It's one of the few retailers that is weathering the storm reasonably well, and is reasonably-priced when you take into account a lovely strong balance sheet.
I imagine improving consumer confidence should enable it to improve performance in 2020. Quite good I think.
All done for today.
Best wishes, Paul,
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Hee hee - loving the red thumbs
SHi Simon
I agree re using Investment Trusts as potential long term holdings, but like to buy them when that Country or region is good value and better still if out of favour as then good chance of buying at a significant discount too.
I usually hold a range of Investment Trusts, but when U.K. value shares, and these were often big dividend payers, got so cheap I mosltly sold my Trust holdings to invest in those instead, along with some of the smaller Companies covered so well here by Paul and Graham., but am beginning to buy Investment a Trusts again.
And yes, warrants and subscription shares were an added Investmeant Trust bonus but sadly there are hardly any left now.
Apologies if other readers are irritated by this being off topic.
No comment on Hargreaves services trading at a significant discount to asset value with a dividend yield scheduled to more than double?
Re Hargreaves Services (LON:HSP)
There are often too many qualifying companies reporting for Paul or Graham to cover them all, so if there are any that specifically interest you then if you can it is worth getting your request in early - together with a snippet such as you have given as to why they might be worth looking at.
I have not looked at them before but a quick scan of the StockReport makes them seem quite interesting.
A few quick thoughts though (on which you may have some insight?) :
I can't cl;aim to have added any real insight there, but those are the things that leap out at me from the StockReport. I am tempted to have a more detailed look at some point, but am rather "time-poor" currently.
Hi Tombholliday,
Hargreaves Services (LON:HSP) is a special situation, so it's not simple to analyse. Therefore it's not practical for me to spend hours trying to interpret it, on top of everything else there was to look at today.
There's a new note from N+1 Singer, which is available on Research Tree, which is your best bet for coverage of this one.
Regards, Paul.
It's nice to see some good economic news for a change.
The flash PMI for the UK points strongly to an improvement in conditions post the election.
Hopefully that bounce will not be derailed by recent events.
Thanks for the comments on China Paul. My portfolio is unleveraged and long term so I am happy to sit out any falls in share prices resulting from the impact of Coronavirus. New pathogenic coronaviruses do of course emerge from time to time, but this one seems to be notable for its infectiousness. One thing I have done is to purchase a medium sized holding in Tristel as I think the huge publicity being generated by this outbreak of coronavirus infections may focus health services' attention on the effectiveness of the company's patented chlorine dioxide technology which kills bacteria and viruses more effectively than many traditional approaches. It is used in some of the company's products used for general disinfection in hospitals, though most sales are for decontaminating instruments. The company's opportunity for international expansion is considerable, although the increasing use of disposable medical devices is a negative. The company is also highly rated so not without risk.
I remember Tolleys. Their Income Tax manual (published manually) had a red and white cove.
Hey Paul,
I just wanted to thank you for the very thorough and high quality analysis you provide us with each day. It has proved invaluable to me. Keep up the good work !
Thanks golfnut, that's really kind! It's my pleasure.
US stock valuations
The bull case is low interest rates drives asset valuations and global growth powers on.
While a PE ratio of 25 - 30 is high that implies an earnings yield of 4% - 3.3% plus you get growth with a tech stock. Compared to low interest rates, these yields seem ok. Also the behaviour of the Fed was clearly demonstrated when the markets swooned on Fed policy simply to let their bond pile run off as they mature, then the Feb u-turned leading to last year's great run up. Then end of last year we had the Repo injection. Ultimately liquidity drives the market and the Fed seems lashed to the wheel. Likewise their soul sister China talks up how they are deleveraging their private debt pile only to release liquidity the minute their numbers look soft. As for ECB and Japan they employ endless versions of QE to hold up their sluggish economies.
Money chases yield so asset values head to the moon. The relationship between liquidity and stock valuations is strong.
As for tech, it's unbelievable how much money they are pouring into R&D. Particularly the Chinese firms Alibaba, Tencent, Ping An have entire towns of tech staff working on their projects. It's pretty remarkable.
The bear case is three parts.
Firstly statistical, such that over a long period of ten years, future returns at these PE rates are very low. Of course the counterargument is interest rates were higher in the past so the discount rate matters.
Secondly, the US needs to deliver earnings growth and there are some signs this is fading. Linked to these points is the yield curve inversion, which we saw a few months back and normally leads a recession by 14-18 months, but it's not a perfect signal.
Finally, eventual debt implosion, while the USA fiscal deficit can (and will be) eventually funded through QE, corporate credit has risen to very high levels at super low yields, including BBB rated and junk. Essentially this is linked to earnings, which must keep growing to prevent a savage derating.
“When the music stops, in terms of liquidity, things will be complicated. But as long as the music is playing, you’ve got to get up and dance. We’re still dancing,”
- Chuck Prince, CEO CitiGroup July 2007 (14 months before the bankruptcy of Lehman Brothers)
I have also tried investing directly in US companies over the years but with limited success. I have added an S&P 500 tracker to my portfolio and plan to add on dips over time (CSP1 from iShares is the product I am using). This also has some correlation with Fundsmith Equity (the only OEIC I own) and Jpmorgan Global Growth & Income (LON:JPGI) - both of which I own for the “plus factor” over and above the index. With large cap US “outsourced” this leaves me free to focus my own research efforts on UK listed small and mid caps (I also mainly outsource UK large caps and Asia).
There are a couple of other interesting US focused ETFs based on sectors/themes that I am monitoring and may buy in the future:
IITU - technology sector but with 50% in top 4 holdings (Apple, Microsoft, Visa and MasterCard)
ICSU - consumer staples sector (defensive)
RBTX - robotics and automation theme
BTEK - biotechnology theme
Other ETFs (and other themes) are available but I’m very comfortable with the iShares products. This area is still a learning curve for me, so absolutely no advice is intended but I thought it might be useful to share some ideas.
Cheers
Simon
Simon
Given your comment and the fact that you are at stocko, so presumably you like factor investing, then if you haven't already you should check out the ishares factor funds. For example ishares world multifactor (FSWD) which is a core holding for me.
Edit: with ETFs, as you probably know, it's important to understand how the underlying index is constructed, so in this case:
https://www.msci.com/documents...
Thank you, I shall take a look
interesting, quite concentrated ETFs. Thanks for posting.
Some obvious absences in IITU, but i guess because some "tech" companies, such as Netflix and Amazon have been reclassified to other sectors recently
To all the posters talking about where to invest:
Look at the main page of gurufocus.com
Then have a quick lie down.
In all seriousness, I do take account of what it tells us.
Sorry, I gave a poor answer.
Go to gurufocus.com
Click on markets.
Then click on global market valuations.
Then lie down.
”Maybe a concentrated UK small caps portfolio, combined with some US stocks might work well? Having better liquidity, and a much larger pool of high quality companies, does make the US market seem more attractive. I've dabbled in it before, but never seriously.”
I have put my toe in the water of the US pool of stocks recently.
I started with £TTD in October 2018 (I still hold though have liquidated 2/3rds of the holding. This still leaves me with more than I invested in the stock).
I took a new position recently in a minnow Paysafe (LON:PAYS) and another under consideration are £RSSS and £SMED both minnows even by UK standards let alone US, where they are completely under the radar. I have done little research beyond understanding what they do.
Excellent commentary Paul on US companies, I wholeheartedly agree ,US have the best businesses in the world,i ask myself numerous times,why put so much time,energy , emotion into something of far less quality with higher risk.I read a stat not so iong ago regarding S&P 500 which has experienced 31yrs of positive returns against 10yrs of negative,of those 10 only four instances produced calendar year losses of 10%,of the 31 twelve years exceeded 20%.
Enjoying the chat re funds. I think investment trusts are a very useful investment vehicle. Main issue with them is ongoing charges.
I expect you have a full agenda already Paul, but I wondered if you could please cover the EBITDA-ahead-expectations Ergomed (LON:ERGO) update?
Revenues are seen in-line, at +26%, with both divisions over 20% growth; however, this seems a slowdown since the interim stage where it was 39%...? Order book is +15%. It seems as though 2019 "benefited from a one-off revenue and EBITDA uplift arising from change orders and project completions", so perhaps in 2020 the growth will be less, albeit helped by their recent acquisition.
The value rating of 7 is a slight turn off.
Coronavirus
I have been informed by a doctor in the NHS that there are just over 100 people being tested in the UK with 20 people being treated.
All treated people are responding well to antibiotics. Majority of cases are northern England and Scotland.
I am not quite sure what to make of it but I was somewhat reassured by the responding well to antibiotics.
This seems unlikely. Antibiotics treat bacterial infections, not viral infections.
Hi vader,
... responding well to antibiotics.
How come? I thought viruses can't be treated with antibiotics?
Regards, Paul.
Coming in a bit late to this thread. Antibiotics won't kill the virus but it is often secondary bacterial infections which kill you eg Pneumonia. This is where the anti biotics provide the relief.
I am a GP and medical director and have been involved in planning for an epidemic here in Israel. Antibiotics are of no use. The good news is that the statistics right now show a mortality rate of 2% unlike SARS which was much higher. In addition, the deaths occurred in older people or people with lung conditions. It is also likely that the real death rate is much lower as I suspect many people will present with very mild symptoms and won’t even be tested....
Thank you danyou. Good to get some information from somebody with knowledge of the matter rather than the BBC who seem to throw reports together depending on the the dramatic effect they will have.
Virtually everybody with severe pneumonia who is seen in the UK by a doctor today will be treated with an antibiotic. There are no reported cases of corona virus in the UK so the fact that the "suspected" cases are responding to antibiotic treatment is not surprising as they probably don't have corona virus.
As a pharmacist i can confirm antibiotics only work against bacterial infections not viral. However they are often prescribed to cure secondary infections. Also the nhs occasionally allows the prescribing of antivirals (Tamiflu) in out breaks eg 2009 swine flu. Perhaps they meant antivirals.
Antibiotics work against bacteria, not viruses.
Antibiotics used to work against bacteria!!!!
Hi Paul
The press like CNBC in the past have talked the fear up of these disease out breaks. Not sure if they just do it just because it is a good story and they have nothing else to say. They don't seem to be doing that this time around, except on their website. Maybe the timing is just not right fopr some people. However, if it spreads to the US there will be some more fear.
There is always Gold. If you are a small bio-pharma company and say you are thinking about working on a cure then that should b e worth a 20% rise in a day. Have you any of those Paul?
I did think that Ch4 news did it well last night! You will just have watch with the sound turned off.
Brief macro points:
- As I've said here before, I agree that the US is better value than we are constantly told. Yes, the FTSE is cheaper, but is it really better value? The valuation of the US hinges on inflation. If inflation surges (as it always used to do in the late stages of market cycles) then the market is toast. Those who believe in mean reversion say that inflation will come back and bite us. My question is: where will it come from? It always used to come from oil. That wont happen today unless there is a middle east war (unlikely - see reaction to Soleimani).
- The US market reaction to any global event always seems parochial from these shores, but in my view it is justifiably parochial. As discussed, the reaction to SARS is difficult to untangle from the Iraq war, but also 3 factors that tend to be forgotten now: (1) we were still conditioned by the deep bear market that started in 2001, (2) valuations hadn't normalised after the market really did get over valued in 2000, and (3) although the US recession of 2001 was officially over, the unemployment rate was still rising, signifying ongoing economic weakness. All of those were more important than SARS. The market started to climb while SARS was breaking out. The market cared little.
- It's a personal choice, but if I was hedging a UK small cap portfolio, I would short the FTSE250, not the US. Oherwise you are exposed to a situation where UK domestic stocks fall, but the US continues to climb, doubling your losses. There are many reasons why that could happen. Also bear in mind that if there was a genuine international crisis, money would flood in to the US, pushing up the dollar. That may have a significant impact depending on how your short is constructed.
Just my thoughts, which can always be wrong.
Spot on!
The median stock in the US is at peak valuation ever. There's no outright bubble valuation but valuation is extraordinarily and uniformly high. Fiscal deficits are high and getting higher. Either they cut spending or they need to monetise the debt with financial repression (ie like they did in the 40s keeping the yield on govt bonds capped at c3%).
IMO the US is going higher (with some volatility) as it will do a Venezuela (but a better version)...create inflationary pressures but keeping real rates low to negative to allow for a slow deleveraging. Its hard to say what that means in currency world as its who's least dirty but making the strong dollar argument is a bit more precarious than it once was. But its unlikely the EU and ECB will be ahead of the curve on developments and so we could see a super strong euro...which Europe partly needs given its resource dependence
"The median stock in the US is at peak valuation ever."
You're right in a limited sense - p/e ratios are at their highest. But to properly value a stock, you need an interest rate and the outlook for US interest rates is probabaly at the lowest and most stable ever. Add in other factors and I disagree with the peak valuation thesis. Valuations are high, but not the highest.
Fiscal deficits don't matter to the valuation, other than in the very, very long term, unless they cause inflation and push up interest rates. See Japan since 1990.
Fiscal deficits are mattering - did you watch last years Big Repo movie?...
And they will matter a helluva a lot if the Fed does really plan to take away its repo support
You happy we have equilibrium?
And the make up of valuation is important. The last great overvaluation was 2000. But that was very narrow. Despite the large fall in indices after that (as TMT and mega caps tanked - the areas that were mega valued) the rest of the market performed well....so general risk appetite stayed robust. There was only hubris clear out on TMT and mega caps.
If you were a chimp restricted to buying smid cap with a value bias you made absolute money 2000-2003 and looked like a genius ...which spawned the massive hedge fund industry as we know it now as anyone can go long smid and short large.
Japan has relevance for China...but very little for the US sadly.
I'm a US bull but the future is not told by past patterns very well unless you back a long time...
John Authers at Bloomberg gives a very measured response to the Coronavirus at http://link.mail.bloombergbusi...
His daily email is well worth signing up to at http://link.mail.bloombergbusi...
Your thoughts on IR35 are spot on. A few of my friends are IT contractors or IT managers, and the story seems to be that companies are cutting back significantly on the direct employment of contractors now.
Good contractors are being offered alternative permanent employment if they want it (but at reduced salaries) others are being let go. It's a major change and affects all industry segments. As I understand it the financial services sector has pretty much stopped using IT contractors altogether. I've heard the same stories for Healthcare and Higher Education.
I assume the work that was being done by contractors will be handled off-shore through consultancy practices (all the well know names PWC, Boston Consultancy etc) or potentially onsite if they can get the staff. The term umbrella company is often use to explain how the tax liability is handled.
This will probably help move jobs away from the south east to other regions in the UK.
All very bad news for the big recruitment agencies.
As an IT contractor, I can confirm that most of the big companies are no longer offering contracts anymore.
Most of the banking permanent offers are not worth remaining for so most people I know are moving to more interesting sectors. The reasons to remain in the big banks was the reward, not the work.
Saying that the recruitment agencies make 10-20% off a temp/contract worker and 40% of the first year's salary of permanent placements and they will work very hard to move people after a year or two to get a new placement fee.
If I was a bank I would ditch the formula 1:4:3 UK/India/Eastern Europe formula as its inaccurate and diverse the talent throughout the UK using specialist firms. Maybe that's a sector to watch.
Paul - can you please comment on TREMOR
Ken, I agree and much prefer ITs over open ended funds. I would also add ETFs into the mix these days as they are cheaper than ITs and generally trade at NAV (I am not a fan of the discount/premium to NAV aspect of investment trusts). Both ITs and ETFs are a great way to gain exposure to elements of the global market without needing to have the knowledge/expertise oneself and without having to worry about the possible redemption issues that might come with some open ended funds.
The two largest providers of ETFs are Vanguard and iShares (Blackrock) and cover most markets and sub indices such as sectors.
Cheers
Simon
Hi Simon.
Agree re ETFs.
Unlike you though I’m a big fan of the opportunity to buy Investment Trust shares at a discount. Even excellent performing Trusts can go to very big discounts during bear markets. Why pay full value for a an Investment Fund if a very similar Investment Trust with the same Manager and holdings is on offer at, say, a 20% discount to NAV? I once bought Geiger Counter Investment Trust at a 50% discount to NAV, luckily just ahead of the uranium sector soaring, and the shares went up 10 fold, and the subscription shares linked to them 60 fold. That was an exceptional one off, but overall Investment Trusts perform better than Investment Funds.
I'd be interested to know more about where one accesses the quantitative data for IT's and ETF's. Stocko only lists quotes. Nothing useful like Stock Ranks etc. Pity. Maybe that information is coming. Appreciate yours and other's time on this.
mercury, TrustNet, Morningstar plus for ETFs Vanguard and iShares have their own sites - none of them are as good as Stockopedia though for quant data. Ed did mention a year or two back that they planned to include IT data on this site at some point - that would be a major enhancement, in my view.
Cheers
Simon
Hi Ken
Apologies, I have only just seen this reply. Of course, you are right, the discount/premium does throw up valuation anomalies (I remember you creating your own niche in warrants and similar valuation anomalies back in the day) but my mindset is to buy forever or certainly for the very long-term. Hence, I am more focused on NAV performance and would like my investment to broadly mirror that.
Both approaches are valid.
Cheers
Simon
Hi Jonno,
London South East platform, which I use (£9.95 per trade) also allows trade on £OCI.
https://www.lse.co.uk/share-trading/
Maybe the sanguine market reaction to coronavirus is because so far the death rate is very low? So though it now looks inevitable that it will spread worldwide, and has already affected more than SARS did, if health effects are short lived and mostly mild it is little different to flu, and at present death rate is lower. But even a hint that coronavirus is getting more severe with death rates rising and market reaction likely to change fast. Travel sector vulnerable?
E.g Carnival who dominate the cruise ship business. Coronavirus could spread like wildfire on a cruise ship packed with more than to 6000 passengers and crew. But big sector falls because of something like coronavirus provide bargain prices. Even the terrible 1918 flu pandemic ended eventually.
Ken
It surprises me that there is evidence that influenza has a higher death rate than this coronavirus. The BBC reports 132 deaths in China from about 6,000 confirmed cases and about 10,000 suspected cases. The death rate from influenza seems to be between1 and 2 per 1,000 depending on the strain each year..
FREng
Happy to be put right if flu is less deadly.
BBC news just now said around 650,000 deaths annually from flu.
One concern not yet getting coverage is the possibility that China is covering up the true Coronovirus death rate. It seems a bit odd if death rate as low as reported that Chinese towns and cities are so deserted, and so much fear about it elsewhere, if getting coronavirus is no worse than mild flu.
A few things from me today.
American large caps - I agree with Paul. Two of my most profitable investments in the last year were Apple and Micron. The formers outperforming results last night were stunning for a $1.5tn company! I had been starting to get twitchy on the sell button having held from around $70 but I think I will hang on and maybe just set a trailing stop a bit above $300.
Tremor International (LON:TRMR) great trading. It may be in-line but almost 30% of its market cap is now cash and yet still trades on a PE of 5! Given its phenomenal cash generation it is likely to be closing in on almost half its market cap in cash over the next year so a cash adjusted PE of circa 2.5. That just feels plain wrong to me so I am long.
Accrol Group (LON:ACRL) we discussed this at the results stage. There was an understandable scepticism towards the results from some based on its history. I felt as though this was missing the point on the turnaround achieved by the new management and the way in which they have addressed the structural issues in the business. Predominantly changing contracts to pass on raw material inflation and re-basing the business to an FX rate around current levels (they will benefit from an increase in the £/$) as well as stripping out a lot of costs. I see a director bought 1m shares at 38p yesterday so clearly management is bullish and I notice the FCA investigation is complete with no action removing any uncertainty there. Note : I am long from 20p for disclosure.
Bonitabeach
No position
Absolutely nothing like Xlmedia (LON:XLM)
Other than being in the same sector of Media it has a completely different business and model.
...and where Tremor International (LON:TRMR) had some overlap with XL Media in the past it has transformed away.
There's either something still really wrong at Tremor...or it'll be double the current price in next 12 months. The past has murk for sure...but what"s the future?
I'm with you on this one Mojo. As we said before, the recent merger and extensive DD conducted on both sides made it unlikely that the assets weren't as they seemed. They paid off debt, which was an obvious thing to do, and bought back shares; all hallmarks of a company with plenty of cash. Anyway, we did well to get shares sub 100p so there's some buffer there. Interesting contrarian one.
I sadly couldn't get all I wanted below 100p but got a decent slug and happy with my 115p ish average price for a full position
XL Media
From their website:
"XLMedia Plc is a market-leading provider of digital marketing services, using proprietary tools and methodologies to generate high-value engagement for our customers."
TREMOR INTERNATIONAL
From their website:
"We deliver relevant audiences at scale with precise targeting capabilities and reengagement tools across the mobile ecosystem."
But please, DYOR.Bonitabeach
you have to do a lot more research than that to understand why the business models are so different.
Hi David,
It's great to meet an enthusiastic holder of TREMOR INTERNATIONAL (LON:TRMR)
You may have the advantage of industry knowledge, I hope you do. I do not, but I do know three more things Tremor has in common with XL Media (LON:XLM)
1.) Israeli Directors2.) Software Driven 3.) AIM Listing - a toxic combination in my book.
There is an awful lot more I could write but you have probably already noticed that at 31/12/2013, before it was floated, trade debtors stood at 57 days sales - not brilliant but acceptable. By 31/12/2018 trade debtors had grown to 94 days sales, and at 30 June 2019 stood at 139 days sales. I am sure there is a perfectly rational explanation.
I wish you luck with your investment.
Bonitabeach
Hi Bonitabeach
I applaud you for your high level snarking.
We will be sure to pay humble homage if you are proved right and kowtow remorsefully to your superior wisdom. It may be necessary as Tremor International (LON:TRMR) is undoubtedly risky with lots of muck to shed and dirt to pack down.
For the moment David and I will take solace in our gain...from muck we have a partly polished something that's approaching 100% up on purchase.
I'll bet you one whole British pound that Tremor will rise more in coming months into the 250-300p 'this might be a real company range'. There's very good reason to look back and hate and the future is never certain. But the future for Tremor seems different from the past its price was locked into.
The high level comparisons you make with XLMedia (LON:XLM) are level 1 persuasive but as we all know to invest successfully in whatever style we must move to level 2 plus at least....and there your points fade to reveal misunderstanding. We can discuss them further if you wish...
However, your warning re quality of company and management are well made and no-one should be in any doubt that Tremor is a speculative stock...moves in the price over the last 18 months both up and down prove that....so people of a delicate disposition and a need for rigid certainties like you shouldn't play. The working capital point is well made but again it is necessary to understand and contextualise what is going on to weigh the risk.
I am known to be wrong at times and to take too much risk in a contrarian style...I don't recommend it to others
Best of luck and lack of hubris with your investments
Your mojo
xxx
Fantastic post on American large caps.The home bias has been a drag on most portfolios Mello hardly mentions stocks outside the island .Concentrating on about 20% of the world market does not make sense .
You and possibly all readers here know this, but just in case not........An easy way around the negative of home bias investing is via Investment Trusts. I use them to invest all round the World, including fast growing Countries like Vietnam.
There are loads of plus points for Investment Trusts over open ended Investment Funds, including the fact that they don’t need to sell their investments when their investors want out. Instead if there is heavy selling (and for other reasons) the share price falls to a big discount to NAV. That’s another plus over Investment Funds, which always trade at NAV, in that £1 worth of assets might be on offer at 70p.
And unlike Investment Funds they can be traded on the market exactly the same as shares. Trustnet is a good site both for Investment Trusts and Investment Trusts. Also Money Observer magazine include an Investment Trust supplement every 3 months, and the latest one is with the magazine currently on sale.
on China. Up Global Sourcing Holdings (LON:UPGS) which was mentioned yesterday, has been dropping the last few days. From 92 to below 80. It sources and imports goods from China. No comment from the company yet. H1 ends Friday.
Up Global Sourcing Holdings (LON:UPGS) financial calendar says the trading update will be issued on Feb 10.
EDIT: They are also presenting at an ED Investor Forum on Feb 5th. I wonder what they can say, just 5 days before their trading update?
My morning smallcap tweet: Gattaca guts holders again
Ergomed (LON:ERGO) Minds Machines (LON:MMX) Pendragon (LON:PDG) Fusion Antibodies (LON:FAB) Oakley Capital Investments (LON:OCI) Plutus Powergen (LON:PPG) Gattaca (LON:GATC) Premier Veterinary (LON:PVG) GYG (LON:GYG) Polarean Imaging (LON:POLX) SCS (LON:SCS) Quixant (LON:QXT), EKF Diagnostics Holdings (LON:EKF), Empiric Student Property (LON:ESP), Renew Holdings (LON:RNWH), Tremor International (LON:TRMR), Empresaria (LON:EMR)
Ergomed (ERGO) guides FY rev in line, adjusted EBITDA ahead of market expectations.
Minds + Machines (MMX) FY trading: co "has experienced a fundamental improvement in topline revenue, revenue mix and cash generation in the year." Is this a beat? Surely would say so if it was. Will pay maiden FY div. Div F/C is 0.
Pendragon (PDG) FY trading: "performance improved significantly during H2, despite challenging market conditions." So a beat then? Er, no. Adj pretax around the bottom end of current expectations.
Fusion Antibodies (FAB) sees FY rev significantly ahead of market expectations but gross margin marginally below. Blames poor newer high margin service sales.
Oakley Capital Investments (OCI) end year NAV 345p/sh, up 9% (inc div) in H2 and 25% YoY. "There have been positive revaluations across the Oakley Funds, driven by continued strong performance from portfolio companies, whose average EBITDA growth was 30%."
Plutus PowerGen (PPG) H1 pretax £116k (-£132k). Confident that directors will provide further loans to keep the lights on. Will they though? "We have to be prepared for tough times ahead and your incumbent directors are determined to ensure that the Company is in a good position to take advantage of opportunities going forward."
Gattaca (GATC) slashes FY U/L pretax-cont guidance to £6m, below current market expectations of £10m. "The market has not recovered as quickly as expected and short-term growth remains uncertain, despite the decisive result in December's General Election. The timing of UK investment in major infrastructure projects is still not clear and certain manufacturing, automotive and rail sectors continue to be impacted by a lack of confidence. In addition, there is continued uncertainty surrounding IR35."
Premier Veterinary (PVG) another loan of £1.1m from a director-owned vehicle. 9% arrangement fee for a 3 month loan! Option to extend by issuing warrants. His exisiting £3.85m loan has payment and interest deferred.
GYG (GYG) sees FY comfortably ahead of previous mgmt expectations. Order book up 31%.
Polarean Imaging (POLX) positive Phase III trail results for its hyperpolarized Xenon Gas for MRI scans.
ScS Group (SCS) trading in line. CEO gives 12 months notice.
Quixant (QXT) guides rev $92.3m, adj pretax $10.7m. "The majority of the shortfall against expected revenue has been experienced in the Gaming Division."
In line: EKF Diagnostics Holdings (LON:EKF) Empiric Student Property (LON:ESP) Renew Holdings (LON:RNWH) Tremor International (LON:TRMR) Empresaria (LON:EMR)
Well done with your excellent reports.
As a cautious investor I have a modest holding in OCI (I wish it were larger). The results have been really impressive I think. Heavy director buying, which is always a good sign and a lead indicator for me.
Hi Greyinvestor
I also have a modest holding in Oakley Capital Investments (LON:OCI), but since it moved to the specialist funds section of the LSE, my platform (Halifax) do not allow me to add to it. Alliance Trust with whom my wife held her ISA also would not allow the purchase of Oakley Capital Investments (LON:OCI) after its move to the Specialist Fund Section. Alliance has since been acquired by Interactive Investor. Do you which platforms Oakley Capital Investments (LON:OCI) can be purchased on? Hargreaves, for example?
All the best
Hi
AVI Global Trust has 8% in Oakley which you may want to consider
I use Interactive investor (having been transferred there from Alliance Trust) and have just checked and it would seem there is no problem with buying Oakley Capital Investments (LON:OCI) on this platform.
A J Bell is happy to trade Oakley Capital Investments (LON:OCI) online - I have just tried a trial purchase.
Saga Share Direct is an online trader (only for over-age 50's!) which allowed me to buy Oakley Capital Investments (LON:OCI).
Good luck
Hargreaves Lansdown seem to offer it on their platform
I have bought OCI in the last 12 months on both A J Bell and HL. I don’t think they’ve blocked it, but there was a hiatus period while OCI filed some new compliance report.
I have a pretty massive holding in AGT, which another poster has pointed out has a major holding in OCI at present.
I had no trouble buying Oakley Capital Investments (LON:OCI) on Selftrade.
Ricardo