Small Cap Value Report (Wed 29 May 2019) - Red Ink, SPSY, XLM, NET, ESYS, Trainline

Good morning!
The RNS feed today is uninspiring, frankly.
To add to the gloom, the market is awash with red ink and is down by 1.3% as I write this.
In particular, I have a holding in British American Tobacco (LON:BATS), which is lower on news that cigarette consumption is reducing at a faster-than-expected rate, mostly because people are switching to alternatives more quickly than anticipated.
But the tobacco sector doesn't explain why the market as a whole is weaker. Mainstream media tries to help us understand the wider malaise:
The blue-chip index took a tumble after the opening bell on Wednesday, falling 0.7 per cent as traders struggled to find anything other than the US-China trade war to focus on.
That doesn't help us much, I'm afraid. Oftentimes, it's not clear why the market is doing what it is doing - the only ones who know are the ones doing the big buying and selling on that day.
Whatever the reason, I've taken advantage of the improved pricing this morning to increase my FTSE exposure, via put options. I haven't got my buying boots on properly yet but I would if we saw the index back around 6500-6600. Might be waiting a while for that!
Here's my latest portfolio breakdown, including cash and the funds in my derivatives account:
- Equities 85%
- Fixed Income 8%
- Cash 4%
- Derivative account 3%
This doesn't tell the whole story, however, as my derivatives trades are leveraged to a significant degree. If I take into account the use of leverage and the underlying exposures, the breakdown looks like this:
- Equities 73%
- Fixed Income 7%
- Cash 3%
- Derivative exposure 17%
Quite a big difference, I think you'll agree!
If you have a spread betting or CFD account, I can't emphasis enough how important it is to understand the notional amount you are betting on. I'm sure most of you already do this, but if anyone out there doesn't do it as a matter of routine, you really should start doing it!
To emphasise the point: if you wouldn't spend £100k on a short-term trade with real money, then it might not be a good idea to do it with borrowed money, either. The losses won't be much smaller for doing it with borrowed money, but they might be a lot quicker.
I'm probably preaching to the converted here, but I just thought I'd mention it on a quiet news day.
As for my own plans: if the market remains around the current levels for the rest of the year, and I never get my juicy buying opportunities, I plan to continue buying small amounts of quality companies at regular intervals, to keep the portfolio around 80%-90% invested in equities.
Today we have a few updates from:
- Spectra Systems (LON:SPSY)
- XLMedia (LON:XLM)
- Netcall (LON:NET)
- Essensys (ESYS)
- Trainline (no ticker)
Spectra Systems (LON:SPSY)
- Share price: 130.5p (+5%)
- No. of shares: 46.5 million
- Market cap: £61 million
FY 2019 guidance gets another upgrade at this mysterious company. It makes machinery and technology for the authentication of banknotes, cigarette boxes, etc.
I've just been having a look at its previous broker profit forecasts.
In March, brokers were guiding for $4 million in FY 2019 and $4.4 million in FY 2020 (on an adjusted pre-tax basis). The broker said their estimates were set "with the usual upgrade potential".
Today, the FY 2019 guidance has indeed been upgraded, from $4 million to $4.4 million. One might almost suspect that an upgrade cycle has been deliberately orchestrated.
The company says the gains have come from "a combination of central bank sensor related research funding and strong first half of the year optical materials sales".
It's too opaque for me, so there seems little point in continuing this analysis.
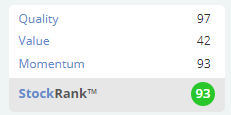
It does enjoy a StockRank of 93, so it ticks a lot of quantitative boxes, and it has been a big winner for investors in recent years. Please note that it is incorporated in the United States.
XLMedia (LON:XLM)
- Share price: 52.75p (+3%)
- No. of shares: 209 million
- Market cap: £110 million
This update is merely in line with expectations, so in normal circumstances I wouldn't bother commenting on it.
However, at a P/E multiple of 5x, these aren't normal circumstances for XLMedia. The market has stopped believing in it, after it had a change of strategy.
It is now focused on publishing, as a website owner, sending its users to gambling companies and financial products.
The non-Executive Chairman says:
As a consequence of the current weakness in the Company's share price and pending approval at today's AGM granting the Company authority to buy shares, we intend to continue the share buyback programme that was initiated in December 2018.
Credit where it is due: XLMedia has reduced its share count from 221 million to 209 million, and is doing the right thing by continuing to buy back shares at these depressed levels.
It's not something I'm going to participate in myself, because I am extremely selective when it comes to foreign companies listed on AIM. The only Israeli stock in my portfolio is 888, a FTSE-350 component, and even that one has been a difficult investment so far.
In summary, this is beyond my risk tolerance, but I acknowledge that the risk:reward could be favourable at current levels. Cash was reported for December 2018 at $47.6 million (the company has been buying back shares since then).
It would be a red flag for me if the buybacks were cancelled or reduced to pursue another acquisition. How could anything be cheaper than its own shares at this level?
Netcall (LON:NET)
- Share price: 51.5p (-9%)
- No. of shares: 143 million
- Market cap: £74 million
I've never looked at this before, but am mentioning it in response to reader comments.
Netcall plc (AIM: NET), the leading provider of Low-code and customer engagement softwaretoday provides an update on trading for the year ending 30 June 2019.
I don't understand what this company does but I might be able to help untangle the RNS a little.
This is a profit warning with product revenues coming in lower than expected. Purchase delays from the NHS and cannibalisation by Netcall's cloud-based products are blamed.
The company is around flat in terms of net debt, with cash almost matching gross debt as of April month-end. We can assume there is an element of window-dressing.
Outlook: "very optimistic".
My view: Not having studied this before, all I can say is that it's clearly very expensive compared to short-term earnings. The latest broker note suggests that the P/E ratio for FY June 2020 is 60x. According to Stockopedia, using last night's numbers, the ValueRank is just 10.
I'm afraid I don't see the sort of rapid top-line growth which would help me to understand this valuation.
Essensys (LON:ESYS)
- Share price: 151p (placing price)
- No. of shares: 48 million
- Market cap: £72.6 million
Admission to trading on AIM and First Day of Dealings
This describes itself as: "the leading provider of mission-critical SaaS platforms and on-demand cloud services to the high growth flexible workspace industry".
In other words, it's hitting three of the absolute hottest themes in the stock market right now:
- SaaS
- Cloud
- Flexible workspace
For context, the loss-making company WeWork has recently signalled an intention to IPO. Its private market valuation has soared to $47 billion.
As the writer at Vox says in relation to WeWork's acquisition spree:
Viewed in one light, what you have is a wildly overvalued real estate leasing company that is flailing around, trying to take advantage of private markets’ excessive enthusiasm for anything tech-related in desperate hope of hitting on something that works.
Well put. Investors are desperate to put money into hi-tech stories right now. And they've also fallen in love with the flexible workspace meme.
According to the admission document, Essensys generated revenues of £9.6 million in the six months ending January 2019, resulting in adjusted net income of £500k. This was before share based payment expenses of £700k.
In the previous financial year, profits of £400k were generated from revenues of £16 million.
Well done to the company and its bankers for achieving a market cap in excess of £70 million and raising £28 million (half of it for the benefit of selling shareholders). I expect that their timing will turn out to have been impeccable.
Trainline (owner of trainline.com) is seeking to raise £75 million and list on the Main Market.
This is "the leading independent rail and coach travel platform selling rail and coach tickets to millions of travellers worldwide, enabling them to seamlessly search, book and manage their journeys all in one place via its highly rated website and mobile app..."
I use this website myself but never realised how international it is - active in 45 countries, apparently. I look forward to learning more about it in due course.
Time's up for now, thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Loving your comment on Essensys Graham that you suspect their timing will turn out to be impeccable, that one actually made me laugh out loud.
Thanks for your general market and company updates as always, always appreciated.
Pete
The theory for buybacks is fine. The 'cancelled' shares, automatically increase the value of all the other shares. But only so long as no value was placed on the cash in the bank.
And it ignores the share price.
As it is, it can be a distortion of the market (and a distortion of the growth rate of EPS). And can be done with that distortion in mind.
With a rising price it magnifies shareholder gain, but with a falling share price it overpays those who have sold.
Personally, I'm not keen. My own experience has been that it handed excess prices to selling shareholders and the company often needed the money down the line.
I'm not keen on upping the dividend either. I believe that should be related to earnings and cash flow: anything else is a distortion.
My preference would be a straightforward distribution. A reverse rights issue would be fine too.
I’m sure they didn’t expect the share to fall to 50p and presumably they also thought buying back would make that unlikely.
I’m not convinced by your wanting XLM to “use the money.”
Surely they didn’t “use the money,” but (admittedly with benefit of hindsight) they wasted it.
That happens so often with buybacks. Hence my bemusement at Graham’s great enthusiasm for them.
Thanks for the reply doublelutz.
Surely the people who no longer wanted to hold and who sold their shares at 90p and others who sold ahead of the big share price falls were the ones rewarded by the XLM buybacks and NOT the loyal shareholders who are now down over 30%?
Or am I missing something?
True, but as I say I guess they didn't expect it to fall to 50p. They probably thought it may be 120p by now. Ory obviously did. They were wrong but had the price gone up it may have looked a good move.
Buybacks are tricky things. Companies that do them are implicitly taking the view that the share price is below 'intrinsic value' and therefore there is a strong temptation to execute the buyback swiftly whilst the anomaly lasts.
All too often though, this does not work out for the best and the largest buybacks seem to be at the highest prices (that's just a perception from the cases I have been involved in).
I don't think the XLMedia (LON:XLM) buybacks have been too bad on this count.
In the two and a bit months prior to the 26th Feb "Profit Warning" they bought back 3.87m shares at probably c. 80p (*), in the subsequent two and a smaller bit months they have bought back 7.86m shares at probably around 56p. So overall they have probably averaged around 63.5p so far.
* - I haven't the level of interest to go through the individual purchases so have based this on the monthly volumes and opening and closing prices (but splitting Feb into before and after)
Obviously the company is not allowed to 'trade' their shares and have to give arms length instructions to their broker, but did they amend that instruction post the profits warning to accelerate purchases (as they would be entitled to do)? Or had they given an algorithm that explicitly bought more at lower prices?
I think the figure of 12k shares bought yesterday as quoted by Ken M is not representative, it is clear that they have bought more at lower prices than they did at higher.
This is not a company that has previously tempted me to research in any detail, but it will be interesting to see if the buybacks accelerate after the AGM; although I should note that they 'only' passed the right to buyback 10% of the shares (same as in the prior year's AGM) which is actually slightly less than their current run-rate of buybacks.
I'm tempted now to do more research here, given that the P:B ratio of 0.81x suggests their could be legs in the buyback continuing (although the P:TB is a less impressive 3.2x.
The potential value of buybacks allowed before the next AGM is barely above 20% of the current cash balance which looks frankly ridiculous, but at the same time makes me highly suspicious of why they are carrying nearly 50% of their market cap in cash (I'm sure if I did a modicum of research this would become obvious).
Graham. Hope you don't mind me questioning your positive views about XLM buybacks.
You say "Credit where it's due ..... with XLM doing the right thing by continuing to buyback at these levels."
And later you wrote "It would be a red flag for me if the buybacks were cancelled or reduced."
Checking out their buybacks since starting the $10 million buyback programme last December, shows that they were then buying back sometimes 100,00 shares a day around 80p and by February 7th at 86p. But that figure and the buyback prices have since steadily reduced, and yesterday with the share at just 49p only 12000 shares were bought back.
Presumably the purpose of these buybacks was to provide support for the share price. Yet since those big early buybacks the share price has fallen by around 30%. And most of their buybacks were NOT at these levels but much higher.
So I find it very hard to be convinced by the argument that their buybacks have been a good thing when most were done way higher than current share price.
Wouldn't shareholders have been better rewarded with a one off special dividend where, unlike with buybacks, they actually GET the money?
And why would ending or reducing their buybacks be a red flag? And if there is a strong case to back up that opinion then the red flag would already be there as buybacks HAVE already reduced.
And why would another acquisition be such a bad idea? Yes if it is a lousy buy, but is it if a quality acquisition at a bargain price?
I've bought the shares today as they look so cheap and unless bad news surely limited downside with their progressive dividend policy?
Current yield is almost 10% and one definite plus for the buybacks is that there are now fewer shares to pay out the dividend.
Another plus is the Stockopedia value (92) and quality (95) marks.
Happy to be corrected if anyone can provide convincing evidence to show that what I've posted here on XLM buybacks is a load of nonsense!
XLM - Obviously, rather than buying back at 80p plus they would have been better off waiting until it fell further. Presumably they didn't expect the price to fall to 50p. Clearly, the main man Ory didn't as he has been buying himself all the way down! Whether he will finish up buying at 30p is anyone's guess!
I probably have a preference for buy backs rather than a special dividend. When I invest in a company, assuming it is something I hope to hold for some time, then the last thing I want is a partial return of cash. I want the company to use the money. If that involves buying back shares off other people who no longer want to hold that to me is good. It may increase my dividends in the future. That is just the way I I look at it anyway. I don't hold XLM. I got out a long time ago. I don't think it is as easy a business as they may have thought at one time.
Volvere (LON:VLE) offering shareholders 1290 a share - spending £16.6M in the process of buying 40% of the co.
Volvere (LON:VLE) appears to be a clear case of management doing the right thing and buying back shares below fair value.
Thanks for the useful intro remarks Graham ..... brightens up a rather dull day.....then off to Kew Gardens for a brilliant exhibition of a Chihuly which might make a good element of an alternative !
Can anyone explain to me the following. I was in conversation with an actuary who claimed by using spread betting he could trade ftse 100 to yield the dividends at no risk. That seems like something for nothing and therefore unbelievable. Anyone got any thoughts on it? Unfortunately a brief conversation which i have been unable to follow up on.
There is no such thing as risk free :)
In spread betting the divi is paid on ex-date (no waiting from ex date to settlement) but the share price opens at a reduced price and by a corresponding amount so there can be no arbitrage there.
I can see how he might sell out of the money call options whilst holding a long spread bet position, known as a covered call. This would enhance the yield, though financing costs would need to be considered. None of this is without risk.
off-topic as such but is anyone having issues logging into HL this morning?
Keep getting errors when trying - 'no_security_credentials' ?
Hi Graham. I think it's arguable that if you're using leverage the percentages in your portfolio should add up to more than 100% - i.e. you're effectively investing more money than you've got.
Yep, that's another way of looking at it. Fair point.
Thank you for your comments Graham. I tend to avoid gearing altogether, so i don't get the excitement of huge gains but i do get to sleep at night. That said i tend to run a concentrated portfolio with some fairly big bets. I was always influenced by Jim Rogers who said in an interview if you want to make money you have to take risk. It really depends how you define that risk and your appetite for it.
A view on Netcall,please ?
Hi Alan, I've taken a brief look at Netcall (LON:NET). G
Re Proposed Non-Standard Finance (LON:NSF) takeover of Provident Financial (LON:PFG) - Matter finally goes into formal CMA Stage 1 40-day review today. Key issue is whether the proposed post takeover remedy of the the Loans@Home subsidiary demerger is a 'clear cut remedy' in the Home Credit market, given Provident's strength in this highly regulated sector.
As an NSF holder, I believe in the deal takeover from a a commercial perspective since I think that the combination of PFG's Vanquis Bank with EveryDay Loans branch network would be very powerful and TrustTwo/George Banco would provide a very effective competitor to Amigo in Guaranteed loans.
Sadly, this 'industrial logic' is being lost in a hugely expensive and personal Boardroom battle in which strategy is playing second fiddle to egos. However, if Woodford/Invesco/Marathon, who own over 50% of Provident Financial (LON:PFG) keep their nerve the deal will certainly pass shareholders. However, now a risk if the CMA or other regulatory body get involved.
So far the value of BOTH NSF and PFG has gone down sharply since the bid was made. Just like Brexit, this just needs sorting one way or the other!
xlm even though they are reshaping they are making plenty of money doing and making all the right moves in the stock market , they are worth 85-100 all day long
XLMedia (LON:XLM)
I guess the proof of the pudding is them continuing to churn out decent profits through the period where the share price is ridiculously low. I have looked at this share but can't make out how sustainable their earnings are or will be , and also the visibility on future earnings income doesn't appear to be great. They also appear to be changing tack business wise and branching into slightly different areas - this suggests what has been the easy cash cow profits wise in the past will not be in the future. So with the uncertainty that appears to be present perhaps the share price is at the right level. There is the added gambling regulation unknowns too that probably don't help.
I guess the lack of bad news today is good news though - my main fear with this company was that the sharp notified drop in turnover not so long back would be followed by further drip feed of bad news going forward the lack of this bad news is definitely a positive in my books - although i was highly sceptical about this share being a bargain when i first looked and am still thinking the market knows more than me with this company.
XLMedia (LON:XLM) AGM statement - trading in line (with management expectation) - restate commitment to progressive div policy and the share buyback, referencing the cash pile. They "continue to evaluate selective publishing acquisition opportunities".
Frustration clearly oozes from this statement. I share their frustration.
9.4% yield this year, 10.4% (f) 2020.
It looks as if XLM may have reached the bottom although it is a bit disconcerting that the share buy backs had little effect in stemming the substantial fall. I think it is just that anything associated with gambling is not necessarily the most popular place to be in at present. Although if you like a gamble yourself then a buy with such a potential yield could turn out to be a very good one! If buying myself I would keep in mind a stop loss of just below 50p and hope that it goes on an upward trajectory from here.
Video: Stobart (LON:STOB) FY results overview by Warwick Brady, CEO
https://www.piworld.co.uk/2019/05/29/stobart-group-stob-full-year-results-may-2019/
Highlights, with a brief overview of each division.
My morning smallcap tweet: Spectra shines again
Netcall (LON:NET), Spectra Systems (LON:SPSY)
Netcall (NET) warns FY adj EBITDA only £3.4m due to delays in NHS product orders plus public sector customers ordering the newly launched Low-code cloud offerings.
Spectra Systems (SPSY) expects FY profit to exceed market expectations. That's so many in a row I can't remember.