Small Cap Value Report (Wed 30 Jan 2019) - CAS, SAL, AUK, CALL, BEG, YU., BOTB, TAP/RTHM, STAF

Good morning!
There is plenty of juicy news for us to digest today.
- Crusader Resources (LON:CAS)
- Spaceandpeople (LON:SAL)
- Aukett Swanke (LON:AUK)
- Cloudcall (LON:CALL)
- Begbies Traynor (LON:BEG)
- Yu (LON:YU.)
- Best Of The Best (LON:BOTB)
- Taptica International (LON:TAP)
Crusader Resources (LON:CAS) - this little gold exploration company is seeking to cancel its AIM admission. It was listed only in April 2018, and was suspended as soon as October.
Is this a record in terms of speed to failure? It's a shame that this kind of junk is still floating around.
Spaceandpeople (LON:SAL)
- Share price: 16p (unch.)
- No. of shares: 19.5 million
- Market cap: £3 million
Significant Property Opportunity
Spaceandpeople had a trading update only yesterday, but is back again with another update. It has commenced a tie-up with Hammerson (LON:HMSO) to provide retail experiences and (on an exclusive basis) its "Mobile Promotions Kiosks" at Hammerson properties.
No numbers are given - all we know is that it's a multi-year contract. The company has made plenty of announcements like this before. While it's hardly bad news, my assumption is that this announcement does not mean a dramatic change in the company's fortunes.
Aukett Swanke (LON:AUK)
- Share price: 0.95p (-27%)
- No. of shares: 165 million
- Market cap: £1.5million
Another stock that is deep in "why are you even listed?" territory.
You might equally be asking "why are you even writing about it?"
This is a stock where I lost a significant amount of money, having been attracted by a superficially cheap valuation several years ago. I learned several lessons from it, so I'm intrigued to see the eventual fate of the company.
It turns out that FY 2018 results from this architectural group are a disaster and yet they could have been even worse, if the company's management of its costs and its cash balance had not saved it.
- Revenue is down by another 22% to £14.4 million. It is down by over 30% in two years.
- The total loss is £2.5 million.
- Net cash was £157k at September 2018, but the company acknowledges that it used its overdraft throughout the year.
Outlook - expecting a better outcome and "a positive result" in 2019, but cautious.
My view
The numbers now look very frightening to me.
- Balance sheet equity reduces from £6.6 million to £4.2 million. Tangible equity reduces from £3.3 million to £1.2 million.
- Receivables turnover is only 2x, implying that it took Aukett about six months to get paid on average. This figure has deteriorated since last year. Massive receivables book of £6 million.
- As has been pointed out by a bear over on the LSE board, the company's cash balance for September 2018 adds up to 3 days' worth of last year's expenses.
The travesty is that everything was made worse by a poorly-timed expansion. Aukett spent a couple of million pounds (more than its current market cap) buying up practises in the UAE in 2015/2016.
Its Middle East segment has produced a £1.2 million loss in 2018, adding insult to injury. All of the cash that has been burned in the Middle East could have been returned to shareholders or used to shore up the core UK operations.
Also worth noting that the CFO handed in her resignation in September. There is no sign yet that a successor has been found.
While a turnaround is still possible, I'm glad I'm not betting on it. I took a painful loss but at a share price that was still multiples of the current level. Unless things change very soon, it looks like this company is going to run out of road, at least as far as existing equity holders are concerned.
If you want to know why I'm now allergic to professional services companies, particularly those with an acquisition-led growth strategy, this company is a good place to start!
Cloudcall (LON:CALL)
- Share price: 113.5p (+3.7%)
- No. of shares: 24 million
- Market cap: £27 million
Paul covered this recently, when he attended Cloudcall's Capital Markets Day.
Cloudcall is a software business that provides a solution to integrate telephone systems with a client's CRM (customer relationship management) software.
The company has never made a profit and is set to remain unprofitable until at least 2020, according to official forecasts. And the StockRank is a meagre 6, i.e. it is a Sucker Stock. It qualifies for two short-selling screens and has seen its share count rise again and again over the years, with another increase today.
There is nothing wrong with investing in early-stage and unprofitable companies, so long as you do enough due diligence to convince yourself that it can overcome the inherent statistical unlikelihood of success (like Paul has, in this case).
This isn't the type of thing I'd invest in, because I have no idea if the Cloudcall solution is better than the alternatives. For example, if I type "integrate telephony CRM" into Google, there are a lot of products which claim to do this.
Bullhorn, which is Cloudcall's key CRM partner, also partners with and promotes three other telephony integrations. Why would we want to invest in Cloudcall, rather than one of the other integrations? That's the sort of question I'd be asking, if I was researching this in further detail.
Begbies Traynor (LON:BEG)
- Share price: 58.6p (+0.7%)
- No. of shares: 110 million
- Market cap: £65 million
Latest Red Flag Alert Report for Q4 2018
This insolvency practitioner updates with the latest insolvency statistics:
- The number of businesses in "significant" financial distress increases 3% quarter-on-quarter to 481,000
- "Real estate and Property" is the hardest hit sector, up 7% quarter-on-quarter.
- Retail gets away lightly, only up 2% quarter-on-quarter.
- Begbies describes Q4 as a "winter of discontent".
Interesting theory on the retail sector:
While the number of retailers in significant distress only increased slowly year on year since Q4 2017, we expect that this is due to heavy discounting giving retailers more cash and delaying their entry into danger. The industry should be braced for a tough start to 2019.
They specifically mention Next (LON:NXT) (in which I have a long position) as an example of a retailer with quality product and a good online and offline offering, meaning that it can thrive even though overall conditions are difficult.
Doesn't it feel like the great rebalancing of the economy has yet to occur? I suspect there is still scope for a windfall of business to come in the direction of Begbies in the next few years. Its revenues are still significantly below the peak of 2009-2011.
Yu (LON:YU.)
- Share price: 155p (+130%)
- No. of shares: 16 million
- Market cap: £25 million
Trading Update and Change of Auditor
Hot on the heels of yesterday's update from Utilitywise (LON:UTW) is an update from Yu Group.
- guidance for the adjusted pre-tax loss in 2018 is unchanged at £7.35 - £7.85 million, on revenues of £80 million
- contracted revenue of £85 million for 2019
- net cash £14.6 million
- new auditors hired after the scandal which revealed its accounts to be misleading
CEO comment
Whilst we are being more selective and prudent in relation to our growth, we are securing new business at a reasonable margin. With a strong balance sheet and a focussed and dedicated workforce, I remain confident in the underlying business....
My view
I would treat this with a lot of caution. SME energy supply is a problematic sector and we still don't have a very good picture of what happened in terms of the misstatement of this company's accounts. We do know that it was unprofitable in 2018, to an extent that completely wipes out the small profit it made in 2017.
Even if it does manage to get back on track, it going to grow at a much slower pace than was previously forecast.
There is a case to be made that this was already in the price when it was trading at a discount to net cash - that is an understandable point of view. But it is now trading at a significant premium to cash.
Checking the bulletin boards and social media, I see that the stock has caught the attention of what seems to be hundreds of people. The combination of an optimistic update and a very limited free float (less than 50% of shares) has helped to more than double the share price today.
Nice quick gains if you can get it! But I would not be hanging around for the after-party.
Best Of The Best (LON:BOTB)
- Share price: 305p (+39%)
- No. of shares: 10 million
- Market cap: £31 million
A nice clear company description at the top of this report:
Best of the Best plc runs competitions online to win cars and other prizes.
There is one remaining physical location - at Birmingham airport.
Indeed, I made a point of allowing myself to be approached by one of the salesmen at this site when I was there after Mello Derby last year.
The car looked great but the salesman's lines were rather uninspiring and canned. I guess they were pretty much what you would expect when someone is standing there all day trying to get strangers to buy raffle tickets. I wouldn't want his job!
The company is still focused on cars through its online channels and you can see the list of stunning cars up for grabs on its website.
Great H1 results:
- revenues +28.5% to £7.1 million
- adjusted PBT +14.7% to £1.1 million
The company appears to have cracked the online marketing problem - no easy task. Congratulations are due.
There was also exceptional income of £2.5 million (£4.5 million in, £2 milllion out) arising from tax issues. Great news.
Staying on the issue of tax, the company's margins will be under some pressure as remote gaming duty (RGD) will increase from 15% to 21% on its "Spot the Ball" competition:
This will directly impact our operating margins going forward and represents a significantly increased tax burden, when combined with material sums of irrecoverable VAT on our cost base that we are also now absorbing.
Outlook - confident. Will try to mitigate the RGD problem.
Tender offer - a weird tender offer is announced at 485p. Why not buy back shares at the current share price? This is the official explanation:
In determining the level of return of value, the Board has taken into consideration its aim of improving the Company's earnings per share, as well as targeting a more efficient capital structure through returning excess balance sheet cash to Shareholders.
A tender offer at the current share price would boost EPS even more (since it would reduce the share count more) while returning the same amount of cash to shareholders. So this explanation doesn't tell me why they choose to execute the offer at 485p.
I'm worried it might have something to do with the possibility that some shareholders might fail to send their instructions in time. To the extent that anyone fails to send their instructions, those who do send their instructions will be able to sell more shares at the ridiculous price of 485p. This will mean a wealth transfer from those who don't send their instructions, to those who do.
I'd like to think that the explanation is more benign than this, and of course I presume that it is, but I can't think of anything else right now. Nothing can surprise me on AIM after the recent shenanigans at Thalassa Holdings (LON:THAL).
BOTB's free float is very small (only 17% according to Stocko) and the shares are horribly illiquid. Taking more stock out of the market is only going to make this worse. So I would tread carefully, even if the underlying business is performing very well.
Taptica International (LON:TAP)
- Share price: 192.5p (+15%)
- No. of shares: 68.5 million
- Market cap: £132 million
We get clarity today on the deal which caused Taptica to suspend its share buyback: it is thinking about joining forces with RhythmOne (LON:RTHM).
RhythmOne is another AIM stock that has had more than its fair share of controversy over the years. It's a US-based video/online advertising company and was previously known as Blinkx, back when a Harvard professor made serious allegations against it.
RhythmOne has been talking about doing a share buyback of its own for years, but hasn't got around to doing one yet. Not doing buybacks is something that Taptica and RhythmOne have in common!
At its most recent H1 results, RhythmOne said that its Board had at last approved a $10 million buyback, but they've since been distracted by the Taptica talks.
From a Taptica point of view, it is telling its shareholders that their company has a similar value to RhythmOne: after the merger, they would be left with 50.1% of the combined entity.
Despite producing annual losses since 2015, RhythmOne is officially forecast to generate $42.5 million of pre-tax income in 2019, and so is allegedly trading at a P/E ratio of 4x.
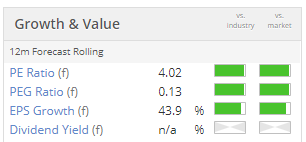
It's a unique situation: two companies trading at a P/E ratio of 4x are trying to merge, when they could be buying back their own shares right now instead. Or they could be buying each other's shares. Either way, they could be using their cash to exploit the extreme undervalution, but they prefer not to, for now.
Ever since the controversy back in 2014/2015, I have viewed RhythmOne catiously. A potential merger with Taptica, where I am also very cautious, and in these circumstances when both of their shares prices are at silly levels, makes me doubly cautious. I could be wrong, but the bad smell surrounding Taptica appears to be getting worse. Good luck to anyone who is involved - I fear that you might need it.
Staffline (LON:STAF)
- Share price: 670p (-33%, suspended)
- No. of shares: 28 million
- Market cap: £187 million
Delay to publication of results
Suspension - Staffline Group plc
This recruitment group announced first thing that the publication of its results would be delayed, offering no reason why and prompting a huge slide in the share price as shareholders wondered what on earth was going on.
Then at 3:50pm, the shares were suspended, "pending an announcement".
There is hardly any point in ringing the Nomad at this point. Hopefully we get some information tomorrow morning.
A shame that there weren't many good companies reporting today, but it can't be helped.
If today's report demonstrates anything, I guess it's the extreme danger that is so often associated with small-cap investing.
Paul will be with you tomorrow.
Safe travels,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Graham - to take a slightly more contrarian view on Taptica International (LON:TAP) and RhythmOne (LON:RTHM)....
Mathematically if you put two companies together currently trading on a PE of 4 you have one larger company trading on a PE of 4. If they achieve the same levels of revenue and profitability as before then the same benefits will accrue as if you owned both individually. The cash will be pooled and thus they can do the same buy back just slightly later. There is no economic downside. If on the other hand one was buying the other on a PE of 20 from a PE of 4 then I would agree that would not be sensible.
Assuming that scale is of genuine importance and that synergies are material enough to matter (I make no judgement either way on management rational) then putting the two together now and then doing the buyback subsequently does make corporate and economic sense given the similar ratings.
On RhythmOne (LON:RTHM) I am actually encouraged that the FD is fairly new as he has a good reputation to protect. He will cast a fresh set of eyes on the numbers and is much more unlikely to go along with anything dodgy imo. This gives me some comfort that trading/accounting is as being told. There is no long term incumbent so the risk of fraud goes down.
On Taptica International (LON:TAP) I am more circumspect given the situation with the previous CEO. However, the potential issue was flagged in the admission doc, the CEO resigned immediately the case went against him and the board didn't protect him but accepted the resignation and appointed a new CEO, which was the right thing to do.
Any merger both companies will need to do extensive DD on each other. Their corporate lawyers will check and double check things like stated cash balances. There will be extensive warranty covenants, personal liabilities and disclosures. Thus if the deal went ahead this would give me some comfort that the stated trading positions are materially as disclosed and can be believed.
Obviously, as we have all found recently even the most robust looking business can have undetected accounting fraud, so one should also cast a sceptical eye and avoid rose tinted spectacles if at all possible but I can't help wonder why you think the bad smell around Taptica International (LON:TAP) is getting worse, other than maybe a natural negative bias (we all have them). If they are prepared to pull their trousers down to RhythmOne (LON:RTHM) and bare all, which they now must do under DD (I have been through it - it's intrusive!) they must be reasonably confident in their position?
It's definitely an interesting situation to see how it plays out.
Frayed emotions...but no smoking gun.
Valuation plus proven operating momentum of Taptica accommodates some losses on large acquired receivables or intangibles on prior acquisitions. Less fat on RhythmOne as the valuation is only good assuming significant pick up in operating momentum (which is being evidenced by cash return that doesn't translate into reported earnings as due to non cash subtractions that appear benign).
So as Taptica holder I have deal risk that could undermine the stonking value my shares currently represent. However, Taptica have proven ability at this in that they picked up Tremor Video in a worse state than RhythmOne (the cash was deteriorating as well as negative earnings) and they have bullied it into positive contribution quite rapidly. It suggests they have commercial ability aligned with their tech capability.
DYOR but IMO Taptica International (LON:TAP) is a market giveaway due to angsty emotions on its news and the general market angst that the news ran into. If the Taptica team believe that RhythmOne (LON:RTHM) turnaround is real and worth paying for with their 4x proven earnings for RhythmOne's 4x forecast earnings thro turnaround then I have some decent reasons based on written history to believe they are making a decent judgement....and at 4x for the combo that seems as if it has relatively high growth and okay (probably improvable) margins then there is quite a bit of fat to accommodate some lumps (receivables? push out bad clients? etc) too.
Feels edgy of course so shower me with embarrassment if I'm a dolt :)
Oh no, I see have incurred the wrath of the mysterious cult of red thumb. I will perform sacrifices to settle the gods.
Staffline:
"Further to this morning's announcement, the Company can confirm that this morning concerns were brought to the attention of the Board relating to invoicing and payroll practices within the Recruitment division".
First it was cake and now staffline! Is this the start of a trend of false accounting? It’s really concerning
I had a 10-minute recorded chat with the CEO of Best Of The Best (LON:BOTB) today - got some useful clarity on the tender offer. Here it is:
http://qualitysmallcaps.co.uk/...
So if everyone takes up their basic entitlement, will there be no premium to the market price?
No they can still sell at 420p, but only 7% of their holding.
Staffline (LON:STAF) Graham, have you managed to slide that into Paul's in tray for the morning?
Re Crusader Resources (LON:CAS) "Is this a record in terms of speed to failure?"
I think there was a company called Madagascar Oil (??) that lasted about TWO WEEKS.
Job well done.
Re Taptica International (LON:TAP) and RhythmOne (LON:RTHM)
It takes all views to make a market. I bought Taptica International (LON:TAP) in last couple of weeks around the 140-144p range as to my eyes an operationally successful company was being given away by the market.
I had looked at RhythmOne sometime H2 2018 but didn't progress any as did not have enough insight to judge the tangibility of their turnaround from a product perspective and the potential to grow that. From a cash flow perspective it looks real although earnings held back by various non cash costs. Deprec and amortisation the greater part of if and in H1 2018 totalled $15m with Taptica also having $5.5m of the same. Both cos have been acquirers/consolidators.
There was great coverage on the Blinkx scandal in FTalphaville back in the day. Look it up. RhythmOne is no longer that business. So best to lay that stink to rest.
There's a fair amount of intangible on both balance sheets from acquisitions and past investment. Operationally Taptica has proved this out into positive earnings and cash whereas the jury is out on RhythmOne but the recent inflexion is encouraging with it looks like positive cash is in progress to positive earnings too. Obviously both companies will face a non cash earnings headwind for a while buy hey that's okay and decently conservative accounting. The valuation of Taptica on seen earnings accommodates some write down in intangibles. I'm not forecasting it but it could obviously happen. RhythmOne would does not have the same operating momentum fat to protect it from a write down so that a risk to me as a Taptica holder.
Taptica have produced value from acquisitions. Now, maybe they are raving loons and its just been luck or there's some heavy duty accounting manipulation going on. The evidence doesn't point that way but would be delighted if someone can show me it and save me some of my cash before its too late! Focused negativity welcomed with open arms. Like everyone else I feel uncomfortable with this given some historic factors...
But if a company has some stink yet has good franchise and ongoing operating momentum its usually good to overlook the stink. It creates volatility and maybe some costs but it doesn't sink a good company. I was introduced to this style of investing by a famous short seller, one of the notorious Feshbach brothers - the late Joe (I also met his brother Matt a couple of times). After giving up the hard school of short selling Joe ran a super concentrated fund of 5 or 6 stocks purely investing in stocks that had some form of trauma but he believed it was short term noise on a good franchise. Among his favourite cues to get involves was discovered fraud or regulatory investigation. Since meeting this guy a couple of times I've looked for the occasional opportunity that roughly fits his vibe as I found his rationale compelling that this is an area of true "market ineffciency".
IMO Taptica fitted the bill. I wrote here about some views I have around the fraud cause against CEO Tal - https://www.stockopedia.com/content/taptica-true-contrarian-or-potential-disaster-438583/ . There's some great comment from others. I don't dismiss the wrongdoing of Tal but I think it requires perspective and noted that it doesn't have anything direct to do with Taptica.
I'm not a fan of foreign stocks listed on AIM so I felt caution re Israeli listing. However, I do like Isreali companies and individuals based on experience in the venture space. Hardcore. Rough as hell too so not for fainthearted.
There's future business risk that I can't really assess in this dynamic space. So far Taptica appear really astute in navigating it. Makes me feel that these guys are real entrepreneurs...like sharks they keep moving and eating. RhythmOne is the next thing to eat....and RhythmOne seems to want to dress itself on a plate for them. That could suggest that there's something wrong with RhythmOne and it just wants to do itself in by passing over responsibility to Taptica. Could be and that might catch me out. My hunch and risk is that both parties see a great logic in tying up and that RhythmOne recognise the better reach, commercial chops and, I guess, ongoing technology adaptation/innovation from Taptica. It's a tough area and very dynamic so no time to stand still and think you have a safe cash cow. Got to keep feeding....
High receivables for RhythmOne and Taptica through the acquisition of Tremor Video late 2017 are a negative. In the case of Tremor it seems that Taptica did a great deal and bought something cheap from management that had an idea but not the commercial skills. Note, that the seller of Tremor has changed their name to Telaria (from Tremor) after the Taptica acquisition. They are seeking to use the cash from Taptica to grow the much smaller rump (Taptica took most of it). They couldn't handle the tech and commercial factors on the bit sold to Taptica. In 2018 results Taptica showed they managed down some of the receivables. A bit of google search on employees of Tremor show they felt the bite from new management kicking their backsides. I'd be happier if Taptica gave more details on receivables quality and ageing...but this is AIM accounting...and the valuation provides protection that some goes bad.
The departure of Tal from Taptica is a negative. Reading the history it seems clear the guy had good ability and leadership. Will Taptica have the chops without him?
Conclusion: I'm nervous but greedy here. I feel that there's a lack of evidence that something fraud or immediate operation is wrong. It's a tough and dynamic business so they could just die on themselves. I did not want Taptica to pay out their cash if they have a growth opp to pay for. In this space that makes sense...keep moving for now.
Give me your negative details!
Thanks for your Taptica International (LON:TAP) / RhythmOne (LON:RTHM) thoughts Graham. Much appreciated.
Jo
Staffline (LON:STAF)
Frankly todays turn of events is beyond ridiculous , i know nothing about etiquette but surely the only sensible course of action was to suspend the shares then tell us the bad news when ready. You can't fan the flame - watch the building burn and stand by all day doing nothing can you - oh yes you can.
If there was no bad reason for the shares to be down that much - i presume they would have had a release advising we know of no reason why the shares are down - if there is nowt up here the lack of them saying that is almost as ridiculous as the first statement fanning the flames.
Perhaps things don't work that quick in real life , but its almost as if everyone was down the pub spending the last bit of cash the company has (well last bit of their available overdraft) enjoying the champers will the trainee as to make a decision what to do.
woe is the company with large debtors book and large debt , large writeoffs and large acquisitions - could be anything that has gone wrong. Or are the bods that have put their money on the news being not good got it wrong? hmmmmm - interesting
A shame that there weren't many good companies reporting today, but it can't be helped.
That's true, Graham, some of the companies you reviewed today are perhaps not investible but you have brought out a number of interesting lessons and asked some interesting questions. Finding out why some companies are or could become basket-cases helps us all learn to avoid them. Thanks for another really useful report today!
Cheers Splode - avoiding basket-cases is a great way to improve one's investing results!
Hi Graham,
Just wanted to commend you on an excellent report today. There are so many great nuggets in here to help people invest, such as don’t buy professional services firms; even if a company looks great if the spread is huge and free float small then it’s akin to pushing a piano uphill; and even dogs may have their day, best to cash out when they do and not hold on for the inevitable reckoning.
It just reminds me the road to investment success is not always to chase the latest hot sector or tipped stock, but to also avoid losses...
Re: Best Of The Best (LON:BOTB) tender offer, the tax rules for people who control a company making distributions are quite complex. There are avoidance rules by HMRC to deter people making distributions that are really dividends (income) but being taxed as if its capital (Capital gains). In additional there are rules were Capital Gains are reduced to 10% for Entrepreneurs Relief, if a greater amount of circa 5% of shares are disposed of.
So the Tender Offer could kill two birds with one stone. Make it likely that they have near total control, and distribute capital to themselves tax efficiently.
Sometimes these tender offers are pre-cleared by the HMRC.
All very convoluted rules admittedly, and it maybe that the owners just wants to be seen legally etc to be even handed about offering a distribution to all shareholders, as some may never be aware of more informal buy back announcement and miss out. This way they get a lump of paperwork forwarded to them, aside from any RNS.
re: BOTB
Thanks for the input Trident. I am leaning toward the view that it is tax-related and look forward to hearing back from Paul on this questoin.
Quick point though: if everybody tenders the maximum, then management's percentage stake is unchanged - so I'm unclear as to how it improves their control position?
Hi Graham. I may be disapearing up my own whatsit on my thinking.The circumstances of where a Tender Offer buyin for 1 in X shares may increase holdings even where everyone takes up maximum entitlement, is where in the detail of the Tender Offer smaller shareholders are given first bite up to a maximum amount of £x. This may occur where some shareholders will be handing in a pitiful 1 or 2 shares, and the Company wants them to get a more cost effective exit.
As the Company can review the make up of its share base, that may take out a lot of small shareholders for not a huge amount of the total offer. So technically, although there is a head 1 in x offer, but in reality larger holders are being scaled back, but still getting a decent chunk, and in reality increase their holding.
To be fair, this does not appear to be the case with Best Of The Best (LON:BOTB) on first perusal.
Hi - Interesting idea, I see what you mean.We'll have to see if it applies to BOTB.
It's difficult to see how Begbies Traynor (LON:BEG) can fail to make huge profits. I've just seen a report from their Preston office where they say that as of 1 January they're putting up their charging rates. Fair enough, one might think, in line with inflation would be around 2.5%.
Ha! Their rates for a partner are increasing from an already very high £395 per hour to an eye-watering £495 per hour, and for a director (for some reason junior to a partner) from £345 to £445.
Even the rates for lowest grade - `support staff', which presumably means typists and the tea lady - are going up from £60 - £110 per hour to a fixed £140 per hour, so more than doubling the lowest rates.
These charges would be iniquitous for a firm in London, let alone Preston. In my experience they only get away with such extortionate charges because the costs are borne by hundreds or thousands of individual creditors, and as no individual creditor would obtain any personal advantage by challenging the charges they can more or less charge what they like.
Sorry, I know this is an investment board, not a place for ranting, but I really feel that people should know what's going on. I suppose that as an investment proposition it makes them very attractive, but I wouldn't buy shares in them on principle.
Love your comments today, Graham, particularly on the perils of debt-fuelled, acquisitions at a premium (where the reckoning comes later) of professional services companies. CVS (LON:CVSG) now in small-cap territory after falling 75% from peak with £200m of dubious intangibles on its balance sheet and a shortage of locum vets hitting profits. When markets turn down investors start to take notice of the naked swimmers' balance sheets which is why this site's focus on the balance sheet is so important. Lots of companies with negative NTAV or debt > 3-4x PBT now struggling and worried about having to write off their goodwill or the terms of their next refinancing.
Thanks very much, mammyoko! Life is better when you avoid all companies falling into this pattern, I find! G
Staffline (LON:STAF)
Falling dramatically - down 28% as I type - the lack of explanation has spooked the market.
Phil
Staffline (LON:STAF) now suspended pending an announcement. Rumours were they were mulling over a takeover of the Cordant Group, but I think this seems a bit more sinister.
Staffline (LON:STAF) RNS of suspension at 15.50 tends not to be the harbinger of good news, would only be worse if issued on a Friday before Bank Holiday. Now out but thanks for the heads up.
Just looked back and see Paul's comments 3 weeks ago:
https://www.stockopedia.com/co...
Re Yu (LON:YU.) still no indication that they have ever made a profit or are ever intending to make one. And that's before the bad news on how much of the debtor book is recoverable (£15.4m stated at the half-year). An impressive short-covering rally, but yet to be convinced that this is going to turn out differently to £UTW
Hargreaves Services (LON:HSP) Has had interims, can not see anything very interesting though NAV is currently stated as 415p, and they are realising assets.
Hi Graham, I wondered if you may have time to consider the possible merger of Taptica International (LON:TAP) and RhythmOne (LON:RTHM) Even if just your quick thoughts.
You were previously unimpressed by Taptica halting their share buyback in pursuing an acquisition. Now that we know more I wondered if your mind had changed?
Some posts above are less than enthusiastic about the announcement!
Jon
Hi Jon, I intend to work my way towards that announcement. Stay tuned! Very interested to read what others think about it, too. G
Does the combination of two dodgy companies make an investable one? Or merely double the opportunities for some skillful inter-company trading?
Paul have tried to DM you on twitter re Cloudcall maybe you could DM me your email thanks steve
zipmanpeter my understanding is the same as you. Using the same logic and yesterday's closing price, I would have expected the shares to go up only 20p or so. Perhaps, the larger rise is because, some investors have just seen the headline price of 485p and have tried to get in. The share is very illiquid and that will have contributed to the rising price. Small investors might have been better selling out at the spike as I think the share will pull back once the news is fully digested. I am a hold btw
Thoughts on Renew Holdings (LON:RNWH) would be appreciated Graham. Excellent AGM statement this morning:
- trading nicely in line
- order books well up, and almost 20% up for higher margin Engineering Services
- all rail CP6 contracts tendered for have been won
- capital markets day coming up, which hopefully indicates they believe there's a good story to be told
Forecasts are for 39.4p EPS this year against a 375p share price (up from 35.5p EPS last year).
Most income is from non-discretionary/non-cyclical sources such as rail maintenance and repair, and the upcoming Network Rail CP6 Strategic Plan 2019-2024 is focused specifically on these areas.
Solid State (LON:SOLI) worth a look ? Stockopedia likes it with a 98 score....
Staffline (LON:STAF) The Company announces that publication of the results for the year ended 31 December 2018 has been delayed. The presentation for analysts previously scheduled for 9.30am on Wednesday 30 January and the presentation for private investors scheduled for 3.00pm on Thursday 31 January 2019 will be rescheduled.
Used to hold this but no longer, uncertainty over Brexit but looks like a deeper problem.
Good spot on Cloudcall (LON:CALL), Paul. Am I being thick or does the RNS not actually state the final price of the placing? I know you can work it out by doing 2,400,000 New Ordinary Shares divided by a £2.4m raise, but it seems unusual not to actually say the price...
Always intrigued by Tender offers as per the Best Of The Best (LON:BOTB) tender. On the one hand it generally allows some small shareholders to exit if the shares are relatively illiquid. It also allows people to take advantage of lower Capital Gains tax on the sale of their shares.
The danger is depending on the make-up of the shareholders base is that overall if the base is made up of many small shareholders that it increases control by the existing major shareholders (who only sell the tender amount) and this allows them to delist, to promote changes, or resist changes via AGM's etc.
I note Best Of The Best (LON:BOTB) in their RNS announcement reference that ongoing tax changes will weigh more heavily on the Company, and I wonder if they are now considering re-registering in another tax domain. As that may have implications for the take-over code, inasmuch as some jurisdictions are not subject to the code, that would probably require a 75% special resolution authority from shareholders.
It will be interesting to hear Paul S take on this as I believe he is a large holder in BOTB and interviewed them recently
I'm still trying to get my head around the Best Of The Best (LON:BOTB) tender offer.
Am speaking to management later.
P.
Excellent. That makes 2 of us then.
Trident,
As I understand the Tender offer, to return cash to shareholders, BOTB will buy 1 of my shares for every 14 I hold ie if I hold 1767 (as I do), then 1767/14 = 126 : they will buy 126 shares at 485p.
I have seen commentary that this tender offer directly helps small shareholders like me exit. As I see it, I am simply left with an even smaller quantity or shares if I take up the offer ie 1767-126= 1641 !!
Clearly, this is a chance to take out some capital but how does it exit anyone? Is my understanding correct. Appreciate any explanations you or anyone can give to this point.
(As an aside, the more time I spend on shares, the more I feel that it is NOT easy for a private investor without specialist accounting knowledge to navigate the investment world. I feel the pull of a minimal time / effort simple passive tracker! )
Would be interested in your opinion on Inspired Energy (LON:INSE) please Graham after the latest update, which shows quite a leap in the Corporate order book. Growth in EBITDA is expected to be 24%... though this is down on the 39% at the halfway stage.
Graham - I guess we now know why the Taptica International (LON:TAP) board postponed the share buy back!
Merger in equity means they haven't used the cash pile to buy a company when they could be buying back shares on a PE of 4. On the downside half that cash will accrue to RhythmOne (LON:RTHM) shareholders but they are giving away 50% in the venture at a higher market cap.
I actually hold both shares and yet I'm not quite sure how I feel about this one.
2018 revenues are about the same for the two companies. Taptica International (LON:TAP) has about 4x as much net cash. The big difference is that Taptica International (LON:TAP) is reporting substantial positive free cash flow for 2018, and RhythmOne (LON:RTHM) is negative. RhythmOne (LON:RTHM) valuation depends heavily on the forecast for strong revenue growth in 2019. If that forecast is going to be met, why are they prepared to merge with £TAP? If it is not going to be met, why would Taptica International (LON:TAP) use its apparently cheaply rated paper to buy them?
My guess is that the RhythmOne (LON:RTHM) forecasts are on the optimistic side, and Taptica International (LON:TAP) is a very acquisitive company which reckons it can take an axe to £RTHM's costs. I hold a small amount of Taptica International (LON:TAP), but not very enthusiastically.
Jarvis Securities (LON:JIM)
Announce higher Q1 dividend of 6p compared with last years 5p and 4.25 for prior year.
Psychic Paul even predicted the amount!
Congratulations to Paul on his portentious summary of Cloudcall on 22nd Jan 2019. Couldn't have been more bang on!!
Morning all!
Good to see that Cloudcall (LON:CALL) has finalised its latest placing, at 100p per share - so only a modest discount, and also modest dilution of c.10%
Let's hope this placing is the last one!
Paul.
Hi Paul, just wondering whether you had chance to speak to management. I normally email on results day but saw a few on here were contacting them directly so thought I wouldn't bombard them.
My morning smallcap tweet: Taptica merger, terms favour TAP holders.
Taptica International (LON:TAP), RhythmOne (LON:RTHM), Best Of The Best (LON:BOTB), Solid State (LON:SOLI), Boxhill Technologies (LON:BOX), Spaceandpeople (LON:SAL), STM (LON:STM)
Taptica (TAP) advanced discussions regarding an all-share merger with RhythmOne (nee Blinkx). with TAP holding 50.1%. Tuesday closing caps £114m and £147m for RTHM. How will RTHM sell this to holders? I hold.
Rhythmone (RTHM) see TAP.
Best of the Best (BOTB) £3.5m tender for 1 in 14 shares at 485p, a 120.5% premium! The very high tender price looks like a ruse to push up the SP. Obviously every holder will tender. They could make it a 1 in 140 at 4850p for example. Also H1 ahead of management forecasts.
Solid State (SOLI) guides FY to exceed current market consensus. Rev above current guidance and adjusted profits significantly ahead.
Boxhill Technologies (BOX) returns from 6 month suspension as it heaves out its H1 and FY to Jan 31 2018. Pretax -£1.7m (B/E). Going concern stmt: "the substantial achievement of the Group's cash flow forecasts represents a material uncertainty that may cast significant doubt on the Group's and the Parent Company's ability to continue as a going concern."
SpaceandPeople (SAL) rabbiit from the hat after yesterday's warning. Had commenced a multi-year contract with Hammerson to deliver innovative promotional and short-term retail experiences across its flagship shopping centres in the UK. Surprised they couldn't trail this yesterday.
STM Group (STM) guides FY rev £21.3m (£21.5m), including an expected £0.5m technical reserve release from London & Colonial Assurance. U/L rev £20.5m (£20.2m) and U/L pretax £3.7m (£3.2m). F/C rev is £20.8m but is this U/L? Warns on costs after its regulatory caning. "Some of the costs of strengthening the Group's governance framework have been incurred in 2018, however, this overall investment in infrastructure will result in an increase to our 2018 cost base which will flow through into 2019 and be reflected in future expectations."
Low & Bonar (LON:LWB) are offering a fairly caustic placing. Unfortunately I have a small holding here. Seems like the disaster that was waiting has decided to put in an appearance after all! Any observations or suggestions?