Small Cap Value Report (Wed 30 Nov 2022) - IGR, MUL, LINV, KETL

Good morning from Paul & Graham.
Agenda
Paul's Section:
IG Design (LON:IGR) - H1 figures look good, but the outlook is only for about breakeven for FY 3/2023, so I'm publishing the first part of this section to alert readers to this point - caution needed! The rest of this section is now up. It could be an interesting turnaround, especially if input costs fall in future, but so far there's not enough evidence to convince me. Plus there's bank refinancing risk to consider.
Strix (LON:KETL) - drops about a third today, on a profit warning. I raise several concerns over the historic accounts, so this share gets a thumbs down from me.
Graham's Section:
Mulberry (LON:MUL) (£150m) - disappointing numbers from this luxury handbags and leather goods company. It swings to an H1 loss and also suffers a large cash outflow as it builds up a large pile of inventories, betting on a big festive season. Expenses have ramped up across marketing, technology, and expanding the store network. It’s an ambitious plan and hopefully it will pay off over time with improved revenues and operating margins. We’ve seen false dawns here before and I believe that Mulberry should allow itself to be taken over by a larger group who can run it profitably. The shares are currently priced at a level where I think buyers would be interested, but it’s not clear if Mulberry’s major shareholders would be willing to let go.
Lendinvest (LON:LINV) (£113m) - the property investment platform and lender confirms its H1 numbers and leaves its expectations for the current year unchanged. It no longer expects any improvement in PBT for this year, but it thinks that the issues are temporary and that it can get back into a strong growth trend in FY 2024. I’ve reviewed its key numbers and am disappointed that it hasn’t already securitised more of its portfolio, in order to reduce its own leverage. As things stand, it remains very highly leveraged and I’m concerned that its balance sheet would not be able to withstand a few more heavy blows.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
IG Design (LON:IGR)
114p (pre market open)
Market cap £111m
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of Gift Packaging, Celebrations, Craft & Creative Play, Stationery, Gifting and related product categories announces its results for the six months ended 30 September 2022.
Webinar - today at noon - register here if interested.
Headline numbers look impressive -
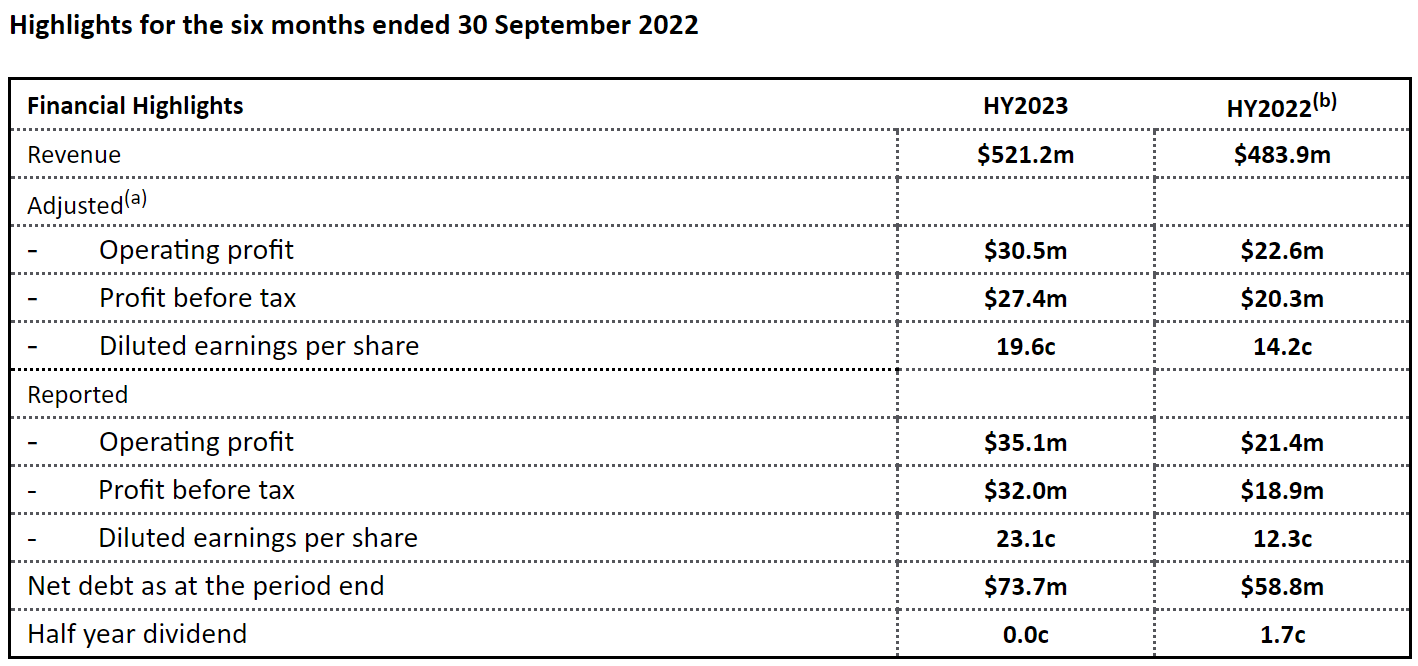
However, there are several points that should temper our excitement - incidentally well done to the company & its advisers for giving prominence to the cautionary points -
- A “full refinancing” is underway, which they hope to complete by FY 3/2023 year end. The existing bank facilities (needed to cope with the seasonal spike in working capital prior to Christmas) expire in Mar 2024. I wonder does “full refinancing” possibly involve an equity element, if the bank wants to reduce its exposure? So dilution could be a risk for shareholders.
- Acceleration in orders for H1, due to customers wanting seasonal (Christmas) stock in earlier, given last year’s supply chain issues. Hence demand pulled into H1 from H2, and a “strong first half weighting” for FY 3/2023.
- Cautious outlook beyond this financial year.
Outlook - the key guidance is a bit vague -
The Group has also seen stronger trading in certain Everyday categories than previously had been anticipated. Due to this, the Board believes that the financial results for the full year to 31 March 2023 will be ahead of expectations, delivering a small full year adjusted profit before tax. As previously communicated the Board remains cautious on its outlook due to uncertainties relating to the current macroeconomic environment.
What does “small” mean? Does this imply that H2 might be loss-making, since it made an H1 adj PBT of $27.4m - which doesn’t sound small to me. Although as a percentage of revenue of $521m, it’s 5.3%, which is lowish. All rather confusing. It’s annoying when we have to check broker notes for the full picture. It’s much better (and fairer) when full guidance is provided in the RNS itself.
Broker updates - see notes from both Canaccord, and Progressive, both are on Research Tree. This gives much more clarity. It turns out that yes, H2 is expected to be loss-making, and is likely to wipe out nearly all H1 profit!
Indeed, Canaccord slashes its FY 3/2023 revenues target considerable, from $965m to $909m.
Although profit guidance is raised, but barely above breakeven - Progressive reckons $1.9m adj PBT. It’s now become clearer what a “small” profit is, they really are talking small, almost nothing, in plainer language. Not very good at all. I wonder if people might buy on the opening bell, not having realised that the outlook is nowhere near as good as the strong H1 numbers suggest?
I’ll publish this now actually, to alert readers, as it’s just before 8am, and finish the section in the next hour...
Since the full year outlook is only for just above breakeven, I don’t think we should be over-analysing the H1 figures, which are not representative of the full year.
Cost inflation - the comments below on sea freight costs surprise me, because this cost has absolutely crashed in price more recently. I wonder if IGR might have contractually locked in at higher prices? That would be a good question for the webinar. Spot rates are actually now right back to pre-pandemic levels, so why isn’t IGR reporting this?
Since the summer of 2021, the Group has experienced significant cost increases, particularly in relation to freight, raw materials and labour. Freight presented the most significant challenge across the Group with the scarce availability of sea containers significantly increasing the freight rates paid. Freight rates in FY2023 so far, though stabilising, have remained higher than the prior period on a number of our key shipping routes.
Raw material costs have increased significantly during this year, especially where higher energy costs are a factor. The average prices paid for paper, the Group's major category of material purchases, increased around 50% compared to the prior period.
Balance sheet - is quite strong. NAV of $371m becomes $273m after writing off intangible assets.
Working capital is good, with current assets of $616m, and current liabilities of $413m, a healthy surplus. Note that both inventories & receivables are very large numbers. The interim figures as at 30 September, show working capital probably at or near a seasonal peak. The 31 March comparative shows receivables more than halve, and the bank debt paid off, which would be seen positively at the bank (because in extremis, it could cancel facilities when they’ve already been paid off from seasonal cash inflows, thus greatly reducing risk).
The problem is, as a seasonal business, it needs large bank facilities to operate. In normal times, that wouldn’t be a problem, but I’m worried banks are now probably being a lot more cautious than normal.
Bank covenants - this sounds positive, and could make it easier to refinance the bank facilities (which expire March 2024) -
The Group has operated well within its banking covenants, with working capital requirements tightly managed and net debt lower than expected throughout the period.
My opinion - It seems to me that the fundamental flaw in IGR’s business model, is that it’s a low margin business, and was not able to pass on big, unexpected increases in costs, to its customers. That should, over time, be fixable, and see the PBT margin possibly return to around the previous level of c.5%. The same core problem has hit many other companies. The answer is to somehow build in flexibility in costs into contracts, although customers won’t want that, so in a competitive, low margin sector, this may not be possible.
IGR’s other problem is that it’s highly vulnerable to supply chain delays, because the product has to be in its customers shops before Christmas, because if deadlines are missed, then the product effectively becomes worthless (who else likes buying wrapping paper for 10p per roll in January each year, or is it just me?!) Hence it was hit particularly hard with all the supply chain problems, and I recall last year that it was forced into over-staffing warehouses at considerable cost, in order to get the delayed Xmas orders out. It talks about excellent customer service, but it didn’t have a lot of choice, as customers would just reject orders that arrive too late for Xmas. About half its revenues are Xmas-related.
The big picture problem, is that wrapping paper, cards, etc, really don’t come with any pricing power, so cheap competition from China, etc, is always likely to erode IGR’s profit margins. For these reasons, I think this is a fundamentally poor business model.
It seems to me that these strong H1 numbers are best ignored, since the bigger picture is that the FY 3/2023 is only going to be around breakeven.
There’s also refinancing risk - will the bank really want a large seasonal exposure to a company that has demonstrated how vulnerable it is to supply chain disruption? Especially when the Xmas-related products become worthless after Xmas? So what would the fire sale value of inventories be, in the worst case scenario? Not very much, I reckon.
On the upside, the recently appointed new CEO could improve things with a turnaround plan, and if profit margins return to previous levels, then on c.$1bn revenues, the effect could be exciting - that's the bull case for this share.
Overall, IGR shares could go either way. If profit margins recover to previous levels, then you could maybe have a 2-4 bagger on your hands, which would be marvellous.
On the downside, there’s dilution & bank refinancing risk over the next 6 months - clearly a bad time to be renegotiating the necessary seasonal bank funding, when lenders are cautious.
Also, there’s very little evidence so far of a profits turnaround - remember it’s only expecting around breakeven for the current FY 3/2023, which to me is not a turnaround, it’s more a case of having stabilised the business, and it not getting any worse, rather than a convincing turnaround at this stage.
If cost headwinds turn into tailwinds, from e.g. falling paper & energy prices, then that could be a nice catalyst for profits to recover. Set against that, will consumers cut back on spending for celebrations? I don’t know, it would be good to ask management if & how much demand changed in previous recessions.
Overall, I’m probably neutral on this one. It’s a possible turnaround, but so far there’s not enough evidence for me to get excited about it, and still considerable risk. In a rebounding stock market, maybe investors will ignore those risks, who knows?
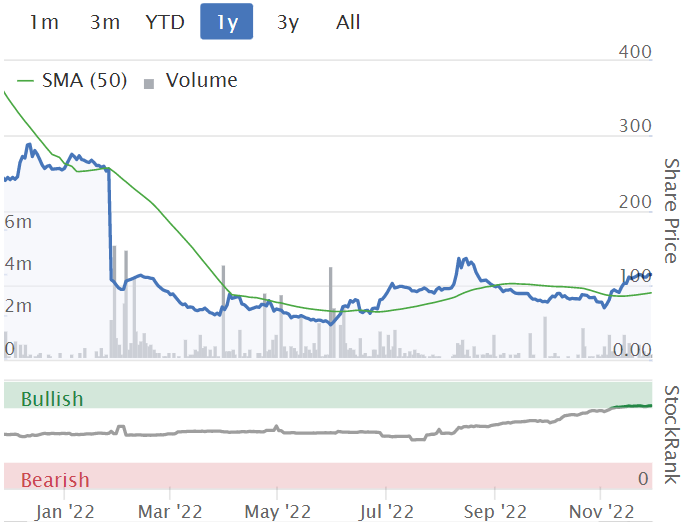
The share price seems to have formed a base this year, indicating more solid investor sentiment, during a nasty bear market. So maybe anyone likely to sell has already moved on? That could be a positive, for traders.
.
Strix (LON:KETL)
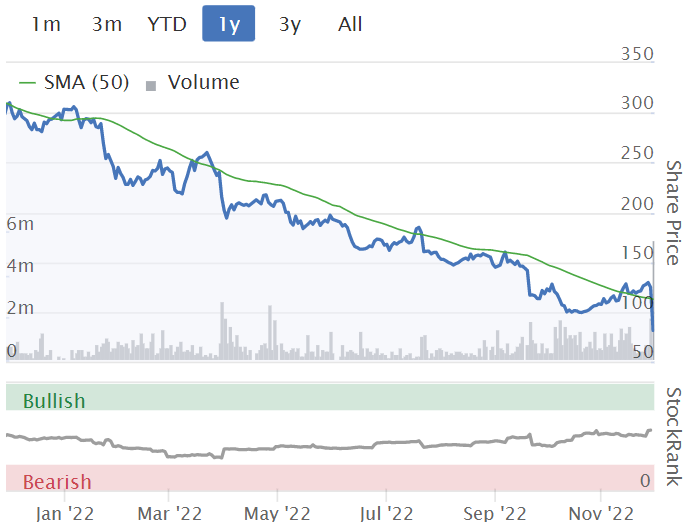
84p (down 33% at 09:02)
Market cap £183m
A nasty reaction to this update, so it must be a profit warning.
Completion of Acquisition
This is an Australian company called Billi, which does instant hot water taps. They look high end, with google showing prices of £4-6k per tap.
A previous RNS says the acquisition is £38m cash, with £10m raised from a recent placing at 115p, the rest funded from a new term loan.
Strix Group Plc (AIM:KETL), the AIM quoted global leader in the design, manufacture and supply of kettle safety controls and other complementary water temperature management components…
Problems in China, and with demand, result in revised guidance (but annoyingly, not stating what previous guidance was, a common omission which wastes all our time whilst we try to find it) -
As a result of lockdown situations as described above and continued macroeconomic and geopolitical uncertainty, not only in China but across a number of its key export markets it now anticipates adjusted profit after tax for the full year to be approximately £23m. The Board recognises that these uncertainties could continue into 2023.
Looking back, the interim results (released on 21 Sept 2022) talked about reduced demand, and uncertainty, but seemed to be saying conditions in China were improving. Whereas today it seems to be saying that conditions are worsening in China.
The guidance in Sept was for £27-29m adj PBT for FY 12/2022. That’s now down to £23m after tax, but tax seems to be negligible for this company (why?!)
Broker update - there’s an excellent note out today from Zeus (on Research Tree), which lowers forecasts, but includes an additional column for the Billi acquisition, which is very helpful to see before & after, as this acquisition is material in terms of the group numbers which it will start to be included within from today.
Something to flag up that I noticed from Zeus’s forecasts, is that Strix has negligible corporation tax each year. Does anyone know why that could be? Brought forward losses perhaps? But when valuing any company we should put in a normalised tax charge, otherwise EPS is flattered, and you end up over-valuing the shares if you don’t adjust for it.
Zeus lowers FY 12/2022 from 13.3p to 10.9p. Normalising corporation tax would take that down to about 8p.
Balance sheet - looks weak, and has too much bank debt.
Cashflow statements - I’ve looked back at the last 2 full years, and the pattern is - operating cashflow is nearly all used up by capex. Debt rising each year. Generous divis funded through increased debt, not internal cashflow. Hence I doubt generous divis can be maintained.
My opinion - I don’t like this share. My main reasons are these -
- Profit margin looks unrealistically high.
- No corporation tax payable - why? Are the profits real?
- Too much bank debt, especially after latest acquisition.
- Cashflow nearly all used up by capex.
- Debt increasing each year, funding big dividends (hence not sustainable).
So it gets a thumbs down from me I’m afraid.
Graham’s Section:
Mulberry (LON:MUL)
Share price: 250p (-12%)
Market cap: £150m
I’ve noticed some curious moves in this luxury handbag maker’s shares recently. You can see from the chart below that volumes have picked up recently, too:
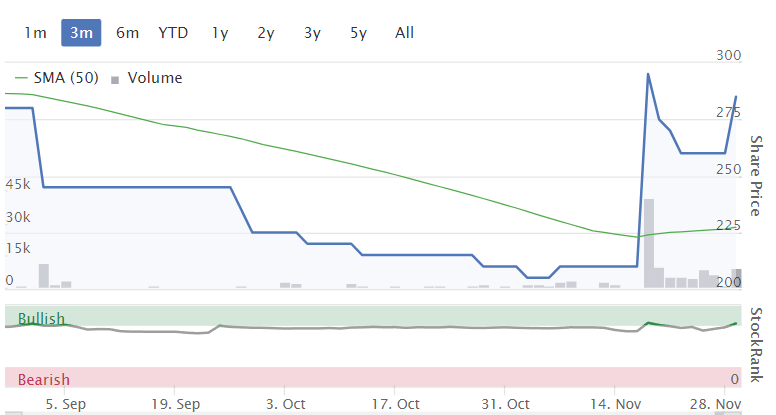
Burberry (LON:BRBY) (in which I hold a long position) issued results on November 17th, and that is what appears to have kicked things off here at Mulberry.
In its results, Burberry outlined plans to “broadly double sales of leather goods” in the medium term, and an “ambition to grow accessories to more than 50% of Group sales in the long term”.
It also said it would “refocus on Britishness and strengthen our connection with British design, craft and culture”.
The Washington Post published a paywalled article on the same day, with the headline “Burberry taps heritage to become a British LVMH”. LVMH is a house of brands that includes fashion and leather, perfume, cosmetics, jewellery and watches.
So I guess people are now inclined to believe that it’s only a matter of time before Burberry ends up owning Mulberry.
It’s probably also worth mentioning that Burberry’s new chief designer, Daniel Lee, has been particularly successful with handbag design. So he will already know a thing or two about Mulberry.
Before we get into today’s interim results, there’s one other important piece of context worth mentioning: Mulberry is majority owned by the Singaporean retailers, the Ong family, and also has a 37% shareholder in the form of Frasers (LON:FRAS) . This means that less than 10% of the company is in the free float.
Ok, here are Mulberry’s interim results:
- Sales down 1% to £64.9m.
- UK sales (about half of total) down 10%, “impacted by the broader economic environment”.
- China retail sales +6%. International retail sales unchanged vs. last year.
- Gross margin 71% (last year: 69%), thanks to “a continued strategic focus on full-price sales”.
Gross margins of around 70% are one of the things that keep me interested at Burberry and it’s good to see Mulberry maintaining its margins, too. They raised prices globally in March and September this year.
The pre-tax loss for H1 is £3.8m (last year: profit of £10.2m). Last year’s profits were boosted by one or two exceptional items and the company says that its results for the current year reflect “additional investment in the Group”.
Outlook
The first eight weeks of H2 have seen “an improved trend in retail revenue… compared to the same period last year, however there remains ongoing uncertainty in the economic and geopolitical environment”.
They are “well prepared for the important festive trading season and the usual second half weighting to trading”.
A new store has opened at Battersea Power Station (they have about 40 retail stores in the UK, including 21 concessions).
Interestingly, they fixed their energy price in October 2021, for a three-year period. That gives plenty of time to adjust to whatever new circumstances they might face by late 2024!
Higher operating expenses
I’m looking for specific reasons as to the operating loss in the period.
“Other operating expenses” increased from £34.3m in H1 last year to £48.6m in H1 this year.
Some of the factors here include:
- Higher marketing spending, particularly to build brand awareness in Asia-Pacific.
- Higher technology spending, “to improve the group’s legacy systems”, and software costs being expensed rather than capitalised.
- They acquired stores in Australia, which needed to be financially supported, and also acquired stores in Sweden from franchisees. They launched “Mulberry Sweden”.
- A new store in China and a new store in Korea. Store relocation in New York and store refurbishment in Amsterdam.
Putting it all together, I can see why expenses might have increased so much - but it’s a very expensive bill for the six-month period. It needs to translate to improved sales in all of these various countries and regions!
Balance sheet
Net cash has reduced to £6.5m (last year: £30m). The company has an RCF, a small overdraft facility, and loans from shareholders at its Chinese and Japanese subsidiaries.
I think I also need to flag the large increase in inventories, from £32m a year ago to £48.7m this year. This is responsible for a large element of the cash outflow.
Inventories have increased “to support our strategy to focus on a direct-to-customer model, to mitigate cost increases, and to prepare for the important festive trading season.”
It might be a smart move, but there’s clearly an increased risk that the company will be left with valuable unsold stock at the end of the season that it will need to write off.
My view
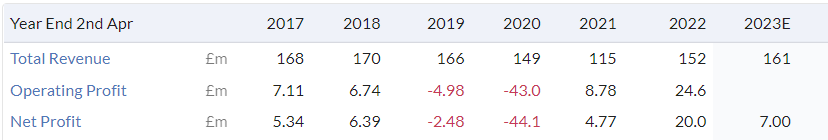
For people who’ve been watching Mulberry for a while, these results don’t come as a huge surprise. (Mulberry was one of the first companies I covered in the SCVR, back in 2016!)
It has always been financially suspect: unable to earn consistent profits and with a top line performance that ebbs and flows. Covid didn’t help:
But it still has enough positive features to keep me interested:
- It rarely dilutes its shareholders. Little movement in the share count for the past decade.
- The major shareholders - the Ong family and Frasers - have relevant expertise and connections. Mulberry is a concession holder at Frasers.
- The growth opportunity in Asia (where Burberry has been so successful) remains of interest.
- When there’s a boom in luxury spending, and Mulberry gets the formula right, it has performed exceptionally well.
One final, speculative point: if Burberry acquired it, then many of Mulberry’s duplicate costs could be eliminated, and there would be wonderful economies of scale. Profitability could improve straight away.
Overall, therefore, I think there’s enough for me to rate these shares positively at the current valuation. They are now trading at a P/S multiple of less than 1x (Burberry trades at 2.8x).
Lendinvest (LON:LINV)
Share price: 82p (+5%)
Market cap: £113m
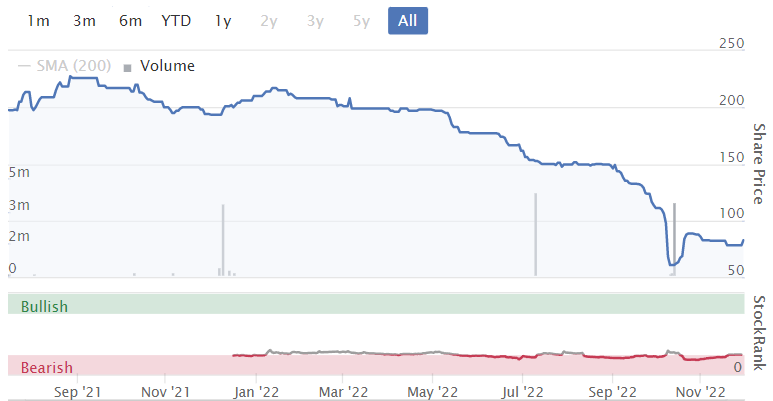
I took an initial look at this share in October. It’s a 2021 IPO that has gone badly so far:
The company provides a range of bridging and development loans to the property sector, and allows individuals and institutions to invest with it in a variety of ways. See more on its website.
In October, it issued a profit warning due to an expected fall-off in the buy-to-let sector, as it sought to protect itself from falling property prices.
Today’s interim results, therefore, are of less interest than the outlook and the latest trading information.
For what it’s worth, the highlights from the results are:
- Platform assets under management +33% to £2.4 billion
- Funds under management +20% to £3.4 billion
- Revenue minus 8% to £42.5m
- PBT plus 45% to £14.8m
The mismatch between falling revenues and rising PBT is due to what it calls “mark-to-market gains on interest rate swap pipeline hedges on the BTL portfolio”.
In plain English, it sounds like the company is sitting on nice gains from derivatives that benefit from rising rates.
The company also benefited from a securitisation deal (selling off a portfolio of loans it made).
These might not be the most impressive ways to earn a profit - rising revenues would be better - but I guess they will have to do!
The securitisation deals are helpful because they get assets and liabilities off Lendinvest’s balance sheet, i.e. they help it to manage its own risk profile.
Current trading and outlook
There is no change to the guidance issued in October. The rise in the LINV share price today might therefore reflect some relief that the situation has at least to some extent stabilised, after the drama of September/October.
PBT is not expected to improve this year (it was £14.2m last year). Some reasons:
- In the short-term, AuM are not expected to grow as quickly as previously thought.
- Margins will temporarily be under pressure from rising interest rates, before normalising towards the end of the financial year (FY March 2023).
- The existing cost base was built on overly optimistic assumptions (although the company did talk about trimming opex in its last update). The cost base has grown faster than AuM.
- The gains on swap derivatives could easily be reversed, wiping out the gains made in H1.
It’s expected that these issues will iron themselves out in due course:
Given the transient nature of these factors and the upcoming launch of our specialist homeowner product we have confidence in our ability to return to growth in profitability in FY24.
Lendinvest also says that the “vast majority” of its borrowers are developers and professional landlords, and are able to withstand the current macro headwinds thanks to fixed rate borrowing and LTVs below 70%.
Lendinvest can reprice its mortgages “overnight”, in response to changing market conditions, and this does sound like a useful competitive advantage (vs. banks who tend to pull their products from the market when they can’t change rates quickly enough).
My view
I’m still getting to grips with an understanding of this company. In theory, I like the business model of providing an investment platform to 3rd parties while also having the company invest its own assets in deals with developers and landlords.
My major concern now is obviously interest rates and the economy.
According to today’s results, Lendinvest had net assets at the end of September of just £60m, down from £97.5m at the end of March.
This fall is directly caused by rising interest rates and how they affect the resale value of Lendinvest’s buy-to-let portfolio. The BTL portfolio fell in value by over £80m during H1. The company does say that more recent interest rate movements imply that net asset value has recovered by £7m.
And then you have to consider the leverage involved: Lendinvest has outstanding loans and advances of £1.1 billion.
Therefore, I have to take the view that this stock is too highly leveraged for comfort. I’m not sure that there would be a margin of safety even if it was priced at a steep discount to book, since the equity cushion looks very, very thin.
Which is a shame, because in theory I like the idea of investing in a property investment platform. The problem is that this company is both a platform and an investor, and it looks like a very risky investor based on these numbers.
If it securitised another very large chunk of its portfolio, to reduce its leverage, I’d be interested to look at it again.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
£KETL "No corporation tax payable - why? Are the profits real?" ... I believe the company is based in the Isle of Man therefore an offshore jurisdiction that has no corporation tax
I just looked quickly at Strix (LON:KETL) for first time - one I have avoided as didn't make sense in past. Some Qs and points:
1) Is there potential for debt covenant stress here? Its got to be at around 2.5x ebitda and above (particularly depending on how adjustments are taken)
2) I don't feel their narrative re what's gone wrong on revenue side makes a lot of sense. They are basically saying that covid zero has bitten them as people can't work and make stuff. IMO to date manufacturers/exporters have been able to negotiate this. Local and central govt is very aware of the need for maintenance of these sectors and the forex they bring in particularly as the domestic economy struggles with real estate very sick and infrastructure non productive (both grossly bloated part of GDP and so the pain is acute). It seems more realistic that something additional is happening -> my guess is that the kettle market must be v exposed to the inventory de-stocking we're seeing + which might be exaggerated by appliance makers perhaps over ordering parts like those that Strix supply when supplies were tight relative to exaggerated demand + strix is in a very narrow vertical so no chance to diversify out of it (I know they've diversified thro acquisition etc so my analysis is flawed)
3) Does 1 and 2 above put some pressure on capex plans. They way to make profit and keep covenants sweet would be to not spend so much on capex. Is this a positive or negative if they do that?
4) I have not view on their patents and their importance or defensibility thro superior production knowhow. However, the rather mad dash for growth thro other channels and acquisitions might be explained by concerns of impact of patents coming off? I'm not 100% sure where their capex goes but if into kettle switches then that could be they think they need automation to defend market share when more competition comes on after patent expiry and/or the need to invest in other products.
5) I was quite frustrated not to be able to find a regional split of sales easily on the company. But I suppose its near all China and then the finished product made by OEMs sold on. I was looking to see how much China is the end market for the products their parts are used in. Massive tea drinking country. With covid zero and quite harsh personal finances going on there I could imagine a fall in demand for appliances like kettles or water purifiers etc. Any views or data on that?
The above is quick very partially informed analysis. I'm interested in feedback and/or to be put right on matters
lendinvest
My limited knowledge of this market place and the companies structure, is that their funds borrowed, are fixed , in that daily they require an interest payment, but the deals they fund for their clients, have a shelf life, 12-18 months. So cost of capital is fixed but income is based on constant tread mill of new deals to ensure that all money is “ placed” in the market. This menas their model is like a hamster on a treadmill, every deal that redeems needs to be matched with a new one to ensure the funds are constantly,earning to pay the cost of borrowing. So interest rates, although a concern, are not I would suggest the biggest.
Late to catch up today and I see its a Strix (LON:KETL) day on the board - got no view on that but will take a look given the battering! Ouch
I see a couple of comments on System1 (LON:SYS1) which is a bit of a let down too. I know it had people interested back a while but that's cooled. People sceptical here. I'm interested in any further pro or con comments people have?...
I note that this half year cash generation poor they have net capitalised £600k of software development (they don't normally) plus net working capital draw on cash as they met payables and had net increase in receivables (to be expected with their move to data services?)
I don't have a view other than something could be very good or bad here...bit of a brainjuicer to work out (my biz model knowledge here is low at mo...wondering whether to look).
I follow Jake Taylor @farnhamjake1 on Twitter and when I get the time listen/watch the Value:after hours podcast. Jake recently (I think yesterday) launched Journalytic and while I have only just signed up, it does look like the service I have been looking for and have tried to solve previously with a blog, OneNote, Evernote etc but never with great success.
Anyway as I thought it might be of interest to readers here.
It can be found at
https://journalytic.com/
Kind regards
Michael
Of Paul's 5 opinion bullet points, the first 2 can be de-emphasised because of 0% corporation tax? Point 4 I don't really follow, isn't capex good if it helps the business?; though declining, free cashflow is still positive. Debt? Yes, too high. Dividends? Could get cut.
I think this share is in the doldrums now and am going to cancel my 70p limit buy because I think it may get cheaper, especially if the big holders decide to reduce. Hindsight as always is wonderful, I should have sold in January when I was in profit.
Strix (LON:KETL) price is a good buying opportunity
Hi
As anyone any insight into the fall on Foresight group (LON:FSG) today? Small volume about 50% of daily average, and no news out.
Not ex-divi
Can see no major links to issues with their underlying funds etcetera
Thanks
Tommy
I hold Foresight group (LON:FSG) (small position)
IG Design (LON:IGR) (I hold)
I remain a big fan of the company and even more so after today's update.
The operating profit waterfall chart below shows:
Source:https://www.thedesigngroup.com...
Volumes are unsurprisingly down and bears might validly point to the huge cost headwinds.
One reason I'm less concerned by this latter point is that gross margins have still improved since the same period last year (16.2% ---> 16.6%.)
This has been helped by the company focussing on higher margin business and closing low margin accounts.
Over time I would hope that gross margins return to their pre-pandemic highs (19%-21%), but 16.6% in the meantime - the highest it's been for 2 years - signals to me that things are on the right track.
---
Working through the rest of the P&L, I'm also quite confused about how the company would make a large loss for the full year.
If I plug in the following assumptions:
then the adjusted operating profit is still quite positive = $10.9m. For me this is a worst case scenario.
Note that FY breakeven operating profit in the above scenario would only come about if Operating Expenditure in H2 jumped to -18% of revenues.
This is entirely possible of course, but the highest it's been in the last 5 years was 15.9% and admin costs, which are presumably quite fixed in nature, look like they have come down quite a lot over the last few years.
---
To allay concerns on the refinancing mentioned in today's announcement, the CEO confirmed that this will not include an equity issuance.
---
With Net Tangible Assets on the balance sheet of $214m/£178m (my workings) vs a market cap of £111m I feel that the downside here is very limited, with huge upside potential, especially if operating profit margins return to their pre-covid levels.
Fingers crossed that they do.
A
Hi Paul ,
Your review and financial analysis on Strix plc was second to none. Keep up the good work.
Excellent overview of Strix (LON:KETL) - a couple of other reasons to be a bit cautious: they are ex private equity (often not a good sign) and more importantly it is not at all clear if they have much of a moat which they like to talk about (there are other companies that produce safety devices for kettles - doesn't sound particularly cutting edge technology).
re: KETL
The Isle of Man has a Zero corporation tax policy so the company does not have to pay any corporate tax
Thanks for covering Mulberry (LON:MUL) interim report this morning, Paul. It shows the importance of having half year results, as the geography of planet Mulberry has clearly changed in the last few months, although not I think for the worse in the long term. I remain a cautiously optimistic holder.
Potentially these purchases of the Australian and Swedish operations could drive long term growth, if profitable then any profits will flow direct to Mulberry and not their concessionaires. Increases in inventory must be partially accounted for by this, as these operations would previously have had their own stock, which now has to be carried on Mulberry's books.
I'm interested in BnB's visit to Manchester. Did you just call in or did you have an appointment? Mulberry.com gives the impression that some shops- the Leeds one as an example- are still by appointment only as a Corona precaution. Could this account for poor footfall?
Long-term I think the big issue for Mulberry is brand image. I can just about recognise a Mulberry bag, as they are subtly branded but I don't see many out and about. There are no end of women with shouty-shouty LV or Gucci branded bags (Always want to ask them if they got them from Bradford market!) though. Irrespective of whether or not they are genuine- presumably not inspiring fake goods is also an image problem??- the centre of high end fashion gravity looks to be big logo bling and Mulberry doesn't do this. I don't know if I've mentioned this before in Mulberry discussions but the quietly confident unostentatious middle classes look to be a dying breed. For the likes of Mulberry (And also Valextra, Smythson and Paul Smith, who I see as more typical image rivals than LV, Balenciaga etc), a comparison with the car industry gives a potentially grim forecast of the future. Whilst all car makers have had existential threats, those that couldn't weather them often seemed to be those that catered for this declining middle class: Rover and SAAB bit the dust, Lancia clings on as a single model pensioner special in Italy, Mercedes survived by rolling itself in glitter.
Before I forget though, their rolling credit facility is good until mid 2024, so they aren't at imminent risk of having the rug pulled from under them like Superdry.
I'm interested in BnB's visit to Manchester. Did you just call in or did you have an appointment? Mulberry.com gives the impression that some shops- the Leeds one as an example- are still by appointment only as a Corona precaution. Could this account for poor footfall?
Our visit was unannounced but I did notice the entrance was well policed. I have to say I really liked the goods on display. Not at all bling and very well constructed - with the rider that Mrs BnB could not get her giant phone into the small handbag she was eyeing up.
My take on the luxury market is that it is really a volume market characterised by exceptional margins aimed at the newly affluent or ostentatious fools with new credit cards. I don’t own a single item from LVMH’s vast catalogue but I’m very happy to own a portion of their profits.
I enjoyed your comparison with the car industry. I’m not sure if it holds water as the “quietly confident unostentatious middle classes” still have a few choices from a new Volvo through an ancient BMW estate (stealth-wealth incarnate - geddit) to the Malaysian and Korean EVs targeting young middle-class families.
Good luck with your investment and I hope the rumoured takeover comes through, because that would seem to me the the optimal result.
Strix (LON:KETL) Extremely helpful analysis on this one Paul, at 77p I was on the fence about buying some for recovery but not anymore, thank you very much.
Commiserations to Strix holders today after reading Paul's observations. Thank you Paul, my KETL is no longer boiling. Those insights are why I enjoy Stockopedia including members' comments too.
A few thoughts on £KETL.
I've held Strix for several years, but trimmed my holdings by 2/3 this year. The large directors' share sales in October 2021 were are red flag. (Note to Stockpedia: it would be great if there was a way to sift/get alerts for large directors share dealings).
The original investment thesis was the intellectual property/large worldwide market share and high cashflow relative to capital needs. I think that is (was?) partly true but it pays to be skeptical about company 'stories' possibly promoted by their brokers/retained PR.
There seems to be a reasonable explanation for the capex programme around 2019-2021, namely the construction of a more efficient factory in China. (This is a paraellel to food flavourings firm Treatt (LON:TET) which over recent years built a more modern, efficient factory in Norfolk. )
Regardless of the 'story', the share price, profit trajectory and directors sales are matters of hard fact.
The best case is that today's RNS can be taken at face value and somehow China finds a way out of its unnworkable and crazy zero covid policy. (Note to self: which other firms could be impacted by China disruption.) The best case is also that Strix's five year trail of business aquisitions somehow comes good. I think it is these rather than -in house capex which has been soaking up operating cashflow.
That said, it is not obvious looking at the Stockreport that the acquired businesses are particularly delivering. I wonder what IRR and payback the company expected. Has it been overpaying perhaps. And could Billi truly by selling boilding hot water taps for over £2K a pop?! I bought installed Quokeer taps in my last two kitchens - work brilliantly, high quality and more like £1.2K for top-of-their range.
On the low coroporation tax, I agree it is an amber warning light. When I worked in the electricity industry there was a generous UK tax break where a firm could make acquisition and then amortise the purchase consideration against its existing business. No idea if this is relevant or still exists. Strix is Isle of Man domiciled.
Overall I am inclined to sit on my hands with my residual shareholding. The danger is today's profit warning turns out to be the first of many. The opportunity is today's situation could represent a nadir. I think if we see substantial directors' buying that might be a cautious buy signal, so lets see.
The history of Director deals are displayed in Stocko under Accounts, Director Dealings for each share, when you are on the relevant share. Obviously RNS's are your other guide to current director deals.
The directors' dealings section is useful feature of Stocko. Companies are obliged to issue an RNS for every directors trade. Trouble is this swamps newsflow with (mainly) trivial trades such as DRIP investments. It would be nice to get alerts say for major trades e.g. £>50K worth.
Strix (LON:KETL) Although the key patent may have expired they have a secret manufacturing process for the tri-metallic switch blade, which they manufacture in the IoM, before shipping to China for assembly etc. They are also undercut by lower safety standard products, which they review and then ‘shop’ to regulated market authorities. Interestingly they have a good market share in China, exactly where you might have thought less regulated products might flourish. They are also improving the speed of automated manufacture of the controls. So its not quite as binary as just checking the status of their original patent.
As for corporation tax - this is generally 0% for non-retail, non-property profits in the Isle of Man isnt it? And in any case there seems to be consistent R&D activity, which would otherwise be deductible I imagine. All just IMHO.
Strix (LON:KETL) CEO and CFO got 5.7m nil priced options in 2020. Sold 1.1m in 2021 netting £3.5m Bought back 350k in the last year at cheaper prices. These shares they bought are the only ones they paid for that they own. Nil paid options are such a disgrace and make it hard to see what real skin in the game MT have.
In fairness the management team did purchase 0.322m shares in the October rights issue at a cost of £0.37m. That counts for something Id say.
D4t4 Solutions (LON:D4T4) (I hold) Interims to end Sept
On the face of it results look worse with a loss of £-1.346m (-0.277m) or an eps of -3.55p ( -0.277m) on revenue up from 7.6m to 8.1m. Not what you want to see from a growth software company priced at a not inconsiderable 50x historic earnings and 28x current year forecasts.
But is the company hiding its stronger light under a bushel?
There are reasons to be cheerful.
The company – very helpfully – confirms market expectations for the current year as £28m revenue and £4.2m adj pbt. Which is quite the turnaround from these interim figures. Is there reason to believe their optimism?
Yes. I think so.
All of which leads me to believe that despite the worsening appearance of H1 the FY forecasts are not overly ambitious and are likely to be met. There is scope for the results to be significantly exceeded but timing for this is not under D4T4 control and might well slip into FY24.
To overcome the H2 weighting and lack of control over partner led contracts D4T4 is investing in direct sales - and recently announced the launch of a product app on the Salesforce platform. Costs of sales and marketing for the direct channel have contribued to increased costs in H1.
The company is not short of cash. It recently returned 12.5p as a special dividend to shareholders and at H1 net was was a healthy £26.2m - a monster cash generator already with £10m cash generated in the year to September.
Hopefully share price weakens in the next few weeks as investors are put off by the lack of jam today and fail to look under the covers. I will likely add a few more as it appears that the prospects for this company are only improving, But of course, things rarely go according to my plan so DYOR,
cheers
Mark
Hello re D4t4 Solutions (LON:D4T4) - why has it got so much cash?
Hoarding over the long term? On a quick look it doesn't look like a company making cash in excess of reported earnings.
D4t4 Solutions (LON:D4T4)
Hello re D4t4 Solutions (LON:D4T4) - why has it got so much cash?
Hello Mojo. On the nail. As usual.
It's an intriguing one. And a relatively recent buy for me. Not sure that it has got so much cash. Yet. It’s cyclical and growing. Which makes it hard to judge the level of excess.
Net cash jumped from £11m at March year end to £26m at end of Sept.
Post period end a special dividend of 12.5p returned £5m.
I expect a similar cycle is underway through H2 as cash outflow covers costs while invoices raised towards year end are not received until after Mar23 (H1 FY24).
Caused by transition of the business from:
All of which tends to obscure progress made within the business. It’s this lack of visibility which has made me wary of the shares, though I like the new management, product and the market opportunity. At the same time the shares are not cheap.
The relationship with Pegasystems/Teradata is powerful but not ideal. Standalone products that can be marketed directly have been developed. API, cookie-less data option, Cloud implementation released and recently an app launched on the Salesforce platform. An experienced sales/marketing team has been acquired/brought in-house for the direct sales channel – all of which will increase costs in the short term, but places the company in a much improved position in the medium/longterm.
I like that the transition of the business and the market opportunity are being funded from the legacy business and is already profitable with plenty of cash backing. Probably enough to allow an acquisition if one presents, though they say thats not the case at the moment and are focusing upon their product development and launches.
But not cheap. I guess it all depends upon whether you like the management, products and market opportunity? I do, but not at any price – so I’m hoping for some weakness to increase my holding on current progress,
cheers
Mark
Thanks Mark. I don't know its history well and haven't read much.
I felt cautious on Bill Bruno instinctively when he joined. Nothing particularly wrong with him as a person but he seems a real sales sort of guy (the kind that will be positive and push on no matter what) and that felt a little at odds with a business that (from my unknowledgeable position!) seemed to be going through a rather technical and protracted transition and maybe needed something more conservative at the helm for a little bit. It's not a strong view just a vibe and if I'm wrong about where they are or on who Bill is then Mr Bruno could be the very right guy for the job. Just one of those intangible feel things...that are often wrong.
A more generic doubt I have is around their products and how they are positioned to sell them (again I emphasise this is poorly/partially informed). Do they have 3 products or 1? I kind of feel that unless they are selling one core product then they are ducking and diving around what companies need/want rather than hitting the main vein. Rolling out bits and pieces of solution rather than the solution. That makes me think that they have product that is reactive and therefore ultimately they will do a lot of defending around rather than product that is leading and continually makes its own case in use...so selling itself. We know that once IT systems are in place they tend to be sticky regardless of true necessity or essentialness as its becomes hard to change...but if you aren't holistically burning the path forward then you are always going to get chipped hard on price or what you provide for the price. A hard downturn or an innovative solution (independent or embedded in something else) could push down hard on their prospects? Or clients just drift away over time. Do they show real pricing power? Have the migrated and raised prices without significant client losses (numbers as much as value tho latter more important particularly if they cleaned out dead wood clients)?
The app/partnering with Salesforce (I believe it means they are in the ecosystem and that other 3rd party marketers on the platform might now sell them on to end users. rather than Salesforce selling them?) - I kind of see this route as okay to test and develop new product at low cost before you have the sales force and channels in place but a weak way to sell established core product. Again pushes my concerns re how well positioned their products is.
The own vs 3rd party IP thing confused me a little as to why it is so meaningful in terms of short run margin. Again probably my lack of knowledge (not deep dived) but it makes me feel anxious about where they are positioned with clients.
The above is all drive-by banalysis that is picking holes. It shows my dissonance in looking at them and maybe not getting it...plus having a reaction to Bruno (that could be very unfair)
D4t4 Solutions (LON:D4T4)
Oooh, Errr, Mojo!
Interesting, Based upon that I've no doubt that you are better off to keep on driving
For me? That's given me plenty to mull over. It's certainly not without it's issues. But then what is? Despite that it might still be an opportunity, at the moment they seem to be making good progress but I'm still not totally decided one way or another and will be watching continued progress closely.
As for Bruno. If you've not already done so I recomment that you - do not - listen to his podcast or look up an image. It will only serve to reinforce your preconceptions?
cheers
Mark
I've watched/listened...I don't dislike...I specifically wonder whether he's what they need...are they ready to sell like he wants? Do they need and integrator and base builder preparing the ground more for a growth push? If they are ready to push on the sales front then he's the type of guy.
Overall, my views are weakly held. The case just jangles in my mind rather than congeals.
Bill Bruno’s LinkedIn profile hits all my “businesss bollocks bingo” tests. He is “humbled by his appointment”, “passionate about data” and asks us to “reach out to him”. Textbook fail.
Haha. There can definitely be a culture difference and personally I put it down to that and that he's a sales guy (from other side of pond!). TBC I like the guy (he's defo got a sense of humour too)...its more about the company and where its at and whether he is the experience and skill set D4t4 Solutions (LON:D4T4) needs or is ready for...
...so I say all this fishing for someone to give me a comprehension of why D4T4 is the right biz at right time...not trashing at all -> I can see there could be something here. But I've laid out some of the (partially/poorly informed) things that hold me back. Maybe there's a presentation that answers a lot of this? (I did watch something this year)
Vertu Motors (LON:VTU)
Yesterday I drew attention to the potential acquisition of Helston Garages. Today it is reported that Yeomans has made the first move by buying 12 of the businesses within Helston. It may not be long before we hear if VTU have concluded a deal for part of the remainder.
see :
https://cardealermagazine.co.u...
re Mulberry
A few observations from what Paul would call my mystery shopping efforts in central Manchester. Mulberry has a small but very attractive range - my wife was reluctant to leave without buying something. And, like Ralph Lauren, there was no Black Friday discount offered - in contrast to Paul Smith. The shop however, just like the tumbleweed- strewn Burberry and Paul Smith, was not seeing much footfall. Cross the road to Selfridges and Harvey Nicks, where LVMH has a big presence, and their leather goods stalls are teeming with young, not particularly affluent, but presumably very brand-conscious consumers.
My take? Burberry, Mulberry et al are just trades. LVMH and Hermes are investments. The former is actual decent value today, the latter has to be seized on a big pullback like last summer.
how is LVMH an investment? it still has to feel the pinch of a recession.
how is LVMH an investment? it still has to feel the pinch of a recession.
Recessions don't last forever, and on a timeline of five years or more, then LVMH and the other luxury goods makers are likely to offer very decent returns. They're never really cheap.
As for Burberry (LON:BRBY) - well, I live in hope that it will find a way of delivering long term value. I've certainly waited long enough ...
timarr
how is LVMH an investment? it still has to feel the pinch of a recession
While almost every other retailer on the planet currently sees falling revenues and even collapse. Isn’t that the very definition of a good long term investment?
no for me it is the wrong time to buy. You can't keep upping prices forever - everyone is feeling the pinch including rich people. I think a lot of people are sheltering in those 'blue chip' stocks and it is a false sense of security.
everyone is feeling the pinch including rich people
Where is your evidence for this assertion? The nature of inflation is to disproportionately affect those of limited means. The genuinely wealthy are relatively untouched. Even today, employment opportunities and wage rises for highly skilled professionals - one (rather poor) definition of “rich” - are red hot.
This “pinch” you refer to is not showing up in the sales figures of LVMH and Hermes, Ferrari and Porsche. One of the reasons is that genuine luxury businesses constrain supply such that demand almost always exceeds their sales objectives. This protects margins and volumes. Bernard Arnault is the second richest man in the world. Think like him or simply ride his coat-tails!
Coincidentally, I have been amazed at how well shares in a fund called GAM Luxury Brands has held up despite goings on in China and of course the Russia situation. (I hold)
If the Mulberry (LON:MUL) product is good, and the brand has pricing power, then I'd argue that it is the best investment. As all they need to do is crank up the branding investment and marketing. And those are not rocket science.
But all the brand equity at Mulberry is concentrated in one label, which makes for a much riskier proposition, not to mention that the management at LVMH is evidently vastly superior. Compare Kering, whose revenues are virtually all from Gucci, to LVMH to see how this plays out over time. Sure, it could be a good trade over the short term and if a bid comes through. But I’m investing on a 10 year horizon.
hi Graham
re System1 (LON:SYS1) - I hold
Interims released today show an adjusted loss of £0.4m. Additionally there is an update on their strategy review which appears to be little more than the founder/CEO to base himself in USA to concentrate on building US sales. Also he is stepping down to become President with the existing COO to become CEO.
Doesn't sound a very inspiring strategic review outcome and the market doesn't like it either with SP down 12%.
Would appreciate your views please.
Snazzy
I've just had a quick skim but also came to the conclusion that the System1 (LON:SYS1) strategic update is a damp squib. Lots of words, not much actual actions or changes. Founder is probably still going to be pulling all the strings, even though giving up CEO position.
The fact is that they have only one good product at the moment, Test Your Ad, and the growth rate on that has slowed down. They've done all the easy sales to their existing client base, and struggling to get more on. Meanwhile, they took a mediocre consultancy business and wound that down - and there's no turning it back.
Now, if Test Your Ad was any good, clients would be banging down the door and they'd have no problems having 2,3,4 years of double digit growth. Yet, they've barely had 18 months of growth.
On top of that, management don't seem to grasp the concept of cost control, linked to revenue growth, and shareholder expectations. They've been increasing costs for over 12 months already; yet the promised revenue growth from that cost increase hasn't arrived. So why continue to double down on aggressive headcount increases and drive even more unprofitability?
So effectively, a doubling down strategy on Test Your Ad, and seeing if it can pivot to a few other use cases (small businesses, digital ads for example).
Just my initial read, I might have got something wrong, as I am planning to do a detailed read when I have time in the coming weeks.
It is funny how two people can look at the same thing and come to different conclusions. "It seems to me that the fundamental flaw in IGR’s business model, is that it’s a low margin business, and was not able to pass on big, unexpected increases in costs, to its customers. That should, over time, be fixable, and see the PBT margin possibly return to around the previous level of c.5%." My take would be that the world is moving to using less of what they do and add that to low margins, I think it is a pretty toxic long term picture. Certainly not a share I would participate in. That of course is investment!!
Mulberry (LON:MUL) so even the iconic high end brands are suffering but it would appear investing for the future, hopefully wisely, it all seems good strategic stuff, especially good to see stella margin retained. As a brand they certainly appear to walk the talk appealing to those with strong enviro views. All good for the future then.
MEDIA-Joules administrator on brink of rescue deal with Phase Eight-owner Foschini- Sky News
Joules Joules (LON:JOUL)
8 minutes ago
-- Source link: http://bit.ly/3UojcGS
-- Note: Reuters has not verified this story and does not
vouch for its accuracy
I'm assuming all shareholders have been wiped out already?
Graham reviewed Strix on Oct 5th, we do not hold but I've monitored it since then with a view to buying. I was also going to ask Graham or Paul to pass comment on today's TU. Last price 91.30 p, this surely won't be the only company to be rocked by China's Lockdowns.
OK, I'll take a look at Strix. I didn't like the numbers in the past, but can't remember why.
Strix (LON:KETL)
I understand, perhaps incorrectly, that the following patent, which expired in February, was the major patent on which Strix’s business model was based, and with the expiry of this patent other manufacturers can now use this IP.
https://patents.google.com/patent/EP1233649A1/pt
To be clear, I do not have a sufficient understanding of Strix’s business model, patent law or Strix’s other IP.
Does anyone more knowledgeable know if Strix has lost its moat?
Disclosure: no position
Seriously impressed with this comment!
Don't know about its moat but it has definitely gone off the boil :D
If that is true, shouldn't the company have told its owners? It is usual for companies to report on relevant patent expiries.
Strix have lots and lots of patents it would take weeks to figure out which was 'major'.
I think the accounts refer to over 150 patents.....
Strix (LON:KETL) Although the key patent may have expired they have a secret manufacturing process for the tri-metallic switch blade, which they manufacture in the IoM, before shipping to China for assembly etc. They are also undercut by lower safety standard products, which they review and then ‘shop’ to regulated market authorities. Interestingly they have a good market share in China, exactly where you might have thought less regulated products might flourish. They are also improving the speed of automated manufacture of the controls. So its not quite as binary as just checking the status of their original patent.
Strix are headquartered in the IoM. Not sure what the IoM corp tax rate is.
Re £STRIX IOM corporation tax is zero for manufacturers.
Paul, if you would look at Strix (LON:KETL) i'd appreciate it. The SP dropped this morning of over 20% based on their Trading Update.
Anyone looked in detail at Strix (LON:KETL)? I've avoided it before as looked too rich but after todays trading update appears to be on a multiple of sub 10* which looks more interesting. They are clearly struggling with China lockdown disruptions but maintaining / growing market share. Even after all that expect adj operating profit after tax of £23m so now on a PE of 9 which appears cheap.
Is there good reason for that? I notice debt has gone up in the last 2 years by about £25m to £61m so I'm less keen that debt is almost 3* PAT which feels a bit of a heavy burden in this environment.
Does anyone know where their secondary warehouse is? as mentioned in the update
looking a bit closer - they also bought a company called Billi that is not included in the £23m PAT for this year. So assuming the new business does £11m per historic trading then it seems Strix (LON:KETL) is now around £33m profits on a cap of £168m so a PE circa 5*
Is that really right?
on an EV / EBITDA basis £230m against say £40m+ so still 6*
I get the lockdowns disruption and the debt is too high imo but still - what am I missing?
Strix have just got back to me and inform me that their secondary warehouse is in Shen Zhen.
Thanks @Rebirth - so I wonder what the advantage of that is? Or are they just holding more stock
Stock is one reason.
Another is that Strix has its main factory in the Zengcheng district in Guangzhou, China, which northwest of Hong Kong and the second one in Shenzhen, which is in southeastern China. As China continues to pursue its no COVID-19 policy it just means Strix can try to offset the impact of regional lockdowns in China.
Strix (LON:KETL) I started to type this 15 minutes ago so apologies if subsequent posts duplicate this.
RNS: 'now anticipates adjusted profit after tax for the full year to be approximately £23m. The Board recognises that these uncertainties could continue into 2023.'
FY21 Adj profit after tax £31.4m (y/e 31/12/21)
So a decline of adj. profit after tax 27%. Share price at 09:14y down 34% so maybe a bit excessive. Not one I would want to buy on the day of the announcement, too easy for the fall to continue, but looking at the 5 year chart I think there is scope for a recovery IF the news from China doesn't get any worse (ie a re-run of Tiananmen Sq. ).
Michael - you are not factoring in the purchase of Billi which has just completed. It adds another £10m+ to next years profit (assuming historic trading)
Well, yes, but if they were confident about that why would they not say something to temper the inevitable market reaction to a 27% fall in FY22 profit? Seems to me they might have restricted visibility of next year.
Separate question - what does the panel think about including charts in posts? Personally I glaze over when confronted with figures, I can't do a thing without a visual representation. But I don't see many other members posting charts.
including charts in a post ...
For me, if the chart has labels / scale / legends, and i can read the text on the chart when it is inline in the comment so it all makes sense
it adds.
That chart is an interesting chart, but, only readable when opened in a new tab by itself.
To a degree in their core business I'd say the rns definitely alludes to that. But the Billi acquisition unlikely as there will inevitably be warranties attached to the sale
Zeus has a note out. Looks like todays profits warning is -17% against expectations so 33% does look a bit harsh.
Looks like reduced forecasts come in at £48m EBITDA for a full year inc Billi acquisition. I want to strip finance costs out of that which is £10m so really the business looks like expecting to generate £38m cashflow less tax and divi.
EV is expected to be £250m with debt at £83m....hmmm. so EV/EBIT is 6*
So on the positive side looks cheap at an earnings level. Acquisition has changed geographic mix and moved away from just controls to being closer to a 50/50 mix with water and appliance.
On the downside debt is too high at the wrong time and needs bringing down by at least £30m I'd say. Still too much reliance on China but reducing, with some limited visibility over trading there for the next few months.
on balance feels like todays reaction is a bit overdone. A range of 100-120p feels more like fair value. I might nibble at these levels
Strix (LON:KETL) has committed a lot to a recenty-opened manufacturing plant in China. Most of their customers (i.e. electrical kettle manufacturers) are in China. Obviously all are at risk from the onerous lockdowns in China and output of kettles will have dipped. I'm expecting this one to bounce though when those lockdowns end. Electric kettles have a finite life (average 3 years apparently) so a lot of the demand will not have been permanently lost, which is what I'm assuming is behind the re-opening of the warehouse to store manufactured components - presumably in China.
Debt is really becoming a concern. A lot of it has been built up by acquisitions in the area of water supply/ filtration products, but the investment in the Chinese manufacturing plant was unfortunately timed.
I hold.
Paul, thank you for your very quick analysis on £IGR
I did buy on the opening bell as it looked too good to be true on headline numbers, and when I saw the Progressive note I was disappointed by the forecast earnings. Together with your note and Progressive analysis I decided to close position until I have done proper research as it has some potential to be a good turnaround story if they can get it right in difficult circumstances.
Thanks again for prompt work,
Greyster
IG Design (LON:IGR) H1 results
Management webinar at 12 noon today. Register here.
Tomorrow, 1 December, we have Creightons (LON:CRL) H1 results with a webinar at 11am. Register here.
DSW Capital (LON:DSW) will release H1 results tomorrow, 1 December, with a webinar at 1pm. Last trading update indicated a strong H1 performance, on track to achieve full year expectations. Register for webinar here.
Cerillion (LON:CER) FY22 results were released on Monday. A record financial performance
Management webinar on Friday 2 December, 12 noon. Register here.
Loungers (LON:LGRS) interims out today. Some strong positives of growing their way through the current and foreseeable recesion.
Significant market out-performance with consistently strong trading
· Headline three-year LFL sales growth of +17.0% is testament to the strength of our brands and our teams
Financials versus last year's very good recovery are struggling but even here there are some bright lights- Rent to revenue ratio further improved to 4.7%
- Strong balance sheet with further year on year reduction in non property net debt
- Utility costs hedged in May 2020 through to September 2024 for the majority of the estate
· New site roll-out accelerated.- 11 new sites opened in the period, comprising eight Lounges and three Cosy Clubs. A further four sites have been opened post the 2 October half year end, three Lounges in Haywards Heath, Stratford upon Avon and Selby and a Cosy Club in Milton Keynes
- Fifth build team added, expanding our new site opening capacity to between 32 and 34 sites per year
· Development of our new roadside brand, Brightside
- Contracts exchanged to acquire four roadside sites
- On schedule to open our first Brightside site in early 2023
Current Trading and Outlook is ok, but query profitability balance versus growth/value for money to justify quite a high PER. Brightside will be an interesting development to watch.
· Positive momentum has continued over the first eight weeks of Q3, with the business consistently out-performing the sector and achieving strong like for like sales growth, with three-year LFL sales across the 32 weeks to 27 November of +17.4%
· Whilst there is no sign of the cost of living pressures abating, we remain optimistic looking ahead to trading over the Christmas period
· With 15 sites having opened year to date we remain on track to open a total of 30 new sites during the course of the financial year ending 16 April 2023, including our first Brightside site.
For Loungers (LON:LGRS) looking on the Brightside - get it? - there is a hint of Little Chef about this and looking at the sites they have chosen for this new development, and the queues on this particular road, there could be lots of people stopping there to break the boredom of the queues! (Why did Little Chef fail? They were generally adjacent to Travelodge's weren't they?)
Given the ever increasing number of Lounge and Cosy Clubs around the country, I wonder if they will be an affordable and - warm - pace to hang out this cold winter. Good for custom provided the majority of customers don't sit over 1 cup of coffee for 4 hours. Good warm place to work if they provide wifi!
Going back to the report, I was impressed by the hedging of the majority of utility costs in 2020 till late 2024. Not sure how many similar operations are i the same street on that front.
Restaurant (LON:RTN) are also hedged fully to the end of 2024 i believe if not further now. I personally think there is a strong read across into shares like this and their next update on trading will see a strong price recovery (in % terms! not saying it'll get back much above 50-60p but looks good at current price. Many times less than they paid for Wagamama (what a disaster bid that was)
Mulberry (LON:MUL) results out - headline loss:
FINANCIAL HIGHLIGHTS
· Group revenue during the period down 1% to £64.9m (2021: £65.7m)
o UK retail sales were impacted by the broader economic environment, down 10% to £34.1m (2021: £38.0m)
o China retail sales increased 6%, despite COVID-19 restrictions, which contributed to the 1% increase in Asia Pacific retail sales to £11.9m (2021: £11.8m)
o International retail sales remained in line with the same period last year at £17.5m (2021: £17.6m)
· Gross margin of 71% (2021: 69%) achieved due to a continued strategic focus on full-price sales and increased volume efficiencies
· Loss before tax excluding adjusting items for the period of £2.8m (2021: profit before tax excluding adjusting items £4.5m)1 reflecting additional investment in the Group
· Reported loss before tax of £3.8m (2021: profit before tax £10.2m which included business rates relief of £2.0m and a one-off profit on disposal of Paris lease of £5.7m)
Paul/Graham, are you covering the update? Thx
Mulberry (LON:MUL) - Cash down sharply. I guess due to setting up Sweden, buying out Australia and big stock level.
But energy costs fixed for 3 years.
Festive period key now.
Not surprisingly, Mulberry (LON:MUL) right back to where the rise started a few weeks ago. I'm not sure my heart condition is up to these sort of ups and downs. PS to self. Must find something more sedate - but occasionally surprises on the upside - like Alumasc (LON:ALU) with today's Asian contracts. PPS Hope they gt paid for them.
[edit] ◄Loungers (LGRS) ►H1-Oct rev up 53% (in line) but pretax £2.8m (£12.8m). Adj EBITDA margin 11% (21,5%). Is that in line? "Whilst there is no sign of the cost of living pressures abating, we remain optimistic looking ahead to trading over the Christmas period."
System1 System1 (LON:SYS1) have reported results today.
Carclo (LON:CAR) interims are in. Is this a pattern we will be seeing more of in 2023 for more companies?
Outlook
á Demand for the Group's products remains robust, but ongoing cost inflation is expected to exert downward pressure on margins throughout the second half and into the following year. As a result, the Board is expecting a second half performance similar to that of the first half.
á Increasing global interest rates are already impacting the cost of financing the Group and we expect this trend to continue, partly mitigated by our focus on cash management.
á The Board is positive about the medium to long term prospects for the Group, driven by structural growth drivers in our end-markets, our strong customer relationships and the opportunity to drive improved financial performance through a focus on operational excellence.
Mmm. The SP of Carclo (LON:CAR) heavily punished as expected
Is that Eps at 1.5p that much below expectations for H1? Full year expected was 3.6? The share price fall feels a bit excessive, albeit not surprised in the current environment.
I don't I watched Investor meet with Carclo this morning. I just find them very uninspiring. I keep thinking this will be worth a nibble but there are too many minus'.