Small Cap Value Report - Wed 5 June 2019 - CARD, IGP, GMD, FLO

Good morning, it's Paul here.
Apologies, I ran out of time & mental bandwidth yesterday afternoon, and couldn't finish the section on VP Group.
7-8am quick views
Card Factory (LON:CARD)
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, announces a trading update for the quarter ended 30 April 2019 to coincide with its Annual General Meeting to be held later today.
I reviewed the most recent accounts (FY 01/2019) here, concluding positively that this is a highly cash generative, good quality business, paying excellent & sustainable (in my view) high dividends. Stockopedia's computers like it too - a high StockRank of 94.
Key points are self-explanatory;
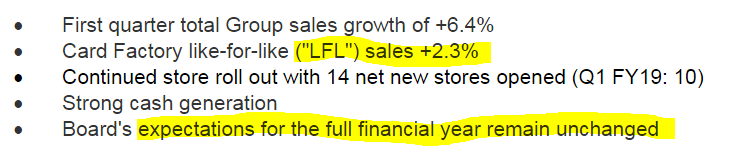
Weak prior year comparator period - how refreshing to see a company be honest, and admit this in an RNS. This boosts my level of trust in management.
- Total 979 stores - must be nearing saturation in the UK? Maybe not, as 50 new stores planned for this year
- CardFactory.co.uk - good start to the year (no figures given)
- Getting Personal - still struggling
- Net debt of £151.3m up 2.4% on a year earlier
Outlook comments sound reassuring;
Card Factory has seen a positive start to the year. Considering the uncertain macro outlook and the continuation of challenging consumer conditions, and with the key trading periods still to come, the Board expects LFL sales for the year to be marginally positive, with full year profit expectations remaining unchanged....
"Overall, Card Factory remains in a strong position, continuing to grow market share, with lessening cost headwinds and a platform for medium term growth."
My opinion - it's clearly doing something right, to be generating positive LFL sales, in an environment of falling shopper footfall (although that's likely to stabilise at some point, we just don't know when).
I particularly like the comment about "lessening cost headwinds"
Valuation - at 193p currently, the PER is just over 11. That feels good value, for a robust business paying a big divi yield. Although how much upside is there, given that earnings have been falling in recent years? EPS was c.20p in 2015-2018, but now seems to have settled around 17p (2019 actual, and 2020-21 forecast).
The main reason to hold is for the excellent divis. I continue to believe these are sustainable, from excellent cashflows.
This business is clearly a strong survivor on the high street, and should benefit from falling rents on lease renewals, offsetting other cost increases.
A thumbs up from me. I don't hold personally, as I only see limited potential upside on the share price. For income seekers however, it makes more sense to hold this long term.
Main report
Intercede (LON:IGP)
Share price: 40p (up c.7% today)
No. shares: 50.5m (potential 7.3m additional shares if convertible loans convert into equity)
Market cap: £20.2m
(at the time of writing, I hold a long position in this share)
Intercede, the leading specialist in digital identity, credential management and secure mobility, today announces its preliminary results for the year ended 31 March 2019.
This is one of my favourite shares, so I've spent most of the morning poring over its results statement. There's tons of positive stuff in the commentary. I might publish my annotated copy of the results statement, to save typing it all up.
Key financial points;
- Revenues up 10% to £10.1m
- Costs slashed, as new product development refocused on core product
- Very convincing turnaround, as profit after tax of £528k reported, compared with an equivalent loss of £3.8m last year.
- Profit after tax is the most meaningful number, due to nearly £1.0m in R&D tax credits being received each year, a highly material benefit
To simplify things, here's my bull/bear summary;
- Bull points
- Amazing quality of clients - hence validating quality of product
- New mgt (Apr 2018 new CEO) delivering ahead of plan - moved into profit a year early
- Development spend of £2.85m all expensed through P&L, none capitalised
- Recurring revenues about half of total. Forecast by broker at £6.3m in FY 03/2020
- Geographic expansion underway - first orders in S E Asia through partner, more expected
- Experts in a specialist niche - 1,000 man years of experience
- Takeover potential from USA - which is 69% of total sales. See below for sample customers - astonishing for a tiny AIM-listed company with only £20m market cap
- Priority under new management is sales/profit growth
- Computer security is a great space to be in - as many organisations need to address data breaches through weak passwords
- Forecasts look modest to me - scope to exceed expectations, judging from very positive narrative today
- New management credibility enhanced, by over-delivering on their plan to date
- Operational gearing - gross margin is almost 100%, so explosive upside if sales really start to grow strongly. That may not happen of course, and there have been false dawns before
- Major customers placing follow-on orders, which proves the product & service are good
Bear case
- False dawns before - revenues rose, but then fell backwards a few years ago
- Balance sheet receivables look high - I will do more checking on this
- Convertible loans are a nuisance, c.£5m debt effectively. Interest cost is 8%, payable quarterly. Conversion price (at option of holder) is 68.8125p. Repayable Dec 2021, so not an immediate issue, but would be nice to get these paid off
- Lumpy licence revenues, makes profit potentially volatile
- Large contract win on last day of financial year - without this, figures would have looked poor
- Highly illiquid shares - hence very difficult to get in or out
- "A number of challenges remain", and "distractions that have interfered with this focus in recent past" - what does this mean, and what are these unspecified problems?
Client list - Intercede products are deployed in 90 places worldwide. So a fairly focused product, with major organisations. Check out the astonishing list of clients below, reported in today's RNS. This is the main reason I bought Intercede shares some time ago;
Sample Customers:
US Department of Homeland Security
Boeing
Wells Fargo
Deutsche Telekom
Kuwait Public Authority for Civil Information
Airbus
US Nuclear Regulatory Commission
Booz Allen Hamilton
US Social Security Administration
Lockheed Martin
United Health Group
Northrop Grumman
UK Government Ministry of Defence
ANZ,
Handelsbanken
REWE
BASF
Coutts
Australian Government Department of Defence
Swedbank
RDW
US Federal Aviation Administration.
Given the above, I'm amazed a larger (probably American) software group hasn't bought Intercede. If that happened, it could be at a big premium - that's what I'm hoping for!
Shareholders - 63% of the shares are held by >3%, as shown below. This is from the company's website, updated on 18 Feb 2019;
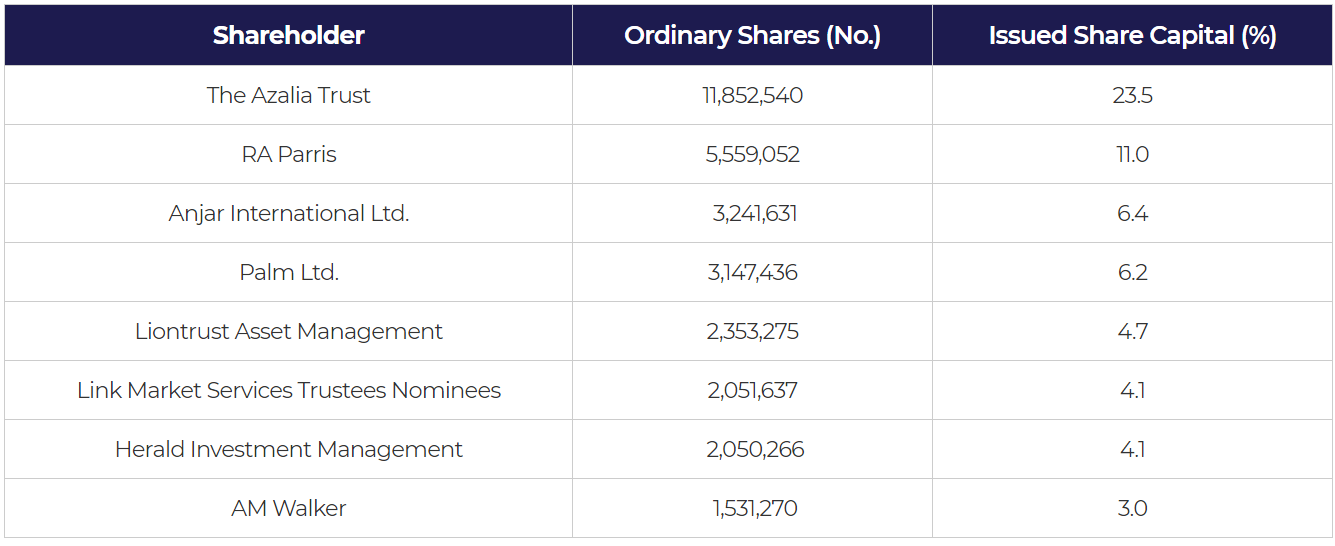
The Azalia Trust - largest shareholder - is connected to a Director, Jacques Tredoux.
RA Parris is the founder, and former boss.
The above shareholdings structure ensures that nobody could swoop on the company and buy it on the cheap.
My opinion - I'm very pleased with the progress made to date.
It's obviously a higher risk share, due to lumpy revenues, lack of liquidity (which means you can't easily get out, if something goes wrong). However, it's the upside potential that really interests me. You only have to look back on the chart, to see the valuation this company commanded when it was delivering strong growth. New management seems to have a credible plan to get things back on track, and that amazing client list seems unique for a company this small.
It doesn't need to raise cash any time soon, so all in all, I think this could potentially be very interesting.
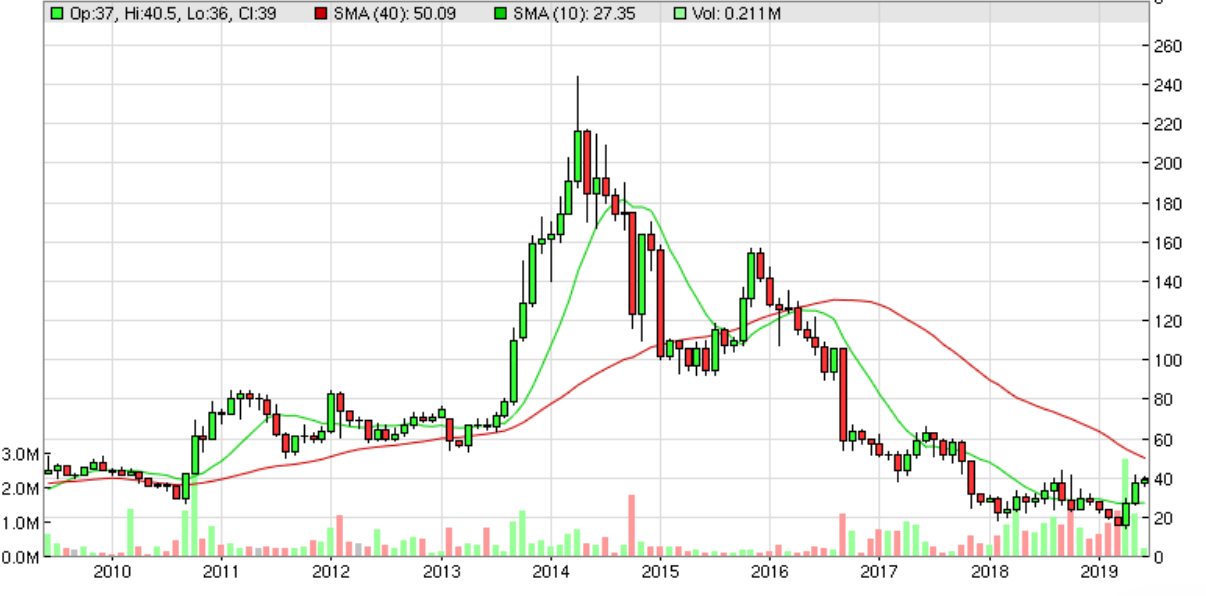
10-year chart below. Bear in mind that the share count has only risen about 10% since 2013, so if things go really well, c.200p could be possible again, perhaps? What are the chances of that happening? No idea! That depends how well (or not) the management execute.
** BREAKING NEWS **
GAME Digital (LON:GMD)
Lowball takeover bid from Sports Direct, at 30p.
They've acquired a block of shares, and now own 38.49% of the company. So going over 30% has triggered a bid under the takeover rules.
It says this is final, and the offer price won't be increased.
This is a lousy price, and means that, if successful, Sports Direct will get all the upside from the new BELONG format.
I speculated about Sports Direct buying the whole thing some time ago, but didn't imagine the offer price would be as low as 30p.
I imagine this bid could succeed, as there must be plenty of stake bulls, who would welcome a liquidity event to dispose of larger holdings that can't be sold through the market, due to lack of liquidity.
Pity, as the new BELONG format looked quite good.
A higher competing offer looks extremely unlikely, as Sports Direct has a blocking shareholding effectively, plus is intertwined with GMD on the JV re BELONG store roll out.
Therefore the logical thing to do, in my view, would be to accept the 30p offer.
Flowtech Fluidpower (LON:FLO)
Many thanks to reader "Luthrin" who flagged up a trading update from this group, released annoyingly during market hours, at c.08:46. This is a very annoying practice, which some companies adopt, in an attempt to issue the news simultaneously to the market, and the people actually at the AGM.
Since most small cap AGMs might only have 1 or 2 shareholders physically present, it makes no sense at all to inconvenience the thousands of other shareholders by announcing a trading update when most will be busy doing other things, and may not see it.
I know a lot of PRs and brokers read my reports, so please would you all urge clients to put out trading updates at 07:00 only. If a profit warning may be necessary, then urge clients to hold the board meeting, and inform the broker, after the market has closed. Then issue the RNS in the morning, at 7 am.
Back to FLO. Today is says;
"I am pleased with the progress that the new Management team has made in 2019. The focus on cost and working capital management combined with investing in our people and systems is clearly proving to be an appropriate strategy to adopt. This will provide a platform for our future growth ambitions, both through organic means and, at an appropriate time, further suitable acquisition activity.
In our Q1 trading update released in April we reported that revenue during the first three months of the current year increased by 14%, 4% of which was through organic means. The business has continued to achieve organic growth in the subsequent two-month period.
The Directors remain confident about the future; we expect our underlying performance to deliver another year of solid progress and we look forward to providing our next Trading Update for Q2 in early July. Overall our trading is in line with market expectations."
That sounds fine. A cynic might point out that the second paragraph doesn't state what level of organic growth is was achieved in the most recent 2 months.
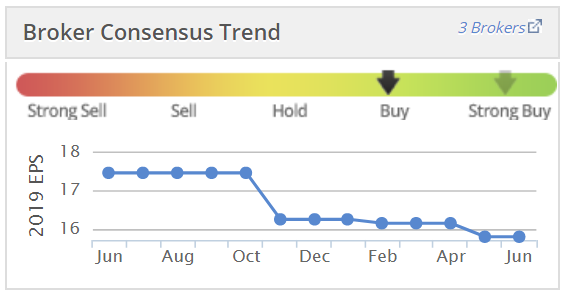
In line with expectations is nice, but the bar has been lowered several times;
My opinion - I reviewed the last full year figures in some detail here on 16 Apr 2019.
Nothing much has changed since then.
Jolly good, that's me done for the day. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
GAME Digital (LON:GMD) just another nail in the Sports Direct coffin.
Keep moving and reality can't catch up with Sports Direct and trader Mike. When reality does drop by perhaps the plan is to be TBTF and get bailed out :O
TBH it could be genius strategy that is hard to see through the fog as there will be a future for the high street
Re Intercede
Just wanted to add my thoughts on Intercede as I’ve been a long term holder.
I think these results are good and they have the potential to grow from here. Some of the growth opportunities include: winning further business in Asia, Federal users putting their existing credentials onto mobile devices and Intercede are well placed to win further business here (these are referred to as derived credentials in the report) and they have further opportunities to sell mobile solutions to a country’s citizens where a government will be the customer. In the last case , a citizen will use Intercede’s authentication solutions to authenticate to government websites or apps and possibly to authenticate to other sites such as banking too. This seems exciting to me.
For the sake of balance, Intercede have cut their staff numbers strongly over the last year or two. They were previously exploring the opportunity to step into some very wide markets with their solutions targeting widespread consumer authentication on the internet when using mobile devices and authentication of devices within the internet of things. The CEO says a little on this in his report. It sounds like such breakout opportunities are not imminent and may have receded in probability but they could remain a possibility for the future as the market evolves. Intercede does work (closely I believe) with some major players in the cyber security space such as Gemalto (now a part of Thales). That could stand them in good stead should the wider market move towards an embrace of PKI (public key infrastructure- their technology is based on this architecture) solutions. Even without any such breakout opportunities, it sounds like they have growth potential over the medium term.
I continue to hold.
Regards
Andrew
Thanks for your write up about Intercede (LON:IGP) Paul,
If anyone is interested, the broker note from finncap is here https://researchlibrary.finncap.com/File/View?file=a4a09769-736f-4187-ab6e-623b457b6b1a .
They reiterate a target price of 80p (unchanged from the last note at the time of the trading update).
The chart shows resistance around 42p which I suspect will get broken on any more positive news.
cheers
Francis
Re GAME Digital (LON:GMD)
I've been commenting here for a while about SPD's increased holding a few months ago and now we know why. Personally I was hoping for 40-50p which was why I accumulated so many shares since the big drop (after their abortive attempt to move out of AIM) but it's a done deal now so time to move on.
Cheers
Francis
Hi Francis
Re GAME Digital (LON:GMD) I too thought 30p was a done deal until I saw management's response for holders to do nothing for the moment!
Does anyone know if this is a normal response? I would have thought, like you, that it was pretty much a done deal.
Thanks
A
Hi Abtan, I don't know the answer to this. Ashley has 38% so it depends if he can force this through at whatever price he wants. Paul reckoned this was a done deal but perhaps management can summon the votes to get a better deal; problem is, I don't think (given Ashley's Belong deal and existing shareholding) anyone else will bid. If they've reduced their cost base and performance of the retail estate has improved, even without any material progress with Belong rollout (I reckon SPD are holding Belong back), the buyout price would be much higher. So the timing is astute from Ashley as results not due until August. Who knows how this will play out?
Back to Love Island!
Cheers
Francis
Hi Abtan & Francis,
FWIW I put some additional thoughts over on the Game specific thread
To answer the specific question though, the management response is entirely normal - "do nothing for now, we will give you our opinion in due course." (You can't I believe accept the bid yet until the offer document is circulated in any case, although you could sell in the market at a small discount.)
The only thing this really tell us is that the bid was not discussed with management in advance.
Personally I don't think it is a done deal yet - I cannot see there being a counter bid but it is possible that not enough shares accept the offer to get to the 75% where they can be de-listed.
So, discounting a counter bid the three outcomes are :
1. The bid fails to get to 75% and the shares remain listed - but you'd be holding a share where Ashley / SPD has substantial influence if not control.
2. The 75% threshold is reached and the shares de-list (Usually I think there would be an opportunity to sell once this has become apparent and before the de-listing)
3. The 90% threshold is reached and any unbid shares are subject to compulsory purchase.
Shareholders have at least up until the first closing date of the bid to make their minds up.
GAME Digital (LON:GMD)
I hope Ashley has £350 mill flowing into his coffers in the next week or so - so that he has the money to pay for GMD - who would have believed his one decent big investment that seems to be doing ok nowadays is a football club.
GAME Digital (LON:GMD)
Well that’s a 30% profit on my small speculative holding, but hasn’t Ashley got this dirt cheap????
Dave
What is mental bandwith?
Thanks
John
Hi Johns54,
I've been mulling your question this afternoon amid all the exciting news flow.
I can only surmise that Paul had depleted his cognitive powers and needed a rest.
Alternatively, he could have run out of his supply of the pharmaceutical he takes to aid his analytical abilities, (street name "Mental Bandwidth"), and so was unable to continue his analysis.
Who knows.
Cheers
Francis
A bit of a bolt out of the blue as far as I am concerned.
Sport's Direct have just acquired c. 15m Shares in GAME Digital (LON:GMD) from Marlborough UK Micro-Cap Growth Fund taking their holding to 38.49% and forcing a mandatory bid at 30p / share.
I had been very sceptical of the idea that Mike Ashley would go above the 30% and bid here , but clearly I was wrong. Shareholders that were banking on a bid however I think were hoping for something quite a lot higher.
No position here, but it will be interesting to see how that pans out.
(Ha I see nicobos beat me to it)
GAME Digital (LON:GMD) for those that haven't seen - Mashley has made an offer at 30p for the Group.
"The Offer of 30 pence in cash for each GAME Share is final and the offer price will not be increased."
Seems a bit tight ! Any views?
Card Factory (LON:CARD) is the type of company I think is very interesting at the moment i.e good quality but at a reasonable price having been pulled down by the general negativity surrounding the retail sector. The market for greeting cards seemed to be something of a dead duck going back a few years but has proved quite resilient. A Card factory store opened in my town a few weeks ago and seems fairly busy (incidentally it has positioned itself within throwing distance of both a large Paperchase and a Clinton's Cards - surely they can't all survive?)
It also has that very attractive dividend and considering a FCF yield of >9% it looks to be safe for now as alluded to by Paul.
Having run through the figures from the last annual report and today's TU this morning I have noticed a few areas of concern that are preventing me from opening a position in this one at the moment.
- Operating margin has fallen yr on yr for the past 4 years (from 23.30% to 16.24%)
- NTAV is -£92.40m (maybe more now net debt has increased) as Paul alluded to in the last report on this company this is not such an issue as receivables are almost not existent and cash generation is so strong, however in a market like today's where uncertainty lurks in the background why take the risk on a company whose balance sheet is not rock solid.
- Expanding on this net debt at £151m is around 2 x operating profit - not a deal breaker but hardly ideal.
- Whilst on the face of it ROCE looks very good at 18.50% CARD has quite a large operating lease commitment c. £167m (admittedly this is weighted more heavily towards shorter term leases which is desirable) When factored in the lease adjusted ROCE come down to 10.53% and as with operating margin is on quite a steep downward trend from 22.50% in 2015)
I may well be being overly cautious with this one but perhaps it isn't quite as rosy as the 94 stock rank might suggest.
888 Holdings (LON:888)
Just coming back to 888 from yesterday.
I always like to look at cash flow.
Operating cash generated in FY18 was USD $42.1m but this was impacted by a one off payment of 24.6m on German VAT. Add this back in gives 66.7m which does cover the 56.6m dividend payment. But I note they spent 12m on intangible assets and similar in 2017 so I suspect the real OP cash is 54.7m which just covers the dividend.
No debt and net cash of 75.9m ex customer deposits (the Stocko number is gross). So no bankruptcy risk.
From yesterday’s announcement hopefully the revenues have stablised. They have a pilot in the USA which may or may not come to anything as there is noise around the DOJ view on the legals.
With a dividend yield of 6.7% and PE around 10.6x at today’s price of 148p it’s probably priced about right in terms of the risk potential for further regulatory costs. But upside if they can keep generating this level of cash and dividends.
I did buy a few yesterday
888 Holdings (LON:888)
jwebster
Nice to know i am not the only madman who picked up shares yesterday (mad as in the chart was not saying buy lol)
But I note they spent 12m on intangible assets and similar in 2017 so I suspect the real OP cash is 54.7m which just covers the dividend.
I wouldn't necessarily agree with that - its made a bit messy by the currency translations etc- i have done my calcs coming from a different angle and here they are.
If we say eps is 11.5 p and dividend per share is 8.8p - thats a surplus of 2.7p per share - say £10 mill surplus. caveat i am presuming EPS quoted is after including amorisation total !! - i don't know that for certain.
they might have spent 12 mill+ on intangibles but there was a matching amortisation charge in the accounts which makes neutral situation. I would say its an unknown though what they need to spend each year in that regard to stay still - hopefully purchases will add to earnings rather than just keep them stable who knows.
Being a bookmaker i would expect the basic cash conversion of profits to be a given - so that only leaves other items which make the difference and i would presume they are more one of in nature and can be excluded? Looking at last year these included $40 mill cash going out in reduced customer deposits and reduced trade payable - these two totals have been factored in before arriving at the $42.1 mill for the year and i would deffo see them as being ignored as swings and roundabouts numbers so adding them back cashflow. I guess that would only leave "exceptionals as the fly in the ointment in the unknown stakes" - as i am guessing they will be after the quoted eps - but i don't know that for sure.
Final Note based om 368 mill shares and dividend of $12.2 cents - that only comes to cash cost of $45 mill - or £35 mill - so it looks like the cash payout of dividends in 2018 was more than 100% of the voted divi too.
888 Holdings (LON:888)
Yes, actually the cash dividend payments cross reporting years so the 56.6m paid is really the higher 2017 dividend number as:
An interim dividend of 4.2¢ per share was paid on 31 October 2018 (US$15.2 million) and a final dividend of 5.9¢ per share plus an additional one-off 5.6¢ per share were paid on 11 May 2018 (US$41.4 million)
So the 56.6m relates to USD 15.7c per share. Yes, a reduced dividend of 12.2c will cost around USD $45m
Agree the customer cash deposit movements shouldn't be counted so add back $12.1m but maybe subtract a similar amount for the annoying items buried under "Cash flows from investing activities" which eat up a similar amount.
All in all, the 2018 12.2c dividend looks well covered by cash
As for reading charts, well, on that programme we would would have to wait months for a flat consolidation period on low volume to slowly shake out weak hands until gone. As that hasn't happened, I'm prepared for the fact 888 share price will be jumpy all over the place as weak hands will be keen to sell any rips I'm sure.
This is one to buy and hold as only proven cash generation combined with good div's will consolidate the price, how long will that take? Could be a while yet. I don't know but figure the odds are ok at this price point.
Back in September I noted on SCVR that I was disappointed in Premier Technical Services (LON:PTSG) to see that the stock rewards to Roger Teasdale as Managing Director were based on EBITDA a non-statuary number open to any amount of manipulation. In PTSG's case the adjustment includes stock remuneration so that however much is paid it does not affect the EBITDA on which it is based. Prima facie this is outrageous. Even more so if you recognize that the total stock remuneration reduced the statutory profit by more than 50%.
At the beginning of 2018 the share price was 190p, at the end of the year it was 139p and today, as the stock award appears in the RNS, it is 72p. So as a (maybe foolish) holder this what I am looking at.
What Roger Teasdale is looking at is being given over 2% of the company (£2.3mm even today).
Mr Teasdale does not look like the type to blush deeply and refuse the reward, but surely John Foley , Alan Howarth and Michael Higgins (the Remuneration Committee) could spare time to mull over what it means to share profits with the owners of a public company, one that I still believe is a good business.
Just wanted to know if anyone else on here as stock in Bidstack BIDS it has been my best performing share this year by some distance - essentially puts adverts into computer games ie perimeter boards inside football stadiums - new business with dome heavy hitters on the board but not an area that I know well - does anyone else have thoughts
I look on with jealously and incredulity at Bidstack (LON:BIDS). A friend of mine backed it in angel round...beers on him.
£75m with reported revenue for FY18 of £300k.
This year they have raised some more and doing a lot of hiring. Raised £5m cash. Very likely they will need to raise quite a bit more before they get to profitability as there's a lot of operational capability to build out to support the tech.
This was the quickest every UK from seed to listing stock. That seems a bit trophy exercise to me....however it could be a genius founder taking no prisoners. Defo an area to move fast
They are on an advertising bidding platform but its with a startup company rather than something big and established.
Their thing of putting ads onto billboards in games is cool....but its yet to be proven as very effective and yet to establish a value for advertisers...will they pay a lot or is it something minimal and OTT synced adverts with other devices on same wifi the dream advertising space for the distracted generation?
For my sins I own Taptica International (LON:TAP) (buying at this kind of price so not been rinsed.....yet!). The whole space is very high flux and hard work to survive...my gamble is that TAP now how to do it and have a product suite that has value and good way to target customers
I actually sold half of my BIDS today in a rare moment of sensibility! It could be a well ramped stock but the story is good and makes sense however we need to see some traction and real numbers - I can understand how big the market could be but just have no idea if the wholething is viable. My problem is that it was not ahuge investment, I sometimes buy small amounts as a memory bank aid, I did it with Tarsus a few weeks ago and never increased my holding which is typical. Anyway if it goes to zero tomorrow I have taken enough out to have amde a profit so it will not feel to awful!
I'm also not blown away by PCF (LON:PCF) results and neither is the market judging by muted reaction. I think Graham is a holder so maybe he could provide some thoughts on what he makes of these interims? Cheers
I hold PCF (LON:PCF) and I don't find any concerns at today's results, in fact rather the reverse. The market has always treated this company with some disdain, possibly because of its majority ownership by the Bermuda bank, but I see progress running as predicted or better.
It had targets to increase customers, portfolios, hold their costs while investing, diversify their offering and maintain a strong capital base. All of these have been done, mostly ahead of schedule and the loan impairment charge still eld to a very creditable 0.4% (adjusted for IFRS 9).
I don't know what would be required to "blow you away", but this is a bank and too much excitement would make me nervous!
£K3C announcement today is really a disappointment if looked at rationally as they are re-confirming no conversion of bigger corporate finance customers in last couple of months. After the bounce they are on a high teens p/e (profit will be £3.5-4m so >15x) following a year when they've failed to bag a big deal and revenues and earnings fell precipitously. Volume this morning 10x the daily already. Wow! There's a lot of people loving this. Zoomy stock. Implicitly people expecting the big fish to fall into place in FY20. I'm an investor purchasing when came down to this price couple of months ago. I reckon it comes down without positive RNS news on big customer ahead of interim as I think people looking at headlines and not the actual. Good long term business though.
Call me grouchy but I looked at PCF (LON:PCF) and met Maybury couple of months ago and I reckon these results are max passable. Its very tightly held by strategic backer (Caribbean family office) so this is quite a thin share for mkt cap. Maybury been out promoting hard in recent months. Why? I didn't read whole release but above someone say they aint capital raising....I thought this would be on the cards again. Funding is a bit harder going forward compounded by balance sheet growth as BoE no longer dishing out near free funding. So got to go to interbank funding market to fill the gap between deposits and lending. If the organic growth is good why is the CEO working it so hard? Something coming - raise, big placement from holder?
In addition, impairment rate rising with balance sheet expanding so fast is a bit of a nervy sign....particularly as recent new business lines touted as lower risk. Did they expand balance sheet ahead of their risk management capabilities?
PCF (LON:PCF)
mojomogoz
Call me grouchy but I looked at PCF (LON:PCF) and met Maybury couple of months ago and I reckon these results are max passable. Its very tightly held by strategic backer (Caribbean family office) so this is quite a thin share for mkt cap. Maybury been out promoting hard in recent months. Why? I didn't read whole release but above someone say they aint capital raising.
this is what they said about capital raising - they are current financing a facility but after that it appears they have no medium term plans - my earlier post could have clearer about that . so perhaps the promoting is with regard to the current £15 mill they are finalising.
per the company
On 11 March 2019 the Bank raised £10.75 million of new equity to support its next phase of growth·Additionally, we are finalising a £15 million Tier 2 capital facility, to optimise the composition and cost of the Bank's capital base and to support organic growth, eliminating the need for further capital in the medium-term. We expect this to be in place in June
mojomogoz
Funding is a bit harder going forward compounded by balance sheet growth as BoE no longer dishing out near free funding. So got to go to interbank funding market to fill the gap between deposits and lending.
do the specific comments below by the company not ease the funding concerns somewhat? - everything seems fine to me in that regard as newbie looking at bank accounts - although i am not sure what % they need to get to without using interbank for it not to be an issue. I am guessing they won't have to add much more onto savings rates to keep the deposits flowing into the coffers.
per the company
The Group's total funding cost fell to 2.4% (2018: 3.5%) as we improved the efficiency of the Bank's treasury structure and continued to replace higher cost wholesale funding. The lending portfolio is now, in the main, funded by retail deposits of £204 million (2018: £108 million) and the support of over 4,500 savings customers.
Hi rmillaree
I am not PCF (LON:PCF) expert and take my comments as loosely informed. I have spoken with CEO and I'll stick by my comment that he's selling his stock hard....not necessarily bad but does mean he's pushing this expectation.
I will try to look when I have time. Don't find reference to financing facility based on quick word search. They look to me like they will need financing sooner rather than later due to pace of their growth. That said they have taken on some shorter duration business I believe so that should see liabilities reverse of balance sheet.
Strangely, they could run into duration mismatch in an odd fashion in that they could find the duration of their customer deposits longer than some of their short term financing they are looking for growth through....this suggests they are going to look to tap interbank market for more of their financing again.
The margin of safety looks fairly narrow so any hiccups from rapid balance sheet expansion (or economic cycle woes) might be challenging.
I could be very off beam. I should look. I'm only likely to invest in this situation when I can see a prob and understand how they deal with it otherwise its hard to get grounded on the quality of their growth.
I own 1pm (LON:OPM) (bought around this price earlier this year and late last). Its got challenges that people have pointed out. Interestingly they did not grow lending as much as they could have wish was a conscious decision but also shows restrictions on their funding capability (a negative and risk for them). But I was more interested in this than PCF as I like the credit risk they have more. IMO they are asset back lending to businesses that are higher credit rating than they are officially given but if you are small company you are given very high risk rating (like sub prime) - so the earnings is in the spread rather than the leverage. CEO Maybury at PCF disagreed with me on this and claimed there was no effective credit spread difference with them and OPM ....but as a bank I don't think this can be right as capital requirements influence what quality you can lend at. The result of this is that I am suspicious that PCF will lend to similar quality businesses but at lower spread as they are forced to by regulatory framework they are in (got to rate the business lower risk to make the loans than OPM do). This could cause negative surprise to PCF....and I note their impairments went up!
Make sense? I might be wrong but I feel there's value and margin of safety in OPM....of course there is funding risk
K3C - yes , EBITDA at upper end of expectations of £5M .... but these are revised down expectations due to delays from earlier in the year. (note had already done £3.1M at H1.....so significant reduction in H2, as signposted)
H1 eps of 5.8p.....
H2 eps of circa 4 p ????
gives FY eps of circa 10p ....well down on 14p eps of prior year and still below eps forecast of 12p.
Share price at 130p = PEx13 based on current performance.
Key questions.... will delayed transactions flow through & will ongoing political flux cause further delays?.
Cheers
jakedog2
jake - pe at least 15 and probably a bit higher and at 17ish given 20% bounce this morning
Flowtech Fluidpower (LON:FLO)
The company released an AGM statement at 08:46 that some may have missed.
Thanks for sharing.
Flowtech Fluidpower (LON:FLO) need a boring year or two delivering on organic, growth, paying down some of the debt and bringing efficiencies into the current businesses.
As long as they do that I can see further upside on their recent increases. After that they can go back to shopping :-)
Note I am long on this and continue to see it as a good company who got burnt a bit last year trying to bring in too many companies at once
Intercede (LON:IGP)
Hi Paul,
Re: intercede
On a quick read through, a couple of questions arise that you may well cover in your report.
* LFL revenue increase, is the 10% adjusted for FX, I didn’t see this mentioned.
* revenue model, software sales & maintenance- is there any move to a subscription model? I see this as a key element now to investing in software businesses.
* a great client list but relatively anemic growth (admittedly during a painful restructure) - can they upsell or sell more, this is part of the problem with license sales, well’s Fargo great, but is there more to come from Wells Fargo.
* resellers- massive list but are there any KPI’s showing where revenue is coming from. This many resellers & a great product could/should be excellent growth.
* they moved away from mass market (and cut out the costs), but does the future include mass market in a different form.
I may have missed these items & I will read further as looks interesting, but would appreciate your thoughts.
Thanks john
£K3C positive update here saying will be delivering results at upper end of expectations and next year will be in line. Strong pipeline of deals coming up. Will this halt the rapid decline of the share price which has been brutal. This is a company which admits to being impacted by Brexit and the delay on the exit. Does this mean that once Brexit is sorted we'll see a significant bounce back?
Also good trading results from GB (LON:GBG). An acquisitive IT company moving from a net cash to a net debt position due to acquisitions. Market cap maybe too big now for Paul to cover but always interesting to read comments from people who follow this share. It has been a good performer for me over the years and keeps delivering positive results.
For those following - the news today is that Non-Standard Finance (LON:NSF) opportunistic nil premium reverse takeover offer of Provident Financial (LON:PFG) (8.88 NSF shares for 1 PFG) is going to to lapse having failed (spectacularly !) to have have gained additional support for its proposed beyond its original sponsors (Woodford/Invesco/Marathon) who together held both 50% of PFG and NSF.
Costs from the failed deal are estimated at £10Mn for NSF (almost 1yrs profit !) and £20Mn for PFG. Reputations from the personal mud slinging have also been hurt on both sides. BOTH parties share prices have tanked during the bid process.
As an NSF shareholder I am disappointed - especially as I thought adding NSF's EverydayLoans network and Guarantor Lending brands to the Vanquis bank credit card operations made a lot of sense. However, from the PFG side I can understand why it was less than attractive and the organizational upheaval was an additional risk and distraction after so much recent turbulence already.
Perhaps in time the tables will turn and PFG will buy NSF which I still think is building a fantastic franchise in an unloved part of the credit market.
Interesting to see if either or both now bounce back as I think both are now undervalued (although not without risk!)
PCF (LON:PCF) - all seems solid enough (one caveat ref debt provisions) - mention of organic growth and need for no more immediate funding is good.
Interest net margin trending down but they seem to have more than compensated with the reduced borrowing costs.
Not really my thing financials of financial companies as basically they probably have the ability to hide away anything they don't like the look of. Someone tell me the banks didn't actually fully realise what the the full ppi hit would years before they provided for those expected losses based on past misdemeanours.
Note the headline "operating income" is a bit of a phony figure imho as it ignores most of the business expenses.
The main danger must be bad debt provisions (Cattles anyone?) - here is a section ref impairment notes - the figure is material in comparison to the pre tax profit of £33.2 mill - so this company will only ever be as good as their debtor book. I don't know much about the quality of this - hopefully a varied portfolio and reasonably short payback period will mean there is no reason to believe this will blow up. I hope i am reading things wrong or they are missing a decimal point or a not when they say 95% of portfolio is past due (cough)
Impairment losses in the period were £1.2 million (2018: £0.6 million), which represents a charge of 0.9% (2018: 0.5%) of which 0.1% was attributable to IFRS 9. This charge is consistent with the underlying loss rates expected from the portfolio going forward. As previously reported, past accounting periods have benefited from significant recoveries from legacy customers that defaulted during the financial crisis, but these are now becoming immaterial to overall performance. The part of the portfolio reported as 'past due' deteriorated slightly in the period to 95% (2018: 96%)
Also, for anyone interested, Malvern International (LON:MLVN) said they would report their year end in May. I contacted them a couple of days ago and got a terse reply saying they would come out later this week. For such a small company, five months seems a very long time to report results - red flag? I bought in opportunistically a few months ago after that large fund sold their shares and am hoping nothing is amiss.
cheers
Francis
Morning Francis,
I agree that 5 months is too long to publish accounts, re Malvern International (LON:MLVN)
Mind you, I always raved about how quickly Staffline (LON:STAF) published its accounts, and look what happened there!
Regards, Paul.
re Malvern International (LON:MLVN) I had some dealings with a previous incarnation of this company in the past and was familiar with their Singapore operation, I would regard the late accounts as a red flag were the company not already on my bargepole list.
Andyi
Francis. I saw Malvern International (LON:MLVN) present when at Mello last month and there they said (according to my notes) that the 2018 results had not then been released yet because of the accountants needing to approve the effects of IFRS changes, which struck me as a vague reason- as IFRS changes affect all companies, nearly every year.
Good morning Paul,
Would like to get your views on Intercede (LON:IGP) 's results. Profit of £0.5 a year ahead of plan, cash up to £3.2 and good pipeline of prospects. I started a 25p position late last year and added at 17p a couple of months ago - I have you to thank for initially flagging this so thank you (sp today is 37p), i owe you a few beers!
cheers
Francis
PCF (LON:PCF)
Interim figures look good. Confident outlook statements. Hopefully might move this from the low placing price.
Phil
Small position
Any thoughts on Impax Asset Management (LON:IPX) welcome please. Aum up, eps down. No position. Ta!
I would also welcome your thoughts on Impax Asset Management (LON:IPX), the market seems the have reacted negatively to the Rns, despite it being positive overall ( except eps down, now exactly sure why).
My morning smallcap tweet:
£K3C, Fox Marble Holdings (LON:FOX)
K3 Capital Group (K3C) guides adj EBITDA at the upper end of the market guidance of 5 Apr.
Fox Marble (FOX) FY rev up 17%, "growth has not been as strong as expected". Blames quarry production volumes in Maleshevë. Pretax -€2.3m (-€3.4m). No f/c. Optimistic outlook. Going concern stmt.