Small Cap Value Report (Wed 7 Feb 2018) - W7L, R4E, GATC

Good morning, it's Paul here, suitably refreshed after my sickie yesterday (thanks for covering, Graham).
Well, what a roller-coaster it's been of late. My view is that markets in the USA just got too expensive, and needed to correct. I don't see any particular read-across for UK small caps. Actually, it's felt quite bearish in UK small caps for several months now, with many shares having fallen considerably from previous highs.
I'm reviewing the debris of recent market moves, to see if there are any bargains on offer. Sometimes when people panic sell, they sell off good things, too cheaply. My hedging strategy worked very well, which was a relief. It's great to have some short positions generating profits in a market downturn, because that gives you peace of mind that you won't become a forced seller. So you can keep a clear head whilst all around are panicking.
Anyway, a correction from excessive levels, and a bit of fear coming back into the market, is a very good thing, in my view. Markets that just rise inexorably, without a pullback, are crashes in the making. I think it's important to remember that bear markets don't just happen randomly - they are caused by the market anticipating economic slowdowns/recessions, and hence reduced corporate earnings. With the world economy now doing well, almost everywhere, these seem very good conditions for businesses. Sure, there's a bit of fear over Brexit, and probably more fear about a Corbyn Government, here in the UK. Jacking up Corporation Tax to 26% (as their first move upwards, probably to be followed by further rises), that would make a dent in UK company earnings. That would hit share prices across the board here. So it's a big worry.
I can't think of a worse time to consider increasing Corporation Tax, than when Brexit uncertainty is probably already making some companies consider whether to stay in the UK or not. Our low taxes, and flexible employment laws, plus a population who speak English as their first language, are big attractions for companies to stay in the UK. So I fear that a Corbyn Government would be absolutely disastrous for the UK economy. In a globalised economy, you can't tax the rich - they just move their money somewhere else, to avoid being taxed. Or they just leave, with their money, and we get precisely zero in tax revenues from them. So there are lots of schoolboy policy errors already evident with Corbyn. Maybe a new generation has to experience Socialism in practice, to become as fearful of it as my generation (and older) are?
Anyway, on to today's small company results / trading updates.
Warpaint (LON:W7L)
Price: 212.5p (up 2.4% today)
No. shares: 76.75m
Market cap: £163.1m
Warpaint London PLC (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 brand, is pleased to announce the following trading update for the year ended 31 December 2017.
This looks to be a satisfactory performance:
The Group continued to perform well during 2017 and the Board confirms that it expects to report results in line with management expectations for the financial year.
I understand why companies use the phrase "management expectations" during the year - because analysts usually don't produce forecasts for partial years. However, when reporting on a full year, I think companies should refer to "market expectations", not "management expectations". Also, companies should always include a footnote, to say what they believe market expectations are. Or provide the range of broker forecasts, where they differ significantly. This is becoming much more important, now that MiFID II has considerably restricted the ability of private investors to access research.
Forecasts - there's an update from one broker, available on Research Tree, which I'm just having a look at now. They forecast 10.2p EPS for 2017, which puts the shares on a PER of 20.8,which looks fully priced to me.
However, the 2018 broker forecast is for EPS to rise to 13.1p, which if achieved, would drop the PER to 15.5 - much more attractive.
Acquisition - is going well so far;
The integration of Retra, acquired in November 2017, has been completed and the Retra business is performing well...
The company issued 11.16m new shares in a placing, priced at 190p, in Nov 2017, to fund the acquisition of Retra. Checking back to the details given late last year, Retra looks to have been acquired at a relatively cheap multiple of earnings;
Retra recorded profit before tax of £2.3 million on sales of £17.5 million in the year to 31 December 2016.
The Acquisition is expected to be immediately earnings enhancing before anticipated (but not quantified) synergies
Although a word of caution when interpreting the accounts of private companies - Directors often draw de minimis salaries, and instead pay themselves mainly through dividends. So that tends to inflate PBT, which would then need to be adjusted down to reflect the payroll costs of Directors once the company is acquired by a listed group.
I always like to see a clear logic for acquisitions, and this one seems to tick the right boxes. Warpaint says that the acquisition will give it access to new suppliers, customers, and markets. Warpaint seems to have paid a sensible price too, so it all looks good.
Outlook - sounds positive;
"We are very pleased with the performance of the Group in 2017. Retra has integrated well with the rest of the Group and we are already seeing new opportunities and synergies from the combination.
"2018 has started well and we look forward to the future with confidence."
My opinion - I'm quite tempted to have a nibble here - the group seems to be trading well, and the price (based on 2018 estimates) looks fair. The acquisition of Retra should increase earnings in 2018, but that will be diluted by the increased number of shares in issue.
Overall then, I think this could be worth a closer look.
Reach4Entertainment LON:R4E
Share price: 1.9p (down 7.3% today)
No. shares: 1,004.1m
Market cap: £19.1m
r4e, the transatlantic media and entertainment marketing company, is pleased to provide a trading update for the year ended 31 December 2017...
I've kept this share vaguely on my radar, after discussing it with Nigel Wray at last year's UK Investor Show. He owns 19.2% of the company, and I think was instrumental in the refinancing done a little while back, where some debt was paid off at a discount, which seemed a clever deal. Prior to that, the company was basically insolvent, so the equity had little to no value prior to the restructuring.
The company track record of trading has been lacklustre, Looking at the graph below, the big one-off profit was due to gains from the debt restructuring & haircut, so it wasn't trading profits;
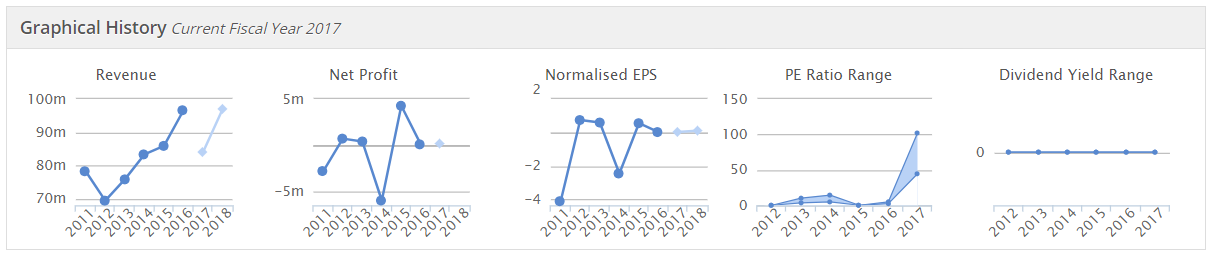
When you see big turnover (much is pass-through revenues), but little to no profit, you have to question whether the business model is viable? The shares seem to be mainly of interest as a potential turnaround, under new management. I like situations of this kind - where new, better management might be able to strip out unnecessary costs, and drive new business wins & new products. The gains from a successful turnaround, based on a bombed-out share price, can potentially be excellent.
The trouble is, that many attempted turnarounds simply don't work - Flybe (LON:FLYB) and Mothercare (LON:MTC) spring to mind, where they seem to be running to stand still.
Update today - 2017 trading performance looks to be slightly below expectations;
The Company is expected to achieve Adjusted EBITDA* broadly in line with market expectations for the 12 months to 31 December 2017 and in line with current market expectations for 2018.
Given that 2018 has only just started, it seems odd to be mentioning performance against expectations this early in the year. Perhaps the company has good visibility of bookings? Even so, I'm wary of an update this early in the new year.
Strategy update - there's some interesting commentary about the group's revised strategy. It seems to be wanting to broaden out into new markets, and geographies. This may involve more acquisitions. A fundraising of £5.5m was done in Dec 2017.
I see that Michael Grade became Chairman last year.
Cost-cutting - has been done, which explains why the group is more confident about 2018 performance;
At the end of 2017, the Company made a number of changes to the business, including a staff restructure, benefiting the underlying ongoing cost base.
These factors are expected to contribute to improved Group profitability in 2018 in line with current market expectations of Adjusted EBITDA*.
My opinion - I'm not yet convinced by this turnaround. To my mind, expanding into new areas, because you can't really make any money from existing ones, isn't attractive as an investment proposition. However, time will tell if the turnaround is good, or not. At least it's properly financed now.
I would have thought that the bank is likely to be supportive, re the Q3 2017 covenant breach, particularly as a £5.5m placing was done recently, in Dec 2017. Although I've checked the last balance sheet, and it was very weak. So adding in the £5.5m recent placing, the balance sheet would still be fairly weak, but not disastrously so.
Overall, it's not for me, but could be worth keeping an eye on, if the turnaround does start to work.
Gattaca (LON:GATC)
Share price: 213p (down 14.8% today, at market close)
No. shares: 31.8m
Market cap: £67.7m
(I no longer hold a long position in this share)
Firstly I must thank a reader here, who challenged me (last time I wrote about it here) on why I was still holding this share, when the fundamentals seemed to be deteriorating, and Ihad just written a report saying that I suspected another profit warning might occur. I had a re-think, and decided the reader was right (telling me that I should consider selling my shares). So I ditched my shares at (from memory) about 240-260p, over several days (it's a surprisingly illiquid share). As I always say, investing is a team sport. So input from readers, particularly when challenging my views, with well-argued replies, is very helpful. Sometimes I can be so caught up in the sheer volume of daily information, and writing about it, that I can't see the wood for the trees.
Anyway, on to today's news from this staffing company,
Gattaca plc ("Gattaca" or the "Group"), the specialist Engineering and Technology (IT & Telecoms) recruitment solutions business, today provides the following pre-close Trading Update for the six months to 31 January 2018.
It's a profit warning, unfortunately, for the full year ending 31 July 2018. Note that, for anyone not familiar, "NFI" means Net Fee Income - ie revenues excluding pass-through revenue;
NFI has grown both in UK Engineering and International, tempered by continued challenges in UK Technology. PBT however, as expected, will be lower than in H1 of last year as a result of our investments in staff and support costs to deliver the increased NFI and to allow for further growth in H218.
Taking a more prudent assessment of the economic outlook, we have tempered our expectations for growth in H2 and consequently we are undertaking a review of our cost base, so as to identify savings, some of which will be achieved in H2.
Notwithstanding these savings, profits before tax excluding non-recurring costs are now expected to be in the order of 15% below the Board's previous expectations.
Not a disaster, but a 15% reduction in full year profits, when we're already half way through the year, is not good.
Forecasts - I've not yet received any updated broker forecasts. However, looking back to a commissioned research note from Equity Development, their last EPS forecast was 36.0p for 07/2018. The company is today guiding to 15% below that, so I make that 30.6p revised EPS for the current year. At 213p share price, that's a PER of only 7.0 - looks cheap, but it's looked cheap for a while, and keeps getting cheaper. Then we get a profits warning. So I'm coming round to the view that it's cheap for a reason.
EDIT (8 Feb 2018) - a note from Equity Development, with revised figures, has just hit my inbox. This is commissioned research, which is freely available to all investors via ED's website. The analyst, Paul Hill, is excellent, and a very successful small caps investor. However, he's been too optimistic on GATC.
His revised numbers come out at 29.7p EPS for 06/2018, which is slightly below the 30.6p I estimated above, but it's close enough. (End of Edit)
Net debt - updated today as follows;
We estimate our net debt position at the end of January at 37m (end July 2017 40.3m).
I don't see the net debt as a problem here. Other staffing companies also carry debt, e.g. Empresaria (LON:EMR) and banks seem happy to lend against the large debtor books of companies like this.
Dividends - once again, the market got it right here. The very high dividend yield turned out to be unsustainable. Today's update says;
In light of the revised full year expectations the Board has decided to reset the rate of dividend in order to restore a more sustainable dividend cover ratio, to enable the pay down of debt, and to reflect a more normalised yield. The Board intends to set the dividend cover at approximately 2x (2017 1x).
Increasing the dividend cover from 1x to 2x, together with reduced earnings for 2018, implies a cut in the dividend from 23p last year, to about 15p in future - which is half the revised EPS forecast mentioned above, giving 2x cover. That would still yield an attractive 7.0%. So, whilst existing shareholders will no doubt be miffed at the reduction in divis, new investors buying in after today's fall in share price would still be buying a high yield share. The reduced divis might now also, possibly, be more sustainable. Providing business doesn't continue to deteriorate. If that happened, then the company might decide to cut divis again, or stop them altogether.
EDIT 8 Feb 2018 - revised numbers from Equity Development indicate a reduced divi of only 11.5p, with cover of 2.6 times. The analyst will have spoken to the company in coming up with that figure, so I think we have to lock on to 11.5p dividends as being the most likely outcome. (End of edit)
CEO resignation - Brian Wilkinson has fallen on his sword. Probably a good idea, as the company & share price have not performed very well under his stewardship, to be blunt.
My opinion - I've lost interest in this company. It's disappointment after disappointment, and the apparently cheap valuation seems to be because the market correctly predicted problems with earnings & divis.
Maybe a new CEO could inject some razzmatazz into the company. So I might revisit the share, if the new CEO unveils an improved strategy, and has a good track record.
All done for today. See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Gattaca. I see the COO Keith Lucas sold shares at 270p on 15 January and a trading statement was issued about three weeks later. This stinks - is there any sanction?
Glad my challenge saved you some money Paul. It perhaps goes some way to pay you back for all the money you have saved and made for me since I became a subscriber to Stockopedia.
I like the Investing is a team sport mantra!
Glad my challenge saved you some money Paul. It perhaps goes some way to pay you back for all the money you have saved and made for me since I became a subscriber to Stockopedia.
I like the Investing is a team sport mantra!
Re Gattaca (LON:GATC) I can't help but be concerned about the size of the debtors. Banks may be happy to finance it, but it leaves them very vulnerable to payment delays and customers going bust. Unless they are all insured. Very big tail, very small dog. With Carillion they said they were mostly insured, but not all. Some managements I would trust to be on top of risks, but can't do that here.
Can we please just not mention C****n, or we'll never get to talk about stocks...
The new generation haven't seen socialism here, but if they cared to look, they would see the results all around the world.
Some previous comments indicate Corbyn is quite an admirer of Venezuela, which is indeed a fine example of what socialism does to countries.
The younger voters are probably unaware that Gordon Brown was borrowing almost as much as Greece when he finished & the previous Labour government required IMF assistance in the 1970s.
If anything, Corbyn seems considerably worse than either of those, so if he's elected, even the middle classes should be thinking about emigrating.
He is by far & away the largest threat to the economy. Whether it be a hard Brexit or remaining in the EU is of little significance in comparison to the threat of extreme socialism.
That would affect post tax profits, dividends, investment returns, pensions & employment. I'm certainly taking the risk into account when considering investments.
jonthetourist,
>>The leading tax haven within the European Community is Luxembourg*. The Finance Minister of Luxembourg from 1989 to 2009 was Jean-Claude Juncker.>>
Yes, of course. He was the prime mover in what I referred to as a race to the bottom.
>> I suggest not holding your breath regarding a challenge to tax avoidance.>>
Perhaps, but I've been encouraged by some of Margrethe Vestager's rulings on Apple, Google and Starbucks.
Feeling quite euphoric. I sold everything yesterday in my SIPP and ISA. I know it has all gone back up today but after an excellent 2017 I have been struggling in 2018 to pick the right ones. I'm going to take a breather until the market settles down a bit. It's quite a good feeling, deep breaths and relax!!! Charles
doublelutz
"they are creating considerable employment, paying over huge sums in PAYE and NIC, vast amounts of vat and pay business rates, etc. All of which make the loss of corporation tax almost a side issue."
Ref starbucks if they left - the alternative is that a uk based business who pays the 19% corporation tax (by not sourcing coffee from Switzerland) and also possibly another 5% dividend tax on top AND all of the relevant uk taxes would likely replace them. Give me that alternative any day of the week IF the basic taxes that HAVE to be paid by uk originated alternatives are being avoided by these "government backed shysters/ex shysters gone legit now honest gov types". Things may be slowly getting better on this front - but i guess this excludes the unknown new loopholes we wont know about till 5 years time.
But would a UK business have replicated Starbucks? Maybe. After all we do have Costa Coffee but Starbucks was one of the first to develop coffee shops on this scale. If we were looking at someone like, say, Amazon then I don't think they would be replicated by a UK company.
A bit pedantic of me but a company does not pay a 5% dividend tax. It is 7.5% paid by individual basic rate UK taxpayers not by the company. Dividends are ignored in calculating the 19% CT. I don't know whether "AND all of the relevant UK taxes" refers to some other tax of which I am not aware. In the past UK companies have done similar things although obviously more difficult now.
doublelutz
"But would a UK business have replicated Starbucks? Maybe. After all we do have Costa Coffee but Starbucks was one of the first to develop coffee shops on this scale. If we were looking at someone like, say, Amazon then I don't think they would be replicated by a UK company."
i guess my point here is that all we really need is a genuine business paying the proper corp tax in the uk on the "real"profits made - it may be a pipe dream but the "the government" should be able to sort this out and they have chosen not to - thats their fault. IMHO its a vastly unfair situation for a one person company or small close company chain (or larger uk chain even) competing and paying the 29%-25% tax on their profits and seeing starbucks paying nowt. I am well aware the company doesn't pay the 7.5% dividend tax per se but if the profits are distributed by a uk company to owner shareholder managers there often will be approx 5% paid on top (by the individuals) that would not be paid where funds are extracted to switzerland to pay for the mighty fine coffee that that country exports.
Its exactly the same situation for other similar things like a retailer who had to compete with no vat jersey sellers of cd's and now no vat china based sellers of the various nick nacks we all love to buy off ebay and amazon.
Paul and others - reference the comments on Corporation Tax, a company controlled in the UK will usually pay UK CT on all profits but with an offset for overseas tax. Bearing in mind that the UK has one of the lowest CT rates in the world apart from obvious tax havens, then you can see that companies trading in foreign countries usually have a higher percentage tax bill than those just trading in the UK. The situation with such as Starbucks, of course, is that they are not controlled in the UK and that makes it difficult for us to collect what we might think they should be paying although bear in mind that they are creating considerable employment, paying over huge sums in PAYE and NIC, vast amounts of vat and pay business rates, etc. All of which make the loss of corporation tax almost a side issue.
GATC sold at a loss , since the name change this company has gone downhill 2,30 pm announcement mmm!!
Loss faith in this company I am going in to a corner to lick my wounds !!
re Gattaca (LON:GATC) - i usually avoid companies with silly names - eg globo ..
Re Gattaca (LON:GATC), pressure on the dividend has been growing - ether the business had to move forward or the dividend needed to go down (although still likely to be chunky at around my guess of 15p). Since there has not been a material improvement nor is one one forecast. The dividend rightly had to go. No one wants to be caught with high debt if a down turn with rising interest rates is coming. This is a proactive if disappointing move IMHO.
More worrying is the shift towards permanent hires in the NFI and dismal forecast. I see these as riskier and perhaps a sign that govt policy on contractors and new ways of internet hiring are biting. That being said GATC has also not delivered vs peer group and vs promises (cost savings from integration of networkers), so CEO going is no surprise.
Net, position not good but not desperate. International growing. Perhaps the new CEO when appointed will do better (or be luckier - part of the reason for poor results is lack of expected govt spending on infrastructure!). Damage done, I will continue to hold. Their focus on Engineering & Technology should do well. Nice candidate for consolidation at current depressed price?
Re comments on corporation tax:
I) Many countries have lowered rates of corporation tax in expectation of attracting inward investment. In the short term this may work, but there must be a concern that this is a race to the bottom, that the net result will be all countries taking less in tax revenue, which means less to spend on health, education, infrastructure and so on.
2) There seems to have been trend towards companies avoiding tax through channelling earnings through low tax countries (e.g. Amazon and Luxembourg, Apple paying 0.005% on revenues routed through the Republic of Ireland), transfer pricing (e.g. Starbucks buying its coffee from a 100% owned subsidiary in Switzerland: the subsidiary over charges but CT is lower in Switzerland than the UK so Starbucks pays less tax overall), special pleading (Vodafone and Dave Hartnett), and so on. All this is legal, of course, and seems to be part of a trend of large corporations challenging the powers of nation states. This makes me uneasy, and it's one of the reasons I voted to stay in Europe (sorreee) because it's only a large block like the EU that can challenge this trend.
Again, treading a fine line of avoiding politics and simply stating fact in relation to those last sentences:
"All this is legal, of course, and seems to be part of a trend of large corporations challenging the powers of nation states. This makes me uneasy, and it's one of the reasons I voted to stay in Europe (sorreee) because it's only a large block like the EU that can challenge this trend."
The leading tax haven within the European Community is Luxembourg*. The Finance Minister of Luxembourg from 1989 to 2009 was Jean-Claude Juncker. He is currently President of the European Commission. I suggest not holding your breath regarding a challenge to tax avoidance.
* http://uk.businessinsider.com/full-list-every-company-named-in-the-luxembourg-secret-tax-deal-database-2014-11
OK, I give up. Gattaca!
You can't put any punctuation at the end of the tags JTC, ie £GATC! Gattaca (LON:GATC)
Oops! £GATC!
£GACT has really ticked me off with these releases and I have just sold at a fair loss. Maybe foolish, but as I have Connect (LON:CNCT) and Card Factory (LON:CARD) too, I have enough boring UK companies to worry about. Move on. I'm minded to put more into even more boring stuff like Henderson Far East Income (LON:HFEL) and European Assets Trust NV NLG1(REGD) (LON:EAT). I know this is a UK small cap board, but at times like these, the older among us wish the investment trust coverage of Stockopedia were better. They are listed companies too! Sitting outside the UK at the mo', I worry about our politicians managing to drive enough investors out that UK single stocks continue to suffer. Anyone got a good small income stock with capital potential in this market?
"This is not the right place for a discussion on politics, unless it is something specific that would affect company earnings & share prices" - I entirely agree, and so Paul, I would rather you hadn't started it!
LordZion, you can open a spread bet at a pound or two a point and short/long the FTSE 100, 250 or, with a greater margin, the DOW on something like spreadex or IG.com. If you make money it's tax free. On that topic, do any of you have your ISAs with IG? I'm with HL atm and absolutely sick of having to type my password every five minutes, and might like to use my ISA as leverage for (mild) spread betting (as a hedge, as Paul has done). What are the spreads / charges like on IG, in you folks' experience?
If any of you would like to share please feel free to message me if you don't want to go o/t on the board.
Hi Runthejoules
I have an ISA with £IG. and their dealing charges are cheaper than HL at around £5 and I believe their fx charges are lower. However they charge £100 for corporate actions. So I prefer Hargreaves Lansdown (LON:HL.) if I want to attend AGM's. Incredibly I have found international stocks in the past to be tradeable in HL but not IG. Did you know you can alter the timeout settings on the HL site in account settings?
Hi Jules2k6, thanks for your reply - I will alter those settings now! Been with them about six years and not realised... by corporate actions, does that include dividends / special dividends or just stock splits or m&a? I'm not rich enough to pay £100 for a dividend!
Hi rRunthejoules IG Group (LON:IGG) 's charges can be found here https://www.ig.com/uk/investments/share-dealing/costs-fees
They don't charge for normal dividends but do if you want to go to an agm or excercise your vote.
Hi Paul
Ive enjoyed the fantasy funds here, and I agree BMUS has probably suffered more to do so with you having more speculative stocks. However lets hope it bashes 2018 again out of the park.
also what you reckon of Minervini predicting the crash, he was saying it at the beginning of the year.
best wishes.
I find Minervini trys to predict a sell off about once a month after his risk model flashes sell, when nothing happens he adds about 10 stocks to his buy alert list. It was only a matter of time until he called one correctly
Brings to mind the saying, "If you're going to forecast, forecast often"
Agree with purpleski that, although there may be a double tax agreement, you cannot get more credit for the foreign tax paid than the amount you would pay on the same profit in the UK.
Lovely to see a mid-afternoon profit warning and dividend cut from Gattaca (LON:GATC) and the CEO has left with immediate effect. What a crap company!
All the best, Si
Gattaca (LON:GATC) , interestingly in the CEO resignation RNS they claimed to have issued a "scheduled trading update", whereas in truth the trading update was scheduled for tomorrow as per the RNS issued on 17th January. It appears they felt it was necessary to issue it early either to avoid it or the CEO resignation leaking - clearly they needed to be released together.
The change of dividend policy announced on the day of the CEO's departure implies there may have been disagreement on the dividend policy. Together with him apparently not being trusted to keep quiet about his resignation for another 2 hours suggests he may have been pushed. However he is of the age that he might have retired (about 63 years old).
The updated outlook is about what I expected. Their debt is very manageable and cheap at the moment, but with rising interest rates it will make increasing sense to reduce it. In any case some degree of dividend cut was clearly required. I am not surprised about the muted reaction given the poor history / low expectations / cheap valuation of the company. I'd guess it still yields around 5% with a PE of 6-7 with debt covered by debtors.
leo,
The need to release two RNS'es at 2:30pm the day before a scheduled update tells me everything I need to know about this company. We're going to have to beg to differ but the management are terrible, you really shouldn't be making excuses for them. The share price performance and value destruction since the Matchtech days has been lamentable. I feel sorry for any long terms holders, but each to their own...
All the best, Si
Gattaca (LON:GATC) the dividend cut was inevitable. They weren't generating enough cash to pay it and so last year extended their borrowings to pay for it!
For once we agree.
More than that I have to say, and I'd be interested in other's comments, I think the recruitment sector as a whole is one which should be avoided at present. The valuations look cheap, the dividends look good (but Gattaca (LON:GATC) has just cut), however, the margins are thin and they seem to keep increasing their cost base and IR35 looks like it will become global in this country not just in the public sector.
Phil
(PS. Personal rant; I despise companies which call any increase in cost an "investment")
For once we agree.
Yes, but the only time we disagreed I was right and you were wrong :-)
I think the recruitment sector as a whole is one which should be avoided at present.
I'd go further and say it should be avoided full stop. I've lost money on recruiters (including Matchtech!) in the past so speak from experience. I'm with Graham on people businesses and no longer invest in companies where the only assets walk out the door every night at 5pm and the operating margins are paper thin. Busy fools come to mind...
All the best, Si
Hi Paul,
Glad you're feeling better after yesterday.
Would it be possible to look at the Numis (LON:NUM) trading update from yesterday or is it not worth it, considering it has little in the way of figures and comparables?
James
So, Corbyn bashing even comes to Stocko!
I do hope your "sickie" didn't need the attention of a Socialist NHS!
I am always fascinated by the argument that if you try to take money from the very rich, they ( presumably fearing the poverty of being down to their last million) will do everything in their power to resist, even to the point of living somewhere they wouldn't normally choose.
I'd like to eavesdrop on a conversation between Marie Antoinette and Tsar Nicholas II on the subject of the precise moment you realise that sharing works better than hogging.
Have the scandals of the banking crash, BHS and Carillon taught us nothing about unregulated greed in a capitalist society? If there is one vital reason for the brexit vote, could it be that, thanks to the EU, we rose briefly to being the 5th richest economy in the world but, despite that, seem not to know how to reasonably apportion the spoils. It will all end in tears if we can't share when there is less to divide up.
TangoDoc,
That's just an emotive rant from you,not particularly worthy of a response.
If you go back to my original article & read it again, perhaps when you are feeling a bit more calm, you will see that I was actually mentioning corporate taxation, which would decrease earnings & hence share prices. As investors, we need to be very mindful of such potential changes in Govt policy. How you got from that, to ranting about unrestrained greed, the NHS, Carillion, etc (which I didn't mention & is not relevant to this column), I have no idea!
This is not the right place for a discussion on politics, unless it is something specific that would affect company earnings & share prices. Which clearly a hike to 26%+ in Corporation Tax would be a material factor in reducing UK earnings for many companies.
Paul.
Just as an apolitical aside on this. You can safely ignore anyone who quotes the stat "5th richest economy in the world". It's true, but nonsensical, in that it ignores population size.
Anyone who thinks the UK is richer than Switzerland, Norway, Austria, Denmark etc needs to get out more.
Jon
Increased taxes do mechanically increase corporate revenue though, as the government spends them on services, salaries or benefits to people who in turn buy more stuff.
There was a trading update from Belvoir Lettings (LON:BLV). I quite like some of the things they have been doing. The financial support to franchisees seeking to acquire portfolios of lettings contracts seems particularly smart. They earn an attractive return on the loan and benefit from the revenue uplift as well. Their acquisition of Brook, a Mortgage Advice Bureau appointed representative, will allow them to offer mortgage advice to customers and they appear to be quite early in the roll-out of this. Their focus on lettings seems to offer a slightly more stable revenue profile than focusing on sales. They tried and failed to merge with Property Franchise (LON:TPFG) but further consolidation seems likely.
I think Walker Greenbank (LON:WGB) 's in-line update from yesterday may be of interest here. They are a cheap company selling expensive wallpaper and furnishings, with a sideline in floods and fires. I had difficulty separating the underlying profits / cashflow from the insurance claims in the last accounts, but they look very good value to me.
Also, no recent news, but UP Global Sourcing Holdings (LON:UPGS) has fallen further following on from September's outlook warning despite significant director buying in November at levels 50% higher than today. Is there another profit warning on the way, or is it just market nerves?
Both are rated "Contrarian" by Stockopedia, which is probably preferable to "High Flyer", especially in today's market. If things go well a "Contrarian" will often become a "Super Stock".
Finally, just a note that I am monitoring Impax Asset Management (LON:IPX) 's monthly fund newsletters and will update my spreadsheet (see previous posts) with guestrapolations of AUM, inflows and fund growth as these become available. I won't be commenting further here unless something dramatic happens though.
Can I ask if the facility you use to hedge is available to the general public?
Was that you on twitter bemoaning the fact that you had lost £250k through switching from short to long at the wrong time?
God no!
If he thought it was you he must be taking the same stuff as the person who posted:
"I'm so pissed off with myself. I was sure this was a 1987-style situation, with a sharp correction due. Loaded up on Dow shorts a while ago, then got too cocky & reversed them to longs last night. Threw away £250k today :-( Idiot!!! "
("last night" having been spent in Amsterdam).
No names, no pack-drill.
"Loaded up on Dow shorts a while ago, then got too cocky & reversed them to longs last night. Threw away £250k today"
Sounds like a portaholic
I know some on here are invested in Revolution Bars. They're offering free cocktails..
http://www.revolution-bars.co.uk/giveaway/
Thanks kh2040. I need a drink after the last week and a half... down 14%...
Thank you for letting us know. I hold.
I feel torn about promotions like this. On the one hand it's a great way to get footfall and entice new customers to try their bars. On the other hand, it could prove expensive, especially if this goes viral. And if it does, there is also a danger of annoying regulars with much busier bars and impairing staff productivity.
But on balance, this is a good time of year to run a promotion like this and the boost to customer numbers with the opportunity to sell them more drinks can only be good for the business.
So I've told my five grown up children (who will no doubt tell others on whatsbook or instasnap (sic) and if I can get to one, will happily avail myself too.
cheers
Francis
Hi Paul.
Seems to be a quiet day for small cap reporting.
I share your views about the last week being a slightly more dramatic continuation in the rotation away from some of the strong momentum small caps that did so well last year rather than a new direction. I see the BMUS fantasy fund is currently down about 20% in the past month (of which roughly 10% is in the last week) with a few of the racier picks such as Connect (LON:CNCT) , Mobile Streams (LON:MOS) and GAME Digital (LON:GMD) in particular being quite aggressively sold down after indifferent company news. (I share your pain - I have a few of the BMUS stocks salted away). Is your feeling that this is just usual ebb and flow of the market or is there perhaps a more fundamental shift away from an M/G focus to more of a V/Q approach? I sense something has been shifting in market sentiment for the past few months but can’t quite put my finger on it.
Gus.
Hi gus 1065,
Yes indeed, BMUS has had a lousy year so far, although that followed on from a pretty spectacular performance in 2016 & 2017.
Practically everything I buy, is bought on fundamentals, with a 2+ year view - both in real life, and in BMUS. So share prices going up or down a lot, doesn't concern me at all, providing my reason for purchase is unchanged.
So of the ones you mention, I think Mobile Streams (LON:MOS) is looking wobbly now, but I'm prepared to give it another 6 months - because the downside is still protected by cash, and the upside could be huge (from a very bombed out valuation) if Indian sales take off properly. It could be a 100% loss though, hence why I'm not averaging down.
GAME Digital (LON:GMD) has been very volatile, peaking at 60p, and now falling to 40p. The last update was fine, and it's heavily protected by a huge net cash pile, and I see interesting potential upside from c.80% of their leases expiring this year - so loss-making shops should almost all disappear. Plus the new sites seem to have an encouraging payback, where the "Belong" gaming format is introduced. So the business could look very different (i.e. much better) at the end of 2018, than it does now.
Connect (LON:CNCT) - obviously disappointing to see a profit warning, but it wasn't a big miss, so on balance I'm happy to hold.
Overall, I probably made a mistake by taking some more speculative positions than usual, at the wrong time to do so last year, but longer term that won't matter. So no changes planned to the portfolio.
Regards, Paul.
Hi Paul.
Thanks for the detailed response. I think Connect (LON:CNCT) and GAME Digital (LON:GMD) will be fine. Having an association with teenage boys who are massively enthused by e-gaming I think the potential in this area for GAME Digital (LON:GMD) could be spectacular. Mobile Streams (LON:MOS) on the other hand is, to my mind, little more than a (small) betting chip at the moment. They might just strike it rich in India but I suspect it would be more by luck than judgement. Not sure if you saw Graham’s write up after last week’s results but it gave a pretty downbeat assessment of their prospects (which I tend to agree with).
Thanks again.
Gus.
p.s. While I’m posting, just seen Gattaca (LON:GATC) have come out with an intraday (grrrrr!) trading statement. Looks as though NFI is up 2% but a proposed dividend cut is lurking at the bottom of the release.
https://www.investegate.co.uk/gattaca-plc/gatc/trading-update/201802071430012119E/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=Gattaca%20PLC%20Alert
Hi gus,
Yes I agree with you - Mobile Streams (LON:MOS) is highly speculative at this stage. If it runs out of money again, then the next placing could be below 1p. High risk, possibly high reward. Not my usual type of thing at all - although if you check out the long term chart, there have been a number of spectacular gains, when some good news comes out & punters go crazy for a few days. Those are good times to bank a multibagger. So who knows? It could have another spike up, maybe?
Regards, Paul.
"Jacking up Corporation Tax ...would make a dent in UK company earnings. That would hit share prices across the board here. So it's a big worry."
Paul, I know your comment is hypothetical, but don't companies pay corporate taxes where their profits are made (accepting that internal cross-charging can distort the picture)? That suggests that profits earned in the UK would be hit, as you say, but not so much for global companies based in the UK but with only a small percentage of profits earned here. I understood that tax was payable only when cash is remitted to the UK - so no tax if cash and profits stay where they were earned.
So rather than hitting share prices "across the board" wouldn't the main impact be on UK-only businesses?
Hi pj8,
Yes, that's right - you make a good point. I was thinking about UK small caps with solely, or mainly UK operations. But as you correctly point out, companies with international earnings would usually be taxed on their overseas profits by overseas Governments (if they have tax treaties with the UK).
Regards, Paul.
I have a UK company that is registered in France (not French subsidiary, setting up a French company SARL is expensive and hideously bureaucratic) and my company pays UK CT on all of it’s French earnings regardless of whether I remit the profits to the UK.
There is a double taxation treaty so the effect is negligible because French CT is 33% for me.
Hi purpleski,
I'm surprised at that. I'm not a tax expert, but I thought the general principle was that companies pay tax in the country in which they operate, So it's surprising that you have a UK company, operating in france, but can opt to pay UK corporation tax.
Maybe we have tax experts who could clarify the position?
Regards, Paul.
Hi Paul
My Ltd company is registered as trading in France but does not own a subsidiary in France (maybe that is the difference?). But I make a Tax return in France for CT purposes and pay CT (at 33% but hopefully Mr Macron will reduce that, if he hasn’t already) on the profit deemed to be generated by activities in France.
My UK accountants then do my accounts in the UK. So, say i make £120,000 and £100,000 is deemed by the French authorities to be generated in France I pay £33,000 in French CT.
In the UK I then pay tax on £120k but the UK CT on the first £100,000 set off against that paid in France under our double taxation agreement with France (but I dont get to use the difference between the UK rate and the French rate, so 14% is “lost”). I then pay 19% on the other £20,000.
So yes too much tax!! Sorry TangoDoc!!
I dont think my UK accountants (mid size firm) are getting it wrong.
I will be interested to hear other people’s thoughts.
I hope this all makes sense and is not too much off topic!!
Best wishes
Michael
Purpleski
"Maybe we have tax experts who could clarify the position?"
Traditionally a Double Irish & Dutch Sandwich or similar ensures the big uns to a certain extent may be able to pay what they want where they want .
I would guess going forward though they may be slightly more keen to perhaps at least pay something approaching 20% somewhere - this being the case the uk looks adequately positioned in this regard.
The stupidity is how easy it is for companies who should have to pay the standard corp tax/vat (and probably to a lesser extent now paye) can avoid paying anything - so Uber aren't a transport company (and therefore liable to pay vat) and dont make any profit and dont have any employees - they shouldn't be allowed to have a presence in the uk if that is the case :)