Small Cap Value Report (Wed 8 May 2019) - EHG, VTU, DISH, ARB, REC

Good morning!
The final list:
- Elegant Hotels (LON:EHG) - half year results
- Vertu Motors (LON:VTU) - final results
- BigDish (LON:DISH) - operational update
- Argo Blockchain (LON:ARB) - operational update
- Record (LON:REC) - business update
Archaeology - a quick note regarding what I said yesterday about the "archaeologists" who inhabit financial regulatory bodies. The Financial Reporting Council has only today imposed sanctions on KPMG and one of its partners for work done on the Co-Op Bank's accounts.
So which year's accounts would these be? FY December 2009! Yet again, we see how slowly the wheels of justice turn.
I'd also like to point out that cases like the Co-Op, Autonomy and Quindell are all very high-profile. In the small-company world, dodgy accounts are much less likely to even be investigated. Tread carefully!
Elegant Hotels (LON:EHG)
- Share price: 71.5p (+4%)
- No. of shares: 89 million
- Market cap: £63 million
Elegant Hotels Group plc ("Elegant Hotels", the "Company" or the "Group"), the owner and operator of seven upscale freehold hotels and a beachfront restaurant on the island of Barbados, today announces its unaudited results for the six months ended 31 March 2019.
Paul and I have covered this share from time to time. Click here for my review of its final results in January.
It has looked "cheap" for a while, with a very high ValueRank. It currently has a high overall StockRank:
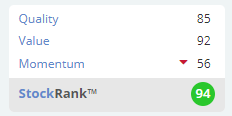
On the other hand, it's a hotel group, so we shouldn't have very high expectations of its growth prospects. Like any property company, there are natural limits in terms of how quickly it can grow.
Today's numbers:
- Revenue +3%.
- Adjusted EBITDA up 7%, adjusted PBT up 5%, adjusted EPS up 27%.
- "Implied NAV" of 156p based on a GBP:USD exchange range of 1.3 and January 2018 property valuations by CBRE.
- "comfortable" with outlook against market expectation.
Occupancy is up but average daily rates are down. All the changes are small.
RevPar (revenue per available room) is up marginally. I believe that the local inflation rate is rising at a faster pace.
Arrivals to Barbados from the UK were up 7% in the period. Given that the UK accounts for the majority of EHG's customers, the rise in revenues and RevPar looks quite weak to me.
There is a reference to increased competition, "particularly in the all-inclusive and value segments". When consumers tighten their belts, hotels suffer.
Tax rates: Barbados has seen massive cuts in corporate taxation. The rate has been reduced from 30% to between 1% and 5.5%. Therefore, the six-month tax charge has reduced from $2 million to $0.2 million.
This helps to explain why (after-tax) EPS has increased at such a faster rate than pre-tax profits.
Net debt is $68.9 million.
My view: this looks too cheap to me. It's probably under-performing the competition in Barbados, but unless there are risks I haven't spotted yet, it still seems a bargain. The current pricing seems to imply a future deterioration in trading and/or very high currency risks. Remember that there is a GBP/USD exposure to worry about (income in GBP, expenditure in USD).
I suppose we might ask the question about whether the ultra-low tax rates in Barbados are sustainable. As a long-term investment, you need to bear in mind that these tax rates could rise again at some point.
I'm tempted to buy EHG for my own portfolio but it doesn't really fit the strategy I'm pursuing, so will instead leave it for others to research in greater detail.
Luke Johnson owns 12.5% of the shares and is currently a non-executive director.
Vertu Motors (LON:VTU)
- Share price: 36.4p (+4%)
- No. of shares: 376.6 million
- Market cap: £137 milllion
Final Results for the year ended 28 February 2019
Vertu Motors plc, the automotive retailer with a network of 123 sales and aftersales outlets across the UK, announces its final results for the year ended 28 February 2019
I will keep this brief but the bottom line is that it's trading in line with expectations in the current period.
The entire auto retailer space has been de-rated thanks to the weakness in the car market and while i do think they are too cheap as a sector, I haven't felt compelled to actually buy any of them myself! So I guess that tells a story.
Similar company Pendragon (LON:PDG) fell into a loss last year. The outgoing Chairman of Vertu remarks today that the entire sector will probably shrink and consolidate:
It is likely that over time there will continue to be a reduction in the number of franchise dealer outlets in the UK and drive further network consolidation.
Vertu generated plenty of free cash flow in FY 2019 (£21 million) and spent almost half of it on dividends and buybacks. That seems like a reasonable thing to do, when the shares are trading at a single-digit P/E multiple.
BigDish (LON:DISH)
- Share price: 2.9p (+2%)
- No. of shares: 286 million
- Market cap: £8 million
BigDish Plc (LON: DISH), a food technology company that operates a yield management platform for restaurants, is pleased to announce further progress in the UK and an expanded growth strategy.
Just a quick update here to say that it's expanding to new towns is now preparing to head for the London commuter towns.
No idea what it could be worth, but it seems like a nice concept.
Argo Blockchain (LON:ARB)
- Share price: 3.5p (+8%)
- No. of shares: 294 million
- Market cap: £10 million
I considered this to be a joke company when it first listed, offering "Mining-as-a-Service" to crypto punters.
Since then, the crypto bubble has burst and Argo has abandoned its "MaaS" strategy. Instead, it is using its crypto mining computers to generate coins for its own balance sheet. Good news.
The other good news is that Argo still has £15 million in cash (as of March 2019).
An investor holding 14% of the shares has called a general meeting with the purpose of booting out the existing managers and (presumably) giving the money back to shareholders.
Will they succeed? I have no idea. I do know that I would much prefer to have £15 million in cash than to own Argo Blockchain in its current form.
Record (LON:REC)
- Share price: 30.75p (-0.8%)
- No. of shares: 199 million
- Market cap: £61 million
(Please note that I have a long position in REC.)
This has been an unsuccessful investment for me so far, and today's update doesn't help.
We already knew that Record had put £40k into a funny little start-up whose shareholders include two directors and a shareholder of Record. A perfect example of a related party transaction.
£40k is pretty much irrelevant when we are talking about a £60 million market cap business, so I didn't care about the initial announcement.
To my dismay, the company announces today that it has put another £80k into the business.
The total investment is still less than 0.2% of Record's market cap, but the optics are terrible. Record needs to become more competitive and find new clients. This start-up sounds like a distraction from that goal.
Record says that the start-up, which runs virtual trading competitions, will help in branding and recruitment and also offer diversification from Record's existing business.
If I was going to cull anything from my portfolio, Record would be near the top of the list. Announcements like this can only make its elimination from my portfolio more likely.
That's all I can manage for today. Apologies once again for the delay.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Hi all
This extremely off subject but I see Pelatro Pelatro (LON:PTRO) are presenting at Mello. I cannot attend but wonder if any attendees could post somewhere their impression of the CEO presentations.
Here's hoping
Steve
ATTRAQT (LON:ATQT) have just announced the acquisition of Early Birds with conditional placing to raise £17.1m at 27p.
Early Birds adds AI capability to ATTRAQT (LON:ATQT) and moves them closer to their strategic goals. Here, Luke McKeever, CEO, outlines the rationale:
https://www.piworld.co.uk/2019/05/08/attraqt-atqt-early-birds-acquisition/
Link to the ATTRAQT (LON:ATQT) RNS with full details:
https://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/ATQT/14066800.html
ATTRAQT (LON:ATQT) create an efficient, personalised, on-line shopping experience for many high profile brands, including ASOS, PrettyLittleThing to ScrewFix.
It sounds interesting. Luke McKeever is an impressive CEO, who's recently taken over the helm. Not profit making yet, but perhaps one to keep an eye on.
Re Elegant Hotels (LON:EHG) I am distinctly unimpressed with the results. The occupancy rates strike me as showing a great real of room for improvement. I have been to Barbados quite a few times and am familiar with their hotels which are largely concentrated in the same part of the island which is not necessarily a good thing in the event of any local difficulties affecting the area. In my view their target clientele are relatively affluent and their price point are fairly high but their lack of progress in improving occupancy rates is an area where I would need to see signs of improvement before I would want to invest here.
Andyi
Hi Andy,
It's hard to judge metrics completely on their own and without any context:
https://www.barbadostourisminvestment.com/tourism-profile/ : Tourism is central to the Barbados economy and employs 14,000 persons directly with 12 percent of GDP attributed to the industry. Its hotel occupancy levels average 65% annually."
So actually, the hotel occupancy rate of 68% across the group, is above average compared to other hotels on the island.
This doesn't mean they shouldn't strive to achieve more, but also isn't a red flag.
Agreed, they can never get to metropolitan city occupancy rates, because of seasonality in the Barbados tourist season.
Financial Reporting Council
A very pleased Andrew Walker
Andrew Walker
Partner
KPMG LLP (UK)
Andrew leads KPMG's Financial Sector team in Birmingham and specialises in providing audit and advisory services to listed Banks, Building Societies and other specialist mortgage and consumer finance lenders. Andrew also leads KPMG's Securitisation team in the UK. His other experience includes deal advisory work, due diligence, accounting advisory and regulatory projects.
Areas of expertise
Advisory,Audit,Deal Advisory,Due Diligence,Enterprise,Financial Services,Internal audit,Risk Management,Sustainability,Transactions
--------------------------------------------------------------------------------------------------------------------------------------------
He was excluded fom the ICAEW for six years but is now firmly back in the fold. "Head of KPMG's Securitisation Team in the UK": is this really the best that KPMG have to offer their unfortunate clients? Every organisation the size of KPMG will have people who are incompetent - it is the reinstatement at the highest level of those shown to be so that offends.
It really is a lawless jungle out there and private investors are at the bottom of the food chain.
Bonitabeach
Bonitabeach, Andrew Walker was fined but I think you will find it was Barry Tootell who was excluded.for 6 years.
homosap,
Thank you for the correction, I misread the report and my apologies to Andrew Walker, if any are due. The points raised by Graham remains valid though; offences are unlikely to be properly investigated, charges rarely brought; if found guilty does the punishment fit the crime?
Bonitabeach
Graham
In the March 21 SCVR you commented favourably on Strix (LON:KETL) , saying "I like this company. I am currently trying to ascertain what is the average remaining life on its patent portfolio, and will let readers know when I have more information on this point."
The SP has dropped sharply in recent days, possibly because of Trump's tweets about China, and may have reached a good entry price (it triggered my alert). Did you find out about the patents?
Hi FREng,
I believe the topic of patents at Strix (LON:KETL) is raised at some point in this 20-minute video:
https://equitydevelopment.co.uk/webinars/?d=%3D%3DAO1UjM
I haven't come to a view on it yet.
Graham
Thanks, Graham. I watched the results video - the protection of IP is early on, from about 3:40. They protect IP even when patents expire, using copyright and (in the regulated market) safety testing of devices that don't use their controls and liaison with local regulators. I'm impressed.
ITV (LON:ITV) down 6%+ on short term fears. Don't delve into companies this size too often however:
A lot to like about those metrics.
ITV (LON:ITV) ...and always the prospect of a takeover bid if it gets too cheap. Probably not a bad one to buy and tuck away.
Hi Edinburgh Investor
ITV (LON:ITV) and £EGH are the only companies I continue to hold that are losing positions of about 25%. Robbie Burns would I think be appalled! Fortunately the rest of the portfolio has more than compensated.
The reason I continue to hold is that the investment metrics are (as you point out for £ITV) in my view attractive and as far as I can tell both companies are financially sound. In both cases I calculate that with dividends received over the last 3 or 4 years I am at break even or perhaps slightly ahead. Also as 'nicobox' comments ITV (LON:ITV) is a credible takeover target, as I would suggest is Elegant Hotels (LON:EHG).
I see significant value in ITV Studios given the current demand for content. ITV Studio companies are responsible for highly successful dramas such as Poldark, the Body Guard and Line of Duty.
Hopefully with patience value will out in the end. It is always difficult to avoid confirmation bias but one obvious downside is that the money tied up in what are currently losing positions could perhaps be more successfully employed. We shall see!
Line of Duty and The Bodyguard are BBC productions, not ITV (LON:ITV). ITV has gone downhill in terms of quality drama imo.
The Bodyguard was shown in this country on the BBC but was actually made by ITV Studios.
https://www.itvstudios.com/news/netflix-picks-up-bodyguard-in-itv-studios-global-entertainment-deal
They also own The Line of Duty production company.
https://www.itv.com/presscentre/press-releases/itv-studios-acquires-line-duty-producer-world-productions
ITV launched a takeover of LOD's production company in 2017. The news of which can easily be found via any internet search provider, or just check World Productions Wiki page (note the owner and parent).
https://en.wikipedia.org/wiki/World_Productions
I thought Line of Duty and Bodyguard were made by World Productions which, since 2017 has been owned by ITV (LON:ITV) or did I misread this?
As a long term income investor I hold.
Hi Justmo
The Body Guard was made by World Productions as was the Line of Duty ITV Studios acquired a majority stake in World Productions in May 2017. Although in fairness the first three series of Line of Duty were produced prior to ITV Studios involvement. The BBC has recently commissioned a sixth series.
ITV Studios sold the Body Guard to Netflix.
Hi Jonno,
Like you say, acquired after 2017, the earlier ones were between WP and the BBC, and were screened on the BBC where they are getting the audience. ITV on the other hand needs the advertising where the drop in revenue was, so needs to screen quality content too. Where would you advertise if you had the choice?
Just in case anyone else comments, I realise you can't advertise on the BBC!
Just in case anyone else comments, I realise you can't advertise on the BBC!
That's not strictly true. The BBC are very self promotional, commonly advertising their own upcoming programs on what is meant to be a public service news website. ITV have complained about this activity in the past and FWIW I agree with them, it is not part of the BBC's remit and they are not supposed to be in "competition" with commercial broadcasters.
All the best, Si
The respected TechMarketView's (TMV) daily free email has a positive opinion about the final results from loss-making Osirium Technologies (LON:OSI)
Stockopedia has this as a sucker stock (not surprising on the figures) but TMV's analysts are shrewd, independent and well informed, in my experience, so Osirium Technologies (LON:OSI) may be worth adding to the watch list. (no position, but considering it).
HI guys - I will prioritise Elegant Hotels (LON:EHG) for you. Cheers. G
Morning All,
FY results this morning from former basket case Smartspace Software (LON:SMRT). Graham I wonder if this would interest you enough to comment?
Paul's last comments (when it was Redstone Connect) were:
I visited this company some time ago, to a briefing on its turnaround strategy under relatively new management. They seem to have done a good job, as this was earlier a basket case under old management, and the old name of Coms.
Overall, it looks an interesting situation. This share is now really a bet on seemingly good management being able to develop a successful software group. It sounds like they want to retain the cash and make acquisitions, rather than returning it to shareholders.
I quite liked this company when I paid them a visit. Management seem down-to-earth, and competent. It could get quite interesting, if they use the cash pile wisely.
The latest balance sheet is pretty good. With the sale proceeds added, then it will be bulletproof - giving scope for some acquisitions.
I am not yet convinced - revenues from continued ops only up 2.8% to £6.3m but they flatter this by sating 2018 included a "large OEM software sale" (i.e comparables not really fair?)...
The space they operate in - workspace management, and the product offerings - interests me, and there's lots of talk of the opportunity (globally) and the progress seemingly being made by the recently acquired business "SwipedOn". But is this really a bit of a start-up, albeit at a potentially "interesting" £5.7m EV...?
Thoughts most appreciated! I completely understand if this just too small/complicated/start-up to be of interest here on the SCVR.
Regards to all!
Smartspace Software (LON:SMRT)
I looked at this a few months ago. My former employer adopted a similar system for room management quite successfully, however from a competitor. After a few minutes I identified at least 10 competitors on google.
I put this in the "too difficult" pile, as it probably needs someone with a smarter system than me to figure out why this one is better than all the competitors.
Good morning Graham
I would appreciate your views on the interims from Elegant Hotels (LON:EHG). There are a lot of moving parts to the financial metrics so your professional eye would be valued; however overall the performance appears positive.
Gross margin is up, free cash is as far as I can tell is satisfactory and if the figures are in right ball park the discount to NAV quoted at 156p is significant. The outlook for the remainder of the year is positive with FX and Brexit being the caveats to continued performance. The shares have been inexpensive for some considerable time so it seems that patience in spades is required if the apparent value is to be recognised. I continue to hold and reckon that with dividends paid the investment is around break even at present. Elegant Hotels (LON:EHG) may succumb to a bid; wishful thinking perhaps?
All the best
Graham, I would be interested in your views on Elegant Hotels' (£ELM) half year report. EPS up 27% and comfortable about meeting market expectations. The US$/£ exchange rate may be important to ELM, but it cuts both ways. A strong $ could reduce demand from the UK, its main market, but at the same time has a favourable impact on the translation of US$ accounts into GBP.
Thanks for your consistent high quality reviews.
Richard
Elegant Hotels looked interesting when Luke Johnson took a big investment in them but the debacle at Patisserie Valerie has made me discount that. I did hold at one time for a bit of profit but it is hard to see it going anywhere fast without someone wishing to acquire it.
I quite like Elegant Hotels (LON:EHG) but I think Paul said in another update that the discount to NAV indicates that the market thinks the assets are over-priced.
I would have thought a valuation for a hotel might be quite volatile (there being no liquid market for them), so can understand erring on the side of caution.
I think the geographical location of the hotels necessitate a low valuation multiple. A natural or man-made event in Barbados would be disastrous for trading. Also I am not sure if anyone would buy the company outright; a large chain would not have so many similar hotels so close to one another, so buying just one would make more sense.
I suppose it is a bit of a proxy for the viability of Barbados as a tourist destination. Having looked at the hotels there seems to be quite a premium on the actual rooms relative to other holiday locations so there must be a big advantage in Barbados itself. Perhaps someone who has been could say.
Demonstrably though it is good business and the market is large (US/UK). Not sure there is a lot of growth in it unless they move to other islands. The management contracts are a good start but not really sure that is where the decent money lies.
I accept the point re concentration but would also argue the converse - scarcity. There are only so many half decent destinations on the planet. The market has been impacted by strength in £ which has held back returns and thus the discount to NAV. This is slightly illusionary as at say $1.5 the NAV would be lower in £ - say 130 but with REVPAR growing and therefore arguably a narrower discount...the company have had an indifferent time earnings wise and find themselves unable to capitalise on additional rooms they have introduced due to revapr weakness. This should return one way or another. Following the divi cut you still get a decent yield and down here I think you can just sit and wait, either the market will return for them and divi can rise again or sol melia or private equity will return. One way or another you can expect much closer to nav (130) in the next few years which will make a decent return irrespective of stock market levels.
It's interesting that Elegant Hotels (LON:EHG) weighting is to H1, which means the full year out turn now for FY2019 should be quite certain, especially as they will have good visibility of revenue for H2 due to the forward booking nature of the business.
So looking very cheap on FY2019 metrics!
My morning smallcap tweet:
Vertu Motors (LON:VTU), 1Spatial (LON:SPA), Ceps (LON:CEPS), BigDish (LON:DISH), Keystone Law (LON:KEYS), Telit Communications (LON:TCM)
Vertu Motors (VTU) FY adj pretax £23.7m (£28.6m) ahead of market expectations (not stated). Rev up 7%, LFL up 5%. "Major capital expenditure programme now largely complete aiding future Free Cash Flow generation." Current trading with management's expectations. I hold.
1Spatial (SPA) acquires geospatial software solutions company Geomap-Imagis for £7m. Placing at 31.5p, a 5% discount.
Ceps (CEPS) FY18 rev-cont up 10%. Pretax-cont £137k (£211k). Div 0. Chmn says "accounts are very confusing and complicated, and it is hard, in the absence of individual company monthly management accounts, for the CEPS shareholder to discern this level of progress and improvement." Yet it publishes FY 4.5 months after year end and last tradng stmt was in H1 RNS in Sept!
BigDish (DISH) "is preparing to set its sights on the London commuter towns." Actually setting its sights on, surely?
Keystone Law (KEYS) FY comfortably ahead of market expectations. Rev up 35%, adj EPS 13.4p, up 43%. FY div 9p.
Telit Communications (TCM) caves on one VAT dispute in Italy, pays €400k without any admission of liability for 2004-2007. Still opposing tax penalty deeds separately issued against Telit in August 2015. I hold.