Small Cap Value Report (Weds 1 July 2020) - TPT, HMSO, LTHM, KIE

Good morning, it's Paul here, with the SCVR for Weds. Please feel free to leave your comments from the 7am start of the RNS, whilst I write up the main report throughout the morning and early afternoon.
See the header above for the company announcements I'll be writing about. I generally only respond to reader requests if you put up some compelling reason why the announcement is worth me looking at. I can't cover everything single-handedly.
To get you started today, here's the link to yesterday's SCVR, which significantly exceeded market expectations with 10 companies covered in total! I added 5 more after lunch, covering: STAF, WGB, TRAK, SYS1, and TST, in addition to the other 5 companies I wrote about in the morning (VNET, D4T4, SOLI, DRV, COG).
Estimated timing - a medium workload today from the RNS, so I should be finished by 1pm or a little later.
Update at 13:21 - today's report is now finished.
.
Lookers (LON:LOOK) - shares suspended due to failure to publish 2019 accounts by 30 June. I might be mis-remembering, but I thought the company had secured an extension to the publication deadline? Maybe not.
Malvern International (LON:MLVN) - shares resume trading today, after a near-death experience. Small fundraising recently secured. New CEO brought in. Everything will hinge on how it can re-start operations. Very high risk, I'm not going to revisit this one, having got it wrong previously.
Walker Greenbank (LON:WGB) - a quick update. A NED has bought £19.4k-worth of shares. The CEO's husband has also just bought £20k of shares. That's helpful.
Also, Gromley and I were swapping our fag packet forecasts yesterday, in the comments section. I've now got an up-to-date broker note, which suggests a loss of £(5.5m) for FY 01/2021. This is based on a revenue assumption of -30% for the full year, which seems overly cautious to me, given that it was -35% in the first 5 months during covid. Although thinking about that, covid would have probably only affected about 3 out of those 5 months, so sales were probably down a lot more than -35% in April & May. Anyway, we have a range of forecasts, with a broker at £(5.5m) loss, Gromley at breakeven, and me at a £(3-4m) loss.
.
Topps Tiles (LON:TPT)
Share price: 47p (up c.4%, but wide spread at time of writing, 09:32)
No. shares: 195.0m
Market cap: £91.7m
(I'm long at the time of writing)
Topps Tiles Plc (the "Group"), the UK's leading tile specialist, announces a trading update for the 13 week period ended 27 June 2020.
It's a Q3 update today because the company's year end is FY 09/2020.
This update looks surprisingly good to me;
Retail trading over the third quarter improved significantly as stores re-opened, with average sales per week growing from £0.8 million during April (when all stores were closed) to £3.9 million in the final week of June when all stores were trading, which was 5.4% below the same week in the prior year on a like for like basis. The Board is pleased by this performance, which was ahead of its revised expectations following the outbreak of Covid-19.
April sales must be online only, as the stores were shut. I've bolded the most important bit above, which is that last week, with stores open again, LFL sales were only down 5.4% on last year's equivalent week. That's very good indeed, in my view, given that plenty of people are still not going shopping.
- TPT stores are well suited to social distancing, with low footfall & spacious stores
- Better than expected customer demand
- Online sales going well, after recent investment
- Commercial - down 16% on prior year's Q3, but trend improving as builders return to work
Property - £18.1m raised from sale & leaseback. This is a great example of why I love freehold property on company balance sheets - because it's a hidden asset that can make all the difference in times of difficulty, which can be sold, or used as security for bank borrowings. Ted Baker (LON:TED) is another example of this, which recently completed a large sale & leaseback on its HQ, and might not have survived if it hadn't had that freehold asset.
Liquidity - looks ample, with £52.9m cash headroom, including a £10m CLBILS facility available. Net cash of £3.9m looks fine, and reflects benefit of sale & leaseback.
My opinion - this looks very good to me, and I think the share is offering good value still, at c.46p. I hold a long position, so may be subconsciously biased, although I try my best to be honest & objective about everything.
Risk:reward has improved significantly today. I'm encouraged by the strong sales recovery (only a bit below last year now), and the liquidity position is fine, so no risk of insolvency. Obviously results for FY 09/2020 are likely to look poor, due to the covid impact. But given the rapid recovery already seen, then I'm feeling more optimistic about the rest of this year. There's lots of anecdotal evidence that furloughed people have used the time to spruce up their homes.
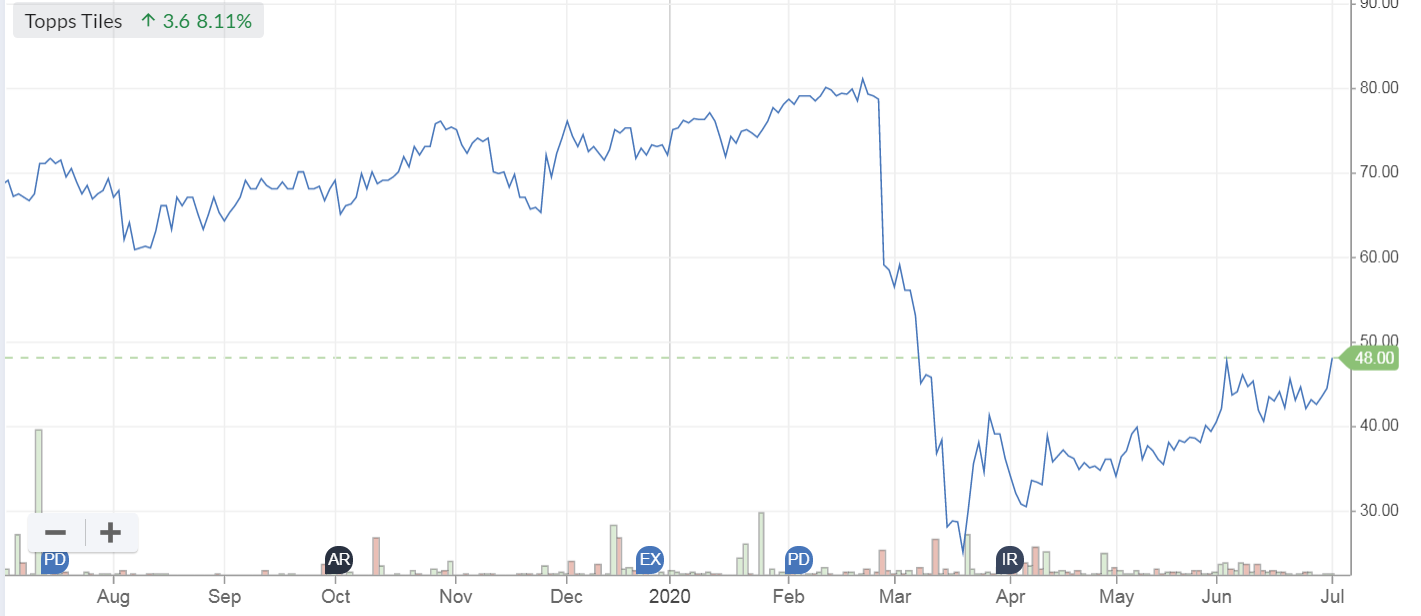
Looking at the chart, I think we could see a return to say 60-70p given time, so there's useful upside here if I'm right. Thinking about that some more, as trading is returning to normal, and there's no need to dilute through a fundraising, then arguably this share should be gradually heading back towards its pre-covid valuation of c.80p.
.
.
Hammerson (LON:HMSO)
Share price: 83p (up 4% today, at 08:32)
No. shares: 766.3m
Market cap: £636.0m
(for the avoidance of doubt, I no longer hold any position in this share)
Debt, liquidity, and rent collection update
Background from me - HMSO owns some mid-market shopping centres, in the UK and Europe. Following the demise of INTU, under an insurmountable debt burden, other retail property companies are very much under the spotlight now. Widely reported problems are that under lockdown, tenants cannot (or will not, in some cases) pay the rent. Also some tenants are going bust, leaving behind empty units. This is causing a financial squeeze, where property companies have to deal with falling capital values of their properties, and potentially onerous debt (e.g. possible breach of banking covenants).
My summary of today's update;
- Negotiated amended covenants with bondholders, until Dec 2021 (see RNS for more details). Bondholders would also get 30% (through an offer of prepayment at par) of the proceeds from disposals, in particular circumstances. Other conditions apply. This shows how the bondholders are asserting themselves, to protect their own interests. Shareholders need to hope that the company keeps on top of things (i.e. doesn't breach covenants), as bondholders can end up in the driving seat once covenants start being breached.
- Approved for £300m Govt loan under CCFF, increasing maximum liquidity to £1.5bn - that seems a lot of liquidity
- Drawn down another £300m on RCF
- Rent collections for Jan-June 2020: 73% for UK, 53% for France, 72% in Ireland
- Rent collections for Q3 (which were due on 24 June quarter date in the UK) - only 16% collected in the UK so far, no figures given for France or Ireland. Confident rent collection will improve as it negotiates with tenants. To be fair, it is very early days, only a week after rents fell due, plus a lot of tenants will have negotiated monthly payments. Hence I don't think this 16% figure is quite as alarming as it might initially seem.
Stress testing - I've run through the numbers to look at a negative scenario, of c.40% negative revaluation of the properties in future (to reflect falling rents, empty units from retail insolvencies, and incentives needed to attract new tenants on cheaper rents).
The figures below are taken from HMSO's 2019 Annual Report, with my adjustments to reflect the estimated impact of covid on property values;
£2,099m directly owned properties - write this down by say 40%, to £1.26bn
£3,017m JVs. These seem to mostly be debt-free, apart from Westquay (Southampton). Write these down by say 45% (to reflect the gearing on WestQuay), arrives at £1.66bn
£1,505m Associates. This is split: £2,114m property assets, £720m debt, £111m other. So if the properties are written down by 40%, then the overall total drops to £659m (a 56% reduction in NAV, due to the impact of gearing)
This arrives at;
2019 valuations = £7,087 property assets, less £2,505m debt = £4.6bn NAV, less £200m other = £4.4bn NAV, or 574p per share
My revaluations = £3,579m property assets, less £2,505 debt = £1.07bn NAV, less £200m other = £870m NAV, or 114p per share.
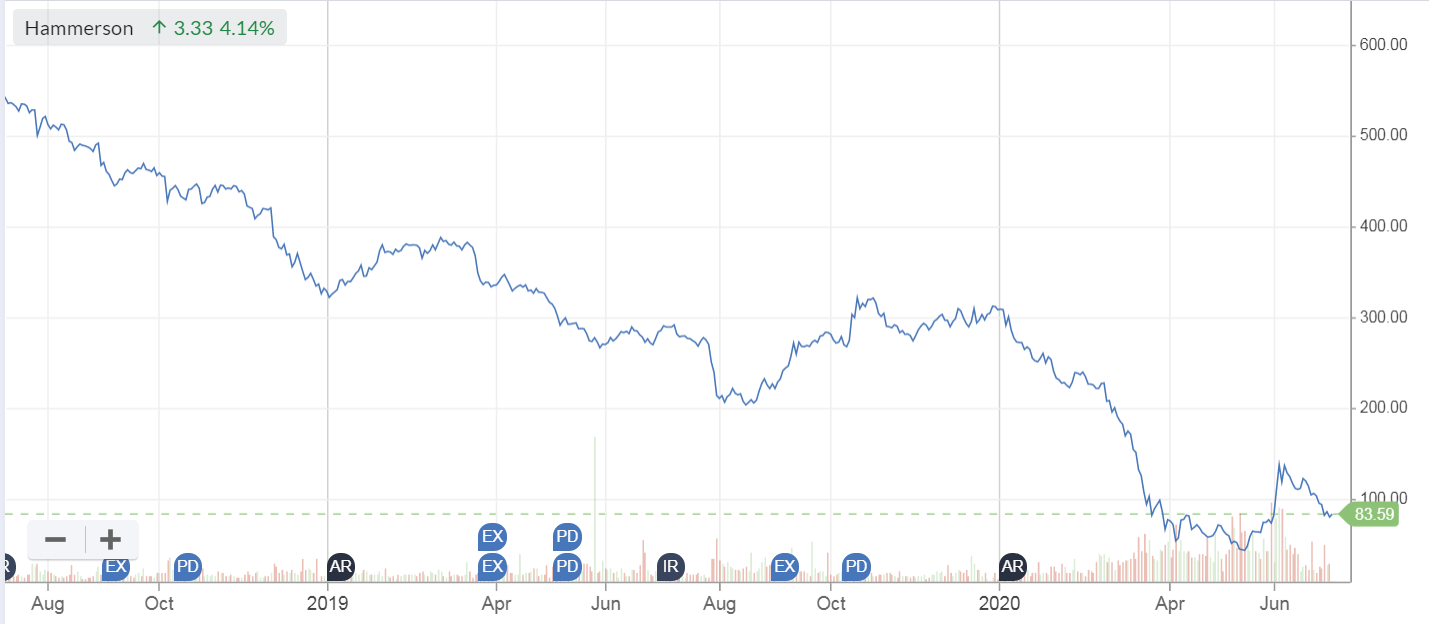
An alarming drop in NAV, as you can see. This explains why the share price is at such a large discount to 2019 NAV - it's because the market is pricing in a c.40% drop in asset values, which actually does look realistic.
What about Loan To Value (LTV)? On the 2019 valuations, LTV looks fine, at 35%. Once we write down asset values as above, by c.40%, the LTV shoots up to c.70% - well into danger territory.
EDIT: Just realised I forgot to add back the assets held for disposal of £466m, since that sale recently fell through. Therefore the total writedown in property values would be higher than as stated above, if we include these additional assets. End of edit.
My opinion - I think the RNS today is good in terms of liquidity - i.e. it sounds as if the group is not under any liquidity or solvency pressure, at the moment.
The problems are building up in the pipeline though. The big issue is that its property assets are likely to be written down in value very considerably, possibly for several consecutive years. When property assets fall heavily, but debt remains the same, then it can all unravel, as it did with INTU, and as demonstrated with my rough figures above.
Who knows at what level asset values might settle? I'm hearing that rents are coming down by as much as 45% for shopping centres. That's a gradual process, because rents can only usually come down on lease expiry, which are spread over years into the future. Or tenants can exit leases when break clauses are present, but each lease is different, with whatever terms the parties negotiated at signing. Of course, many leases are ending when the tenant goes bust, happening on almost a daily basis at the moment. I see TM Lewin, and Bensons/Harveys are the latest to go bust in their current form (then re-surface through a pre-pack, or move online completely as TM Lewin has just announced).
Looking at HMSO's 2019 results, it wrote down the value of its properties by £(295m), plus there were large losses of £(423m) relating to Joint Ventures. which is writedowns of asset values too. Overall, NAV at end 2019 was £4,377m, down 19.4% on prior year.
That equated to a very healthy 601p per share EPRA NAV. The current share price is only 83p per share, indicating that the market believes HMSO's assets are wildly overvalued, and that there's potential solvency risk too, otherwise the discount wouldn't be so huge.
As demonstrated above, if the property values do end up falling by as much as 40%, then the equity at HMSO would look very vulnerable. Bondholders are already flexing their muscles, as we've seen today. If future covenants are breached, then the bondholders could potentially force the group into administration. The assets are then sold, and bondholders are first in line to be paid. Equity might end up with little to nothing.
So, in a downside scenario of minus 40% property revaluations, then I think HMSO equity could be toast. However, it has got time to sort things out, as the liquidity position looks OK, and the bank debt seems to be unsecured (per today's RNS). What happens if the bank facilities are withdrawn though?
I think HMSO needs to do an equity raise, which might be possible if the re-opening goes well, and covid retreats once better treatments/possible vaccine, might be rolled out in 2021 perhaps?
Overall - this looks like the share price could continue to be volatile. It's one of the most heavily shorted shares in the market, which led to a lovely short squeeze not long ago, which was a very profitable trade for me (56p in, and c.120-134p out, in stages). Would I buy again at the current price? Probably not, but it depends on how retailing pans out in the coming weeks & months. If shoppers return to shopping centres en masse, then HMSO's rent collections would improve, and it could survive with asset values impaired less than in my stress tests above (which are probably worst-case scenarios). If people continue to avoid shopping centres, then HMSO could slowly unravel. It's not under any immediate threat, but the storm clouds over it are fairly clear, longer term, once those asset values are devalued to levels that reflect tenants inability to pay current rents.
Shopping centres seem structurally challenged assets. Would I want to part-own shopping centres? No - because divis look unlikely, as balance sheets either blow up, or are repaired. Is the move to online shopping going to reverse? Very unlikely. Going to a shopping centre at the moment is surely a joyless, stressful experience. So I cannot see footfall/revenues returning to normal any time soon. But who knows? Maybe the public will adapt to social distancing measures, wearing masks, etc,? After all, that's fairly normal in the Far East now, and people still go shopping there.
There's a lot of downside already priced-in. In conclusion, I'm probably neutral on HMSO at this level. Rather a long-winded way of arriving at that conclusion, but I wanted to work through the numbers & throw them out there to you, for your comments. I'm not a specialist in the property sector, so might have missed something. Therefore please treat my figures as only very rough estimates, which might contain errors. As always, doing your own research is essential.
.
.
James Latham (LON:LTHM)
Share price: 840p (unchanged today, at 11:18)
No. shares: 19.9m
Market cap: £167.2m
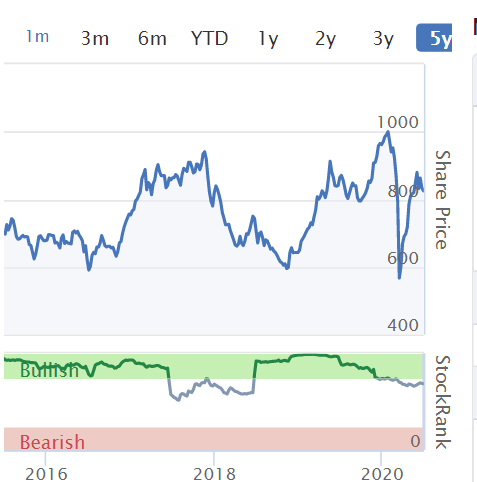
This is a timber products importer & distributor. It's still family-run, and a lot of us in the small caps world admire the way this business has been well-managed, with conservative finances, and a well-covered divi, etc. Having said that, looking at the 5-year chart, it's not actually been a particularly good investment, unless you happened to buy the dips, and sell the surges. The drawback to trading this share, is that the quoted spread is so wide, and it can't usually be bought or sold in any decent size. Maybe it's not as good as my preconceptions suggest?
.
FY 03/2020 results - quite good. PBT up nearly 3% to £15.7m , on revenues up 5% at £247.1m.
EPS flat at 63.1p, or up 3.9% if we use the adjusted EPS of 64.0p - not much difference.
PER is 13.1 times on the adj EPS - good value, although the company is looking ex-growth, so I wouldn't want to pay a high multiple for it. That said, in a zero interest rate environment, a PER of 13.1 looks good value for a business that generates plenty of cash, and has a nice balance sheet. Providing earnings are not going to collapse of course.
Dividends - are still being paid. That's the advantage of having a strong balance sheet, and divis that are well covered. The final divi is down a bit at 10.0p (LY: 12.9p). Total divis for the year are 15.5p (LY: 17.9p), yielding 1.8% - better than nothing.
I think it's worth mentioning that a company's dividend paying capacity is arguably more important than what it actually pays out. LTHM could pay out a much bigger div yield, and at some point in the future, it might do so. And/or pay special divis, with the surplus cash. A short term downturn in trading doesn't mean that divis stop for several years, unlike highly geared companies. Mgt comments on divis;
The board considers this level of dividend to be prudent given the balance between the good results achieved in the year to 31 March 2020 and the difficult market conditions experienced during the first quarter of the current financial year caused by the COVID-19 pandemic.
Covid impact - usual actions have been taken, conserving cash, quick action to reduce costs, etc.
Sales in April were down 60% on LY, improving to down 40% in May. June improving further, expected to be down 20% on LY. Isn't it good when companies just give us the numbers, instead of a lot of waffle! Well done LTHM and its advisers.
The full impact of the virus and the effect on the wider economy are impossible to predict at this stage.
Maybe, but the company should be able to give guidance, even if it's a range of possible outcomes, from downside scenario, base case, and optimistic case.
Access to broker forecasts - this is a general point, not specific to LTHM. I am very unhappy with the widespread lack of access to forecasts at the moment. This information is currently generally being withheld from private investors, but the top brokers are giving forecasts for their esteemed clients only. It's all highly unsatisfactory, maybe even illegal - for brokers to provide forecasts privately to their top clients, which have been based on privileged information sourced from CFOs of the companies.
With no access to any forecasts for LTHM, I think it's best to just write off the results for this year. If business is already back to a run rate of only 20% down on LY, with the construction industry only recently having re-started, then I imagine trading might gradually return to normal. So maybe we should value it on next year's earnings instead, and assume they're likely to be similar to FY 03/2020? As long as I can see a fairly decent resumption of trading, to not too far below last year (as with TPT above, and LTHM), then I'm comfortable with this approach to valuation.
Outlook - the section titled "Development Strategy" in interesting. It talks about possible acquisitions, new products, etc. To me, this emphasises how strongly financed companies can think about expansion in a downturn, taking advantage of weaker competition. Whereas highly geared companies have to retrench, and focus on survival. Let's hope that more companies, and the City, learns from this crisis, that loading up on debt is potentially ruinous, whereas running a strong balance sheet, provides great benefits & security in the tough times.
Balance sheet - I'm so sad, that I actually get a tingle of endorphins when I review a strong balance sheet!! So, am I tingling now? Yes! With a couple of reservations.
NAV is £104.3m, including intangibles of only £2.7m, giving NTAV of a whopping £101.6m
What does that mean in practice? It means the fixed assets of £36.0m are owned outright. The same can almost be said of all the inventories of £44.3m, & the receivables book of £47.0m. Both look a little high to me - I wonder if customers are paying late? There could be some bad debts in that receivables book, if lots of builders go bust? I doubt it would be a big problem though, as the large builders are all very strongly financed.
There's only £29.9m of current liabilities, with the cash pile of £17.0m covering more than half of that.
Overall, it's bulletproof.
The only thing I don't like, is that £11.8m pension deficit, which has gone up 36% in the year.
My opinion - a very nice, solid business, at a reasonable price. Good value actually, in my opinion. It may not be the most exciting business out there, but I see it as a very safe, long-term thing that conservative value investors tend to like.
.
Kier (LON:KIE)
Share price: 87.5p (down 10% today, at 13:00)
No. shares: 162.1m
Market cap: £141.8m
Kier Group plc (the "Group"), a leading construction and infrastructure services group, today provides an update on trading since 1 April 2020 (the "period").
It has a 30 June 2020 year end, so this update is for Q4 (and presumably the whole FY 06/2020).
The CEO says;
- "Underlying trading remained resilient"
- Decisive mgt actions are delivering significant benefits
- Good liquidity position
Covid - adversely affected revenue, and increased costs. 80% of sites remained open. Almost all sites now open.
Outlook - continues to win "high quality work". £7.6bn order book at 31 May 2020.
Whilst the Group anticipates that the effects of COVID-19 will continue to affect volumes and result in additional costs as the Group adapts to operating in a post-COVID-19 environment, the strength of the Group's orderbook, its expertise in managing complex projects and its long-standing client relationships enable the Group to remain confident in its outlook for the financial year ending 30 June 2021.
Cost-savings of £100m flowing through.
Various other points are mentioned, but it's all a bit disjointed. I'm only really looking for the overall picture, which is not clear from today's update.
Fundraising likely? - this is probably what's whacked the share price today;
Before COVID-19, the Group had made good progress in implementing a number of measures to reduce its net debt and strengthen its balance sheet. As a result of COVID-19, over the next 12-18 months, further actions will be taken, including: continuing to implement a range of self-help measures, driving a further increase in the Group's operating cashflows, continuing the process to sell Living and a potential equity issue.
Net debt -
... The Group's average month-end net debt for the current financial year is expected to be c.£440m.
Covenant waivers agreed with its bankers for 30 June 2020. In other words, it breached its covenants. In this type of situation, bank support often hinges on an agreement to raise fresh equity. Therefore, I would work on the basis that an equity fundraising is almost certain to happen. Not knowing what terms the funding might be raised on (it could easily be at a deep discount), then I'm not interested in looking any further at this share. Existing private shareholders are often excluded from fundraisings, and can end up getting diluted by instis buying at a discount in a placing.
Pension fund - in talks with trustees over recovery payments.
My opinion - it's too complicated, and given that an equity fundraising now seems almost certain, I can't see any motivation to buy the shares now. Would I want to own shares in a sprawling, low margin infrastructure group? Absolutely not. It's just an awful sector, where many similar companies have collapsed under too much debt.
I suppose the upside case here is that, with a strengthened balance sheet after a fundraising, the shares could re-rate.
.
That's it for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
Hi Timarr,
There was previously a court case by Ryanair looking to prevent On The Beach (LON:OTB) etc from reselling airline tickets and therefore stoping OTB customers from booking the whole holiday in one place/one go. Id forgotten about this when i bought back and your comment above reminded me, do you know if thats still active, i don’t recall mention of it recently.
There was previously a court case by Ryanair looking to prevent On The Beach (LON:OTB) etc from reselling airline tickets and therefore stoping OTB customers from booking the whole holiday in one place/one go.
Yeah, I looked at this a while ago, As far as I can tell Ryanair sued everyone and, eventually, most of the OTA's just quietly dropped them. Underlying that is that Ryanair wanted to become an OTA themselves but personally I wouldn't buy a cute puppy from Michael O'Leary if I could avoid it.
It's difficult to know how material this is but I'd have thought the airlines would be happy if anyone was booking flights right now.
timarr
personally I wouldn't buy a cute puppy from Michael O'Leary if I could avoid it.
And that is the challenge. Ryanair and O'Leary are fantastic operators who invariably end up with the only "cute puppies" available. On many levels I hate them as they always outsmart me but I keep coming back for more. Apart from occasionally feeling a little ripped off, I have never had a bad A to B experience. Even my last flight with them to Oslo (Airport as near to Oslo as Heathrow is to Manchester) was a wonderfully joyous & efficient experience. (2 hour train journey to the centre of Oslo was fantastic). Will I use them again? Probably, will I feel a little ripped off? Probably. Will there be an alternative that won't likely go into administration, offer reasonably convenient departure/return take off time, fly direct from a reasonably local airport and for an affordable price? Probably not. Michael will be the only one offering the cute puppies...
Paul , cant give you uptick today , the tally says 185 as I type but the mouse wont allow me to plus 1 ???? Anyway as always many thanks for your fine efforts.
Thanks for the update on the broker forecasts for Walker Greenbank (LON:WGB) Paul.
I agree with you that the forecast of a 30% YoY reduction in revenues seems overly pessimistic, implying virtually no further pick up in sales for the rest of the year.
For a further "fag packet" view of their revenue profile during the first 5 months - you're right that up until lockdown Revenues should have been largely unaffected. This might suggest that revenues were down by c. 75% at the height of lockdown recovering to -31% in the last 4 weeks.
My initial thoughts yesterday were that the -35% Revenues for the 5 months was better than I expected but that the -31% for the last 4 weeks was not as good as I hoped. On reflection I think I have flipped my view on that, but getting an update on latest trading at the end of July.
Anyway - if the revenues do prove to be 30% down on the full year, that would be an extra nearly £7m off the gross profit figures we discussed yesterday so the broker's view of a FY loss of £5.5m suggests they are in the same ball park as me on the Opex reductions achieved.
Disappointingly, it does not look like the company have made a recording of the analysts call available, however at least they have published the slide deck
Not too much leaps out at me from the presentation. Although there are a couple of useful waterfall charts (#8 & #9). Also an interesting slide (#16) on the customer needs they are addressing - almost incomprehensible without the spiel that no doubt accompanied it - but I am at least reassured that they do recognise that they are a consumer business.
(I seem to recall I had "a bit of a rant" a few months ago when they described themselves as B2B.)
Good points, thanks Gromley!
I'll check out the Walker Greenbank (LON:WGB) slide deck, thanks for the link.
Amur Minerals (AMC)
This is my Micro Cap choice and a no brainer multi bagger....
See below article....
Amur Minerals - (LON:AMC) - The Start of the Final Rise! (Nickel Mining)
https://www.stockopedia.com/content/amur-minerals-lon-amc-the-start-of-the-final-rise-nickel-mining-628718?order=createdAt&sort=desc&mode=threaded
There are a few more before this latest one if interested....
Again DYOR and GLA.
I assume you meant to post this on one of the advfn boards rather than here ;)
Driver (LON:DRV)
From yesterday's SCVR:
Driver has done a results webinar today, I'll put up a link to the recording, when it becomes available (from BRR Media) - if anyone spots this, please do put up a comment here, with the link.
At last it is available at : https://webcasting.brrmedia.co...
Balance sheet - receivables stands out as very high, at £21.8m. Are there any potential bad debts in that total, I wonder? It would be worthwhile to ask the question.
All explained by CFO about 16.5 minutes in
It could possibly become a takeover target at some stage? I seem to recall there was a flurry of takeovers at good prices in this sector a while ago.
The recent increase in stake by AB Traction of Stockholm (they started by buying from the Buffettology Fund when that pulled out of small caps) has got people on another board very excited, pointing out that AB Traction bought in to both Waterman and White Young Green leading to their being taken over.
Smashing, thanks for that sharw! Very useful points & link.
Regarding the Cello Health (LON:CLL) takeover announced this morning I thought the premium was on the mean side.
My entry in the Stock Picking Challenge consists of the 5 that I owned at the end of December and that I thought could receive a bid this year. 3 have not yet and are in negative territory, Indigovision came up trumps and my entry shows +123% compared to Cello Health showing +19.7%. (Of course, in retrospect I should have chosen a load of mini-cap US pharmas making a loss but which would multibag should a nasty virus emerge!).
I added to my own holding in December at 133p following more buying from Kabouter of Chicago described as a "friendly activist" hedge fund. Interestingly they are not among those who have signed irrevocable undertakings to accept. Will they find a counterbidder, is "An implied enterprise value multiple of approximately 12.3x Cello Adjusted EBITDA of £14.8 million for the year ended 31 December 2019" on the low side or am I just being greedy?
Paul:
Lookers (LON:LOOK) - shares suspended due to failure to publish 2019 accounts by 30 June. I might be mis-remembering, but I thought the company had secured an extension to the publication deadline? Maybe not.
Yes, you were mis-remembering - they warned of this on 8/6 and in the SCVR of that day you wrote:
Late accounts, possible suspension of shares, auditor resignation
I've re-titled the announcement. from the original, which was "Update on Results".
This is a worrying announcement.
https://www.stockopedia.com/co...
Topps Tiles (LON:TPT) has seen a halving of its operating margin from 2009 to 2019, with little that I can see to reverse that decline. I suspect that the market place is now a lot more competitive.
hi Paul nit Revolution Bars Group, I mean ticker RBGP..... the Rosenblatt Law firm
Hi Paul,
Your positive write up on Topps Tiles (LON:TPT) this morning might encourage me to take the plunge given that more people might be doing up their bathrooms/kitchen as a result of lockdown! However, I think this is also a good example of how we have to be careful with Stockopedia's Stock Reports given the impact of IFRS16 (treatment of leases) on balance sheets and associated ratios. The introduction of this standard for the year to October 2020 by Topps Tiles (LON:TPT) has created a very false impression of the company's financial position in the Stockopedia Stock Report. This is exacerbated by the fact that in the Balance sheet data (TTM) there doesn't seem to be a £125m increase in fixed assets to set against the additional £130m in capitalised lease liabilities (source: latest interim report). This distorts Enterprise Value and related ratios as well as generating extreme gearing ratios and questioning Topps Tiles (LON:TPT) solvency (Z score, F Score). Might be stating the obvious but it does demonstrate that we can't take a Stock Report and associated Stock Ranks at face value. DYOR (with your help!) as we always say.
AIUI, in both kitchens and bathrooms, Topps Tiles (LON:TPT) products are being replaced by products that they do not supply. Specifically glass splash backs in kitchens and large panels for use in showers. The business has been dying on its feet for years and seems unable to significantly increase sales or margins. That is not to say it might not be worth more than the current SP but why invest in a business in terminal decline... ...except perhaps for the dead cat bounce?
All IMHO. Cheers, Martin
Re Topps Tiles (LON:TPT) 's prospects being undermined by increasing incidence of "glass splash backs in kitchens and large panels for use in showers" replacing tiles, I would also add that online is also becoming more significant as people grow in confidence in making big ticket items online.
Now you can easily get a sample tile through the post plus very good online visualisation tools so the value the value of Topps national chain of retail stores is decreasing.
To be fair, this is why they have pushed into the commercial side in recent years that is +/-50% of the market - the only problem being this is only a few % of Topps sales at present.
I see it as becoming a value trap in Stockopedia terms.
Now you can easily get a sample tile through the post plus very good online visualisation tools so the value the value of Topps national chain of retail stores is decreasing.
I don't buy this on-line visualisation thing at all. Anyone that has tried to find tiles for a kitchen or bathroom will know that the light in a specific room can make a massive difference to their appearance. Without seeing sample tiles in place in the room itself, you are likely to end up with a disappointing end result. I think there is still a lot of mileage in retail space for certain businesses and Topps Tiles strikes me as a good example, where people want to see the product in the flesh and need help and advice in selecting a suitable product to meet their requirements.
All the best, Si
£TPT - I agree the majority of the consumer tile market remains in this physical shop space (and that some physical shops will continue to do well). But if Topps are the market leader in stores and even 5-10% of the market has migrated on line (I am assuming this is true but have not found good data to support the %), this disproportionately affects them.
Automatic quotes online also puts ever more pressure on pricing. Unique, only-at-Topps lines instore only partially offsets this pressure.
Finally, in my recent and personal experience, the colour/shine of tiles is only really visible and 'true' when they are ALL the tiles up in your own room. The light in the showroom is very different to my poorly lit bathroom for example and varies on the weather outside.
Hi all,
With regards to £HMSO - can anyone explain what Goldman Sachs is doing: they twice increased position up to 10% and within few days reduced to 0%, latest is on today's RNS. What they are doing? Appreciate your comments.
Toops Tiles (LON:TPT) is a very well managed business, as evidenced by the sale and leaseback and strong balance sheet. The last week of June LFL only down 5% is remarkable although June overall was down 20%. Perhaps need to be careful not to read too much into just one weeks performance as there must be some pent up demand to be satisfied.
The next few months in retail and leisure are going to be fascinating.
Yes good point, I suppose with tiling, a lot of it would be one-off project work, so a big spike in sales after lockdown could then subside, as you say.
Does anyone know what the split of TPT's sales is, re DIY work, or repeat business from professional decorators?
Hi Paul,
Great piece of work on Hammerson (LON:HMSO) explaining what might happen to valuations. If feels consist we my own thought and valuation. (graph below). It assumes an -18% drop in rents FY20 and then -6% decline thereafter. ( NAV reaches 109p by 2024).
Ultimate valuation is dependent on the footfall of the consumer and how much rents can be collected.
DYOR
BSV
I see TM Lewin are closing ALL their UK stores. Its interesting how some businesses see so little value in having physical stores while others do.
React (LON:REAT) came in with great numbers this morning. A tiddler in market cap but a nice potential growth story in the making. As mentioned it is very small but acorns and oak trees and all that..
This comment sounds like a ramp to me.
It actually reported numbers on Monday, not today, and I briefly reviewed it here. It made a miniscule profit, certainly not "great numbers". There was a more upbeat outlook statement.
Can you try to make comments more factual please.
David Smith who comments on economic matters in The Sunday Times said early on that virtually all British recoveries are V shaped, but that unemployment would be an ongoing issue.
I know of an IT company that is having good sales performance but has got some of its fee earning staff on furlough, and all staff on slightly reduced hours, because they can't tell whether some of the momentum is from a previous buoyant period, and some fee earners have reduced work. Despite what people are signing about Zoom etc. it is also clear that in larger companies the internal communication process is stretched somewhat, and perhaps people are underestimating some of the efficiencies that come from face to face interaction at work.
This could mean some redundancies at the end of furlough, but possibly the Company may have a decent profit.So a mixed bag.
I know some small businesses that are doing better than feared but will still have redundancies. It's a mixture of resetting their strategies, having a better view of which employees are delivering and which were perhaps getting carried along by the rest of the office staff and are not so well equipped for the new normal, and not letting a good crisis go to waste.
The trouble with GDP data, is that recession/recoveries may look V-shaped overall, but that tends to mask a big & more prolonged downturn in private sector activity, offset by the public sector running a big deficit, which tends to gradually reduce over c.7 years (as happened after 1990 & 2008 recessions).
Thinking back to what happened after 2008, as regards corporate earnings, many small caps took years to rebuild their earnings. It certainly wasn't V-shaped in terms of earnings.
It depends on the sector though. At the moment we must be seeing the most extreme divergence between different sectors that I can remember before.
Everything could change again very rapidly, if there are positive medical developments.
It seems to me that the UK small caps sector is very vulnerable to negative investor sentiment. Sentiment seems to switch between extreme gloom, and euphoric optimism, without warning. This is an incredibly difficult market to navigate, and predict.
Whilst in the US, we have extreme levels of euphoria in anything growth or tech-related. This is absolutely bizarre, given the extent of the economic downturn, and massive unemployment, plus soaring covid cases. I've never seen the market completely ignore such a tidal wave of extreme negative factors. It's basically because the whole system has been rigged to force people into equities, by stripping away returns on other assets, and flooding the system with money.
Stuff like this (asset price booms to unrealistic levels) never usually ends well, but this bizarre situation could continue for years. Nobody knows.
Paul, re your second paragraph - and I do mean this nicely: you just want to be loved, don't you?
Isn’t that true of us all? Except possibly Simoan
Hi Paul, any thoughts on the fund raising at Revolution Bars?
Thanks
Mark
We've covered that before. Here's the archive of my stuff on RBG.
There's nothing new to report.
Thanks-I have read this . I probably didn't make my sell to clear-is there any news on how much existing shareholders subscribed to the round and the general feeling on funding now required?
Hi they released an update a couple of days ago about the open offer take up, hopefully the following link works
https://www.stockopedia.com/share-prices/revolution-bars-LON:RBG/news/revolution-bars-result-of-open-offer-urn:newsml:reuters.com:20200625:nRSY1427Ra
thanks Tommy
Sometimes the hard numbers are worthy of mention,
YTD
FTSE 100 -18.9%
FTSE 250 -22.5%
ALL -19.4%
£ -7% ( in Euro) -7.5% (in $)
Gold (measured in £) +23.4%
All UK Govt +9.45%
Inflation linked UK Govt +14.91%
Uninvestible bonds showing a clean pair of heels to equity - a clear deflation vote so far. 1992 to 2020 and bond market trucks on - so balanced portfolios have done ok again.
Personally Im not interested in playing this trend. This is not to my credit but I saw the turn in 2001 .... to favour value... and am happy to sit this one out until it turns. I am playing Gold. My watch list of :
US Bond yields, Dollar and commodities remain tilted to deflation as you would expect. The commodities have V shaped like equities and show a real mix of returns but Oil and Copper are not yet showing enough to suggest anything is changing. Banks stocks reflect the flat yield curve. Whilst the Fed may be able to depress short term yields ... the 10s and 30s still have plenty of scope to reflect fundamentals. They have not moved yet. The FED has stepped back significantly in the last month from very high levels of buying in March/April.
Lumber is strong, some of the softs are strong.
What am I on about you may ask? Well the UK stock indices have a value tilt... a pick up in inflation would be good for UK stocks and initially Sterling. Rising bond yields may prove difficult for indices/ especially US indices/ but not all stocks. We can plough through the RNS for the last six months but we will learn very little about which stocks to invest in, its needle in a haystock stuff! Big thanks to Paul and Graham for trying. Make no mistake all the bright minds are focussed on this one issue and the conclusion seems to be, its not working yet...so fiscal policy follows. We will see. Best of luck to everyone in the second half....
@RDHowarth
Thanks for the excellent macro analysis. Please keep them coming!
RDHowarth
I would be interested to know where your % increase for index linked gilts comes from. My analysis of individual IL gilts using data on https://www.fixedincomeinvesto... suggests that the increases for issues with maturities up to 20 years is nothing like the increase YTD you suggest. Beyond 20 years the YTD growth is admittedly much higher, and closer to your quoted number, so perhaps these maturities have a higher weighting in the average growth number?
ACouncil
Good question - I am desperately short of info re IL markets. I used to be lucky enough to sit next to a bond team who I could just go and ask. Anyway, I use the ishare index linked fund return which is 14.9% and designed to track the IL UK Govt market over 5 years. Most of the other fund incl Vanguard are similar although a little lower - between 10% and 15%.
I pick these up from fund analysis on AJ Bell platform which i find pretty good. If Im making a mistake please let me know.
Welsh based micro cap Haydale Graphene Industries (LON:HAYD) put out an interesting RNS this morning. Functionalised Graphene Enhanced Fabric for Antibacterial Masks. 'The global healthcare PPE industry has an approximate value of 17 - 19 billion USD (Source: Frost & Sullivan), with huge growth seen in the personal healthcare industry. The graphene coated fabric will provide an additional solution to this industry.'
Versarien (LON:VRS) tom winifrith’s head will explode this morning over this .
Anyone thinking of buying this or Catenae Innovation (LON:CTEA) would be wise to google his comments, he’s marmite of course but when he’s on a fraud/blatant ramp hunt its worth being cautious.
Interesting RNS from Versarien (LON:VRS) . They have a very generous loan of £5m from the government and at the same time have pulled the plug on their chinese joint venture mumbling about protecting their IP. Looks like the gov is expecting them to make graphene in this country, which would be good if they could find someone to sell it to. (disc: bought a few shares as a flutter.)
My morning smallcap tweet: Versarien pulls rabbit from hat to offset bad news.
Versarien (LON:VRS) Kier (LON:KIE) Cello Health (LON:CLL) Wameja (LON:WJA) Malvern International (LON:MLVN) £Beiji Benchmark Holdings (LON:BMK) Catenae Innovation (LON:CTEA) DP Aircraft I (LON:DPA) WANdisco (LON:WAND) VR Education Holdings (LON:VRE) Topps Tiles (LON:TPT) OptiBiotix Health (LON:OPTI) Bioventix (LON:BVXP) Lookers (LON:LOOK) Richland Resources (LON:RLD)
Versarien (VRS) gets £5m Innovate UK loan to significantly increase its manufacture of quality assured graphene. From almost nothing! Aslo, as cynics predicted, Young-Graphene Technology Co fails to cough up for its 50% of JV. VRS buys share for nominal sum. Delays FY accounts to 11 Aug. Neill Ricketts says "We remain well placed in China and the triggering of the backstop arrangement with YG has not fundamentally altered our strategy". Ha, ha.
Kier (KIE) recent Q trading 'resilient' with c.80% of sites remaining open. Almost all sites are now open. Agrees covenant waivers.
Cello Health (CLL) rec cash offer of 161p, a 44% premium.
Wameja (WJA) Mastercard provides €15m Loan Facility to HomeSend to fund pre-payment timing gaps.
Malvern (MLVN) resumes trading on AIM.
VRS also, as cynics predicted, Young-Graphene (Beijing) Technology Co fails to cough up for it's 50% of JV. VRS buys share for nominal sum. Delays FY accounts to 11 Aug. Neill Ricketts says "We remain well placed in China and the triggering of the backstop arrangement with YG has not fundamentally altered our strategy". Super.
Benchmark (BMK) sells veterinary and diagnostic services business FishVet for c £14.5m.
Catenae Innovation (CTEA) covid tracing App ready to be rolled out across the UK and globally, well ahead of schedule. We are receiving enquiries about the app and are in discussions about local and international sales opportunities. I doubt this tinpot has stolen a march on UK Gov't, however easy that may appear.
DP Aircraft (DPA) bust airline Thai Airways will make only interest payments until Sept.
WANdisco (WAND) initial deal worth up to $1m with a major British supermarket. Also strong uptake for Azure Cloud product.
VR Educatio (VRE) MOU with Virtual College, an industry-leading digital learning solutions provider, to provide and deliver technology enhanced learning solutions in the UK and Middle East.
Topps Tiles (TPT) recent week sales £3.9m, down only 5.4% YoY. Does £18.1m sale and leaseback.
OptiBiotix Health (OPTI) non-exclusive distribution agreement with Actial Farmaceutica for distribution of CholBiome and CholBiome-X3 in four new territories in the Asia Pacific.
Bioventix (BVXP) finds a CFO to replace non-board accounts person. I hold.
Lookers (LOOK) suspended due to late finals.
Richland Resources (RLD) cash shell suspended as it fails to make acquisition. Now in late-stage discussions for an RTO.
Thanks Mr C. Cello Health was on my watch list because it has had a consistently high stock rank. But I never managed to figure out how health care marketing worked, so I never pulled the trigger. One more example of me trying to understand the fundamentals, looks like I should have just blindly trusted the stock ranks (again!).
@Paul - great work yesterday. I'd be interested in MS International Ms International (LON:MSI) if you have time.
Wandisco (LON:WAND) - at last what seems like meaningful news - I wonder which supermarket ((employing 400,000 - Tesco?) thay have onboard now..?
To add to the general praise - yes, great report yesterday. Dunno how you do it day after day.
James Latham (LON:LTHM) reporting today, excellent results as far as I can tell. Carmensfella pointed me at these years ago and they continue to grind away, producing value.
Outside of that I'm scratching my head over a couple of things. Yesterday the BoE's Andy Haldane - one of the few economists worth listening to, in my view - suggested that the recovery was "so far, so V" - the forward indicators suggest a V shaped recovery. At the same time he warned over unemployment soaring. Today SSP (LON:SSPG) have announced that they're looking at 5,000 redundancies in the UK. I'm left wondering what a recovery that's accompanied by mass unemployment will look like?
On another, not small cap note (sorry Paul) I also thought the J Sainsbury (LON:SBRY) statement was interesting. They're excellent - grocery sales up 10%, digital has doubled. And yet, and yet - profits will be flat because of the Covid-19 mitigation measures, and then only because of business tax relief. I wonder if this reads across to other retail and leisure stocks many of which, I assume, won't see the same kind of revenue boosts. So extra costs, lower footfall, lower revenues = significantly lower profits?
The last crisis seemed like playing poker in the dark, this one feels like three dimensional chess.
timarr
I was a little confused by Haldane's messaging; that we are on track for a v-shaped recovery, but that could all be stymied by mass unemployment. Surely levels of employment are a driver of recovery not a symptom?
To add a miniscule data point, my family owns a number of restaurants up and down the north east coast. The average reduction in seats across the restaurants is 33%, with extra staff required for cleaning and registering customers names and addresses. They've done a test opening without the public in one restaurant and concluded the kitchen would likely need some kind of air conditioning installed to make food prep in PPE bearable for staff.
It's increasingly looking like the only way to not lose money over the next 12 months is to keep staff on furlough to the last possible moment, then shutter the restaurants that can't be ret-conned into takeaway only, to reopen again at the start of the 2021 summer season. This from a company that is almost entirely freehold sites.
Even if open, with 1 metre distancing, I can see a good chunk of the restaurant trade going under. The margins are thin enough as is.
Read across into pubs, leisure, and retail, and I just can't see Haldane's 'V' anywhere.
Hi IML
I was a little confused by Haldane's messaging; that we are on track for a v-shaped recovery, but that could all be stymied by mass unemployment. Surely levels of employment are a driver of recovery not a symptom?
Generally it's a bit more complicated than that. Rising unemployment is the thing that really hurts the economy - people are unwilling to spend because they're worried they'll lose their jobs. That usually feeds straight through into big ticket purchases like houses, big holidays, cars, furniture, etc. When unemployment stops and everyone feels more confident rising people start spending again.
Trouble is here I'd have thought we're looking at rising unemployment for the rest of this year which, accompanied by the general unertainty around the economic shock, is likely to drive a recession. I don't see how Boris's New Deal can feed through quickly enough to stop that - but if it works then I guess we'd see a recovery pretty early next year, Covid permitting.
That scuttlebutt on your family restaurants is fascinating - although I imagine less interesting and more worrying for your family. Can't help thinking that world will look different when we move into recovery. The Redrow (LON:RDW) update yesterday was another sign as they ditch London projects in favour of houses in the suburbs to meet demand for larger properties with gardens.
I'm still hopeful that the world will be a better place at the end of this, but it's a hell of a way to get there.
timarr
Timarr- To be honest my family is probably one of the better placed around. My dad has always been extremely conservative with cash reserves etc after a restaurant fire 30-odd years ago nearly took him out of the business altogether. They could conceivable shutter for a multi-year period, pay down the relevant taxes on the freehold sites, dispose of the other leases, and spring open post-COVID. It would hurt, but it wouldn't be fatal.
They are definitely an outlier in this respect. Even some nationally feted restaurants around the North-East are going to be in dire straits.
Interesting discussion. Some estimates are that over-capacity in restaurants could be as much as 40%. That's been known for a while. What intrigues me, is that bars/restaurants/retailers that can survive, and adapt (online/takeaway/outside spaces), could end up with a nice opportunity to grab market share from greatly reduced competition. This could also be positive for margins, because there would be less need to discount prices, if scarce capacity is booked up by customers in advance. We could even end up with a completely changed dynamic, where it becomes difficult to find a table in a restaurant, and prices go up?
Although once covid is defeated, then social distancing wouldn't be needed any more, and things probably go back to normal. All those empty restaurant & bars that went bust in the covid crisis, are then let out again to new operators, on low rents, and capacity returns.
So I do think we need to look beyond the current situation. The longer term always sorts itself out, after every crisis of every kind.
Another minor data point from the two businesses in which I still own a substantial interest. Both are customer-facing and long-established. One re-opened on 15 June and the other will re-open on Saturday 4 July. It seems to me from the experience so far and the projections we feel able to make that both these businesses will survive but sales will be reduced and costs are higher to achieve the required standards. Therefore there will be no returns for the investors, none at all, for the foreseeable future. This seems to replicate IncredibleMosesLeroy's family's report.
From an investment point of view and with the benefit of 50 years' experience in the property game I think there will be some bargains around. For what it's worth I think that a lot of retail property is worth about a quarter of what it was, the reduction in value made up mostly by reduced rents and the rest by reduced multipliers. So for example a shop that had an FRV of £50k p.a. on an FRI institutional lease might have had a CV of £1MM (5% yield). The same shop might now have an FRV of £20k on a ten year lease with monthly rental payments and an annual option to break, and a CV of £250k (8% yield). That sort of thing. We haven't got there yet and most commercial surveyors will disagree with me but I think that's where we are heading. A few months of paying UBR and insurance on empty properties, which gradually become fly-blown and vandalised, will make landlords think. I hate this, I had hundreds of thousands tied up in commercial property, and it's going to happen to me. But any retail/hospitality business that is clever enough to find a method of operating that is break-even in the short term could lock in some very low rents or even buy some nice freeholds at very low prices. Those are the investments to look for at the moment.
"Surely levels of employment are a driver of recovery not a symptom?"
"Rising unemployment is the thing that really hurts the economy"
Actually, even changes in employment are still a symptom, not a driver of the recovery.
The chart below is US data but it's the same pattern as the UK. Note how the unemployment rate continues to rise after the recession is over.
The above is the unemployment rate. The same is true if you look at the total unemployed people.
In simplified terms, what changes at the end of the recession is that the number of newly unemployed people starts to go down each week. Then there is a lag as the number of new jobs being created starts to increase. In this phase, businesses have stopped firing people, but aren't confident enough to create new jobs. Unemployment will carry on increasing until the new jobs being created exceed the newly unemployed.
It's V shaped but the right hand upstroke is shorter than the left hand upstroke :-)
Thanks IncredibleMoses Leroy for your comments on a possible strategy being considered by your family's restaurants, this was very interesting. Strategic reviews must be going on across the leisure sector as companies seek to respond to the phasing out of the furlough scheme as reality hits home. I just had an email from "Steam Dreams" (which runs steam engine drawn trains with meals on board) asking a range of questions to customers to determine what COVID-19 induced changes would be acceptable or unacceptable to people considering future bookings. They proposed that future passengers should sign a statement saying that they had no symptoms of COVID-19, nor had any contact with any infected individuals before they would be allowed to travel. They also asked whether passengers planned to go ahead with their existing bookings which I refused to answer as this could be interpreted as a cancellation which would void any rights to a full money back. Incidentally, I am still waiting for a refund of a cruise booking with Carnival which Carnival said would be with us two weeks ago. Carnival has refunded just 50% of the amount owed which suggests to me they are in a desperate position and I note in the media that they are selling ships. I am now taking legal action against the travel agent in order to obtain the outstanding money owed as the payment for the cruise was made to the agent, so they have a legal obligation to provide the refund. I imagine many travel agents will pick up the tab in this way if operators go bankrupt or refuse refunds and I guess this will include where foreign hotels go bust. I wonder if OnTheBeach is exposed to this problem or whether their customers pay direct to the hotels booked?
LOL as long as you get your money back... Legal obligations blah, blah, blah. On the one hand I don't blame you, on the other hand individuals demanding money back ultimately ends up with firms going bust and people without a job. Don't know what the right answer is but not sure this is it.
I imagine many travel agents will pick up the tab in this way if operators go bankrupt or refuse refunds and I guess this will include where foreign hotels go bust. I wonder if OnTheBeach is exposed to this problem or whether their customers pay direct to the hotels booked?
It's complicated and depends on the way the contracts are structured. However, if you booked with a card then the ultimate recourse is to your card issuer who is obliged to refund you. I won't go into the technical complexties but the issuer will then seek reimbursement from the operator's bank.
If you try and get a refund and they refuse to play ball I'd go to your bank pdq - just make sure you have some written evidence that you've tried to get a refund and then refuse to go away until the bank actually does something (they'll often try and fob you off back to the operator, but will eventually give in).
The whole travel industry model is broken - the reason refunds are so hard to get is that the operators have already spent the cash on stuff like fuel, hotel rooms, etc. They simply don't have the money to pay everyone back and, for the time being, regulators are turning a blind eye rather than forcing the issue and seeing lots of companies go bust. I have some sympathy, but it does make most of the sector univestable. What's the point of a safety net that only works when you don't need it?
I do, however, hold On The Beach (LON:OTB) - and as they make clear in their various filings their model sees them hold most customer cash in escrow rather than forward paying it to airlines and hotels:
The Group remains the only listed UK travel business that operates a fully ring-fenced customer trust account in which customer funds are held until the point of travel. Therefore, the Group does not rely on cash received for forward bookings to trade. Monies that have been received for holidays that are cancelled by a closure of airspace can be repaid to customers in cash with limited impact on the Group's working capital.
(From the recent interims).
This makes them a survivor come what may and if you believe that the industry will eventually limp back towards some sort of normality then they're about as good as you can get. Put it this way - if I was so inclined to go on holiday overseas then they'd be my first choice.
There are other reasons for liking On The Beach (LON:OTB) - the low capital costs associated with running a largely online business and their ability to rapidly flex their discretionary costs. For instance, they stopped advertising as soon as they realised no one could travel. This means they have an innate advantage over a lot of competitors, quite a few of whom will go under.
The whole online travel agency (OTA) market is fascinating - it includes the likes of Expedia, Booking,com, etc - and can get quite fractious when it comes to reselling airline tickets (although I reckon the airlines will take any business from any source when things reopen). But OTB have carved out a niche and established brand recognition - and they don't don't have a cohort of highly p'd off customers seeking refunds who'll never use them again.
I mean - what's not to like? Well, other than the fact that no one can fly anywhere at the moment ... :-)
timarr
Great post Timarr. Don't always agree with them but usually well crafted and insightful. OTB does appear to have the hallmarks of being a beneficiary from the huge dislocation taking place within the travel industry. My only worry with stopping of all advertising is dilution of brand awareness that had started to build and how quickly this can be recaptured. It was still a relative newcomer to the market and there will still be some big well funded players whose misdemeanours will soon be forgotten.
As an investor in OTB, it is unusual because monies from clients goes into what is effectively a 'Trust Account' which is operate from the OTB business account, but which OTB administrate. They then release the funds from this to the airlines, hotels etc. at set dates. This should mean that the money in the 'Trust Account' is there for refunding rather than has been used elsewhere in the the business.
It's why OTB's turnover is so small - £100+m last year - given the number of hols it sells and, compared with other companies, its operating margin is so good i.e. because a lot of the money it takes never actually goes through OTBs accounts.
I agree. There is no V shaped recovery possible and I can't see the evidence of what he is talking about. Unless he's talking about share prices which have been 100% artificially enhanced by central banks. The only V I can see is virus cases going down and back up again in the US. This cannot end well and in my view shares will be below the March lows within 2 years, maybe much less. The virus is one part but the bigger picture is indebted governments, currency creation, indebted businesses (and ever inflating p/e ratios!) and individuals which is a bubble waiting to burst in my opinion. The virus has just been the catalyst to this bursting. I expect in the short term a lot of pain including mass unemployment and property prices falling which then lends itself to a loss of confidence etc. It's not good but I make no apology for a country and businesses not living within their means. As for MMT, well let's not go there!
Lee Brown
I agree. There is no V shaped recovery possible and I can't see the evidence of what he is talking about. Unless he's talking about share prices which have been 100% artificially enhanced by central banks. The only V I can see is virus cases going down and back up again in the US.
I am probably in the minority here but i am of the thinking we will have a V shaped recovery of some sorts - we are probably playing with shapes though as to me although it will look more like a V than anything else it will likely be a stunted V in that we don't get fully back to the starting point of the V quickly. We should recover at least 80-90% of what we lost though and to me thats gonna be closer to a V than anything else so i am sticking to this letter. Athough what happens after that shape wise i don't have the foreseight of Hari Seldon undfortunately (omg foundation the tv arrrives in 2021 - i thought 60 year wait for I Robot the movie was too long - its been 70 years wait for this bad boy ! )
Here is an example of why i think V is the most suitable term (stunted V?) - if we look at James Latham update today they are already showing great bounceback from the bottom - however you look at the numbers below though its reaonably clear that the lfl figures this time next year will be much closer to the 100% pre covid starting point than any of the numbers listed below so that meets "my" definition of V - albeit probaly a stunted one. I am kid of presuming here there is no material lockdown 2 on the scale of lockdown 1 - i will deffo be wrong if we do have material lockdown 2.
April was a particularly challenging month with sales at 40% of April 2019 sales. We have seen more customers coming back to work throughout May, with positive trends on numbers of orders taken and total number of trading customers, with sales at 60% of May 2019 sales. This positive trend is continuing in June, and sales are expected to be 80% of June 2019 sales.
Having worked in finance at J Sainsbury (LON:SBRY) (many light years ago), and subsequently had a great interest in the food retail sector, I can tell you they (& their rivals) will be very keen not to be seeing to be profiting from the Covid-19 pandemic, and the misery it has caused to UK citizens. I strongly suspect that their reported bottom line performance in the last quarter or so will be heavily influenced by bulky provisioning - adding to their 'rainy day' funds. On past form it is reasonable to assume any pain suffered in their supply chain will primarily be borne by their suppliers.
Hmmmmm......Everything in my ASDA appears to have gone up and all special offers have been removed. One example I can remember, 9 pack of Toilet rolls, complete with fluffy dog £4.50, now over 5 pound.
My shopping bill certainly is higher, or maybe that's because there nothing else to do.
I would say there are certainly looking at maximising their take during this time.
Re Paul's undoubted Quality AND Quantity - Yesterday was 4,688 Words !
I was a little surprised by the Bioventix (LON:BVXP) announcement this morning "Appointment of CFO". I looked back at the news feeds and don't see any prior announcement of an incumbent leaving. Could it be that they never had one before? Does anybody know who was performing this function before or if it would be normal for a £200m market cap company not to have an FD? I'd be interested to know if our knowledgable crowd here believe that anything might be inferred from this new appointment in terms of the future direction of travel perhaps?
Morning johnsmith68 - Their own website says they have an FD - Ms Treena Turner FCA who appears to be a partner in a local Accountants Practice - NO mention of a CFO
[removed - Q already answered]
Bioventix (LON:BVXP) - as has already been highlighted the role seemed to have been performed by an accountant at a local practice. Evidently, a part time role.
The appointee seems over-qualified for what seems, in accounting terms, a quite undemanding position unlikely to require F/T attention. And as you infer - is the FD still in post?
But one thing that has struck me here is that a lot of revenue is self reported by customers and there has been under-reporting of these revenues in the past - maybe this is something that the company thinks needs more attention.
I agree on that self reporting point. The Bioventix CEO Peter Harrison strikes me as a totally trustworthy person who takes it for granted that other people are also honest. I prefer a trust and verify approach and would welcome the new man doing an audit or two at their customers.
Paul. Your excellent SCVRs over the past year or so that I have been a subscriber to this site are alone well worth the subscription price. Your SCVRs are invaluable to a private investor like me who definitely does not have an accountancy background. So your in-depth write-ups on companies certainly help me in deciding which companies to have on my watchlist and which one to keep well away from. Paul - keep up the excellent work - it really is appreciated not only by me, but i'm sure by everyone here.
I second this. I've learned more from Paul's missives than any other single source on equities. Even yesterday threw up this gem:
"Excessive receivables can be a precursor to accounting problems, in my experience, so I watch this area carefully"
Check receivables turn into cash. Seems obvious but I never thought of that.
Thanks Rebirth!
When people shower me with praise, I brace myself for the sting in the tail, but there wasn't one with your comment, so thank you! :-)
Obviously both Graham and I get some shares right, and some wrong. We cannot predict the future, but we certainly try to flag up good & bad points about all companies we cover, and then leave it up to readers to absorb all that, and come to your own conclusions.
Also, I really like it when readers point out things that we may have missed, that's really helpful, as to cover 500+ companies, we obviously can't spot everything.
Best wishes, Paul.
Agreed, I like to think of the SCVR as an insurance policy to educate yourself and protect the downside. I for one have definitely avoided many losses from what I have learnt on here.
I have to take issue with you Mr Gromley on behalf of the BoD of £SCVR .
We were specifically advised by our Nomad and IR not to mention numbers as muddying the waters is well know to be the "best practice" expected in the City.
Anyway the FD (self-isolating) and the Nomad's intern (virtual lecture for his degree) are the only people that understand these number thingies.
Hope this clears up the matter to your satisfaction and hope you have the good grace to formally apologise in the pages of a well known broadsheet.
"here's the link to yesterday's SCVR, which significantly exceeded market expectations"
I guess that is somewhat better than "materially exceeded"? But without telling us what the market expectation was that's not a vastly useful comment, I really wish pundits would adopt best practise and give us a clear view of what the original expectations were. TSk TSK.
;-)
(I thought it was a great effort anyway)
Ha ha!
Evening Paul any chance you can take a look at Rbg Holdings (LON:RBGP) (RBG Holdings) at some point in near future? Law firm, recently bought an M&A firm in Manchester for diversification, low overheads as uses solicitor contractors, is in the top 5 UK law firms, outstanding value in comparison to them.
Very interesting company...