Small Cap Value Report (Weds 12 Dec 2018) - SDRY, FTC, DPP, FUL

Good morning, it's Paul here.
What fresh horrors has the market served up for us today? It looks like at least 3 profit warnings, judging from the top % fallers list, so I'll start with them.
Superdry (LON:SDRY)
Share price: 380p (down 33.7% today, at 09:10)
No. shares: 82.0m
Market cap: £311.6m
Interim results for the 26 weeks ended 27 Oct 2018.
Good grief, I didn't expect this fashion brand to come back within my small cap remit again - its market cap was over £1.6bn at the start of this year, and is now just over £300m. I know this share is popular with private investors, so my commiserations to any readers who are holding this one.
The share price is all over the place, it's up 22p to 402p just in the time I wrote the above.
I reported on the profit warning in Oct 2018 here, fearing that it had another profit warning to come.
Note that Superdry has a profit seasonality leaning towards H2. So the H1 numbers need to be seen in that context.
The highlights today look grim, with profit down by almost half;
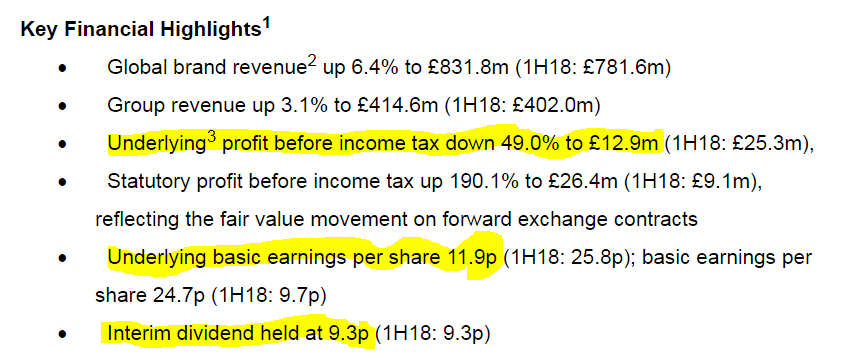
Although it's interesting to see that the dividend has been held.
Current trading & outlook
Unseasonably warm weather has continued through November and into December (Superdry's two biggest trading months in the year) across all of our key markets. Given Superdry's reliance on cold weather related product continues and a lack of innovation in some of its core categories, sales have remained under pressure despite a strong performance in the Black Friday week. This has resulted in an adverse profit impact of around £11m in November and the Company expects a potentially similar profit impact in December if trading conditions do not improve.
There is still considerable uncertainty in terms of the weather outlook, the changing shape of consumer behaviour in the peak trading period and the impact of wider economic and political uncertainty. Reflecting those impacts and the uncertainty in the remainder of the financial year the Company expects underlying profit before tax to be in the range of £55m to £70m.
It's very helpful when companies give specific profit guidance like this. My initial reaction is that the market cap of c.£300m looks a bargain if the company is still on track to report £55-70m underlying profit, in a bad year, when plenty of things seem to have gone wrong. That compares unfavourably with £97.0m underlying profit last year (ending 28 Apr 2018).
I suppose the market's worry is that the trajectory of profits is now downwards. So next year could be profits down to c.£30m, and then breakeven or a loss the following year, if this trajectory continues.
The other question is whether current management will be chucked out by the founders? There has already been a public spat where founders (big shareholders still) have slated the strategy of current management. That could give the share price a nice boost, potentially, on hopes for a turnaround, maybe?
The narrative with today's results talks about improving its product. That's the fundamental problem it seems, with weather exacerbating it - the company has mentioned before that it relies heavily on sales of winter coats. Although does the public really need to buy a new coat every winter? I'm still wearing an old £8 gilet from Primark, and it does a perfectly satisfactory job.
Another worry with Superdry is whether the company has signed up for too many expensive shop leases? It seems to like expensive, flagship style shops, in pricey locations. That could become a millstone as High Street footfall continues to decline.
Balance sheet - looks pretty solid to me, which strengthens the case for having a punt on this share, in the hope of a trading recovery next year.
There doesn't seem to be any bank debt. It held net cash of £19.2m at end Oct 2018, down from £33.8m a year earlier. This looks to be a seasonal low for cash, with inventories turning into cash over Nov, Dec & Jan, giving historically higher cash balances at the year end in April.
Inventories & receivables look rather high to me. So I imagine the company will have to discount its winter stock, to clear it - giving a double whammy of lower sales, and lower gross margin.
It does have to dip into its overdraft a little from time to time;
During the period the Group increased its uncommitted bank facility from £20m to £40m. This will reduce back to £20m in the second half of the year.
The maximum drawdown on this facility in the period was £26m.
In recognition of the continued growth of the Group's Wholesale operation and changes to inventory flows reflecting the increasingly global nature of the brand, and in planning for the longer term, the Group is in the process of arranging a revolving credit facility to accommodate peak working capital requirements, ready for year end.
I don't think there's any reason to be alarmed at this. The amounts are relatively small, compared with even the reduced level of profits. Also, there are substantial inventories & receivables, to give the bank comfort that it's not risky lending to Superdry.
Overall then, I'm happy with its financial strength.
My opinion - this looks a lot of business for the money. I'm sorely tempted to catch the falling knife, as there could be a decent % gain here from any recovery in trading, or from a change in management.
Filtronic (LON:FTC)
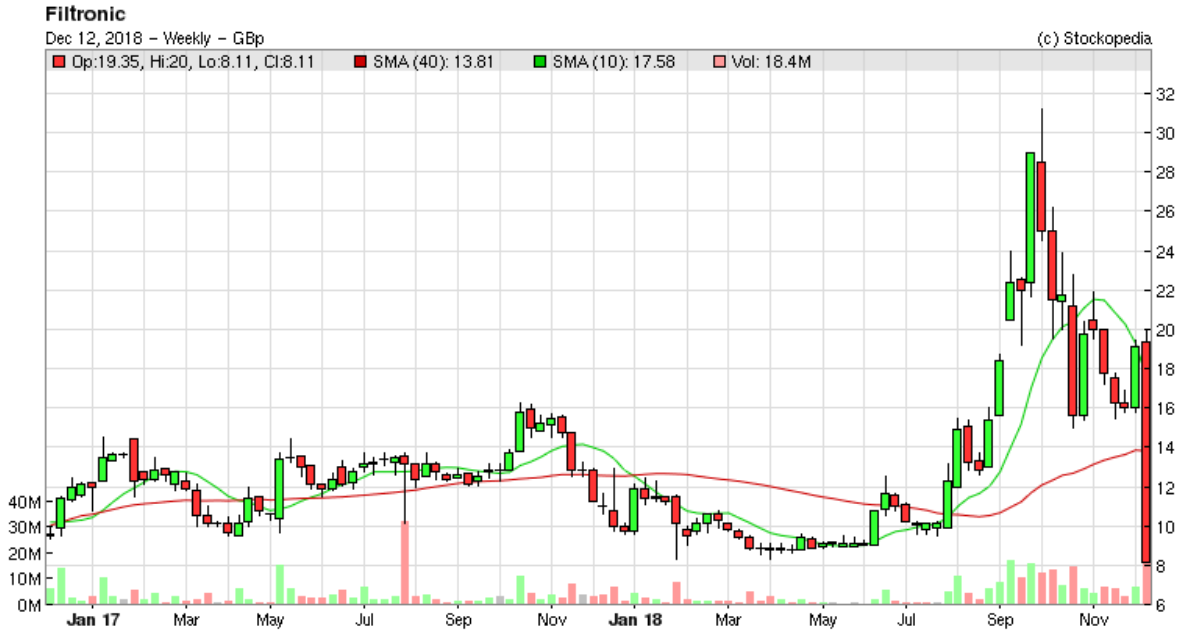
Share price: 8.2p (down 54% today, at 10:21)
No. shares: 208.1m
Market cap: £17.1m
Trading update (profit warning)
Filtronic plc (AIM: FTC), the designer and manufacturer of antennas, filters and mmWave products for the wireless telecoms and critical communications markets, provides the following trading update.
Unfortunately for shareholders, it's a profit warning for H2;
Sales in the first half of the financial year were £10.4m (H1 FY2018: £12.8m). Whilst sales were lower than the prior year we have traded ahead of our internal sales projections in the half.
However, despite good early take up, we regret to report that demand for the recently introduced Massive MIMO ("mMIMO") antennas is now expected to be substantially lower than we had forecast in the second half of FY2019 and as a result, the Company expects to be loss-making for the current financial year.
The other part of the business is trading alright.
Cash - the company says it has enough;
Net cash at 30 November 2018 was £2.3m (H1 FY2018: £3.1m). The Board is of the opinion that it has sufficient cash reserves to allow it to operate at this lower level of revenue whilst it explores and executes an alternative strategy for the antenna business.
My opinion - this company has historically disappointed, because it has so little visibility on sales, and hence profits. It needed a rescue fundraising to prevent it going bust a few years ago. £2.3m cash doesn't strike me as providing much headroom, now the company is loss-making again.
If I held this share, I'd probably just take the loss, and move on.
DP Poland (LON:DPP)
Share price: 17.0p (down 28% today)
No. shares: 152.8m
Market cap: £26.0m
DP Poland, through its wholly owned subsidiary DP Polska S.A, has the exclusive right to develop, operate and sub-franchise Domino's Pizza stores in Poland. There are currently 62 Domino's Pizza stores, 36 corporately managed, 2 under management contract and 24 sub-franchised.
- Softening of LFL sales growth in Q4 (Oct-Dec 2018)
- Increased competition from delivery aggregators
- Reduced marketing spend, to focus more on profits than sales growth
- EBITDA for 2018 expected to be broadly in line with expectations
- Sales & EBITDA for 2019 will be impacted
My opinion - this company has a terrible track record. In a nutshell, its business model simply isn't working. It's never made a profit, and costs seem to go up as fast as sales increase.
Why invest in something that has proven to be a commercial failure (i.e. constantly loss-making), over more than 8 years?
Fulham Shore (LON:FUL)
Share price: 10.75p (up 14% today)
No. shares: 571.4m
Market cap: £61.4m
(at the time of writing, I hold a long position in this share)
This is a small casual dining group, operating Franco Manca pizzerias (mainly in London), and The Real Greek.
Interim results announced today cover the 6 months ended 23 Sept 2018.
As has been widely publicised, the casual dining sector is suffering badly at the moment, due to;
- Over-capacity - too many restaurants chasing too few customers
- Heavy price discounting from struggling operators
- Reduced footfall on High Streets
- Increased costs, especially wages, business rates, etc
So there's no doubt that things are grim out there.
Against that backdrop, FUL's interims today look solid;
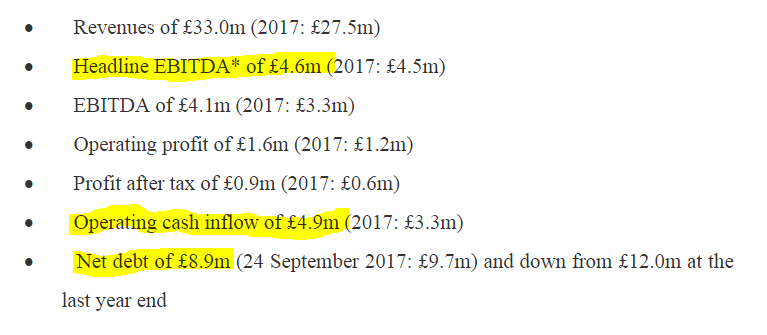
Note how EBITDA is very similar to operating cashflow. That's why it's a very useful measure in the retail & hospitality sector. Less so in other sectors (e.g. tech companies that are capitalising a ton of payroll costs).
Cashflow statement - this shows the strength of this business. The new site openings programme was slashed, due to difficult market conditions. As a result, the business is now generating plenty of cash.
Note how net debt reduced by £3.1m in the 6 months, even after having spent £1.7m on capex for new sites. I was a bit concerned previously that net debt was running a little warm. Today's figures are reassuring on that front. So I no longer see the net debt as a potential problem. It's now relatively modest, at roughly 1 times EBITDA.
So investors who focus too much on the statutory P&L figures, are missing the main point! It's all about generating cash, and recycling that into new sites. This is a self-funding roll-out, one of my favourite type of investments.
New sites - retail or hospitality companies which have a successful & differentiated offering, can do tremendously well by expanding at times like this, by negotiating fantastic deals with desperate landlords. This is confirmed by FUL today;
We continue to look for well-located new sites at reasonable rents throughout the UK, for both Franco Manca and The Real Greek. The increasing availability of restaurant space, lease incentives and capital contributions, in the current climate, should enable us to achieve higher site returns on capital than we have previously recorded.
We are conscious that the longer we wait on a new site or location, the greater the choice of sites, and potentially the better the incentives from landlords.
We believe that our two brands are now firmly established; we can afford to grow at a measured pace.
What a difference between canny management here, waiting for great deals to fall into their laps, and the PE-fuelled mania of restaurant openings which is now going so badly wrong for many competitors.
In the bad times, the best businesses can actually flourish. Hence why I hold this share personally, as it seems clear to me that both Franco Manca and The Real Greek are excellent formats, which are attractive to customers.
Outlook comments are positive. The most important bit is this, indicating that the (previously paused) roll-out plans are being stoked up again - excellent news;
During the current financial year to date we have seen sales and profit growth, improved operating cash flow, and reduced debt exposure for the Group. These factors, together with our successful new opening so far this year, have led us to consider increasing our opening programme beyond the current financial year, subject to how political events in the UK develop.
In the financial year ending March 2020 ("FY2020"), we plan to open more restaurants than the current financial year. We have to date exchanged contracts for a new Franco Manca in Edinburgh to open in FY2020 and have a number of further locations in advanced legal negotiations with landlords.
My opinion - it's pleasing to have one glimmer of light in my otherwise fairly battered portfolio!
It's clear to me that FUL is going to be a long-term success story. Today's reassuring results make me happy to continue holding, and will probably increase my position size here when funds permit, especially if that coincides with a dip in price. 9p feels the right sort of level to be buying more, in my opinion.
The widespread availability of good sites, at low rents, make this the perfect time to be expanding a successful restaurant format. That should sow the seeds for a much bigger, and more profitable business in say 5+ years' time. Meanwhile, weaker competitors fall by the wayside, leaving more market share for the restaurant formats that the public prefer. Therefore the dismal outlook for the sector as a whole, creates opportunities. That's the creative destruction of capitalism at work.
I'll leave it there for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
One of the main problems that i see for Superdry are their store size in the UK they are generally to large and they have learnt by this mistake and its going to be corrected as their leases come up for review and their growth comes more from overseas and via Wholesale, Ecommerce and at a lower level from their owned stores.
Its clear that currently they have problems but there is nothing that can't be improved so i still see great future potential...but clearly others will have a different view and if they are buyers or sellers their views will be reflected in the share price.
May I point you all to the company presentations at https://corporate.superdry.com/investors/results-and-presentations/ , in particular yesterday's presentation at https://corporate.superdry.com/media/2545/fy19-interim-results.pdf
To me some of the presentation appears to be straight out of MBA school eg 'brand development', 'fundamental product repositioning', 'transformation programme', 'cost review'.
Looking at some of the product comments (eg 'Wincheater - legacy products kept in range for too long' on slide 18 yesterday) I wonder if management has alienated the core franchise and is also missing the differentation / brand values of the co. --- ie the Windcheater was and still is a differentiated product in terms of price point and availability. Some of the new products (eg the 'Jared' on the same slide) appears to me to be more appealing to 'chavs' (apologies for stereotyping) and may actually alienate the core clientele.
Management also seems to be focused on short term sales rather than the lifetime value of the sale - eg on slide 23 --- I would suggest as an investor that a lot of those products (eg the 'limited edition' or the 'fresh colour palette' hoodie) may be a one season product and you risk end of season stock issues.
The move into snow / sport appears to me to be a rationale move into an 'adjoining adjacency'. However I am 'bemused' that a management that is claiming the 'wrong kind of weather' is increasing its winter snow bet!
I have some concerns that the wholesale strategy may be cannabalising the owned stores.
On slide 35 the management discuss Far East sourcing. This reeks to me of a management that lacks clothing expertise. Both Boohoo and Zara have built their model on 'fast fashion' based on nearshoring - as the flexibility more than offsets the cost advantage. (Compare the performance of Zara and H&M vs M&S).
Slide 40 - the jacket the model is wearing is interesting. One of the key differentiations of SuperDry is the triple zips....so if you lose them what is your differentiation. Also after the discussion in the slides re reducing the logos it is interesting to note that the jacket has logos - just in different places.
Despite all the above though it seems to me that the discount to tangible book value makes this an interesting stock.
The comment about Brexit and SuperDry is interesting because of the disconnect it implies. I believe that (to simplify) the young voted to remain whilst the old voted to leave. Hence if anything the founder's donation would enhance the brand value of SuperDry with its core market.
I think a more fundamental question is whether 'professional management' enhances a business when it takes over from a founder or not. We can argue about asset turnover and capital ratios - but fundamentally a brand needs to connect with its consumers. I would argue that a variety of businesses have suffered the 'benefits' of professional managers over time.
Is SuperDry broken? I would disagree. Rather it may be a misunderstanding by new management that it was a seasonal business - whilst spreadsheets and investors demand a stable business with certainity.
The focus on shrinking SKUs _might_ be justified. However part of the management presentations appear to benchmark the SKUs vs other retailers. This in itself seems to me to be part of the problem. Are you trying to be as mundane as competitors or different?
Why are they not benchmarking to Inditex (Zara) or BooHoo? The latter is particularly pertinent given that the new SuperDry management wants to be a 'digital first' company.
This brings us to the nub of the issue - is there a problem with SuperDry or is there a problem with the management? In particular I am wondering if the CEO's background (Co-op, Kingfisher (/Screwfix / B&Q), Matalan, Boots and Dixons is entirely relevant and pertinent).
A quick comment on Superdry (LON:SDRY).
If it’s just the weather, how come Canada Goose $GOOS are doing so well ? Their main products are ridiculously expensive and warm down filled jackets for anyone that doesn’t know. Quite different quality to paul’s Primarni puffer!
The answer is fashion and fad. Superdry (LON:SDRY) is now naff. I’m a dad and quite like their products which says it all !
Once you lose the ‘cool’ factor, it’s not easy to get your mojo back.
My worry would be that this could be the next Crocs $CROX .
Don’t catch a falling knife. Wait until the chart bottoms and profit turns a corner before getting in.
You may miss out on some of the early gains but this can still go a lot lower first with continued selling pressure and large overhead resistance.
Hi Nicobos, Did you watch the video?
Your right its about Crocs they only sold Crocs! Superdry's existing performance is about their existing range, the weather an the economic conditions that we have their future is nothing to do with any of these factors...and if you are a dad wearing Superdry sorry you are naff.
Hi Mark,
Sorry, I don't agree with your statement:
"Superdry's existing performance is about their existing range, the weather an the economic conditions"
I think its simply that they are not a cool brand anymore. They can change the range, the weather can go positively Artic, but the 17-25 demographic won't wear the stuff (even if, or especially if, their mums want to buy it for them). I think they are now a bit undervalued, but not a long term proposition unless the brand recovers. Just my opinion (as a new holder, today, and an ex-holder, 2 years ago).
There are a few interesting points about Superdry but most of them are dated and reflect on the past when the tee shirts, hoodies and parka jackets that they are famous for where designed and introduced by Julian Dunkerton & James Holder that was a fantastic start to the Superdry brand but its not the end of the story and a new team and ideas are required to move the company forward. The fastest growing categorises in fashion are ladies and children's ware and ladies buy most of the clothes for their boyfriends, husbands and kids so they are the most important people that Superdry need to impress and influence along with the next generation of kids coming through. Remember most guys will wear a tee shirt until its falling off their backs and a parka jacket for even longer (just like Paul) but that is not the same for the ladies and certainly not their kids because they grow out of their clothes every year! I think that Superdry is in better hands now that Julian Dunkerton has moved on.
I am just an humble investor who has purchased Superdry shares yesterday and twice today (and if they go down again i will buy tomorrow as well) my guess is that there is a very long way to go for this super brand but of course i do hope there are a few people out there who also see it my way. if you would like to know more about Superdry check out their website and the Supergroup corporate website, there is a great presentation video added today.
You only need to watch the first 60 mins to understand where the business is going, not a lot of time if you are thinking about investing in this company (I would not bother with the last 30 mins of question time just make up your own mind).
I just got a email from Superdry offering 20% off everything with the code XMAS. Looks like they have stock they need to shift.
I cannot find Paul's Report on Photo Me.
I would be very interested in your opinion Paul.
Last time I was in a London Franco Manca it was full of the real Italians and my gf and I both enjoyed the good-value vegan pizza. It filled up as the evening went on. I hold... should have bought more! :-)
One of the issues with Superdry appears to be the weather (first sentence in the prose of the RNS today and last page of the presentation). The following suggests the weather is about to turn - https://www.express.co.uk/news/weather/1057730/BBC-Weather-forecast-UK-snow-Met-Office-snow-warning-BBC-Carol-Kirkwood
I am wondering if that will impact Superdry sales?
Secondly it is worth noting that the stock is now trading at a discount to its tangible book value - this might entice some value investors.
Thirdly I think I need a stiff gin to wipe out my vision of Paul after reading:
' Although does the public really need to buy a new coat every winter? I'm still wearing an old £8 gilet from Primark, and it does a perfectly satisfactory job.'
Re Superdry
I'd suspect that it's more than just Weather. There's a political angle as well.
"Brexit vote campaign gets £1m from Superdry co-founder"
One of the co-founders of the fashion label Superdry has donated £1m to the campaign for another EU referendum. Multi-millionaire Julian Dunkerton said he was backing the People's Vote campaign because "we have a genuine chance to turn this around
https://www.bbc.co.uk/news/uk-politics-45235655
Not going to win you many friends in that population segment that voted predominantly LEAVE
Contrast that to Wetherspoons. TM has done pretty well out of Brexit over last couple of years. He backed Leave.
And I for one go out of my way to hit a Spoons if there is a choice of pubs where I happen to be.
Suspect I am not the only one changing my spending habits over Brexit.
I think given the vote was close to 50/50 you will have proponents from each side that would cancel anything like that out. Anecdotally many of my friends and I used to spend quite a bit of money in Spoons, but most now actively avoid their pubs due to the owner's stance and overbearing political messaging on beer mats etc. Admittedly they were never a choice destination before that.
Also from a cynical stance the 18-30 demographic which spends the most on clothing was heavily remain voting, so could actually be a PR stunt to boost sales!
The 18-30 demographic was heavily Not voting, so you'd think they didn't give a monkeys either way (unless the next referendum is held on an island or jungle....) but as everyone has said the brand is now with the more "gammon" of purchasers, then the pro-EU aspect is likely to have deterred exactly the wrong people here.
but I think Dunkerton is right (not on the ref, obviously) in that current management are just not doing things right. Simple as that.
The 18-30 demographic was heavily Not voting, so you'd think they didn't give a monkeys either way
The post-referendum analysis now suggests 64% of registered under 24's voted and 75% of those voted Remain. That's in contrast to the initial analysis that suggested only a third of young people voted.
Obviously no one's allowed to know exactly who voted or how so this is all statistical analysis - but so were the initial figures. And the updated numbers do make more sense in the context of the overall voting numbers than the original figures. It's also directly in line with the estimated youth voting figures in the last General Election.
However, given that 70% of Superdry's revenues are generated outside the UK it seems unlikely that their founder's pro-Remain proclivity has much to do with their woeful performance. More likely it's just that their clothes are crap ...
timarr
"The post-referendum analysis now suggests 64% of registered under 24's voted."
I think the key word is registered, what is the proportion of under 24s that were registered? I know before the last election they was a surge in registrations just before. Most seem to have voted Labour.
Hi Tamar,
I don't think Superdry clothes are crap (they are actually, relatively good quality (IMO). Its just that they went ex-cool a while ago and the high/repeat spending youngsters are just not buying the brand anymore.
Also the weather is just an excuse from management. The last few winters have been cold enough to buy a coat. Even if this winter was exceptionally cold, would the youths then go out and buy a Superdry coat?? Don't think so. The kids are far more fashion sensitive than temperature (or Brexit) sensitive.
I still think today was probably an over-correction and they are undervalued. I'll be watching tomorrow for a short term bounce-back to trade on (after it hits the bottom). Not a buy and hold though unless the company gets shaken up. Even then, not sure how they can recapture the Brand strength!
Yeah for me an issue is how the brand slaps SUPERDRY in big letters all over its gear. That maybe works for you when you're new n hip, but not so good when the fashion tide turns. I think it makes them particularly susceptible to the crowds following the crowds to some other next thing (esp when god forbid "parents" start to wear the stuff)
I don't have an organised view on Superdry (LON:SDRY). But lemonjar's comment resonates for me as a shopper. I always objected to the excessive labelling so never checked out their gear. Whilst the label is cool all that messy labelling drives higher margin. My casual observation is that the wearers of Superdry in UK have become increasingly naffer looking (its a bit chav at times)...and the cooler youngsters ain't wearing it. My children's wannabe 'roadman' friends wouldn't be seen dead in some Superdry. Some labels okay (particularly sport or some higher value stuff) but so is non-branded or lowly branded stuff from many outlets (Gap, Uniqlo, even Next).
Superdry makes me think of Next (LON:NXT) when I was a kid in the 80s (in Aberdeen, now I'm London so maybe there's a geographical dissonance in this comment) and Next seemed quite cool and fresh and a label you wanted. But it soon became just a better Marks and Spencer (LON:MKS) - make sense?
It strikes me that Superdry in the same transition phase from a UK perspective...but they haven't built the breadth of a Next, Gap or Uniqlo.
From UK perspective and not much expertise in the company it strikes me that Superdry may need a turnaround and brand reposition...probably to something more utilitarian like the other labels above. That reduces margin and means they are running a lot of expensive retail outlets with lower margin and a struggle to become a more volume player.
I have no insight on the bigger overseas operation. A lot depends on how separate the UK v overseas is. Travelling around Europe and Asia I see a tendency for youngster to wear stuff that is more covered in messy labelling than is the case in the UK (naff, dodgy and unscientific observation!). So perhaps its a brand more suited to overseas?
The above is as much speculation as analysis as not expert in this stock....but I've persuaded myself that I will read up a bit on the stock but with a bias that they are likely to go through more pain and reorganisation that will likely depress sentiment and price for longer. Something interesting may arise but could be a fail too.
My kids are still buying and wearing Superdry in school .....but then I teach in a Highland school among the mountains and lochs and we have still to catch up with the rest of the country.
I do not often post on Stocko ....but you seriously invest on the basis of the political views of the founder / major shareholders. I am truly glad you do not manage my money.
FTC lost its strategic direction at about the same time its core product became obsolete (about 5 years ago) and it lost out to larger players forcing it into areas with short term profits. Bad to worse, dump the shares if you have them
Surely Superdry (LON:SDRY) must be vulnerable to a takeover bid at this level? Or if Dunkerton wants to be back in charge his price to take it private just got a lot more affordable.
I’m sorely tempted to break all my rules on profit warnings and take a small punt.
What’s going on at RM2??! It’s up nearly 20,000%!
200:1 share consolidation. As boring as that I'm afraid!
Edited: unnecessary, as brballs got there before me.
If you read the RNS you will know the answer (200:1 consolidation) so not a very good question for a financial advisor to ask!
Edit - yes, brballs got there first but left up for rest of comment.
Sharw
You'll be glad to hear I own retail shops and an online business now. Financial advising and RNSs are far too boring.
I'm really not surprised by Superdry (LON:SDRY) - I have been saying for years that their products are dated and had a sweet spot around 2010 when their heavily branded T-Shirts & coats were being worn by young & trendy people (me excluded). They became very popular & successful and as a result everyone starting buying their gear including lots of middle aged men with beer guts. They are moving away from the stuff covered in brands and logos but the paradox is .... what makes them different to anything else? Don't like their products & they have tough competition from the likes of ASOS. Not a holder nor a buyer of their shares!
Much happier report today from Fulham Shore (LON:FUL) who issued interims today (up 12% at 10.6p). Revenues up 20% at £33.0m with only 2 more restaurants opened (now 59) and Headline EBITDA* of £4.6m. Bank debt starting to come down and good start to new year reported. Very experienced mgt team and founder directors in place and seem to be navigating casual dining sector issues well with skin in the game (eg Chm D Page/ MD N Mankarious both ex Pizza Express in growth days own 34%)
Even more interesting is the split between 2 key brands in the sector breakdown in the notes. The Franca Manca pizza side which first caught my attention is much bigger with 43 outlets contributing 64% of revenue. However, The Real Greek generates more headline operating profit (£1.5Mn vs £1.4Mn) from only 16 restaurants and uses far fewer assets (£8.2 vs £43.1Mn) to do so. (Accountants: am I missing something like freehold property in this as this seems to good to be true?!)
Presumably this shows the effect of less competition/need for promo discounts than in the heavily contested pizza sector. The Real Greek could be a real winner if it can be rolled out at scale over time as good, cheap lease emerge from the casual dining sector wreckage.
Personally, I still think Franca Manca will do OK long term since it is distinctive in a big pizza market (sourdough pizza, everyday-low-price, inherently low cost model - few variants, own label drinks, direct from source supply, deliberately smaller/cheaper 2y sites).
I bought to hold until national roll out is nearly complete and, frankly, am well under water on my investment for now having bought in at 17p 18monts ago before the whole casual dining sector went down. Nevertheless I remain optimistic that in 3-4 years time the investment will have come good (after sector consolidation) and would consider buying more if I didn't face a concentration risk.
EDIT - just refreshed to find the big boys are writing about FUL (ie Paul!) and nice to see (confirmation bias) has a similar opinion
This is NOT scientific:
There is a (french) site calle vente-privee that sells on clothes. You have to log in and so the prices do not appear in google.
Superdry has come up there quite frequently over the last 12m or so.
That made me think they were under pressure.
In other news, John Lobb (shoes) came up as well about a week ago. The last time I remember something like that was in 2006 I saw some mauviel pans in TK Maxx.
Like I said not scientific, but tells me that people across a lot of the income spectrum are spending less.
They do also provide a pretty good value range of ski clothing.
I am not really sure who Superdry target these days. It used to be a slightly up market casual clothing company that was worn by teens, twenties. Now wandering round you see more warn by overweight middle aged men (such as myself). I am not sure now it will ever be 'cool with the kids' again.
Isn't this what happened with French Connection a few years ago?
...and Gap before that and Benetton and American Apparel and Laura Ashley and so on. Teen fashion brands have a life, and, when they are done, nothing brings them back to their former level.
I think the advertising has always been directed at the teens/twenties, but the clothes are worn by all ages. This is nothing new, and is maybe one of the strengths of the brand.
I'm genuinely astonished that Superdry (LON:SDRY) has taken so long to instigate a change in strategy with regard to reliance on cold weather clothing. In the last few years have been getting progressively warmer, with record highs in summers and much milder winters. Yet any profit warnings or difficulties experienced in the past 3 years seem to always blame a lack of cold weather. It really makes me wonder whether management there is simply inept, climate change denying, or both...
That said, if the decline can be arrested from here, this potentially looks good value.
Morning Paul. I was wondering whether you might have a look at Bigblu Broadband (LON:BBB) if you have time. Apparently optimistic update, which doesn't mention the word profits ...!
Ricardo
Taptica International (LON:TAP) has initiated a share buyback which, given the liquidity of this share, probably puts a bottom-in for a tradeable recovery with 180p as a stop loss and a sensible interim target of 240p so good risk: reward (Assuming no other shock revelations and gap-down opens).
All these gaps are setting-upr some good R/r gap trades if you keep stakes low to manage risk
Not good news from ASOS (LON:ASC) or Superdry (LON:SDRY) but JD Sports Fashion (LON:JD.) is doing fine, so its not so much the high street at fault, but poorly executed fashion brands.
The tone in the interim statement for JD Sports Fashion (LON:JD.) back in September sounded positive, with good +ve lfl too, although they did make a brief mention of the "uniquely weather-challenged trading period" in respect of Outdoor fascias which made only £2.9m EBITDA compared to £6.5m the previous year. Admittedly this is a small part of the business.
I do have half an eye on JD Sports Fashion (LON:JD.) but I'd be tempted to wait for a trading update given how Retail is generally doing so poorly, especially when Superdry (LON:SDRY) claim that the "unseasonably warm weather has continued through November and into December" - personally, I think the last 4-5 weeks have felt just as cold as usual and I've been out and about in thick coats and a woolly hat!
Some gaps up too with Fulham Shore (LON:FUL), Huntsworth (LON:HNT), Anglesey Mining (LON:AYM)
DSC
Please forgive my ignorance, but please could you tell me what a share price gap is, and what it tells us? Or if you could point me to a source or website that explains?
Many thanks,
Ricardo
"please could you tell me what a share price gap is"
Gap down = open is lower than yesterday's low point (so a gap in the candlestick chart)
Gap up = open is higher than yesterday's high point (also a gap in the candlestick chart)
This is important to technical analysts, an area where I'm not much of an expert.
I thought it was the difference between the opening price and the closing price? Not the previous day's low or high points.
Oh, sorry! I knew I was not an expert, but clearly in saying so I still over stated my competency :)
Thanks for the correction Herbie.
It was not meant to be a correction, just my understanding and a query for the experts.
The above refers to the most common type of gaps which occur between the close of one day's trading and the open of the next. They occur owing to large imbalance between supply and demand for a share arising from a change in 1) fundamentals (from an earnings report, profit warning etc), 2) in sentiment (rumours, suspicions, impacts of other similar shares) or 3) overall market behaviour (when markets are very volatile or after a major event like 9-11). Often it is more than one of the above.
In practical terms they constitute a hole in a chart where no trades have occurred. Gaps occur in both directions of price and have different meanings.
What it tells you in the most immediate sense is that there has been a very significant change in the behaviour of the stock. The judgement comes in gauging whether the market has overreacted to the catalyst and what action you may want to take. There are also many other factors involved: very low liquidity stocks can gap regularly on news as it doesn't take many orders to disrupt the supply-demand equilibrium. It tends to be less common and more significant in high liquidity shares. Overall market volatility and sentiment also play big factors so at the moment many "investors" are nervous and are panic selling on bad news. This has a tendency to cascade and overshoot which can open opportunities (what is often called technical selling also occurs as stop-losses are hit and new liquidity enters in rapid succession).
The charts of Taptica International (LON:TAP) and Superdry (LON:SDRY) both show recent big gaps: Taptica International (LON:TAP) more on sentiment as the CEO has been forced to resign owing to fraud from a previous company: Taptica International (LON:TAP) have protested there is nothing fundamentally wrong with the company while Superdry (LON:SDRY) has some serious fundamental issues as Paul has shown.
Traders will often exploit gaps based on rules and metrics : they can be very profitable but need good risk management and discipline. Ditto with more patient investors who thoroughly understand when sentiment has become irrational. That said the market can stay irrational longer than one can satay solvent .
Many thanks for your very helpful (and much needed) explanation!
Ricardo