Small Cap Value Report (Weds 14 Sept 2022) - BPM, CHH, JOUL, BVXP, BOTB, TUNE, WINE, HRN, BIRD, ANP, TWD, RCDO

Good morning from Paul & Graham! We're having a catch up day today, so Graham's done shorter comments, and I'm carrying on probably to mid-afternoon, so watch this space! Also we're seeing some interesting reader comments, so do check that section below too, and thanks to everyone contributing. Today's report is now finished.
Agenda -
Paul's Section:
Churchill China (LON:CHH) - I have a good rummage through yesterday's interim results to 6/2022. The figures are good, and a decent outlook, with record order book. However, its end customers are under severe strain right now, so I am worried that order books could be heading for a fall. For that reason, it's difficult to justify the current valuation.
Joules (LON:JOUL) [no section below] - is going from bad to worse, with news yesterday that negotiations with Next (LON:NXT) for an equity stake to rescue it, have fallen through. It confirms the obvious, that it now needs to do an equity fundraising. I’m speechless at how badly handled this has all been.
The c.£12m market cap might be tempting for a punt, but we don’t know what the terms of the now inevitable refinancing will be. The bank has been very helpful so far, but the clock is ticking due to its Nov 2022 deadline. Dilution could be huge, given that the market cap is now so low, and the bank might require a substantial equity raise, and who would want to rescue it now? For that reason, I wouldn’t want to gamble on the outcome, and I’ll wait for a proper refinancing to be done, and a hopefully credible turnaround plan. The twin risks are of heavy dilution (which now looks almost inevitable), or an even bigger risk that it might end up being put into administration, and a pre-pack being done, wiping out existing shareholders altogether. Those grubby deals get done in private, often with no warning. Sorry again that this one has been such a disaster, it’s just been so badly run, by incompetent management. [no section below].
Best Of The Best (LON:BOTB) - an in line trading update today. Also I comment on the latest large management share selling, to strategic investor Tedi Sagi. This can be viewed two ways - disappointment at yet another big Director selling at just 400p, or excitement at a new investor bringing expertise and an international expansion strategy.
Naked Wines (LON:WINE) - plummets 33% today, due to a bearish-sounding update last night, and a recently appointed NED leaving immediately. I ponder whether WINE has become a value share yet, now that the sexy growth story looks to have unravelled. The short version is, probably not value, and I'm worried about the bloated inventories, and negative cashflow effect of the business shrinking - as seems likely now. Going concern was a "material uncertainty" with last accounts, but mgt said it has levers to pull - let's hope they are heavily leaning on those levers as we speak, as they need to be. It's now about survival, rather than growth, not a good basis for investing, in my experience.
Blackbird (LON:BIRD) - a reader request for me to look at its interim results today. Revenues tiny, at £1.5m in H1 but good growth of +78% vs H1 LY, but up less +29% vs H2 LY. EBITDA loss little changed vs H1 LY, at £637k, but favourable moves in LTIP costs have reduced the loss before tax. Underlying loss looks to be almost flat vs H1 LY, so nothing to get excited about there, in terms of underlying performance. Plenty of cash at £11.6m (and no debt), so cash not a worry, with years’ cash burn in the bank. Market cap of c.£70m is based entirely on future hope. So there’s nothing to support the price on fundamentals at present. Good luck with it!
Anpario (LON:ANP) - interim results show a big hit to gross margin, and little sales growth, but profits mostly maintained through admin cost cutting. Superb balance sheet. Wobbly outlook comments, may struggle to meet (let lone beat) 2021 results. It's looking increasingly difficult to understand why Anpario is still on a premium rating, despite the sluggish growth.
Trackwise Designs (LON:TWD) [no section below] - this has collapsed in stages, down to only 11.4p (£4m market cap). Thankfully, Graham talked me out of considering a small, speculative position in it here at end July 2022. The company needs cash, and today’s news says that the hoped-for asset backed lending has fallen through, because production orders from the main customer has been reduced. It’s negotiating with the main customer to amend its contract to provide up-front cash. TWD is also “reviewing a number of options for additional funding”. With the market cap already down to just £4m, it might be easier for someone to just buy the whole company, or let it go into administration, and buy the assets quickly & cheaply. Existing equity might well be in the last chance saloon now. What a pity, as the products sound very interesting indeed. I remain on the sidelines, watching. Big dilution/insolvency risks now look very high, I’m sorry to say. [no section below]
Ricardo (LON:RCDO) - 439p (£271m mkt cap) [no section below] I remember a reader suggested this engineering consultancy group as a possible takeover candidate, when we were trying to guess what might be the next RPS (LON:RPS) (which received a big premium bid from Canada). I’ve just looked at RCDO results for FY 6/2022, and like what I see. In line with exps. Nice recovery from LY. EPS (continuing) was 28.5p, rising (forecast) to 33.2p this year (per Liberum). Bank debt now modest, and £150m+£50m facility agreed until July 2026, so has scope for acquisitions. Net debt £35.4m. 10.4p divi. Software business sold post year end for $17.5m + £3.0m possible earn out. The share price has bounced a lot from recent lows. PER still only 13.2 (on FY 6/2023 forecast). Still looks good value, and a bidder could afford to pay a lot more, if they value it like RPS. Interesting!
Graham's Section:
B.P. Marsh & Partners (LON:BPM) (£113m) (+3% yesterday) [no section below] - this is an investor in financial insurance businesses (mostly insurance intermediaries) with a good track record of growth in NAV per share over time. NAV has grown from 273p per share in Jan 2017 to 463p per share in Jan 2022. It has paid a small dividend every year since 2012, but the main attraction is the growth in capital value, and the share price (302p currently) tends to trade at a big discount to this value. Yesterday’s trading update also confirmed that the company aims “at least to maintain” the current dividend payout for the next two years - the forecast yield is 0.9%, according to the StockReport.
More importantly, “the majority of BP Marsh’s portfolio companies have performed well in the period”. Two of its major investments continue to grow strongly and looking forward, BP Marsh is confident that “it will continue with its historic growth trajectory”. Insurance rates are increasing such that increased costs “will at least be matched by an increase in premium rates”, i.e. inflation is being passed on. I’ve owned shares in this before and would consider owning a small stake in it again, trusting in the expertise and discipline of the management team.
Bioventix (LON:BVXP) (£177m) (+8%) [no section below] - this famously successful biotech issues a strong trading update for FY June 2022. After a slow start to the financial year, “we have seen an improvement in performance and our trading result for FY2022 as a whole is likely to be significantly ahead of market expectations”. The company attributes this to post-Covid recovery (general diagnostic activity in hospitals and clinics reduced as a result of Covid measures). There is also a bounce related to the strong dollar/weak pound, as Bioventix earns 50% of revenues in US dollars but its results are reported in pounds.
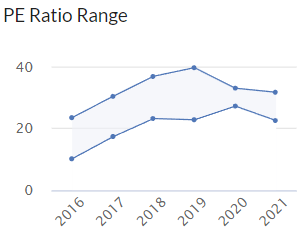
At around 26x after this morning’s bounce, the Bioventix PE Ratio is still at the cheaper end of where it usually trades. This is a famously high-quality business earning revenues of c. £650,000 per employee (!). On the assumption that its intellectual property is just as valuable now as it was pre-Covid, this pricing could be seen as a buying opportunity for a stock that is almost never on sale.
Focusrite (LON:TUNE) (£438m) (-7%) [no section below] - this musical equipment supplier issues a profit warning: while revenues for FY August 2022 are in line with expectations at £180m, rising costs are hurting margins. These costs relate to the familiar issues with semiconductors and freight, and have so far only been partially offset by price increases. Administrative costs are also rising and as a result, EBITDA will be “slightly” below expectations.
Additionally, the company references the importance of cash generation: it has used up its cash balance on acquisitions and on rebuilding its inventory (another consequence of supply chain uncertainties is that companies need to tie up more cash in their inventories, to ensure that customer orders can be fulfilled). While Focus has an excellent long-term track record, the lack of growth and the loss of its cash balance - which reduces its flexibility when dealing with current challenges - suggests to me that the market is correct to treat it cautiously for the time being. It’s categorised by Stockopedia as a “Falling Star” and I agree that its multiples should continue deflating until it demonstrates better resilience in these economic conditions.
Hornby (LON:HRN) (£48m) (+2%) [no section below] - an in-line trading update from this model railways company. Sales and margins are unchanged from last year, and the company is gearing up already for the key Christmas season. Shipping dates have been brought forward in a sensible measure to prevent a repeat of the supply chain problems. As for the outlook, the company suggests that the hobby sector can tough out bad economic conditions: “We are mindful of the impact the current economic climate may have on demand, but remain encouraged by the historic performance of the hobby industry in prior downturns and our expectations for the full year are unchanged.”
Separately to the trading statement, the company carries out a cleaning-up exercise; the independent directors had failed to express their “fair and reasonable” view in relation to some related party transactions with the Chairman, as required by AIM rules. They do so today.
For my detailed view on Hornby, see the SCVR of 16 June 2022. Today’s update lets us know that management remain confident in their plan, despite the various economic distractions and challenges of the past three months. I remain interested in the story of operating leverage possibly giving Hornby profits a big boost in the years ahead, although it could be argued that the market cap is already pricing this in.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Churchill China (LON:CHH)
1220p (up 4% yesterday)
Market cap £134m
These are good numbers, showing a nice recovery from the prior year H1, which would have been impacted by the pandemic.
Also, note from this handy table on Stocko, that pre-pandemic CHH had a consistent H2 bias to revenue & profits, so the good H1 numbers this time augurs well for FY 12/2022.
Here are my notes from running through the interims announcement -
H1 revenue up 73% to £41.4m, as it bounces back from the pandemic (don’t expect this rate of growth to continue though).
UK & Europe are the 2 main markets, at 39% and 42% of revenues. US & RoW are small, an opportunity for growth perhaps?
Profits (before tax) £3.4m in H1, up strongly from £1.0m LY (last year).
Adj EPS 24.7p (up from 4.5p LY)
Given the H2 seasonal bias to profits, the consensus forecast of 60.3p shown on the StockReport looks achievable or beatable - so lowish risk of a profit warning this year I’d guess. As for 2023 though? It's too early to say, although I'd be worried that a further rise to forecast 75p EPS in 2023 might be a struggle, if the current macro headwinds continue or worsen. So ideally I'd like to see forecasts quietly lowered for 2023, to prevent a profit warning.
No broker notes available, because the broker is Investec, who stop us getting access to research. EDIT: research notes from Singers have since come up on Research Tree, thanks for that (they weren't there earlier today when I checked, but I might have put in the wrong ticker)! End of edit. Time to change broker to a PI-friendly outfit, such as Finncap, Singers, Liberum, WH Ireland, or any other that publishes research on Research Tree? It beats me why any small cap would use a big broker, that has no interest in the main buyers of the shares - PIs. It's not just haughtiness though - due to MiFiD, brokers have to charge for research, so are then not keen to give it away to PIs, as that would undermine their source of income from institutional buyers of research. Time to scrap MiFiD?
Webinar - there doesn’t seem to be anything arranged for PIs. I’ve just nagged the PR, to ask if they would facilitate results webinars in future, because I know a lot of us find them invaluable, to increase our understanding of companies, and get a flavour of the people running them. So let’s hope the company takes up this suggestion. All companies should be doing results webinars for PIs these days, it should just be standard practice.
Balance sheet - remains very strong. There's been no dilution over the pandemic period, as the finances are more than strong enough to get through difficult patches.
Note that receivables has risen a lot, which I would expect, as business recovers from the pandemic. So that’s not a concern, although of course it has consumed cash.
I’d like to know what “other financial assets” are - there’s no explanation for this line. This has risen materially, from £1.0m a year ago, to £4.0m at Dec 2021, to £5.0m now. Although checking the last prelims, it refers to “net purchases” of other financial assets, so I’m wondering if this is cash on deposit, or hedging instruments? More detail should be provided, given the size of this line on the balance sheet.
Curiosity got the better of me, and note 16 to the 2021 Annual Report explains that these are term deposits (i.e. cash placed on deposit to get a higher interest rate), with Santander and Lloyds Bank. So this line should be seen as equivalent to cash, making the balance sheet even stronger.
I’ve gone a bit round the houses there, because the financial highlights disclosed “Net cash and deposits” of £15.7m, which we can quickly see is the combination of £10,650k cash, and £5,016k of “other financial assets”. Mystery solved!
Pension deficit is dropping, and is now £6.4m. There’s no information on what the deficit recovery payments are, if anything, so this would need more research - the answer is probably in the archive here, for previous SCVRs reporting on full year results.
Cash generation - wasn’t good, with cash reducing. This is due to working capital normalising, capex, and divis paid out, which combined exceeded cash generation. I don’t see that as a problem though, because cashflow should improve in H2.
Capex - the commentary today indicates more expenditure on automation & energy efficiency, but not quantified, but I anticipate a fair bit of cashflow is likely to be directed into continued capex, but not a worry if the payback on investment is decent.
Inflation - selling prices have been raised twice, but no figures have been provided - I would have liked a bit more detail on this, e.g. selling prices have been raised x%, in response to input costs rising y%. The commentary says price rises have “help offset” - which sounds ambiguous - does that mean fully offset, or only partially offset? Ah, I see it’s the latter, with the phrase “mitigate in part” later used. The price rises have been accepted by the market, and are similar to those introduced by competitors, it says, which reassures me.
Energy - clearly a big issue for this sector, given the need for expensive ovens to bake the clay, and other energy usage in factories.
Re energy price hedging, this looks good at hopefully cushioning CHH from the energy crisis for about the next year from now -
Our energy hedging position is relatively robust. We largely secured our volumes and pricing earlier in the year for a substantial proportion of our anticipated usage for the remainder of 2022 and the first nine months of 2023. We are mindful of the extended impact of volatile energy pricing and will continue to monitor market movements carefully.
Outlook comments are a bit vague, and no clear guidance is given, other than this -
We are aware of increasing levels of uncertainty in the general business and economic landscape and the possible effect of this on demand for our products, although we continue to benefit from good order levels after the period end. We are, however, mindful of the potential effects of an economic slowdown on our revenue and will manage our business accordingly. Input costs, in particular energy, remain volatile. Our energy costs are largely hedged well into 2023 and we will continue to monitor our exposure in this area. The business' principal focus over the next few months will be to develop our manufacturing operations to support increased output and efficiency levels both in the short and longer term. We will continue to invest in our people and our productive capacity.
We remain confident that Churchill is a resilient company and is well positioned to continue to grow in line with our established strategy over both the short and long term. We look forward to delivering an improved year on year performance in 2022.
Given that H1 is way ahead of H1 LY, then saying FY 12/2022 will be ahead of LY, is setting the boundaries pretty wide!
Note that in another part of the commentary, it refers to a record current order book.
So it looks as if the outlook should be pretty decent, although bear in mind the hospitality sector is having a seriously hard time right now, due in particular to energy costs, and consumers reining in spending in some areas.
My opinion - I’m impressed with these numbers, and have always liked this share, due to its decent products, widely used in the hospitality sector (e.g. my recent mystery shopping of J D Wetherspoon (LON:JDW) saw a curry served on a lovely blue patterned Churchill China plate), and excellent balance sheet. Although valuation is usually a stumbling block, in that CHH shares seem to usually command a premium that has tended to strike me as at least partly unjustified. Photographic evidence -
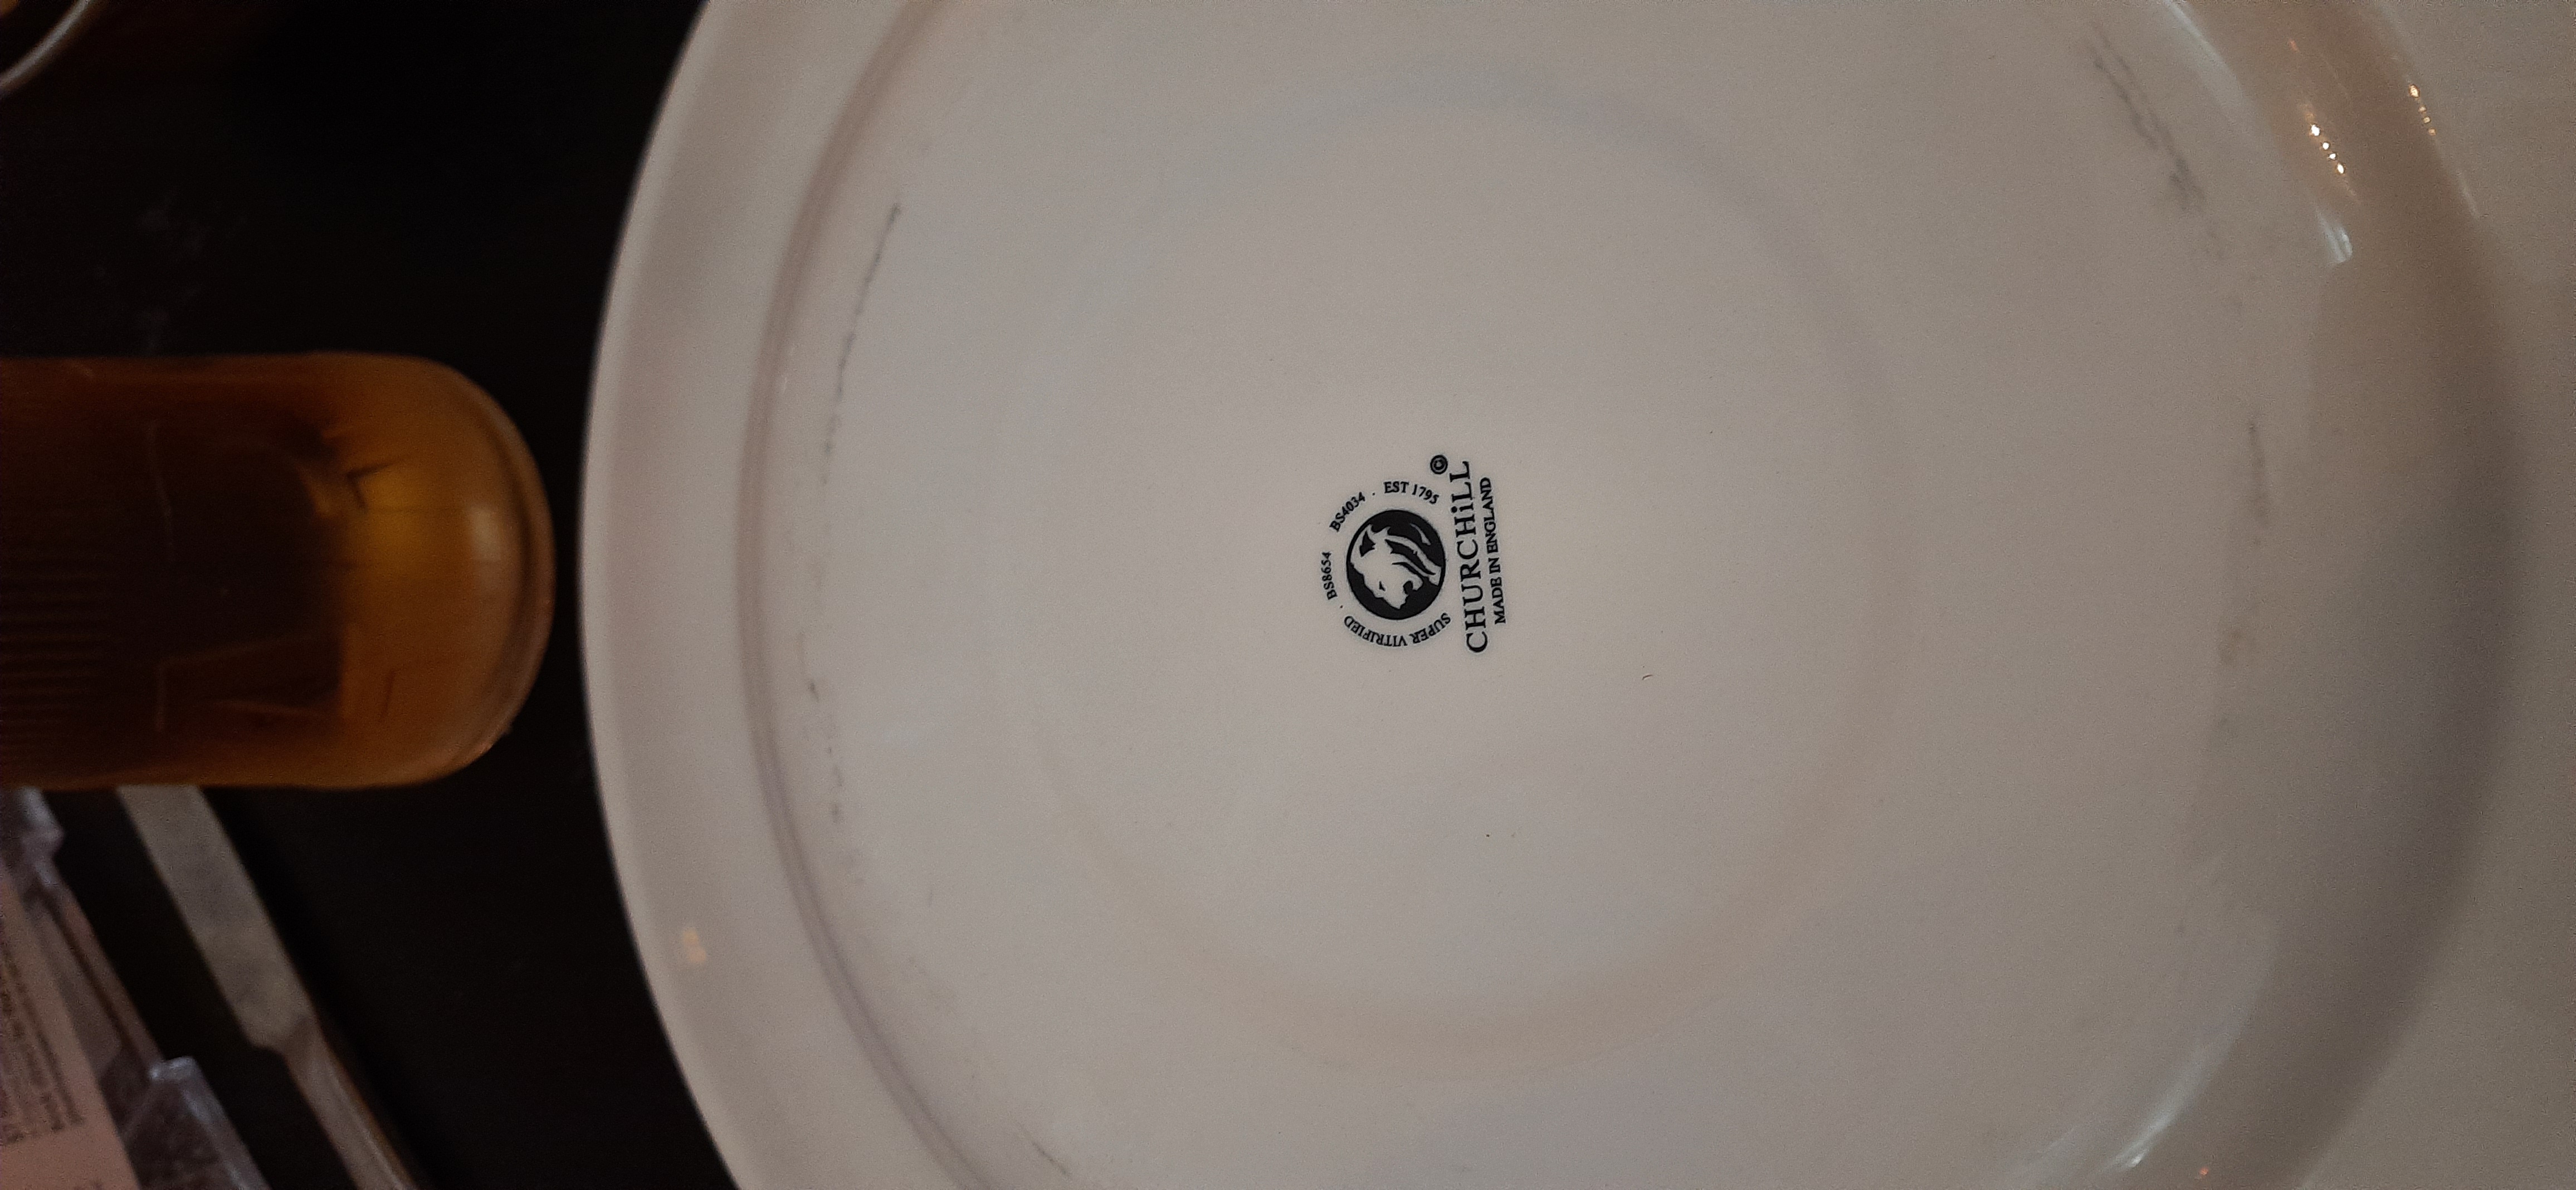
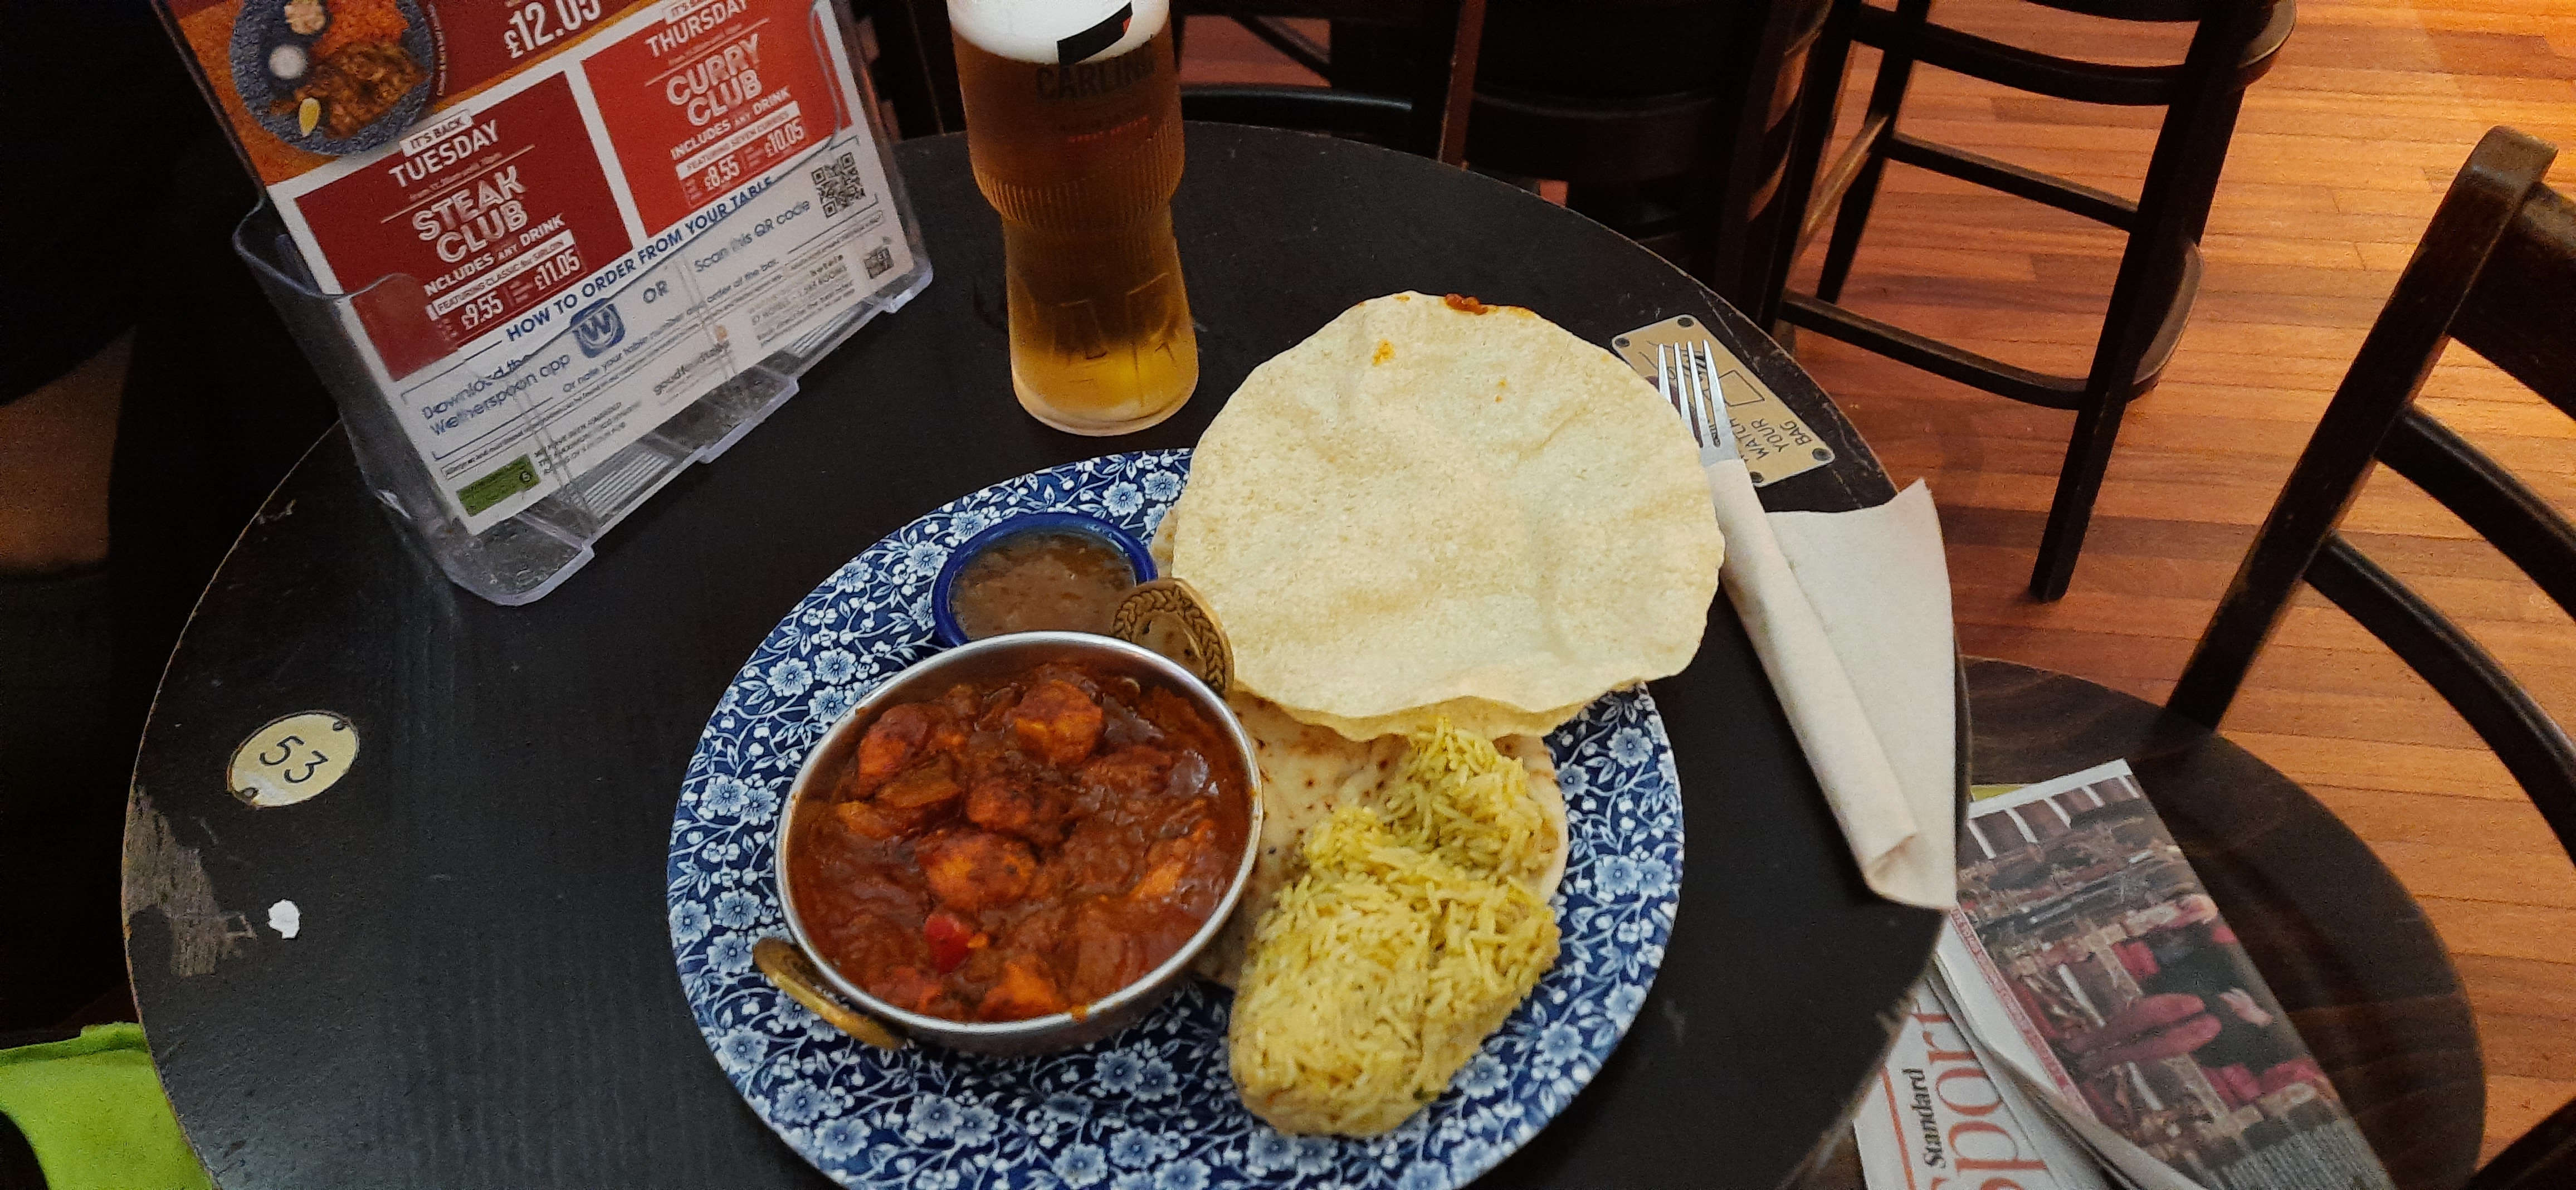
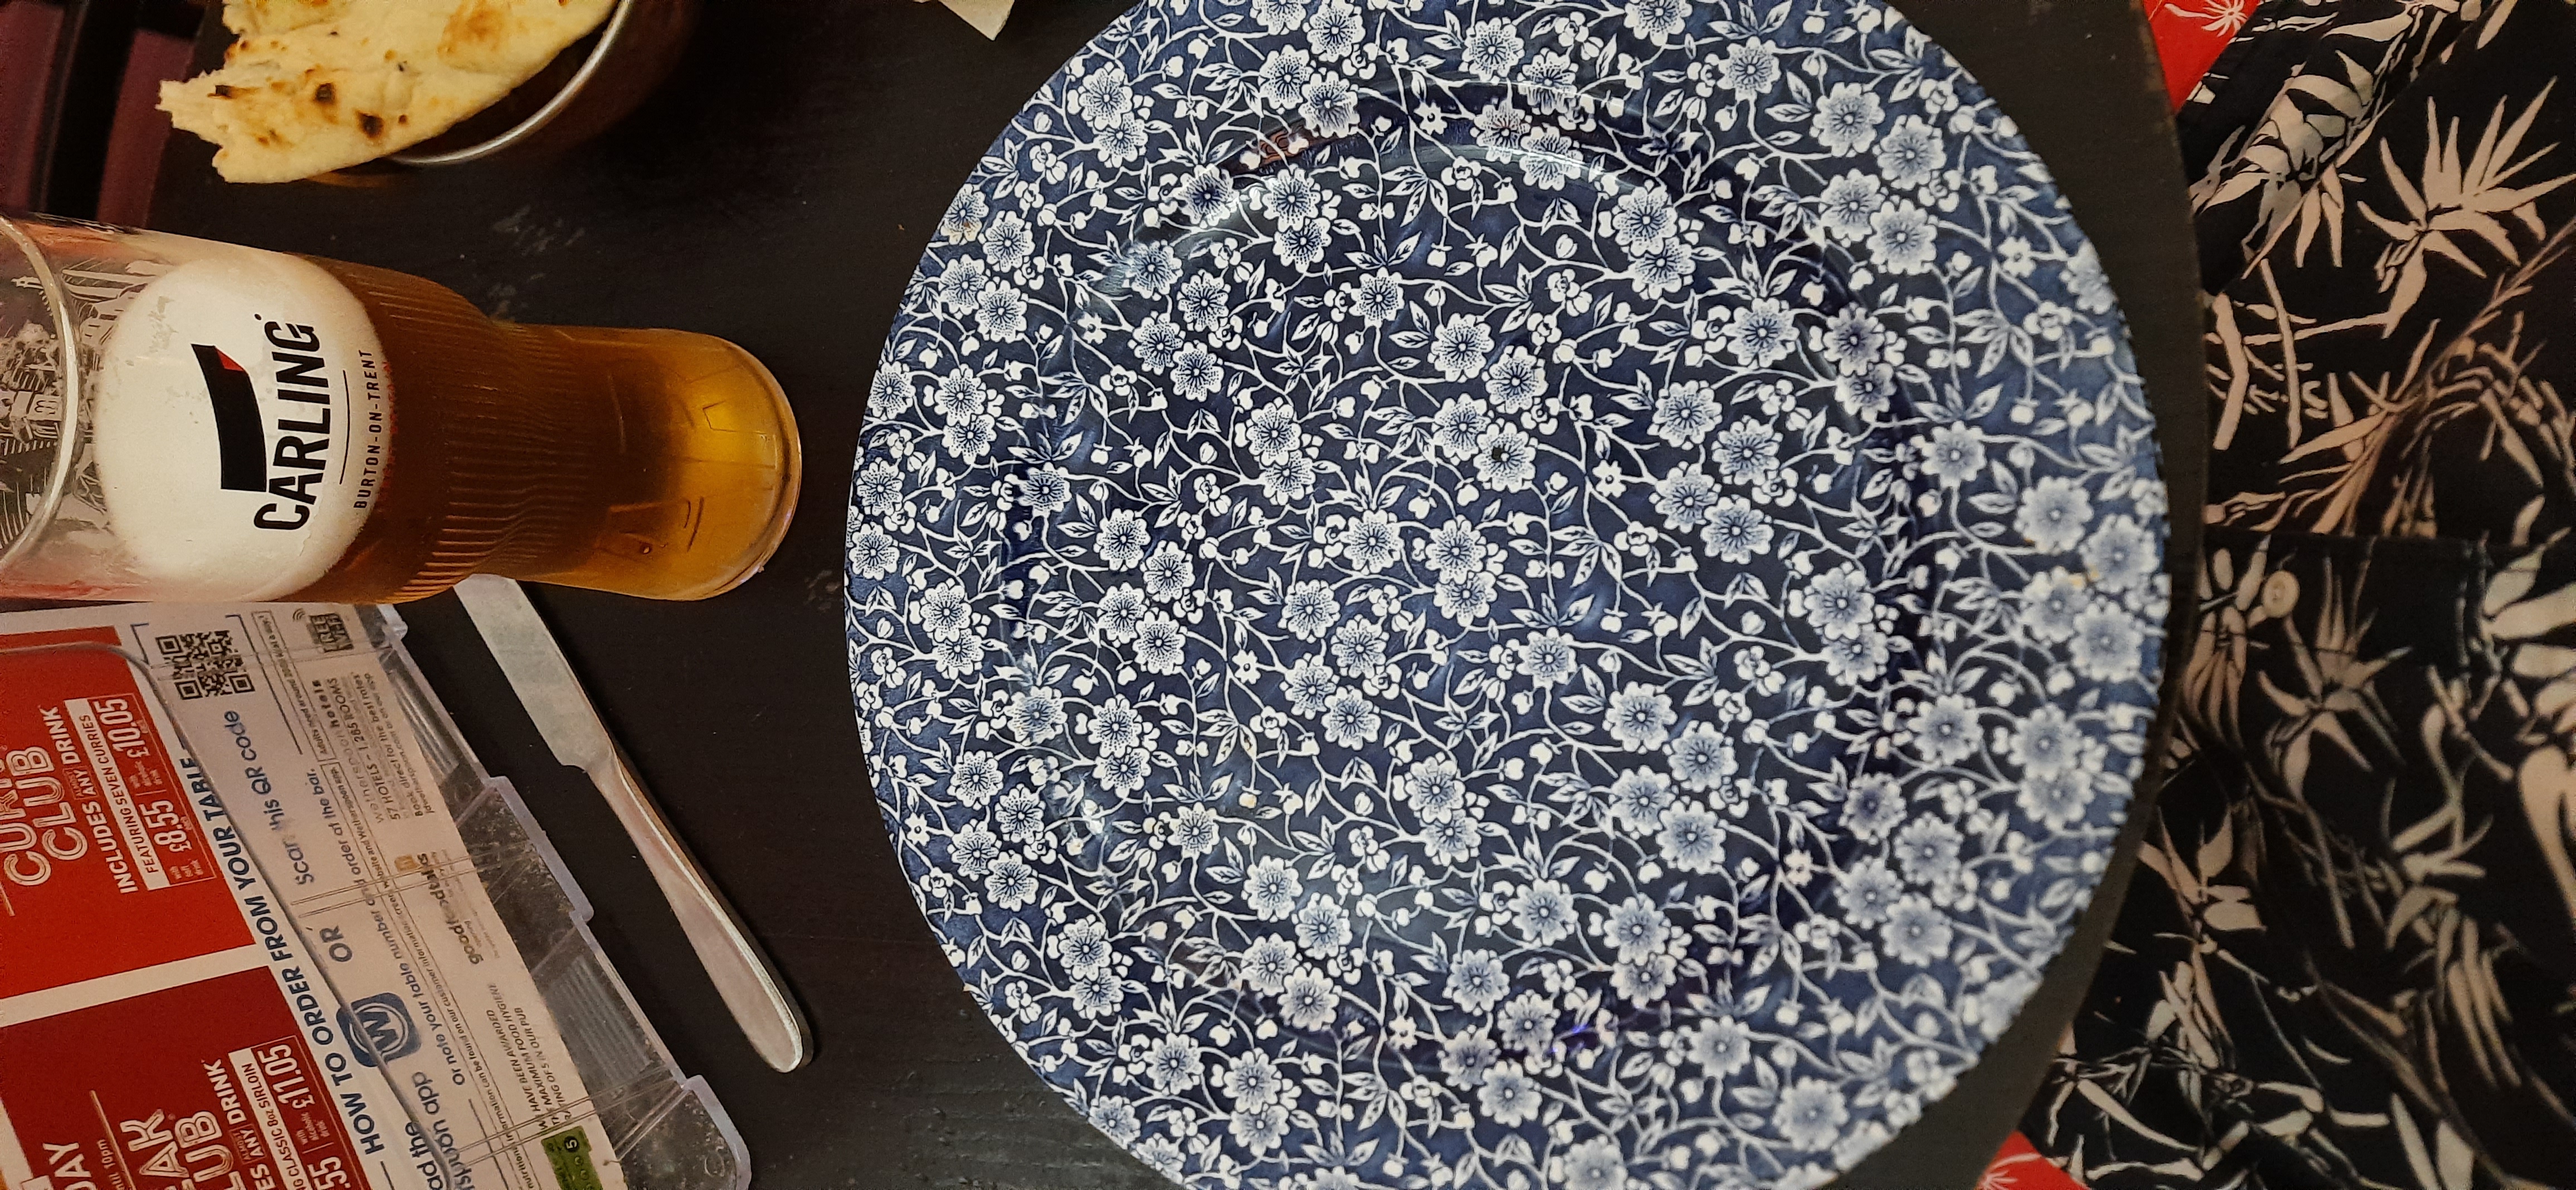
(above: "clean plate kid", as Mum used to say! I licked the plate clean for the last shot. As it was Wetherspoons, nobody batted an eyelid LOL!)
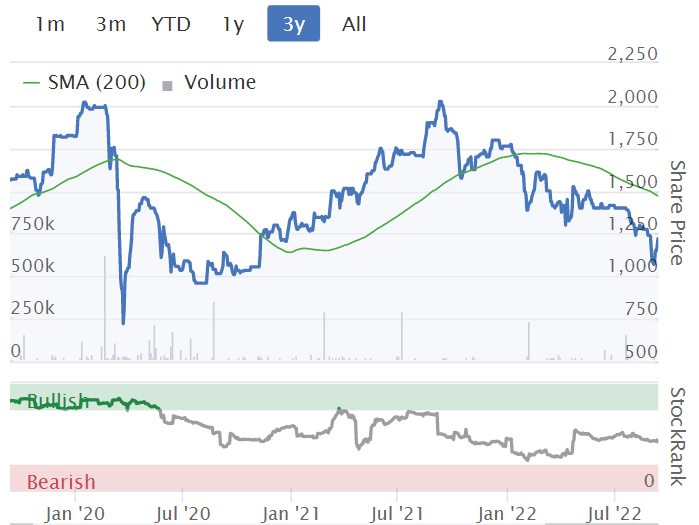
Given that CHH might do say 60-70p EPS this year, can a share price of 1220p really be justified? Especially when we know that CHH’s end markets are under severe pressure, and many independent hospitality outlets are likely to go under - due to severe cost pressures, and nervous consumer discretionary spending.
Although recent Govt support, said to be c.£40bn to help businesses for 6 months with an energy price cap, should help - but we haven’t yet heard the detail.
Taking everything into account, whilst the drop in share price for CHH shares make it more attractive, I really don’t see it as good value, given the intense strain that its end customers are now under - just look at share prices for restaurants & pubs to see what I mean.
On the upside, CHH is viewed by the market as a high quality company, so longer term, the current share price might be attractive, who knows?
.
Best Of The Best (LON:BOTB) (I hold)
440p
Market cap £37m
Best of the Best plc runs competitions online to win cars and other prizes.
The Board is pleased also to confirm that the Company is trading in line with market expectations for the current financial year. Further to the announcements made last week regarding the signing of a Letter of Intent with Globe Invest Limited and their subsequent strategic investment, we look forward to updating shareholders with more details in due course.
The last broker note I can find, is from June 2022, which indicated 53.9 EPS for this year, FY 4/2023. So today’s confirmation of in line trading, suggests the PER is only 8.2 - cheap apparently, especially given the consistently good cashflows at BOTB which have resulted in generous divis, special divis, and tender offers in recent years. Although as we've seen, profitability can be volatile at BOTB, with high online marketing costs being a headwind.
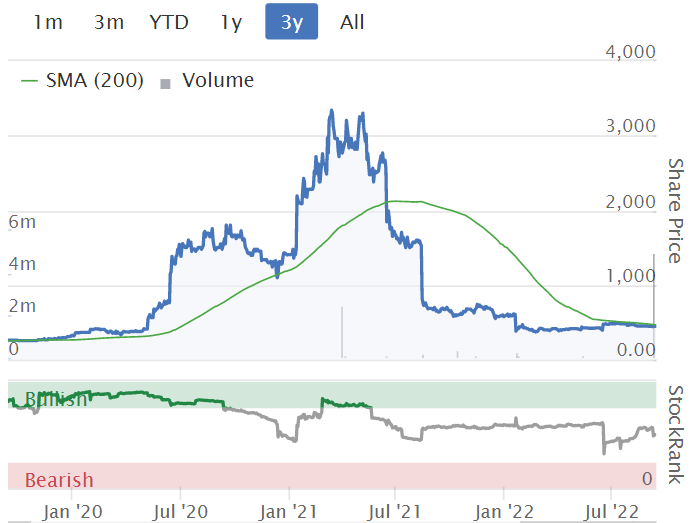
Obviously the elephant in the room, is why have founder management been so keen to sell up? I can see why they took advantage of the pandemic boost to profits, to bank £60m at £24 per share in April 2021. The only surprise is that the institutions which bought those shares haven't sued, given that the share price started collapsing within weeks, as a wave of bad news began.
Management sold more in the recent 600p tender offer, then here on 8 Sept 2022 came news of founder management selling the bulk of their remaining shareholdings to the famous Tedi Sagi, who is acquiring a 29.9% stake from the founders (no new shares being issued), at just 400p. The existing management will continue running the business (for now).
My opinion - I’ve got mixed feelings about this. Bringing in a strategic investor could pave the way for a full takeover later? Existing management seem to have lost interest, and seem likely to move on, I reckon. So would I, with £60m+ in the bank!
So why should we pay over 400p for the shares now? Well maybe because the new major shareholder could bring expertise, contacts, and ideas into the business which existing management lack? The update on 8 Sept talks about plans to take the business international, which existing management seemed to baulk at previously.
Ultimately though, the people who know the business best, have now sold down most of their holdings, which tells me that they don’t see a great future.
It’s tempting to imagine that the new investor, and expertise, could turbocharge future growth. Previous management were often criticised for being too cautious, and not taking any risks, instead prioritising cashflow. That could be about to change.
There’s no doubt that events over the last three years have left a very sour taste.
However, there’s now a clear catalyst for accelerated growth, and potentially exciting international growth. I imagine we’re likely to see a change of management fairly soon, which might be for the best.
Personally, I only hold a tiny scrap of this share, as I want to keep a foot in the door. Could it be a potential future multibagger (again)? Under new management, new investors, and new ideas, it’s possible, but we’ll have to wait and see.
.
Naked Wines (LON:WINE)
97p (down 33% today)
Market cap £72m
Two announcements came out after the market closed last night, which I’ve only just spotted because the share price is a top faller today.
NED resigns - Pravin Ravi has resigned. He only joined the board on 25 August 2022, less than 1 month ago. He was a non-independent NED, being a representative of 10% shareholder, Punch Card Management.
We could speculate on the reason given for his rapid resignation, but no scenario I can think of would be positive. There’s no reason given in yesterday’s RNS.
Business Update - again, announced last night after the market had closed.
Unfortunately, this is rather vague, but it doesn’t sound as if things are going well, does it? -
The Group intends to provide a Trading update on the week commencing 17th October for the first half of FY23, which ends on September 26th.
The company is reviewing potential operational and financial plans for the next 18 months and will update on these plans alongside our trading update. The Group's focus is on developing plans demonstrating increased profitability, cost restraint and improved payback.
Alongside this process we are in active discussions to address our credit facility to reflect any revised plan. The Group remains in compliance with all obligations around this facility through Q1 and expects to have headroom to the Q2 covenant tests.
Reading between the lines, this sounds as if WINE has given up the idea of being a sexy growth story, and is now concentrating more on survival.
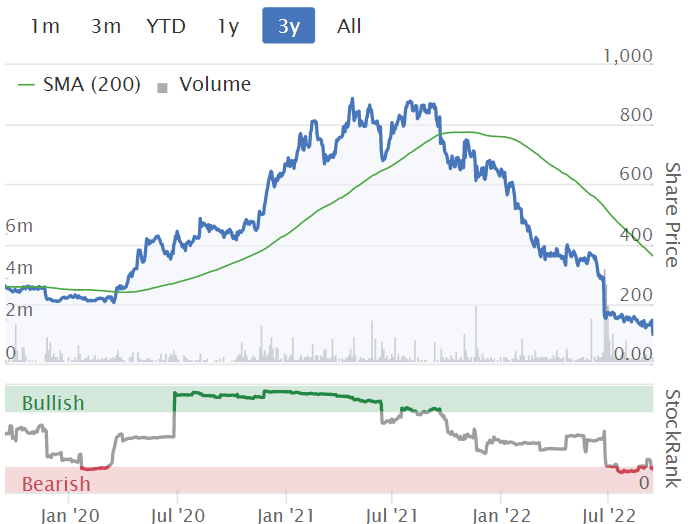
Clearly the market saw this coming, hence the share price collapsing -
.
.
In these situations, I focus on 3 things -
- Solvency - is there risk of it going bust (or having to cause major dilution with a rescue refinancing)?
- Is it now a value share - i.e. valuing it conventionally, on assets & likely future earnings?
- Could it be a convincing turnaround?
Looking at those in turn -
Solvency - the last balance sheet looked OK in total - with NAV of £110m. Writing off intangibles of £33.5m gives a still healthy NTAV of £76.5m.
The trouble is though, that inventories look way too high, at £142m, remember that’s at cost price too. If as seems likely, the business is now set to shrink in revenues, then its existing inventories would have to reduce very considerably - maybe by at least half? And that could require loss provisions to be made against some of those inventories.
Also, the £40m cash pile belongs to its customers - the equivalent liability to “Angels” who have paid money up-front, is much larger, at £76m. The trouble with that, is that as the business shrinks, then so does the benefit of customer cash reducing, thus it might even consume cash, rather than generate it, if the business shrinks.
Note that a $60m credit facility was only recently put in place, but there is already a risk re covenants.
Note from the going concern statement with the last accounts, it highlighted that a covenant waiver might be needed in Q1, Q2, and Q4. It seems that Q1 & Q2 were OK in the end, but what about Q4? Going concern concluded with saying there was a “material uncertainty” - never a good look. However, the company countered with saying it has “levers” to pull which could provide £30m extra cash headroom - e.g. cost cutting, disposing of wine on the wholesale market (which worries me about provisions being possibly necessary).
Value - is it a value share yet? No, not really. The market cap is £72m, slightly below NTAV, but the trouble is, that NTAV could shrink, both from trading losses, and inventory write-offs.
We can’t value it on a PER, because WINE has never made any significant real profits. It invented its own measures, such as “Contribution profit”, and “Standstill EBIT”. I’ve always been highly sceptical of these measures, as you’ll see from our archive.
Turnaround potential - much to early to say. Yesterday’s update seems to be focusing on the need to hunker down and survive, rather than being confident about the future.
My opinion - I’ve never rated this share, because it seemed more hype than substance. And it never made any real, meaningful profits. The story was that repeat customers are highly profitable. Those supposed profits were then funding expansion. Now that expansion is no longer the story, then overheads will need to be slashed. Will that end up creating a smaller, but highly profitable business? I’m very doubtful, but we’ll see.
Overall, this looks a salvageable situation, because it’s still got decent net cash. The key point to survive, is turning those bloated inventories into cash. If that can be done without too much of a hit to profits, then equity holders could be OK.
Unwinding the cash owned by Angels, would however see cash outflows.
Overall, it looks quite finely balanced to me, hence I wouldn’t be interested in getting involved. The most likely outcome, is a continued grinding down in share price, but that depends on future newsflow. It’s difficult to see much of a catalyst for a reversal in the downward trend. Would it be attractive to a bidder? Probably not, but that’s always difficult to anticipate. Is there anything unique about Naked Wines? Not really, I see little difference between it, and the other subscription wine services, such as Virgin Wines UK (LON:VINO) and the unlisted competitors. Margins are quite low, and the product handling & storing costs are significant, and customers shop around for the best deals.
.
Anpario (LON:ANP)
500p (down 12% today, at 12:45)
Market cap £120m
This niche animal feeds business has shed £16m of yesterday’s market cap, on release of interim results. Here are my notes from reviewing the H1 figures -
H1 revenues only up 3% to £16.5m - emphasising how small and niche this company is, which is selling globally in a huge overall market. It doesn't seem to have convinced many farmers of the benefits of its products.
Gross margin sharply reduced to 42% (from 50% H1 LY), reducing gross profit from £8.05m to £6.9m. Reason - cost increases, and time lag from raising prices. Margin now improving in H2.
Energy costs - very little gas used. Solar panels have reduced electricity consumption by 32%, so sounds fine.
Admin costs down sharply, from £5.4m to £4.6m, which has absorbed most of the reduction in gross profit, preserving profitability mostly.
Operating profit £2.3m vs £2.65m last H1.
Low tax charge this time has artificially boosted EPS vs last year, so be careful with EPS & PER calculations.
Balance sheet - is amazingly strong. Includes £13.3m of net cash. Current assets: £31.2m, current liabilities £4.0m - that seems excessive working capital to me - a nice problem to have.
Cashflow - poor this time, but for acceptable reasons - building inventories, to ensure the co has product availability.
Outlook - a bit wobbly. Says full year may not meet LY. Talks about international expansion, and more acquisitions.
My opinion - this is a decent little company, with a good track record, and a strong net profit margin. However, the growth has been quite pedestrian over the years, and it must only be scratching the surface of potential markets globally. So why isn’t growth more exciting? Are management ambitious enough, or happy to just keep growing modestly, and hoard cash? Talk of further acquisitions suggests to me that growth potential for existing products is probably limited.
In tough, bearish small caps markets, the risk here is that increasingly investors might question why a company with apparently little growth potential, is still on a premium rating?
I think we need to see something more exciting happen here - namely a more ambitious plan to aggressively grow organically.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
£spsy
I see on Twitter that there was an investor presentation this afternoon. Does anyone know if it is recorded anywhere please?
In response to the detail on CHH. Churchill China raised prices by 12% in November 21 and 10% in May 22 (almost not reflected at all in these numbers). They will likely look to raise prices again towards the end of the year. Energy is 87% hedged for the remainder of 22 and 63% for 23 at significantly lower rates than the current spot prices. A 6% pay increase was brought forward and they have been targeting employees with more skills with higher pay rises. They have various opportunities for self help - solar panels on the roof will reduce electricity costs by c20% (electricity is 7% of costs), they may be able to fire around 25% of their products only once, rather than twice, which would reduce gas consumption by c40% on the manufacture of these products etc.
Currently, the main constraint is labour as they cannot fill all their orders. They are now outsourcing some of their production to local manufacturers around Stoke, who are struggling with their retail sales. In time, Churchill will probably acquire some of these small competitors.
In my view, they are the industry winner, but it is a difficult environment due to cost pressures right now.
Feathered Capital, re £CHH and ",,,,solar panels on the roof will reduce electricity costs by c20% (electricity is 7% of costs)"
What is the source this (and the other) detailed insight? I have a big position for me in £PMP and have been trying to understand such matters. I assumed that energy would be a bigger part of total cost of a pottery firm and of a magnitude/intensity that solar+battery would struggle to match.
(BTW - I am usually a solar fan and think nearly all businesses with land /roofs should be looking to do solar as I understand cash payback was typically <10 years on pre-Ukraine costs for larger commercial sized arrays, can provide emergency power back up (at least for low demand office equipment) and is almost certain to pay back eventually unless business closes as energy use is forever. Few company investments have this combination of desirable characteristics IMHO. )
Vertu motors on the slide probably due to concerns over exposure to energy bills heating showrooms ?
Looks seriously overdone on a long term basis and I think there’s a bit of a shakeout going on of weak holders.
If ever there is a company begging to be taken over by private equity this is it, total no brainer buy the company , sell and leaseback the properties and your getting a big bag of cash for nothing .
Churchill China is covered by Singers if you want forecasts.
Hi Feathered Capital,
How strange, I checked on Research Tree this morning, and there were no forecasts from Singers (or anyone else) available for Churchill China (LON:CHH)
But now there are! So maybe it was just a glitch? I'll edit the article accordingly. Thanks for pointing this out, have a thumbs up!
(I always do check first on Research Tree, before saying there are no broker notes available)
Regards, Paul.
Probably already been said, but I'm not sure how the management at Joules have managed to drop the ball this badly. The middle class yummy mummies seem to want to crawl over broken glass to buy Joules gear - my wife and her friends have tons of it and I can guarantee I'll be getting something from them every birthday and Christmas!
The point, if I have one I guess, is the brand has significant value if it can be maintained. Would be a shame to see it disappear or move down the quality scale
I agree on the viewpoint of my wife and certain friends seem to live in Joules (LON:JOUL) and that it makes an easy birthday and Christmas present for may friends and family to just buy another top online. Then there are the occasional bigger ticket items like a new winter coat every few years. You just go straight to Joules do not pass Mountain Warehouse or Sainsbury's...
I would agree and add to the anecdote about how many of these have actually been purchased full price, or how many are at the £'s off and that is the first search, so you get the logo but maybe last period or least seasons version for 50% off? The quality is the same but we are not in the band or area where it is a new wardrobe every season. Yes it needs to be Joules for the quality, look and feel (and brand) but will still wear the item they got three years ago.
I found personally last month that it was hard to find the actual Joules clothing for the "friends of Joules" yes I get easy margin for selling other folks stuff, but we are shopping for your products so put them front and centre every time, don't make me search for them.
I suspect that it will be a cheap buy out, did anyone call Mr Mike yet Frasers (LON:FRAS) ???
Tommy
ps. I do not hold
Yes surely a lot of value in the Joules brand. If Next continue to faff around deciding whether to acquire, wouldn't be surprised if someone else jumps in instead - would make ideal fit for M&S and I'm Mike Ashley would also be keen.
Paul
As a quick counter point to Focusrite .
Stock build and resulting decrease in cash can be considered negative
It can also be viewed positively , on the condition the stock is the right stock , as the GBP v USD is heading down the toilet (1.15 ish now) the stock in hand would have been purchased in the past 6 months at circa 1.3 .
So you might argue they have banked a nice 15% currency gain .
Still cash like Elvis and Charles is king so I am sure the FD would prefer to be sat on that cash cushion .
Hi planetx,
It was Graham who covered Focusrite (LON:TUNE)
Personally, I'm relaxed about inventory build up, if it's a deliberate strategy to improve availability of product for customers. Also, many companies are seeing inventories and receivables are going up naturally, as they're having to pay more per unit for fresh stock, and then passing on the higher prices to customers. So two debits rise, but only one creditor rises (trade payables), hence inflation naturally sucks in cashflow in this way, and it's not necessarily a concern.
Good point that you also make about recent dollar strength possibly creating a temporary boost to gross margins, although I suppose that would depend on cheaper inventories (bought when the dollar was weaker) now being sold at newly increased prices? I suppose it will differ from one company to another, depending on how much product is sold in different currencies.
We're generally seeing some quite big currency effects in recent results.
Regards, Paul.
Dollar rate shouldn’t make any difference to purchase price assuming they are buying from the Far East and have a buyer that knows the ropes. A strong dollar impacts both RMB and GBP. If the RMB has fallen 5% against the dollar then you should be paying 5% less for the goods in USD. If anything if they have stockpiles then this probably have cost them more than current prices. Shipping costs, lower commodity prices and factories running at 50% capacity in China have all brought landed prices down.
Hi
UK Hydrogen stocks were commented on in the SCVR in the past couple of days.
But sadly, Hydrogen stocks are falling persistently.
ITM Power (LON:ITM) reported today and is down over 26% today at time of writing.
ITM Power (LON:ITM) has a bigger loss than anticipated, costs have risen, they are re-focusing to less ambitious plans and like others struggling with macro conditions. On the positive side, they have a lot of cash reserves (£395m, on a market cap of £939.36m). Also, the CEO is stepping down, but will remain in a strategic role.
I hold ITM Power (LON:ITM) Ceres Power Holdings (LON:CWR) and AFC Energy (LON:AFC) in small amounts and am bullish in the longer term for this sector. But as I have posted in the past it is a highly volatile sector so not at all for the risk averse.
From my experiences with these UK based stocks and others in US, Canada, Norway and Sweden, I perceive that although this is a potentially an important new energy sector, so much of it is embryonic (although much of the technology is proven and well understood).
The potential is clearly there, as is the Geopolitical will to see it mature.
IMO I think investing in it requires (a lot of) research and thus conviction, a longer term view, a commitment to cost pound averaging both on the down side and the upside (so a degree of trading mentality).
That said, with these persistent share price falls, some attractive entry points could be forthcoming.
ITM Power (LON:ITM) is a loss maker but could become a M&A target, or a turnaround with a new CEO.
Ceres Power Holdings (LON:CWR) reports 22/9, and is down 10% today hitting quite a long term support line at about 509p. A price it was in May 2020. Think, is Ceres Power Holdings (LON:CWR) the same company today as it was in May 2020? No, it has evolved significantly since then. So an attractive entry point could be close.
AFC Energy (LON:AFC) is similarly bouncing around a support, in the low twenties to thirties pence level.
I am not at all suggesting these as buys. They are all start ups with unattractive Stock ranks. They are risky. But they could be candidates for thematic watch lists.
Regards
Howard
Dr. Paul Jourdan of Amati fund managers shared some interesting views on hydrogen whilst discussing Getech (LON:GTC) back in July, at 48:20 mins here on Vox markets, basically saying how difficult hydrogen is and questioning whether it will even be a viable energy source: https://www.voxmarkets.co.uk/m... just to offer a counter view.
Hi woodcub
Thanks I will take a look.
Regards
Howard
Manufacturing Hydrogen is a simple process.
You stick a pair of electrolysers into a bucket of water (H2O), pass electricity through them, and the Hydrogen & Oxygen will separate.
And if the electricity used is generated from (say) wind or solar, then the Hydrogen can be classed as truly 'green' Hydrogen.
The problem for ITM Power (LON:ITM) (which manufactures the electrolysers) is that it remains sub-scale - cash burn was £53m last year & is projected to be £110-135m in the current year.
Unfortunately most buckets of water contain a lot more than just H2O, so not as easy as all that.
And igniting H2 in air is an extremely simple process.
Hydrogen gas is a very small molecule, it leaks easily and penetrates metals such as iron, making iron pipes brittle. Liquid hydrogen is a tricky fuel, as NASA seem to be learning ...
Thanks again Howard. I was waiting for an entry point for ITM. Today’s update was interesting but not what I expected. Will wait a little longer to see what the new ceo says. Interesting sector.
AFC Energy is a terrible stock. Do not touch this!
You could consider investing in a hydrogen related ETFs to spread the risk....Some ETFs here https://www.justetf.com/uk/how...
Howard, please save yourself from any more loses. In my view, these businesses are extremely likely to continue to haemorrhage cash into the distant future. It's a fantastic idea, but ultimately these businesses have not managed to make anything commercially viable.
As an example, ITM Power has £5.6m of revenue!!!!! On a market cap of c.£1bn before today. This figure has barely grown in real terms (forget pct terms!) and they have missed every analyst forecast for 10 years.
Hi FeatheredCapital
Thank you for the heads up.
I'll reassess the holdings. They are extremely small though, as I went in expecting a lot of volatility, but I will dig back into the histories in greater detail.
I might have got sucked into the stories too much.
Again, many thanks, I appreciate it.
Regards
Howard
Have been in and out of Ballard Power and Fuelcell over the years but now hold Cummins as the safest way to play Hydrogen.Also have Air Products on a watchlist .Obviously neither is a pure Hydrogen play
Very odd series of announcements from £WINE last night...
Analyst from top two shareholder resigned after just two weeks on the board. Company confirmed that there has been no breach of covenants and will update on trading in October (which should rule out a horror profit warning), but something is up...
Grateful for any thoughts?
Could you possibly cover Blackbird (LON:BIRD) today?
Hi djack,
I've just added a brief comment on Blackbird (LON:BIRD) to the summary section above. Here it is -
Blackbird (LON:BIRD) - a reader request for me to look at its interim results today. Revenues tiny, at £1.5m in H1 but good growth of +78% vs H1 LY, but up less +29% vs H2 LY. EBITDA loss little changed vs H1 LY, at £637k, but favourable moves in LTIP costs have reduced the loss before tax. Underlying loss looks to be almost flat vs H1 LY, so nothing to get excited about there, in terms of underlying performance. Plenty of cash at £11.6m (and no debt), so cash not a worry, with years’ cash burn in the bank. Market cap of c.£70m is based entirely on future hope. So there’s nothing to support the price on fundamentals at present. Good luck with it!
Regards, Paul.
£MTC ( I Hold small position) Any thoughts on the huge rise yesterday 60%+ at one point Fell back a bit this morning. I was looking for info if a bid had come in but can't find any. Surprised it rose so much on the results, would appreciate any comments.
Hi ckidcurrie23,
Mothercare (LON:MTC) issued FY 3/2022 results yesterday afternoon. I've just had a quick look, and the figures & outlook are quite good actually. Balance sheet looks a lot improved, although moving the pension deficit into an asset, looks unrealistic, that would be a key area to research.
It was hit hard by closure of its Russian business, post year end. But the guidance given sounds fairly reassuring.
Could be worth a closer look, as it's now a franchise, capital-light overseas business model, post the restructuring.
Regards, Paul.
Thanks Paul Appreciate you taking the time to look
Best Of The Best (LON:BOTB) - the problem I have with the recent Tedi Sagi investment is we don't yet know the terms of the deal. For example, is he going to want to provide a hefty charge which could dent Best Of The Best (LON:BOTB) profits in the short-term? I think best to stay out until those terms are clear
Trackwise Designs (LON:TWD)
I followed this with a view to invest but at results on 28/7 there were some worrying aspects and I have been sitting on my hands as has Paul:
Graham: "Profit warning - revenue from TWD’s most important customer has been “delayed” and brokers have this morning slashed their FY 2022 revenue forecast by 53% to £10.5m. They forecast year-end net debt of £14.5m, which looks very dangerous to me in these circumstances. I consider this stock uninvestable.
[Paul adds: Thanks for this Graham! I was warming to TWD as a speculative punt, but your update today has put me off. Looks more risky than I suspected when I looked at it here in June. Interesting new products, but I'd like to see more secure finances before investing here".
https://www.stockopedia.com/co...
65 minutes into trading this morning they announced further problems with the orders from the major customer and hence funding: https://www.londonstockexchang...
SP down 42% at the moment, having already fallen 57% from the day before results to yesterday's close.
Thanks Graham!
Unbelievable that Trackwise Designs (LON:TWD) (I hold) should now have a market cap of just £4m. World-beating technology that allows the production of any length printed circuits that are the way forward for wiring harnesses on aircraft, medical devices, batteries and EVs. Once running the presses should be able to churn these things out at very high margins.
But a classic case of running out of money at the wrong time. Been holding on thinking that at any moment there'd be an announcement of another massive contract (like the one with Arrival that's now gone pear-shaped) that would ensure their future and lift the share price. Can't help but feel that in the US they would be treated very differently; CelLink raised $250m in February this year.
Now down 90% but that shouldn't deter others from watching this closely as, if they can dig themselves out of this hole, their pipeline of opportunities (34m) potentially represents a massive opportunity.
I was a holder and have followed Trackwise Designs (LON:TWD) for a number of years. The technology sounds fantastic with potentially multiple applications across many industries. However, they've been saying this for a few years now during which time they've had multiple equity raises.
I think this raises the question, is the technology really that valuable as the customers aren't exactly queuing up? This is despite having engagements with a few established, world class car OEMs.
Sorry to be down on this one but it seems retail shareholders are losing money on TWD equity raise after equity raise.
I don't think there is any doubt that the technology is incredibly valuable Cuddlesticks. Question is, who will eventually make the money out of it? Looking more likely that it won't now be me!
re Trackwise Designs (LON:TWD) the technology is valuable, to the tune of a lot more than 4 million. BUT, building up production using a completely new process is expensive, and their planning seems to have placed too great a reliance on revenue building fast enough to meet the costs. I don't, and haven't held, but I have burnt my fingers before on good technology that ran out of money. With 20:20 hindsight, they should have raised much more money when they floated, or at least built a further raise into their projections. Unfortunately, the most likely scenario from here is that the company is bought by someone with the deep pockets that are needed. With any luck, and imho, purchasers now stand a chance of getting their money back and a bit more, but not those who backed it earlier. Not personally sure the public London market is capable of supporting these sort of businesses until they get to be much later stage.
Artisanal Spirits (LON:ART) new note out today from Equity Development following Interim Results - and a reminder that we have an investor presentation with management at 4pm today (register here: https://www.equitydevelopment....)
Summary of note (link to full report - "Successfully following a clear route to growth": https://www.equitydevelopment....
The Artisanal Spirits Company (ASC) continues to deliver on its strategy to take advantage of the sizable and fast growing global premium whisky market. Interim results released today reconfirmed robust growth in both revenue and membership in the first half of FY2022, and trading so far in the second half also appears strong. As a result, we maintain our confidence in close to 20% sales growth this financial year and reiterate our 150p fair value for the shares.
Membership numbers grew in all of ASC’s seven operating regions with the strongest increases being recorded in the UK (+31%), Europe (+33%) and Australia (+28%). Since half year end, membership increased further to 36,000 as growth in China resumed.
The notional retail value of ASC’s cask inventory, which we believe should be a focus in relation to the market capitalisation of the group, increased from £430m at end-December 2021 to £455m at this year’s interim stage. The retail value of this inventory should grow further as the company’s whisky stocks mature. Moreover, the ongoing purchase of whisky by ASC at earlier stages of the maturation process augurs positively for future gross margins.
Interesting move by Terry Smith and Co today to liquidate their emerging markets fund, the shares are up as it was trading at a discount to NAV. We do not hold but I consider Terry Smith to be a very good honest and straight forward Fund Manager. We have held Smithson and are looking to reinvest into that mid cap fund. Forgive me commenting outside our SCVR realm, I think the move is of interest though.
Are they liquidating due to poor returns and a belief they can't beat the markets in EM. Or due to lacklustre investor demand and not being able to achieve a sizeable AUM for the fund?
I suspect it's a bit chicken and egg. Their inability to generate decent returns has in turn curtailed the popularity of the fund. At this point it's become a rounding error fee wise in the context of the original fund, and let's be honest a bit of a stain on the brand. So the decision to wind up is a win-win for both them and shareholders. I've been a (tiny) shareholder since inception and am personally a little bit sorry to see it go. Firstly, it's been a fantastic education in how difficult it is to consistently make money in EM. My take is that it is far better to access the growth opportunity through the developed market multinationals (Diageo, Unilever, etc) then diving in locally with all the associated FX, illiquidity risks, etc. I assume that's been their conclusion too. Secondly, the AGM was a great way to chat to Terry in person, who would usually attend and mingle after the meeting. A far cry from the Fundsmith annual meeting and the thousands of attendees that this attracts.
As an aside it will be very interesting to see if there are any mid-term implications for Feet's sister Smithson Investment Trust. This has obviously been a magnitude order more successful than Feet but has suffered a massive derating since peak and now trades at a double digit discount to NAV. I personally think some of their stock selection benefitted from significant unwarranted multiple expansion and will now struggle in this environment
Artisanal Spirits (LON:ART) Admittedly one of these post-pandemic over-priced IPOs , so don't get anchored on the historic share price but this one is at least delivering, unlike others. I don't particularly like resorting to EV/Sales or to "notional retail value of stock (8x + market cap) for valuation but they are delivering good growth in sales and, importantly for the future , membership. Investment in distribution, in the blended brand and in oak casks as well as young spirit whose maturity boosts margins over time, is holding back profit for now but they are well enough funded. Having just become a member of the Scottish Malt Whisky Society, the brand dynamics are cool. Global in scope and both US and Chinese markets picked up. Worth a look for the growth orientated
Hi MightyPedro,
Thanks for the heads up on Artisanal Spirits (LON:ART) - I've been meaning to properly look at this for a while, but I'm sceptical about the concept that you can anticipate future profit margins from cost, to a possibly inflated eventual sales value, and somehow argue that the shares should be priced to include this future profit margin. So I wasn't convinced by a research note I read on this company earlier this year.
But when time allows, I'll try to take a fresh look at it.
Regards, Paul.
Dunelm (LON:DNLM) - I know it's too big to be covered here but results are fantastic. They are so in tune with events! Superb business on a p/e < 10
Hi eParo,
I've not looked at Dunelm (LON:DNLM) results yet, but it's one of my top picks for mid-sized retailers, operating from cheap & popular sheds in retail parks, and selling affordable homewares. It might even benefit from people cancelling big ticket purchases, and instead spending a smaller amount on affordably sprucing up their homes with new curtains, cushions, ornaments, etc.?
The current valuation looks attractive, if you think longer-term, in my opinion.
Although note that brokers have been quietly lowering expectations for FY 6/2023 -
Regards, Paul.
You might have thought todays decline in inflation (in the UK) be met with a bit of optimism...but no !
Headline rate has declined, but core UK CPI inflation hasn’t peaked yet. The fear is that inflation triggered by energy and supply chain shocks is getting embedded into the general economy, making it harder for the central bankers to get inflation back to the 2% target.
I think with the big sell off America yesterday, the FTSE is holding up pretty well TBH,
I notice milk eggs and bread and clothes are all big movers up in inflation...which makes me feel that inflation is spreading to all parts of the economy, which is going to be harder to eradicate, harsher rate rises and then of course more chance of recession. I think this counters the positive News.
However I am becoming more bullish about the way small caps are behaving. Seems bombed out small caps are running out of sellers and 'low' levels are holding. Yes we don't have buyers yet either, but I am a little more bullish than a month or so ago about good quality value small caps on low P/E's.
Time will Tell!
Bioventix (LON:BVXP)
Nice Trading update this morning.
Substantially ahead of market expectations and pleasingly troponin is doing well.
Phil
(I hold)
Focusrite (LON:TUNE) trading update reports good revenue growth and sustained demand but pressure on margins due to cost increases only partially offset by price increases. As result EBITDA likely to be slightly below management expectations. Cash, depleted by acquisition of Linda and rebuilding of inventory, remains a priority. I think this is a well run business but like many, it is having to deal with factors outside its control. Nevertheless, its products are well regarded and demand is strong. I hold.
Focusrite (LON:TUNE) I agree great products and I use them myself however the following stood out for me in todays trading update As at 31 August 2022 the Company had a net cash balance of approximately nil (FY21: £17.6 million net cash). Most of this has been spent on acquisition but what about the rest? Seems to be a cash burn and is a placing therefore likely?
Focusrite (LON:TUNE) RNS says cash has been depleted as a result of acquisition and rebuilding inventory. Given cash has declined from £17.6m to nil and the Linea acquisition cost £12.1, the balance of the shortfall is easily absorbed by restocking both finished product and key components. I would hope that cash can be rebuilt from strong revenues going forward. It was commented that revenues are now running at nearly double the last financial year prior to the pandemic.
Focusrite remains a very cash generative business. They will certainly not need to come back to the market, unless they intend to make a large acquisition. As stated by rwh3ue, most of the cash depletion is due to an acquisition.
Focusrite had an outstanding period during Covid and growth is likely to be flat over the next couple of years as revenues were potentially brought forward during the crisis. The management team are shrewd operators and their recent acquisitions will make a contribution going forward.
Some open ended funds own Focusrite, which is extremely illiquid, and these funds are facing redemptions which is making them forced sellers in some of these stocks. This can hurt share prices quite rapidly.
Over the long term, I feel that Focusrite will recover as now it is relatively inexpensive compared to what it once was; however, we may be waiting two years before we see strong increases in revenue again.
Ricardo (LON:RCDO) good prelims in my view, lots of figures and much to digest, Positive outlook statement and if the 46% or so increase in the final dividend from 5.11p to 7.49p is anything to go by, the future is promising.
However given prevailing sentiment, Mr Market will likely be unimpressed. I hold.
CentralNic (LON:CNIC) nice bolt on acquisition with an existing supplier - initial consideration is $11.2m in cash and M.A. Aporia generated $35m of revenue, $3.5m of gross profit and $2m of EBITDA in 2021. An earnout of $7.8m may be payable depending on performance metrics up to 2024.
Hopefully strip out some costs and maximise profits.
And Zeus raise forecasts as follows this morning
'We raise our EBITDA by $2.8m in 2023 and $3.0m in 2024, assuming the acquisition grows substantially in 2022 and in line with CentralNic’s Online Marketing division (7% pa) in 2023 and 2024. We increase net debt by $11.2m and raise Adjusted EPS by 3.3% in 2023 and 3.5% in 2024'
Low P/E for this company, much to like here I think.
(I hold)
I agree with your comments, Happy to continue holding and watching the company build out its capability. This fits my "will it be bigger in 5 years time" criteria
UK August Inflation better than expected:
https://twitter.com/John_Stepe...
And US worse (yesterday), yet cable still on its a***e.