Small Cap Value Report (Weds 20 Sept 2023) - WINE, BIG, ACSO, FIF, TRST, JDG, W7L

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
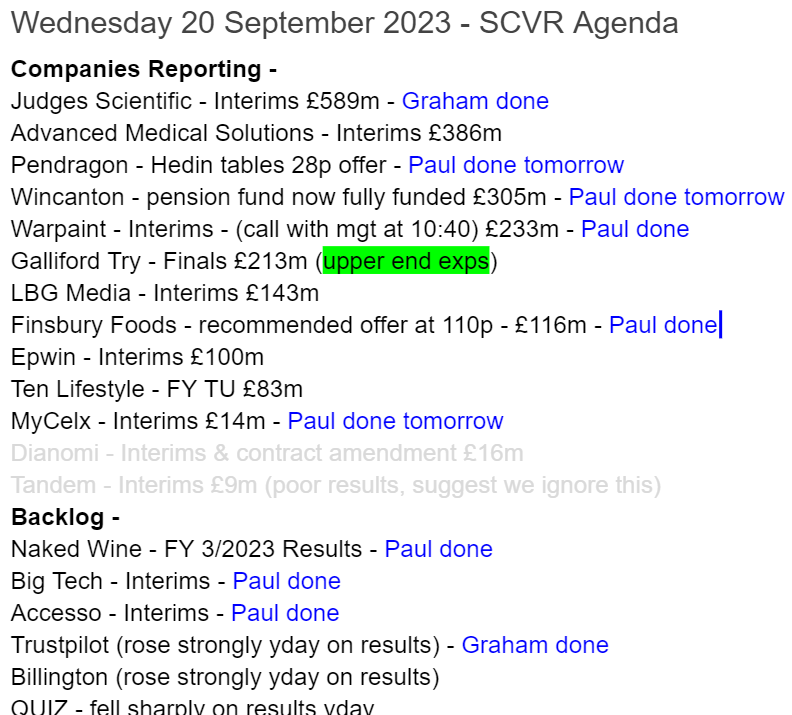
Summaries
Naked Wines (LON:WINE) - down 8% to 64p (£48m) - FY 3/2023 Results - Paul - RED
I reviewed this wine subscription service negatively earlier this year, and the FY 3/2023 results don't change anything for me. Its well-known problems include being massively over-stocked, resulting in most of the customers' cash deposits being sucked into inventories. Material uncertainty in going concern statement is a red flag. Current trading is weak, as it cuts back on marketing spend. Could be a turnaround, but too risky for me at this stage.
Big Technologies (LON:BIG) - down 6% to 216p (£628m) - Interim Results - Paul - AMBER
A Sept 2021 float, so beware of this vintage - many were over-priced and opportunistic, which has killed the IPO market for now. Useful tracking devices worn by eg the elderly, detecting if they've had a fall or gone AWOL. It's a nice, profitable, cash generative business, with recurring revenues. Owner/managed still. I find the valuation a bit toppy, and management greed over share options repels me. Lovely cash pile looks surplus to requirements, so could do deals with it.
accesso Technology (LON:ACSO) - down 11% to 658p (£277m) - Interim Results - Paul - AMBER/RED
H1 results reflect the usual seasonal split towards H2. Growth has slowed, and it's spent the cash pile on acquisitions, which I'm not keen on. Overall this share never quite convinces me that it's any good, and the story is feeling rather stale now.
Finsbury Food (LON:FIF) - up 22% to 109p - Recommended takeover at 110p - Paul - AMBER
Management has agreed with 10% shareholder DBAY for a cash takeover offer of 110p. It doesn't look generous enough to me, so we'll see what happens - maybe DBAY will have to increase the bid, or someone else might gatecrash the party?
Trustpilot (LON:TRST) - up 16% yesterday to 96.45p (£404m) - Interims (ahead) - Graham - GREEN
An excellent interim report from this review site. Putting adjusted EBITDA mischief to one side, the company is not far off breakeven and has generated a meaningful amount of cash in the last six months. I remain positive on it, as the bull thesis is currently playing out.
Judges Scientific (LON:JDG) - up 4% to £92.49 (£612m) - Interim Results (in line) - Graham - AMBER
A solid set of numbers with strong organic growth and a very strong top line, thanks to the large 2022 acquisition. I remain neutral for valuation reasons, as continued success is priced in. The company deserves its rating but I still wouldn’t rush to buy at this level.
Warpaint London (LON:W7L) - down 2% to 298p (£230m) - Interim Results [in line] - Paul - GREEN
Strong interim results as expected, and management confirm they are comfortable with (previously raised) FY 12/2023 forecasts. I think there's possible upside on forecasts, so see a profit beat as being more likely than a profit warnings. There seems loads of growth runway, with international markets only scratched the surface so far. Strong balance sheet, good & growing divis, hands-on owner-managers, could this be the perfect GARP share?! Thumbs up from me again, as usual.
Paul's Section:
Naked Wines (LON:WINE)
Down 8% to 64p (£48m) - FY 3/2023 Results - Paul - RED
Naked Wines is the well-known, innovative wine subscription service than was meant to be all about connecting wine enthusiasts with small growers. I don't think the business model has ever really worked, and I’ve always rejected the company’s attempt to split the figures to pretend that its core customers are hugely profitable, and that growth spending (massive marketing costs) was somehow separate. That was (and is) nonsense, because of customer attrition - it has to spend heavily on marketing, to keep refilling the hopper, because it loses customers otherwise. I feel vindicated in this view, because it has more recently been forced to cut marketing spending, and surprise surprise, sales are now falling heavily.
It’s also spent almost all the customers’s cash on buying wines, whereas competitor Virgin Wines UK (LON:VINO) keeps customer cash segregated, which I think is much more prudent, and ethical.
Could WINE customers end up as unsecured creditors and lose their cash, if it goes bust? That looks one potential outcome to me.
I viewed WINE negatively RED on both 27 April, and 4 July 2023, and haven’t seen anything in these delayed results to change my mind.
Key points from my skimming of the results statement -
53 weeks to 3 April 2023 but for convenience I’ll refer to that as FY 3/2023.
Large adjustments to achieve a profit, it’s loss-making on a statutory basis £(15)m statutory PBT loss is the more accurate number for me, not the £17.4m adj EBIT.
The most concerning adjustment is an inventories write-down, either £10.3m, or £14.0m (two different numbers are mentioned) - ie being forced to reduce the carrying value of some wines to below cost. This could be the thin end of the wedge, and indicates to me the risk of a much bigger problem. It’s still massively overstocked. And of course even after inventories are written down, they’ll still only probably be sold at a negligible profit margin, so there’s a double hit to profits. I don’t like the way the company tries to gloss over this as “right-sizing”. It’s not, it’s bad buying of poor product, in my book.
Net cash crashed from £39.8m to £10.3m in the year. It should have £71m in customers cash ring-fenced, but it isn’t ring-fenced, a lot of it has already gone.
Current trading is poor - “slower than expected” revenues in Q1, down 18%.
Detailed guidance is provided, which I like, saying forecast EBIT of £8-12m for FY 3/2024. IF that is achieved, it sounds like the company might have bought some time to turn bloated inventories into cash - that’s the number one problem.
Inventories still forecast to be huge at £145-155m at 3/2024 year-end. There’s clearly been excessive, and bad buying here, that’s what worries me the most, and I think the bad news might be being drip-fed out, but only time will tell on that front.
£18.2m charge for other asset impairments.
Going concern statement is a red flag - “material uncertainty” - so this has to be treated as very high risk.
Balance sheet net tangible asset value of £84m sounds healthy, but how much of that is real, if it turns out that the £166m inventories is full of poor wines that can’t be sold?
Paul’s opinion - I’m pointing out fairly obvious negatives about this share that we’ve been aware of for a while now, so there’s nothing new in the figures.
The market cap is only £48m now, so I’m wondering if there’s a chance a turnaround here might create a multibagger? It strikes me that the former founder, who returned to try to save the company, is doing sensible things to turn it around, and there’s a chance he might succeed. So I wouldn’t completely write this off. My hunch is that more inventory write-offs could be needed, and the clock is probably ticking on the necessity to turn their wine lake into cash, and prevent any more ruinous buying commitments (note the comments that it needs co-operation from major suppliers).
The additional problem is that I don’t think there was ever any evidence of this being a good business in the first place. It’s never really made any money from the Naked Wines business (the original, disposed business was cash & carry Majestic Wines, which was sold off).
I’m happy to keep an open mind, and look out for early signs of a turnaround, but I don’t see anything credible on that front yet.
Good luck to them though - it’s easy for us to criticise, and sit in judgement, but much harder to deal with battling to sort out a problem business. I just don’t want to risk my own money on the outcome here.
Big Technologies (LON:BIG)
Down 6% to 216p (£628m) - Interim Results - Paul - AMBER
This is a new share for us here at the SCVR. It floated in Sept 2021, selling remote monitoring software/hardware, specialising in healthcare and criminal justice. “Buddi” seems to be its main brand. It was founded in 2005 by Sara Murray, CEO and largest shareholder at 25% today. Uses include monitoring where elderly people are, if they’ve had a fall, etc. My immediate thought with that, is whether it’s old technology now that could be replaced with smartphone apps perhaps?
EDIT: There's a more useful description of the business in the reader comments here, from FeatheredCapital, who says that BIG's business is now almost entirely focused on tagging for criminals, and it's winning business internationally too. Thanks for taking the trouble to post this, very useful.
Interim numbers look quite good - this is a highly profitable, and cash generative business.
Key figures -
H1 adj EPS 4.3p, expecting an even split for FY 12/2023, so c.8.6p? That would put it on a punchy PER of 25x.
Outlook - good H2 visibility from recurring revenue streams. “Lower end” of market forecasts doesn’t sound good enough to me, to justify the valuation -
Assuming no further strengthening in sterling over the second half of the year and no new contract wins, the Board expects the Group to deliver full-year revenue of approximately £54m with an adjusted EBITDA margin of around 60%, which is at the lower end of current market expectations(1).
(1) Latest company compiled view of market expectations show adjusted EBITDA of £32.7m to £34.7m (stated before share-based payments).
Litigation claim is mentioned, re 2018 acquisition.
Share options charge is an outrageous £5.5m in H1 alone! Maybe if management could keep their hands out of the till, the valuation might look a bit more attractive?
Statutory PBT of £9.0m in H1.
Very strong balance sheet - c.£100m NTAV, including a growing £76m cash pile, with minimal liabilities. So it clearly has plenty of options for acquisitions, etc.
Good cash generation.
Paul’s view - just an initial quick look, and I like the figures - this is a decently profitable, high margin business, with pots of surplus cash. Is it worth £628m though? Probably not, is my initial reaction, but that’s just based on a desktop review of the figures, not any deep dive into the products, competition, etc.
Zeus reckons there’s scope to beat its forecasts with new contract wins, which would bring down the PER from a rather-too-high 25x to something more reasonable perhaps.
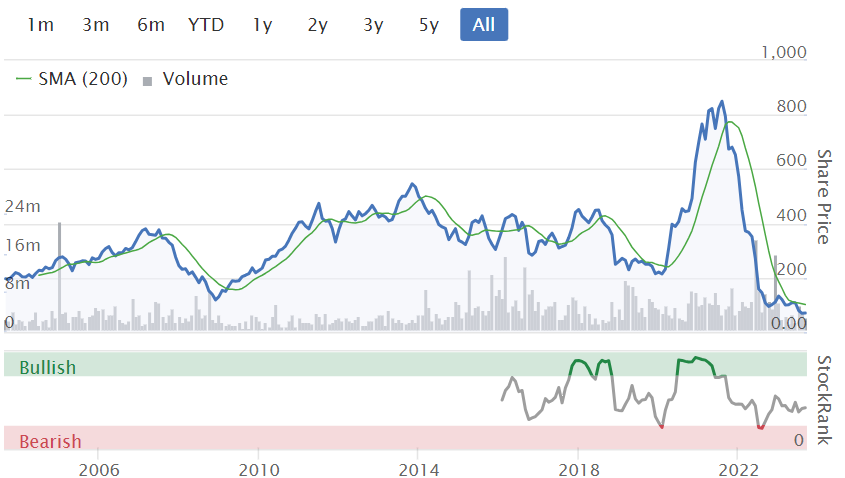
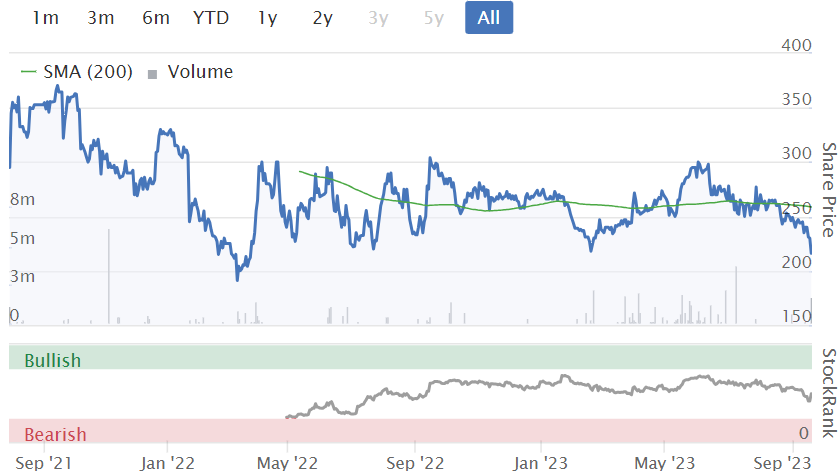
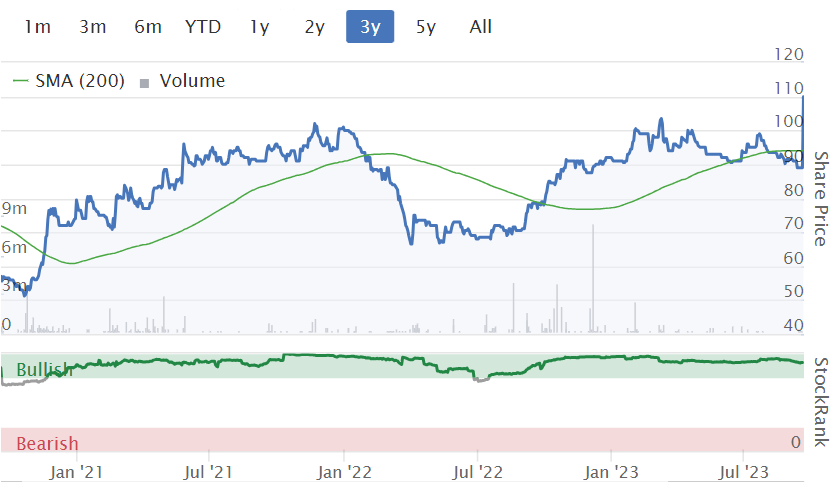
Downward trend since listing in Sept 2021 - and still not cheap -
accesso Technology (LON:ACSO)
Down 11% to 658p (£277m) - Interim Results - Paul - AMBER/RED
A quick review of these interims leaves me underwhelmed. Growth has slowed, and overheads have increased (which it annoyingly tries to present as somehow positive!). Outlook comments say it’s trading in line with FY 12/2023 expectations, and remember that there’s been an H2 seasonal weighting in the past, so the small H1 statutory loss doesn’t alarm me. Figures have always been difficult to interpret, too many adjustments and little sign of genuine profits historically I think.
The worst thing is that the previously super balance sheet has been damaged badly through 3 acquisitions, taking net cash down from $65m to only $9m. Fine if they’ve spent wisely, but only time will tell, and doing more acquisitions does make me worry that there may not be much faith in the core business perhaps? NTAV is now down to only c.$20m.
Paul’s opinion - I can’t see anything much of interest here, and the story is now very stale I think. So I’ll shift down a gear from AMBER, to AMBER/RED, to reflect the weakened balance sheet from yet more acquisitions.
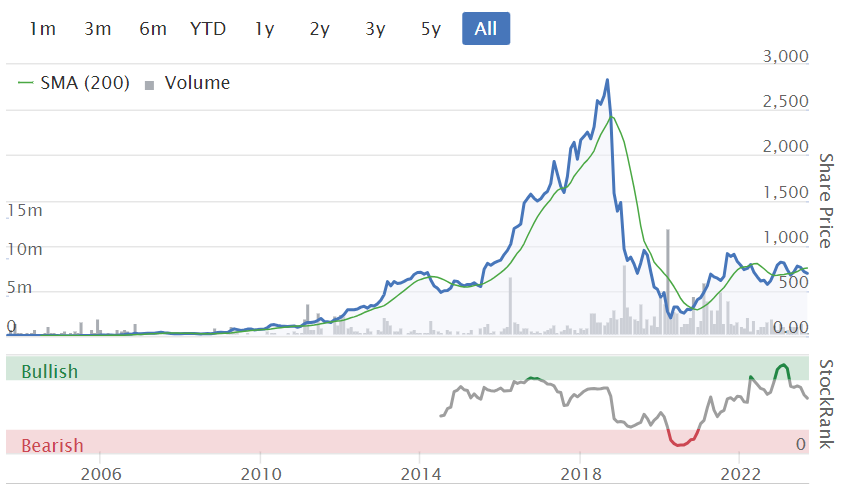
Massive multibagger originally, but a lot of it turned out to be hot air -
Finsbury Food (LON:FIF)
Up 22% to 109p - Recommended takeover at 110p - Paul - AMBER
We quite like FIF here at the SCVR, usually being mildly positive about it, but it’s a boring share that never seems to go anywhere. Not a bad business though, making cakes for supermarkets and cafes, but lowish margin. It seems well managed.
Management has reached agreement with existing 10% shareholder DBAY Advisers for it to take over the whole company at 110p cash. Not a blowout offer, the norm is for 30%+, this is only about a 24% premium on last night’s closing price.
Although the announcement does point out that it’s a 55% premium to the last date before DBAY’s interest was announced, on 2 Sept 2022.
Still, a forward PER of only 8.3x last night, was hardly including much of a bid premium in the valuation, but FIF has always been cheap.
DBAY says it wants to accelerate growth through acquisitions, as a private company.
The deal only has lukewarm 14.3% support so far.
Paul’s view - I think DBAY has pitched this too low, and might need to sweeten the deal to 120p+ to get it voted through, but time will tell. You have to remember that institutions often like a takeover, as it’s a liquidity event that enables them to sell, whereas in an illiquid share they might otherwise be stuck with it, unable to sell. Whereas we private investors can enter & exit much more readily, a key advantage we have over fund managers.
There’s the possibility of a higher competing offer, now FIF is in play. Or if you want to play it safe, there’s the option of selling some in the market now for 109p. Your money, your choice, as we always say!
Warpaint London (LON:W7L)
Down 2% to 298p (£230m) - Interim Results - Paul - GREEN
This owner-managed makeup company is one of my favourite GARP shares, which we’ve been raving about here for a while now. There have been several big upgrades to forecasts this year, and I think it looks set to possibly beat even these increased FY 12/2023 forecasts, as it comes into the seasonally busy autumn/winter season.
Thank you to management for squeezing me into their morning Teams/Zooms, which gave me a chance to ask a few questions, which I’ve included in my notes below.
H1 revenues £36.7m (up 46%) - seasonally slower half
International is now 64% of total revenues, and growing faster at +58%
Expecting H2 weighting as usual - which I reckon could mean the 14.4p EPS forecast from Shore could be beaten (as 6.5p already achieved in H1). A profit beat seems more likely than a profit warning, is my view of these numbers.
Gross margin of 39% is nothing special, but I asked management about this, who replied that they spend very little on marketing compared with other brands with higher margins, so it balances out fine. It's value for money product, not fancy high end stuff that needs big marketing budgets.
Net cash of £7.1m, and a lovely strong balance sheet as always - as we typically see at owner-managed businesses, who don’t tend to take the risks that hired hands often do with empire-building sprees fuelled by debt.
Current sales growth is similar to H1, with the 8 months sales up 45%
Supply chain and inflation - all sounds under control, some additional costs coming through, but they’ve put through selling price rises I think.
Strategy is to keep targeting big retailers. Trials with Superdrug and Boots in the UK mentioned as having good growth potential. All started with the Tesco deal initially 50 stores, which grew to 1,400.
Previously seen as discount products, W7L and Technic have now become brands in their own right, and are sought out by customers, so can be more picky about which retailers they’re sold in.
Affordable brand, so appeals in a cost of living squeeze.
I commented that despite the impressive growth, the numbers are still quite small, considering growth is now international. Surely there’s a massive potential runway for growth? Yes, management agrees, huge growth upside long-term.
What could go wrong? Unexpected events happen, as we’ve seen with covid, Ukraine war, supply chain disruption, etc. Business model has proven very resilient - in particular conservative balance sheet means going concern is never a problem, even if sales go to zero for a while. Also they keep plenty in stock, so can deliver for months, even if shipping disrupted.
Online - good growth but quite small. Could grow faster, but margins are better through retailers I think was the gist of what they were saying.
China - started selling direct online there, and starting to gain traction, quite unusual for a UK brand.
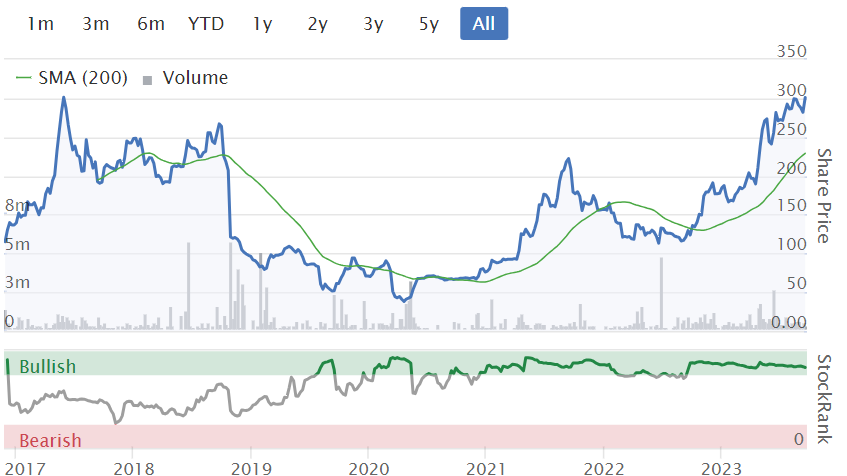
Paul’s opinion - the share price looks up with events at 300p, but I reckon we could see another beat against forecast later in 2023, and the long-term investment case here is so strong, I think the price is fully justified.
Hence I’m going to stick with GREEN.
Why on earth didn’t I buy any myself, as it’s been one of my favourite GARP shares for a long time now, and the results & forecasts keep getting better and better!? Oh well, never mind. I’ll pick up some shares at some point, for sure.
Management always really impress me, as what I specifically look for - hands-on, down to earth owner-managers. No fancy talk, just delivering on their strategy. Look at how little the share options are too - this puts many other companies to shame. And they pay generous divis too, so the growth is all self-funded, whilst spewing out nice divis along the way. I genuinely can’t see any problems with this, W7L seems an almost perfect GARP share.
I suspect that with patience, this share could be moving to new all-time highs in future.
Graham’s Section:
Trustpilot (LON:TRST)
Share price: 96.45p (+16% yesterday)
Market cap: £404m ($499m)
This well-known review site has been catching my attention recently - see our review of the H1 trading update in July.
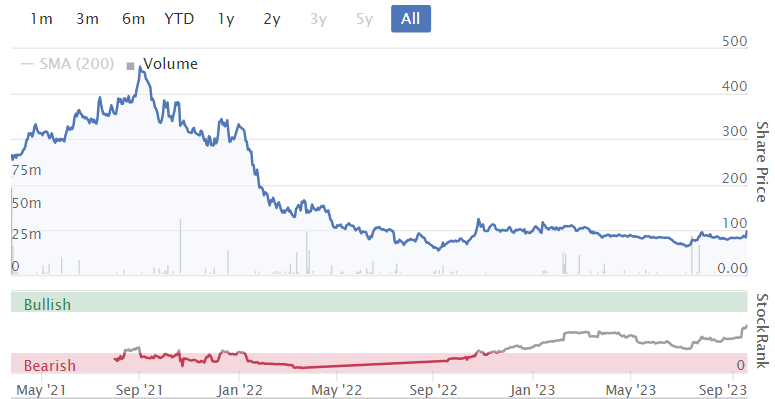
The share price is up 50% from its low in July, but it remains far below the valuation at which it floated in 2021:
Yesterday we had H1 results for June, with raised expectations for the full year. The headline numbers were already known:
Revenue +18% at constant currency to $85m
Annual recurring revenue +21% to $180m
Adjusted EBITDA comes in at $5.7m, vs. $3m expected.
However, the company also provides an adjustment to its adjusted EBITDA!
They say that due to improved profitability, accounting rules now allow them to capitalise the sales commissions paid to their employees, and they have done this in H1 2023.
They say that if you don’t exclude these commissions, then EBITDA was really only $3.4m.
So on an apples for apples comparison, I don’t think they have beat the expected EBITDA number by all that much.
The cash flow/profit numbers are simpler to understand and do impress me:
Free cash inflow of $6m (vs. $13m outflow in H1 last year)
The statutory net loss reduces to just $2.5m (vs. $9m in H1 last year)
The company’s net cash has increased from $73.5m to $82.7m over six months.
Business highlights - there are now 106,000 active domains (up 13%) and the number of monthly users rose to 52 million (H1 last year: 42 million).
The company’s new CEO has just finished his first week in charge, as the Founder wished to take a backseat and become a NED (the Founder is however currently missing from Trustpilot’s Board of Directors page).
Outlook: Trustpilot gave a revenue warning at the start of this year, but they have been very pleasantly surprised by progress since then, especially in Q2. “This positive trend has continued into Q3”:
Consequently, we maintain our outlook for mid-teens constant currency revenue growth for the full year but, with further operating leverage in H2, we anticipate that adjusted EBITDA (before the impact of capitalising sales commissions) will exceed the current range of market expectations.
I have found one analyst note published yesterday morning, and it suggests adj. EBITDA of $6.2m in the current financial year (back in July, the expected range was $2.4m - $4m).
Plans for future dividends and buybacks?
The company doesn’t specifically mention dividends or buybacks. However, now that it is profitable, and given that it has a very healthy cash balance, it is able to start thinking about what it might do with excess capital:
Trustpilot has a strong balance sheet and the business is now cash flow positive. As we consider our capital allocation policy, our priorities include continuing to invest in people, innovation and go-to-market to drive organic top-line growth and retention. We also aim to maintain the flexibility to engage in targeted M&A, assessed against rigorous returns criteria, to accelerate our product strategy or to strengthen our presence in specific regions. We are committed to returning excess capital, not required for other priorities, to shareholders.
Graham’s view
I did believe that Trustpilot was undervalued, but at the same time I’m surprised that the market saw fit to increase the share price by 16% yesterday. The adjusted EBITDA beat does not seem very impressive to me, considering the change in accounting treatment.
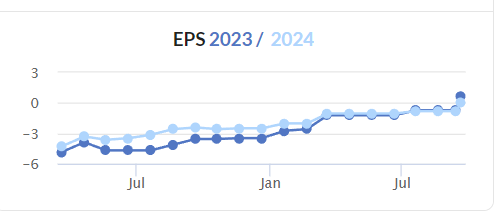
On the other hand there is no doubt that the company is experiencing nice momentum in earnings estimates. And its cash flow and profit metrics are much improved on last year.
Here is the very helpful earnings estimate chart from the StockReport:
When it comes to valuation, enterprise value is now around $420m, give or take. With $180m of ARR, that’s an EV/ARR multiple of only 2.3x.
A quick search suggests that US software companies are currently trading at an average EV/ARR multiple of around 6x-7x.
I view Trustpilot as being of higher quality than the average software company, due to its brand name recognition and the lack of meaningful competition it faces. So for me, it doesn’t make sense that it should trade at a cheap ARR multiple.
The fact that it’s now cash-rich and approaching breakeven reduces the risk. In summary, the bull thesis is playing out and I remain positive on Trustpilot!
Judges Scientific (LON:JDG)
Share price: £92.49 (+4%)
Market cap: £612m
Judges Scientific, the group focused on acquiring and developing companies in the scientific instrument sector, announces its unaudited interim results for the six months ended 30 June 2023.
We reviewed the corresponding H1 trading update from Judges in July.
Key points:
Organic revenue up 16.5%
Revenue up 32% to £61.3m
Adjusted PBT +33% to £12.8m
Cash generated from operations +40% to £11.5m
Statutory PBT £0.8m (H1 last year: £3.9m)
The reopening of China after lockdown policies ended appear to have played a big role in the positive result.
M&A: after the £80m acquisition of Geotek last year, its largest ever, Judges chose to take things easy on the acquisition front. It spent less than £4m on acquisitions in H1 2023. I do like to see companies spend a little time digesting large acquisitions, before they move on to new ones!
Outlook summary:
Business environment still in recovery mode.
Strong second half anticipated for the Group due to the timing of the next Geotek coring expedition.
Strong H1 Organic order intake and solid Organic order book (21.4 weeks at the end of August) augur positively for H2.
The Board expects that the Group will meet market expectations for the full year.
The Chairman also write a longer outlook statement later in the report, highlighting the need to “sharpen our acquisition discipline” in the face of higher interest rates and higher inflation.
Estimates: Multiple brokers are now covering this stock: Shore Capital, WH Ireland and Liberum. I’ve chosen Shore Capital at random and can confirm that their adjusted PBT estimate for the current year is £31.6m, with adjusted EPS of 368.1p.
Note that this implies nearly £19m of adjusted PBT in H2, much higher than the result in H1 (£12.8m). This goes back to the lumpiness of Geotek’s business, which had been flagged in advance of the acquisition.
Excerpt from the Chairman’s comment:
"During the period all the measures of Organic performance were again beaten, with results bolstered by the contribution from Geotek. While we have not yet returned to a pre-pandemic trading environment and we continue to operate in a challenging world, we have seen improving prospects across our markets.
Graham’s view
I have taken a neutral stance on this one for valuation reasons:
While I remain a long-term fan of Judges, it would be remiss of me not to mention that the company has posted a statutory loss in H1, if you don’t allow for the various adjustments it has made to its numbers.
Adjusting items in H1 2023 add up to £12.4m, up from £5.2m in H1 2022 and higher than the entire adjusting items for all of 2022.
They include:
£6.1m of amortisation.
£5.5m relating to the issue of shares for the purchase of Geotek (the Judges share price rose after the deal was agreed; therefore the value of the shares being issued rose, and this must be reflected somewhere in the accounts).
I can happily treat the second item as being exceptional in nature, but the first item is more debatable.
For what it’s worth, the cash flow statement shows after-tax cash generation of about £7m (there are many ways to do this, but I use operating cash flow minus investing cash flow minus lease payments, ignoring cash spent on acquisitions).
That £7m figure is not far from what you would get if you took the adjusted PBT figure (£12.8m) and added back in the cost of amortisation (£6.1m).
So for me, the “real” earnings in H1 was about £7m.
H2 should hopefully be much stronger again, but I feel I’m left with little choice but to maintain my neutral stance on this one for the time being. At a market cap of over £600m, its wonderful track record and acquisition process seem priced in.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Destiny Pharma (LON:DEST) Interim results: "XF-73 3 – 0 The competition"
There were few surprises in Destiny Pharma’s interim results as the recent achievements on its two lead Phase 3-ready products had previously been announced. We have made minor changes to our forecasts but none to our valuation as a result of the interims. Destiny’s new CEO delivered a polished and knowledgeable presentation only twelve days into the job handling analysts’ questions with ease and delegating to Destiny’s CFO and CSO where appropriate. We have delved into the details of the analysts’ meeting in the body of this note (see PDF below for full details). Link to research report: SEE HERE
Any Index watchers here? Where is FTSE 250 heading in the next few months? tia
Still in a sideways choppy move for now. MACD moved to buy 1st Sept, October uptrend held, still underwater with moving averages.
The big volume days have been down days. Could go either way, but im leaning more to positive side right now if we get through next 2-3 weeks. Any rally looks very tentative, so its definitely a stock pickers market for now.
If anyone wants a simple way to look for tops/bottoms, on say the AIM index (doesnt work well on choppy sideways moves) then a weekly chart with 10w and 20w moving average does a good job. Wait until it crosses. It lags slightly so wont pick the exact bottom but its reliable.
2008 - was 8 weeks into a rally when it crossed.
2003- crossed 6 weeks into a rally. Picked this one fantastic. Following this anyone should have been out all the way down for 3 years, then go long close to the absolute bottom.
This was the rally that followed in 2003. Monster rally with hardly a down week for 12 months.
Today- it picked the top well in Oct 2021. Had a false buy signal in February this year for 3 weeks tho. If it does turn and cross in the next few weeks it'll coincide with making a higher high which would be even better. Or it could continue down with the trend.
Intriguing charts Wolf - do you use same moving averages for individual shares??
I haven't tested it but suspect it may be a bit too slow on individual shares, which can move 20%+ in a week. Indexes move slower so this isn't so much of a problem.
Triggered a sell on S&P early 2022, then buy early 2023.
Hi Wolf from some of your previous posts i'm thinking there is a slight more tweaking with this do you use in these examples sma or ema and I seem to remember you pick the high price point of the day (memory foggy) does that also apply with these examples.
Regards Andy
Hi Phoenix. These are ema(closing price, not high) found they give less false signals than sma. DAX is close to triggering a sell signal now.
10 day average is what I use specifically for trend reversals on stock downtrends. It's high for the day, EMA. These are shorter term trades where I'm looking for a 15%+ pop in price when the trend changes. Best have a volume spike as well.
Pendragon (LON:PDG) (I hold) - news that Hedin + Penske have bid 28p for the whole lot - rejected by board news link
Interesting that they have rejected it as according to Zeus research note this morning the Lithia deal works out 27.4p
Will be interesting if Hedin come back with an higher bid (say 30p) which then puts the BOD into a more difficult position.
Yes I do hope so, from a personal perspective I would rather a complete cash take over not a structured deal as proposed by Lithia.
This is what I wrote on Monday ( Hedin had said they would sell their stake for 35p)
Here is the link to the 35p bit I referred too, Would be a seller of their stale at no less than 35p
Also something else I read from the trade press was that Hedin walked away due to a legal dispute regarding Pinewood Dealer software and Pinewood Technologies Asia Pacific Ltd. High Court hearings have commenced Case details Also I know Paul mentioned possibly buying into this to get hold of the Pinewood part of the biz but this link is worth reading as it says the deal is structured in such a way as to remove Pinewood from the deal...Hedin won't be able to block the deal etc
It does appear that as it is an asset sale and not a takeover a 51% majority is all that's is need but as Paul has already mentioned Zeus comments, it does look like they are getting the deal on the cheap, hopefully other shareholders push for a better price.
I for one would like a complete take over - surely if Pinewood was so great why leave it behind as a separate entity unless of course they are parking the litigation risk with it which would not surprise me at all.
Likewise I prefer capital gains to dividends so would prefer an outright buy. If it appreciates up to 28 or 29 I will be tempted to sell up and take 45% profit. Not bad for a three week holding. If only I could do that more often
I sold just under half my position today on the spike up after the news ( yes shame I can't do that more often too, I bought that lot end of July). I will probably wait on the balance in case this ends up with a mini bidding war.
spot the odd one out re. house builders
Bellway (LON:BWY) up 4%, Persimmon (LON:PSN) up 5%, Redrow (LON:RDW) up 3%, Barratt Developments (LON:BDEV) up 4%, MJ GLEESON (LON:GLE) up 6%, Crest Nicholson Holdings (LON:CRST) up 6%
meanwhile... Springfield Properties (LON:SPR) down 9% lol
it didn't participate in the house-builder rally in stock prices from oct 22 - mar 23 either
Springfield Properties (LON:SPR) - "Results in-line; Prioritising cash generation in FY24" (new research note here: https://www.equitydevelopment....)
Springfield’s results to May ’23 are in line with expectations, confirming a record year of completions despite a challenging market backdrop. Decisive action has been taken to reduce costs (£4m annualised savings) and the main focus for FY24 is cash generation, which should result in a meaningful reduction in net debt by the year end. Whilst the broader market outlook remains uncertain in the near term, we are encouraged by recent developments in Affordable housing (increase in Scottish Government Affordable Housing Investment Benchmarks) and remain confident in the Group’s long term growth prospects, which are underpinned by the large land bank and a very strong market position (top three builder in Scotland).
As of 31st May, the Group had 6,712 owned plots and strategic options over a further 3,255 acres (equivalent of a further 33,000 plots). The gross development of the owned landbank is c.£1.9bn, providing firm underpinning for long term shareholder value. We recently initiated coverage (An undervalued, high quality growth story) and continue to see scope for a material re-rating of the shares. Our Fair Value / share is 110p, based on an undemanding rating of 0.9x Price/ Book.
Ten Entertainment (LON:TEG) and Galliford Try Holdings (LON:GFRD) I hold
Impressive results from both this morning in my opinion.
Ten Entertainment (LON:TEG) I don't have a great deal add to the earlier informed comments by other Stocko members, only that I continue to remain puzzled by the anomalous valuation difference with Hollywood Bowl (LON:BOWL) .
Galliford Try Holdings (LON:GFRD) . I don't ordinarily invest in low margin business, but CEO, Bill Hocking has done a really good job since his appointment. The company operates two divisions, building and infrastructure. The former involved with the construction of schools, prisons etc. Infrastructure has a significant presence in the water industry and road construction/maintenance. Logic dictates that the company should be a beneficiary of the recent debacles regarding sewage discharges and raac concrete.
In this mornings prelims it announced that it has "Increased confidence in FY24 outlook, with pre-exceptional profit before tax expected to be at the upper end of the current range of analyst estimates."
Regarding the order book it added
"Frameworks, which provide good visibility of future revenue, amount to 82% of our order book (2022: 90%). Importantly, frameworks provide the certainty of a pipeline of work with repeat clients on established terms and conditions.
The Group started the new financial year with 92% of planned revenue secured for the 2024 financial year (2022: 90%)."
The final dividend is 7.5p which when added to the 12p special dividend gives a return of around 9% on last night's close.
Galliford Try Holdings (LON:GFRD) has no debt or defined benefit pension obligations.
Some potential negatives are that exceptional items of £10.5m were incurred in the year relating to ongoing investment in digitisation and that the large cash balance is mainly a result of advanced payment by clients. However the company is presumably earns interest on what is a sizeable amount.
I will conclude by observing that Richard Staveley, savvy manager of Rockwood Strategic (LON:RKW) investment trust, part of the Harwood stable has a sizeable holding in Galliford Try Holdings (LON:GFRD).
Fintel (LON:FNTL) H123 analyst presentation given yesterday video & podcast.
Pebble (LON:PEBB) half year results presentation from 5.9.23 video & podcast.
The results were slightly ahead of Canaccord's expectations.
Going forwar Facilisgroup should provide operating leverage and cash generation should increase as CAPEX is reduced.
Judges Scientific (LON:JDG) are hosting a H123 webinar this afternoon at 16.45. Presenting will be the CEO, CFO, COO and the New Business Development Director, just appointed. Register here.
Good results especially with the addition of Geotek to the 6 mths. Outlook in line with forecasts.
Rev £61.3 +32%
aPTP £12.8m +33%
aEPS 152.8p +23%
Organic rev +16.5%
Order book 23.5 wks
Here are recordings of other results presentations over the last few weeks:
Made Tech (LON:MTEC) FY23 results presentation by management video & podcast.
Rev £40.2m
GM 35.81%
aEBIDTA £1.5M
aPTP £1m
Contracted backlog £67.9m
Cash £8.5m
FY24 rev to be in line with FY23
SThree (LON:STEM) Q3 Trading Update presentation from yesterday video & podcast. Macro conditions are challenging. Net fee performance -7% against strong comparatives. Contract 84% group net fees. Lots of detail about the movement on contract and perm in the different geographies. Productivity is 38% above pre-pandemic levels. The contractor orderbook is flat yoy which together with net fees already recognised ytd gives 90% visibility of the FY consensus forecasts. The Technology Improvement Programme is on track and on budget and will drive scale and higher margins. This tech platform will provide a clear differentiation to their peers.
Of interest is the read across to the macro picture in different sectors, Engineering +20% strong across all regions driven by energy and particularly renewables which was up 28%. Technology -6%. Life Sciences -24% (both macro and strong comparatives) still ahead of pre-covid.
The announcement that Wincanton (LON:WIN) has finally got out of its historic pension trap deserves to be applauded. This company has been through the shadow of death and almost exactly 10 years ago (November 2013) , quite correctly, made the following comment on results.
“If you want to see a really awful Balance Sheet, then check out this morning's interim results from Wincanton (LON:WIN). Net assets are negative to the tune of £275.1m! Deduct their £110m intangible assets, and you're down to negative £385.1m!! In any previous Recession it would have been put into Receivership, in my opinion. This time it's all been distorted by Govt policy of encouraging Banks to allow zombie companies to continue trading. I think that is lulling some investors into a false sense of security.”
As it turned out management had the skill and grit to turn it around so my hat tip to them for today’s news. Many lessor teams could hardly have been faulted for throwing in the towel.
I should have said that it was Paul who made the Wincanton comment ten years ago.
Wincanton (LON:WIN)
In any previous Recession it would have been put into Receivership, in my opinion.
Huh - why would you ever put a profitable company paying its way into receivership due to wonky balance sheet? that would normally make zero sense unless creditors would get 100p in the pound. Its not uncommon for companies to go many years with past negative stuff on the balance sheet. As long as its making profit and can pay its way thats nearly always better than alternatives there was no need for receivership imho unless i was missing something?
Note perhaps board could have taken viewpoint it was better for them and their cosy salaries doing pre pack but that certainly would not have been in the interests of the shareholders.
Note i wouldnt use such strong wording ref the pension scheme ref todays news - imho the company is off the naught step (for now) - the calcs are only ever a snapshot in time though so one never knows if the positive news now might be reversed out in the near future. It is obviously brilliant news - presumably reading betwen the lines the pension company (rightly?) had them by the short are curlies and they now only agree to grab em there again if they slip back into problems?
Practicably speaking if thats swap from paying £25 pa to paying nowt thats huge cashflow boost to company near term. Thats one issue with the level of payments though - the reality probably is that paying nothing doesnt reflect the overall position very well if they may have to pay in future - similarly paying £25 mill pa was probably making it look worse than it was if it was obvious payments of that level would not be needed forever. Shareprice reaction seems muted - but presumably good news had to arrive if it was a gioven deficit was being tackled aggressively.
Hi Paul
As you are speaking with Warpaint London (LON:W7L) shortly perhaps you could ask them about the following from the"Summary and Outlook" section of their H1 results...
"As in previous years, the Group's sales are expected to remain second half weighted, reflecting Christmas seasonal sales and ongoing sales momentum. We anticipate updating further on trading later in the year..."
Last year there wasn't a further TS until the FY one on 11-Jan-23. So are they committing to an extra TS between now and then?
Thank you Martin
Hi Graham, would appreciate your thoughts on Team17's (LON:TM17) interim results yesterday. You've helpfully covered them in the past and this update was a bit of a mixed bag. Whilst it didn't happen in one foul drop, the share price has shed about 10% since the results came out. I think the obvious takeaways might be the right ones (overheads increased which is bad. Management suggests this is partly due to timing which we need to see play out. Cautious outlook for H2 but they believe this is de-risked by good top line performance in H1. Why no finance income!?!) Thanks!
Team17 (LON:TM17)
The detail that prominently caught my attention, a point you alluded to in your post, is the sharp decline in gross margins: falling from 48% in the first half of last year to 43.3% this year. A look back to 2017 reveals that this is the lowest the margins have been up until now.
In a recent update, the board emphasized its anticipation to deliver full-year results that align with the current market forecasts. However, pinpointing the consensus on these expectations has proven to be difficult. A glance at Stockopedia shows an estimated EPS of 26.2p for 2023, contrasted starkly by the 3.9p EPS in the first half of 2023.
The management’s commentary on the market landscape does not instill confidence, highlighting a persistent high level of competition in the marketplace. Interestingly, they project an improvement in gross margins in the second half of 2023. Despite this anticipated improvement, I find it challenging to see how it could sufficiently bridge the substantial gap between the H1 2023 EPS and the projected annual EPS.
As of now, I do not hold any shares in the company and plan to remain on the sidelines for the time being.
Warpaint numbers and prospects look good to me. I like Sam he seems to be a straight hitter, worked up from the bottom so knows the business inside out. I wonder if there is a turn down in economies whether make up would suffer badly. All in all a rare find this stock, priced about right for now.
I saw this as the classic defensive option. Offering a wide range of relatively modestly priced product, which brings instant feel good to the user. A recession winner?
'The Lipstick Effect'
A well known concept, been recognised for years, whether it has any truth ? Probably. Although Warpaint's offering is not luxury.
The lipstick effect is the theory that when facing an economic crisis consumers will be more willing to buy less costly luxury goods. Instead of buying expensive purses and fur coats, for example, people will buy expensive cosmetics, such as high-end brands of lipstick.
Hi Paul,
Big Technologies (LON:BIG) I thought I would clarify a few points on Big Technologies:
99% of Big’s revenues come from the criminal justice sector. Monitoring elderly people, which is where the group started, is effectively irrelevant.
The electronic tagging market looks set to grow at 10%+ over the coming years. The main drivers of this are worldwide prison overcrowding and the technology being better than it used to be.
This is not something that can be done by smartphone apps as you have mentioned. This monitoring often involves ensuring that some very bad people don’t go to places where a court has ordered that they cannot be – unfortunately, this is about as bad as you can imagine. The data from the tag will need to stand up in court if there is a breach. The technology is therefore mission critical and must not fail.
Big’s technology is currently regarded as the best in the market – it is lighter, smaller, has a longer battery life, lower recharge time, faster install and (most importantly) the best location technology. The location technology is absolutely critical as not only does this help keep bad people in check, but it also means less false alerts/ callouts for the police. Every time there is an alert the police have to attend and this extremely costly. For example, it is extremely costly if the police are called out just because the person enters a building with no signal. Big now do all of NZ’s tagging and monitoring and have saved the government millions.
Big have multi-year contracts all over the world and as you can see from their revenue growth they have been taking market share rapidly. At the moment, we are all waiting for a huge decision from the UK ministry of justice which should be announced over the next few weeks. It is to do all of the UK’s electronic monitoring and is worth £20m a year!!! This will obviously impact the share price depending on the decision.
Even if Big don’t win the transformational MOJ contract (I think they are in with a very good chance as G4S, the incumbent , were fined £44m for overcharging the government in 2020) there are a huge number of tenders to go after worldwide over the coming years. In addition, Big are about to launch their alcohol detection tag – some people are banned by a court from consuming alcohol! This market is worth well over $80m in the US alone and, once again, Big have the best technology.
Hi FeatheredCapital,
Thanks for the detail on Big Technologies (LON:BIG) - it sounds like their website is rather misleading, in focusing on tracking the elderly, if nearly all their business is now criminals, that should have been explained on their website.
The way you describe it, the company sounds a lot more interesting, thank you! :-)
Regards, Paul.
Looks like a decent enough acquisition from Journeo (LON:) announced this morning. Earnings enhancing but isn’t going to move the needle that much in its own right - maybe 5-10% increase. However, gives them a solid footprint across the Scandi region and an obvious base for expansion into Germany and Poland.
I like what this management is doing overall. Hopefully the share price can start to reflect some of that progress soon. It’s on what a PER of 7 for FY24?
Journeo (LON:JNEO)
I like the acquisition as a springboard into Northern Europe and to build out that runway.
Also have you seen the Cavendish note on Journeo this morning? They are forecasting a free cash flow yield of 20% for next year, that's tremendous.
Journeo (LON:JNEO)
Yes and cash conversion looks genuine at just under £5m next year to move to a net cash position of £8m
Given the market cap is only £30m that would mean 40% market cap is net cash and a PER of 7ish or sub 4 cash adjusted.
Feels too cheap but will be illiquid and probably therefore share price moves will be in steps followed by consolidation. Happy to hold here. I have a personal target of 400p+ over next couple of years fwiw. Would like a divi whilst I wait but outside of that I’m very comfortable with the holding.
Agreed on everything said. It's become a top 5 holding for me mainly due to its increase in Share price in the last year. I sometimes consider top slicing but management continue to be running the company in the right way so I continue to hold.
I'm happy to forgo any dividend as long as the share price continues to appreciate
MPAC (LON:MPAC) - Any followers/views here? Recent results weren't covered in the SVCR. Looks like a turnaround on the way:
Order intake of £62.4m (2022: £32.8m) contributing to a closing order book of £77.5m (30 June 2022: £62.6m; 31 Dec 2022: £67.2m)
Mkt cap £41m
EPS fcst 2023 26.9p followed by 37.9
P/Es 7.44 followed by 5.28
Pegs 0.182 and 0.413
"Current trading is in line with the Board's expectations and full year market guidance remains unchanged. Margins are normalising as anticipated and with a strong order book and prospects pipeline, Mpac is well positioned to deliver on the previously announced H2 weighting to the financial year, despite the challenging trading environment."
Last director buy was £25k in May at well above the current price of £2.
Yeah MPAC (LON:MPAC) appears to have traded through the trough of supply chain difficulties and successfully updated strategy to get what should be a very stable 35% revenues in servicing. That type of revenue is sticky and underpins the business.
Cash flow improved as inventory unwinds so a net cash position now. The fact the order book is up significantly also important.
The Freya battery storage business isn’t priced in at all. That could be hugely material but management are playing it down until it comes to fruition which is sensible.
1 year forward PER of 5 looks far too low so let’s see.
Taken an opening position MPAC (LON:MPAC)
I had a quick look at MPAC (LON:MPAC) after reading these bullish comments here.
Interim results - showed order intake up strongly.
Underlying PBT £1.9m, improved from £1.1m a year ago. OK, nothing madly exciting there.
Outlook - in line with expectations, forecasts unchanged.
Balance sheet is only adequate I'd say, not good. NTAV negligible, once you write off the false pension surplus, and intangible assets. Pension schemes actually in an actuarial deficit, requiring deficit recovery cash payments of £2m pa, plus admin costs. That's a large element of profit/cash generation spoken for.
This share got talked up unrealistically highly in 2020 & 2021, then seriously disappointed. So I think it needs to earn back credibility with investors. Given recent history of missing its numbers, I personally wouldn't rely on forecasts as being automatically achievable.
Probably priced about right for now, I'd say. The most interesting bit is the order intake growth, which could be pointing towards improved results in future, so one to watch maybe!
Regards, Paul.
MPAC (LON:MPAC) I hold for all the reasons you state eParo. It looks massively undervalued to me; all the underlying metrics seem to be spot on and the growth vs PE stratospheric. Decent balance sheet too. The Freya deal caused me to top up and with the continued pressure on the price vs progress on the ground I am looking to do so again. It looks like the market has slammed it for the dip in profit and won't relent until it has recovered - shouldn't be too long on these statistics.
Yet another potential recovery stock that feels very similar to Equals (LON:EQLS.
How do you get these writeups out so early Paul! Kudos.
A few interesting ones for me today that some others follow here
Assetco (LON:ASTO)confirms value of parmion and a strategic investment in their ETF business. Should be worth double the current price or more
Finsbury Food (LON:FIF) sold most of these at £1 but takeover today at £1.10
Shanta Gold (LON:SHG) results sound good? Any views. I'm not great at valuing mining companies but feels like worth materially more than current value, deleveraging
Tandem
Quick scan looks pretty bad .
Margin down
Cash down.
Stock down
NAV up due to property imcrease .
Starting to look and feel like a loss making / break even company that’ has spent all its money and reserves building a lovely warehouse .
Stock figure is key one here down to 5.9 million which looks pretty low for its turnover .
So how is it going to generate any cash ?
margin is through the floor ? Stock is low so no cash to be released from that ? Losing money ?
Feels like an asset property play now with a zombie business inside it ?
E- mobility seems to be doing well but if that grows needs financing but there’s no cash ?
All after a quick read .
Agreed - had been on my watchlist a while ago but couldn’t get quite comfortable with it fortunately for me. Results look horrid and outlook no better. Need a strategic rethink by looks of things
Joules built a lovely warehouse/offices, then went bust. Was that £20 million? Can't remember. Inspiration Healthcare spent a lot of time and money building new state-of-the-art offices/warehouse and the share price has tanked. It seems difficult for (some) management to keep their eye on the ball whilst developing premises.
Problem was Tom Joules pulled millions out and did a runner. I held.
Some years ago (well OK about 40 years ago) the US company Tektronix used to issue very human, lighthearted, commentary on their annual reports, often ruefully admitting their mistakes. On one report I recall the comment that ran something like, “ our new warehousing was built to handle our future growth, unfortunately the warehouses arrived before the future did”!
We could do with alot more honesty and wit in announcements compared to the vogue for no comment or subterfuge.
Wincanton (LON:WIN) report this morning that their Pension Scheme is in surplus and will not need any further contributions until the 2026 valuation, saving £23 - £25m per annum , I couldn't be further from a pension expert but it occurs to me that this might be a read across for others .
Any ideas from better informed subscribers?
It depends unfortunately. Each pension scheme will be invested in different assets with different liability matching and hedging, so whilst current environment should be overall positive for schemes I wouldn’t be inclined to read across from one to another unless you know the construct of the pension portfolio and can see direction of travel.
Generally, Interest rates up = liabilities down = deficits down
But not always.
And there may be a lag if the valuation is triennial.
Like PS says, dyor, you may find something good.
Finsbury Food
Looks like Dbay have made their move .
Looks a rubbish offer
I held for a while as there are sone smart cookies In the mix (LDG / d bay / Rockwood) but got bored as reading about cake and bread making was not conducive to my low carb diet .
Bid looks low and feels a bit of a cstitch up but just goes to show pays to keep an eye on some of the small cap hotshots .
Finsbury Food is being purchased by funds managed by DBay which I assume is Logistics Development Corp, which is trading at substantially below n.a.v. . Although I am attracted by the accelerated M&A activity planned for Finsbury (assuming the deal goes through) I don't plan to retain my stake as I am less keen on the "transformational" type of M&A which DBay says it is hoping to execute.
Looks like another microcap delisting today in the form of Brandshield Systems (LON:BRSD) - a serial loss maker who consistently brought out the begging bowl to continue with their growth strategy (i.e. keep the lights on.) The reasons cited are a lack of liquidity in the shares and costs associated with maintaining the listing (including the legal / admin burden.) Sir Terry Leahy was a significant shareholder and supported a number of raises, perhaps highlighting the further risk of a delisting when there is a shareholder like him high up on the list.
Warpaint London (LON:W7L) I hope you might have time to include their Interims today please
Record performance and good to get more detail on their US expansion (described as ‘significant’). Dividend increase shows confidence. I suspect some may be slightly spooked by the higher inventories as they gear up for the key H2 gifting season but these occur each year
I remain a happy holder
Another vote for Warpaint (LON:W7L) please. Basically what she said.
Yes, I always report on Warpaint London (LON:W7L) you don't need to request it!! It's one of my favourite companies & management. I've got a call booked in with mgt at 10:40, so will report back after that. They're doing webinars too I think, so will probably be the same material.
I have family living in China and every trip here they return with a suitcase full of makeup. The reputation of Chinese cosmetics is that ingredients are very suspect and everyone buys Japanese, Korean or western brands. I fancied Warpaint London (LON:W7L) when the shares were expensive but life got in the way when the price dipped and I missed the chance. Good luck to holders but I'm watching for another chance like Paul.
Another request for Warpaint London (LON:W7L) please.
On a quick scan this mornings numbers suggest around a 10% beat of expectations and with their large H2 weighting FY24 turnover will comfortably exceed £100m.
Warpaint London (LON:W7L) I hold. Stonking results. Not my normal type of company but I saw their presentation in Mello Chiswick in about May 22 I think. At that time everything was positive, including the amount of skin in the game of the senior management. They seemed to be approaching a pivot point and so it proved.
From this point they seem to have the platform to go for an enormous potential market. I suspect their quality (decent) / price (low-ish) mix will serve well over the next few years. If they can keep as good a control on the business going forward as they have to date this could continue in rapid GARP mode for years to come!
My morning smallcap tweet: Tandem's toy cycle hiccup
Finsbury Food (LON:FIF) Tandem (LON:TND) Dianomi (LON:DNM) Wincanton (LON:WIN) Ten Lifestyle (LON:TENG) Genflow Biosciences (LON:GENF) Crimson Tide (LON:TIDE) Hercules Site Services (LON:HERC) Capital (LON:CAPD) Pensana (LON:PRE) Quantum Blockchain Technologies (LON:QBT)
◄Finsbury Food (FIF)► rec offer of 110p, a 24% premium. [SP=89.5 Cap=117m]
◄Tandem (TND)► H1-June rev down 24% despite bike rev up 19%. Interim div 'postponed'. Warns FY rev 11-13% below mkt exp and underlying pretax B/E. Blames consumer squeeze and poor weather. "Toy sales, typically considered recession-proof, have slumped in Britain." [SP=200.2 Cap=11m]
◄Dianomi (DNM)► revises contract with publisher in light of low traffic. The amendment is expected to increase rev and profitability in H2 and beyond but in H1-June, it will resulted in a lower gross margin and adjusted EBITDA hit of £1m. [SP=54 Cap=16m]
◄Wincanton (WIN)► no further contributions are payable to 2026 into its pension scheme due to its being in surplus. Saves c.£25m (+ RPI rises) PA. [SP=246.75 Cap=307m]. I hold.
◄Ten Lifestyle (TENG)► guides FY-Aug net rev c.£63m up 35%, modestly ahead of market expectations. Adj EBITDA c.£12m, in line. [SP=98.52 Cap=83m]
◄Genflow Biosciences (GENF)► gets clearance to commence Phase I/II Clinical Trial of GF-1002 in NASH patients. [SP=2.05 Cap=6m]
◄Crimson Tide (TIDE)► wins 3yr mpro5 contract in US worth c.$72k with the expectation that this will grow following the initial rollout. [SP=2.3 Cap=15m]
◄Hercules Site Services (HERC)► Civils Projects div wins £3.1m of contracts. They "provide substantial opportunity for Hercules to cross-sell its labour supply and suction excavator services to blue chip clients." [SP=26.02 Cap=16m]
◄Capital (CAPD)► wins 3yr contract in Nevada worth c.$35m PA once all the rigs are fully operational from 2025. Also update on Ivindo Iron contract. [SP=80.4 Cap=156m]
◄Pensana (PRE)► gets £317k grant from Innovate UK under its CLIMATES programme. [SP=36 Cap=103m]
◄Quantum Blockchain Technologies (QBT)► update on porting Method A and Method B algorithms into commercial miners. [SP=1.21 Cap=14m]
I think after this morning's numbers only an idiot would continue to raise rates especially since recent large increases will not have filtered through yet.. We shall see. Building suppliers have been moving up the last couple of weeks in anticipation
Wolf, you can count on Bailey raising tomorrow then!
Judges Scientific (LON:JDG)
Another healthy set of numbers from Judges Scientific. Business continues to pick up post Covid, with some supply chain issues still remaining, requiring above average working capital, reducing cash conversion.
Organic revenue up 16.5% and overall revenue up 32%, as there was a full contribution this half from the Geotek acquisition and 2 smaller acquisitions. Guarded optimism for the future, with a stronger H2 expected, due to Geotek coring activity occurring in H2.
ROCI slightly down, due to increased equity following the Geotek acquisition. They expect to meet expectations for adjusted EPS for the full year and increased dividend by 10%.
Steady as she goes here. An impressive management team and the Geotek acquisition seems to have been a good one.
Any comments welcomed.
Well, it made a loss; which is missing from your note and their spiel.
Finsbury Food (LON:FIF) - ungenerous bid from DBAY this morning. They only hold 10%. Tempted to hold on as if bid is defeated / withdrawn, downside risk is minimal
Warpaint London (LON:W7L) I hold
Cracking interims - CEO says:
"I am delighted with the Group's continuing strong performance in the first half of 2023, with a record level of sales and profits delivered. I believe the Group is very well positioned to achieve further growth and I remain confident that margins can be maintained going forward.
"Warpaint is a global business with the capacity, expertise and strategy, coupled with balance sheet strength, to drive future growth from both our existing and new customers. Whilst we continue to experience good growth in the UK, I am particularly pleased with the growth we are seeing in Europe and the US. As in previous years, the Group's sales are expected to remain second half weighted, reflecting Christmas seasonal sales as well as ongoing momentum.
"We look forward to updating further as the year progresses, and with significant opportunities for continued growth, both already secured with our existing retailers and in discussion with additional major retailers globally, I am confident that the Group will continue to perform well for the remainder of the year and beyond."
£TEN
Another positive update from ten today they keep delivering operationally giving punters something decent at decent prices. One would expect if things were going to get super tough that would start to happen now. Perhaps they are benefiting from under capacity in sector at present - if they and and others keep expanding could we end up with an excess capacity at some stage ? That’s the main danger to me - main thing is they seem to be giving customer decent experience by investing some of cash flow back in sites keeping them modern.
Positive news ref energy prices too hopefully that’s good sign for all.
We have secured energy cost security at sustainable levels beyond our current contract out to the end of September 2026. These factors give us the ability to drive modest profit growth from our underlying like-for-like sales growth.
Very good update from Ten Entertainment (LON:TEG) . what I liked is that the market was clearly pricing for a bit of a downturn yet the 2nd half has accelerated with like for like sales +12.8%. That should drive strong profitability and clearly demonstrates the value in a difficult market. They are net cash and going to be trading close to 40p EPS with a very clean business. A PER outlook of just 7 looks pretty miserly
Ten Entertainment (LON:TEG) presumably?
Positive sounding update with adjusted PBT marginally ahead of H1 2022 although PAT lower due to one off benefits last year. Positives include energy price security as mentioned above plus inflation costs being managed prudently and in the rear view mirror.
Full year revenue expected to be at top of guidance range. Harwood Capital hold just under 16% and Stocko shows it qualifies for a couple of shorting screens.....make of that what you will
Hi Sutters - Stocko screens have been suckered by leases which now show up as net debt when in actual fact the company has net cash. It’s a perennial problem. Such a rubbish accounting standard but hey Ho!!!
Ten Entertainment (LON:TEG)
Yes sorry not enough coffee first thing and couldnt work out how to edit on my ipad.
Stocko shows it qualifies for a couple of shorting screens.....make of that what you will
That proves that the basic Altman screen is sometimes a heap of crapola and not fit for purpose. I can only presume that the nonsensical lease liabilities somewhat affect the calcs. This company is in rude health and has zero financial worries - any screen or calc saying otherwise is talking as much sense as alexa when its respondig to a scots person. Not even sure the company does actually fail the test either - stocky has summary figure well over screen threshold quoted - 2.38 v 1.8.
Both screens penalise the company on altman - the James Montier Screen is slightly more interesting in that the company is also being penalised for having earnings well above the historical average (doing well in plain terms!!) - thats fair comment we have seen many companies make hay over covid only for earnings drop away - in some respects Ten Entertainment have had a purple patch so that wouldnt be a surprise if they reverted to the mean a bit. The test of time will sort this issue out - the longer the company keeps delivering the current level of earnings then the more teh James Montier screen will back down and say these earnings are sustainable. Its 6 year average here so realsitically speaking is current year estimated of 30p eps ore eps 6 years ago of 5p more relevant - James Montier is looking at ten figures 6 years ago and presumably ignoring the current year estimates !!!
Facts are calendar year earnings (annoying 1st jan ye !!) 2022 (1/1/23) 2023 and 2023 are/ are expected to be 30p each year plus - compared to 3 prior years of 6p 15p 18p. factoring in this year and next year cape calcs looks to be decently under 15 whereas the screen currently shows 42 (presumably based on historical figures) - i would expect ten entertainment would exit this screen soon (next years financials perhaps?) as long as they hit current targets and all other things remain equal. In some respects earnings could dip 1/3 below expecvtations and the new would beat the old in this regard.
Fire the cannons on the new bull market! Big beat on inflation , especially core suggests this is the top of the interest rate cycle after Andrew Bailey's recent comments. Inevitable recession to follow but markets bottom before the recovery...
Epwin (LON:EPWN)
Very robust set of figures from Epwin - unlike many others around them they seem to be holding their head above water - that might be due to acquisitions but they have sufficient cash flow to allow them to pay for minor add ons as they go. Shareprice suggests this is still a very much unloved company that no one wants to own hey ho.