Small Cap Value Report (Weds 25 Sept 2024) - OTB, WATR, TIME, BIG, EMAN

Good morning from Paul, Graham & Roland. We have a full house today! (as I [Paul] have to finish early, to swap AirBnBs here in Malta). It's working remotely, rather than a holiday - you need a change of scene every now and then, after working from home for the last 22 years!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
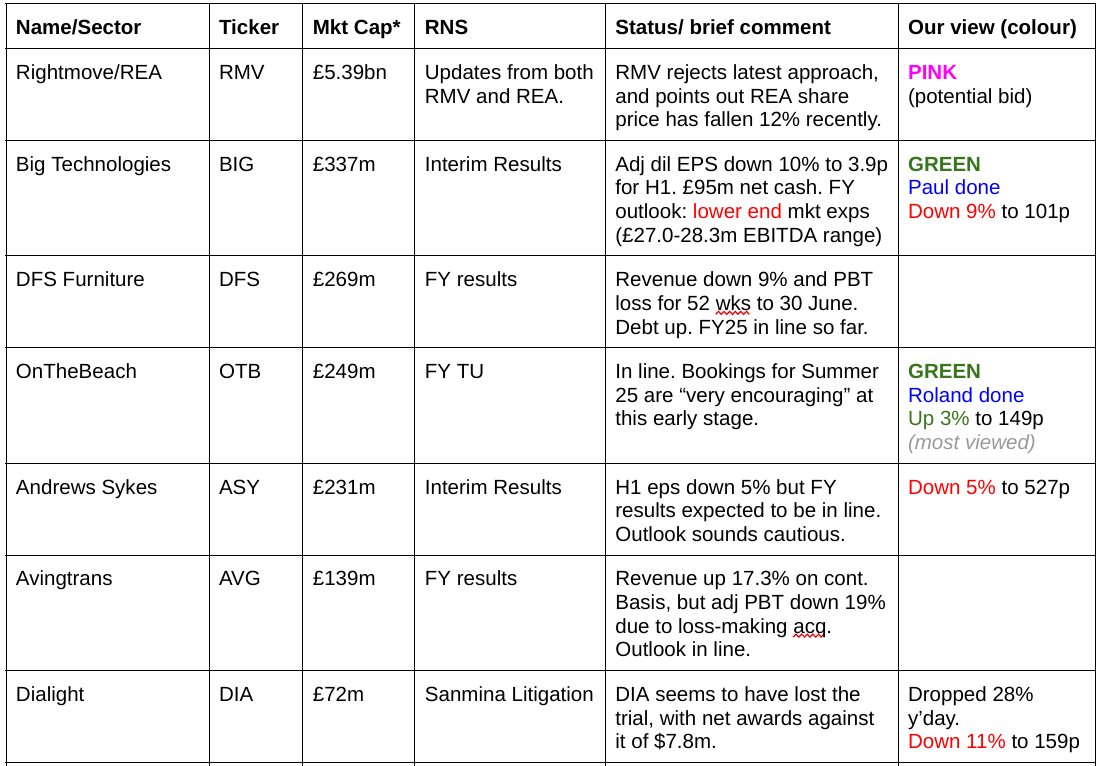
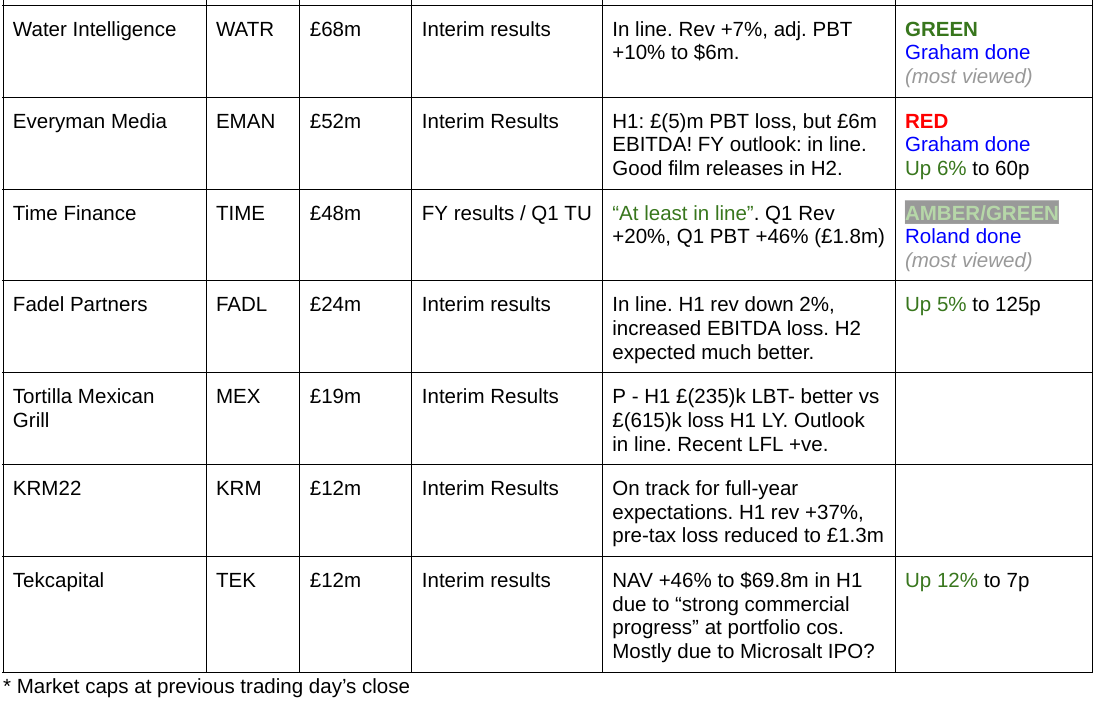
Summaries
On Beach group (LON:OTB) - up 3.3% at 149p (£249m) - Pre-close trading update - Roland - GREEN
This online travel agent appears to have had a strong finish to the year, with adjusted PBT up by 31% and an improved year-end net cash position. The pipeline of forward bookings appears positive, albeit it’s still early in the year. OTB shares look decent value to me, given the improved profitability implied by today’s trading update. I remain positive ahead of December’s FY results.
Water Intelligence (LON:WATR) - up 5% to 405p (£70m / $94m) - Interim Results - Graham - GREEN
I’m giving this a negative outlook when it comes to my stance on it! WATR has posted good interim results, in line with expectations and including a 10% increase in adj. PBT to $6m. However, to keep my positive stance on this share, I need it to do a little better when it comes to underlying sales growth (currently just 2%) and its quality metrics.
Time Finance (LON:TIME) - down 2% to 55p (£52m) - Final results / Q1 trading update - Roland - AMBER/GREEN
I’m encouraged by progress at this SME specialist lender and believe the valuation looks reasonable. This turnaround story gets a cautious thumbs up from me and appears to be gaining momentum into FY25.
Big Technologies (LON:BIG) - down 11% to 99p (at 09:10) - £287m - Interim Results - Paul - GREEN
Almost, but not quite a profit warning today - at lower end of a fairly tight EBITDA range for FY 12/2024. Amazing balance sheet with about a third of the market cap in genuinely surplus cash, persuades me to take a positive view of risk:reward. Although bears might say it's now looking ex-growth. It's a high margin niche, and orders could be won for its innovative new devices (eg alcohol sensing tags). The price has come down a lot, and I find it more attractive value now.
Everyman Media (LON:EMAN) - up 6% to 60p (£55m) - Interim Results - Graham - RED
The outlook is in line with expectations for 2024 and the company warns that growth in 2025 might be lower, as it keeps its expansion plans limited. The market has treated this news positively, perhaps because of concern over the growing net debt position (£26m). Given its lack of real profitability, its capital intensity and its failure to demonstrate economies of scale up to this point, I see this a poor investment proposition.
Paul’s Section:
Big Technologies (LON:BIG)
Down 11% to 99p (at 09:10) - £287m - Interim Results - Paul - GREEN
Starts off with a nice simple explanation of what they do -
“Big Technologies PLC (AIM: BIG), the leading, integrated technology platform for the remote monitoring of individuals, is pleased to announce its interim results for the six-month period to 30 June 2024 (the "period").”
The main markets are international, re law enforcement, tagging of offenders, but it also provides services for monitoring of elderly/frail.
Shares have done really badly, since being one of many opportunistic & over-priced IPOs in 2021. Are they now in value territory, I wonder?
Today’s news is a mild profit warning alongside not very good H1 results.
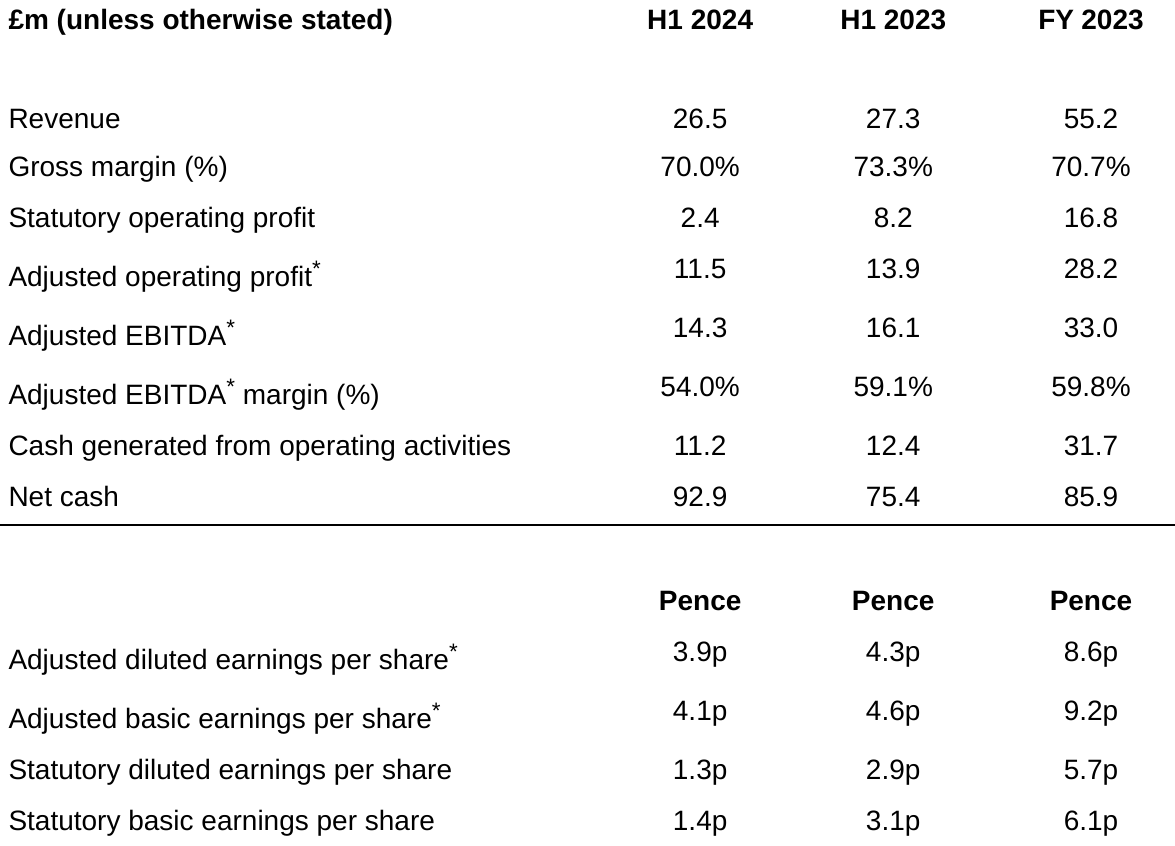
H1 headlines don’t mention my preferred measure of adj PBT unfortunately - but does include adj dil EPS (down c.10% on H1 LY), which is a reliable number I usually find - although note the big gap between adjusted and statutory, so we’ll have to check the adjustments for reasonableness -
BIG had previously disclosed that a large contract which was being extended on short-term renewals has now ended.
We’ve looked at it twice this year previously -
19/1/2024 - BLACK - fell 20% to 102p - profit warning. Loss of Colombian contract, and US startup costs. Zeus lowers 2024 fc by a quarter. Paul - amber/green as looking interesting value.
28/5/2024 - AMBER (Graham) 167p - In line TU. Some concerns, including valuation.
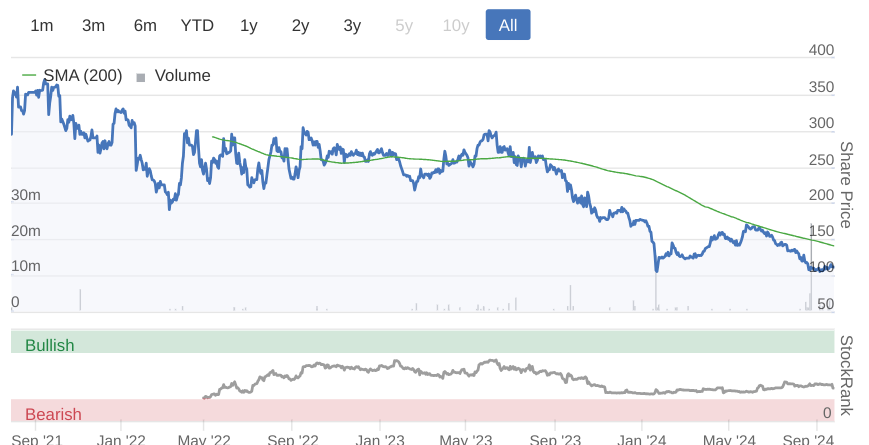
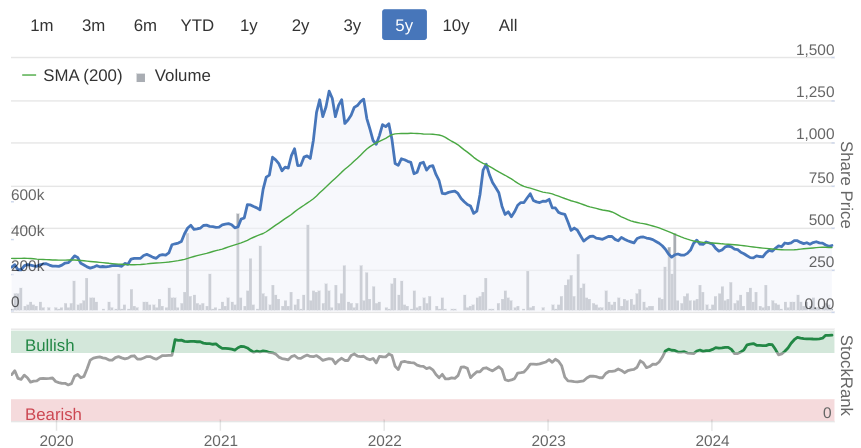
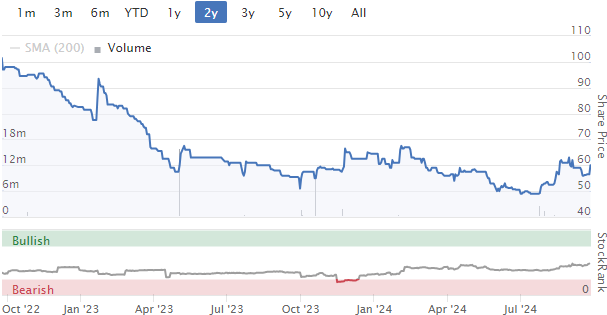
As you can see from the chart above, BIG had a nice recovery after its Jan 2024 profit, warning, but has seen all those gains wither away, and we’re now back down to Jan 2024 levels again.
So we have lacklustre H1 results, with adj dil EPS down 10%.
Some cost issues are blamed, but it still has very high gross margins -
“High gross margin of 70.0% in H1 2024, but down by 330bps due to the revenue decline, increased depreciation as we roll-out the latest 4G technology and increased operational costs”
I like these points below, especially the obvious potential for an alcohol sensor, for enforced sobriety for people who do things a lot worse than just offending people on social media and via email when they get back from the pub -
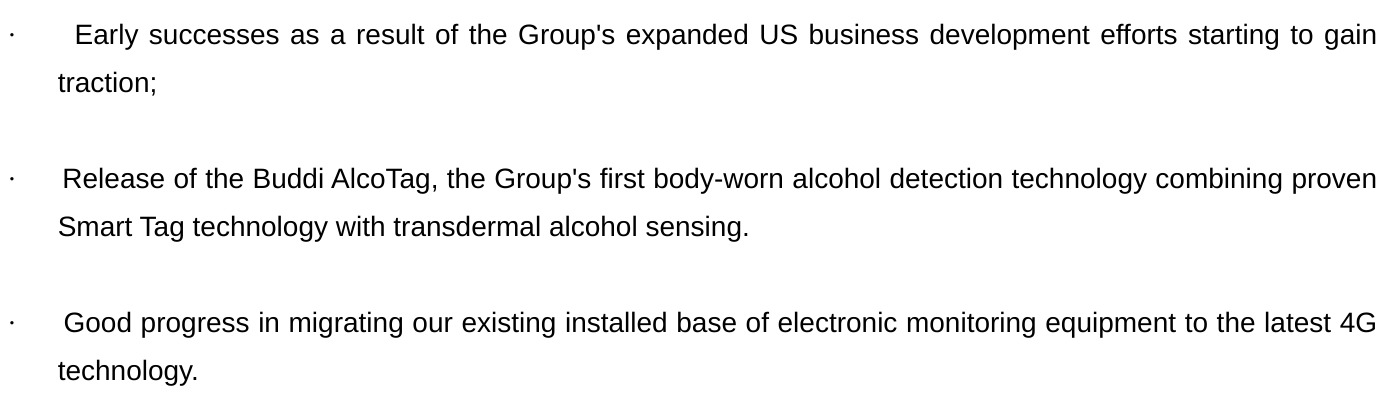
What about the outlook - it’s a slight reduction in guidance to the lower end of quite a tight range, so personally I’m seeing this as only just a minor profit warning - although we’ll have to check the broker changes, to see if they’re slipping a big warning out by the back door.
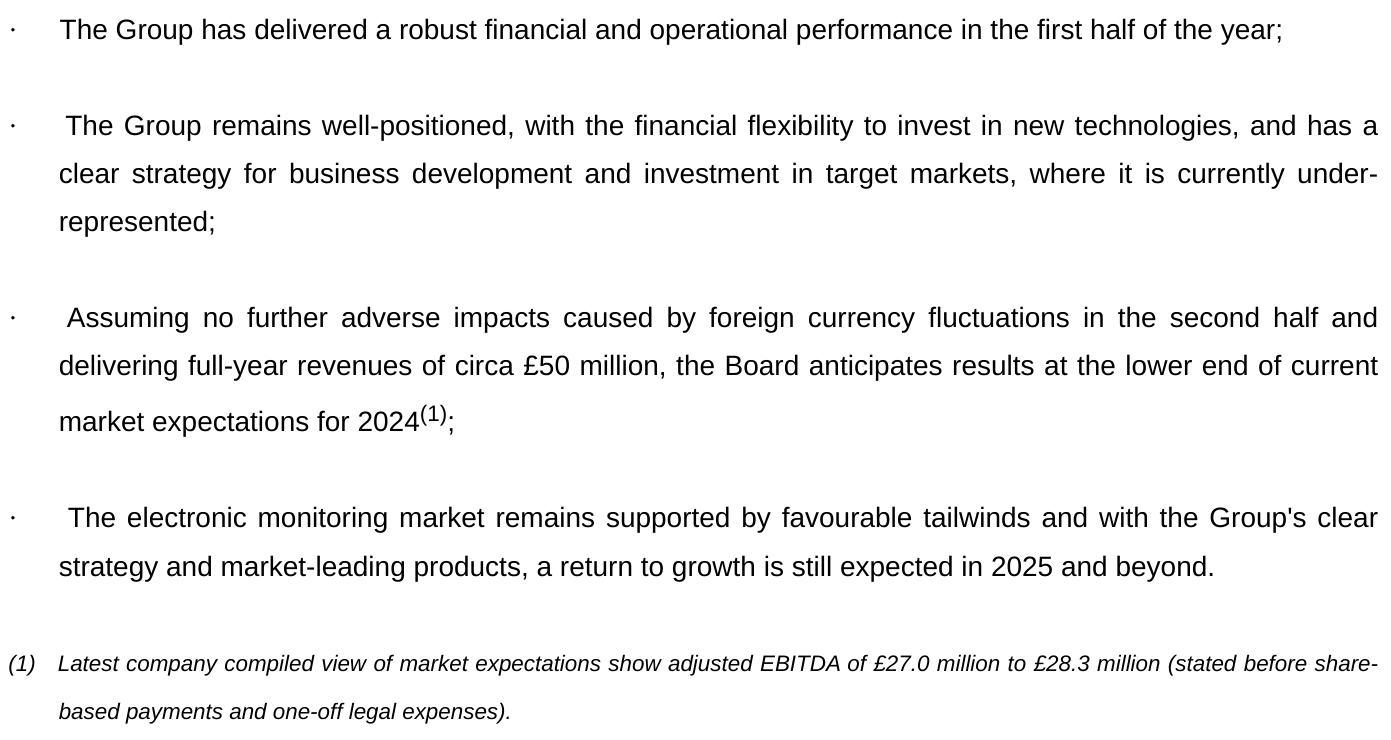
Broker update - thanks to Zeus for providing more detail, really helpful. Zeus has 6.5p estimate for dil EPS in FY 12/2024. The StockReport has 6.94p consensus, so it looks a modest drop. FY 12/2023 actual was 8.5p, so clearly earnings are going in the wrong direction (down), and bears might point out that BIG now looks ex-growth, and with margin pressure.
It’s tricky to value it on a PER, since we don’t really know if future earnings are going up, or down!
Balance sheet - a very important consideration, as BIG is swimming in cash. It’s a pretty crazy balance sheet actually! There’s £95m of cash sitting there (and earning interest), with hardly any creditors offsetting it. So I would say BIG has about £100m of genuinely surplus cash/capital. That gives it lots of options (acquisitions, tender offer or buybacks/divis).
This surplus cash is about a third of the market cap, so it’s a highly favourable point which should be reflected in the valuation of its shares.
Legal costs - I’d forgotten about this. There’s a case rumbling on, see the update today. Hopefully not a serious risk, but it would be better not to have a legal case. Quite hefty legal costs of £3.1m are booked in H1. More work needed on this by potential investors.
Share based payments - are really excessive. Not good. Especially as it’s awash with cash, but doesn’t pay divis too. So whose benefit is this company actually run for? I hope the institutions vigorously flag this misalignment of interests to the 26% founder CEO.
Paul’s opinion - Despite various niggles, I think the valuation at BIG of c.100p is looking attractive, especially as a third of it is cash backed.
We’re having to guess a bit re earnings, which could go either way, I don’t know.
That said, it has a track record of operating, and innovating, in a profitable niche, where the costs of using its products to hopefully help rehabilitate offenders in the community are a fraction of the costs of prison - making obvious sense. However, there must be loads of other companies in the same field, so how do we know if BIG is going to be a long-term winner or not?
Overall, I’m going to push the boat out here, and say valuation is sufficiently attractive for me to go GREEN at c.100p, on my assessment of risk:reward (which is partly subjective of course, and I don’t know what the future holds, so could end up being wrong as the facts change over time).
Graham’s Section:
Water Intelligence (LON:WATR)
Up 5% to 405p (£70m / $94m) - Interim Results - Graham - GREEN
Water Intelligence plc (AIM: WATR.L) (the "Group" or "Water Intelligence"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide its unaudited Interim Results for the period ended 30 June 2024.
I was positive on this primarily US-based business back in February after the release of its full-year trading update.
Let’s see if its interim results can justify my confidence:
Sales across the entire WATR network up 2% (includes both franchised stores and corporate stores).
Revenue +7% to $41.5m.
Adj. PBT +10% to $6m.
The revenue mix has changed a little, with more revenue from corporate stores and a slight (2%) reduction in franchise royalty income. In February, we discussed how WATR was buying back one of its US-based franchise stores, in order to operate it directly. It looks like there have now been several of these acquisitions.
As a general principle, when a company buys back its franchisees, this tends to increase revenues and profits, while at the same time reducing the company’s quality metrics.
Net debt of $3m, down from net cash of $1m at Dec 2023.
Exec Chairman snippet:
"We achieved strong double-digit growth in profits and EBITDA during 1H while continuing to invest in our long-range growth plan. Our balance sheet remains strong and under-levered enabling us to have "dry powder" to complement our organic growth plans with accretive acquisitions…
Expansion: in addition to existing UK/EU business, WATR recently purchased an Irish plumbing business for a total cost of €2.3m.
Graham’s view
There’s plenty of detail in this report to get your teeth into.
The big picture from my point of view is that WATR is continuing along its chosen strategic path: trying to find organic growth wherever it can, investing in new technologies and expanding through M&A.
The resultant growth is not particularly dramatic in the short-term but over the long-term it has made progress, without too much growth in its share count:
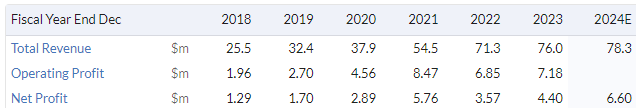
The Executive Chairman owns 28% of the company and has been the driving force behind the company for 14 years. So I think he has no shortage of credibility or alignment.
I’m going to leave my positive stance on this one unchanged. However, I won’t do this indefinitely - I will need to see some improvements if I’m going to stay GREEN.
Firstly, I would like to see network sales growth pick up from the current 2% level, at least to match the current US inflation rate (2.5%) and preferably higher than that.
Secondly, the company’s quality metrics are still OK but are lower than they were historically (according to Stockopedia’s calculations), and are not at the level I’d expect from a quality company using the franchise model. If WATR continues buying back its franchises, perhaps these metrics will remain under pressure?
Without any improvement in the network sales growth rate or the quality metrics, I’ll probably be adjusting my stance on this one lower at some point in the foreseeable future.
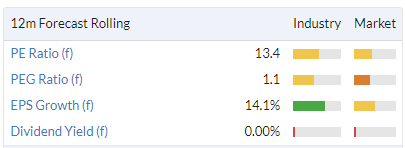
The StockRanks still love it (StockRank is 94) but the weakest ranking it gets is the one relating to Value. Let’s see if it can boost performance over the next 6-12 months, to justify the rating it’s on:
Everyman Media (LON:EMAN)
Up 6% to 60p (£55m) - Interim Results - Graham - RED
Let’s check out the H1 results to June from this premium cinema group.
Financial performance: everything moving in the right direction. The outlook is in line with expectations for 2024.
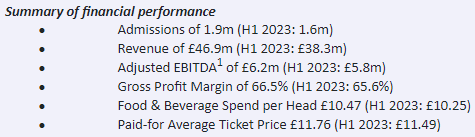
Remember that the entire film/TV industry (including the likes of Adf (TSE:DRX)) was affected by Hollywood strikes last year, which had knock-on effects for this H1 period that is reported today.
With the effects of those strikes receding, there is a strong H2 weighting expected for the current year.
The film roster over the next few months includes Joker 2, Gladiator 2, Wicked, Moana 2 and a Lion King movie. A powerful set of releases, in my view!
Everyman’s full-year expectations: revenue £108m, adj. EBITDA £19.3m. This implies a 30% increase in revenues in H2, compared to H1 - that doesn’t seem unrealistic at all to me, given the upcoming film releases.
Everyman has also enjoyed a remarkable increase in market share over the past twelve months, from 4.2% to 5.6%.
As a premium offering, there are going to be limits in terms of what it can achieve on this front, which arguably makes the increase in market share all the more impressive! But of course the challenge is to operate profitably as it opens new venues in more locations.
One new venue opened in H1 2024, and another two will open in H2. Four openings are planned for 2025.
Additionally, there has been a 76% increase in membership, to over 45,000 - a year ago, it was only 26,000. New apps for Android/iOS offer customers a range of services and help to promote the membership offering.
Outlook - this includes a warning that growth in 2025 will reduce from current market expectations.
Having carefully evaluated our expansion opportunity, we are comfortable that continuing to scale at current levels - three new venues in 2024, and four in 2025 - will provide a robust increase in footprint. Whilst this level of openings will naturally reduce the rate of growth in 2025 from current market expectations, this allows the company to strengthen its balance sheet and reduce net debt moving forward. This will give us the scope and flexibility to take advantage of excellent pipeline opportunities in 2026 and beyond.
Given the share price reaction, it seems that the market is taking the news of slower expansion as good news (assuming that investors have read the entire announcement, which can’t always be taken for granted!).
Net debt is mentioned as a reason to keep growth at a modest pace over the next year. It currently stands at £26m. This is purely the financial debt - there are also significant lease liabilities (having a present value of over £100m)..
Graham’s view
If I had only read the introduction and the CEO’s statement, I would have no choice but to be excited about this stock.
However, the bad news is left to the FD to explain.
This business just doesn’t seem to make any money, no matter how big it gets:
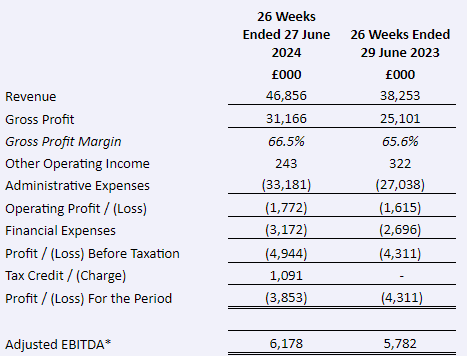
H1 revenues are up and the pre-tax loss is up, too.
But a bigger loss isn’t reflected in deteriorating EBITDA. On the contrary, EBITDA is looking better than it did in H1 last year.
The FD explains that more venues have driven higher admin expenses including higher fixed costs, depreciation and pre-opening expenses. Labour was the highest cost increase, with the national living wage increase being a factor here, too.
If I was trying to find a bullish perspective on this stock, I’d start by pointing to the pre-opening expenses as one-off in nature. But they only amounted to £200k in H1. So they can’t help to bridge the gap between EBITDA and the pre-tax loss.
Depreciation/amortisation is the elephant in the room: it was over £7m in H1 alone.
There are also financial expenses of £3.2m.
Thanks to modern lease accounting rules, EMAN’s rent payments are included in these two categories
The upshot is that adj. EBITDA remains utterly useless as a measure of profitability, and I find it embarrassing that the company continues to report it in its “Summary of Financial Performance” while leaving out any stricter measure of profitability.
Paul was AMBER/RED on this one in April and I could leave that stance unchanged but with net debt having increased since then and with the company still showing no signs of real profitability, I’m inclined to stick with the RED that I originally put this on.
As a cinema buff, I genuinely like what Everyman is doing - I just find it difficult to imagine a bright financial future for its current shareholders.
Roland’s Section:
On Beach group (LON:OTB)
Up 3% to 149p (£249m) - Pre-close trading update - Roland - GREEN
Today’s trading update from this beach holiday specialist covers the year ending 30 September 2024, including the key summer season.
The considerable progress made over the last twelve months has set us up for further success in FY25.
Checking back through the archives, I see that we last covered On The Beach in May, when Graham reviewed the interim results. He concluded that “the stock is cheap” and the business could be well placed for the future.
We’re now on the far side of this year’s peak holiday season, so what’s changed?
On The Beach’s share price hasn’t moved over the summer, but today’s update seems broadly encouraging. Let’s take a look.
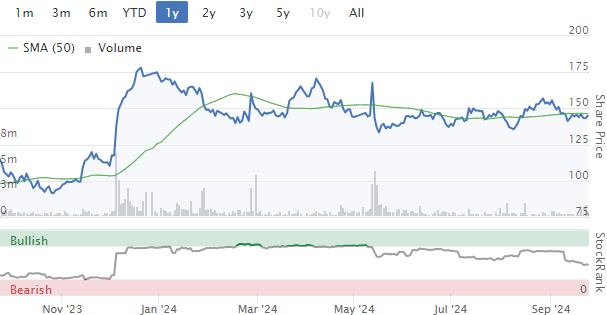
On The Beach says its Total Transaction Value (TTV) rose by 15% to a new record of £1.2bn last year. I imagine some of this reflects price rises rather than volume growth, but it still seems positive to me.
As an agent, OTB won’t report all of this as statutory revenue. For context, Stockopedia’s consensus forecasts show revenue rising by 8% to £184m this year.
As this is a trading update, the company has not included details of revenue or profit, other than to report:
Adjusted PBT in line with market expectations, despite incurring significant one-off costs related to the Ryanair integration.
A helpful footnote confirms that the consensus estimate for adjusted PBT is £31m, 31% above the £23.6m reported last year.
I would guess this means that adjusted earnings will also be in line with consensus. Stockopedia shows forecast earnings of 14.7p per share for FY24. This would represent an increase of 27% from FY23 adj earnings of 11.6p ps.
I’m encouraged to see earnings rising more quickly than revenue, as this appears to confirm that the business is delivering positive operating leverage as volumes recover post pandemic.
The group’s capital-light model means it can add volume without a corresponding increase in fixed costs. When this happens, profit margins rise more quickly than sales.
Indeed, On The Beach confirms this in today’s update, reporting “significant improvement in operating leverage”.
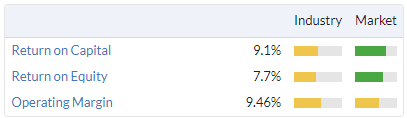
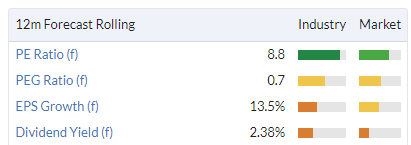
I expect the group’s operating margin and return on equity to return to double digits this year, as they were prior to the pandemic:
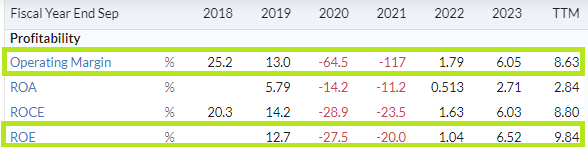
With the stock only trading on 10 times FY24 forecast earnings, I think stronger profitability could potentially support a much higher share price.
Cash generation also appears to have been strong. The group ended the year “debt free” and with a cash position of c.£95m. This reflects peak cash at the end of the summer trading season, but it’s still an improvement over the comparable cash figure of £76m at the end of FY23.
It’s worth noting that On The Beach does still appear to rely on debt during the year – the half-year results showed a net bank debt position of £47m, by my reckoning. So there are some big movements in working capital during the year as the company accepts customer prepayments and pays its own suppliers.
Dividend: following the reintroduction of the interim dividend in May, the board expects to recommend a final dividend as well.
Ryanair partnership - costs? On The Beach signed a deal with this leading budget airline in February that gives OTB “free and fair access to Ryanair seat supply”.
This deal marked an end to a legal dispute between the group and seems positive to me, but it appears that setting up this partnership has incurred “significant one-off costs”. These might be worth checking in the results, as they could impact statutory profits.
Outlook: CEO Shaun Morton says that Winter 24 volumes are currently 34% ahead of last year, with “customers seeking winter sun and enjoying our long-haul destination packages”.
At this early stage, bookings for Summer 25 are said to be “very encouraging”.
No formal outlook statement was provided today, with further detail promised with the FY results in December.
Roland’s view
I was a fan of this business prior to the pandemic and am pleased to see that its recovery is continuing.
Share price reaction has been muted this morning, presumably because the results are in line and no outlook has been provided for FY25.
It may also be worth noting that earnings growth is expected to slow significantly in FY25, according to Stockopedia’s consensus numbers:
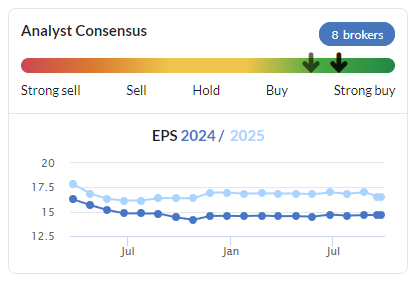
Perhaps some caution is merited, given the risk that consumer spending could remain under pressure.
However, the stock’s valuation looks very reasonable to me for a cash-generative business where I expect to see double-digit returns on equity.
I share Graham’s previous view that the stock continues to look cheap and will stay green on this one.
Time Finance (LON:TIME)
Down 2% to 55p (£51m) - Final results & Q1 trading update - Roland - AMBER/GREEN
Significant increases in Revenue, Profit Before Tax and Earnings Per Share. Own-Book origination and Lending continue to grow as Net Arrears fall
This small-cap business lender specialises in providing asset, loan and invoice finance to UK SMEs. It has proved to be a successful turnaround, although the shares have yet to return to their historic highs.
Today’s results and Q1 update suggest to me that progress is continuing to plan.
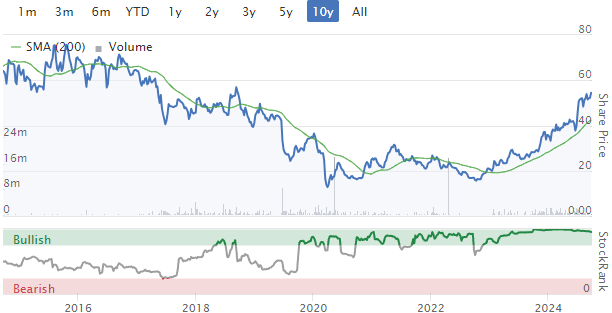
Final results summary: Let’s start with a look at the lender’s numbers for the year ended 31 May 2024.
Revenue up 30% to £33.2m
Pre-tax profit up 41% to £5.9m
Earnings per share (dil) up 30% to 4.8p
Loan book up 18% £201.2m
Net assets up 7% to £66.1m
Net tangible assets (ex goodwill) up 13% to £38.6m
Financial performance improved last year, although the board does not yet feel that it’s appropriate to pay a dividend – the last payout was in 2019.
Credit quality and exposure to any wider slowdown in the UK economy is obviously a relevant factor for a business of this kind. Fortunately, performance seems to have improved modestly last year:
Net deals in arrears at 31 May 24 of 5% (31 May 23: 6%%)
Net bad debt write-offs equal to 1% of loan book (31 May 23: 2%)
Trading commentary: the company has continued to increase its focus on own-book lending, rather than lending through brokers. Own-book loans accounted for 97% of lending last year, down from 96% in FY23.
In numerical terms, own-book origination increased to £91.6m last year, from £73.4m in the prior year.
Lending growth was strong in both of the group’s core divisions:
Invoice financing up 16% to £65m YoY
Asset Finance up 37% to £85m YoY (particular strength in hard assets)
Time Finance said it had funding headroom of “over £65m” at the end of May, providing ample scope for further lending growth.
Profitability: this isn’t a business I’m hugely familiar with, and when I looked at the StockReport, I was struck by the apparent low profitability of the business (in terms of return on equity):
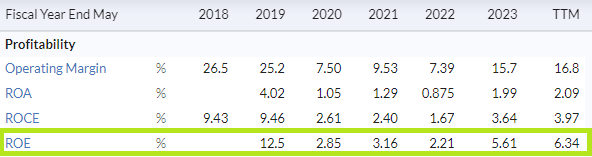
However, these results highlight a large difference between net assets (£66.1m) and net tangible assets (£38.6m).
Checking the balance sheet shows that the difference between these two figures is largely made up of £27.3m of goodwill. I haven’t researched the origins of this figure, but it’s unchanged from last year and doesn’t seem recent.
I don’t normally ignore goodwill (which typically represents past capital allocation decisions). But in this case I think it makes sense to focus on tangible assets, so we can understand the level of return being generated by the business on its trading assets (i.e. loans).
Based on last year’s net profit of £4.4m, my sums suggest a return on tangible equity of 11.5% (FY23: 10.2%).
This seems reasonable to me, if not outstanding. However, the improving trend from last year suggests the company’s strategy may be delivering positive results.
Balance sheet: Equity on a lender’s balance sheet can be a small number that’s the difference between two very large numbers. Big banks are a classic example of this. A small change in asset (loan) values can wipe out equity almost completely.
In Time’s case, the tangible equity on the balance sheet does seem to be more meaningful. Tangible assets of c.£38m represents the difference between net receivables (loans) of £178m and payables (funding) of £141m.
Thus, in theory, the company might be able to absorb losses approaching 20% of its loan book before its equity was completely wiped out.
In practice, things probably wouldn’t be allowed to get this far. But on first inspection, the balance sheet seems fairly decent to me.
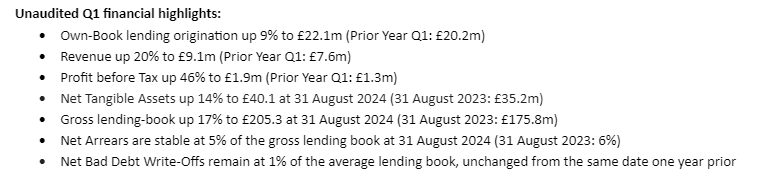
Q1 trading / outlook: progress so far this year appears positive, with the trends I’ve highlighted above continuing into FY25. Indeed, momentum appears to be strengthening, with Q1 PBT 46% higher than the same period last year.
I’ve pasted in these highlights, to save me retyping them:
An updated note from house broker Cavendish is available on Research Tree today (with thanks).
Cavendish has FY25 earnings estimates of 5.6p per share, rising to 6.5p in FY26. Consensus shown in Stockopedia ahead of these results for FY25 is 5p per share, so I suspect we will see upgrades coming through over the coming days.
This FY25 estimate prices the stock on approximately 10x forward earnings.
Roland’s view
Time Finance seems to be becoming a mini Close Brothers (LON:CBG) – this troubled FTSE 250 lender has a significant business providing secured lending to UK SMEs.
I’m encouraged by today’s results and while I’d want to learn more about the lender’s customer base and lending policies and funding arrangements before considering an investment, my view is broadly positive.
In terms of valuation, I think the shares look reasonable, although not necessarily as cheap as they might seem.
Based on the Q1 net tangible asset figure of £40m, the stock is trading at around 1.3x net tangible assets.
Assuming a return on tangible equity of 12% gives a return on cost of equity of about 9% for buyers at current levels, according to my sums.
That looks about right to me, but Time Finance’s strong execution and continued growth mean I’m happy to take a positive (amber/green) stance here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Everyman Media (LON:EMAN)
Market Cap £53m!
Valuation is bonkers for a company that trades in an industry that in the long term they will all go bust.
The company generates no cash and they only stay in business by increasing their borrowings year after year after year…………
All the best
Hi all, looks like. Yu (LON:YU.) is having a tough day. I am going to hold my breath, not sell and see how long this choppy period will last.
Any thoughts on why its down? They had a moan up about the AIM market, have they got investors worried they may delist?
CEO comments about the market may be one reason, however is he moaning or providing his opinion? I don’t recall in his comments wanting to delist.
He definitely didn't say anything about delisting but I think this is what investors are worrying about. Hence the selling.
Yep. CEO owns over 50% of Yu (LON:YU.) so investors think he may de-list. I've taken a substantial chunk out over the last 2 days. Now a very small holding.
Intercede (LON:IGP)
Just reading through the Special Resolutions passed at today's AGM, the following;
9. That, in accordance with article 10 of the Company's articles of association and the Act, the Company is generally and unconditionally authorised to make market purchases (within the meaning of section 693 of the Act) of ordinary shares of 1 pence each in the capital of the Company (Ordinary Shares). within the parameters set out in the Notice.
99.95
Presumably this is the Company clearing the way to starting share Buy Backs at some stage?
(The Act referred to here appears to be the 2006 Companies Act, where section 693 does indeed talk about Companies buying back their own shares. 99.95 is the %age shareholders voting 'Yes').
Everyman Media (LON:EMAN)
Hi Graham
Thanks for the justifiably scathing review of Everyman.
I completely agree that the debt position looks scary and it has made me think twice about whether I wanted to keep owning this.
The reason I have decided to hold is because the company still has £9m of available liquidity (£7m loan facility + £2m cash) and are expecting debt to come down by the end of the year, despite opening 2 more cinemas soon.
Hopefully this is the start of a reduction in debt, which is a priority for management.
Some other positives that are perhaps worth highlighting:
The most expensive membership is £680 per person per year.
The cheapest membership is £95 per person per year = £79 ex VAT so this should be £3.6m of recurring ticket income only at least. Presumably people will still buy food once they get there.
https://www.everymancinema.com...
I wonder if membership revenues could be a material part of the top line one day?
If that holds true for 2024, then admissions will finish at c.116m. This is extremely low and my hope is that it represents a bottom going forward, especially given the weak film slate in H1.
For context 2019 admissions were 176m.
Their highest buy-in price in the last 12 months was 60p i.e. this is the lowest price they would need to offer shareholders if they breached the 30% ownership threshold.
One of their directors is a NED for Everyman. Hopefully he knows what he's doing!
It's a risky one, but I'm keeping my fingers crossed that capex comes down, debt comes down and the material positive underlying cash flows that I believe are there come out to say hi.
A
abtan….If it is risky to hold Everyman media and you need to keep your fingers crossed. Why not just take a hit on the loss and put t(e money into something else that might stand more chance of increasing in value….If you do you will probably be rewarded by fewer sleepless nights wondering how the shares are doing
Everyman Media (LON:EMAN)
Hi Penny
I'm actually in profit for Everyman, so no need to take a loss :)
That aside you ask a fair question.
The biggest current risk I can see is the debt position.
The company says that this will start coming down by the end of the year and this seems a reasonable assumption based on what we know.
So if my biggest worry is actually something that will be remedied in a reasonable timeframe, then my focus moves to Valuation and Growth.
Valuation
I have found in the past that my biggest wins have come from contrarian positions where I think I see hidden value. It doesn't always work!
However, my hope is that by the end of next year the underlying cash generation i.e. excluding expansionary capex will be c £8m -£9m.
And this assumes no growth in UK admissions next year vs the current low level this year, which I would hope is being overly cautious.
I don't think a company making this much cash should be worth £53m.
Growth
Everyman is in this wonderful position where it is growing seat numbers and it can increase prices each year - that's a double whammy of growth right there, which should provide a decent foundation going forward. I think they said their target was 100 cinemas in the UK vs the c50 they have now.
---
Thinking more short term perhaps it might be better to sell and buy again in 2-3 months to see how UK admissions progress through the rest of the year? I've thought about it, but the stock is very illiquid, so this option is quite tricky.
I hope you don't mind me asking, but I'd be interested to hear your thoughts. Have a I convinced you that there might be an opportunity here :) ?
Thanks for the question; it certainly gets the thought-process working.
A
abtan
My portfolio performance improved dramatically once I sold as soon as there was iffy news unless it was also clear that the problem was temporary. . We’ve got doubts in spades with Everyman Media (LON:EMAN) and Graham’s update covers them, it gets a RED rating. And yiannos has just summed up the declining sector it operates in and the increasing debt.
The share is down 36% since listing, and down 75% from the 2018 £2.50 peak.
The latest update is open about shorter term negatives but more optimistic about 2026. That’s a long way off.
A good question to ask is could the money staked be better employed in an alternative share with less risk and much more upside potential. What’s the answer to that question with Everyman Media (LON:EMAN) ?
EDIT.
Just to be clear. I’m not advising anyone to sell Everyman Media (LON:EMAN. My point was about selling when having doubts etc.
Everyman Media (LON:EMAN)
Hi Ken
Thank you very much for the reply.
I think the iffy news has been there for a while :)
But point taken of course.
On the sector declining, I'm not sure where that has come from.
All I see is stable admissions data for the 20 years before covid (see below) with up and down years in-between.
It hasn't quite made it back to the pre-2020 level, but I'm a believer that it will recover. Cinema will always be an escape, even in this streaming world. My kids can't wait for Moana 2 and I always enjoy a date night.
Here are the UK cinema admission stats for the last 20 years for reference, but feel free to click on the link and see the number of admissions back in 1946! The industry has definitely declined since then :)
https://www.cinemauk.org.uk/th...
In short No not convinced….In the past I have held stocks that show promise go up and then fall back and back and back….(who hasn’t …to those without hands raised are you sure!!)….Recently I held Quinteq (Thanks Stocko) and they were nicely up but recently started to really backtrack eroding the gains….After a fair few days of this I sold (still in profit) and have gone elsewhere….They can always be bought back later on…Today they are still below my selling price …..I may be right ,I may be wrong but the new purchases make sense and make life positively interesting…..Good luck whatever you do
Everyman Media (LON:EMAN)
Hi Penny
Thanks for sharing your thoughts.
Indeed, I can always buy back later. It's certainly not a bad reason to sell right now.
A
PS I learnt a lot form Ken on another now defunct site….It changed my attitude towards ‘Take a nice profit and run it elsewhere’ from ‘oh no it’s fallen again I was in the black now it’s red’….and you can always just sell half…just in case
Hi Abtan
I think you make a very good eloquent case for Everyman Media (LON:EMAN) and raise areas of potential upside that I hadn't considered. We are members and always spend through the nose when we go there, it's not a cheap pastime!
Having said that with an EV of circa £80m and minimal free cash flow it's all in the price and I'll believe the debt reduction plan when I see it, but I hope I am wrong for your sake.
I do believe they are building this up to sell on and the Kaye family (who were invested in this from the beginning) are very shrewd operators and have an excellent track record in this sector spanning many decades.
It's not for me but I wouldn't be at all surprised if we wake up one morning to a takeover announcement, good luck!
Everyman Media (LON:EMAN)
Hi Burnet Onions
Thanks for your thoughts.
On your cashflow point, here's an excerpt from last year's CFS:
Even excluding the landlord contribution, the potential for positive cashflows certainly seems to be there, especially if admissions edge back to their pre-covid levels.
There is of course 1 very important number missing from the above and that's the £17.6m spent on capex and acquisitions, which is why cashflow looked so bad last year.
It's good to see that this was <£5m in today's interim report.
----
"I do believe they are building this up to sell on...I wouldn't be at all surprised if we wake up one morning to a takeover announcement"
I completely agree and in the short term I think the Blue Coast 60p purchase price should provide a bottom if this happens.
For what it's worth, I also wonder if they'll do an equity raise soon to shore up their balance sheet. That would certainly help.
Finally here's a snippet from last year that I found interesting regarding Amazon moving into the cinema theatre space. Of course, nothing happened here, and Netflix have indicated that they want to remain online only for now, but it's certainly an intriguing idea that a streaming services might expand offline.
https://www.reuters.com/busine...
Thanks again
A
For anyone holding Goodwin (LON:GDWN) (who don't seem to like 7am RNS's) an intra-day trading statement which is positive, if light on numbers. Very interesting that the US government are funding radiographic testing facilities for the castings being produced for US navy: https://www.stockopedia.com/sh...
On the other hand, slightly disappointing that the Duvelco polyimide facility not quite up and running yet.
Whilst today's mid-morning update from Goodwin (LON:GDWN) sounds somewhat positive, there is absolutely zero useful information regarding overall trading in relation to market expectations. All we get is the asinine "..profitability and cash generation is continuing to move forward."
I can hear Paul tearing his hair out as I type!
ReGoodwin (LON:GDWN) there are no market expectations…& personally I quite like it that way..it seems to work reasonably well
North Atlantic Smaller Companies Investment Trust (LON:NAS) Spire Healthcare (LON:SPI)
I don't hold NAS but like to read their reports (1/2 year out today) to see what Mr C H B Mills (or "posh bloke" to planetx) is currently thinking of the state of the market.
Also, it looks like they are looking to buy more Spire and for some buyouts in their indirect holdings through Oryx and Odyssean. Watch this space!
Extract:
"August saw very considerable turbulence in the financial markets, although other than the fall in Polar Capital which reduced the NAV by 0.6%, the impact on the balance of the portfolio was negligible.......
I have had a chance to meet with all our major quoted holdings over the past three weeks and in not a single case do I see cause for alarm and in some cases such as Spire Health we will be adding to the holdings if we can find attractive entry points. I am also hopeful that some of our indirect holdings through Oryx and Odyssean will be subject to corporate activity in the coming months."
Interesting. Thanks for posting Peter.
His " I am also hopeful that some of our indirect holdings through Oryx and Odyssean will be subject to corporate activity in the coming months." led me to take a look at the top holdings in those funds, to see where the takeover prospects could be. From Oryx I hold Centaur Media (LON:CAU) and Niox (LON:NIOX) , both of which could make potential targets. Others (not held) could include Hargreaves Services (LON:HSP) or Restore (LON:RST) . I don't hold any from Odyssean but may look closer at Flowtech Fluidpower (LON:FLO) and NCC (LON:NCC)
Avingtrans (LON:AVG)
For those that are interested, Paul Hill's interview with Steve McQuillan and Stephen King.
Q&A with Avingtrans CEO, Steve McQuillan & CFO Stephen King - Vox Markets
https://www.ft.com/content/206...
Aim shares face ‘cliff edge’ if UK axes tax break, warns Peel Hunt boss
Surely this is the biggest concern right now for smallcap investors?
The scary thing is I wouldn't put it past them. They are talking about a minimum C rating for rental properties whist is ridiculous... D is fine, D is normal, most older houses with good insulation and a modern boiler are a D.
Sorry for the off topic rant but if they do this it will massively adversely affect the rental market.. I have a single investment property
It's really hard to claim there's a premium built into AIM shares based on the tax advantages. Perhaps on some of the biggest , most reliable shares on AIM like James Halstead (LON:JHD) FW Thorpe (LON:TFW) Judges Scientific (LON:JDG) . But generally similar businesses certainly don't trade on a premium on AIM compared to the main market. You'd hope in a world of efficient markets there'll be buyers to step in if there are forced sellers. Changes in either business property relief or capital gains tax don't affect the underlying value of the businesses, it would be an incredible opportunity if AIM really did fall by 20%.
Octopus are a name to watch out for on shareholder registers as by far the biggest IHT fund. They seem to pop up as the biggest shareholder quite often in some of AIM's old reliable stalwarts, where you would try to park cash with the lowest risk on AIM like James Halstead (LON:JHD) and Nichols (LON:NICL) . But surely anyone holding a comparable and similarly rated share like A G Barr (LON:BAG) will be trading it in for Nichols if there's a lot of forced selling after the budget...
I am sure this is holding AIM shares back I have taken profits and transfer to family avoiding IHT tax
Hopefully you will survive the next 7 years mabie41!
I think that Labour's policy towards the inheritance tax relief for AIM shares held for 2 years will be a good indicator of the quality of the government. Regardless of arguments for and against this relief, I would suggest that it is a matter of common sense that any major changes should either be phased in or delayed for at least 5 years after the announcement to ensure that any change in share prices or manager changes at IHT funds can occur in an orderly fashion, enabling those affected to make new arrangements. Let's see what happens.
Agree re phased introduction, or alternatively the pragmatic solution would be to limit BPR claimable per estate
Indeedy it would be simple to say - only applies for purchases after this date initially with reasonable period of time for orderly rearrangements to be done if they want it to be gone within say 3-5 years. that way one can set a line in the sand that is fair and reasonable (ref how to manage change).
I was reasonably confident labour would not go nuclear stupid ref taxes pre election - they arent exactly instilling ANY confidence up to now with me - so i am wobbling a bit ref confidence levels(i think perhaps we would all agree is labour have had a poor perioe - if they were a football manager they may already have had a vote of confidence from the chairman already !)
I think that Labour's policy towards the inheritance tax relief for AIM shares held for 2 years will be a good indicator of the quality of the government.
Last year just 64 estates used AIM BPR to shield £800 million from IHT. Given that the relief kicks in after only two years that looks unjustifable, particularly when there's a broad need to raise taxes. Unfortunately as soon as a tax break is introduced the very rich and their advisors will be all over it, creating a tax avoidance scheme that will eventually attract government attention.
Quite how the Chancellor will go about this will be interesting: personally I'm hoping it will simply be removed as that will no doubt offer some juicy bargains, but more likely it will be capped and the qualification period increased to seven years to match the normal IHT gift exemption. I would hope there'd be some mechanism for ensuring family controlled firms like Nichols (LON:NICL) or James Halstead (LON:JHD) can pass on ownership without paying IHT - that was the reason BPR was brought in, in the first place.
More generally AIM is a terrible market - in just under 20 years the index value has fallen from 1000 to about 780. If this is the best that it can do while supported by BPR I hate to think what it will look like when it's removed. If I was the government I would be making overtures to Nadaq to open up a small cap market here, if they can replicate what they've done in the Nordics that would properly liven things up. It's about time the useless LSE had some proper competition.
timarr
Avingtrans (LON:AVG)
Prelims look good to me on an initial read. Engineering division continues to perform well with its focus on nuclear and end markets, The medical division is progressing towards commercialisation, albeit as yet makes no contribution to the bottom line.
As I have posted on several occasions the medical division comprising Adaptix (portable 3D x-ray) and Magnetica (portable helium free MRI machines) is the potential cherry on the cake. If either are successfully commercialised the shares will appreciate significantly.
For now and paraphrasing Christopher Mills the engineering division is worth more than the current share price with Adaptix and Magnetica in the price for free.
Debt is modest; there is also a modest but increasing dividend and the management team of Steve McQuillan and Stephen King with the very able Roger McDowell as Chairman are more than competent.
It has become my largest holding having overtaken Volex (LON:VLX) .
All views welcome, including of course those of Paul, Graham or Roland.
Avingtrans (LON:AVG) Hi Jonno, I sold out of this one for a modest profit because I don’t see the medical businesses in at zero cost. And I rate the chances of commercialisation at only moderate. There is a heavy load on management time in growing unfamiliar businesses that has a price paid by the other businesses in the group. And the average rate of success in commercialising medical innovations is not high. Why should two guys with engineering management expertise have a better chance of success? I don’t think they will find it easy and would be better sticking to their knitting. I own a lot of quality industrial compounders already, and this one, while a business I respect, does not offer better prospects - or attractive diversification - while carrying higher risk.
That said, I like the management and wish you all the best with the investment.
I agree that saying Magnetica and Adaptix are in the Avingtrans (LON:AVG) share price for free is too simplistic. There will be ongoing losses from these businesses for some time and they might ultimately fail. However, I can say that I had correspondence with Steve Mcquillan a while back and he reassured me that he was familiar with MRI businesses from his time at Oxford Instruments and that he has also recruited well from GE and Siemens as well as OI to ensure sufficient expertise in the business.
I like management here and I am invested in the belief that the odds of success are reasonable.
But how long are you prepared to wait? I sold this morning as literally, it's not providing much of a divi and continues to drift without any real traction on how and when they will start bringing the money in.
Avingtrans (LON:AVG)
Some fair points guys and yes it is perhaps too simplistic to say the medical division is in for free but having bought at arond £2, I am happy to stick with it.
As you are a “full house” today, would be interesting to hear views on Kitwave (LON:KITW) fund raising last night and acquisition. Pretty dilutive (14% of overall share capital) and as always little time for individual shareholders to participate ☹️. I hold but considering my options…
I quite liked Albertos' post on Kitwave (LON:KITW) late yesterday (copied below for grouping purposes - hope you don't mind Albertos) I'm off to find out more about the Australian system.
Kitwave (LON:KITW)
An 8% drop over 4 days and then a placing - seriously!
The sooner we adopt the Australian system the better. Does anyone actually believe the "City" did not know about this and was selling knowing they could replace at a cheaper price. It stinks. There are no Chinese walls.
Institutional placing £30.5 m - for the great unwashed £0.5m - reminding us all once again that nobody can be trusted look after their own finances and needs to pay a fee to the great and good for advice.
London is dying, and its happening due to its own actions.
Apologies but this happens continually and really p****s me off.
Peter, it is a disgrace. I tried to top up at 8.30 only to see price has bounced back tp £3.25. The system is wrong. Back in the day I worked in stockbroking underwritten rights issues was the standard way for companies. Underwritten by institutions, this was pre big bang, not one large bank. These placings are wrong in every way, shareholder have no longer any pre-emptive rights. Does make you wonder why we bother to invest, and try nad help companies grow. The idea that the market exists to help companies grow seems long dead, it is a playground for the funds. As my ex boss told me when I was a young stockbroker, thinking I was doing important capital raising stuff “ Remember your just selling second hand share certificates” ! I left the city a few years later post big bang.
I do miss the old days with proper rights issues where every shareholder however small got to take part.
I have raised KITW with the Share Society to have a look at. Since the shares are back to £.35, about the price before the fall, Institutions have made a quick 9% and more importantly the broker who did the placing would seem to have misled the company into placing at such a low price. Arguably it could have been done at £3.25 which would have lessened the dilution the excluded Private Investors have suffered.
Well said Peter. The great Unwashed are regarded with contempt.
Peter T . Kitwave (LON:KITW) Yes the 8% fall in the 4 days before the placing is disgusting! Does that mean anyone has broken the current regulations? If so, then what was their role, and which regulations were broken? If the current regulations were not broken, then what regulatory changes would be required to fix the problems?
Any institution/individual contacted re a placing prior to the announcement should be put in a “closed period” i.e not allowed to deal in that share prior announcement.
All fair points, but allow me to play devil’s advocate…if you believe in the long term prospects here, should you really care about an 8% drift in the share price? If you feel it brings management’s ethics into question then perhaps yes.
You might be more concerned by the dilution but on balance I’d rather a placing than more debt. What puzzles me is why they’ve been paying fairly generous divis if they’ve been looking for an acquisition of this size, surely better to clear some of the debt?
Just my opinions, I’d be interested to hear what others make of them.
Hi Gmjs. I am not a long term holder of anything. I profit from short term increases in the share price of companies which I hold. What really irritates me is that some market participants are better informed than the others. The "others" tend to be private investors which should have the same access to price sensitive information as the institutions, but the reality is that private investors are kept out of the loop.
That's fair enough- I can see that would be frustrating
4 minute vid here about Creed. Looks a very well-established and successful family business, with the directors staying around for while. Without repeating the info from the RNS, its a big one for Kitwave. £70m deal, increasing Rev from 630m to a projected 800m next year. The cuurent downside right now is that those blessed folk at Liontrust are slowly divesting themselves of their substantial holding. They need to be out of the way to allow the SP to take its true course, which should most definitely be up.
Forecasts excellent, at ~450p v 310SP today.
FWIW Cannacord has increased their TP for Kitwave (LON:KITW) nearly 10% to 495p on the back of it’s acquisition of Creed Catering, which they see as earnings enhancing after the first full year.
finals from OPG Power Ventures (LON:OPG) - a great year, revenues almost triple from last year and cash generation of £20.5m (50% of the Market Cap). Moves to being in Net Cash and outlook comments suggest continuing good progress to follow.
I like this one (ESG thoughts aside) - stocko ranks it at 91 overall.
I would appreciate if it were possible to take a look?
Well I've held OPG Power Ventures (LON:OPG) since 2018, cost 22p/share, and thus is a well-proven dog. Since December 2019 shareolders have seen plenty of excuses why a dividend should not be paid since and now; "dividend policy:
The Board firmly believes that it is in the interests of stakeholders and the Company to conserve cash to meet its operational and capex requirements and also to provide for any adverse impact on account of economic uncertainties. Therefore, the Board has decided not to declare a dividend for FY 24. The Board will revisit the Group's dividend policy in due course."
Moreover, as a general view it seems to me that India plus some African countries don't want to let any profit out of their country.
My morning smallcap tweet: Crowe flies at SYME
Supply@Me Capital (LON:SYME) Time Finance (LON:TIME) Enteq Technologies (LON:NTQ) Dialight (LON:DIA) Technology Minerals (LON:TM1) Petards (LON:PEG) Shield Therapeutics (LON:STX) Big Technologies (LON:BIG) Avingtrans (LON:AVG) Directa Plus (LON:DCTA), On Beach group (LON:OTB), DFS Furniture (LON:DFS), Andrews Sykes (LON:ASY), Water Intelligence (LON:WATR), Everyman Media (LON:EMAN), Fadel Partners (LON:FADL), Tortilla Mexican Grill (LON:MEX), KRM22 (LON:KRM)
◄Supply @ME Capital (SYME)► auditor Crowe resigns having carried out a reassessment of the risks involved. [SP=0.01 Cap=4m]
◄Time Finance (TIME)► Q1 own-Book lending origination up 9% t. NTAV up 14% to £40.1m. Guides FY at least in line. [SP=56.2 Cap=48m]
◄Enteq Technologies (NTQ)► £1.5m placing at 5p, a 44% discount, to expand the current fleet of SABER tools and working cap. Also £0.5m Retail Offer. [SP=9 Cap=6m]
◄Dialight (DIA)► Sanmina litigation verdict revealed. DIA to pay $7.8m net to opponent. DIA loses on fraudulent inducement and wilful misconduct bvut wins on breached the Manufacturing Services Agreement (MSA). Sanmina wins claim that DIA breached the MSA with respect to Sanmina's accounts receivable and 'excess and obsolete' materials claims. DAI "considering potential post-trial motions in respect of the levels of damages, interest payable and legal costs. It is also reviewing its options with regards to appeal." [SP=162.59 Cap=65m]
◄Technology Minerals (TM1)► 48% owned owned battery recycling business, Recyclus completes a 10-week programme to recycle 4,000 end-of-life Li-ion battery modules sourced from EVs. [SP=0.1 Cap=2m]
◄Petards (PEG)► wins £0.4m+ order for a critical communication system to be fully delivered within the current year. [SP=8.88 Cap=5m]
◄Shield Therapeutics (STX)► success in Phase 3 clinical trial of new oral liquid suspension for children with iron deficiency anaemia. CO due €1m as development milestones. [SP=3.66 Cap=29m]
◄Big Technologies (BIG)► H1-June rev down 3%. Blames ending of a criminal justice contract in Colombia. Warns FY results at the lower end of market expectations of adj EBITDA £27m-28.3m. [SP=111.5 Cap=333m]
◄Avingtrans (AVG)► FY-May adj EBITDA slightly ahead of the upgraded market expectations at £14m. Current trading in line. [SP=410 Cap=136m]
◄Directa Plus (DCTA)► H1-June rev down 26% "mainly due to delayed commencement of some large contracts and strategic refocusing on higher value contracts". Warns FY rev materially below market expectations of c. €17m. [SP=16.49 Cap=17m]
In line: OTB, DFS, ASY, WATR, EMAN, FADL, MEX, KRM
Another strong set of results with good top and bottom line growth from Time Finance (LON:TIME) this morning. Net Bad Debt Write-Offs equal to only 1% showing the quality of their increasing lending book. Still looks good value to me.
Time Finance (LON:TIME) .....results which a privileged few seemed to get wind of judging by yesterday's otherwise unexplained 8% lift!!
Exactly my thoughts too. I hold but would like to have bought more today supported by the safety afforded by the results but beaten to it
Time Finance (LON:TIME) - Also worth noting Cavendish upgraded their price target to 112p from 71p.
China and HK have followed through today, although off the highs of the day. At least it wasn't a one day wonder. Silver and Copper in particular were up 3-4% yesterday... the commentary is mixed, J Authers not convinced by monetary stimulus into a balance sheet recession ( The Japan argument) - time will tell whether more policy follows. Fidelity China Special Situations (LON:FCSS) got a decent nudge yesterday... even though its underweight Alibaba and Tencent, the NAV still picked up 4% on the rally... and looks an ok way to jump on the trade... although I have no real edge other than 10% discount and looks to "broadly" track the index over the last 2-3 years.
Institutions are underweight or short China and HK so I think this is the start of the rally even though it wasn't the Bazooka stimulus package the market will eventually want,
Thanks for the macro summaries. Another snippet of news that caught my eye yesterday was the latest USA consumer confidence result, third lowest result in 2 years.
Morning All,
On Beach group (LON:OTB) looks pretty good update to me. Will you be covering this morning guys?
Many thanks.
Hi JohnDoe, thanks for the suggestion, we will be covering On Beach group (LON:OTB)!
Roland
Business recovered to pre pandemic level but share price remained stagnant for years
Dialight (LON:DIA) Ouch!!
The jury awarded damages of $0.9m to Dialight in respect of Sanmina's breach of contract, and awarded c.$5.3m in damages against Dialight in respect of Sanmina's AR claim and c.$3.4m in damages against Dialight in respect of Sanmina's E&O claim.
A popular blogger on X was buying after recent director purchases ahead of the ruling!
EParo thanks for highlighting this as a Sanmina (NSQ:SANM) holder no news passed my portfolio news feed, so was unaware.
Perhaps the Directors are confident of a successful appeal.
It does make you wonder why the directors were buying a short while ago pushing up the shareprice. Do they know something we dont?
Sterling continues to appreciate . £=$1.34 and £=€1.20
Does that indicate UK economic strength or weakness elsewhere?
Plenty of $ earners in FTSE100, so a headwind for them but a tailwind for importers.
Think it’s more to do with interest rates expectations than much else.
It’s all to do with the sausages
*OECD Raises 2024 U.K. Economic Growth Forecast to 1.1% From 0.4%
*OECD Raises 2025 U.K. Economic Growth Forecast to 1.2% From 1.0%
Yes - fantastic - signs labour are delivering already (well thats how they will use the data my comments are completely tongue in cheek)
Gold is now six bagger over the last 20 years - don't tell Gordon Brown
This is very true or a 9 bagger in £, equally gold has had very long periods of sideways movements while other assets have raced on in value indeed over the last 110 years it has only 7 bagged.
A lump of metal with no mass practical use and yields no income yet a store of value and hedge against inflation and or the debasement of fiat currencies.
A divisive asset if ever there was one, just like bitcoin (I hold neither!)
Is interesting how the increase in value of gold over the last hundred years has been mostly since America dropped the link to dollar in 1971. Do have some exposure to it through shares and ETF's and in case of any currency debasement.
Thanks for this. I love the market debate on the ‘barbarous relic’. Out of interest, where do you get your data from? I think you might be comparing apples with pears here. The gold price was ‘set’ at the beginning of the period you mention whereas now it’s [largely] a market derived price. Fwiw - I’ve owned for a long period as part of a wider portfolio approach. I think this is how you need to think about gold. I’d also compare it to cash (massively debased) and bonds in terms of its risk/reward profile. That said, there is no totally safe investment out there, as the Gold Reserve Act would attest to. Irrespective of individual views on gold…..I do find central bank buying of gold over the last decade really fascinating. Best of luck out there.