Small Cap Value Report (Weds 26 Oct 2022) - MADE, MEAL, BMY, OTB, VNET

Good morning from Paul & Graham.
A couple of long-running problems (MADE and MEAL) look to be reaching the end game, so I typed up some thoughts last night (Paul). Happy to discuss, so please do add your thoughts in the comments.
Agenda
Paul's Section:
Made.Com (LON:MADE) - a bombshell announcement last night, saying that takeover talks have been terminated, as none of the parties could commit to the required timetable (end of October) for firm offers. Says it might suspend the shares. Unfortunately for holders, this looks as if insolvency is imminent.
UPDATE - another update this morning from MADE, saying that its operating subsidiary company, MDL, has stopped taking new customer orders. This looks to be a precursor to putting it into administration, as it needs more cash from the plc. This raises the interesting possibility that MADE might cut off its trading subsidiary from further funding, possibly leaving a cash shell with some remaining cash - so not necessarily a complete wipe out for shareholders? But that depends on what cash there is left, and also what liabilities are at topco level. I've just been discussing this with a bear on MADE, who dug out some interesting information that the group holding company seems to have given a pledge (which sounds like a fixed charge) to the bank, in respect of property leases. So any remaining cash might be spoken for possibly? It's total guesswork at this stage. Normally when companies fail, they're up to their eyeballs in debt, and there are cross-guarantees between group companies, so the whole lot goes into administration. MADE is unusual, in that it's got net cash, but is burning through it so fast, that the operating company will almost certainly have to be made insolvent. Possibly, leaving some cash at topco level?
Parsley Box (LON:MEAL) - another bombshell yesterday, with an announcement saying that it is considering de-listing the shares. Still has cash in the bank, but needs more. I'll be glad to see the back of this share, so we can focus on more interesting investment ideas with a better chance of success.
On Beach group (LON:OTB) [no section below] - last night I had a quick look at yesterday's trading update from this online travel company, concluding that it's starting to look potentially good value as a recovery share. Here's a link to that comment, if you're interested. It's quite handy to use links direct to particular comments, which you can do by clicking on the thing that looks like a link in a chain, next to any reader comment.
Graham's Section:
Bloomsbury Publishing (LON:BMY) (£341m) - interim results are out for this publisher, famous for its Harry Potter connection. It is a much broader business than just HP books however: it also has significant revenues from a wide range of other consumer books, and a growing academic and professional division. I review the financials here and find little to shake my belief that this is a high-quality business with few faults. It remains confident of achieving its full-year expectations.
Vianet (LON:VNET) (£16m) - a solid update from this “internet of things” company. Beer monitoring systems are fully online again but post-Covid input cost inflation will impact profitability in the short-term, even if revenues get back to the levels seen in FY March 2019 or FY March 2020. Vending machine solutions continue to gain traction. Overall, there are definite seeds of encouragement to be found in this update. I personally dislike the company’s style of presenting itself, but I must acknowledge that these shares could rebound at some point, if profit margins normalise.
Made.Com (LON:MADE)
0.7p (down 90% yesterday afternoon)
Market cap £3m
Update on Formal Sale Process & Strategic Review
Key points -
- Interested parties asked to make firm offers by end October (next week)
- All parties have said they are not able to meet this deadline.
- Hence discussions have been terminated.
- MADE is no longer in possession of funding proposals, or possible offers.
- FSP is still technically ongoing, but in reality I think it’s effectively over now.
- Board is considering the position.
- Will preserve value for creditors (not shareholders!) if it can’t raise further funding, or receive a firm offer before existing cash runs out (no figures or timing is given for this).
- Suspension of listing - might be appropriate.
My opinion - as regulars here will know, I’ve been emphatically ringing the alarm bells about insolvency here for a few months. I get no pleasure at all from seeing people lose money, so am not going to crow about this imminent failure. See our archive here for the warning signs.
Remember this only floated in June 2021, and now looks almost certain to go bust imminently. A total, unmitigated, disaster.
Is it worth a gamble at sub-1p? I would say no, but if it's like betting on the Grand National for 100:1 for fun money, then that's up to you. It's usually not a good idea to throw good money after bad.
As mentioned before, someone is likely to buy it out of administration, so I expect the brand name (and concept) to continue in some form, but with existing shareholders wiped out. A sorry tale.
UPDATE - although note my further comments above, with another announcement this morning raising a feint possibility that there might be some cash remaining at group topco? But this is total guesswork, and liabilities (e.g. bank guarantee re leases) might absorb any remaining cash possibly? Too uncertain to gauge at this stage.
Parsley Box (LON:MEAL)
4.0p (down 58% yesterday)
Market cap £3m
This has been an absolute crock since day 1 - another disastrous 2021 IPO, that we’ve regularly torn to shreds here at the SCVRs, with good reason. Terrible product (I mystery shopped it several times), terrible management, and awful numbers, and horrific cash burn.
I mystery shopped it again here, very disappointing, awful product. Basic principle of retailing - if you appal and disgust your customers with terrible product, you won't have many future customers!
Key points from the latest update -
2022 trading “remains in line with market guidance” (i.e. heavy losses & cash burn)
Cash reserves down to £3.5m
Assessing sources of capital - so it needs more cash, and it sounds like the stock market isn’t interested in pouring more cash down the plughole.
Considering whether to de-list from the stock market.
Mentions the “wider stakeholders” - which is one of the biggest red flags you can get, as this word often indicates existing equity is likely to be worth little to nothing.
My opinion - we’ve made it abundantly clear here at the SCVR previously that MEAL is not likely to succeed, based on the poor figures and high cash burn. To be fair, Directors did stump up a lot of the last fundraise in March 2022 from their own personal funds.
Surely even they must now be realising that the game’s up, hence why they’re thinking about de-listing?
I know it’s easy to be disparaging about companies that are failing, but at least they tried. We wouldn’t get anywhere as a society, if we didn’t have entrepreneurs, prepared to be bold, and try out new ideas, and investors to back them. In the case of MEAL, I think they executed badly, very badly. Bottom line for me, the products were generally awful, just terrible. Meat dishes only had tiny specks of meat, they were more like soup, not casseroles.
The top 9 shareholders at MEAL control almost ¾ of the company, so it looks likely to me they’ll probably just take it private, which would mean saving a lot of costs (listing fees, advisers, unnecessary NEDs, PRs, etc).

.
The interesting thing here, is that in the last fundraise, the Directors were actually quite kind to minority shareholders, and paid a generous price for their new shares (20p). Whereas more hard-nosed types could have screwed private investors. So with only about a quarter of the shares in public hands, worth under £1m, there’s a possibility that the Directors might take it private for around the current share price. Or, investors could just accept the de-listing (if it happens), and continue to hold the shares in a private company, if possible.
Personally, I just like to draw a line under failed investments like this, and move on. Why waste time monitoring some lousy public business, that then becomes a lousy private business?
Bad luck to holders, but it hasn't worked out, and is never likely to work out. Walk away, and find something better to engage your energy, is my view. Holding on to bad investments (or worse, averaging down and hoping for a miracle) just saps your life force, as we've all experienced no doubt.
.
Graham’s Section:
Bloomsbury Publishing (LON:BMY)
Share price: 418.65p (+2.5%)
Market cap: £341m
This is an independent book publisher - see its investor relations website here. Paul analysed its most recent full-year results in June. Today we have interim results for the H1 period ending August 2022.
Shareholders will be pleased to hear that Bloomsbury is confident of achieving the Board’s expectations for the year.
The main numbers:
- Revenues +22% to £122.9m, helped by three acquisitions.
- Organic revenue growth 12%
- Adjusted PBT +23% to £15.9m
- Reported PBT +17% to £12.9m
The CEO describes them as “very strong results”:
These are our highest ever first half sales and profits. These results demonstrate the strength and resilience of our strategy of publishing for both the consumer and academic markets, our growth of digital revenues and our global diversification.
The business is split into “Consumer” and “Non-Consumer” divisions.
The “Non-Consumer” division serves the academic and professional markets. It has “higher, more predictable margins and greater digital and global opportunities”, and includes Bloomsbury Digital Resources, ("BDR") an online service for libraries and researchers
Both divisions saw excellent growth in H1, with the help of acquisitions, but the growth in the Non-Consumer division stands out to me. Within this division, the Digital Resources unit saw revenue growth of 69% to £13.6m. Profit more than doubled to £6.6m.
This unit is targeting 50% organic revenue growth at a 30% profit margin over the next five years.
Strategy - I like this section. Bloomsbury sets out its overall goals and its goals for each unit, and whether or not it achieved them in H1.
The goals in the Non-Consumer division are straightforward enough: it wants growth, and has a stretching growth target for BDR.
In Consumer, it has some non-financial goals:
- “Discover, nurture, champion and retain high quality authors and illustrators, while looking at new ways to leverage existing title rights.”
- “Grow our key authors through effective publishing across all formats alongside strategic sales and marketing.”
- “As the originating publisher of J.K. Rowling's Harry Potter, to ensure that new children discover and read it for pleasure every year.”
It says that all of these goals were achieved in H1, including 35% growth in Harry Potter sales (25 years after initial launch).
Bloomsbury is also looking to “expand international revenues and reduce reliance on the UK market”. It especially wants to “take advantage of the biggest academic market in the USA”. 73% of revenues are now overseas, up from 65% last year.
My view
There’s a lot to like here, and it’s hard to find anything to dislike.
The profit margins are very good for a start. The operating margin drops out at over 10%, and that’s if you take the very strict approach of using the unadjusted numbers.
If you allow the company to apply its adjustments, the operating margin is 13%. And the gross margin is excellent at 54%.
Exposure to the US dollar has tremendously boosted things, too, although you won’t find this on the income statement. It’s in the statement of comprehensive income:
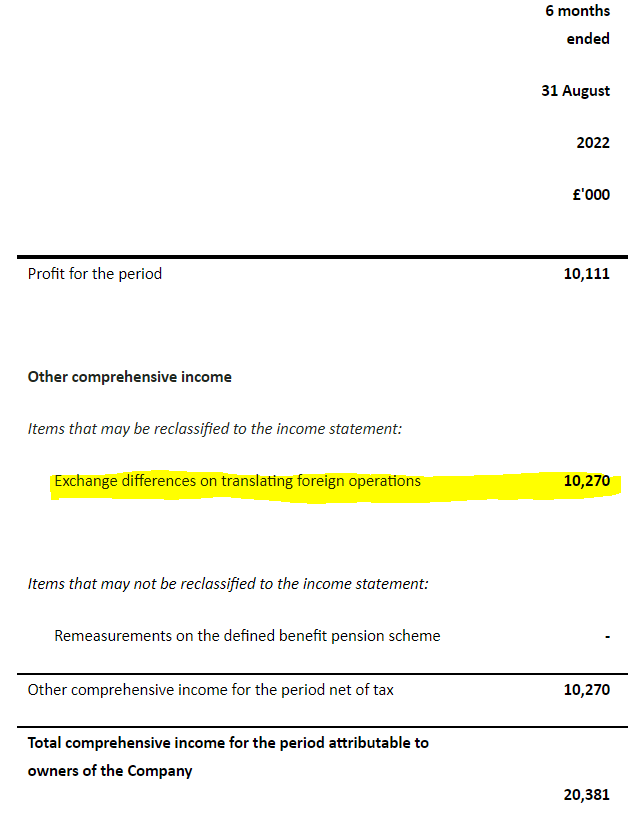
This currency exposure has effectively doubled the company’s overall profits for the period, from £10m to £20m.
Of course you can argue that this is beyond the company’s control and could easily reverse in future periods, but it’s still a very nice boost to the company’s financial picture.
The balance sheet is excellent, with no borrowings (apart from leases), cash of £41m, and net assets of £182m.
Thinking more broadly about the business, I think the digital resource (BDR) unit looks particularly exciting. But there is growth throughout every division.
And while I’m very cautious about companies engaged in heavy M&A activity, there is no denying that Bloomsbury appears to be the rare company that is able to do it successfully.
As it says today, it has completed 18 acquisitions since 2008. During that time, it has paid an attractive dividend stream and its book value per share has, overall, been increasing. ROCE and ROE are not too high but they are, I think at acceptable levels. The Stock gets a QualityRank of 96.
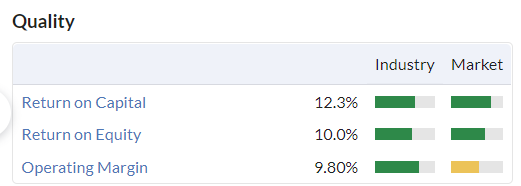
So I’m unable to find fault in Bloomsbury. Have I missed something? Perhaps. But I must tentatively agree with the Stockopedia computers that this is an excellent stock offering good prospects.
Vianet (LON:VNET)
Share price: 56.5p (+10%)
Market cap: £16m
Back in 2019, I noted that Vianet had managed to use almost all of the buzzwords of the era: “cloud-based”, “Big Data”, “Software-as-a-Service”, “ecosystems” and “Internet of Things”.
It looked fairly valued to me, based on its earnings at the time, but it has since endured a rough few years (damaged by Covid, no doubt). The share price is down 60%.
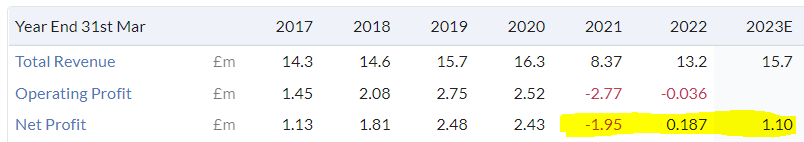
Let’s see what today’s trading update for H1 has to tell us:
The positive momentum in our Smart Zones division in FY2022, as COVID-19 restrictions eased, has continued through H1 2023. The Group's hospitality sector customers are now fully operational on 100% billing, and this has resulted in a strong rebound in year-on-year revenues.
Despite the “challenging” conditions in hospitality, Vianet maintains that this has actually led to increased demand for the data and analysis tools that it provides. Remember that Vianet has been built around the old Brulines business, i.e. beer monitoring systems.
Elsewhere:
In the Smart Machines division, the team continue to win new contracts and build the Group's order pipeline. Continued demand for our end-to-end vending management solution and cashless vending solutions has resulted in a footprint of 52,490 vending connections in H1 2023, up almost 24% on H1 2022.
Financially, we have the following insights:
- Revenues +13% to £7.2m
- Recurring revenue 86% of the total.
- Pre-tax loss of just over £100k, although it looks like it made a small adjusted profit if you exclude the impact of an impairment relating to an acquisition.
Sales should “return to pre-pandemic monthly run rates in FY2023”.
Unfortunately, component costs have risen, so pre-Covid profitability sounds like it will be a big challenge. Maybe new products will help:
The Board expects further improved results and sales growth in H2 2023. A significant new product release is scheduled for November and will establish SmartVend as the industry-leading vending management software platform.
You can check out the SmartVend business here.
My view
I’m always left cold by Vianet’s investor communications. It’s hard to put my finger on why exactly this is the case, but the use of buzzwords is certainly a big part of it
I just don’t come away with a satisfying sense of clarity around the company’s products and progress. It might be entirely my own fault for failing to understand what it is that the company is doing.
Financially, things aren’t great. Paul covered FY 3/2022 results in detail, noting that cash flow had been used up in capitalised development costs.
So we are left in a situation where the company’s core beer monitoring business is less profitable than it was before (due to input cost inflation), and its other activities are yet to take up the slack, while at the same time burning through any cash flow the company is generating.
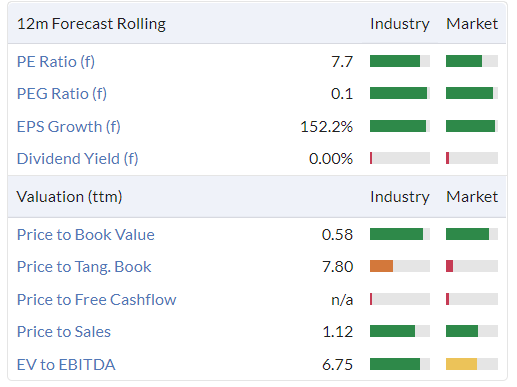
So personally, this is not a share I’d be interested in, though I may be leaving a big opportunity on the table at this valuation. If it hits forecasts it will be cheap here. But that’s a very big “if”.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Paul, once the likes of Made.Com (LON:MADE) and Parsley Box (LON:MEAL) are out of the way, I wonder if this column could start picking up on some of the dull but creditworthy companies still turning in decent results. No one has commented today on the update from Solid State (LON:SOLI), but they have beat expectations, modestly, look set for further progress, and stand on a historically cheap valuation - PER of 14.2 and PEG of 0.6 according to Stocko. I hold these as it happens, but there are more of this ilk out there.
On a different note, thank you Graham for your comments on £VNET. Like yourself, I have been aware of this stock for a long time, but somehow they struggle to get enough money from their customers to pay for the business taken as a whole. In theory, this will change as the vending machines business develops, however, where are the numbers? And their customers must all surely be keeping cash on a tight rein at the moment. I don't hold.
Regarding Vianet (LON:VNET) (I hold)
Warning - Long ramble. Huge apologies in advance. I meant this as a short response. I don’t seem to be capable of that and have ended up with an over-lengthy ramble on why I see an opportunity today in Vianet.
'somehow they struggle to get enough money from their customers to pay
for the business taken as a whole. In theory, this will change as the
vending machines business develops, however, where are the numbers?'
I think that's a good summary of the present situation.
It needs a lot of numbers to overcome the recent level of spending upon product development. All of which is capitalised and there has to be a concern that this is becoming a never-ending treadmill. Add to that the many years over which they have never quite managed to deliver the predicted growth. Does raise the risk a lot. None of which means that they won't achieve the numbers this time (or even next time) but it does mean the sensible option has to be to give it a miss. Presumably thats why the price remains where it is.
I also see the 'jargon-ology' that Graham described. Thank you Graham for the excellent review.
The gratuitous language that caught my attention in this update is
'data lake'
I mean. Puhleas :-)
I sense from this that they are trying very hard to sell themselves, mainly to customers, as a very different company today. Primarily a SaaS type company based upon (near) real-time data analytics, management and payment services from which they derive high margin recurring revenue rather than the box sales of old. I don't think the sales and marketing jargon impresses the small cap investment community much - especially those who invested in the dividend paying Brulines beer flow monitoring of old.
A big problem has been that the dividend paying Brulines of old paid out way too much to afford the product development the company needed to capture new growth markets. Whereas the Vianet of today is spending so much on product development it might never make enough profit to afford a dividend.
Will it end well? Tough one.
My problem is that I like the technology that they have developed and are continuing to enhance. And I like the market that they addressing with it.
In my view the pandemic and lockdowns are having two opposing impacts upon the company.
The most obvious is that it closed much of their customer base down almost overnight. The company acted swiftly to retain connections on reduced revenue during lockdowns. Inevitably a proportion of the customer connections were lost. Mainly old style pubs using the old brulines installations and old style vending machines (typically in offices, with no data connectivity). In effect this has sped up the loss of weaker and lower margin connections. As a result the company is now growing connections from a lower base than pre-pandemic, but once installed these connected devices are much stickier and higher margin recurring revenue.
Pulling in the opposite direction - Rather than hundker down during lockdown the company took a £3m CBils loan and blew it all on continued product development spend. launching its new cloud-based data management portal allowing its customers near real-time data insight and adding contactless payment provisions. I'm sorry it is really hard to get away from all the jargon.
A consequence of the pandemic has been to increase the volatility of sales from all types of sites as demand rises and falls sharply as well as a rise in cashless and contactless payments. For example - does a national coffee chain put in a manned retail outlet on a station platform, or an unattended site? With rising costs of manning the outlet, plus the increased risk of staff not being available - the ability to fulfil demand from unattended sites is increasingly attractive to chains trying to juggle rising costs with demand. Vianet is directly addressing this market. The Costa contract and the recent Lavazza win (across Europe - much of which won't yet be generating revenue) demonstrate the product is attractive and competitive. But the market is still growing from a relatively low base. The product is not limited to vending machines - sorry unattended retail - it is already refitted back into the old pub product as 'idraught', a hub enabling any remote asset monitoring as well as payment solutions, connection to POS, and other site management systems and devices.
Future market is potentially enormous. EV charging stations for example. But then in Vianet speak - it always has been and it might remain potential. Though it wouldn’t need to capture much to transform the companies revenues?
So then it comes down to the numbers, Which on the face of it are slow to recover to their pre-pandemic levels. The recent H1 showing a small loss (after a small writedown of intangibles). The update says that pre-pandemic revenue run rate will be achieved in the current half. Management still expects full year profits of 3.8p eps (I guess that’s probably adjusted in some sense) which implies current profitability is rising sharply from the first half around breakeven.
Even so its trading on over 14x forecast earnings in the FY to march 23 on the current depressed share price of 56p. Which is not cheap in the current bear market.
But an FY 24 with little or no futher growth would double that - 7.6p eps and a much more comfortable earnings multuple around 7x . Good value but not that cheap if it doesn't keep growing?
Will growth in earnings continue in FY24?
There is an assumption that the bulk of profits is provided by the old 'brulines' business. That's no longer necessarily the case .Looking at the numbers - that changed in the second half of last year FY22 - when operating profits at the smart machines division exceeded that of smart zones for the first time. And on lower turnover due to the higher margin of the connections.
The smart machines division increased connections by 25% in the last 12 months - although revenue only grew by 12.5% - indicating a lot of those connections whilst installed have yet to generate their first recurring revenue.
Thats a very promising performance for Vianet - but its early days. And if there is a banana skin out there - I'd fairly much expect them to find it. The headwinds of component prices for device installation and potential slow down in rate of new connections/closure of more hospitality sites are clear hazards if the looming recession deepens.
Thats my basic rationale for my recent investments in Vianet. Not the sensible approach but I like the new product (if not the language) and I like the markets it addresses in the long term. With the shares on 7x the year to March 24 it looks reasonable value right now – with the possibility (always accepting its chequered history) of GARP like growth in for little or nothing. But with little downside risk from here if it doesn’t materialise?
apologies for the over lengthy ramble
cheers
Mark
Eurocell (LON:ECEL) - AXA have been selling out from 5.59% to 1.64%, could be a good reason why the price has dropped down to £1.31 now. £150 mil market cap at current volume.
Bargain I think.
Good Spotting, ‘NewInvestor1972’.
Regarding institutions' buying and selling, how long does it take before Stockopedia picks this up?
According to my screenshot, AXA has not changed its positions since last year.
However, Stockopedia did notice a massive increase in volume sales, on 19/10/22, but according to my non-expert eye, it indicates a positive volume. so slightly confused.
Its recent update (early September for memory) looked favourable and its now below its March/April 2020 low, indeed hasn't been at this low level since July 2018.
Is using the word curated a red flag?
Companies using the word:
Time Out (LON:TMO) down 73% since IPO
Made.Com (LON:MADE) down 99.5%
Chill Brands (LON:CHLL) down 80%
[edit] Unbound (LON:UBG) down 92%.
This deserves more than a thumbs up ! Unbound (LON:UBG) holds my first place for obfuscation (edit : in fact their RNS of 28 July 'Initial launch of curated multi-brand platform')
It’s the same old story. Bullshit baffles brains.
Hi Paul and Graham, the tickers have disappeared again (except Vianet). When this happens, would you prefer us to put it in the chat here or report it on the green button? I know you can put it right quickly, but if it's a tech thing then you might want us to go to the people who can fix it at source (we hope).
Good question, Indie. I'm not sure. I've asked Paul what he thinks! G
I gave Oakley Capital Investments (LON:OCI) the once over following comments below. I think I thought it would be an easy rebuff. It actually looks worthy to me.... perhaps not right now but it can go on the list.
The balance sheet in terms of future commitments looks manageable. The headline number is quite high at £979m but assuming it falls due rather steadily over 5 years... set against current cash and revolver of nearly £200m...certainly no immediate pressure. I think they could raise money easy enough although the discount is a bit of headache.
If I was to take issue it would be the 14x EBITDA multiple. It would be unfortunate if they have to lower this due to lack of growth or comp group multiples at a time they find themselves short of funding. It may represent a headwind for NAV progression which goes some way to explaining the discount. The investments themselves look diversified and balanced. Should pressure fall on valuation and the discount remain persistent then it could be disappointing in a market recovery. The counter argument here would be that the large fund V is in a strong position to make great investments and likely strong NAV progress in the outer years of a 5 year cycle.
This is why I think I will wait since short term upside would be limited to a partial closing of the discount. Longer term I agree it looks very solid and probably quite exciting after more funds are deployed in the V vintage.
Oakley Capital Investments (LON:OCI) the EBITDA multiples are actually very reasonable compared to some of the other venture type PE funds, and at least they are very open on their valuation metrics. It's also good that the majority of NAV growth is driven by earnings growth. Something like Molten Ventures (LON:GROW) doesn't even disclose its valuation metrics, where valuations appear to be largely based on previous funding rounds.
I see Revolution Bars (LON:RBG) are "rewarding/giving away" 4.5 m shares to directors in 3 years time, subject, besides other things, share price movement. Do we ever get to hear what the target share price needs to be to trigger these awards?
Revolution Bars (LON:RBG)
Do we ever get to hear what the target share price needs to be to trigger these awards?
I think that's unlikely!
According tot he RNS the Remuneration Comm will decide - essentially as they see fit at the time! It looks pretty shocking to me.
subject to the Group's Remuneration Committee being satisfied that the Group's underlying performance and delivery against its strategy and plans is sufficient to justify the level of vesting having regard to such factors as the Remuneration Committee considers to be appropriate in the round
Yes, I saw that announcement from Revolution Bars (LON:RBG) about share options. There are 230m shares in issue, so it's about 2% of the company. It always rattles my cage when I see share options being issued in a bear market. It feels like a kick in the teeth to shareholders, who have suffered the losses of a plunging share price, whilst management give themselves some free upside, on top of generous salaries.
Trouble is, if you kick up a stink about these things, nothing happens, because the institutional shareholders wave it through.
It was good to see some operational management being given share options too, but the overall numbers look far too heavily skewed to the CEO & CFO. Why does a CFO need share options at all? Yes it's an important role, but they're essentially keeping the score, not leading the team in a way a CEO does.
There's a lot of evidence to suggest that rewards from share options are often random - if you happen to be in a CEO job when the economy soars, profit soars, and the options become valuable. Plus they can incentivise excessive risk taking, e.g. using too much leverage to make reckless acquisitions.
Regards, Paul.
I'll hold my hands up as I bought Made.Com (LON:MADE) @ £2.00 & sold it very shortly afterwards at £1.98. Thank the various deities for that.
I only bought an investigatory position e.g. enough for me to have a proper look at it as remember their sofas came up quite often when we were looking for a new one, ended up going with DFS with a 16 week lead time fwiw. It was classic jam tomorrow I think the promise was of profitability as the revenue grew & then operational gearing kicking in. Revenue was growing rapidly when I looked at it which is why I was interested. I think there were also interesting incentives for the designers.
It's a 1 company example of the exuberance that was in the markets last year. Not a company that I would even slightly consider this year. I may print out the buy contract note as a reminder to stick to good companies at fair valuations otherwise I should just buy an index and forget about share picking altogether.
I know Paul there are clear warnings signs when a company is in trouble but perhaps you could do a piece on warning signs that us less knowledgeable ones would find helpful.
Re Made.Com (LON:MADE) I'd be fascinated to understand what went wrong both in case there are helpful lessons or 'warning signs' for investors and also for the benefit of helping UK plc generally. From a customer perspective I loved its products which I thought were very well designed and well-marketed, and reasonably priced (for the quality). I feel rather disappointed it's on the verge of administration just as I've moved into a new place!
I've never gone through its accounts but it did strike me that it sold a lot of different product lines - even to me as a customer it felt a bit much at times. Did it try to expand too fast and stretch itself too thinly? Are the days of doing a fast online land-grab, and hoping investors/banks will continue to cough up, over for now? For similar online retailers should we be wary of anyone trying to expand too rapidly? Arguably something similar happened at Purplebricks (LON:PURP) although that's hanging on for now due to its pots of cash although it is struggling with profitability as well.
Re Made.Com (LON:MADE) I'd be fascinated to understand what went wrong
“Events, dear boy, events”
One factor is the marketing spend was far too high. It didn't make money even at the EBITDA level so was growing without a firm foundation IMO. Obv the supply chain caused big issues too. It should have been a great model with low working capital requirements.
Purplebricks have poor customer service. Best avoid.
My experience.....as Paul mentioned with Parsley, the product is key to failure, I ordered a number a few years ago and some were ok, but most were terrible quality for the price. At least with IKEA you know what you are getting.
My own experience has been the opposite. All the products I've had have looked great and seem well constructed.
Assume you are talking about IKEA products ... and not Parsley Box (LON:MEAL)'s.
My experience.....as Paul mentioned with Parsley, the product is key to failure, I ordered a number a few years ago and some were ok, but most were terrible quality for the price. At least with IKEA you know what you are getting.
Here's Liberum's initiation note in 2021:
"MADE is disrupting a £94bn market which is at a tipping point of online adoption. It has a disruptive vertically integrated model with strong competitive moats. MADE is about curation and inspiration and its design-led focus differentiate it from the wider market. Operating a just-in-time inventory model that, backed by MADE's proprietary technology, de-risks the model while maximising working capital and marketing efficiency underpins an attractive financial profile. With multiple drivers for sustainable long-term growth the roadmap ahead is compelling." TP 250p.
Since when is a store that designs its furniture and owns its factories disruptive? Like Ikea, MFI and Thomas Chippendale come to that. And when I hear the word curation I reach for my gun.
Any use of the phrase
"...<company> is disrupting the £<many billions> market..."
is an big avoid signal for me.
Re Parsley Box Parsley Box (LON:MEAL) this is what I said on my blog in April 2021: "I have now sampled their products – prepacked dinners and have come to the conclusion that I question whether this is likely to become a great company. The meals are rather bland and you can buy cheaper equivalents from supermarkets. They do have the advantage of a long shelf life and do not require refrigeration, but so do other products such as canned goods so I am not convinced there is a big market for them. The company is spending money on national TV advertising, on channels focused on the elderly like me. You can always generate sales if you spend enough on marketing, but that does not necessarily mean that you have a profitable business". From Paul's comments it seems the products got worse not better. Looks like I judged it right.
Bloomsbury
Rock solid yet again .
If there is one share I have that gives me zero cause for concern it is Bloomsbury .
Well run, built on granite , loads of cash , backed up by the Harry Potter “most”
Investing would be so easy if you can find 5-10 of these and just sit back and let them deliver year after year .
Graham's reviewing £BMY as we speak, should be up soon!
Never really looked at Parsley Box (LON:MEAL), but what is striking above is that Schroders appears on the list - not like Andy Brough to chase a crock of s***t!
Andy's fund invests in about 300 small caps from what I remember - so naturally is going to get the old piece of s**t in there. Richard Leanard, the arrogant family fund manager of PI World fame, only manages 8-10 stocks and kept raving about Made.com being his no.1 pick last year. and how he would make "a LOT of money".
Tamzin please tell me - when is Mr Leanard back on PI World? Cannot wait for his next interview.
Dulpesh we have all had disasters especially over the last 12 months, poking fun at siomeone who puts themselves out there is hardly fair. That said no doubt Richard bailed long ago as the story changed, I would have.
Me neither!
...but we all make mistakes.
No plans to interview Richard at the moment. Yes, he got it wrong on Made.Com (LON:MADE) but got it right on Bloomsbury Publishing (LON:BMY) which is the stock that keeps on giving whilst paying you while you wait.
Parsley Box (LON:MEAL) seems to have been one of many eCommerce floats in 2020 and 2021 that presented growth due to the pandemic as if it were structural growth. It fooled a lot of us, including the fund managers that overpaid by a factor of 10x or more for some of these floats. So we shouldn't feel too bad if we also got it badly wrong, as so did many of the professionals. Although personally I was never attracted to MEAL because on mystery shopping it, the food was absolutely awful! So it was obvious that they wouldn't get much repeat business. Parsley Box's product makes a 1970s school dinner look like cordon bleu - if it was discovered congealed at the back of a cupboard 50 years later!
It's easy with hindsight to see that eCommerce sales were unsustainably high in 2020-1, with the physical shops often closed, and £400bn of QE printed as soon as the pandemic started, which was used to buy up all the Gilts issued at super-low yields by the Treasury, to fund enormous cash bungs to businesses & households. Meanwhile, we sat at home, with something like £150bn of "enforced savings" piled up in bank accounts, and went on an eCommerce spending spree. I know I did, with Amazon turning up at least once per day, plus rails of new clothes appearing in my bedroom, as I "mystery shopped " £JOUL , Next, and French Connection numerous times.
Also, I remember commenting on a webinar that the actual product from MEAL looked absolutely nothing like the photos in its catalogues or website. The CEO acted surprised when my comment was read out, so he was either deluded, misleading us, or maybe just wasn't aware that the product being churned out was absolutely dire. To be fair, there were one or two items which were nice, e.g. the half bottles of red wine, and some cake.
So I feel that in this case, just trying out the product told me everything I need to know. Plus the awful, cash burning accounts of course. Put those two things together, and it was very easy to avoid this share from day 1, which is not hindsight, it's as set out in a total of 18 negative articles here about MEAL, so I'd be very disappointed if any SCVR readers lost money on this share.
We're pretty good at spotting inadequate business models and finances here at the SCVR. Maybe that's half the benefit of these articles, to steer people away from the worst shares? And obviously if we don't cover anything at all, then it means we think it's no good.
Regards, Paul
On initial reading, the interim results from Bloomsbury Publishing (LON:BMY) look extremely good and bode well for the future. I need to look at the numbers in more detail, but remain a very happy holder. Despite recent acquisitions, the company has £41.5m of cash with undrawn lending facilities and is increasing its overseas earnings. US revenues increased to 36% of Group revenue.
One interesting and tantalising titbit relates to the release of a Netflix production based on a novel by one of the company's authors, see below. If the film is half as popular as Games of Thrones, it would I suspect provide a significant impetus to earnings. Merely speculation but one never knows.
"TheThree-Body Problem by Cixin Liu, a HoZ title, has been filmed by the creators of Game of Thrones and will be shown on Netflix in 2023."
All views and comments welcome. Paul/Graham any thoughts?
Good to read that Bloomsbury Publishing (LON:BMY) had their “highest ever first half sales and profits” and are increasing the interim dividend by 5%. (I hold.)
Good update out of OCI today. I hold. Shares continue to trade at a whopping discount to NAV. Only issue is can they generate enough cash to meet future commitments. Directors and entrepreneurs have serious skin in the game. I continue to hold and will buy when I have free cash.
I agree. a good morning it would appear. I hold Oakley Capital Investments (LON:OCI) and Bloomsbury Publishing (LON:BMY)
MADE a MEAL of it! Ok, I'll get my coat
It's not a DEAL MADE in heaven......