Small Cap Value Report (Weds 7 Dec 2022) - OMG, MMAG, SDI, MOON, WINE, MSI, REDD, QUIZ

Good morning from Paul & Graham. Today's report is now finished, we got through nearly everything on the agenda, it's a nice feeling when that happens!
Agenda
Paul's Section:
Oxford Metrics (LON:OMG) - FY 9/2022 results from yesterday don't look particularly good, but under the surface something interesting seems to be happening here - strong demand, and a big increase in order book, plus delayed orders (supply chain) suggest a much better year is likely for FY 9/2023. Over half the market cap is a huge net cash pile, from a remarkable deal disposing of Yotta. Overall, I think this share looks very interesting, and is still reasonably priced. It gets a thumbs up from me. Over to you - OMG looks worth a closer look.
Musicmagpie (LON:MMAG) [quick comment] - a series of profit warnings, collapsing earnings forecasts, and rising debt, led me to regard MMAG as uninvestable here in Sept. Shares have bounced strongly (in % terms) from the lows, so is there hope of a recovery, or is it a dead cat bounce? Today it says trading for FY 11/2022 has been in line with expectations. But bear in mind expectations have been lowered from 7.5p EPS to -0.1p EPS. Net debt is £8.2m (better than expected) out of a £30m facility. Record Black Friday sales, and it talks up the prospects for its mobile phone rental offering. I remain unconvinced this is a viable business model, but at least trading is not getting any worse. £28m mkt cap looks (mag)pie in the sky to me! [no section below]. EDIT: note that even the house broker doesn't think it will generate any PBT in the next two years.
Moonpig (LON:MOON) - We warned readers here in Sept that Moonpig looked to have overpaid for a large, debt-financed acquisition. That's very much confirmed by today's interim results, which show how the balance sheet has been wrecked by this acquisition, leaving a vulnerable consumer discretionary business that's facing tightening demand, and with a mountain of debt to service. Risk;reward looks poor to me, so I'd steer clear of this one for the foreseeable future.
Naked Wines (LON:WINE) - Interesting interim results, seem to show some progress has been made. The main problem is wildly excessive inventories, which have peaked at over £200m. It's taken a £8m hit against those (adjusted out of the headline numbers, of course!), but I worry such an extensive wine lake could have other nasties lurking in it. It's also spending customers' cash, which I don't like, it should be ring-fenced. I discuss the bull & bear points below, and think this share could go either way, so am neutral.
Redde Northgate (LON:REDD) [quick comment] - Interim numbers look fine to me. It presents more conservative underlying numbers (which seem to strip out the unusual profits on disposals from temporarily high vehicle residual values), alongside statutory numbers. There’s also an important section on timing differences re residual value/depreciation changes, that seems to be pulling in some extra profit this year. That’s probably why next year’s forecasts are down (45.8p vs 49.1p). Full year outlook is good - “modestly above market expectations”. My view - the value investment case looks good - fwd PER of 7.9, divi yield of 6.0%, nicely asset backed too with P/TBV of only 1.26. Don’t worry about the debt, as it owns £1.1bn in vehicles, which is much more than the debt. Thumbs up from me. (no section below)
Quiz (LON:QUIZ) [quick comment] - good interim figures out today. H1 profit of £1.8m, on almost £50m revenues. Very strong gross margin at 61.6%. Excellent balance sheet, with £9.2m net cash (down to £7.8m as of yesterday - normal fluctuation, not a concern). Current trading - weak in Oct, better in Nov. FY outlook - at least in line with market expectations. My view - great to see the business fully recovered from the pandemic, and profitable again. Still looks cheap to me. (no section below)
Graham's Section:
SDI (LON:SDI) (£166m) - these interim results have disappointed the market, although there is no change to revenue and adj. operating profit forecasts. What has changed is interest rates, and a higher interest bill will take a small bite out of SDI’s adj. net profits this year and probably next year, too. Net debt has risen to a level that is unusually high for SDI, but the company maintains that its balance sheet is “unstretched” (i.e. it has a low net debt/EBITDA multiple) and that it can carry on with further acquisitions. Unfortunately, organic revenue growth has fallen to just 3.8% and looks like it remains vulnerable, due to an ongoing reliance on some Covid-related sales. I agree with sellers today who have helped to push this to a more modest PE multiple. SDI still has the ingredients of a high-quality compounder but without organic growth I would be wary of overpaying for it.
MS International (LON:MSI) (£61m) - excellent H1 results from this very quiet, family-controlled group of businesses. Even after nearly 30 years of consecutive dividends to its shareholders, MSI’s cash balance (£24m) remains formidable as a percentage of its market cap. Today’s strong results (PBT of £3.5m) were achieved without any contribution from the company’s Defence division, which will hopefully be able to make meaningful profits in the years ahead with the help of a large US Navy contract. I love finding quirky businesses like this which quietly do a good job for their shareholders. MSI gets the thumbs up from me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Oxford Metrics (LON:OMG)
101p (up 12% yesterday)
£131m
Oxford Metrics plc (LSE: OMG), the smart sensing software company servicing life sciences, entertainment and engineering markets, announces preliminary results for the financial year ended 30 September 2022.
- Year of strategic progress with disposal of Yotta -
- Record order book underpins more than half FY23 revenue expectation -
- Overall strong demand picture provides encouraging momentum into new year
FY 9/2022 key numbers don’t look particularly remarkable -
Revenue up 5% to £28.8m
Adj PBT down 36% to £2.6m
Adj basic EPS 2.55p down 7% (and giving a PER of 40x hardly a bargain at first sight)
Dividend of 2.5p (up 25%), giving a yield of 2.5% (note there is only a final divi, no interim divis, and a flurry of special divis were paid in 2015).
As you can see below, the longer term track record doesn’t really show much progress over the last six years -

.
So what’s all the excitement about?! Onto the positives -
Net cash pile of £67.7m, which is 52% of the market cap, which mostly arose from a stunning deal to dispose of its Yotta subsidiary for £52m. This also was the main contribution towards the statutory profit of £47m for FY 9/2022, a one-off.
Delayed orders due to supply chain saw £3.5m of orders deferred into next year, which on a high gross margin (it’s 68% overall), might have hurt FY 9/2022 profit by about £2m perhaps, and that could be recouped in FY 9/2023, if supply chains normalise maybe?
Finance income of £305k in FY 9/2022 could increase considerably now, e.g. a 3% interest receivable rate on the £67.7m cash pile could see c.£2.0m in finance income this new year.
Huge increase in order book looks very interesting - up 307% to £24.0m, which looks nearly comparable with revenues for the whole of FY 9/2022 (£28.8m).
My main questions are -
Q1. What are they going to do with the cash pile? It’s c. half the market cap, so highly material.
Progressive suggest that management are looking at acquisitions, but finding price expectations still too high. Very sensible! So it sounds as if they’re likely to sit on the cash, until the right opportunity is found - I’d say that’s ideal, as there’s less chance of them making a horrible mistake. Also management has already proven its skill in acquisitions & disposals. The deal with Yotta was barn-storming, as it looked a waste of time, yet they sold it for £52m! So these people clearly know how to do favourable deals.
Q2. What’s caused the huge increase in order book, and is this likely to continue? If so, we might be witnessing one of those rare, but lovely situations where companies see a step change in demand upwards, which can be very lucrative.
A note from Progressive (i.e. effectively from OMG, just indirectly) says that customers are more willing to place orders now, to ensure supply. Hence this suggests maybe some front-loading of demand, that could ease in future, possibly? Even so, the massive increase in order book speaks for itself - clearly OMG has products that are in strong demand, which I like a lot.
Forecasts - Progressive has pencilled in a hefty 28% rise in revenues to £36.9m in FY 9/2023, and the commentary says this does not include catching up with delayed orders, hence there could be upside on this number. The tone of the note suggests forecasts are more likely to be raised, than reduced, which I like. Although it is increasing overheads in some areas, to develop the business.
Adj PBT is expected to go up from £2.6m to £5.9m, and it sounds like there’s upside potential on that number too. If achieved, that would be 4.1p adj EPS.
Tax charges are lowered by R&D tax credits.
Valuation - the obvious way to value OMG, is the £131m market cap, less the £68m cash pile, giving a cash adjusted market cap (or EV) of £63m.
If it hits forecasts of £5.9m+ PBT his year, then that looks an attractive valuation, a PER of about 12 (I’ve assumed half the normal corp tax rate, at 13%, to allow for tax credits).
My opinion - this looks very interesting, and it gets a thumbs up from me on a quick review.
Outlook comments also sound positive, yet the valuation is still reasonable.
I think this share could do very well, if demand continues to be buoyant.
So I’ll hand it over to you, for more detailed research - well worth a closer look in my view.
.
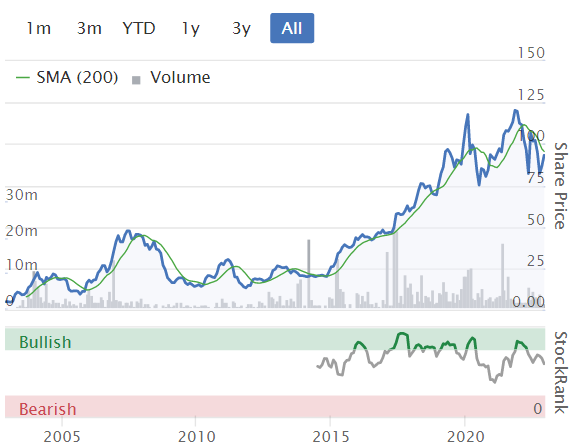
Note the StockRank is upper-middling. This is an interesting one, in that I don't think the Stockopedia computers would necessarily know that 52% of the market cap is now net cash. So paradoxically, when the FY 9/2022 figures feed through into the data, we might even see the quality score fall, since it would look as if things like ROCE had fallen. So it might be a situation where man can do better than machine?!
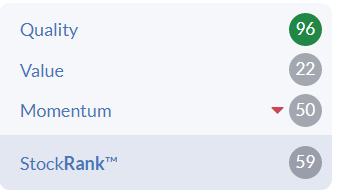
For the same reason, I think we can ignore the value score, because that also probably won't know that half the market cap is net cash.
Moonpig (LON:MOON)
123p (down 19% at 08:42)
Market cap £419m
This is one of the day’s largest % fallers, so we need to take a look at what’s happened.
I last looked at MOON here on 21 Sept 2022, concluding that it had overpaid for a big acquisition, and taken on too much debt, at the wrong point in the cycle.
H1 results to 10/2022 (for FY 4/2023) don’t look great -
H1 revenue flat at £143m
Adj PBT down 22% to £18.9m
Disruption from Royal Mail strikes.
Outlook comments say trading has become “progressively more challenging” in Oct & Nov.
Revenue guidance for FY 4/2023 now £320m (but annoyingly doesn’t say what previous guidance was). Stockopedia shows £343m forecast.
Guidance for EBITDA unchanged, due to “actions taken” - looks like cost-cutting, especially marketing spend.
Expecting gearing to reduce in H2, to between 1.9x and 2.0x EBITDA by 4/2023.
Net debt now too high for me, at £208.8m, was £113m a year ago. Of this £19.8m is lease liabilities, so net bank debt is £189m.
Bank covenant is 3.5x EBITDA (from April 2023 until Jan 2026)
The company recognises debt is too high, and it sounds like there won’t be any divis -
Our short-term priority is deleveraging.
Finance costs of £5.8m in H1 uses up 39% of operating profit, so funding the debt pile is definitely an issue. Note 13 gives detail of interest rate hedges.
Going concern note - the company gives itself a clean bill of health here, which surprises me. There again, online businesses do have a flexible cost base, and can reduce marketing spending very easily. Although that could result in a downward spiral of falling revenues & eventually profits.
Balance sheet - was bad before the big acquisition, and now looks absolutely dreadful.
NAV is negative at £(57)m, but that includes £213m of intangible assets, mostly goodwill on acquisitions (and similar, they call it something else now). The big acquisition seemed to have negative NAV of £(47)m, so has made MOON’s balance sheet a lot worse, on top of the goodwill. Writing off all intangible assets, gives NTAV of an alarmingly negative £(270)m. Although with little in the way of inventories or receivables, you could argue that it doesn’t need a strong balance sheet.
Note 8 shows that it also capitalised £6.66m of internal payroll costs relating to IT development in H1 - hence EBITDA is not meaningful.
Trade payables have shot up, with note 12 showing a new payable of £49.3m (zero in the prior year comps) called “Merchant accrual”. The commentary explains what this is - being the money owed to providers of experiences, where MOON has received the voucher cash up-front -
The merchant accrual balance acquired upon business combination with the Experiences segment was £61.2m. A payables balance is recognised when a gift experience is sold to a consumer, to reflect the expected future liability to the merchant; this balance is settled through the remittance of cash to the merchant following redemption of the voucher by the recipient.
My opinion - this looks a bit of a mess to me. It’s quite clear now that, as I previously thought, the big acquisition of Experiences was a terrible mistake. It seems to have added little profit/cashflow, but come at a massive cost, funded through debt, which is now too high.
Management seemed oblivious to the consumer downturn, and that its products don’t get much more discretionary, so are likely to suffer when consumers curtail discretionary spending.
Demand is softening, so it’s maintaining EBITDA by cutting marketing spending - which I imagine would itself then cause revenues to fall.
In happier times, and with little to no debt, MOON would look a good business. But in tough times now, with a mountain of debt on its very weak balance sheet, I think MOON looks vulnerable.
Is it likely to go bust? If things get really bad, with an extended recession, it cannot be ruled out. If the business shrinks, and has to chase its own tail by reducing marketing spending, then it’s possible a downward spiral could emerge, with the debt mountain then becoming an existential problem, requiring a big equity fund raise.
Even in the upside case, where everything turns out fine, with debt reducing over time, shareholders probably won’t get any divis for several years.
For me therefore, risk:reward looks poor, and any ideas I had of buying this share for a recovery are off the table completely for the time being. I can see why people are ditching the share in the market today, that looks entirely logical to me. Why take the risk?
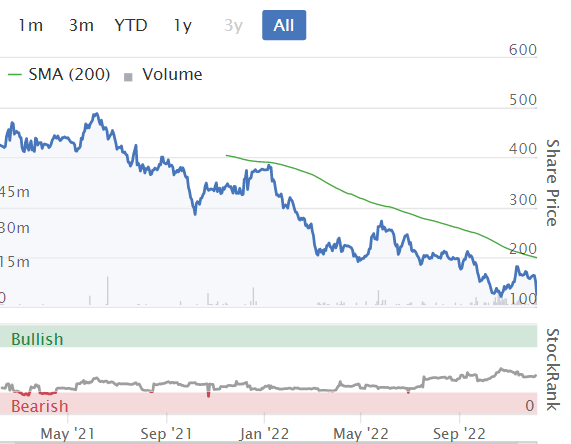
The poor fundamentals suggest that sub-100p could just be a matter of time.
This one is another disastrous, over-priced 2021 float. No wonder the IPO market is dead now, after all those fund managers got stuffed with things like this.
.
Naked Wines (LON:WINE)
100p (up 3% at 10:55)
Market cap £74m
Naked Wines is the larger of the two listed wine subscription services (the other being Virgin Wines UK (LON:VINO) ). It’s a bit of a special situation, where it ran into various problems, which I won’t repeat (it’s all in our archive here), and the issue now is whether the turnaround actions are working or not?
H1 figures (26 weeks to 26 Sept 2022) -
Revenues up 4% to £165.8m
Adj PBT has improved to £4.6m (H1 LY: £1.7m)
Statutory PBT is a £(215)k loss.
Adjustments of £4.8m include a £7.9m provision (cost) to write-down the value of US inventories. See note 4 for more detail on other adjustments.
Improved adj PBT has been achieved by slashing advertising costs by 44% to £10.0m (saving £7.9m) - but as with Moonpig above, will this have a negative impact on future sales? It stands to reason that it would, otherwise the implication is that advertising/marketing spend is just wasted money.
Current trading -
Currently, we are trading profitably in line with our expectations over the key holiday quarter and reconfirm our revised guidance for FY23 shared in October.
Profit guidance - is adj EBIT of £9-13m for FY 3/2023
Balance Sheet - has been boosted nicely by favourable currency translation of about £17m (see reserves section of BS), with NAV now £127.3m - note this is well above the market cap. Deducting £37.2m intangible assets gives us a still-healthy NTAV of £90.1m.
The stand-out item is the gigantic inventories figure of £209m. The company has said before that it plans on de-stocking. To put this into context, H1 cost of sales was £93.3m. So inventories of £209m is over 13 months of sales. I appreciate that selling wine might involve storing, or advance purchasing, but even so this is clearly a wine lake that is way above what it should be. Given than a provision of almost £8m was booked in H1 (against wines that will have to be sold below cost), I suspect that might not be the last provision needed against excessive inventories. When problems like this emerge, they tend to leak out gradually, with the first hit not being the last. Sometimes they can be much, much worse than anyone imagined, which is why excessive inventories is such a big risk.
Cash is down to £41.6m, and there’s a new term loan of £18.7m, so net cash is £22.9m. Sounds OK, but it’s not, because WINE is holding £87.7m of customer’s cash (that’s what the “Deferred Angel and other income” liabilities represent. So basically, WINE has spent the customer’s cash, to a large extent. That’s not illegal, but it strikes me as unethical. Note that small competitor VINO keeps customer cash in a separate trust account, which is much better.
My opinion - the main issue is that WINE needs to dig itself out of the big hole of its own making - buying up loads more wine than it should have done.
My main worry is that the wines it holds in excessive inventories could be wines that customers don’t like. Therefore de-stocking may not be as simple as the commentary implies.
This share could go either way.
Bull case - if it successfully reduces inventories (which need to roughly halve, I think), and achieves the guidance for improved profits, then I could see this share maybe doubling or more.
Bear case - that the massive inventories could contain a lot of poor wines that it can’t sell, leading to more write–offs, and erosion of the balance sheet. If forecasts are not achieved, and customers drift away because of reduced marketing spend, then the cash could run out (as customers withdraw it), leading to potential solvency problems.
Overall, I think it looks fairly evenly balanced, and could go either way.
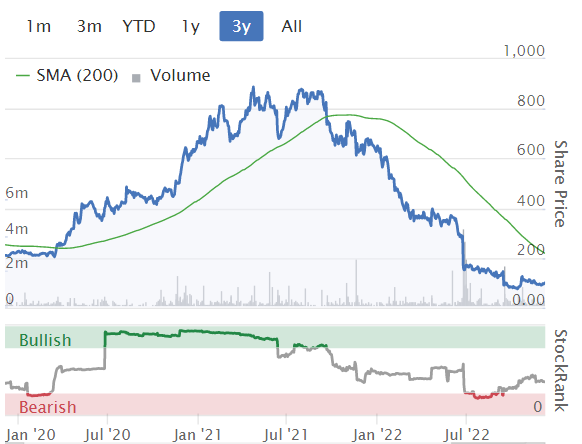
It's hardly issued any new shares in recent years, so theoretically there could be good upside on the share price from here. Although the bull market pandemic valuation was nuts.
Graham’s Section:
SDI (LON:SDI)
Share price: 161.5p (-6.65%)
Market cap: £166m
This is “the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications”. I tend to think of it as a smaller version of Judges Scientific (LON:JDG) or a much smaller version of Halma (LON:HLMA) .
Let’s look at the interim results for the period to October 2022.
Firstly, the outlook for the full year is in line with expectations.
However, these market expectations only relate to sales of £66.3m and adjusted operating profit of £12.8m. The estimates for adjusted PBT and adjusted EPS have marginally reduced, both for this year and for next year.
H1 headlines:
- Revenue +28% to £31.7m.
- Adj. operating profit +19% to £6.9m.
- Reported operating profit +7.7% to £5.6m.
Nearly all of the growth is the result of acquisitions, with only 3.8% organic (Judges Scientific did better at its interims, reporting 7% organic revenue growth for the H1 period to June). SDI says that this H1 period is up against “stronger comparatives” compared to last year.
Acquisitions - four companies have been acquired during the calendar year so far.
I spoke to the company’s new CFO at Mello last month and asked whether the company might outgrow their existing acquisition strategy soon, and need to start acquiring larger companies. The response was that the current strategy would remain viable for several years.
Looking at the acquisitions so far this year, their price tags have been (net of cash acquired): £13m, £4.2m, £7.7m, £4.9m. So the company is still working at the very small end of the spectrum.
Trading - mixed comments on trading, including that “demand from OEM customers was more variable this half year than the equivalent period last year”, and supply chain issues continue to pose difficulties across all of SDI’s businesses.
In better news for the company, “inflationary cost increases have, in general, been passed on to customers where possible and gross margins have generally held”. I would hope and expect that SDI would have the pricing power to enable it to do that.
Revenues - are being boosted by large orders received by ATIK relating to cameras for PCR machines. These orders were received from a particular customer and they will be completed during H2. SDI has “no visibility” of future orders from this customer.
It sounds like organic revenue growth is going to remain challenging at SDI. Covid gave rise to “revenue and profit fluctuations which have not fully settled yet”, and if the PCR-related orders are finished soon, then I’m not sure that SDI will be able to make up the difference with other activities.
Profits - margins have reduced due to the acquired businesses having lower margins than the group as a whole.
It may also be important to note that “most of our power and heat costs are fixed until Q1 2023” - so there could be a vulnerability in H1 next year.
Net debt - rises to £15.4m, from a net cash position six months previously. Headroom on the bank facility is a further £6m, with possibly an additional £5m available on top of that.
Outlook
The COVID 19 related orders at Atik will complete this financial year, as has been previously communicated. The weighting of these camera deliveries are skewed to the first half of the year. SDI Group continues to execute on its business model, adding two quality businesses to our portfolio and maintaining growth. A higher interest rate environment will lead to a small increase in interest rate expense in the second half. We look forward to delivering a full year trading performance in line with market expectations.
My view
The market has reacted negatively to this statement, although it doesn’t appear to contain very much that is new.
It does contain the news that interest costs are increasing (but is this really news?).
Accordingly, the company’s broker has increased their estimate of SDI’s interest cost for the current year by £0.4m. They trim the adjusted net profit forecast from £10m to £9.7m. They also make a tiny downward adjustment to next year’s adjusted net profit forecast (£9.9m).
My guess is that investors are disappointed to see confirmation that organic growth is at such a low level (3.8%), despite inflation being passed onto customers. This implies that volumes are down organically.
I also read overnight that China is planning to reduce the amount of PCR testing it does. If PCR is finished as a mainstream pandemic tool, then ATIK’s PCR-related orders might also be finished, and achieving organic growth might be even harder for SDI next year.
What all of this says to me is that SDI can reasonably be valued on an ex-growth basis. Sure, this might just be a temporary blip due to the recessionary conditions. But does it make sense to pay a growth company valuation for a company that isn’t growing and that now has a net debt position to manage? I don’t think so.
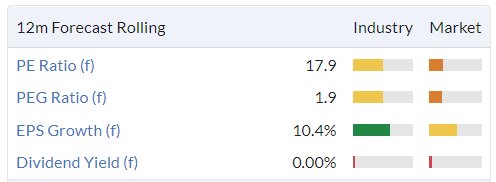
With the company trading at a PER of nearly 18x last night, I can understand why the shares have come off this morning.
Over the long-term, I would still expect SDI to do fine, assuming that they don’t take on too much financial risk. They appear to be very relaxed about their cash position:
The Group has an unstretched balance sheet and has sufficient access to funds, alongside its steady cash flow, to acquire new companies and invest in our current portfolio of businesses.
I don’t understand why they would want to fly close to the sun - why not spend a year paying off the debt, bedding in the recent purchases, and then carry on with acquisitions?
I still agree with the consensus that this company is of much higher quality than your average AIM stock. The track record is very good, over many years. However, in the absence of growth I would put it at a modest valuation multiple for the time being.
MS International (LON:MSI)
Share price: 377p (+9%)
Market cap: £61m
I’ve just got off the phone with the highly knowledgeable investor Simon Hedger - who tweets at @vokdaquickstep - and has MSI as his top holding, for some extra background info on what is happening at this company.
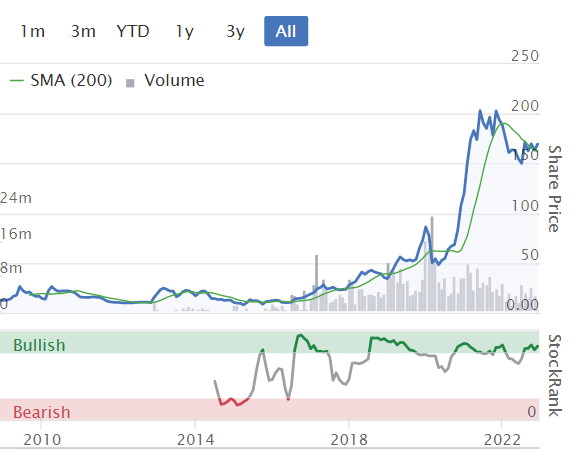
It’s now up by over 25% since we last covered it in the SCVR in June.
It has been a rare outperformer this year, and has had an excellent few years in terms of share price performance.
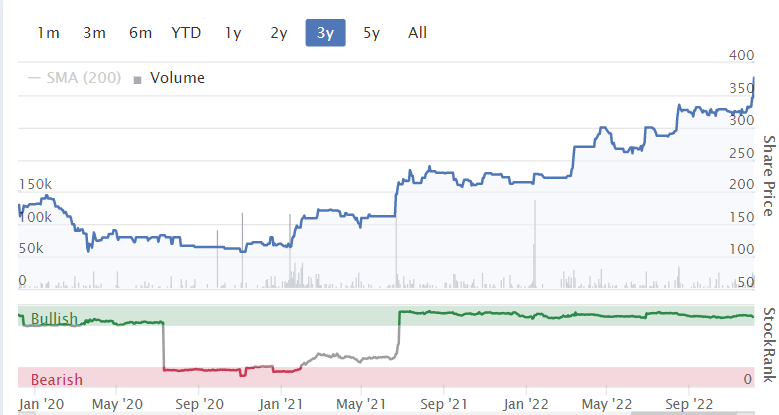
This company has paid annual dividends ever since the early 1990s, and its dividends have generally increased over time. Not your average AIM stock!
It is a family-controlled business, with fewer than half of the outstanding shares trading freely. There are four operating divisions:
- Defence
- Forgings
- Petrol Station Superstructures
- Corporate Branding (link)
For more information, check out its Berkshire Hathaway-style website (I am long $BRK.B).
The company issues the bare minimum of RNS announcements, and has no broker coverage (both are indicators of a potentially good investment, in my book!).
Let’s see what we can learn from these interim results for the period ending October 2022:
- Revenue £42m (last year: £33m)
- PBT £3.5m (last year: £0.8m). No adjustments.
- Cash £24m (last year: £15.5m). No borrowings.
Now looking at each division in turn:
Defence
This division “carried substantial costs” in H1, as operations were moved into upgraded facilities in Norwich.
MSI investors are very excited about the possibility of a large US Navy contract, and have been digging into the details around this. Today’s RNS includes the following:
Pleasingly, our participation in the United States Navy's multi- phased programme of 'weapon approval procedures' with respect to our 30mm Naval Gun System, continues to progress through their comprehensive testing procedures. We are encouraged with their observations to date. A great prize, still for us to win! Our existing land and building facilities in South Carolina can be further developed, to meet any resulting defence opportunities.
I don’t think this project is officially “in the bag” but it sounds like it is very close. By all accounts, it could make a big difference to MSI in the years ahead.
Forgings - MSI’s steel forging facilities in the UK, US and Brazil “continue to operate at a high level of activity”. The challenge of rising energy costs “is being successfully managed”.
Petrol Station Superstructures - UK and Poland operations “experienced a high level of quality activity in the period”.
Corporate Branding - “good progress” as it recovers from Covid restrictions.
Outlook - gives little away. This company does not do forecasts.
We believe that we have progressed strongly and created considerable opportunities through our commitment to being bold whilst building a substantial war chest to support our continuing investment, particularly in defence. Notwithstanding, we remain vigilant, in order to react to any changing circumstances.
Interim dividend - 2p (last year: 1.75p)
My view
I defer to those who’ve put long hours into studying this one. What appear to be highly informed comments can be found in the thread below, including once again an interesting contribution from Mark (username “illiswilgig”).
This company does not promote itself at all and so investors must do their own digging and come up with their own investment thesis.
One of the quirky features of today’s results statement is that you have to dig into the footnotes to find any of the details about segmental performance. Here is the relevant table:
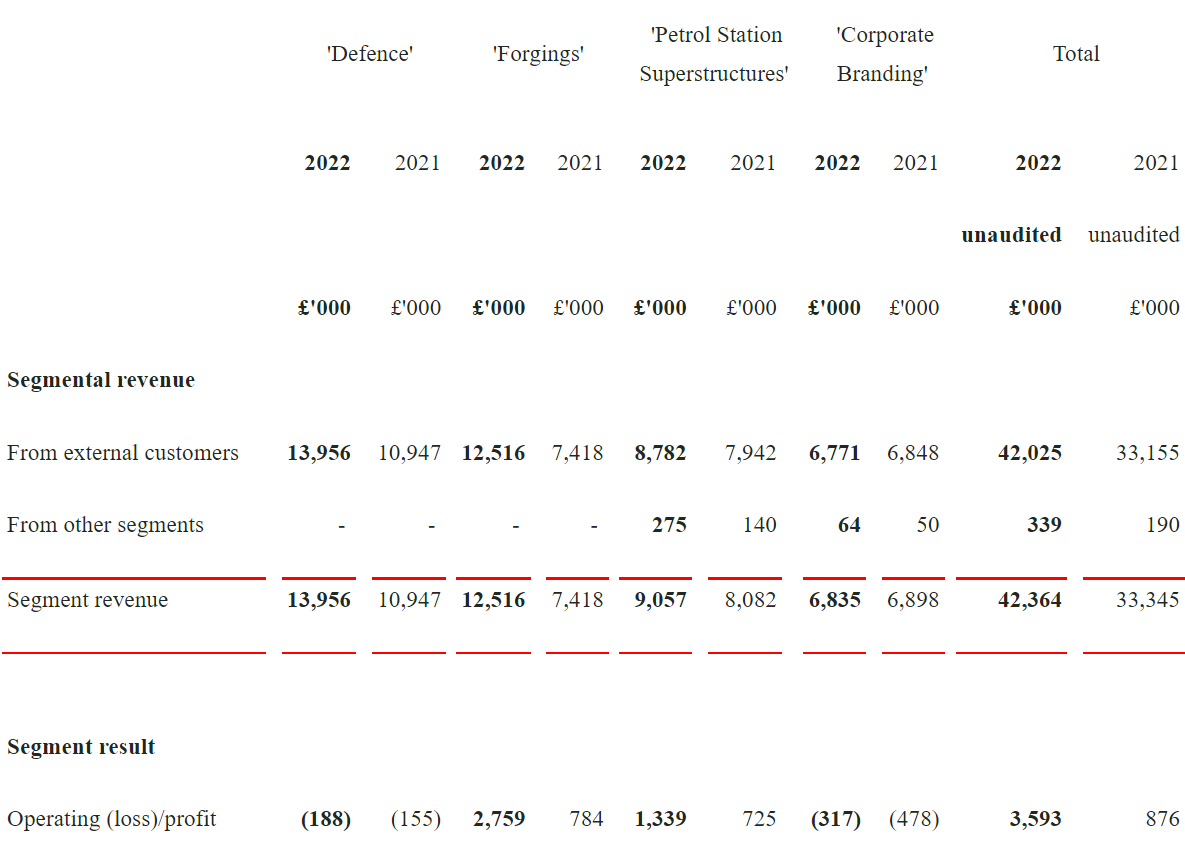
That’s probably a lot to take in, but the key points are:
- Defence, despite generating the largest revenue of any division, produced another H1 operating loss. This will hopefully show meaningful operating profits in the periods ahead.
- Excellent growth in revenues and profits at Forgings.
- Good performance from Superstructures, though Corporate Branding again made no contribution to H1 profits.
I will maintain my positive view on this company and this stock, despite the share price having increased materially since I last looked at it.
My reasoning is simple enough. Since I last looked at the company, it appears to have edged closer to US Navy success in its Defence division. The other divisions, in aggregate, have continued to perform very well. And the cash position has grown further: even today, after the latest share price gains, cash still covers nearly 40% of the market cap!
Given that I already had a positive view on the stock, I can’t find any reason to change my view. The share price rise is more than fully justified, in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Oxford Metrics (LON:OMG) (I hold)
Outlook
"Based on order intake so far in the new financial year which, includes our largest ever single order, demand remains strong."
---
Historical Data
https://find-and-update.compan...
MS International (LON:MSI)
Thanks for answering those points to Nanotrader, Mark! With a range of subsidiaries each of them having their own individual cash position, it personally wouldn't worry me to see some of these subsidiaries occasionally using overdrafts and paying some interest. G
drink the wine before buying Naked - my experience has been quite poor.
I've mystery shopped Naked Wines (LON:WINE) (twice), and Virgin Wines UK (LON:VINO) - in both cases, the introductory offers were attractively priced, and the wines were OK - nothing particularly special, or memorable about them.
Delivery works quite well if there's always going to be someone in, but I found it a bit restricting, knowing that a delivery was arriving, and then effectively being trapped at home until it arrived, as you wouldn't want to pop out and find one of the neighbours enjoying your order!!
Both WINE and VINO claim strong client retention though, so plenty of people must like their wines.
On balance, I think there's there's a ceiling to the market size, and hence the scale of both businesses, with a constant churn of customers, hence heavy marketing spend required. VINO strikes me as a better, run, safer investment than WINE. Although WINE does have recovery potential, if it can get the inventories down & avoid a profit warning.
Regards, Paul.
They're an interesting company I've been a customer of WINE for over 5 years now I've certainly had my ups and downs with them during that period. They have a solid customer base where you pay £20 per month that accumulates in your account so when you order a case your account goes to £0 and you pay the additional funds to complete the order. So I pay £240 per year but I order at least two cases of their finer wines per year (total 24 bottles) as quite a few have a cellar life of anything from 6 to 15 years. I've tried Laithwaites and some others but WINE is definately the best of the lot in my opinion especially when you get to know your growers. They are small growers where they produce small quantities which creates a frustrating situation when you order - they sell out so you end up trying to find other wines to fill your basket. I think the UK they have 300,000 subscribers all fighting for the best wines. Once you get to know how it works you time your orders when your favourite growers release a vintage and you quickly fill your basket before they run out.
The customer funding goes to supporting wine growers they will typically be from the industry starting up their own vineyards, they need funding that is where the cash goes in advance before any wine is produced. They support the small holder wine growers, offer them advice etc.
Now the wine lake was caused by two situations from what can fathom out. In 2020 their staff all started working from home (Covid lockdown), they pretty much stopped all orders which seemed insane to me because wine suppliers were one of the few companies that could operate during the restrictions. They said it was to allow time to increase warehousing space. Next they started bailing out wine growers dotted all over the world who could not export their wines to restaurants because of Covid. This created a lake of wine. A lot of the Covid relief fund wine sold very quickly once they got the site up and running again for ordering online, it was slow the situation was that bad I had to order wine from elsewhere until they sorted it all out
The marketing they do tends to be in large hotels where there is a ticket price but if you roll up to them and order a case of wine the entrance is free. They get to meet the wine growers from all over the world they are very popular but I'm not sure they make money or even covers their costs from holding these events because from what I was told by an employee on the phone when I first ordered is the mark up is 30% on the wines that come (I can only assume this is the case). So a £100 case of wine is £30 of mark up. The staff seem to have perks where they have access to wine I'm not sure they have limits on this. These are the areas that concern me most - their control of costs. They have an extremely loyal fan base who frequently repeat order so the key yo their success is making that profitable, not to tempt new customers with a heavily discounted mixed case where a lot will say it was OK but nothing special. That's because they don't get to find the ones that fit their palate or style. So expanding is not key here it's making that loyal customer base repeat ordering produce more profit. Well that's a bit of background I hope it helps.
Thanks for posting that, ettrader, very interesting! Useful "scuttlebutt" that adds credence to what WINE says about customer loyalty, etc.
Carclo (LON:CAR) bad news just announced here. Seems a contract that was expected to be worth £10-15m revenue p/a for 10 years has been cancelled by the OEM just before the production phase. No reason is given.
Sorry to any shareholders that might be holding.
edit: Market cap down to £9m now which appears very cheap from an equity perspective but debt is £36m so an EV of £45m. Be interesting to see what the OEM has to pay in compensation for the order cancellation. If that can meaningfully reduce debt the business may start to be worth a look. I will stay on the sidelines though for now but interested if anyone closer to the company has any good info.
Thanks for flagging the Carclo (LON:CAR) news david, I hadn't spotted that.
I dropped coverage of Carclo in June here, concluding that equity looked worthless, due to bank debt & pension scheme liabilities.
This big contract cancellation could be a nail in the coffin. Although it depends on the contract wording, and what (if any) compensation CAR might be able to extract from the customer?
Will the bank pull the plug? Who knows. It might let the company continue trading, for a hopefully better outcome in the future.
However you look at it though, it's very difficult to see any value in the equity.
Agree. It's unfortunate but the market isn't good for raising equity at the moment and that's really what they should do to reduce debt. Even if they make £7m profits (doubling the half year) that's still £20m too much debt really. Haven't looked into debt servicing costs but an extra 3-4% could wipe another £1.5m off the bottom line if it is all variable.
The compensation for the cancellation contract is probably key. It's £100-150m of lost revenue so if the contract is strong then you could see £5-7m maybe?? That might be enough along with cashflow in 2nd half to reduce debt to £27m perhaps.
Littered with risks this one and much better value out there but I'll keep it on watchlist to see if things change.
Many thanks for your (as usual) superb analysis of Oxford Metrics (LON:OMG) Paul. It’s crucial that the cash pile is wisely used and the big risk is that it might not be! Another attraction (perhaps??) is that Oxford Metrics (LON:OMG) might tempt a bidder? So I see it as a lockaway share with (unless the cash is wasted on a daft acquisition) a good chance, for reasons Paul has covered, of an upbeat trading update ahead or possibly a bid.
Also re the Stockopedia quality/value numbers not being a good guide, isn’t this a problem quite often and with Sharepad numbers too? e.g I hold a lot of Investment Trusts and there are some astonishing bargains available right now with Trusts in some sectors: e.g UK and Europe Commercial Property on discounts to NAV up to nearly 50%!, I.e investors can buy for 50p a Trust worth £1 (AND if these were open ended Funds where investors always have to pay the full value the share price would be £1 instead of 50p). Yet Stockopedia figures for the likes of value sometimes make no sense at all and one of THE most important things to consider, the discount to NAV is not covered by Stockopedia at all!
Also Commercial Property Investment Trusts are SO much better than Ooen Ended Property Funds. They have no option but to lock their investors in when there is heavy selling, whereas Investment Trusts just go to huge discounts (like right now) when there us heavy selling to give great buy opportunities sometimes AND dividend yields are as high as 10% too.
I’ve wandered from £OMG. Apologies.
Hi Ken,
Thank you for flagging up that investment trust situation, could I trouble you to throw out a couple of names to guide some further research?
For what it’s worth I’m currently very interested in the industrial and precious metals mining space. The Rio’s and BHP’s of this world are sitting at PE’s of 5, yields of 8-10% with enough cash to see them though a year or two of reduced demand and China concerns, but tightening supply, demographics and emerging market electrification and growth are going to have that demand roaring back soon enough.
I haven’t checked out any investment trusts in this space, but I think I will now, as buying them at a discount now provides a nice little tail wind when the discount (eventually!) narrows.
John, ticker GIGB would give you an ETF with a good spread of mining stocks if that's of any interest to you.
I'm slowly building a position in it on pull backs.
Blackrock World Mining Trust (LON:BRWM) is an IT I hold in this sector. Only on a very small discount (1.2%) to NAV but pays a quarterly dividend. Another option is Blackrock Energy and Resources Income Trust (LON:BERI) which adds holdings in oil stocks to the mix, also pays a quarterly dividend and is on a discount of about 4.2% to NAV.
Thanks John Gibson
I’ve just lost a detailed reply ….so here’s a much shorter one. So ask if wanting more info.
Best site for Investment Trusts is aic.
Here’s the link that takes you straight to the Commodity and Mining Trusts:-
https://www.theaic.co.uk/aic/f...
I’ve held Blackrock World Mining Trust (LON:BRWM) CQS Natural Resources Growth and Income (LON:CYN) and Blackrock Energy and Resources Income Trust (LON:BERI) since near the end of the Mining sector bear market which ended in early 2016. Mining sector goes its own way and that bear market was not only far worse than the 2008 Banking crisis crash but also happened during a general bull market.
Using the link above, just click on the red heading for each Trust to bring up a wealth of info. e.g TOP10 shares in their portfolio, discount or premium to NAV and dividend yield etc. Also click on Announcements heading for must read info like Monthly fact sheets, results etc.
If going for one only there’s a strong case for Blackrock World Mining Trust (LON:BRWM) as they have 40% or so in big Miners like Rio Tinto (LON:RIO) Anglo American (LON:AAL) BHP (LON:BHP) £VALE £GLEN.
Be wary of big discounts. Sometimes they show the Trust is a bargain but at others e.g Baker Steel, they reflect very poor performance. A snag with buying now is that it’s after big sector gains and CQS Natural Resources Growth and Income (LON:CYN) Blackrock World Mining Trust (LON:BRWM) and Blackrock Energy and Resources Income Trust (LON:BERI) are all up between 30% and 45% over 1 year and a lot more over 3 and 10.
Other sectors with Trusts on unusually high discounts to NAV include Private Equity and U.K. and Europe Commercial Property Trusts. e.g I hold Phoenix Spree Deutschland (LON:PSDL) on crazy imo near 50% discount, SREI on equally overdone 40% discount as well as Aew UK Reit (LON:AEWU) 8% dividend paid quarterly, Schroder European Real Estate Investment Trust (LON:SERE) Alternative Income REIT (LON:AIRE) and Ediston Property Investment (LON:EPIC) who pay dividends monthly.
Another sector worth checking is Country Specialist which includes Vietnam. That’s been a great place to invest over the years but recent falls there look a buy opportunity. I‘ve held VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) long term. I’m clueless on individual Vietnam or Chinese or wherever Companies away from the UK so relying on Managers with proven records who are often natives of those Countries via Investment Trusts is a great way of investing all round the World AND in some interesting UK sectors too.
Ken, thankyou this is great information.
I must admit these REIT's are starting to appear on some value screens so I am getting interested..
Alternative Income REIT (LON:AIRE) is one in particular.
I am assuming the drivers behind the performance in these property REIT's are
1) Ability of management / track record?
2) Asset valuation under pressure from a reduction in property prices, new legislation on green credentials etc?
3) Market Sentiment generating the discount to NAV?
This is probably an over simplification, forgive me, but I can see that property pricing is reducing along with market sentiment, however at some point sentiment is likely to pick up and then property prices will follow thus accelerating potential gains....meantime a little divi as a sweetener...
Am I anywhere close
Thanks Again
Paul
TheFloatingInvestor.
It would take ages to post what you need to know about Property Trusts, but yes to your point3. A reason why the sector has fallen recent is because higher interest rates make the big dividends paid by many Property Trusts less appealing to big investors. But the recent share price falls mean anyone buying now gets a higher dividend yield.
When there’s a lot of selling Investment Trust discounts widen and sometimes dramatically so. To improve your knowledge the updates from the Trusts themselves are an absolutely key source. Ditto NAV updates and Manager comment on NAV. And how well is the dividend covered and is the current high dividend for many Property Trusts sustainable or even with increases likely. So always check out what the Trusts themselves say about their dividends.
Key must knows include rent collection figures and if disposals are above the price they paid etc. Also is the Trust focus mainly office or retail or Warehouses etc.
Though ADVFN bulletin boards are often poor or very poor quality (often matching the lack of quality of that Company) those on the individual Property Trusts and also “The Commercial Property thread” there are an exception so have a look there too.
Good to flag some of the value in investment trusts right now. The private equity funds also look very good value with many on 40% discounts such as Harbourvest Global Private Equity (LON:HVPE) Pantheon International (LON:PIN) and £APEO
Thank you all, I’ll look into those, cheers!
Any you can recommend ken mitchell please
The one retail share I have Quiz has reported this morning and I note it is in Paul's agenda to cover. I have continued to hold only because I have felt for a while on several valuation levels it has been too cheap. In the 6 months to Sep they have an eps of 1.19p. Christmas and New Year are a busy period so only time will tell how macro issues affect the outcome for them and the resulting eps for the second half. EPS last year ran in at 2.8p. Given a tailwind I would hope they can do better this year, say 3p, which would put them on not much more than 5 times. Their balance sheet is pretty solid and they have increased cash from £4.2m to £9.2m with a further £3.5m of bank facilities. Seems to me that with their very competent management team, balance sheet, inc revenues and margins, even if the macro situation deteriorates they can weather it. So downside not bad and upside well a simple P/E of 10 times would put them on 30p if guess is right. I remain a holder.
Just come off the Company presentation. I just like their down to earth pragmatism. Holder.
Busy week for me with a few of my holdings reporting. A mixed bag. It I've become accustomed to bad news and in-line statements are starting to feel like a win.
I'm unused to an actual positive statement and this mornings interim's from MS International (LON:MSI) (my largest holding) - the tiny tin-pot metal basher from Doncaster - are very positive indeed. The company never gets carried away with optimism the executive chairman of many years (decades even) merely commenting
'It is pleasing to report that the Group has continued to perform strongly'
before getting down to the numbers
Revenue £42m up 26% (£33.16m)
Profit £3.46m up from a small loss £0.77m
Eps 17.4p up from -3.4p
and the cashpile increased by 8m to £23.88m (mcap £56m at yesterday's 350p )
Remarkably these numbers are despite a small operating loss from the main defence division (due to moving to upgraded production facilities), a high level of profit from the forging divisions with facilities in South Carolina, Brazil and Doncaster, which has been invested in for some years and is now benefitting from 'reshoring' of large forgings, doubled operating profits from the 'supserstructures division' largely engaged in forecourts and reduced losses from the signs and branding division which is growing its small UK business quickly.
The company is not to everyones taste. There are no forecasts for the company. Nor does it speculate upon future figures. I understand from shareholders that attending the AGM is about the only way to engage with the company and is very beneficial. Not untypical behaviour for a company which is effectively family controlled with over 50% of the shares controlled by the executive chairman and related parties. But as I say - not to everyones taste.
It's particularly pleasing that today's figures have been achieved with no profit contribution from the defence division - as the it is normally the largest contributor to profits and in the future significant growth in the defence division is anticipated.
It seems that their approach to customer relationships is much warmer than shareholder relationships. Which is the way that I like it to be. In particular the US government. Which is in the process of awarding a sole source contract to roll our the Defence Division 30mm auto-cannon Weapon System across the US Navy and Coastguard.
Trials continue and award of sole source contracts are complex but the Government last week published its intention to proceed with the award of the contract. The progress is likely to be maintained as its a relatively small contract for the US Navy - though game-changing for MSI - and the system trials demonstrated the ability to Counter Unpiloted Airborne Vehicles (CUAS). Additionally Ukraine is already a customer (though its via the US and not clear if any systems have yet been delivered) and the company has developed a mobile and truck mounted version of the system for direct sales internationally in addition to the naval version.
I've not plugged this mornings numbers into my forecasts yet - but anticipate that I'll be upgrading my expectations for this years revenue and profits based upon H1.
My current forecasts are for £78m FY revenue and £6.3m in FY profit 39p eps. But they've beaten my H1 estimates by £7m in revenue, £1.7m in profit and 7p in eps.
Simply adding that to my forecasts gives something around £85m revenue, £8m profit and 46p eps. The company remains significantly undervalued and thats before accounting for the growing cashpile a significant part of the current Market Capital.
I'm certainly pleased by today's progress. But as I say not to everyones tastes,
cheers
Mark
I held MS and its a good value share doing good numbers with cash in a good sector (at least whilst defence spending is on the up)
Sold though as the family running the company have excessive pay levels and it is a company run primarily for their benefit not for shareholders .
Also could not get any responses t from them despite being 20 miles away
Also not sure I want to be holding shares in a company making products used to kill people.
So agree good company but taken as a whole I did not like what I was seeing and its not something I wanted to support.
Hi planetx - I respect your point of view. And I agree to the extent it affected my level of investment . Having had a very small holding for many years the lack of transparency, family control and level of direct payments held me back from taking a much larger position at the covid lows.
While it's currently my largest holding - that says as much if not more about the sad performance of my other holdings. In some cases - disastrous - but totally self-inflicted.
With some background in the defence industty I also understand your concern.
I'm not investing for the branding/signage, the superstructures or the forgings. Nice though they are I'm sure. It's the electro-optic technology that they have developed which drives my investment. Not the cannon. That's a standard( Northrop-Grumman) US design. Its the sensors, actuators, mount and software that the UK adds. Which make it an attractive and relatively low cost system for its performance.
It's getting harder to avoid such electronic systems being used in the defence industry. DJI-Mavics and Starlink appear to be integral to the current conflict in Ukraine. I saw a report posted by Bellingcat (I think) on a teardown of a crashed Iranian UAV which identified components and subsystems from over 20 US manufacturers.
When used for Counter-UAV this automated (man-in-the-loop) system is arguably likely to be saving lives not taking them. But I venture into the realms of philosophy I think. Dangerous territory. We all have to make our own decisions over what we find acceptable. I don't find it easy. But neither is it with big oil, big pharma?
cheers
Mark
Mark
Well done for holding .
It’s clearly a good company we’ll run with a great family running it who understand their business .
Nothing wrong with and one of the best AIM shares .
Just those 2 things put me off but at the time I was reducing to 6-8 holdings and it only just failed to make the cut .
I had also timed a good purchase and made a 25% turn in a week so too the short term dopamine hit of a quick profit .
Solid but unspectacular holding for me MS International (LON:MSI) Compounded around 9% p/a + dividends so decent returns for the patient.
My forecasts are not dissimilar depending on the success of the US Navy contract of 45-50p eps. I'm trying to work out where I think fair value is. 600p ish feels about right - ie 9 or 10* earnings + 150p of net cash.
But also tricky to see it getting there somehow.....I don't really want to compare multiples with the likes of BAE as I'm not sure it is a good proxy despite the defence crossover. Any thoughts?
Hello David.
MS International (LON:MSI) - good returns for the patient. Indeed. Well put.
can it get to 600p. Good question. My thoughts?
Short answer. Yes. Not overnight. But in the short, short-medium term 1-2years. Thats assuming that profits continue to recover/grow and without assuming a significant re-rating of the shares.
There is signifiant upside beyond 600p depending upon progress. In the long term this looks quite likely.
Short answer longer.
With a quick finger in the air upgrade to my FY forecast based upon this mornings figures I'll go for profits 7.6m to 8m.
At 9x rating (BAE is currently 14.3x 12m forecast ) thats enterprise value of 68m - 72m add in an estimated 25m cash pile at FY end gives market cap of 93m to 97m or sp of 570p to 598p (based upon 16.2m shares on stockreport) or a sp range 560 - 584p using a more realistic 16.6m diluted shares. Either way that's close to 600p for FY23 in May without assuming significant re-rating or other progress.
I see three potential catalysts for further re-rating of the shares in the next year or two:
[1] At 100m market cap the company comes on far more radars
[2] Formal progress with the US sole source contract
[3] Part deployment of the growing cashpile to bolt-on acquisition(s) to the divisions
Of course that all assumes that everything goes according to plan. Almost never happens with my plans. So I am quite prepared for it to take a little longer say 2 years to get to 600p.
I might amend my thinking once I've had time to sit down quietly and process todays results, but I doubt it will change the destination, just the route to get there,
cheers
Mark
MS International (LON:MSI) interesting results from this very quietly stated conglomerate of sorts.
For the half year EPS of 17.4p so around 35p+ expected for the full year.
Net Cash is about £1.50 of the share price. So trading on a PE of around 10 with 40% of it's market cap in cash doesn't feel bad value. Pays a reasonable divi yield too.
Defence is going well as you'd expect and looks like they are relatively confident of winning business with the US Navy, which I suspect would be material.
Never going to trade on high multiples but looks decent value with upside.
Another purchase of shares yesterday (£68k) by CEO Nicola Foulston in RBG Holdings (LON:RBGP) following on from her purchase of £161k on Monday after the profit warning. Nice to see that she has some skin in the game. I hold.
Thanks for the Moonpig (LON:MOON) pointer on svcr recently. Clearly massively overpaid for the acquisition. High interest costs
On a typical valuation basis of PER can't see how its even close to a three figure share price . (am short). Don't know if this will make the cut for update today Paul with the busy agenda
Love the comment also on proprietary AI that sent out birthday reminders. hardly AI to do that,
Morning topturkey,
Thanks! Yes I'm working on Moonpig (LON:MOON) right now actually. It came up as the biggest % faller of the day (for non-resource sector stocks), so biigest risers/fallers go to the top of our agenda.
Section should be up fairly soon, I've done most of it.
Regards, Paul.
Here's today's agenda below. Hopefully that might pre-empt the "why haven't you covered this..." type comments, which we find distinctly unhelpful, because we can't cover everything.
If something is stand-out interesting, just tell us, and we'll try to cover it.
It's not random. We look at all the day's main announcements briefly, and select the ones which seem of most interest (good and bad). Why cover bad stuff? To warn people away from it, if it's really bad, and to look for recovery opportunities. Also to cover things that nobody else covers, and build up a database of comments for future reference.
We cover a huge number of companies, in most sectors.
Well you cover far more than I expect you to do. I’m a totally satisfied member on this site. Thanks for all you do which apart from giving me detailed insights on many shares also educates me for my own research.
Hi Graham, can you help explain 2 points i'm not sure about with MS International (LON:MSI) - there appears to be a finance cost in the P&L when they have a massive cash position. Also the pension deficit has come down but the £900k p.a. payment remains till 2028. Can it not be reduced? Or is that not allowed once you commit. Thanks!
Hi Nanotrader - I noticed your points as well. I don't have a clear answer. One of the features of this company is accepting a limited level of information and shareholder interaction. Old school possibly describes it best.
On finance costs.
In the last annual report there is a note concerning breakdown of finance costs. Lease liabilities (for certain properties and motor vehicles) features.
Also overdraft charges. Which may seem strange. But I imagine a certain amount of the cash is held in both the US and Europe in addition to the UK it may not be enough to avoid overdrafts occasionally and I doubt that much of the cash is held in Brazil? Which may account for use of overdrafts.
I don't know where or how they hold the cash. I am surprised that in the 6months to October its not been earning more - but the rise in interest rates has been one of the fastest on record and it may be that interest payments have yet to be made. Or cash moved to more appropriate accounts. I speculate. Good question for the AGM perhaps?
Pension commitment
Yes. I rather hope that the level of payment can be amended if the pension moves into significant surplus. But that's not yet the case. There is an exposure to LDI, though only around 10%, so the cash may well have been useful. From what I know of the company I'm not surprised that they choose to fully fund the pension. At the moment its a commitment. I imagine the auditors insist on it being shown as committed until it is otherwise?
As I say this company is not to everyones taste. It has many of the hallmarks of an old school family firm. Long term stewardship of family firms can be beneficial but in the short term decision making tends to be less transparent. Minority shareholders are along for the ride. Something I try to keep in the back of my mind,
cheers
Mark
thanks for the response. I wonder if the cash isn't easily accessible, hence the overdraft fees. I don't tend to go to AGMs but looks like one I should attend given the lack of info in the statements
Redde Northgate Redde Northgate (LON:REDD) (Ihold) has produced interims. This "leading integrated mobility solutions platform providing services across the vehicle lifecycle" has LCV as its main product but doesn't tell us what it stands for. I recall it is vehicle hire.
It has produced many pages of financial tables which are confusing to the lay reader (me) with substantial differences betwen reported and adjusted results, and y-on-y comparisons. Performance seems to moving in the right direction, and what I can understand is that the interim dividend is increased from 6p to 7.5p.
I would welcome an expert assessment of the results.
Richard
Redde Northgate (LON:REDD) guides FY "modestly above market expectations"
Hi RichardK,
We've done well on Redde Northgate (LON:REDD) here in the past, so I'll try to take a look at it later this morning. Just need to get through some quick comments on the smaller stuff to get that out of the way.
Regards, Paul.
LCV - I assume it stands for Light Commercial Vehicle i.e. vans.
Redde Northgate (LON:REDD)
Another plus 1 from me ref request for expert analysis - looks like Paul is on the case.
Ref my thoughts on the numbers.
I would give this company A++ for reporting honesty and transparency. The numbers are never gone to be "easy" to make sense of - but what is there is very well laid out and provides enough info for one to get to ones prefered metric. I would highly recommend anyone looking at the numbers to at least try to dig to the detail.
For redd i would first default to the underlying numbers - they show of 84 pre tax compared to 102 statutory pre tax. These adjusts remove amortisation of £10 mill which i am fine with and adjust back gain on depreciation
The elephant in the room is disposal profits of £25 mill - if you go full tonto and remove all disposal profits you are left with £59 mill pre tax say £47 mil post tax. Thats eps of 20p. If we say 40p eps for year that pe of just below 10. I would say these calcs are pretty (bordering on very) conservative.
The really good news here is that even without any gains ref vehcile sales this company is clearly doing good business. The cherry on cake of vehicle sale profits is also real extra cash to help pay down debt or buyback shares or pay the divi.
Overall top marks for management here particualrly the cfo who lays out some very useful detail in the updates - it is potentially a very mesy set of numbers.
Main thing is they seem to be growing organically and getting some real good long term b2b decent contracts in place that will make the work of their customers easier.
My one obvious worry here is that they clearly benefit from supply chain constraints ref supply of vans and the like. Will they be able to get the business through the door at great rates if there is glut of new and old vans doing the rounds at cheap values in 18 months time? - so there is definately potental for current tailinds to unwind ref the "general trading sweet spot". To me the fact the company is delivering on point so well operationally means this has turned from cheap punt some time back to decent medium term hold unless shareprice goes up materially or there is evidence that that my presumption they have a really good solid niche and scale of operation turns out to be wrong (hopefully that presumption is not wrong).
Shoutout to the fact there are nil exceptional items in these numbers - why make an exceptional out of a normal expense if you dont really need to !!
Hi RichardK. LCV stands for Light Commercial Vehicle. Hire of Ford Transit type vehicles is Northgate's bread and butter.
SDI (LON:SDI) RNS is Interims not just an update. The outlook seems too cautious.
Better to under promise then over deliver.
Cash flow seems tight at least in the short term.
Poor cash flow is what struck me from these results. A build up in stock & creditors, which according to Finncap, is caused by stockpiling to obviate impact of supply chain difficulties. Cash is king.....
The interims from Quiz (LON:QUIZ) are encouraging with an increase in sales, profit, cash and gross margin.
SDI (LON:SDI) in line update looks like a possible beat for the year.
I hold both.
finance income dont seem very for £Quiz given cash balance?!
why would it? This is a backward looking set of interims from Mar to Sep. Interest rates on cash balances would be close to zero.
Going forward you'd expect circa 2 or 3% so may well add £250k p/a to the bottom line going forward.
Do like Quiz, not yet a holder and after recent rise was hoping to buy on weakness.
No mention of the more recent gross margin for £Quiz though. Based on their twitter feed, i suspect there has been more than normal discounting to get to that flatish Oct/Nov sales performance. Flat sales and higher costs would not be a good cocktail for H2.
Did you read the outlook section - "At least in line with market expectations"
I've followed Quiz (LON:QUIZ) quite closely and 'mystery shopped' using the app, website and in-store over the last 3 years. I've noticed over the last few months that they've increased their range for women (including petite and plus ranges) significantly, dropped the men's range altogether and now allow returns either in-store or via the post.
The shop in Bluewater (Kent) is always busy - the checkout staff said lots of women are buying clothes for parties etc. Friends who wouldn't have shopped in Quiz before, now buy (some clothes) from Quiz - it no longer seems to be the preserve of lower income 16-25 year olds..
I feel the clothes are well made and designed, particularly for the price and although there are bargains to be had, there are lots of full-price items in-store and online which appear to be selling. I get the impression that if something doesn't sell well or is in the wrong season management cut the price ruthlessly and promote via social media with an "Up to 70% off" attention grabber..
I do hold Quiz and from a shopper's perspective it looks to be doing the right thing.
This is very helpful, thanks Mjfgs.