Solid State H1 profits to rise despite 55% drop in NATO revenue

Analyst’s view:
Order intake from such large public sector clients is inevitably lumpy, but my impression is that Solid State is moving in the right direction, with order book growth and improving margins. The shares look reasonably valued to me at current levels and I'm happy to leave my previous broadly-positive view unchanged today.
Down 3.6% to 175p (£100m) - Trading Update & Notice of Results
Electronics group and power supply specialist Solid State is on track to report an increase in revenue and profit for the first half of this year - but it's a close-run thing.
Comparatives with last year have been made very tough due, to the large contribution from the NATO Support and Procurement Agency (NSPA) in H1 26. This valuable customer is described as "substantial but irregular".
As a result, today's outlook guidance is 'only' in line with expectations, despite double-digit growth in some markets.
H1 summary: key points
The target for Solid State's management is to achieve continual underlying growth regardless of NSPA sales. Today's update suggests to me that CEO John Macmichael is making a fair job of meeting this challenge.
The headline numbers for the six months to 30 September show a modest increase in both revenue and adjusted pre-tax profit:
Revenue to be "in excess of £87.5m" (H1 26: £85.7m)
Adj pre-tax profit to be at least £5.0m (H1 26: £4.9m)
This guidance suggests a c.2% increase versus the previous year, with stable margins. However, these flat headline figures mask a significant increase in non-NSPA revenue:
H1 27 non-NSPA revenue +25% to £77.1m
H1 27 NSPA revenue -55% to £10.4m
Drilling down into the company's segmental results suggests a similarly mixed picture, with varying conditions across different product lines:
Components: H1 27 revenue is expected to be c.30% ahead of last year due to a combination of "increased customer demand" and price rises in the memory market. The company says its overall order book remains strong despite "a small number" of projects being paused as memory price inflation has made them unviable. One significant positive is that stronger demand for own-brand products has improved the revenue mix, lifting margins. Higher margins are expected over the full year, with progress towards the medium-term target of 7.0% to 9.5%.
Systems: H1 revenue fell by around 20% due to the lower level of NSPA revenues compared to last year. However, non-NSPA revenue rose by c.30% during the period, which seems a pretty respectable result to me. Management flags up promising demand for products including rugged computers and "radio frequency and communications products". From this, I'd guess that growth is still being led by defence demand. The recent $26.2m win for Project CAIN confirms is an example of this. Profit margins for this business are expected to remain in line with the medium-term target of 12.5% to 15% this year, but my impression is that revenue may be slightly lower.
Power: H1 saw "strong demand", with revenue expected to be around 10% higher than the same period last year. Management flags "significant orders for battery systems" from Tier 1 customers in markets such as robotics, drone and naval sonobuoys. Margins are expected to improve this year, with further progress towards their target range of 10% to 12.5%.
Outlook
Order book: including the recent Project Cain order (which came after the H1 period end), Solid State's order book is now £141.5m, 33% ahead of March 2026. This improved visibility into the 2027/28 financial year.
Profit guidance is unchanged today:
Order intake has remained strong at the start of the second half, including the second tranche of Project CAIN. With a strong order book and good visibility, we remain confident in meeting our expectations for the full year.
Broker forecasts are also unchanged this morning, with both Cavendish and Zeus leaving their previous estimates unchanged.
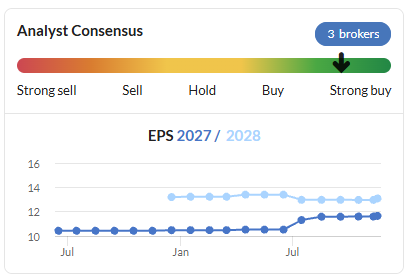
The consensus chart shows EPS progress is expected into next year, albeit narrower than originally hoped for:
Roland's view
Engineering businesses often experience slightly lumpy growth in revenue and profits when their sales are linked to large government orders. That seems to be the case here, but my overall impression is that Solid State is still moving in the right direction.
Profit margins are mostly rising and the company is winning plenty of new business away from its valuable but lumpy NSPA relationship.
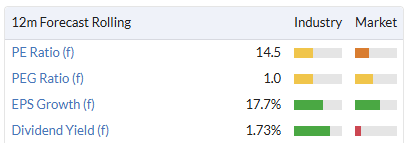
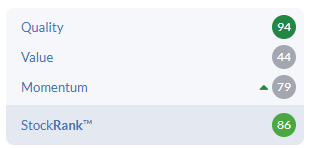
In my view, the shares look reasonably valued at current levels, a view supported by a PEG ratio of 1.0x and decent StockRank:
I'm happy to leave our previous AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Solid State (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?