Stock in Focus: A Speedy Hire could prove costly

Shares in Speedy Hire have lost 55% of their value this year. They are worth 97% less than when they peaked in 2007. Pretty much the only Speedy Hire investors still in profit are those who bought between 2010 and 2012, when the shares regularly dropped below 30p.
Speedy Hire blamed this year’s woes on inept management, poor customer service and misallocation of resources. We don’t really know how this strange situation came about, but it was serious enough for the firm’s chief executive and finance director to be shown the door in July.
A second profit warning then followed in September, advising investors that fixing these problems would take longer than originally expected.
More recently, two of the firm’s non-executive directors resigned. Their departure came in the wake of reported merger discussions with fellow big faller HSS Hire. According to Sky News, which reported this story, the proposed merger had the backing of a number of major shareholders. This deal might have made sense, as it could have provided improved scale and significant cost-cutting potential from de-duplication.
As things stand, however, Speedy Hire remains single. The firm does at least have a decent balance sheet and a fairly reliable dividend history, but is it a buy?
Rank decline
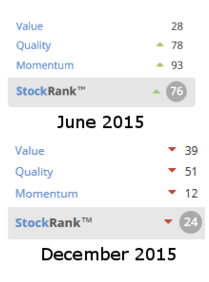
Stockopedia’s algorithms have turned steadily against Speedy Hire this year.
In June, just before Speedy’s first profit warning, the shares were up 50% on the year-to-date and had a StockRank of 76.
Today, the shares are worth 55% less than at the start of 2015 and have a StockRank of just 24. Value, quality and momentum scores are all poor and getting worse. Speedy Hire looks like a falling star that’s at risk of becoming a sucker stock.
Is this a fair view, or should investors take heart from the more positive commentary in November’s interim results?
Value?
Speedy Hire has a ValueRank of just 39. The only possible bright spots, according to Stockopedia, are a price/book ratio of 0.8 and a price/sales ratio of 0.5.
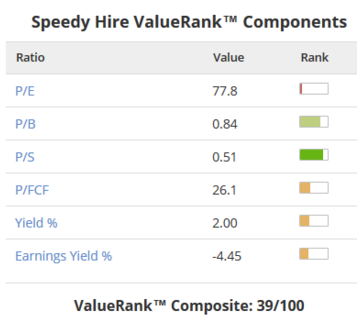
Personally, I’m not sure these are reasons to buy the stock. In my view it’s unlikely that Speedy could ever realise full book value for its fleet of rental assets if it was forced to sell them, so I’d view the P/B as appropriate, given the depressed earnings outlook.
Similarly, as Speedy only managed an operating margin of 1.9% last year, a low price/sales ratio seems appropriate to me. This ratio should be an indicator of how much profit a firm’s sales generate. In Speedy’s case, the answer is not a lot.
By way of contrast, van hire firm Northgate has a P/S ratio of 0.8 and an operating margin of 15%. Equipment hire firm Lavendon has a P/S of 0.96 and an operating margin of 11.6%. Speedy’s rating looks about right, to me.
One area which didn’t seem quite right was Speedy’s trailing P/E ratio of 77, based on normalised earnings of 0.45p per share. Occasionally, the normalised earnings calculated by Thomson Reuters and used by Stockopedia don’t marry up very well with the measure of adjusted earnings used by companies and broker forecasts. This seems to be one of those cases.
Looking back at Speedy’s results, trailing adjusted earnings for the last 12 months come out at 2.13p per share. This equates to a more reasonable TTM P/E of 16.4. I think the main difference between the two sets of figures is the £14.2m of exceptional costs Speedy incurred during the first half. These were the result of this year’s restructuring and write-downs:
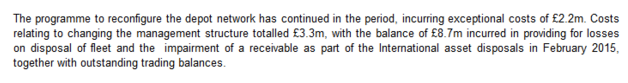
These sound like genuine one-off costs to me, so I’m happy to disregard them. However, as they were included in administrative costs, Thomson Reuters may not have filtered them out when calculating Speedy’s normalised earnings per share.
One positive so far this year is that Speedy Hire has maintained its dividend payout. If the final payout is also left unchanged, then the shares offer a reasonable prospective yield of 2%.
Uncertain quality
Speedy’s QualityRank of 51 suggests a fairly uninspiring business. The firm’s long-term average returns have generally been quite poor, with return on capital employed averaging just 1.6% since 2010.
The firm lacks any evidence of a moat. Equipment hire is a heavily commoditised business which Speedy itself describes as having “few barriers to entry”. Failing to take proper care of its SME customer base was one of the failings identified by the firm earlier this year. Rectifying this could take time and prove difficult with so much competition.
Speedy’s fundamental health scores aren’t great either. A Piotroski F-Score of 5 reflects falling profitability and rising long-term debt. Although the earnings adjustment I discussed above may have some impact on this score and the other quality metrics, there’s no denying the trend of falling profitability.
A lack of momentum
Speedy Hire’s shares trade more than 50% below their 52-week high with a whole raft of negative momentum indicators:
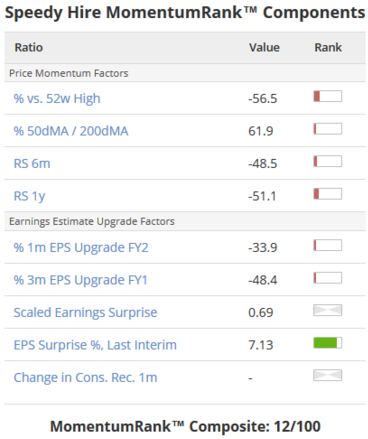
Although the last interims were apparently slightly ahead of expectations, this isn’t a compelling picture. Even if Speedy does offer some value, such a low MomentumRank suggests that it could be some time before a price recovery begins.
Indeed, I’m not really sure that these shares are cheap enough. The latest broker forecasts suggest earnings of 1.37p per share for the current year, rising to 1.52p in 2016/17. That gives forecast P/E ratios of 25 and 23 respectively.
The outlook
However, the five brokers who cover Speedy Hire don’t seem confident. The consensus forecast for current year earnings per share has fallen by 42% over the last month. Next year’s forecast has been cut by 27% since last month.
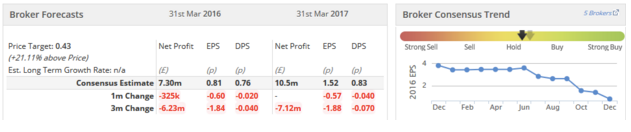
Given these aggressive downgrades, I’m a little concerned about the possibility Speedy might issue a third profit warning. The interim commentary did not make it clear to me whether Speedy expects to deliver any concrete evidence of a recovery in H2.
My view is that it may be too soon to buy into a possible recovery - I’d rather have more information before deciding.
However, this is only my opinion. I may be wrong -- please DYOR and share your thoughts in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?